Wise: revenue growth slows to 21%, but the shares still offer decent value

Analyst’s view:
I stayed positive on this stock in July, when Wise released some disappointing news for its investors. Today, there are again a few reasons for possible caution. Growth rates have receded a little, and the company continues to voluntarily sacrifice margin on currency exchange. But at 18x earnings, for what I consider to be an exceptional company, I don't need to demand that every trading update is perfect. I think Wise is on track to be a much bigger business in 3-5 years than it is today, so I'm staying positive.
Down 2% at 881.8p (£9.04bn) - Q2 FY27 Trading Statement
Familiar themes at this currency specialist: double-digit growth across all key measures, combined with a reduction in the "take rate".
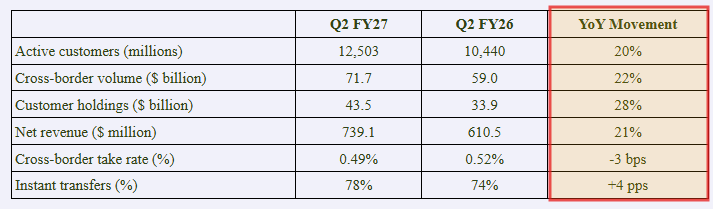
The ongoing reduction in take rate is explained like this: "we continued to proactively invest part of our operating leverage to further strengthen our competitive advantage of lower prices for customers ".
Let's do a quick comparison against the Q1 trading update:
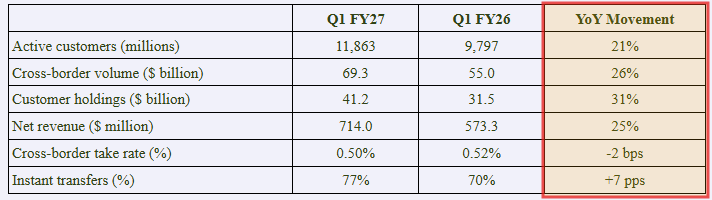
We can see modest reductions in the year-on-year growth rates between the two tables: revenue growth falls from 25% to 21%, and customer growth falls from 21% to 20%.
Turning back to today's update, and the outlook statement:
Wise now expects FY27 net revenue growth to be in the upper half (17.5% - 20%) of our 15-20% medium-term target range on a constant currency basis
Wise continues to expect FY27 income before tax ('IBT') margin around the top of our 20-25% range. For H1FY27, we expect the IBT margin to be c.23%, including one-off expenses equivalent to c.2ppts. This includes c.$15 million relating to the dual listing of Wise.
This strikes me as an impressive profit margin, whether or not you include the one-off expenses.
CEO comment:
"More than 12 million customers chose Wise this quarter to move over $70 billion around the world, paying 49bps on average, with 78% of transfers completed instantly. Customers are also using Wise for more of their everyday financial needs - spending $14 billion on Wise cards and increasing holdings to $44 billion.
Graham's view
We last mentioned this one in July, on the news that Wise had been denied in its US application for a national trust bank charter.
That's not a full banking licence, but it would have strengthened Wise's position in the United States - getting more control over the financial infrastructure it uses.
As things stand, Wise in the US is licensed only as a money transmitter, and has to rely on fully-licensed banks in order to operate. It will make another application to upgrade its status in US at some point.
I stayed positive on this stock in July, when that disappointing news was released (circled in red):
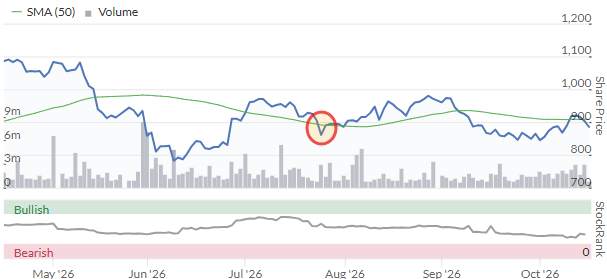
Today, there are again a few reasons for possible caution.
Growth rates have receded a little, and the company continues to voluntarily sacrifice margin on currency exchange.
But I am staying positive once again today.
The reason is simple: I continue to view Wise as offering decent value in the context of a high-quality, fast-growth international fintech brand.
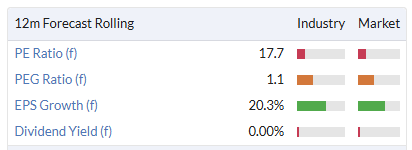
If the earnings multiple was 30x or higher, I'd have to stop and think a little longer about this. But at 18x, for an exceptional company, I don't need to demand that every trading update is perfect. I think Wise is on track to be a much bigger business in 3-5 years than it is today, so I'm staying positive.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Wise (3)
Comments here are also visible in the Daily Stock Market Report
Wise (LON:WISE)
Morning all!
Wise (WISE) Q2 FY27 — Another Solid Quarter, with Some Interesting Platform Disclosures
TL;DR
Wise delivered another strong quarter: active customers +20%, cross-border volumes +22%, net revenue +21%, with Wise Business continuing to outperform (+32% volume growth). Customer holdings increased 28% to $43.5bn, while card spending rose 30%.
Management upgraded FY27 constant-currency net revenue growth guidance to the upper half of its 15–20% range, while maintaining its expectation of an income-before-tax margin around the top of the 20–25% range.
As ever, I found the earnings call the most interesting:
• Wise Platform now accounts for approximately 6% of cross-border volume, progressing towards its 10% medium-term target.
• Platform’s average take rate is approximately 40bp, versus 49bp for Wise overall. This varies by partner, payment corridor and services provided.
• Existing Platform partners are adding routes, OakNorth and Vivid are live, and the CFO reported no known partner churn.
• Wise says it has submitted its remediation work relating to the US consent orders; regulatory confirmation remains outstanding.
My conclusion: Wise continues to execute well, with encouraging evidence of deeper customer engagement and growing institutional adoption.
The investment thesis looks intact, but Platform profitability and the sustainability of its economics remain unproven.
Happy to do a deeper dive if there’s interest.
Otherwise, I’ll leave my Q2 musings here and get back to the day job!
looks good !
Thanks for the summary. As ever the market just shrugs everytime they show results of growth and adding value to customers. Its been called by some the Amazon of payments in that for years Amazon focussed on growth over profit, hope the SP goes the same way eventually