Daily Stock Market Report (Fri 16th Oct 2026) - WISE, ENT, RNK, SSIT

Good morning! There’s been some news leaking out from Anthropic, maker of the AI assistant Claude, over the last day or two.
Both the BBC and Bloomberg report that the company has told investors that its Q3 revenues were $16.8 billion.
This would represent quarter-on-quarter growth of 45%, down from quarter-on-quarter growth of 140% in the prior quarter.
While that is still an extraordinary growth rate, it remains to be seen what valuation the IPO process will support. It was previously thought that the company was aiming for a market cap of $1.8 to $2 trillion.
If we annualise the Q3 revenue figure, we get annualised sales of less than $70 billion and a price to sales multiple of 27x-30x at the valuation range mentioned above. This is going to be a very interesting IPO!
Overnight market movements:
The FTSE is flat at 10,835
S&P 500 is up 0.2% at 7,760
Brent crude (December) is down 0.8% at $105.05/bbl
Gold is up 0.1% at $4,175oz
Bitcoin is up 0.1% at $82,075
The Agenda is complete. I intend to look at Wise and then may take the opportunity to cover one or two interesting stories I may have missed this week! Cheers.
Update: all done for now, have a great weekend!
Companies Reporting
Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Wise (LON:WISE) (£11.1bn | SR40) | Active customers up 20% year-on-year. Net revenue +21%. Cross-border take rate down 3 basis points to 0.49%. FY27 outlook: now expects FY27 net revenue growth to be in the upper half of our 15-20% medium-term target range. FY27 income before tax margin around the top of our 20-25% range. | GREEN = (Graham) | |
Ithaca Energy (LON:ITH) (£4.8bn | SR93) | CEO has informed the Board of his intention to retire by 31st March 2027. The Board has commenced a process to identify a successor. | ||
Man (LON:EMG) (£3.8bn | SR86) | Assets under management of $270.9bn as at September 2026 (June 2026: $253.6bn). Positive net flows during the quarter of $10.1bn. | ||
IP (LON:IPO) (£629m | SR82) | Portfolio company Microbiotica raises £36m in Series C financing. This will support the advancement of MB310 into Phase 2 clinical development in ulcerative colitis. IP invested £4m in this round and will have a 16.4% stake valued at £24.1m. | ||
Halo Minerals (LON:HALO) (£279m | SR7) | Updated Competent Person’s Report for Playa Verde copper tailings project in Chile increases the Ore Reserve by 5.4% to 33.94 Mt. On the Ore Reserve alone, supports an after-tax NPV10 of US$174.3m and an after-tax IRR of approximately 46%. | ||
Iofina (LON:IOF) (£106m | SR93) | Due to the impact of the lower levels of water at the plants, the delay in commissioning of the IO#11 brine line and the timing of IO#12, the Company now anticipates H2 production to be closer to 440-455MT. IO#12 IOsorb® plant is now commissioned. The new plant is undergoing hydrotesting, and brine water is now flowing through its system, with production expected to begin and ramp up over the coming weeks. | PROFIT WARNING? Share price down 15% at the open. | |
Helix Exploration (LON:HEX) (£76m | SR6) | The Montana Board of Oil and Gas Conservation has granted an exemption, subject to standard periodic gas composition review, allowing the Company to vent waste gas (which at Rudyard is primarily nitrogen) and therefore restart Rudyard operations with immediate effect. | ||
Aura Energy (LON:AURA) (£42m | SR10) | Quarterly Activities Report for September 2026 & Tiris BFS Confirms Low-Cost, Near-Term Project | Tiris Uranium Project in Mauritania: With the Bankable Feasbility Study (BFS) released and pilot plant commissioning scheduled to start in November 2026, the Company’s focus turns to funding and building the Project. Ongoing dialogue with financial institutions and strategic equity investors for debt and strategic equity funding, Tiris BFS: post-tax NPV of US$500.3 million, Aura’s attributable share is US$425.3 m. |
Graham's Section
Wise (LON:WISE)
Down 2% at 881.8p (£9.04bn) - Q2 FY27 Trading Statement - Graham - GREEN =
Familiar themes at this currency specialist: double-digit growth across all key measures, combined with a reduction in the "take rate".
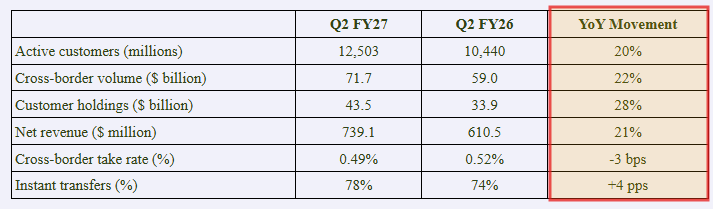
The ongoing reduction in take rate is explained like this: "we continued to proactively invest part of our operating leverage to further strengthen our competitive advantage of lower prices for customers ".
Let's do a quick comparison against the Q1 trading update:
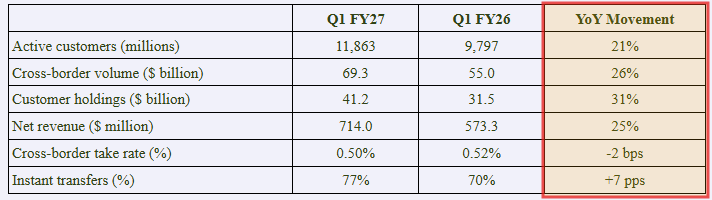
We can see modest reductions in the year-on-year growth rates between the two tables: revenue growth falls from 25% to 21%, and customer growth falls from 21% to 20%.
Turning back to today's update, and the outlook statement:
Wise now expects FY27 net revenue growth to be in the upper half (17.5% - 20%) of our 15-20% medium-term target range on a constant currency basis
Wise continues to expect FY27 income before tax ('IBT') margin around the top of our 20-25% range. For H1FY27, we expect the IBT margin to be c.23%, including one-off expenses equivalent to c.2ppts. This includes c.$15 million relating to the dual listing of Wise.
This strikes me as an impressive profit margin, whether or not you include the one-off expenses.
CEO comment:
"More than 12 million customers chose Wise this quarter to move over $70 billion around the world, paying 49bps on average, with 78% of transfers completed instantly. Customers are also using Wise for more of their everyday financial needs - spending $14 billion on Wise cards and increasing holdings to $44 billion.
Graham's view
We last mentioned this one in July, on the news that Wise had been denied in its US application for a national trust bank charter.
That's not a full banking licence, but it would have strengthened Wise's position in the United States - getting more control over the financial infrastructure it uses.
As things stand, Wise in the US is licensed only as a money transmitter, and has to rely on fully-licensed banks in order to operate. It will make another application to upgrade its status in US at some point.
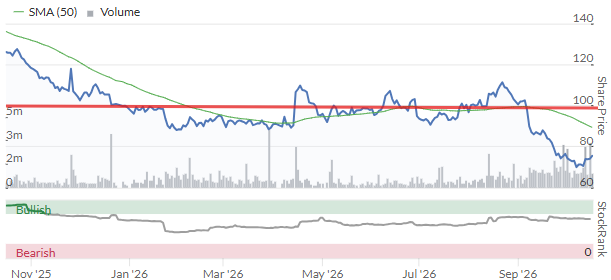
I stayed positive on this stock in July, when that disappointing news was released (circled in red):
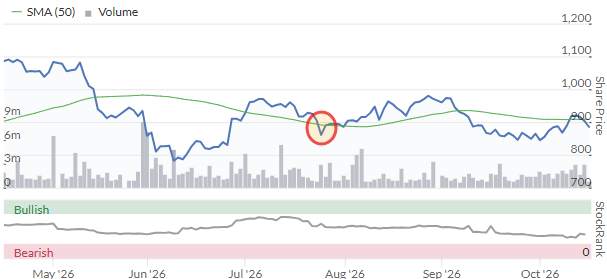
Today, there are again a few reasons for possible caution.
Growth rates have receded a little, and the company continues to voluntarily sacrifice margin on currency exchange.
But I am staying positive once again today.
The reason is simple: I continue to view Wise as offering decent value in the context of a high-quality, fast-growth international fintech brand.
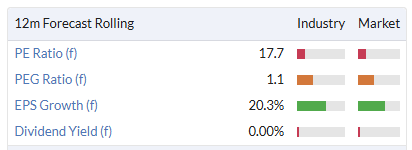
If the earnings multiple was 30x or higher, I'd have to stop and think a little longer about this. But at 18x, for an exceptional company, I don't need to demand that every trading update is perfect. I think Wise is on track to be a much bigger business in 3-5 years than it is today, so I'm staying positive.
Entain (LON:ENT)
(Backlog section)
Down 1% yesterday at 439.1p (£2.8 billion) - Q3 Trading Update - Graham - AMBER =
The valuation here has collapsed over the past year. The market cap was £6 billion in August 2025, which is the last time we covered it.
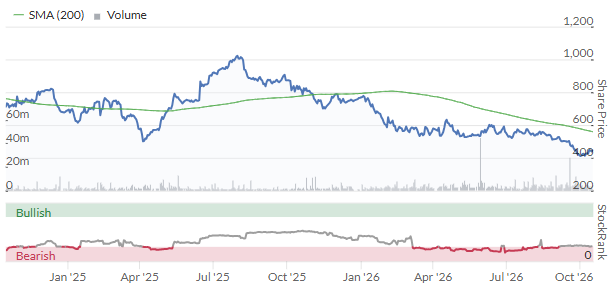
Rachel Reeves brought the hammer down on the gambling industry in November 2025. Bad news for Entain's UK-based brands, especially Ladbrokes and Carol. See here for a complete list of their portfolio.
Roland and I have been neutral in this one, even prior to the tax increases. Key reasons include the level of debt involved, along with its messy, heavily adjusted accounts.
Here are the highlights from yesterday's trading update:
Q3 net gaming revevenue +2%
Q3 online net gaming revenue +3% which would have been higher if not for "particularly customer-friendly sports results".
Outlook: FY26 guidance reiterated: expect Online NGR growth of 4-6%, on a constant currency basis, with Underlying EBITDA (exc. Parent fees) at the lower end of £910m to £960m range.
CEO comment:
I am pleased with our Q3 performance which reflects the strength of our execution and reinforces the resilience of our globally scaled business as well as its ability to consistently deliver high-quality growth.
Graham's view
As a long-suffering shareholder in Evoke (LON:EVOK), I'm not impressed by a highly-leveraged gambling company that emphasises its adjusted EBITDA.
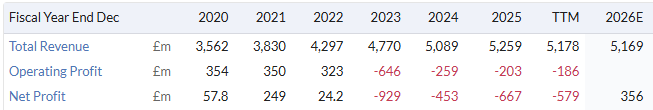
In H1, Entain reported an underlying EBITDA of £479m, but it was still loss-making on a statutory, after-tax basis.
It has been loss-making on a statutory basis for a while now:
Underlining the risky nature of the sector, the company's Brazil revenues have collapsed by 36% - there was "an increasingly challenging market prior to the immediate Online gambling ban announced on 25th September 2026".
The P/E multiple is only 7x but that doesn't take into account the leverage involved (£3.2bn or £3.6bn as of June 2026, depending on how you count it). The leverage multiple was last reported at 3.1x - my rule of thumb in most sectors is that I'm uncomfortable with anything over 3x.
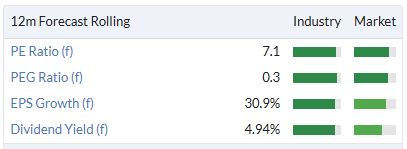
Forecasts also tend to allow for the company's adjustments, which are a big deal at Entain. In H1, for example, there were nearly £200m of "separately disclosed items", including £96m of "legal and onerous contract provisions" and £57m of "other" costs (!).
It might even be possible to justify AMBER/RED here, but I'll just leave us on neutral.
Rank (LON:RNK)
(Backlog section)
Unchanged yesterday at 74p (£347m) - Q1 2026/2027 trading update - Graham - AMBER/GREEN =
Solid stuff from this casino and bingo hall operator:
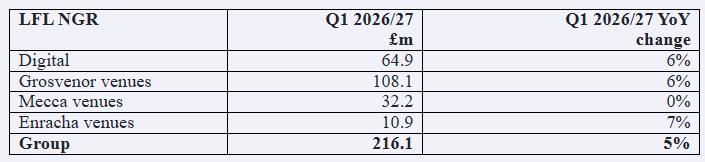
It's nice to see that growth is shared between digital and land-based venues - this is not a case where the land-based venues are in secular decline, as we often see with bookies.
The digital business has survived the higher taxes:
The UK business continues to demonstrate resilient customer metrics despite the higher tax regime introduced in April 2026 and reduced above-the-line marketing spend.
"Above-the-line" is a nice bit of marketing lingo - it refers to mass-market advertising, rather than targeted efforts to convert individuals. In response to higher taxes, many UK gambling companies have responded by cutting their advertising budgets. In this context, UK digital growth of 6% seems very good to me.
Grosvenor casinos: customer visits are up 1%, with a 5% increase in spend per visit. Maybe this could have been a little better, considering that casinos have been allowed to install more machines since last year. Gaming machine revenue was up 14%. But at the same time, 3 casinos were closed (Swansea, Reading, Sunderland).
Mecca (bingo): flat revenue, as the hot weather reduced visitor numbers.
Outlook:
The Group has made a strong start to the new financial year and, based on the current industry tax regime in the UK, is confident of delivering Group LFL operating profit in line with market expectations for the current year.
CEO comment, highlighting further tax risk:
“Speculation regarding the upcoming Budget continues to weigh heavily on investor sentiment, but our message has been clear: any increase to Machine Games Duty will increase costs, reduce venue viability, lead to venue closures and job losses, reduce tax receipts and halt investment. HM Treasury recognised these economic arguments last year and, with the right conditions, we believe our casinos and bingo clubs can play an important role in the Government’s growth agenda.”
Graham's view
I don't want to wade too far into politics here, but I think casinos will have every right to feel let down if the government doubles taxes on the very machines that they have only just allowed casinos to install in their properties. It actually feels like a bait-and-switch!
I toned down my enthusiasm for Rank in August, when I highlighted the risk of higher MGD.
The stock continues to offer decent value based on current profitability (and it has net cash on the balance sheet):
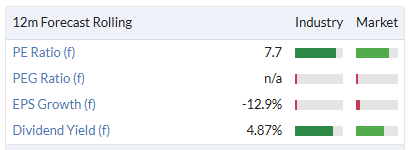
Given the fragility of land-based earnings, and the tax risk, I'm going to remain a little cautious on this one. AMBER/GREEN it is. Hopefully we see a friendly budget, in which case I'd expect the share price to recover to c. 100p.
Seraphim Space Investment Trust (LON:SSIT)
(Backlog section)
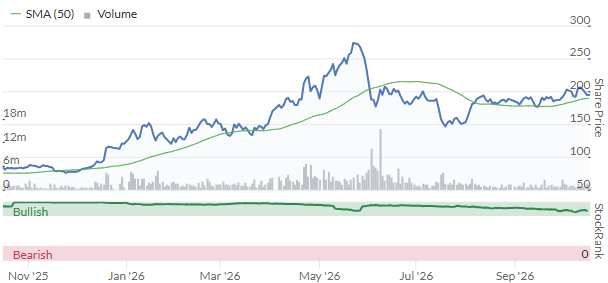
Down 2% yesterday at 194.4p (£461m) - Full Year Results - Graham - AMBER =
Seraphim Space Investment Trust plc (LSE: SSIT), the world's first listed SpaceTech investment company, announces its results for the financial year ended 30 June 2026.
This popular trust now has two share classes: SSIT and SSIC (C-shares).
The C-shares were used as a fundraising mechanism so that Seraphim could raise capital without suffering cash drag that would affect the performance of SSIT. Over time, SSIC shares will gradually be converted into SSIT shares.
That was a very clever idea in principle, but it does create a layer of complexity when studying the company's results.
Here are the key numbers for SSIT, the ordinary shares:
Net asset value £570m
Net asset value per share 240.49p (so SSIT shares are trading at a discount to this)
Thanks to the use of C-shares for fundraising purposes, there has been no change in the SSIT share count year-on-year.
As a result, both SSIT's NAV and its NAV per share have increased at exactly the same rate over the past year. Their growth rate was 102.9% - a remarkable result.
The main holding continues to be the Finnish company ICEYE (53.9% of total NAV, compared to 37.4% a year ago).
What it does: "ICEYE owns the world's largest and most advanced SAR (synthetic aperture radar) satellite constellation". Here's its website.
Beyond that concentrated holding, Seraphim is reasonably diversified. The next three largest holdings account for 6.4%, 5.8% and 5.3% of NAV.
But ICEYE itself deserves a few more words. Check this out:
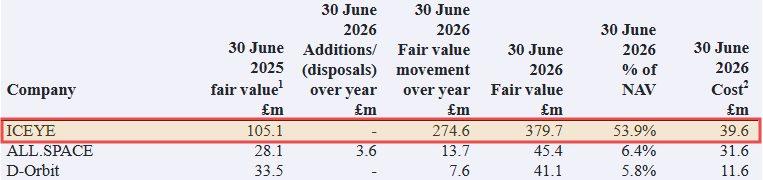
The net cost of Seraphim's investment in ICEYE is just £39.6m, and this holding is now valued at £379.7m, having seen its fair value increase by £274.6m over the past year! On its way to becoming a ten-bagger.
ICEYE enjoys a private market valuation of over €10 billion. Here's some background on its business performance last year:
ICEYE (53.9% of NAV) continued its transformation into a global defence and intelligence leader, reporting unaudited 2025 revenue of more than €250m and EBITDA exceeding €100m. Its joint venture with Rheinmetall was awarded a €1.7bn contract to provide Germany with space-based reconnaissance capabilities. The company also signed a $168m contract with the Finnish Defence Forces and an agreement with IHI Corporation in Japan for the delivery of an initial four satellites with options for up to 20 more.
The 2025 revenue number mentioned above implies an eye-watering price-to-sales multiple of 40x. This should fall to 20x in the current year, based on what we've previously been told about revenue doubling, and then hopefully fall further in 2027. It has an order backlog of €1.5 billion, and recently announced a partnership with Nokia to develop low earth orbit satellite communications systems.
Outlook: Seraphim expect more fundraisings at higher valuations. This would further boost NAV.
While ongoing volatility in listed space stocks remains a cautionary indicator, we remain optimistic about the portfolio’s overall trajectory...
We also anticipate continued momentum in portfolio fundraising, including further large-scale rounds at higher valuations. This should provide additional validation of the commercial progress and growing maturity of the portfolio’s leading companies.
Graham's view
I was neutral on Seraphim in June, when we learned that ICEYE had just achieved a valuation of over €10 billion.
My cursory review of these latest results does not motivate me to change my mind.
If you're convinced by the opportunity in the space sector, then clearly this trust is going to carry some appeal.
If instead you believe that space is in a bubble (financially), then you'll probably want to stay away.
Personally, I do fall into the latter camp. Price-to-sales multiples of 20x tend to scare me away, even for the highest-quality businesses, and I don't know if ICEYE is a high-quality business. As for the rest of the portfolio, I assume that the valuations are similarly frothy. The poster child for the sector - Space Exploration Technologies (NSQ:SPCX) - has a ValueRank of 5.
Value investors always tend to miss out on opportunities like this. But there are plenty of ways to make money in the markets - and if this one has been a winner for you, I'm glad!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

23 comments
Seeing as you guys are having a friendly scrap about investing in Iofina (LON:IOF), another risk to be aware of is that the spot price of iodine is not publicly available. And the price of iodine can be quite volatile. Therefore, as an investor you have no real visibility of profitability until results are published.
Zotefoams (LON:ZTF) Shares up sharply on the day. Can’t see any news (i hold)
Cockney Rebel spoke positively about it in his weekly review
Not that it moved the markets but rmillaree and Jon F made some good points in our chat about Zotefoams (LON:ZTF) on the Four Kinds of Share Lose Money discussion
Including that they have just announced a minor bolt on US acquisition which they may be able to seriously ramp up volume through.
I like the business but don't hold and wont do until the top two executives put their hands in their own pockets to risk their own cash, which they haven't done so far, for some reason. Might be biting my own nose off now to spite my face given what the share price is currently doing but there you go !
Thanks both. I also noticed after I posted the question that Berenberg apparently published on it yesterday with a 609p price target. We will see….
Re:Anthropic
"While that is still an extraordinary growth rate, it remains to be seen what valuation the IPO process will support. It was previously thought that the company was aiming for a market cap of $1.8 to $2 trillion"
Various reports attributed to Reuters suggest that some prominent investors at the recent investors open day had suggested a valuation of 1.5 trillion USD.
I’ve been researching Water Intelligence (LON:WATR). I think this looks very interesting after a large recent fall in the share price. The company is openly saying that revenue and profit is about to grow organically from its new preventative water leak lines of business. It seems a lot of investment has gone into this and so the operational gearing should be good from here. Canaccord just stated this: “Water Intelligence trades on 8.4x FY26E and 7.6x FY27E P/E, and 5.1x and 4.6x EV/ EBITDA, against 20x+ P/E for US water-tech peers. We see this as undemanding for a profitable, cash-generative business that is growing both organically and through acquisitions.” Paul Hill flagged a recent FT article about consolidation of this market in the US. To me, WATR is a clear takeover target that is currently priced very negatively. Not saying it’s the greatest business in the world but it looks like a great risk reward bet.
Held it on and off for years now and made some profits on the way up at times. Been doing nothing though now for a couple of years and whilst I am patient and not going to sell before I at least see a 400 price its really out of fashion. It was commented here that the company has significant manager owned and all excess cash and profits continue to be paid out re-aquiring franchises so nothing ever seems to come to shareholders. The Texas rollout (using a more efficient model of utilizing the assets first done in Texas) doesn't seem to be baring much fruit at the moment but its very very slow but steady progress. I will remain invested as I'm addicted tovalue but I might die before this one gets realized :-)
[I hold Water Intelligence (LON:WATR) ]. I think it will be hard to take over. There are some big institutional stakes from successful instutional investors; the chairman owns about 25%, and judging by the capital allocation I think he has big ambitions for it in the long run.
Water Intelligence (LON:WATR)
does the chairman (PSS?) still own the licence for the ip (or whatever it is?) it never really sat well with me that a situation like that should exist long term ? perhaps not a deal breaker if its on commercial terms and disclosed but i simply dont see how he can do stuff in the best interests of the company if its in his best interests to maximise return on that IP to his own company from Water?
Water Intelligence (LON:WATR)
Rmillaree, thanks for your contribution. Yes. My understanding is they still own the licence for the major IP that got the company started, but there are no royalties to pay until a $5m threshold is crossed. Beyond that threshold it would be 3% royalties, which I believe could reduce operating profit by 10% to 15%. But the companyhas been doing things to mitigate against it's reliancet by gaining access to other IP outside of PSS and partenrships with Streamlabs and Chubb insurance. Beyond that it get's really complex trying to pin down the exact financial situation regarding all payments in that direction to come to a summary figure. I've looked up more info but haven't got to any final financial figure. One thing to note is that that Patrick Desouza gurantees a proportion of WATRs commercial bank debt, so they can get cheaper loans which is a benefit. The main thing that they are relying on is the indpendent directors who have an impressive background to make sure that the conflict of interest (identified under the UK Takeover Code Rule 2.5.1 is subject to proper governance.
I found out a lot relating to your query, as it prompted me to research the issue. It would probably be too much to list just here and there might be some little inaccuracies as I've only just looked into it nore to attempt an answer to your question. But my feeling is that the risk is smaller than it might appear on the surface and I think it's far over-discounted in the valuation. So I'm not dissuaded from my holding at this point. I still think it's just far too cheap for the metrics and growth and potential.
Water Intelligence (LON:WATR)
at basic level though whats to stop PSS falling out and then they cant use the ip at some later date ?
surely its in the interests of Water Intelligence (LON:WATR) shareholders to simply pay a wad to get the ip back and avoid the obvious potential for it to get messy.
Note i am not in any way trying to suggest it may get messy.
Just my thoughts:
Nothing is stopping them apart from them having a joint commercial interest. But there is alternative IP available, which Water Intelligence (LON:WATR) has already started to take advantage of and is building to reduce the dependency. There would be some disruption but shareholders wouldn't need the company to buy it back. They would be able to get what they needed to continue elsewhere. Whether the technology would be as good is questionable, because some of the technology developed is leading the field I understand. Bbut the company has got all the franchises in place and is buying back franchises which gives them a greater moat I think. This kind of situation i fairly common in small companies that are still growing up. I'm not entirely discounting that it could get messy; I just don't think the chances are high enough to make it a less than attractive investment. But everything you are coming up with is intelligent considerations.
The big risk with Iofina (LON:IOF) always has been that their contracts for their raw materials (brine rich water from fracking wells) is never a guaranteed supply.
This time round, they blame it on frackers doing maintenance and so shutting off supply.
But when oil prices are low and frackers curtail output (as fracking is the marginal supply highest cost producer) then Iofina also suffers.
In addition, selling brine water to Iofina is a small part of a frackers total revenues and profits. So they are not incentivised to keep supply steady either.
If a company has supply that is not guaranteed, and no alternative sources... what PE ratio will you assign it?
One that reflects the value of its future cash flows. Which, as with US shale output, pretty much increase every year with a nice long runway of plants to roll-out. Every time they do so, the supply issue gets diversified away. Hardly a big drop on the back of such a risk.
I respect your super strong conviction that supply issue risk is not a problem anymore for Iofina (LON:IOF) going forwards. That conviction is definitely a good foundation for investing in Iofina, if you are.
Not a problem anymore? It is only up 5x over the past decade. The burden is on you to argue what has changed so that it is no suddenly a problem. My view is that this marginal risk is becoming increasingly marginal due to diversification of plants. I do hold and I don't intend to sell at the time of writing. I will not hesitate to do so if something better crops up, especially given the nearterm momentum is now broken. The game is maximising returns after all.
I think you've misread my comment. I agreed to disagree with you. I think supply is a key problem. You think it is not. And I respect your conviction?
I apologise for the belligerence, it is in my nature. I just enjoy a scrqp, and you are a good investor who is worth arguing with. Thanks for your grace.
A couple of positive chemical updates this morning:
Helix Exploration (LON:HEX) - Got the green light to restart operations at Rudyard. Get the gas going!
Iofina (LON:IOF) - IO#12, their largest processing plant has been commissioned and handed over to their ops team. Agreements in place for two more plants!
Wise (LON:WISE)
Morning all!
Wise (WISE) Q2 FY27 — Another Solid Quarter, with Some Interesting Platform Disclosures
TL;DR
Wise delivered another strong quarter: active customers +20%, cross-border volumes +22%, net revenue +21%, with Wise Business continuing to outperform (+32% volume growth). Customer holdings increased 28% to $43.5bn, while card spending rose 30%.
Management upgraded FY27 constant-currency net revenue growth guidance to the upper half of its 15–20% range, while maintaining its expectation of an income-before-tax margin around the top of the 20–25% range.
As ever, I found the earnings call the most interesting:
• Wise Platform now accounts for approximately 6% of cross-border volume, progressing towards its 10% medium-term target.
• Platform’s average take rate is approximately 40bp, versus 49bp for Wise overall. This varies by partner, payment corridor and services provided.
• Existing Platform partners are adding routes, OakNorth and Vivid are live, and the CFO reported no known partner churn.
• Wise says it has submitted its remediation work relating to the US consent orders; regulatory confirmation remains outstanding.
My conclusion: Wise continues to execute well, with encouraging evidence of deeper customer engagement and growing institutional adoption.
The investment thesis looks intact, but Platform profitability and the sustainability of its economics remain unproven.
Happy to do a deeper dive if there’s interest.
Otherwise, I’ll leave my Q2 musings here and get back to the day job!
looks good !
Thanks for the summary. As ever the market just shrugs everytime they show results of growth and adding value to customers. Its been called by some the Amazon of payments in that for years Amazon focussed on growth over profit, hope the SP goes the same way eventually