Seraphim Space Investment Trust: NAV up 103% on ICEYE, but valuations look stretched

Analyst’s view:
I was neutral on Seraphim in June, when we learned that ICEYE had just achieved a valuation of over €10 billion. My cursory review of these latest results does not motivate me to change my mind. If you're convinced by the opportunity in the space sector, then clearly this trust is going to carry some appeal. If instead you believe that space is in a bubble (financially), then you'll probably want to stay away. Personally, I do fall into the latter camp. Price-to-sales multiples of 20x tend to scare me away, even for the highest-quality businesses, and I don't know if ICEYE is a high-quality business. As for the rest of the portfolio, I assume that the valuations are similarly frothy. The poster child for the sector - Space Exploration Technologies (NSQ:SPCX) - has a ValueRank of 5. Value investors always tend to miss out on opportunities like this. But there are plenty of ways to make money in the markets - and if this one has been a winner for you, I'm glad!
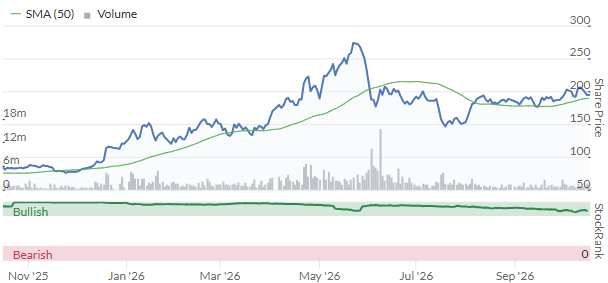
Down 2% yesterday at 194.4p (£461m) - Full Year Results
Seraphim Space Investment Trust plc (LSE: SSIT), the world's first listed SpaceTech investment company, announces its results for the financial year ended 30 June 2026.
This popular trust now has two share classes: SSIT and SSIC (C-shares).
The C-shares were used as a fundraising mechanism so that Seraphim could raise capital without suffering cash drag that would affect the performance of SSIT. Over time, SSIC shares will gradually be converted into SSIT shares.
That was a very clever idea in principle, but it does create a layer of complexity when studying the company's results.
Here are the key numbers for SSIT, the ordinary shares:
Net asset value £570m
Net asset value per share 240.49p (so SSIT shares are trading at a discount to this)
Thanks to the use of C-shares for fundraising purposes, there has been no change in the SSIT share count year-on-year.
As a result, both SSIT's NAV and its NAV per share have increased at exactly the same rate over the past year. Their growth rate was 102.9% - a remarkable result.
The main holding continues to be the Finnish company ICEYE (53.9% of total NAV, compared to 37.4% a year ago).
What it does: "ICEYE owns the world's largest and most advanced SAR (synthetic aperture radar) satellite constellation". Here's its website.
Beyond that concentrated holding, Seraphim is reasonably diversified. The next three largest holdings account for 6.4%, 5.8% and 5.3% of NAV.
But ICEYE itself deserves a few more words. Check this out:
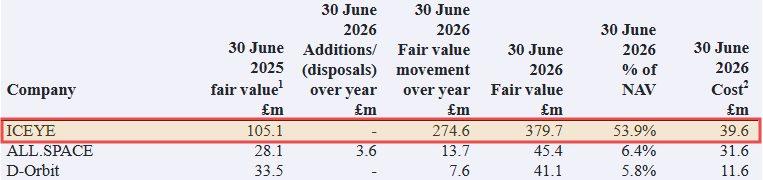
The net cost of Seraphim's investment in ICEYE is just £39.6m, and this holding is now valued at £379.7m, having seen its fair value increase by £274.6m over the past year! On its way to becoming a ten-bagger.
ICEYE enjoys a private market valuation of over €10 billion. Here's some background on its business performance last year:
ICEYE (53.9% of NAV) continued its transformation into a global defence and intelligence leader, reporting unaudited 2025 revenue of more than €250m and EBITDA exceeding €100m. Its joint venture with Rheinmetall was awarded a €1.7bn contract to provide Germany with space-based reconnaissance capabilities. The company also signed a $168m contract with the Finnish Defence Forces and an agreement with IHI Corporation in Japan for the delivery of an initial four satellites with options for up to 20 more.
The 2025 revenue number mentioned above implies an eye-watering price-to-sales multiple of 40x. This should fall to 20x in the current year, based on what we've previously been told about revenue doubling, and then hopefully fall further in 2027. It has an order backlog of €1.5 billion, and recently announced a partnership with Nokia to develop low earth orbit satellite communications systems.
Outlook: Seraphim expect more fundraisings at higher valuations. This would further boost NAV.
While ongoing volatility in listed space stocks remains a cautionary indicator, we remain optimistic about the portfolio’s overall trajectory...
We also anticipate continued momentum in portfolio fundraising, including further large-scale rounds at higher valuations. This should provide additional validation of the commercial progress and growing maturity of the portfolio’s leading companies.
Graham's view
I was neutral on Seraphim in June, when we learned that ICEYE had just achieved a valuation of over €10 billion.
My cursory review of these latest results does not motivate me to change my mind.
If you're convinced by the opportunity in the space sector, then clearly this trust is going to carry some appeal.
If instead you believe that space is in a bubble (financially), then you'll probably want to stay away.
Personally, I do fall into the latter camp. Price-to-sales multiples of 20x tend to scare me away, even for the highest-quality businesses, and I don't know if ICEYE is a high-quality business. As for the rest of the portfolio, I assume that the valuations are similarly frothy. The poster child for the sector - Space Exploration Technologies (NSQ:SPCX) - has a ValueRank of 5.
Value investors always tend to miss out on opportunities like this. But there are plenty of ways to make money in the markets - and if this one has been a winner for you, I'm glad!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Seraphim Space Investment Trust (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?