Entain: guidance held, but 3.1x leverage and a 36% fall in Brazil keep us cautious

Analyst’s view:
As a long-suffering shareholder in Evoke (LON:EVOK), I'm not impressed by a highly-leveraged gambling company that emphasises its adjusted EBITDA. In H1, Entain reported an underlying EBITDA of £479m, but it was still loss-making on a statutory, after-tax basis. It has been loss-making on a statutory basis for a while now: Underlining the risky nature of the sector, the company's Brazil revenues have collapsed by 36% - there was "an increasingly challenging market prior to the immediate Online gambling ban announced on 25th September 2026". The P/E multiple is only 7x but that doesn't take into account the leverage involved (£3.2bn or £3.6bn as of June 2026, depending on how you count it). The leverage multiple was last reported at 3.1x - my rule of thumb in most sectors is that I'm uncomfortable with anything over 3x. Forecasts also tend to allow for the company's adjustments, which are a big deal at Entain. In H1, for example, there were nearly £200m of "separately disclosed items", including £96m of "legal and onerous contract provisions" and £57m of "other" costs (!). It might even be possible to justify AMBER/RED here, but I'll just leave us on neutral.
Down 1% yesterday at 439.1p (£2.8 billion) - Q3 Trading Update
The valuation here has collapsed over the past year. The market cap was £6 billion in August 2025, which is the last time we covered it.
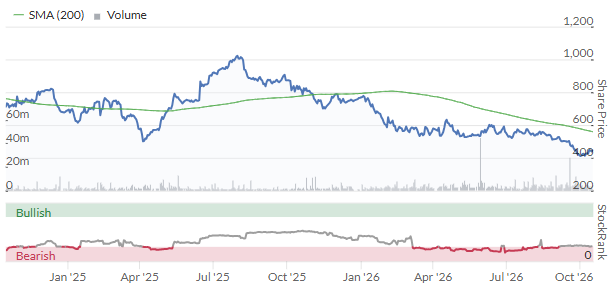
Rachel Reeves brought the hammer down on the gambling industry in November 2025. Bad news for Entain's UK-based brands, especially Ladbrokes and Carol. See here for a complete list of their portfolio.
Roland and I have been neutral in this one, even prior to the tax increases. Key reasons include the level of debt involved, along with its messy, heavily adjusted accounts.
Here are the highlights from yesterday's trading update:
Q3 net gaming revevenue +2%
Q3 online net gaming revenue +3% which would have been higher if not for "particularly customer-friendly sports results".
Outlook: FY26 guidance reiterated: expect Online NGR growth of 4-6%, on a constant currency basis, with Underlying EBITDA (exc. Parent fees) at the lower end of £910m to £960m range.
CEO comment:
I am pleased with our Q3 performance which reflects the strength of our execution and reinforces the resilience of our globally scaled business as well as its ability to consistently deliver high-quality growth.
Graham's view
As a long-suffering shareholder in Evoke (LON:EVOK), I'm not impressed by a highly-leveraged gambling company that emphasises its adjusted EBITDA.
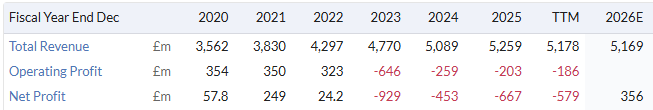
In H1, Entain reported an underlying EBITDA of £479m, but it was still loss-making on a statutory, after-tax basis.
It has been loss-making on a statutory basis for a while now:
Underlining the risky nature of the sector, the company's Brazil revenues have collapsed by 36% - there was "an increasingly challenging market prior to the immediate Online gambling ban announced on 25th September 2026".
The P/E multiple is only 7x but that doesn't take into account the leverage involved (£3.2bn or £3.6bn as of June 2026, depending on how you count it). The leverage multiple was last reported at 3.1x - my rule of thumb in most sectors is that I'm uncomfortable with anything over 3x.
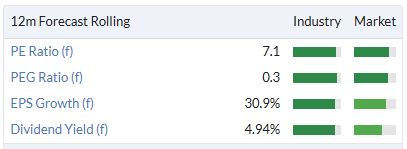
Forecasts also tend to allow for the company's adjustments, which are a big deal at Entain. In H1, for example, there were nearly £200m of "separately disclosed items", including £96m of "legal and onerous contract provisions" and £57m of "other" costs (!).
It might even be possible to justify AMBER/RED here, but I'll just leave us on neutral.
At the time of publication, Graham has a long position in ENT.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Entain (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?