Rank Group: UK digital revenue up 6%, but a rise in machine duty is the main risk

Analyst’s view:
I don't want to wade too far into politics here, but I think casinos will have every right to feel let down if the government doubles taxes on the very machines that they have only just allowed casinos to install in their properties. It actually feels like a bait-and-switch! I toned down my enthusiasm for Rank in August, when I highlighted the risk of higher MGD. The stock continues to offer decent value based on current profitability (and it has net cash on the balance sheet): Given the fragility of land-based earnings, and the tax risk, I'm going to remain a little cautious on this one. AMBER/GREEN it is. Hopefully we see a friendly budget, in which case I'd expect the share price to recover to c. 100p.
Unchanged yesterday at 74p (£347m) - Q1 2026/2027 trading update
Solid stuff from this casino and bingo hall operator:
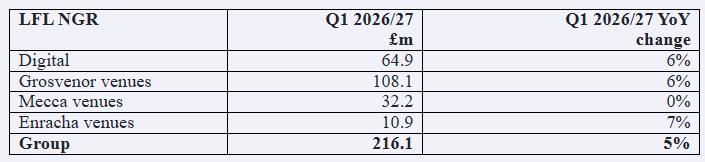
It's nice to see that growth is shared between digital and land-based venues - this is not a case where the land-based venues are in secular decline, as we often see with bookies.
The digital business has survived the higher taxes:
The UK business continues to demonstrate resilient customer metrics despite the higher tax regime introduced in April 2026 and reduced above-the-line marketing spend.
"Above-the-line" is a nice bit of marketing lingo - it refers to mass-market advertising, rather than targeted efforts to convert individuals. In response to higher taxes, many UK gambling companies have responded by cutting their advertising budgets. In this context, UK digital growth of 6% seems very good to me.
Grosvenor casinos: customer visits are up 1%, with a 5% increase in spend per visit. Maybe this could have been a little better, considering that casinos have been allowed to install more machines since last year. Gaming machine revenue was up 14%. But at the same time, 3 casinos were closed (Swansea, Reading, Sunderland).
Mecca (bingo): flat revenue, as the hot weather reduced visitor numbers.
Outlook:
The Group has made a strong start to the new financial year and, based on the current industry tax regime in the UK, is confident of delivering Group LFL operating profit in line with market expectations for the current year.
CEO comment, highlighting further tax risk:
“Speculation regarding the upcoming Budget continues to weigh heavily on investor sentiment, but our message has been clear: any increase to Machine Games Duty will increase costs, reduce venue viability, lead to venue closures and job losses, reduce tax receipts and halt investment. HM Treasury recognised these economic arguments last year and, with the right conditions, we believe our casinos and bingo clubs can play an important role in the Government’s growth agenda.”
Graham's view
I don't want to wade too far into politics here, but I think casinos will have every right to feel let down if the government doubles taxes on the very machines that they have only just allowed casinos to install in their properties. It actually feels like a bait-and-switch!
I toned down my enthusiasm for Rank in August, when I highlighted the risk of higher MGD.
The stock continues to offer decent value based on current profitability (and it has net cash on the balance sheet):
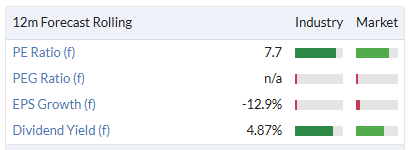
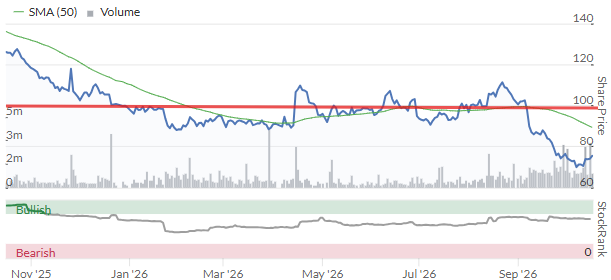
Given the fragility of land-based earnings, and the tax risk, I'm going to remain a little cautious on this one. AMBER/GREEN it is. Hopefully we see a friendly budget, in which case I'd expect the share price to recover to c. 100p.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Rank (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?