Alumasc: solid Q1 trading with order book +67%, we lift our view by one notch pending greater clarity

Analyst’s view:
Today's in-line update provides some reassurance after three cuts to consensus forecasts over the last 15 months. I think Alumasc's valuation could be attractive, but would argue that our contrarian tag remains fair given challenging conditions in the UK (90% of revenue) and the lack of a permanent CEO.
Up 7% at 248p (£90m) - AGM Trading Update
We turned RED on building products group Alumasc in July following the suspension of former CEO Pamela Bingham, pending an investigation into her professional conduct. She was subsequently dismissed in August, following the conclusion of a "full independent investigation".
The company remains under interim management and has not yet shared any information about the reasons for Bingham's dismissal, as far as I'm aware. In my opinion, this lack of disclosure casts a slight shadow over what otherwise appears to be a fairly reassuring trading update today.
Q1 FY27 trading: positive momentum
September's full-year results signalled "a positive start to FY27" with revenue up by 5% in the first two months of the year.
Today we learn this momentum has continued, with Q1 revenue (Jul-Sept) rising by 9.6% thanks to positive performances across the group:
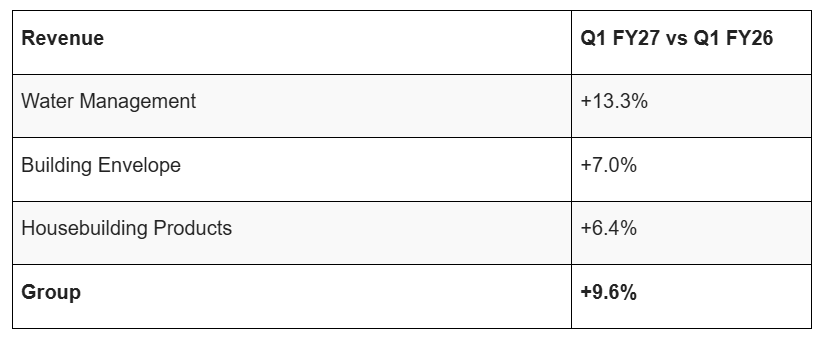
Profit margins are also said to have improved during the quarter, reflecting both operational gearing (i.e. higher activity levels) and recent cost cutting.
According to management, Q1 performance was aided by the company receiving its first call-offs on the £2m project at Singapore's Changi Airport. There were also further sales to Chep Lap Kok airport in Hong Kong. Excluding these customers, revenues "were still 5% ahead of Q1 FY26".
I may be wrong, but management's decision to specify an underlying sales growth figure excluding certain projects suggests to me that the airport contracts are large one-offs that may not be readily repeated.
Indeed, the company reminds investors that it's seeing "subdued demand conditions, particularly in UK residential construction markets". The UK generated c.90% of revenue last year, so remains very important despite efforts to increase export sales.
Order book up 67%
Alumasc's share price has responded well to today's news. One reason for this is likely to be the continued growth in the company's order book.
In September, we were told that the order book at the end of August 2026 was 56% higher than in August 2025.
Today, we learn that Alumasc's order book at the end of September 2026 was 67% higher than at the end of September 2025. The company doesn't seem to disclose the value of its order book, so we can't be completely sure of what this growth means in absolute terms relative to previous time points, but it certainly sounds positive.
Recent wins flagged today include a £2.1m Building Envelope contract with Manchester University and a £0.4m Water Management project at the Tin Can Island Port Complex in Nigeria.
Outlook & Broker Estimates
Today's update is in line:
The Board remains confident of progress in FY27, in line with expectations, and in the Group’s ability to outperform its underlying markets and deliver significant shareholder value.
House broker Cavendish has left its FY27 forecasts unchanged today:
Revenue up 6.8% to £114.5m
Adj EPS up 29% to 26.1p
Roland's view
There are certainly some positive aspects to today's update, but I think it's also worth remembering that consensus forecasts have been cut three times since last August:
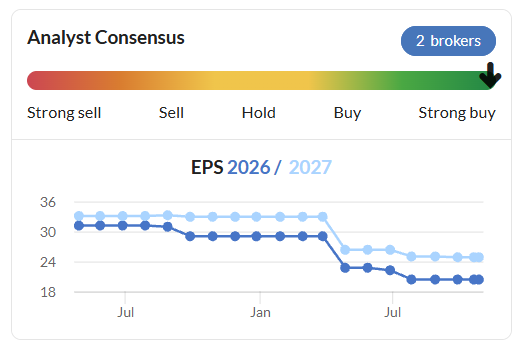
Today's update is only in line with expectations and the company warns of continued difficult conditions in its core UK market, despite the bullish commentary around the order book.
I think shareholders also need to consider the unexplained departure of the company's last CEO and the interim nature of current management.
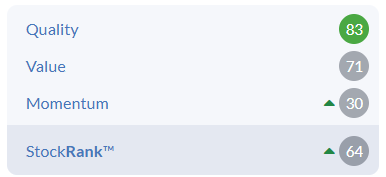
On balance, I think the StockRanks' Contrarian styling remains apt. This could be an interesting situation, but I think there's still some risk around earnings visibility. This is reflected in the low MomentumRank:
However, if Alumasc can continue to deliver on forecasts, the current valuation could be quite attractive:
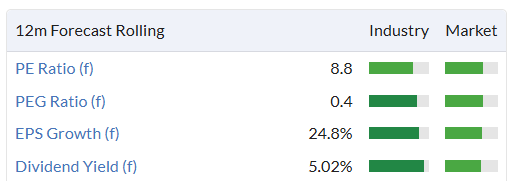
For this reason, I am going to move our view up by one notch to AMBER/RED today. While I'd like more clarity on the CEO situation, I think it's probably too severe to remain fully negative considering we have had two in-line trading updates (September's FY26 results and today) since the CEO was fired.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Alumasc (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?