ASX: Has the CHESS debacle undone their quality?

Continuing the theme of looking for stocks that are quality compounders, this week I looked for a stock that was both a quality compounder but also scored reasonably well on the value side. To find such a stock I had to relax my quality criteria slightly, but doing so led me to ASX (ASX:ASX).
The ASX is of course a household name, being the dominant stock exchange in Australia and the eighth largest securities exchange in the world. It derives its revenue from four main business lines:
Markets - 28%
Securities & Payments - 27%
Technology & Data - 24%
Listings - 22%
In addition, their large cash balances contributed net interest income of $32 million in the first half of FY23.
This fairly even spread of revenue across different aspects of the business creates a fairly stable revenue base. Revenue actually grew quite strongly from $636 million in 2013 to $1,095 million in 2019, but has been flat since, coming in at $1,097 in FY22 and an expectation for $1,016 in FY23.
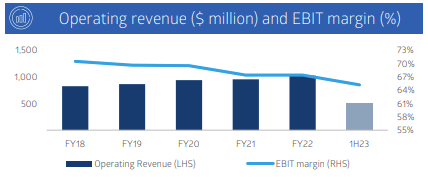
Source: ASX, Investor Day Presentation slides, 6/6/2023
Operating margin has been declining due to increasing expenses, but is still at a very high level compared to other companies, including when benchmarked against other global exchanges. Return on equity has been around 13% in recent years, but will dip this year, following the debacle that was the CHESS replacement project.
ASX has received a lot of criticism for its handling of the project to replace its equity settlements system, CHESS, which is now over 30 years old. They embarked on an ambitious project to use blockchain technology but it was plagued by delays and finally axed last year. This has resulted in the share price declining 32% in the last 12 months.
But temporary operational problems can provide long term opportunities for the patient investor. Of course, the trick is to be certain that they are temporary and will not present an ongoing drag on the business, or worse, turn into an insurmountable problem.
Given ASX’s dominant position in the market and the essential nature of its services for the Australian economy, the regulators keep a very close eye on it. A new CEO was appointed last year and she is making steps to rectify the problems. This will mean capital expenditure will increase from the current level of about $95 million to $110 - $140 million in FY24 and is expected to remain at those levels over the medium term.
Returning to the initial proposition, of the ASX being a quality compounder, the data for the Quality compounder screen is presented in the table below. (For an explanation of the Quality compounder screen, refer to this article)
Criteria | Threshold | ASX |
QualityRank | 80 | 97 |
Long-term ROCE | 18% | 18.2% |
TTM ROCE | 15% | 15.8% |
Operating margin 5 yr avg | 10% | 71.9% |
Operating margin TTM | 10% | 51.2% |
Net margin 5 yr avg | 8% | 45.5% |
Net margin TTM | 8% | 26.7% |
OCF / EPS | 0.8 | 1.8 |
Avg FCF (long term) / Assets | 8% | 7.6% |
Sales CAGR 5 yr | 0% | 3.3% |
Sales TTM / Sales Prior TTM | 5% | 12.3% |
Debt to assets | <50% | 0.7% |
Interest cover | 10x | N/A |
As can be seen, the ASX meets all of the criteria that have been set out in the screen except for one. When comparing the free cash flow yield, it falls just short of the 8% threshold. Interest cover has been noted as not applicable, due to the fact that they have net interest income. ASX have minimal financial debt on their balance sheet. They do show a high level of short term liabilities, but these relate to funds owed to market participants and are offset by cash and short term investments.
Having said that, this will probably change soon, as they expect to issue $200 - $300 million in corporate bonds in the coming year to support their capital expenditure program. However this is still relatively modest compared to total equity of $3.6 billion and total assets of $15.5 billion.
I have recently written about two other Quality Compounder stocks, namely PWR Holdings (ASX:PWH) and Netwealth (ASX:NWL). (You can read those articles here and here.) As was noted in both those articles, these types of stocks often trade at high valuations. The notion is that in the long term you will be compensated for paying a high price by the growth of the business.
But the ideal situation would be to acquire a Quality compounding stock at a low valuation. Given the market is wide awake to these stocks, that is unlikely to happen unless there has been some significant event, such as a messed up project. Even then, the ASX does not rank as cheap, but it’s current Value rank of 65 represents a reasonable valuation level. The forecast PE ratio is about 24 and the dividend yield 3.7%, fully franked.

Of course, it is only worth paying up for a stock if the future looks rosy, not just the past. There are some risks with ASX. Clearly project execution on its big technology grades is a big one. Another is regulatory risk and competition. At the moment it enjoys close to a monopoly position in its key segments, however if the regulators are unhappy with its performance, they may try and facilitate greater competition.
At an operational level, the challenge will be to return to stronger levels of revenue growth whilst keeping expenses under control. Also, they plan to reduce the level of the payout ratio to free up more funds to invest in their technology improvements.
ASX has been unpopular for good reasons in recent times, but value investing requires bravery because you have to go against the trend. The ASX may be an opportunity worthy of consideration, but keep your eyes wide open.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
The author holds interests in the following stocks mentioned in this article: PWH. This position can and will change at any time without notice.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?