Aviva up 2.5% as it continues to deliver; very reassuring outlook

Analyst’s view:
We've been moderately positive on Aviva and I think it makes sense to keep that stance unchanged today. For a look at some of the factors that caught my eye in the H1 results, please do refer back to the article in August. For now, I think the picture remains unchanged: we have a highly reputable insurance business doing everything that is expected of it from investors, customers and other stakeholders. It continues to offer value and there should be scope for quality metrics to improve over time.
Up 2.5% at 758p (£22.8bn) - Q3 2026 Trading Update
The last time we covered Aviva was in August, at the interim results.
Today's Q3 update continues the encouraging news flow.
Let's check out some of the highlights for the nine months to September 2026.
General insurance premiums +19% to £11.8bn
Combined Ratio 93.8%, improved from 94.4% last year (the lower the better)
Wealth net inflows £10.9bn, total wealth AUM up 19% to £267bn
No disappointments here. Or as CEO Amanda Blanc says:
“Aviva is in great shape. Our performance has been excellent in the first nine months of 2026, demonstrating once again the benefits of scale across our diversified business. We continue to deliver strong, profitable growth, particularly in the capital-light areas of General Insurance and Wealth."
It's important to highlight that Aviva bought Direct Line in July 2025, so the comparable nine-month period last year includes only three months (July-Sep) to which Direct Line contributed. Ideally, we might have been given figures for organic growth this year, excluding Direct Line.
It was the same at the interim results a few months ago: very high total growth figures were provided, but the precise contribution of Direct Line and organic growth was not provided.
However, there is one way that we can get an organic growth figure: by looking at any Q3-only figures given today.
Here's one, relating to General Insurance (UK & Ireland personal lines):
Discrete Q3 premiums were up 5% reflecting growth in both Intermediated and Retail, including on both Aviva and Direct Line brands.
The appendix provides more Q3-only information. Across all Personal Lines for the UK, Ireland and Canada, gross written premiums (GWP) were up 4%.
For all commercial lines, GWP were down 6%.
The net result is that total GWP were up 1%. So I would treat this as the best available indicator of organic growth in general insurance.
Explaining weakness in commercial lines, Aviva says "we maintained underwriting discipline to focus on profitability in current market conditions" (in the UK&I) and "larger scheme wins in Global Corporate and Specialty have been partly offset by the competitive rating environment" (in Canada). So in all regions, a soft environment is to blame - consistent with what we've heard from other insurers.
Outlook: very reassuring, in my view.
We are on track to deliver our three-year Group targets: Operating EPS CAGR of 11% (2025-28); IFRS Return on Equity of >20% (by 2028); and Cash remittances of >£7bn (2026-28 cumulative).
We continue to expect operating EPS growth in 2026 to be broadly in line with our 11% target rate.
Graham's view
We've been moderately positive on Aviva and I think it makes sense to keep that stance unchanged today.
For a look at some of the factors that caught my eye in the H1 results, please do refer back to the article in August.
For now, I think the picture remains unchanged: we have a highly reputable insurance business doing everything that is expected of it from investors, customers and other stakeholders.
It continues to offer value:
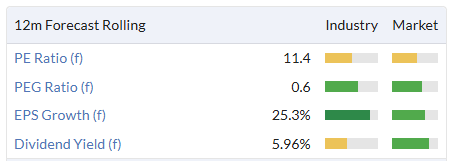
The "quality" metrics may look a little low, but there should be scope for these to improve over time as they focus on General Insurance/Wealth and (hopefully) the results for 2026 will be a little cleaner than last year. The 2025 results included £360m of "integration and restructuring costs".
It's a complex business but it continues to perform and a moderately positive stance seems defensible to me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Aviva (9)
Comments here are also visible in the Daily Stock Market Report
Graham, have you pasted the Wise (LON:WISE) summary into the Aviva (LON:AV.) notes?
FYI Aviva (LON:AV.) AV. AI's summary: "The nine-month trading update itself is in a linked PDF that the announcement does not reproduce. "
Doing things properly is better than an AI bodge.
I've written it myself! G
From my reading - the results from Canada ( which represent circa 28% of their overall General Ins premiums ) are disappointing but it is only one Quarter figures.
Thanks Graham!
Hi - sorry off topic but just to let you know you were right about Interactive Brokers having an involvement with IG Group as 'custodians'. Pity the staff at IG Group weren't as clued up as you; they were totally unaware until my case. They could have saved a lot of time, effort and worry on my false 'fraud' situation. Thanks again.
No worries, glad to hear I was able to provide some helpful context
For what it's worth I thought they read quite well on most metrics except the word broadly slipping into the eps growth statement. It read like a quite close broadly but u can never be sure on these things....so I half expected them to open down 2-3% but haven't yet... I still think the decent divi growing thesis is intact so not too concerned by this update one way or another. Stock is not in the teeth of market concerns at present so likely ok. I own.