B&M European Value Retail reports 24% earnings jump as turnaround takes hold, we see further upside

Analyst’s view:
I've been cautiously optimistic about a turnaround at this value retailer for some time, so I'm pleased to see that today's results show a clear improvement in both sales and profit margins. B&M shares aren't as cheap as they were, but today's guidance appears to underpin current market forecasts and debt levels are falling. I think it's fair to move to a broadly-positive view.
Up 19% to 332p (£3.3bn) - Interim Results
I've been cautiously optimistic about a turnaround at this value retailer for some time, most recently upgrading our view to neutral in June. Historically, B&M was a much more profitable business than the big supermarkets. My view was that there was no reason why this couldn't be the case again if the business was correctly managed.
B&M's share price has risen by more than 50% since then my last look at this stock, so I'm pleased to see that today's results show improved sales and profit performance and introduce clear financial guidance for the current (FY27) year.
Half-year results summary
Today's headline figures show strong progress:
Revenue up 3.6% to £2,848m
Adjusted pre-tax profit up 16.6% to £121m
Adjusted EPS up 24.3% to 8.9p
Free cash flow up 158% to £132m
Net debt down 29% to £61.3m (including leases)
Interim dividend up 2.9% to 3.6p
One of my previous concerns was the level of leverage in this business, so I'm pleased to see net debt is now falling. According to management, leverage excluding leases fell to 1.3x EBITDA in H1, while leverage including the group's £1.5bn of leases fell to 2.8x (H1 FY26: 2.9x).
B&M UK: another key problem was that like-for-like (LFL) sales growth in the core UK business had largely come to a halt and was negative in some segments. Addressing this was CEO Tjeerd Jegen's first priority after taking charge.
Fortunately, his Back to Basics plan appears to be delivering results. LFL sales were positive across the UK business in H1:
B&M UK H1 LFL sales +0.4%, including +3.2% LFL in Q2.
FMCG (consumer goods) LFL sales were flat in Q2 and have turned positive so far in Q3.
Mr Jegen is now moving onto the second phase of his turnaround plan for the group's core business. This will involve improving the productivity of the UK store estate by moving away from the company's one-size-fits-all approach to stores and introducing a range of different retail formats and layouts.
Early trials of a new format in Wigan are said to be encouraging and the company now plans to adopt successful features and layouts progressively in store refits.
B&M France: Elsewhere in the business, B&M France has continued to gain scale, with LFL sales +5.9% in H1.
The company says its share of the French discount market rose by 1% to 9.4% in H1. Management believes France is "several years behind the UK in market consolidation", providing an attractive growth runway.
B&M now has 156 stores in France and now expects to open 15-20 new stores this year. For context, the company has 797 B&M stores in the UK (a country with a similar population).
Heron Foods: this is a discount/convenience food retailer whose stores are usually located centrally in less affluent towns. Performance has been poor in recent years and the business generated an adjusted EBITDA margin of just 2.9% last year.
A new Managing Director is taking charge at Heron but performance has already started to improve under the retiring MD - sales growth turned positive in H1 and Heron's H1 EBITDA margin improved to 4.6% (H1 FY26: 3.9%).
Outlook & FY27 Guidance
B&M now feels confident enough to issue guidance for the current financial year, which ends in March 2027:
Adj EBITDA (pre-IFRST 16) of £450m to £500m (FY26: £459m)
Adj pre-tax profit of £280m to £330m (FY26: £284m)
The first point to make about these figures is that they don't necessarily represent much progress over FY26, depending on where results fall within the guidance range.
One reason for this is probably that a lot will depend on performance during the current "Golden Quarter" - the run-up to Christmas that's B&M's key trading period each year.
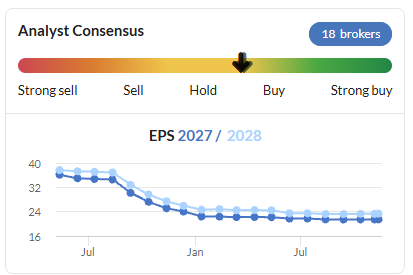
I don't have access to updated broker forecasts today. From what I can see through various sources, FY27 broker consensus prior to today was at the lower end of the guidance range the company has provided with these results.
This may mean that we'll see some broker upgrades filter through to the StockReport in the coming days:
Roland's view
Based on existing forecasts, today's share price gain has left B&M trading on a FY27E P/E of 15 with a 3% yield. That's probably at the upper end of what I'd want to pay for this business, especially given that debt levels still remain relatively high for a big retailer. With £1.5bn of lease liabilities, I'd prefer to see B&M operating closer to net cash, excluding leases.
However, the direction of travel is clearly positive and I continue to be impressed by the detail focus and clear-headed strategy of the group's CEO.
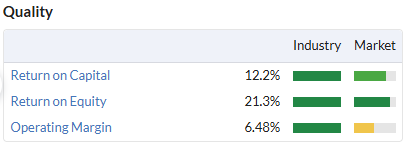
It's also worth noting that B&M's quality metrics are already far better than those of the big supermarkets, even at this relatively early stage in its turnaround:
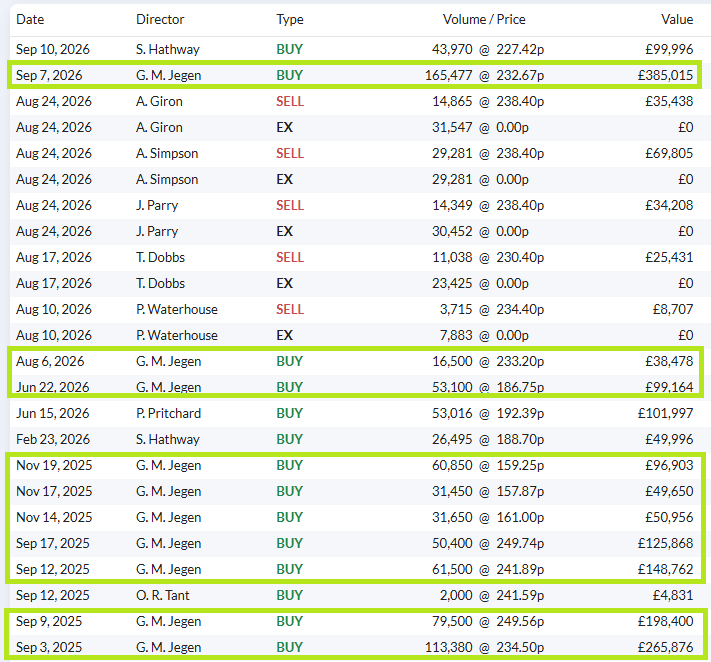
Another factor that alerted me to the potential for a strong turnaround here was Mr Jegen's share-buying activity after taking charge. His most recent purchase was for £385k in September (at 233p), but this is only the latest in a string of meaningful purchases since his appointment:
Our research has previously found that material share buying by CEOs and CFOs is often a positive indicator. Perhaps the most famous example of this in recent times is Rolls-Royce, whose then-new CEO was a heavy buyer ahead of the stock's re-rating.
I'm not suggesting that this will happen with B&M. I think this business is more constrained by economic constraints and perhaps market saturation (in the UK) than Rolls Royce. Cost inflation and cost-of-living issues are likely to remain a real issue here, limiting B&M's ability to raise prices or boost margins.
Even so, I do think this turnaround has further to run, with the added potential of continued growth in France.
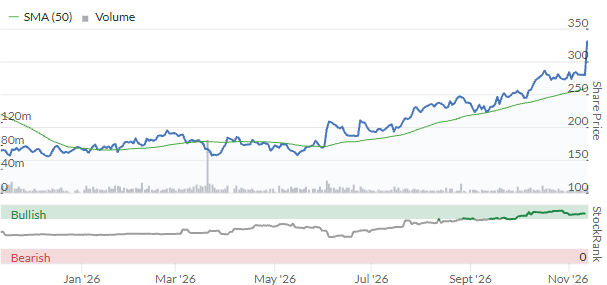
I'm encouraged to see this view is reflected by the StockRanks, which have risen steadily in recent months and earned B&M Super Stock styling:
I'm moving our view up by one further notch to AMBER/GREEN today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on B&M European Value Retail (3)
Comments here are also visible in the Daily Stock Market Report
Yes and what a crazy market - Galliford up by a smidgeon of a percentage and B&M European Value Retail (LON:BME) up nearly 18% today - Oh and Young & Co's Brewery (LON:YNGA) with excellent results down 3.5% - obviously not good enough!
investor sentiment seems to be the key driver behind how a positive update impacts share price. Interesting when viewed through the efficient market lens.
To be fair to B&M European Value Retail (LON:BME) , a share price of 325 is fair value based on historic PE average and assuming you believe they hit upper end of today’s guidance.
I’d rather have a larger margin of safety than rely on such an optimistic happy path to add to my current holding.
The price jump says to me that this was being heavily watched for signs of a recovery.
Hi Paul - Agree - I read that as - great time to cash in and move on