Daily Stock Market Report (Fri 1st August 2025) - MRO, ITRK, CLAI, TIME, TENG, FUTR

Good morning!
It has been a very busy week for updates; let's see what Friday has in store for us.
It's also the first day of the new month, and I'll be giving our spreadsheet an update later this afternoon.
I got called away to deal with something this morning, so I will be updating the report throughout the afternoon - please stay tuned! Thanks for your patience.
All finished with stock coverage for the week now, thank you.
Spreadsheet accompanying this report: link (last updated: 30th June).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
International Consolidated Airlines SA (LON:IAG) (£17.7bn) | “Robust demand delivering good earnings growth.” Rev +8%, PAT +43.8% (€1,301m). | ||
| Intertek (LON:ITRK) (£7.8bn) | Half-year Report | SP -8% “Strong FY25 expected”, mid-single digit LFL revenue growth. On track for medium-term targets. | AMBER (Graham) This is a quality assurance provider with a fabulous track record when it comes to earning an economic return on its capital and its equity. However, today’s report only assured that the company was on track for the medium-term. The current year is a little more complicated, and the newswire confirms that these H1 results were slightly below consensus (4.5% organic growth vs. 4.7% expected). The company says it is still targeting mid-single digit growth, but of course that’s a range and not a precise figure. EPS forecasts have been nudging lower for Intertek for most of this year, which is tricky for the share price when it's much more highly-rated than the wider UK market and when growth is already so modest. Stockopedia categorises it as a Falling Star. As I do think it's a quality company, and as the miss against expectations was so slight, I'm comfortable with a neutral stance. |
Pearson (LON:PSON) (£7.0bn) | On track to deliver guidance. Stronger growth expected in H2. H1 sales +2% underlying. | ||
Melrose Industries (LON:MRO) (£6.5bn) | Guidance for the full year unchanged at constant currencies. H1 revenue +6%. | AMBER (Graham) Can't get away from a neutral stance here, as the current market cap could easily represent fair value in my view. | |
IMI (LON:IMI) (£5.5bn) | Guidance reconfirmed. H1 rev +2% organically. On track for mid-single digit organic rev growth. | ||
Alliance Witan (LON:ALW) (£5.0bn) | NAV total return -0.7% vs. MSCI ACWI +0.6%. Share price discount to NAV stable at 4.7%. | ||
Playtech (LON:PTEC) (£1.23bn) | Strong performance since May. H1 adj. EBITDA at least €90m. Confident in ability to execute. | ||
Future (LON:FUTR) (£741m) | Commencement of programme to purchase up to £55m of shares. | AMBER/GREEN (Graham) [no section below] I don't include every share buyback RNS in this summary table - only if I think it's significant relative to the company's market cap. In the case of Future, £55m is over 7% of the market cap, so I do think it's material. And it's an interesting choice when the company has junk bond ratings at S&P and Moody's (BB+ and Ba2 respectively). Clearly it thinks there is a greater opportunity in buying back its own shares rather than in boosting its credit rating! The earnings multiple is only 5.4x according to the StockReport. Remember that this owns GoCompare (a company I was very fond of, when it was listed) along with many other well-known media brands. It had a profit warning as recently as May and is probably not for those who want to sleep soundly at night, but the potential reward does look interesting to me at this level. | |
Oxford BioMedica (LON:OXB) (£487m) | Four-year loan facility of up to $125m, refinances existing $50m facility. | ||
Public Policy Holding (LON:PPHC) (£215m) | Completes acquisition of Pine Cove Capital in Austin, Texas. | ||
Amcomri (LON:AMCO) (£96m) | €2m upfront paid in cash, €1.5m deferred earn-out. | ||
Invinity Energy Systems (LON:IES) (£91m) | £10m grant and planning approval for project that will be reference site for new and existing customers. | ||
Ten Lifestyle (LON:TENG) (£59m) | Integrated with OpenTable to provide a joined-up digital dining service. "Ten's high-net-worth and mass affluent members can search and book over 60,000 restaurants in markets including the UK, USA, Canada, Middle East, Mexico, Australia and parts of Asia. Offering superior access and benefits not available on the internet or restaurant's own website..." Also launches an AI tool to review customer communications. | AMBER (Graham) [no section below) This "global concierge technology platform" has intrigued me in the past, but its lowly profit margins suggest that it has limited pricing power. Its customers are family offices, private banks and wealth managers who wish to provide luxurious lifestyle services to their clients. I was neutral on it at a similar share price last year and Mark was neutral on it more recently. Today's two initiatives do sound interesting, and the CEO says that they "represent a step-change in our ability to serve more members with higher quality, greater consistency and improved operational efficiency." I would think that premium restaurant booking facilities are a key element of the service. But I shouldn't budge from our neutral stance until there is some evidence of financial gains for Ten's shareholders. This RNS was published via RNS Reach, implying that it's not material to the company's short-term results. | |
Windar Photonics (LON:WPHO) (£55m) | In a strong position, well-placed to deliver significant increase in revenues during 2025. | ||
Time Finance (LON:TIME) (£51m) | Improved facilities to an aggregate of more than £250m. Embarking on a new three-year growth plan. | GREEN (Graham) [no section below] I’m a fan of this small-cap business lender with a focus on “hard” finance (secured lending of two types: invoice finance and asset finance). Today’s announcement should enable continued scaling up of their business. If I go back to the last set of full-year results published for May 2024, I calculate that the company had total available facilities then of slightly more than £200m (£154m in Asset Finance and £50m in Invoice Finance). The growth and development of these facilities over time is exactly what investors will want to see - plus, at some stage, their diversification into other forms of funding. But for now there doesn’t seem to be any problem with their current facilities. This trades at a P/E multiple of 8x and is a Stockopedia Super Stock. | |
CEL AI (LON:CLAI) (£10m) | SP -17% | DARK RED (Graham) [no section below] This is one of the worst announcements I’ve ever read. The company formerly known as Cellular Goods is fleeing from LSE main market regulation, and it is not even going to put up with the regulation on AIM (where a prospectus is often not necessary to raise money). Instead, it wants to join Aquis in order to “execute our Bitcoin treasury strategy aggressively”. As I wrote earlier this week, I’m automatically RED on any company with a Bitcoin Treasury policy, as I presume they are already overvalued or are seeking to become overvalued, in order to raise funds at an excessive price. The London market needs a simple bitcoin ETF to take the air out of these Bitcoin Treasury companies. |
Graham's Section
Melrose Industries (LON:MRO)
Up 7% to 548p (£7.0bn) - Half-year Results - Graham - AMBER
Melrose Industries PLC ("Melrose", the "Company" or the "Group"), a world-leading global aerospace and defence business, today announces its interim results for the six months ended 30 June 2025 (the "Period").
This has never been covered in the SCVR/DSMR, and it’s a quiet Friday, so let’s take a look!
Defence is a popular sector these days, but MRO shares remain within their range, no runaway gains here:

Note that it demerged Dowlais (LON:DWL) back in 2023.
The company’s Engines and Structures divisions “provide technology for more than 100,000 flights a day”.
Some nice results here today, with everything moving in the right direction. There’s positive operating leverage and a very large increase in adjusted profits:

Notably, the unadjusted pre-tax profit is even higher than what’s shown above (£379m).
CEO comment:
"We delivered a strong performance in the first half with a 29% improvement in profit and cash flow significantly stronger than last year despite the backdrop of supply chain and tariff disruptions. Our multi-year transformation programme will be completed by year end and the benefits are already reading through with more to come… We are confident about delivering sustained increases in profit and cash flow in the years ahead and our free cash flow target of £600 million in 2029."
Engines: growth of 11%, and it sounds busy with contract extensions and a “deepened relationship with the Swedish Defence Administration”.
Structures: this is “a design-to-build partner on the world's most successful and highest volume aircraft”
Revenue growth is only 3% on a like-for-like basis, and there’s a decline of 7% including the loss of exited businesses. Still, adjusted operating profit grew by 32%. A restructuring programme is “nearing completion with full benefits expected in 2026 and beyond”.
Guidance: unchanged on a constant currency basis, excluding any tariff impacts.
Changing currency rates are having a negative impact and the company provides new numbers based on the stronger pound and weaker dollar. Adj. operating profit of £620-650m (previously: £650-690m).
Graham’s view
I can’t pretend to be an expert on this business, but I’m intrigued by the fact that it has a StockRank of only 13 and is categorised as a Sucker Stock. That’s pretty poor for a FTSE-100 share!

But the financial track record is indeed pretty poor, looking at the statutory numbers:

And in the absence of real profits, it hasn’t been able to generate decent quality metrics:

Another negative is that the company is only forecasting that it will generate £100m of free cash flow this year, despite an adjusted operating profit of up to £650m. That seems like pretty poor cash conversion to me. It is planning for much higher free cash flow in future years.
An obstacle facing it is the interest bill which isn’t small, running at over £100m a year currently.
Net debt is £1.4 billion, with a leverage multiple of 2.0x. It’s pretty normal for the big-caps to leverage up, so I guess this isn’t a big surprise.
To try to find a conclusion, I’ve applied some checklist items, including a quick review of the company’s earnings forecast trend (it’s negative).

In the end, I just can’t get away from a fairly boring AMBER stance on this one. It's trading at a modest P/E multiple which could easily represent fair value in my view. The Sucker Stock categorisation is probably a bit harsh:
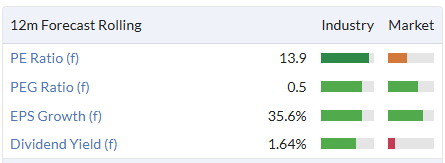
In conclusion: I guess this is why we don’t study big-caps as often - it's difficult to form a strong opinion on them! But at least we have this one in the archives now.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

41 comments
Could someone do a deep dive on Time Finance (LON:TIME) Time Finance please and give insight?
I've written loads on Time Finance (LON:TIME) on Stocko and elsewhere (I think you can go to my profile and search past comments and posts) as I used to hold and it was a top 3 holding for me.
Sold out recently at 60-63p. Thought that the key bull thesis was already well known, so that was fully priced in. Also that their new strategy was just "more of the same going forwards" and other positive factors like their bad debt and arrears couldn't get any better (but could get worse).
Would consider holding again. Think management have done a good job so far. But need something attractive - price, or story.
Future (LON:FUTR) Another point to note is that the company intends to cancel the shares that it will buy back. This is better than holding them in Treasury with the intention of giving them away to the directors as part of their compensation / bonus arrangements. Cancelling the shares increases the EPS, whereas giving them to directors does not increase EPS.
Hi Team I was hoping for some comment on International Consolidated Airlines SA (LON:IAG) and Time Finance (LON:TIME) if Monday is quiet.
"Dark Red". Oh dear.
A good result from the Supreme Court. Monday should be a good day and we will no longer have this case hanging over the finance sector. Phew!!
I agree with the result, although there is still the second case going on regarding the interest rates charged. I don't think this is such a big a deal though.
Will there be a costly admin exercise if people ask for their credit agreement to be reviewed to see if their interest rate was "fair"? They have nothing to lose by enquiring?
Re Spire Healthcare (LON:SPI) it looks as if Harwood Capital have upped their stake in the business to 4%.
Court judgement on the car finance ‘scandal’ due out today at 4.30pm. Good move to release it after the markets close. Everyone will have the weekend to study it and consider their position without a knee jerk market response affecting the situation.
I’ve got several stocks that are potentially at risk from an adverse judgment so I am hoping for some good news.
Hopefully, the hint of retrospective legislation by the girl from customer services will moderate the outcome, but it’s not to be trusted.
Yes Andrew the live naked trader radio show I did from this morning is on auto repeat.
Tune in at this url
fast.citrus3.com:8832/stream
Press play it might say "not secure" but it is, I'm not after your details!
It's on a different server so you may need to turn volume up when i talk and down a bit for the music bits. Apologies.
Included your ideas for trader songs, a look at lots of shares plus some of your ideas and loads more. Thanks for some great contributions.
On Windar Photonics (LON:WPHO) pleasing that they are continuing to make progress in North America, their key strategic ambition for growth.
However, I wonder if the latest Big Beautiful Bill in the USA means the pipeline there will all but dry up in 2 years time, as tax credits have been slashed for Wind in the USA and hard to see many more new projects get off the ground.
Windar will still be able to sell into all the existing wind farms, but is their medium-term growth strategy in doubt?
Or can they pivot and just depend on growth in Europe, Asia? Food for thought.
Renewables Infrastructure (LON:TRIG) , in today's Q2 NAV update reported
The final investment decision for the repowering of the Cuxac onshore wind farm in France was approved, which will see the site benefit from a new 20-year inflation-linked Feed-in-Tariff and its generation capacity doubled from 12MW to 25MW, as the six existing turbines are replaced with six new and larger turbines.
and
". . positive impact of technical enhancements relating to turbine hardware and software upgrades on several projects . ."
It is likely that as technology evolves, other wind farm operators will look to do something similar, in order to maximise the use of their assets and their grid connections. Presumably this will involve upgrades to installed Windar Photonics (LON:WPHO) kit and software. (I hold)
For those interested in the Investment Trust sector the monthly discussion board for August is here. https://www.stockopedia.com/co...
Watches of Switzerland (LON:WOSG) - I'm not a holder but wonder why it's the top faller today with no news. I cannot see tariffs having much of an effect but maybe I'm wrong.....
Watches of Switzerland (LON:WOSG) overnight news of 39% tariff on Swiss exports to US. I imagine that WOSG stores in US are supplied direct from Switzerland ( Rolex etc.) and not from WOSG's own stock in the UK. Worth checking this as there may be an opportunity here, the stock has fallen C9% today and is thru support and at a 5 year low.
Ah - must be it - but the tariff was 31% already - cannot believe the Swiss will sit back. On the other hand, cannot believe USA customs will allow Swiss watches shipped from UK to go through at 10% - The whole world would try that on!
The industry term is called trans-shipping.
Up to the American customs how they enforce it.... obviously with Rolexes, its hard to say "oh this batch were manufactured in the UK"
But for other goods.... especially non-branded ones....
Re UK & EU tariffs on exports to the US: Also according to today's Guardian, the UK's 10% tariff 'stacks,' i.e. is in addition to its previous average 3.7% Most Favoured Nation tariff rate for exports to the US - the new average tariff rate is in fact 13.7%; whereas the EU's 15% levy is not stacked - it replaces the EU's previous 4.8% MFN average export tariff on goods to the US. So the new tariff rates are UK: 13.7% on average vs 15% for most EU goods exports to the US, including, importantly, cars and car-parts such as engines.
Re US tariffs on imported Swiss watches: Trans-shipments incur a tariff of 40% according to today's Guardian.
I think SEGRO (LON:SGRO) is best in my view (share price has come off a lot lately, so I've purchased some). Tritax Big Box REIT (LON:BBOX) is also quite good and I have held this for a while. Londonmetric Property (LON:LMP) are excellent as the real estate consolidator vehicle, but they have other segments. This has been the hot sector for the last few years, but share prices have come off a fair bit as rental growth has slowed a tad. EDIT - agree with timarr!
TR Property Investment Trust (LON:TRY) are possibly the best real estate hold as they have a good long-term record.
SEGRO (LON:SGRO) is by some way the leader in this space and no idea why it's fallen so much - very good track record and strong rental growth potential yet discount is pushing 30%. Yield around 5% so getting paid to wait for a re-rate. Its size means that there is probably no prospect of a bid if that's what you're looking for but otherwise this looks a good option.
Are there any other Reits that are focused on warehouses like Warehouse Reit (LON:WHR)? Looking to do some research in this area. WHR was the obvious but now in the midst of a takeover.
SEGRO (LON:SGRO)
Have you looked at SEGRO - I hold. Interests in Europe too with more data centres on the agenda. Steady performer.
Are there any other Reits that are focused on warehouses like Warehouse Reit (LON:WHR)?
Sort of:
The first two are looking at datacentres as well, which dependent on your view, may be a good or a bad thing.
The smaller players such as Urban Logistics and Warehouse have been, or are being, taken over.
timarr
Supermarket Income REIT (LON:SUPR) - a warehouse with a shop attached.
Not that it's been a good investment to date in capital gains terms.
Supermarket Income REIT (LON:SUPR) - a warehouse with a shop attached ... Not that it's been a good investment to date in capital gains terms.
Nah, it leases properties to supermarkets. Safe as, well, supermarkets, but hardly going to shoot the lights out.
Up 20% for me, well off its highs, yield of over 7% pretty much guaranteed. Nice easy hold. Buy when the discount to NAV goes over 20%. Sp will rise as interest rates fall, but never going to be exciting.
timarr
Thanks everyone for the suggestions! That's my weekend sorted then :)
The Naked Trader live radio show starts from 8.30 this morning. Main show from 9am.
Tune in at this url press play button
fast.citrus3.com:8832/stream
Take part: whattsap 07950028120 / robbiethetrader@aol.com
You can take part with your best idea for a song title connected with trading £50 for the best and will play the best at the end.
Also what's your fave share and why or what's your worst disaster and what did you learn.. Anything goes.
Includes a look at cos reporting today inc IMI Pearson and intertek and a few from yesterday.
"Money for Nothing" Dire Straits....?
Is it possible to listen back later?
Check out his website, there should be a link on that.
With all the takeover activity happening in the UK market, 'another one bites the dust - queen'
S&P500 was sold off at the 6,400 resistance level yesterday. It's a brave call, but I'm calling the top of US markets on 31 July after stellar H1 results by the Ai Mag 7 and before todays tariff deadline. I could be wrong very quickly and look rather foolish, but "Nobody rings a bell at the top of the market".
Stock market crashes tend to arrive in September or October. August is usually a reasonably good month. I suspect this melt up has a few more weeks to go,
Not judging by markets past few days, AIM in particular
The small pullback after such strong results would indicate you might be right.
Oddly I was thinking the same thing this morning!
Hi Graham,
Thanks so much for all the hard work that goes into these updates, they’re incredibly useful to me and I appreciate them.
Just a small suggestion for the spreadsheet as you mention giving it an update later, would it be possible to order it alphabetically by company name? On busy days, it would really help quickly locate stock details. I usually search by ticker, which works fine too, but thought I’d mention it for you to consider.
Let's not push too hard, there's only so many minutes in an hour, Silverback.
Hi Silverback, thanks very much for the suggestion! I can certainly add the company names to the sheet, and then if you are searching by name you will quickly find whatever you're looking for.