Daily Stock Market Report (Fri 2 May 2025) - PSON, SHEL, GAMA, NWG, ROR, APAX, STAN

Good morning! After a busy week for company updates, let's see what the newswire has lined up for us today.
The agenda is now complete, with something of a big-cap bias today. Please share any requests for backlog items in the comments below.
11.30am: that's a clean sweep, so I'm wrapping up today's report. Thank you for reading and I hope you enjoy the long weekend. We'll be back with you on Tuesday.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
Shell (LON:SHEL) (£146bn) | Ahead of exps. Q1 adj earnings of $5.8bn (+52% vs Q4 24). Divi unch, further $3.5bn buyback. | AMBER (Roland) Q1 results have received a boost from the group’s core oil and gas production business. Shell has a clear strategy and seems to be executing well. A stronger balance than BP has allowed it to maintain aggressive share buybacks. However, earnings forecasts have been trending lower and macro uncertainty remains. Without taking a stronger and more subjective view on commodity prices, I think I have to remain neutral at current levels. | |
Natwest (LON:NWG) (£42bn) | Q1 adj profit +36% to £1,252m. Q1 return on tangible equity of 18.5%. Net impairment charge of £189m.2025 income and returns are now expected to be “at upper end” of guidance. | AMBER/GREEN (Roland) [no section below] Today’s Q1 results are ahead of consensus expectations, according to Reuters. CEO Paul Thwaite now expects full-year results to be at the upper end of expectations. Based on guidance for FY25 RoTE of 15%-16%, this implies the remainder of the year might not be quite as profitable as Q1. One reason for this might be the bank’s view on the UK economy, highlighted by today’s higher impairment charge. On a more positive note, the UK government’s holding fell below 2% yesterday, so NatWest is now fully under private ownership again, for the first time since 2008. The shares aren’t as cheap as they were, but the fundamentals look strong to me and the c.6% yield seems safe enough. I’m happy to maintain our moderately positive view on this bank. | |
Standard Chartered (LON:STAN) (£26bn) | Q1 adj profit +11% to $1,357m ahead of exps. Tariff uncertainty. 2025/2026 guidance unchanged. | AMBER (Roland) [no section below] Today’s update seems broadly positive, but highlights the “increased global economic and geopolitical complexity” resulting from tariffs. I don’t see any specific concerns, but StanChart is less profitable than rival HSBC and has much smaller scale. The shares are up >40% in 12 months and now yield under 3%. I’m inclined to take a neutral view at this level. | |
Pearson (LON:PSON) (£7.8bn) | Adj rev +1%, all units trading in line. Exp H2 weighting to growth. 2025 guidance unchanged. | AMBER (Roland) [no section below] Pearson reports sales up 1% in its core Assessment & Qualifications business (61% of FY24 profit). Performance elsewhere is mixed and this strikes me as a slightly weak update. Full year sales and adjusted profit guidance are unchanged today, but their delivery appears to be dependent on a stronger H2 performance. I note that consensus has trended lower over the last year. The profitability of this group is average (10% ROCE) but its shares trade on a P/E of 17. I can’t get higher than neutral and would personally be inclined to caution. | |
Rotork (LON:ROR) (£2.6bn) | Revenue “modestly lower” in Q1, order intake up by “mid-single digit” YoY. April trading in line. Tariff surcharge applied where needed. Mgt exp “year of progress”. | AMBER/GREEN (Roland) [no section below] The industrial flow control specialist says it has three US plants which represent c.20% of total sales and can supply “the majority” of local demand, presumably minimising the impact of tariffs. | |
Gamma Communications (LON:GAMA) (£1.2bn) | Gamma has moved its listing from AIM to the Main Market. This process has now completed. | GREEN (Roland) [no section below] Entry into the FTSE 250 later this year looks likely for Gamma, as far as I can see. This could bring the stock into more mainstream active and passive funds - although checking the shareholder register, a number of major institutions are already present. Personally, I see this move to the Main Market as a mild positive, but not in itself a reason to buy or sell the stock. I’m happy to leave Megan's positive view in March unchanged. | |
Apax Global Alpha (LON:APAX) (£573m) | Q1 NAV -5.7% to €1.16bn. Total NAV return +0.5% at constant FX. Expect only minor tariff exposure. Average TTM EBITDA growth of 16% in the underlying private equity portfolio. Valuations “generally flat overall”. | AMBER (Roland) [no section below] This investment trust provides exposure to Apax private equity funds (focused on tech, services and internet/consumer) and a portfolio of debt investments. NAV fell in Q1, although this appears to have been largely driven by USD dollar weakness. This offset earnings growth in underlying PE funds and impacted the reported value of the trust’s USD debt investments. At 119p, the shares trade at a 40% discount to today’s reported Q1 NAVps of 200p and offer a 9.3% dividend yield. I haven’t looked at this trust in detail and am not familiar with the underlying Apax PE investments. I think the main risk in PE currently is that valuations could gradually drift lower as owners are forced into realisations. However, my initial impression is that Apax Global Alpha could offer value and may be worth further research. |
Shell (LON:SHEL)
+3.5% to 2,520p (£151bn) - Q1 Results - Roland - AMBER
Today’s results from oil and gas giant Shell appear to be 12% ahead of consensus estimates, according to figures commissioned by Shell:
Q1 2025 forecast adjusted earnings: $4,963m
Q1 2025 actual adjusted earnings: $5,577m
The group’s Q1 earnings were 27% below the Q1 2024 but were 52% higher than in Q4 2024. Market convention is to use year-on-year comparators, and in most cases I think this is more useful. But for a largely unseasonal commodity producer with heavy exposure to commodity pricing, I tend to think that sequential comparisons are more meaningful.
Checking through the detail of the consensus estimates, more than half the outperformance was driven by the group’s core upstream (oil and gas production) business. Refining, Integrated Gas (LNG) and marketing delivered smaller beats to analysts estimates.
In reality, I suspect the improved quarter-on-quarter performance is due to Shell’s heavy gas exposure. Courtesy of Trading Economics, we can see in this chart that natural gas prices strengthened in Q1 versus Q4, helping to offset weaker oil prices:

Shareholder returns: Shell has announced another $3.5bn quarterly share buyback today for Q2, while the group’s quarterly dividend has been left unchanged.
CEO Wael Sawan said earlier this year that the company’s dividend is sustainable down to an oil price of $40 per barrel, while buybacks can be sustained down to $50 per barrel, so these shareholder return plans are consistent with this.
Balance sheet: Q1 adjusted earnings of $5.6bn were converted into $5.3bn of free cash flow, according to the company. This was consumed by cash outflows on buybacks ($3.3bn) and dividends ($2.2bn) during the period.
As a result, Shell’s net debt rose by $2.7bn to $41.5bn as the company funded working capital movements and payments relating to the acquisition of Singapore LNG trader Pavilion Energy.
Gearing rose to 18.7% during the quarter, but this remains well below the figure of 25.7% reported by BP earlier this week. I don’t see Shell’s gearing as a concern; as well as being lower than at BP, in my view Shell also has a stronger record of financial discipline.
Outlook: Shell is maintaining its spending plans and reiterated guidance today for capital expenditure of $20bn to $22bn in 2025 (2024: $21bn).
As far as I can see, full-year earnings expectations are not changed significantly by today’s results. However, it may be worth noting that earnings have trended lower over the last year. Macroeconomic uncertainty and recent falls in energy prices could maintain pressure on forecasts, potentially.

Forecasts suggest modest valuation multiples, albeit in a sector where this is the norm (in the UK, at least - CEO Sawan hopes to close the valuation gap with US majors):

Roland’s view
Today’s results from Shell compare favourably to those of UK-listed rival BP, whose first-quarter results came in below expectations on Tuesday (see our coverage here).
In my view, Shell has generally been better run and benefited from a more consistent and coherent strategy than BP over the last 20 years. This has been reflected in the two companies' share price performances:
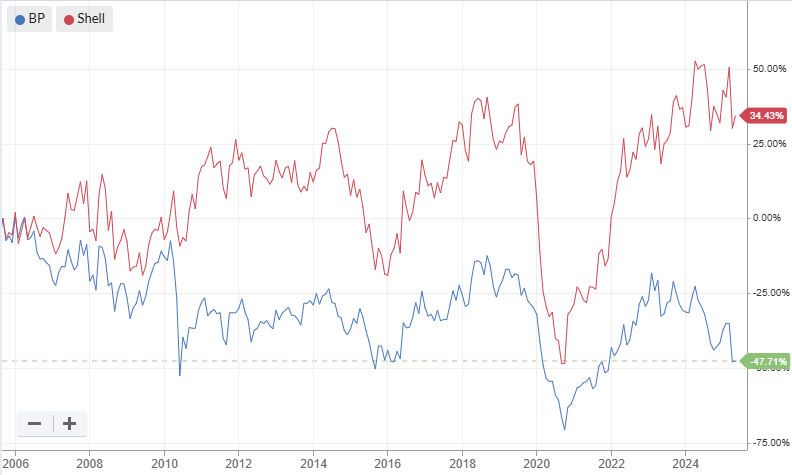
Stockopedia’s algorithms style Shell as a Contrarian stock, due largely to its weakening momentum:

I might normally be tempted to take a moderately positive view here, given Shell’s strong execution, reasonable valuation and rapidly-diminishing share count. However, given the erosion to earnings forecasts and external macro risks, I think a neutral view is more sensible at the moment.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
Berkshire Hathaway (NYQ:BRK.A) Warren Buffett has announced his retirement, I’m a big fan of. Great track record in business and he hasn’t seemed to have been involved in some kind of scandal despise all his wealth and years in the spotlight.
Let’s see if he makes a few more moves with his cash pile before standing down later this year.
Here is the link announcing Warren Buffett's retirement:
https://www.bbc.co.uk/news/art...
As a bank holiday weekend special offer for investors who have never been to a Mello two day conference we are providing one day taster access for just £30 and the offer lasts until midnight on Tuesday but limited to 12 tickets
https://melloevents.com/mello2025 Just apply code NewMello25
4imprint (LON:FOUR) - I was wrong on the de minimis exemption. See below:
https://mattbrazier.substack.c...
But presumably if the tier 2 and 3 suppliers are based in China (and lots of them will be), they will have to pay the hefty tariffs to get the blank product into the US in the first place.
yes, but that is also true for all the competition. It would be more concerning if until now FOUR had been getting a benefit from de minimis versus its competitors and that this might at least partly explain how it has consistently won market share.
Edit: Hadn't seen sparklers post as I was preparing this. Apologies for the repetition.
Despite the weather forecast, here's something to (hopefully) cheer us all up today. Reported on CNBC today.
While global markets have been gripped by turbulence in the wake of U.S. President Donald Trump's seesawing tariffs policies, British stocks have enjoyed a bumper rally. London's FTSE 100 index, which has gained more than 5% since the beginning of the year, rose by 1.25% on Friday. It marked the fifteenth consecutive day of gains for the index, its new longest run ever.
As we end the week with the FTSE 100 registering its fifteenth consecutive daily rise (yes, you did read that correctly!) it provides another reminder of the perils of market timing. Three weeks back several posters on this site were talking up how pleased they were to have sold as markets fell and that they were now staying in cash for the foreseeable future. In the horribly grim market at that time this all sounded like a perfectly sound strategy........ until suddenly, and with no obvious catalyst, it wasn't!
I am absolutely not immune to bad stock selections myself and have suffered with two or three of those in recent weeks. Luckily, what I didn't do was compound those individual mistakes by trying to be clever with the market as a whole. No doubt there are many subscribers now sitting in that uncomfortable place where they are holding too much cash but can't bring themselves to jump back in to their favoured stocks at prices now considerably higher than where they were sold. Painful isn't it?
My advice. Work out what amount you are comfortable to keep in the stock market for the long-term and then stay fully invested.
Further to my earlier post I have bought an opening position in Restore (LON:RST). Unexciting perhaps, but Charles Skinner, CEO knows the business inside out and like many small caps it is hardly expensive.
The share price is starting to tick up and there has been significant buying by management. Most notably Charles Skinner bought 100,000 shares at 280p last August and more recently spent a further £100,000 acquiring 44,438 shares at 225p. CFO, Dan Baker has also been a buyer, spending £150,000 on the shares between November 2023 and August 2024. More recently he purchased a further 25,000 shares at 224p.
I like it when senior management spend their own money on shares as opposed to nil cost options.
Seems the markets like the idea of PM Farage.
/s
Yes that’s the reason
Not the payrolls!
I suspect it is more the 'comparative cheapness' of the UK market and likelihood of interest rate cuts rather than Mr Farage and his political aspirations that is providing a tailwind for UK equities. Helped by the economic uncertainty and lack of political leadership in America
As oft said careful what one wishes for!
Sounds like Serica Energy (LON:SQZ) Enquest (LON:ENQ) deal is not happening?
Looks like Serica shares holding up well and Enquest starting to tumble a bit, normal I guess due to the reverse nature of the acquisition, Enquest had maybe been up a bit as it was expected Serica would pay some level of premium to take it on
I am long Serica and perfectly happy with the decision, much less uncertainty ahead by not doing it, doesn't feel the time anymore to do something big like this, too much uncertainty in the world already
Don't know if the writers will have time to say anything about it this late in the day but would be curious to see their thoughts next week
Useful write-up on Shell (LON:SHEL) , thanks for this.
Re Warpaint London (LON:W7L)
I've been scratching my head a bit on the recent results and trading update/outlook for Y/E'25
Easier to bullet point
SALES - Y/E 12 '25 Forecast of £128M ('24 Y/E £101.6M) using all current forecast/info looks too high even with the inclusion of Brand Architeks. Equates to +26%, but Q1 currently only +14% albeit against a strong comparator in Q1 '24. However management are NOT given to overstating co's prospects/forecasts.
PBT Y/E 12 '25 forecast increase +18% and EPS forecast +10.6% BOTH seem too LOW especially given the excellent operational gearing - see this in action in Y/E12 '24's results
GROSS MARGIN - Increases from 39.9% to 41.2% for Y/E '24
OPERATING COSTS Up in '24 vs '23 a modest 1% - amazing given levels of growth achieved
DEBT None, nett cash, even after the acquisition of BA and the extra £ that must be needed for ever expanding working capital requirements and increased Tax payments - see below
STORE ROLL OUTS Big numbers of new stores in Europe, USA, UK with Denmark, Spain and the Netherlands seeing significant sales growth all +20%. UK expansion into Tesco, Morrisons, Superdrug, Boots
ONLINE SALES +35% with fulfilment in many countries via Amazon
TARRIFFS Majority of product is made in China but US Sales are only c8% of all sales so any 'damage' would surely be minimal but could be another reason forecast sales are not achievable
CONCLUSIONS From all the info I have read so far I find it hard to accept that the 12/25 Sales figure of £128M can be achieved, However I'm not sure this matters as the forecast EPS and PBT figures definitely look beatable, unless I am overlooking something?
ADDITIONAL THOUGHTS
Store roll outs must cost money for new displays etc - so may see costs increase but can't imagine this is massive and has been going on for a number of years anyway
Working Capital requirements are clearly going to increase but again at what cost? Co is nett cash and so will only be a 'loss' of interest income, which is probably quite minimal
Can anyone add any further thoughts here? Am I missing something glaringly obvious? I know that the Corporation Tax Rate & HMRC payments schedule have been increased/changed due to the size of the business and so will clearly affect net cash held, PAT & EPS but again nothing too onerous...
Warpaint London (LON:W7L)
That have raised all the amount for the acquisition of BA; something that made me think twice at the time having in mind that BA had half of that in cash!
All the best
Mind you Yiannos with the benefit of hindsight a 510p strike price at a 2.5% discount to the then market price and only c4% dilution compared to today's sp at 380p looks like pretty good business to me?
Also I'm guessing that working capital needs and some decent dividends are chewing through cash at a fair lick?
Looking at elf Beauty (NYQ:ELF) makes me more sceptical than ever.
The acquisition of BA does not make any sense. £14m kept for the acquisition it seems that Warpaint London (LON:W7L) is not generating anything meaningful.
Biggest shareholders offloaded £M at much higher prices. Might have a short term bounce but the future is not bright. Growth not sustainable.
All the best
Some shares I have been watching.
Kitwave (LON:KITW) The share price continues to tick up and has formed what Richard Crow refers to as a nice bowl. Also there has been good director buying recently. I like the business in that it is easy to understand and replicating its logistics and geographical coverage would be very difficult in my view. Debt is higher that I would like but should fall as the recent acquisitions began to contribute. I have a reasonable size holding and am now close to break even having added a few recently.
MPAC (LON:MPAC) I have a modest holding bought around 410p as the price declined. Again I like the business and the trend towards automation and am tempted to add, but what puts me off is the almost complete absence of director buying. I am not sure how many shares Adam Holland, the CEO holds but it is pretty minimal. Again debt is somewhat on the higher side of what I would like.
Restore (LON:RST) Again a business that is easy to understand and in the nicest sense of the word 'boring'. Contrast with MPAC (LON:MPAC) there has been persistent director buying. I am tempted to join them.
All of the above are inexpensive, PEs of 10 or less, but one needs to be cognisant of debt. MPAC (LON:MPAC) doesn't pay a dividend.
Kitwave (LON:KITW) should have a trading update shortly.; next week I would think.
Happy to hear views for and against any of the above.
MPAC (LON:MPAC) unexpectedly now a Value Trap....I think an anomaly. Lack of any flag-waving from Directors is a concern. Seems good value at this level, without the trap.
The Phoenix was asking Graham for an opinion on 4imprint (LON:FOUR) yesterday and I have posted here about the stock previously. I have changed my mind on the company and you can find my revised view at the following link for anyone interested:
https://mattbrazier.substack.c...
Great write up Matthew thanks for flagging.
Hi Matt, I appreciate your wish to behave ethically BUT can see no reason why you should not do all your selling (in this case) before releasing your 4imprint (LON:FOUR) research to your substack. After all, you did the research and should be the primary beneficiary of it. You owe the rest of us nothing
Thank you for that, shanklin100.
I have a tendency to change my mind often and overtrade. This could create a conflict of interest when combined with writing about stocks, particularly when they are small and illiquid as many of those which I trade and write about are. I want to steer as far away as possible from any hint that I might benefit from people following me into trades, and only trading following a delay after publishing seems like the best way to achieve this.
You might say that a better way would be not to write at all, but I enjoy writing and see it as a way to showcase my work as well as bring discipline to my investing process. Perhaps it will turn into a paid subscription service one day, but right now I'm just seeing how it goes. I also see it as a way to build a network - being a full-time private investor can be quite solitary.
I'm pretty sure that no one is following me into trades currently as I don't have many subscribers and hope (and suspect) that my readers are independently minded in any case, but I'd rather try and avoid the possibility altogether. Enforcing a lag between deciding to trade and executing might also help to reduce overtrading!
Thanks for the write up on 4imprint (LON:FOUR) I actually made the opposite move, recently buying. I think there is a fair chance of another profit warning in the near term (possibly a big one if we see significant disruption such as you have described), but prepared to sit this out as feel this should blow over quite soon and FOUR should emerge stronger in the long-term as weaker competitors fail. Only a small position though as I expect this to remain volatile.
Paul Scott has also recently bought a small amount as have I, like yourself the start of a long term hold for me so dipping my toe in now to watch.
We are entering the traditionally poor summer season.
I show the FTSE All Share index percentage price change for each month in chart 1.
Chart 2 shows the probability of a price rise in each month.
These are averages from 1970 to 2022 inclusive.
Strong support for the old adage, Sell in May, Go Away until St. Ledgers Day.
For those interested I have a book on stock market seasonality, it covers this and a range of other seasonal patterns. On Amazon, called 'The Seven Secrets of the UK Stock Market'.
I have posted yesterday the May performance for the S&P for the last ten years. No need to post it again.
You are missing the very important point that we already had one of the worst and violent corrections in history in April.
There are plenty of opportunities in both the US and the UK at the moment.
There are companies over the pond they will be growing their revenues at 25%+ CAGR for at least the next 10 years
Robinhood Markets (NSQ:HOOD) is just one of many.
All the best
100% Yiannos
I see opportunity and good looking charts all over my screens currently, hitting the nail on the head with your comment on last months activity
I'm glad we still have some sanity on this board
Callum
Watch out for a personal view of Aurrigo International (LON:AURR) a little later. Not surprisingly, I view it as a big British opportunity though it is apparently small beer at the moment. Heard that before? Well you will hear it again later.
The Assura (LON:AGR) bid situation is becoming very interesting as the deadline for the PUSU for Primary Health Properties (LON:PHP) bid looms - it's 5 May.
As a reminder, Assura (LON:AGR) are currently recommending a bid from KKR & Co (NYQ:KKR) which effectively means 48.56p per share in cash.
The Primary Health Properties (LON:PHP) last bid was for 0.3848 PHP shares and 9.08 pence per share. Since the tariff sell-off, the PHP share price has climbed significantly and as of this morning, with PHP trading at 102.84p, this offer is equivalent to 48.65p for every Assura (LON:AGR) share.
Which is probably why the Assura (LON:AGR) is trading slightly above both offer prices this morning.
Thanks for this reminder Tortoise - would be ironic if Assara agrees to go with PHP and KKR comes back with an offer to take the newly combined company which at current levels would still be a bargain.
Meanwhile another interesting situation looms- Kenmare Resources (LON:KMR) and possible offer from consortium led by former CE - deadline extended to 15th May
AGR. They might have chosen a deadline day that was not a public holiday...
Whats the likely impact on Gamma Communications (LON:GAMA) given the move to main market? Assuming any index trackers/ETFs would have to hold some of the shares now?
entry into fste250 in september at current market cap,
Would ftse 250 entry not happen in the next review in June or is there a rule that prevents this?
That’s a good question the SP has dropped nearly 25% since the announcement but it’s been a chaotic period generally.
Guessing that funds who held for IHT reasons will have to sell, but no garentee that will occur before the move I guess.
Neil - the IHT rules dictate that shares must be held directly by the person - not through a 'fund'. There are a couple of schemes out there which comply but its very limited so doubt there will be much effect on the SP. On the other hand - I am guessing many who held for IHT will hold on anyway simply as a mainstream holding.
Neil - the IHT rules dictate that shares must be held directly by the person - not through a 'fund'. There are a couple of schemes out there which comply but its very limited so doubt there will be much effect on the SP. On the other hand - I am guessing many who held for IHT will hold on anyway simply as a mainstream holding.
You're right about the fact that shares must be held directly for BPR, but there is an impact. Take Octopus, for example, where this impacts their nominee AIM IHT ISAs and their VCTs as well as their managed funds, where shares are held in the name of the shareholder but are still managed by Octopus for IHT purposes (and therefore will have been sold).
Octopus directly held 8% of Gamma Communications (LON:GAMA) as well as an unknown percentage of directly held managed shares before the main market announcement. Their direct holding has now been liquidated as, presumably, has been their managed holding. That's not insignificant and must have had some impact on the share price.
timarr
Hopefully Gamma Communications (LON:GAMA) share price will initially move upwards based on the index trackers purchases. I'm sure that there will have been a lot of sells based on the AIM IHT changes so all those sellers are now gone. SThree (LON:STEM) initially did really well when it first moved across.
I would expect the price to increase as it gets included in the index at least in the short term, see
My tuppence worth : as has already been noted, Octopus was the largest holder of GAMA when GAMA announced the move to the main market. I believe they had to sell down before today. That meant there was a deadline to meet. Any professional knowing all of this and looking for a good entry price would be unlikely to buy much before the deadline, meaning liquidity for Octopus would not be good thus exaggerating the price drop. A few weeks ago GAMA announced a 50 million pound share buy back. Those shares were largely to be cancelled. So there is now a lower share count, down several percent, which should add positively to the value of each share going forward. It also allowed Octopus to complete selling. Key dates over the next couple of months - end of May ftse quarterly index rotation will be announced and it is likely GAMA will be included in the ftse 250 index. I expect that move would be effective as of the end of June. Further, there is an ex-div date at the end of May. Some of these events may result in share price appreciation. Finally, there will be an AGM on May 14th and in previous years this has been accompanied by a trading update.