Daily Stock Market Report (Fri 20th March 2026) - ULVR, JDW, WRKS, DFS

Good morning and welcome to Friday's report.
Update: I've added a section on DFS from the backlog.
That's all we have time for today - thank you for all your comments this week. I hope you enjoy the weekend.
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Unilever (LON:ULVR) (£100bn | SR57) | Confirms press speculation that the company has received an inbound offer for its Food business and is in discussions with McCormick & (NYQ:MKC). | AMBER/GREEN = (Roland - I hold) Today’s news continues a run of media speculation this week about a possible disposal of the Food business. As a shareholder, my view is that this would probably be neutral or positive for the business, so I’m leaving my view unchanged today. | |
Smiths (LON:SMIN) (£7.3bn | SR65) | Agreed sales of Smiths Interconnect and Smith Detection for a total of £3.3bn. A further £1.5bn shareholder return will begin following the completion of the Detection sale later this year. Updates FY26 guidance to reflect sale of Smiths Detection; now expects organic revenue growth of 3-4%, with H2 growth of 5-7% and operating margin of c.20%. | ||
Gamma Communications (LON:GAMA) (£790m | SR60) | Appointed Damien Maltarp as CFO. He joins from LSEG and previously BT. Maltarp will join “at the latest in September 2026” - the current CFO is leaving at the end of March. The CEO will provide oversight of financial operations in the interim. | ||
J D Wetherspoon (LON:JDW) (£685m | SR43) | H1 like-for-like sales up 4.8%, revenue up 5.7%. Adjusted pre-tax profit down 31.9% to £22.4m. Wetherspoon has outperformed industry index but warns that cost pressures and consumer affordability may result in profits that are slightly below current market expectations. | BLACK (AMBER/RED =) (Roland) Today’s profit warning follows on from downgrades during the autumn and in January. While the valuation has become more modest, so has Wetherspoon’s profitability. I’m leaving our broadly negative view unchanged until some signs of stability emerge. | |
SDCL Efficiency Income Trust (LON:SEIT) (£493m | SR n/a) | Sale of a portfolio of assets to Kyotherm for up to c.£105m, a discount of c.9% to Sept 25 book value. This is expected to result in a c.1.2p reduction in NAVps. Day-one cash proceeds are expected to be c.£84m. This will be used to reduce debt, bringing pro forma gearing to c.65%. No change to FY26 target dividend of 6.36p. | ||
Cab Payments Holdings (LON:CABP) (£229m | SR46) | The Board has rejected the StoneX possible offer of 95p on the grounds that it “significantly undervalued CAB Payments”. | PINK | |
Atlantic Lithium (LON:ALL) (£142m | SR22) | Parliament of Ghana has ratified a 15-year Mining Lease for the Ewoyaa Lithium Project. Agreed royalties will apply from 5% to 12%, depending on Spodumene pricing. The lease allows the company to advance discussions re. funding and move towards a final investment decision. | ||
Smarter Web (LON:SWC) (£136m | SR18) | CFO Albert Soleiman has resigned with immediate effect and will step down following a handover period. He is thanked. The current Financial Controller and Head of Projects (& former CFO) will become interim CFO. | ||
Strategic Minerals (LON:SML) (£132m | SR43) | Metallurgical study shows a 19.2% increase in WO3 overall recovery to 85.8%. Recovery of silver has also been confirmed. | ||
Taylor Maritime (LON:TMI) (£113m | SR98) | Plans to undertake a further return of at least $30m in Q2 2026 by way of a partial compulsory redemption of shares. Company says a previously agreed $17m vessel sale has now been completed and confirms that it intends to continue the managed realisation of the company’s assets. | ||
Arrow Exploration (LON:AXL) (£64m | SR72) | Mateguafa 11 (M-11) well has been drilled to a total measured depth of 11,455 MD feet and has encountered oil bearing sands in the C7 and C9 Carbonera formations. Corporate production is approx. 5,325 boe/d. M-11 is expected to contribute additional production. New reserves report shows 10% reduction in 2P reserves to 20,102Mboe. | ||
Zenith Energy (LON:ZEN) (£42m | SR39) | Acquired additional agrivoltaic development project in Lazio, Italy, with an installed capacity of c.10MWp. Total consideration is €1.02m. | ||
Works co uk (LON:WRKS) (£23m | SR74) | Plans to cease trading online immediately; its website will become “non-transactional”. £2m of closure costs. Upgrades FY26 and FY27 EBITDA guidance for continuing operations to £13.5m and £15m respectively (previously £11m and £12.7m). | AMBER/GREEN ↑ (Roland) The company makes a simple and compelling case for shutting down its online sales and upgrades forward profit guidance as a result. Given the modest valuation and positive sales trends prior to today, I think it’s fair to upgrade our view by one notch. | |
Sound Energy (LON:SOU) (£18m | SR28) | Tendrara Gas Gathering Systems has been fully tested and commissioned. Entered into €1.3m term loan with 20% interest per 120 days to provide working capital prior to revenue from LNG sales from Tendrara. Also raised €0.5m in a placing at 5.0p per share (37.5% discount to last closing bid price). | ||
Ground Rents Income Fund (LON:GRIO) (£17m | SR9) | Sold freehold ground rent interests in Manchester and Southampton for a combined price of £4.58m. This represents a 0.6% discount to independent valuation and 5.3% net initial yield. Proceeds used to repay a secured loan. Further disposals are progressing. | ||
Power Metal Resources (LON:POW) (£15m | SR57) | Investing $1m for 2.6% in Next Minerals S.A., a Chile-based copper mining company. Deal provides exposure to the “mine-ready Comahue underground copper mine” in the Antofagasta region of Chile. | ||
Plexus Holdings (LON:POS) (£9m | SR20) | Received orders from a UKCS operator that “will lead to about £1.5m of work” under the recently announced framework agreement (13 Nov 25) for rental wellhead services. Revenue is expected over a 12-month period, subject to rig scheduling. |
Roland's Section
Unilever (LON:ULVR)
Up 1.3% at 4,631p (£101bn) - McCormick & Co - Response to media speculation - Roland - AMBER/GREEN =
(At the time of writing, Roland has a long position in ULVR.)
News that Unilever is considering a sale of its entire Food business (including Hellmann’s, Marmite and Knorr) probably shouldn’t be a complete surprise.
The group has already spun out its ice cream and spreads businesses in recent years. CEO Fernando Fernandez has made it clear his focus is on expanding the faster growing and high margin Personal Care and Beauty operations.
Here’s what we know about this story so far:
Tuesday 17 March: Bloomberg reports that Unilever is considering the separation of its food business.
Wednesday 18 March: The FT reports that Unilever has held discussions with Kraft Heinz Co (NSQ:KHC) on a “megamerger of their food brands”.
Thursday 19 March: Unilever confirms that the company has received “an inbound offer” for its Foods business from US food group McCormick & (NYQ:MKC).
Unilever confirms that it has received an inbound offer for its Foods business and is in discussions with McCormick & Company, Inc. There can be no certainty that any transaction will be agreed.
Talks appear to be at a fairly early stage and Unilever’s management is careful to tell us how much they still like the Food business:
The Board believes Foods is a highly attractive business, with a strong financial profile led by market-leading brands in growing categories and is confident in the future of the Foods business as part of Unilever.
Roland’s view
Unilever’s business has always been distinguished by its heavy exposure to emerging markets, where competitive pressure from cheaper supermarket own brands is lower and the power of food brands is still stronger.
Even so, I think there’s no avoiding the direction of travel in this sector. While my household still purchases Marmite and Persil, there’s no doubt our kitchen contains more supermarket-branded food products than it did in the past. That’s less true in the bathroom cupboard, perhaps providing anecdotal support for the group’s strategy.
Unilever has also already disposed of some of its lower-quality and slower-growing food operations. The remaining Food business generated an attractive 22.6% operating margin last year, but was still the slowest-growing part of Unilever’s business when measured by revenue or volume growth:
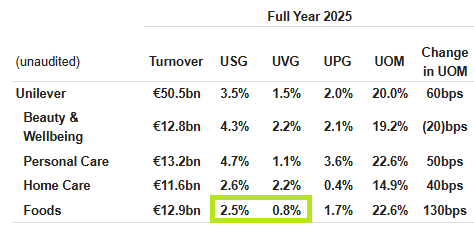
Estimates from analysts at Jefferies quoted in the FT today have suggested the Foods business could command a valuation of $36-37bn.
Selling such a large element of the business would leave the group looking very different. However, given that McCormick is a much smaller business (market cap c.£11bn) I wonder if the deal might be structured as a reverse merger, leaving Unilever shareholders (once again) with a stub of shares in the spun-out entity.
This is all speculation for now – but as a shareholder, my general view is that a disposal of the Food would probably be neutral or positive for the business. Given the recent share price pullback, I don’t see any reason to change my previous AMBER/GREEN view following today’s news.
J D Wetherspoon (LON:JDW)
Down 12% at 552p (£608m) - Interim Results - Roland - BLACK (AMBER/RED =)
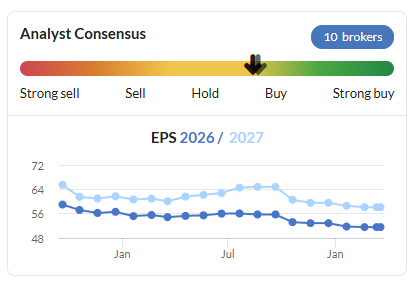
Unfortunately it’s another profit warning today from this popular pub chain, following a downgrade in the autumn and a further cut to expectations in January.
Chairman Tim Martin was more explicit in his guidance than he sometimes is – possibly not a good omen:
There is clearly considerable pressure on consumer finances, combined with higher taxes, wages and energy costs for the hospitality industry. This may result in profits that are slightly below current market expectations.
Wetherspoon shares are down sharply today, but our view has always been that this is a well-run business with attractive scale. Do today’s half-year results provide any hope that value may be emerging here?
Half-year summary
I think the underlying trends highlighted by today’s interim results can best be described as mixed. On the one hand, sales performance was positive:
Revenue up 5.7% to £1,087.8m
Like-for-like sales +4.8%
Bar sales +7%
Food sales +1.3%
Slot/fruit machines +8.9%
The company also says it has outperformed an industry tracker index for the last 42 months, maintaining this record in February. This could suggest Wetherspoon continues to take market share, or at least has better pricing power than peers:
NIQ RSM Hospitality Business Tracker Feb 26: Pub Groups LFL 1.0%
Wetherspoon Feb 26 LFL +3.2%
Slightly oddly, I notice that Wetherspoon doesn’t appear in the list of participants for this industry survey.
Unfortunately, a 5.7% increase in sales over the last six months was not sufficient to cover the 7.3% increase in operating costs over the same period. Profits fell sharply:
Adjusted pre-tax profit down 31.9% to £22.4m
Operating margin 4.9% (H1 25: 6.3%)
Adj earnings per share down 27.9% to 15.5p
Interim dividend unchanged at 4p per share
The commentary in today’s report makes it clear the problem of rising costs outpacing revenue growth is a long-running trend:
At the same point in FY19, sales per pub were 35.4% higher in H1 2026 - above inflation.
However, energy costs are 80% higher than in H1 FY19 and wage costs are said to be 61% higher than they were then.
The company claims the pub sector has lost around 15% of its beer trade since the pandemic. This is perhaps more challenging for Wetherspoon’s value-and volume driven business model than it might be for some premium operators.
Property & Capital expenditure: changes to the group’s pub estate were limited during the period, with six pubs opened and six closed. At the end of the period, 794 managed pubs were trading, with a total of 15 expected to open during the financial year.
Wetherspoon’s is also continuing to expand its franchised estate. Eight franchised pubs opened during the half year, bringing the total to 16. Around 15-20 are expected to open in the current year. Franchised pubs are said to “have performed well” and could potentially improve Wetherspoon’s profitability, given their capital-light nature.
Outlook
I don’t have access to updated broker forecasts today, but the c.10% drop in the share price this morning suggests to me that consensus earnings could fall by a further 5% or more.
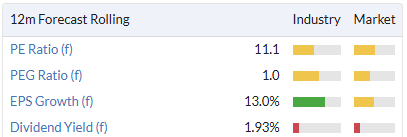
My guess is that the stock’s forward valuation is likely to remain broadly unchanged. The current rating is below JDW’s historic average P/E, but I think this may be justified by weaker profitability and the uncertain outlook:
Roland’s view
Today’s results highlight the long average tenure of the company’s pub and kitchen managers (15.7 years and 11.7 years respectively) and other employer quality metrics such as high food hygiene scores and Top Employer ratings.
I continue to see this as a well-run business, but there’s no escaping the pressure this business model is under at the moment from rising costs and pressure on consumer finances.
I think the company’s focus on the value end of the market may not be helping in this regard – JDW shares have underperformed big listed peers over the last five years:
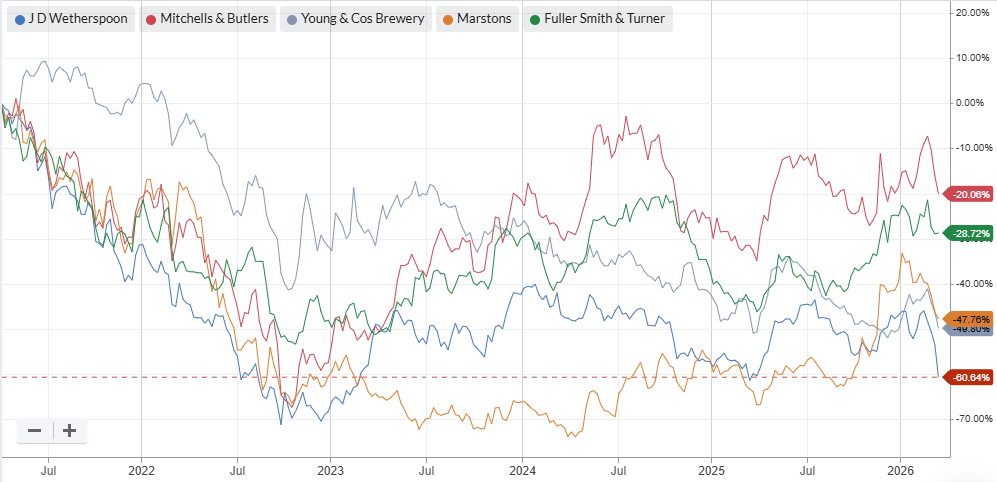
I’m relieved to see Graham downgraded our view to AMBER/RED in January, since when the share price has fallen by a further 20%.
I’m going to leave that view unchanged today to reflect the continued decline in profitability.
However, if Wetherspoon can deliver on revised guidance over the remainder of the financial year (y/e July), then I’d hope that we might be able to return to a neutral view later in 2026.
Works co uk (LON:WRKS)
Up 19% at 44p (£28m) - Update regarding online proposition - Roland - AMBER/GREEN ↑
This is a fairly unusual announcement – a retailer announcing that it is stopping online sales and upgrading its profit guidance as a result.
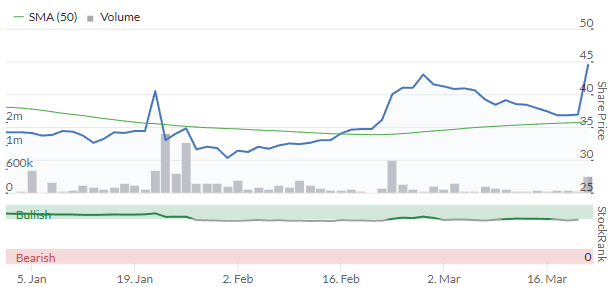
Today’s news from The Works has received a rapturous reception from investors. It’s not hard to see why. As Mark discussed in January, we already knew that store sales were outperforming online after two consecutive years of online logistics issues.
This update makes the case for abandoning online sales even more clearly:
Since launching online in 2012, 90% of sales have still come from “its profitable estate of more than 500 stores”.
Operational problems experienced with two different third-party fulfilment partners over the last two years have “outweighed the progress made” with online sales.
Given the “small and reducing revenue contribution and loss-making performance” of online, the Board has decided the online channel “is no longer sustainable”.
With immediate effect, The Works’ has now moved to “a non-transactional website”. A quick check this morning shows this has already happened – price information is available together with a find your local store facility.
New trading model
The company’s website will act as an online shop window for the business. Closure of online operations is expected to reduce operating costs and sharpen the focus on the group’s store estate, which is expected to expand further:
The store estate offers significant growth potential, with ongoing like-for-like (LFL) sales growth and scope to expand the Group's footprint by a further 100 locations. A net 5 new stores are set to open in FY26, with a further 10 planned for FY27.
Outlook & Upgraded Guidance
This is where it gets exciting.
Management says that like-for-like sales are up by 3.3% for the year to date (y/e 30 April). This is expected to support a FY26 pre-IFRS 16 Adjusted EBITDA of £11.0m in line with current market expectations.
Checking back, the equivalent EBITDA measure for FY25 was £9.5m, so it seems The Works is able to generate profit growth from much lower sales growth than JD Wetherspoon (see above).
The closure of online is expected to result in around £2m of exceptional costs.
However, once these have been adjusted out, the profitability of the remaining business is expected to improve significantly. As a result, EBITDA guidance has been upgraded today:
FY26 guidance for continuing operations is restated to pre-IFRS 16 Adjusted EBITDA of £13.5m (+23% vs £11m previously).
FY27 Adjusted EBITDA guidance is upgraded to £15.0m (+18% versus £12.7m previously).
Roland’s view
While adjusted EBITDA is not the same as actual earnings, today’s upgrades appear to provide a reasonable level of support for this morning’s c.20% share price rise.
With the stock trading on a FY26E P/E of 6 prior to today’s news, I think it’s probably fair to say that the shares may remain reasonably valued. If the company’s store-only strategy performs as expected, then I think a further re-rating may be possible.
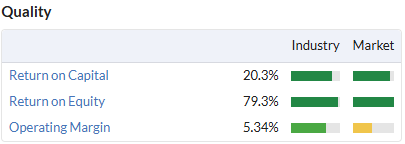
The Work’s capital-light model means that its quality metrics are strong, so cash generation could also be good when the drag from online is eliminated:
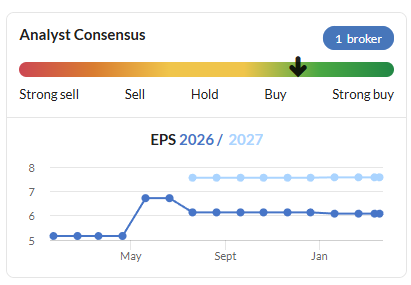
Today’s upgrade should also create a more positive trend in earnings forecasts:
Mark was neutral on The Works in January, largely due to the continued problems with online sales. Given the strength of today’s upgraded guidance the removal of the drag from online, I think it’s reasonable for me to move our view up by one notch to AMBER/GREEN today.
DFS Furniture (LON:DFS) (Backlog)
Unch. yesterday at 149p (£365m) - Interim Results - Roland - AMBER =
Furniture group DFS reported half-year results on Thursday that appeared to be in line with expectations. Although the share price was largely unmoved on the day, the stock has been a big casualty of the recent sell-off in consumer stocks:
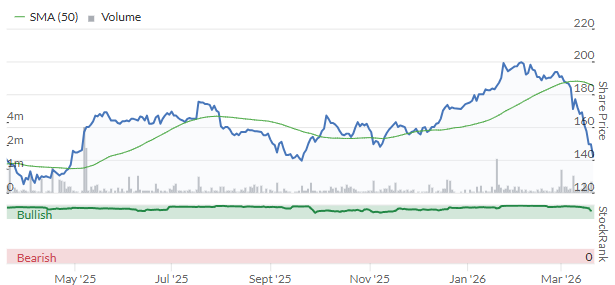
Graham turned neutral at a higher price in January, admitting that DFS’s strong H1 profit growth and reduced net debt meant the picture had improved significantly.
He also noted that “if a furniture group like DFS is doing so well […] UK consumer sentiment cannot be as bad as some companies would have us believe”.
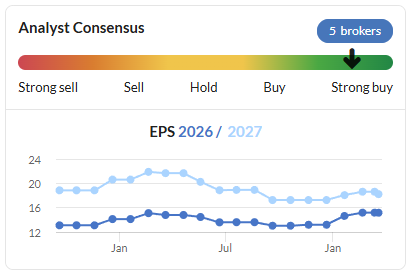
January’s update included an upgrade to full-year guidance that lifted FY26 EPS estimates by 15% to 15.2p:
Half-year summary
This week’s interim results leave full-year guidance unchanged but do provide a little more colour on recent trading. Here are some of the main points:
Revenue up 8.6% to £547.7m
Order intake growth YoY: 2.3% (H1 25: +10.1%)
Gross margin up 1.1% to 57.8%
Pre-tax profit up 92% to £30.3m
Adj EPS up 85% to 9.8p
Net debt reduced by £56.1m to £60.6m
Leverage multiple of 0.8x (H1 25: 1.6x)
The increase in H1 profit is certainly very impressive, although order intake appears to have slowed since last year.
However, one point I’d make is that the company admits working capital timing means actual leverage at the year end was 1.0x – the top end of DFS’s target range of 0.5x - 1.0x.
Personally, I would prefer this business to target a net cash balance (like its delisted peer SCS) to reflect the risks associated with the huge negative working capital position on the balance sheet:
H1 inventories, receivables and cash: £89m
H1 trade payables: £245.8m
If orders slow, DFS will stop receiving cash upfront from customers but would still need to unwind its outstanding payables.
This may not happen if trading remains stable, but management commentary suggests there could be some risk of weaker trading in H2:
Since the half year we have seen some softening in footfall linked to adverse weather conditions over the period and consumer confidence remains delicately balanced.
Outlook & Guidance
DFS left its upgraded guidance from January unchanged this week:
We remain focused on executing our strategy and in combination with our disciplined approach to gross margin and cost management we are comfortable reiterating our guidance of full year PBTu(A) in the range of £43-50m. This assumes no material supply chain disruption resulting from current geo-political events impacting the timing of delivery of customer orders.
This guidance implies H2 pre-tax profit of between £12 and £19m, compared to £13.3m for the same period last year.
Consensus FY26E EPS of 15.2p puts the stock on a forward P/E of <10 after recent falls, potentially unemanding for a business where returns on capital have now returned to >10%.
Roland’s view
Given the improvement in H1 profit, I guess that achieving a similar result in H2 shouldn’t be too demanding. However, there’s a strong seasonal bias to H1 in this business so I’m not sure how certain this is.
There might be a case for upgrading our view to be more positive, especially as DFS currently enjoys a decent StockRank and Super Stock styling.
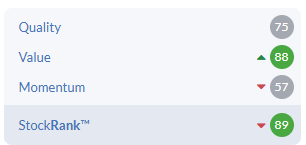
However, like Graham I am not entirely sure how robust profits are here and would prefer to see a stronger balance sheet. On balance I am going to remain neutral today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

88 comments
Hi Yiannos, I really hope so, for everyone's sake!
On the other hand, someone (who sadly has left Stocko) predicted $150 dollar a barrel oil by April and appears to have been nearer the mark... https://x.com/LogWeaver/status...
So much for a quiet Friday then, it's flying out of the window.
I've moderated one comment by Yiannos and one comment by Alastair. I don't want to pick sides here, and have just one suggestion: if you're not getting along with someone, please just stop directing comments at them. This is a place to talk about investments, not each other. Thank you.
I'm sorry to see the disruption that's happened here, various comments should have been moderated. Apologies to all involved.
Yes, Stocko should have blocked this.
The list of members who have made considerable contributions and improved my investment knowledge and market insight is a long one. This includes all those present over the last few days. Each have their own approach and style that adds to the Stocko experience. I would hope that all involved continue to contribute.
Turns out even sensible people on an investment forum can end up descending into personal insult nonsense.
Humans eh?
Roland, I'm suprised you hold Unilever (LON:ULVR)
A quick glance at the Stockreport tells me, here is a company with static turnover, a Stockrank of just 58, PE 17 and a yield of 3.5%
Not only that, its net debt is monster and they are considering to offload large parts of the business.
OK, the chances of going out of business are slim but there must be - there are! better investments.
In case this comment upsets - Stocko is great and worth every penny!!!! lol as they say.
Works co uk (LON:WRKS) management are coming to Mello2026 on the 2nd June. They will be exhibiting and presenting to investors twice on the day.
Tickets are still on Early Bird so excellent value: https://www.melloevents.com/mello2026
Gavin Peck (Chief Executive Officer) & Rosie Fordham (Chief Financial Officer) will be with us to present to investors, take your questions and a great opportunity to meet them F2F.
Join us in June to ask them about the closure of their online business, outlook for the business and more...
Works co uk (LON:WRKS) just one of the FIFTY management teams that will be with us across the two days!
Troubles at HL possibly good for AJ Bell and Interactive Investor (ABDN)? They already annoyed clients with fee rises, and now this.
HL back online 1:30!
I have been a client of Hargreaves Lansdown for over 22 years.
The current shutdown is very concerning. I feel HL should put out a Statement giving more detail as to why this unprecedented shutdown is still taking place.
I like the bit on their help page for 'which services are unavailable?' 'Some services, such as accessing your account on mobile app or web, placing trades or adding or withdrawing money from your account, are temporarily unavailable'
As an online broker I think that represents a bit more than 'some services'!?
I can log in now so hopefully it's resolved
Is that a realised or unrealised loss? I'm in unrealised loss territory, however I regard this as part and parcel of the short-term 'cost' of being invested, rather than sitting on the sidelines.
Thanks to all who attended the Yellowstone Advisory Private Investor Event last night. We heard some great presentations from 4 very different companies: AFC Energy (LON:AFC) DP Poland (LON:DPP) Huddled (LON:HUD) and the Oberon UK Smaller Companies Fund. A good reminder that there are lots of excellent smaller companies listed on the UK stock market. If you’d like to see the presentations please email info@yellowstoneadvisory.com
If you’ve not attended one of these private investor evenings before but would like to, these are the dates for future events: 13 May, 24 June, 16 September, 11 November.
Four companies present their investment case in 15-20 minutes followed by Q&A and after all companies have presented there is an opportunity to talk to the management teams over drinks and canapes.
J D Wetherspoon (LON:JDW)
another downgrade in expectations here - slightly surprised that the company has failed miserably ref forecasts this year. I always thought they were pretty catious and were more likley to surprise on the upside than downside. I do have some sypathy - they have headwinds left right and sector trying to run hospitality business in uk at present and most of those headwinds flow directly from RR. Unfortuantely with increasing debt - its often a double whammy - if your profits drop you repay less debt and have higher interest costs to boot. at least net debt is on target - debt is perhaps easier to manipulate - so they might have simply delayed or choped some capital expenditure.
I was kinda hoping 18 months ago now would be the time when the reduction in freehold purchases would free up cashflow for debt to come down and they would get teh double benefit of lower interest costs. At present its the exact opposite that debt is still rising - doh.
I am not convinced there is going to be any good news short term here - i cant see energy costs , wage costs , and RR levied taxes coming down in real terms anytime soon so they will just have to bumble along.
Agree - the Mkt has hit them hard today and I guess the thinking is that they sell beer and food so cheaply, there's little profit margin. Fuller Smith & Turner (LON:FSTA) and Young & Cos Brewery (LON:YNGA) on the other hand hardly moved SP today.
J D Wetherspoon (LON:JDW) The obvious lever to pull is surely to increase prices in pubs. The chain is so much cheaper than rivals for food and beverages, surely most Wetherspoons customers wouldn't mind paying a few more pence for their food and ale, would they!
"J D Wetherspoon (LON:JDW) The obvious lever to pull is surely to increase prices in pubs. The chain is so much cheaper than rivals for food and beverages, surely most Wetherspoons customers wouldn't mind paying a few more pence for their food and ale, would they!
Possibly. Getting the price point right in a pub or bar is quite difficult. In rough terms, if a customer drinks two pints at say £5 per pint ( illustrative price) and you raise it to £5.50 per pint, then there is the danger that they will just have one pint. Not a great outcome.
If however, Card Factory, another value retailer increases prices 10% it probably wont affect the sale of the card.
Wetherspoon are very good with combined drinks and food offers on defined nights which attracts regular custom from a diverse customer base. I think it must be quite a sticky repeat turnover. Even this has problems, as some of the offers are at xx.99p which makes it quite obvious if one week the price increases.
I think that Tim Martin is natural retailer with an intuitive flair for knowing what customers want. The problem is that even his skills are being tested in a sector under some considerable pressure.
No Position either Card or Wetherspoons
J D Wetherspoon (LON:JDW)
I think that Tim Martin is natural retailer with an intuitive flair for knowing what customers want. The problem is that even his skills are being tested in a sector under some considerable pressure.
100% agree with your comments here
I think there is a possibly political slant to this too - spoons clearly have room to raise prices in some areas without affecting volumes materially.
I paid 1.99 for pint of Stowford Press in rammed spoons in newcastle week gone friday - that almost feels to cheap. perhaps this is targetted loss leader type stuff as they know they sell so little its not material though - but they have alot of very cheap stuff.
Ref the political slant - i get the impression that when the powers that be screw them over - spoons make a point of not overly raising prices -"quickly" just so that they can send message to the powers that be that they are being hard hit by changes - if you up process and keep margins people will say - well you are still raking it in arent you.
plenty of scope for them to raise prices in 6-12 months time once the dust has settled.
dont get me wrong here - its not great that they have had two profit marins and i think its probably safer to presuming they might not be materially sandbagging here and they need to keep some element of value to keep the punters flocking in.
What is happening with the Gold price
We may find various explanation for why the gold price has dropped so much when you expect it to go up or at least stay static. My explanation is simpler: Market manipulation!
The old buyers , who bought when the price was in $3000-4000 range are not affected but the momentum traders and late investors have been wiped out by this manipulation. Once they are out, the price restarts it climb slowly until the next peak.
I have my own small evidence for this market manipulation. Some years ago, during a more sleepy gold peak I spread bet with IG , a small bet of £5.
For fun, I put a stop loss at 100 points below my price, knowing the gold price does not move more than 5-10 points at most. The next day , to my astonishment, I was stopped out though the gold had moved only 5 points.
I called IG to find out when did the Gold dropped by 100 points. They told me that 2 minutes before midnight it traded briefly at more than 100 points down and back up! Clearly Not IG fault by I was out of the trade.
I see that phenomenon is happening at a larger scale now!
I was caught in patterns like that with Gold and Silver around 20 years ago.
J.P. Morgan were fined $920 million (not sure if this is a record) for market manipulation a few years ago.
They are the main bullion bank and shockingly also the custodian managing and safeguarding the Silver ETF.
Yes gold and silver are massively manipulated.
Having said that i think gold is down at the moment because traders need cash and gold is very liquid internationally, it has also had a big run this year.
always buy some gold a few ounces when the stock markets are flying then when stocks are being dumped you can sell if you want some cash the last time to buy at 2195 was jan25 by the way russia and china are always buying gold its in her interest to keep agro going
Plus dollar strengthening, and if interest rates go up that increases argument of gold not having a yield, I personally think it will go a lot higher long term due to continuous currency debasement assuming Trump doesn't destroy us all, I think we can all agree Western governments will keep increasing deficits.
We may find various explanation for why the gold price has dropped so much when you expect it to go up or at least stay static. My explanation is simpler: Market manipulation!
i have no idea what planet you are living on yadi - gold prices go up and down - sounds like you think it should be a one way steet.
gold has hugely outperformed most other investment types over 6 months - 12 months - 5 year and 10 year periods.
That run might continue but you are deluded if you have eexpectations that gold price can carry on outperforming indefinitely - and also not expect material pulbacks if you are lucky enough it does
Note the facts are you are up against the likes of mighty hedge funds and other serious money - who is going to rule the roost ref the trend in prices? - its not you !! - tree shakes are normal and you should expect to be on the end of them. Does that stetch to market manipulation it doesnt matter - small beer like you are the easy taregt - especially if many are using similar stop loss tactics that are likley to trigger in unison.
"i have no idea what planet you are living on yadi - gold prices go up and down - sounds like you think it should be a one way steet".
Get up on the wrong side of the bed this morning Mr Millaree?
BTW, a speller checker is a wonderful thing ... you see we can all play this zero sum game.
re Gold - apologies I can't resist. Manipulation and £5 bets I think not afraid.
Despite all the stories about $ debasement and investors wanting to exit the system the best chart I have seen is a perfect fit between Chinese money supply growth and gold ....which suggests Chinese buying...which could be for many reasons but obviously diversification makes sense. With this buying the trend picked up and accelerated which is classic momentum, so the market adjusted to indiscriminate buying and sent the price exponential. Silver took longer to join in but then did what it always does. The "story" was left in no mans land because it more than hedged any potential pick up in inflation early.... most investors who wanted exposure had it.... so the Iran situation did not create new buyers.
As volatility picks up - margin calls rise - losses materialise and all this needs financing. Anything that did well is a source of funds and Gold and precious metals fit the bill perfectly. A fairly normal correction has begun and it does not look out of proportion to the rise. If a normal test of the 200 day transpires this has further to go. Gold £4000 silver £50 would be perfectly normal....the abnormal situation was the rise last year....and this opens the prospect of a significant pull back. Whether that is a buy or sell is for individuals to decide....I sold all my Fresnillo (LON:FRES) into the rally and am not minded to buy it back anytime soon. The miners will still be making good money at these levels but much less than last year....
Net net the story really caught everyone's attention which leaves little room for the asset to be defensive...for now. I see nothing unusual in this... the dollar still rises in times of stress and this is not good for precious metals. Given the recent move I suspect some investors have too much.
RDH,
I would say that pretty much nails it. Thanks for your invaluable input.
Apologies for typo - should read $4000 and $50 ...not £ sterling ....
I believe rmillaree has emphasised that he is dyslexic. Maybe it was someone else.
I have always been an admirer of his passion for the market and his willingness to listen and accept different opinions. I have always valued his posts and many others that have disappeared.
All the best
Any chance of an update on your thoughts on the war at some point James.
SPI - No RNS but Sky News reporting Bridgepoint is preparing a bid at c£2.30, but extension to for offers likely.
https://news.sky.com/story/mar...
"Sky News has learnt that the former owner of Oasis Healthcare, the dentistry chain previously run by Spire's chief executive, Justin Ash, is formulating plans to launch a bid for Spire Healthcare Group worth around 230p-a-share."
Works co uk (LON:WRKS) has finally bitten the bullet with online trading. Will make a lot of holders very happy, including me.
Indeed. Its good that Works co uk (LON:WRKS) finally realised that they can't run an online shop. The writing was on the wall as none of the c-suite have strong eCommerce experience, and their most senior eCommerce person was also very weak.
It does show though that the c-suite here is either not skilled enough breadth-wise, or maybe a bit too mediocre to adapt to new technologies, innovations, etc. Doesn't bode well for future prospects. What if AI comes along and and radically disrupts their industry? If they can't even make eCommerce work, can they make AI work?
Hope you may find the time to look at yesterday's DFS Furniture (LON:DFS) half year results. Most of the day was trading 6-7% down but ended up level. With a high Stockrank, its an interesting one.
Roland, if you have some spare time could you look at Essentra (LON:ESNT) from Tuesday this week? Thanks
Lol, it looks like Hargreaves Lansdown are telling me that time in the market beats timing the market, so they removed my ability to log in entirely since yesterday evening (argh!).
Same here
Yes, looks like it’s down for all of us.
No good for a get out quick system.
I'm guessing completely but my assumption would be it's a due to a coordinated cyber attack targeted to coincide with a period of maximum market volatility. Hargreaves is still my main account but I've deliberately diversified to three other providers for a situation such as this and would recommend anybody to do the same if their circumstances allow. I could of course be absolutely barking up the wrong tree!
This Hargreaves information can be accessed from the Home page. They say it is not a cyber attack:-
“We’re currently experiencing technical issues which are affecting some parts of our website and app. This is impacting clients’ ability to transact on their accounts and some of our services are currently unavailable.
All clients’ assets and data are secure and there is no evidence of any cyber incident data breach or system compromise.
We're sorry for the inconvenience we know this will cause and are working to restore our service as soon as possible.
This page will be updated with all the latest information, so please do check back here.
Our Helpdesk is available to take your call but are unfortunately also unable to transact on your behalf. For urgent enquiries or if you need extra support, please contact us on 0117 900 9000.”
This link provides more (limited) info and a FAQ section
https://www.hl.co.uk/status
Ken - Yes but 'no evidence of a data breach' is not the same as not being subject to an attack which results in the site being unavailable. You don't need your data to be compromised in order to be unable to trade.
Stories like this often seem to emerge when trading volumes are high and investors need the service more than ever -- the names of the providers changes sometimes, but the pattern stretches back decades.
Spot on always ideally have two accounts due to the fact as you say a lot of the time the main players systems collapse on huge volatility events just when you want to buy/sell more than ever.
I would love to know how much investment in shares and funds has been moved to cash since the Orange Man decided to go to war.
I went 90% cash first thing Monday morning after the attack was launched. I compare the situation to an earthquake. It’s safer to be outside. You don’t know which buildings will collapse.
And all the “wisdom” about not timing the market seems to me to miss the point. There’s no point taking unquantifiable risks.
One of the advantages we have as small private investors is nimbleness. Use it.
I am also sitting mostly in cash and waiting patiently for a better dip.I might be wrong, but the world looks very shaky at present, and better opportunities to buy might present themselves. I know the old saying time in the market, etc, is often trotted out, but in my opinion, that’s also industry propaganda, which earns fees on assets invested and earns less (or nothing) on cash sitting idle. So structurally, the industry is biased toward clients invested.
But even very smart investors often struggle with timing because markets turn before the news improves, fear is highest near the bottom, and confidence is highest near the top
So the issue isn’t really about blind investing, it’s about human behaviour.
Buy low, sell high, fear is the other guy's problem
I know the old saying time in the market, etc, is often trotted out, but in my opinion, that’s also industry propaganda, which earns fees on assets invested and earns less (or nothing) on cash sitting idle. So structurally, the industry is biased toward clients invested.
That's basically correct.
The story is that if you'd missed the best thirty days in the market over the last 40 years you will lose virtually all of the market uplift. This is convincing evidence that you should stay invested ... or is it?
Well, the problem is that the best days in the market tend to cluster around the worst days, in bear markets, as investor uncertainty triggers volatility. This means that hitting the best days virtually also guarantees hitting the worst days too - and that's significantly worse for returns than holding on.
Basically if you miss both the best and worst days you'll outperform buy and hold. The trick is to not be suckered into selling on every dip in fear it's another bear market. We've seen lots of false dawns over the past few years with posters confidentally announcing they've gone to cash, only see markets continue to climb.
Anyway, that suggests that big up days in the next few weeks are selling opportunities. However, the issue here is about the duration of the conflict and the after effects. Typically a war ending leads to a bull market - but there could be lingering impacts if the attacks on energy infrastructure continue. And in any case, as no one has actually declared war and Trump has already announced that they've won, while continuing to blow billions a week in munitions, how will we know?
Personally I'm as heavily in cash as I ever am, but looking for opportunities to buy quality stocks at a discount. Not much evidence of that yet, but if this continues pockets of longer-term value will emerge.
timarr
I am holding around 40% cash at the moment with good diversification in Gold, Commodities and Ruffer which have served me well. But my concern is we have a half wit in the US who has no idea of what he is doing whilst carrying out all sorts of diversionary tactics to avoid the Epstein story. The net effect is that too many investors are sitting on the old adage that you hang tight and wait for everything to recover. The damage to the Qatar LNG lines will take 5 years to repair not to mention elsewhere. This can only be inflationary which will affect costs and therefore Price Earnings ratios leading to downgrades across the spectrum. Add to that the breach in trust which has originated from the tariffs and scorn meted out we are left with a diminishing global story which will also impact on trade. I know people only want to hear good news and dismiss everything else, but I am afraid I first joined the markets in 1988 and I have never seen such a shit show as we have today. Even 2008 as terrible as it was we had competant and serious politicians leading the way out of what was a market lead tragedy. I wasn't going to add this but there you have it.
Can't disagree Camtab the only thing I would throw into the mix anyone who remembers the first gulf war will know Saddam set all the oil fields of Kuwait alight on his exit the thought was they would take years to put out.
Red Adair was sent in with his team and they got things under control in a lot shorter time frame than predicted.
Despite the worst of humanity being at the wheel on multiple fronts at the moment the flip side is we generally can also achieve great things when we are not trying to exterminate each other so hopefully if this mess gets sorted out repairs will be done in a faster timeframe.
I an 50%cash too but where is best place to park it are short term money funds OK I have already lost money on UK gilts in last month
I an 50%cash too but where is best place to park it are short term money funds OK I have already lost money on UK gilts in last month
There are a few options:
A lot depends on your preferences - cash gives optionality but you're only protected to the FCA limit and may give rise to IT liability, short term gilts can fluctuate a little bit but can also give CGT protection outside of a SIPP or ISA, MM funds can take time to move in and out of. The ultra short term bond funds are pretty safe, although you've just missed the quaterly ex-dividend date on ERNS.
I have all four, in different amounts for different reasons.
timarr
Hi Tim could you be good enough to ping up the isin number for the ultra short bond fund ideally the one hedged to gbp.
Thanks Andy
Hi TP
iShares £ Ultrashort Bond UCITS ETF GBP (Dist) (LON:ERNS) ISIN is IE00BCRY6441
Cheers
timarr
Thanks as always Tim
I sympathise but…. The long term history of all markets suggests these risks pass. Even recessions and bear markets are not consequential to long term returns. Ofcourse needing money short term is a different matter. Pension selling to meet liabilities will increasingly be a factor to consider but my view will always be geo political events need to be bought. At period ends - normally a year - rarely do investors justify below par returns with avoiding drawdown ….
Having said that the move yesterday in bonds and sterling signal much fewer rate cuts. Not helpful for rate sensitive sectors like housing —>>> the govt should step in with a policy but i am not sure they are ready yet. This weekend is too early but the pressure will build … this is what governments are for.
Also news for the straight is so bad a global effort to keep it open has to be developed - time is running out, so let’s hope soon. Good luck all……
35% of mine and rising.
Rising because i put stop losses on everything.
I do not advocate for that as under normal circumstances blind stop losses are probably not a good idea. On the other hand I've been able to sleep.
Wouldn't even accept a phone trade so it looks like traders' screens are down too. Malware attack? I am, looking forward to a hefty chunk of compensation. :-)
They say not… IT problem….
The Hargreaves Lansdowne website is still out after the market opening. Not a good advertisement for the HL tech staff. Maybe they have started using AI.
Possibility of an attack? Sure hope not.
When I try to log on thru the App HL tells me it is “ Planned Maintenance “ . I have just asked them when did they inform me of this .
I’ve now raised a formal complaint with HL.
I still haven’t had any proactive communication beyond the generic status page, and access has been unavailable since yesterday evening in both app and website. That’s effectively a full loss of account functionality during a period of significant market volatility. For me, the issue isn’t just inconvenience, it’s the inability to monitor positions, manage risk, or take action if needed. Appreciate others are in the same position, but that doesn’t make it acceptable. Will be interested to see how they respond, particularly around explanation and whether any form of compensation is considered.