Daily Stock Market Report (Thur 22nd Jan 2026) - ING, MPE, JDG, KOO, WRKS, BME, KITW, ZTF, ECEL, FUTR, TSTL, AJB, MAB1

Good morning!
Wrapping it up there, thanks everyone.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
Fresnillo (LON:FRES) (£29.8bn | SR80) | Fresnillo has paid CAD$770 million (US$555 million) in consideration, funded with existing cash on hand. Adds a 10 million oz gold resource base, led by the Novador project - an asset capable of producing 200,000+ oz/year for over a decade. | ||
Associated British Foods (LON:ABF) (£13.3bn | SR82) | 16 weeks to 3rd January. Group revenue -0.9% (constant currency) vs. prior estimate -1%. Primark like-for-like sales growth -2.7%,. total sales growth +1%. | ||
South32 (LON:S32) (£9.87bn | SR87) | FY26 production guidance maintained at operated assets. H1 operating unit costs tracking in line with guidance. Guidance for non-operated Brazil Aluminium is under review as S32 awaits the operator's revised ramp-up profile, following lower than planned quarterly volumes. | ||
Tritax Big Box REIT (LON:BBOX) (£4.35bn | SR63) | £14.2 million increase in contracted rent from asset management activity. 4.0% like-for-like portfolio ERV growth. 33% loan to value. | ||
Computacenter (LON:CCC) (£3.25bn | SR88) | Q4 and therefore the year as a whole ahead of expectations. Revenue +32% (cc). Adjusted profit before tax to be no less than £270m, comfortably ahead of market expectations (£253.6m). | ||
Harbour Energy (LON:HBR) (£3.13bn | SR70) | 2025 production (474 kboepd) at the top end of guidance. Stronger than anticipated free cash flow generation. 2026 guidance: production of 435-455 kboepd, production rates to increase towards 500 kboepd by year-end. | ||
AJ Bell (LON:AJB) (£1.8bn | SR47) | SP +5% Platform: customer numbers increased by 29,000 to close at 673,000, up 20% in the last year and 5% in the quarter. Net inflows £1.5 billion. Investments: net inflows £0.3 billion. | GREEN = (Graham) [no section below] The exceptionally high quality we’ve talked about before remains apparent with AJ Bell continuing to grow at remarkable rates considering both the size that the business has already reached and the maturity of the industry. I note that even the Investments arm is enjoying net inflows, another phenomenon we’ve discussed previously. With AUM of £9.5 billion (up 32% in the year), this is now an important player in the market. And with the stock trading at 17x earnings, it doesn’t look overpriced to me at all (QualityRank 95 with ROCE and ROE of ~50% or higher).. | |
B&M European Value Retail SA (LON:BME) (£1.74bn | SR48) | Q3 LfL revenue at B&M UK down 0.6%. Deeper investments planned to clear discontinued lines, reduce SKU count and to clean up stock. Now expects FY26 Adjusted EBITDA £440m to £475m, compared with previous guidance of £470m to £520m. | BLACK (RED =) (Graham) I’m going to cautiously leave this on RED, which is consistent with our approach to profit warnings. Also I note that net debt was £859m at the interims, approaching 2x the new EBITDA forecast. So there isn’t a very strong balance sheet to fall back on, if trading were to continue deteriorating. | |
Senior (LON:SNR) (£956m | SR64) | Stronger than expected trading since November, notably in Aerospace. Full-year adjusted PBT to be comfortably above previous expectations. There will be restructuring costs (treated as adjusting items in the results) at the Flexonics business. | ||
Boku (LON:BOKU) (£677m | SR48) | Revenue for FY 2025 is expected to be ahead of market expectations at c.$128.5m (exps: $127.5m). FY 2025 adjusted EBITDA also ahead of market expectations at c.$41m (exps: $39.8m). 2026: expects to deliver medium-term guidance of organic revenue growth above 20% on a CAGR basis and adjusted EBITDA margins above 30%. | ||
M P Evans (LON:MPE) (£653m | SR97) | Own crops +8%, total crops -4%. Crude palm oil production -3%. Use of independent crops being deliberately restricted (“a low-margin source of supply”). Average mill-gate price for CPO up 5% vs. prior year. | AMBER/GREEN (Mark) The figures here look in line with recently upgraded Cavendish forecasts, with commodity strength offsetting a decline in production, following a change in strategy to buy in fewer third-party crops. With the share price of MP Evans, and all Palm Oil producers, doing well recently on the back of this commodity strength, there is no getting round that investors will need to take a view on where we are in the commodity cycle for Palm Oil. Those who are bullish and expect current CPO and PK pricing to remain elevated, will see further upgrades and upside to come this year. Those expecting the recent commodity pricing strength to moderate, may be better off getting out ahead of that. The recent declining Momentum Rank gives some pause for thought. However, this remains cheap enough for anyone neutral on commodity pricing to take a mostly positive view. | |
Harworth (LON:HWG) (£538m | SR39) | “We remain confident in achieving £1bn of EPRA NDV, albeit… it is increasingly challenging to deliver against the roadmap set back in 2021. Against this backdrop, the timeline for achieving our milestone extends beyond December 2027, with a range between the end of 2028 and end of 2029. | ||
Wickes (LON:WIX) (£524m | SR93) | 2025 adjusted PBT expected to be in line with market forecasts. Retail LfL revenue growth 5.7% for the year. Group LfL revenue growth 4.9%. | ||
Young & Cos Brewery (LON:YNGA) (£503m | SR86) | LfL sales +11.2% for three weeks to 5th January. For the 14 week period ending 5th January, total managed revenue +5.6% (LfL +5.7%). Admission to the Main Market “will enhance the Company's corporate profile and appeal”. | ||
Future (LON:FUTR) (£484m | SR73) | Buys “a UK-based digital publishing group that combines the authority of a trusted media brand with the authenticity and engagement of the creator economy.” £39.9m upfront payment from existing facilities, plus earn-out. Total consideration capped at £80 million (requires growth to FY 2029). | AMBER/GREEN (Mark - I hold) [no section below] | |
Auction Technology (LON:ATG) (£409m | SR25) | AGM TRADING UPDATE & Statement regarding Auction Technology Group plc | FY guidance confirmed. Separately, Fitzwalter attempts to clarify matters, saying there is “inconsistent information between certain shareholders as to the events that culminated in the Company's pre-emptive announcement of FitzWalter's possible offer”. | |
Gulf Keystone Petroleum (LON:GKP) (£403m | SR62) | 2025 gross average production of 41,560 bopd, towards upper end of tightened annual guidance range of 40,000 – 42,000 bopd. 2026 gross average production guidance of 37,000 to 41,000 bopd. Considering a listing on the Euronext Growth Oslo, subject to favourable market conditions. | ||
Mortgage Advice Bureau (Holdings) (LON:MAB1) (£397m | SR65) | 2025: in line with expectations. Revenue +19% (£318m), adj. PBT +12% (£35.8m). Outlook: “the impact of prior economic shocks is now receding… The Group has entered 2026 with good momentum and continues to trade in line with the Board's expectations.” Outlook for refinance lending is particularly strong. | GREEN = (Graham) [no section below] I've been a fan of this (franchised) mortgage advisory business for years, and I'm enthused by today's update. We have double digit revenue and adj. EBITDA growth for 2025, in line with expectations. Productivity as measured by revenue per advisor continues to trend nicely upwards. Looking forward, the mortgage market is set for a busy year with the number of products at an all-time high and borrowers and lenders enjoying post-Budget stability. I'm expecting MAB to perform very strongly in this environment and the signs are positive for continued growth in 2026 (EPS forecast for this year: 50.7p). | |
Elixirr International (LON:ELIX) (£393m | SR74) | FY 25 revenue is expected to meet or exceed market expectations of £149 million. FY 25 Adjusted EBITDA margin is expected to meet or exceed market expectations of 28.1% - 29.2%. Has entered FY 26 with a record amount of revenue contracted for the year. | ||
Judges Scientific (LON:JDG) (£382m | SR41) | Satisfactory performances in the Rest of Europe and China have been more than offset by the USA, where there has been no recovery since the September update. Adjusted earnings per share for 2025 to be in the region of 275p per share, 6% down on current market expectations (292p). Starts 2026 with a lower-than-desired order book. Geotek's next coring expedition is now unlikely to be until early 2027. Board considers it prudent to provide guidance for 2026 Adjusted earnings per share of 200-250p. | BLACK (AMBER/RED ↓) (Graham) While I still have great admiration for Judges, I am going to have to downgrade our stance here by one notch to AMBER/RED, in light of the profit warning. But this is one of those instances where I’ll be eager to go back to neutral or positive, if there is evidence of stabilisation. In the short-term, however, I’d be braced for continued difficulties. | |
Forterra (LON:FORT) (£366m | SR61) | Revenue of c.£386m, 12% ahead of the prior year (2024: £344.3m). Adjusted EBITDA in line with market expectations with margin progression, adjusted PBT and adjusted EPS ahead. Net debt c. £56m. Longer term market fundamentals remain attractive. | ||
Mears (LON:MER) (£287m | SR88) | Expects to report Maintenance-led revenues for FY25 +10% to in excess of £610m. Expects to report Management-led revenues for FY25 -13% to in excess of £500m (2024: £577m). Adj. profit before tax -2% to no less than £62.5m (2024: £64.1m) (slightly ahead of consensus). Average daily net cash position during FY25 of £52.8m (2024: £59.6m). | ||
Taylor Maritime (LON:TMI) (£212m | SR42) | Revenue $28.0m, Net loss $3.2m, Adj. EBITDA $5.2m. Cash $187.7. Distribution of $143.4m to shareholders at 94.41cents per share, based on the unaudited net asset value. | ||
Netcall (LON:NET) (£201m | SR65) | H1 Revenue + 15% to £26.5m (+11% organic), Adj. EBITDA +12% to £6.4m, in line with management expectations. Net Cash £14.8m (30 Jun 25: £27.2m). | ||
Zotefoams (LON:ZTF) (£198m | SR91) | FY revenue +7.2% to £158.5m, slightly ahead of market expectations, Ad. PBT +37.9% to £21.1m, ahead of market expectations. | AMBER/GREEN = (Mark) [no section below] | |
Tristel (LON:TSTL) (£191m | SR75) | H1 revenue +14%, Adj. EBITDA +17%, Cash £13.3m. Matt Sassone, Chief Executive Officer, has confirmed to the Board his decision to resign to take up a worldwide President role with a large US multinational. | AMBER/GREEN = (Mark) [no section below] | |
Kitwave (LON:KITW) (£185m | SR68) | 295 pence in cash per Kitwave Share, 33.5% premium to last night’s close. Recommended by the board. Irrevocable undertakings and a letter of intent for 21.6% of shares count. | PINK (Graham) [no section below] This level of premium (33%) is around the minimum of what I consider to be acceptable and where offers tend to get Board and shareholder approval. The support from shareholders is significant (21.6%) and while it’s not yet a done deal, I would expect a cash offer that is recommended by the Board and already supported by a large block of shareholders is likely to go through. The buyer is a mid-market private equity firm active in the US and Europe, and it’s good to see that this type of buyer is still active in the market despite the strong returns we’ve seen over the past year. Kitwave is a company we’ve had mixed views on (see the profit warning last July) but the buyer is only paying 10x earnings. | |
Kitwave (LON:KITW) (£185m | SR68) | Revenue +21% (-1% LFL) to £802.7m, adj. Op Profit +11.7% to £38m, trading has been in line with management expectations since the Group's last trading update. | PINK (see above) | |
Animalcare (LON:ANCR) (£175m | SR31) | Revenue +20% CCY to £89.1m, u/l EBITDA +50% to £17.4m, (consensus: £89.2m and £17.6m). Net debt £9.1m (FY24: £9.0m). Entered 2026 with positive momentum. | ||
Fonix (LON:FNX) (£168m | SR60) | H1 Adj. EBITDA +6.4% to £8.3m, in line with management's expectations. Enters H2 with positive momentum. | ||
Genel Energy (LON:GENL) (£166m | SR36) | Patrick Allman-Ward as an Independent Non-Executive Director and Chair of the Board. | ||
Eurocell (LON:ECEL) (£123m | SR70) | FY25 Sales and adjusted PBT to be in line with expectations (sales flat). Expect pre-IFRS 16 net debt £22m, (30 Jun 25: £29m) 0.7x pre-IFRS 16 EBITDA, ahead of our previous guidance of 0.9x. “Trading conditions have remained subdued, with challenging macroeconomic conditions and weak consumer confidence continuing to impact both the repair, maintenance and improvement market (RMI) and new build housing.” | AMBER/GREEN (Mark) [no section below] | |
Pharos Energy (LON:PHAR) (£87.6m | SR73) | FY WI Production 5,398 boepd net, in line with guidance (Vietnam 4,095 boepd, Egypt 1,303 bopd). Revenue $115m, Cash $40m. FY26: production guidance increased from 2025 to 5,200 - 6,400 boepd net. Group capex $50m. | ||
Ilika (LON:IKA) (£68.7m | SR20) | H1 Revenue -40% to £0.6m, due to reduction in grant funding. LBITDA excl. SBP £3.2m (25H1: LBITDA £1.9m), Cash £6.9m (25H1: £10.1m) Confident they can secure larger follow on orders for the Steareax M300 batteries. | ||
Kooth (LON:KOO) (£37.8m | SR54) | One year contract with an undisclosed US State for the provision of digital mental health services for up to 100,000 students. The contract has an expected value of $2.6 million. | AMBER/GREEN = (Mark - I hold) | |
Fiinu (LON:BANK) (£32.4m | SR4) | None of the 20 million additional consideration shares will be issued to Granicus Holdings OŰ, since review confirmed order book was below threshold. | ||
Strategic Minerals (LON:SML) (£30.8m | SR27) | £4m gross raised at 1.3p the closing mid-market price of the Company's shares last night. | ||
Emmerson (LON:EML) (£28.5m | SR20) | The Company is required to submit its Memorial (case outline) by the end of Q1 2026. | ||
Works co uk (LON:WRKS) (£25.3m | SR85) | H1 LFL sales +0.3%, Stores +4%, online -36%, Pre-IFRS 16 Adjusted EBITDA loss of £1.0m, adjusted loss before tax of £5.1m (H1 FY25: £6.5m loss)., net debt £5.3m (H1 FY25: £8.5m), on track to deliver FY26 profit in line with market expectations. | AMBER ↓ (Mark) | |
Predator Oil & Gas Holdings (LON:PRD) (£23.7m | SR9) | BON-18 well commenced in Bonasse Field, expected to take 2 weeks and add 300-400bopd. | ||
Artisanal Spirits (LON:ART) (£23.4m | SR17) | In line with expectations with in-market trading improving in H2 versus H1 in the key geographies of UK, Europe, USA and China. | ||
Medpal AI (LON:MPAL) (£22.2m | SR6) | Previously it took an hour to process 40 prescriptions, but with the update in place, the Robopharma robot is capable of processing more than 100 prescriptions in less than 5 minutes. | ||
Maintel Holdings (LON:MAI) (£19.4m | SR34) | Expects FY25 results will be in line with consensus, with total revenue expected to be £92.2m and Adjusted EBITDA expected to be £7.2m. Net debt £18.3m (31 Dec 2024: £16.7m) | ||
Eenergy (LON:EAAS) (£18.8m | SR37) | First multi-site award with Symphony Healthcare Services, with a total contract value of £0.7m | ||
Ebiquity (LON:EBQ) (£17.9m | SR23) | Expects FY25 revenues of c.£73.4m, adjusted EBITDA of c.£8.1m and adjusted operating profit of c.£4.6m. Expects FY26 revenues and profits to be ahead of FY25. | ||
Ingenta (LON:ING) (£15.2m | SR99) | Revenue flat at £10.3m, Adj. adjusted EBITDA -11% to £1.6m ahead of market expectations. Net cash £4.7m (2024: £3.6m). Final Dividend +10% to 2.75p. | AMBER/GREEN (Mark - I hold) | |
Kelso group (LON:KLSO) (£13.4m | SR36) | Expects to receive cash return from NNC’s disposal of Escode announced yesterday. | ||
Hardide (LON:HDD) (£13.2m | SR42) | Revenue +28% to £6m, EBITDA £1m (FY25: £0.0m), EPS 0.2p (FY25: -1.9p), net debt £1.6m (FY25: £2.1m) . “Strong trading momentum of Q4 FY25 continued into Q1 FY26” | ||
Prospex Energy (LON:PXEN) (£12.4m | SR14) | Contract for the rental of a transformer at the El Romeral gas to power plant in Andalucía, Spain | ||
RC Fornax (LON:RCFX) (£11.5m | SR35) | Selection as a Specialist Provider on Aurora's Evolve network | ||
Cloudbreak Discovery (LON:CDL) (£10.5m | SR6) | 15 samples over 1g/t gold. £1.85m gross raised at 0.56p, 25% discount to last night’s close. |
Graham's Section
Judges Scientific (LON:JDG)
Down 11% to £51.20 (£341m) - Full Year Trading Statement and Notice of Final Results - Graham - AMBER/RED ↓
The introduction doesn’t try to hide the bad news here:
The Board of Judges Scientific plc, a group focused on acquiring and developing companies in the scientific instrument sector, provides the following update on the Group's trading performance for the financial year ended 31 December 2025 and the continued headwinds impacting the outlook for FY26.
The share price is down over 10% this morning but the news can’t come as a major shock to shareholders: Judges has been struggling to regain momentum for some time.
We were most recently neutral on it in November, when we learned that the driving force behind the company for so many years, Mr. David Cicurel, was moving to non-Exec Chair.
Trading conditions
There have been “uncertainties around US federal funding for scientific research” (Trump-related, I presume?). The company informs us today that in the “there has been no recovery since the September update” when it comes to the United States. Other regions have been “satisfactory.”
Here’s a quote from an article published in the last few days by The Hill, a US political newspaper:
After a year of government layoffs and sweeping funding cuts under President Trump, many researchers are hanging on by a thread.
The administration has said it is realigning federal spending to match its agenda, but scientists respond that even proposals that advance the White House’s goals have been ignored or cut. Medical advancements, education research, defense priorities — no area has proven safe from frozen funding, which has also come alongside massive reductions in the government agencies that support these areas.
And in even more bad news for Judges:
Additionally, despite general resilience in industrial-focussed markets, H2 saw reduced investments in offshore wind which had been a strong growth driver for the Group.
Order intake: this saw a "progressive weakening” during 2025, and by the end of the year was down 6% for the full year.
2025 guidance: adjusted EPS will be c. 275p, 6% below expectations of 292p.
For context, adjusted EPS was 283.4p in 2024, and it had been 374.6p in 2023.
2026 outlook: this is unsurprisingly poor.
The Group starts 2026 with a lower-than-desired order book. The reduction in Organic order intake has meant that the opening Organic order book has reduced to 15.7 weeks of sales (31 December 2024: 18.7 weeks; 16.9 weeks without Geotek's coring expedition).
The delivery of Geotek's next coring expedition is now unlikely to be until early 2027.
As we noted at the time of the acquisition of Geotek, the addition of this business was likely to increase the lumpiness of JDG’s results, and this is increasingly evident now.
In the US, “uncertainty remains around the timing of a return to normal trading in the USA”.
2026 adjusted EPS will be 200-250p, “which assumes the absence of a coring expedition and no recovery of trading in the USA”.
Graham’s view
I’m a long admirer of this business but with sustained weak performance, it’s difficult for me to be positive on it now.
It’s not the company’s fault that its share price got overheated a few years ago, with expectations that turned out to be unrealistic:
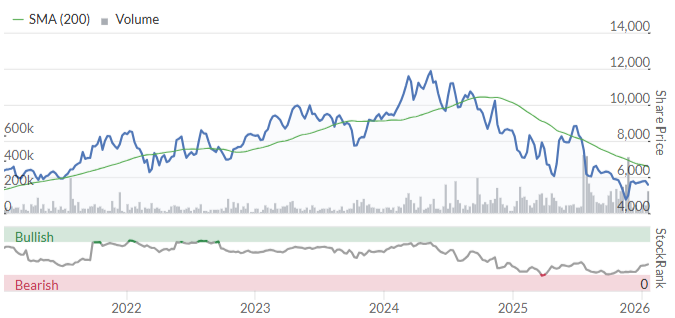
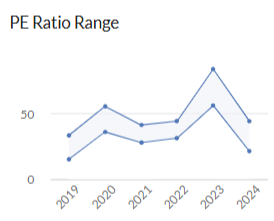
The earnings multiple soared to impressive heights before returning to a more level:
Some reasons to be careful:
This is not just a “blip”; revenues and orders have shown signs of moderating and weakening for a few years now. Organic revenue was already down 8% in 2024, before the company ran into a very difficult 2025.
As a victim of its own success, my impression is that Judges has struggled in recent years to find exciting acquisitions that can successfully move the needle. Geotek doesn’t seem particularly successful at this point.
Dependence on government funding is a double-edged sword and at the moment, Judges is on the wrong end of this risk.
The wide range of possible outcomes for 2026 (200-250p adjusted EPS) implies limited visibility.
Some reasons to be positive:
The business is still profitable; even at the low end of new guidance.
At the top end of new guidance, the shares are now trading on a PER of 20x, which is not a terrible entry point for investors who believe in the long-term resilience of the group.
The new CEO (from February 2026) has been with Judges for nearly 3 years already, and had a long stint at Halma and before that at Renishaw. Perhaps he’ll bring some new ideas that can reinvigorate performance?
While I still have great admiration for Judges, I am going to have to downgrade our stance here by one notch to AMBER/RED, in light of the profit warning. But this is one of those instances where I’ll be eager to go back to neutral or positive, if there is evidence of stabilisation.
In the short-term, however, I’d be braced for continued difficulties.
B&M European Value Retail SA (LON:BME)
Down 0.2% to 172.68p (£1.74 billion) - Q3 FY26 Trading Statement - Graham - RED =
B&M European Value Retail S.A. ("the Group"), the UK's leading variety goods value retailer, today provides a trading update for the third quarter ("Q3") of its current financial year ("FY26"), relating to the 13 week period from 28 September 2025 to 27 December 2025.
We’ve been sceptical about this one and for pretty good reasons, including some accounting problems.
Today’s update does little to inspire confidence, with the company cutting profit forecasts.
Revenue figures:
UK LfL -0.6% in Q3, -0.2% year-to-date.
Group +2.9% in Q3, +3.6% year-to-date.,
CEO comment:
We entered our Golden Quarter sharper on price to reinforce our value proposition with our customers. Price investment has continued, particularly in FMCG, and while the full benefits will take time to come through, I am encouraged by the early signs of like-for-like (LFL) sales growth at B&M UK late in the quarter. This includes the strong sell through of our seasonal ranges, which contributed to 3 percent UK LFL growth in December, with similar LFL trends continuing in early January trading.
I get that this is a value retailer and it’s competing on price, but as an investor I instinctively recoil from the phrase “price investment”. I’d prefer a much plainer phrase - discounting, or even price cuts - rather than a phrase that makes these things sound grander than they really are.
The strategy of “price investment” is not the only issue affecting results currently:
…we are identifying opportunities to make deeper investments in clearing discontinued lines to support planned reductions in SKU count and to clean up stock as we restore on-shelf availability towards industry benchmarks. As with our pricing actions, these are investments in the long-term strength of B&M, but they do impact near-term financial performance. As a result, we are revising our full-year guidance downwards to reflect these actions and the financial underperformance at Heron. We now expect FY26 Adjusted EBITDA (pre-IFRS 16) to be in the range of £440m to £475m, compared with our previous guidance of £470m to £520m.
Let’s use the midpoints of these ranges to estimate how large this profit warning is. The new midpoint is £457.5m, while the old midpoint was £495m. That’s an 8% reduction.
The second paragraph quoted above is again rather euphemistic. What it amounts to is more price cuts! This time on old stock.
Again, I recoil from this sort of phrasing. Whenever I hear something like “we are identifying opportunities to make deeper investments”, I interpret it as “we have to make deeper price cuts in order to get rid of our old inventory”.
Looking ahead, the CEO is more confident:
I remain confident that the actions we are taking will restore sustainable LFL growth at B&M UK over the next 12 to 18 months and provide a strong foundation for future growth."
Graham’s view
I do think we’ve been very harsh on this one, giving it a RED, but I’ve not seen anything in today’s update to change that stance.
The share price has barely reacted, implying that investors are already very sceptical and able to price in a profit warning like this.
The earnings multiple is in single-digits, as you’d expect:
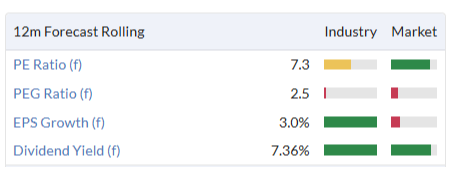
I’m going to cautiously leave this on RED, which is consistent with our approach to profit warnings. Also I note that net debt was £859m at the interims, approaching 2x the new EBITDA forecast. So there isn’t a very strong balance sheet to fall back on, if trading were to continue deteriorating.
Mark's Section
Ingenta (LON:ING)
Down 7% at 97p - Trading Update - Mark (I hold) - AMBER/GREEN
(At the time of writing, Mark holds a long position in this stock.)
Good news here:
The Group expects to report revenues for FY25 of £10.3m (2024: £10.2m), with adjusted EBITDA ahead of market expectations at £1.6m (2024: £1.8m).
However, I’ve got to say that I did expect this. At the half-year they did £0.9m adjusted EBITDA, and while each half can be noisy, it didn’t take much for them to beat full year expectations, and I think many shareholders took the same view. This is a very conservatively run company, and adjusted EBITDA here is almost certainly adjusted down to account for the FX effects seen in H1.
Broker coverage:
In order to work out how this all plays out, I turn to Cavendish’s update note. This is actually a slight miss on their revenue forecasts, but gross profit increases slightly due to better mix. The beat on EBITDA flows down the income statement to give a 22% upgrade in Adjusted EPS to 10p. Although this is a sizeable upgrade to EPS, it is still down on the previous year. I wouldn’t be surprised if the company are still holding something in reserve and end up slightly higher than this, but it is still unlikely to exceed the previous year’s figure.
Contracts:
Although the company highlighted a new Edify customer onboarded during the period, I can’t help feeling they are a little disappointed with the slow pace of converting a large sales pipeline into new customers. This is perhaps understandable given how weak much of the business landscape was in the latter part of 2025, with few companies committing to new software systems, given their own variable outlooks. However, this hasn’t been helped by the previously mentioned difficulty in getting salespeople with the relevant specialist skills. However, they are a little reticent around how long it will take to see the fruit of recent sales activity in the numbers, saying they are:
…confident that new business activities will bear fruit as the year progresses, and achieving growth in profitability from the 2025 level will to some extent be dependent on the speed with which new customers can be onboarded. The Group expects to announce FY25 results in April 2026 and will provide a more detailed outlook on 2026 at that time.
And:
Looking forward, the existing teams are actively working on sales proposals which will be submitted in the first quarter of 2026 which we hope to report on in due course.
Cash:
While I largely expected the EBITDA beat, this is a pleasant surprise:
…closing cash balances at 31 December 2025 of £4.7m (2024: £3.6m). The Group has no debt.
This cash figure was ahead of my expectations, especially as they paid £630k out in dividends during the year. It also came in significantly above Cavendish’s £3.8m estimate. Today’s commitment to pay out a further 2.75p final dividend, means that Cavendish’s forecast is also exceeded.
Valuation:
Cavendish point out:
Ingenta trades on an FY25E adj P/E 10.5x (ex-cash P/E of 7.4x), a significant discount to its peer group on 18x.
This is a very cheaply-rated stock compared to an already cheap UK small-cap market, let alone the software sector.
Mark’s view
I view this company as pretty much a free option at the current price. The high level of recurring revenues together with the high free cash flow these generate, plus a third of the market cap in net cash, means that the current valuation looks more than underpinned, even if their strategy to drive sales growth fails to deliver.
The total addressable market for their software solution is huge, so there is a certain amount of frustration in the market with the slow progress in delivering a sales uplift. A sentiment I share. However, with long sales cycles and weak market conditions in 2025, it shouldn’t be surprising that it will take some time for additional sales efforts to be seen in the numbers. If they can generate meaningful sales uplift, the recurring nature of the wins mean that Cavendish’s 260p Price Target doesn’t look out of place.
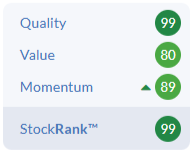
Hence, I am in no rush to sell, or change our previously mostly positive AMBER/GREEN view. Especially while it remains one of the most high-rated stocks by the Stockopedia algorithms:
M P Evans (LON:MPE)
Up 1% at 1264p - 2025 Crop and production - Mark - AMBER/GREEN
Their own crops delivered a decent increase in production. However, there was a significant decline in third party crops bought in:
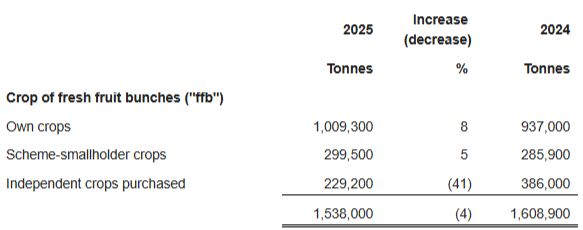
The company is keen to point out that:
The Group continue deliberately to restrict the amount of independent crop purchased for processing in its mills, a low-margin source of supply, with an overall 41% decrease in 2025. This is part of the Group's ongoing strategy to change the input mix to its processing facilities to prioritise its own, higher-margin, harvest.
It did mean that overall production was down 3% for both Crude Palm Oil and Palm Kernels
Pricing:
The decline in production has been more than offset in the increase in price achieved:
The Group received an average mill-gate price for its CPO of US$866 per tonne in 2025, 5% higher than the US$823 in the previous year. Prices for PK were, on average, US$748 per tonne in 2025, a substantial 42% higher than the US$525 in 2024. This high-price environment has had a positive effect on the Group's revenue and profitability, as reported in the Group's announcement on 10 November 2025.
It is this huge increase in the price of Palm Kernels that has had a significant positive impact on profitability at MP Evans and all Palm Oil producers. Palm Kernels are the seed inside the oil palm fruit, meaning that they will always be a smaller part of palm production. While crude palm oil is mainly an edible oil, whereas palm kernel oil often goes into detergents, cosmetics and personal care. This makes demand less price sensitive, and growth in demand for these products has been responsible for the big price rises.
Looking at the numbers, it seems these are in line with wat their broker Cavendish expected for 2025, following upgrades towards the end of the year.
2026:
Looking forward the company say:
Pricing in early 2026 remains robust, with the Group tendering its CPO output for sale at approximately US$850 per tonne
It would be good to get an update on the Palm Kernel pricing, as strength there has also been a big driver of recent upgrades.
There is also the issue of recent flooding:
Consistent with the Group's announcement on 2 December 2025, work to restore normal operations at the Simpang Kiri estate in Aceh following some flooding has progressed well and there was no material impact on the Group's crop, production or costs for 2025.
They pointedly don’t say that there has been no impact to 2026, which leave this open to the possibility that production may be down
Forecasts:
Cavendish sees EPS dropping by 27% in FY26 to 154cents, based on a $750/tonne mill-gate CPO pricing. There is still scope for this to be upgraded if pricing remains firm. However, they say it is too early in the year to consider this. Whatever happens they expect the dividend to increase, and give a 4.8% yield.
Mark’s view
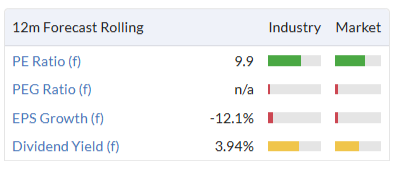
The share price has done well over the last few years. Despite this, it still trades on a forward P/E of less than 10:
However, it has always been a cheaply-rated stock, reflecting that it is largely a commodity play. Over the very long term, management has done well, growing the business. However, overlaid on this is significant gyrations in price reflecting the medium-term commodity cycle:
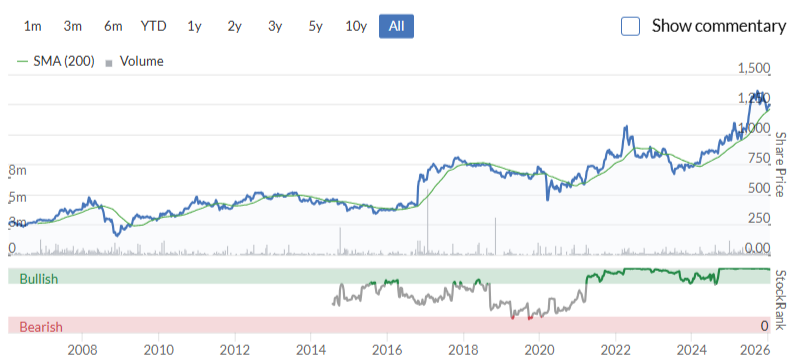
I don’t expect that to change anytime soon, so anyone investing here absolutely has to take a view on where we are in that commodity cycle. Those who are bullish and expect current CPO and PK pricing to remain elevated, will see further upgrades and upside to come this year. Those expecting the recent commodity pricing strength to moderate, may be better off getting out ahead of that. The recent declining Momentum Rank and share price chart suggests that at least some larger investors are taking that view:
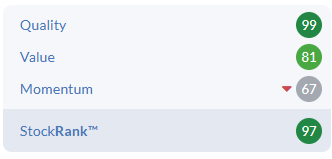
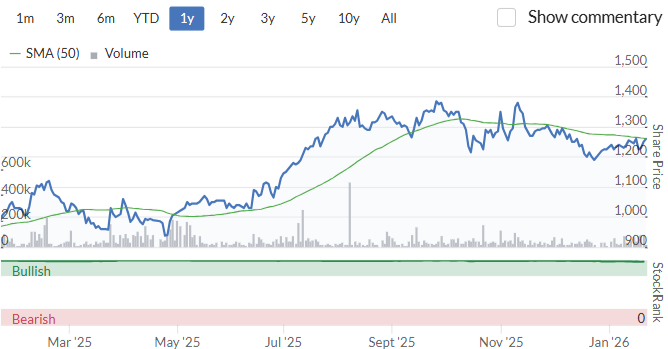
However, it remains a SuperStock, and not that expensive, so I don’t think these concerns are enough to change our previously mostly positive view of AMBER/GREEN.
Kooth (LON:KOO)
Up 7% at 112p - $2.6m contract win with new US State - Mark (I hold) - AMBER/GREEN
(At the time of writing, Mark holds a long position in this stock.)
Details of this contract win are a little vague:
…announces that it has agreed the terms of a one year contract with an undisclosed US State (the "State") for the provision of digital mental health services for up to 100,000 students. The contract has an expected value of $2.6 million (the "Contract").
The sad fact is that provision of mental health services has become a bit of a political hot-potato in the US. The issue seems to centre on the idea that parents should be involved with all aspects of care for their children, including mental health. This makes sense until you realise that this may also stop teens accessing the support they need, in some cases. Like so many seemingly unrelated things these days, this has been polarised along political lines. So this contract win is far more likely to be a “Blue” state than a “Red” one.
The one year contract term suggests that there is a certain amount of trial to this win. Their landmark contract in California averages out at $47m revenue per annum, and serves 6 million 13-25-year-olds statewide.
However, winning business in a new state, even for a smaller number of users and an initial term, is good news, as it expands the potential for future wins and longer term contract extensions. A British company winning these contracts against what is usually much larger US corporations suggests that their product offering is particularly strong.
The strength of the market reaction reflects this potential, plus that the shares have sold off significantly since their July trading update disappointed the market. The issue is that they rather surprised the market by spending £7.2m on direct marketing in H1 to support their California contract. I suspect that this spend was always planned, but that this was very badly communicated to the market.
In September, they guided adjusted EBITDA down 6-8%, but due to FX impacts rather than trading, meaning the £9.4m EBITDA Canaccord forecast still stands. It is disappointing they didn’t take the opportunity today to confirm this. Even if they get close to this, an EV/EBITDA of less than three seems low for a company with a unique product and significant growth potential.
Mark’s view
This contract win shows why I have kept the faith here, despite a recent share price performance suggesting that FY24 trading was a one-off that would never be repeated. The concentration risk remains high. California remains around 90% of their US revenue, even with this additional state win. However, the upside remains high, as the ability to roll out their platform across many more states and into other countries is undiminished. I don’t see that badly communicated marketing spending changes that.
The shareholder register also gives me confidence that this potential may eventually be reflected in the share price:
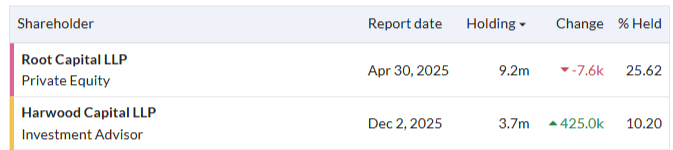
In a separate announcement today, Harwood/Rockwood went above 11% on 20th January. The Root Capital holding is a stub from listing, and appears to be held in Root Capital II Fund, which has been in disbursement for sometime and may even be the fund's last holding (Root was renamed ScaleUp in 2021). They last placed shares at £2.80 and while that may be some level above today’s price, I think it would be around that level that Root would be looking for an exit. It may require a renewal or extension of the California contract to be in the bag, to give some earnings visibility. However, there looks to be a deal to be done to me, if any of the US healthcare tech providers wanted to scale up in a growth area.
This is all speculation on my part and should be taken with a pinch of salt. However, I think the shares look better value today than they did when I took a broadly positive view following their last contract extension, so am happy to remain AMBER/GREEN.
Works co uk (LON:WRKS)
Down 17% at 34p - Interim results and Christmas trading update - Mark - AMBER ↓
There appears to have been some speculation yesterday that this trading update would be good. This means that the share price reaction today isn’t as bad as it looks, as the stock has just reverted to the level earlier in the week:
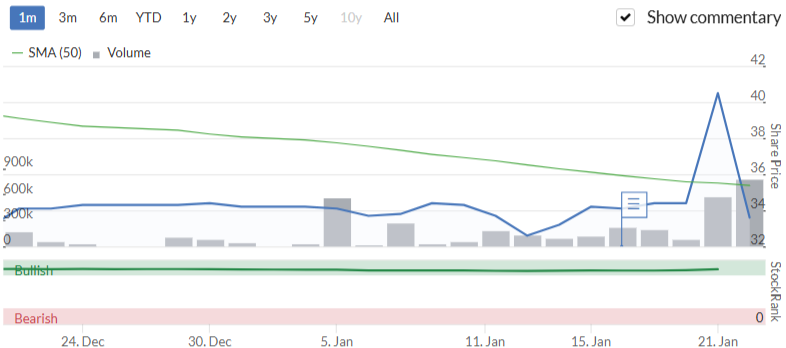
As it happens, these are said to be in line with previous expectations:
Remain on track to deliver FY26 profit in line with market expectations of pre-IFRS 16 Adjusted EBITDA of £11.0m and sales and profit growth in FY27.
Christmas Trading:
While the overall performance may be in line, there is significant variation between stores and on-line. H1 sales were already known at +4% LFL store and -36% LFL on line. Christmas trading doesn’t look great though:
Over the 11 weeks to 18 January 2026….Store LFL sales increased 1.2%…online LFL sales declined 51.8%, in-line with our revised expectations as we went into the festive period, resulting in total LFL sales declining 4.2%
They had problems last year, and booked £1.2m of exceptional fulfilment costs due to issues with third party logistics. This led me to question how ahead they really were last year. If they hadn’t excluded these as one-off, they would have missed expectations and not beaten them. And these issues have proven to be anything but one-off - they changed logistics suppliers, and appear to have had an even worse performance. In their results presentation, they confirmed that they will still be booking “a small amount of exceptional fulfilment costs”. They say this should be lower as the biggest impact is on profit by controlling demand. However, this does question how in line they really are without seeing the figures.
While they largely blame the logistics providers, I can’t escape the feeling that if they have had similar issues two years running with two different providers, the issues may be internal, not external. There appears to be no mention of any claims against either of the supposedly under-performing logistics companies.
In the H1 results released today, there are no exceptional fulfilment costs, but they do exclude £0.5m of costs related to the change of logistics provider:
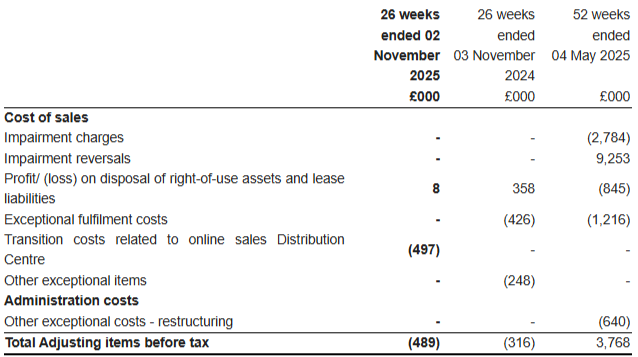
If we accept these adjustments, then there are signs that they do have some positive momentum. Adj. LBT is down to £5.1m from £6.5m, in their typically loss-making half.
Balance sheet:
Net debt excluding lease liabilities is down from £8.5m to £5.3m, again in a period where inventories will be at a high. Lease liabilities still exceed lease assets by £13.8m, this is down from £19.2m the year before suggesting that they are in a better position on their leased estate.
Net tangible assets have increased over the last year, due to retained profits, but standing at just £6m there isn’t any real asset backing here. There is no dividend, and I still don’t think they are in a strong enough position, over the whale trading year, to pay one any time soon. Not least, they would need to do a capital reduction to form a distributable reserve, as retained earnings are negative.
Mark’s view
I’m struggling to form a cohesive view on this one. Let’s weigh up the evidence:
Pros:
If you accept the adjustments its still very cheap on forward earnings
H1 results suggest reasonable momentum on earnings and debt
The store performance is very credible in difficult market conditions
In line for the FY despite online issues.
Credible strategy of focussing on non-screen-time activities for children
The Stock Rank is 85
Cons:
Online performance very poor for second year running and I’m not convinced they have yet got a handle on this.
Ongoing exceptionals not very exceptional, and cast doubt on the quality of previous ahead announcements
Retail is a highly competitive sector
Momentum Rank 54 and 6m share price down 30%
No capacity for dividends or buybacks in the short term
Not much downside protection should things go wrong.
I think overall I’m going to stay neutral, at least until it is clear that the online issues are behind them. AMBER
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

41 comments
Zotefoams (LON:ZTF)
Nurzel
Peel Hunt increased FY25 EPS forecast by 6.6% and left outer years unchanged.
are you 100% sure that the Peel Hunt update you mention was actually yersterday ie its not an old historic note ? - i have been unable to find link for update by them post reults confirming that 2026 expectations have been kept as they were previously. I am unable to find any updates at all that cross reference 2026 expectations yesterday.
Thanks for the extensive coverage again today.
On Tristel (LON:TSTL), as Mark mentioned the results continue the trend of 10% plus revenue growth. I'm inclined to be a little more generous to the interpretation of the CEO leaving. "The opportunity I have to return to the US with my family, and to work in such a senior role with a large US multinational, is one which resonates with me on a personal level." That sounds to me like he got a job offer from a larger firm that he felt he couldn't turn down along with the personal reasons for going to the US that Mark highlighted. Digging into the details a bit more there are quite a few positives.
H1 Financial Highlights
· H1 revenues increased by 14% year-on-year
· Gross Margins maintained at 81%
· Adjusted EBITDA increased by 17%
· EBITDA margins of 28%, comfortably ahead of the 'at least 25% target'
· Continued progress in US with revenue growth in line with internal forecasts
· Tristel continues to be debt free and cash generative
(I hold)
Ingenta I think you really need to add that this is a tiny company that is too small for any institutions - not necessarily a bad thing - but that daily trading is rarely over £100k which does bring its own risk despite a relatively large cash balance and no debt.
MP Evans - I don't see the this is in any sense 'green' - indeed it strikes me that is is basically the opposite thereof. Palm oil is mostly used for processed foods and the increase in plantations has hugely impacted wildlife through deforestation. Where am I wrong?
Computacenter I am highly prejudiced as this is a big holding for us but the release today is extremely good and if the p/e is a little elevated the RoCE is really excellent. There should be a lot more to come terms of earnings growth. If the stock were not so tightly held - from memory around 40% is held by the founders and their charities - better liquidity would tempt bigger players onto the share roster.
Vanquis Banking (LON:VANQ) my top pick for ‘26 is in demand today and banging its head against 120 again. Looking for this to revisit 130 before results next month. I’ve always seen this as a potential bid candidate. Now would be the time for an opportunistic bid, with the company having turned itself round.
Pleased to see PayPoint (LON:PAY) back above 500 and pulling away. Phew! Thanks to Graham for the heads up on this. It had been on my watchlist for some time but never hit the buy button until Graham reviewed it as one of his picks for the year.
Excellent work Graham in Covering such a large number with cryptic comments ; thanks.
Surprised that the Works co uk (LON:WRKS) WRKS is not mentioned at all today as quite a few knowledgeable small caps investors have this as one of their NAPS for this and next year and a friend of mine and I both have very large positions in it. They reported today, price dropped a lot, but the broker (Singer) note is very strong.
Works co uk (LON:WRKS) was up 17% yesterday. Not sure the size of your holding, has any bearing on which stocks, get covered on here.
Picked in NAPs? There are lots of higher ranked stocks in the CC sector than Works co uk (LON:WRKS) it was ranked SR85, l believe. Currently there are 20 CC stocks, ranked 90 and above.
There are a lot of stocks reporting today and now they are not covering just small caps, there are bound to be some not being covered.
Results are coming thick and fast. So much more to talk about than I will.
Judges Scientific (LON:JDG) down 11% on warn. A far cry from their peak at over 11000p. Back then they had a value score of 5, so that would have been a good cue to take a little off the table at least. Fwd PE is 19 and interest cover is less than 5, so it's not quite my cup of tea. If I already had shares, I'd probably continue to hold. But I wouldn't add or buy. Just me view. They seem to have lost their way a little.
Computacenter (LON:CCC) up 8.3% (I own). I liked the quality and growth of this one, which is why I bought. PE of 16.6 looks acceptable to me.
B&M European Value Retail SA (LON:BME) Down 0.6% on lfl of 0.6%, coincidentally. I used to own this one, but sold at a loss. That net gearing looks awfully high to me. An Enterprise Value of £4b against a mkt cap of £1.7b looks mighty leveraged. These guys had better turn the situation around, I think. The sooner the better, too. Things are beginning to look distinctly iffy.
AJ Bell (LON:AJB) Up 3.7% on a nice set of results. Good quality company that's on my radar. I don't own, though (don't let that put you off, I think it's a good company). Value score is 29, too, fwd PE of 16.6. Looks like a good buying top-up opportunity to me. I think Plus500 (LON:PLUS) and IG group (LON:IGG) are good alternatives (I own both, but I think PLUS is stronger than IGG).
Tristel (LON:TSTL) Up 1.4%. Revenues up 14%. Nice. I bought some in Oct 2024 at 395p, and some earlier this year at 436p (now 405p). The latter was arguably a mistake. I think it had been tipped in Investors Chronicle not long beforehand. I was (vaguely) aware of that, but bought anyway. So everyone loaded up, leaving the share price nowhere to go. Hence the muted reaction to the results.
Fwd PE is 21, which is at the racier end. Value score is 25, which is OK enough if you think you've got a good long-term steady compounder. TSTL seem to be doing everything right, and I think there's a good long-term story here. I'll probably be looking to top up in future as circumstances allow.
M P Evans (LON:MPE) Up 2.8%. I'm doing OK on that, up 38% since I bought in May 2022. I'm thinking of perhaps taking a little off the table. Palm oil prices are high, so maybe a good opportunity to take some profits (?). Indonesia is getting increasingly political. Some (non-MPE) plantations have been taken over by the gov't. The plantations taken over were not legit with the planning permissions (etc.), apparently. MPE is above board, but it still makes me nervous. Govt's have "ways and means" of bringing companies onside, and, well, I'm just anxious about it. In the past the board have expressed their confidence in the political situation. Make of that what you will.
Young & Cos Brewery (LON:YNGA) up 4.2%. I don't hold, but it seemed an interesting company given the travails of the sector of late. LFL +11.2%, which is more than satisfactory. I wonder if it is in a position to clean up as others succumb to the pressures. I intend to continue watching to see if I'm right. Should be interesting.
"An Enterprise Value of £4b against a mkt cap of £1.7b looks mighty leveraged."
B&M European Value Retail SA (LON:BME). I think that must include lease liabilities. Just looking at cash vs. borrowings in the latest interim results I get about £850m of net debt, which would give an EV of £2.5b against a mkt cap of £1.75b. Whilst I'd rather my stocks all chose to run with net cash rather than net debt, I don't see £850m of net debt as a problem in the context of around £450m operating profit pa.
Non-current lease liabilities outweigh non-current right-of-use assets by about £80m, so I guess one should really add that as well, so call it £2.6b EV. Current trade payables and current lease liabilties all neatly net-off against current inventory. Overall I'm not too concerned about the balance sheet; they've deliberately leveraged somewhat by paying special divs in the past and could cease that in the future if required.
I hold a small position as of 2 days ago in my value portfolio. Very cheap on a p/e and fwd div basis, and the fairly new CEO has bought the best part of £1m quids worth in the market over the last 6 months, at both lower and higher prices than today.
B&M European Value Retail SA (LON:BME)
I think that must include lease liabilities.
Correctamundo - they were £1.2 bill per last annual report so i would be excluding that amount from my calcs. I nearly got suckered in here when the new leader came in and i thought he had likely kitchen sinked everything - i was tempted to go aisnt tyhe faling knife. Couldnt have ben more wrog - i have been spectacularly unimpressed by new leadership - as highlighted well by Graham , they dont half spout some gibbersh to cover up pooor trading. Is it a cash money making machine that wil sort its woes at some stage - almost certainly - but i am in no hurry to take the plunge whilst things are still trending worse.
Once again, MC, nobody cares a hoot about whether you have gained or lost on your share dealings. Its totally irrelevant to anyone but yourself. You are pretty well the only person on Stocko who insists on doing this, just about every post you make.
Your comments on companies are, however, useful and interesting..If you could stick to just that I for one would be grateful.
What a horrible comment
Very rarely come on here nowadays and have my account set to cancel on renewal
Stocko should take note, far to many keyboard warriors on here nowadays with nothing of value to add!
a lot of the posters worth listening to are no longer here, that should tell you something
Can someone hep me out with a trade type please as I am a novice?. I see that there were Off Book trades totalling 104,228 shares in Ashtead Technology (LON:AT.) this morning. Why do these trades take place outside the usual institutions? I just wanted to understand the potential implication, if any, of the movement of this fairly sizeable chunk of shares. Any input would be appreciated. Thanks
Extract from Google Gemini when I posed your general question, not specific to Ashtead Technology Holdings (LON:AT.) .Just put your question in and it gives a good run down of the potential reasons then you can dig deeper and see what it says about the specific company / trades you're interested in. I find it really good for all sorts of questions related to shares, finance, portfolio management, etc. Just double check the accuracy before you action anything.
Thanks Cayman69. Everyday is a school day
Biffin - nobody else has replied to your question so let me have a go. The majority of trades for larger stocks are done via an order book. Basically you enter the number of shares and the price at which you are prepared to buy or sell them and these are automatically matched with other entries. These are labelled AT = automatic trade. The likes of you and I do not have access to this process so we go via our broker to a 'Retail Service Provider' (previously called market maker) who run their own books and try to match prices on the order book. So when you deal with them it is a trade off book usually labelled O. There is often an advantage here. Trading on book is always at the quoted bid or offer but RSPs will often go inside those quotes (the 'spread'). So as an example with Ashtead Technology Holdings (LON:AT.) at 12 32 the bid price on the book was 409.5 and the offer 411.5 but we have an O trade of 1529 shares at 410.5322 - inside the spread.
Edit - I see that while I was writing this another person replied. I will leave this up as it is from a slightly different angle.
Thanks sharw, much appreciated.
Mark Thanks your write-up on M P Evans (LON:MPE) . I find today's TU disappointing and high stock rank unjustified. Sadly the Mkt gives them no credit for being 'green' Maybe if prepared to hang on, things will change - but for now, If you compare to AEP Plantations (LON:AEP) they are the clear winner over the past few months. But maybe best to look elsewhere for better opportunities
Whoops - M P Evans (LON:MPE) up 5% now
NCC (LON:NCC)
With a deluge of trading updates at 07 00 each day this week readers may not have spotted that yesterday afternoon NCC confirmed what Sky News (who else?) had told us earlier in the week - that they have sold the Escode half of the company to private equity for £275m. This leaves them as a pure play on cyber security.
We are told "As the Cyber business review includes the possibility of a potential sale of the entire issued and to be issued share capital of the Company, NCC remains in an offer period under the Takeover Code".
Chris Mills of Harwood reckons that on a split and sale of both parts the shares are worth 200p. You can find his thoughts here.
The trouble is that whilst 'cyber security ' sounds exciting, it has consistently delivered low growth and poor margins. Hence the market seems to be taking the view that NCC (LON:NCC) has sold off the good bits and the rump isn't worth as much as Harwood thinks.
Surely a bizarre reaction to the Zotefoams (LON:ZTF) trading update? Very strong numbers for the year to Dec 2025 and I think we already knew about moderating footwear sales to Nike in 2026. Certainly forecast revenues for next year on Stocko are only £175m when mathematically you get to £182m with a full twelve month contribution from the Konstellation acquisition added to this year's £156m (ex Konstellation). Does anyone have any updated broker forecasts from today?
Peel Hunt increased FY25 EPS forecast by 6.6% and left outer years unchanged.
Thanks, Nurzel. Should rally again then.
Zotefoams (LON:ZTF)
Surely a bizarre reaction to the Zotefoams (LON:ZTF) trading update?
Not really - whats more important the udpated expectations ref 2026 and 2027 - or the rubber stamping of what happened last year? . If the market is slightly worried that 2026 forecasts might be downgraded in next few days - its natural that thats overall bad news rather than good. Invariably if 2026 was to take "hit" so would 2027.
The market has little room for companies promising chomping double digit returns - to then not deliver on then promise - if you are growing be cautious ref promised growth and updgrade as you go !. Its them thats chosen to say 2026 would be 17% better than 2025. Thats a big ask they have set.
Does anyone have any updated broker forecasts from today?
i cant find any but i only did quick search - bnroker upate saying 2026 is on track is probably the missing bit today. Ok looks like 2026 left unchanged - thats good news.
You are reinforcing my point, rmillaree. I think that Zotefoams (LON:ZTF) have already flagged the lower footwear sales as evidenced by the forecast of a like-for-like fall from this year's revenue of c£7m. I am hoping that this means they are set to meet or beat this number. We shall see.
Zotefoams (LON:ZTF)
If their broker of choice has updated today to keep forecasts intact - thats good news - gives me the confidence i needed . so i would agree with your comments 100% that although its mentioned it hopefully was expected and factored in already - or can be clawed back elsewhere.
Shame they dont add simple line to say something along the lines of "overall we are confident entering 2026" thats enough nudge nudge wink wink to me to say they are on track if for some silly reason they arent meant to say it without checking with brokers or whatever.
with beat for year just finished and steady as you go update 6% decline is slightly surprising - without specific good news ref future though some may always depart then building after update.
Hi rmilaree, not sure whether your reference to "chomping double digit returns" is a general observation. Certainly Zotefoams (LON:ZTF) hasn't promised such.
Anyway each to their own.
Zotefoams (LON:ZTF) is hardly expensive if one believes current forecasts. In fairness I think that operationally Ronan Cox has so far played a good hand; the investment in Vietnam, appointment of Brandon Thomas (ex Nike) , partnership with Seohung in Vietnam and Spanish acquisition.
One of my few gripes is the paltry number of shares acquired by the new management team sort of reminds me of MPAC (LON:MPAC) where the same criticism applies. Having said all of that I own a few Zotefoams (LON:ZTF) so am singing from my own song book.
All the best
Zotefoams (LON:ZTF)
Hi rmilaree, not sure whether your reference to "chomping double digit returns" is a general observation. Certainly Zotefoams (LON:ZTF) hasn't promised such.
i might have played slight loose with wording - but stocky is showing 17.5% expected growth in net profit/eps 2026 - thats what i was referencing well over 10%. to me 17% is chomping growth compared to your average uk listed company and espcially bearing in mind how well they have done the last 2 years.
One of my few gripes is the paltry number of shares acquired by the new management team sort of reminds me of MPAC (LON:MPAC) where the same criticism applies. Having said all of that I own a few Zotefoams (LON:ZTF) so am singing from my own song book.
I think thats ofte justa fact of life nowadays if its non founder people - or (hopefully) more good mangers rather than entrepreneurs. You are right that they can take outsized riask with our money and they can walk away if it goes tits up. I thinbk zote board havae always been reaosnably sensible though - albeit perhaps their blu sky stuff they obviosuly got wrong.
I just dont think there are enough managers who want to come in and chuckm like 200-300 of their money at shares.
Kitwave (LON:KITW) bid looks low ball to me but seems a done deal so I sold up at the open this morning. Happy to move my money elsewhere at this stage
Fonix (LON:FNX) reads well and no justification for the share price weakness over the last 6 months. European expansion looks interesting and continues to pile up cash so another increased dividend coming.
Kooth (LON:KOO) Good contract win and bodes well for the California contract which runs out in the summer.
I like Fonix (LON:FNX) for the medium term - the technology seems to work, clients appear sticky, good runway, strong balance sheet and a nice divi - so we are being paid to wait. I've held for a while and seen my profits erode as the price has slipped, but today's update has prompted me to top up a little.
I agree that the bid for Kitwave (LON:KITW) looks low. I don't hold but since coming to market they have impressed me as a well-run company in an unfashionable business, and they have been on my watchlist. Stocko gives the exit PER as 7.5.
Young & Cos Brewery (LON:YNGN) Yet another of my AIM portfolio decides the grass is greener on the main market. Is there really evidence for that? Several possible replacements: Nichols (LON:NICL) and James Latham (LON:LTHM) top of the possibles for LTBH; I try not to tinker. Any other suggestions welcome but with a combined portfolio of over 80 shares (not all AIM) might already have them.
About time they woke up and also got rid of the two classes of shares. I sold out months ago but kept Fuller Smith & Turner (LON:FSTA) . Lathams is a great company but I sense they are controlled by the family for the family - better opportunities elsewhere for the rest of us. But they have been on the rise past few days since they bought back some Pref shares.
Quiet day for news today, then.
Zotefoams (LON:ZTF)
Nice beat on adjusted pbt - £21.1 mill v £20.5 forecast so well done to company here - these are record results.
Note per current forecasts they are expcting to add another £3 mil of net proifts for 2026 - thats a forcast increase of 17.5% - so thats adecent ask - helts hope they are being conserative.
Key here is conirmation 2026 forecasts havent been dropped - so we are completely in the dark until we get broker updates - an all to common unanceptable position unfortunately.
One minor worry is the following bit ref by far their best sectr which mentions moderation and normalisation - not what you want to here when they are expecting to deliver higher profits and we done have explicit confirmation unless i missed it that 2026 is on track despite comments below.
After an extended period of strong growth, we anticipate that demand from our footwear customer will moderate in 2026 reflecting normalising inventory requirements. EMEA revenue also includes £2.0m from the recently acquired Overseas Konstellation Company S.A. ("OKC").
Hopefully they are simply capacity restricted present and new Vietnam facility should provide uplift - or they have suitable plans despite above comments - nothing specific to really worry me.
Looks like they have a year of hard work moving from China to Vietnam - hopefully the new facility is cutting edge compared to waht they have now. Not without execution risk though such a change.
I might have been tempted to sell this had rating got to decent multiple - they are clealry in a sweet spot but that doesnt alwasy last forever - i am probably being overly cautious though they are certainly delivering and capacity should be increasing unless broker updates say otherwise.
Sounds like a comment to add in the possibility of a mild profit warning
Zotefoams (LON:ZTF)
Sounds like a comment to add in the possibility of a mild profit warning
the answer is i dont know - and if we have a broker update the answer is contained there - i dont get how listed companies can update soem off book and not tel shareholders straight. Hopefully there is no mild profit warning - or if there is its done via broker that we have out in plain sight before 8 am. i am not in the chosen group ref broker updates - if there is one i aint seen one. In absence of specific downgrades its probably business as usual.
one issue i am probaly ignorijng here is thats its probbaly not pracgticable for brokers to always get up to speeed if stuff is doen over xmas and new year - do they keep working so its buisnes as ussual - or do they just say to the company - you are on your own here ref futiure forecasts - just dont say anything while covering your back.
I would like to think if they were going to downgrade fro this eyar taht would be out in the open - we may have to wait. If i had to guess i would say hopefully they are still on track ref 2026.
Commiserations to holders of Judges Scientific (LON:JDG) after this morning's trading update.
Judges Scientific (LON:JDG) has been a bit of a private investors' and bulletin board favourite over the past decade or so. And it's been a great investment. But lately the stock itself has been locked in what Stan Weinstein identified as a fourth-stage decline (https://www.investopedia.com/a...). These are the kinds of situations that I've struggled with over the years, caught in the grip of an internal tension between taking profits and holding on long term, like a 'proper' investor with a business mindset and all that. Often times, when I've realised its a good idea to sell, it's often been too late, and much of my gain has disappeared again. Have others grappled with the same psychological challenges? Or has it been difficult to think of stocks as one thing and their underlying businesses as something else? Maybe that last question leads to a solution? Maybe Stockopedia can be a big part of the solution for many? Am I, perhaps, alone in my internal agonies?
Bob, I expect most of us can relate to what you said. IMO the recovery at Judges Scientific (LON:JDG)will have to wait until the market for selling scientific instruments to Government labs recovers, especially in the US. So the question is whether this might happen when a new administation comes to power, or more gloomily in the distant future when public debt is back under control.