Daily Stock Market Report (Fri 26th June 2026) - DFCH, WISE, DEVO, HERC

Good morning. Apple increased the prices of its MacBook and iPad products by 20% yesterday, citing memory shortages caused by the AI boom.
While the US firm has held off from hiking iPhone prices so far, the decision sparked a 6% drop in Apple shares yesterday over concerns that consumers would be unable to absorb higher prices. This triggered a broader sell-off in Asian indices – the Nikkei closed down nearly 5%, while Korea’s chip-heavy Kospi index closed nearly 7% lower.
The AI boom has driven fantastic profits for many companies in the sector, but it is hardware intensive and global semiconductor manufacturing capacity is constrained and relatively inflexible. It may be worth watching for further company-specific impact from such shortages.
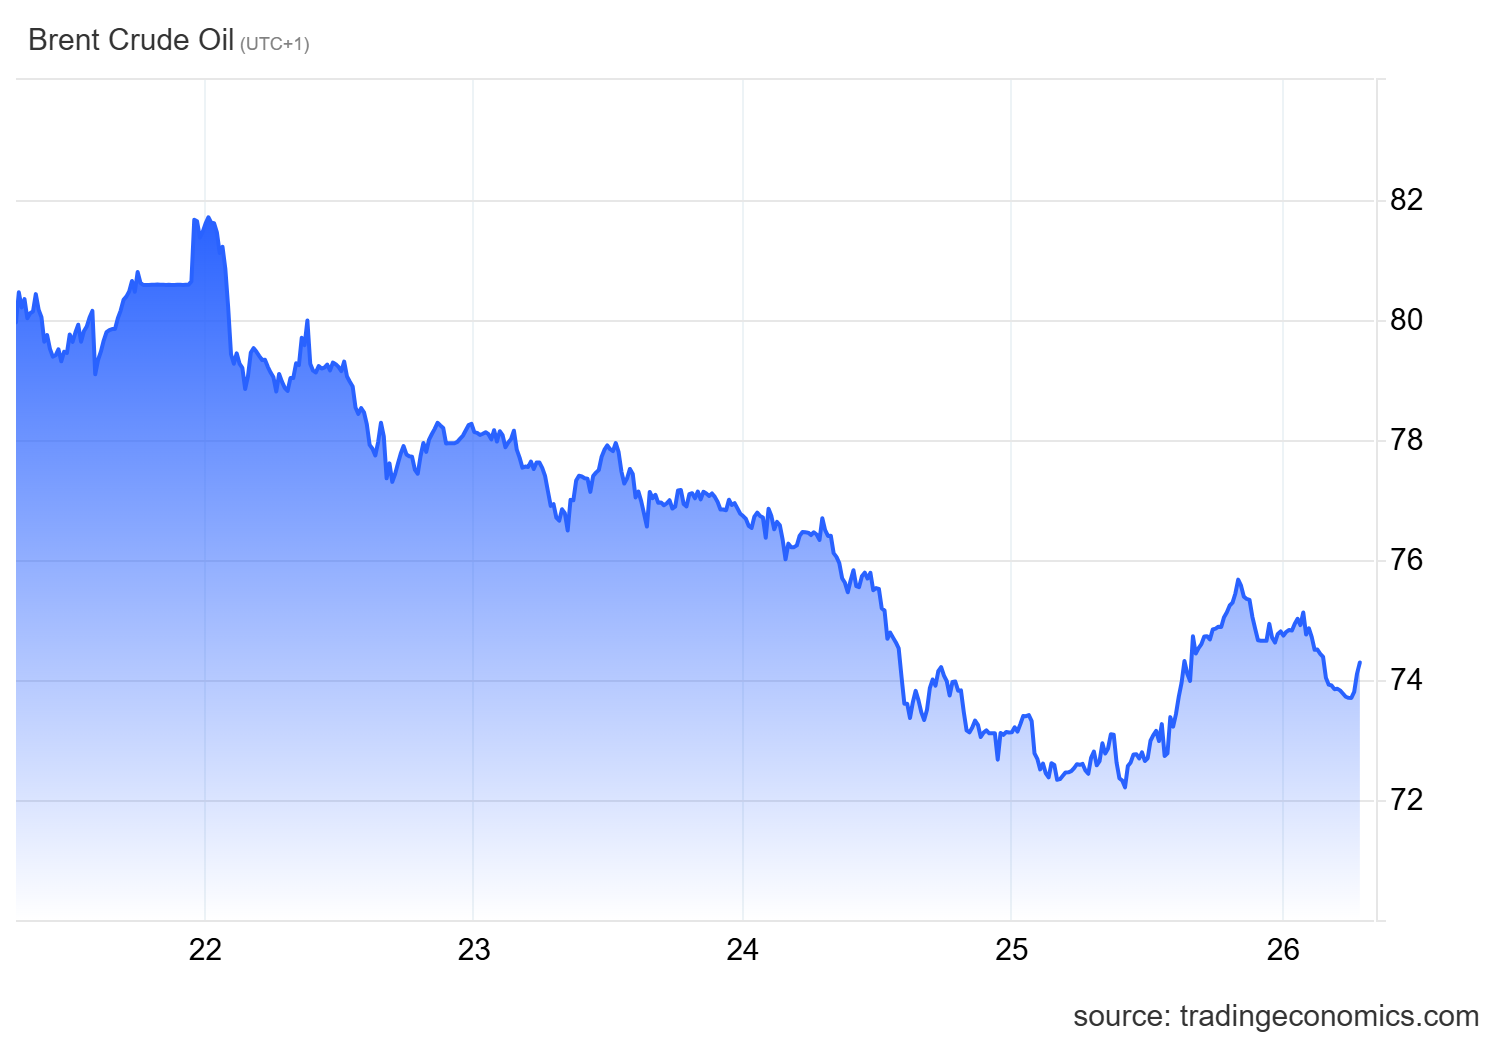
Elsewhere, a number of oil tankers attempting to exit the Strait of Hormuz turned round and paused their journeys after a ship was attacked on Thursday. The International Maritime Organization has paused its evacuation programme for ships bottled up in the Strait. However, the impact on oil prices has been very limited so far.
Finally, this week’s European heatwave is said to be the worst on record. It’s described by scientists as being impossible without climate change. With increasing health impacts and risks to key infrastructure, I wonder if this will become a greater area of focus for policymakers (and businesses) over the coming years.
On a related note, apologies if there is some disruption to service this morning - the thunderstorms here in the north east have triggered power cuts and my internet connection is intermittent.
Overnight market movements:
The FTSE is set to open down 0.6% at 10,470
S&P 500 is down 0.7% at 7,307
Brent crude (August) is down 1.2% at $74.55/bbl
Gold is down 0.5% at $4,013/oz
Bitcoin is down 2.9% at $59,767
Today's report is now complete. Thanks for bearing with me today, I hope you have a good weekend.
Spreadsheet accompanying this report: link
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
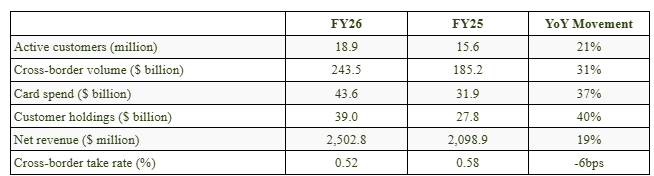
Wise (LON:WISE) (£10bn | SR53) | Net revenue +21%, with pre-tax profit down 8% to $660.4m. Take rate -6bps to 0.52% with cross-border volume +31% to $243.5bn. Active customers +21% to 18.9m. Outlook: expects FY27 net revenue growth in the middle of the 15-20% range, with pre-tax margin around the top of the 20-25% range. No change to medium-term targets. | GREEN = (Roland) I think these results show that Wise is continuing to execute on its long-term strategy of building market share by providing a high-quality and keenly-priced service. The falling take rate and decline in profits don’t concern me. Margins remain high and rapid volume growth means that management should be able to manage profitability as needed. While this business model does carry risks – as highlighted by the ongoing Belgian money-laundering investigation – I think the investment thesis remains attractive and am comfortable with the valuation. | |
Barratt Redrow (LON:BTRW) (£4.2bn | SR43) | New CEO Dean Banks will join on 21 September 2026. The current CEO will step down at that time but remain with the group until March 2027. | ||
Zegona Communications (LON:ZEG) (£3.8bn | SR96) | Completed refinancing of “all its existing senior secured notes and senior facilities”. Improved terms will deliver annual interest savings of c.€60m and extend the maturity of Zegona’s capital structure beyond five years. Annualised interest cost of the new debt structure is €170m. | ||
XPS Pensions (LON:XPS) (£627m | SR61) | Acquired Austin Professional Resourcing LLP, a UK-based actuarial consultancy working with insurers and financial sector clients. APR generated revenue of £10.7m last year. Cash consideration of £3.3m will be paid on completion, with £3m due in 2027 and further contingent payments totalling up to £10m in years two and three. | ||
Guardian Metal Resources (LON:GMET) (£429m | SR27) | The company will publish its pre-feasibility study for the Pilot Mountain Tungsten Project on 30 June 2026. | ||
Beximco Pharmaceuticals (LON:BXP) (£385m | SR n/a) | Late results: FY25 net revenue +10.7%, with profit after tax +19.3% to BDT 6,999m (£42.1m). EPS of BDT 15.56, recommended dividend of BDT 4.75 per share. | Beximco shares have been suspended since 2 Jan 26 but will resume trading today. | |
Kistos Holdings (LON:KIST) (£191m | SR43) | Revenue -1.6%, adj EBITDA +1.3% to $96.6m. Net debt of $76m. Average production of 8,940 boepd. FY26 production guidance unchanged at 19,000 - 21,000 boepd. | Slow to publish FY25 results. | |
Aew UK Reit (LON:AEWU) (£165m | SR59) | NAV per share down 1.42% to 103.38p for y/e 31 March, with NAV total return of 5.7%. EPRA EPS down 11.3% to 7.98p, giving 99.8% dividend cover for the unchanged payout of 8p. EPRA vacancy rate of 9.4% at 31 March (FY25: 7.5%). | ||
Distribution Finance Capital Holdings (LON:DFCH) (£99m | SR64) | H1 update: new loan origination expected to close at c.£1bn, +21% vs H1 25. Aggregate loan book is expected to close >£915m, +25% vs H1 25. Outlook: average loan book has exceeded expectations in H1, now expect to report full-year profit ahead of expectations, with pre-tax profit of at least £13m and ROE in excess of c.17%. | GREEN = (Roland) Another upgrade from this fast-growing specialist lender. Updated broker forecasts suggest encouraging earnings growth and the valuation remains very reasonable in my view, with a discount to book value despite last year’s 12%+ return on equity. Small lenders always carry some risk, but I’m happy to stay fully positive here given the strong fundamentals and good momentum. | |
Devolver Digital (LON:DEVO) (£85m | SR55) | H1 performance ahead of expectations with revenue expected to be “at least 60% higher than 1H 2025” and adj EBITDA expected to reach “mid single-digit” $m. Strong start due in part to the Devolver Steam Publisher sale held in H1. However, sales of a recent major new game have been disappointing so far. No change to broker forecasts. | AMBER = (Roland) Devolver had a strong start to the year, but a recent game launch has been disappointing (so far). It’s too soon to know if the shortfall will be covered by the remaining slate of new games scheduled for H2 - the company has promised an update in September. Broker forecasts are unchanged today, but my number crunching suggests there could be some risk of a profit warning later this year, without a fairly strong H2 performance. Net cash of $37m underpins the market cap and a forward P/E of 11 isn’t unreasonable. But a lack of visibility or obvious bargain characteristics means that I’m leaving our neutral view unchanged today. | |
Clean Power Hydrogen (LON:CPH2) (£68m | SR n/a) | Agreed settlement with Lagan MEICA relating to the Northern Ireland Water 1MW MFE220. Contract will be terminated through the payment of a settlement sum, but the settlement is contingent on a fundraise by 31 July 26. | CPH2 shares have been suspended from trading since 29 May 2026. | |
Zephyr Energy (LON:ZPHR) (£67m | SR28) | Acquired 27,000 acres in Utah, “doubling the acreage footprint around Zephyr’s White Sands Unit” in the Paradox project. Funded from existing cash resources. | ||
Panther Securities (LON:PNS) (£49m | SR56) | Sold freehold warehouse property in Peterborough for c.£3.25m in cash. This is a £250k increase on the book value of £3m. Proceeds will be held for reinvestment. | ||
Character (LON:CCT) (£49m | SR77) | A party connected with the new occupier of Infinity House has exercised an option to purchase the property. A deposit of £980k has been received, with a further payment of £8.82m due on 23 July 2026. | ||
Zenith Energy (LON:ZEN) (£31m | SR24) | The International Centre for Settlement of Investment Disputes will accept post-hearing briefs on 31 July 26 and 30 Sept 26 and deliver its final reward in Q1 2027 (estimated), relating to the claims launched against the Republic of Tunisia by Zephyr in the amount of approximately US$572.65 million. | ||
Defence Holdings (LON:ALRT) (£30m | SR11) | Completed £4m fundraising at 1p per share. Placing was “significantly oversubscribed and scaled back”. | ||
Cirata (LON:CRTA) (£23m | SR10) | Completed fundraising to raise gross proceeds of c.£5.1m at 15p per share (an 18.9% discount). 34.2m new shares will be issued, increasing the existing share capital by 27%. | ||
Ampeak Energy (LON:AMP) (£21m | SR16) | 2025 revenue 4.2% to £15.0m with EBITDA -53% to £3.7m and a net loss of £13.9m. Net assets down 60.5% to £6.8m. | Slow to publish FY25 results. | |
Hercules (LON:HERC) (£18m | SR36) | Secured enhanced debt facilities with IGF, comprising an increased invoice discounting facility of £20m (previously £16m) and £5m of term loans, of which £4m will be used to settle the final earn-out payment for Advantage NRG. | RED = (Roland) [no section below] It may be logical for Hercules' lender to increase the size of this credit line and offer additional loans, but I’m not convinced this is good news for shareholders. While the increased facilities are billed as helping to support the company’s growth, revenue is only expected to rise by 5% this year – hardly gangbusters. What this update suggests to me is a looming cash crunch. Hercules is borrowing to fund deferred acquisition payments, while also drawing additional debt to help turn its receivables into cash more quickly. Broker forecasts from SP Angel prior to today already suggested net debt of £10.8m at the end of September, paired with a full-year operating loss. Presumably year-end net debt will now be higher than previously expected. I don’t see any option but to retain our RED view today. | |
ARC Minerals (LON:ARCM) (£17m | SR10) | 2025 net loss of £9.1m (2024: £2.1m). Year-end cash of £635k. Recently began a geophysical programme at Virgo Point, targeting drilling in H2. | Slow to publish FY25 results. | |
Tap Global (LON:TAP) (£10m | SR5) | Tap customers will soon be able to receive their salary and third-party payments directly into their Tap account. Rollout for Euro area customers starts today, with GBP payments “expected to follow in due course”. |
Roland's Section
Distribution Finance Capital Holdings (LON:DFCH)
Up 9% at 65p (£m) - Trading Statement - Roland - GREEN =
DFCH is a specialist lender providing finance for caravan and motorhome manufacturers, dealers and more recently for individual buyers. Graham has been positive on this business for a while, most recently in April.
Today’s trading update is ahead of expectations and sounds fairly positive to me:
Full Year Profit expected to be materially ahead of market expectations driven by loan book performance and new product growth
Trading highlights:
New lending is running ahead of expectations and historic seasonality. New loan origination in H1 is expected to total c.£1bn, an increase of c.21% over H1 last year. The Q1 figure was £469m, suggesting a sequential Q2 growth rate of 13%.
The group’s loan book is expected to end the half year “in excess of £915m”, 25% ahead of the same point last year.
A new lending product aimed at consumers is seeing strong momentum, especially in the static caravan and holiday park sectors. The loan book is expected to reach £40m by the end of H1, a near-threefold increase from £15m at the end of 2025. Loans are originated through dealers who are already part of DFCH’s network. This product is also contributing to a longer average tenor for loans, which the company sees as a benefit.
Portfolio quality remains “exceptionally strong”, with the cost of credit risk remaining "well within" the group’s target of less than 1%.
Outlook
DFCH has provided explicit new guidance for 2026 today:
In light of the Group's average loan book exceeding expectations through the first half alone, coupled with continuing low arrears and impairments, the Group expects to report profit before tax of at least £13m for the period ending 30 June 2026, delivering an annualised return of required equity in excess of c.17%.
Broker Panmure Liberum has shared updated forecasts through Research Tree this morning. They’ve upgraded 2026 pre-tax profit forecasts by c.16% to £22.4m, citing the higher than expected average loan book (which improves interest income).
Earnings forecasts have been upgraded across the board:
FY26E adj EPS: 9.4p (previously 8.1p)
FY27E adj EPS: 10.6p (previously 10.0p)
FY28E adj EPS: 11.7p (previously 11.5p)
These estimates price the shares on FY26E P/E of 7x after this morning’s gains.
Roland’s view
This morning’s upgrade continues a run of upgrades for DFCH, highlighting the strong momentum in the business at the moment:
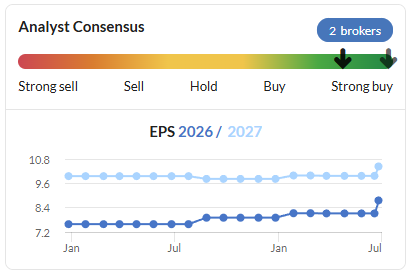
The valuation also remains potentially attractive, in my view. At 66p, the stock continues to trade at a discount to last year’s book value of 76p per share.
When paired with double-digit returns on equity, this seems fairly undemanding to me:
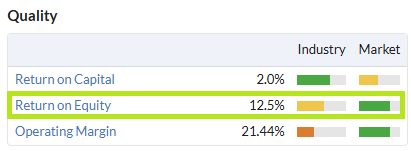
While the quality score remains low, the main metric I look for in businesses of this type is return on equity (paired with a healthy balance sheet). I think DFCH ticks both boxes and expect profitability to improve if growth continues and bad debt remains manageable.
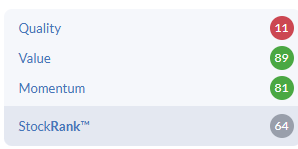
Small lenders are always quite risky, so I wouldn’t make DFCH a large part of my portfolio. But I’m quite comfortable maintaining our positive view on this business today. GREEN
Wise (LON:WISE)
Up 6% at 878p (£9.0bn) - FY26 Results - Roland - GREEN =
Thank you to subscriber David Holdsworth for providing some early analysis on today’s results in the comments.
Money transfer group Wise moved its primary stock market listing to the US in May, but has maintained a secondary listing in the UK. So I think it’s fair to maintain some coverage here in this (UK-focused) report.
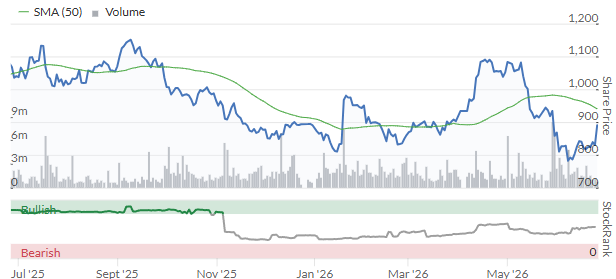
For some backdrop on recent share price movements, it’s worth remembering the stock fell by around 20% at the start of June. This was prompted by the news that Wise is being investigated by Belgium authorities, in relation to possible money laundering offences relating to c.€500m of transfers. There’s no update on this issue in these results.
Wise’s FY26 results showcase the characteristics I’ve come to expect from this business: rapid growth in usage with more measured growth in revenue, as Wise continues to focus on keeping it pricing ("take rate") as low as possible.
For some context on the company’s aggressive pursuit of low pricing, Wise’s take rate has now fallen from 0.64% in April 2024 to 0.51% in the three months to 31 March 2026. That’s a 20% cut in two years!
Financial performance: Wise’s profit performance is complicated by the fact that as a non-bank it’s ability to pay interest on customer deposits is strictly restricted. Even though it would like to be more generous with customers.
Graham’s covered this previously, but today’s commentary highlights the boost this provides to the group’s margins:
[We maintain our medium-term target for an] Income before tax margin of 15-20%, including 20% of interest income above the first 1% yield retained. However, until we are substantially able to pay out additional interest to customers, we expect to report an above-target income before tax margin of 20-25%.
With no immediate prospect of this situation changing, I think it’s easiest to follow the statutory accounts. These show a slight decline in profits last year, as expected:
Pre-tax profit down 8% to $660.4m;
After-tax profit down 9.4% to $498.7m;
Diluted earnings per share down 8% to 48.43c.
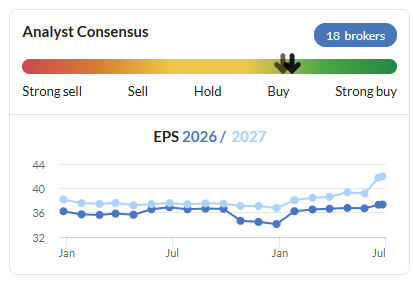
Applying today’s exchange rate gives me an earnings figure of 37.7p per share, which is very close to the consensus figure of 37.3p shown on the StockReport. So my conclusion is that these results are largely in line with expectations.
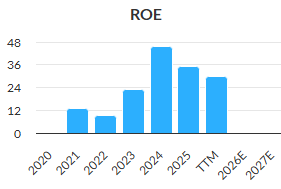
Profitability: these results give Wise a FY26 pre-tax profit margin of 26% and a return on equity of 25.9% – both excellent figures, albeit ROE is (intentionally) below last year:
Capital allocation strategy - buybacks
Wise spend $470m buying back 35.9m shares last year for its Employee Share Trust – effectively a remuneration cost, in my view. This equates to an average price paid of c.990p, slightly above the current share price.
For 2027, the company has announced a new $500m buyback of which c.40% will be allocated to the EST, with the remainder presumably used to reduce the group’s share count. I don't have a problem with this in the scheme of things; it looks affordable to me.
FY27 Guidance
Today’s results included clear guidance for the current year:
Net revenue growth “around the middle” of the 15-20% medium-term target range;
A pre-tax profit margin “around the top” of the 20-25% range.
Applying this guidance to today’s FY26 results gives me the following estimates:
Net revenue of $2,940m;
Pre-tax profit of c.$720m;
Diluted earnings of around 57 cents per share (c.43p), assuming unchanged tax rates etc
As far as I can tell, today’s guidance is slightly ahead of previous consensus for FY27, but not massively so. Even so, this seems likely to extend the recent positive trend in earnings forecasts:
Roland’s view
By continually cutting its “take rate” [fees] to reflect growing economies of scale, Wise’s services become more competitive and attractive for a wider number of users. It’s a land grab strategy similar to that pursued by Amazon in the past.
I think this is a smart approach. This is a business where strong volumes and deep liquidity provide a competitive advantage and help to support further expansion. While Wise probably could make more money in the short term by maintaining its take rate on higher volumes, I think doing so might make it harder for the business to achieve it’s long-term strategy of becoming a dominant player in its markets.
After all, $43 trillion is moved across borders by people and businesses every year (according to Wise). The company’s share of this last year was just $243.5bn, or just 0.6%. Aiming big seems sensible to me.
My estimate of 2027 earnings suggests Wise is trading on a forward P/E of c.20. For a business with strong quality metrics and double-digit revenue growth, I don’t think this is unreasonable.
I am in the camp that believes Wise has a long growth runway and the potential to become a much larger and more profitable business.
The Belgian investigation remains a risk and is perhaps a reminder of the pitfalls that can befall fast-growing fintechs. Even so, I think the long-term investment thesis here remains very positive and am happy to maintain our GREEN view today.
Devolver Digital (LON:DEVO)
Up 8.5% at 19p (£93m) - Trading Statement - Roland - AMBER =
Today’s update from this publisher and developer of indie video games has received a warm reception, but to my mind it’s broadly neutral overall. What the update gives with one hand, it appears to take away with the other.
H1 ahead of expectations
The good news is that Devolver has had a strong start to the year, with H1 performance “ahead of expectations”.
The favourable year-on-year comparison is in part due to the Devolver Steam Publisher sale being held in 1H 2026, in addition to a positive start to the year with 3 Top 10 Global Best Sellers on Steam in January.
We’ve commented on Devolver’s confusing update style before and today is now exception. Rather than providing explicit figures, management have provided percentage changes and vague suggestions.
Revenue
H1 revenue is expected to be “at least 60% higher than 1H2025”;
Based on last year’s results, this implies H1 revenue of at least $62m
Underlying adjusted EBITDA
Leaving aside the absurd double level of adjustment being applied here, it looks like profits are going to bounce back from last year - when Devolver generated just $0.1m of EBITDA in H1:
H1 “underlying adjusted EBITDA” is “projected to reach mid single-digit US$ millions”.
My guess is that this means a range of $5-7m of adjusted EBITDA.
STARSEEKER release has “been disappointing”
The strong H1 performance may not continue into H2. Early sales of a (presumably) important new game are said to have been disappointing:
In June, Devolver's subsidiary System Era released STARSEEKER: Astroneer Expeditions into Early Access with a significant platform deal accompanying the launch. Unit sales have been disappointing so far but review scores are improving and there are regular content updates planned for August and through to the end of 2026 which the Board believes can re-energise the game.
Investors with an interest in this sector will probably know more about this than me – as Ed has highlighted previously, it’s possible to mine publicly-available data to get an insight on new game sales before companies report to the financial markets.
I’d certainly recommend this kind of supplementary research for anyone considering an investment in games publishers.
Outlook & Broker Estimates
Devolver has a number of other new games slated for the second half of the year and remains positive about their prospects:
Subsidiary studio Firefly enjoyed a very positive response to its announcement of Stronghold 4, building 250,000 wishlists in just two weeks. Equally encouraging is the interest in other games slated for 2H 2026, Warhammer 40,000: Boltgun 2 (c. 260,000 wishlists) and Shroom and Gloom (c. 220,000 wishlists).
However, the disappointing launch of STARSEEKER does seem at risk of putting a dampener on the full-year outlook. Today’s full-year guidance is noncommittal, with a further update promised in September:
The strong 1H 2026 performance and the positive response to pending games are expected to combine to build a profitable cushion although this will be offset by the slower than expected initial launch of STARSEEKER. We will provide further details on 1H 2026 performance and guidance for the full year 2026 at the time of the Company's half-year results in late September 2026.
Brokers Panmure Liberum and Zeus have both published updates today. Both brokers have left their FY26 estimates unchanged, but I’m surprised at the wide variance between each company’s estimate:
PanLib FY26E adj dil EPS 1.4 cents
Zeus FY26E adj dil EPS: 2.4 cents
These figures average to give the 2 cent consensus estimate shown on the StockReport. But in my view, the variation between these forecasts highlights the lack of visibility on sales for the remainder of the year.
Roland’s view
This business floated opportunistically during the pandemic video game boom and has disappointed investors ever since:
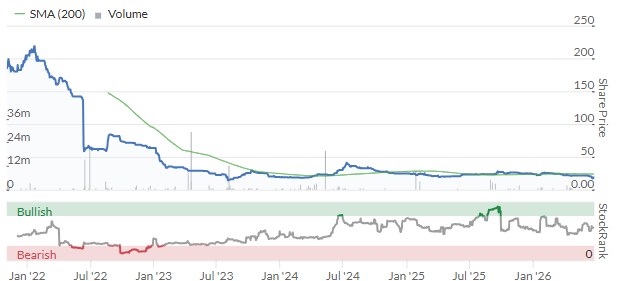
While broker forecasts are unchanged today, I think they do provide some useful context for today’s H1 guidance.
PanLib’s forecasts suggest full-year adjusted EBITDA of $12.8m, while Zeus comes in at $14.6m due to slightly higher revenue assumptions.
Today’s guidance for "mid single-digit" H1 EBITDA suggests to me that Devolver could easily miss full-year expectations if H2 is not as strong as H1.
Based on today’s commentary, I would suggest there is some risk of a profit warning later this year, unless other new games perform well.
While Devolver’s $37m net cash position helps underpin the market cap and provide a margin of safety, I can’t get very excited about this business. Devolver has operated at a loss in each of the last four years. Based on today’s update, I’d argue that the outlook for this year also carries some uncertainty.
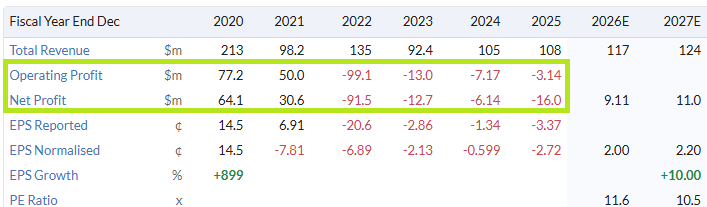
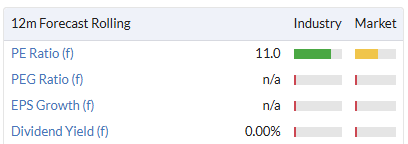
We’ve been neutral on this business previously. I’m going to leave that view unchanged today to reflect unchanged forecasts and the reasonable valuation:
However, while in-depth sector research might unearth an opportunity here, I am inclined to think there are more tempting choices elsewhere.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
Join us for our next MelloMonday show on Monday 29th June 2026, at 5pm, hosted by Jamie Ward who has been on our BASH panel on numerous occasions..
The programme for the evening is as follows (subject to minor change):
5:00pm Fireside Chat with John Goold, CEO at Kelso Group plc
5:30pm Company Presentation from Oxford Metrics
6:10pm Company Presentation from Accsys Technologies
6:40pm Company Presentation from Pathos Communications
7:10pm Company Presentation TBC
7:40pm BASH (Buy, Avoid, Sell, Hold) Panel
For more information, click here: www.melloevents.com/mm290626
There are lots of interesting sessions and all members and individual ticket holders will be sent a recording of the show within 48 hours. For half price tickets, use code MMSTOCKO50.www.tickettailor.com/events/melloeventslimited/2022799
In light of recent weather I hope the 5pm is a poolside chat!
Maybe "Fireside Chat" needs a rebrand to "Poolside Chat" over the summer months if this weather hangs around ;)
It seems to me that nearly every morning Stockopedia doesn't work properly, with either complete failure to open a particular share page or opening with gaps on the page, mostly I'm looking at european shares if that might be a factor, is anyone else finding the same or is it unique to my system?
yes, it has got very buggy in recent weeks
It seems to help if you do a CTRL-SHIFT-R to refresh everything. Like links have expired, I'm not a web expert, just doing what one of the people who answered my query suggested. I started back in the nineties with Windows and the default was to automatically get a refreshed page when you clicked a link. It seems these days with cloud based storage you get a cached version of a page, which might not be up to date, to improve response times. That's fine until it's not, it appears.
Charts not working for me today on desktop or IOS
Volex (LON:VLX) some fall from 700p, looking better value now
Volex (LON:VLX) For info, there's a results presentation on Investor Meet Company at 1430 this afternoon.
The presentation was excellent, watched by this happy shareholder.
Volex (LON:VLX) I also found it very informative. I had recently reduced my holding but intend to stock up again before FTSE250 move is complete.
Volex (LON:VLX) Any number of reasons for price drop - including those who hold just for the IHT relief selling out before move to the FTSE250
What I hadn't really taken on board prior to the confirmation of the move to main market by Volex (LON:VLX) was the existence of IHT "efficient" funds. My assumption was that most who were concerned about IHT would assume they have a bit of time before their wills are executed, so no immediate rush to act, and any effect of the main market listing would be spread over time. But that doesn't apply to trusts in the same way. Which may explain part of recent moves - in addition to recent sharp moves up in the SP, and largely "as expected" forecasts.
Has anyone used CMC Spectre the leverage free spreadbet product? The tax advantages are appealing at first glance.
A bit more context….
The headline is “no overnight financing”. Instead, the costs are largely:
So for a typical UK equity position you’re looking at roughly 1.2% per year plus the spread.
For long-term investors, the interesting question is whether those ongoing fees are more than offset by the potential tax advantages of spread betting. For higher-rate taxpayers with large taxable portfolios, it’s an intriguing proposition.
Disclaimer: I own shares in CMCX (and also IGG)
How do dividend payments work in this CMC Spectre product (or spread-betting accounts in general)? Do you receive the dividends (taxable as dividends) or is the position adjusted to account for the dividend (e.g. a share price/position of 100p pays a 3p dividend is the position adjusted to 97p and no actual dividend payment is received)?
The marginal dividend tax rate is 35.75% for higher rate tax payers. So if you're paying a 1.2% account maintenance fee per year (plus the spread but no stamp duty to pay) then any share yielding over 3.56% will save you more in dividend tax than the account maintenance fee of 1.2% - that is IF the position price is adjusted for dividends and you don't actually receive the dividend payment. And on top of this any "capital gains" are tax free (which is the real attraction here).
The dividends on spreadbets are not taxed as I understand as they are nominal adjustments rather than actual dividends.
You just have to make sure your spread betting is seen by HMRC as "recreational", and not your main source of income! (Does it cease to be recreational if you start making consistent profits?)
Indeed
I’m gainfully employed, some might argue differently
Maybe an alternative to an ISA?
I’d say in addition to if you use your full allowance
Some interesting commentary about small caps and the investments held in the Montanaro UK Smaller Companies Investment Trust (LON:MTU) final results : https://www.stockopedia.com/sh...
Barratt Redrow and the rest of Housebuilders
At a recent webinar I asked Ed Croft on the absence of housebuilders stock in his presentation. His reply was : "they are cheap by all measures but there is no momentum and such stocks may remain cheap for a long time".
This week we have witnessed the return of the momentum and most of the housebuilders shares are up by around 10%. Now that we have the value and momentum , I consider it is a good time to buy for me. In Stocko rankings , the scores are low but that is the norm for the Contrarian shares.
In yesterday discussions, someone posted a link from Phoneix Asset Management discussing Barrat in a 430 pages which may be of interest for those keen on the sector. It contains interesting statistics relating to the housebuilders in general and BTRW in particular.
In the meatime the dividends could provide the attraction. Actually I sold my Barratt Redrow (LON:BTRW) holding quite a while ago at considerable loss (what you lose on the swings you can gain on the roundabouts) but I've kept Taylor Wimpey (LON:TW.) on.
Personally I would wait for the retest and confirmation of a higher low. If the long term low is in then there is no rush. Better for confirmation. Market has become excited by the prospect of lower interest rates but we still have to find out what the government's plans are. Momentum rank is still on 2!
Morning all
Could one of the team cast their eyes over Distribution Finance Capital Holdings (LON:DFCH) . Yet another PBT upgrade for this small £100m mkt cap company.
Thanks
Morning Threepeat,
Distribution Finance Capital Holdings (LON:DFCH) is on the list for today!
Roland
Thanks Roland
Cirata (LON:CRTA)
Oh what a surprise, remember Wandisco, now living with a new identity as Cirata, needs more money. At least the story has changed to accurately reflect that they help users of large databases, running on an obscure operating system called Hadoop, move that data to the cloud while still running. Back in the day it was ramped to the heavens as the only way for anyone to move data anywhere and given an equally ridiculous price tag until the salesmen invented sales to cover its limited appeal. Best ignored imho.
Zotefoams (LON:ZTF) Watch out all you Zotefoams fan - The Times has today published a lengthy Buy recommendation
Zotefoams (LON:ZTF) Has good rankings, but its price has remained rather stagnant. I’m somewhat surprised by its high momentum rank.
SDG: Sanderson design . Good to see the terms of the LTIP , so often hidden from us. And they look stretching in the extreme for a full pay out. Seems the company is quietly positive for a medium term recovery.
The Devolver Digital (LON:DEVO) update this morning certainly sounds interesting given revenues are up 60% in H1 but full year market expectations are currently for 8.3%. Not a company I've looked at before. Looking at the Stockopedia archive it looks like they're prone to giving slightly PR-ed updates.
Looking at Steam statistics it might be that their game 'Quarantine Zone' has particularly driven success? https://steamdb.info/publisher...
Worth a look today perhaps?
I held Devolver Digital (LON:DEVO) on the basis that Quarantine Zone and other titles would result in a turnaround. The sales were good and the turnaround may be happening now but, if the latest game has flopped then they might struggle for momentum until Warhammer and other games come out this autumn.
Having said that it is continuing sales from their back catalogue that seem to be important long term.
Share is illiquid so I'd start small. If momentum does build then share price could move quickly.
Personally I have moved to Frontier Developments (LON:FDEV) which appears to be generally on a more positive trend.
You're right - I tried to do a bit of trading on this today (made a tiny profit) and it was unbelievably illiquid. No sellers or buyers for long periods of time. I guess if H1 does follow through to H2 this could see a strong rise though!
Thanks for covering Devolver Digital (LON:DEVO) today Roland!
Wise (LON:WISE)
Good morning and happy Friday!
A few thoughts after yesterday evening’s results and earnings call.
Apologies if there’s any overlap with the Stockopedia team, I wrote this early doors before work.
At a headline level these were difficult to fault:
• Active customers +21% to 18.9m
• Cross-border volume +31% to $243.5bn
• Customer holdings +40% to $39.0bn
• Card spend +37% to $43.6bn
• Net revenue +19% to $2.5bn (top end of medium-term guidance)
• Pre-tax margin 26%
• >$500m new share purchase programme announced, with around 60% expected to represent genuine share count reduction rather than simply offsetting employee dilution.
What also stood out was where management is choosing to reinvest.
Marketing spend increased over 60% year-on-year, alongside continued investment in Platform, sales and compliance, yet guidance was maintained and profitability remained exceptionally strong. To me, that’s what you hope to see from a founder-led compounder: investing aggressively while the incremental returns still appear attractive.
Operationally, I felt there was little not to like.
Growth remained broad-based, customer engagement continues to deepen and almost half of revenue now comes from non-cross-border sources, reinforcing the diversification of the model.
The Platform business feels increasingly important.
It’s currently only around 5% of volumes today, but management sounded genuinely enthusiastic about both the pipeline of new Platform customers and the deeper embedding of existing ones. Kristo commented:
“We are very excited about the Platform pipeline.
You are going to be hearing about new names that will be coming out. As you rightly pointed out, it is a combination of new names that join Wise Platform, but also the deeper embedding of the expansion of the existing names.
We love the customers that we have on Wise Platform, and we love the new ones that are coming on board.“
For an apparently unexcitable Estonian, I felt he sounded energised about this.
On Belgium, I’ve deliberately avoided commenting until now because there is very little information to opine on.
Listening to the call, my view hasn’t changed materially.
The investigation remains an uncertainty and deserves to be taken seriously; it shouldn’t be ‘hand waved’ away and based on June’s price movements I suspect the market will continue to dislike the uncertainty until the matter is resolved.
However, there was no indication of escalation or operational disruption. Management’s comments were matter-of-fact rather than defensive. They reiterated that they have no new updates from the prosecutor.
Ultimately, I think investors should distinguish between headline risk and thesis risk.
Belgium could still result in a fine, additional remediation, higher compliance costs or, in a more severe scenario, regulatory restrictions that impede customer onboarding or business expansion.
Those outcomes would matter.
However, based on the information available today and management’s comments on the call, I didn’t hear anything suggesting such measures are imminent, nor anything indicating the long-term economics of the business have materially changed.
One moment I found particularly interesting on Wise’s first earnings call as a dual-listed company was a U.S. analyst citing the falling take rate as part of a bear case.
I feel that continues to miss a canonical feature of the Wise model as Kristo describes it, and is integral to my investment thesis.
Nick Sleep would probably recognise this immediately as “Scale Economies Shared”.
Wise deliberately returns the cost savings generated by scale to customers through lower pricing. Those lower prices stimulate higher volumes, which deepen the network, further reduce unit costs and generate another round of savings to share.
The flywheel reinforces itself.
If volumes continue to grow strongly while take rates gradually decline, that therefore isn’t evidence of a weakening business—it should reinforce that the flywheel is working as management intends.
As always, time will tell, but I came away from the call slightly more positive than I went into it.
RE: Wise (NSQ:WSE)
One moment I found particularly interesting on Wise’s first earnings call as a dual-listed company was a U.S. analyst citing the falling take rate as part of a bear case ... I feel that continues to miss a canonical feature of the Wise model as Kristo describes it, and is integral to my investment thesis.
Agreed. It's no surprise to find US analysts are as short-termist as UK ones: my experience of having worked in US companies is that the usual operational approach is to maximise each quarter's earnings and worry about the next one when it comes around. One benefit of owner control is that the company can ignore this.
Also agreed on the regulatory issues. The regulators will do whatever they do and the impact could be anything from minor to major, secondguessing this is pointless. Regulatory risk is built-in to the business model. The outcome will be interesting, though, as it'll shed some light into the company's operations.
I wouldn't be surprised to see the share price fall again today. Although perhaps I'm being overly optimistic.
timarr
Good progress and I was inclined to add - until I saw the colossal buy-backs going into employee trusts (if I understand correctly). What about shareholders?
RE: Wise (NSQ:WSE)
Good progress and I was inclined to add - until I saw the colossal buy-backs going into employee trusts (if I understand correctly). What about shareholders?
We don't get a say - Kristo runs the show. It's not uncommon in US companies and my (entirely cynical) view of UK companies relisting in the US is that it's not about improving returns for shareholder but for employees. The limited evidence suggests firms moving their domicile to the US actually see worse share price performance:
https://www.newfinancial.org/r...
Anyway, it's the price we pay. Hopefully excessive employee remuneration should be a note in the rear-view mirror in a decade or so. At least some of the buyback is to the benefit of shareholders - not always the case in the US.
timarr
$300million of the buyback will be going towards cancellation of shares. The other $200million is going into the employee benefit scheme. Seems a fair balance.
I’m obviously too ignorant to understand the difference ? Off setting dilution or cancel existing shares has the same eps benefit doesn’t it - removing a negative and adding a positive are the same I think - mathematically anyway - which I believe is what counts.
Wise (LON:WISE)
one thing is if they are mentioning "fines" thats sounds like an aceptance that they may have broken the rules ? i do fully agree that its an occupational hazzard doing what they do somewhat.
For me to view the Wise Stock Report I would have to upgrade my Stocko subscription but won't be bothering. It's sort of been there, done that for me as l first bought Wise in October 2024 at 721 pence, sold a batch 3 weeks later at 907 pence and sold the remaining portion at 1168 pence in June 2026. At present the share price appears to me to be a suitable entry point as was that of October 2024. Moving the listing of Smurfit WestRock (NYQ:SW) to the NSYE created the same problem and I felt compelled to sell before the company left the FTSE, which I did, having held untouched since 2016. We PI's have to keep moving, the Devil always takes the hindmost.
Wise (LON:WISE) It is still under it's UK listing, on here.
Hi David. have you ever taken a look at Flywire (NSQ:FLYW) ?
I like the idea of companies that disrupt and remove barriers/costs in financial transactions. There isn't much overlap between Wise (NSQ:WSE) and Flywire (NSQ:FLYW) yet apart from maybe in universities and tuition fees.
Wise (NSQ:WSE) is approximately 5 times larger that Flywire (NSQ:FLYW) but Flywire (NSQ:FLYW) is growing quickly. I like it because it targets complex sensitive institutions such as universities and hospitals (medical fees) and integrates itself with a land and expand model. This makes the institutional clients very sticky and provides a significant moat.
Apparently Flywire (NSQ:FLYW) aren't the cheapest but thrive in complex environments where trust and consistency are more important than being the "cheapest" provider.
Flywire (NSQ:FLYW) doesn't have a single controlling entity/person either which I prefer.
Clearly it isn't an either or situation but I thought I'd introduce Flywire (NSQ:FLYW) as they operate in the same field and it may be an interesting alternative for some.
Hi
Apologies for the slight delay in getting back to you; I was slightly struggling to get the comments to load.
Thanks for mentioning it.
Funny you should say that as Flywire has actually been on my “to investigate properly” list for a while, although I haven’t yet done enough work to form a view.
On first principles I can certainly see the attraction.
As you say, it’s solving complex, high-trust payment workflows rather than simply competing on price, and those institutional relationships sound inherently sticky if execution is good.
My initial question would probably be whether Flywire’s moat ultimately compounds as strongly as Wise’s.
Wise increasingly feels like it’s building a global payments network where scale itself reduces unit costs, allowing management to lower prices further and strengthen the network.
Flywire appears (at least from your description) to be building deeper vertical software integrations and workflow moats instead.
Both can be excellent businesses, but they’re quite different economic models.
I’ll add it to my list for a proper look. It would actually be quite an interesting company to put through the Purfleet framework rather than assuming it’s simply a smaller Wise.
Flywire (NSQ:FLYW)
I’ve had a look at this using my own investment lens. I don’t have access to broker reports or Stockopedia’s US data, so this is based on publicly available information and my own research.
Firstly, thank you for mentioning Flywire.
Flywire wasn’t a business I knew particularly well.
Thanks for suggesting it—I’ve spent a short while trying to understand what the company is actually building rather than primarily looking at the numbers, and it’s been a genuinely interesting exercise.
My first impression is that it looks like a much more interesting company than many businesses that get lumped into the broad “payments” sector.
The key point, in my opinion, is that Flywire isn’t really trying to win by being the cheapest or fastest payment processor.
It is trying to become deeply embedded inside complicated industries where the payment itself is only one part of a much larger workflow.
Universities don’t simply want to receive tuition fees. Hospitals don’t simply want to collect invoices.
They need reconciliation, payment plans, compliance, reporting, foreign exchange, integration with existing finance systems and a great deal of administration that sits around the movement of money. Flywire appears to have spent years building software around those workflows.
That makes it quite a different proposition from companies such as Wise.
Wise, to my mind, is primarily solving the problem of moving money better than the banking system.
Its advantages come from scale, efficiency, transparency and a continually improving global payments network.
The customer chooses Wise because it is cheaper, faster and more reliable than the alternatives.
Flywire is solving a different problem.
It is attempting to become part of an institution’s operational plumbing.
If it succeeds, customers may become sticky not because payments are difficult, but because replacing the surrounding workflow becomes disruptive.
I think that’s an important distinction.
Where I became more cautious is when I started asking whether that workflow creates a durable moat or merely a temporary advantage.
This is where I’d separate the business from the investment.
The business itself looks good.
Whether it becomes an exceptional long-term investment is much less obvious.
The bullish argument is fairly straightforward.
International education should continue to grow over time.
Healthcare administration continues to digitise.
B2B receivables remain surprisingly inefficient.
Travel has become increasingly international again.
All of those trends play into Flywire’s strengths.
The company has also been executing well operationally.
Revenue has continued to grow at an attractive rate, profitability is improving, operating leverage is beginning to appear and the balance sheet remains strong.
Management also seem to understand their niche rather than trying to become all things to all people.
There is a lot to like there.
However, I think the bear case deserves equal attention.
The biggest question I’d ask isn’t about valuation.
It’s about durability.
How difficult would it actually be for a university or hospital to replace Flywire in five or ten years’ time?
The integrations undoubtedly create switching costs, but are those switching costs comparable to Visa, Mastercard or even Wise’s network? I’m not convinced they are.
Similarly, payments infrastructure continues to become more competitive every year.
Generalist platforms such as Stripe and Adyen are investing heavily in enterprise capabilities.
ERP vendors continue embedding payments into their software, while banking infrastructure keeps improving. None of those developments necessarily destroy Flywire’s position, but they do mean the company has to keep earning its place.
I also noticed something that I think deserves monitoring.
Revenue growth has been excellent, but some recent growth has been acquisition-assisted, and gross margins have come under pressure as the business mix has evolved. Neither of those is fatal—in fact acquisitions may prove extremely sensible—but they make it harder to judge the underlying economics of the core business.
I’d want to see those margins stabilise over time while operating margins continue expanding.
Another consideration is that Flywire’s largest vertical, education, is not entirely under its own control.
International student flows are influenced by visa policy, geopolitics and government decisions in countries such as the UK, Canada, Australia and the United States.
Those markets are attractive over decades, but they can become surprisingly volatile over shorter periods.
That’s a different type of risk from the one faced by Wise.
If international students move from one country to another, Wise largely doesn’t mind—it simply moves the money wherever it needs to go.
Flywire, by contrast, has more direct exposure to the health of specific institutional markets.
So, coming back to your comparison with Wise, I actually think the two businesses are more complementary than competitive.
Both remove friction from moving money.
But they’re removing different kinds of friction.
Wise is trying to become core financial infrastructure.
Flywire is trying to become core workflow infrastructure inside particular industries.
Personally, I think the former has the potential to become the more powerful long-term business model.
A successful global payments network becomes stronger as every new customer joins.
Scale drives lower costs, better pricing, broader coverage and ultimately reinforces the competitive position. That positive feedback loop is one of the reasons I’ve become increasingly convinced by Wise over the past couple of years.
Flywire’s feedback loop feels narrower.
It may become exceptionally strong inside education or healthcare, but I’m less certain that success in one vertical naturally strengthens the business in every other vertical to the same extent.
That doesn’t make Flywire a poor company.
Far from it.
In fact, I think it’s exactly the sort of business that’s worth studying because it sits in that interesting middle ground—better than an ordinary payments processor, but not obviously possessing the sort of wide, self-reinforcing moat that characterises the very best compounders.
If I were trying to summarise my current view in one sentence, it would probably be:
“Flywire looks like a high-quality vertical payments software business that still has something to prove before I’d place it in the same conversation as the very best long-term compounders.”
At the moment, I’d happily keep Flywire on a watchlist.
Whether it ultimately becomes an investment for me will depend less on headline revenue growth and more on whether the next few years demonstrate that its customer relationships, margins and economics genuinely strengthen with scale rather than simply grow with demand.
Either way, it was a very worthwhile rabbit hole to disappear down, so thank you for the suggestion, and I hope I’ve helped.
VBW
D
Wise (NSQ:WSE) Wise (LON:WISE)
Hi David
I'm a bit late to the commentary here, but I've finally had a chance to go through the massive 20-F document and catch-up on the earnings call.
I know you've covered most of the below already, but there were a few additional figures that I believe I've calculated correctly, so I thought they would be worth sharing.
With apologies for the formatting/bullet-pointing - these are from my own notes.
FY26 FY Results:
Big boost in new customers in H2 (not sure why 2026 was high/2025 was low?)
% yield on card spend has increased, now close to 1%.
Wise is receiving this benefit
Wise (NSQ:WSE) Wise (LON:WISE)
You might also be interested in this snippet from Wise's recent US filing:
"In June 2026, the media reported on an ongoing money laundering inquiry by the Brussels prosecutor’s office relating to Wise Europe SA, which we discussed further in our Form 6-K on June 1, 2026.
The inquiry is incomplete, with no known timeline or outcome.
We are not aware of any current legal proceedings that we believe will have, individually or in the aggregate, a material adverse effect on our business, results of operations, cash flows or financial position."
Of course we have no idea what's going to happen, but it seems like Wise have no idea either.