Daily Stock Market Report (Fri 28 Feb 2025) - Portfolio, MEGP, MGAM, RMV, FKE, OBD, SAG/RCDO

Happy Friday everyone, I hope your portfolio has done well in this results-heavy week.
Before getting into today's news, I thought it would be fun to show you my personal portfolio. This isn't meant to be a model portfolio and of course it's not a recommendation. It's simply what I've ended up with after a long chain of decisions. It also reflects my bias towards inertia when it comes to investing.
- Volvere (LON:VLE) (33%)
- Berkshire Hathaway (NYQ:BRK.B) (27%)
- IG group (LON:IGG) (13%)
- Next (LON:NXT) (9%)
- Rightmove (LON:RMV) (5%)
- Burberry (LON:BRBY) (5%)
- British American Tobacco (LON:BATS) (4%)
- Evoke (LON:EVOK) (2%)
- International Personal Finance (LON:IPF) (2%)
- Impax Asset Management (LON:IPX) (1%)
In truth, I found this portfolio somewhat frustrating for a while, as my largest holding made no progress in share price terms for four years (roughly from 2020 to 2024).
That investment has also been a source of enormous sadness, as the co-founder and CEO, whom I had spoken to on a number of occasions, tragically died young.
Looking forward, I know that this portfolio needs to be improved and I do intend get more new ideas into it over time, especially from my watchlist and companies I've been GREEN on in these reports. But that also depends on dividend income and on disposals/takeovers from the existing portfolio.
Thankfully, my three largest holdings have carried their weight in recent times. The first is up by over 80% in the past year. The second is only up by 20%+ over the past year, but it is up by 140%+ over five years. Even IGG, which treaded water for such a long time, has done well recently. It's up by 35% over the last year, while also paying a dividend. Patience has been rewarded, and it leaves me with a question to answer about what to do with these unrealised capital gains. A nice problem to have.
With that out of the way, let's get into today's news!
Graham
The report is finished now.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
International Consolidated Airlines SA (LON:IAG) (£16.3bn) | Final Results | Beats expectations. | |
Pearson (LON:PSON) (£8.9bn) | Final Results | Positive outlook in line with expectations. | |
Weir (LON:WEIR) (£5.9bn) | Final Results | 202 op margins, cash conversion significantly ahead of exps. 2025: confident to be in line. | |
IMI (LON:IMI) (£4.8bn) | Final Results | 2025: expect another year of strong progress, mid-single digit organic growth, EPS 129-136p. | |
Rightmove (LON:RMV) (£5.2bn) | Final Results | 2025: expect rev growth 8-10%, 1% membership growth, revenue per account to grow £95-105. | AMBER/GREEN (Graham) Spending big to keep its technological lead against rivals. Market share is under a little pressure but it remains around the extraordinary 80% mark. Valuation is always expensive but whenever it drops below 20x I view that as a bargain. Currently c. 23x. |
Spectris (LON:SXS) (£2.8bn) | Final Results | 2025: expect to trade in line, with strong growth in adjusted operating profit. | |
Primary Health Properties (LON:PHP) (£1.2bn) | Final Results | NTA (net tangible assets) down 2.8% to 105p (SP 91.4p). Values have started to stabilise. | |
ME International (LON:MEGP) (£829m) | Secondary placing | SP -9%. Investment company sells 7% of MEGP at 200p; MEGP shares fall to around this level. | AMBER/GREEN (Graham) It's not good news that a private equity firm is selling, but I don't think it warrants a change of stance. |
Morgan Advanced Materials (LON:MGAM) (£720m) | Final Results | SP -17%. Weak outlook statement. Uncertain end-market demand. Slower growth in BEVs. | BLACK (AMBER) (Graham) Retreating from my mildly positive stance after another profit warning. I do still see some value but given a highly uncertain outlook for 2025, I can't fight against the downtrend. |
Benchmark Holdings (LON:BMK) (£200m) | Q1 Results | SP -5%. Q1 revenue down 30%. Adj. EBITDA loss. Cash £14m, net debt £62m. | |
Ricardo (LON:RCDO) (£146m) | Strategic Investment | Science Group now owns 8.46% of voting rights in RCDO. | AMBER/RED (RCDO) GREEN (SAG) (Graham) [no section below] SAG and RCDO have similar market caps but SAG (which had net funds of £27m as of Dec 2024) has spent £12m+ buying RCDO shares. SAG’s directors are keen to point out that their own shares have made strong compound gains over the long-term, while RCDO shares have hit 15-year lows. They describe this as a “strategic investment” but the strategy is not described in today’s RNS and is not clear to me. I leave our colours on each company unchanged for now. If SAG keeps buying RCDO shares, I may need to think about putting them on similar colours. |
Oxford Biodynamics (LON:OBD) (£11m) | Final Results | Revenue £0.6m, op loss £12.9m. Raised funds in Jan; has “limited” cash. Going concern warning. | RED (Graham) [no section below] Raised £7m in Jan. Further cost reduction actions may be taken following a review. According to the company’s baseline forecast, more funding will be needed in the final quarter of 2025. If the baseline forecast is not met, funding might be needed sooner than that. This is an automatic RED from me due to the risk of dilution. Dilution might be considered the best-case scenario in this case. |
Fiske (LON:FKE) (£8m) | Interim Results | Rev £3.9m. Op profit £0.3m. Outlook: headwinds and uncertainty, but has solid platform. | AMBER/GREEN (Graham) [no section below] Nearly £900m in AUM and assets under administration but it struggles to earn material profits. The core business needs to scale up to prove its worth. Balance sheet has cash of nearly £6m and an investment in Euroclear which looks to be worth £5m+. Net assets of £10.5m are almost entirely tangible. On the whole, this appears to be undervalued and to offer deep value but more detailed research is needed. How might the value be unlocked? |
Graham's Section
ME International (LON:MEGP)
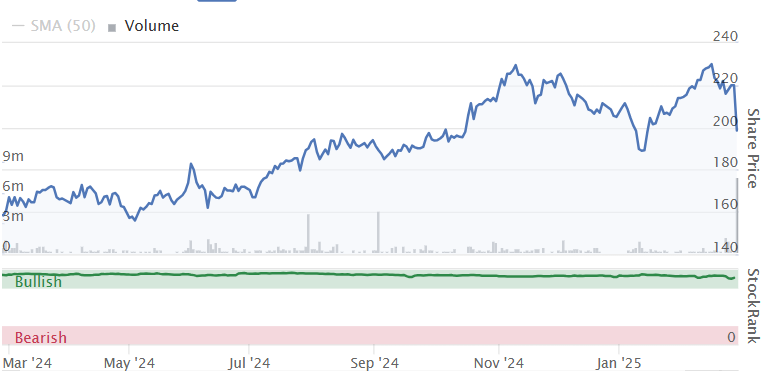
Down 9% to 199.4p (£749m) - Result of Secondary Placing in ME Group - Graham - AMBER/GREEN
Last night as the market closed, an RNS was released with information about this proposed secondary placing.
(Secondary placing means that it’s the sale of existing shares by shareholders, not by the company itself.)
The seller is Montefiore Investment which until now was a 12% shareholder in MEGP.
The RNS last night said that they intended to sell c. 5% of the company.
This morning we learned that they have in fact sold 7%.
To do so however they accepted a discount of about 20p or 9%. The stock closed last night at 220p, but the sale has gone through at 200p.
And what next for the remaining shares held by Montefiore? They have agreed to a 45-day lock-up but we might reasonably expect that these shares will hit the market sooner or later.
About the seller: Montefiore a Paris-based investment manager with €5bn of AUM. They have a representative on the Board of MEGP but perhaps not for too much longer? They look like a reputable outfit.
Graham’s view: there is no information regarding the identity of the buyers of the shares so we’ll need to keep an eye out for that.
In general, it’s never positive to see a major shareholder selling their stake. Especially when that shareholder is highly knowledgeable and professional. I note in passing that MEGP’s CEO is French and that most of MEGP’s photobooth revenue derives from France. Paris-based Montefiore do not make many investments. They will have an extremely strong understanding of the company.
At the same time, I don’t believe that we should allow our view on MEGP to be altered too much by this news.
For every share sold, a share has been bought. There are buyers who see value at 200p.
And we can’t know for sure why Montefiore is selling. There are possible reasons for their decision which have little to do with MEGP itself.
I am therefore going to leave my AMBER/GREEN stance unchanged on MEGP, which is the position I took on Monday this week when it announced full-year results.
Morgan Advanced Materials (LON:MGAM)
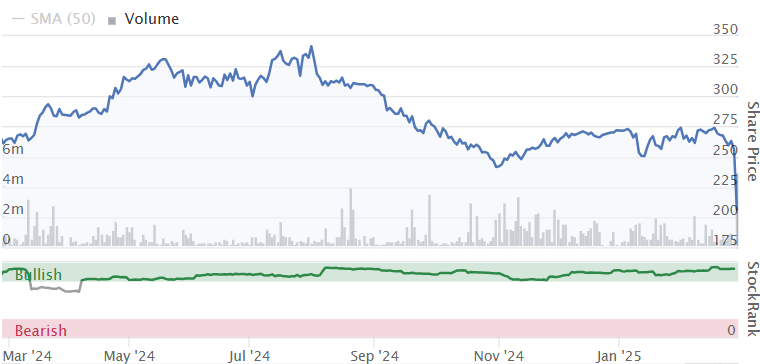
Down 22% to 200p (£565m) - Preliminary Results - Graham - BLACK (AMBER)
We don’t cover this one very often. The first time was last November when I was too optimistic on it, taking an AMBER/GREEN stance at 245p. It issued a mild profit warning that day but was happy to continue buying back its own shares.
Roland had also looked at it in October, noting a vague outlook statement.
The company is “a global manufacturer of advanced carbon and ceramic materials for complex and technologically demanding applications”.
Its businesses are broken into three categories: thermal products (which offer heat resistance, fire protection and insulation), performance carbon components (rail, aerospace, etc.) and technical ceramics.
Unfortunately there is more bad news today with a very weak outlook statement.
Firstly, here are some headlines from the full-year results for 2024.
The growth rates used are adjusted to be organic and assume constant exchange rates.
Revenue +3.7% to £1.1bn
Adj. op profit +16.5% to £128m.
Return on invested capital 18.5% (LY: 17.6%)
Net debt £226m (up from £185m)
This all looks quite promising. The statutory results aren’t bad either, e.g. there is unadjusted PBT of £85m (LY: £78m). The main weak point in the statutory results is that unadjusted revenue fell by 1%.
The CEO comment shows no signs of panic:
We have delivered robust organic constant currency* revenue growth against a backdrop of increasingly challenging end-markets, with good progress made in our business simplification and efficiency initiatives, continuing our track record of self-help. We remain focused on delivering against our strategic initiatives and expect a return to a 12.5% adjusted operating profit* margin during 2025."
The outlook statement is where we need to focus. Revenue expectations have deteriorated:
Demand in a number of our end-markets is uncertain. Our current outlook for revenue in 2025 is for a mid single-digit organic decline and assumes no recovery in H2. Our simplification programme has been accelerated given the weaker demand…
Demand for semiconductor capacity has been impacted by the slower growth in BEVs leading to high customer inventory levels in the short term. We have scaled back investment accordingly and now expect to invest c.£60 million in semiconductor capacity (prior estimate £100 million) to deliver incremental revenues of £40 million and adjusted operating profit* of £12 million in 2027 (prior estimate £80 million revenue, £25 million adjusted operating profit*).
Regarding tariffs, they say “with such a wide range of potential tariffs being considered, and with the details of those unknown, it is not possible to estimate the impact at this stage”.
As a result, their guidance for 2025 assumes no direct impact on their financial performance arising from tariffs.
That's understandable if they are unable to come up with any sensible forecast, but at the same time isn’t it likely to be too optimistic?
Estimates: checking prior estimates, I see that MGAM was supposed to enjoy revenue growth of about 2% in 2025. That has now swung to a mid single-digit decline.
Additionally, the loss of £13m of forecast operating profit from semiconductors is alone sufficient to cause a c. 10% trim to operating profit forecasts.
Buyback continuation
In a move that will antagonise the opponents of buybacks, the company has also announced the continuation of its share buyback programme. Its existing programme must be underwater now, as MGAM shares are trading around the bottom of their 5-year range.
Nevertheless, the company will continue with another £10m tranche. This is the second tranche coming from its £40m plan.
They aren’t worried about leverage:
In the context of the strong balance sheet position, the Board continues to consider a share buyback to be an attractive use of capital to drive shareholder value alongside the significant ongoing organic investment. The Company continues to target through the cycle leverage range of 1.0x to 1.5x net debt to adjusted EBITDA excluding M&A and expects to remain within this range during 2025.
Graham’s view
I should retreat from my mildly positive view on this as we have a string of profit warnings to contend with, and it’s difficult to argue that the company offers deep value when it has a material net debt position and the outlook is so uncertain.
That said, I would still expect it to generate a reasonable ROCE/ROIC and profit margin even if it lost 10% or more of profits. It’s starting from a position of strength, e.g. see these quality metrics.

So I guess I do still see some value here, but I don’t want to fight against the trend by keeping that stance after another profit warning. Hopefully I can go positive on it again before too long.
Rightmove (LON:RMV)
Up 3% to 662.4p (£5.2bn) - Final Results - Graham - AMBER/GREEN
At the time of publication, Graham has a long position in RMV.
I thought I could give this one a brief look.
Market share is currently 80% in terms of the time spent by UK consumers on property portals.
The trend here is negative and is something I need to worry about. Although market share isn’t falling fast, it probably is falling. For example, this metric was reported at 84% in 2021 (since then, Boomin has been replaced by PrimeLocation in the list of peers, so it’s not an exact comparison).
However, the overall market is growing in terms of time spent and RMV has logged 16.4 billion minutes in 2024, up from 15.4 billion minutes in 2023.
The only UK-based online platforms that are busier are the BBC, Reach (LON:RCH) and the government (gov.uk). 80% of traffic is “direct and organic”, i.e. virtually free.
The financial highlights are uneventful.
Profits aren’t growing as quickly as revenues, as the company fights to maintain its technological lead:

The company has a small cash balance of £41m after returning £182m to shareholders in 2024 in dividends (£74m) and buybacks (£107m).
ARPA (average revenue per advertiser): up £93 to £1,524 per month with both estate agents and developers paying more. Total membership grows 1%
Property end-market trends in early 2025 are “supportive” with lower BoE base rates beginning to feed through to mortgage rates.
Outlook:
In 2025, we will continue to build a larger, more diversified, digital Rightmove ecosystem in line with our strategy. We expect revenue growth of 8-10%, building on our progress in 2024 and benefiting from: the full-year impact of Optimiser Edge uptake; further product-led growth across our core business; and continued progress within our Strategic Growth Areas of Commercial Property, Mortgages and Rental Services. We expect c1% growth in membership and ARPA growth of £95 - £105 across estate agency and new homes developers.
The underlying operating margin is expected to be unchanged at 70%. The actual, unadjusted operating margin in 2024 was only a few percentage points lower at 66%.
Graham’s view
It’s a little expensive as always, and growth is undramatic.

But for this price, it offers a company of the utmost quality (in my view).
The company is hated by some estate agents, for reasons that we can understand.
From a shareholder perspective, I sleep soundly with this in my portfolio.
In the event that US-backed competition from OnTheMarket meets with success, I suspect that this will come primarily at the expense of Zoopla, not Rightmove.
There was takeover interest in RMV last year, which we covered in this report. Rupert Murdoch’s REA Group eventually walked away after offering 781p of value. I had previously said I wanted at least 800p before I’d even consider selling up. That remains my view today.
I was AMBER on this at 672p last September. RMV’s P/E ratio has since moderated slightly, falling from >25x then to <23x today.
Perhaps this is a little optimistic, but I’m happy to nudge my stance on this up to AMBER/GREEN today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

96 comments
Ever curious and never to be happy until I come across the holy grail in investing I've lost count of the projects I have created. This time I'm Looking for a common thread to help me to decide on when to add to and when to sell companies held within my portfolios. It's the 50dMA to be the tool to monitor the changes from one week to the next, entered up each Friday on an Excel spreadsheet reproduced below. Green cells for a postive figure, pink for negative. Blue cells for when negativ changes to poitive and yellow for when the reverse occurs. Comparisons are easlly made and I expect the picture to become clearer as more entries are made. Right click on the image and select New Tab for better visibility. Comments will be welcomed excepting those taking the mick re my selections.
Silver Moon
Have you thought about thinking as a fractional owner ?
I find that mindset much easier than anything price related
I do have fractional ownership in a way with Amedio Air Four but price-related numbers keep the grey matter working at my age of 80 years.
ME International (LON:MEGP)
I sold my holding in the last week or so at prices between 210p and 216p, not because I don't like the company, but because the share price appeared up with events and a profit of around 60% seemed a decent outcome. The proceeds were used to add to Zotefoams (LON:ZTF) Card Factory (LON:CARD) and Eurocell (LON:ECEL) the sale may have been auspicious but my purchases in terms of the price paid and today's closing prices were not.
Anyway the reason for the post is that until recently my local Sainsburys had ME photobooth at the entrance, today I noticed that while it still has a photobooth the name on the booth was Max Spielman. My inclination, as I speak a little German was to think that this is a German competitor. Apparently not!
Max Spielman it turns out is part of the Timpson Group that acquired it in 2008. Also Max Spielman is a fictitious name according to its website and doesn't exist, corporately anyway.
About Us | Max Spielmann
How good the Max Spielman photobooths are relative to those of the ME Group I don't know, but there appear to be providing some competition in the UK
There will be some stiff competition between ME International (LON:MEGP) and Timpsons with MEGP bringing out Kee.me and Timpsons muscling in on the photo booths.
I've written up this week's The Week Ahead, a slimmed-down version but hopefully it does the job:
The Week Ahead (3-7 March) - AI Sentiment, NFP, UK earnings season
Here are the performance figures for FTSE100, FTSE 250 and AIM index over 1 and 5 years, and also since October 1996 when the AIM index started at 1000 level.
FTSE100 1 year up 16% and helped by so many FTSE100 constituents being International shares.
FTSE 100 5 years. Up 34%.
FTSE100 since October 1996. A miserable (compared with a lot of major markets) UP 120%.
FTSE250. 1 year up 6% and 5 years up just 5%. BUT! Since October 1996 the FTSE250 has QUADRUPLED!
AIM INDEX. DIABOLICAL!!!!
AIM INDEX. 1 year DOWN 5%. 5 years DOWN 18%……and since it started in October 1996, DOWN 30%!
For comparison the DOW JONES index is up 7 times since October 1996 and the NASDAQ is up 10 times.
DAX index is up 7 times. INDIA is up 20 times since Oct 1996!
Can’t get the figure for Vietnam, sometimes described as the new India, but VinaCapital Vietnam Opportunity Fund (LON:VOF) which I’ve held along with VietNam Holding (LON:VNH) for most of this century is up 8 times since October 2003 starting level.
Enough evidence that a portfolio dominated by AIM shares is not a good way to invest?
Hi ken
I don't think those index figures are total returns. As the UK is so dividend heavy you can't really compare internationally without considering reinvesting dividends.
I don't have figures for the period you're quoting but between 2003 and 2023 the TSR on the FTSE100 was 241%, I wouldn't be surprised if the 1996-2025 TSR was of the order of 400%. Not as good as the US, but not bad.
AIM is awful, of course, but it was designed as a high risk, high return market. It was always going to generate a lot of terrible companies. What is slightly unfair in your comparison is that as companies have become successful they've moved away from AIM - so AIM is left with rubbish and the big winners don't get included.
Melrose Industries (LON:MRO), Unite (LON:UTG) , Genus (LON:GNS), Domino's Pizza (LON:DOM) , Hiscox (LON:HSX), Entain (LON:ENT), Big Yellow (LON:BYG), Breedon (LON:BREE), Alpha International (LON:ALPH) and Plus500 (LON:PLUS) all started out on AIM. I'm sure there are more. Its performance would look a lot better if they'd stayed!
AIM has clearly lost its way, though, there needs to be a serious rethink of what it's for.
timarr
I have found my investment performance improved since I started using the following rules three years ago, don't invest in aim or loss makers, avoid anything sub 200 mil market cap as generally to illiquid, use naked trader 3 x profit to debt rule, generally max pe of 20 min 6 , divi to be covered min 1.5 times avoid anything yielding more than 7%, spread max 2%.
That's the basics but as I mentioned earlier I'm moving 90% to ETF;s and Investment Trusts I work in the investment industry but I'm averaging the same as Rathbone Global Opps for about 20 hours of my time per week so intending to do some back testing on four way asset split as per Ed Shing's latest article with intention to moving to that if it merits.
After 25 years of average returns the odd big win anyone remember Cove Energy and plenty of disasters such as Torotrak and the like its finally got through to my thick skull I don't have the right temperament to make it into the top 5-10% of investors.
Serabi Gold (LON:SRB) big drop today - no news might be linked to yesterday’s drop in gold price. Not sure I’ve got the stomach for small cap mining shares……
JD Sports Fashion (LON:JD.) down to 79p - looks oversold now perhaps
International Personal Finance (LON:IPF) being sold on the back of great results and outlook.
Hold tight. The tide will turn.
Tempted to top up
Using the Transactions operation in my portfolio has now only given "buy" as its sole option. Deposit or withdraw function seems to have disappeared. Is it me ? or has an update gonre wrong
No problem on my folios.
Logged first thing, and tech team have replicated so on their to-do list.
Work around:
Click on the buy transactions and then amend the transaction mode to change to required transaction type
With reference to the post by bsharman at 10am today which mentions Jeremy Grantham and his views on a US Market Crash I have kept an Interview he gave Merryn Somerset Webb in Money Week Magazine on 3rd September 2021, over 3 years ago, when he said the same thing. The Article was headed " The US is in one of the Greatest Bubbles in Financial History"
If he thought he was right 3 years ago the current omens are much worse which I do find very worrying.
Tritax Big Box REIT (LON:BBOX) I hold
I happen to be one of those subscribers wondering if my subscription is worth renewing since the change of focus here. I have generally found little coverage of stocks I am interested in, being mainly a small cap investor. Today I hoped for something of value to me when I asked for comment on the final results of BBOX who reported
"Transformational year with significant strategic progress and excellent operational performance
Record rental reversion, attractive development pipeline and compelling data centre opportunities
Delivering highest total accounting return level since 2021"
A 5% + dividend yield to boot so it looked to me worth covering. Instead, out of around 60 comments 14 were directly about Grahams portfolio. A few others might have been triggered by something someone said about Grahams personal holding. Is it of interest to me, no.
Was BBOX covered, no. It's not even on the list.
In general, I think the value derived from the hard work put in by the team here and the comments of readers has declined markedly so it informs my decision about continuing to subscribe. I hope Ed, et al are taking note.
rwh3ue
Do you realise that there are a lot of excellent threads on Stockopedia? This link gets you to them:-
https://www.stockopedia.com/di...
Also re your gripe about Tritax Big Box REIT (LON:BBOX) not getting any coverage. It’s an Investment Trust and there is an excellent Investment Trust thread too. And it has included a lot of coverage of Investment Trust REITS. Here’s the link for the February Investment Trust thread.
https://www.stockopedia.com/co...
Charles Mitchell runs the Investment Trust threads and he starts a new thread every month…..so a new March one is imminent. Perhaps it’s worth maximising the benefits of your Stockopedia subscription as there’s so much on it, with this thread just a small part…….though some subscribers never seem to look beyond this thread,
A few are too quick to criticise Graham or Roland when they are providing excellent analysis and making this one of the go to places on Stockopedia. And it’s one of many.
Yes Ken, the link you posted is my home page for Stocko and I do read other threads. My point was a bit wider than just BBOX.
Would anyone have any thoughts on Pan African Resources (LON:PAF) which I hold. It's had a good run over the last 12 months but Stocko tells us a Shorter is involved. Could this be the reason for the recent dip? Pan African only pays a dividend one yearly, in December so that's a long way off which may be off-putting.
This volatlity must mean something is going on, the trend sems to have broken.
Serabi Gold (LON:SRB) Is similar, gold price is down, profit taking probably, after a good run.
Pan African Resources (LON:PAF)
"Stocko tells us a Shorter is involved."
That's interesting. Where does Stocko tell that? According to shorttracker.co.uk Marshall Wace have a disclosed short position of 0.5% but I can't see anything else. I assumed the recent price movements were related to the trading update and results released on Feb 10 and 12.
Negatives included a decline in headline EPS, operational challenges, and increased debt.
Positives were the acquisition of TCMG, forecast production growth, and a potential rise in gold prices, which should improve cash flow and ultimately reduce debt. I top sliced in December but continue to hold the remainder. Perhaps I am too optimistic about the future trajectory of the gold price.
It's on the Stock Peport, Dwit, in the Screens Passed box.
"It's on the Stock Peport, Dwit, in the Screens Passed box."
I see what you mean now. I thought your were referring to actual short selling, which as far as I can tell doesn't appear in stocko.
I hold Pan African Resources (LON:PAF) (belatedly jumping on the gold rally) but am in no way knowledgeable in this. I attributed the recent dip to a combination of them reporting on decreased outputdue to power cuts from ESKOM at the end of last year (which apparently was more ongoing than assumed at the time) and the chill political winds blowing from the USA. I'm just hoping the worst is over...
Thanks for posting on your personal share holdings. I am always impressed at the patience you show in your shares. Impatience is one of my biggest failings.
Thungela Resources (LON:TGA)
100 SR and I have a small position. Not a widely discussed stock on here...the FTSE coal badboy based in South Africa!
They have today released a trading update (ahead of their financial results early March) that the earnings per share looks set to decrease...
- 9% dividend yield
- attractive PE ratios
- brokers upgrading forecasts recently
- very healthy ROE/ROE ratios
- healthy cash position
I would be interested in getting others views on this stock. Down 4% today and I am considering increasing my position. Anyone else holding?
Not holding (and wouldn’t due to it being a coal miner) but I would say you should see if it bounces off the 450 support level and consider your investment then. You might want to add more if it looks like it will stop its descent at 450 but if it starts to break into new lows then I would get out. Looks like it might be a range trading opportunity perhaps.
I know that’s not the opinion on the company you were looking for but given the downward trend you need to work out if you want to average down (always risky) or get out.
@Carey Thank you for your comments. I do not consider myself a charting expert, but there's a chance that this could be a higher low (see previous low in February 2024 and then the higher low in September 2024). I am tempted to increase my position in what I think is a sound, undervalued company with a stock rank of 100.
Since the start of this month it has been in a straight downtrend. But prior to that, over the past calendar year it has been range bound yes.
Yes Snooze, I hold. For me, it's a large position so I invite you to share my pain. I bought at 694 pence so am a good third down on this investment. I reckon on catching up sooner or later and have reaped a dividend of almost 7% for the last whole year.
Edit: Reading CB's comment below if I had oodles of spare cash I'd double down, this would help my position bearing in mind that the trading update indicates to me that the dividend will rise if not the share price. When I held a small position I collected dividends of 13 to 15 % in Thungela Resources (LON:TGA) .
My thoughts exactly, I am going to increase my position today.
Yes, I hold too. Generally sound financial position. 9% dividend yield, but the div cover is a bit low. Think I will hang in and what happens. Don’t want to sell now as market is so depressed generally.
Re Primary Health Properties
Any interest in PHP?
Company narrative today suggests that preliminary results are slightly ahead of market consensus .
Dividend increased from 6.7 to 6.9p and fully covered. Rental income increases 2.9 % with 89% of rent roll covered by "Government bodies"
Borrowing of 48.1% to wards the higher end of quoted range (40-50%). Decline of 2.8 % in adjusted NTA.
I have bottom fished here and am currently breakeven. Bought on the basis that interest rates might come down further but inflation likely to rise sharply.
Thanks for sharing your portfolio Graham.
Your thoughts brought to mind an adage
"Time in the market is better than timing the market".
Anybody elese out there feeling utterly dispondant with 250/AIM ? I have a portfoilo of around 40 stocks well spread, I look at it in dismay. JUst back from a weeks skiing and its carnage yet again. When oh when will the mkt improve. We all have stock pick winners dont we but our long term portfolios. Last summer was looking hopeful now woeful.
Time for a bike ride on a beautiful day
Totally agree, but I have been here before. Time to hold your nerve. Not sure what the catalyst will be, but it will improve at some point.
Yes totally agree. Every day feels like Groundhog Day with my portfolio value slowly diminishing.
Hang on in there Mike.
The FTSE AIM index has seen terrible performance (except for a huge gain just before the tech bubble burst in early 2020) ever since it started. The AIM index was started last Century at 1000 and now is down 30% from that starting point! DIRE!
So any portfolio that holds a lot of AIM shares will have done very badly unless the investor managed to find the shares that way outperformed the index. It’s far easier finding winners where the majority in that region or sector are rising than it is when the majority are doing very badly.
The answer is not to focus on such a narrow area but to have a diversified portfolio including perhaps some Investment Trusts to invest all round the World in much better performing markets than the UK and way way better than the awful AIM index here.
A portfolio heavily weighted to one small sector of the very wide investment world will either be a disaster area or a roaring success.i.e it’s a gamble.
The size of our portfolios can vary widely. There’s no right answer on that beyond too small with a huge amount in just one or two shares being very risky. What if one of them is a fraud? It’s unlikely but it has happened to what looked to be rock solid companies. I top slice as soon as any one investment gets to too high a percentage of our portfolios.
A portfolio of over 100 investments takes a lot of monitoring and risks averaging down overall performance.
Key thing though is not what is or isn’t the right way. Is if it’s working for us then keep doing it. And if it isn’t working don’t continue doing it. That shoukd be so obvious, but it’s amazing how investors persist with methods that have failed them badly. That includes holding on to and believing in blue sky hopeless shares even when they have fallen over 90%!
If you browse the statistics for Aim shares on here, you will see that a very large number are not profitable and are consistently losing money. Many have to finance these losses to continue in business and that generally means going back to their shareholders to stump up. The banks are unlikely to lend as there is no certaintly that any loans would be repaid let alone the interest on the loans paid. There are quite a lot of casualties on the Aim market where even the shareholders have given up support. The quality of many AIM companies is very low. Many companies on Aim have no turnover and are living on a prayer that eventually their idea or development will eventually bear fruit and bring in profits. In many cases it does not. It is not surprising that the Aim market has been a disaster. If you want to avoid disasters, steer clear of Aim shares that are not paying a dividend. There are some good quality gems that are paying dividends that go from strength to strength. Choosing FTSE 100 or 250 stocks is far safer but once again, avoid those incurring losses, not paying a dividend or those that are heavily geared. That way you are likely to have far less disasters and you have a chance of making steady growth. Looking at the chart performance of the main market and comparing it to Aim bears this out.
It is like death by a thousand cuts at the moment. Most days the majority of my portfolio is down and it tends to get worse through the day. The US is in bubble territory (just listened to a podcast with Jeremy Grantham on Bloomberg) - the sentiment in the UK is terrible and the markets need some support/initiatives to promote it. Although the UK is relatively cheap it will move in sympathy with the US and this means that if there is a crash or correction in the US then the UK market will fall in response. I don't know what to do in these market conditions, so if any one else has some tips or advice please do share!
Yes bsharman, can't wait for the US tech bubble to burst, and see the fallout grind our feeble AIM and small cap positions into the dust.
Perhaps this would be a good topic for one of our experts to pick up?
Basically UK small company share prices can, and most likely will get worse, so what should we do about it, and when?
Perhaps if there was a correction in US tech and a tiny fraction of that sprinkled on the UK market then it could be a positive, but I am probably just being overly hopeful.
I'm not an expert forecaster - neither bullish or bearish. I cherry pick stocks that I understand and use more and more of. Of course it's easier to succeed with a rising tide..
There's an awful lot of financial commentary out there and some of it awful financially. So I do find it interesting that Grantham predicted 50%+ bubble crashes in 2000, 2008, 2011, 2018 and 2023. Always with good reasons. Two of the crashes even actually happened..
Stuck clock tells the correct time twice a day….
I recommend Justin Waites book “micro cap millionaire” for everyone struggling with this. Has some useful strategies for dealing with downward markets and portfolio management.
Hi Mike - so miserable at the moment. I decided not to fall prey to yet another financial adviser and lose money to them every year as the only absolute guarantee, whilst they get paid for me paying other fund advisers to invest, so I'm now DIY. Stockopedia has my trust despite all this. My 20 shares invested in a NAPS-esque way have done OK - and better since inception in March 2023 than any savings account I could find (I'm around 20%) - but I have lost about 10% of value over this last 6 months and even the FTSE is outclassing me. So depressing. Perhaps I'm just demonstrating once again that I'm no good with money. Still, rules are rules and I'm sticking to them, and so I won't do anything unless there is a profit warning I notice (see recent posts) and will only re-evaluate in March and September based only on metrics - not on stories. Wish me luck. No Mike, you are most definitely not alone.
Hi Jim. Last year I was up around 20% by this time in the year. This year has been a bad start and I am down 10%. It’s hard to not over react but that is the best thing to do at the moment.
I don't really understand why they are down this year. There doesn't seem to be an obvious factor to me - is it just general negative market sentiment?
Currently about -5% YTD and below equivalent indices so feeling very disappointed. The only bright part of my portfolio are my REITs which are all slightly up and supported by strong dividends.
Building the war chest ready to pile in as I see the current weakness as a parallel to the Oct 2023 capitulation where anyone with stop losses was taken out.
It's been tough watching my portfolio go sideways since last June before heading down since mid Jan. Contributors include GRG, JDG, FGEN, TRCS, YU and W7L. Exceptions include FTC and III (no doubt a Ken Mitchell favourite).
Darkest before dawn and all that.
Agreed Mike I've been moving most of my pot into ETF's and Investment trusts .
I only need to average 5/6% per annum so I am mulling changing strategy towards Ed Shing's latest article of 25% in gold, 25% money market (paying 4-5% at mo) 25% in bonds I would need to get more skilled up in this area as can move around a lot depending on duration, and i'm thinking final 25% split between S&P 500 equal weight ETF, EuroStox 60 ETF and FTSE 100 ETF (last one for commodity exposure if we have another year like 2022 again)
I reckon I could run this in 30 minutes per week with quarterly rebalancing and spend the other 10-15 hours per week I spend on stocks devoted to something I would be more successful at.
I'm guessing like me for you its a bit of a drug so maybe keep 5-10k back for a couple of mid cap gambles.
When oh when will the mkt improve. We all have stock pick winners dont we but our long term portfolios. Last summer was looking hopeful now woeful.
I'm possibly in cohort of one but I think these markets are terrific value. Over the last couple of years I've been able to pick up a whole range of stocks at remarkable yields and yet I can still recycle that dividend flow back into buying even more of them.
So far this year across my (very large) portfolio I'm seeing an average earnings rise of about 5.5% and a dividend rise of about 6.3%. Yet my portfolio has fallen by about 7%.
Red ink in the portfolio is simply people reacting. Ultimately what matters is that companies continue to grow earnings and eventually that turns into share price appreciation. If we buy at the wrong time - and I often do - it can take longer for that to come through, but it will still happen.
Of course, it's important to buy stocks that don't need to raise equity in these sorts of markets, and there's plenty of opportunity for more short term volatility. But generally markets go down about a third of the time, and those down days often happen together. Stressing about them just makes for unhappy people.
timarr
Hi timaar
You can add me to your cohort, although I admit that it is disheartening to see perfectly good shares with decent prospects and valued very modestly on most investment metrics continue to fall in price. In the main I tend to remain fully invested and like you use dividend income to add to existing holdings.
Most of my portfolio that consists of 24 small cap shares is AIM listed, not by design but because I like and understand the companies. To date I have been fortunate to avoid any profit warnings and shares such Zotefoams (LON:ZTF) that I bought recently around 305p after the positive trading statement post termination of its investment in 'Rezorce' and Kitwave (LON:KITW) results due next week, but trading in line as at last November's update continue to be marked down. Hopefully the outlook statement for the latter will confirm a continuation of that trend.
It is difficult to know what to make of the market in small caps at the moment, so for me its back to sitting on my hands!
Anyway that's my tuppence worth. I suspect that I have got off somewhat lightly so far, with the portfolio down around 3% since the start of the year.
All the best
Anybody elese out there feeling utterly dispondant with 250/AIM?
Yes! Over the past few weeks I have exited most of my AIM positions. The only two that reman are Gamma Communications (LON:GAMA) which will soon be moving to the main market and AdvancedAdvT (LON:ADVT) which I view as something of a special situation.
My thinking is that AIM is close to being a broken market or at least, a market for mainly just retail investors. The death knell was delayed in last autumn’s budget as only half of the IHT benefit was removed but how long before the other half is removed? Are wealth managers going to be directing funds towards AIM or encouraging their clients to quietly exit stage left? The liquidity is so poor I can’t imagine it is a fun place for fund managers these days.
As for the FTSE 250, I’m sticking with it for now as I don’t believe there are any particular structural issues, merely a lack of confidence in UK PLC which as timarr has already concluded, might represent an excellent buying opportunity. That said, the FTSE 100 is having a good year which might be more to do with dollar strength than confidence in the UK.
Enjoy your weekend everyone!
Yep, another crappy end to a crappy week.
it’s been bearish for about 3 and a half years now on aim, not sure what the catalyst will be for a bull market, if it can even turn around - maybe peace in Ukraine and cheap gas will help
Take me back to mid 2021 and I’d sell the lot rather than losing at least 60% of my PF
Hi Mike, I don't know whether or not to feel consoled by your note and the similar sentiment in other investors replies, at least we know we're not alone so thanks for that. At least you've missed most of it by being away all week!
I started the year well, boosted by a takeover for my largest holding. At that point I was a genius but six weeks later I'm reflecting that this week, and today especially, has been one of the most depressing.
I'd be slightly better off if I acted quicker on my very tight stop rules but I'm also finding individual stocks crashing right through them in a single day with no news. I've been stopped out of a lot of stocks lately and as of today am 50% cash - self preservation to fight another day, and sleep slightly better between now and then.
Hope isn't a great investment strategy but I do hope we'll all feel better this time next week.
Hi Graham, I must agree that patience is rewarded since a number of companies I gave up on and sold at a loss have since been doing very well indeed. Of course, if we bought at the right time we should have no such worries in 99% of our investing.
I've been looking at the "strategic investment" - Science (LON:SAG) buying 8% of Ricardo (LON:RCDO) shares and can't make sense of it at all. I don't hold either but Ricardo (LON:RCDO) is on my watch list on the basis that it must get its act together eventually and when it does it is undervalued. I don't see a lot of overlap in the two companies and I find both a tad fragmented.
re Ricardo (LON:RCDO), I thought the sense was that Science (LON:SAG) thinks it can make money doing some common sense rationalisation on Ricardo (LON:RCDO). As it has done on other companies. And if someone else does the job they will still make money.
Tritax Big Box REIT (LON:BBOX) I hold
Full year results look pretty good to me. Any chance of some commentary?
Many thank for sharing your portfolio, Graham. I really appreciate it.
No problem at all Mark - I'm not embarrassed by it, no need to keep it secret!
Nice to see a genuinely long-term, patient investor who sticks by their positions. With quality names like Berkshire and Next that's probably the right approach.
It was very honest sharing your portfolio, thank you.
I also have to be honest and say i was genuinely shocked by it. As they say diversification is the only free lunch. So why not take full advantage?
We can hazard a guess on what the top 100 shares in the market are but in no way do we know what the top ten are. This indicates that portfolios up to 100 are reasonable, for example shares that have a 90+ stock rank. But of course many small holdings create more maintenance and dealing costs, so we want less than this.
The NAPS portfolio Ed runs has 20 deliberately spread across industries. This makes sense. Personally i have about 30 shares but a lot of the total value is in now in gold / silver / bonds / property because i think the market outlook is very poor with Trump in power.
If you only want to hold a few shares then a 'barbell' portfolio could work. A heavy weighting in a very diversified tracker like an All World global ETF. Then high risk and hopefully high return shares in a range of speculative oportunities. I think the Berkshire holding does thankfully give a lot of stability because Buffett is holding a lot of cash at the moment.
Unless you are over 90 you have time on your side, and dont need to aim for returns of 50% in one year. This means more feasible returns of 10% each year for 5 years can be planned for and probably achieved.
Thanks for sharing your portfolio Graham I’ve only held 2 of these in the past. What strikes me about it is the size, it is compact which I find interesting, as I have a habit of too many shares believing it spreads risk. I seem to like buying shares that I like the look of but don’t invest enough in the winners. What’s your rational behind a tight portfolio?
"I have a habit of too many shares believing it spreads risk" So have I, Archer, 110 companies in our portfolios yesterday, 109 today. Risk is spread, experience is gained over time, dogs are gradually recognised for what they are and eliminated and the folios begin to flourish. All other things being equal of course, not getting into politics.
Its not the number of stocks but the weight of each stock.
Graham, it’s great to have an overview of your portfolio so thank you for sharing. I’m struck by the fact that it’s relatively concentrated (10 holdings, all but one UK listed small / mid caps) and also that the position sizes vary so much (from 33% to 1% of the portfolio). I suspect this might be a result of your natural “inertia” as well as the recent run-up in the price of Volvere and others. But it does mean that the smaller holdings effectively have no impact on the overall position (even if Impax doubled overnight, it wouldn’t make a great deal of difference to the overall portfolio). I struggled with this in my own portfolio and, for holdings under 5%, I now have a strict “double or kill” policy (either double my holding or sell it altogether) to avoid the “noise” of tracking shares which don’t contribute to overall performance).
This isn’t intended as criticism or even advice; I just wanted to contribute to the discussion by posting the things that popped into my head as I read this over my morning coffee. Hopefully it stimulates some more debate!
33% in a 42 million company is very risky..
Too right. I actually think Graham's portfolio is utterly bizarre. Thank you for sharing, Graham, but for goodness sake get a bit of diversification in there! Two holdings making up 60% of the total is just crazy, especially when one is an obscure small cap and the other depends on the continuing investment success of a company whose reputation is based on on a 94 yr old CEO!
I completely disagree that a good portfolio must have many stocks. There is a strong argument for focusing on winners and knowing everything about a few companies rather than a little about many. Also hat off to Graham for his patience. The hardest part of investing. Proof is in the results. I wish I had those returns over last year.
Berkshire Hathaway (NYQ:BRK.B) has many stocks though, around 40.
I think Graham's portfolio is cautious and sufficiently diversified. You have to look through the number of names in the list.
Volvere (LON:VLE) is the odd one out for me. Surprised he does not hold many of yearly picks, only his two smallest ones.
I’d suggest there are many definitions of risk…& on some of the better definitions of risk Volvere (LON:VLE) would score really highly…most of its market cap is cash derived from previous successes..the remainder is a highly successful pie factory that occupies a valuable freehold site and serves the supermarket sector with a range of products that could fairly be described as recession proof. I hold a small position here & saw first hand the lengths mgt went to try and get a live video link working so Graham could participate in the AGM a few years back. I’ve also held it for many years so my bias might be considerable…I too v much miss Jonathan Lander he was a pleasure to interact with & genuinely warm & funny whilst being an extremely talented capital allocator…his brother will doubtless look after his legacy & other shareholders in the process.
Beautiful comment, Rhomboid!
ME International (LON:MEGP) secondary placing yesterday because the second biggest shareholder, Montefiore Investments, wanted to reduce their stake. They've sold 7% of the company shares and will keep a 5% still. The placing was at a 10% with a price of 200p.
I had ridden the Megp rise like many in here but decided to go short via spread bets when it failed to take out the previous high at 220 and formed a double top. Closed it now for a nice profit. Will see how far it falls or stabilised before going long again
A belated thank you for the extensive write up’s of Brickability (LON:BRCK) and International Personal Finance (LON:IPF) this week (I hold). In this tough market these analyses are appreciated and reassure that they are still good companies despite the SP being suppressed.
You're very welcome. I wish I could have covered more this week but the flow of news has frankly been overwhelming at times. Hoping to catch up a little today.
I'd add to that your write up of MACF yesterday - a typically even keeled piece of analysis which is particularly valuable when shares are trading near multiyear lows.
Hi Graham. Placeholder has wrong day on it.
Thanks Revs, fixed that.
I wonder if the UK avoids tariffs (as hinted after Starmers meeting with Trump) might we see a little more positive sentiment for UK stocks that sell into US? Especially if other regions take a tariff hit.
Starmer/Trump meeting yesterday being reported as having gone much better than expected. Fair play Starmer but being a gloomy sole at the moment I couldn't help looking back in history to the Neville Chamberlain "peace in our time" thing. Gosh, that is gloomy!
Actions speak louder than words so waiting to see what actually happens.
Tough market at the moment but still opportunities to search out? Suggestions on the best way to play these markets?
My understanding is that because of our trade balance there is probably a disincentive to raise tariffs on the UK. Not sure Starmer knows what's going on to be honest...
It's difficult knowing what's going through Trump's mind. It seems to vary from day-to-day. Having followed the news for the last week, everything keeps changing, with many twists and turns. I'm not solely talking about the US, either, but more broadly about Ukraine, Russia and Europe. I've come to the conclusion that we'll only know what happens after the fact.
I found a webpage about net exporters and imports. https://www.statista.com/chart...
It's quite interesting. It's no surprise that China is the world biggest net exporter, followed by Russia (I didn't expect that), Norway (another surprise), the Germany, Saudi Arabia and Japan.
The world's biggest net importers are US (absolutely no surprise there), then the UK (oh), India, France, Brazil and Turkey.
Although he hasn't explicitly come out and said it as such, I think Trump has in mind that he really wants to beef up America's manufacturing base with a view to improving both domestic consumption and exports.
Given that UK is such a big net importer, that probably explains why he views the UK favourably, with Europe being "atrocious" (which some on here may agree or disagree about with varying degrees of strength).
It also explains why he not seeking to impose tariffs on the UK.
I think the UK is in quite a good bargaining position wrt Europe and others.
How can you really take anything from what a man says when he is a proven cheat, liar and rapist? Overwork it but the only thing he is interested in is becoming the king of the US and helping Russia.
Spot on he is the ultimate black swan for markets denied calling Zelensky a true leader a dictator today if Biden had of carried on like this the press would have slaughtered him.
Hi Mark one thing to highlight Peter Zeihan did a piece a while back on Trump and the US pulling back from globalization, he talked about how their biggest ally Japan got a trade deal but it was so bad it was humiliating however Japan could see what was coming and essentially just wanted in with the US in the new world order regardless.
Hopefully we will get something but my personal opinion is we need them way more than they need us and Trump isn't known for being charitable unless your surname is Putin.
Dover soles, lemon soles, sand soles but gloomy soles?
Oops!, apologies for the misspelling. Sole/soul. I'm such a silly fish.
What about plimsoles for the active investor?
Peter
Have to wonder whether anything Starmer thinks he’s achieved will be ‘true’ in a couple of days.
I watched this broadcast on MSNBC a few days ago which made me a gloomy soul. Some of the reactions are quite interesting, even from some Americans.
https://www.youtube.com/watch?v=4EZ7gayXMSI