Daily Stock Market Report (Fri 5th September 2025) - PEEL, G4M, BKG, ASHM

Good morning and welcome to today's report.
The agenda is now complete.
Update 12.30: today's report is now complete. We're expecting a busier week next week, as Mark discusses in The Week Ahead.
In the meantime, I hope you have a good weekend.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Berkeley group (LON:BKG) (£3.4bn) | On track to achieve FY26 PBT of £450m, in line with guidance. Expect a similar result in FY27. | AMBER (Roland) [no section below] I’ve long viewed this brownfield redevelopment specialist as one of the best-run housebuilders on the UK market. However, today’s in-line update suggests to me that the business will generate a return on equity of c.10% in both FY26 and FY27. At this level of profitability, the shares look fairly valued to me, trading in line with last-reported NAV. In addition, I’d echo Graham's previous comment that Berkeley's ongoing practice of making share buybacks at or above book value may be propping up EPS, but isn’t accretive to NAVps. For a property company, I’d prefer to see surplus cash returned as dividends unless the shares are trading at a discount to NAV. I'm staying neutral. | |
Ashmore (LON:ASHM) (£1.22bn) | SP -6% AUM -3% to $47.6bn, net outflows reduced to $5.8bn (FY24: $8.5bn) Adj PBT -33% to £70.1m. | AMBER/GREEN (Roland) Another year of net outflows, with investors withdrawing more than 10% of opening AUM through the year. It’s some consolation to me that Ashmore’s positive investment performance recouped much of this loss. But until investors start to allocate cash back into the group’s emerging market funds, it looks like earnings will remain depressed. The 10% dividend yield is not covered by profits, but it is still supported by a strong balance sheet, with over 70p per share of surplus capital. That should limit the near-term downside risk, in my view, while significant recovery potential exists if Ashmore can manage to start attracting positive flows. While I remain broadly positive on the recovery potential of this business, I don’t think I can be fully positive on the stock with the current combination of outlook and valuation. | |
Tufton Assets (LON:SHIP) (£224m) | Sold Neon (a ship) for $23.5m, a 2.6% premium to NAV. IRR 13.5%. Now has 19 vessels. | ||
Camellia (LON:CAM) (£145m) | Rev +2.5%, Loss before tax £10.4m. NAV -10% to £312.4m. 2025 results exp ahead of 2024. | ||
Peel Hunt (LON:PEEL) (£125m) | SP +10% Strong start to year in M&A and capital markets. FY26 results now to be ahead of expectations. | GREEN (Roland) [no section below] Graham correctly called this broker as GREEN in July and today’s update seems to confirm that activity levels in UK equity markets may be improving. Peel says it has acted on some "substantial" M&A transactions in recent months and now has 58 FTSE 350 clients, up from 52 at the end of March. The firm also reports signs of improving activity in capital markets and execution services. Profits can bounce back quickly in this type of business. With ample net cash on the balance sheet and a valuation of just 1.4x net assets, I see no reason to change our positive view today. | |
Victoria (LON:VCP) (£76m) | Trading remains in line with July guidance. Focus remains on self help initiatives and deleveraging. | ||
Gear4music (HOLDINGS) (LON:G4M) (£56m) | Q1 FY26 revenue +27% vs Q1 FY25. FY26 results to be ahead of exps (rev £155.8m, PBT £3m) | AMBER/GREEN (Roland) The music equipment retailer says it’s gaining market share and benefiting from more supportive market conditions in the UK and Europe. Today’s upgrade is the second in three months and has sent the share price to a post-2022 high, leaving the stock up by 50% since Graham turned GREEN in June. I think there’s scope for further growth (and upgrades), but I’m also aware this remains a low margin retailer with limited visibility of sales ahead of the peak Christmas trading period. Gear4Music has also struggled to consistently generate attractive returns in recent years, leading to an unfortunate debt splurge. While leverage now looks comfortable to me, I think some further growth is already priced into the current forward P/E of 23. To reflect this view, I’m moderating our view by one notch today. | |
Tialis Essential IT (LON:TIA) (£21m) | Begun delivery of major UK govt contract announced Jan 25, exp value £15m over 5 years. | ||
Fadel Partners (LON:FADL) (£13m) | Rev -11%, adj EBITDA £(2.4)m. FY outlook unchanged for EBITDA loss of $0.8-1.0m. |
Roland's Section
Gear4music (HOLDINGS) (LON:G4M)
Up 10% to 292p (£61m) - Roland - AGM Statement & Trading Update - AMBER/GREEN
[...] strong trading in the year to date provides the Board with sufficient confidence to once again increase its expectations for the Group's financial performance for the year ending 31 March 2026
Today’s update from this online music equipment retailer is short but sweet, with Gear4Music upgrading its profit guidance for the current year for the second time in three months. (Graham turned GREEN at the last upgrade, with June’s results, flagging a possible opportunity)
My reading of today’s update is that the company has successfully retrenched following the post-pandemic slowdown and is now benefiting from some of the same competitive advantages that fuelled its earlier growth:
Revenue in the first quarter of FY26 (Apr-Jun) was 27% ahead of the same period last year, “with traction continuing in Q2 FY26 to date”
Refreshed growth strategy is delivering results, aided by “a more favourable competitive landscape” in both the UK and Europe
Management believes the group is gaining market share
Outlook & Estimates
With the caveat that it’s still early in the year and ahead of peak Christmas trading, the company now expects FY26 results to be ahead of the upgraded guidance provided in June.
Gear4Music doesn’t provide updated financial guidance but does reference current consensus expectations for revenue of £155.8m and pre-tax profit of £3m.
Fortunately, paid research house Progressive has issued an updated note this morning providing more detail on expectations for this year and next:
FY25 actual EPS: 3.8p
FY26E EPS: 12.1p (prev. 9.3p)
FY27E EPS: 12.5p (unch)
This is a 30% upgrade for FY26 – a substantial increase.
However, strong recent share price gains mean Gear4Music is still trading on a FY26E P/E of 24 after this morning’s gains.
Progressive’s FY27 forecasts have been left unchanged today, which the research house says reflects a lack of formal guidance from the company. An update is expected with the H1 results in November.
Roland’s view
Gear4Music (and its shareholders) have been on a remarkable journey since its listing in 2015:
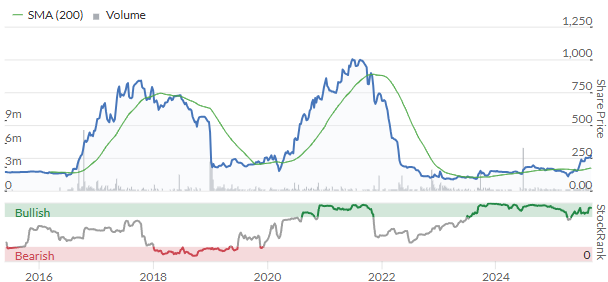
Earnings expectations have also been volatile over the last year, perhaps serving as a reminder of the limited visibility the company has on consumer demand:
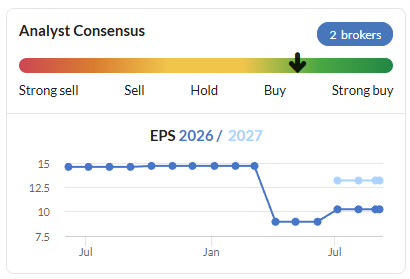
Our coverage has reflected this, with Mark and Megan both warning of the elevated debt levels in April, before Graham turned positive in June when full year results showed a reduction in debt and improved trading.
The StockRanks have picked up the opportunity this year and Gear4Music’s shares have risen by 50% since June:
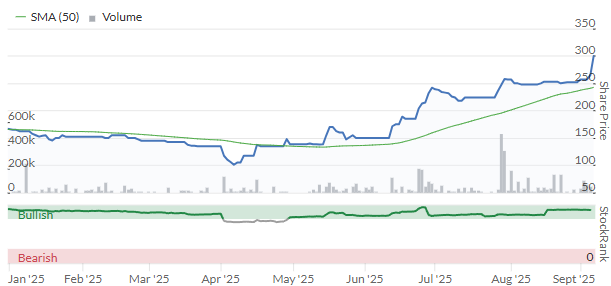
Where does that leave us today? I’ve been impressed by Gear4Music’s progress in recent months and I think there’s a reasonable chance of further upgrades.
At the same time, my feeling is that forward visibility on sales is somewhat limited ahead of peak festive trading, due to competitive pressures and the uncertain consumer backdrop across Europe.
A further concern for me is that this remains a low-margin retailer. From what I can see, operating margins have averaged around 3% since the company’s IPO, ignoring the distortion of the 2021 pandemic boom year.
Returns on capital have also been low in recent years – presumably below the cost of capital for this business. This probably explains the company’s previous use of debt to fund growth – profitability was not high enough to allow the business to self-fund major expansion.
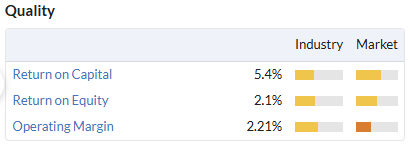
However, today’s updated forecasts suggest to me that ROCE could improve to c.8% this year, with potential for further improvement in FY27. Further debt reduction also seems likely – I no longer see leverage as a significant concern.
I’m also impressed by current momentum here and aware that repeated upgrades can often trigger a surprising run of growth, as Ed has discussed recently.
I don’t want to get hung up on the valuation as I think there is scope for further growth beyond current expectations over the next 18 months. However, with the share price up by 50% since Graham turned GREEN in June, I think some of this potential is now priced in.
For these reasons, I’m going to moderate our view by one notch to AMBER/GREEN today.
Ashmore (LON:ASHM)
Down 5.5% to 162p (£1.15bn) - Roland - Final Results - AMBER/GREEN
Emerging market specialist asset manager Ashmore has benefited from the broader share price rally in this sector this year, but has come off the boil recently. Today’s results seem to provide some justification for this, with the Reuters newswire suggesting today’s results have fallen below consensus expectations.
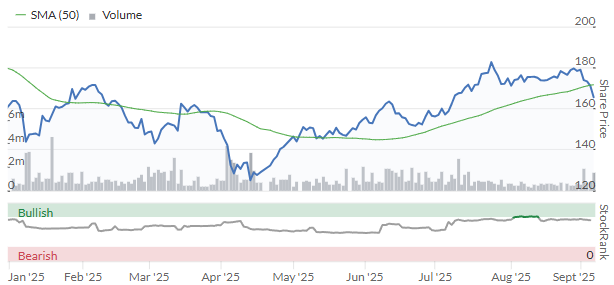
Let’s take a look.
FY25 results summary (y/e 30 June)
The main headlines from this morning’s results show revenue down by 23% to £144.1m. This drop was mainly driven by a 19% decline in management fees, which fell to £129.7m.
Lower management fees are a reflection of lower assets under management. Ashmore’s year-end AUM fell by 3% to $47.6bn, but average AUM through the year was 7% lower, at $48.9bn.
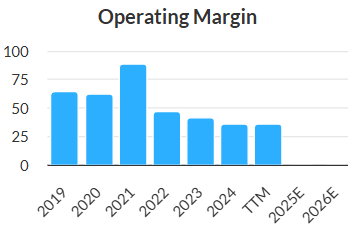
Employee costs fell by 15% to £71.8bn. This largely reflects the drop in performance fees earned last year and the resultant reduction in bonus payments. However, with salary costs unchanged there was still some negative operational gearing. Operating profit dropped 34% to £49.4m, excluding £9.4m of gains on seed capital.
Although these results still show Ashmore generating a creditable 33.7% adjusted operating margin, this is down from 39.8% last year and well below historic levels:
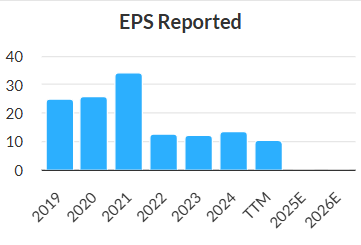
EPS & Dividend: the dividend for the year was held at 16.9p per share, giving a 10% yield. This was not covered by reported earnings of 11.8p per share, but may reflect a) the strong balance sheet and b) founder/CEO Mark Coombs’ 29.5% shareholding. This provides him with dividend income of c.£35m per yearr.
Balance sheet: Ashmore shares are trading at around 14x today’s reported earnings, but as we’ve commented previously this business has a very strong balance sheet with capital and cash that cover the majority of the market cap:
Net asset value: £782.6m (FY24: £882.6m)
Surplus capital over regulatory requirements: £510.9m (FY24: £599.2m)
The group’s surplus capital is equivalent to just under 72p per share, by my calculations, supporting nearly half the current market cap.
It’s probably worth noting that both NAV and surplus capital have reduced since last year. My feeling is that this largely reflects the maintenance of the dividend at 16.9p – a level that’s not been covered by earnings since 2021:
While I’m not generally a fan of uncovered dividends, in this case I think it is a justifiable decision. Ashmore has ample surplus capital and can readily afford to return some of it to shareholders.
This aside, I think some of the other movements in the balance sheet are also worth noting. Ashmore’s cash balance fell from £512m to £349m last year, but this was largely due to £113m of additional capital invested in the company’s seed funds.
These are investments for which Ashmore is building a track record in the hope of being able to offer them to clients in the future.
In this case, management says funds were invested in strategies including “frontier blended debt, impact debt and Mexico equities”. They were also used to help scale up some existing funds:
providing additional scale to existing funds in anticipation of client demand as investor interest in the emerging markets asset classes gathers momentum.
Trading commentary: is the outlook for this business as poor as Ashmore’s profit slump suggests?
My impression is that this company has been suffering from the same malaise as many other parts of the market – its offerings have underperformed the Mag 7 and broader US market.
However, today’s commentary suggest Ashmore’s performance is not too bad when compared to relevant benchmarks and improved dramatically last year:
As at 30 June 2025, 57% of AuM is outperforming over one year, 70% over three years and 81% over five years (30 June 2024: 40%, 59% and 62%, respectively).
The real problem was that clients continued to withdraw funds from all the group’s strategies despite seemingly positive performance:
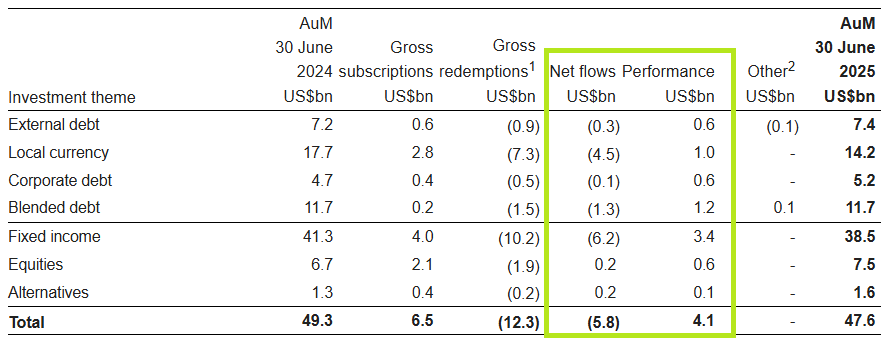
Today’s results go into considerable detail on market conditions and Ashmore’s efforts in various regions of the world and make interesting reading.
The company is putting increasing effort into some of its regional offices. While local office AUM only represents 16% of the group total, this is seen as an important area for long-term growth and diversification.
Outlook
As always, CEO Mark Coombs is a perma-bull on the opportunities in emerging markets, but in fairness I can see his point. Surely at some point there will be a rotation from the largest US stocks into a broader range of opportunities?
The global macro environment remains complex, notably with the impact of US policies and geopolitical risks including conflicts. However, several themes are evident and point to the need for investors to rebalance allocations away from the US and to other regions, and particularly to emerging markets, in order to position for higher risk-adjusted returns over the medium term.
Coombs also notes that recent changes to emerging market credit ratings have been “net positive” and suggests that the prospect of a weaker dollar may mean that emerging markets become relatively more attractive for foreign investors in US markets.
There’s no formal financial guidance in today’s results, but consensus estimates prior to today were cautious, suggesting another weak year may lie ahead:
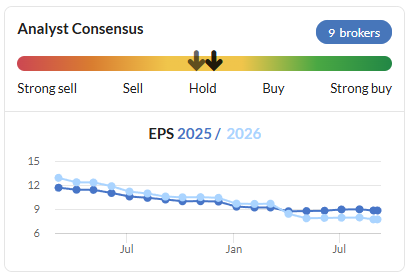
These figures put the stock on a FY26E P/E of21, with a tempting (but uncovered) 10% dividend yield.
Roland’s view
I’m reassured by the continued strength of Ashmore’s balance sheet and by its positive investment performance over the last year.
In a more neutral market, I’d argue that these would comfortably underpin the current valuation.
The key issue for me is that the company is continuing to suffer sizeable net ouflows – and I can’t see anyway to know when this trend might change.
On balance, I think Ashmore remains reasonably valued and conservatively financed. If net inflows return, this business should have the potential to deliver a strong recovery in profits.
However, I don’t think I can be fully positive at this time given the uncertain outlook and uncovered dividend. I’m going to move our view down by one notch to AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

26 comments
Today’s continued fall in Cohort (LON:CHRT) reminds me to ALWAYS pay attention to Director sells. The sales that three of them made in July were pitched at the all time high. I did not sell - silly me. The sales were made along with an announcement of higher expectations, but:-
Rule 1 is: Follow the money not the words
Something to think about with Science (LON:SAG)
I took the same lesson for Brickability (LON:BRCK) this year - director sales at the 1 year peak in June 2025 at 69p (including a cool £2 million sale), price now 55p. Your rule 1 is spot on....
what info sources do you use for director dealings? I could do with a simple, preferably single (or two) source
Hi, I look out for RNS alerts here on stock (check director dealings RNS alert types are ticked on your filters), and/or the director dealings tab on the StockReport page.
Google is free !!
I totally agree Aislabie.
Best to just completely ignore the quoted “reasons” for the sales and the noise from the unconscious bias shareholders who insist its all ok.
I have a long list of smallcap company’s directors who sold at the top in my shareholdings which I failed to react to. And who’s share price subsequently bombed. Not any more. Luceco , Treatt, Calnex all in the hall of shame.
No wrongdoing I’m sure but it just shows you !
A 27% sales increase for Gear4music (HOLDINGS) (LON:G4M) is huge and so I thought I would use AI to drill down into the demise of their competitors. If anyone knows this market well could they comment on the competative landsacpe "AI intrepretation" below?
If correct, its very encouraging for Gear4music (HOLDINGS) (LON:G4M) and is likely to lead to further broker upgrades.
Perplexity... Gear4Music PLC reported that their sales have increased due to the exit of key low-cost competitors in the UK and European musical instrument retail market, specifically PMT (Play Music Today) and GAK (Guitar, Amp & Keyboard Centre).
Principal Low-Cost Competitors
PMT (Play Music Today): Once the UK’s fourth largest musical instrument retailer, with 11 stores and a significant online presence, PMT entered administration in June 2025 after struggling with shrinking margins and rising costs.
GAK (Guitar, Amp & Keyboard Centre): Based in Brighton, GAK was one of the UK’s biggest retailers of musical instruments; it entered insolvency earlier in 2025, resulting in store and online business closure.
BAX Music (Netherlands): A pan-European online price discounter, BAX Music also went insolvent in April 2025, reducing competitive pressure for Gear4Music in continental Europe.
Market Impact
Gear4Music directly purchased selected assets (stock, websites, trademarks) from the administrators of PMT and GAK following their exits, further strengthening its market position and enabling it to benefit from market consolidation. The departure of these retailers has led to a more favourable competitive landscape for Gear4Music, supporting its increased sales momentum in 2025.
That AI summary regarding competitors of Gear4music (HOLDINGS) (LON:G4M) is accurate. However, Bax music have started up again. They didn't have a great reputation before, not sure how much competition they'll be going forward - I would suspect not a lot.
I'd be surprised if the demise of PMT & GAK account for all the sales rise, as they are more local type shops ( of which there aren't many left now) rather than big mail order outfits.
The main competition for them now will be Juno Music, Andertons & the big European outfit Thomann. In my experience, there's not much customer loyalty in this market- most buyers are looking for the cheapest price, hence the slim margins.
I am a suffering shareholder at Ashmore (LON:ASHM) .....
The sentiment around Emerging Markets assets have already started gathering momentum since Liberation Day in April. Plenty of data points on EM ETFs growing, money flows into EM Debt and Equity....
And ofc, Ashmore is mainly dealing with institutional clients, who are "slower" to move money around in allocation. So fair enough, expected May, June (last two months of HY) to not see any benefit.
What was disappointing with today's HY results is the lacklustre Outlook statement. No mention of "inflows" in July and Aug. Silence speaks volumes.
Not long to go, however, till they do their Q1 update (Jul-Sep) at the start of October... maybe they are seeing inflows and waiting till then to announce...
Any thoughts on why £SPSY has fallen so far other than the 'devaluation' of the $US vs the £?
Any thoughts why ME International (LON:MEGP) has fallen so far since putting itself on the market, as it were?
I've been adding to my ME International (LON:MEGP) during the takeover process based on its pretty good financial metrics.
It's never looked especially likely that any takeover will proceed and presumably 36.5% holder Serge Crasnianski won't want to sell up on the cheap. Maybe the somewhat declining share price reflects that fact and that at some point the takeover clock will run out of time. Not sure when this deadline actually is?
ME International (LON:MEGP) down to 190p on no news as far as I am aware. Good solid business looks like a good entry point
You know was waiting for 190ish to add . Great business. Just markets have bounced and has remained static
A read across for Focusrite (LON:TUNE) today from the Gear4music (HOLDINGS) (LON:G4M) update.
I bought back in recently after seeing that their new products seem to be selling well (going by stock levels at some of the big retailers, including Gear4music (HOLDINGS) (LON:G4M) ) and the share price more or less stabilising. Hopefully they are doing well from the increased activity at Gear4music (HOLDINGS) (LON:G4M) .
No recent commentary on Empire Metals (LON:EEE, why? I hold.
Any investors out there who've done a deep dive on Tufton Assets (LON:SHIP)? The valuation seems crazily low but the stock price goes nowhere. I get that it's not a growth stock, but even as in income stock it seems lowly priced.
Sorry to hijack this thread again, but following on from my comment on Wednesday’s DSMR, there is now a growing shareholder group forming re Zytronic (LON:ZYT^E25) to answer any questions re voting or other matters. Any holders wishing to be involved please DM me on X (same username).
What is going on there? Read in the paper that Henry Spain is wanting to use it as a roll-up
That is correct. But people who can’t vote or aren’t aware they need to vote run the risk of getting trapped and not seeing their capital again. Lots over on “the other place”.
Berkeley group (LON:BKG) - Not so smart shareholder return as stated in the update today - shares have declined whilst they have been buying in. Next seems to be on of the few major players where they are renowned for timing it right.
Sadly share buybacks are a default response for a lot of listed companies. Where actually they are a bad use of capital and they often buy at the wrong price like before a profit warning(s)!!! Also the £££££ amounts are so small to make any material difference. Financial engineering rubbish!
Big sale by the chair at Science (LON:SAG)
Thoughts anyone?
Sold to satisfy institutional demand apparently.
That's what they all say.
Science (LON:SAG) Not a surprise if instis want to buy. The result ofScience (LON:SAG) successful share purchases of Ricardo (LON:RCDO) is that Science group now has a lot of cash, so options for growth. The chairman added to his personal holding while being an activist in Ricardo (LON:RCDO). He has seen the value of his holding increase plus there have been share buybacks, which would increase the percentage of his holding, so he is cashing in at the margins on Science (LON:SAG) successful M & A moves.