Daily Stock Market Report (Fri 7th August 2026) - DGE, WYN, SDG, GDWN

EasyJet: the takeover by Apollo has been given the green light by Sir Stelios Haji-Ioannou and his family, saying “I am pleased with Apollo's strategic intentions for the easyJet business, which aim to create more growth”. The rival bidder Castlelake has dropped out. To comply with EU airline ownership rules, the Haji-Ioannou family and other European-based investors will need to stay invested in the business - the procedures needed to satisfy regulators are only just beginning.
Iran: oil has been ticking higher again, with various negative developments around the Strait of Hormuz. The latest one is that Iran now wishes to ban US and Israeli ships from the strait, and that “hostile countries” would have to pay compensation to gain access to it. This comes after Iran and Oman jointly agreed on how those two countries wish to jointly manage shipping routes in the area.
President Trump said yesterday that negotiations with Iran are “moving along good”, but the US blockade of Iranian ports continues and Iran’s financial demands appear to be increasing, and so it’s difficult to see a full reopening of the Strait in the short-term.
AI smart speakers: Bloomberg reports that OpenAI is planning to launch a smart speaker in 2027. It will be shaped like a doughnut, easy to carry around the house, and function as “an AI-first computer that can help users get things done”.
Overnight market movements:
The FTSE is down 0.1% at 10,860
S&P 500 is flat at 7,709
Brent crude (November) is up 1.3% $81.50/bbl
Gold is up 0.8% at $4,275/oz
Bitcoin is down 0.3% at $64,250
Calling it there - thanks everyone! Have a great weekend. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Renewables Infrastructure (LON:TRIG) (£1.75bn | SR85) | Announcement of Interim Results for the six months to 30 June 2026 | NAV as at 30 June 2026 was 101.1p per share (Dec 2025: 104.0p), “principally as a result of reductions in revenue forecasts adversely impacting the portfolio valuation.” Agreement signed in July 2026 to divest of stake in the Beatrice offshore wind farm for c. £155m. Further divestment processes underway. | |
Goodwin (LON:GDWN) (£1.41bn | SR32) | Confirms that it has commenced a strategic review to consider a range of potential options. These options include the potential sale of a substantial part of the Mechanical Engineering division, which includes GSC, GI, Noreva, Easat and Pumps. | AMBER ↑ (Graham) | |
Oxford BioMedica (LON:OXB) (£715m | SR16) | H1 revenues +c. 9% to £80m. Guidance: FY 2026 revenues now expected to be £180-200m (expectations: £228m) as a result of changes in client ordering behaviour and later-than-expected operational readiness of OXB's Durham, NC site. Lower EBITDA margin guidance as a result of lower revenues. Unchanged medium and long-term ambitions. | BLACK | |
Franchise Brands (LON:FRAN) (£280m | SR73) | Celebrated its 10-year anniversary of trading on AIM this week. Compound annual total return to shareholders of just over 17% over the decade. | This is a Reach announcement - non regulatory press release (Graham). | |
Stelrad (LON:SRAD) (£195m | SR93) | H1 revenue down 9.1%, adjusted operating profit up 4.9% (£16.7m). Statutory operating profit £15.7m. “Trading in the second half to date has been in line with our expectations and the outlook for the full year remains unchanged.” | ||
Genel Energy (LON:GENL) (£140m | SR26) | DNO offered 69p per share (current share price: 49.95p). 38% premium. The Genel Board rejected it; DNO remains willing to engage. | TAKEOVER | |
Pharos Energy (LON:PHAR) (£131m | SR83) | Increased recommended all-cash offer from Ratio Petroleum: c. 28.8p in cash plus 4p special dividend. 29.2% premium to the PHAR share price in June and 0.5% premium to the Serica offer. “Ratio believes that the Increased Ratio Offer provides Pharos Shareholders with greater certainty and deliverability than will be achieved under the Serica Offer.” Irrevocable undertakings to support this offer in respect of 41.76% of existing Pharos shares. | TAKEOVER | |
Wynnstay (LON:WYN) (£86m | SR93) | Significant expansion of its Glasson Fertilisers blending operations. The total project investment is expected to generate a return on net assets in line with the group's stated target of not less than 10%. | AMBER/GREEN = (Graham) | |
Arrow Exploration (LON:AXL) (£79m | SR76) | Including production from the IC-3, IC-HZ4 and IC-HZ5 wells, total gross corporate production is over 5,000 boe/d. As of 1 August, the company's estimated cash balance was US$27.5 million. The company continues to have no debt. | ||
Rentguarantor Holdings (LON:RGG) (£76m | SR35) | Has received notice for the exercise of warrants in respect of 9,733,334 new ordinary shares of 10p each at an exercise price of 17.5p per share. This will raise gross proceeds of £1,703,333.45 for the company. | ||
Sanderson Design (LON:SDG) (£56m | SR98) | Group revenue increased 6% to £51.4m. Third Party Manufacturing revenue up 19%. Direct-to-consumer revenue up 137%. Balance sheet remains strong with net cash of £10.2m. Expects full-year trading to be in line with market expectations. | AMBER/GREEN = (Ed S) | |
Potentially AI (LON:AGI) (£25m | SR15) | Registrations for early access to its consumer app have reached 25,000. Will begin onboarding in the coming weeks. |
Graham's Section
Wynnstay (LON:WYN)
Up 1% at 377.4p (£88m) - Investment in Scottish Fertiliser Capacity Growth - Graham - AMBER/GREEN =
Roland was moderately positive on this in June.
This agricultural supplier has a below-average track record when it comes to economic returns (ROE/ROCE); the current CEO is working on a five-year plan to improve this.
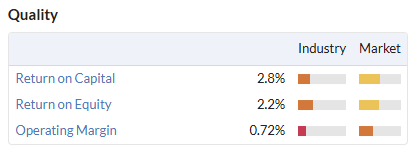
Today’s announcement concerns a new investment designed to improve operational efficiency, but it doesn’t give me too many numbers to work with:
Wynnstay Group plc (AIM: WYN), a leading integrated partner to UK agriculture, is pleased to announce a significant expansion of its Glasson Fertilisers blending operations at Montrose, Scotland. This latest investment will significantly increase the Group's fertiliser blending capacity, improve operational efficiency and create one of the largest fertiliser blending plants in Europe on completion.
Highlights:
Long-term lease for a "substantially larger production facility at Barrack Road, Montrose” that will double the company’s blending capacity in Montrose. It’s expected to be at full production during H1 of FY October 2027.
Disposal of the existing Cobden Street site to partially fund the new site.
The total investment, including working capital, is expected to generate a return on net assets in line with the target of not less than 10%.
CEO comment:
"This investment is another important milestone in the delivery of Strategy Genesis and demonstrates our continued confidence in the long-term growth opportunities for Glasson Fertilisers…
"Following the successful expansion of our Avonmouth fertiliser operation, this investment further strengthens our manufacturing network and reflects our disciplined approach to investing capital in projects that generate attractive long-term returns…
Graham’s view
A return on assets of greater than 10% is acceptable in my book. Combine that with some leverage (which doesn’t have to be from a bank, it could also be from customers or suppliers) and pretty soon the return on equity can get to 15%+, which I would start to view as attractive.
However, at the moment, these higher returns are just hopes and promises. They might pan out, they might not.
And I’m no agricultural expert, but I would assume that many types of agricultural supplies - feeds and fertilisers in particular - are subject to a high degree of commoditisation. Wynnstay’s gross profit margin has been running at around 14% (see the H1 results), which I would say is consistent with that statement.
So I would say there are natural limits on the returns that Wynnstay might achieve, even in a best-case scenario.
The valuation does reflect this:
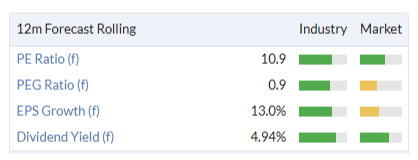
I’m therefore happy leaving our moderately positive stance unchanged. If Strategy Genesis works out, this will become a higher-quality business that is worthy of a re-rating higher. If it doesn’t work out, then there’s a reasonable chance that investors haven’t overpaid for it anyway.
Goodwin (LON:GDWN)
Up 10% at £207 (£1.55bn) - Recent press speculation - Graham - AMBER ↑
A brief but very important update from Goodwin:
The Board of Goodwin notes recent press speculation regarding the potential sale of parts of the Mechanical Engineering division.
The Board of Goodwin confirms that it has commenced a strategic review to consider a range of potential options to maximise value for shareholders whilst ensuring continuity for all stakeholders, including customers, and the long-term prosperity of its businesses. These options include the potential sale of a substantial part of the Mechanical Engineering division, which includes GSC, GI, Noreva, Easat and Pumps.
The Financial Times had the scoop overnight, saying “Several buyout firms that have records in defence have submitted expressions of interest to the London-listed engineer in recent weeks”.
Goodwin’s portfolio of companies is diverse; the companies mentioned above carry out the following activities:
GSC (Goodwin Steel Castings): the manufacture of high integrity, technically advanced castings. Includes nuclear, defence and shipbuilding capabilities.
GI (Goodwin International): heavy project engineering. Used in nuclear, petrochemical and power generation.
Noreva: a manufacturer and supplier of non-slam check valves.
Easat Radar Systems: design, build and install high performance antenna systems for defence contractors, civil aviation and border security agencies. Used in both civilian and military markets.
Pumps: submersible pumps manufactured in India.
Based on the above, it sounds like the Goodwin Board are interested in potentially selling more than just their defence-focused businesses. But the FT might also be 100% correct that there are bids coming in for the defence companies.
Graham’s view
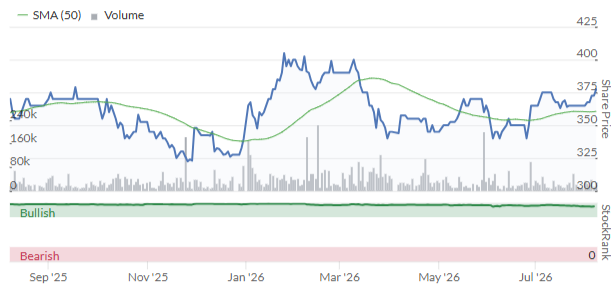
Goodwin has treated investors to quite a ride over the past year: soaring from less than £100 per share to about £280 per share at the peak, before collapsing on a very gloomy trading update and now rising again.
Despite having a market cap well in excess of £1 billion and being in the FTSE-250, it doesn’t provide useful forward guidance, leaving it up to investors and analysts to do their own work when it comes to figuring out what the company might achieve.
This isn’t trivial even for simple businesses, but when dealing with a conglomerate that works on large government contracts, it’s far from straightforward.
I’m not going to pretend that I know what Goodwin might be able to sell these business units for. I will go out on a limb and say that I think now is a good time to sell defence sector assets: valuations are strong as geopolitical tensions have simmered and as defence spending has risen. The likes of BAE Systems (LON:BA.). is trading at 24x forward earnings, and Rolls-Royce Holdings (LON:RR.). is at 34x (I concede that’s more than just a defence stock).
It’s also true US stock valuations are extremely hot - making it a good time to sell to US-based investors. Given the sensitive nature of Goodwin’s work, I expect US (most likely) or UK buyers.
Goodwin did tell us previously that it expected PBT of at least £71m in FY April 2026. Those results have not been released yet. The current market cap leads me to believe that the business is trading at around 29x trailing earnings, depending on tax rates. We’ll get those full year results in a few weeks. That earnings multiple makes me nervous, but there’s no denying that the company’s growth in recent years has been spectacular. If they keep growing like they have before, that multiple will soon prove to be irrelevant.
For now, I’m inclined to put us on a neutral stance on Goodwin. This is a case of the stock being in my “too difficult” tray, at least for now. If they do sell off a few businesses and achieve a simpler structure, they may end up being easier for simple-minded investors like myself to analyse - and might therefore get out of that tray.
Ed Sheldon's Section
Diageo (LON:DGE)
Up 6% yesterday and up 1% today at 1,753p (£38.6bn) - Preliminary Results 2026 - Ed S - AMBER =
(At the time of writing, Ed S had a long position in DGE.)
FTSE 100 dog Diageo – which I hold sadly – posted its Preliminary Results for the financial year ended 30 June 2026 yesterday. The market clearly liked something in the report as the stock jumped 5.6% yesterday and it’s up another 1% today. So, let’s take a look at what’s going on here. Is new CEO Dave Lewis turning things around?
Headline numbers:
Net sales down 3.0% to $19,643m
Organic net sales down 2.0%
Operating profit down 27.2% to $3,156m
Operating profit before exceptional items down 2% to $5,683m
Basic EPS down 26.3% to 78.1 cents
Basic EPS before exceptional items up 0.7% to 165.3 cents
Adjusted free cash flow of $3,211m was $463m higher than a year earlier
Net debt as at 30 June 2026 was $20.5bn – representing a net-debt-to-adjusted EBITDA ratio of 3.1x.
Final dividend reduced to 30 cents from 62.98 cents taking the total full-year dividend to 50 cents per share versus 103.48 cents per share the year before.
In terms of estimates, analysts were looking for:
Sales of $20.27bn (miss)
Adjusted operating profit of $5.89bn (miss)
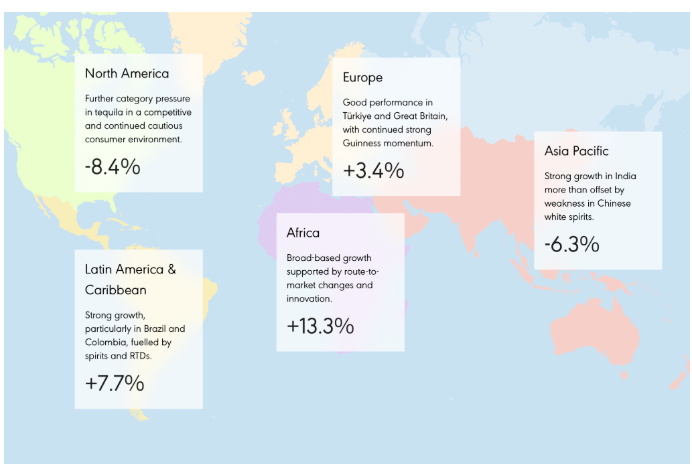
So overall, a pretty poor performance for the year. The company noted that growth in Europe, LAC and Africa was offset by weakness in North America (-8.4%) and Asia Pacific.
It’s worth pointing out here that Diageo is experiencing challenges in China due to the government's crackdown on Chinese white spirits (CWS). It notes that excluding CWS, organic net sales for the group would have been c.1.5% higher.
In terms of restructuring (it’s engaged in a 2-year restructuring programme), restructuring charges were $0.9bn. This included c.$752m costs for the implementation of its new operating framework.
This new operating framework is expected to deliver c.$850m savings over two years, starting this financial year. These savings will allow the company to invest in its turnaround without needing to reduce operating profit (it stressed this multiple times).
Impairment charges were $1.5bn. This related largely to Turkey (due to the impact of hyperinflationary accounting and change in pricing in market), as well as the write down of the Don Papa brand and certain other smaller brands.
(As a fan of rum, I always knew that Don Papa was a terrible acquisition. It’s absolutely awful in my view!).
Capital Markets Day presentation
In the company’s Capital Markets Day presentation, Lewis said that his plan is to:
Focus on spirits including ready-to-drink (RTD) cocktails (Smirnoff RTD is a standout)
Continue the double-digit growth of Guinness and gain share
Retain premiumisation as a key value creator but activate the wider portfolio to serve more customers across more occasions
Turnaround North America whilst growth continues in the rest of the world
He notes that the company does need to rebase profit to support this plan.
Lewis is targeting leverage of 2.75x this year and 2.0x by 2029. As leverage comes down, the Board will explore dividend increases and/or share buybacks.
“It will not be easy, but we are confident that over the next 3 years we can recover the Diageo business to strong profitable growth creating value for shareholders.”
As for growth forecasts, the company expects sales growth to be flat this year. It is then targeting 1.5% growth in FY2028 and 2.5% in FY2029.
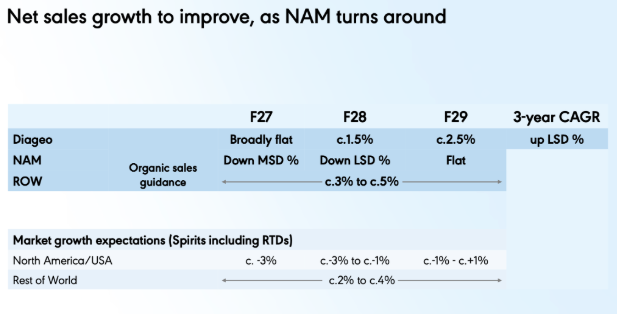
For organic operating profit, it is targeting mid-single-digit growth between FY2027 and FY2029. For free cash flow, it is targeting $8bn in cumulative FCF over the next three years.
Ed S’s view:
On balance, I see reasons to be optimistic here. While performance last financial year was no doubt poor, CEO Dave Lewis is clearly working hard to turn things around.
Already, he has:
Lined up a substantial amount of job cuts. Here, he is focused on global, back-office functions and in areas where there is "massive duplication."
Cut the dividend materially.
Announced plans to nearly double the capacity of Guinness (production capacity is slated to increase from 8.2m hectolitres (mHL) today to 15.7m by 2031, an increase equivalent to 300 Olympic-sized swimming pools).
Developed strategies to appeal to more consumers, e.g. more focus on RTDs.
“This new strategy, executing with a new, more agile, competitive and cost-effective operating model, gives us confidence that we can return Diageo to a business consistently creating value for shareholders. We remain a business with a very strong premiumisation agenda, but by activating our wider portfolio, we will be able to serve more consumers, across a variety of occasions. There is hard work ahead, particularly in North America, where improving performance is a clear priority, but we are confident we can deliver without taking a step back in operating profit.”
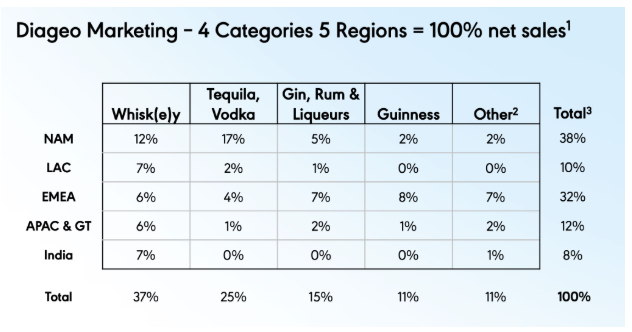
Of course, he is still facing major challenges. One is that attitudes to alcohol are changing, with younger consumers drinking less (due to affordability, a growing focus on exercise and wellness, and the fact that they want to look good on social media).
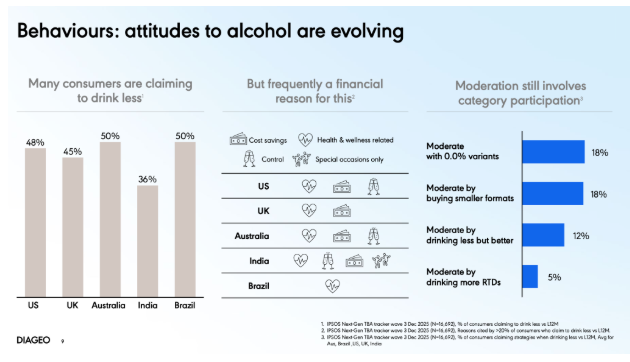
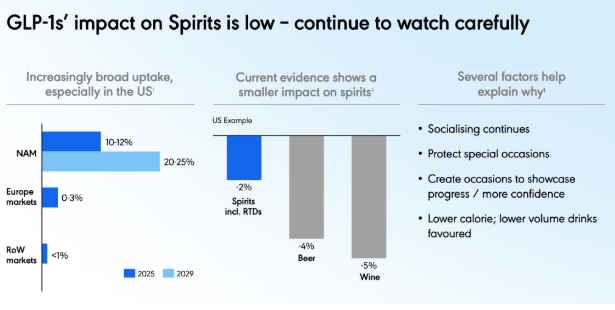
GLP-1 weight-loss drugs are another potential headwind. The company says that their impact on spirits is low, however, I still see this as a key risk, especially in North America where adoption is high.
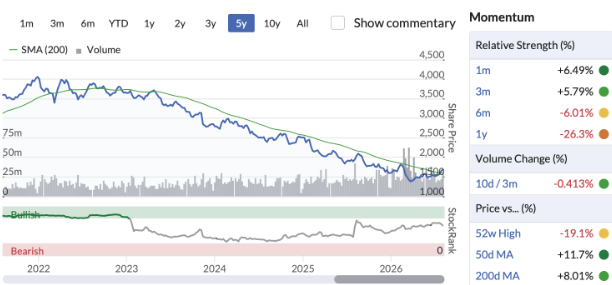
In terms of the valuation, taking the adjusted EPS figure for FY2026, we get a trailing P/E ratio of 14.2x at today’s share price. That doesn’t scream ‘bargain’ given the company's challenges and its substantial debt pile, but it’s also not particularly high for a global consumer goods company with a solid portfolio of brands.
The trailing dividend yield is around 2.1%. So, there is not a lot of income on offer but 2.1% is better than nothing.
Putting this all together, I’m going to leave the stock on AMBER. I do think the company is heading in the right direction (and that the bottom is probably in for the stock), however, whether it can beat the market in the medium to long term is still uncertain.
Sanderson Design (LON:SDG)
Up 2% at 79p (£56m) - Half Year Trading Update - Ed S - AMBER/GREEN =
Luxury interior furnishings company Sanderson Design Group has today posted a half-year trading update for the six-month period ended 31 July 2026. This stock has a StockRank of 98 and a ‘Super Stock’ rating so let’s take a closer look.
H1 FY27 highlights:
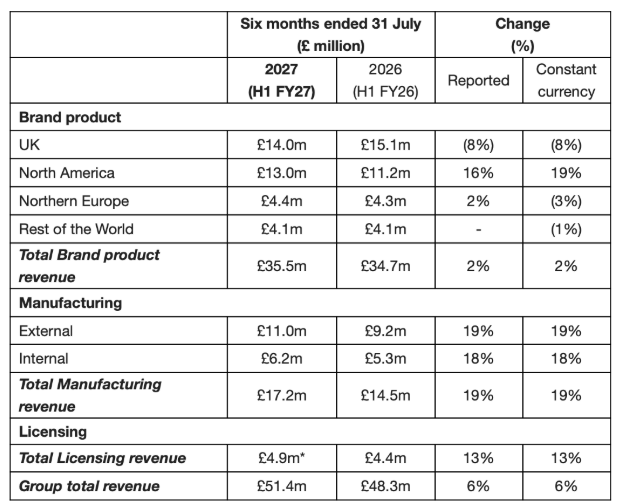
Group revenue increased 6% to £51.4 million.
Total brand product revenue up 2% to £35.5 million, with significant growth in North America (+19%) more than offsetting anticipated UK softness (-8%).
Third Party Manufacturing revenue increased 19% to £11.0 million, with excellent demand from US brands and buyers.
Total Licensing revenue up 13% to £4.9 million, driven by the renewal of the global Blinds2Go agreement (£1.4 million of accelerated income).
Direct-to-consumer revenue in H1 2027 significantly exceeded that achieved in H1 FY26, rising 137% to £1.6m.
Balance sheet:
Net cash position at period-end of £10.2 million (31 January 2026: £9.8m), having purchased £1.4m of shares into the EBT in H1 FY27 as previously announced.
Guidance:
The Board expects full-year trading to be in line with market expectations.
It says that FY27 market expectations for adjusted underlying PBT are £6.5m.
In the update, the company points to strong progress against core strategic priorities:
North America – Its focus on North America is paying off, with 19% revenue growth during the period. North America continues to be the Group's highest margin and most profitable region as well as the fastest growing.
Brands – Launched in May 2025, the Highgrove Collection by Sanderson is creating a 'halo effect' on the Sanderson brand, with very strong sales growth in every region and ahead of Management's expectations. Highgrove has been particularly well received in the US, where Sanderson brand sales are up significantly (+45%).
Manufacturing – The proactive restructuring of operations together with the "Future Factory" initiative has led to a strong recovery in this segment's performance, up 19% on prior year.
Digitalisation – Performance of the direct-to-consumer (DTC) sales channel, via brand websites, has been particularly strong, with revenue in H1 FY27 more than doubling compared to the prior period.
“As we look ahead, we remain focused on delivering our strategic priorities and are confident in the Group's ongoing ability to generate profitable growth.
Ed S’s view:
The Super Stock rating and the 98 StockRank piqued my interest here and taking a closer look, there's quite a bit to like about this small-cap AIM stock.
For a start, the company appears to have multiple sources of growth. Not only is it seeing strong growth in the US right now (which is offsetting weakness in the UK) but it’s also doing well on the manufacturing side and the DTC side.
Note that the US is the group's highest margin and most profitable region. So, if it continues to see strong growth here, there could be scope for an earnings beat in FY2027 (the consensus forecast at present is 6.38p per share).
"We are particularly excited about our prospects in the US, where trading has been excellent with a clear upward trend. The US represents a major growth opportunity where our strategy to develop relationships with and collaborate with industry experts and celebrated designers has proven key to stimulating demand.”
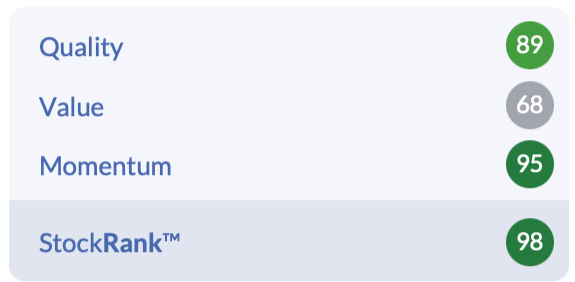
Next, the balance sheet looks solid – net cash at period-end was £10.2 million (market cap is only £56m). Note that Stockopedia gives it a score of 89 for quality.
Turning to the valuation, it seems quite reasonable (although Stockopedia only gives it a score of 68 for value). Taking the earnings forecast for this year, we get a P/E ratio of around 12.4, so there’s potentially scope for a re-rating here.
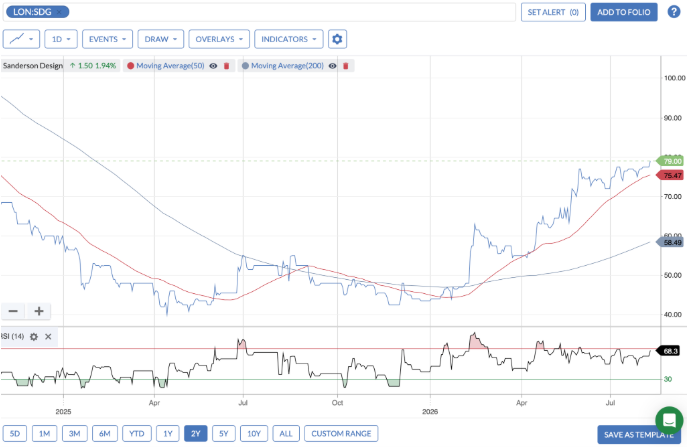
Finally, from a momentum perspective, the set-up looks relatively attractive (Stockopedia score of 95). At present, the stock is above both its 50-day moving average and its 200-day moving average while the RSI is 68 (not overbought yet but getting close).
On the downside, analysts only expect top-line growth of 4.5% this financial year. So, it’s not exactly a growth stock.
Meanwhile, the performance in the UK is a concern. This is a major drag on overall performance.
There are also plenty of risks that could derail the bull thesis – a slowdown in consumer spending, new tariffs, etc.
Overall though, I think this stock looks interesting from a value perspective. I’m going to keep it at AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

64 comments
China has been buying huge amounts of Gold in the last few months, in July they bought the highest amount since Jan 22. Whether they're just taking advantage of the drop in the price of Gold or can foresee some event(s) that would require them to massively increase their Gold holdings, who knows, but when there is a buyer in the market buying the volume they are, the price is sure to react - Gold has increased by about 10% from its recent bottom.
Are we really going to sell valuable defence assets to the US??? Have we gone mad?
I used to trade a lot of UK small caps but over the past year this has reduced as a consequence of the ridiculous spreads on both platforms. Now unless I am totally convinced that the stock is good I'll suck up the costs involved however I'm more inclined to walk away from the trade.
I'd say the spreads appear similar on HL & AJB the latter not very good in regard to quotes for mid cap European and US stocks and I believe HL is less user friendly than a year ago.
What platforms do you use?
IBKR convert the stash to dollar and then away you go - liquidity no problem, well for my small trades. Has a British ISA (lol) but no problems to date.
IG seems to be having issues. No finger on it yet but losing confidence. Apple App is rotten anyways which does not help me as an ideologue.
I have been trying to buy Butler National (PNK:BUKS) but neither AJBell (my SIPP) or II ( my ISA) want to get this for me. Can anyone confirm whether a US “pink sheet” stock is permitted within SIPPs and ISAs?
Butler National (PNK:BUKS)
Into aerospace and defence. A momentum sector.
Has a moat called a STC - supplemental type certiciate for modifications to aircraft kit.
Also into Casinos (gambling) which seems a company diversifying its knitting. Nothing wrong but how will an investor pick the winner.
Still no clue what it does well or its moat so as the dragons would say - I'm out.
I've been trying to buy them too. Would love to know how. AJBell not supporting this
Have you tried IG, unsurprised given my past experience with trying to invest via AJ Bell in smaller US lines that thet demur
No, I haven't. I'll give it a try
I don't think IG deal in those sort of stocks.
IBKR are probably the best bet.
Hi Pink Sheet stocks are not an eligible investment for an ISA and unlikely in a SIPP given this is not an eligibile market under HMRC guidance
So Warsh didn't hike, as the market wanted and 30 year bonds sold off. Today the non farms play ball with Warsh and miss, disappointing with a small fall of 23,000 not a rise as expected (40 to 80k). Bonds rally and yields fall which I think is good news....and equities therefore trade up. This tells us the rather obvious that rates are more important than growth at the moment. This data will increase confidence that the CPI data might continue to play ball next week which would be another piece in the jigsaw. A high number won't go down well and reverse today's positive mood.....but maybe Warsh knew all this was coming when he didn't raise ... it would help his credibility if CPI plays ball next week. Obviously the US government doesn't really want higher rates given borrowing and spending levels.... the dollar is off which could well gain more air time if the weakness continues.
Seem to be in consolidation - lets settle it down.
But why are precious metals getting a boost. I have many miners and ETF's and all moving up. This cannot be ignored and at the same time not understood by most of the talking heads.
To me I think this signals something bad is coming. A Black Swan. Don't know who what why - that's the definition - unpredictable however clever you are. China/Taiwan we know about so a 'grey' swan.
Our investments in good stuff doing good stuff and likely to do good stuff in the future then a moat that can hide behind with the fire breathing dragon swan appears.
PS. I am very positive on the US market for as long as Trump is in Town. That maybe the 'Black Swan' when he leaves Dodge. God help us all.
It may but precious metals running to the tune of the Dollar - which may be weakening. By definition there are always potential black swans out there but I would be careful using gold and metals as the tell all indicator. Long bonds and currency also playing a part.
Anyone else having problems with HL login? Yesterday couldn't login, appeared my mobile no had vanished off the account so tfa wouldn't allow it to proceed. Supposed to have it added by them yesterday. Tried today, still problems, another phonecall, supposed to have been added again. Tried again still not working, waiting on callback for 3rd support callback.
Sorted on 3rd support call. Finally.
Thank you for the coverage of Wynnstay Graham, we've stuck with it through it's problems as it's maintained dividend payouts and for it's discount to net asset value. I agree it's never going to shoot the lights out but I like the fact it's growing again.
You're most welcome, JASVFS! thanks for the suggestion earlier. Have a good one.
I have been a long term holder of this one - it’s been ok with the regular dividends. However I suspect the multiple heatwaves we have had this year may negatively affect this business in the short / medium term so am considering selling out to see what happens.
I would have thought if Goodwin (LON:GDWN) sell the mechanical engineering division it would hollow out the company quite substantially, it's quite a sizable chunk of the business, is it not?
Wow M Winkworth (LON:WINK) announce they have initiated legal proceedings against their own chairman. As a reminder he owns 41.25% of the company according to Stockopedia data! I wonder what's going on. Looks very messy!
And as I've been reminded - the CEO is his son!
Hargreaves Services (LON:HSP) stockrank has jumped down by 11 in the past 30 days. Did Ed say anything about jumps down in the recent webinar?
I’m seeing the SR of Hargreaves Services (LON:HSP) as 91 today which is down around 7 points from its recent highs.
IIRC, Ed does advocate selling when the SR drops below 80 in order to recycle cash into stocks with more positive return drivers.
Where are you seeing such a big drop in the SR of Hargreaves Services (LON:HSP) ?
When I look now, the SR of Hargreaves Services (LON:HSP) is 88. Hovering over the 88 gives a popup that says -11 in the last 30 days.
That is strange - this is what I am seeing right now for Hargreaves Services (LON:HSP)
Re HSP
I am currently seeing a StockRank of 86 - down 11 over the last 30 days
Hargreaves Services (LON:HSP) this is what I get right now , and a -11 SR
I have the same as this. Very curious -especially for someone relying on the stockranks for portfolio management!
Just to be absolutely clear, I see 60,87,76,91 and -6 over last 30 days. as in JohnSmiths post.
I see the same as Helvellyn. Suggest you raise a query via the green button - I suspect you may be pointed at different sources.
There is a reason why two people may see different StockRanks for the same stock. It is due to differences in their site settings, which you can find here: https://www.stockopedia.com/a/settings
At the bottom you will find 'Ranking Universe':
If a person has changed this from the default of 'Local' then they will see different ranks, as they have a different ranking set.
I hope this clears things up.
When you click on the red downwards arrow next to the SR, it shows the drop.
It is only 86 today, mostly due to QR fall, from recent results update.
I assume that is because largely as earnings are expected to fall in the current year after exceptional gains on the monies Tungsten West paid (£7mn I believe) for the contract termination plus the two renewable land plot sales which added another £9mn. Hargreaves made a one-off partial buyback offer at a considerable premium to the (then) share price to reflect these exceptionals in the wallets of investors (if they so wished - I did). Profits last year were 'way' above 'normal' but still very real..
It would be strange if this expectation for lower profits this year weren't reflected to some extent in these attempts to summarise companies by formula.
I have kept the balance of my holding as I think there are quite strong possibilities of the company strategy - becoming asset light and developing the German business - being successful in time.
Re Sanderson Design (LON:SDG). Assuming North America sales ("highest margin, most profitable region") continue at current growth rates and that UK sales contraction is sustained I estimate a FY28E EPS of 8.0-8.5p — above Singer's base case of 7.2p, (which implies a more conservative deceleration in US momentum). Applying a 12-14x P/E, produces a fair value of 96-119p. So Sanderson Design (LON:SDG) is still reasonable value in my view.
I would agree-I hold. Would not be surprised if a US company bid for it given the increased exposure to the North America.
Sanderson Design (LON:SDG) Licensing seems to be falling off a cliff? Excluding the one-off, accelerated revenue from the renewal.
The story 1-2 years ago was "plenty of new licensing contracts signed, loads of steady licensing revenues to come, all of which are super high margin, and offsetting the weakness in the main business".
You'll also see that there was barely any commentary about licensing in this update. Not even when they ran through each "division". Also no commentary around profitability, profit margins, etc. Except to say in-line with expectations for the year.
One suspects that licensing is now declining. Despite management spending lots of time and effort on it, and trumpeting it, for years. Great USA sales are masking the UK problems, licensing problems. Its fine if the USA sales are now in growth, structurally.
Boon: A Singer note out on Friday addresses this directly. On an underlying (pre-IFRS 15) basis Singer says income rose c5% to over £4m. Not collapsing — modestly growing.
"Licensing income rose 13%, driven by £3.6m of accelerated income, including successfully renewing and extending the scope with Blinds2Go (£1.4m). As well as other renewals, the rest of the accelerated income was driven substantially by new agreements, which bodes well for future income growth. On an underlying (pre-IFRS15) basis, income increased by c5% to over £4m."
What’s clear is that Sandersons’ licensing-as-UK offsetting-engine narrative has quietly been replaced by US-as-growth-engine. The question is whether +16% US is durable. Singer think H2 will be the first period where US revenue exceeds UK — That's a genuine inflection if it lands.
That is much clearer from the broker, thanks!
The underlying rate is the key here, as the lumpy accelerated income makes YoY comparisons meaningless. I don't know why Sanderson doesn't provide underlying alongside the headline. (Well - I know why... because the headline growth rate looks better!)
As long as the US stock market keeps rising and those 401Ks of older generations keep increasing... will probably keep driving renovations, etc.
Renewables Infrastructure (LON:TRIG) Dividend cover 1.1 which is inline, current yield 10%- target dividend is 7.55p . NAV is 101p. They are going to continue with the share buyback programme which they claim is supported by the majority- well state the continuation vote was passed with a 99.3% majority. I would rather see an increased dividend. Saba have yet to target this trust trading at a substantial discount to NAV!
I’ve done some shopping here, thank you
Goodwin (LON:GDWN) released an RNS at 7.14am this morning re possible sale of part or parts of its business. Not showing on Stockopedia for some reason!
It's showing for me Goodwin (LON:GDWN)
Looks like a US defence customer, reliant on GDWN wants to buy the supplier before a competitor does.
https://archive.ph/EvcWJ
Where have you got this information please Sam ?
I know from RNS from sometime back that they supply a US defence customer, Northrup-Grumann from memory. Goodwin don't send out tons of RNS, it wont take you long to check. Did you read that FT article I posted?
Thanks Sam
That link doesn't seem to work??
It works for me and at least one other I know of, try cut and paste into your browser.
Still showing yesterday's share price. The shares are up nearly 10%.
Now up 14.6%.
Currently up 15.5%. You cannot rely on Stockopedia for up to date pricing, the prices are way behind, plus Goodwin took ages to uncross this morning.
Anyone else having with the IG platform today? Can't get it to work.
Working OK for me, via the app.
OK. I don't use the App, could never get on with it. It is working now but l had a devil to get in initially.
I use the IG App which I can log into as normal but it unusually isn't providing me with any quotes. Tested on a large cap too to check it's not just low liquidity in several small caps.
I've noticed this happen to me earlier this week (with a small cap).
There is a green/red status circle on one of the screens, next to the stock name. I've realised when it is red, no orders can be placed... but then it was only temporarily red, and goes green after a while. Had it happen to several shares in my portfolio.
I've already been thinking of moving away from IG, and this is another blow - not being able to get a quote, not being able to place an order during market hours... just too unreliable. Think I might just suck it up and move to HL. Have other investment accounts already in AJ Bell. Other platforms I considered were Interactive Investor (good if you want to consolidate multiple accounts, and also family member accounts in one place) and Barclays.
Anyone use / recommend Interactive Brokers? All looks good (platform, pricing, etc) but not convinced by their uk small cap execution/liquidity.
IG are now using IBKR in the back-end, and judging by the grumbles I have (and others above) looks like one to avoid for UK small caps....
IBKR do have a level 2 order book add-on, which seems fairly priced and will be useful to gauge what sort of limit orders can get filled quickly.
As Boon says, IBKR execution now provide the backend for IG JFYI. They have no access to the RSP system, so for smallcaps you're going to get worse execution by far with IBKR / IG.
I AJ Bell for our ISAs and Dealing a/cs and H L for our Sipps & DDs. HL is also used for our children's ISAs & SIPPs. both are good for family member a/cs accounts, HL is slightly more user friendly.
Do you buy/sell any UK small caps?
If so... how do you find HL compared to AJ Bell for trade execution quality? Getting quotes, how good are the prices that are provided, etc?
HL is good for all of those things, AJ Bell also good.
HL has rubbish fees for lots of things (but not all things), and frequent tech issues these days (in trying to modernise the platform, they seem to often break it)
I have instead just started moving every year to whichever platform puts on the best cashback offers before the start of the tax year provided they have otherwise good fee setup, seems to always be some companies doing 1% deals these days. Then just keep the investment strategy simple enough that you can do it from any platform: don't trade too frequently, don't get involved in illiquid micro cap nonsense, etc
Of course, if you have some kind of genuine edge dealing with illiquid microcaps, just get on the platform that helps you out there
Wynnstay doesn't do exciting but this morning's RNS comes close. As Ramsdens leaves AIM soon, Wynnstay becomes our largest holding. The share price has been forming an irregular Ed's bowl, I'm hoping today's latest Project Genesis move is received well. Fertilizer production is a very important subject with supplies still in jeopardy from the Middle East and I welcome the idea of running production in tandem until the first quarter of 2027 from the disposed old site, and the new expanded facility. I hope it makes today's Agenda, all comments appreciated, it hasn't been an easy investment.