Daily Stock Market Report (Fri 9th Oct 2026) - MCON, OMG, PTSB, TBTG

Good morning!
After all our chat yesterday about how to encourage IPOs, we do have an IPO to mention today: Airtel Mobile Commerce N.V. (AMC).
This is said to be the biggest London IPO in five years. AMC - known as “Airtel Money” - provides an electronic wallet to 50 million customers in 14 African countries.
I don’t see AMC on Stockopedia yet. According to an RNS it has published this morning, it does expect to start trading on the LSE’s Main Market today, at the open (edit: conditional dealings only - the full IPO is due on 14th October).
Highlights:
Market cap £5.3 billion, based on the offer price of £1.96 per share
270 million shares being sold by minority shareholders, with another 27 million shares “being made available”. Total offer size £582m or 11% of the company.
No new money being raised for the company.
Airtel Africa (LON:AAF) owns 77.85% of AMC and reiterated today that it “is not selling existing Airtel Money shares in the Offer and is expected to remain a long-term strategic shareholder”.
This might not be a company that we are too familiar with, but I for one will warmly welcome any IPO that happens in London these days.
Overnight market movements:
The FTSE is up 0.9% at 10,535
S&P 500 is up 0.3% at 7,790
Brent crude (December) is down 1.3% at $102.95/bbl
Gold is up 1.4% at $4,195/oz
Bitcoin is up 0.7% at $82,400
Leaving it there for today, have a great weekend.
Companies Reporting
Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Airtel Africa (LON:AAF) (£11.2bn | SR85) | Airtel Africa is not selling existing Airtel Money shares in the Offer and is expected to remain a long-term strategic shareholder and to support Airtel Money's next phase of development as an independently listed business. | ||
SSP (LON:SSPG) (£1.41bn | SR62) | Remains on track to deliver full-year earnings per share of c.14.0p, up c.18% year-on-year. Launches a new £50m buyback. | ||
Permanent TSB group (LON:PTSB) (£1.37bn | SR46) | SP +2% | TAKEOVER (Graham) [no section below] | |
Beauty Tech group (LON:TBTG) (£520m | SR81) | SP -4% | AMBER/GREEN = (Graham) [no section below] | |
Caledonia Mining (LON:CMCL) (£357m | SR66) | Gold produced in the Quarter: 17,030 ounces (Q3 2025: 19,106 ounces). Management reduces production guidance for Blanket for FY 2026 from a range of 72,000 to 76,500 ounces to a range of 69,000 to 72,500 ounces. | PROFIT WARNING (share price down 8%) | |
Hargreaves Services (LON:HSP) (£256m | SR94) | Selected by Sizewell C Limited for the design, procurement, manufacture, installation, testing and commissioning of three foul water treatment facilities required for the construction of the Sizewell C nuclear power project. "Will help underpin existing Group revenue and underlying profit before tax forecasts in the year ending 31 May 2027 and 31 May 2028." | ||
Mincon (LON:MCON) (£169m | SR86) | Revenue for the nine months to 30 September 2026 is 28% ahead of the same period in 2025. Full year 2026 revenue and EBITDA will be ahead of market expectations. | GREEN = (Graham) | |
Distribution Finance Capital Holdings (LON:DFCH) (£122m | SR68) | New loan origination reached £561m, up 22% year-on-year (Q3 2025: £460m). Remains on track to meet market expectations for the full year | ||
Motorpoint (LON:MOTR) (£117m | SR56) | Retail volume growth of 7.6% compared to H1 FY26. The Board remains confident in the outlook for FY27 and trading is in line with the recently upgraded market consensus | ||
Scancell Holdings (LON:SCLP) (£114m | SR8) | Operating loss £17m. Cash £5m vs. convertible loan note £17m. Going concern warning: "The Group's ability to continue as a going concern is dependent on securing additional funding, and completion of the Merger and PIPE Financing requires shareholder and regulatory approvals... These events are outside the Group's full control." PIPE financing, UK offerings and debt financing are expected to generate $95m. | ||
SIG (LON:SHI) (£103m | SR92) | Simon Kesterton, Chief Financial Officer, will be appointed Chief Executive Officer with effect from 1 May 2027. Current CEO to become non-Executive Chair. | ||
Oxford Metrics (LON:OMG) (£39m | SR52) | Trading Update and Strategic Update & Acquisition of Move AI assets | SP -10% | PROFIT WARNING (AMBER ↓) (Graham) |
Amigo Resources (LON:AMGO) (£37m | SR81) | "Mojimoto and Kabete advance seamlessly from pilot-scale production into integrated, commercial-scale processing hubs." | ||
Atome (LON:ATOM) (£19m | SR4) | ATOME notes "recent incorrect and/or misleading media statements and coverage in Paraguay regarding the Villeta Project ...media reports to the effect that there was no reason for ATOME to have expectations as to particular tariffs mischaracterise the basis of ATOME's legitimate expectations and its rights as a matter of international law. " | ||
Eco Buildings (LON:ECOB) (£15m | SR2) | New manufacturing line announced in June now in manufacture. AI-enabled automated line remains on schedule and within budget, with operational readiness targeted by the end of 2026. |
Graham's Section
Mincon (LON:MCON)
Up 12% at 88p (£205m) - Interim Trading Update -Graham - GREEN =
I turned fully GREEN on this in April with a market cap c. £130m. It has gone from strength to strength:
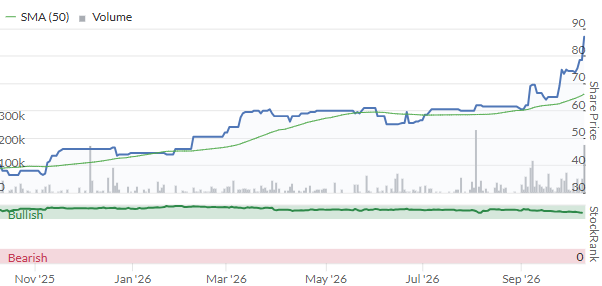
As a reminder, this is an Irish engineering company that makes drilling tools. I think of it as a sort of anti-Somero (Somero makes levelling tools, whereas Mincon makes tools for breaking through rock!).
I've been fascinated with Mincon for a while. Profits can be volatile but it pretty much always does make a profit, and it has great quality scores:
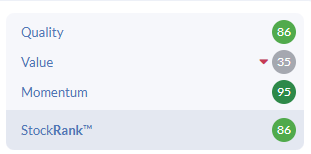
Like Somero, Mincon relies for a large part of its business on constrcution demand (50% of revenue), but mining (38%) is also a very important sector. Fortunately, both of these cyclical sectors are currently very busy.
Today's Q3 update:
The strong momentum reported in the Group's half-year results has continued through the third quarter, and revenue for the nine months to 30 September 2026 is 28% ahead of the same period in 2025, with most of this growth coming from the construction sector... This is particularly evident in North America, where work on existing major infrastructure projects will continue into 2027.
Although this is an Irish and UK-listed stock which does sell into Europe, its most important region right now is probably North America and especially the United States. The Americas contributed over two-fifths of its revenues last year, and it reported growth of 48% from the Americas in H1.
Let's keep reading:
Continuing the momentum from the first half of the year, our mining business has also grown across Africa, Australia and North America during the period. Higher raw material costs continued to put some pressure on margins during the past quarter, some of which we offset through modest price increases to customers. These cost pressures have since eased... the Board now expects that full year 2026 revenue and EBITDA will be ahead of market expectations.
Estimates: our thanks to ShoreCap for publishing on Mincon today.
They have raised revenue estimtes for the next three years (FY26 to FY28) by 13-15%.
The new EPS forecasts are as follows:
FY26: 5p (up 30% from 3.8p)
FY27: 5p (up 10% from 4.5p)
FY28: 5.6p (up 7% from 5.2p)
I think it's interesting that the broker has kept FY28 relatively stable - probably very wise not to get carried away by short-term success, given the unpredictable nature of construction/mining demand.
Graham's view
I was already GREEN on this, so clearly I'm not changing stance on it today.
I acknowledge that the current P/E at about 18x is a litte rich. Even on FY28 earnings, the multiple only falls to 16x.
So this is no bargain, especially for an engineering company. But I'm starting to suspect that Mincon may have some serious competitive advantages.
For example, it has something called a "Spiral Flush" system for low-impact foundation drilling which has been patented and is said to be highly innovative and effective in urban environments.
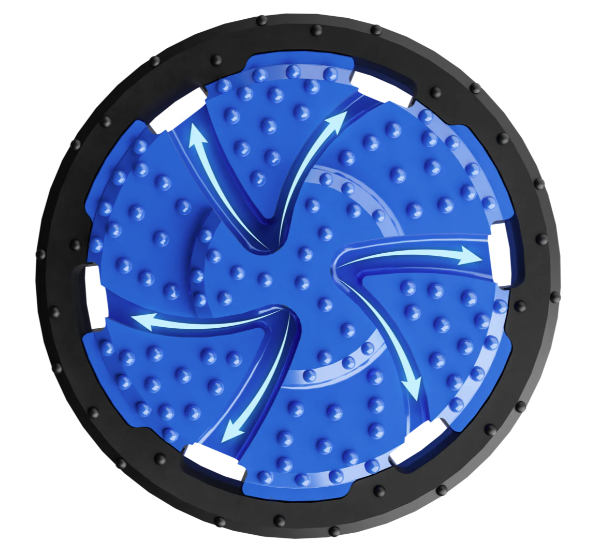
I'm no construction expert, but the results here are consistent with a company that's got something special.
Well done to Mincon - let's see if they can keep up this terrific momentum.
Oxford Metrics (LON:OMG)
Down 10% at 31.4p (£35m) - Trading Update and Strategic Update -Graham - AMBER ↓
Four RNS announcements from OMG today, including an acquisition, a share buyback and confirmation of a new CEO. The market doesn't seem too impressed.
Let's dive into the "Trading Update and Strategic Update":
Trading since the publication of the interim results (being the six months ended 31 March 2026) on 17 June has been below the Board’s expectations, reflecting changes in Vicon’s established end markets, pressure on research funding and delays to major projects in Industrial Vision and Metrology Systems
Vicon is OMG's motion capture system used in life sciences, engineering and entertainment.
New guidance
FY26 revenue of £47m to £51m (expectations: £56.2m)
Adjusted EBIT loss of -£0.5m to -£3.9m (expectations: profit of £3.0m).
Important to note that FY December 2026 is a 15-month period that began in October 2025. Changes to the accounting reference date, which cause these strange financial periods, are sadly often associated with mishaps and trouble.
The wide range in new FY26 guidance "reflects uncertainty over the timing and conversion of a few larger near-term customer opportunities".
FY27 guidance:
FY27 revenue to be below expectations (which are £52.5m)
Adjusted EBIT to be at or above current market expectations of £3.5m.
The company's response:
In the expectation of continued weakness in some of its core markets, cost savings and margin improvement actions are ahead of the implementation plan for 2027 and will be further extended. In addition to the recent acquisitions and product launches, incremental investment will be directed to Vicon’s significant opportunities in markerless and hybrid systems, robotics and accelerating the move to recurring software revenue
It all sounds a little incongruous: cutting costs while also investing more and making an acquisition?
The good news: cash as of September 2026 was £29.5m, covering most of the market cap. This remains from a £52m disposal made back in 2022.
Acquisition: they make a small AI-based acquisition ("Move AI Ltd"), which "is expected to be highly complementary to Vicon and enhances its existing capabilities". Judging by its website, I can see the similarities with Vicon. The price means that it's a modest bet: just £725k including immediate transaction expenses.
Share buyback: a new £3m buyback, which is reasonable considering the very large cash pile.
New CEO: an German executive has been hired as CEO, to begin subject to obtaining the right to work in the UK. He will begin on 1st December.
Graham's view
There's a lot to unpack here. Based purely on the performance of Vicon, I'd be RED. Mark (who held OMG shares at the time) looked at this stock in some detail last December - well worth a read.
The reason I can't be RED is the company's enormous cash balance. This cash balance has been declining - it was £37m at the last year-end, and will continue to fall as they make more acquisitions.
Like many companies, then, it becomes a question of management's capital allocation skills. In that regard, the new CEO is an unknown quantity to me, and the share price performance since the Yotta disposal is a damning verdict on the company as a whole:
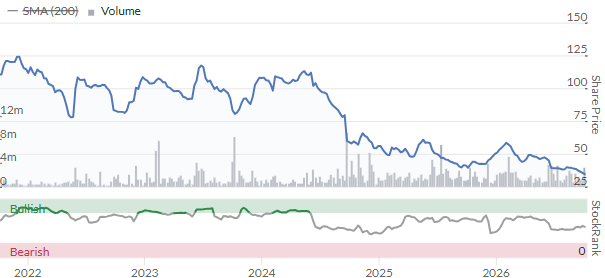
I only see modest annual dividends of about 3p to help account for this share price performance - the rest of the fall reflects the market's disappointment.
I'm going to put us neutral here today, down one notch from the last time we looked it. My gut tells me that AMBER/RED might be justified, but neutral is fair. Since it's already trading close to the company's cash balance, it's fair to say that investors already expect little from the company's operating businesses.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

30 comments
Aston Martin Lagonda Global Holdings (LON:AML) up 18% today...on no news? 8x normal volume
complete basket-case ofc, but curious, interesting...
Mincon (LON:MCON)
Thank you covering Graham. I first looked at Mincon (LON:MCON) when it was around 45p but faild to press the button. I eventually bought for my daughter's ISA at around 62p despite the fact that I thought it looked a little expensive.
Reasons:
Keller (LON:KLR) that is knocking the barn doors off in North America is significant customer.
The mining cycle continues in full swing.
The commercialisation of HITS (hybrid impact tecbnology) formerly known as Green Hammer and agreement with Epiroc its much larger American contemporary to use HITS . Link below for those interested.
Mincon advances Hybrid Impact Technology™ with Epiroc collaboration - International Mining
Have a great weekend
Thanks jonno. Much appreciated.
Hi
For those invested in Seraphim Space Investment Trust (LON:SSIT) or Space Exploration Technologies (NSQ:SPCX) . This RNS highlights Russia seems to be manoeuvring military satellites close to commercial satellites such as ICEYE (an Seraphim Space Investment Trust (LON:SSIT) investment). And possibly manoeuvring close to Starlink satellites.
Link to the posting here ... https://www.stockopedia.com/a/share-prices/space-exploration-technologies-NSQ:SPCX/news/01a120a5-5661-7417-a9a0-a1ef7fd06733
Regards
Howard
Back in the 1960s the US detonated a nuclear weapon in space (the test was known as Starfish Prime) and they have recently admitted to deploying a new weapon in space too.
This is one of the new domains of warfare.
I guess the broader point is that everything we build now has to be defended/protected... (and therefore, there is an investment opportunity too - sad, but true).
Airtel Mobile Commerce NV (LON:AMC)
Thanks for bringing this up Graham as I didn't realise it was listing today (edit: I've just seen your edit and can see that it is in fact listing next week.)
I actually read through the prospectus yesterday and there's no doubt that this is a fascinating company with a long runway for growth.
A few thoughts:
The company, however, stated that expectations this year were for mid-20% growth, which seems low.
Is the company being cautious or is it part of a plan to under-promise/over-deliver?
By my calculations - which I'm pretty sure are correct - this value has fallen from 0.91% in FY19 to 0.67% in Q1 FY27.
The Q1 FY27 (0.67%) value is also down 8% from the 0.72% recorded in Q1 FY26.
I was surprised by this given that the company said that it is moving into more value-generating products e.g. personal loans, which I thought would have higher take rates/commissions.
So is the decreasing take rate a sign of more competition? Will the decrease continue? And most importantly should we even care when both User Numbers and TPV (Total Processed Value) per Customer are rising so fast?
Or is there a chance of significant growth from non-Airtel customers as well?
I'd be interested to hear what other people think of the company.
Hi abtan
RE: Airtel Mobile Commerce NV (LON:AMC)
Or is there a chance of significant growth from non-Airtel customers as well?
No, but maybe ...
Technically Airtel Money is tied at the hip to Airtel Mobile - you need an Airtel SIM to be an Airtel customer. This is the same as the other major mobile money operators in Africa. So expansion of the consumer base of users relies on attracting the Airtel Mobile subscriber base to use the Airtel Money service.
However, most of these wallets are interoperable - so if I use a Mpesa wallet at an Airtel merchant it routes through the Airtel network, attracting interoperability fees and increasing the transaction volume through the network. Here Airtel operates a more like Visa or Mastercard, sitting in the middle and collecting fees on the tollroad.
In some countries I believe Airtel Money has to be an independent legal entity to perform this role and that's part of the reason for the spin-off. It's tied to financial services and payment regulations, but I can't say I've looked into it very closely.
Also Airtel have a big bulk payment business - bill payment, salaries, utilities, tax payments etc. Bulk payments aren't sexy but the value moved is enormous.
Overall, I think Airtel Money has a lot of room to grow and I don't think the IPO valuation was unreasonable, although it takes a lot on trust (although we could say the same about Airtel Africa (LON:AAF) and that's worked out OK). I picked up some stock in the IPO and may add if it settles lower next week.
timarr
Airtel Mobile Commerce NV (LON:AMC)
Thanks for the response Timarr
There do indeed seem to be a lot of opportunities for the company, with many metrics pointing in the right direction over the last 12-18 months.
I can't say I'm won over yet, but then I do miss a lot of excellent opportunities by overthinking these things.
I don't have any spare cash right now anyway, but the IPO document made for an interesting read. I'll be keeping my fingers and toes crossed that it works out well for you and other shareholders.
I'll share some numbers below in case anyone finds them useful/insightful. There are some calculations in there, but I believe everything ties in with figures from the Prospectus.
Thank you for your coverage of Mincon Graham, we've built a medium size holding since 2024 and I was pleased to see this morning's update. It's our second time riding the mining/ drilling cycle with this company. When China started restricting exports of rare earths it seemed sensible to check out Mincon and CAPD which we subsequently started to buy into. As another of my many investments mistakes is selling too soon, we have an almost nice to have dilemma with both, as you say it's no bargain for an engineering company, so when does a bottom fisher by nature sell and try another pond? I like the company too but it's now trading above net asset value so much food for thought.
Mincon (LON:MCON)
Hold it, but obviously DYOR.
Growth companies should not be valued by their PE…….
It’s an obvious multibagger.
All the best
Thanks yiannos1, we will. Eurocell and Steppe Cement similar graphs, if you have time to glance at them.
Steppe Cement (LON:STCM)
We have alerted our community on the 16th September, trading at 25p at the time, emphasising :“STCM.L (Steppe Cement)-This looks to be trading at a deep discount. For patient investors, this is significantly undervalued.”
I will have a proper look on Eurocell (LON:ECEL) over the weekend and try to report my findings.
All the best
You're very welcome! G
Interesting bid for First Tin. A bit low for my liking but Metal X do have the funds to develop them so let's wait and see.
I see Space Exploration Technologies (NSQ:SPCX) is entering the U.S. cellular market. Telecoms off this morning, I sold my NAPS Vodafone (LON:VOD) on the back of it, would have sold in December anyway.
If you are following a NAPS type strategy and have sold Vodafone (LON:VOD) what Telecomms sector stock do you intend to replace it with if any. I don't think there any that meet the NAPS selection criteria other than Gamma Communications (LON:GAMA) which is subject to a takeover and Airtel Africa (LON:AAF) which just misses out with a stock rank of 90 (though to be fair Vodafone (LON:VOD) stock rank has also slipped to 89)? Also given that Musk has a habit of promising the Earth (and Mars!) and his plans generally take a bit longer to deliver are the investment banks over reacting to the short to medium term competitive threat.
Hi ACounsell,
Under my NAPS critieria both Gamma Communications (LON:GAMA) and Airtel Africa (LON:AAF) would be included, I need STOCKRANK above 90.
Therefore come December when I start my 20 NAPS picks, there would be no TELECOMS selected, so I would pick two from other sectors (maximum 3 per sector). I do also select a monthly NAPS pick that removes any sector that already has 3 picks, so if a TELECOM company appeared later in the year, there is a chance I would pick it then and hold for 12 months.
With regards Elon, yes he does over promise, but the share price of his companies do deliver and many a bear has got beaten up betting against Elon. Currently I own none of his shares, but would look to getting into Space Exploration Technologies (NSQ:SPCX) on any dips.
Hi GloucesterBob.
All makes sense. I am running a version of Ed Croft's QVM portfolio which is a variant of NAPS with some selling rules https://www.stockopedia.com/co.... . Subject to these variations my holding period is 12 months as with the NAPs but running from August to August (in theory to avoid the crowded trades following the annual NAPS review by Ed). On Friday this meant I sold Water Intelligence (LON:WATR) which had fallen by more than 20% from cost and replaced it with the next best Industrial sector stock which was Jet2 (LON:JET2). Just my luck then to see this morning's headline in the FT weekend: "airlines sound alarm on costs crisis" and "carriers fear for survival". Even the ever bullish though often given to hyperbole, Michael O'Leary, was quoted as saying "this is a full blown crisis, everybody is going to be hurting next year". Great timing on my part it would seem but systematic rules are rules - I fear I might be exiting Jet2 (LON:JET2) in the not too distant future if this all plays out as the cataclysmic FT headline suggests!
Mincon (LON:MCON) Thanks for the update here, I do not hold but like the business. Having said that it seems to me quite highly rated for an engineering business which was my beef when I last looked at it. I also was put off by the spread which when I looked was pretty horrid. Probably missed the best of the rise so I am back on watching.....
Trainline (LON:TRN) The Government announcement today seems about what the company was expecting. Given how bad the state is at tech one wonders how long it will take to resolve the operator ticketing sites into one. Seems to me TRN still has a good hand to play and despite the pick up today the stock looks cheap would amuse if Government asked TRN to help with the ticketing process.......
Trainline (LON:TRN)
will the new merged system though not make it easier for other to setup simple system dial in and beat tranline on price ? i would guess the prior complexity probably made it more hassle than it was worth trying to compete?
Games Workshop (LON:GAW) article from Alphaville https://www.ft.com/content/42a5c77c-d09c-40b3-8ad2-4a01633dd6a0
Disappointing update from Oxford Metrics (LON:OMG), they seem to be fighting cheaper competition. I fortunately sold out of this some time back, I think there are prospects of recovery here, but best to wait for the present and see how it plays out.
Interesting jump in Morgan Advanced Materials (LON:MGAM) today, taking it to new high for the year, on rumours of a disposal of the thermal products division. There could be more rerating to come, they have been undervalued for some time. I hold.
Seraphim Space Investment Trust (LON:SSIT) Ordinary shares NAV has a 22p lift die to round of financing for Xona- 2nd largest holding. Seraphim Space Investment Trust (LON:SSIC) took part. The SSIC shares are trading at a discount to the launch price. They will be converted into ordinary shares at some stage in the near future. SSIC on my calculations(AI) is a cheaper way into SSIT- but do check the conversion figures.
I hold both Seraphim Space Investment Trust (LON:SSIC) and Seraphim Space Investment Trust (LON:SSIT).
I asked ChatGPT about the conversion and this is what it said. I have not attempted to check the numbers:
Seraphim Space – SSIC conversion and valuation
For anyone holding Seraphim Space C shares (SSIC), here’s my understanding of the forthcoming conversion into ordinary SSIT shares.
The first partial conversion will use the 30 September 2026 NAVs, with the conversion ratio and timetable expected in November. Conversion is not 1-for-1 but based on relative NAVs. All C shares should convert within 18 months of their May 2026 issue.
Valuation
SSIC was issued at 100p and its last reported NAV was approximately 98p, yet the shares have recently traded around 77–80p, a discount of roughly 20–22%. The underlying NAV has therefore held up reasonably well despite the share-price decline.
Meanwhile, SSIT’s March NAV was 177.63p. Subsequent valuation uplifts from ICEYE (approximately 73p per share) and today’s Xona financing (approximately 22p) imply a theoretical NAV of around 273p, before performance fees and other portfolio movements.
Is SSIC cheap?
Possibly, but not necessarily relative to SSIT.
Assuming SSIC NAV of 98p and SSIT NAV of 273p, the illustrative conversion ratio would be approximately 0.359 SSIT shares per SSIC share.
At an SSIT share price of 202.5p, that equates to approximately 72.7p per SSIC share, below SSIC’s recent trading price. These figures are illustrative, not the announced conversion terms.
Investment case
The upside lies in continued SpaceTech portfolio growth and potential narrowing of the discount to NAV. The risks include uncertain private-company valuations, concentration in holdings such as ICEYE, and the possibility of a persistent discount.
My conclusion: SSIC’s 20% share-price decline doesn’t necessarily reflect deterioration in its underlying investments. However, conversion itself won’t automatically eliminate the discount, and SSIC may not currently be cheaper than SSIT.
November’s NAV and conversion announcement should provide much greater clarity.
Thank you. I think Gemini had ignored the ICEYE uplift. So yes SSIC are not cheap - though depends on the SSIC NAV at conversion. My fault for not giving Gemini the ICEYE uplift. Lesson learnt it did not remember from a previous chat. Whereas Claude would have.
Mincon’s Q3: strong numbers, With a carefully chosen word?
Mincon (LON:MCON) Q3 trading update this morning is good news. What interested me most, though, wasn’t the numbers. It was one word the board chose not to use.
The numbers. Nine-month revenue is 28% ahead of last year. At the half-year the figure was 19%, so the third quarter accelerated sharply; Shore calculates that Q3 revenue grew about 48%.
The board now expects full-year revenue and EBITDA to be “ahead” of market expectations. For a company that previously warned on profits, it’s the first time since early 2024 that the board has said it will beat expectations.
The wording. Mincon’s board chose the plain “ahead”, with no full-year figures. Shore's broker note goes further. It says the board expects revenue and adjusted EBITDA to be “significantly ahead” of market expectations, and raises its FY26 EBITDA forecast by 18% and EPS by 30%.
This raises the question of how the Mincon update would score Ed’s up and coming guidance-scoring model. Is the company RNS more informative, the broker note, or both? It also shows just how useful services like Research Tree may be for accessing timely information.
Mincon (LON:MCON) can be difficult to trade, with wide spreads and low volume. But I see it as a repeat Jump/Momentum/PEAD candidate so I hold.
It's typical of the direction of travel in the west that on the day a multinational engineer Senior (LON:SNR) is de-listed and acquired, a "software" company is listed at more "value". Sad.
I feel your pain bottom o t h , I remember a few years ago a TV personality I admired, Fred Dibnah, on being made an honorary Doctor at Birmingham University, commenting on the fact that most engineering students were Chinese. They have 10 year plans rather than ripping one up every 5.