Daily Stock Market Report (Mon 10th August 2026) - PLUS, MSLH, NICL, ESNT

Good morning. The situation in the Middle East remains in flux, with Iran reported to have replaced a top security official in the midst of negotiations with Oman over a deal for shipping through the Strait of Hormuz. However, oil traded higher over the weekend, perhaps signalling caution about the near-term prospect of improved flows.
Elsewhere, Taiwan Semiconductor Manufacturing (TSMC) said its monthly sales rose by 45% in July, driven by AI demand. More broadly, Asian markets have traded higher today as fears of a US rate rise eased and investors continued to back the AI trade.
Looking ahead, company news flow is expected to ease somewhat this week as we head into the summer lull. Let’s see what today has in store.
It's looking pretty quiet today, so we're happy to take request for any backlog items. Update: Essentra (LON:ESNT) has been covered in the backlog.
Overnight market movements:
The FTSE is down 0.3% at 10,873
S&P 500 is up at 7,767
Brent crude is down 0.3% $83.62/bbl
Gold is up 0.3% at $4,342/oz
Bitcoin is up 0.4% at $65,109
Ed Sheldon joins me (Roland) today.
Thanks for your comments and suggestions. Today's report is now complete - see you tomorrow!
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Plus500. (LON:PLUS) (£2.58bn | SR73) | H1 revenue +12% with pre-tax profit +0.8% to $183.2m. Active Customers +10% to 197.3k with ARPU +2% to $2,346. Launched US prediction markets offering. 2026 outlook: revenue and EBITDA expected to be in line with current market expectations. | AMBER/GREEN = (Ed S) | |
Marshalls (LON:MSLH) (£459m | SR83) | Revenue -0.5%, adj pre-tax profit +13% to £24.9m and adj EPS +14.4% to 7.6p. Net debt down 10% to £137m. Outlook: FY26 profitability expectations unchanged. | AMBER ↑ (Roland) Today’s results give me the confidence to upgrade our view on this building materials business. While profitability remains subdued, margins have recovered from last year’s lows. My feeling is that the core business has been stabilised while the solar unit continues to provide high-margin underpinning for group profits. Management sounds confident of hitting full-year expectations. When housing market activity does eventually improve, I think Marshalls could do well from current levels. For now, the valuation looks about right to me, with a useful 4% yield to reward patience. | |
Nichols (LON:NICL) (£380m | SR72) | Acquired “functional soft drinks brand” VITHIT for €75m (c.£64m). VIT HIT generated sales of €26.5m and an adjusted operating profit of €4.2m in 2025. | GREEN = (Ed S) This acquisition makes sense, in my view. It’s very much in line with Nichols’ area of expertise and is expected to be immediately earnings enhancing. With the stock trading at a reasonable valuation, and the StockRank rising, I’m keeping it at GREEN. | |
Luceco (LON:LUCE) (£363m | SR94) | Dr Müller was previously divisional CEO in the Safety Sector at Halma and has previously worked at ABB, Osram and Bosch. He will start work on 1 September 2026, when John Hornby will step down as CEO and from the board. | ||
Caledonia Mining (LON:CMCL) (£312m | SR58) | H1 revenue +17% to $142.3m with pre-tax profit +41% to $48.9m. H1 gold production -19% to 32.1 koz, but performance improved significantly in Q2 due to access to high grade mining areas. Outlook: 2026 production guidance unchanged at 72-76,500 koz with AISC now expected to be $2,500-2,700/oz (prev. $2,100-2,300/oz). 2027 gold production at Blanket is now expected to be above previous guidance of 72-76,500 oz. | ||
Galantas Gold (LON:GAL) (£204m | SR26) | To date, the Company has drilled 5,060 metres of a planned 5,000-metre program at the Indiana project near Copiapó, Chile. The visual results of potential disseminated style mineralization and the resulting potential exploration targets warrants an expansion of the drill program to 12,500 metres, which will be funded from the Company's current cash position. | ||
H-Power (LON:HPOW) (£126m | SR18) | Successful completion of the first phase of its Komatsu Joint Development Agreement programme. The second and final phase is scheduled to take place from September 2026 through to December 2027. | ||
Likewise (LON:LIKE) (£74m | SR67) | Purchase of 60,000 square foot High Bay Distribution Hub in Corby has exchanged, with completion expected on 21 August 2026 for a total consideration of £9.57 million. This hub will significantly increase storage, cutting and trunking capacity through the Likewise Floors Logistics Network when it commences operations in January 2027. | ||
Aurrigo International (LON:AURR) (£62m | SR9) | Awarded £1.43m in grant funding from the UK Government to investigate how autonomous vehicles can be used to make airports safer. | ||
Hercules (LON:HERC) (£34m | SR37) | New Pay and Bill platform has been successfully implemented across the business. The platform provides a modern, scalable operating foundation for the business and is expected to deliver a range of operational benefits over time. | ||
ImmuPharma (LON:IMM) (£25m | SR5) | Has selected Kymos Germany/Prolytic as bioanalytical CRO partner for its Kapiglucagon program. This is expected to support the bioanalytical work required for the program's non-clinical and clinical development. | ||
Cadence Minerals (LON:KDNC) (£22m | SR61) | Refurbishment progresses from 77% to 87%; completion target maintained | High-grade results derived from one hole (TKDD014) intersecting LREO mineralisation in the TK4 sill, two holes (TKDD015 & TKDD017) drilled into the TK1 dyke mineralised structure, one hole (TKDD016) intersecting mineralisation in the TK5 sill and one hole (TKDD018) targeting the TK7 sill. | |
| Kendrick Resources (LON:KEN) (£25m | SR16) | Teufelskuppe – New Drill Results | Refurbishment of the Azteca processing plant at the Amapá Iron Ore Project has progressed from 77% to 87% weighted physical completion since 27 July 2026. 31 August 2026 completion target is unchanged. | |
Angus Energy (LON:ANGS) (£15m | SR39) | Initial cash sweep completed following successful financial restructuring. ORRI Cash Amount of £1.95 million repaid in full. Total debt repayments of £5.241 million since 24 June 2026. |
Backlog
Essentra (LON:ESNT) (28 July)
Share price +12% to 108p on the day, market cap £305m - Half-Year Results- Roland - AMBER ↑
Shares in this chemicals group have been on a decade-long downer that’s seen the stock fall by more than 85% since peaking in 2015. Although the broader chemical sector has had a tough few years more recently, Essentra’s problems appear to have pre-dated this sector weakness.
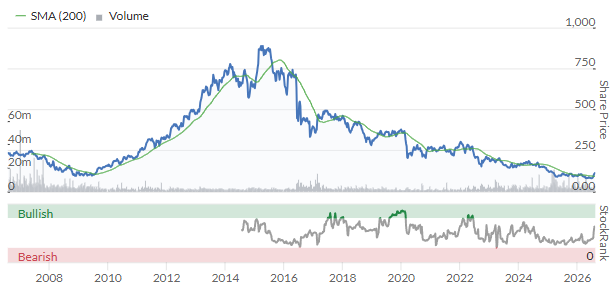
However, as Nurzel notes in the comments, Essentra enjoyed a decent share price bounce recently ahead of its half-year results on 28 July. The StockRank has also risen.
We didn’t manage to cover these on the day, so as it’s quiet today I’m going to circle to them now.
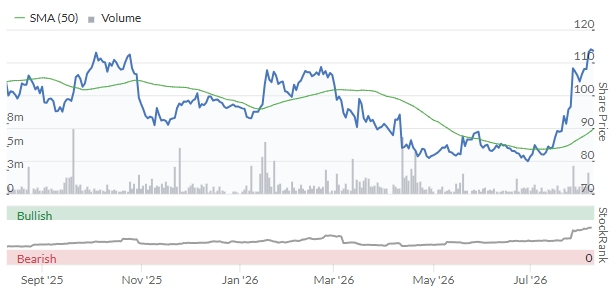
Our last look at this business was in October 2025, when Graham covered a profit warning from the group, which describes itself as “a leading global provider of essential components and solutions, focusing on the manufacture and distribution of plastic injection moulded, vinyl dip moulded and metal items.”
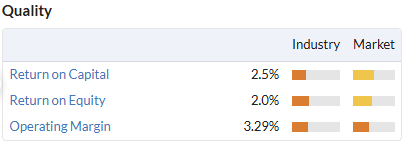
The group has slimmed down significantly since 2020 through a series of disposals aimed at creating a higher margin, capital-light industrial components business. Quality metrics like these suggest to me that this strategy has not yet delivered the hoped-for benefits:
To give an idea of the scale of the remaining £320m market cap business, Essentra is active in 28 countries and has c.3,000 employees, 16 manufacturing facilities, 27 distribution centres and c64,000 customers. I am not all that familiar with this business, but my initial impression is that it sounds like a business that should be generating more than £300m in annual revenue.
Do July’s interim results provide any signs that a genuine recovery is underway?
Half-year summary: FY26 expectations unchanged
I guess the key point about these half-year figures is that they were in line with expectations, with no change to 2026 full-year guidance.
The numbers themselves also appear positive, with most numbers moving in the right direction:
Revenue up 9% to £166.1m
Adjusted pre-tax profit up 12% to £14.0m
Reported pre-tax profit up to £3.1m (H1 25: £1.3m)
Adjusted EPS up 26.5% to 4.3p
Interim dividend up 12.5% to 0.9p
There’s clearly a big divide between adjusted and reported profits that we need to understand. The H1 adjustments fall into two categories:
Amortisation of acquired intangible assets: £4.8m
Adjusting items: £6.1m
Checking the footnotes shows the adjusting items include various acquisition, disposal and restructuring costs (£2.2m), IT upgrades costs (£3.2m) and pension charges (£0.7m). All of these are costs that also occurred last year. I would be inclined to treat them as business as usual, in particular those relating to IT and pensions.
However, I can see why the company is tempted to rely on such adjustments – doing so improves Essentra’s H1 operating margin from a reported figure of 4.3% to an adjusted figure of 10.9%.
Personally, I’m not convinced. Looking at the cash flow statement, my sums suggest a free cash outflow of £1.1m during the first half, before acquisition and share buyback costs.
That figure looks much closer to the reported net profit of £5.3m for the half year than it does to the company’s adjusted earnings.
Cash outflows are also reflected in net debt, which rose by £10m to £99.1m during the first six months of 2026 (versus Dec 25). This reflects the impact of the acquisition of mechanical component designer Boteco for £5.1m in June, together with £1.2m of share buybacks.
This increase saw leverage increase to 1.6x, from 1.5x a year earlier.
Trading commentary: “organic revenue growth”
Essentra says it saw organic revenue growth “supported by underlying volume improvements, pricing and order book momentum” in H1. We aren’t given any details of the order book, though.
Revenue rose by 9%, or 7.8% on a like-for-like basis, which does seem broadly positive, with all three of the group’s operating regions seeing like-for-like growth of at least 5.7%. Volume growth isn't explicitly stated, but my impression is that it was a low single digit percentage, overall.
Price increases certainly accounted for a decent chunk of revenue growth, as the company took “pricing actions throughout the first half” to offset higher freight and raw material costs. The group's gross margin fell from 43.6% to 43%, highlighting these pressures. A production move from Costa Rica to Mexico also created some inefficiency, but this is expected to reverse in H2.
I'm cautiously encouraged that Essentra can increase prices while delivering some volume growth. I would hope that cash generation might improve over the full year.
Outlook
Trading to date is in line with the Board's expectations and FY26 expectations remain unchanged. Whilst the Group is mindful of the wider geopolitical environment, continued strength in order intake and revenue momentum provide confidence in full year delivery.
Essentra has now established a new target for an adjusted operating margin of 14% in 2028. While this is a useful improvement on the 10.9% reported in H1 26, I’ll be interested to see how many large adjustments are required to achieve this.
Broker forecasts from Singer Capital were upgraded following the results to reflect the expected contribution from the Boteco acquisition, in addition to “a slightly better organic growth rate”:
FY26E adj EPS: 7.1p (+9.2% vs 6.5p previously)
FY27E adj EPS: 7.8p (+4% vs 6.5p previously)
FY28E adj EPS: 9.1p (+5.8% vs 8.6p previously)
The consensus figures on the StockReport are slightly lower for 2026 but match the Singer estimate in 2027. The trend chart shows a very modest rise in earnings since July, after multiple downgrades last year:
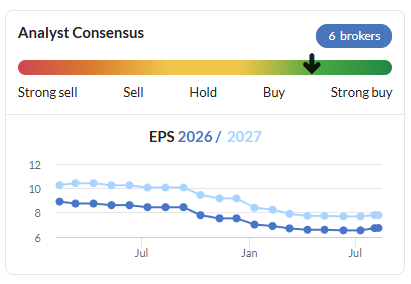
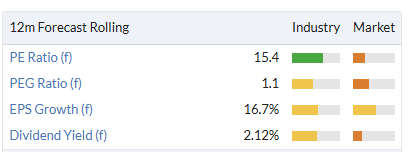
These estimates put the stock on a rolling P/E of around 15, according to our metrics:
Roland’s view
On the strength of this initial review I’m happy to move our view from AMBER/RED back to AMBER, but I don’t see any obvious reason to take a positive view. Adjustments notwithstanding, this still looks like a low margin business with material debt and not-great cash generation.
In-depth research might reveal greater opportunity here – if performance improves as forecast, then perhaps the business might justify a higher rating.
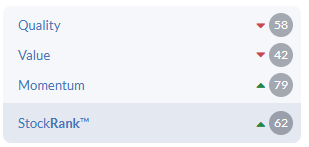
For now, I’m staying neutral – a view shared by the StockRanks:
Roland's Section
Marshalls (LON:MSLH)
Down 2.8% at 176p (£455m) - Half-Year Results - Roland - AMBER ↑
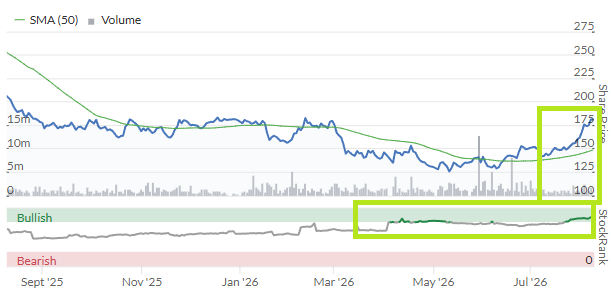
This construction materials group has a much higher StockRank than it did when we last covered the shares in March. Recent share price action has also been positive, perhaps suggesting the market is starting to price in a long-awaited bottom for the business:
The headline figures from today’s results appear to carry a mixed message – while sales remain flat, profitability has improved considerably and net debt has fallen. Management are even confident enough to announce an increase to the interim dividend:
Revenue down 0.5% to £317.8m
Adjusted pre-tax profit up 13.2% to £24.9m
Reported pre-tax profit up 68.4% to £19.7m
Adjusted earnings per share up 14.4% to 7.6p
Interim dividend up 13.6% to 2.5p per share
Net debt (exc. leases) down 9.8% to £136.8m
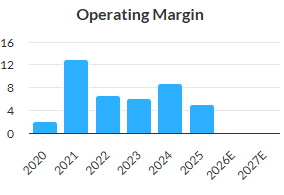
My initial take from these figures is that Marshalls has now completed the restructuring and cost-cutting processes needed to restore some of the profitability that’s been lost since profits peaked in 2021.
Today’s H1 operating margin of 8% is comfortably ahead of the 5% reported last year, although still below the double-digit margins Marshalls has historically been able to achieve during periods of strong trading.
Returns on capital also remain under pressure. Even the company’s own measure of “adjusted annualised ROCE” was only 7.2% during H1, unchanged from the same period last year.
My own calculation using reported figures suggests ROCE of 4.2% for the last 12 months.
In both cases, these returns are likely to be below Marshall’s cost of capital, meaning the business may not be generating a positive economic profit.
Cash & Balance Sheet: the reduction in adjusted net debt reported today seems encouraging, but this is a year-on-year figure, relative to June 2025. Comparing net debt to the end of 2025 shows a much flatter picture, with total net debt falling from £177m at the end of December to £175.3m at the end of June.
That’s consistent with the cash flow statement, which shows free cash flow of £2m for the half year.
In fairness, six months is a short period. I’m content to see debt hasn’t risen and hopeful that the year end will bring a modest improvement in the group’s balance sheet.
Half-year leverage of 1.7x EBITDA is a slight improvement on the 1.8x reported at the end of last year, so things are slowly moving in the right direction.
Divisional trading: solar shines through
I tend to think of Marshalls as a brick and block firm, but this view is a little outdated. These results provide a useful reminder that the group’s roofing business Marley, acquired in 2022, is now an important contributor, thanks mainly to its solar unit.
Landscaping Products: revenue down 0.2% to £135.1m, operating profit £5.5m (H1 25: £0.3m).
Building Products: revenue down 0.9% to £85.6m, operating profit down 10.1% to £6.2m.
Roofing: revenue down 0.6% to £97.1m, operating profit down 6.9% to £23.1m.
Softer market conditions in new build housing and RMI (repair, maintenance and improvement) are said to have weighed on sales in the two core units.
For me, the standout conclusion from these figures is that the group’s two historic core businesses generated an operating margin of 5.5% and 6.2% respectively, whereas Roofing generated an operating margin of 23.8%.
The roofing business has two main elements, Marley Roofing Tiles and Viridian Solar. Marshalls doesn’t split out the profit between these two operations, but I’m pretty sure that bulk of the profits are coming from solar, with the roofing tiles business ‘enjoying’ similar economics to the group’s other core operations:
Growth in Viridian Solar was driven by higher volumes and continued commercial discipline, whereas the lower profitability in Marley reflected softer volumes in a competitive and subdued marketplace alongside weaker manufacturing efficiency.
Checking Companies House for Viridian Solar supports this view – the 2024 accounts (the latest available!) show Viridian Solar generating a 35% operating margin.
Recent strong growth in Viridian has been aided by a tailwind from new building regulations relating to the fitment of rooftop solar in new homes. The company notes this is now levelling out, but this business still seems to be a valuable asset for Marshalls.
Outlook
Anyone hoping that the improvement in profitability would support an upgrade to full-year expectations is likely to be disappointed:
Market conditions are expected to remain subdued with no material recovery in end-market demand during 2026. Against this backdrop, management remains focused on disciplined execution, tight cost and cash control, and targeted commercial actions to mitigate external cost pressures.
However, for me the key points is that trading (and cost savings) are said to be on track and that full-year expectations are unchanged.
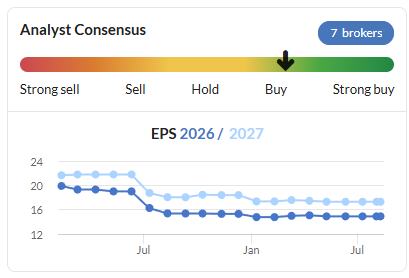
Against a backdrop of multiple profit warnings last year, I think this represents valuable progress:
Roland’s view
To me, the company’s decision to increase the interim dividend today suggests a good level of confidence in being able to deliver on current forecasts.
The core business appears to have stabilised, while the solar business is providing support for profits during a low point in the cycle. When housing market activity does improve, history suggests Marshalls should see positive operating leverage in its core manufacturing business, supporting higher margins and materially higher profits.
Based on our consensus forecasts, these put Marshalls on a FY26E P/E of 12, falling to a P/E of 10 for 2027. Forecasts for a 7.48p dividend in 2026 give a potential yield of more than 4% – a decent reward for the patience that may be needed.
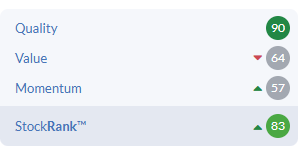
I stayed cautious on Marshalls in March, but I think it’s fair to move our view up by one notch to neutral after today’s interim results. The StockRanks also share take a similar view, with Neutral styling and an above-average StockRank:
Ed S's Section
Plus500. (LON:PLUS)
Up 6% to 3,978p (£2.58bn) - Interim results for the six-month period ended 30 June 2026 - Ed S - AMBER/GREEN =
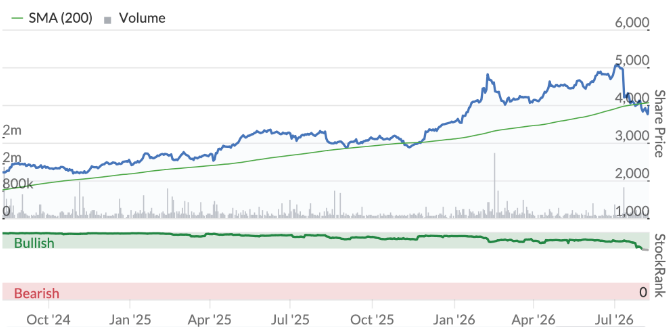
Trading platform operator Plus500 has today posted its half-year results. To set the scene, the company put out a half-year trading update on 13 July and the stock tanked 15% (it has continued sliding since then).
Today's numbers:
Revenue increased by 12% YoY to $462.9m.
Operating profit up 1% to $184.4m.
EBITDA up 1% to $187.5m, reflecting the Group's deliberate step-up in customer acquisition investment, the natural scaling of revenue-linked costs in the US business, and a short-term FX headwind from a materially stronger Israeli Shekel versus the US Dollar.
Basic EPS grew by 6% YoY to $2.17.
Total shareholder returns of $182.5m, comprising $100.0m in share buyback programmes and $82.5m in total dividends ($1.2001 per share).
Dividends: interim dividend of $0.5135 per share and a special dividend of $0.6866 per share.
Cash and cash equivalents of $861.3m as of 30 June 2026.
Key performance metrics also improved:
Active customers up 10% to 197,294.
New customers up 17% to 65,723.
Total customer deposits rose by 10% to $3.4bn, with an average deposit per Active Customer of c.$17,300.
Trading income, the Group's primary revenue driver, increased by 15% YoY to $441.8m.
The non-OTC business delivered revenue growth of c.30% YoY, increasing its contribution to c.15% of total Group revenue (H1 2025: c.13%).
Guidance:
“Plus500 enters the second half of 2026 with strong momentum and a clear strategy across its OTC and non-OTC operations.”
“The Company's Board of Directors expects FY2026 revenue and EBITDA to be in-line with current market expectations, following several upgrades earlier this year.”
Note that the company provides market expectations of: FY2026 revenue of $811.5m and EBITDA of $365.1m.
H1 operational highlights:
The OTC business expanded its geographic reach, including new operations in Canada and Latin America, and launched 24/5 trading on stocks and ETFs.
The Group's non-OTC business launched a CFTC-regulated B2C prediction markets offering, including sports contracts, as well as single stock futures, and secured additional B2B partnerships with Wealthsimple and Nelogica.
Ed S’s view:
The lack of profit growth here is obviously a bit disappointing given that 2026 has been a blockbuster year for trading activity. However, there’s certainly some justification for the performance:
During H1, the Group deliberately invested an incremental c.$16m in marketing technology to accelerate new customer acquisition, with a continued focus on attracting higher-value customers.
Commissions and fees increased by 34% YoY to $44.6m, reflecting the continued scaling of the Group's non-OTC business, where a portion of the cost base scales directly with trading volume and increased customer numbers and revenue. The company says that it views this dynamic positively and expects it to persist as it continues to scale its non-OTC operations, with commissions and fees growing broadly in step with the pace of US revenue growth over time.
Payment processing costs increased by 10% YoY to $24.1m, reflecting higher customer deposit volumes and the Group's continued success in attracting and retaining a larger base of active, higher-value customers across its global platforms.
It’s worth noting that the customer acquisition spend appears to be paying off:
In H1, 20% of OTC revenue was generated by customers trading with Plus500 for up to one year (H1 2025: 16%).
New customers increased by 17% YoY to 65,723 in H1.
ARPU increased by 2% to $2,346 and AUAC (average user acquisition cost) decreased favourably by 1% YoY to $1,230.
“The strategic focus on higher value customers and investments in retention technologies continued during the period and resulted in a strong ROI on recently acquired cohorts converting into high-quality revenue more quickly than in prior periods.”
Looking beyond this issue, I see the company’s move into prediction markets as a positive. In the US, this area of the financial markets is booming today.
“The Group launched its CFTC-regulated B2C prediction markets offering in February 2026 and introduced sports event-based contracts in June 2026, the highest-engagement category within prediction markets.”
Already, the non-OTC side of the business is seeing strong growth. In H1, revenue was up approx. 30% year on year.
The company notes in today’s report that this area of the business is on track to generate annualised revenue of approximately $140m in FY2026. In H1, it contributed 15% of group revenue versus 13% a year earlier.
“The Group's expanding US presence, comprising B2B, B2C and B2B2C channels across futures and prediction markets, is a proven growth driver which continues to provide compelling opportunities for expansion.”
Taking a step back and looking at the financials, there’s a fair bit of quality here.
The balance sheet is strong, with no debt. Meanwhile, return on capital employed (ROCE) is very high.
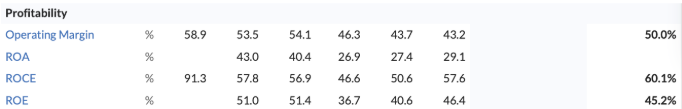
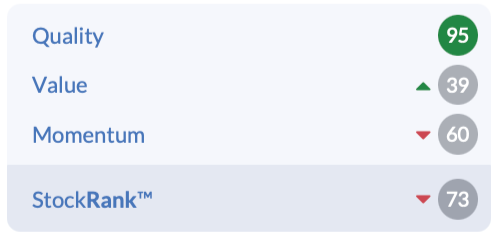
The Stockopedia rating system agrees, giving PLUS a 95 for quality.
Turning to the valuation, it looks very reasonable if we take the 2026 consensus earnings forecast of $4.10. That forecast puts the stock on a forward-looking P/E ratio of around 13.
I wouldn’t rely on that forecast though. In this industry, operating conditions can vary significantly from period to period (market volatility, mega IPOs etc.).
As for shareholder returns, the company is paying dividends (including special divis). And the payout is well covered by earnings.
It’s also doing buybacks. Since 2017, Plus500 has repurchased approx. 40% of its issued share capital.
Overall, I’m cautiously optimistic here. I like the trading operations theme in general – not only is market volatility creating opportunities for companies that operate in this area but younger generations are more active when it comes to the financial markets.
And with this company, we have a high-quality operator with plenty of growth potential trading at what appears to be a reasonable valuation. Dividends and buybacks add weight to the investment case.
I’m going to leave the stock on AMBER/GREEN.
Nichols (LON:NICL)
Up 1% to 1,055p (£380m) - Acquisition of VITHIT - Ed S - GREEN =
We covered soft drinks company Nichols a few weeks ago when it posted its 2026 interim results. At the time, Graham gave it a GREEN rating on the back of its attractive valuation.
Today, we have news of an acquisition. Let’s take a look at the details.
The acquisition:
Nichols has acquired 100% of the issued share capital of VITHIT Limited and its subsidiaries (VITHIT) for a total cash consideration of €75.0 million (approximately £64 million) on a debt-free, cash-free basis. VITHIT is a functional drinks brand offering a portfolio of low-calorie, low-sugar beverages fortified with vitamins and functional ingredients.
VITHIT has established market-leading positions in the UK and Ireland together with a presence across 13 other international markets. For the financial year ended 31 December 2025, it generated revenue of €26.5 million (representing a 3-year CAGR c. 9.5% with over 90% sales growth since FY21), an adjusted operating profit of €4.2 million, and adjusted PBT of €4.1 million.
VITHIT is an excellent strategic fit for Nichols given its leading market positions in a structurally attractive soft drinks sub-category, complementary asset-light operating model, established profitability and significant growth opportunities. The acquisition is expected to be immediately earnings enhancing.
The strategic rationale:
VITHIT will provide Nichols with a considerably strengthened position within the significant and growing health and wellness segment of the soft drinks market.
VITHIT has an asset-light operating model supporting synergies of more than €1 million per annum and a clear integration plan.
Meaningful opportunities to accelerate VITHIT's current sales growth by leveraging Nichols' distribution capabilities, strong customer relationships, brand-building expertise and infrastructure.
Further diversification of the group's portfolio and revenue streams.
The acquisition is expected to be immediately earnings enhancing and to generate returns comfortably in excess of the group's cost of capital.
Funding details:
The acquisition has been funded through cash on Nichols' balance sheet.
Proforma for the acquisition, the group remains net cash positive at 30 June 2026
A new revolving credit facility will be provided by NatWest post-acquisition for working capital purposes.
Following completion, Nichols will retain substantial financial flexibility and reaffirms the recently improved dividend cover policy of 1.5x.
Ed S’s view:
This acquisition makes sense, in my view. It’s very much in line with Nichols’ area of expertise (Nichols’ portfolio includes Vimto plus a range of licensed brands including MyProtein, Levi Roots, ICEE, and Sunkist).
And health-focused drinks is a rapidly growing industry. According to Mordor Intelligence, the market is set to grow by around 7.1% per year between now and 2031.
VITHIT’s financials look solid: 3-year revenue growth CAGR of 9.5% and an adjusted operating profit margin 15.8% last year (Nichols’ operating margin last year was 15.6%). Nichols says the acquisition will be immediately earnings enhancing and generate returns comfortably in excess of the group's cost of capital.
Taking a closer look at VITHIT’s products, they appear to be a hit with consumers. On Amazon and Trustpilot, review scores are very high.
On the downside, Nichols only had £66.2 cash and cash equivalents on its books at 30 June. So, the acquisition is set to pretty much wipe out its cash balance.
However, it notes that a new revolving credit facility will be provided by NatWest post-acquisition for working capital purposes. It adds that the board remains committed to its existing capital allocation framework and dividend policy.
With its established market position, alignment with our asset-light operating model, proven profitability and significant headroom for growth, VITHIT perfectly fits the acquisition profile we have been looking for and is fully aligned with our long-term growth strategy.
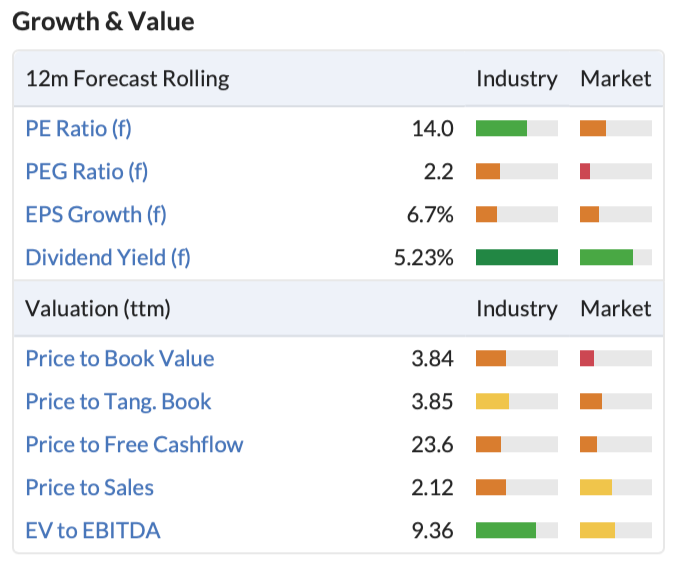
Looking at earnings forecasts, Nichols currently trades on a forward-looking P/E of around 14. Graham’s take in July was that a trade buyer would pay significantly more than 14x forward earnings for this business and I agree with him.
This is not just a valuation story though; there’s also a nice dividend yield on offer. With analysts expecting a payout of 51.3p per share for 2026, the prospective yield is around 5%.
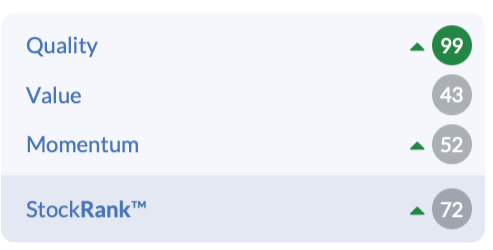
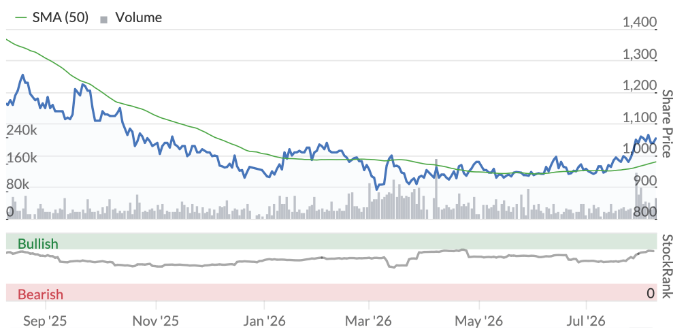
One other interesting thing to note here is that the StockRank has jumped recently. Over the last 30 days, it has increased by 16 to 72.
Momentum has been a key driver here. It’s up 15 points over the last 30 days.
Putting this all together, I’m happy to leave the stock at GREEN. I think it looks interesting at current levels.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

30 comments
Hi Roland,
Could you please take a look at Serica Energy (LON:SQZ) some time this week. They posted half year finacials last Thursday.
Best Regards
Andy
Stock Ranks
On Friday there were many comments by people seeing different SRs for the same share (HSP as it happened). Fed up with this I put it to the green button and Oliver replied to me and to the board. Since this was in the afternoon and many stop looking at this early on a Friday I copy it below. It not only gives an answer but shows the green button does work!
Oliver Cooper Staff 87 posts Fri, Aug 7, 2026In reply to BrusselsLad
There is a reason why two people may see different StockRanks for the same stock. It is due to differences in their site settings, which you can find here: https://www.stockopedia.com/a/settings
At the bottom you will find 'Ranking Universe':
If a person has changed this from the default of 'Local' then they will see different ranks, as they have a different ranking set.
I hope this clears things up.
Thanks sharw, that is very helpful. Indeed, I had not seen the reply on Friday nor had I posted the question using the green button.
I use the StockRanks mainly for my investments outside the UK (mainly Europe as I am in the Euro zone). So I do have my settings set to regional ranking. It is logical that the SR differs but I had not picked this up. I do look at this in the UK but it does not play a direct role in my investment strategy.
It would appear that Hargreaves Lansdown have realised their error in pricing ISA portfolios at the Offer or Buy price in their new App layout. This morning my ISA was unavailable to view through their App ( with a Technical Issue error message) but OK in the website. I rang to query this and also ask about their policy on ISA portfolio pricing. A very polite chap first of all queried my sanity when I explained they had been using Buy prices to value clients ISA holdings viewed in the new layout, when I assured him I was correct he told me couldnt believe they would do that. He said he would flag this to the IT team! 20 minutes later the App is available to view but in the old format and at Bid or Sell prices. I personally hope they ditch the new App layout.
On the desktop website HL have lost the ability to order the portfolio by either overall or daily percentage gain/loss, you can only order by £value overall or daily gain/loss. I have raised this with them over a month ago and after they initially said it was my browser they have later admitted that other users have also raised the same issue and they are attempting a fix however unsure on timescales. I would have thought such basic functionality would be simple to restore but HL appear to be constantly introducing changes which make the site worse (intentionally or unintentionally). Style over substance when you lose basic functionality on the site.
Yes, I've had the same problem with HL's website. I flagged it with them month's ago, then a few weeks later I was told "they were working on a solution but had no timescales for a fix". Last week I queried it again with some new failings. Their reply "send us videos of the problem and we'll investigate" !! Surely it's not my job to debug their crappy website! Why can' their IT team just try it for themselves.
Hi Helvellyn as you know I totally agree and have also been in communication with them. My İsa this am has shown both the old ( good) format and the new ( bad) format. Sadly it has now reverted to the new format again.
As you say their prices are all over the place , some bid , some mid , some offer.
A shambles
Tresawle, thanks for that, your reply prompted me to take open the HL app again and as you say it has reverted to the new format with some bid, some offer and some random prices for my holdings.
Shambles at best !!
HL new app is terrible I have told them they said they would reform it Much better to go back to old app it was excellent better than ii or AG Bell
Vistry (LON:VTY)
Vistry Group PLC, down 7.7% at 261.8p, 12-month range 220.00p-746.40p. The FT reports credit insurer Allianz Trade is cutting the cover it offers to suppliers of the housebuilder. Citing people familiar with the decision, the newspaper says the move could result in cover being reduced by up to 70%. The final level of cover provided may hinge on Vistry's financial performance in times to come, the FT reports. The likes of Allianz Trade insure suppliers in case customers fail to pay for services or products.
Serica Energy (LON:SQZ) Good to see financial discipline by not getting involved in a bidding war.
A good set of results from HgCapital Trust (LON:HGT) with a strong performance and a NAV of 530p, materially above the share price. Good long term hold as software WILL benefit from AI.
Looks decent update, although the discount not much different to the other PE funds. They apply an EBITDA multiple of 23 which is certainly not cheap, but you're paying 17x at the current discount which is more reasonable (albeit more expensive than many listed peers such as Sage). The thing that puts me off is the £2bn in commitments which is large relative to the size of the portfolio and slow pace of realisations - it's not immediately clear how easy it is to opt out of these obligation - they mention they can opt out where certain conditions are met which feels a bit vague to me.
Vistry (LON:VTY)
I note the comment on Allianz cover being subject to review. Ref my previous comments on the company being accident prone. Unless my memory is overtly faulty I seem to recall when monickered as Bovis something similar happened and everyone thought this would end in tears. It did 'nt at the time as I recall Vistry becoming the City's favourite house builder.........
What is that saying ( had to AI this )
George Santayana: "Those who cannot remember the past are condemned to repeat it"
Others of course will say ' it will be different this time..........'
Hmm time to toss the 2 headed coin and call tails
Re : Vistry
Story reported in the FT that trade insurer Allianz were reducing their cover to suppliers of Vistry. The FT reports that ..
"it is adjusting its credit limits for Vistry, which could result in cover being reduced by up to 70 per cent"
Some concern that this would result in a cash flow problem for Vistry.
Nichols (LON:NICL) and Likewise (LON:LIKE)
I think the acquisition by Nichols a logical step given the increasing impact of weight loss drugs on drinking and eating habits of the UK population. Nichols is a pretty conservative business so you would think they have given this type of diversification a considered thought process. I like...
Lots seem to be happening at Likewise and a lot at pretty breakneck speed. One wonders whether consolidation is now required. Interesting to note the strength of Headlam (LON:HEAD) which is an obvious rival and who LW are obviously keen to replace. It all looks very positive for LW but a lot of new shares have been made available recently....
Marshalls (LON:MSLH)
My quick thoughts here
1) The headline out come looks as good as can be expected given the macro conditions for the business hardly rate as attractive
2) The Management initatives look to be bearing fruit... a tick
3) Catalyst for any re rating has to be some up tick in construction where the outlook hardly seems less than cloudy. Whilst people are reining in spending Marshalls products are generally going to fall into the discretionary bucket
4) I ditched when they decided to buy Marley as I did not see this as complimentry to the business model. Marley owners have a pretty checkered history; unclear why Marshalls would do any better. I think the placing price for the shares at the time v where we are now about sums up the situation
I remain sanguine
Marshalls (LON:MSLH)
The UK leader in landscaping products appears to be in making progress in difficult markets. Looks good value despite the share price recent rise.
Not so long ago it traded as high as 800p. Given a buoyant backdrop, which one day is likely to happen there is no obvious reason why it shouldn’t get back there. In the meantime there is a reasonable yield on offer.
Thoughts from Graham and colleagues appreciated.
Morning jonno, Marshalls (LON:MSLH) is on the list.
Roland
Marshalls (LON:MSLH) there are now 25% more shares in issue than back when they traded at 800, probably to do with a placing when they bought the Marley Tiles business in 2022 (iirc), however TBF 600 would still be an attractive outcome for shareholders here I imagine !!
Good point Helvellyn
Yes and also worth noting Marshalls was expensively rated back then on a PE of around 20. I personally wouldn't expect it to acheive those sort of ratings again any time soon. I think 400p is achievable in the medium term it we see a recovery in its markets
Hi Helvellyn,
Just checking back.
A little less than 29 million shares were issued at 650p to help fund the Marley purchase raising £187m. This represented 11.4% of the enlarged share capital.
Marshalls (LON:MSLH) paid £535m for Marley Roofing.
Heady times.
All the best
Marshalls (LON:MSLH)
Thanks for flagging up
Not so long ago it traded as high as 800p. Given a buoyant backdrop, which one day is likely to happen there is no obvious reason why it shouldn’t get back there.
How on earth would you come up with 800p per share valuation - that seems ridiculously stretched based on where they are now ? - i get it you are talking about the future but 800p seems to be fantasy land based on my quick glance of where company is now. Can you even come up with future sensible calcs to jutstify 500p never mind 800p?
800p is admittedly overly optimistic and one has to take account of the dilution resulting from the Marley purchase. But if and when the housing/construction market turns the corner the share price will be a lot higher that it is today, helped along by cost savings
Marshalls (LON:MSLH)
i must admit there could be genuine reasons for hopes that profits might bounce back - particlarly if there has ben material acquisition and sum of the parts profits are both on the floor this might very well be the case here ?- perhaps potential for outperformance if the historic profits of each as a separate business suggests profits may be multiple higher - it seems structurally harder specifically for housebuilders to make decent profits at present - so i am not currently expecting old highs to return anytime soon ref housebuilders - but perhaps more niche outfits might have ability to return to former glories with higher volumes if and when we actual;ly start building homes and get peple into them !. With housebuilders i think it seems to be the case that build costs have gone up way faster than house prices - if house prices are still "stretched" for many and new houses will be coming on tap quickly at some stage - i can see lag ref house prices trending downwards in real terms with costs going up in real terms not a great mix if you make your margins on the basis prices will keep p[ace with inflation - note overall i think thats a perfect scenario for many - house prices in this country have been ridiculously high for to long - period of zero growth or negative growth is just what is needed to get the have nots back into the haves category - that will only really start to show if we do provide much much more affordable housing - over to you AB
£2.8m market cap Thruvision (LON:THRU) wins a £3m contract, being delivered in the second half of the year, after winning other recent contracts. Worth a fresh look?
Thanks for the suggestion Tortoise, but Thruvision (LON:THRU) is a little small for us, as we don't generally go below £10m market cap.
Roland
Hi Roland, can you look at Essentra (LON:ESNT) that reported on July 28. Looks like the turnaround is starting to materialise here. Cheers
Noted, thanks for the suggestion.