Daily Stock Market Report (Mon 16 Dec 2024) - FTC, AVGO, DUKE, XLM, SAGA, VID, TSTL

Good morning!
To start off the week, I'd like to mention Stockopedia's new podcast that has been produced by our colleague Lawrence - Companies and Markets Weekly.
The first episode features Roland, Lawrence and myself as we discussed the financial stories that we found most interesting last week. It's available on Spotify and Apple Podcasts.
Huge thanks to Lawrence for spearheading this - and I hope you like it!
12pm: this report is finished for today.
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing. Links:
Daily Stock Market Report: records from 5/11/2024 (format: Google Sheet). Updated to 10/12/2024.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Ricardo (LON:RCDO) (£250m) | Acquisition & divestment. | Ricardo is spending £51m on an advisory firm and is divesting its Defense unit. | |
Videndum (LON:VID) (£245m) | TU | Profit warning? 2024 rev £280m (StockReport: £315m). Dec 2024 banking covenants amended. | RED (Graham) |
Tristel (LON:TSTL) (£187m) | AGM Statement | In line. Expecting to hit or exceed three-year revenue growth target of 10-15% by June 2024. | GREEN (Roland) |
| Saga (LON:SAGA) (£177m) | Saga and Ageas insurance partnership | Saga selling underwriting unit (£65m). Will outsource home/motor, cons. up to £140m | AMBER (Roland) |
Filtronic (LON:FTC) (£158m) | TU | H1 25 results to be ahead of expectations. Reports pull-forward of orders. | AMBER (Roland) |
Duke Capital (LON:DUKE) (£124m) | Interim Results | Cash rev down 4% to £13.5m, free cash flow down 26% due to fewer exits. “Positive outlook”. | AMBER/GREEN (Graham) |
| Concurrent Technologies (LON:CNC) (£117m) | $3.3m contract win | Order for standard computer boards from existing US customer. No change to guidance. | |
| XLMedia (LON:XLM) (£33m) | Update on distribution of capital | Proposes £16m ($20m) tender offer, half of potential total cash available following disposables. | AMBER (Graham) |
Cirata (LON:CRTA) (£31m) | Contract wins & FY24 guidance | New contract with IBM, but FY24 bookings guidance withdrawn due to pipeline delays. |
Summaries
Filtronic (LON:FTC) -up 4% to 75p (£163m) - Trading update - Roland - AMBER
The electronics group has upgraded its guidance for FY25 as existing orders are pulled forward. I’m positive, but I wonder if this could have a negative impact on FY26 trading. Broker forecasts suggest some risk of a profit drop next year. I’m broadly positive, but I reckon the shares are up with events.
Duke Capital (LON:DUKE) - up 3% to 30p (£153m, 510 million shares outstanding) - Interim Results - Graham - AMBER/GREEN
The interim results show little change with a mild increase in recurring revenue and a flat dividend. More interesting is the change in strategy as Duke moves away from the UK equity market as its primary fundraising tool. It’s now looking for managed accounts or joint ventures that would deliver fee-based revenue. I think the change makes sense and could see Duke evolve into a unique type of fund manager.
Saga (LON:SAGA) - up 6% to 131p (£187m) - Saga and Ageas agree new insurance partnership - Roland - AMBER
The over-50s travel and insurance group has confirmed a partnership with insurer Ageas to complete the transition of Saga’s insurance operations to a capital-light, marketing-only model. Substantial cash inflows are expected, but seem unlikely to accelerate the group’s deleveraging. The shares could be cheap, but I think risks remain. I’m staying neutral for now.
XLMedia (LON:XLM) - down 24% to 9.45p (£25m / $32m) - Update on distributions to shareholders - Graham - AMBER
Proceeds from XLM’s disposals that are likely to make their way to shareholders’ pockets turns out to be lower than hoped for. Only up to $5m is anticipated from earn-outs (out of a maximum $15m) and shutting-down costs could cost up to $13m. Hopefully this is the last disappointment from XLM before it leaves the market.
Videndum (LON:VID) - down 18% to 210p (£197m) - Pre-Close Trading Update - Graham - RED
Detailed forecasts are unavailable to me but the new revenue estimate looks very poor at just £280m. The company is trying to boost margin but at the same time it announces a £25m impairment that will hit both stock and intangibles. Prior management gets blamed for what has happened here, even though the Hollywood strikes and weak demand in the content creation market provided ready-made excuses. With the company requiring very loose covenants from its banking syndicate, it’s an automatic RED from me.
Short Sections
Broadcom (NSQ:AVGO)
Up 24% on Friday ($1.05trn) - Q4 results - Megan - AMBER
A 24% share price leap to take the company’s market capitalisation into $1trn territory, was enough to make Broadcom (NSQ:AVGO) one of the most popular shares on our site over the weekend. It’s rare for our community to be so interested in the StockReport of a non-UK share, but AI companies tend to buck the trend. Broadcom seems to be giving lots of investors Nvidia vibes.
Both semiconductor companies have very exciting exposure to the artificial intelligence industry. Nvidia specialises in a unique piece of hardware known as a graphics processing unit (GPU). Broadcom has both the hardware and software products, but it's the software solutions that are really benefiting from the surging demand from AI customers.
In the fourth quarter of the 2024 financial year (to November), revenue was up 51% to $14.5bn. In the year as a whole, AI revenues were up 220%.
In the company’s earnings call, its chief executive Hock Tan fuelled the excitement which has propped up companies with AI exposure (and the US markets as a whole) with his outlook for the coming years. He told investors that the addressable AI market for Broadcom is expected to rise from $20bn currently to between $60bn and $90bn by 2027.
Megan’s view:
It’s good to see another semiconductor truly joining the AI party, which Nvidia has attended on its own for most of the year. Broadcom’s share price has doubled in the year to date, which is still some way behind its larger peer, but nonetheless impressive.
The problem with Broadcom is that sales growth is far less consistent than that of Nvidia. While the larger company manages to deliver consistent growth on a quarterly basis, Broadcom’s growth is coming in surges.
Its earnings momentum also isn’t quite as impressive as that of its larger peer and margins aren’t growing, which is surprising given the market opportunity.
That said, I can’t see the US market turning away from Broadcom in 2025. For momentum investors happy to ride the wave of positive sentiment towards AI companies, this could keep delivering. For those looking for more fundamental value, Nvidia looks like a far better pick. AMBER.
Tristel (LON:TSTL)
Down 2.6% to 380p (£181m) - AGM Statement - Roland - GREEN
This infection control business has issued an AGM statement today confirming that the company is trading in line with expectations.
Tristel also confirms that it expects to “hit, if not exceed” its existing three-year target of 10%-15% revenue growth by 30 June 2025 (the end of its current financial year).
This business has a strong share in the UK healthcare market and a long history of growth, supported by its proprietary disinfectant formula. Tristel is now hoping to gain a foothold in the US market, having gained FDA approval for some of its core products.
Megan took a closer look at Tristel in the latest Week Ahead article, which is worth reading for a broader view on this interesting business. She highlights the scale of the opportunity and the challenges involved in US expansion for small UK companies. Today’s AGM Statement alludes to this, warning that US sales growth has been below expectations:
This is primarily due to the stringent purchasing bureaucracy of signing up new healthcare accounts, alongside the time taken to train sales reps with the Company's longstanding partner Parker Laboratories.
On a more positive note, US customer feedback is said to be “encouraging” and the company’s sales pipeline “remains robust”.
Tristel will publish its interim results on 24 February 2025, when I imagine more detailed information on trading may be provided.
Roland’s view
If Tristel’s US expansion is successful, this business could be worth significantly more in the future. Unfortunately, I don’t see any way to predict how likely this might be.
However, a weak share price performance and the introduction of a more generous dividend policy have left this highly-profitable business looking more attractively valued than previously:
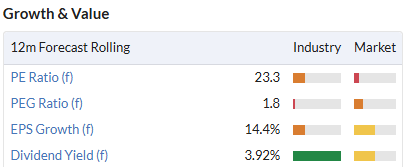
I think the current valuation is largely supported by the existing business, with the US offering potential long-term upside. On this basis, I’m happy to maintain Megan’s GREEN view.
Graham's Section
Duke Capital (LON:DUKE)
Up 3% to 30p (£153m, 510 million shares outstanding) - Interim Results - Graham - AMBER/GREEN
I downgraded my stance on this last month after the company raised funds at 27.5p, which I considered to be a disappointing price at which to raise new equity.
They had last raised at 35p in 2022.
Today’s interim results show 4% growth in H1 recurring cash revenue, up to £12.7m.
A dividend of 0.7p has been paid per quarter, entirely flat at this level since March 2022 and in truth this hasn’t changed much since early 2019 (0.67p).
With £15m of capital deployed in H1 into “follow-on” investments, Duke argues that there has been “an increase in the maturity and profitability of the underlying portfolio”, and that this will result in higher EBITDA multiples upon exit.
New funding strategy: Duke outlines a fundamentally new approach to its strategy.
Building on the strategic review we undertook in the last financial year, we have been developing a long-term funding strategy which is not reliant on raising equity via the UK public equity markets…
…the time is right to move towards a third-party capital model and as such, we intend to raise future additional capital via new Managed Account / Joint Venture structures. The clear benefits of this strategy will be to eliminate cash drag, deliver accretive fee-based revenue and reduce Duke's dependence on the UK public equity markets, thereby minimising dilution and enabling us to execute on strategic growth opportunities more rapidly and at scale. With this in mind, during the period, Duke engaged a placement agent to approach potential capital providers and, as previously announced, has received indicative term sheets from Tier-1 capital providers on potential new funding, with further term sheets expected.
Outlook: they maintain “a positive outlook for the months ahead, albeit we recognise the need for caution in relation to the UK economy”.
Graham’s view
Firstly in terms of valuation, the market cap at the new, higher share count I calculate to be £153m, which is not far off balance sheet equity of £162m.
The bigger question today is around the implications of the new strategy.
I’m impressed that the company has decided to stop relying on the UK equity market for funding. I always knew that they were ambitious to raise funds but it has been clear in recent years that the price at which funds might be available has not been very attractive, and the quantity of funds available has probably not been attractive either.
I give credit to them for saying that the decision to raise funds recently “was not taken lightly and reflected the near-term investment opportunities” within their existing portfolio. It’s clear now that raising equity at that sort of price is not the plan going forward.
If Duke evolves into a sort of private equity fund manager, largely managing 3rd party funds, this is something I could support. Readers will know that I like fund managers with a niche, and Duke’s mortgage-style funding product for medium-sized businesses could certainly be considered niche!
The new plan is still in its infancy, however. Term sheets are really just proposals and negotiating tools. We’ll have to see what comes of the term sheets received so far by Duke. But I do think that the new plan has some interesting potential, and I remain comfortable with a mildly positive stance on this one.
XLMedia (LON:XLM)
Down 24% to 9.45p (£25m / $32m) - Update on distributions to shareholders - Graham - AMBER
This is a special situation as cash is being distributed to shareholders with the only questions left being “how much?” and “when?”
In October I did some calculations and estimated that XLM would get a cash balance of at least $52.5m (£41m), before various costs and ongoing cash drain, and before discounting for certain risks. I suggested at the time that a c. $50m (£39.5m) market cap might be fair, and took a neutral stance.
Unfortunately, the company has announced today that it is only expecting to have about $40m (£32m) of available cash “after taking account of reasonably expected costs and liabilities and expected further receipts”, including deferred consideration and earn-outs from its disposals.
What has gone wrong? Firstly, cash at the end of October 2024 was only $17.7m.
This is despite the company starting with $19m at the end of June, and receiving $10m during October for its European disposal.
The only major payment I was expecting was a $4m outflow for a prior acquisition.
My conclusion is that the North American business must have been burning cash very rapidly in the period before it was sold, and/or that the costs of selling it must have snowballed.
Inflows due after October:
$20m initial payment for North American business (already received)
April 2025: $7.5m deferred payment for European business
Earnouts: only $3-5m is now estimated in earnouts, out of a possible $15m. The amounts will be finalised in late Q1 2025 and payable in April 2025.
This gives a gross cash figure of $48-50m, before costs.
Today we get an estimate of winding-down costs and they are huge: $11-13m. The amount of tax due is yet to be finalised.
That leaves a range for cash available of $35-49m. XLM’s market cap has moved to 10% below the bottom of this range, which I think is reasonable.
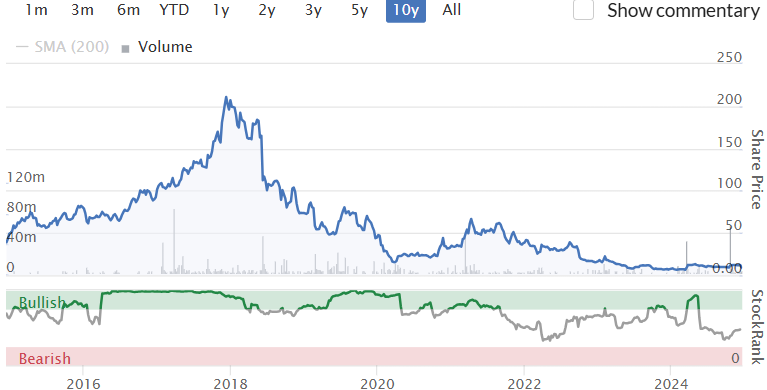
Graham’s view: it turns out that I was too optimistic with my initial calculations, but I’m glad that I stuck with a neutral stance as voluntary liquidation events like this are unpredictable and I have noticed that I am often surprised by the amount of costs they incur while trying to sell down or shutter their businesses.
XLM shareholders can look forward to a £16m/$20m tender offer, and hopefully another one in the middle of next year. But there’s no getting away from the fact that the company has again failed to live up to investor expectations. Shareholders might be glad to see the back of this one at last.
Videndum (LON:VID)
Down 18% to 210p (£197m) - Pre-Close Trading Update - Graham - RED
I was RED on this in September due to concerns over its indebtedness.
That problem continues today with the following trading update:
The recovery in our markets continues to be slower than expected, but we are seeing some signs of gradual improvement, which we believe will benefit trading in H1 FY25.
FY24 Revenue: now forecast at £280m, this compares with £307m last year and a £315m forecast on the StockReport.
Profitability: breakeven in terms of adj. continuing operating profit, but that’s before the impact of several items including a £25m write-off (impairment) of stock and intangibles.
The write-off is described as “non-cash” but if the company is writing down stock then the impact on cash flow is pretty clear: the company expects to make a loss on inventories that it previously intended to sell for profit.
There’s also a £10m charge for restructuring costs associated with a savings programme.
Net debt is expected to close the year at £135m, of which £30m are leases.
This is a major deterioration compared to June 2024, when net debt was £117m including leases.
Covenants: the leverage covenant for Dec 2024 moves to 5.5x EBITDA. The interest covenant moves too, and the March 2025 tests are also relaxed.
I think 3.25x is the “normal” leverage covenant here.
When things were really stressed in early 2024, VID’s banking syndicate moved it up 4.25x.
If they are now moving it up to 5.5x, I doubt the banks are at all relaxed about this. This is far beyond a level that banks are typically comfortable with.
The interest covenant (EBITDA/net interest) has also moved to an extremely loose level. The company is only required to earn an EBITDA of 1.25x its interest bill.
These will be interesting discussions:
Our Revolving Credit Facility is set to expire in August 2026. We are actively working with our lending banks to secure an extension or a refinancing during H1 2025, in addition to addressing necessary amendments to the February and March 2025 covenants. An update will be provided in Q1 2025.
The Executive Chairman seems to blame former management even more than he blames market conditions:
Since assuming my expanded role, I have seen significant opportunities within the business. However, it has to be recognised that there are areas where management processes, cost discipline, and contractual and commercial acumen require strengthening. These challenges were exacerbated in some areas by challenging market conditions. The new management team has identified the issues and is addressing them at pace.
Graham’s view
VID is now doing what distressed companies do: reducing discretionary spend, merging divisions, and cutting costs wherever possible. And its prices are going up in an attempt to improve margins.
With the bank temporarily allowing the leverage covenant to go to 5.5x, as demand seems to be very soft, I have no choice whatsoever but to keep this on RED. I think this company needs to raise more equity and that they should have done it yesterday.
But they already raised £125m of fresh equity a year ago, at 267p, in a move that was supposed to fix the balance sheet. So I also can't blame shareholders if they are reluctant to pour any more money into this. A dire situation.
Roland's Section
Filtronic (LON:FTC)
Up 4% to 75p (£163m) - Trading update - Roland - AMBER
Today’s half-year trading update is short but sweet for shareholders in this electronics business, whose biggest customer is Elon Musk’s SpaceX (Filtronic provides radio equipment used to link Starlink ground stations with its low-earth orbit satellites):
the Board now expects to deliver stronger results for the full year than current market expectations
Filtronic shares have already tripled this year. As I’m writing shortly after 8am, the shares are up a further 4%.
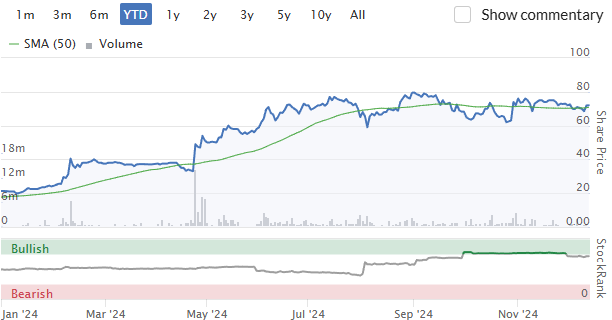
We last covered this electronics group on 31 October when the company included an “in line” update with its AGM Statement. So I think it’s interesting to try to deduce what might have changed in the relatively short period since then.
Today’s statement is truly very short. Here are the main points:
H1 trading: “significant growth in revenue and profits” for the six months ended 30 November 2024.
H2 trading: the company says customer demand is robust, with “the second half benefitting from pull-forward of customer orders”. Results for the year ending May 25 are now expected to be ahead of current market expectations.
If H2 performance will benefit from orders being pulled forward, this raises the risk that the subsequent H1 could suffer unless Filtronic can secure significant new contracts. We’ve seen this with Solid State recently.
Outlook: no upgraded guidance is included in today’s trading update, but fortunately we have an updated note from house broker Cavendish - many thanks.
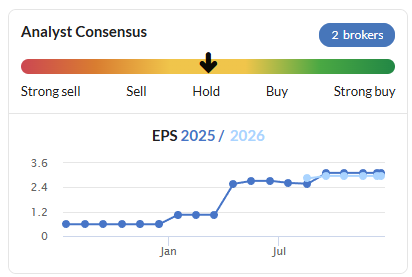
Cavendish’s analysts have upgraded their FY25 earnings forecasts by 25% to 4p per share, but have left FY26 forecasts unchanged at 3p per share.
These estimates seem to reflect the risk I’ve suggested above that Filtronics profits could fall next year, unless the company wins significant additional new business to offset the pull-forward of orders into the current year.
Based on a share price of 75p at the time of writing, these estimates put Filtronic on a FY25 P/E of 19, rising to a P/E of 25 next year.
Roland’s view
It’s still quite early in the company’s second half. Filtronic has shown strong momentum over the last year with some significant additional orders for power amplifier modules from SpaceX.
I would not rule out the possibility of the company maintaining this momentum to support further profit growth in FY26, but there’s no visibility on this at present.
I’m also encouraged by the evidence of operating leverage in the company’s financials as it’s grown over the last year - profitability has improved significantly:
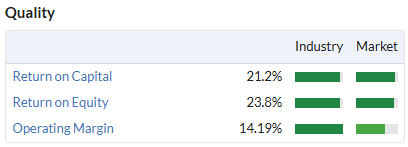
I’m broadly positive on the medium-term outlook for this business. But I think it’s fair to say that a reasonable amount of growth is already in the price at current levels. I am going to maintain our AMBER stance on this high flyer.
Saga (LON:SAGA)
Up 6% to 131p (£187m) - Saga and Ageas agree new insurance partnership - Roland - AMBER
Today we have confirmation of a partnership agreement between Saga and Belgian insurance group Ageas. This was first mooted back in October, when Paul covered the original announcement.
Saga shares have risen on today’s news, but we should probably remember that they were trading on an abnormally low forward P/E of 3.4 before the market opened.
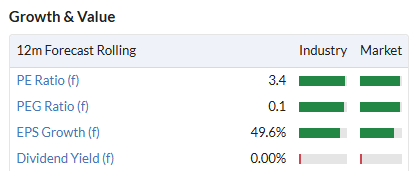
Having read through the details of the partnership, my feeling is that shareholders should not necessarily expect any immediate benefit. While a lot of cash is changing hands, I don’t think it will leave Saga with any surplus distributable cash.
Partnership structure: today’s agreement applies to home and motor insurance. Saga will sell its underwriting business to Ageas and enter into “The Affinity Partnership” – a 20-year deal with Ageas to sell home and motor insurance.
Saga will retain responsibility for the brand and direct marketing, while Ageas will take on price comparison website distribution, pricing, underwriting, claims and customer service.
Financials
Saga appears to be in line to receive significant cash consideration, relative to its sub-£200m market cap.
Underwriting sale: Saga will receive £65m from the sale of its underwriting business (AICL) to Ageas, plus a further £2.5m when operational readiness is achieved = £67.5m
Partnership consideration: Saga will receive “upfront consideration” of £80 million in two tranches.
The company will also receive contingent consideration of up to £30m in 2026 and the same again in 2032, subject to certain volume and profitability targets being met.
Saga will also receive commission payments based on an undisclosed percentage of the Gross Written Premiums generated over the term of the partnership.
My sums suggest the total consideration received by Saga as a result of this transaction could be £207.5m, plus commission.
However, these payments will be subject to the company’s accounts achieving a clean auditor report in July 2025 and to Saga securing refinancing for its £250m July 2026 corporate bond and for the £85m loan facility held with chairman Roger De Haan, which matures in April 2026.
I think this is a useful reminder of the relatively leveraged nature of this business. Saga also has c.£375m of secured cruise ship loans, on which the company is currently benefiting from relaxed covenants and deferred payments.
Use of proceeds: Warren Buffett’s vast investment empire has been built with the help of the huge pool of ‘float’ generated by his insurance businesses. That is, premium payments received upfront, ahead of any possible claims or payments to underwriters.
Today we see the impact of this business model when it’s reversed (my bold):
“Proceeds from the Affinity Partnership will principally be used to offset the working capital impact associated with the transition to the Affinity Partnership. SSL has historically benefited from a favourable working capital profile. This arises from customers making largely annual payments at the start of their insurance policy, which in the case of motor and home are then remitted to panel underwriters between 30 and 90 days later.”
In other words, while Saga expects to receive up to £140m in partnership consideration payments, this inflow will broadly be offset by working capital outflows as the company will no longer receive premium payments.
Arguably, the only real upfront outlay being made by Ageas is the £65m spent on acquiring Saga’s underwriting unit, AICL.
Of this, Saga’s management plans to hand back £22m to Ageas to gain control of the “the Enbrook Park property”, which is currently owned by AICL. This 27-acre site is Saga’s former corporate headquarters. It closed last year but according to the internet, is now rumoured to be lined up for a housing development.
The remaining £43m from the AICL sale is expected to be used for debt reduction and other general corporate purposes.
Impact on earnings: while costs will fall as a result of the partnership, Saga’s future income from home and motor insurance sales will be limited to an undisclosed level of commission.
The company will also forgo the profit from the AICL underwriting business. This business made an after-tax loss of £9.6m last year, but recovered to a profit of £13.4m during the six months to 31 July 2024. Ageas appears to be buying AICL at a point where cyclical conditions are improving.
Finally, Saga also expects to incur “one-off transition costs” of c.£25m. I’d imagine most of these will be cash costs, so they could absorb around half the remaining £43m surplus from the AICL sales.
Outlook: I don’t have access to any broker updates, but the company has provided some updated guidance today:
As a result of the above changes to revenues and costs during the Transition Period, SSL's underlying profit before tax is expected to fall in 2025/26 and then partially recover in 2026/27, before recovering to or exceeding 2024/25 profitability in the first full financial year following achievement of SSL's run-rate cost base under the Affinity Partnership.
For comparison, consensus forecasts prior to today suggested the following progression of underlying earnings:
FY24 actual: 30p per share
FY25e: 26.6p per share
FY26e: 37.6p per share
We’ll have to see how these forecasts change over the coming days/weeks.
Roland’s view
Saga already sells travel insurance and private healthcare through partnership arrangements. Today’s deal will complete the transition of the group’s insurance business to a capital light, marketing-focused operation.
Alongside this, the group will continue to operate its cruise ship and travel business.
My feeling is that the overall financial impact of transactions announced today will be broadly neutral over the next few years.
In particular, I think it’s disappointing that there doesn’t seem to be any clear path for accelerated debt reduction.
Saga shares remain deeply depressed and could be trading at bargain levels, on a P/E of 4.
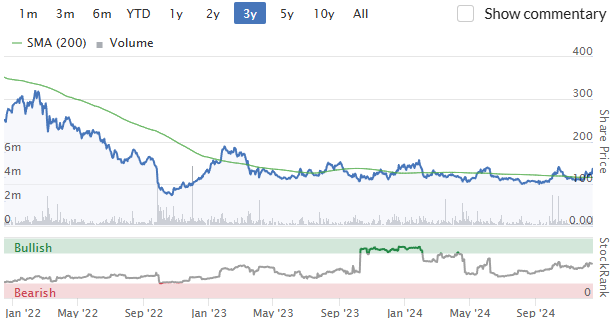
As far as I can see, the current consensus forecast for this year is likely to be underpinned by the cruise and travel business – this segment generated £54m of pre-tax profit over the 12 months to 31 July 2024.
However, I can’t ignore the debt risks here. Saga’s net financial debt was over £600m at the end of July 2024. H1 cash interest payments totalled £20m.
The completion of today’s transactions is also dependent on successful refinancing, perhaps a little earlier than might otherwise have been required.
On balance, I don’t feel I can take a strong view here without at least seeing Saga’s next full-year accounts and updated broker forecasts. I’m staying neutral for now. AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
Duke capital I find to be a really irritating share yes it pays a dividend but it never moves in price because it is always issueing new capital so I sold them a few years ago.SAGA I like because it does seem to be heading in the right direction and de leveraging a little bit at a time. Is it not less leveraged than the likes of Carnival so therefore a bettewr bet than them
On DUKE I think the idea is the move to 3rd party capital will mean they won't need to keep raising equity. However, I suspect it will take a while for them to gather sufficient assets to really move the dial in terms of earnings growth, so I will probably stay on the sidelines with this one.
I’m a relatively new holder of Duke Capital (LON:DUKE) but can’t help feeling the same way. I participated in the recent rights issue but will likely look to sell if the shares recover to around my average cost of 31p.
it looks like bitcoin would of been a much better investment this past few years than any uk stocks.
Plenty have outperformed bitcoin over 3 years, even some large caps.
Bitcoin price growth: 1 year +150%, 2 years +500%, 5 years: +1400%, 10 years: +40000%.
Nothing to see, just any other typical FTSE100 company :)
Rolls-Royce Holdings (LON:RR.) over 500% 2 years.
Bitcoin only 110% over 3 years? Rolls-Royce Holdings (LON:RR.) +400%.
Of course some smaller stocks have done better.
I hold Pennant International (LON:PEN) and today watched their recent IMC presentation and Q&A, which I found impressive.
Klaas van der Leest, the CEO of Intercede (LON:IGP) is a recent NED and minor shareholder. PEN has a blue chip client list to match IGP's, though I don't think they overlap heavily so perhaps there's synergy.
What are your thoughts Graham, on the mid-cap Nexxen International (LON:NEXN) ensuing delisting on the LSE and move to the NYSE? I watched its investor presentation on the Investor Meet Company site today and decided to sell my holdings. It was one of the dogs in my kennel, the reason for me to sell.
Hi Silver Moon, I covered NXN in August and Megan did in November. I was not a fan of that one. G
Thanks, there's no doubt that I read those coverages at the time and left things untouched as upward trending was going on, sort of. Since that time the trend accelarated thus saving me more than a few dog biscuits, although truth to say, a previous attempt to recover my situation still wasn't sufficient.
Jubilee Metals (LON:JLP) issues an operational update on 7 Nov 2024 confirming they were on track to reach copper production guidance of 5,850-7,500 tonnes for FY25.
Share price is down 21% on todays news: reports increased unplanned power outages in Zambia, significantly affecting its Roan operations, while the Sable refinery remains less impacted due to private electricity supply. Munkoyo and Project G mining operations are unaffected and stay on schedule. However, the company notes uncertainty regarding whether Q2 FY2025 production targets will be met, with further updates expected soon.
On its Large Waste Project, which contains over 260 million tonnes of copper-rich rock, the due diligence period extends to January 2025, and the acquisition cost reduces from $30 million to $18 million, with $11.5 million still payable by December 2025. On track to complete the final due diligence by the new deadline.
Additionally, the company issues 2.7 million new shares at a price of 1 pence per share following an exercise of options. This issuance represents a 0.09% increase in Jubilee’s total share capital.
I'm wondering if viewed on a longer term outlook, could this be a buying opportunity with a potential to multibag? Does the upside outweigh the risks? Or do you think the SP has further to fall?
The following summary of Keelan's excellent recent article on 13 Nov 2024 might be appropriate:
Copper Operations in Zambia:
Sable Refinery Expansion:
Challenges and Share Price Decline:
Recent Turnaround Efforts:
Operational Recovery:
Momentum Building:
Broker Optimism:
CEO’s Outlook:
Macro Trends Supporting Copper:
Risks and Opportunities:
Tagging. I see every stock on the list has been tagged today, this is not how it was done previously, usually only stocks that have reviewed got tagged. Think there needs to some consistency. I favour only reviewed stocks being tagged, this makes searching easier.
Rusty, I'm aware of this issue - I fix the tags every day when I finish writing the report and I know for sure what's in it! Good to raise it though. G
I prefer that they are all tagged, much easier than having to click through to see basic info like P/E etc. I did give feedback to Stocko a couple of years ago that it would be a cheap win to allow the basic info popup that you get elsewhere by hovering over a linked company name as happens on many other screens; must be some technical reason preventing it?
But then if you use search, you will get lots of tags and then spend time looking for why they have been tagged. Some members the other week, could not find a tagged stock, because it was buried in the text. I often search for the last full review on a stock. More tagging will make this even more difficult than it is now.
Agreed - nothing worse than trying to find the latest research on a stock only to find they were purely named as a competitor in another companies research analysis.
Ok got it, I incorrectly thought we were referring to the Securities mentioned list down the right hand side. Agree for searching it makes sense to only include those with a report.
Back to Ricardo (LON:RCDO) again, I reckon that they have swapped £123m of revenue making £23.5m for £25.8m revenue making £7.3m. Allowing for the cash left over of £16m and assuming that it can be invested in a similar business that adds a further £8.1m revenue and £2m profit. The whole exercise has cost the company over £14m of operating profit out of a total of c£40m in 2024. It might be the right thing to do strategically, and maybe the market was aware of the anticipated reduction in defence to come, but that is a huge headwind to face over the next couple of years. Even if this transaction was flagged a while ago, I am surprised that the shares are not falling today.
Sound levels were fine on apple, great podcast to start the week!
I really enjoyed the new podcast. I realise that I’m in a minority but I prefer reading the transcripts on most podcast. Thanks for providing one.
Does stockopedia do podcasts......link
Hi jmallin - we do now, yes. You can currently find them:
I'm also working on adding video episodes to YouTube going forwards, so it'll be accessible there and on YouTube Music.
If you don't have either of those platforms, you can listen to it here: https://zencastr.com/z/Of4DqrR...
UK's Saga (LON:SAGA) rises after underwriting business sale, partnership with Ageas
** Shares of Saga SAGA.L up 5.3% at 130.2p
** The British holiday group enters into a 20-year motor and home insurance partnership with UK units of Belgium's Ageas AGES.BR
** Ageas will pay Saga 80 mln pounds ($101.04 mln) upfront under the partnership and acquire its Insurance Underwriting business for 65 mln pounds, Saga said
** Ageas will take on price-comparison website distribution, pricing and underwriting, claims and customer servicing activities, while Saga will retain marketing responsibilities
** SAGA shares down ~11% YTD
Saga ( LON:SAGA) I hold
I would love to know the impact on the company’s financial forecasts of today’s announcement but Numis + Peel Hunt do not make public. So if anybody here can throw any light, I would really appreciate.
I recall that there is some negative working capital offset with the underwriting division so debt reduction not as clear cut.
I keep an eye on their 2026 bonds which are trading circa 95.5 ( middle) which does not seem to flag any distress
Optically on Stockopedia forecasts, look very cheap on an earnings basis and does not appear any forecast changes picked up by Stocko in recent months
We have the Canal+ SA (LON:CAN) IPO today.
There has been a dearth of IPOs for the past year or two. I thought it would be interesting if the Stocko team could give their opinion on it. Spinoffs are often good opportunities. Does this fall into that camp? I had an initial look at the prospectus but it didn't scream "great value" to me.
Canal+ was down 20% yesterday
Videndum (LON:VID) . Another company having a tough time with revisions required to banking covenants and yet what did they announce on November 5th..........a share buyback! Surely, a risky and futile exercise in the circumstances.
As someone who doesn't have Spotify or apple, any chance of a neutral version, YouTube, acast for instance.
I hope that not too much time gets spent on this diversification as I use a desktop pc and don't involve myself with watching Spotisfy or Apple Podcasts.
I have both and look forward to watching regularly. Another great addition to the offering. Thanks, Team.
I second your comment Gloucesterbob. I don't have either either.
You can get Spotify free, although you may get some adverts. I only use the free version.
Hi Gloucesterbob and Threepeat - I'm working on getting it onto YouTube and YouTube music. For now, you can listen here: https://zencastr.com/z/Of4DqrR...
Is it just me or is anyone else scratching their head over the disposal of the defence business by Ricardo (LON:RCDO) ? They appear to be selling a business with £123m of revenue making £23.5m of profit (60% of Group profit!) at an operating margin of 19% for £67.5m. They mention the upcoming end of the ABS retrofit program, but to sell at this price must mean they expect sales to fall off a cliff in the medium term despite the buoyancy of defence markets right now. The earnings dilution could be painful even if today's simultaneously announced acquisition is a good one. I don't hold.
Thanks for the podcast guys I enjoyed it. However please could you up the volume levels? Lawrence and Roland are very softly spoken and even on top volume I could hardly hear them especially with outside noise . That’s my only complaint though and the content was excellent. Thanks
Yes, I agree; the content was great, but the sound levels were off. I found Lawrence to be really quiet, whilst Graham was very loud.
Thanks for the podcast though, it’s sure to become a regular weekly listen.
I found the volume level to be fine, l had mine on about 2/3, on Spotify. Lawrence is a bit quieter though.
I'm glad I'm not the only one with volume issues. I did email Lawrence and raise this issue. Maybe it just Spotify?
Hi all - thanks a lot for all the feedback, really appreciate it. We couldn't hear any issues like this when we were listening back, but it's been a common thread of feedback. I'm going to spend some time this week getting to grips with this to stop it being an issue going forwards.
A JV announcement from Henry Boot (LON:BOOT) this morning - though what it amounts difficult to say but certainly looks interesting. Any thoughts, Graham ?
https://newsfile.refinitiv.com...
Good morning Graham, you looked at XLMedia on the 21st October and thought it might look interesting at 12.88p with some caveats, if you have time to read it, does today's update change your opinion? They expect to make a £16 to £20 million tender offer to shareholders in the New Year. We are long term sufferers, I'm not complaining as we've had profit along the way but it's been in our dogs portfolio for a few years now and I'll be please to see it put down.
Thanks for the suggestions JASVFS, perhaps I'll be able to write a short section on this one. A shame that it has had to end like this. G
Filtronic (LON:FTC) "ahead of expectations" update. Should see a 10% uplift. I hold.
According to Ed's article last week, we should see some good drift upwards over the next few months.
At the moment 2026 forecasts are slightly lower than 2025, hopefully there is more visibllity to bolster the former.
As doctordave says - Filtronic ahead of expectations just as Synectics (LON:SNX) did last week - both members of the "clearest trending small caps" list.
Clear trending stocks tend to have strong "earnings surprise" history, which often repeats itself. Just as "profit warnings come in threes" on the downside, "ahead of expectations" tend to come serially on the upside. After first day jumps, prices often drift in the direction of the surprise.
Impossible to tell what will happen with Filtronic, but the model for how to think about these scenarios (on average) is in my article last week ( "Ahead of expectations").
Filtronic (LON:FTC) "ahead of expectations" update. Should see a 10% uplift
if it’s a pull forward of orders from next year, as reported, then it might be stealing from the following year’s profit. This thought might explain the muted reaction to what seems a bullish report.
Looking at broker notes this morning BnB whilst they have upgraded this year to 4p eps they have left next year flat at 3p eps so suggesting negative growth for FY26? Don’t follow Filtronic (LON:FTC) particularly closely after I missed the big rise having called that very wrong but I can’t get particularly excited on a PER of 25 as I don’t really understand where the earnings growth is coming from medium term. Would be good to hear why the bulls think this will continue growing and why the brokers seem to be calling 3p EPS the next couple of years baseline?
Hi David. I attended the Filtronic presentation at Mello and was impressed with the recent success riding on Musk's coattails. But I found it uninvestable (under my methodology) based on the unforecastable lumpiness of orders and the reliance on a single customer. The time to buy was when orders started picking up and stood in stark contrast to earlier performance. Growth may well persist and I wish holders well, but the odds of disappointment have dramatically increased, weakening the investment case (for me). One I missed and well done to those who profited.
Filtronic (LON:FTC) has a major constraint irrespective of demands for their products. Most of their current staff are in their 40's and 50's and have been there since inception. Hence, they would be suitably qualified and experienced.
There are insufficient RF engineers mainly due to the lack of a syllabus at degree level for Electronic Engineering to cover RF technologies in detail. This I find astonishing.
They have opened a research lab in Cambridge Science Park with about a dozen employees. They are hoping to capture some of the graduates and are promoting RF technologies with the academic staff at the university.
In the longer term, this may address this problem. However, the demands from Space X is very dynamic and they require a quick turnaround. The company has managed so far met these demands but unsure if this will becomes a burden in the future. Filtronic (LON:FTC) are growing with other contracts being granted so as long as they keep their heads above water, I see Filtronic (LON:FTC) has a bright future.
I hope we see some further strength. I've come close to selling this with my -20% stop loss rule but held on, just......