Daily Stock Market Report (Mon 27th July 2026) - PINE, QTX, VOD, PHAR/SQZ, SWG, VSVS, EMAN, CWK

Oil: there have been two nights in a row without any US attacks on Iran, and Iran for its part has said that it has stopped retaliating. The US Ambassador to the UN says that President Trump is “giving the talks some space”. It seems that negotiations are taking place behind the scenes.
The financial result of all this is a nice big drop in the oil price to start the week, down about $6 compared to where it was last Friday morning. It’s still about $17 higher than it was before the conflict started.
Stocks like the news too, with the S&P 500 set to open up by 1%, and the FTSE also due to tick higher this morning.
Shein: the Chinese “fast fashion” company, headquartered in Singapore, is preparing to IPO in Hong Kong. The timetable is unclear yet, but this should be of interest to Boohoo/ASOS fans. The company’s latest filing shows that it swung to a quarterly loss after the US increased duties on small imported packages. The EU has just done the same thing, in a move that was clearly (in my view) targeted at companies like Shein and Temu.
Overnight market movements:
The FTSE is up 0.3% at 10,770
S&P 500 is up 1% at 7,480
Brent crude (October) is down 5% at $87.10/bbl
Gold is up 1% at $4,090/oz
Bitcoin is up 1.3% at $65,450
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£197bn | SR65) | H1 revenue +9% to $30.7bn with adj EPS +12% to $5.21p. “Double-digit growth in Oncology and Rare Disease offsetting headwinds from Farxiga US loss of exclusivity and China volume-based procurement”. Outlook: FY26 guidance unchanged for adj EPS growth of “low double-digit” percentage. | ||
Vodafone (LON:VOD) (£26.4bn | SR87) | Service revenue +5.2% with adj EBITDAaL +6.2%. Total revenue +9.7% to €10.3bn, reflecting consolidation of Three UK. Outlook: expect to deliver the upper end of revised FY27 guidance (adj EBITDAaL €13-13.3bn, adj FCF €2.6-2.9bn). | AMBER/GREEN = (Roland) Today’s upgrade to FY27 profit guidance was expected by the market. It reflects the recent acquisition of a controlling stake in M-Pesa owner Safaricom, rather than any outperformance in recent trading. Despite this, I think this is a solid trading update, with positive growth in organic service revenue (a key measure) across the group’s core operations. While returns on capital still need to improve, I think Vodafone is moving in the right direction and remains reasonably valued. I’m happy to remain broadly positive here. | |
DCC Energy (LON:DCC) (£5.4bn | SR94) | The DCC board is recommending a KKR-backed cash offer that will see DCC shareholders receive up to 6,797.22p in cash. This represents a premium of 24% to the undisturbed price of 5,380p, prior to bid speculation emerging. | TAKEOVER | |
Tritax Big Box REIT (LON:BBOX) (£4.6bn | SR57) | Planning secured for 107MW Manor Farm data centre, together with an accelerated route to power delivery. The project is targeting a 9.3% yield on cost and a pre-let agreement is with solicitors. | ||
Cranswick (LON:CWK) (£3.0bn | SR69) | Q1 revenue +5.5%, driven by volume growth of 8.2%. LFL revenue +4%, with LFL volume +6.4%. Strong UK demand with lower export sales. Outlook: FY27 trading 2027 remains in line with expectations. | AMBER/GREEN = (Graham) [no section below] This meat producer is a little pricier than it was when Roland looked at it in May but the company has been a classs act for many years and I wouldn't be particularly concerned about the current P/E multiple of 17x, given the track record here. Today's update shows modest like-for-like revenue growth of 4% as lower input prices were passed onto customers. Volume growth is significant and capital investment plans remain on track: this company has proven expertise when it comes to capital allocation, reinvesting for compound growth over many years. | |
Vesuvius (LON:VSVS) (£1.12bn | SR83) | H1 trading profit expected to be c.£74m. Operational issues in the Steel division are continuing to impact performance. Advanced Refractories is also seeing “a challenging trading environment”. Outlook: now expect FY26 trading profit to be “slightly ahead” of FY25. | BLACK? RH note: previous consensus was for 9% adj EPS growth in 2026, so I’m fairly sure this represents a cut to guidance. | |
Serica Energy (LON:SQZ) (£1.00bn | SR90) | The Pharos Energy (LON:PHAR) board has withdrawn its recommendation of the Ratio offer and is now recommending the Serica acquisition to shareholders. | TAKEOVER (AMBER/GREEN =) (Roland) [no section below] | |
| Pinewood Technologies (LON:PINE) (£363m | SR30) | Friday 24/7 pm: Joint Statement regarding a possible offer | Ridgeview Partners (private equity) has made a non-binding cash offer for Pinewood of 448p per PINE share. This is a 43% premium to the undisturbed closing price on 23 July. | TAKEOVER (Roland) On a near-term view this offer seems quite fair, but zooming out to FY28 and beyond suggests to me that this offer may not be that generous. Unfortunately for disappointed private investors, I suspect that the support of nearly 49% of Pinewood’s existing shareholders – including its main US customer – means this could be a done deal, assuming Ridgeview makes a firm offer. |
Aston Martin Lagonda Global Holdings (LON:AML) (£361m | SR37) | In response to investor questions, the company confirms that the £550m debt financing announced on 22 July is secured against certain assets in a new subsidiary plus “certain other assets of the group”. Additional details are also provided regarding the security of the Senior Secured Notes due 2029. | ||
Big Technologies (LON:BIG) (£296m | SR43) | H1 revenue +6%, with ARR +5% to £53.2m. H1 adj EBITDA +14% to £14.2mn, with adj FCF +42% to £9.6m. Outlook: “well positioned for further growth in H2 2026 and beyond” following various new contract wins. | ||
Science (LON:SAG) (£239m | SR92) | H1 revenue -17%, due mainly to a reduction in low-margin defence revenue. Adj op profit +2% to £11.5m. Adj EPS +6% to 20.4p. 2026 share buyback expected to exceed £20m. Outlook: board expects “sequential period growth” in H2, mainly driven by the Services division. | ||
Mkango Resources (LON:MKA) (£149m | SR2) | Commissioning of finished magnet production equipment targeted for H1-2027, ahead of fully integrated U.S. operations in Q2 2028. | ||
Quartix Technologies (LON:QTX) (£123m | SR64) | H1 revenue +125 to £19.4m with pre-tax profit +21% to £4.8m. EPS -15% to 5.52p due to higher tax charge. KPIs: ARR +11% to £38.9m with fleet customers +6% to 33,550. FY26 Outlook: “confident in delivering market expectations” (Adj EBIT of £10.1m and free cash flow of £4.9m). | AMBER/GREEN = (Graham)
I’m inclined to think that this offers decent value at 14x next year’s forecast earnings. I think it comes down to whether you view the prospective revenue growth rates are sufficiently appealing, and how you think Quartix will be able to handle ongoing deflation in the telematics business. Personally, I don’t have a strong conviction in the answers to these questions, but I am leaning towards a positive view: I think the current double-digit revenue growth is not to be sniffed at, for what is now a reasonably mature business. As for our stance on the stock, I agree with Roland’s previous AMBER/GREEN. | |
Aoti (LON:AOTI) (£93m | SR39) | H1 revenue +10% to c.$35m with underlying revenue +18% excluding the discontinued Arizona Medicaid business. Net debt of c.$6.3m. | ||
Zephyr Energy (LON:ZPHR) (£79m | SR30) | Signed non-binding LOI with Atlas Oil Company for up to $15m of non-dilutive pre-production financing for the Paradox project. The funding would be in the form of a prepaid commodity purchase agreement and sale of hydrocarbon marketing rights. Repayment of proposed funding would be through future production sale proceeds. | ||
Helix Exploration (LON:HEX) (£71m | SR10) | Matthew Ciardiello is appointed CFO with effect from 31st July. He currently leads Anexus CFO, the fractional CFO servicer for clients in the natural resources sector. | ||
Everyman Media (LON:EMAN) (£46m | SR58) | Admissions up 20.5% to 2.6m. Adj. EBITDA +32% to £10.8m. “While trading performance has been positive for the first half, the Directors retain a degree of caution for the full year outlook due to the challenging economic environment and the significance of Q4 trading to the overall annual performance of the Company.” Directors considering investment projects that would generate long-term returns but affect H2 profitability. Continues to engage with stakeholders on the Delisting of the Company. | RED = (Graham) [no section below] I find it both impressive and surprising that the market cap here has increased since I looked at it in June - despite the threat of a delisting. Ordinary investors need an unusual degree of conviction to stay invested here. As for today's update, it's a strange situation where positive trading figures are accompanied by very cautious commentary. Directors who collectively own 45.6% have expressed a desire to delist it - could this be one of those instances where a company delists just before it starts to succeed? Either way, I'll stay RED on this as I've been consistently very negative on the company's financial prospects and even if I'm wrong about that, a delisting is on the cards. | |
iFOREX Financial Trading Holdings (LON:IFRX) (£43m | SR31) | H1 revenue $27m (H1 last year: $27.6m). Adj. EBITDA $4.2m at constant currencies, in line with Board’s expectations. Actual adj. EBITDA only $2.4m due to the strength of the Israeli shekel. Taking a cautious approach to FX rates for the year. Accordingly, due to exchange rates, full year operational costs are expected to be c.$2 million higher on a US Dollar basis than previously expected at the start of the year. | ||
80 Mile (LON:80M) (£40m | SR8) | Placing to raise £1.9m before expenses at 0.67p, 10% discount to Friday’s closing price. The Company held high-level talks in Nuuk last week with regulatory and oversight bodies and is pleased with the status of permitting and support shown for the Jameson project | ||
Tortilla Mexican Grill (LON:MEX) (£28m | SR n/a) | FY December 2025: revenue +8.5%. Net loss after tax £15.1m. Adjusted EBITDA down 76% to £1.1m. Strong UK trading momentum in the first half of 2026. UK LfL sales +13.9%. | Shares currently suspended. | |
Gana Media (LON:GANA) (£24m | SR2) | “The tournament has been a resounding success for Gana and the progress we announced on 22 June continues to compound across many key metrics for the business, and whilst the World Cup left us just a few days ago, we are already seeing the pace of growth continue… Q3 is set to be a period of significant growth potential.” | ||
Pathos Communications (LON:NEWS) (£18m | SR N/A) | H1 revenue up 14% to $7.3m. H1 adj. EBITDA +31% to $1.7m. Overall performance in line with Board expectations, and confident in meeting market expectations for the FY 2026. | ||
Zinc Media (LON:ZIN) (£17m | SR34) | Headwinds in the market may impact the delivery of some large productions due in H2. Three secured FY26 projects have started later than anticipated pushing £5.5m of previously secured H1 revenue into H2. In addition, £5m of revenue originally anticipated for FY26 has been delayed into FY27. | BLACK? Share price only down 2%. | |
RTC (LON:RTC) (£11m | SR90) | Revenue down 6% to £45.2m. Profit from operations £0.8m (FY25: £1.3m). EPS 4.21p (FY25: 6.62p). Outlook: “The Group's order book remains resilient, and during the period we secured six significant contract wins and extensions, including long-term agreements with key clients… well placed to benefit from improving activity levels.” | ||
Shearwater (LON:SWG) (£11m | SR50) | FY June 2026: revenue and adjusted EBITDA are now anticipated to be ahead of market expectations with expected revenue of c.£42m, up 33%, and expected adjusted EBITDA of £2.5m, up 41%. Enters FY27 with positive momentum. Market expectations were revenues of £35.5m, adj. EBITDA £2.4m. | AMBER/GREEN = (Roland) Today’s update shows a significant revenue beat for FY26, but only a smaller EBITDA beat, indicating costs may have risen faster than sales. Despite this, momentum does seem positive here and the FY27E P/E of 10 falls to a single-digit multiple when the group’s large net cash position is considered. On balance I’m happy to maintain Mark’s previous broadly positive view today, with the caveat that this is an illiquid micro cap with a very mixed record of profitability. |
Graham's Section
Quartix Technologies (LON:QTX)
Down 2.5% at 246.7p (£120m) - Interim Results - Graham - AMBER/GREEN =
Quartix Technologies plc (AIM:QTX), a leading supplier of subscription-based vehicle tracking systems, analytical software and services, is pleased to announce its unaudited results for the half year ended 30 June 2026.
We’ve been following this telematics company for a long time. Unfortunately it has been several years since the share price saw a new high:
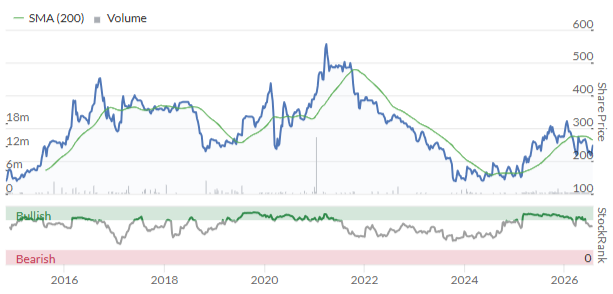
In April, Roland lowered our stance on Quartix to AMBER/GREEN on signs of slightly slower customer acquisition in Q1, although the trading update at that time was in line with expectations.
Today’s interim results again say that the Board is “confident in delivering market expectations for the current year in respect of revenue, Adjusted EBIT and free cash flow.”
This continues the recent trend of stable EPS forecasts, which previously saw a nice upgrade cycle:
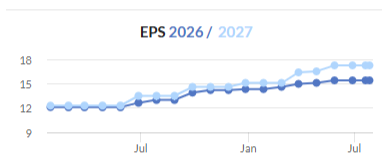
Turning to the H1 highlights:
Revenue +12% (£19.4m)
Adj. EBIT +21% (£4.9m)
PBT +21% (£4.9m)
Note the very clean conversion from adjusted EBIT to statutory PBT: no funny business and no significant finance charges.
Cash on the balance sheet is £4.8m, with no borrowings.
That cash balance has fallen since December 2025 (£5.6m), so it’s worth checking why. The reason is clear from the cash flow statement: dividends paid of £3.6m, which exceeded free cash flow (£3m).
Dividends continue to increase, with a new interim dividend of 2.7p (interim dividend last year: 2.5p).
Turning to Key performance indicators:
Annualised recurring revenue + 11% to £38.9m
Fleet subscription base (number of vehicle tracking units) +7% to 343,000.
ARR per vehicle up 3%
In simple English: there has been a modest 3% increase in pricing per vehicle tracked, combined with 7% growth in the number of vehicles tracked. The 3% pricing increase includes an inflationary price adjustment plus an upsell to dashcams.
Chairman comment (Andy Walters is also the largest shareholder):
"The Group has delivered a strong financial performance in the first half, with solid growth in revenue, profit and free cash flow. This reflects the strength of our subscription‑based model, disciplined pricing and increasing upsell momentum across our customer base. The second half has started well, and with targeted investment in our upsell capabilities and customer acquisition we look to the remainder of the year and 2027 with confidence."
Estimates from Cavendish have been reiterated and include:
Revenue growth of about 13% this year and 8% next year.
Adj. PBT of £10.1m this year and £10.9m next year.
Adj. EPS of 16.3p this year and 17.6p next year.
Graham’s view
I’m inclined to think that this offers decent value at 14x next year’s forecast earnings.
There have been concerns in the past around telematics pricing: the technology is getting cheaper all the time, and this has undoubtedly held back revenue growth at Quartix.
In the short-term, however, pricing is standing firm and is even rising a little.
If the stock was priced in SaaS terms, it would be very cheap at only 3x ARR.
Considering the deflation in the sector, however, it’s probably more logical to value it on a multiple of earnings.
The positives: it offers excellent quality metrics (see below), and I have no concerns about the balance sheet or management. It’s always reassuring to have the founder and major shareholder at the top of the company.
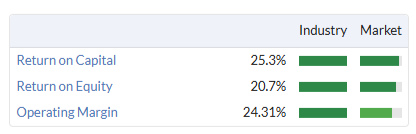
The question marks: I think it comes down to whether you view the prospective revenue growth rates are sufficiently appealing, and how you think Quartix will be able to handle ongoing deflation in the telematics business.
Personally, I don’t have a strong conviction in the answers to these questions, but I am leaning towards a positive view: I think the current double-digit revenue growth is not to be sniffed at, for what is now a reasonably mature business.
As for our stance on the stock, I agree with Roland’s previous AMBER/GREEN.
Vesuvius (LON:VSVS)
Down 13.5% at 391p (£970m) - Trading Statement - Graham - BLACK (AMBER/RED ↓)
This brief trading update has caused quite a blow to the Vesuvius share price:
Trading profit for H1 2026 is expected to be c. £74m. Since our trading update on 28 May 2026, we have continued to be impacted by operational issues in our Steel division. Additionally, Advanced Refractories is experiencing a challenging trading environment, particularly in Europe. The operational issues, whilst temporary, are causing a greater impact than previously anticipated. They are being addressed and are expected to be resolved by the end of the year. Accordingly, we now expect full-year trading profit to be slightly ahead of trading profit for FY25 on a constant currency basis.
For context, trading profit last year (FY December 2025) was £151.1m.
Trading profit is what Vesuvius calls adjusted operating profit.
Checking last year’s results, I see that FY25 was itself a pretty poor year, compared to what the company had previously achieved. They said that 2025 was a “challenging year with difficult end market conditions, particularly in EU+UK”.
In their outlook statement, they predicted that 2026 would “mark a transition to recovery in the Steel and Foundry markets, with, in particular, the impact of trade protection measures in Steel starting to have a meaningful impact on our Steel markets as from the latter part of the year”.
Unfortunately, that recovery has not materialised, as the “extended weakness in our end markets” has continued.
Graham’s view
This is not a stock I look at very often. The last time appears to have been a trading statement in May 2025, when the market cap was £930m (today: £970m).
At the time, I kept our neutral stance unchanged, noting very limited growth.
Going into today’s trading update, the market was only expecting the company to achieve modest revenue growth of about 3% in the current year. It seems that this will now not be achieved.
The way that I mentally categorise VSVS is as a very heavy industrial stock: it’s a “global leader in molten metal flow engineering and technology”, providing various products to foundries, furnaces and other industrial processes.
These stocks typically do not trade at high multiples. In the case of Vesuvius, it was at 11x last night:
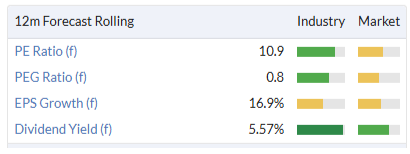
I think that trading profit was supposed to grow at c. 14% this year. If instead we only get 1% growth, that’s a c. 11% cut to the earnings forecast. So I think the 13% drop in the share price is fair.
As for our stance on the stock, I will turn AMBER/RED in the short-term, consistent with our philosophy that profit warnings are often followed by more profit warnings. Although fundamentally, on a long-term view, I do think that the current valuation is probably fair. This stock does not excite me very much, I must admit!
Roland's Section
Pinewood Technologies (LON:PINE)
Up 34% at 421p (£484m) - Joint Statement Regarding a Possible Offer - Roland - TAKEOVER
This RNS statement from automotive dealership software group Pinewood.AI was actually published at 6.45pm on Friday, well after the market closed. Here are the key details:
Bidder: Ridgeview Partners LLC, a US private equity firm founded in 2024
Possible cash offer of 448p per PINE share (valuing Pinewood at c.£545m)
Major shareholder support: shareholders representing 48.7% of Pinewood shares have indicated their support for the offer. Supporters include Lithia Motors (NYQ:LAD) (31.95%), the dealership group that purchased Pinewood’s UK dealers (Pendragon) and with which it is working closely in the US.
Possible rollover alternative: if the offer proceeds, shareholders wanting to remain invested would be offered the chance to retain an interest in a Cayman Island company incorporated for this purpose. This would be subject to various constraints and limited to c.£250m of Pinewood shares. Friday’s RNS notes that shareholders “would have limited information rights” unless they held a 25% interest. In other words, any private investors choosing this option would probably be kept in the dark regarding performance and would likely be unable to sell their shares until Ridgeview decided to sell Pinewood. 32.8% of shareholders are reported to have indicated that they would choose the Rollover Alternative. I would speculate that this might include Lithia.
A done deal? Given the level of support from major shareholders, I think this offer is almost certain to succeed, assuming Ridgeview decides to make a firm offer.
It’s certainly true that a cash offer of 448p represents a significant premium to the recent share price:
43% premium to the undisturbed closing price of 314p on 23 July 2026;
53% premium to the volume-weighted average price of 293p over the last month;
64% premium to the volume-weighted average price of 274p over the last three months.
However, 448p is a number that shareholders have seen before over the last year:
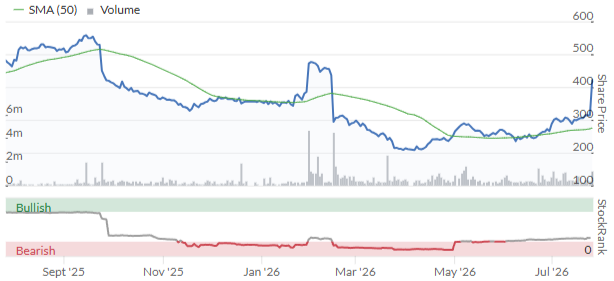
Pinewood shares topped 500p last year when the company issued a solid set of half-year results and optimistic-sounding medium-term profit guidance for FY28.
Failed 500p bid: despite this, broker forecasts were trimmed and the stock drifted lower until the start of 2026, when private equity group Apex Partners was in discussions with the firm regarding a possible offer of 500p per share.
Unfortunately, Apex decided not to make an offer in February “in the light of the prevailing challenging market conditions”.
Shortly after this, Pinewood issued a profit warning:
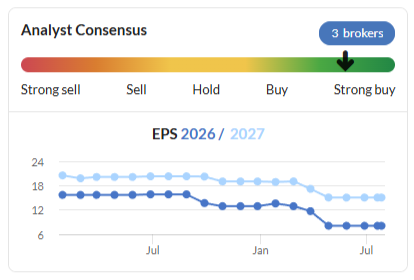
That brings us to the end of last week.
Is 448p a fair price?
Ridgeview’s possible cash offer of 448p is more than 10% below the failed Apex bid. Is this a fair price, given the decline in near-term profit expectations since the start of this year?
Broker Zeus has been publishing its coverage on Research Tree, making it the only one of Pinewood’s brokers whose coverage is available to private investors.
The latest Zeus forecasts are from April, when the company cut its estimates to reflect the company’s latest guidance on implementation timing:
FY26E adj EPS: 8.1p
FY27E adj EPS: 14.3p
FY28E adj EPS: 31.0p
Friday’s possible offer thus values Pinewood on a FY26E P/E of 55, falling to a FY28E P/E of 14.5.
Roland’s view
Based on my simplistic review above, I would say that the fairness of Ridgeview’s offer depends on how confident investors are that the company can achieve current FY28 forecasts.
This is purely speculation, but I wonder if this offer is as much about Lithia as it is about Ridgeview. As a reminder, Pinewood is currently rolling out its systems across Lithia’s US dealership business (>300 dealers nationwide).
If (as I am guessing) Lithia accepts the rollover offer, it might be able to secure a 25% interest in the unlisted business, giving it a seat on the board together with a supportive private owner who has purchased the business at what I’d suggest is a very reasonable price.
Pinewood could then get on with its rollout, away from the public eye, before being refloated or sold to another owner in a few years when earnings could be significantly higher, generating a nice return for both Lithia and Ridgeview.
Once again, this is only speculation on my part.
What does seem true to me is that this offer is likely to succeed, potentially without much competitive pressure.
I can imagine that shareholders with confidence in the long-term prospects of the business may feel short changed by this bid and I have some sympathy with this view.
While I think there’s some risk the large-scale US rollout could take longer than expected, fundamentally I think this looks quite a nice business to own. Once installed in a large dealer network, I’d imagine Pinewood’s software will be very sticky and could generate high-margin recurring revenues.
Unfortunately, it probably doesn’t much matter what retail investors like us think – a small number of large holders are likely to decide the outcome of this situation.
Vodafone (LON:VOD)
Up 4.5% at 120p (£27.1bn) - Q1 FY27 Trading Update - Roland - AMBER/GREEN =
The headline from today’s first-quarter update is that FY27 results are expected to be at the upper end of guidance.
The reality seems to be that while Q1 trading does look healthy to me, today’s upgrade was already expected and is being driven by the company’s recent acquisition of a controlling stake in its Kenyan Safaricom business for €1.36bn. Safaricom owns the M-Pesa mobile money business, in addition to its mobile network operations.
Today’s updated FY27 guidance includes specific information on the contribution expected from Safaricom this year, now that it’s fully consolidated into the group’s accounts.
Here’s a summary of Vodafone’s Q1 performance (April-June 2026):
Total revenue up 9.7% to €10.3bn, with 5.2% organic growth and an additional contribution from the full consolidation of Three UK (Vodafone now owns 100% of this former JV)
Adj EBITDAaL +6.7% to €2.9bn (+6.2% organic)
Operating profit: rose by €2.9bn to €3.9bn for the first quarter, but this is mainly due to an accounting gain arising from the Safaricom transaction. In this case, I’d say Q1 adj EBITDAaL growth is a more useful metric of performance (despite the horror of this heavily-adjusted metric!).
Divisional performance:
Germany: service revenue rose by 1.2% (Q4: 1.3%) in the group’s largest single-country market. Management reports higher wholesale and fixed line revenue, reflecting growth in consumer broadband average revenue per user and in business services. Mobile remains under “competitive pressure”.
UK: organic service revenue +0.6%, excluding the benefit of the consolidation of Three UK. Continued momentum in Consumer Broadband and Business fixed line services.
Other Europe & Turkey: organic service revenue +1.0%, aided by strong business growth.
Africa: continued double-digit service revenue growth, with Q1 +12.6% (Q4: +10.9%). Strong growth in both connectivity and financial services.
Business service revenue: corporate customers are a key growth target for the business. Organic service revenue in this division rose by 5% in Q1 (Q4 +3.2%), “with high double digit-growth in digital services due to strong demand for our SaaS2, IoT and cloud & security products.”.
Outlook
Our guidance for the year now includes the impact of consolidating Safaricom with Group Adjusted EBITDAaL expected to be €13.0 - €13.3 billion and Adjusted free cash flow expected to be €2.6 - €2.9 billion. We now expect to deliver the upper end of our updated Group guidance ranges.
Consolidating Safaricom from 1 July is expected to add €1.1bn to EBITDAaL on a nine-month basis. This acquisition isn’t expected to have any impact on group free cash flow.
Vodafone’s previous FY27 guidance was for adj EBITDAaL of €11.9-12.2bn, so we can see that today’s increase is entirely due to the additional contribution from Safaricom. There seems to be no change to the expected performance of the remainder of the business.
Roland’s view
I was broadly positive on Vodafone in May and am going to retain that view today. While the shares are not quite as cheap as they were a year ago, I think the valuation remains reasonable – today’s free cash flow guidance equates to a FCF yield of c.9%, albeit this is an adjusted figure.
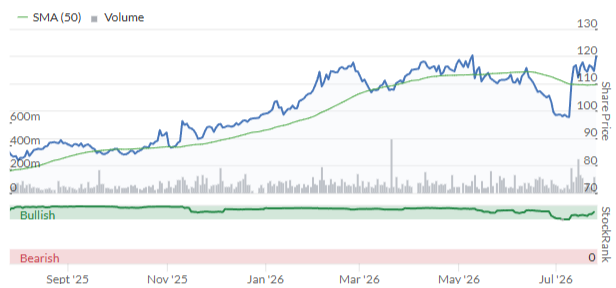
More broadly, I think the business is moving in the right direction and that CEO Margherita Della Valle may yet achieve her goal of improving the group’s return on capital.
Of course, as things stand ROCE remains far too low to cover the group’s cost of capital – failure to improve this over time could see equity value erode, as has happened in the past:
Another possible concern is that net debt is expected to remain relatively high, in a range of 2.25-2.75x adj EBITDAaL.
While I’d personally like to see this lower, I recognise that a near-utility business of this kind can support this level of leverage without too much risk.
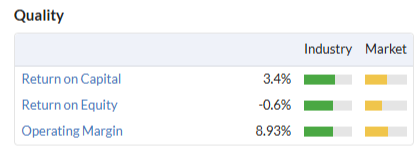
The StockRanks have a Neutral styling for Vodafone, with a weak QualityRank holding back what would otherwise be a pretty strong factor profile:
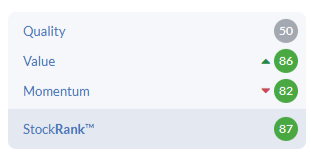
This reflects my view too – I think AMBER/GREEN is a fair view in these circumstances.
Shearwater (LON:SWG)
Up 21% at 55p (£13.4m) - FY26 Trading Update - Roland - AMBER/GREEN =
Shares in this micro-carp cybersecurity, advisory and managed security services group are up by more than 20% as I type, following today’s ahead of expectations year-end trading update:
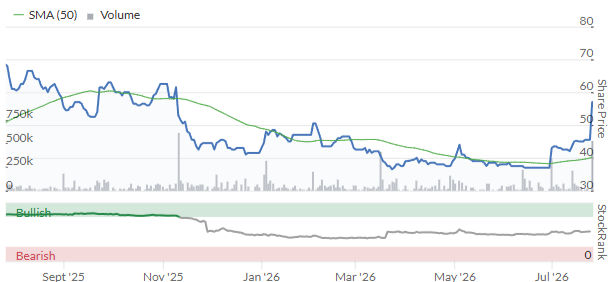
Looked at differently, the shares are still lower than they were a year ago! Cynicism aside, momentum does seem to be improving here, with a number of recent contract win announcements (e.g. here).
FY26 trading: key points
Today’s update covers the year to 30 June 2026. Management reports “a strong trading performance in H2”, driven by continued growth in Services and recent contract wins.
As a result, revenue and adjusted EBITDA are now anticipated to be ahead of expectations:
Revenue is now expected to be c.£42m, an increase of c.33% year-on-year and 18% above previous consensus of £35.5m.
Adj EBITDA is now expected to be £2.5m, an year-on-year increase of 41%. This is 4% above previous consensus of £2.4m.
Year-end net cash of £5.6m (FY25: £5.1m)
The Board plans to seek shareholder approval for a reallocation of capital between reserves in order to allow dividends and/or buybacks.
FY27 outlook:
The Group enters FY27 with positive momentum, supported by continued demand for its cybersecurity services and a strong pipeline of opportunities. The Board remains confident in the Group's prospects for the year ahead.
Revised broker estimates
Thanks to Cavendish and Research Tree, we have access to updated forecasts this morning.
FY26E adj EPS: 4.9p (+9% vs 4.5p previously)
FY27E adj EPS: 5.9p (prev. 5.8p)
Cavendish suggests its current FY27 forecasts could be “a basis from which to outperform” and maintains its 90p price target.
Roland’s view
Following this morning’s rise, Shearwater trades on a FY27 P/E of c.10.
I haven’t looked at this business before but my initial impression is that the share price is playing catch up with recent good news but may now be up with events, at least for a period.
Even using the latest adjusted forecast numbers, this business only appears to be generating an operating margin of c.3% and single-digit returns on capital.
The current FY27 forecasts may well be upgraded over the next year, but then again they may not. I’d need to do more research to understand the prospects and expected run-off from the existing order book.
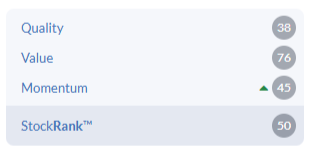
My view appears to be reflected by the StockRanks, which are neutral:
Shearwater’s small size and lack of liquidity means I would be cautious about going into this business in any size unless I had a thorough understanding and strong conviction of its growth prospects. The group’s track record of profitability is very mixed:
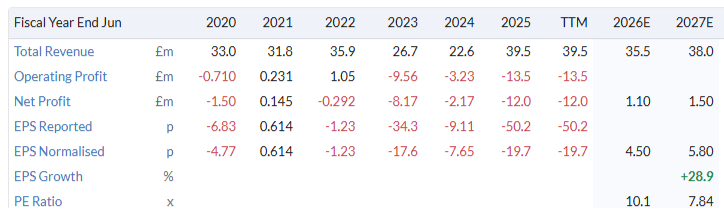
However, recent positive momentum does seem encouraging and Shearwater’s valuation falls to a single-digit P/E when net cash is considered – around 40% of the market cap. This should provide a decent margin of safety to support the equity.
Mark was AMBER/GREEN on this business in February at a share price of 50p. I’m going to give Shearwater the benefit of the doubt and leave that view unchanged today, ahead of further updates from the company.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

35 comments
Don't forget we are in the Mags earnings week as highlighted by Mr N.
The US debt and rising inflation are the future of 'all' markets. Someone thinks Japan about to explode but probably been happening for years. Who knows. The CapEx sentiment is strong so "good news, may be seen as bad news". Stupid markets.
Buy and Aston Martin Valkyrie or whatever and at least enjoy it before you crash it into a ditch.
I have just been looking at Private Credit as it seems to be in the news at the moment . Also how it is attached to life insurers.I didn't realise that Private Credit in the UK is around £100 billion. LGEN & SDLF have around 10-15% on their books with Aviva & MNG in single digits. Something to bear in mind if there is a downturn.
Most of this private credit held by the UK life insurers is investment grade and in lower risk areas such as infrastructure debt, social housing, and long-income property debt. This is fundamentally different to the private credit causing all the negative headlines in the US - this is more about the private equity backed lending to smaller, risky companies (often sub-investment grade), with software a particular concern. This is exacerbated by the fact that a lot of this private credit sits in semi-liquid vehicles which allow retail investors to redeem their positions - obviously a major problem for an illiquid asset class. I really would not be too concerned about the private credit held by the likes of Aviva, which should be reasonable resilient in a downturn.
Staffline (LON:STAF) (I hold)
Last Wednesday the share price was 36.8p - it's now 46.8p on higher than usual volumes. Interim results are due tomorrow..
Does somebody know something?
Sell the news...
SThree (LON:STEM) also up strongly in the last week. I think the sector has done well this month.
IG Design (LON:IGR)
100p+ today!
Buying companies with deep cash reserves builds wealth.
All the best
I was hoping this might be discussed today. I hold, has gone up 13% today on no news. Good recovery profile.
Hi
I bought a few could only deal in very small tranches. The company buy back machinery is hoovering up stock which is probably why the price has come up. Might knock mine out for a decent short term profit
Not a bad idea taking a 30%+ profit in such a short time!
I am keeping mine.
All the best
As a summer special, we are making tonight's MelloMonday free for non-members. Join us from 5pm for a taste of MelloMonday. Become a full Mello Member for access all year round.
Gervais Williams kicks off tonight's show. #EAH & #FRP present and the BASH covering #BOOM & #ROSE completes the show: https://www.melloevents.com/mm270726
Continue to be very satisfied with holding Tritax Big Box REIT (LON:BBOX).
"Phase 1 is expected to be one of the most advanced data centres in Europe totalling 448,000 sq ft of data halls across three floors"
107 MW growing to 147 MW subject to further planning permission I imagine they'll get. Being built in an existing industrial centre right where the important high speed cabling can be joined onto.
Not the most exciting holding in my portfolio but a very sensible and calm holding that IMO will get acquired for a healthy premium at some point in the near to medium term.
How do hope shares like 80 Mile (LON:80M) manage to persuade City investors and small investors to support placing after placing, despite a history of vast over promising and share falling 95% or so from the peak.
This is what 80M (called Blue Jay Mining before the name change) were promising 6 years ago. Huge ilmenite production by the end of 2021 for their Dundas Mine project in Greenland. . In the event their supposed wonder mine did even get started to be built.
So what an empty promise this was:. The promise of £multi million revenues from what turned out to be this fictional mine came to nought. Yet despite that they continue to get placings away.
“We are delighted to have received strong support from two important Greenlandic and Danish government-backed institutions,” chief executive Roderick McIllree said. “This support demonstrates the mutual desire to grow the country’s mineral resource industry and we hope that Bluejay will be that vanguard.”
The company aims to produce between 440,000 and 600,000 tonnes of high purity ilmenite by the end of 2021. It will start the approval process for a mining license in three to five months, it said.”
80 Mile (LON:80M),
ken,
like you I'm baffled why institutions keep giving money to this outfit. In BlueJay days it even attracted funds from some partnership outfit by Bill Gates and other big names like that, plus Danish Govt and EU. With Trump's threats over Greenland I thought 80M might have attracted his interest too. Perhaps it is their US OTC listing that has become a new milking cow for 80M?
I remember it well from MW days. It all seemed so attractive, just scoop up the precious metals from the beach, all laid bare by the retracting icecap. I personally fell for the story at the time but was just glad I escaped from it without too much damage
I see Rod Mcllree is still there, didn't he take out a decent chunk of money in earlier days? so he's ok of course.
Hello Graham, would appreciate you looking at Quartix Technologies (LON:QTX), please.
Morning Graham - Be interested to hear your thoughts on the Serica / Pharos deal ?
Hi I am a big fan of Chris Cox and his management team, On the face of it this looks like a no brainer deal in the Serica mode, However, ( given the market reaction) deep dive suggest that there are inherent risks in that it is not clear if production in Egypt can be brought back to earlier years levels and as for Vietnam well you are buying the rights to 2 blocks that need drilling and that is where the costs start mounting. Plus as the first venture outside North Sea we have political risks introduced....... Would be pretty typical of Vietnam to want a slice of any pie from a successful well.
Any chance of some thoughts on Pinewood ( I hold in my SIPP) where the takeover on projected forward revenue and earnings appears miserly to say the least, Appreciate maybe plenty of execution issues
Also I hold DCC; again this offer looks pretty low ball I think nearer £70 for a takeout
Morning Martin,
We'll add Pinewood Technologies (LON:PINE) to the table shortly and will try and take a look this morning.
Roland
Hi Roland
Thanks for the Pinewood comment. Your summation is fairly accurate in my view. As my holding is in my SIPP, the unlisted rollover vehicle ( assuming I wanted something totally illiquid) would not be a qualifying investment. Assuming Ridgeview come up with the dosh I am resigned to just cashing in even if it is at a price I see as at least 10% below where it should be given the scaling of recurring revenue this business is capable of generating !
Martin
TACO trade strikes again! Trump spends all last week ratcheting up talks about how he will bomb the hell out of Iran. Oil price and the likes of Shell (LON:SHEL) and BP (LON:BP.) share prices rise (and probably US oil companies too). The price of US gasoline at the pumps goes up and threatens his standing in the mid term elections so he calls off the strikes. However, you don’t need to be a conspiracist to suggest he told all his sycophant mates what he was planning so they could make a bundle by shorting oil related instruments. The market manipulation is astounding!
I heard a rumour ( obviously unfounded!) that the Trump dynasty alone had made circa $1bn from the war in the Middle East surely a nasty rumour put around by the Democrats. Given the price of Gas generally changes at most outlets daily any rise is immediately felt by US consumers who are as under pressure as UK consunmers from cost of living
What I find even more astounding is nobody in the US seems hugely bothered by the fact the manipulation/corruption isn't even hidden.
Much better that the corruption is hidden as previously? ;) Joking.
Difference between left and right is that the right are more open about it.
"Show me a rich politician and I'll show you a crook". As they saying goes.
Reply to Revs8: Don't kid yourself. Nothing previously compares to the sheer scale of the current corruption.
We’ll have to disagree on that. Some unbelievably wealthy left wing politicians out there. Certainly didn’t come from their salary.
Your probably correct Revs it just astounds me there seems to be near zero push back from the population in general but I think the West is becoming more conditioned to accepting these things so long as it doesn't impact on our day to day lives.
The only real pushback comes from food and energy prices going up for average families but a billion here a billion there obtained by dubious means nobody seems to fussed.
People are frightened of Trump. Do you remember how he barred law firms which implemented diversity policies from government work? If prestigious law firms can't stand up to him, who can?
Hi Sorry was away counting my billion dollar kick backs! Trump has about 40% of the population who would vote for him even if he committed an atrocity. You should never underestimate how right wing most voters are in USA which is what the Democrats did in 24.
Isn’t that the reason they get into politics?-:)
All the best
Vesuvius (LON:VSVS) possible to cover? Sitting in my dividend portfolio. Says it has loads of challenges, but says slightly ahead.
I'm afraid you need to read the above, Eric. This is another irritating example of a company that makes everyone waste time fishing around for forecast expectations rather than just telling us what they were. As Graham says, this is probably a mild profit warning from Vesuvius (LON:VSVS) and does them little credit by hiding behind a 'slightly ahead' of last year comment.
Monday 24th???
I was testing you, eggbaconandbubble.
"Well done! I was waiting to see which one of you would be first to spot that" - Captain Mainwaring