Daily Stock Market Report (Mon 29th June 2026) - SOLI, FSG, WYN, SNWS, TUNE, MEX

Oil price: I said last week, rather optimistically, that the US-Iran conflict might be over. Since then, strikes have been exchanged in the Strait of Hormuz and both countries have accused the other of breaking the ceasefire.
However, the latest reporting (as of an hour ago, from the BBC) says that both sides have agreed to stand down from these latest attacks. Talks are set to resume tomorrow, and the Brent oil price has fallen further to $72, which is a pre-war price last seen in February this year. And so it seems that a peaceful resolution remains very likely.
Overnight market movements:
The FTSE is unchanged at 10,525
S&P 500 is up 1.1% at 7,390
Brent crude (August) is unchanged at $72.00/bbl
Gold is down 0.7% at $4,060/oz
Bitcoin is up 0.75% at $60,100
Wrapping it up there for now as I have a dental appointment! See you tomorrow.
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£222bn | SR81) | Recommendation based on TROPION-Breast02 Phase III trial where AstraZeneca and Daiichi Sankyo's Datroway showed a statistically significant and clinically meaningful improvement for the dual primary endpoints of overall survival and progression-free survival. | ||
BT (LON:BT.A).A (£19bn | SR84) | BT and Verizon to form international JV & Updated Guidance for International JV Formation | BT and Verizon to combine their international operations in a new 50:50 JV, serving >3,000 customers in 180 countries, with c.$4bn in annual revenue. Transaction expected to close in 2027, no material change to FY27 profit or cash flow forecasts. | |
Plus500 (LON:PLUS) (£3.3bn | SR85) | Has launched CFTC-regulated Kalshi sports event-based contracts in the US, “bringing the highest-engagement product category in prediction markets directly to its customers.” | ||
Bridgepoint (LON:BPT) (£2.0bn | SR34) | Kayne is a private market real estate platform with c.$117bn of AUM. Upfront enterprise value of c.$1,393m, comprising $759m in cash and c.$189m of newly-issued BPT shares. Represents “a high single-digit multiple of expected 2027 EBITDA”. | ||
Georgia Capital (LON:CGEO) (£1.32bn | SR81) | Board has approved early redemption of US$50m of local bonds. Settlement expected in August 2026, following which GCAP will have fully repaid its holding company debt. Company also announced a further $10m buyback in addition to its current $50m buyback. These steps complete GCAP’s GEL 700m capital return programme. | ||
Foresight group (LON:FSG) (£458m | SR85) | AUM +8% to £13,024m. Revenue +11%, adj EBITDA +10% to £68.6m. Adj EPS +13% to 46.4p, with dividend +12% to 27.1p. Current trading: post-period end AUM c.£13.1bn and FUM c.£9.2bn, following incremental fundraising. | GREEN ↑ (Graham) | |
Porvair (LON:PRV) (£395m | SR77) | Revenue +9% (2% OCC), adj pre-tax profit +10% to £13.2m. Adj EPS +11% to 22.1p. Outlook: “Before taking account of the part-year contributions from GV and Carekem, the Board's expectations for the full year remain unchanged.” | ||
AdvancedAdvT (LON:ADVT) (£205m | SR28) | Revenue +23%, adj pre-tax profit +21% to £13.4m, adj EPS +23.5% to 10.5p. Net cash of £96m. Outlook: “the group is trading in line with the management’s expectations”. | ||
Ferrexpo (LON:FXPO) (£171m | SR) | The Group continues to operate under highly constrained conditions as a result of the war in Ukraine and related operational and financial challenges. Expects to have sufficient cash to continue operating beyond August 2026. Continues to pursue $100m equity fundraise. | (Shares suspended since May.) | |
Smiths News (LON:SNWS) (£167m | SR98) | Secured a new long-term contract with Associated Newspapers, publisher of the Daily Mail and The i Paper. Effectively secures national distribution of ANL’s leading titles from January 2028 through 2037. Represents an incremental uplift in revenue of c.£105m from Jan 2028. | GREEN = (Graham) I think the profit numbers in 2027 will be under some pressure, as one-off costs are incurred. Then the two expanded contracts should start to run profitably the following year. The big news today is that 2028 is now shaping up to be even better than we might have automatically assumed after the last contract announcement. So there’s no reason to change my positive stance here. This is a Super Stock (StockRank 98) on a P/E multiple of about 7x after today’s gains. | |
EcoSynthetix (TSE:ECO) (£166m | SR29) | Ministerial Approval Received for Namibia PEL 98 Farm-Out. PEL97,99 & 100, and South Africa Block 1 Section 11 Processes Underway. | ||
Focusrite (LON:TUNE) (£115m | SR78) | Revenue +1.3%, adj EBITDA +5.7% to £24.7m, adj EPS -7.7% to 15.6p. Launched 38 new products and 66 updates to existing product lines, net debt halved to £8.6m. Outlook: Q1 trading ahead of prior year, expectations for FY27 are unchanged. Broker Cavendish notes that Focusrite’s adjusted EPS for the 12 months to 28 Feb 26 of 15.6p was below their March forecasts of 17.3p Cavendish “to review [FY27] forecasts following this morning’s result." | AMBER ↑ (Roland) [no section below] Today’s results claim to be in line with expectations, but earnings have missed broker estimates (see left), so it looks like Graham was correct to be cautious in March. Another blot on these numbers is the £9.8m impairment for the Sequential business, “reflecting the difficult market for premium synthesizers”. This follows a £5.4m impairment to Sequential assets in FY24. I believe Focusrite paid c.£18m for Sequential in 2021, so the company has now written off nearly 85% of the value of this deal. While I recognise that market conditions have been tough at times, this doesn’t seem like a very good capital allocation decision by management. The current year is said to have started well and Focusrite says its FY27 expectations are unchanged. This suggests earnings could rise to c.19.5p and places the business on a P/E of 10. That could be a decent entry point if the group can deliver a return to sales growth, which should benefit margins. On balance I am going to revert to neutral today, although I would have liked to see updated broker numbers too. | |
Solid State (LON:SOLI) (£109m | SR76) | Revenue +23%, adj pre-tax profit +72% to £8.6m. Adj EPS +77.4% to 11.0p. Strong demand from defence and security sector, accounting for c.47% of group revenue. Outlook: open order book of £102.4m, expects to exceed current market expectations for FY27. | AMBER/GREEN = (Roland) These results are ahead of revised FY26 consensus forecasts and also include an upgrade to FY27 guidance. Solid State’s strength in defence appears to be driving good levels of growth despite some more challenging conditions elsewhere. Positive operating leverage delivered an improvement in margins last year, but profitability still remains somewhat average and the shares aren’t obviously cheap. Despite this, I don’t see any reason to change my previous view today given the strong momentum in the business. | |
Roadside Real Estate (LON:ROAD) (£106m | SR16) | Acquisition of DA Roberts Fuels Ltd is further delayed due to HMRC process timelines following a family bereavement associated with the vendor. Now expect completion in Q3 2026. | ||
Somero Enterprises (LON:SOM) (£103m | SR81) | Following investigation, Computershare has confirmed that “certain shareholder votes were not submitted to Computershare and as a result were never included in the final vote count”. The Board recognises “the significant proportion of votes cast against AGM resolutions” and is reviewing the situation. A further update will be provided in mid-July 2026. | ||
Andrada Mining (LON:ATM) (£82m | SR19) | “... strong start to the new financial year”. Q1 contained tin production +20% to 286 tonnes, with tin concentrate production +16% to 473 tonnes. Elevated tin prices expected to support strong cash generation. Funding secured for Uis ore sorting expansion. | ||
Wynnstay (LON:WYN) (£81m | SR94) | Gross profit +0.7%, adj pre-tax profit +11.7% to £6.0m. Adj EPS +15.5% to 20.9p, with net cash +5.8% to £10.9m. Reports challenging agricultural market conditions, but says restructuring benefits are evident through improved performance. Confident in delivering FY26 results in line with expectations. | AMBER/GREEN = (Roland - I hold) These results show improved profitability in mixed trading conditions. It seems that the five-year Project Genesis plan is starting to deliver results. The risk is that it’s too soon to know if this will lead to a sufficient improvement in future free cash flow to offset the multi-year increase in spending required. At this stage I remain broadly positive. I think the valuation is reasonable and see no reason to change my view given the in line nature of today’s guidance. | |
Creo Medical (LON:CREO) (£61m | SR17) | “As previously reported, the FY25 growth momentum has continued into FY26 with strong trading performance in the first three months of the current financial year…. FY26 revenue growth will be between 50% and 60% compared to FY25 (previous guidance was between 40% and 60% growth).” | ||
Blencowe Resources (LON:BRES) (£37m | SR9) | BRES has selected the preferred site for the future downstream operations associated with its Orom-Cross Graphite Project in Uganda. Has secured an option to purchase a site of 100 acres located approximately 35km north of Gulu in Northern Uganda. | ||
Tortilla Mexican Grill (LON:MEX) (£29m | SR79) | SP -3% Final results to be “broadly in line” with May guidance. Additional time needed to review French operations to ensure matters are fully understood. Shares to be suspended on 1st July. | AMBER/RED = (Graham) [no section below] | |
Atome (LON:ATOM) (£28m | SR1) | ATOME continues its engagement with the relevant authorities in Paraguay and ANDE, the state-owned electrical distribution entity, with regards to the Power Purchase Agreement necessary for the Villeta Project. | ||
Portmeirion (LON:PMP) (£26m | SR50) | The agreement for a new 5-year £36 million asset-based lending facility has now completed and is at a lower blended coupon than the prior facility. | ||
Fiinu (LON:BANK) (£24m | SR2) | Revenue £663k. Operating loss £10.3m. Cash £3.94m. Chief Strategy Officer resigns. | Publishing results just before the six-month deadline. | |
Genedrive (LON:GDR) (£21m | SR18) | Collaboration agreement with Thermo Fisher Scientific Inc. enabling genedrive to develop a CYP2C19 pharmacogenetic in vitro diagnostic test for deployment on Thermo Fisher Scientific's QuantStudio™ 5 Dx real-time PCR laboratory platform. | ||
Xtract Resources (LON:XTR) (£15m | SR41) | Pre-revenues. Operating loss £2.2m. “The year under review has been very active and to a certain degree transformational. The transformation being conversion from greenfield and brownfield project into development and production.” | ||
Fulcrum Metals (LON:FMET) (£12m | SR15) | Signs a non-binding US$20 million royalty financing term sheet and a £200,000 equity subscription with Chancery Royalty in relation to the Teck-Hughes tailings project in Kirkland Lake, Ontario. | ||
Powerhouse Energy (LON:PHE) (£11m | SR2) | Revenue for 2025 was £1.23 million (2024: £499k), all derived from Engsolve activities. Operating loss £2.9m. “Powerhouse currently has approximately several live enquiries, defined as opportunities the Company believes have potential to become revenue-generating projects.” | Publishing results just before the six-month deadline. | |
Arcontech (LON:ARC) (£10m | SR63) | New contract for its CityVision real-time market data platform to enable multiple data sources to be consumed by various applications written in different programming languages. Value c. £800k. Current performance for FY26 is in line. | ||
Tap Global (LON:TAP) (£10m | SR5) | Launches Stabld, the Group's own stablecoin, live within the Tap app's Earn product from today. Stabld is the brand for the Group's planned family of fully-reserved, fiat-backed stablecoins. | ||
Safestay (LON:SSTY) (£9m | SR51) | Revenue £20.6m (2024: £23m including discontinued operations). Loss £10.1m. NAV per share 22.21p. Current trading: average bed rate is marginally ahead of the prior year. Occupancy levels impacted by consumer behaviour changes. | Publishing results just before the six-month deadline. | |
Autins (LON:AUTG) (£8m | SR87) | FY26 revenue £17.6m (FY25 equivalent: £19.3m). Adjusted operating profit £0.4m. Outlook: in line. FY27 revenues £22m and profit after tax £0.8m, weighted to H2. FY28 revenues £26m, profit £1.4m. The Board is now guiding FY29 revenues of £27m and PAT of £1.9m. |
Graham's Section
Foresight group (LON:FSG)
Up 7% at 438.5p (£490m) - FY March 2026 results - Graham - GREEN ↑
We already had a full-year update from Foresight in April, covered by Mark.
Since then, the company has announced the sale of £1 billion of its AUM - it wants to focus on Real Assets and Private Equity, and so it sold its public markets division (“Foresight Capital Management”).
Today’s full year results therefore exclude FCM:
AUM £13 bn (+8% year-on-year, or +5% at constant currencies)
FUM £9bn (+7%, also +5% at constant currencies)
Revenue £165m (+11%), of which recurring revenue is £135m.
This good underlying growth converts into a 10% increase in “Core EBITDA pre-SBP” which rises to £68.6m (SBP means share-based payments).
Let’s sense-check this against the actual profit figures. From the annual report itself:
Operating profit £54m (prior year £41.4m)
PBT effectively the same figure, £54m.
So while the company focuses on “Core EBITDA pre-SBP” (what a mouthful), the actual profit figures themselves are clean and not so far off the adjusted ones.
Current trading: AUM has ticked up to £13.1bn and FUM to £9.1bn, marginally higher than the year-end numbers.
Executive Chairman comment:
We enter the new financial year wholly focused on our core Real Assets and Private Equity divisions with a diversified fundraising pipeline across institutional and retail investment vehicles managing long duration capital, and remain committed to our medium-term growth guidance."
Worth noting that Mr. Fairman owns nearly 30% of the business, so he is highly aligned with other shareholders.
Estimates: Cavendish say that today’s core EBITDA number is in line with consensus: revenues missed expectations, but expenses were also lower than forecast.
The 12% increase in the dividend announced today (to 27.1p) was slightly higher than expected.
Cavendish have not yet reviewed their forecasts but they do maintain a “BUY” rating. They forecast adjusted EPS of 51.9p in the current year (FY March 2027), and then 68.1p the following year.
Graham’s view
I must confess that I don’t know Foresight’s funds very well.
The breakdown is that they are mostly (£11.1bn) invested in Real Assets in Europe and Australia. This is further broken down as follows:
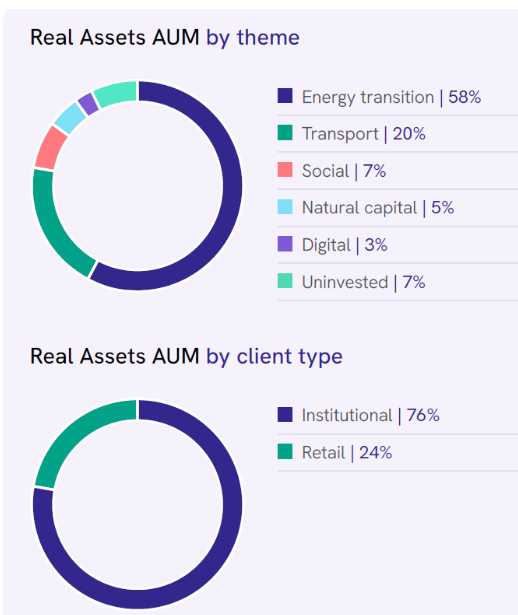
As you can see, the majority is invested in the “Energy Transition” - wind farms and woodland, for example.
Fundraising continues for their new FEIP II fund, about halfway towards their €1.25bn target.
The rest of AUM (£1.9bn) is Private Equity; they are “one of the most active UK regional SME investors”.
As far as our stance on this goes, I don’t see why not to be fully GREEN on it.
EPS forecasts have been stable:
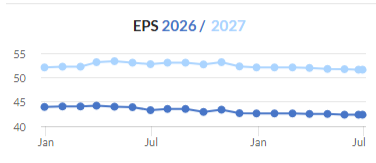
Mark pointed out in our previous coverage that FUM forecasts would be missed, but this hasn’t had much of an impact on profits. And when businesses are trading at c. 8x earnings, I don’t think we need to expect everything to go perfectly as planned: if the general growth trajectory continues for a few years, and economic returns remain strong, then the current valuation will be too cheap either way.
This has a QualityRank of 99: successful fund managers often generate very strong margins and returns, as this one does.
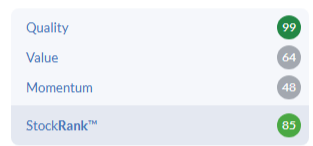
I’m therefore taking us back to fully GREEN, as I don’t see what there is to dislike. The P/E is still below 10x after today's rise and is even 6.4x based on FY March 2028 forecasts.
Looking at the chart for the past few years, I see that the share price has been pretty stable, all things considered. The market wasn’t expecting much:
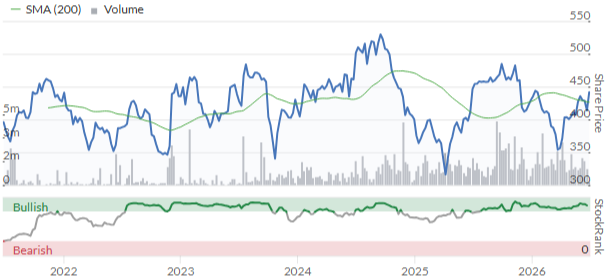
But recent performance shows that fund managers can still do very well out of the “energy transition”. Maybe the structure is key here: investing mostly in private, real assets and gaining long-term commitments from their customers?
Smiths News (LON:SNWS)
Up 3.6% at 70p (£173m) - Associated Newspapers Limited - National Contract Win - Graham - GREEN =
More great news from Smiths News, this cigar butt stock that refuses to die: it has “a new long-term contract with Associated Newspapers Limited… publisher of 'Daily Mail', 'The Mail on Sunday' and 'The i Paper'.”
The transformational agreement with ANL…is on enhanced commercial terms for Smiths News and includes (i) an expansion of the distribution territories in which the Company is appointed as ANL's exclusive wholesale distributor, thereby effectively securing national distribution of ANL's leading titles across all of Great Britain, to take effect from January 2028 and (ii) an extension in the contract term of our appointment through to July 2037.
This sounds very similar to the other contract we reported on recently, where News UK & Ireland (publisher of the Sun) upgraded to national distribution at Smiths News, with a £125m uplift in annual revenue for Smiths. The News UK contract also runs until 2037.
The ANL contract is expected to lift revenues by c. £105m p.a. from January 2028.
The two contracts announced recently therefore “represent c.36% of the national newspapers and magazines market having been secured from January 2028 for Smiths News”.
CEO comment:
Today's announcement continues to reinforce our position as a trusted partner for our industry and further secures a sustainable future for print news distribution, reflecting our shared commitment to supporting the industry over the long term."
Estimates: the previous contract announcement warned us that there would be costs associated with expanding their geographical capabilities. Today’s announcement reaffirms this but doesn’t yet give any details. But it’s very reassuring that the increased capacity will now be used by at least two of the company’s major customers!
In the absence of more detailed guidance, Canaccord Genuity have left their forecasts unchanged today, expecting 10.4p of EPS this year (FY August 2026) and 10.3p of EPS next year.
Graham’s view
I think the profit numbers in 2027 will be under some pressure, as one-off costs are incurred. Then the two expanded contracts should start to run profitably the following year.
The big news today is that 2028 is now shaping up to be even better than we might have automatically assumed after the last contract announcement.
So there’s no reason to change my positive stance here. This is a Super Stock (StockRank 98) on a P/E multiple of about 7x after today’s gains.
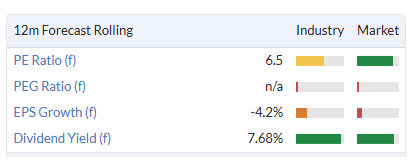
It has announced a combined £230m of incremental revenues from two major customers, starting in 2028. For context, annual revenues have been running at about £1 billion.
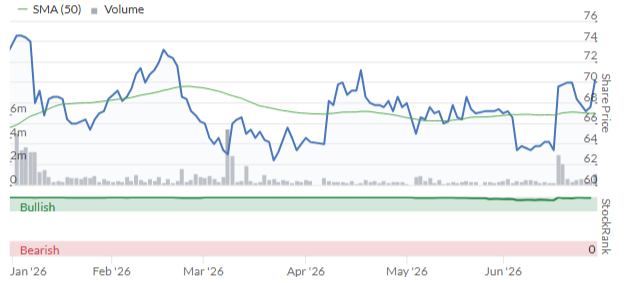
Checking the share price, I see that it has been range-bound year-to-date. I can’t predict the future but based on the fundamentals, it would make sense to me if this broke out of the range to the upside before too long.
Roland's Section
Solid State (LON:SOLI)
Up 5% at 202p (£115m) - Final Results - Roland - AMBER/GREEN =
Electronics group Solid State upgraded its FY26 guidance in April. The company has followed suit today by beating revised consensus forecasts and upgrading its guidance for FY27.
The resulting upgrade should give our broker consensus trend chart a pleasing uphill slope:
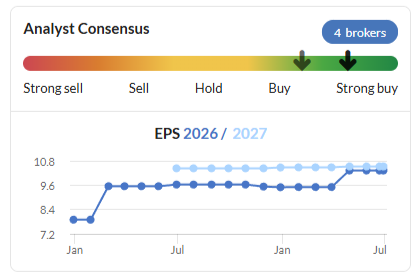
I’ll return to today’s upgraded forecasts shortly, but let’s take a look at the main points from today’s results.
FY26 results summary (y/e 31 March)
Revenue up 23.2% to £154.1m (+1.4% vs consensus £152m)
Adjusted pre-tax profit up 72% to £8.6m
Adjusted EPS up 77.4% to 11.0p (+6.8% vs consensus 10.3p)
Dividend up 10% to 2.75p per share
Net debt down 43% to £4.2m
Orderbook -1% to £102.4m
Trading commentary
All three divisions delivered improved year-on-year performance, supported by strong demand for AI data centre infrastructure and defence and security applications.
Solid State’s reporting structure was tweaked last year to separate the Power segment from Systems and Components. The group now has three reporting segments:
Power (revenue +15.6% to £31.8m, op profit +500% to £1,677m): demand for battery technologies and systems “has grown across a range of un-crewed applications”, including drones, autonomous underwater vehicles, robotics and unmanned ground vehicles. The division signed c.$20m of new defence orders in the final four months of the financial year.
Systems (revenue +48% to £62.5m, op profit +71.6% to £8.9m): “Adoption of the Persistent Systems communications ecosystem and our associated technology solutions continued to build, supporting strong equipment sales under the NSPA framework programme.”. Delivered a $10.8m order to the British Army in Q1 under Project CAIN, a multi-year programme.
Components (revenue +8.2% to £59.8, op profit +2.3% to £2.2m): market conditions were challenging. However, demand in the medical and defence sectors was strong, “particularly for certain power-related products driven by AI-associated data centre investment”. A number of new design wins have been secured in the UK and US, but the company warns of the growing impact of longer lead times and rising prices for certain components, especially memory products.
Looking across the business, the US accounts for around 23% of revenue, while the UK is the largest single market at c.45%. Europe makes up the majority of the remainder.
Solid State’s CEO Jon Macmichael notes that the group’s UK and US production footprint remains one of its “most important strategic assets”; governments in both countries are keen to secure domestic supply chains for defence equipment.
Profitability: last year’s strong revenue growth delivered welcome operating leverage, with sales rising more quickly than operating costs. The result is a significant improvement in profitability (using reported profits):
Operating margin: 4.5% (FY25: 1.1%)
Return on Capital Employed (ROCE): 8.6% (FY25: 1.9%)
Return on Equity (ROE): 6.5% (FY25: 0.8%)
To its credit, Solid State also reports both ROE and ROCE in today’s results. These are adjusted figures, though, and result in somewhat higher numbers than my standard calculations (which mirror those in the StockReport):
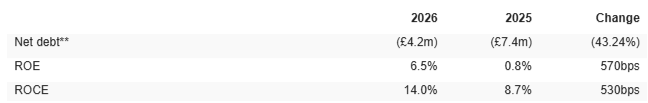
Should I allow Solid State’s profit adjustments? Checking the details in the footnotes shows these are all fairly standard:
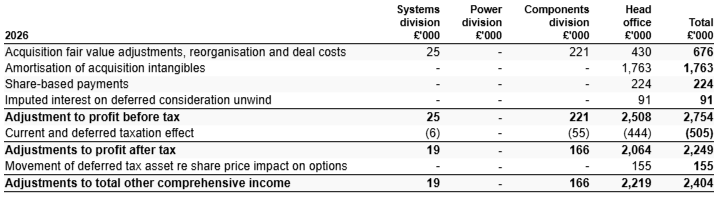
Personally, I find it easier to use the statutory figures. I see share-based payments as remuneration and I think that deducting amortisation from the balance sheet while leaving it in the profit calculation is likely to flatter the returns on capital being generated by past acquisitions.
My litmus test is usually to consider whether free cash flow is closer to reported net profit or adjusted net profit. In this case, free cash flow of £5.3m lies midway between the relevant figures of £4.1m and £6.3m.
This gives the stock a free cash flow margin (vs revenue) of 3.4%, supporting my view that while profitability is improving, it would be nice to see a further improvement in margins.
Valuation: today’s results and share price rise give Solid State a trailing P/E ratio of 19. Using free cash flow instead gives a multiple of 22.5, again supporting my preference for non-adjusted figures.
Outlook & Broker Estimates
The Group has had a good start to the new financial year with current trading in line with the Board's expectations, and we expect to exceed current market expectations for FY26/27.
Solid State ended the year with a flat orderbook of £102.4m, but Mr Macmichael is evidently confident this provides sufficient visibility to upgrade guidance for FY27.
House broker Cavendish has upgraded FY27 forecasts today and introduced FY28 estimates:
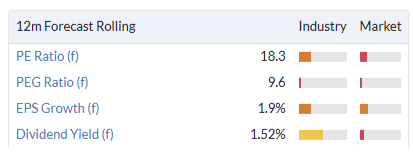
FY27E adj EPS: 11.5p (+9% vs 10.5p previously)
FY28E adj EPS: 12.7p (+10% vs FY27E)
These upgraded estimates leave Solid State’s forward valuation largely unchanged, albeit with an improved rate of EPS growth:
Roland’s view
I upgraded Solid State to AMBER/GREEN in December, suggesting that the business had “the potential to deliver medium-term growth in defence as well as an eventual recovery in industrial demand”.
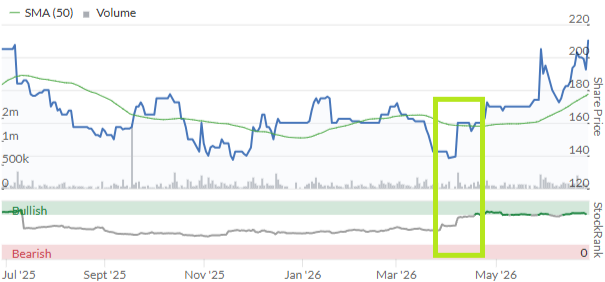
This optimistic view was followed by a sharp StockRank Jump in April (a signal covered in Ed’s latest article), since when the share price has risen by around a third:
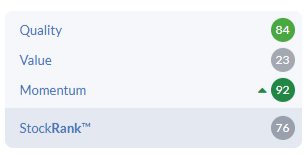
Strong Quality and Momentums scores should be enhanced by today’s results and support a High Flyer styling at the time of writing:
While the valuation remains relatively full and profitability is still below the level I’d like to see, the direction of travel is clearly positive. I don’t see any reason to change my previous view today. AMBER/GREEN =
Wynnstay (LON:WYN)
Up 2% at 358p (£83m) - Interim Results - Roland - AMBER/GREEN =
(At the time of writing, Roland has a long position in WYN.)
This agricultural group is a producer and distributor of grain, fertiliser and animal feed. Wynnstay also has a network of retail stores supporting the agricultural/rural market. The group’s footprint is predominantly the west of England and Wales
Wynnstay is currently mid-way through a five-year plan instigated by CEO Alk Brand shortly after his appointment. In broad terms, the aim of Project Genesis is to improve profitability and efficiency and create a more integrated business with stronger potential for growth.
Low growth and poor returns on capital have been a hallmark of this cyclical business, but Brand believes he can change this.
I bought shares in Wynnstay as I was attracted by the (then) deep discount to book value, balance sheet strength and long dividend track record. But as Mark highlighted in February, increased spending has reduced dividend cover and the valuation isn’t as cheap as it was.
Do today’s interim results support continued confidence?
Half-year results summary
Profitability improved sharply during the six months to 30 April, at least on an adjusted basis:
Revenue flat at £304m
Gross profit up 0.7% to £42.3m
Adjusted pre-tax profit up 11.7% to £6.0m
Adjusted EPS up 15.5% to 20.9p
Net cash up 5.8% to £10.9m
Interim dividend up 3.5% to 5.9p
Performance was reassuringly similar at a statutory level, with reported pre-tax profit of £6.2m and earnings of 21.3p per share. I don’t see any concerns over adjustments in these figures.
Trading commentary
Agricultural markets remained mixed during the period. Livestock sectors continued to experience pressure from farm profitability dynamics, whilst uncertainty around government policy and agricultural support schemes remained a feature of the trading environment. The Group also faced ongoing inflationary pressures across labour, logistics, energy and other operating costs.
Feed & Grain (adjusted pre-tax profit +144% to £2.2m): “one of the clearest demonstrations of the benefits being delivered through Project Genesis”. Although manufactured feed volumes were lower on a LFL basis, the reduced cost base and optimisation of manufacturing operations completed last year drove a significant improvement in profitability, while also creating additional manufacturing capacity to support future growth.
Arable (adjusted pre-tax profit +36% to £1.9m): this division benefited from higher manufactured fertiliser volumes and a full-period contribution from the Avonmouth blending facility. Short-term volatility due to the Middle East conflict provided “a modest benefit to profitability”, although much of the spring selling season had already been contracted. No disruption to fertiliser supply chains was experienced during the period.
Stores (adjusted pre-tax profit -36% to £2.0m): the fall in profit was mainly due to “lower small bag feed sales and inflationary cost pressures”. There was some improvement in performance during the second quarter.
It looks to me like the changes made so far through Project Genesis probably are delivering tangible results.
This is reflected in a tangible improvement in profitability at a group level.
Profitability: Wynnstay is a commodity business with a large proportion of pass-through revenue (cost price + margin). This means it can be useful to consider the ratio of operating profit to gross profit when looking at margins:
H1 26 operating margin: 2.0% (H1 25: 1.8%)
H1 26 op profit/gross profit: 14.4% (H1 25: 13.1%)
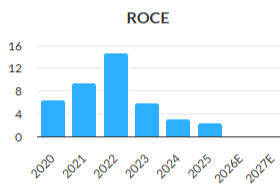
Trailing 12-month return on capital employed: 6.4% (FY25 underlying: 6.1%)
While low, these metrics are improving and should also be seen in the context of the company’s discount to book value. This increases the effective theoretical returns available to shareholders.
For example, current-year forecasts imply a return on equity of 5.5% based today’s reported book value of 583p per share.
However, the stock currently trades at 358p, around 40% below book value. Buying the shares at this level means current forecasts imply a return on cost of equity of nearly 9%. That’s still not very high, but it’s a lot better!
Unfortunately this is also a reason why I only expect Wynnstay to trade close to book value on rare occasions when it’s enjoying a cyclical boom in profits – unless Project Genesis really can transform the profitability of the business.
Past performance provides a graphic illustration of the cyclicality of this business:
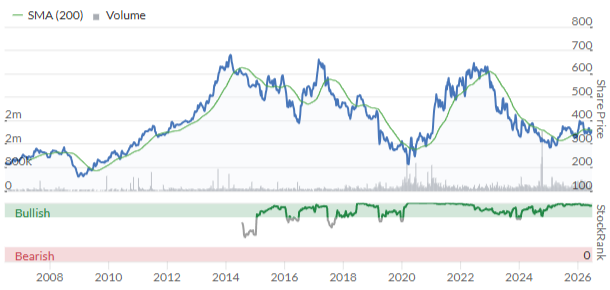
Cash generation: Wynnstay has a heavy seasonality to cash flow due to working capital movements – the company must build up large stocks to support the farming calendar. H1 marks a low point for cash.
Pressure on working capital rose this year due to higher commodity prices, but the impact on cash flow was offset by “strong working capital management”:
As expected, the half year reflected the peak point of the Group's annual working capital cycle. During the period, agricultural commodity prices increased, particularly within fertiliser markets, creating additional working capital requirements. Despite this inflationary backdrop, the Group improved cash conversion through tighter inventory management, aged debt management, disciplined procurement and enhanced working capital controls.
The upshot of this is that Wynnstay ended the half year with a much higher payables balance than last year:
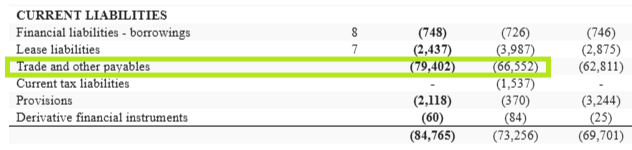
What we can’t tell from these numbers is the proportion of this increase which reflects higher commodity prices, versus the impact (if any) of slower payments to the group’s suppliers.
However, the increase in the company’s receivables balance was on a similar scale to the increase in payables, leaving the receivables/payables ratio largely unchanged. This suggests to me that much of the increase in payables was due to higher commodity prices, with Wynnstay also seeing a comparable rise in the value of unpaid invoices owed by its customers.
Overall working capital remained unchanged at c.£84m at the end of the half year, suggesting to me that the company is indeed managing working capital more successfully.
Of course, the real test of the group’s working capital management will be the year-end balance sheet. Broker forecasts suggest it should fall from £25.7m to £21.5m as the combination of higher capex and dividend payments drive overall cash outflows.
Outlook
The Board remains confident of delivering full-year results in line with current market expectations, representing a further improvement on FY25.
Broker forecasts from house broker Shore Capital are unchanged today:
FY26E adj EPS: 31.5p
FY27E adj EPS: 34.6p
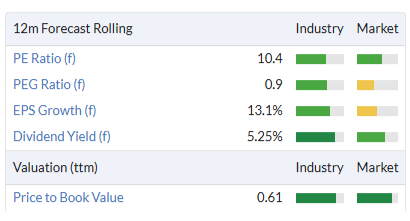
These forecasts put the stock on fairly modest multiples, with the dividend yield still attractive at 5%:
Roland’s view
Wynnstay’s profitability appears to be improving in quite mixed market conditions. The catch is that ongoing higher levels of capital expenditure mean that free cash flow is expected to be close to breakeven in both FY26 and FY27. This means that the dividend will effectively be paid out of the group’s net cash balance, rather than from surplus trading profits.
This may not be a problem if the capex delivers hoped-for results and future cash flow reflects this. But it’s too soon to know how likely this is.
Today’s in line results are broadly encouraging, as far as they go. I think it’s also somewhat positive to see that Mr Brand has spent nearly £80k buying Wynnstay shares since his appointment in October 2024.
Wynnstay’s share price has pulled back somewhat since Mark’s comments in February and the valuation looks relatively more appealing to me today. The StockRanks also have broadly positive view, with Super Stock styling:
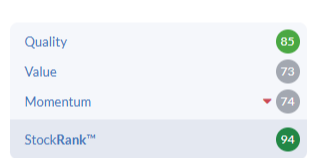
I’m going to leave our AMBER/GREEN view unchanged today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
Following the results for Focusrite (LON:TUNE) , Harwood have increased their stake to 5.1%, and on the same day the new Chairman designate bought 80,000+ shares at 200p. The market seems to have liked that today.
Newly listed companies.... does anyone know of a clean way to easily get a list of companies that are newly listed on the LSE?
While each stock report has a "publicly listed" date on them, this can't be used as a filter screen.
Any external websites/sources to find this information?
My use case is that I'd love to, on a quarterly basis, get a list of the companies listed in the prior quarter, and then go through them (or use AI) to get a quick summary and top-line. To potentially add to my list of companies to research more deeply.
Have you tried producing the quarterly list using AI ? I'm still using the previous version of Excel but I believe using the latest version you can ask AI to produce a table in .xls format then paste it into a spreadsheet.
I have tried using LLMs to research and find the companies that have IPO-ed in the prior quarter. However, I have noticed that it is not comprehensive; it misses out some, especially smaller companies that list.
So therefore, asking if there is already a definitive source available. Why use LLM which can be unreliable without very complicated prompts and harnesses, when there is an old-school solution somewhere?
Does this work for you? Would have to filter out just ipos
LSE New issues page/link
Thank you so much! This works for my purposes. I can probably use an LLM to filter for me the "true" IPOs vs the secondary listings, etc.
I had an inkling the data-set was on the LSE website, but when I had a stab at it..... its one confusing website....
Somewhat ironically I run the question though Claude to find the page on their website. They are pretty good for that as well.
Thanks for shining the Green light on Smiths News (LON:SNWS) Graham, it's in the green corner of the Bubble Chart on all 3 Ranks. I've held it since 2011 and has been fraught at times, feeling I was walking a tight-rope. The dividends have been really nice since Covid, a shame it is just 1.9% of my portfolio.
On another subject I'm looking forward to the 23rd of July and the Stock Ranks Jump Effect webinar. I've discovered the View analysis on a portfolio page and Voila! Ed once said all of his investments are in the Green, how I envy him but reckon that if my portfolios had an 84 instead of this 82 I would be beating the FTSE All-Share.
Forgot about the Analysis view in Folios! They are quite interesting at a glance.
Here's the screenshot for The Boon Fund.
While Value and Quality only 69, 61.... most of my shares are in the upper right for QV, which is my approach.
VERY speculative RiskRatings haha. 60% in Speculative, Highly S, or Adventurous...! Hopefully, this is sensible Speculative... when combined with the High Q and High V...
Surprised of so much of my portfolio has a "neutral" rating for Style. Would have expected more "Contrarian" given what I look for... is Neutral really Neutral, or is it a catch-all for "Other / Don't Know"?
What has happened to news on the Stockreports? Nearly everything is under "other" and there is just a press number, when l click on the Original report, it is just blank. This includes results. See Focusrite (LON:TUNE) and various others.
On Wynnstay (LON:WYN) it does look to me like the restructuring is working and they said that investment has been made in the business but the costs of this have been "absorbed" in the Group's improved financial peformance. This investment I beleive and but they fact they can make the business better and deliver better numbers is encouraging. If they make a RONA of 10% with NA of £134m, knocking off £800k for net interest and then taxing at 25% I get 39p of earnings so it's on 9x with a good yield.
AdvancedAdvT (LON:ADVT)
Results look brilliant, right up to the adjusted EBITDA line. Below that is a £5.6M "Fair value on financial assets" write off.
Other than a rather technical statement of what the nature of the charge is, I cannot see any explanation on the results update despite hammering EPS. Crudely, it looks like a more sophisticated version of goodwill. The write down is about a quarter of the value standing at the start of the year, and leaves a further £15M on the balance sheet. How exposed is that to a further write off? I guess it will be written off over time, but might it be £1M or £10M next time?
I accept it is not a cash adjustment but it seems to tell us something (not very good) about recent acquisitions.
Having said that I am a big fan of Vin, and do hold the stock. However, I don't like this trend in focussing our entire attention on the EBITDA line, particularly in a company growing by acquisition.
Strongly agree with all you say, Monty9. I do not believe this elephant in the results has been covered adequately in the results. I have always believed VM has been open and honest but this omission may be a red flag.
Doesn't ADVT own 12 million shares in M&C Saatchi? It looks like they had a bad year, measured from February 2025 to February 2026. They fell about 50p, which would be a £6m loss in fair value.
AdvancedAdvT (LON:ADVT)
Graham
Doesn't ADVT own 12 million shares in M&C Saatchi? It looks like they had a bad year, measured from February 2025 to February 2026. They fell about 50p, which would be a £6m loss in fair value.
yep see my post below that is the reason
AdvancedAdvT (LON:ADVT)
Other than a rather technical statement of what the nature of the charge is, I cannot see any explanation on the results update despite hammering EPS. Crudely, it looks like a more sophisticated version of goodwill. The write down is about a quarter of the value standing at the start of the year, and leaves a further £15M on the balance sheet. How exposed is that to a further write off? I guess it will be written off over time, but might it be £1M or £10M next time?
thankfully the audited report with extra info is available on the company website - looks like this adjust is related to its investment in listed companyy M&C Saatchi (LON:SAA) – M&C Saatchi - the entry makes complete sense if the value of that investment has tanked during the year.
https://advancedadvt.com/inves...
This includes the investment in M&C the carrying value of which is determined by stock market price and represents approximately
10.1%. of the Company's net assets as at 28 February 2026. There can be no guarantee that the Company will be able to dispose of
the M&C Investment at a value equal to or more than the value for which it was obtained. In the Company's Consolidated Financial
Statements, the M&C Investment is accounted for as an asset held at fair value. The shares are revalued to market value at the end
of every reporting period with gains or losses on valuation taken to the profit and loss account. Further, any fall in the share price
of M&C would have a corresponding negative effect on the value of the M&C Investment and potentially the share price of the
Ordinary Shares, which could have a material adverse impact on the Company's performance and prospects. This exposure was
evidenced by the movement in the M&C share price during the period, including a fall of 47 pence which reduced the carrying value
of the investment by £5.64m; since 28 February 2026, the share price has increased by 6 pence to 134 pence (as at 24 June 2026),
increasing the value of the investment by approximately £0.7m.
Thank you rmilaree - very helpful.
Jamie Ward will be interviewing Simon Bragg at 7:10pm tonight in an interview that will include investing that avoids value traps and overpaid executives to round off tonight's MelloMonday.
The programme for the evening is as follows (subject to minor change):
5:00pm Fireside Chat with John Goold, CEO Kelso group (LON:KLSO)
5:30pm Company Presentation from Oxford Metrics (LON:OMG)
6:10pm Company Presentation from Accsys Technologies (LON:AXS)
6:40pm Company Presentation from Pathos Communications (LON:NEWS)
7:10pm Mello Insights with Simon Bragg
For more information, click here: www.melloevents.com/mm290626
There are lots of interesting sessions and all members and individual ticket holders will be sent a recording of the show within 48 hours.
For half price tickets, use code MMSTOCKO50
https://www.tickettailor.com/events/melloeventslimited/2022799
This geezer Burnham is likely to crash the markets.
God forbid if he makes Millibrain the Exchequer!!!!!
Smiths News (LON:SNWS) they keep coming out with good news! Looks like medium term revenue will increase significantly.
tinyBuild (LON:TBLD) is up 15% in early trading. In the last 24 hours, the number of concurrent players of its new game 'Sand' on Steam reached a peak of 38,000 - which is really good for an indie publisher and points to the company doing very well this year given they're due to release a couple of other games this year with good followings. Market expectations look too low to me. I hold.
Those of you at Mello recently may have had chance to talk to Solid State (LON:SOLI) about their drone component sales. SOLI drone exposure is underscored by the $10.8m Project CAIN MoD contract for drone command and control. Some 47% of SOLI revenues are now in defence (£72m of FY26's £154m), with an order book of £102m, and today's FY26 results beat consensus EPS by 7%. The Cavendish target has been upgraded this morning to 301p.
I hold Solid State (LON:SOLI) and I am pleased with the upgrade to FY 2026/27 so early in the year. The only concern I have is the low operating margin for a business that supplies to defence, power and communications sectors. If they can rise towards the low teens over the medium term the investment case would be transformed.
The low Solid State (LON:SOLI) operating margin is a fair concern, though the ROCE improvement from 8.7% to 14% in FY26 is an encouraging leading indicator — capital is beginning to be deployed much more productively, and if operating margins recover toward the FY21-24 average of 9%-plus, ROCE could move well above 15% on the current asset base.
Good morning Graham, the world needs The Straits if Hormuz open, but while Netanyahu's interests don't ally, I fear Trump's responsibility to reinstate free passage will not be straight forward. Our biggest holding after Ramsden's likely departure will be Wynnstay, I'd appreciate comments of their HY if you have time. I'm relieved and impressed by it's resilience in hard times, project Genesis seems to working well with Eps + 15.9% - DIv +3.5% Net cash + 3.5% Net debt full IRS16 - 34.5%. Statutory Pbt +10.2% and confidence on delivering FY expectations. It's not exciting but it seems pretty safe whoever is Prime Minister?
Would be great if you have a chance to run the rule over Foresight group (LON:FSG) team.
Will do, Phoenix!
Thanks as always Graham
All looks very positive at first glance with all figures moving in the right direction and a positive post Results update, to boot.
Throw in a 12% increase in the existing 6% dividend yield, what's not to like? It's been below its historic levels for a while, although has been playing catch up already this year.
Looking forward to what Graham has to say.
Agreed Andy plus they specialize in infrastructure investments so different from the other fund managers and from memory the main man is in his golden years so might be looking for an exit in short to medium term,
Arcontech (LON:ARC) - Nice contract win
If only Arcontech (LON:ARC) were able to see some growth this company could be a very useful share to hold. Forecasted PE of around 10 with a nice cash pile underscores the value - I continue to hold
Is that a little bowl appearing do you think? Analyst forecast showing +132% target albeit it that is probably the house broker.... Not so good is the falling away in Op Margin and ROCE so maybe I will curb my enthusiasm for now.