Daily Stock Market Report (Mon 7 July 2025) - MWE, PLUS, POS, SHEL, CRPR, SWC, GST, PHP, ETP, JIM, RKH

Good morning and welcome back! Roland and I are with you today.
It's a reasonably full-looking table of news today, but in truth there aren't too many results or trading updates.
Spreadsheet accompanying this report: link.
11:30am: we are going to wrap up the report there for today, cheers!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Shell (LON:SHEL) (£155bn) | Profits from gas and refining to be “significantly lower than Q1”. Production guidance tightened. | AMBER (Roland) | |
HALEON (LON:HLN) (£34bn) | Restating historic results to reflect new reporting segments launched in May. No changes to results. | ||
Plus500 (LON:PLUS) (£2.3bn) | H1 rev +4% to $415m, EBITDA +1% to $185m. Active customers +2.3%; record deposits of $3.1bn. | GREEN (Graham) While I’ve never entirely abandoned my reservations around customer churn and the lack of hedging, I’ve been happy to stay GREEN on Plus500 for some time, due to its prodigious cash generation and its ability to return vast amounts of this cash back to shareholders. With an update today that’s at least in line, I’m happy to leave this view unchanged. | |
SSP (LON:SSPG) (£1.5bn) | See Wed 2/7 - SSP’s JV partner has placed an anchor stake at the top end of the IPO price band. | ||
Alpha International (LON:ALPH) (£1.4bn) | The deadline for Corpay to make a firm offer has been extended until 5pm on 24 July 2025. | PINK | |
Primary Health Properties (LON:PHP) (£1.3bn) | Adj earnings +2.2% to £47.3m, dividend +2.9% to 3.55p w/ 100% cover. NTAV +1.1% to 106.2p. |
PINK (AMBER/GREEN) (Roland) [no section below] | |
Smarter Web (OFEX:SWC) (£826m) | Placed 7m shares at 327p, raising £22.9m. Further 14m shares being offered to fund bitcoin purchases. According to today's RNS, the company will have 256 million shares in issue; this is the basis for my market cap calculation. | RED (Graham) [no section below] | |
Pinewood Technologies (LON:PINE) (£459m) | Consideration paid: £2.5m. Acquisition is expected to add £0.5-0.7m in incremental EBITDA. | ||
Rockhopper Exploration (LON:RKH) (£377m) | Insurer confirms loss has been triggered re. Ombrina Mare arbitration. Expects €31m payout. | AMBER/RED (Roland) [no section below] The expected receipt of this insurance payout is good news, as far as it goes. But this result is much less than the c.€80m the company had hoped to receive in a best-case scenario. Looking ahead, a final investment decision on the Falkland Islands Sea Lion field is expected later this year. RKH owns 35% and has loan funding (at 8% interest) from operator Navitas for some of the expected $1.4bn Phase 1 capex. But management has previously said the company will probably need to raise funds to meet its remaining Phase I obligations, which I estimate at perhaps $160m. In addition, the company is involved in an ongoing tax dispute with the Falkland Islands govt that could result in a £59.6m liability due after production starts. Management says this is making Sea Lion financing “significantly more difficult”. Even if everything goes ahead as planned, first oil is not expected until late 2027. | |
Ferrexpo (LON:FXPO) (£292m) | Iron ore output -40% to 1.3m in Q2 due to liquidity problems following suspension of VAT refunds. | ||
Pantheon Resources (LON:PANR) (£281m) | Placing at 21.15p, a 14% discount to Friday’s closing price. Proceeds used to support ongoing activities. | ||
Renold (LON:RNO) (£160m) | Strong FY25. Demand in early FY26 “slightly below” prior year. Pricing to offset higher costs. | PINK (recommended offer at 82p) | |
Guardian Metal Resources (LON:GMET) (£82m) | Acquires additional mining claims 15k from company’s project in Nevada. | ||
| Corero Network Security (LON:CNS) (£74m) | Corero Secures Initial CORE Customer Contracts | $1.5m expansion of a partnership. New $0.3m partnership. | |
1Spatial (LON:SPA) (£52m) | UK: return to more typical activity levels. US: slow. Confident to grow in FY26 and beyond. | ||
MTI Wireless Edge (LON:MWE) (£40m) | Three existing customers order military antennas worth c. $1.6m, for delivery over next 20 months. | AMBER/GREEN (Roland) [no section below] Today’s wins include the provision of antenna for airborne use, anti-jamming GPS and “sophisticated beam forming”. They are said to be for use supporting drone management systems. Encouragingly the orders have come from two international defence firms in addition to a local (Israeli) customer. I’d imagine there’s further scope for growth in the drone market for MTI if these orders are successful. However, unchanged forecasts suggest these wins were already priced into existing forecasts. My previous view (see 27 May) also remains unchanged. | |
Artisanal Spirits (LON:ART) (£35m) | Private individuals will be able to buy an individual cask. Only a handful will be released each year. | Reach announcement. | |
GSTechnologies (LON:GST) (£30m) | Placing raises £1.75m at 120p (sp: 138p). 250k retail offer. Purpose: to build bitcoin treasury reserve. | RED (Graham) [no section below] I'm automatically RED on all companies with a Bitcoin treasury policy. GST jumped on this bandwagon recently, as we noted in this report, claiming that bitcoin "offers liquidity comparable with to cash while serving as a reliable store of value". The adoption of this policy now serves as the basis for equity dilution. According to the StockReport, GST has never made a profit and is categorised as a "Sucker Stock". As noted in relation to SWC, I'm far more bullish (in the short-term) on the companies that can benefit from serving the demand for these stocks, than I am on the stocks themselves. CMC Markets (LON:CMCX are GST's placing agent through their CapX division. | |
James Cropper (LON:CRPR) (£21m) | Loses a significant customer but FY 2026 exps seem unchanged. RNS could be more explicit. Broker estimates: house broker Shore Capital has left FY25 forecasts unchanged today. It will reinstate FY26/FY27 forecasts when CRPR’s FY results are published later this month. | AMBER (Roland) [no section below] I don’t feel much wiser after reading today’s RNS. Cropper has lost a significant customer but provides no detail on the scale of the revenue impact. This news also does not appear to change the company’s expectation for the Paper & Packaging division to return to breakeven later this year. Elsewhere, expected “single-digit” FY26 revenue growth in the Advanced Materials division seems unexciting to me. The company has previously said that efforts to improve the performance of both divisions are expected to yield more impressive results from FY27 onwards. With a FY25E P/E of 18 and no outer-year forecasts from the house broker, I’m inclined to downgrade our view to neutral until this month’s FY results provide some clarity. | |
Plexus Holdings (LON:POS) (£16m) | FY June 2025 in line. Rental fleet growing and Mid East contract progressing. New USA contract. “...whilst the macroeconomic environment remains challenging, opportunities for Plexus are encouraging and the Company remains confident in its strategy for sustainable growth.” | AMBER/RED (Graham) [no section below] We covered the March fundraise by Plexus here. Funds are now being put to work as planned, expanding the company’s fleet of wellhead systems. A note from Cavendish this morning leaves forecasts unchanged (FY June 26: revenue £9.4m, adj. PBT £0.2m). As the company is still at such an early stage in its development and offering very limited profit margins for now, I’ll leave my moderately negative stance unchanged, to reflect the view that this is a high-risk play. | |
Eneraqua Technologies (LON:ETP) (£10m) | SP down 32% FY Jan 2025: revenue £63m (<exps? StockReport says revenue forecast is £81m) and PBT in line. Balance sheet strain: exploring interim funding should it be needed. | RED (Graham) [no section below] | |
| Jarvis Securities (LON:JIM) (£8m) | Sale of Retail Execution-only Brokerage Business | SP +14% (RNS at 9:18am) The sale to Interactive Investor goes through for £11m, with £9m to be paid shortly and £2m deferred for up to c. 18 months. JM’s other operations are being terminated/closed down, which will take approx. 15 months. JIM will become a cash shell. Directors intend to make a distribution to shareholders (if allowed by the FCA) and cancel the listing. | PINK (Graham) [no section below] It's a relief that the sale has gone through, but it's still a sad end to the story and I would not be tempted to buy in here with the goal of receiving a cash payment from the liquidation in due course, as I’ve found this deep value strategy to be very underwhelming in the past. My main learning point is to “run for the hills” when companies announce an FCA-ordered skilled person review (see our previous coverage of JIM here). |
Graham's Section
Plus500 (LON:PLUS)
Up 1% to £33.20 (£2.4bn) - Half Year 2025 Trading Update - Graham - GREEN
Plus500, a global multi-asset fintech group operating proprietary technology-based trading platforms, today announces its trading update for the six months ended 30 June 2025.
When I covered this company’s Q1 update in April, I noted that there had been a year-on-year revenue decline (Q1 2025 vs Q1 2024), accompanied by a slowdown in customer recruitment.
Q2 (and H1 more broadly) show a return to growth:
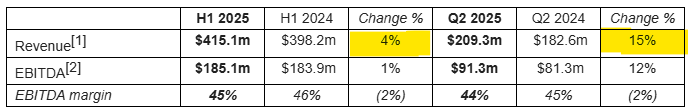
The tariff-related turmoil must have been a big help. Similar stocks such as IG group (LON:IGG) (in which I have a long position) saw their share prices strengthen during April, as more people looked for ways to trade the market volatility.
Plus500 don’t have much to say about that today, instead focusing on their strategic milestones.
CEO comment:
"Plus500 delivered further operational and financial progress in H1 2025. We expanded our global presence with new regulatory licences in Canada and the UAE, added to our growing list of clearing memberships with ICE Clear US and announced the exciting acquisition of Mehta Equities in India, which will provide us access to the largest retail futures market in the world.
H1 growth is attributed to Plus500’s “proprietary technology and unique system architecture”, rather than to the market’s tariff tantrum!
After recruiting 27,000 new customers in Q1, this improved slightly to 29,000 in Q2. The number of active customers also improved.
The standout figure is customer deposits, which increased from $1.5bn in H1 last year, to $3.1bn in H1 this year. Plus500 remind us that they have been focusing on higher value customers - and numbers like this tell us that it is working! Although again, the importance of the market backdrop should not be discounted.
US futures business: this has been highlighted as a significant growth opportunity, and Plus500 tells us that their total non-OTC revenue (futures and share dealing) grew to 13% of their total revenue in H1.
Cash balance has grown since March, to “over $925m” as of the end of June. The next round of dividends and buybacks will be announced at the H1 results in August.
Outlook:
Following a strong start to the year, the Board of Directors of Plus500 remains confident in the outlook for the Group for 2025 and beyond, reflecting the Group's market-leading technological capabilities, balance sheet strength, earnings resilience and the emerging opportunities, particularly within the B2B (Institutional) futures space.
Estimates
The company helpfully provides a footnote stating that consensus forecasts are for FY26 revenue of $746.2m and EBITDA of $345.2m.
A note from Panmure Liberum this morning leaves their forecasts unchanged - they are below consensus, but they note that H1 EBITDA ($185m) is more than half (54%) of their own full-year estimate.
The H1 EBITDA result is also more than half, again about 54%, of the consensus full-year estimate.
Graham’s view
With most of the full-year EBITDA estimate having already been achieved in H1, you’d have to think that there’s a decent chance of a full-year beat. But I do think that market conditions in H1 were especially favourable, even if Plus500 haven’t acknowledged that today.
(I wonder why they don’t acknowledge it - surely it’s what most of their investors are thinking?)
As a reminder, this what the VIX Volatility Index did at the start of Q2:
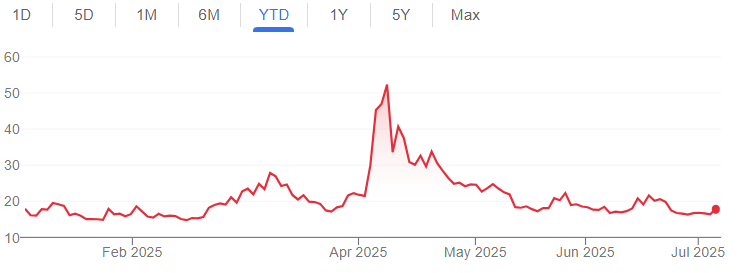
On balance, I think it’s fair to leave full-year forecasts unchanged, as there is no certainty that markets will be as exciting in H2 as they were in H1. So there is no point in getting carried away at this stage.
And overall, I don’t see any reason to change my positive view on this stock.
It has probably hundreds of millions of dollars of surplus cash; adjusting for this would give a slightly smaller earnings multiple.
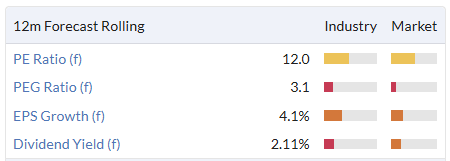
While I’ve never entirely abandoned my reservations around customer churn and the lack of hedging, I’ve been happy to stay GREEN on Plus500 for some time, due to its prodigious cash generation and its ability to return vast amounts of this cash back to shareholders.
With an update today that’s at least in line, I’m happy to leave this view unchanged.
Roland's Section
Shell (LON:SHEL)
Down 3% to 2,543p (£150bn) - Second quarter update note - Roland - AMBER
Today’s second quarter update from Shell follows a detailed format that’s decided to give City analysts some advanced clues on the likely outturn in the company’s next quarterly results.
As I commented in April, I don’t model Shell that closely so instead tend to look for any areas of change relative to previous guidance. Today’s update highlights a few points that show some variance from previous guidance at the end of Q1:
Integrated Gas: profits from the group’s gas business are expected to be “significantly lower” than during the first quarter. This appears to be driven at least partly by lower production, with production guidance trimmed this morning
Q2 gas production expected to be 900-940kboepd (previously 890-950koepd)
Q2 LNG production expected to be 6.4-6.8m tonnes (previously 6.3-6.9mt)
Oil production is expected to be towards the top half of previous guidance.
Chemicals & Products: profits are expected to be “significantly lower” than in Q1, despite improved refinery margins and utilisation. The problem appears to be an unplanned outage at one of the group’s chemical plans, resulting in a quarterly loss for the chemicals sub-segment.
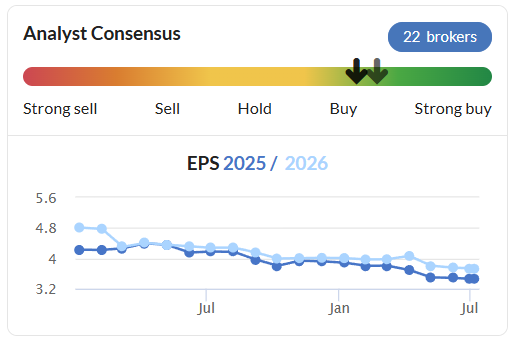
Outlook: analysts have trimmed earnings forecasts for Shell this year. The content of today’s update suggests to me that a further slight moderation may be likely, albeit not a significant change:
Roland’s view
Today’s update appears to be mildly negative and Shell’s share price has fallen slightly.
However, as I commented in April and May, I think minor quarterly variations in performance such as those highlighted today are far less important than the cyclical picture – commodity prices and global demand.
While Shell’s share price has held up relatively well so far this year, given external events, the company’s StockRank has been falling steadily:
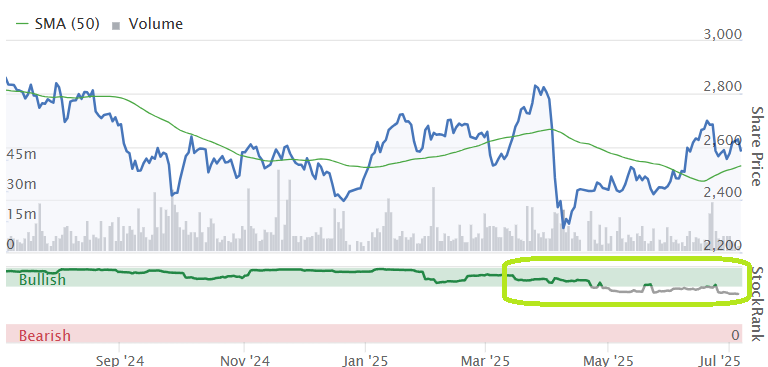
Shell’s StockRank was 94 at the start of 2025, but is now down to 64, with momentum now notably weak:
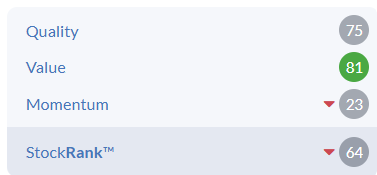
My previous view that the company’s valuation is probably in the upper half of its normal cyclical range remains unchanged.
Indeed, the share price recovery seen since April’s tariff sell-off means Shell’s CAPE10y valuation ratio has now risen to almost 14x (from 12.5x on 7 April):
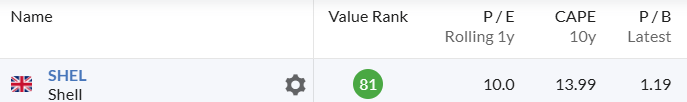
Personally, I don’t find this a compelling valuation at which to buy a cyclical and capital-intensive business with fairly average quality metrics.
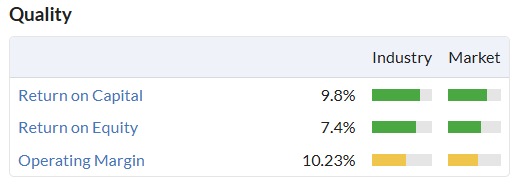
At the same time, I recognise that if market conditions and external events combine to provide support for oil and gas prices, then Shell could continue to perform well and fund further high levels of buybacks and dividend growth.
The StockRanks are neutral at this level and so is my view, which I’m leaving unchanged at AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
Plexus Holdings (LON:POS) I assume that the once we get to the actual day where client confidentiality ends (in July 2025) for the £9m special project they will do another announcement, so we might see a bounce then.
Plexus Holdings (LON:POS)
the fact they have an under wraps customer should not prevent any company from updating ref future guidance one way or another should it ?
surely is the overall expectations that matter - in that regard having pukka broker that can rubber stamp they will have decent income and profits "next year" (commencing 01/07/2026). i guess that might only be possible if they have something firm enough to satisfy brokers. - so lack of any "this year and next year projections" - suggest they are choosing not to provide transparency or cant do so.
If they dont provide that they shareholders will continue to have almost no visibility ref ongoing projects.
If shareholders are expecting transformation from mid next year ref incoem and profits they really need to be pushing the company to get something formally out into the public domain
with nil visibility i cant see how anyone can really try and value this entity ? kstehcy this and that means didly squat - whereas we expecting toi make 0.3 mill profit ye 30/6/2026 and 3 million profit ye 30/6/2027 would at least confirm that there are expected profits and not pipe dreams of being able to make money.
Ref valuation here well on current known knowns i dont think we have anything useful to go on until - we know "how much profit they base profit they will make when the new kit is out doing its thing". I suggests if they dont have active plans to be making £3 mill NET profit next year (starting 01/07/2026) then valuation looks sketchy. Plus that neds to be ongoing sustainable profits - not the stuff they have previously churned out.
The comments on Rockhopper are showing next to Pinewood Technologies in the Companies Reporting table above.
very sorry about that, fixed it! Graham.
Holders of M P Evans (LON:MPE)(I Hold) will be interested in this Palm oil report. "
"Palm oil prices are jumpy this year, with markets rattled by geopolitical tensions and shifting biofuel policies that are reshaping markets for one of Southeast Asia's most important commodities." https://asia.nikkei.com/Busine...
The update from CRPR really annoyed me this morning. They said a lot but in the end said nothing!
After saying they lost a significant customer in Paper & Packaging, they said: The Board's expectations for the Paper & Packaging business in FY26 remain for it to report a significant improvement in Adjusted EBITDA against FY25, and the achievement of run-rate Adjusted EBITDA breakeven in the final quarter.
For the group as a whole:
Overall, the Board is confident that the Group will deliver significant growth in Adjusted EBITDA profitability in FY26 against FY25.
Why not just say: we previously expected to earn X in Paper & Packaging, and now we expect Y. We previously expected to deliver X for the group as a whole, and now we expect Y.
The broker left forecasts unchanged, which does say something, but the broker's commentary didn't add much clarity, either.
In summary: there were far too many words and far too much effort to "PR" the message. Why not just give us the facts?
Remind me again, why are the London markets in decline? Peel Hunts boss was on R4 this morning welcoming the 'new relaxing' of regulation! Honesty is not found in the City of London.
An excellent trading update from Coral Products (LON:CRU) today. "Profitability expected to be materially above market expectations ....".
Released mid-morning, as usual, in a cunning plan to ensure this good news gets minimal attention.
https://www.investegate.co.uk/...
Metals Exploration (LON:MTL) (I hold). Many subscribers are interested in this one because it is in the NAPS portfolio.
Massive price rise recently, but bearish points are that Jim Mellon (Britain's version of Warren Buffett) is reducing his stake. There have also been some large management share options granted.
The current price is full, on a PER of 11. Thinking of selling half and putting it into Thor Explorations (LON:THX), who are on a lowly PER of 3.
If Graham and Roland have time, a brief review would be very welcome.
Yes, MTL will get a brief review, Epitychia! Thanks for mentioning it.
Actually, I've just looked into this and there's no news from MTL today, and we can't see any significant news from it recently. So actually this isn't something we can put into today's report. Sorry! Do feel free to continue sharing your own view on it. G
Jarvis Securities (LON:JIM) have just made an announcement, shares are up 15%.
Thanks Rusty.
I am one of many x-o customers proud to have reported them to the FCA. IC was a big fan, they laundered money for some of the most evil people on the planet (allegedly) due to lax controls and brown envelopes. Good riddance! But they get to keep the money. It's London stupid!
Another of your snotty comments (your words) at people who can't defend themselves snowflake. You made similar allegations some months ago while still a customer and hoping the deal went through so it wasn't so bad. I prefer the reply to that comment from albertos:
Or are they just a small player outside the City which the FCA hate and know if they tie them up in knots for a couple of years they'll become unprofitable and throw in the towel.
Who knows?
But I know what I think.
I expect anyone who knows the whole story is tied up in non disclosures but I was a satisfied customer and investor in JIM for 20 years with no complaints and as far as I'm aware their only sin was trusting their Model B (white lable) clients to do the right thing in vetting their clients. How come it took 20 years for the FCA to regulate them, was it politically motivated to get a hide to nail to the wall to encourage the others?
I am sure they will have tried their utmost to defend themselves,
Metals Exploration (LON:MTL) Ok thanks. A puzzle why it climbed 10% on Friday. Maybe a bid in the air?
SHEL is an interesting one for income investors, perhaps. P/FCF is 6.8, so a free-cashflow yield of around 15%. That's a lot. The fly in the ointment is that they've announced lower profit. But still, there's some margin of safety here. Brent is about $68, which seems neither too low not too high. So, meh, a 10% free-cashflow yield seems the least you could get. Not bad.
If you really wanted to play oil though, buy SHEL when Brent is $40 and sell if it reaches $80.
Thanks for that Mark! Roland is working on SHEL this morning. G
I wouldn't put too much emphasis on Brent though.....SHEL is very exposed to LNG/gas and in a few years LNG/pipeline gas revenues will exceed oil products. Has very high spot LNG exposure.
This is worth being aware of (i.e. claims that SHEL is too bullish on LNG), although I'm not qualified to comment on it:
https://www.accr.org.au/downlo...
Maybe James Cropper (LON:CRPR) should be renamed 'James comes a cropper'! Can't say I'm too unhappy to see David Stirling struggle, after he ramped the potential of 'Rezorce' at Zotefoams (LON:ZTF) then dumped his stock at a peak price and departed before it got ditched as soon as the new CEO came in!
Never nice to wake up to a profit warning on a Monday morning!
Its a mixed bag in the statements. I wrote up something longer on my Substack, but my key thoughts:
I don't like that they didn't talk much about Advanced Materials in the TU, much more about Paper. I get that's the division where the warning is - but their strategy should be to really focus on the potential of AM, as the much higher margin part of the business, and the area with most growth potential. Unless, of course, the subdued commentary means AM is not performing well either?
(I hold in the Boon Fund)
News feed not showing some folio news...Rockhopper Exploration (LON:RKH) insurance news found on free site but not on stocko. Any advice on setting please.
If you play around with your settings, it will come up on the newsfeed, it is on mine, probably under "other".
Thanks Rusty2...it did pop up at 07:18. My issue is that a free site is showing RNS at 07:00 and Stocko which costs a pretty penny has an 18 min lag. Opening the Stocko RNS is pretty illegible where free site is formated. Currently evaluating the value of the paid service.
America Party launched by Elon Musk. Endorses Bitcoin as he says "Fiat is hopeless "
It's true they are. And Alfa Romeo
Abarths are fun though, even if they do fall apart, far more interesting than Teslas. Perhaps he should put all his money in the Smarter Web (OFEX:SWC) company, doesn't look like a Ponzi scheme one bit.
Gone from goading a sitting President, to his now entire political party and the Country's dollar strength!? Sounds like his software needs an update.
It looks like the investment in sales staff by Corero Network Security (LON:CNS) is beginning to pay off.
$1.5 million CORE platform contract expands Corero's TierPoint relationship
- $0.3 million CORE platform agreement with Cooper Health