Daily Stock Market Report (Thur 10 April 2025) - 90 day pause, RNK, BBSN, JD., TET, TTG, TSCO, THS, MRK, NXR, SPEC

Good morning! These markets are extraordinary - the S&P rose 9.5% yesterday and the FTSE is this morning scheduled to open up by 5% after Trump announced a 90-day pause on his "reciprocal" tariffs - with the exception of China.
Comment from Mark:
Good morning! Mark here. It’s going to be a good day! The FTSE futures are up over 5% as Trump tweeted last night that tariffs on everywhere but China would be “paused” for 90 days at 10%. Unfortunately, the UK was already at 10%. However, oil rose around 10%, Gold was up 4% and the NASDAQ almost 10%, so these factors have dragged the FTSE higher.
I can’t help feeling that this isn’t all over, though. Even 10% tariffs embed inflation into the US economy, perhaps meaning rates stay higher for longer. Plus, who would make a major investment decision when policies are changing so rapidly? So we may see a US recession anyway. 90 days is long enough for a brief respite and then markets to start to worry about the upcoming “cliff edge”.
However, today isn’t a day for such a curmudgeonly reality. Enjoy the rise for as long as it lasts!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Tesco (LON:TSCO) (£22.4bn) | Preliminary Results | FY25 guidance: adj. operating profit £2.7 - 3.0bn (FY25: £3.1bn). Increase in competitive intensity. | AMBER (Megan) Despite the slightly tempered outlook, I’d argue that some trends are still on Tesco’s side (lower propensity of Brits to spend out, economic turbulence favouring defensives). It’s a tempting option in markets like these, but neither exciting, nor cheap enough for me at these levels. |
Anglo American (LON:AAL) (£21.4bn) | Update on Sale of Coal Business | Working towards satisfying customary conditions. | |
JD Sports Fashion (LON:JD.) (£3.6bn) | Share Buyback | Initial £100m buyback starting today. | AMBER (Mark - I hold) [No section below] Technically, this news was announced as part of the midday trading update yesterday but RNS'ed this morning. Seems mistimed to start a buyback on a day the shares are up 11%, but this is just the tariff news, which is positive for JD. This is a great business on a modest rating, so buying back shares makes sense. With guidance of being net cash after the buyback by the end of the year, this doesn’t place them in any difficulty either. Some doubts over strategy and reliance on brands remain, hence the AMBER rating overall. |
Great Portland Estates (LON:GPE) (£1.0bn) | Q4 Business Update | Strong end to year. 32 leases & renewals, 9.9% above their March 2024 estimated rental value. | |
Rank (LON:RNK) (£365m) | Trading Statement | Like-for-like net gaming revenue up 10.9% in Q3, up 12.2% YTD. Full year profit expected in line. | GREEN (Graham) Very pleasant growth rates, a rising trend of earnings forecasts, and a modest earnings multiple. I'm a fan of this one at current levels. |
Foresight group (LON:FSG) (£348m) | FY TU | Expect FY25 core adj. EBITDA to be in line (£62.2 - 63.8m). New buyback: up to £50m over 3 years. | |
Mears (LON:MER) (£324m) | Final Results | Strong start to 2025. Increases 2025 guidance, revenue >£1,050m, adj. PBT >£50m. | |
Petrotal (LON:PTAL) (£300m) | Q1 Ops and Financial Update | Q1 production 23,280 bopd. Tracking ahead of annual guidance. Cash flat at $114m. | |
Treatt (LON:TET) (£195m) | Trading Update & Share Buyback | Profit warning. H1 lower than last year. Now expect FY25 revenues £146-153m, PBTE £16-18m. | AMBER/RED (Graham) Downgrading this after a serious profit warning. I do perceive value on a fundamental basis given the assets on the balance sheet, the lack of debt and the track record of profitability. However I do need to downgrade my stance to reflect that one profit warning is rarely the beginning and the end of the bad news. |
Norcros (LON:NXR) (£178m) | FY Trading Update | FY25 adj. profit in line. Net debt flat at c. £37m. Strategic review of Johnson Tiles South After. | AMBER/GREEN (Mark) [no section below] This is on a low P/E, and these results confirm that they are in line on an adjusted basis. However, LFL revenue is flat, so this perhaps shouldn’t be on a high rating. When I look at measures that include the debt, and adjust for the ongoing pension contributions, this isn’t as cheap as it first appears. Getting rid of their loss-making tile business in South Africa may give a further uplift, and the algos like it, giving it a Superstock classification due to its consistent score across all three QVM measures. |
TT electronics (LON:TTG) (£148m) | FY Results, Management Changes & Business Update | Rev -13% CCY, EPS down 34% to 11.0p. Net debt £97.4m (1.8x leverage) CEO falls on his sword, with immediate effect. CFO designate becomes acting CEO. | AMBER (Mark) |
Tharisa (LON:THS) (£142m) | Q2 Production Report | PGM production +8.7%, Chrome Production +1.8%. PGM price +2.9%, Chrome price -13.3%. Net Cash $79.3m. | AMBER (Mark) |
Savannah Resources (LON:SAV) (£113m) | FY Results | Loss of £4.4m, Cash £17.7m. | |
hVIVO (LON:HVO) (£100m) | Final Results | Rev +12% to £62.7m, EPS +33% to 1.69p. Orderbook £67m vs £80 million at FY2023. Outlook: Revenue guidance £73m, with H2-weighting. continued profitability and cash generation. | |
Devolver Digital (LON:DEVO) (£93m) | Preliminary Results | Rev +13.5% to $104.8m, loss $6.4m in line with previous guidance. Outlook: Strong pipeline but H2-weighted, single-digit revenue growth, similar bottom line to FY24. | |
Iqe (LON:IQE) (£93m) | Joint Development Agreement | JDA with X-FAB to create a European-based GaN Power device platform solution. | |
Marks Electrical (LON:MRK) (£60m) | FY25 Pre-close TU | Rev +2.6%, Net Cash £8.8m. Adjusted EBITDA down 16% to £4.2m. Maintained 2026 guidance. | AMBER/RED (Mark) |
Enwell Energy (LON:ENW) (£59m) | Quarterly Ops Update | 1,865 boepd, down 12%. Cash $101.8m of which $15.9 is in USD/GBP/EUR. Ceased all field operations following suspension order. | |
Inspecs (LON:SPEC) (£40m) | Final Results | Flat revenue on CCY basis, Op profit up 17% to £3.4m. Net debt excl. Leases slightly reduced to £22.9m. 25Q1 in line with expectations. | AMBER/RED (Mark) [no section below] |
Brave Bison (LON:BBSN) (£30m) | Final Results & Strategic Acquisition | Acquisition of “The Fifth Group” for £1m of shares at 2.5p, cash of £0.575m and up to £6m contingent consideration. | AMBER/GREEN (Mark) |
Renalytix (LON:RENX) (£25m) | Q3 TU | In line. 20% Q-Q revenue growth. | |
Cambridge Cognition Holdings (LON:COG) (£14m) | Contract Win | £1m over 6 years. |
Graham's Section
Rank (LON:RNK)
Up 4% to 81.4p (£381m) - Trading Statement - Graham - GREEN
Let’s take a look at this brief trading statement.
Like-for-like numbers for Q3 are encouraging, with >10% growth in the major categories of Grosvenor (casinos) and Digital:
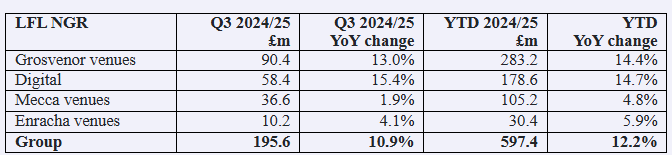
At the Digital business, I note a big divergence between the UK (+18%) and Spain (down 2.9%).
At Grosvenor casinos, investment has paid off with 14.5% growth in table gaming (poker, blackjack, etc.).
CEO comment:
"Since announcing our interim results in January, we have continued to deliver strong growth and expect to deliver Group like-for-like operating profit for the full year in line with expectations. This is notwithstanding the uncertain economic environment and the significant cost and regulatory headwinds that we face from the start of Q4 (1 April 2025).
We expect the Government to publish the statutory instruments for land-based casino reforms in the coming weeks and anticipate the roll out of additional machines and sports betting to commence during the summer.
Graham’s view
This stock has been depressed since the inflationary period of a few years ago:
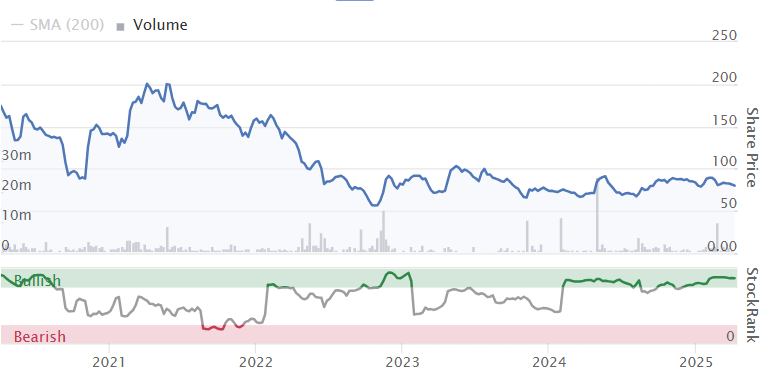
I’ve been GREEN on it for a while, in anticipation of profit margins recovering with improved consumer sentiment and with lower inflation.
This seems to be playing out:
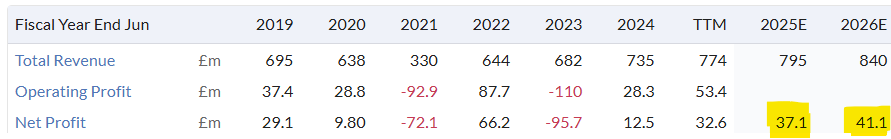
Recent interim results showed an underlying like-for-like operating profit of £32.9m (previous year: £21.2m).
Expectations were raised for the full year:
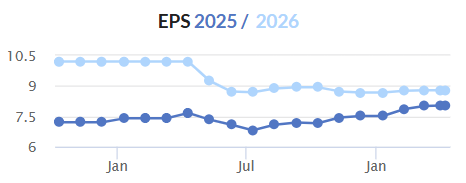
Given the pleasant trend in earnings forecasts and the cheap earnings multiple (9x), I think I can have few qualms about keeping my positive stance on this one.
The StockRank is a healthy 86:
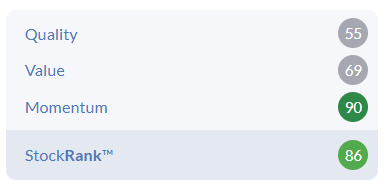
Being a largely physical rather than online business, it does carry more risks than its purely online equivalents - exposure to fluctuating wage costs, energy, tourism trends, etc. But when it’s firing on all cylinders it is highly profitable, and I tend to think that the risks are priced in at these levels.
Treatt (LON:TET)
Down 26% to 237.5p (£143m) - Trading Update - Graham - AMBER/RED
Treatt, the manufacturer and supplier of a diverse and sustainable portfolio of natural extracts and ingredients for the beverage, flavour and fragrance industries, announces the following trading update for the half year ended 31 March 2025 (the "Period").
Unfortunately I was AMBER/GREEN on this one last time, when I looked at Treatt’s full year results in December.
Today’s update contains little positivity. Let’s start with some H1 highlights:
Revenue £64.2m (H1 last year: £72.1m)
Adj. PBT £6.6m (H1 last year: £10.6m)
Net cash £0.9m.
Outlook:
Whilst the order book and pipeline are robust, including some exciting new customer wins in Premium, we now expect full year PBTE to be between £16m and £18m, reflecting an ongoing softening of consumer confidence in North America, recent geopolitical uncertainty and sustained high citrus prices, resulting in lower customer demand
The new full-year revenue forecast is £146 - 153m. At the midpoint, that's about 8% lower than the previous consensus forecast.
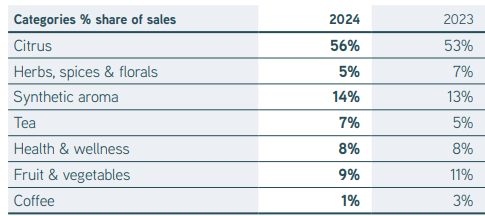
The company's “Heritage” segment seems to be suffering from particularly weak demand - this segment includes their main “Citrus” category (56% of total sales last year) and “Synthetic aroma” (14% of total sales).
The “Premium” segment is smaller and includes “Fruit & Vegetables”, “Health & Wellness” and Tea.
An overview of the categories from the 2024 annual report:
Treatt says that US consumer confidence “has softened, impacting demand for carbonated soft drinks and the overall beverage market in North America”, and they don’t expect it to get better given recent macro developments.
They’re not wrong about that: see this update from the US Consumer Confidence Index two weeks ago.
The Expectations Index—based on consumers’ short-term outlook for income, business, and labor market conditions—dropped 9.6 points to 65.2, the lowest level in 12 years and well below the threshold of 80 that usually signals a recession ahead.
Turning back to Treatt’s announcement:
Notwithstanding these trading challenges which we expect to moderate, we are encouraged by some exciting wins in Premium, including securing a large new customer in North America, and capitalising on the low and no sugar trend. Additionally in New Markets, we have a healthy pipeline of opportunities for H2 and are progressing distribution arrangements to expand our reach.
Buyback: it’s a strange sort of day to announce this, but Treatt announces a £5m buyback which reflects their “strong cash performance together with the Board's confidence in Treatt's strategy and medium term outlook”. They did successfully eliminate nearly all of their net debt in the previous financial year.
Graham’s view
To be consistent with our understanding of profit warnings - that they tend to be followed by a protracted period of poor performance - I’m going to have to downgrade our stance on Treatt today.
That said, I do think that the stock might be close to a “deep value” sort of price.
The balance sheet for September 2024 showed net assets of £142m, around the same level as the current market cap. This value was almost fully tangible, consisting in the main of PPE and working capital, and with almost no debt.
I also note that (before today) the stock passed 5 bullish stock screens, including some old favourites such as Ben Graham’s Deep Value Checklist.
If it was already in deep value before today, it surely must be there now after a 30% fall!
The company has been profitable every year for decades, although its profitability does tend to be volatile. As a result, its quality metrics are volatile, too. There is clearly a substantial amount of economic sensitivity at play.
Based on the new profit forecast, I think it’s trading at around 11x adjusted after-tax earnings.
I would bet that Treatt’s profitability will bounce back from this period of weak consumer confidence. It has recovered in the past from similar setbacks. And with a sound balance sheet, I’d argue that the stock offers above-average value at current levels.
However, I have to respect the fact that there’s been a profit warning, so I’m going to be AMBER/RED on this today.
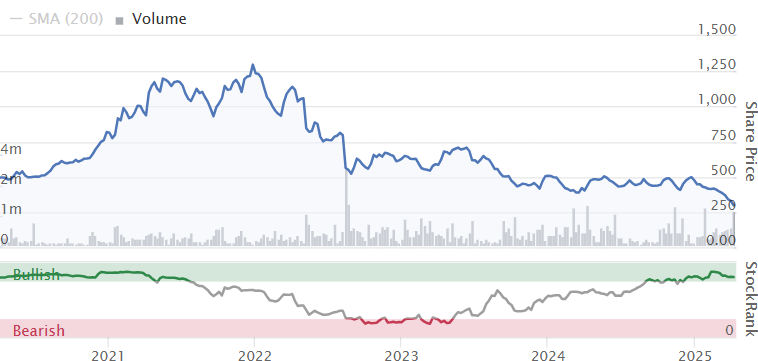
It has been quite the journey from a high of over £13:
Megan's Section
Tesco (LON:TSCO)
Down 6% to 316p (£21bn) - Final Results - Megan - AMBER
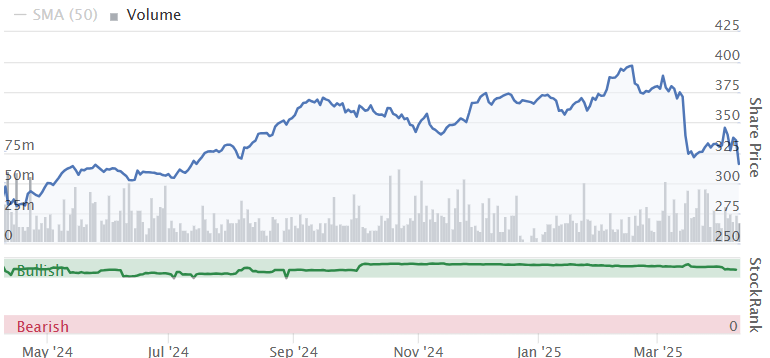
There is one line in final results from supermarket giant Tesco which has caused the blip in the share price this morning:
“In the last few months, we have seen a further increase in the competitive intensity of the UK market.”
It seems as though this competition is forcing the company to chip away at prices, which means adjusted operating profits are expected to be between £2.7bn and £3bn next year (down from the £3.1bn reported in these numbers). It’s not a profit warning as such (the company hadn’t previously issued any clear guidance for the 2026 financial year), but it’s a downturn in trajectory that analysts had previously forecast.
None of that takes away from the fact that Tesco has done a phenomenal job at keeping competition at arms length. The company’s share of the UK market has now climbed for 21 consecutive months and is now at its highest level since 2016.
Looking at data from Kantar Media suggests that the market share has been taken from Asda, Morrisons and Sainsbury (all of which have seen their market share decline). And while it has had to share that newly available market share with Aldi and Lidl, the momentum of those European discounters has slowed in the last couple of years.
Tesco can thank its Clubcard for such impressive resilience. In FY2025, 84% of sales were clocked on a Clubcard and there are now 18m Tesco Clubcard app users in the UK. This loyalty scheme is built on the premise that Clubcard customers can get their basic goods at cheap prices (and basic goods normally are cheaper than the likes of Aldi and Lidl). Then, having been brought into store for the cheap weekly shop, loyal customers will be tempted by higher priced items. In FY2025, Tesco’s ‘finest’ range rose 15% to £2.5bn. This helped send adjusted operating margins up slightly to 5% (from 4.6% last year).
There is, however, only so much heavy lifting that the Clubcard can do. And as market penetration rises, the opportunities for the loyalty scheme to make a difference begin to diminish.
Throw in the fact that cost pressures are rising, and the outlook for the business is not as sunny as investors would have liked.
In FY2025, the company was forced to take a £289m non-cash impairment on the current fair value of assets, most notably, its stores. This was a result of an increase in both costs and discount rates (owing to a rise in government bond rates) which has undercut the current value of future cash flows expected from these stores. The impairment dented reported profits in FY2025.
Megan’s view
At first glance, there’s not an awful lot to be excited about here. Margins and return on investment aren’t especially high, while growth is as good as can be expected for the country’s largest supermarket chain.
But Tesco has been well managed. That is shown in the fact that while revenues have only risen at a compound annual rate of 1.5% in the last five years, earnings CAGR is almost 10%.
Investors who bought at the nadir in 2016 will have doubled their money. But that nadir was not hugely tempting. At the time, the company was facing bankruptcy risk, having reported its biggest loss in 100 years of trading following a major accounting scandal. At their low point, shares were trading on 18 times forecast earnings.
The stock still hasn’t reclaimed its highs of pre-2008 financial crisis, but after decent momentum in the last few years (barring the market-driven declines of the last couple of months), shares are now trading on 12 times forecast earnings. Although it’s worth noting that these forecasts might decline after today’s update.
So it’s not really a value play and it’s certainly not a growth stock. But it is the market leader in a sector for which trends are currently supportive. It’s also defensive, which is what investors need in times like these. On balance, it’s not for me, but for investors looking to deploy their cash into a stock that can weather international economic turbulence, it might not be a bad option. AMBER
Mark's Section
Brave Bison (LON:BBSN)
Up 17% to 2.7p - Final Results & Acquisition of The Fifth Group - Mark - AMBER/GREEN
This highly acquisitive company continues to make good deals. This time, it is “The Fifth Group” which is described as:
…the award-winning influencer marketing division of News UK. The Fifth was founded in 2019 and delivers influencer marketing, social strategy and end-to-end creator-led campaigns for brands including YouTube, Disney+, UKTV, FOX Entertainment, Tommee Tippee, The Times, TSB & SamsungTV.
Most importantly, this is another deal where most of the payment is contingent on performance:
On completion of the Acquisition, News UK will be issued with 40 million new Brave Bison ordinary shares (the "Consideration Shares"), worth £1 million at an issue price of 2.5 pence per ordinary share, and will receive cash consideration of £0.575 million. News UK will also receive 25% of profits generated by The Fifth over the next three years, capped at £6 million (the "Contingent Consideration").
Their broker Cavendish today say:
Following the recent acquisitions of Engage, Builtvisible and The Fifth, we are confident in raising our net revenue forecasts by 18% to £25.5m, and nudge up adj PBT by £0.1m to £3.9m. The acquisitions are likely to contribute positively to profits in the first year, but are partially offset by National Insurance rises from April 2025. Net cash reduces by £4.7m, but remains healthy at £5.3m.
We also get final results today, which are presented in a very handy table:
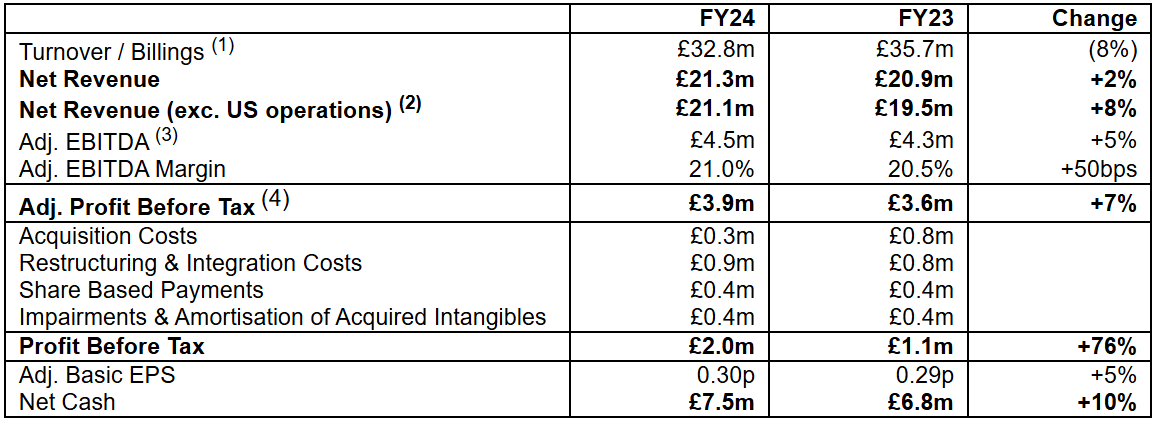
However, the thing that stands out is that almost none of the adjustments here are exceptional. This company doesn’t look like it will stop acquiring businesses that need restructuring. Plus, the key management intentionally caps their salaries and gives themselves options at 3p/share. While this undoubtedly makes them strongly aligned to shareholders, it also makes that SBP charge a real cost. A more realistic EPS figure is probably around 0.2p.
Cavendish also says:
Brave Bison’s valuation looks highly compelling given it trades on an FY1 adj P/E of just 8.1x versus peers on 9.3x, whilst retaining significant net cash and growing net revenues by 20% in FY25E.
This seems nonsense. How can a slight discount to peers be “highly compelling”, especially as the revenue growth is all inorganic, and the rating becomes a premium if one includes all the costs associated with the acquisitions?
Outlook: They remain positive, highlighting their long-term track record of growth. Saying:
We continue to win new clients, expand our capabilities ahead of the competition and make accretive acquisitions that drive us forward. We are excited for the future and look forward to updating shareholders throughout the year.
Share consolidation: a 100:1 consolidation also announced today will make the share price look more normal for UK companies, but, of course, it doesn’t change the fundamentals.
Mark’s view
It is hard to be too harsh on this business as it is cash-generative and is putting that money to work by getting some very good deals where they have to put up little cash up front. After the last acquisition, I rated this AMBER/GREEN at 2.4p. With the shares having nudged up since, but forecasts remaining largely flat, despite another acquisition, it is tempting to downgrade this. However, I think the long-term growth story remains intact, as demonstrated by today’s deal, so I am happy to leave the stance as it is.
TT electronics (LON:TTG)
Down 11% to 74p - Final Results & Management Changes - Mark - AMBER
Management changes: CEO Peter France to leave with immediate effect. Eric Lakin, CFO designate, to be appointed acting CEO. This leaves quite a management gap. Their former CFO is retiring, so they appointed a CFO designate, and no sooner has he got his feet under the table than he is running the show. All this during difficult times.
Business changes: It looks like consultants are being used at the Cleveland manufacturing facility to try to turn this around. They are also likely to be closing or selling their components manufacturing in the US, saying:
The downturn in the Components market and the associated impact on our dedicated manufacturing facilities servicing that market, mostly in North America, has highlighted the sub-scale nature of this business. Accordingly, the Board has determined that the Company will now assess all options in respect of this business segment.
Their Final Results also released today reveal the issues:
In North America, distributor de-stocking, which has continued for longer than originally expected, had a significant impact on demand for our components products. We took cost action, reducing headcount by almost 400 in the first half equating to £9 million of annualised benefit, to offset the lower demand; the £1.7 million severance costs were incurred within adjusted operating profit in the period. In the second half we took further cost action reducing headcount by a further 100 heads (severance costs of £0.6 million) and bringing the annualised benefits to £12 million in total. Furthermore, we experienced operational execution issues in two North American sites, Cleveland and Kansas City. This, combined with the performance of the component business created a significant profit shortfall in North America. In light of this trading performance and reflecting a revised view of recovery, we have booked a £52.2 million non-cash write-down being a £36.7 million non-cash impairment of goodwill for the region and £15.5 million write-down in respect of assets within a North American components site.
This table shows the impact on their North American operations:
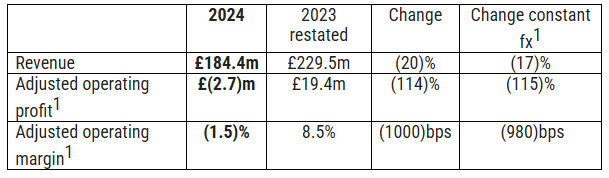
In contrast, European revenue was up 14%, excluding divestments they made, with a 66% improvement in operating profit. Asia had a 6% underlying revenue decline but an operating profit improvement of 27%. This is very much a North American problem for the company.
“Project Dynamo”: This is the name they have given their efforts to fix the problem. This is wide-reaching with eight workstreams spanning cost savings (£17m net), working capital (£27.8m by the end of 2026), commercials and innovation. These all seem sensible actions, but it will take some time to see the benefits.
Going Concern: In their Severe Downside scenario they would need to take mitigating actions:
This severe downside scenario reduces EBITDA by £11.7 million, £23.9 million and £29.3 million for the 12 months to 30 June 2025, year ended 31 December 2025 and 12 months to 30 June 2026, respectively. At these levels of EBITDA, the modelling shows that the Group would need to implement some mitigating actions in order to meet the financial covenants. These mitigations could include but are not limited to reducing incentive payments, wage and salary savings, reduced dividends, capital expenditure and additional working capital measures. In this severe downside scenario, to remain compliant with covenants, the Group would need to implement mitigating actions with a EBITDA impact of circa £5 million or cash flow impact of circa £16 million, which the Board believes would be readily achievable from the range of mitigating actions available to the Group. After the impact of these mitigations, the modelling shows that severe downside scenario passing the financial covenants.
These do at least look severe compared to the covenant EBITDA of £45.6m that is calculated in these results. However, none of these actions are yet in response to the tariff announcements, which are specifically mentioned as an additional risk in the going concern statement:
However, the recent introduction of US global tariffs and certain retaliatory tariffs provide an uncertain and volatile macroeconomic backdrop which could have an impact beyond that assumed in the severe downside case. This has led the Board to conclude that it is not possible to be certain of meeting the covenant test in certain extreme scenarios, in particular where customer reticence in placing orders against the backdrop of tariff uncertainty reduces order intake. Even in this scenario, the Company would seek to negotiate an adjustment to its covenants. These matters represent a material uncertainty which may cast doubt upon the Group's ability and the Company's ability to continue as a going concern for the period up to 30 June 2026. The financial statements do not contain the adjustments that would result if the Group and Company were unable to continue as a going concern.
This will worry many investors as there is a real and unquantified risk from tariffs to this business. Unsurprisingly, with this going on, they are not paying a dividend.
Debt: Indeed, it seems they probably can’t pay a dividend as they have agreed on a relaxation of debt covenants that prohibits it if interest cover falls or is forecast in the next two testing periods to fall below 4.0 times. At 31st December 2024, interest cover was 4.4x, so this is fairly tight against this restriction. The leverage ratio is better at 1.8x versus a covenant of 3.0. The overall net debt has been improving and stands at £97.4m, including lease liabilities, versus £126.2m the year before.
Pension: This is one defined benefit scheme that was actually in surplus, and not just on an accounting basis. They got a buy-in for the UK scheme in 2022, and a buyout is being finalised. This will probably see the remaining £7.1m surplus returned to the company.
Adjustments: The bulk of these were goodwill and asset write-downs, which means that it is probably reasonable to take their adjusted figures. Operating cash flow exceeds operating profits, and with capex running below depreciation, this is at least generating cash to pay down their debt.
Outlook: There is no research available to individual investors, but this reads like a profits warning:
We remain resolutely focused on our operational improvement plan, Project Dynamo, and our clear action plan to improve operational efficiency and productivity however the current uncertainty has increased the downside risk for the Group and the board now expects adjusted operating profit to be in the range of £32 million to £40 million.
This year’s adjusted operating profit is pretty much bang in the middle of that range, suggesting that the mid-case EPS will be around 11p again. This is around 30% below the consensus in Stockopedia:
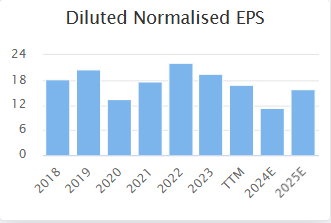
Hence, the drop today is fully understandable. However, it does mean the forward P/E is now around 7x, which may be cheap. However, with the sizeable net debt, it is also worth looking at other measures, such as EV/EBITDA. Here, the Market Cap is £132m at 74p, and the EV around £230m. EBITDA is given as £50.9m, giving an EV/EBITDA of 4.5. This isn’t particularly cheap, but if we consider this the nadir in terms of trading, there is scope for this to look like good value on any recovery.
Mark’s View
The good news is that the problems here are primarily restricted to the North American operations. The actions taken in Europe and Asia, including non-core divestments, have significantly improved profitability there. The plan for a similar turnaround in North America is far-reaching and looks very sensible. If this goes to plan, the business will look cheap. Volex recently made a partial share offer for TT that valued the business at around 130p, which was rejected as undervaluing the business. During the rebuff, management revealed that they had received higher cash offers that they also turned down. With a now-reduced board, they may be more amenable to considering one of these. However, the bad news is that tariffs have the potential to throw a spanner in the works, and these are specifically mentioned in their qualified going concern statement. Any impact here is highly uncertain and possibly significant. Graham went with an AMBER stance in February, and given the risks, I’m going to take the cop-out option and go for the same.
Tharisa (LON:THS)
Up 8% to 53p - Q2 Production Report - Mark - AMBER
Weather interruptions meant that reef mining was down about 12%. However, higher recoveries saw a slight production increase for both PGMs and Chrome:
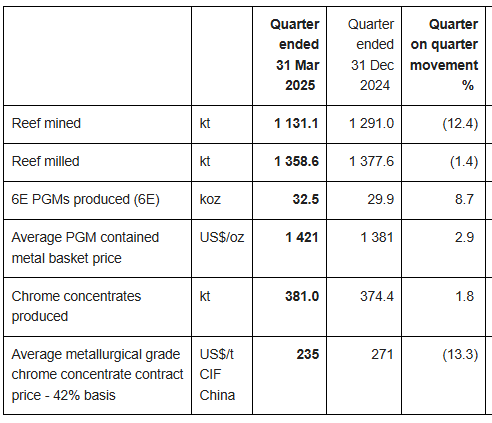
However, pricing was under pressure this quarter, particularly for chrome concentrate. Looking further forward, worries over auto production have impacted spot prices for PGMs, but Chrome has strengthened. How long this will remain, given the US tariffs on China, is uncertain.
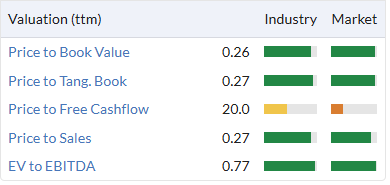
Production guidance remains steady with that given with Q1 production, which means that barring a huge collapse in commodity prices, this will remain one fo the cheapest stocks on the UK market:
However, the market still has significant doubts over their strategy of investing into developing the Karo PGM mine in Zimbabwe. Even on a reduced development plan this is taking up all their operating cash flow and more, which sees net cash falling:
Group cash on hand of US$175.1 million (30 September 2024: US$217.7 million), and debt of US$86.1 million (30 September 2024: US$108.8 million), resulting in a net cash position of US$89.0 million (30 September 2024: US$108.9 million)
Mark’s view
I had this as AMBER following their FY results last year due to the large capex committed to developing Karo. Since then, the share price is down from 65p to 53p. However, the company’s strategy looks even riskier in a world where tariffs have the potential to significantly curtail commodity demand, so I maintain my wait-and-see stance.
Marks Electrical (LON:MRK)
Flat at 57p - Trading Update - Mark - AMBER/RED
Marks issues a multi-year profits warning in November with several issues contributing to their problems:
An new ERP system was reducing their capacity for deliveries
A move away from more premium products, which reduced order value per van.
I commented that this left them between a rock and a hard place; in order to try to recover profitability, they are going to have to forgo sales growth, and there may be a limit to the number of premium brand customers in the current market. They continue with this strategy saying:
We are actively pivoting the business back to our historically successful premium focus, in order to deliver an uplift in margin performance. This strategy is on-track and margins improved in the second half of FY25, despite a weak peak trading period. Our objective in FY26 is to continue to drive this sustainable margin recovery and this focus may be at the expense of revenue growth.
At the time of the profits warning, Canaccord cut 2025 revenue from £126m to £119.6m and EPS from 3.5p to 1.5p. So this appears to be a further revenue miss:
Record full year revenue of £117.2m (FY24: £114.3m) representing a growth rate of 2.6%.
They talk about margin improvements, so things may look better for the bottom line but I don’t think we can rule out this also being an EPS miss.
Outlook: They say:
As predicted, our H2-25 growth rate was impacted by the ERP switchover, resulting in a decline in revenue during the period of October to December, but this was quickly followed by a return to growth from January to March. This improvement in underlying growth momentum, with a strong exit rate in March of 6.6%, provides us with the confidence to maintain our guidance for the year ahead.
They will need to keep up this March exit rate over the next 12 months to hit Canaccord’s FY26 revenue forecasts, in tricky market conditions. Even if they do, it will put them on a 34x 2026 P/E.
Mark’s view
This still looks materially overvalued on any medium-term forecasts. That the share price hasn’t sold off further is probably because Frasers Group have been actively buying and are now the second-largest holder. Mike Ashley clearly thinks he can run things better, but with founder Mark Smithson still holding over 70% of the shares, it seems unlikely he can force the issue. Hence, it’s an AMBER/RED for me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

83 comments
Norcros (LON:NXR)
Graham
When I look at measures that include the debt, and adjust for the ongoing pension contributions, this isn’t as cheap as it first appears.
Whilst that is fair comment Norcros has had a decent history of being able to reduce debt quite quickly generally speaking.
Thanks to the most excellent people at Equity Developmnets we have a new note update that confirms they expect net debt to drop down to under £13 mill by 31/03/2027 - thats less than 2 years away. So i understand to a degre that the debt is real - but simply the normal course of their business will chop that down very quickly based on current projections being met . They have had decent form in the past ref delevering on promises ref debt reduction. so at present i would say that the debt is a somewhat "temporary peak" which is to be expected with the GW chunky Acquisition not so long back.
Ref the pension - there is also good news in that regard too - as per the recent pension update the company expects that from June 2027 the contributions may drop from £3.8 mill pa to £1 mill pa - with those funds going into escrow so some possibility they may be able to claw back something ref that £1 mill pa. No guurantees here plenty that can go wrong with pensions!! - i would expect that they would not be sying this though if they were not decently confir
So 100% correct with regard to these current state of play - but they simply need to keep plodding along for the next 24 months with things being as expected for these 2 issues to subside.
I wont disagree that growth is anaemic at best which is probbaly the main issue looking at thne investment case - at least ED have the eps numbers increasing in 2026 and 2027. with the current low level of contruction/housing/consumer spending on homes levels - keeping ones head above water is not the worst result in the world.
link to ed note on company website - why cant more companies have quality projections like this on their website?
https://www.equitydevelopment....
Update ref pension contributions
The schedule of cash contributions to June 2027 of £3.8m per annum (indexed by CPI) that was agreed in the 2021 valuation, will continue. As a result of the new agreement, once the Scheme is deemed to be in surplus on a technical provision basis, contributions will be directed to an escrow arrangement. Cash contributions post June 2027 are expected to be less than c.£1m per annum and will only be paid to the extent that asset performance or any escrow funds do not cover ongoing scheme administration fees. The escrow arrangement minimises the risk that the Scheme becomes overfunded with a trapped surplus.
Nat Rothschild just bought another £250k’s worth of Volex (LON:VLX) - bodes well, he’s up to 25% of the company now
At the moment it looks as though the S&P500 is going to lose all yesterday's gain.
Mears MEA no-one seems to be looking at this beyond a few comments in the intro (I may have missed comment below if so apologies). I would rate it as much more important than BB or Treatt as it is in one of my portfolios whereas I have sold both of the others!
Basic - diluted EPS last year (Dec 2024) at 48.9 compares to 31.9 for Dec 23. Historic p/e x8.2. FY dividend up 23% historic yield 4%. Only a guess but historic RoCE should be well above 15%.
Pretty upbeat guidance also. The main concern here (I am pretty sure) has been the government's avowal to eradicate profiteering in the business of asylum accommodation and the expectation on how that might affect the 'service providers'. Stockopedia - whose future forecasts are I believe an average of analysts' estimates - had an expectation of a much larger fall in revenues and a 25% drop in profits this year as a result. These seem much too pessimistic give the guidance, big increase in the order book (but this is very l-t) and compensating new business in other areas.
My only gripe is that I personally am not a fan of share buybacks. I think they are a disease that are actually reducing liquidity in the UK market and thus damaging prospects of institutional investment. But overall good figures, upbeat guidance and not too dear. A good company at a fair price, perhaps?
https://www.dividenddata.co.uk...
Have been reading the comments here the last 3-4 days regarding the current state of the US bond market and the US possibility of defaulting!
The chance of this happening is ZERO.
During the COVID period the FED were buying about 100B a day! to provide liquidity to the bond market and keep rates down. Same will happen again if/when the bond market shows signs of crashing. To be precise this is when the 10Y goes above 5%.
iShares Trust - iShares 20+ Year Treasury Bond ETF (NMQ:TLT) this is the benchmark that every experienced investor should be watching.
iShares iBoxx $ High Yield Corporate Bond Fund (PCQ:HYG) also is something that should be watched on a daily basis.
Credit spreads also have widened but not to an alarming level.
Can’t remember who has suggested this but I have read a post here that the BOE should sell all US bonds (about $800B)! The implications of this is simple-THE UK economy will simply crash and there is no need to go into more detail.
Very worrying seeing the Trump administration making the stock market a MEME COIN!
I get the tariffs on China that should have been implemented long time ago but, but how can an economy of almost $30T size expecting not to have a trade deficit in relation to other much smaller economies is just plain BONKERS.
All the best
Hi yiannos1
Many thanks for the two bond benchmarks, very useful.
Regards
Howard
Some amazing SP increases today but surprised at how little reaction to this news from Henry Boot (LON:BOOT) that they have successfully obtained planning for 300 homes Just 0.5% increase!
https://newsfile.refinitiv.com...
Any chance of running the rule over Foresight group (LON:FSG) Graham another fund manager that looks cheap as chips, they are more geared for the institutional market so fund outflows issue you would hope would be less of a risk and from memory head man bought a mil worth of stock a while back.
He is also a major share holder and in his golden years so maybe something could happen here in the short (ish) term .
Andy
In fact a total £2m share buys from the Board earlier this year. Mind you - who says you cannot time the market - well maybe it helps if you are a director. Look at sales last year at circa 490p against today's 325p. Its all a mugs game for the rest of us.
Foresight group (LON:FSG) seems to be doing well with decent inflows and another big buyback announced. I've always been a bit put off by their focus on "core EBITDA pre-Share Based Payments" as their main profit measure, but otherwise all looks good.
https://uk.investing.com/indic...
Try this have a play around and you can find pretty much all bonds, gold, major indicies, without hopefully teaching you to suck eggs red is good for bonds green is bad.
A painful lesson now finally learnt, as follows: - when a company has a very long-term highly regarded senior management team who abruptly up and leave at a point when everything looks particularly rosy for their business this is an enormous red flag:
Oxford Metrics (LON:OMG) - Sold a barely profitable software business for an impressive multiple of sales, leaving them with a huge cash pile to invest in their 'world class' Vicon motion capture business. However, the CEO then abruptly departs a few months later to run Ordnance Survey and his sidekick FD leaves shortly after. A few months later Vicon has a profits warning.
Zotefoams (LON:ZTF) - Share price rising on the back of hopes for 'Rezource', an environmentally friendly milk/juice carton solution. Long-term CEO suddenly retires. A few months later the new CEO mothballs the Rezource business saying it is not commercially viable.
Treatt (LON:TET) - Massive expansion in the UK and US with 'state of the art' facilities to capture a larger share of a growing market. Long-term CEO and FD both leave within months of the new UK opening. Today a profit warning.
Its obvious really. Who departs when all is set fair for a rising share price and the chance to reap the rewards of a successful enterprise? Answer: those who know that all in the garden is not quite so rosy as portrayed!
Also XPP a few years back.
I haven’t commented here for ages.
But Covid taught me that there is no point trying to get out and back in (i.e. time the market). That little foray into timing the market ended disastrously, costing me 34% of my portfolio. In the long run (good company) stocks go up and to the right.
If back in November when Trump won you were clever enough to predict this mayhem (did anybody?) and sell out then congratulations but I wasn’t.
I have just sat this out. I am looking forward to May, to see what Buffett has been doing in this market mayhem.
Regards
Michael
I should have added that I think the 90 day pause means forever and that there is a good chance that, when cooler heads bring pressure to bear, the 125% tariff on China will be reduced.
It is really above my pay grade but I do have some sympathy with higher, negotiated, tariffs on China:
But Trump’s irrational economic policy is not the way to be going about trying to reign in China.
Regards
Michael
It is an authoritarian regime, and I would question whether we should be doing unfettered business with such a state.
Hmmmm - is it not a mater of fact that thne majority of Chinese people are happy with the way their country is setup (one party state)?
If the people are happy with a one party state is that any reason not to do business with that state and or tell them what they should be doing it different before they can sell us cd's.
I despair of the default attitude of some in the west that if things arent the way "we want" that we have any right to intefere and tell them they cant do whatb the people are happy with.
Obviously China does do some things that seem nefarious at face value - in that regard i suspect other countries may be doing similart stuff behind the scenes that may not be as much flagged up. Last time i looked compared to many western counrties China does not tend to send their troops around the world killing the locals with abandon (disputed local territorries excepted)
I always think anyone who does deals with China does so at their risk.
I for one applaud how they have managed to improve the living standards of the majority of their population over the last 50 years. Compare that to many countries in africa and middle east where we have where we have actively propped up the people in chnage and many of those countries have gone backwards ref quality of living.
Rmillaree,
The Uighur muslims in the "re-education camps" all across north and western China say 'hi'.
I wont agree that that country is perfect far from it - i dont disagree with someone having moral objections to that country. But the reality of the world we live in as that every country does it their way.
In our country we treat some radical muslims as terrorists and chuck them in jail for their beliefs where should we draw the line in that regard to firmly held beliefs of minorities.
Heck if you overstep the thought police in this country they will loikley turn up at your door and possibly arrest you on the merest hint of an accusation.
its not great that China expects the Uighur muslims to kowtow to something against their beliefs thats a fact. Heck in this country females are forced to compete against biological males at pool and we have chucked biological male rapists in womens prisons - the world can be crazy at times. Heck we force people in this country to live next door to soemone who may kill ina heartbeat them as they cant be deported as that would be against their rights
Not the time and place for politics so won't say anymore. But....... wow.
Not the time and place for politics so won't say anymore. But....... wow.
Hey i didnt start it - it was others saying perhaps we shouldnt do buisnes with china
As ‘way’ says below, this is not the time or place for politics. I would suggest you research quite what is happening to the Uighur population, and then decide for yourself if it is comparable to a British jail.
I wish you all the best with your investing, genuinely, and won’t be commenting any more.
As ‘way’ says below, this is not the time or place for politics. I would suggest you research quite what is happening to the Uighur population, and then decide for yourself if it is comparable to a British jail.
Hey i didnt start the conversation - i wa repleying to someone who said we should probably not be dealing with China - i am more than happy that mods remove the thread if its ot - if someone is gonna leave one side of an argumnet in place though an dothers cant respond then thats "not verty free speech" is it. Just toodle on bye if you dont like it. - note the original poster asked if we should be dealing with china ! - they asked the question and i just oferred my opinion.
You are missing my point here obviously - i am not backing anything China does - or comparing one situation directly to another. Simply pointing out that many countries do stuff that is abhorent -to others us included at times. Its easy to try and paint us us the good people and others as nasty pieces of work - in the real world its not all black and white.
I don't disagree all countries have had their moments of shame. I do feel your response on China was far far to generous, but I respect your right to have an opinion that differs from mine. In investing I look for differing opinions to try and test the strength of my investment/understanding of the company in question.
When it comes to politics I know people on here, understandably, would prefer it discussed elsewhere. That is why I said I wouldn't discuss it any more.
We are both free to our opinions, and I respect yours, even if I disagree strongly with it.
Great to see you back Michael, miss your postings!
New subscriber here. Not happy with the delayed pricing. The subcription fee is not cheap. Also if you have a big move on a stock, most of the figures on the main page for that stock become meaningless.
I don't think it is too much, to expect live prices and continuous updates throughout the trading day in 2025.
We have all of these fantastic computers in 2025. Why not use them.
There is that Sean, but I for one doesn't want to be chasing his arse all day.
You need trading view with additional subscription for live pricing. Stockopedia is a research tool not a trading tool.
You can get streaming prices on HL without logging in or even an account and anyway - I always check out prices if in any doubt
I have lots of options for live pricing. The point is if a stock has a large move in the morning. Then i look at that stock on here and all of the figures are wrong. Even the most basic things like Market cap and Enterprise value. This is 2025 not 1985.
Sean,
I have been investing in financial markets for 35 years and I can tell you from experience £295pa for Stockopedia is peanuts for the content you are receiving.
To put this into context a Bloomberg terminal will cost you £28,000 pa
Not sure how old you are or how experienced an investor you are but nothing like this existed in years gone by and certainly not at this price point so I am super grateful to all the wonderful people at Stockopedia for making this available to us.
Thank you
CD REFS was close, but that was around £600 per year, decades ago. STOCKO even bought out CD REFS so you are getting that information thrown in as a brucie bonus.
Used to have Sharelockholmes until the guy retired and stopped the service. The fee was £60 per year
So we are paying this research platform generously and they won't even give us live prices?
If a want a more current price I just google it - "<company name> share price". It's usually more current than Stocko and you get a nice graph of the day's movements which helps give you a feel for where the sp is going.
Surely the issue is that you didn't understand what you were buying, not with Stockopedia.
If you think it's a lot of money perhaps you should look at what they provide, they don't hide it.
https://www.stockopedia.com/le...
Quotes
We provide delayed intraday quotes on most stock exchanges we cover at Stockopedia. Real time pricing is the most requested feature on our suggestion forums. We do intend to move towards real time quotes in the future. If this is important to you please do vote on the feature in our suggestion forum.
https://www.stockopedia.com/le...
Even that is incorrect, the closing prices are not available until 17.10, if you look at your folios before then, there can be some large price moves until 17.10
The annoying thing, for me, is the price is based on the last trade. Numerous times the big risers and fallers, in my folio have not moved, it is just because of the spread. This last trade price is nonesense
Around 8.20-8.30am you don't know if is based on today's or yesterday's price. Why not zero out yesterday's price movements at 8am?
Big movers often are delayed until 8.30am.
Not to mention Stockopedia's gross errors on their 'Analyst Forecasts' section. As an example take a company called 80M, Stocko shows (and has done for an age) the target price to be 8,983.33% higher than the prevailing price. Clearly wrong. I have raised this point with the team on several occasions over several months and nothing has been done. They simply continue to blame their data provider. If it's that inaccurate get rid of it - it's misleading.
Live pricing would be good and something I've requested before - I can only assume it's quite costly and would need some sort of premium subscription to make it viable for Stockopedia.
TradingView provide add on real time UK data for £60/yr.
It's a fundamentally different product from Spedia which is primarily an analysis/screening tool while TView is foremost an advanced charting platform.
I was a VectorVest subscriber before they closed the UK part. Real time was requested and was always said to be far too costly. As other have said Stockopedia (which is great) is an analysis platform not a trading platform. Horses for courses !
It's not just the live pricing - all the data is wrong in Stockopedia which makes a mockery of the whole system. They can't even add up the data in your portfolio correctly (which is basically just a fancy Excel spreadsheet) - the figures in mine have been wrong for a long time. I have to keep telling stockopedia and then the errors miraculously "disappear." This means I am MANUALLY correcting them. I think someone in this thread said "nothing like this existed in years gone by." That's very true - it's a long time since I had to do any manual checking on figures because someone couldn't write software that simply added up a column!
Forgot to put in my earlier post that I've been reading about Trump possibly reneging on some US debt. If true, he seems to be trying to run the world's largest economy like one of his failed casinos.
Scary stuff.
https://www.yahoo.com/news/don...
This is one of my worries also Raven he's talked about defaulting before I fear this may be the next grenade he tosses into the arena we really need to be unloading our $500 bil odd of treasuries sharpish.
Brave Bison (LON:BBSN) seems to be continuing to progress nicely. Growth in revs + earnings, smaller but earnings enhancing acquisitions continuing (this one mainly paper but additional commitment to purchase in the market) , and now a dividend. Management credible and delivering? I think so.
New Cavendish note: "valuation looks highly compelling given it trades on an FY1 adj P/E of just 8.1x versus peers on 9.3x, whilst retaining significant net cash and growing net revenues by 20% in FY25E".
Well we've lost our "Brexit Bonus", "Our special relationship" bonus and our "Starmer did so much good work beforhand we got a good deal" bonus. Was nice thinking we had an advantage for at least a little while.
What is wrong with the site this morning? Prices are completely wrong
Platform performance
A day like this is good to compare their performance.
IG and ii I had no issue trading. 212 is still awaiting the trade after 10 minutes!
Natwest working well. Old school I guess.
Or it could just be nobody else uses it anymore.
Is anyone else having problems with HL this morning? No updated portfolio prices...
Hargreaves Lansdown (LON:HL.^C25) has a new Boss, I'm happy, I've been paid off.
So Trump has managed to impose 10% tariffs on most of the world and they're overjoyed. :)
Shame I can’t login to my broker AJ Bell, “site outage”. Incompetent clowns
Their reliability is questionable in my own experience, as I've encountered issues with them on more than one occasion. This morning has been yet another frustrating experience, and the standard response of 'we have a helpdesk you can phone' I will get is simply not good enough.
Yeah, I’m sick of them. 6 months ago I complained about a couple of things, one being 404 page not found error messages when viewing my portfolio in an evening and clicking on the fund links. It was an intermittent problem, but they they didn’t have a c,ie what I was talking about and asked for the times it happened. Told them to speak to their IT dept and check the log files. Last I heard of it and it still happens. They’re frustrating
IG not working either.
Try Charles Stanley Execution Only. We pick the phone, deals get done or worked. You can use email too. No problems in 20 years.
I left AJ Bell last year, their service has gone downhill considerably over the years. Had all manner of problems with their website, if you closed an account or did something similar you'd suddenly not be able to access anything and their suggestion was to open another account you didn't want.
When they taxed US dividends in my SIPP they'd claim that it was because of withholding tax, despite having a very clear statement on their site you wouldn't pay tax on US dividends - I did eventually get to the bottom of this, but it took about 4 attempts with different excuses and effectively I had to give them the answer in the end. I don't believe they ever updated the circumstances that would lead to US dividends being taxed and they still have a blanket statement that they don't charge tax on US dividends. I had various other issues with them, including issues transferring an old works pension scheme despite giving them very clear instructions.
I'm with ii now, my expectations were much lower because they're cheaper, but to be honest I've found their service much better.
With many thousands of customers at AJ Bell it is always possible that some are having a problem. So I think it is only fair that I step forward to say that I have had no substantive problem over the last 12 years, and any issue has been dealt with courteously and quickly. Just a toe on the other side of the balance.
I completely agree re AJ Bell and have had a much worse experience with ii. As you say, with thousands of clients, there are always going to be a few cases where things go wrong.
Of course, that's only fair. I would have said the same if you'd asked me 3 years ago. Only minor issues which were resolved quickly, I may have been unlucky. I don't mind if things go wrong, it's the blatantly false information I was given multiple times that made me leave.
Why had the shares been slipping so much on no news. How did people know?
hVIVO (LON:HVO) i have a small holding
Interesting niche company issued final results today. Some promising elements but would like to understand why forecast revenues are up but profit margins lower than this year. Hope the team has time to review.
Audioboom (LON:BOOM) Get an RNS turkey award for leading yesterday with "10x EBITDA !!!" on a minuscule sum. Punished by the market for stupidity and an attempt to mislead.
Interested to hear from those who sold out and went completely/predominantly to cash. When do you plan to get back into the market, what trigger or situation would make you buy?
I am not all in cash but the best approach in the current mayhem might be to buy stocks which could benefit from huge volatility. Maybe IGG and CMC?
I also bought some Ramsdens in addition to the various Gold investments already held. I see this is a low risk bet.
Interesting that the US blinked first. Their low tolerance to financial pain should encourage other countries in the Tariff negotiations.
Disclosure - hold IGG CMC and Ramsdens
Trump has remained steadfast in his aim, no blinking to be seen there.
I've been out and in, then out again. I was lucky to make a small gain, but this 'trading' went totally contrary to my process of 'time in the market'. I'm not at all convinced that things are getting better after the latest 'pause' in tariffs (how many times has that happened now?). So I'm mainly back in cash, and will see where we go from here.
Why? Because I think what is happening now is more unpredictable than anything that's gone before. My experience and reading of previous market shocks was that there was a kind of logic about them, and I felt each time fairly confident that things would get better fairly quickly.
With a 4 year term still ahead, Trump seems determined to be the centre of attention on the world stage, and that does not bode well for a benign investing environment, in my opinion. He thinks he's the world's greatest businessman, when he clearly is not.
https://www.newyorker.com/maga...
So, I'm going to sit and wait. At least for now. But what do I know.
Sold anything that hit (in my head) -20% stop loss. Scottish Mortgage Investment Trust (LON:SMT) , Polar Capital Holdings (LON:POLR) for instance. Have bought back over the last couple of days about quarter of the holding at a lower price. They have gone past what I have sold them for now, so I will wait, until China and US do a deal, we are not out of the woods. I suspect there may be a few more down days to come.
Should those shares keep going north, then will look elsewhere, there are plenty of buses on this road and we do not need to get on the first one that comes along.
I watch the weekly charts of the indices. I want to see some sign of an uptrend (10 wma above the 20wma, and/or a positive MACD) or at least some strong support and reluctance to go lower. Nothing is precise and I may miss the bottom or it may drop further. The real key is knowing you have to be bold and get back in at some point, don’t sit on the sidelines forever.
For the uk I find the AIM 100 tracks sentiment the best, but of course everything is beholden to the US right now.
Hi Jschoffer, Good question. I can't see a situation to buy anytime soon. I'm all in cash since the Tesla lawn sale (bad desperate sign). I'm usually in 12+ tech stocks and often US. Time for me to sit on the sidelines for a bit and watch the play in awe.
There has been ALOT of talk since November that everything is bubblish/overpriced. Mag 7 overconcentration etc etc In the same way that there was alot of talk pre 2008 crash about bubbles. Animal spirits etc just waiting for the damn to break.
I also read recently (here) that profit warnings like buses come in threes. And to get out at the first strike.
It feels like a massive USA/globalisation profit warning out there.
I'm no pro but I (AI) researched the last 25yrs of bears (S&P500);
.com = -49% / 56 months to recover to previous highs
2008= -56% /17 months to recover
Covid -34% / Just 5 months
If you invested $100 in the S&P 25 years ago and held - you would have c$630 today.
If you were for the same period not invested in 2001, 2008, 2022 you would have c$1200
Admittedly the challenge is in the timing. (AI is pretty good for perfect hindsight scenarios) But you don't need to time perfect tops and bottoms.
I'm a transatlantic sailor and there is known expression that ;
"the time to put a reef in - is when you first think about it". There's nothing fun about shortening sail in a gale. Also big storms often have a lull in the eye of the storm. And then it kicks off again. It's scary and exhausting.
Sailing metaphors are not perfect for financial markets. But I can't see any signs of calm weather on the horizon or in the skies.
Good luck to everyone out there. I've battened down the hatches and I'm out.
I also sleep like a baby :)
(BTW The trump narrative is extraordinary; 'Best S&P500 trading day EVER yesterday." "Price of eggs down 60%' with zero context of bird flu or the previous 19% drop. Trump is the Story Stock par excellence. I would not be surprised if he, with no sense of irony, launched a stable coin)
Stable genius coin.
Good morning Mr Schoffer!
For what it is worth ....
I am just sitting and watching the bond markets. The bond market will be my biggest guide ... the bond market is a much better canary than the equity markets. I will be 62 this year and cannot afford a significant drawdown, so I probably play things more cautiously than a younger person with more time would. I have a small list of new stocks, and I will add to existing positions when the chicken bones align (basic chart analysis).
One interesting observation is that some of my equity holdings (eg Proeduca Altus SA (MCE:PRO) listed on Madrid, barely moved and I will allocate some new capital to these little gems ... Afterall it is not often you see a company with 270 million turnover and a consistent ROCE of 200% + and huge growth potential in a market with excellent demographics.
I also noted my agricultural and food stocks barely moved during the orange tariff crash: (Premier Foods (LON:PFD), M P Evans (LON:MPE) , A G Barr (LON:BAG) , Cresud SACIF y A (NSQ:CRESY) . Solid boring businesses with limited to no exposure to US geopolitical strategy and in my circle of competence. I also really like Volvere (LON:VLE) which I don't own but which one of the Stocko team wrote about recently.
The China-USA trade war has a long way to run as it is existential to their geopolitical global aspirations which are mutually exclusive. We will all be caught up in the crossfire whatever the individual country tariff regime is. I do not for one moment think this is over .. as JPM said yesterday: "it is the end of the beginning.
Trump and his tariff tantrum is a symptom of deep structural problems with global trade (another way of saying Trump has a point with China and Europe) and the larger elephant in the room is the level of global sovereign debt, which tanking the global economy is not going to help.
Just the thoughts of an ageing dilettante farmer.
Can you recommend a site where it's easy to see what's going on in the bond market?
Live Bond Rates and Prices - IG UK
When Trump has gone
My partner is 75% cash as she follows the idle investor rules (largely). Next month if the index > n day moving average, will buy.
Idle Investor, that was the book I was thinking about just now, thank you Andrew
Just bought into TET, and out come poor results, and a silly share buy back. I'm not impressed.
Poor TTG results also, sounds chaotic.
Greyinvestor
I also bought TET yesterday.
I am in good company!
Profit warning from Treatt (LON:TET)
Massively leveraged players in the Treasuries futures basis swaps markets were potentially rocking the financial system (Alphaville column FT). Someone told Trump's advisors and he blinked. Better day ahead?