Daily Stock Market Report (Thur 12th March 2026) - RST, OTB, TCAP, FSJ

Good morning! Today's Agenda is complete.
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Halma (LON:HLMA) (£14.8bn | SR75) | Continues to expect mid-teens percentage organic constant currency revenue growth, including a continued benefit from premium growth in photonics within the Environmental & Analysis Sector. Adjusted EBIT margin (excluding the one-off profit in the first half) of around 22%. Cash conversion to be in line with KPI of 90%. | ||
Informa (LON:INF) (£9.97bn | SR51) | Revenue up 6.3% on an underlying basis, adjusted operating profit up 8.7% (to £1,139.8m). 2026 is trading to plan. “We continue to target higher underlying revenue growth in 2026 at 6%±, with B2B Live Events underlying growth of 7%+, alongside double-digit growth in underlying earnings per share…” | ||
Computacenter (LON:CCC) (£3.36bn | SR87) | Revenue +33.2%, services revenue +2.9%. Adjusted operating profit +11.3% (£274.7m). Exited 2025 in a strong position. ”Looking to 2026, while we remain mindful of the uncertain macroeconomic and political environment, as well as the hardware component shortages currently affecting the IT industry, we are confident in our ability to navigate these challenges. Therefore, we expect to make further strategic and financial progress on an organic basis, enhanced by the acquisition of AgreeYa.” | ||
Shawbrook (LON:SHAW) (£2.14bn | SR85) | Underlying PBT +16% to £340.5m. Underlying return on tangible equity was 17.2% (FY 2024: 17.5%). ”We enter 2026 with strong momentum and a clear line of sight to delivering our medium-term guidance. With a scalable platform, prudent capital allocation and proven execution, we are well positioned to continue delivering high-quality growth and returns for shareholders…” Medium-term guidance reiterated, including mid-high teens growth in underlying PBT. | ||
Bridgepoint (LON:BPT) (£1.99bn | SR18) | 13.0% growth in underlying management fees and other income. Assets under management increased by 24.5% to $94.1 billion. Reported profit before tax of £85.7 million (FY 2024: £80.7m). “Bridgepoint posted an impressive performance in 2025 with funds across our platform continuing to deliver for the world's top institutional investors… Looking ahead, we are making excellent progress in fundraising and there is a good transaction pipeline in place for 2026 and beyond.” | ||
Helios Towers (LON:HTWS) (£1.93bn | SR64) | FY 2025 performance ahead of expectations. Revenue +8%, adj. EBITDA +12% ($471m). Profit after tax increased by US$12.4m to US$39.4m. 2026 outlook: adjusted EBITDA of US$510m-US$525m. | ||
TP Icap (LON:TCAP) (£1.83bn | SR86) | Revenue +6%, EBIT +14% (both at constant currency). Adjusted EBIT +10% to £348m. Despite a £9-10m currency headwind, “the Board still expects the Group to achieve adjusted EBIT in line with current market expectations”. Market expectations: adj. EBIT £361m (range of £347m to £370m). | GREEN ↑ (Graham)
I’m fine with upgrading this to GREEN (from Roland’s AMBER/GREEN). The StockRank is strong at 86, the P/E is modest at about 8x even after today’s gains, and it has beaten expectations for 2025. The effect of heightened volatility in oil markets is impossible to predict with certainty but it’s probably not a bad thing for TCAP. So this is looking quite interesting to me here. The share price has stalled since November 2024, but the profit outlook has improved quite a bit since then. | |
Resolute Mining (LON:RSG) (£1.61bn | SR66) | RSG has formally approved the Final Investment Decision for its Doropo Gold Project in Côte d'Ivoire, marking a transformational step towards construction and production. Net cash of US$209m (December 2025). “As the Project advances, Resolute will continue to evaluate all funding options in the context of prevailing market conditions, to maintain its balance sheet flexibility and as additional growth initiatives are identified.” | ||
Energean (LON:ENOG) (£1.57bn | SR48) | Agreement to acquire Chevron's 31% operated interest in Block 14 and 15.5% non-operated interest in Block 14K, offshore Angola. The first step in Energean's strategy to expand its operations into West Africa. Block 14 assets produce around 42 kbbl/d of oil in total, equivalent to 13 kbbl/d net to the interest to be acquired. The base consideration is $260 million in cash. Contingent payments of up to $25 million per annum, capped at $250 million in aggregate, may become payable up until 2038. | ||
Volution (LON:FAN) (£1.24bn | SR57) | Revenue +21.7%, adjusted operating profit +21.1% (£51.6m). Organic revenue growth of 4.2% (at constant currencies). The short to medium-term outlook “remains very encouraging”. “Following the Group's strong first half performance, we expect to make further strategic and operational progress in the second half of the year and the Board now expects adjusted earnings per share for FY26 to be at the top end of the range of market forecasts." Forecasts are for EPS of 35p to 36.5p. | ||
Vesuvius (LON:VSVS) (£1.08bn | SR92) | Revenue +0.7% like-for-like. Adjusted operating profit down 17% like-for-like to £151.1m. Challenging year with difficult end market conditions, particularly in EU+UK. Performance in line with expectations. Whilst we are mindful of the current geopolitical uncertainty, absent an extended disruption, we continue to expect to deliver profit growth in 2026 in line with expectations, on a constant currency basis. | ||
Trainline (LON:TRN) (£739m | SR80) | FY February 2026: net ticket sales +7%, revenue +2% (both at constant currency). “A robust trading performance, in line with previously raised expectations.” Expecting a double-digit percentage increase in adjusted EBITDA, within the previously upgraded guidance range of 10% to 13%. | ||
Alfa Financial Software Holdings (LON:ALFA) (£573m | SR44) | Revenue +15% to £126.7m, Op Profit +17% to £40.1m, PBT +18% to £40.1m, Net Cash £26.4m (FY24: £20.5m). “Over recent years we have been very successful in growing our US business so that it now accounts for 45% of our revenues, which at current exchange rates creates a headwind for growth in our reported results. Overall however, despite the impact of currency headwinds and wider macro uncertainty, we expect to see good revenue growth in 2026 and beyond.” | ||
Restore (LON:RST) (£315m | SR47) | Revenue +27% to £304.7m, Adj. Op profit +18% to £55.5m, Adj. EPS +23% to 22.5p. Net Debt excl leases £123.8m (FY24: £89m). “Trading since the start of the year has been strong. All divisions are performing in line with or above our expectations, and accordingly we expect full year adjusted profit before tax to be slightly ahead of current market expectations.” | AMBER/GREEN = (Mark) Growth here is all acquisition-led with organic revenue from continuing operations down slightly. We therefore need to be careful making investment decisions based on adjusted figures which include all the benefits from acquisitions but exclude all of the associated costs. This is a steady and cash-generative business and using acquisitions to store up sticky customers and shred costs is a good strategy. I am therefore a bit concerned about the buyback announced today, as it will limit the scope for further bolt-ons unless they are willing to relax their leverage target range. However, fundamentally, it is now cheaper than when we last reviewed it, with EPS forecasts rising and the share price dropping. It also appears to have some momentum behind the business, even if the numbers require heavy adjustments to show it. So I am happy to keep our broadly positive view. | |
Ab Dynamics (LON:ABDP) (£285m | SR44) | Positive trading momentum in the final quarter of FY25 has continued during 26H1. Order intake in H1 of £64m (HY25: £66m, FY25: £110m). | ||
On Beach group (LON:OTB) (£280m | SR52) | FY26 bookings +10%, Q1 travelled volumes +14%, Q2 +34%. Limited exposure to ME, but significant slowdown in demand following the onset of conflict in the region, particularly to destinations such as Turkey, Greece, Cyprus and Egypt. Both will impact Group profitability and as a result the Group is temporarily suspending its guidance of £39m to £43m Adj. PBT for the full year. | BLACK (suspension of forecasts after ME impact) /AMBER/GREEN ↓ (Mark) I can see the attraction for long-term holders who believe in the management’s medium-term ambitions. However, with today’s update not being able to quantify the short-term impact of world events, let alone longer-term effects, the uncertainty increases significantly. So at the risk of playing ping pong with our stance, I think we have to be more cautious today. I was also surprised at the lack of reaction prior to today’s news, and I wonder if it makes sense to take a wait-and-see approach across the sector. Especially for those travel businesses that have yet to report the impact they are seeing, or like OTB are unable to quantify it. | |
Secure Trust Bank (LON:STB) (£269m | SR97) | Lending+8.1% to £3.3bn, Continuing PBT Flat at £59.3m, CET1 +60bps to 12.9%. TBV/share +5.8% to £19.73. £10m buyback. “Having taken decisive strategic actions in 2025, 2026 will be a transitional year to launch new products and reduce cost.” | ||
James Fisher And Sons (LON:FSJ) (£256m | SR90) | Revenue +4.3% to £377.2m, u/l Op. Profit +56% to £28.6m (reported PBT £4.3m), Net debt £54.4m (FY24: £56.1m). “Trading has started the year in line with management expectations; the Board remains confident in delivering further progress in 2026.” | AMBER = (Mark) Yet again, I am struggling to see the attraction here. These results appear to be a slight miss, and profit increase requires investors to believe the many adjustments are fair. This calls into question their ability to hit their medium term 10% operating margin target. However, the market appears to have priced in them as if they have already got there, and more, giving considerable downside if they fail. There appears to be little in the way of balance sheet protection at these levels, with increasing net debt once leases are included, and a declining TBV. While the Momentum Ranks stays strong, I am happy to keep our neutral view, but I would be quick to take a more negative stance if that Momentum started to fade. | |
Optima Health (LON:OPT) (£162m | SR67) | Enters partnership with Perkbox to deliver occupational health and wellbeing solutions, expected to deliver £6.5m revenue pa. Forms part of the £8.3m annualised new business that was secured or at preferred bidder stage in the HY26 results. | ||
GreenX Metals (LON:GRX) (£138m | SR11) | LBT $8.21m (25H1: $2.09m Loss), Cash $2.19m (25H1: $6.83m), before raising $13.6m gross in Feb 2026. | ||
Jubilee Metals (LON:JLP) (£121m | SR27) | Secured additional high-grade copper feed material for the Roan concentrator for $1.8m. At Large Waste Project, the sellers have elected to receive the next stage payment of $2.6m in Jubilee shares. Balance of the acquisition $5.4m. | ||
4Basebio (LON:4BB) (£80.3m | SR1) | Scott Lorimer appointed as Chief Operating Officer. | ||
Fairview International (LON:FIL) (£40.3m | SR8) | Revenue +7.1% to £2.98m, PBt +122% to £1.22m, EPS +100% to 0.16p. “The increase in enrolments and applications is particularly encouraging given the additional resources we have invested in marketing our schools since the IPO.” | ||
Abingdon Health (LON:ABDX) (£20.1m | SR18) | $2.5m contract to provide project management and expert technical support for the development and regulatory submission of a clinical self-test. Will commence shortly with the majority of the revenues to be recognised in FY27. | ||
Sareum Holdings (LON:SAR) (£19.3m | SR4) | LBT £1.85m (25H1: £1.33m Loss), Cash £2.49m (30 Jun: £3.55m). |
Graham's Section
TP Icap (LON:TCAP)
Up 7% at 263p (£1.96bn) - Final Results - Graham - GREEN ↑
It’s an excellent headline to start off the full-year results at this major international broker.
Record results, with adjusted EBIT ahead of expectations, announcing an £80m share buyback
They must have had an interesting week or two, considering the action in the oil markets.
Adjusted EBIT is up 10%, while real EBIT is up 14%:
They say that consensus expectations for adjusted EBIT was £345m, so they are 1% ahead of that.
Announcing an £80m buyback, the CEO says:
This strong performance reflects the disciplined execution of our strategy. We grew the business, maintained strict cost control and continued to drive operating leverage. This is evident in our increasingly diversified buy-side and sell-side offering, with both Global Broking and Liquidnet delivering record profitability.
The £80m buyback would eliminate 4% of shares outstanding at the current market cap - not bad.
Let’s take a quick tour their the strategic highlights:
The acquisition of Vantage Capital Markets was recently announced - looks highly complementary.
“Strong broker recruitment in Energy & Commodities” - this division saw a revenue decline in 2025, but I presume it will be busy in 2026?
Ongoing expansion of Liquidnet and investment in the data business Parameta, but there will be no IPO of Parameta in the short-term (“the context remains challenging for an IPO”).
£35m of annualised savings across the group, £10m ahead of plan, with a total of £50m targeted by 2027.
Liquidnet and Parameta are both growing revenues at modest rates: 4% at Liquidnet, 5% at Parameta.
Current trading and outlook
The Group has continued to benefit from supportive market conditions in the current fiscal year to date. We have significant US dollar earnings* and at current spot rates we would anticipate a £9-10m FX headwind to our 2026 adjusted EBIT. Despite this, the Board still expects the Group to achieve adjusted EBIT in line with current market expectations.
Expectations are for EBIT of £361m (range £347m to £370m).
It’s worth reflecting on the statement that they are expecting to do this despite an FX headwind of up to £10m.
I interpret that very positively, as FX movements are of course beyond their control.
Hopefully, for them, the dollar can recover later in the year and enable them to beat expectations.
Checking the GBPUSD exchange rate, I see that it’s up by 3.4% over the past year (from about 1.30 to 1.34). It makes sense that this would feed through to TCAP’s results (60% of its revenues are denominated in USD, versus only 40% of costs).
Graham’s view
I’m fine with upgrading this to GREEN (from Roland’s AMBER/GREEN) for the following reasons:
StockRank is strong at 86
P/E is modest at about 8x even after today’s gains.
Highly reputable businesses (this is a giant in global financial markets, even if it’s not a household name).
Nice mix of brokerage and data services.
Beating expectations for last year and trading in line for the current year, despite an FX headwind (suggesting very strong underlying trading).
Earnings forecasts have oscillated within a narrow range, implying good visibility:
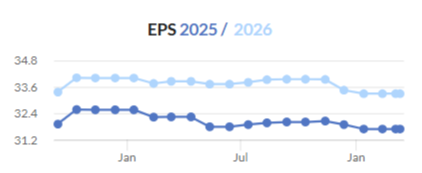
The effect of heightened volatility in oil markets is impossible to predict with certainty but it’s probably not a bad thing for TCAP.
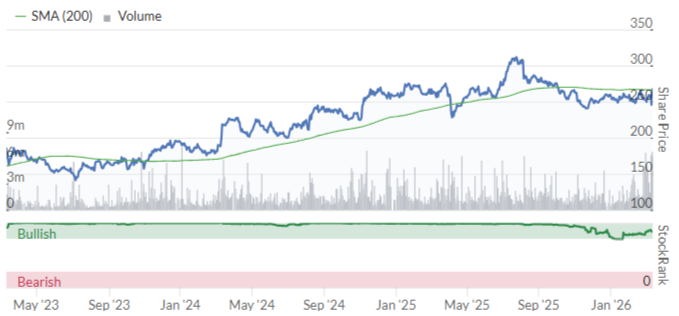
So this is looking quite interesting to me here. The share price has stalled since November 2024, but the profit outlook has improved quite a bit since then:
Mark's Section
Restore (LON:RST)
Up 5% at 243p - Full Year 2025 Results - Mark - AMBER/GREEN
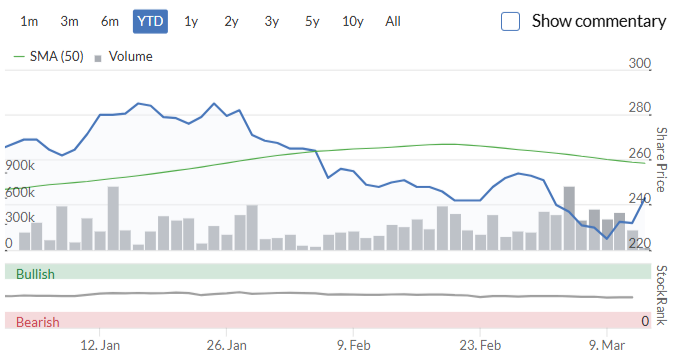
So far this year, the share price has been tracking downwards, reflecting generally weak market conditions for companies of this size:
However, it seems unlikely that their core business of document storage and shredding should be impacted by UK government policy or the war in Iran, and so it has proven. Revenue from continuing operations is up 27% to £304.7m and Adjusted EPS comes in at 22.5p versus the 22.1p consensus in Stockopedia. However, both of these are slightly problematic:
Organic Revenue Growth:
When we’ve reviewed this on the DSMR in the past, we have commented that it is hard to justify a P/E greater than high single figures for a business without organic growth. In these results, they say:
Organic growth was broadly flat as we continued to focus on operating margins, particularly in our digital and IT Lifecycle activities.
Broadly flat, of course, means slightly down. Things look better going forward, where they say “We expect to see healthy organic growth in 2026, now that our businesses are in the right shape.” but this doesn’t quantify this. Is “healthy” just slightly above inflation at say 5%, or more like 10-20%? And how far into the future can this organic growth be sustained? These factors make a huge difference to the multiple that investors should be paying for this business.
Looking at brokers’ notes for guidance, I see Canaccord have around 13% revenue growth for FY26 pencilled in and around 5% for the following years. Cavendish are more conservative at 10% and 3%, respectively. Without a significant acquisition spend forecast, these will be the expected organic growth rates. With a small amount of operational gearing, a high single-digit EV/EBIT multiple should be justifiable.
Adjustments:
What stands out is that you can drive a lorry full of document storage boxes between the adjusted and statutory earnings:
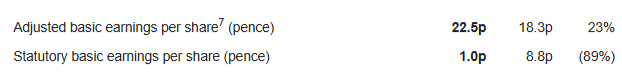
Here’s how the figures break down:
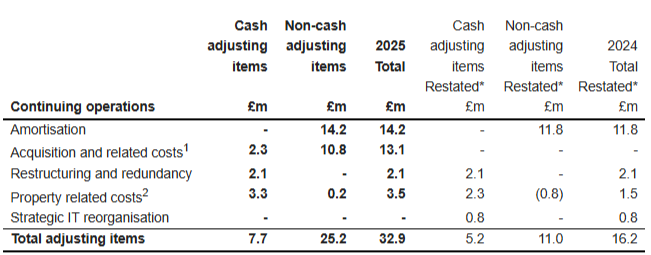
While the majority of these are non-cash, there is no getting around that a company such as this has significant leeway in their reporting of adjusted EPS. When they include the profit benefit from acquisitions, but exclude the cost of making those acquisitions and rationalising the cost-base of the acquired companies, then the adjusted figures are always going to improve. In this case, the period contained significant activity on this front:
Acquisition of Synertec and six further bolt-ons, expanding the Group's capabilities across inbound and outbound communications and strengthening market share in shredding.
Outlook:
2026 has started well:
Trading since the start of the year has been strong. All divisions are performing in line with or above our expectations, and accordingly we expect full year adjusted profit before tax to be slightly ahead of current market expectations
However, I am mindful of the dynamics described above. They say they have made two further bolt-on acquisitions in early 2026, so with them likely adjusting out the acquisition costs, it should not be surprising that adjusted PBT forecasts increase.
Canaccord increased their FY26 adj. EPS by 3.7%, from 24.1p to 25.0p, which follows a 5% upgrade they made in December. Cavendish make no change as they were already at a more aggressive 26.5p for FY26 adj. EPS.
The company is clearly benefiting from work over the last few years to improve the profitability of their core businesses. For example, in Technology, they generated an adjusted operating profit of £2.8m vs a loss of £1.4m in 2023.
Balance sheet:
There are further signs that these improvements have a significant acquisition component. Net debt excluding lease liabilities rose from £89m to £123.8m. This is within their 1.0 - 2.0x target range, but at 1.9x, it is at the upper end.
This is expected to reduce slightly during 2026. However, Canaccord increase their 2026 year-end forecast to £120m from £103m, partly due to them estimating £15m of shares bought back in the period. This suggests that there may not be as much headroom as in the recent past to make these earnings-enhancing bolt-ons while remaining within their target leverage.
Earnouts from past acquisitions appear to be accounted for as “Other payables”. These have gone from £0.2m to £16.0m over the past year. Personally, I would treat this as additional debt, as it is highly likely to be paid in cash, unless things go seriously wrong with the acquired businesses.
Cash flow:
Things look much better on the cash flow front, with reported Free Cash Flow up 4% to £42.9m. The company increase their dividend by 19% today and initiate a £20m buyback. A 7.8p dividend is forecast for FY26 costing around £10m. Canaccord say these are “both funded by FCF without limiting future growth investment”, I’m not sure I agree with this statement. Current forecast FCF is largely going on the dividend and buyback in FY26. If they want to make further material acquisitions it will require them taking on further debt and relaxing their target leverage multiple.
Mark’s view
The reality is that this is a relatively mature business that will not grow quickly without further consolidation. I don’t think we should place too much faith in adjusted figures, which take all the benefit from acquisitions and don’t include any of the costs. However, that doesn’t mean they don’t have significant opportunities to acquire bolt-on businesses, eliminate duplicate costs, and keep scaling up. This tends to be a profitable and sticky business, which means it has nice, predictable cash flows. This enables them to run with high leverage and further juice the returns to equity. The process of storing up customers and shredding costs is a fundamentally good one.
I am therefore a little concerned that the inclusion of a buyback means acquisition opportunities are weaker than in the past, or that they will need to push their leverage ratio to make them. The good news is that this should help support a share price that has been weak recently, perhaps more due to institutional flows than changes in the business outlook.
Both Canaccord and Cavendish have pretty high price targets, making the case for undervaluation compared to global peers, or where the company has traded in the past. However, they make this case using some pretty punchy multiples, in my opinion, for a business that has mid-single digits organic growth potential over the long-term, and limited scope for further acquisitions. However, it is a steady, cash generative business that is doing the right things in order to turn around its struggling parts, and grow the rest (via bolt-ons).
Fundamentally, it is slightly cheaper today than when we last reviewed it on the DSMR, having had some modest EPS upgrades and a share price that has fallen. So I see no reason to change our previous AMBER/GREEN stance.
On Beach group (LON:OTB)
Down 11% at 171p - AGM Trading Update - Mark - BLACK (suspension of forecasts after ME impact) /AMBER/GREEN ↓
For the first five months of the year, things have been going well here with positive momentum building:
· FY26 bookings: +10%1 and bookings from repeat customers +19%
· Q1 FY26: travelled volumes +14%
· Q2 FY26: travelled / departure volumes +34%.
However, this is one of the first instances where we are seeing the direct impact of the Iran war in the numbers, rather than the market anticipating the impact:
Current trading from 1 March 2026
Whilst the Group has limited exposure to destinations in the Middle East, it has experienced a significant slowdown in demand following the onset of conflict in the region, particularly to destinations such as Turkey, Greece, Cyprus and Egypt. It’s impossible to predict when the conflict will end, and the pace at which demand for these destinations will recover, but both will impact Group profitability. As a result the Group is temporarily suspending its guidance of £39m to £43m Adj. PBT for the full year.
This makes sense. I think the direct impact is pretty limited. The chances of being hit by an Iranian missile while on holiday in the Eastern Mediterranean is incredibly low. However, as events in Dubai have shown, it doesn’t take much to create significant disruption.
The reason most people book package holidays is that they have to organise very little themselves and don’t have to worry about things that independent travellers have to consider. If disruption becomes more common, it’s easy to imagine these types of bookings drying up.
Perhaps the most worrying aspect is that they are unwilling to quantify the impact of the Middle East turbulence. This makes it very hard to say whether today’s 11% drop in share price is an overreaction.
What is a little surprising to me is that the market hadn’t anticipated this disruption, with the shares only down around 7% over the last month:
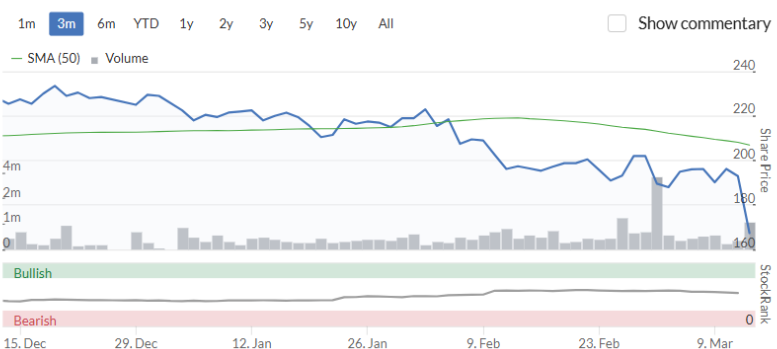
While On The Beach doesn’t have the same direct costs as someone like Jet2, which operates its own aircraft, I expect that flights to “safer” destinations will increase as higher fuel costs are reflected in fares. (OTB doesn't block-book flights, but rather books the individual flights in real-time when a customer confirms a holiday on their website).
There is some reassurance that they continue to trade profitably and generate cash. However, it would take quite some disruption for them to go from £39-43m EBIT on £138m forecast revenue to a loss, so this isn’t as comforting as it first sounds.
They also remain committed to their medium-term “ambition” of “£2.5bn TTV, £100m EBITDA, £85m PBT and 38.7p EPS.” It seems a bit strange to quote a precise EPS figure; how will they know precise finance or tax charges in the future?! However, it is clear that the current share price of 170p-ish will look too cheap if they hit these figures. Even before today’s withdrawal of guidance, I can’t see any specific recent coverage on Research Tree. I’m guessing these are described as “ambitions” as they are further out than the current forecast window. In the current environment they may prove too optimistic.
Read across:
I am also surprised by the lack of reaction elsewhere in the sector. Jet2 appears to have reacted to this announcement by dropping 4% today. Overall, though, both Jet2 and Hostelworld are only down around 10% over the last month, not that far off where OTB was prior to today’s fall. While they have different business models and target markets, the scope for continued disruption is still high.
Tui has dropped 20% in the last month, although it still has higher relative strength over the last six months:
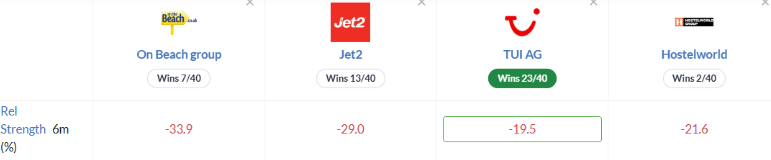
I’m not sure I’m keen to jump in anywhere in this sector at the moment. The scope for continued disruption far beyond initial expectations seems quite high to me.
Mark’s view
Graham upgraded OTB to GREEN when he last reviewed it on the DSMR, on valuation grounds. The price is now understandably below that level, and I can see the attraction for long-term holders who believe in the management’s medium-term ambitions. However, with today’s update unable to quantify the short-term impact of world events, let alone longer-term effects, the uncertainty increases significantly. So at the risk of playing ping pong with our stance, I think we have to be more cautious today. AMBER/GREEN.
James Fisher And Sons (LON:FSJ)
Up 1% at 510p - Preliminary results - Mark - AMBER =
I've always struggled to see the attraction in James Fisher and Sons. But the SuperStock moniker, and the investment from turnaround specialist Rockwood Strategic, suggests I am missing something.
I am hoping today’s results will change my mind. But the top-line figures aren’t a great start…:
Revenue increased 4.3% to £377.2m
The only forecast I can see is from Singer, who had £395.9m revenue pencilled in, so this seems like a miss. Reuters’ third-party reporting seems to confirm it:
UK marine services firm's 2025 revenue fell 9.9%, missing analyst expectations.
Adjusted operating profit for 2025 missed consensus.
Company cites disposals and staged closures as main drivers of revenue decline.
Regardless of this analysis, I expect a company trading on a 20+ P/E ratio to be growing faster than this.
Things are better on the profit front though:
Underlying operating profit increased 56.3% to £28.6m
At least on an adjusted basis:
Reported profit before tax of £4.3m (FY24 £54.0m, which included £54.9m from gain on disposals)
Adjustments:
As usual when there is a big gap between adjusted and reported figures, we need to dig out the details:
None of these looks particularly one-off, apart from £2.2m of pension payments included in “Other”:
Other - comprises costs outside the normal course of business, including exceptional legal and professional fees relating to isolated matters. It also includes £2.2m associated with the estimated settlement of a historic pension matter.
Amortisation and impairment are, at least, non-cash.
Balance Sheet:
They say “net debt reduced in the year to £54.4m” in their headline. But when I look at the details, this is down from £56.1m. In other words, it’s barely budged. This excludes lease liabilities which have increased with the leasing of additional tankships, meaning net borrowing, including all lease liabilities, was £144.1m versus £108.0m at the end of 2024.
Overall, the balance sheet doesn’t seem that strong to me. Payables now exceed receivables and there are increasing provisions. There is little in the way of tangible asset value backing, and the tangible book value has been declining:
Outlook:
The outlook statement is in line:
Overall market conditions remain largely supportive, and 2026 trading has started in line with management expectations. Whilst early in the year and mindful of macroeconomic and geopolitical uncertainties, the Board remains confident of delivering continued progress in 2026, building further towards our medium-term financial targets of 10% underlying operating profit margin and 15% ROCE.
However, that means a forward P/E of over 20. Singer forecasts growth into 2027, but that requires some faith, given today’s revenue miss, and still doesn’t make them look cheap.
It is also worth thinking about what their “medium-term financial targets” actually mean. A 10% margin on roughly £400m in revenue is £40m in EBIT. Say we give them a 10x EV/EBIT rating, that would be an EV of £400m, or a market cap of around £245m, pretty much today’s figure.
There may be some modest revenue growth. However, this would be based on 2028 or 2029 numbers and would need to be discounted back to today. All in all, it seems like the market has already priced in the medium-term targets as having been met, whereas the company’s history would throw considerable doubt on their achievement. Plus, the word “adjusted” may continue to do the heavy lifting in their results.
Mark’s view
I’m sure there is some grand plan that I’m missing which will appear in forecasts well outside the forecast window. However, yet again, I'm still struggling to see the attraction. If the company is doing well in the current defence and oil environment, why would they suddenly see a step-change in fortunes? Their “medium-term financial targets”, if achieved, make them look fairly valued today.
Given the strong MomentumRank, I’m happy to keep our previous neutral stance, but would be quick to take a more negative view if that Momentum starts to fade. AMBERDisclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
On Beach group (LON:OTB) Travel volume in Q2 up 34% Q1 up14% but booking only 10% is that not concerning ? also Q2 travelled / departure and Q1 Only travelled is that a typo ?
Anyone holding Hydrogen Capital Growth (LON:HGEN) - they put out a meeting notice saying that they intend to take the co private. Price down about 50%
Computacenter
What did not market like about the CCC results that caused the shares drop by more than 6%?
I am curious if the outlook was felt to be too uncertain or perhaps the French business impairment caused anxiety. I was surprised and had expected a neutral to positive reaction.
I'd really appreciate it if you could look at TP Icap, which should be a beneficiary of market volatility. The Board has effectively shelved plans for a minority US listing in the immediate term of Parameta Solutions, noting that the "context to achieve a successful listing remains challenging". Previously, a listing was considered for as early as Q2 2025....
NextEnergy Solar Fund Limited update wasn't covered yesterday? They reduced the dividend which made the stock go down some 16%. I think they are going to use the money to change the solar panels of some of their older farms to make them more efficient i guess generate more energy meaning more $$$. If you care about capital appreciation that's a positive. The panels themselves are the cheapest thing you can change in such setups - I have a system installed and the real expensive bit is the inverter.
A lot of so called 'dividend' investors are ignorant. Dividends don't come from magic - they come from the balance sheet of the company so as soon as one is paid out the stock price is adjusted (down) accordingly. You don't want dividends you want capital appreciation. The company retaining more money on its balance sheet is positive. If you watch the news the global energy supply is being squeezed and what NextEnergy has are valuable assets trading at a big discount to net asset value. This is a sitting duck now awaiting a predator!
Ben - you are right to mention this - even for those who sold out before - its an important news item and was missed, as was MNG today.
On another front - I am still annoyed that there are examples such asGulf Marine Services (LON:GMS) showing a dividend yield of 6.18% when in fact the company has never paid a divi and has yet to actually declare one. I pointed this out to Stocko and have chased them a couple of times. They refer to broker forecasts but thats not reality.
I don't really see what your problem is bohenie. The 6.18% dividend yield on Gulf Marine Services (LON:GMS) is clearly shown as a '12 month rolling forecast'. Just scroll down the summary page and the data confirms exactly what you say. No dividend has been paid in any of the years from 2019 to Dec 2024. It is up to you as to whether you believe analysts forecasts for 2025 and 2026.
It is probably more helpful when screening for income to see 'current' dividend yield rather than 'forecast' but equally, it is useful to see the expected direction of travel for future years.
Thanks Sparkler - Ok - agree it comes under heading of rolling 12 months forecast - but - My problem is that GMS have never paid a divi - it's one thing if a company has a record of paying that brokers forecast will rise - but GMS simply has no record so these so called forecasts are fantasy imho. GMS may decide the time is not right - or go for buyback or purchase yet another vessel - it's up in the clouds. Thats without considering the troubles in ME right now.
I think you are missing the point here, Ben. Many of the funds like NextEnergy Solar Fund (LON:NESF) are set up with the intention of investing in assets that can generate a sustainable return that is sufficient to both cover payment of large dividends AND leave sufficient capital to reinvest for growth. The dividend cut is an admission that the managers have, at least to some degree, failed in that objective. I don't know the stock myself, but the share price reaction makes sense even if the dividend cut was the correct thing to do to protect future returns.
As an ignorant dividend investor myself, NextEnergy Solar Fund (LON:NESF) is now worthy of consideration again . The previous dividend was clearly unsustainable and so I sold mine a while ago. I was paying my own dividends out of my capital as the share price kept dropping.
Now that the divi has been chopped by about 50% and will be well covered, the probable 9% yield and big nav discount makes it an interesting income play. I don’t buy the ‘ripe for takeover’ argument. Unless the price is ludicrously cheap there would appear to be no takers for mature assets.
Back on the watch list.
RE NESF
"I don’t buy the ‘ripe for takeover’ argument.
Neither do I.
Whatever "reset" has occured at NESF looks to have been becuase the existing business model has not been delivering for shareholders.
The key question for shareholders is not how the return is distributed, but if any of the return is possible without the subsidy. I dont see how the assets of a heavily subsidised business can be correctly valued - the market appears to have similar concerns.
Graham any thoughts would be welcome on Alfa Financial.
Graham, can you comment on On Beach group (LON:OTB) TU and suspension of guidance please.
Appreciate it
On Beach group (LON:OTB)
I am on the sidelines here and would say for non holders - specific external events beyond control of company that are likely to be create shareprice weakness is the perfect time to be looking at picking up shares. Travel and airlines will always have blips in the road - this looks like a blip to me that i wouldnt expect to change teh medium term outlok for the company in ay way.
Is the current war going to be enough to stop someone wanting to go abroad ? Nope - imho they will just swerve the danger zone. that can create extra demand elsewhere perhaps (spain?)
One thing Trump is is a pragmatist who cares little about opinions of others - if the Iran war thing aint working - he aint gonna keep it going if it carries on losing lives of Americans with no gain being made. He could porbabaly walk away tomorrow and say that the main job of demilitarising Iran has been done so that thanks to him the middle east is now safer (thats what he would say not my opinion). Not even convinced that the Iranian leaders particualrly want a fight if they know the reality is that they are top of the list personally ref potential losers if it carries on.
I already have Jet2 (LON:JET2) top of my shopping list at present .
I would say ref short term shareprice any uncertainty can create weakness - so not great if you want to sellup and exit very soon. perhaps though they might quickly (preuming military action subsides) rework guidance and lop £10 mill off this years profits £5 mill off next years profits and do some kitchen sinking.
Fair play to the company for actually suspending forecasts here - i dont like companies without a plan/forecasts but it makes perfact sense here to say we need to simply wait 4-6 weeks to see if there are signs of return to normality before we can give sensible guidance and in the meantime being honest that current guidance likely wont be met is perhaps sensible
Thanks rmillaree. Seems a sensible viewpoint . I also have some Jet2 (LON:JET2)
On Beach group (LON:OTB) price already rising -just quoted 175p
This a response to all the comments on On Beach group (LON:OTB) and Jet2 (LON:JET2) and Saga (LON:SAGA) which are each interesting in their own right. On Beach group (LON:OTB) have been brutally honest in their declaration this morning and all credit to them. They have been bullish about extending into long haul, higher priced holidays and I guess the Gulf will have been a popular element in this expansion, so they will be hurt in a way that would have been less relevant in the past. In the past - and I am referring to the Turkish earthquake, they were quickly able to switch back to their homeland of Spain and Canaries, i.e. the Western Med. I am assuming their nimble approach will help again, although it will be in the context of a seeming trend to later/last minute bookings this time, which they are also very good at. Jet2 (LON:JET2) are the strong man in the market and they will suffer less, but they will suffer and I would not be looking to buy them at the moment. The strength of Saga (LON:SAGA) seems to be related to their 2 cruise liners, and I don.t see that changing soon. They have got their house in order on the insurance side, and their river cruises are European oriented. I see a likelihood of profit taking here, but not an unstable demand situation. All IMHO of course.
PS. I see that at 1300 Saga (LON:SAGA) is down almost as much as On Beach group (LON:OTB) which is surprising, although I reiterate that the former is probably partly profit taking on a stock that has risen a lot in the past 12 months.
What sort of fuel does Saga (LON:SAGA) use for their cruise ships, and what % of their operating cost is fuel? (guessing its quite high!)
And have they hedged their fuel requirements?
Maybe just investors putting 1+1 that its not just airlines but also cruise ships that would be impacted by high oil prices.
As a traveller I love Jet2; helpful staff; excellent at airports and in resorts; low compensation payments due to delays and they make every effort to get people back when then are issues. What concerns me is that EZJ are now getting into hotel packages and will compete accordingly, putting pressure on Jet2. I wont comment on O'Leary but he treats staff and customers alike! I still use Ryanair but as a last resort. Don't forget TUI. Just been on trip with them and it was excelllent. This is a very competitive market.
Jet2 (LON:JET2)
yep i like them for the same reasons - they are a funadementally a decent honest reliable business - it aint easy keeping holidaymakers happy - and its perhaps a diminishingh return trying to keep the 5% of people happy who love to complain for a living.
What concerns me is that EZJ are now getting into hotel packages and will compete accordingly, putting pressure on Jet2.
I would agree that it sounds like there may perhaps be overcapity in the marektplace now with companies starting to ramp up expansion post covid - i wont disagree with anyone who thinks is best to swerve this entire sector - my only hope is that as a group they would have all learned their lesson from covid and should sensible be contrating more on making sustainable margins - rather than expansion for expansion sake - there are very few ceo's though that are hyper conservative in that regard - they all sem to think they are the bees knees and can continue growing "medium term" - often if we look at the current period/next 12 months - the reality of growth isnt that its always done without hiccups - eg lower margins. Just look at MPAC (LON:MPAC) and their plans for global expansion that vanished in a puff of smoke. Sometimes its hard to say if lower margins would have happened anyway without expanasion - so not saying its an easy job to work out. Clearly Jet2 (LON:JET2) have had a purple patch ref profits 2024 and 205 - so it kinda makes sense having lower rating on the basis thats is competitive industry as you rightly highlight- ie peak purple patch ref margins probably wont continue. As we are now though the market already believes that next year will be materially worse than peak 2025 earnings - things may get worse but i trust managemnt to give us realistic projections when they update - at present though as of now i would expect further downgrade is waaay more likely than upgrade factoring in what On Beach group (LON:OTB) have said today.
Rm , why is Jet2 top of your list and not OTB ? OTB have no big fixed cost like Jet2 and others
Jet2 (LON:JET2)
Its just a rock sold company with many years of decent trading and a bulleptoof balance sheet - they seem very trusted brand which i alwasy like to see.
looking at stocky JET2 last year had 90% of shareprice covered by NAV - i think that had £2 bill of net cash at last accounts year end (that wont be all their money but is treble the figure that easyjet have)
On Beach group (LON:OTB) has 60% of shareprice covered by NAV which aint terrible but not as good
TB have no big fixed cost like Jet2 and others
agreed but i see OTB as being more of a middleman - if they have to pay "margin" to Jet2 for using their planes - well can Jet2 deliver same to customer cheaper if they deal direct and dont have to hand over margin to the airline as they are the airline and get it at cost. I think they had semi spat with Ryanair not so long ago (who do ryanair not fall out with) that does highlight that the power might be more with the airline - dont get me wrong i am happy to buy On Beach group (LON:OTB) - i cant see independents going away and they can perhaps pit Ryanair against Jet2 perhaps ref volume deals - so they might have stonger hand than i give them credit for.
In summary personal choice swayed by rock solid balance sheet and trusted brand.
I have a feeling that the Iranian regime has got the bit between its teeth now. It has survived the war so far, probably strengthened among the faithful - of which there are many, and although the unhappy are numerous, they are powerless and will be dealt with extremely seriously if there are protests. The US allies will be very unhappy by now, and they will be suffering in a sense at least as much as the Iranians - and for what? they may be asking.
When Trump pulls the plug, as he will, as the Iranians have said the war will be over when they say it is, not when the US says. They will have the determination to keep the Straits of Hormuz closed longer than the ROW will be able to put up with, muttering as they are today of taking action which may push the price of oil (and consequently gas too) up to the equivalent of $200 a barrel. Now that really would be something.
US forces, despite the massive bombardment have not succeeded in stopping Iranian missiles from hitting oil tankers in the Straits or attacks on the countries around the ME. So they have severely weakened Iran's missile and drone capacity but not closed it down because there must be so many Iranian delivery sources or fast mobile sources around this huge country which can keep up the barrage for some weeks yet. Interesting next few weeks ahead, sadly. All IMHO of course, and I hope I am wrong.
I didn't follow my gut instincts to sell everything when Trump's armada was being built up, and I did the same thing before his tariff day in 2025, Two costly mistakes.
fair comments time will tell as to how long it continues as is.
I see On Beach group (LON:OTB) is down 13% on their TU today
Does anyone know roughly what % of their business is covered by the war zone?
Costs
Restore (LON:RST) A very nice ‘boring’ business. As Christopher Mils puts it so adroitly, a business that gathers dust and cash.
I hold
Any views from Graham and team welcome.
Re Restore (LON:RST) a nice interview on a different perspective with Charlie … highlights how he thinks in terms of cash which will serve us well in this investment IMO…. (I hold ).
One to short? I am never keen on shorting stocks as it never feels right but its very hard to resist not doing so on Saga. Its had an amazing run and has started to fall in view of the market sentiment. Look at the value of the 2 stocks below. On the Beach, OTB ( top chart) was great value and this morning is as I write 14% down (not surprisigly due to outlook). Saga ( bottom chart) a more expensive stock has soared in the past, encouraged by a positive RNs it gave. Yet I personally cannot see how the outlook is not going to be affected; It does have mitigation of having some of its business in insurance. Any thoughts?A reminder of its Rns:
29 January 2026
Saga plc
Trading Update
Growth in underlying profit expected to be ahead of guidance
Significant strategic progress including launch of new Insurance partnership
Saga plc (Saga or the Group), the UK's specialist in products and services for people over 50, provides the following update on trading for the period from 1 August 2025 to 28 January 2026.
2025/26 Outlook
· The Group is expected to report an Underlying Profit Before Tax that is ahead of the prior year, and an improvement on our half year guidance.
· Ocean Cruise has continued to deliver an excellent performance, with a strong load factor of 93%, a 2ppt improvement on the 91% previously achieved in the prior year, and a per diem of £394, a 10% increase on the prior year.
· River Cruise Underlying Profit Before Tax has also continued to grow, benefitting from the launch of Spirit of the Moselle, achieving a load factor of 89%, in line with last year, alongside a per diem of £349, which is 7% higher than the prior year.
· Holidays is expected to report a stronger Underlying Profit Before Tax than last year, supported by booked revenue growth of around 13% and passenger growth of 11%. This performance reflects the positive impact of our decision earlier in the year to consolidate our Travel businesses under one management team.
· Insurance Broking outperformed our expectations, with continued growth in policy sales in three out of our four insurance products. Underlying Profit Before Tax is now expected to be marginally higher than last year and ahead of our expectations.
· Trading EBITDA is still expected to be ahead of 2024/25.
· Net Debt is expected to be marginally lower than the half year and significantly lower than the prior year, an improvement on previous guidance. This is supported by the strong trading cash flow and final proceeds from the sale of our Insurance Underwriting business, which were higher than previous guidance. Leverage is now expected to be below 4.0x. This excludes the £60m received from Ageas in December as a result of the new partnership going live. This receipt will temporarily further reduce Net Debt in the short term, pending a corresponding unwinding of working capital in 2026/27.
· In December, Saga Money launched a new and improved instant access savings account as part of our new partnership with NatWest Boxed; further innovative financial products are expected to be launched in 2026.
Looking ahead to 2026/27
· The Ocean Cruise booked1 load factor is 70%, 3ppts ahead of the same point in the prior year, and a per diem of £445, which is 13% ahead.
· The River Cruise booked1 load factor is 59%, 4ppts ahead of the same point in the prior year, and a per diem of £367, which is 3% ahead.
· Holidays booked1 revenue is £132m, 5% ahead of the same point in the prior year, and passengers of 39k, which is 1% ahead.
· Insurance Broking Underlying Profit Before Tax is expected to be in line with previous guidance, as the Ageas partnership becomes fully embedded in 2026/27.
· Following strong cash generation in 2025/26, the Group has passed its peak leverage point, with further reductions in both Net Debt and leverage, expected in 2026/27.
1 Bookings at 25 January 2026
Mike Hazell, Saga Group Chief Executive Officer, said:
"This has been a period in which we traded ahead of expectations, particularly in Travel, delivered excellent financial results and continued to implement our strategic plans. Demand for our Ocean and River Cruises continued to grow and we saw a material increase in the number of customers taking our hotel and touring holidays. Trading in our Insurance Broking business has also been strong and ahead of expectations. The Group now expects to report an Underlying Profit Before Tax ahead of the prior year, and an improvement on the guidance we gave at the half year.
"Alongside this, we have made significant strategic progress. We have simplified our Travel business under one management team, creating a single, more efficient and customer centric operation. At the same time, we successfully completed the sale of our Insurance Underwriting business and launched partnerships with Ageas in Insurance Broking and NatWest Boxed in Money.
"As we look ahead, we expect the momentum to continue to build in our Cruise and Holidays businesses, while in Insurance Broking we expect Underlying Profit Before Tax to be in line with previous guidance. We continue to make progress against our longer term plans and are currently ahead of our expected trajectory. We remain confident of delivering underlying profitability of at least £100.0m, and leverage below 2.0x by January 2030."
The Group's preliminary results for the year ending 31 January 2026 are scheduled for Wednesday 15 April 2026.
Interesting charts of contrast - illustrative of your name, momentum, Any chance of naming the companies? I concede age and declining sight may mean I have missed them.
was looking at Saga and On the Beach. I have just edited post to make it clearer
if you like, but I will be topping up on it
Thank you!
Momentum-if you haven't seen it have a look at Roland Head's comments made on November 26 post Mello and Alex Wood's comments on Saga. Assuming Alex's reasoning is right, and there was also a very large purchase (1.2M shares at 2.74) by de Haan on 29 September last year, I think there's good reason behind Saga's rise. I hold, but did reduce at 5:50. Wood was holding out for a rise of some 3 to 4 times in the SP from something like 280p at the time.
Thanks I will have a look but ultimately what drives the markets is sentiment. I did open a short on it soon after my post
Thanks Charlie, have now looked at November 26. Interesting read. I like saga a lot as a company and will most likely dive in to buy at some time in the future. As a trader I tend to follow the market which is why I shorted it today. I closed my short at the end of the day and took profits. Unfortunately the market is ruthless and it will give its judgement. I have learned from experience you make money if you follow the market sentiment.
Appreciate your thoughts on LON:FAN if you have capacity? I do not own but has been on my watchlist for past 6 months. They are acquiring companies and growing cash flow and dividends steadily.
If you could also cover M&G (LON:MNG) that would be appreciated. The capital position looks more stable than Legal & General (LON:LGEN) from a quick glance at their results, but possibly not growing as strongly as Legal and General.
Is there any chance of adding Savills (LON:SVS) reporting full year results and US acquisition today?
Ab Dynamics (LON:ABDP) I hold
Can you add please. Trading update. In line with "Company compiled analyst expectations is for a mean adjusted operating profit for the year ended 31 August 2026 of £24.4m"
Problem. in China with a European OEM experiencing significantly lower revenues than expected. Mostly non cash impairment of £16m and planned review of the business in H2.
Outlook - "Underlying demand drivers remain strong, and the increased customer activity seen towards the end of the last financial year has continued into HY26. As a result, the Group carries forward £47m (28 February 2025: £42m) of orders, which together with revenue already delivered in the first half provides c70% cover of FY26 expected revenue. The order book includes £18m expected to be delivered in FY27, building visibility into the medium term."
We have this in the table, rwh3ue! G