Daily Stock Market Report (Thur 16th July 2026) - SOM, MSI, ROR, CAPD, DNLM

There’s little overnight news to report:
US strikes on Iran continue. An Iranian-linked supertanker has been hit as part of the new blockade of Iranian ports.
SpaceX is in the headlines as its share price has fallen back to $135, which is where its IPO was priced. It was over $200 a month ago.
Thomas Tuchel is still expected to lead England into Euro 2028, despite criticism of his defensive substitutions in last night’s loss against Argentina.
Overnight market movements:
The FTSE is down 0.35% at 10,470
S&P 500 is unchanged at 7,575
Brent crude (September) is down 0.5% at $83.80/bbl
Gold is down 0.7% at $4,030/oz
Bitcoin is unchanged at $64,900
Site issues: there are issues with the site this morning, I'm very sorry I don't have more information but I have raised the alarm!
Afternoon update: I believe things are running more smoothly now.
Roland Head joins me today.
The Agenda is complete. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
BHP (LON:BHP) (£155bn | SR85) | FY26 copper production was down 3% to 1,952.8kt but within guidance. Iron ore production up 1% to 264.7Mt, also within guidance. All assets expected to be within unit cost guidance despite inflationary pressures. | ||
SSE (LON:SSE) (£30bn | SR) | Significant increase in renewables output, up 31% year-on-year reflecting favourable weather and capacity additions. Earnings guidance unchanged for adjusted EPS of between 168 - 193p for 2026/27 and between 225 - 250p for 2029/30. | ||
Experian (LON:EXPN) (£24bn | SR60) | Q1 revenue +10%, in line with expectations. Full-year expectations are unchanged. | ||
Diploma (LON:DPLM) (£9.1bn | SR74) | Organic revenue up 15%, “very strong Q3 performance”. Further upgrade to FY26 guidance: organic revenue growth 14% (prev. 12%) with acquisitions to add 6% (unchanged). Operating margin of c.26.5% (prev. c.25%). “Operating profit growth of c.42%, representing a further c.7% upgrade” to previous consensus of £454m. | ||
DCC (LON:DCC) (£5.4bn | SR93) | An improved offer from KKR is under discussion that would total up to 6,797.22p per share. The increase represents a 125p consideration for the expected sale of the DCC Technology business. The original base offer of 6,525p + dividend has been “substantially agreed”. PUSU deadline has been extended to 5pm on 27 July. Q1 trading update: group operating profit on a continuing basis was in line with expectations. | TAKEOVER | |
Frasers (LON:FRAS) (£3.4bn | SR90) | Revenue +8.7%, driven by international growth of 59.2%. Adjusted pre-tax profit -4% to £538.0m due to an increase in impairment and finance costs. Adj EPS -15.1% to 83.3p vs consensus of 98.5p. Attempted acquisitions of HUGO BOSS and Accent Group mean that it is “not appropriate to provide financial guidance for FY27 at this time”. | ||
RS (LON:RS1) (£3.0bn | SR87) | Positive momentum seen at the end of last year has continued into FY27. Full-year expectations appear to be unchanged (consensus: revenue £3,014m, adj pre-tax profit of £261m). | ||
Rotork (LON:ROR) (£2.38bn | SR) | Recommended cash acquisition of Rotork by ABB Ltd. Cash offer of 506p per share, comprising 503p plus a dividend of up to 3p. Represents a 73% premium to yesterday’s closing price. | TAKEOVER (Graham) | |
Qinetiq (LON:QQ.). (£2.33bn | SR79) | Q1 trading was “consistent with full-year expectations” for FY27 revenue growth of 3-5% and adj EPS growth of 8-10%. | ||
Premier Foods (LON:PFD) (£1.73bn | SR93) | Revenue up 2.7% with branded revenue up 4%. Further market share gains in Grocery and Sweet Treats. On track to deliver FY26/27 Trading Profit expectations. | ||
Dunelm (LON:DNLM) (£1.65bn | SR58) | Q4 sales +2.9%, FY26 sales +3.1%. FY26 profit in line with expectations (consensus for FY26 PBT of £210m). | AMBER/GREEN = (Roland - I hold) [no section below] After two profit warnings since January, it’s a relief to see Dunelm meet revised guidance for FY26. Today’s commentary suggests costs were in line with expectations and shows a modest improvement in sales, despite some adverse impact from very hot weather and general pressure on consumer spending. I estimate free cash flow of perhaps £140m based on today’s guidance. That would value the shares with an 8% free cash flow yield and cover the forecast dividend yield of 6.9%. I think the shares could be good value at this level if FY26 proves to be a low point for earnings, as expected. While there’s no guidance for FY27 today, I don’t see any reason to change our previous broadly positive view. As a holder, I’d consider buying more at current levels. | |
Ocado (LON:OCDO) (£1.50bn | SR20) | Underlying revenue +1%, with adj EBITDA of £81m, excluding Kroger and Sobeys closer impacts. FY26 outlook: Technology Solutions revenue c.£500m and EBITDA margin of c.30%. | ||
Trustpilot (LON:TRST) (£1.13bn | SR76) | H1 revenue up 23% to £151m, with bookings up 22% to £171m and ARR up 15% to £313m. Growth driven by Enterprise and US (+27% cc). On track to deliver full year guidance. | ||
Funding Circle Holdings (LON:FCH) (£525m | SR61) | H1 revenue +50% to c.£138m, with pre-tax profit of c.£23m (HY 25: £6m). Overall credit extended was £1.7bn (HY25: £1.1bn). “Firmly on track to achieve our FY 2026 guidance” for at least £235m in revenue and £35m of pre-tax profit. | ||
Metals Exploration (LON:MTL) (£406m | SR48) | Q2 gold revenue of $47.1m (Q1 26: $52.9m) with pre-tax free cash flow of $25.2m (Q1 26: $29.3m). Construction continues at La India with first gold on track for December 2026. To support funding, the company is in the process of finalising a $27m mining equipment loan with a local Nicaraguan bank. | ||
Thor Explorations (LON:THX) (£365m | SR99) | Q2 gold sales of 17,050oz at an average price of $4,535/oz, generating revenue of $77.3m. FY26 production guidance unchanged at 75-85koz of gold. Cost (AISC) guidance is also unchanged. | ||
DFS Furniture (LON:DFS) (£335m | SR64) | FY26 adj pre-tax profit expected to be c.£45m, in line with previously upgraded guidance. Net debt reduced to c.£69m at 28 June, from £107m in FY25. | ||
Gooch & Housego (LON:GHH) (£239m | SR55) | Private equity offer of 1,234.9p for each G&H share, comprising 1,230p plus the 4.9p interim dividend. This represents a 40.7% premium to yesterday’s close and a 34% premium to the volume-weighted average price of 918p over the last month. | TAKEOVER | |
MS International (LON:MSI) (£238m | SR48) | “Revenues broadly in line with last year of £115.01m (2025 - £117.50m) with a reduced profit before tax of £15.06m (2025 - £20.05m), which was both anticipated and signalled in earlier shareholder communications.” Received first contract for newly developed MSI-DS Multi Weapon Station for delivery into the Middle East in 2027. Chairman and largest shareholder Michael Bell steps down. | ||
Capital (LON:CAPD) (£233m | SR89) | SP +6% Stronger-than-expected H1 2026 revenue of $219.0 million, up 37.6%. Reiterates full‑year revenue guidance of $410 - $440m. “...well positioned to deliver continued growth across all three divisions." Panmure Liberum update: confirms forecasts are unchanged: - FY26E adj EPS: 15.3p - FY27E adj EPS: 20.3p | AMBER/GREEN = (Roland) [no section below] There are a number of moving parts within this business, which generates income from providing a mix of drilling, mining and laboratory services to miners. To add to the complexity, Capital also has a concentrated investment portfolio of gold miners. As far as I can see, this update is essentially in line with expectations and suggests a fairly even split of revenue across H1 and H2. Fleet utilisation improved slightly versus Q1 and with a number of rigs currently in transit, I wonder if this could improve further in H2. I’m reassured to see average monthly rates per rig rose by 10% in H1, suggesting that capital expenditure levels among gold miners remains strong. One key near-term risk seems to be the possibility that the Reko Diq in Pakistan mine could see a temporary reduction in activities due to security concerns. Although the contract is still said to be performing in line with expectations, this is a large project for Capital and any shortfall could hit full-year expectations. Capital shares currently trade on a P/E of 9 and at a small discount to book value. On balance, I don’t see any reason to change my previous moderately positive view on this founder-led business. | |
Helical (LON:HLCL) (£229m | SR40) | A strong start to the financial year. “Our development pipeline looks increasingly well timed…” £12m profit from sale of 100 New Bridge Street to be returned to shareholders via capital return B Share Scheme (pending approval at General Meeting today). | ||
Gulf Marine Services (LON:GMS) (£195m | SR62) | Four-year charter for one of its self-elevating accommodation units, to be deployed offshore Brazil. | ||
Ramsdens Holdings (LON:RFX) (£193m | SR92) | Revised and final offer of up to 684p per share, comprising 675p per Ramsdens share and up to 9p in dividends. | TAKEOVER | |
Crest Nicholson Holdings (LON:CRST) (£189m | SR46) | A more cautious outlook for the remainder of the financial year. Discussions with lenders to amend its covenants. The waiver of the interest cover covenant has been extended to 30 September 2026. | BLACK? (FY26 EBIT at lower half of previously guided range) | |
Aew UK Reit (LON:AEWU) (£170m | SR78) | Under the terms of a Possible Offer, AIRE shareholders would receive 0.725 shares in AEWU for each AIRE share held. This represents a 6% discount to AIRE’s NAV per share. | TAKEOVER | |
Foxtons (LON:FOXT) (£129m | SR59) | Trading has been adversely impacted by the prolonged downturn in the sales market, as well as short-term volatility in the lettings market following the introduction of the Renters' Rights Act. Reversal of £3m of previously recognised revenue that had been contractually due. Full year adjusted operating profit to be in the range of £17m-£19m. | BLACK | |
Inspecs (LON:SPEC) (£106m | SR76) | Robert Brodie will join in Autumn 2026. Was CFO of City Energy Network. | ||
Pharos Energy (LON:PHAR) (£104m | SR73) | Group working interest 1H production was 5,650 boepd net, in line with FY2026 guidance of 5,200 - 6,400 boepd. | TAKEOVER (under offer) | |
SIG (LON:SHI) (£97m | SR53) | “Whilst trading in the first half improved sequentially, no material recovery in market conditions in H2 2026 is anticipated and, therefore, the Board now expects the FY 2026 underlying operating profit to be c. £25m.” | BLACK | |
Somero Enterprises (LON:SOM) (£96m | SR83) | Better-than-expected trading in H1 2026, as improved conditions seen toward the end of 2025 continued. Continued stabilization in US private non-residential construction. FY 2026 revenue to be ahead of market expectations, with commensurate improvement in profit and operating cash generation. | AMBER/GREEN ↑ (Roland) I think it would be unwise to discount macro risks and greater competitive pressure, but I don’t see why Somero can’t remain a leading player in the concrete-levelling field if the business is well managed. A useful 19% upgrade to 2026 EPS estimates is enough to persuade me to turn more positive here, despite limited visibility. | |
Premier Miton (LON:PMI) (£63m | SR54) | £0.8 billion net outflows. Positive market/investment performance of £0.5 bn. AUM falls from £9bn to £8.6bn. Investment performance is improving across a number of key strategies. On track to deliver previously announced cost savings. | ||
MTI Wireless Edge (LON:MWE) (£60m | SR91) | $4m of orders recently received, all of them to be delivered by the end of Q1 2027. It was “an above average period of demand”, and it “significantly enhances our order book for FY26 and FY27 and supports the overall growth of the business.” | No reference to any impact on expectations. | |
Hercules (LON:HERC) (£24m | SR34) | Subsidiary company Advantage NRG has secured two further contracts across the National Grid electricity transmission network with a combined value of c. £3.4 million. | No reference to any impact on expectations. | |
Shoe Zone (LON:SHOE) (£23m | SR68) | May and June sales ahead of market expectations. Now expects an adjusted loss before tax of no greater than £1.0m for FY26, an improvement on the previous guidance of an adjusted loss before tax in the range of £1.0m - £2.0m. | ||
Northern Bear (LON:NTBR) (£14m | SR77) | Revenue +10.2%. Adj. operating profit flat at £3.8m. Net cash position increases from £2.5m to £6.2m. FY27 outlook: “underlying revenues to remain broadly consistent with the excellent underlying results in FY26 , notwithstanding our significant investments in both personnel and premises intended to generate further future opportunities and mitigate the negative effects of the present economic outlook.” |
Graham's Section
Rotork (LON:ROR)
Up 67% at 485.2p (£3.96bn) - Offer for Rotork plc - Graham - TAKEOVER
After a lull in takeover activity, UK-listed stocks are suddenly dropping like flies again.
Rotork is an old name on the stock market, having been listed continuously since 1968.
But it turns out that Swedish-Swiss company ABB is willing to put a high price on it:
506p in cash (including a permitted dividend of 3p).
It’s a recommended acquisition and it’s at a 73% premium to yesterday’s close.
This is far above the typical minimum needed to get deals over the line, suggesting that a) the stock has been severely undervalued, b) the Rotork board negotiated a very generous offer, or c) some combination of the above.
Valuation:
The Implied Enterprise Value represents a multiple of approximately 5.3x Rotork's sales and 19.5x Rotork's adjusted EBITDA for the financial year ended 31 December 2025.
19x EBITDA is a serious earnings multiple. In P/E terms, the offer is about 29x, head and shoulders above the 16x forward multiple that it was trading at yesterday.
What it does: Rotork makes industrial flow control equipment: actuators, gearboxes and related software.
It will fit in nicely at the industrial conglomerate ABB:
Rotork is expected to operate as a separate division within ABB's Automation business area under a strategic growth mandate, consistent with the ABB Way. The Acquisition would add 3 per cent. to ABB Group revenue and 12 per cent. to the revenues of ABB's Automation business area for the financial year ended 31 December 2025.
The Chair of Rotork says: “The combination brings together two companies whose purposes are closely aligned, with a shared focus on automation and electrification to enable more sustainable and efficient operations.”
Irrevocable undertakings/letters of intent: there is no word yet from major shareholders as to whether or not they support the acquisition. They may have only heard about it today, like the rest of us. Here are the top entries on the shareholder register:
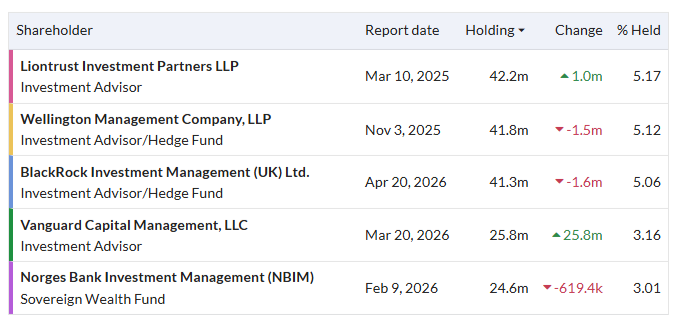
As we don't yet have undertakings or letters of intent from these institutions, we can't say for sure what position they'll take. But I expect that they are very likely to be pleased with the prospect of a windfall at a 73% premium.
Graham’s view
Congratulations to anyone holding Rotork overnight. I think this is likely to go ahead due to the enormous premium being offered, far above where the UK market was willing to value Rotork.
As always, I have mixed feelings about this spate of takeovers. The obvious downside is that it leaves us with a smaller pool of listed shares to analyse. On the other hand, given that stock market valuations are low, we need these takeovers to realise value for our investments. And that's very important, too!
I'd be relaxed if there was a steady stream of IPOs to replace the companies that are leaving us, but that is not the case.
At least this wasn’t yet another US takeover. If anything, it proves that takeovers aren’t just being driven by the much higher valuations on the other side of the Atlantic.
Roland's Section
Somero Enterprises (LON:SOM)
Up 14% at 211p (£110m) - Trading Update - Roland - AMBER/GREEN ↑
Today’s upgrade makes for pleasant reading for shareholders in this US small cap, which produces concrete-levelling machines used by construction contractors.
Somero makes most of its money in the US but has suffered a slump in sales in recent years following the pandemic-era warehouse boom. It looks like the group’s performance may be starting to recover under newish CEO Tim Averkamp.
H1 trading update:
The Board is pleased to report better-than-expected trading in H1 2026, as improved conditions seen toward the end of 2025 continued through the first half, primarily reflecting continued stabilization in US private non-residential construction, the Company's largest market.
Customer activity in the region has improved, with some projects previously delayed by uncertainty over tariffs, interest rates, restrictive immigration policy, and geopolitical conflict beginning to move forward.
North America: Somero says it’s seeing improving demand for its larger Boom Screeds following a three-year decline, with new models contributing to sales. I guess this could reflect contractors who purchased equipment in 2021-23 deciding to upgrade to newer models.
Other markets: Somero remains heavily dependent on the US market which generates about three quarters of revenue. But the company is trying to expand in Europe and Australia and say it’s seeing some progress in these markets:
Europe: “trading was ahead of H1 2025, despite the market continuing to be affected by macroeconomic and geopolitical headwinds, as well as competitive pressures”.
Australia: trading “continued to normalise, improving moderately year on year”.
Rest of the World: “trading is expected to be broadly comparable with H1 2025”.
Outlook
Following the stronger first half, and assuming trading in the second half of the year is in line with management expectations, the Board now expects FY 2026 revenue to be ahead of market expectations, with commensurate improvement in profit and operating cash generation.
Somero specifies consensus expectations as being for revenue of $86m and adjusted pre-tax profit of $13.5m.
Fortunately, house broker Cavendish has made updated forecasts available on Research Tree this morning – many thanks. These show a useful increase to full-year expectations:
FY26E revenue: $90.6m (+5.4% vs previous)
FY26E adj pre-tax profit: $15.8m (+17.2% vs previous)
FY26E adj EPS: 22.3c (+19.4% vs previous)
FY26E net cash: $33.2m (unch)
This is good news, as it looks like Somero’s 2026 profits should now be ahead of those reported for 2025 (adj PBT: $15.2m, adj EPS: 20.0c).
It’s also encouraging to see that balance sheet strength has been maintained and that margins should improve this year as volumes start to recover.
Governance review: Somero recently suffered a remarkable shareholder rebellion, with a majority of shareholders apparently voting against every AGM resolution (see here and here).
I don’t know the background to this, but the company is carrying out a governance review and says today that it will publish the results on 21 July 2026.
Roland’s view
Somero’s operating profit has fallen by nearly 70% since 2021, but today’s update suggests 2026 could mark the start of a return to (modest) growth.
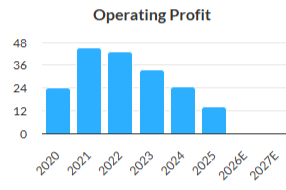
There’s still plenty of macro exposure to consider here – not least what happens if the data centre boom slows in the US.
Cavendish hasn’t published any forecasts for 2027 yet, suggesting visibility is limited. As I understand it, this is a characteristic of this business. In previous management webinars the company has explained that contractors don’t generally order new machines until they have a committed work package to deliver. As a result, Somero has to maintain good stock availability despite only having very short-term visibility on sales.
Today’s upgraded forecasts and share price movements leave Somero trading on a 2026E P/E of 13 with a possible dividend yield of 3.9%.
While Somero’s sales and profits remain well below past levels, this is reflected in the share price. Personally, I think a return to historic highs may be unlikely. My impression is that Somero faces more competition than it did historically.
Even so, I don’t see any reason why Somero can’t remain a leading player in the concrete levelling market if it’s well managed. I think there’s scope for further gains if the company can deliver a sustained return to (modest) growth:
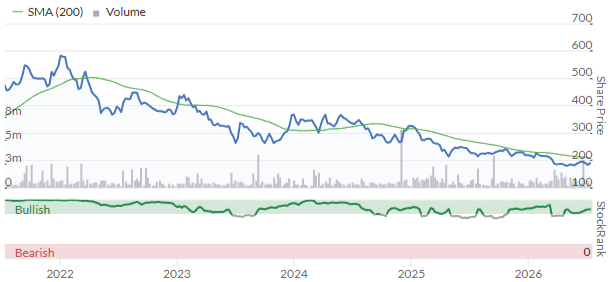
Graham was neutral on Somero in June and the StockRanks have mirrored this view.
I’m tempted to remain cautious, but in the light of today’s upgrade I think it’s fair to update our view to be moderately positive, at AMBER/GREEN.
MS International (LON:MSI)
Down 4% at 1,400p (£230m) - Final Results & Directorate Changes - Roland - GREEN =
Today’s results are slightly overshadowed by the news that MSI’s executive chairman and largest shareholder Michael Bell has stepped down after 50 years with the business.
Mr Bell explains his departure with the comment that “age brings notable challenges”. He will become Life President from today and has also entered into a consultancy agreement for a fee of £12,500 per month.
Bell will be replaced by two men:
Michael O’Connell is promoted from Group MD to CEO. He has worked with Bell for over 40 years and is “fully aligned with my [Bell’s] approach to the business”. O’Connell is a 6.5% shareholder.
Anthony Wreford will become non-executive chairman. Mr Wreford is an experienced strategic advisor who is said to have “played an important role in the Company’s recent strategic decisions in an independent advisory capacity”.
Of course, the main strategic change in recent times was last year’s decision to focus on developing MSI’s defence business and investigate the sale of its other divisions (Forgings & Petrol Station Superstructures and Branding).
Possible disposals: today brings news that the company is in talks with potential buyers for the sale of the Petrol Station Superstructures and Branding business. No details are available currently, but Mr Bell hopes that “an announcement can be made before the end of the summer”.
The company also reports unsolicited interest in the Forgings business and plans to revisit this once the Petrol Station Superstructures sale is “approaching a satisfactory conclusion”.
Today’s results are presented with the main focus on Defence, reflecting the group’s strategic plan. Let’s take a look.
FY26 results (y/e 30 April 26): key points
Revenue down 2.1% to £115.0m
Pre-tax profit down 24.9% to £15.1m
Diluted earnings per share down 24.5% to 65.7p
Net cash of £46.5m (FY25: £28m)
Full-year dividend of 26p per share (FY25: 23p)
There are no broker forecasts in the market for this business, so we cannot see if these numbers are in line with expectations. However I think that they are.
In its FY25 results, the company advised that delayed purchase decisions in the defence sector meant that FY26 results could be adversely affected. This seems to have been reflected in today’s numbers.
Defence and Security: in today’s management commentary Bell sounds a note of frustration about the length of time needed to navigate government procurement processes (my emphasis):
Additionally, it's very encouraging that most Governments now regularly state that defence should have a higher priority. However, getting to the point where these objectives translate into firm defence orders is a jump that's taking longer than reasonably anticipated. Anyone with an eye on the political agenda will have seen how Governments are reassessing their defence priorities and objectives against other financial demands.
Despite this, there is some positive news on the company’s MSI-DS Terrahawk counter-drone system:
Following on from the successful trials of the MSI-DS Terrahawk VSHORAD, these systems have been providing vital protection within the Middle East. The MSI-DS Terrahawk has been officially recognised as having provided protection against a significant number of drones within the region during the conflict.
The group’s newly-developed MSI-DS Multi Weapon Station has also received its initial order, “for delivery into the Middle East in 2027”.
More broadly MSI reports “a substantial level” of interest in its “combat proven systems” and expects much of this to convert to orders in due course. The company has appointed a new US VP of Business Development to help develop US land and naval markets.
Management reminds us that revenue from defence contracts is only recognised when control of goods and services passes to the customer:
The significance is that, whilst we might be busy in our manufacturing and production facilities, the timing of the transfer of control means revenue and profits are not instantly recognised.
Profitability & Balance Sheet
Today’s accounts show a reduced operating margin of 12.1% (FY25: 15.9%). But this remains a very profitable business – my sums suggest a return on capital employed of 18.7% (FY25: 22.5%).
Cash generation also deserves a mention. MSI’s net cash position improved to £46.5m last year (FY25: £27.8m). Checking the cash flow statement suggests this was due in large part to a net working capital inflow of c.£11m, as inventories and receivables fell sharply (presumably reflecting completed orders).
Stripping out working capital movements suggests to me that free cash flow was about £11m last year, giving perfect 100% conversion from net profit of £11.0m.
This looks like a high quality business to me, in financial terms, with great balance sheet strength and liquidity. I don’t have any concerns in this regard.
Outlook
Nomad Shore Capital has published an updated note on MSI today but hasn’t included any forecasts for FY27. The company’s guidance for the year ahead is also limited, albeit positive:
As we have previously communicated, these results confirm a year of strategic progress and new opportunities without these being yet reflected in the overall financial performance. I am confident that many of the market barriers that have constrained us last year will ease during the current financial year.
I, therefore, leave the Board confident that our prospects remain excellent.
Roland’s view
Last year’s earnings decline means the shares look more expensive than they did in January, despite a flat performance so far this year:
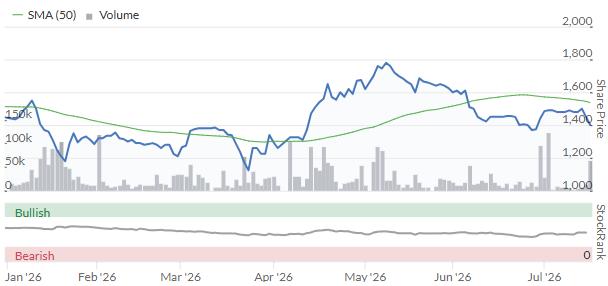
Today’s results value MSI shares on 21x trailing earnings, with a 1.9% dividend yield. This P/E falls to 17x if net cash is stripped out.
The investment case here is based on the potential for significant growth in defence, paired with possible proceeds from the disposal of the group’s other operating divisions.
Taking a medium-term view on this suggests to me that this story remains intact and that there could still be some value on offer here. I wonder also if there’s the potential for a takeover of the defence business once the other divisions have been divested.
We’ve been GREEN on this business in the past, with Graham commenting in January that “this is really a call on the integrity and judgement of management, rather than any real insight into prospects of the company’s defence division”.
I’m inclined to maintain our positive view today on the basis that I think the story of management integrity and strategic consistency remains intact and could deliver further value, on a medium-term view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

61 comments
Roland quite positive on Dunelm (LON:DNLM) but after two profit warnings I sold at 736p back in May 2026. Current share price and today’s bounce demonstrate that the ‘sell on a profit warning’ doesn’t always work. Though to be fair if I had sold on the first profit warning the current price would still be below the level it closed at after the profit warning. Perhaps the mantra should be ‘always sell on the 1st profit warning’!!
Yes, it’s sell on the first profits warning to cut the loss asap. Selling after later warnings can be far too late, with big loss, and sometimes as with Dunelm (LON:DNLM) today, just ahead of the worst being over. Dunelm (LON:DNLM) looks tempting again after the much more promising update today.
DCC (LON:DCC) (I hold)
The bid for DCC has been sweetened a little but major shareholders still oppose it.
A short summary of the latest in the FT:
The “improved” offer changes little. The additional £1.25/share is conditional on the Nexora sale, leaving the core £65.25/share bid unchanged. Aviva, Fidelity, Marathon and founder Jim Flavin all remain opposed, arguing DCC is worth materially more, with Fidelity stating it would not accept less than £70/share. The revised proposal appears to acknowledge extra value in Nexora rather than increase the valuation of DCC’s core business.
Roland - Thank you for such a detailed review of the Somero Enterprises (LON:SOM) trading update.
Have you noticed the dwindling share count, where the company bought back 1m shares (c.2%) alone on 25th June 2026 (Reported 26th June 2026)?
I assume the StockReport KPIs only reflect the 55m shares reported in the last Financial Accounts, rather than the 51,776,016 of issued share capital.?
I should probably ask if a live share count can be included in a future Stockopedia upgrade.!
Somero Enterprises (LON:SOM)
I think your summary is likely pretty spot on Oliver - i always think of it as Brucie bonus when share count is reducing that the stated numbers at prior end are kinda "behind the game" - do remember though that the cash will have departed the building to pay for shares - so on lfl basis they will be earning interest on $5-$8 mill dollars less if thats waht they have splashed on shares.
I think its most likley weighted average for last year - so thats probbaly conserative in itself if count was reducing in year.
Note the annual report flagged up 800k ish shares that might be needed ref restricted stock units - thats in 2025 calc - but might not be in licve current count - so perhaps safer to add 1 mill to total count - if they may need to issue new shares or use bought back shares rather than cancelling them.
deffo good point tmade hat there is decent decrease in shares in issue
i dont know how current year eps estimates on stocky would be calculated
Rmillarie - Good point.
Somero Enterprises (LON:SOM) are very cash generative, and have communicated the minimum cash (no debt) they will retain in the business.
So if there is a sudden 1million share purchase, just days before a highly positive trading update, there is a fair bit of missing information to calculate latest KPIs.
More problems with the site this afternoon. I really do think that someone needs to explain to paying customers what the issues are, and what fixes are being put in place with a timetable so we can all manage our expectations.
I have put a message to the same effect on the green button, and would suggest others do the same. This site, when working properly, is for me the best site available to help me on my investing journey. But when things aren’t working as they should, (and they’re not at the moment) then I can’t help but wonder at the accuracy of the information that the site is presenting to us.
Please someone in customer services, say something.
Thanks
Shoe Zone (LON:SHOE)
Smith Brothers bought at 80p in 2021 and the price went up over 300%.
Now they bought at 50p. Should see more upgrades soon, similar to today’s. Probably the next one is to turn profitable.
All the best
Agree. Good recovery potential.
This is my first—and quite possibly my last—message here, please forgive me if this is not the right place to post. I have been investing for many years, but I would never claim to be anywhere near the standard of the expert staff and contributors on this board.
My dilemma is whether to renew. I am now approaching 80—perhaps one of the oldest members here—and while my heart tells me to continue, my head says it may be time to start moving gradually back towards cash. As an interim step, I have begun shifting towards investment trusts, helped by the outstanding comments from knowledgeable contributors on the monthly IT thread, especially Charles and Ken Mitchell. However, I have less understanding of investment trusts, and they do not seem to be especially well supported by Stocko. I would therefore be very interested in the views of this outstanding and supportive community, which I have enjoyed and learnt from over the last few years.
You could take a look at Seraphim (SSIT) to add a bit of spice. I hold for a bit of fun. Its share price seems linked to SpaceX, although it seems to have little to do with it. The two have been falling together recently.
Seraphim focusses on European satellites etc and the Moneymakers podcast recently suggested that the NAV of one of its investments (ICEYE) is now worth EUR10bn and should give SSIT a current NAV of about 250p a share - it's trading on a massive discount.
Interesting, I'll take a look but I may be selling rather than buying these days
You’ve presumably heard of inflation.
Sharia compliant funds will be popular soon enough and as safe as Windsor Castle.
Personally i would have thought investing would be an excellent hobby in old age.
You may want to keep the risk profile fairly modest by holding cash, an equity tracker and then a small fun portfolio of a few shares selected by using the stock ranks or even following Ed's NAPS selections.
I unequivocally endorse this view! The older I get the more time there is to research, consider and act or not. Good work for what little brain I have and it beats Wordle.
Thanks Epitychia and Charlie51. That's what my heart keeps saying but head is more cautious. Reducing the risk profile, moving towards ITs and looking at NAPS does seem a good way forward. Perhaps give it another year or two and see how it goes. Keeps the brain active. Thanks both for taking the trouble, appreciated
You might get some value from the work of Jonathan Davis who writes and broadcasts about investment trusts - interviewing funds managers and analysts, and publishing reviews of individual trusts.
His podcast is free and called Money Makers; his website is here: https://money-makers.co/ (subscription required).
He also writes on Substack too.
I think that you are taking a sensible approach. IT's, ETF's and trackers will keep your money working whilst reducing risk that a portfolio of individual shares brings. The Podcast 'The Art of Investing" is worth a listen as they have a "broad brush" approach to the markets and don't invest in individual shares.
Whilst I like the Money Makers show I stopped listening due to the numerous portfolio managers plugging their fund and trotting out the usual "top down / bottom up / taking the long view" platitudes.
Norfolk Oldboy
Remarkable to read your post – I could have written it myself! Same age profile, same concerns and same options being considered. I’m not happy with the markets at present and have moved my 2 portfolios (ISAs) to 50% cash until I feel happy to reinvest. The cash will go to Money Market funds if required. The portfolios already hold several ITs and ETFs with help from the IT thread plus many shares selected using Stockranks etc. Other selections are based on input from Byte Tree (Charlie Morris) which I find a great learning / support publication. I could never abandon Stocko and consider it superb value.
My main reason to keep going is also to keep my brain working whilst everything else declines. As soon as I feel really concerned about things I may retire.
Stick around and we can catch up in the early 2030s. Good luck.
Thanks Jim. It's comforting to know others feel the same way. I think this board is so encouraging and always good to get a wide range of views. As I say my head keeps telling me to get out but I still like the challenge. I think I just need to reduce the risks in the portfolio, those s where success is always just round the corner. If I make it to 2030 I'll be very happy to catch up. Cheers
Norforlk Oldboy
I have recently started using Short Duration Bonds (especially useful in Stocks & Shares ISAs with upcoming tax on Cash) to allow me to invest in a very Cash Like Asset (Liquid, little volatility) which you can choose to compound or repay as income.
An Accumulating Short Duration Bond has the added benefit of being a Capital Gain when sold, rather than creating an additional income stream.
The best Short Duration Bond (Fund) I have found is the Royal London Short Term Money Market Fund (Class Y Accumulation)
SEDOL: B8XYYQ86
ISIN: GB00B8XYYQ86
Unfortunately this investment asset can not be tracked in Stockopedia, but I have been able to purchase it through AJ Bell & Barclays Smart Investor.
For reference, I am an unqualified private investor, and this is not advice.
Don't go Norfolk Oldboy, it's fun on here as well as educational. I'm 83 still learning and sometimes earning, helped greatly by Ed's posts, Roland Graham and Mark analysis, and some very wise experienced investor's comments and tips.
thanks JASVFS, nice to know there are others as old as me. I like to try to keep learning too and have leart much from those experts you name, and many other posters on here too. Think I'll keep going for a while longer
Keep Going Norfolk Old boy, it is known that Crosswords and puzzles are good to keep the brain alive and the Stock Market and Equity Investment is the major puzzle. I agree with your Stockopedia sentiments and also invested in Inv Trusts for years, more recently i have created a list of main ETF's & choose between them and Trusts. At 90 though i am looking at ways to reduce the equity work effort and have a trial running on Ed's Naps for UK and QM's for the USA. . but still including Funds & ETF's. I enjoy attending Mello and meeting other investors there as well as the occasional Substack. As well as the mind the physical walking/Gym is also so important.
Ps. last week came back from a stay in Norfolk nr Halt beautiful country side and serene. Envious.
Fully understand about your need to be cautious.
Re your comment about finding Investment Trusts difficult to understand; the focus on the Investment Trust threads here tends to be on the less straightforward ones and not the mainstream Trusts that are very easy to understand.
I’ll do an explanatory post on the straightforward mainstream Trusts on the July Investment Trust threads in the next few days. Some of them have been in existence since the 1800s (the oldest F&C Investment Trust (LON:FCIT) started in 1868. There are mainstream Trusts investing in UK, Global, Emerging Markets , US, Technology etc so they can be a very good way to diversify I.e not just UK. . Some have increased the dividend for over 50 years with City Of London Investment Trust (LON:CTY) the first to 60 years of increases.
These Trusts have portfolios similar to ours in the Countries or sectors they invest in, and it’s easy to find their top 10 biggest holdings. I’ve held some of those Trusts for years, and all are well in profit.
One snag for you is it’s best to do the buying in bear markets to maximise the eventual gains in the next bull market. Unfortunately for you we’re now in a bull market, so it’s not the ideal time to be buying them.
I'm 77 and nowhere near giving up investment in shares. As far as i'm concerned, yr 80 is the new 60! Provided you ENJOY investing in shares , i would definitely keep quite a lot of money in shares: it can be a bit of fun to study your portfolio each day. [ i had a bit of fun today when my Rotork shares went up by about 66%]
i would just say that it would be good to keep some money aside, so you would not have to ever distress sell some shares that are showing a loss. And also to keep a bit of an eye on dividends, so that overall your shares are showing a reasonable income [but don't aim for high dividend shares] so that you can sleep at night when shares have the inevitable moments of decline. During Covid , i had a sufficient income so that i never once was forced to sell a share.
Good luck!
Has there ever been so many takeovers listed on this report? The UK market really is shrinking , yet I haven't been the holder of a company targeted for years
I'm really hoping the IPO activity picks up when autumn comes.... we need more fresh companies....
Speaking of IPOs - there's a new one to come soon. An enterprise software company based out of Australia, servicing wealth management companies and fund administration companies. Bravura.
https://profile.lsegissuerserv...
Can you post your portfolio so I know which stocks to avoid then
Another decent UK company Gooch & Housego (LON:GHH) goes very cheap!
One of my recent calls in the photonics theme.
All the best
I agree that seeing Gooch & Housego (LON:GHH) go - and without a fight- is hugely disappointing . We have so few genuine world class tech companies that it seems like another death knell for the UK public markets. Even my 100% profit tastes bitter when I believe there was so much more to come
Northern Bear (LON:NTBR) I hold
Today's prelims look decidedly decent to me. Given the well known problems in the building/construction /services environment, they have grown revenues, profits and cash. The special dividend shows a vote of confidence IMO. I would appreciate it Graham if you could cast your eyes over these results and give us your verdict.
The special dividend makes up for the lack of interim dividends, not to say that I'm unhappy. I hold.
Shoe Zone (LON:SHOE) SP this morning is now above the 50p at which the Smith brothers bought 2.75m shares in May.
Rotork (LON:ROR) Another one down. Presumably the bid will succeed at this price. How much longer before there are no engineering companies left on the LSE?
Screen for falling stars in the engineering sector. Keeping an eye on Renishaw (LON:RSW)
Also Porvair (LON:PRV) given the significant Italian strategic shareholder who has gradually crept up towards the 30% (mandatory takeover) limit. Sadly the price arguably partially reflects this and has been creeping up recently. Would also add Spirax (LON:SPX) which has some absolutely world class elements and is currently unloved.
Btw. I do own Rotork (LON:ROR) (LON:PRV) but was only building a full position size so quite bittersweet. Business was an absolute steal at the undisturbed level and kudos to all the stakeholders involved, price was falling in the days before - so definitely no insider leaks here. Generally I just cannot get my head around the ongoing antipathy for the UK market. Our pensions funds and presumably many retail punters seem determined to inject ever more into the over valued US market plus opaque / illiquid / high fee alternative markets. Meanwhile gems like this sit there in full view and no one cares.
Was going to sell my Ramsdens Holdings (LON:RFX) shares yesterday to crystalize profits but got sidetracked by the football. Every cloud...
Selling them today?
Current share price of Ramsdens Holdings (LON:RFX) is 665p vs. a recommended offer of 684p. Does this suggest there is some concern that the deal will not go ahead - potential competition concerns following previous purchase by Firstcash Holdings (NSQ:FCFS) of H & T pawnbrokers? Interested in any thoughts as I continue to hold at the moment though if followed Ed Crofts QVM Portfolio (a variant on NAPs) to the letter it would be a sell signal.
Current share price of Ramsdens Holdings (LON:RFX) is 665p vs. a recommended offer of 684p. Does this suggest there is some concern that the deal will not go ahead
I think the discount speaks for itself most of the time with takeovers
1 - its a given that until deal is done anything could go wrong and might go wrong - think of how many house sales fall through over minor stuff and then think about changing market conditions - financing may be needed and any other reason. thats without mention sector regulatory hassles
then there is the danger Ramsdens shareholders vote no - on aquick skim unless i have missed it that doesnt look like a done deal
2 uncertainties aside there is often the discount that may relate to time you have to wait for payout to be made - if you sell shares now you can park funds and earn interest so its only natural that there will be discount if its epxected you have to wait 3 months befroe you get your dosh - why would anyone hand over cash "now" if they can hand it over in 3-6 months time.
This kinda looks done deal - if we think shareholders wil vote yes - they may not though if they think they might be able to get a bit more.
Its always sensible to assess where you think price would be if it falls through - with forecasts improving things look ok - but share was sub 450p not so long back - so it seems plausible if bid were to fall through that share might be back to 500p or less - thats potentially big drop compared to the extra premium you are waiting for. With forecasts improving though one may be happy to hold anyway - so ignoring the bid would you remain holder at 684p? if you would well that makes it easy to go back to sleep.
The price does include the dividend. So maybe not a big discount as you think. The share price was around 279p, this morning, no surprise the price has dropped back.
I held onto Ramsdens Holdings (LON:RFX) thinking the initial bid too cheap, so pleased to see today's uplift. Will now probably sell, albeit trading looks strong.... not sure if another bidder will emerge...Only question is where to invest the proceeds....
Northern Bear (LON:NTBR) results are more of the same. eps 23p +18%. net cash >40p a share. thus adj pe <3x. 10 yr record shows sales >60%, profits doubled, 10m debt to 6m cash. share count reduced 20m to 14m . chart continues l.term modest uptrend. i hold
Northern Bear (LON:NTBR)
agreed - this company aint ever gonna set the world alight with regard to "ratings" and there tone is perhaps more fitting of a yorkshire buisness than one from newcastle - they dont really ever do upbeat - i think there is room for some companies to have uber conservative outlooks - they have clealry had purple patch - and with many listed companies that doesnt always result in new higher permanent level of profits - permanent uplifts to material high results one has to work hard long term. They are perhaps small and nimble enough to eak out a nice niche between the really big boys and the smaller entities that they dont need to compare with.
I would say the balance sheet is finally at a position where it can truly be classed as conservative - with large payables owed out at any moment in time its good to have some money in the bank to cover bad periods or the odd large contract going on - note average cash is less half than the year end cash so £6 mil is a bit of a false numberr imho . Simple old school expanding what you have mostly organically - or in small imcrements is a fairly simple plan. Much contracting work works on fairly standard margins that can be calculated beofre one quotes for work.
Nothing not to like here at current shareprice - infact i think company would perhaps still look cheap at 150p - obviously having had two execptional years i suspect broker forecasts might still be for 2027 earnings to be down on year just finished - lets hope they get tickup from expectations now. Reading between the lines whilst they may not be saying it i suspect they are well placed to do ok this year - they have had i think very profitable non repeating jobs though so some reduction in forecasts "for now" makes sense. And if then market is looking forward its going to say company is going backwards - i would say overall the company is most certainly progressing forwards nicely - not so long ago £2 mill clean profit was a good year here now is closer to £3 mill one might hope for in a normal year.
Stockopedia is working for me again, I'm pleased I didn't sell our Ramsdens holding after Bidcos first offer! We also hold CAPD which is on your Agenda Graham, I hope you get time to look at their offset between rising revenue and demobilising on two contracts, I'm tempted to add at the current price.
Views on Capital (LON:CAPD) would be welcome. Thanks.
Capital (LON:CAPD) Looks a better than expected update to me. I would have thought some contracts that don't work out was fairly normal in the nature of the business. Even so, it would be interesting to learn what went wrong at NGM. This was originally billed as an expansion of the business into the North American drilling market. Clearly it hasn't worked out and they are not intending to look for further work in the US. A long-term hold for me.
It appears that recently, in the last 3 to 4 weeks, broadly speaking, this website has suffered many problems. It's as though a service provider has been changed for a cheaper version and we are getting a poorer service as a consequence. This empowers competitors. I hope warnings are heeded.
Sort it out Ed!
yes really bad !
they were, ofc, happy to take the annual subscription out of my card/account without any heads up re. renewal beforehand!
poor form IMO
No report today?
lf you could have a look Somero Enterprises (LON:SOM), please.
Also MS International (LON:MSI) and Funding Circle Holdings (LON:FCH), please.
The report has now appeared.
Company names are missing so far on RNS reports this morning, on my computer. Has anyone else got the same problem?
Stockopedia is a great platform backed by an awesome team. The one area that still needs work is communication around service status, incidents, and future plans. A bit more transparency and more timely updates would go a long way. The product & people are excellent—now let’s make the communication around tech issues match it.
That's very fair comment Neil... we pay a lot for the service, can we please get an explanation why the website is down so often .. I can't currently look at portfolios or research a stock ...
I happily pay my Stockopedia subscription for a reliable data source - unfortunately it has recently become an increasingly unreliable service which dents my confidence and wastes my time.
Consistency of service and product are the key elements to business success. I fear that if these on going and ever more regular issues are not resolved, Stockopedia will become less attractive to those of us that place it in such high regard.
The only way to suggest an improvement is via the green button. You have no idea if anyone else has made the same suggestion & once submitted it just goes into a black hole. Was it rejected, in a to do list? Who knows. No-one gets back to you.
For a site so dependent on subscriptions, keeping the subscribers informed and updated should aid retention.
SeekingAlpha is primarily focused on US markets and equities and much cheaper in what they offer in relation to Stockopedia.
Its stocks by quant service is much better than Stockopedia’s StockRank.
I want to open Stockopedia app every morning at 7 and demand that I receive the service that I have paid for. I understand fully and accept a couple of days in a calendar year of issues similar to today’s, but it feels that we are heading for a couple of days in a year of NOT having any problems.
I hope everything is sorted, although I am certain that this is related to liquidity issues.
All the best
I think they are changing things - there was something about urls. Some apps give users access to a beta version so they can test before release to all.
I would volunteer to do that