Daily Stock Market Report (Thur 25th September 2025) - IGG, JNEO, DFS, CTA, PMP, ZOO, CHRT, CAU, MRK, MERC

Good morning! Here we go - let's see what reporting season has in store for us today.
8.15: Agenda complete!
2.30pm: wrapping it up there, hopefully I'll see some of you at the Stocko webinar at 5pm!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
3i (LON:III) (£37.7bn) | Both portfolios performing resiliently. Action LFL sales +6.5%, total sales +18% year-on-year. | ||
Halma (LON:HLMA) (£12.7bn) | Organic growth guidance raised from upper single to low double digits. Margin guidance unch. | ||
Babcock International (LON:BAB) (£6.18bn) | Full-year exps unchanged. Macro is “supportive”. Strong growth in Nuclear & Aviation. | ||
IG group (LON:IGG) (£3.69bn) | FY26 still expected in line (rev £1,110.7m, PBT £497.9m). Q1 net trading revenue -2%. | GREEN (Graham holds) Staying bullish on this stock which I view as a high-quality financial brand offering both quality and defensive characteristics. Recent trading (for Q1 FY26) is softer than Q1 and Q4 FY25 - the ups and downs of volatility and trading activity are part and parcel of the business. A protracted slump in activity can't be ruled out, but I still like this as a long-term investment. | |
Petershill Partners (LON:PHLL) (£2.5bn) | H1 distributable earnings $152m (+9%). Proposed return of capital of 415 cents (35% premium). | PINK | |
Vistry (LON:VTY) (£2.05bn) | Part of govt’s £2bn injection. Vestry’s total funding for affordable homes is now £252m. | ||
Mitchells & Butlers (LON:MAB) (£1.58bn) | FY25 outlook in line. Next year: cost inflation £130m. Confident to outperform the sector. | ||
Future (LON:FUTR) (£678m) | On track for market exps (revenue £743.2m, adj. op profit £205.6m). Revenue “broadly as expected”. | ||
Cohort (LON:CHRT) (£649m) | SP -5% FY26 growth exps unchanged. H1 revenue slightly behind last year. Optimistic about new orders. | AMBER (Graham) [no section below] Some slight disappointment is evident in the share price reaction to this AGM statement - this share has achieved an increasingly punchy rating over the past two years, bringing with it the weight of increased expectations. Today's statement also notes an H2 weighting "as in previous years" and a big swing in cash is forecast: from net debt of £30m at the end of H1 to net funds of up to £15m at year-end. The market is expecting FY2026 to be stronger than FY2025, and a weaker H1 year-on-year (in revenue terms at least) suggests to me that meeting full-year forecasts could be a challenge. As this is a "High Flyer" where the momentum rank has weakened, I'm inclined to pre-emptively switch to neutral here, while acknowledging that long-term holders might see no reason to head for the exits at this stage. | |
DFS Furniture (LON:DFS) (£351m) | FY25 LfL orders +10.2%. Adj. PBT £30.2m. FY26 to be in line: “comfortable with consensus”. Consensus profit before tax and brand amortisation is £39.4m. “The market demand drivers for the upholstery sector remain delicately balanced. Consumer confidence remains below the long term average and inflation remains elevated but housing transactions have been recovering, consumer savings levels are relatively high and interest rates look set to fall.” | AMBER/RED (Graham) [no section below] A nice reassuring update today - it’s a nice use of language when a company says it is “comfortable” with earnings forecasts. But we’ve been RED on this stock (see Mark in March) due to balance sheet concerns. Today’s report shows the company having bank leverage of 1.4x, a big improvement on last year’s 2.5x although still above the company’s target range 0.5-1.0x. The net debt figure is £107m (not including leases). They provide a measured take on the economy, offering both positive and negative drivers for their business. As leverage is no longer stressed, I’m happy to upgrade this to AMBER/RED. The profit figure is very clean. Do bear in mind that lease liabilities are enormous (their present value is £350m+) - that’s standard operating procedure for retailers but it’s one reason why I prefer when they have low net debt or ideally net cash. | |
Intuitive Investments (LON:IIG) (£230m) | Hui and leading baijiu brand to cooperate to introduce Sports Lottery Hongbao promotions. | ||
Tristel (LON:TSTL) (£174m) | New ultrasound probe decontamination product. First detergent of its kind with colour technology. | ||
Amicorp FS (UK) (LON:AMIF) (£149m) | Rev +7.8%. PBT $2.5m (H1 2024: $1.6m). Expecting steady growth in H2. “Well positioned.” | ||
Mercia Asset Management (LON:MERC) (£142m) | Positive start to current financial year. “Well-positioned.” Cash £35m. £3m buyback ongoing. | GREEN (Graham) [no section below] This regional investor has seen a modest (10%) share price increase since I reviewed it in April. Unlike mainstream fund managers, it has been able to raise funds and AUM , and the valuation is at a discount to NAV. Today's reassuring update doesn't give too much away, but I'm encouraged to see it buying back its shares at this level, even if the £3m programme will only reduce the share count by a few percentage points. I'm not put off the by high P/E multiple: the bull thesis here is as much to do with the balance sheet as it is to do with a new and growing fund management proposition. Third-party funds under management were last reported at £1.8 billion, up 10% organically in FY March 2025. | |
Seeing Machines (LON:SEE) (£120m) | Mandatory DMS in all new EU vehicles in nine months. Current trading in line with expectations. | ||
InvestAcc (LON:INAC) (£106m) | Organic rev growth 20.3% (to £6m). EBITDA +33% (£2.8m). Strategic priorities unchanged. | ||
Journeo (LON:JNEO) (£84.2m) | H1 Revenue -4% to £24.5m, Adj. PBT flat at £2.8m, EPS -15% to 13.0p, order intake +25% to £30m. Cash £18.0m (31 Dec: £14.3m), (£9.0m after acquisition post period end). Confident in meeting full year market expectations. | AMBER/GREEN (Mark) | |
Braemar (LON:BMS) (£78.8m) | H1 revenue expected to be -16% to £63.8m, with u/l profit -31% to c.£5.5m. Net debt £5.6m (31 Jan: £2.5m) after £2m buyback. Strong forward order book means expectations for the full year remain unchanged, with H2-weighting. | ||
Hansard Global (LON:HSD) (£68.9m) | New business sales +6% to £82.4m, AUA -2% to £1.13bn, u/l profit -40% to £5.1m, Final Dividend held at 2.65p. | ||
Marks Electrical (LON:MRK) (£65.1m) | Lower revenue trend of Q1 due to the pivot back to the premium segment continued into Q2. Cautious consumer impacting avg. order value, resulting in higher delivery costs. Other costs increasing due to employee costs and new ERP system. Material impact on full year profit guidance. Now expect adjusted EBITDA for FY26 to be approximately £1.7 million. Interim dividend cancelled. | BLACK (AMBER/RED) (Mark) [no section below] | |
Logistics Development (LON:LDG) (£60.4m) | 30 June unaudited estimated NAV per share was 26.7p, an increase of 8.67% compared 31 March. | ||
Centaur Media (LON:CAU) (£59.8m) | Marketing Week, Festival of Marketing and Creative Review, sold to Haymarket Media Group for an enterprise value of £3.9m. Proforma net cash £71m. | AMBER/GREEN (Mark) [no section below] | |
STV (LON:STVG) (£53.5m) | H1 Revenue flat at £90.0m, Adj. operating profit -37% to £6.7m, Adj EPS -54% to 7.1p. No change to full year 2025 outlook as guided in July. | ||
Petra Diamonds (LON:PDL) (£36.9m) | Extension of lock-up agreement to 29th Sep. | ||
Cobra Resources (LON:COBR) (£36m) | H1 LBT £0.45m (24H1:LBT £0.38m), Net cash £0.84m (24H1: £0.49m. | ||
Chariot (LON:CHAR) (£32m) | LBT $4.7m (24H1: $8.2m), Net Cash $5.6m (24H1: $3.6m), after June fundraise for $7.1m gross. | ||
Arecor Therapeutics (LON:AREC) (£27.4m) | H1 Revenue flat at £2.0m, LBT £2.5m (24H1: LBT £4.6m), Cash £1.9m (24H1: £2.5m). Post period-end, will receive a royalty monetisation £5.2m, extending the cash runway into 1H 2027. | ||
First Tin (LON:1SN) (£27.1m) | Participating in an EU-funded XTRACT consortium project to demonstrate that indium can be extracted directly from the ore body using bioleaching. | ||
Poolbeg Pharma (LON:POLB) (£25.4m) | Signed an agreement with a specialist blood cancer trials organisation, Accelerating Clinical Trials Limited, to conduct the upcoming POLB 001 Phase 2a trial. Secured the supply of an approved bispecific antibody drug for the trial at no cost. | ||
CT Automotive (LON:CTA) (£24.7m) | H1 Revenue -11% to $54.1m, Adj EBITDA +14% to $8.4m, Adj. PBT +2% to $4.2m. Net debt $12.1m (24H1: $5.8m). Outlook: FY25 Revenues expected to be slightly softer due to timing. Strong margin growth in H1 means on track for FY25 profit expectations. | AMBER/GREEN (Mark - I hold) | |
Blencowe Resources (LON:BRES) (£21.9m) | Higher-grade tonnes added to Camp Lode resource. High grades continue in infill zones at Northern Syncline. | ||
Portmeirion (LON:PMP) (£18.9m) | H1 Revenue +1% to £37.1m, h/l LBT £2.9m (24H1: LBT £2.6m), h/l LPS 21.0p (24H1: LPS 19.2p), Net debt £14.8m (24H1: £13.4m). Challenges ahead due to uncertain economic environment and with a significant Q4 weighting. | AMBER/RED (Mark) [no section below] | |
ARC Minerals (LON:ARCM) (£16.7m) | H1 LBT continuing operations £2.3m (24H1: LBT £0.5m), Net cash £0.7m (24H1: £1.6m). | ||
Mothercare (LON:MTC) (£16.1m) | Franchise sales -18% to £230.6m, Adj. EBITDA -49% to £3.5m, Adj. LAT £2.5m (FY24: PAT £3.5m), Net borrowings £3.7m (FY24: £14.7m). Outlook: 1st 23wks franchised sales -25% to £80.7m. Will result in materially reduced profitability. | ||
Genincode (LON:GENI) (£12.3m) | Collaboration with a London NHS Foundation Trust, becoming the first hospital trust in the UK to provide the Risk of Ovarian Cancer Algorithm (ROCA) surveillance test service as part of its Familial Cancer Clinic. | ||
Zoo Digital (LON:ZOO) (£11.6m) | Expects 26H1 revenue $22, in line with 25H2. 26H1 EBITDA is in line with management expectations. Looking to normalise working capital after active management of creditors in FY25 | AMBER/RED (Mark) [no section below] |
Graham's Section
IG group (LON:IGG)
Down 1% to £10.50 (£3.65bn) - First Quarter Trading Update - Graham - GREEN
(At the time of publication, Graham has a long position in IGG.)
The main headline here is that we have an in line outlook statement for FY26.
IG’s investor website lays out the consensus estimates for the next three years:
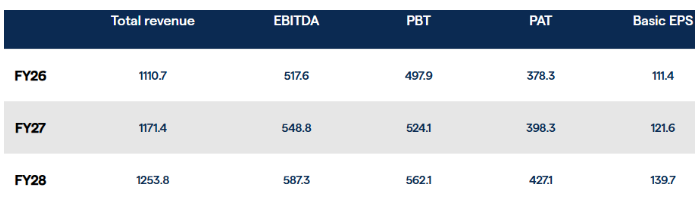
At £10.50, the shares are therefore trading on a current-year P/E multiple of 9.4x.
Today’s update demonstrates the simple truth that the trading platforms cannot maintain their performance, when their clients are choosing to trade less:
Net trading revenue of £231.9 million declined 4% on the prior year and 8% on the prior quarter, as strong OTC customer income retention was offset by lower trading activity in less supportive market conditions.
Just after I left for my recent holiday, we published a more in-depth look at IG, where I highlighted two primary risks for IG. One of these - which I described as inevitable - was lower volatility leading to lower trading activity (the other was regulation).
Q1 FY26 is the period from June to August 2025, i.e. after the Trump tariff situation calmed down. So I don’t think it should come as a huge shock to find that quarter-on-quarter trading revenue is down 7%. Within OTC derivatives (which includes spread betting), quarter-on-quarter revenue is down 11%.
Tastytrade, the US options trading platform for retail investors, has seen very good 16% revenue growth year-on-year (5% quarter-on-quarter) to $54.7m. That’s about a fifth of IG’s total revenue for the quarter.
Freetrade: IG’s official customer base, and its assets under administration, have both exploded thanks to the recent acquisition of Freetrade. But Freetrade’s customers are very much low-value compared to the existing base - they trade rarely, generating very little commission when they do. IG's task now is to activate a meaningful proportion of these customers. Thanks to the acquisition, their customer base has grown from 545,900 (Q1 FY25) to 1.315 million (Q1 FY26).
They say that performance at Freetrade has been “excellent” in Q1, and that is borne out by a 32% increase in net trading revenue at the division to £6.5m (comparing recent revenue to revenue last year, prior to the acquisition). But it’s still just a tiny percentage of IG’s total revenue - about 2%.
As covered by Roland recently, IG has also made a small (£87m) acquisition to accelerate its crypto offering in the Asia Pacific region. Freetrade cost £160m.
Buyback: £16.8m has been spent out of a planned buyback of £125m. Looks like they’ve spent an average of £11.20 per share - higher than the current share price. I don’t have any major objection to a buyback at the current level.
Graham’s view
I risk becoming a broken record on this one, but I’m in good company as the StockRank is also consistently high here:
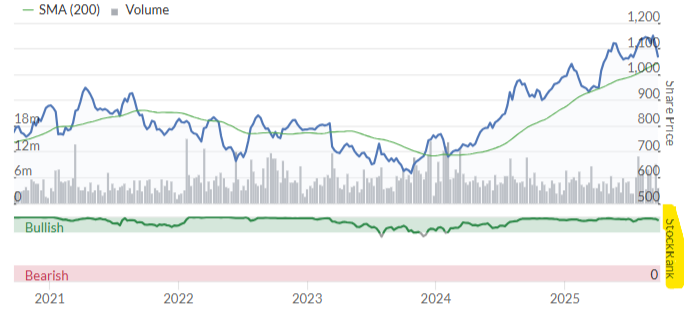
The current StockRank is 94, making it a "Super Stock" (albeit one with declining momentum):
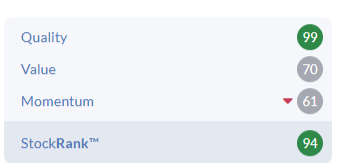
Note that in addition to posting very high quality metrics, it also has value/defensive characteristics:
That’s on top of the fundamentally defensive nature of a business where activity tends to pick up when investors are panicking.
I’ve said pretty much everything I want to say about IG - please see my recent article for more background. It’s currently my third largest holding, representing 12% of my portfolio. Of course nobody can rule out a protracted slump in trading activity levels, but that cycle is part and parcel of this type of business. At the current valuation, I still like the risk/reward on offer here.
Mark's Section
Journeo (LON:JNEO)
Down 7% at 456p - Half-year Report - Mark - AMBER/GREEN
I’ve got to say I’m a little underwhelmed by these results. Revenue is down 4%, adjusted PBT flat and EPS drops by 15% to 13.0p. Partly, this is to do with my expectations. When the 6-month chart shows the share price almost doubling:
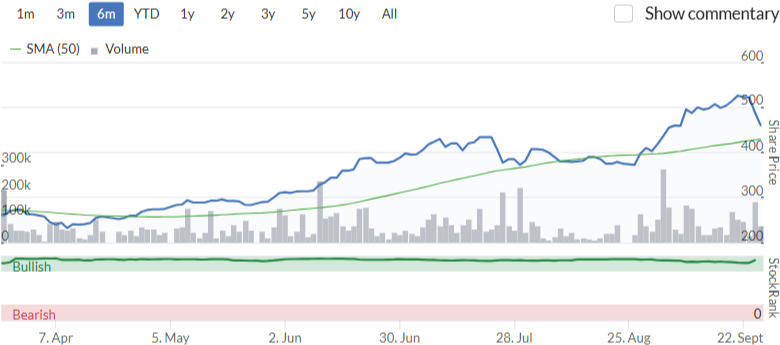
…and when the forward P/E is 19, I really would be expecting results to show increasing EPS. However, this decline was partly due to timing effects. They say:
H1 2024 included £3.4m of revenue from the first phase of the New York City contract, which successfully completed during 2024. H1 2025 included no revenue from this contract.
Journeo provide good segmental reporting and the impact of this can be seen in the trends for Infotec:
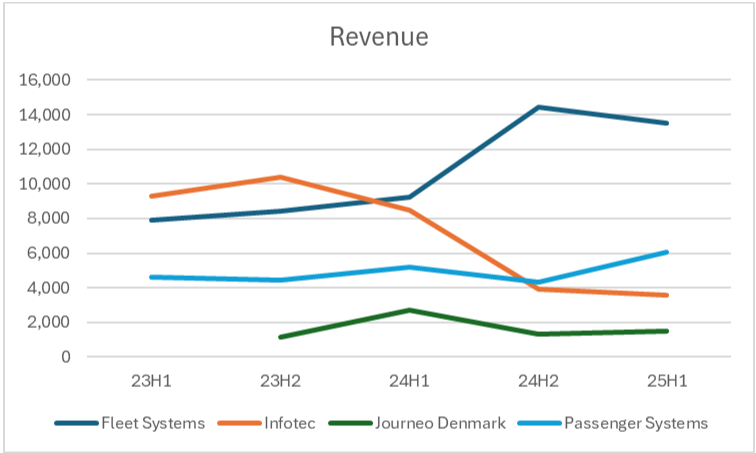
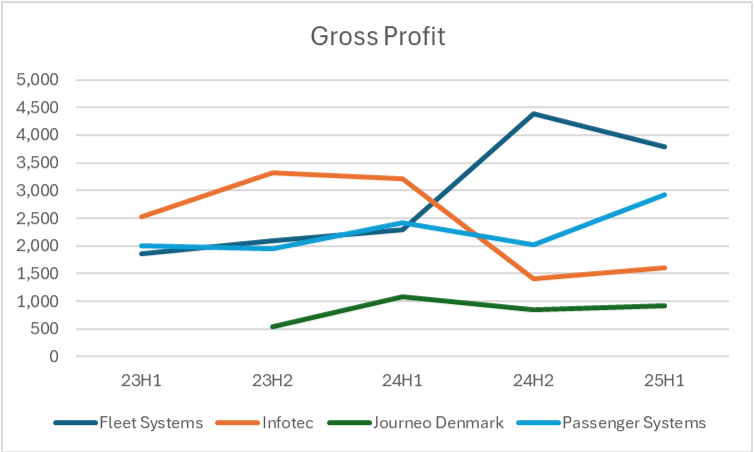
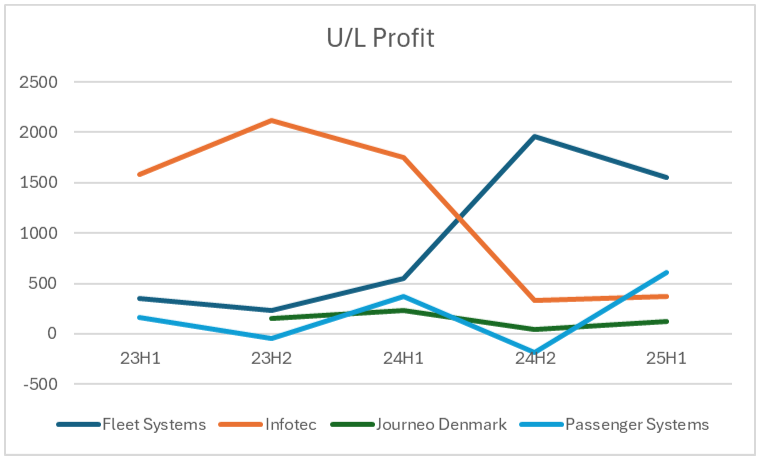
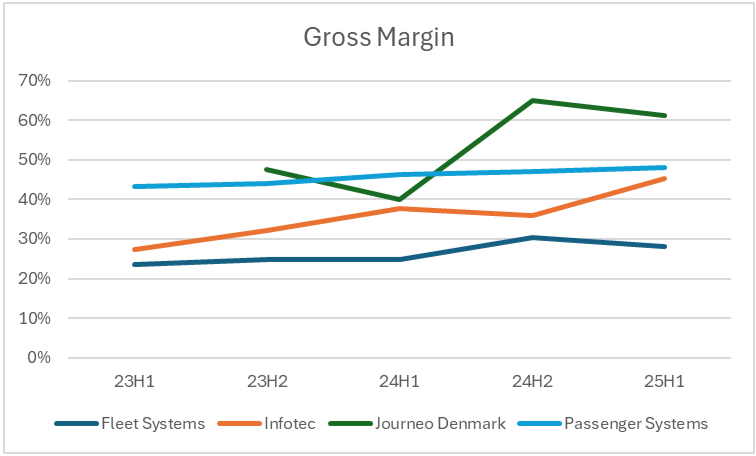
The decline in infotech revenues has been particularly offset by revenue growth in Fleet Systems (although this is down slightly on H2 last year) and Passenger Systems which is starting to make a meaningful contribution.
US orders have started to come in for Infotec, where they say:
The relationship with Outfront Media Group ("OFM") and the New York City Metropolitan Transportation Authority ("MTA") continues to grow in strength, with two significant orders placed in H1 2025, totalling $5.2m, that will serve North America's largest transportation network.
However, even if they delivered all of that in H2, it won’t bring Infotec revenue back to the levels of when they were delivering the initial New York City subway contract.
Part of the reason that I had been expecting better results is that there have been a string of contract announcements over the past six months. Of course, it is unreasonable to expect the company to recognise revenue on these immediately. Today they guide in line for the full year, which their broker Cavendish have as £56m revenue and 26.5p EPS. This leaves £31.5m revenue to deliver in H2 and 13.5p EPS. This is aided by an expected £4m from their recent acquisition of Crime and Fire Defence Systems.
This growth is supported by positive trends in orders:
· Sales order intake increased by 25% to £30m (H1 2024: £24m) providing increased visibility into H2 2025 and beyond
· Sales opportunity pipeline increased to £80 million (H1 2024: £60m)
But it is worth noting that they don’t give an overall orderbook. I do wonder if investors have reacted to the recent announced orders expecting the company to beat expectations. Whereas the reality is that they will need to keep delivering similar orders in order to to hit expectations. While I don’t think there is a risk of a miss, contract announcements seem a regular occurrence here, I think the idea that contract announcements will lead to upgrades may be false in this case.
It would be nice to also have some breakdown of order metrics by BU, as the gross margins across the business vary significantly For example, an additional order at Journeo Denmark would likely have at least double the impact on profits with its 60%+ gross margin, compared to one in Fleet Systems at sub-30%:
Looking at the detailed income statement, it is a pleasant surprise to see a company that makes very few adjustments:
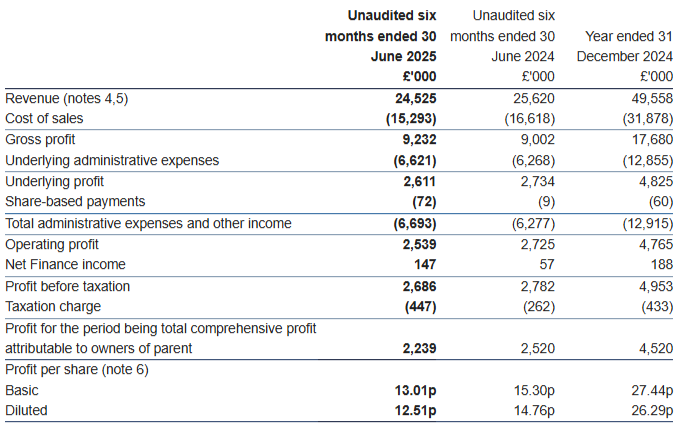
A SBP charge has increased, and I think that investors should at least account for that by using the diluted EPS. The drop in EPS is due to an increased tax charge. I can’t see any discussion around this in these results. Since tax rates are still well below UK corporation tax rates at 16.6% for 25H1 versus 9.4% in 24H1, I am assuming this is due to lower R&D tax credits or use of historical tax losses. Cavendish are assuming 17.9% tax rate for FY25 and 194% in FY26, meaning this will remain a small drag on EPS growth rates
Looking further ahead, Cavendish had 6% organic revenue growth and 11% organic EPS growth for FY26, they increased this by 31% at the revenue level and 20% at the EPS level due to the recent acquisition. This makes the forward P/E still look reasonable, especially if we adjust for the remaining £9m of cash. However, in my opinion, investors should only pay up for organic growth, and here a 14x P/E compared to an 11% growth rate.
Mark’s view
Overall, this leaves the short-term finely balanced. On one hand, the weak H1 results are largely due to timing issues and I don’t see why they won’t achieve FY forecasts. This means that the shares look reasonably priced on around 14x forward earnings, especially when you consider that there are few adjustments and there is still around £9m of net cash. Cash continues to build, although partly because they choose to retain capital, rather than pay a dividend.
On the other hand the shares have risen strongly and have almost doubled in the last six months on an EPS trend that has been entirely flat until they announced a recent acquisition:
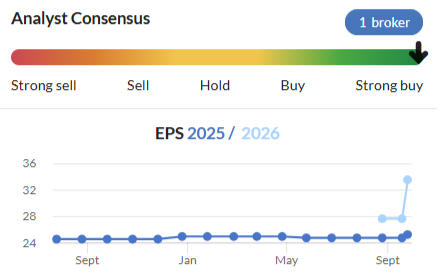
It seems that many investors expected that the stream of recent contract wins means that the management are being conservative in their forecasts and that they will beat expectations. Today’s results, with declining H1 EPS, means that possibility looks more remote. I do think that this is the type of business that needs to generate continuous order wins and without a detailed breakdown of the order book, it is hard to judge if these announcements will be leading to incremental revenue.
These recent share price trends have propelled this to High Flyer status:
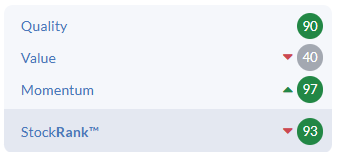
The Momentum Rank has risen even this month, so isn’t an obvious sell signal. However, looking to the future, this is likely to fall as these results and today’s share price fall are assimilated into the ranks. Our research into High Flyers suggests that it is often better to have a hair trigger when it comes to a declining Momentum Rank, and sell at the first sign of trouble. Once short-term price momentum starts to turn down in a stock with high recent gains, it can be a long way down before value characteristics start to provide support. Today’s chart suggests that point may well be today:
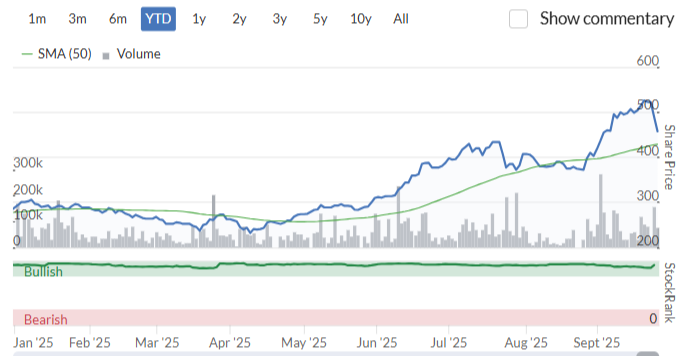
In reality, it probably depends on investors' timeframes. Those who bought this as cheap quality stock and then rode the momentum up to the current share price level will view today as an opportune moment to take significant profits and move on to better short-term opportunities. Those who bought for the possibility of a multi-year growth in orders and believe in the company’s strategy to reach £100m revenue and double-digit operating profit in the medium term, will be happy to hold through any short term volatility. I tend to use the latter for forming my view, hence, I am happy to keep this as AMBER/GREEN on long-term fundamentals.
CT Automotive (LON:CTA)
Up 4% at 35p - Half-year Report - Mark (I hold) - AMBER/GREEN
This is another company where revenue is suffering from global macro headwinds:
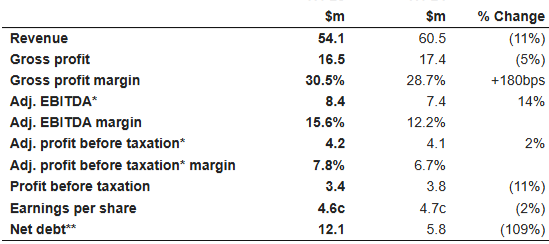
However, improved margins see it manage to increase profitability, at least on an adjusted basis. These are those adjustments:
During the period, the Group incurred non-recurring expenses totalling approximately $0.9m, comprising:
· $0.3m (H1 24: $0.3m) relating to hyperinflation adjustments in Türkiye,
· $0.2m associated with a one-off tooling amortization,
· $0.4m of severance costs in Türkiye following union pay increases agreed upon earlier in H1 25.
While severance costs are likely to be one off, I’m less convinced by the hyperinflation adjustment. Surely the bad point of hyperinflation is that it is sticky and once embedded in an economy is recurring? Indeed, it appears to have occurred in 24H1 as well, although it is reversed for the full year! The key point here is it is non-cash, as it gets added back in in the cash flow statement, which makes its exclusion perhaps more reasonable.
Net debt increased, but this appears to be wholly due to one customer:
Trade receivables increased by $9.6m to $35.3m, primarily due to a delayed payment from one customer, which was received in July and an increase in tooling prepayments for future programs, which corresponds to an increase in deferred revenue.
Net debt increased from $6.2m at year end to $12.1m. The key contributor was a delay in payment from a key customer which had a net impact of approximately $4m. Net debt normalised in July 2025 at $7.4m following receipt of the one-off delayed payment.
This seems reasonable, and their customers will be large global Auto OEMs or Tier 1s who should be a good credit risk. However, I will certainly be asking about credit insurance in their results presentation on Monday, as delays of this kind, or at worst, non-payment, can stretch the finances of smaller suppliers. Net debt will increase slightly in the short-term to $9-10m at year end, but declining significantly in FY26. Even at peak net debt will be around 0.5xEBITDA so this seems perfectly reasonable.
Outlook:
This is pretty much the same as the HY results, the impact of weak revenue being made up by stronger margins:
· Solid H1 25 performance with strong margin growth despite industry-wide tariff-related volatility, placing the Company on track to hit FY 25 market expectations for profitability.
· Revenues for FY 25 are now expected to be slightly softer reflecting timing adjustments only-no change to long-term production volumes, with demand ramping up in Q1 26.
I can’t see any updated broker coverage, so my assumption is that the current 12.8c EPS remains valid. This means that there is a fair bit to do in H2 to hit this figure, although there was a H2 weighting in FY25. Longer-term they seem to be in a good place with increased quoting activity:
Revenues for FY 25 are now expected to be slightly softer reflecting timing adjustments only-no change to long-term production volumes, with demand ramping up in Q1 26.
Significant expansion of the global sales team, now covering every major automotive region, driving RFQ book to all-time highs.
Overall, the Group's margin progression and a record RFQ pipeline provide a solid platform for a stronger second half with the contractual pipeline giving the Board confidence over current FY 26 market expectations and beyond.
Very few companies are expressing confidence in FY26 at this point, which underlines that this is a business with good revenue visibility, barring some questions over exact timings.
Valuation:
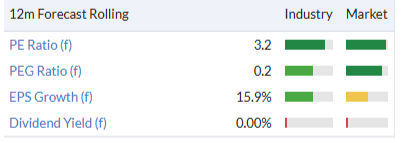
All of this puts them on a very low forward P/E for a company forecast to grow EPS by 16%:
Perhaps more importantly given their industry, they are growing with some really strong returns on capital:
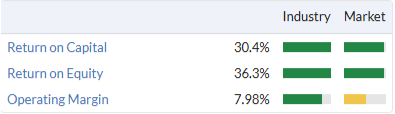
The automotive industry is cheaply-rated, and single digit P/E’s are not out of place for major players. However, these ratings are usually accompanied by large amounts of debt, lacklustre growth and single-digit returns on capital. CT has modest debt, is winning business that should lead to strong revenue growth going forward and good returns on capital. Being a smaller player in a highly competitive industry is not without risk, but has the advantage of having the runway that bigger companies will miss.
Mark’s view
Having worked in the Automotive industry in the past, with some interiors experience, I am naturally averse to investing in it. It tends to be low-margin, cyclical and facing structural headwinds, plus a volume game. However, CT appear to have done very well as a smaller niche player using technical innovation to drive increased business. They are effectively a tier 2 business but one of the signs of their success is that they often get directed by the OEMs, who recognise their capabilities.
The long-term chart shows an optimistic float price, but by April this year the shares had lost over 80% of their value, largely on the assumption that tariffs were going to seriously impact their business:
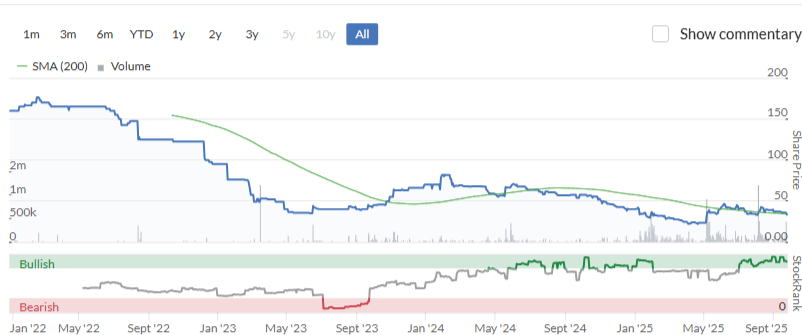
Instead of tariffs damaging the business it turns out that customers were moving business to them as their Mexico facility actually faced lower tariffs than elsewhere. Despite generally weak automotive markets and my aversion to the sector, I held my nose and bought in because the valuation just seemed to mismatch the company’s profitability and ability to grow. The shares recovered somewhat but have sold off more recently as global economic concerns have again come to the fore.
At the end of the day, if the company can continue to win business, grow sales and EPS, with a ROCE well above their cost of capital, significant shareholder value will be created. While the market will never give an automotive supplier a high rating, a consistent mid single-digit P/E rating on EPS growing double digits will still generate very nice returns from here. I am happy to keep our previous broadly positive view of AMBER/GREEN, and hang on for what could be quite the ride.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

53 comments
Excellent nuanced in depth reviews by Mark. Just cancelled my subscription elsewhere.
Graham, clicking the ticker in the above table for Babcock I find that they have branched out into selling muffins and bagels, By the look of the chart recently it seems they are doing quite well out of this interesting side-line. :) BAB (PNK:BABB) Babcock International (LON:BAB)
Fixed it Peter XD
Journeo (LON:JNEO)
Mark - if I may offer a very minor criticism you write: "I’ve got to say I’m a little underwhelmed by these results. Revenue is down 4%, adjusted PBT flat and EPS drops by 15% to 13.0p". That was already published - 0n 29/7 the company issued a preclose statement far more detail than most companies including:
Group revenue decreased by 4% to £24.5m (H1 2024: £25.6m)
Adjusted profit before tax of £2.8m (H1 2024: £2.8m)
https://www.stockopedia.com/sh...
At the preclose the company said: "Revenue for the full year is expected to be approximately £52m, in line with current market expectations, with adjusted profit before tax expected to also be in line at £5.2m".Today they simply say "Journeo is on track to deliver another record set of full-year results, in line with market expectations", which is not satisfactory because those expectations have changed since the preclo by the 2/9 acquisition announcement. At that Cavendish said "We have upgraded our FY25E adj EPS by 11%, our FY26E adj EPS by 20%". So it would have been far better if the company spelled out what it now understands to be market expectations as it did before.
Hi sharw,
Fair point, perhaps I shouldn't have been underwhelmed as the major headlines were known. Although I don't think the company spelled out that the rising tax charge would have such an impact on EPS. It's partly just a feeling right? I see a company on a forward P/E of 19 and then H1 EPS down 15%, and my instinct is to run away from danger! As I hopefully explain in the rest of it, I think that instinct is wrong. (Although, I also think it is wrong to buy on the assumption that they will beat expectations, or use growth rates after acquistions to compare to forward multiples in metrics such as the PEG). Hence my slightly bipolar view, it doesn't look great value on any near-term metrics and the momentum that has driven recent returns may quickly reverse, but deliveirng on the medium term targets would make them look very cheap.
On forecasts, in general, I agree. However, when it is one broker and is free to all investors, as is the case here, I am much more forgiving than when a company has multiple brokers that treat their research like some holy text that can only be accessed by the worthy select few!
Cheers,
Mark
Hi Mark
Thanks for your reply. I would agree with you that it is wrong to buy on the assumption that there will be an 'above expectations' announcement and I think there was a lot of that from 300p at the end of May to 526p last Friday and I suspect much of today's drop was from those buyers (says he with a longer term view with average purchase price 176.4p and maximum 279.9p).
IMC at 13 00 tomorrow.
Journeo (LON:JNEO)
If one wants some positive news stocky have upped 2026 eps expectations from 27.6p eps to 33.5p today . £5.6 mill net profit expected. So not too lomng to wait till they are back on positive trend - and who knows theer could be good news at year end perhaps.
I am surprised at the reaction yesterday - as the minor expected dip in eps ref 2025 has been on the stocky system for months i am pretty sure.
Journeo (LON:JNEO)
rmillaree - don't get too excited - it has taken Stocko 24 days to get those figures in - they are the ones I mentioned in an earlier post as being Cavendish's revisions on 2/9 following the acquisition so the rest of the world already had those built in.
Journeo (LON:JNEO)
oh - doh - at least they are there now :)
This could help to move renewable energy from producers to consumers....https://www.pv-magazine.com/20...
Love the 'straightforward' analysis at Mothercare (LON:MTC) this morning: "We are accelerating discussions with several parties to monetise the operational gearing in the business by restoring critical mass"
I don't hold
Morning guys. I know you have previously covered CRN ,and Roland holds in his portfolio, but please could you add GLV ,to this morning's coverage. Another £3/4B size Irish builder, reporting H1 today. Results look first class, and my belief is this and CRN are far more advantageous builders to hold ,due to growth ,and growing divi. figs [GLV due to add divi later this year, but currently doing major buybacks],especially as Ireland's financial situation is so much stronger than here , and their government's financial ability to back builders. Ireland to has a large property shortage.
I took some profits off CRN,a while ago ,and added a small holding , in GLV, unfortunately buying thro' H/l there as a 7% b/o spread ,but I'm still up 15%.Tony
Join us at 1PM TODAY for a Mello Results Special webinar. Richard Crow kicks off the show with a talk on Bowl Charts followed by six company presentations and a results round up by Ildar Davletshin, CFA
This webinar is FREE to attend and here for all to enjoy: https://www.melloevents.com/rs250925
Webinar schedule:
1:00pm "Charting Bowls" with Richard Crow
1:20pm Company Presentation from Time Finance (LON:TIME)
1:50pm Company Presentation from Eagle Eye Solutions (LON:EYE)
2:30pm Results Round-Up with Ildar Davletshin
2:50pm Company Presentation from Social Housing REIT (LON:SOHO)
3:20pm Company Presentation from PCI- PAL (LON:PCIP)
3:50pm Company Presentation from Skillcast (LON:SKL)
4:30pm Company Presentation from IP (LON:IPO)
5:00pm Results Special Closing Remarks
Short Interest
A question was asked about the short interest in Yellow Cake (LON:YCA) which is high (ish) at around 5% but not alarmingly so. Obviously Its a decent slug of stock if it needs to be closed in a hurry and maybe some of it was closed yesterday.
It's tempting to think all a short is based on a negative view but I would argue most shorts even if >0.5% may well be a fairly close hedge. You could be hedging the Sprott fund and playing relative discounts...and in this case a strong move in Uranium doesn't hurt the short. Or you may be hedging Nuclear exposure more widely...positions in a variety of stocks inc. miners and new tech etc....again I would argue strong moves across the sector do not matter so much. My points here are that some shorts are an active negative bet but many are simply hedges of long positions ... and so a large short interest isn't always as negative as you might assume.
Yesterday, to my surprise, Yellow Cake (LON:YCA) rallied into the close which I guess was the reaction to the previous days Uranium price...held back earlier by the placing. News that the placing went well and had been upscaled simply added fuel to the move. The sensitivity to this move of the short interest depends how well they did in closing in the placing and also, what positions they have in combination with their short. It's possible the move reflects a closing of the short and therefore the removal of an overhang ( potential fund raising). As I said yesterday I have been expecting this for a while and am pleased it's out of the way....especially if the Uranium price continues to rally. The fact they have surplus funds I don't mind too much but Im not wild about it generally.
In summary, be careful assuming a significant short is negative and/or ultra price sensitive. It isn't necessarily so. Looked at alone, without the context of the portfolio it has limited information IMO. In the case of Yellow Cake (LON:YCA) I am semi relaxed.
Journeo (LON:JNEO)
Ok no sign of any upgrades today - so tickover stuff - however there is decent progress ref the order book and the sales pipeline. So probably enough to keep most holders happy. Personally i tend to gloss over the contract stuff somehwat and presume that most contracts are simply covering prior stuff finishing - and up till now and for the rest of the year thats probably going to be the case in that the dial hasnt really moved this year ref expectations - acquisitioon aside.
Shoutout to the company for producing an exceptionally clean set of numbers yet again.
no exceptionals that i can see - the only mention of exceptional in the ye accounts was with regard to the performance of the fleet solutions.
No net increase in capitalises stuff whether that be plant or intangibles - thats despite the company have decent r&d spend.
i wish more companies acted like this and simply didnt pimp out teh numbers "because they can" - ok sometimes having detail ref excveptionals is good where it is genuine - but too many companies do stuff that looks like they are including standard often repeated stuff. Note that also helps too ref cash conversion - so nice that underlying profits less tax should all be filtering to bottom line to invest or payout to shareholders.
2024 was a greta year compare dto what had gone before so stabalistion is fine - they did have the chunky new york subway contract last too that needs to be covered by smaller stuff elsewhere - they have done that.
They still have the goal to move to £100 mill revenues - they still have £9 mill cash after latest acquisition so whilst this years expected growth isnt stonking and current price is not cheap- they do look to be trending in right direction ref future growth.
Hopefully if turnover keeps increasing individual large contracts will be less vital to whether its good year or bad year - ref SAAS some nice future income flows in that regard - SAAS can potentially be the real money earner if they have mostly fixed costs ref that side of things and can grow customer based paying revenue per unit.
I though about selling up/top slicing when shareprice peaked at over £5 - but i am still happy holder even if the fluff has now gone out of the shareprice somewhat.
shareprice reaction today is not unexpected - i think some perhaps may have been getting carried away with what to expect here and it never helps when one is up against good comparatives.
Rather surprisingly there was a pre-results sell off yesterday, and a further sell off today for Journeo (LON:JNEO)
Journeo (LON:JNEO)
Rather surprisingly there was a pre-results sell off yesterday, and a further sell off today for
I think quite a few momentum traders prefer to sell befroe results day if there is uncertainty - whilst the risk here was the upside imho ref trading update - i think that was widely know. And it doesnt hep that the copmapratives from last year make progress look worse than its been.
the shareprice has made huge gains with very little change to fundamentals (imho 12 months ago they had alot of worm to do to replace the NY subway contract and be where they are now) - imho if momemtum traders are folloiwng the flow up - when they exit the building - we can end up back at the typical no premium small company rating thate many listed companies have.
With the benefit of hindsight temporarily cashing ones ships in and banking profit at the top looks a good call. often its hard to tell where the top is - if they had upped profits today for this year materially we wont have been where we are now.
I try not to over trade solid companies - but as they say its only a tangible profit when you sell and bank gains - so well done to those that have made profit and can buy back in cheaper when they choose.
Regarding Journeo (LON:JNEO) been on an amazing run, at 500p was screaming to take profits
Morning,
Personal group (LON:PGH) ex div but still dropping like a stone, any reasons why?
No position but watching with interest...
ME International (LON:MEGP) continued drop, impatient sellers bailing as no offer?!
Got to be 60/70% upside at these levels
I do hold PGH...so watching too! They had a good run up to results and a beat or more positive outlook anticipated?
I wrote about Personal group (LON:PGH) last week - what I think is the bear case and the valuation was too toppy - here's the direct link to my comment: https://www.stockopedia.com/co...
I read it Boon, good article
Could you please add Altyngold (LON:ALTN) to the agenda? That'd be great, thanks!
A rather uninspiring update from IG group (LON:IGG) this morning.
IG group (LON:IGG)
anyone holding this share (same applies for CMC Markets (LON:CMCX) and Plus500 (LON:PLUS)) needs to understand that the figures will often look ugly - there is quite a bit of natural variability here so i tend to concentrate on the bigger picture and not be over picky aboiuta poor period. They are on track (i have generally found their projections to be on the conserative side - although natural variability makes that a hard job)
It does look a mixed bad ref numbers delivred - thats just life though.
I dont hold this share but with current p/e of 9.5 it looks solid value - i think they have enough fingers in enough pies to hopefully improved diversification ref the bottom line.
dividend yield makes this look like asolid hold even though i dont own - and i nice stock for someone looking for somethig reasonable value - and happy to accept the risk that comes with working in the sector they do. eg could then government try and get some extra tax out of transactions their customers have at some stage? Personally this company has been around lomg enough for me to not be worried.
Anglo Asian Mining (LON:AAZ)
Azerbaijan Copper, Gold and Silver miner, worth a look at their future plans over the next 2 to 3 years.
Good H1 2025 results today.
Total revenues of $40.9 million (H1 2024: $13.4 million)
o Attributable to all processing facilities operating continuously throughout the Period which yielded higher production volumes and strong commodity prices
o Higher gold bullion sales of 9,781 ounces (H1 2024: 6,000 ounces) sold at a higher average gold price of $3,077 per ounce (H1 2024: $2,174 per ounce)
o Copper concentrate sales rose to $10.4 million (H1 2024: $0.5 million) reflecting the increasing proportion of copper within the Group's production
· A return to profitability with profit before taxation of $7.1 million (H1 2024: loss of $5.5 million)
o Gross profit of $13.8 million (H1 2024: gross loss of $1.7 million) due to higher revenues
o Higher finance costs at $1.7 million (H1 2024: $1.2 million) due to higher borrowing costs
· Cash generative with net cash generated by operating activities of $11.4 million (H1 2024: $3.2 million)
· Investments in our future growth continued during the Period
o $8.0 million of capital expenditure predominately on mine and processing plant development (H1 2024: $6.3 million)
· Net debt position (excluding leases but including advance from Trafigura) reduced to $13.1 million at 30 June 2025 (31 December 2024: $14.7 million)
· No interim dividend declared for 2025
Should I be pleased that Petershill Partners (LON:PHLL) (I hold) are delisting and returning capital to shareholders? Following International Personal Finance (LON:IPF) (I hold) yesterday that makes two of my best performing companies just disappearing . The pool is getting smaller and smaller !!!!
RE: Petershill Partners (LON:PHLL)
Given the majority ownership it was a matter of time before it got taken out, the only question was the premium offered - which is acceptable in my view.
Nice easy money, taking the dividends while they rolled and a decent premium at the end. Not much not to like.
timarr
Ok then I will take the money -any recommendations on what to do with it ?
Some positive half year results from Microlise (LON:SAAS), would appreciate it if you take a look as I hold.
Buy some Chapel Down wine and let us know what you think !
Chapel Down (LON:CDGP) Just read yesterdays update. Whilst I've not tried Chapel Down (visiting in two weeks time) I would urge folk out there to try our sparkling wines, far, far superior to still. I've taken bottles of Hinhead our local winery to France, our friends here adore it and just dont believe its from Sussex. Its about the marketing of it, the quality is superb after all we now have the same climate as Epernay had 50 years ago. Spoil yourselves and try some. It's not a PLC business its for an entreprenur with very deep pockets but then why let the tax man have it.
The CEO was on BBC Breakfast radio 4 around 06.30 this morning. Worth a listen if you are a fan
On Chapel Down (LON:CDGP) I noted from yesterday's announcement that they scrapped their £32m winery investment... which is substantial for a £77m market cap, £16m revenue company...
And the CEO said: "it will not affect growth plans".
So basically, admitting that it was a big vanity, white elephant project. How can a £32m capex investment be signed off if it is not material to growth plans?
Luckily, that decision was not made by the current CEO CFO, but the former ones I believe. And the largest shareholder, Michael Spencer, is joining as Chairman. Maybe that means they are getting the business back to a commercial objective, rather than being there to fund director's lifestyles.
I agree with mikebianchi on the sparkling wines. They are good, to my unsophisticated palate. As good as champagne?
The problem is the commercial side of the equation. Champagne houses are sitting on a massive glut of champagne due to waning demand in the last few years. On top of that, English Sparkling Wine output is set to massively increase, as the great harvests (2023?) start to come on the market soon. I believe its not a simple case of being able to age the current inventory for longer. So all that inventory, bottled, will need to find buyers.... and UK sparkling wine doesn't have a great demand profile overseas, so who in the UK is going to buy up all those excess bottles, along with all the excess Champagne bottles that will flood the UK too?
I remember years ago. my astonishment at the fact that British airways was apparently the biggest buyer of champagne - wonder where they stand now ?
The move to Prosecco in the lounges was met with outrage and disbelief. Normal service has been resumed and I can confirm that the quaff quotient is reassuringly high.
Didn’t our late Queen serve Chapel Down whenever foreign dignitaries popped over for state visits? Not sure about the King though
I think Pennefeather (Chapel Down (LON:CDGP) CEO) is being a bit disingenuous about this decision. Sure the new winery would have giving a short-term hit to margins in terms of depreciation, but it is difficult to see how it would not have helped long-term operating margins against the alternative now chosen which would appear to be contract bottling, etc.
Not tried Chapel Down in a few years, but am a big fan of Camel Valley (in Cornwall), which do a superb range of sparkling wines and still good value.
Agree about Camel Valley sparkling wines. Good enough for Raymond Blanc to have one bearing his name at La Manoir. Knocks champers into the long grass imo.
ECO Animal Health (LON:EAH) trading statement initially reads very well but it’s actually an in line statement. Nice that they confirm what the market expectations are.
Given the recent share price improvement it will be interesting to see if the market is happy with this improvement in sales. IMO this is a turnaround opportunity and benefits of ECOVACCIN launch still to come. I hold
Surprised about the China strong demand for Aivlosin for ECO Animal Health (LON:EAH) . Pork prices are currently in the doldrums again, and pork producers suffering for margin. This is usually the time in the past when the producers then cut back on Aivlosin, to save costs, and because they don't need to fatten the pigs up more, given the low pork price. But maybe there are other factors at play here that I can't see.
New vaccines - no mention at all. Presume they're stuck in regulatory approval limbo, and likely further delays to the launch timelines. FDA has had massive staff cutbacks due to DOGE. Wonder if that is going to slow down vet product approvals, as they prioritise human products.
CT Automotive (LON:CTA) maintains FY25 and FY26 EPS guidance putting it on forward p/e of 3.5 and 3! Incredibly cheap!
Jaguar landrover closure affect?
Not even mentioned
I have no position here but am surprised that, as suppliers to JLR, they did not think it necessary to mention any impact even if it was just to say that it is immaterial. I don't know enough about this business so perhaps JLR aren't a big customer?
Why do you think that JLR are a customer of CTA ? As far as I am aware CTA have never mentioned JLR in any RNS or meeting.
On their website, on the 'About Us' page, under the timeline they state '“CT UK established to support JIT manufacturing, assembly and supply in CKEU, Magna and JLR.” That is all that I can publicly find.
CT Automotive (LON:CTA) - and this is from 2009. That is all I, or rather ChatGPT, could find.
CT Automotive (LON:CTA) I have previous automotive supply experience, tough industry, low margins, ever increasing energy, labour and raw material costs, serious competition from huge global suppliers with lower cost base. Management will need to be extra special to increase sales and more importantly margins.
Or invent the need for a bail out from a Labour Government?
What if the same happens to tesco standards are being set?!
Seems insanely cheap, it’s priced like an African miner.