Daily Stock Market Report (Thur 30th July 2026) - RR., LORD, ASAI, VANQ, WJG, FNTL, BATS, SYS1

Fed interest rate decision: there was no change to US interest rates last night, with a vote of 9-3 in favour of leaving rates unchanged. The FOMC statement was identical to the prior month.
Chairman Kevin Warsh has attempted to say as little as possible about his own views on the need to raise rates in the short-term. He did vote to hold rates in yesterday’s meeting, along with the majority of his FOMC colleagues.
In last night’s press conference, this was the closest he came to expressing a view, and it was again non-committal. He again emphasised that interest rates would be just one potential tool:
“If inflation continues to be elevated through the forecast period, interest rates could well be part of that solution, but I wouldn’t say it’s in isolation.”
The core CPE price index, the Fed’s preferred measure of inflation, is currently running at 3.4%, stubbornly higher than their 2% target.
Brent crude oil: this has risen $4 since yesterday morning, after the US hit a wide range of Iranian targets and LNG tankers were attacked off Egypt’s coast.
Bank of England: no change to rates is expected at the BoE today but it will be interesting to see how the vote splits. Two of the nine members of the MPC can be expected to vote for rate hikes, but a couple more may join them. UK inflation in June was measured at 2.6%.
Overnight market movements:
The FTSE is down 0.7% at 10,820
S&P 500 is up 0.2% at 7,340
Brent crude (October) is up 1.1% at $89.00/bbl
Gold is down 0.7% at $4,035/oz
Bitcoin is up 0.8% at $64,000
Mark Simpson joins me today.
Calling it there, thanks! Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Shell (LON:SHEL) (£185bn | SR96) | Q2 adjusted earnings $9.8 billion (Q1 2026:$6.9 billion). Record upstream production in Brazil and record refinery utilisation. Cash flow from operating activities $21.4 billion (Q1 2026: $6.1 billion). | ||
Rolls-Royce Holdings (LON:RR.). (£115bn | SR68) | Full year 2026 guidance raised: “we now expect £4.7bn-£4.9bn underlying operating profit and £3.8bn-£4.0bn free cash flow”. Further confidence in mid-term guidance. Previous 2026 guidance was £4.0bn - £4.2bn underlying operating profit, £3.6 - £3.8bn free cash flow. | AMBER/GREEN ↑ (Mark) These are strong H1 results, leading to a roughly 17% upgrade in FY guidance. There may be more to come, too, if the usual pattern of a slight H2 weighting repeats this year. However, with a forward P/E of 33, upgrades are expected, and the complexity of a business of this scale makes it almost impossible to value as an external non-sector-specialist. However, it is clear that momentum is with the business on multiple fronts and as such, we should be broadly positive while that business and share price momentum remains. | |
British American Tobacco P.l.c (LON:BATS) (£103bn | SR89) | SP -2.5% H1 in line with expectations; Confident in FY26 guidance. 3-5% revenue growth, with mid-teens New Category growth (lower end of medium-term guidance ranges). Adjusted diluted EPS growth now expected to be towards the middle of 5-8% medium-term guidance range. | AMBER/GREEN = (Graham - I hold) We already looked at the H1 trading update here. Today's oultook statement is reassuring, with the company "firmly on track to deliver our full-year 2026 guidance". Growth in New Categories revenue of 18% at constant currencies is excellent; these products are now responsible for a sixth of total revenues. FX is proving to be a headwind to results but I very rarely allow this to sway my view on companies. I still consider that most of the important factors here are moving in the right direction, e.g. leverage below 2.5x by year-end. with the company on track to meet or exceed cash conversion guidance of 95%. The earnings multiple (12.5x) hasn't moved much since I last looked at BATS, and so I'm going to leave my moderately positive stance unchanged. It's no longer a true bargain, but I think that's justified by its deleveraging and its ongoing modest growth, led by New Categories. | |
Lloyds Banking (LON:LLOY) (£64.8bn | SR67) | PBT £4.3 billion (H1 last year: £3.5 billion). Return on tangible equity of 17.1%. For 2026 the Group reiterates its guidance, including ROTE of greater than 16%. They expect a ROTE of greater than 18% in 2028 and c. 20% in 2030. | ||
BAE Systems (LON:BA.). (£60.7bn | SR75) | “Given the strong operational performance in the first half, we are upgrading guidance across all key financial performance measures for the full year.” Underlying EBIT now expected to increase by 10% to 12% (previously 9% to 11%). | ||
London Stock Exchange (LON:LSEG) (£44.9bn | SR54) | H1 PBT +29% (£1,278m). 2026 guidance: organic income growth raised to 7.0-7.5% (from 6.5%-7.5%). EBITDA margin guidance raised from +80-100 bps to around 100 bps. | ||
Anglo American (LON:AAL) (£42.4bn | SR54) | Revenue +11%. Loss of $0.9 billion includes the impact of a reduction in the carrying value of the Steelmaking Coal business to reflect the agreed sale terms. | ||
HALEON (LON:HLN) (£33.4bn | SR64) | Organic revenue growth 2.6%. Adjusted operating profit +8.2% (£1,364m). FY 2026 outlook unchanged. | ||
AIB (LON:AIBG) (£19bn | SR80) | H1 ROTE 23.2%. 2026 guidance: Net interest income is expected to be > €3.8bn (previously c. €3.8bn). ROTE is expected to be > 20%. | ||
SEGRO (LON:SGRO) (£13.1bn | SR73) | 5.3% like-for-like net rental income growth. 6.6% EPS growth. EPRA net tangible assets per down 2.5% to 902p. The portfolio valuation decreased 1.2 per cent driven mostly by the application of higher yields by SEGRO's incoming UK valuer. | TAKEOVER | |
Informa (LON:INF) (£11.4bn | SR58) | 6.8% underlying revenue growth in H1. Reiterating full year guidance, whilst further increasing the 2026 Share Buyback Programme to £350m. Guidance: 6%± underlying revenue growth and double-digit underlying growth in adjusted diluted EPS. | ||
Rentokil Initial (LON:RTO) (£11.2bn | SR55) | Revenue +4.5% at constant FX. Adjusted PBT +9.8% ($459m). Net debt $3,575m. Outlook unchanged: “We have seen some weakness in North America Residential lead flow towards the end of Q2 and into July, however we still expect to deliver FY 2026 profit in line with current market expectations.” | ||
Schroders (LON:SDR) (£9.48bn | SR77) | Net operating income up 17% to £1,419m. Adjusted operating profit up 46% (£460m). | TAKEOVER | |
Endeavour Mining (LON:EDV) (£8.47bn | SR64) | H1 2026 production of 564koz at AISC of $1,871/oz. On track to achieve FY-2026 guidance with operating performance weighted towards Q4-2026. | ||
Mondi (LON:MNDI) (£3.48bn | SR36) | H1 2026 underlying EBITDA of €379 million, including a forestry fair value loss of €35 million (H1 2025: €564 million including a fair value gain of €18 million). Margin pressure from higher input costs and lower average selling prices. ““Trading momentum improved through the first half and we enter the second half with higher packaging paper prices, supported by good order books.” | ||
Seplat Energy (LON:SEPL) (£3.31bn | SR94) | Unaudited Results for Six Months Ended: 30.06.2026 & Agreement to Assign a 10% interest in NNPCL-SEPNU | Production averaged 139,509 boepd in H1, up 4% from H1 2025. Reported free cash flow of $526 million. 2026 production guidance unchanged. Agreement reached to sell a 10% interest in NNPCL-SEPNU JV to NNPC Ltd. Headline transaction value of $281.6 million. Completion expected in H2. Proceeds will be split ~50:50 between a dividend and debt repayment. | |
Drax (LON:DRX) (£2.56bn | SR91) | Operating profit £265m (H1 2025: $301m). Adj. EBITDA of £279m (H1 2025: £460m) “reflects a good performance across the portfolio, which reflects lower achieved power prices and is inclusive of planned and unplanned outage work in our pumped storage business.” Outlook: FY26 expectations for Adj. EBITDA in line with analyst consensus estimates. | ||
JTC (LON:JTC) (£2.31bn | SR54) | Trading in line with management expectations. | TAKEOVER | |
Helios Towers (LON:HTWS) (£2.1bn | SR52) | +14% year-on-year Adjusted EBITDA growth. Further upgrade to FY 2026 guidance: 3,500-4,000 tenancy additions (prior: 3,000-3,500). Adjusted EBITDA of US$520m-US$535m (prior: US$515m-US$530m). | ||
Hammerson (LON:HMSO) (£1.96bn | SR58) | Guidance raised. FY26 EPRA earnings guidance increased to growth of +c.27% to c.£132m (£125m underlying vs. previous guidance of c.£120m, £7m from the acquisition of Manchester Arndale). Intends to raise c. £190m in connection with the £218m acquisition of a 50% interest in Manchester Arndale. | ||
Chemring (LON:CHG) (£1.62bn | SR46) | CEO has informed the Board of his decision to retire. Successor already appointed. Tom Newman joins from Babcock International Group where he was CEO of Babcock's Land and UK Aviation Sector. After a transition period, Newman to become CEO on 1st January 2027. | ||
Great Portland Estates (LON:GPE) (£1.42bn | SR37) | GPE has fully let the office space at Carrington House, W1, after leasing more than 6,900 sq ft of Fitted workspace at record rents for the building of up to £105 per sq ft, 8.1% ahead of ERV. | ||
Resolute Mining (LON:RSG) (£1.04bn | SR49) | Group gold production of 45,192oz (Q1 2026: 59,603oz) with operating performance meeting expectations. AISC of $2,484/oz (Q1 2026: $2,210/oz) is as expected due to lower production at Syama and higher royalty payments from elevated average realised gold prices. Q2 EBITDA of $128.5m (Q1 2026: $202.9m). Net cash of $317.4m (Q1 2026: $315.4m) | ||
Firstgroup (LON:FGP) (£996m | SR60) | “…trading performance for the financial year-to-date has been in line with the expectations outlined in the FY 2026 Results on 18 June 2026 and subsequent announcement regarding the agreement to sell Mistral Data published on 29 July 2026.” | ||
Elementis (LON:ELM) (£996m | SR47) | Revenue +4.7% to $318.2m, Adj. Op Profit +16.4% to $73.2m. Net Debt $163.8m (31 Dec: $185.4m). New share buyback programme of £25m using net cash proceeds from the sale of the pharmaceutical manufacturing business. Confident in delivering full year performance in line with expectations (adjusted operating profit $132.5m.) | ||
Pets at Home (LON:PETS) (£927m | SR90) | Q1 Revenue +3.9% to £614m, Vet revenue +1.9%, Retail +4.9%. No change to FY27 guidance. | ||
Vesuvius (LON:VSVS) (£903m | SR71) | H1 Revenue flat at £913.7m, Trading Profit -4% to £74m, EPS -5% to 16.3p. “We expect full-year trading profit to be slightly ahead of trading profit for FY25 on a constant currency basis.” | ||
Alfa Financial Software Holdings (LON:ALFA) (£519m | SR42) | H1 Revenue +4% (+5% CCY). TCV +17% to £347m. Well positioned to achieve expectations for the year. | ||
Halo Minerals (LON:HALO) (£340m | SR7) | The First Environmental Tribunal of Chile has rejected in its entirety the judicial challenge filed on 28 November 2025 against the Chilean Committee of Ministers' environmental approval of the Company's Playa Verde project. | ||
Gooch & Housego (LON:GHH) (£334m | SR53) | Trading performance for FY26 expected to be more heavily weighted towards Q4 than previously anticipated, reflecting the impact of supply-chain constraints on the timing of order book conversion and programme deliveries, and global uncertainties remain a risk to the near-term execution of G&H's strategy. The Board's expectations for FY26 currently remain unchanged. | ||
Vanquis Banking (LON:VANQ) (£296m | SR61) | H1 total income +8% to £237.5m, Risk-Adjusted Income -6% to £135.1m, PBT +57% to £7.7m. NTAV/share +1% to 143p. CET1 -0.9% to 15.6%. “Management and the Board remain confident in the medium term outlook for the business. This is underpinned by the growth opportunity within the large and underserved target addressable market.” | AMBER ↓ (Mark) Reasonable-looking H1 results and a moderation in outlook mask sizable downgrades to EPS forecasts, with Panmure Liberum taking a whopping 63% out of their FY26 forecasts. Given that the bottom line here is the difference between several large numbers, the idea that this is just a blip and that FY28 numbers will make the company look very cheap should probably be taken with a pinch of salt. There is potential value here for those willing to take the longer-term view, as indicated by the discount to NTAV. However, I think in the near to medium term we should be guided by the Stock Ranks, which have done a good job of indicating when investors should be considering an investment here. These suggest we should be neutral at the moment. | |
ASA International (LON:ASAI) (£259m | SR69) | SP -11% Gross OLP up 12% year-on-year, surpassing $600m. Delivered both resilience and growth in the second quarter, which supports our positive expectations for the second half of 2026. | GREEN = (Graham - I hold)
I can understand why there has been some selling today, given the weaker growth and the increase in the portfolio at risk. However, I’m going to stay GREEN on it, as I don’t think today’s update changes anything fundamentally about the investment case here. And I think the risks are priced in at a P/E multiple of around 4x. Of course it could be argued that I’m talking my own book! | |
Wilmington (LON:WIL) (£249m | SR57) | FY Revenue +37% led by the recent acquisition of Conversia (organic revenue growth 4%). Adj. PBT +12% to at least £31m. Net Debt £53.1m (31 Dec: £65.0m). | ||
Fintel (LON:FNTL) (£201m | SR35) | H1 Organic revenue +2.0% to £37.4m, Organic adjusted EBITDA +11.2% to £11.8m. Net Debt £38.2m. | AMBER = (Mark) | |
Sovereign Metals (LON:SVML) (£167m | SR10) | Kasiya Definitive Feasibility Study shows Pre-tax NPV8 of US$2.2bn on capital expenditure to first production of US$727m. | ||
Foxtons (LON:FOXT) (£117m | SR56) | H1 Revenue -3% to £83.7m, Adj. EBITDA -25% to £10.4m, PBT -57% to £4.4m, Adj. EPS -36% to 1.8p. Net Debt £28.4m (25H1: £18.2m). £4.5m of annualised cost savings implemented. Expects full year 2026 adjusted operating profit to be in the range of £17m-£19m, with performance weighted towards H2. (Warned 2 weeks ago). | ||
EKF Diagnostics Holdings (LON:EKF) (£112m | SR63) | “Trading during the period was in line with management expectations, with improved gross margin, growth in adjusted EBITDA and continued cash generation.” H1 Revenue flat at £25m, adjusted EBITDA showed continued growth. Cash largely flat at £16.0m. Remains on track to deliver growth at the revenue and adjusted EBITDA levels for FY 2026 in line with current market expectations (£54.7m and £13.6m. | ||
Ten Lifestyle (LON:TENG) (£90.4m | SR76) | A new partnership spanning a selection of AEG Presents' leading UK venues, festivals and live entertainment events. | ||
Robert Walters (LON:RWA) (£87.2m | SR59) | H1 NFI -4% to £134.6m, Operating Loss £4.5m (25H1: £7.8m Op loss). Net cash £17.2m (25H1: £30.1m). Continues to expect 2026 Group net fees to be slightly below 2025. Envisages an operating loss for the year towards the upper end of current market expectations (Operating loss £8.1-£14.2m). No dividend. | ||
Ondine Biomedical (LON:OBI) (£77.2m | SR18) | NHS Golden Jubilee is the first hospital in Scotland to adopt Steriwave nasal photodisinfection. | ||
Shield Therapeutics (LON:STX) (£61.5m | SR16) | Q2 revenue $11.9m, resulting in 27% growth in H1 2026 compared to H1 2025. Cash $8.3m (31 Mar: $12.4m). | ||
Gemfields (LON:GEM) (£54.2m | SR31) | H1 Revenue +72% to $102.9m, Net Debt $44.1m (25H1: $33.3m). | ||
Power Probe (LON:PWR) (£49.7m | SR46) | H1 revenue -17% to $17.7m, Adj. EBITDA -31% to $3.8m. Trading was in line with expectations and gross margins improved. Significant product launches in late H1 2026 are expected to contribute materially to revenue in the second half of the year. | ||
Watkin Jones (LON:WJG) (£46.3m | SR44) | Signing of six new contracts, with a combined value of c. £60 million at margins in line with guidance, signals further progress of our strategy to diversify the business, allowing us to strengthen our secured pipeline and enhance future revenue predictability. | AMBER/GREEN = (Graham) | |
System1 (LON:SYS1) (£43.8m | SR65) | Revised terms: 135p cash & 2.04 Brave Bison shares, valuing the business at 327p, 20.4x FY26 Op Profit. | TAKEOVER (Graham) [no section below] I've had one or two issues with how Brave Bison has presented its cash-and-shares offer for System1. They previously used a 20-day VWAP of their own share price (94p) to calculate the value of what they were offering, instead of their most recent share price of 90.5p. And in calculating the premium against the prevailing SYS1 share price, they emphasised the SYS1 price all the way back in February, when they first invested in SYS1, rather than the most recent price. The real premium of their initial offer was 4%, in my view. Today's offer is said to be at a 7% premium but that is once again based on a BBSN share price of 94p, not 90.5p. And for what it's worth, the current BBSN share price is 88.3p. When I do the maths myself, I get a premium of 3-5%, depending on exactly which figures I choose to use. Perhaps System1 shareholders are desperate enough to accept this deal? I'd be a little surprised if they were. | |
PCI- PAL (LON:PCIP) (£36.6m | SR45) | Confirms its strategic reseller partnership with NICE Systems. | ||
Synectics (LON:SNX) (£32.9m | SR88) | Contract valued at US$2.4 million to provide its Synergy security and surveillance platform for a major casino property on the U.S. West Coast. Majority of the contract is expected to be delivered during 2027. | ||
Lords Trading (LON:LORD) (£27.4m | SR48) | SP -22% | BLACK (RED ↓) (Mark) This is a stinker of an update, with profitability cut to zero and net debt forecast to be £6.5m higher. With the share price down around 20% today, but half the enterprise value as bank debt, the EV has only really declined by about 10%. This is a possible under-reaction to today’s news. However, the share price trend suggests that bad news was at least partially expected. The company highlights the potential for recovery in better markets. However, there are many building products companies that look cheaper at the moment with the same or better recovery prospects, cleaner accounts and without the debt risk. Given the risk to equity holders that any further significant deterioration in trading would represent, I think we need to have a fully negative view here. | |
Quadrise (LON:QED) (£22m | SR6) | The Amended JDA now sets out a non-binding but more specific development focus, with an updated time schedule for the joint testing of the parties' respective fuel technologies. Final lab tests on refined Licella HTL bio-oils in H2 2026. | ||
Ondo InsurTech (LON:ONDO) (£19.3m | SR1) | Revenue +20% to £4.6m, Operating Loss £6.4m (FY25: £5.2m). Net Debt £5.5m (FY25: £3.1m net debt) after £3.5m net equity raise in the period. £2.9m equity raise and £2.0m convertible issued post-period end. “...entered the new financial year with clear positive momentum.” | ||
Fiinu (LON:BANK) (£14.5m | SR1) | Granicus Holdings OÜ proposes to remove Dr. Marko Petteri Sjoblom as a director of the Company, and that independent directors should review the Company's executive leadership and governance arrangements. | ||
Mycelx Technologies (LON:MYX) (£13.6m | SR50) | Revenue +24% to $2.1m. On track to meet the market's expectations for FY2026 of $11.0m, with 80% of the revenue forecasts either booked, contracted or expected through recurring lease and media sales. Cash $500k. |
Graham's Section
ASA International (LON:ASAI)
Down 11% at 230p (£222m) - Q2 2026 Business Update - Graham - GREEN =
(At the time of writing, Graham has a long position in ASAI.)
ASA International Group plc (LSE: ASAI), one of the world's largest international microfinance institutions, today provides a business operations update for the three-month period ended 30 June 2026.
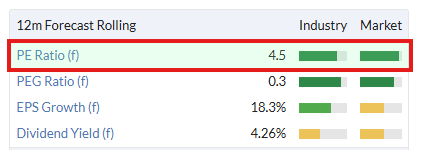
ASAI is a stock I’ve been quite excited about this year. I’ve been pulled in by the earnings multiple:
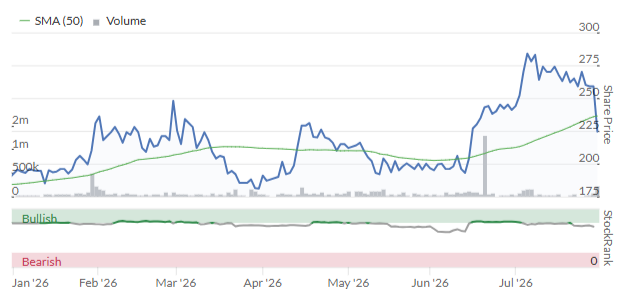
Even after today’s sell-off, it’s still up healthily year-to-date:
Let’s check out today’s Q2 update.
Highlights:
Outstanding loan portfolio up 12% year-on-year, surpassing $600m
This sounds good but it's true that prior growth rates were much faster: in 2025, for example, growth was 33%. In the Q1 update, year-on-year growth had moderated to 25%. Today’s Q2 update shows growth moderating further still. The quarterly growth rate was just 4% - perfectly good for many businesses, but slow in the context of ASAI’s recent progress.
Client base up 11% year-on-year excluding India
Especially considering that this excludes India, the growth in the client base is therefore lagging loan portfolio growth by a few percentage points.
A simple conclusion is that average loan sizes are increasing. Remember that loan sizes here are tiny: the average outstanding amount per client is a little over $200, with the average initial loan size being $347. It makes sense that loan sizes should gradually increase over time, and I think that’s happening here.
PAR >30 (GN note: portfolio at risk, more than 30 days due) of 2.4% vs. 2.0% a year ago
PAR>30 was 2.4% as at 30 June 2026 compared to 2.0% as at 30 June 2025, which remains industry-leading. One of the main drivers was the introduction of new trade regulations in Uganda which negatively affected clients.
I’d be more concerned about this if ASAI was a marginally profitable lender. But that’s not the case: net interest margin was 39.3% in 2025. Speaking roughly, this represents a huge spread between the yield the company earns on its loans, and the interest it pays on its borrowings. Net interest income was $244m, while total operating expenses were $143m.
In that context, a slight tick-up of 0.4% in the portfolio at risk (PAR) doesn’t worry me much. The company has the profit margin to absorb it. And 2.4% is not a bad number in its own right. In 2024 the PAR was 2.2% and the company was highly profitable despite being significantly smaller then, compared to today.
Digital platform live in Tanzania, rollout underway in Kenya and Nigeria.
India Gross OLP brought down 86% year-on-year to USD 4.3m as operations are wound down.
It’s a good thing that Indian operations have been wound down so quickly, when the decision was made to exit.
Indians simply have too many other good options when it comes to accessing credit. It’s an important reminder that as economies develop, there eventually comes a time when the microfinance model is no longer competitive.
CEO comment:
"We are hugely proud of the resilience demonstrated by our clients, and consequently by our loan portfolio, given the challenging circumstances seen across many of our markets. ASA International delivered both resilience and growth in the second quarter, which supports our positive expectations for the second half of 2026.
"While we remain mindful of ongoing geopolitical developments, we are encouraged by the momentum seen across key markets including Pakistan, Ghana and Kenya. Combined with our industry-leading portfolio quality, continued progress in our digital transformation agenda and the further reduction of our exposure to India, we believe ASA International is well positioned to execute on its strategy to deliver sustainable growth."
(I’m glad he went for “sustainable growth” rather than “profitable growth”!)
Looking through the tables, I see that quarterly growth in the number of clients was just 1% (excluding India), and quarterly growth in the loan portfolio (also excluding India) was 4%. The main differences I can between the regions are:
Fast year-on-year growth in South Asia and East Africa compared to the other regions (Southeast Asia and West Africa)
PAR is highest in Southeast Asia (4.9%) and very low in South Asia (0.6%).
Graham’s view
I can understand why there has been some selling today, given the weaker growth and the increase in the portfolio at risk.
However, I think it’s worth pointing out that market expectations already suggested that growth would be much more limited this year:
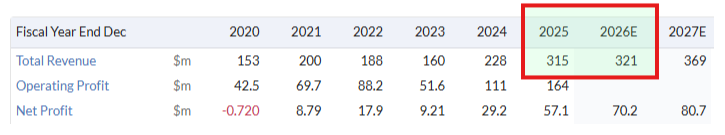
Lending is always a risky business, and rapidly growing lenders can be prone to serious mishaps. I do not have any problem with the company taking a small pause in its growth trajectory. It’s still vastly bigger than it was just two years ago.
Also, when I look into the details, I see that recent growth has been concentrated in an area with very low and falling PAR (South Asia). At the same, ASAI grew at the slowest pace in Q2 in the area with highest PAR. (Southeast Asia). That is logical: grow fast where it is safer, grow slowly where it is less safe.
I’m going to stay GREEN on this today, as I don’t think today’s update changes anything fundamentally about the investment case here. And I think the risks are priced in at a P/E multiple of around 4x. Of course it could be argued that I’m talking my own book!
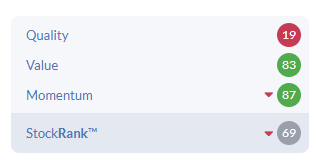
Stockopedia rates it as a Turnaround. I do think this low QualityRank is a little unfair:
Watkin Jones (LON:WJG)
Up 1% at 18.2p (£47m) - Q3 update - Graham - AMBER/GREEN =
Watkin Jones plc, the UK's leading developer and manager of residential for rent, provides the following update on trading for the three months to 30 June 2026 ("Q3").
Times have been tough for WJG:
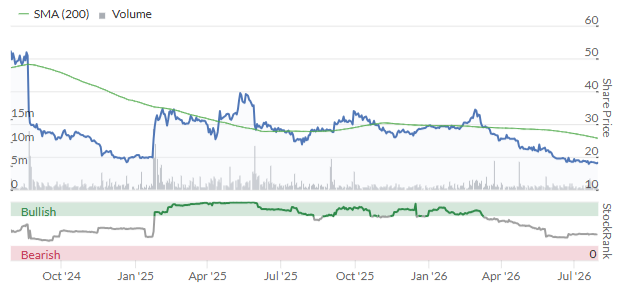
We’ve been moderately positive on it, due to the discount to book value which the stock offers. At the end of H1 (March 2026), it reported adjusted net cash of £61m and had tangible balance sheet equity of £114m, both figures being significantly higher than the current market cap.
Today’s Q3 update:
Whilst the geopolitical and economic backdrop continues to impact both confidence and liquidity in our key markets, the Group remains focused on execution and the factors within our control. This includes successfully delivering our in-build projects in line with stated margin guidance and carefully managing our costs and cash, in particular with further earlier procurement of selected sub-contract packages and materials to mitigate inflationary pressures.
“Controlling the controllables", in other words.
Six new contracts worth £60m have been signed so far in H2, but I wouldn’t be very confident in predicting the profits that might flow from these over time.
In H1, the company’s operating profit was around breakeven on total revenues of £100m. WJG says that the margins on the new contracts are “in line with guidance”.
Five of the contracts are in the Refresh division, providing remediation, fire safety, refurbishment and asset improvement works to existing Purpose Built Student Accommodation.
This sounds like a clear warning that full-year expectations might be missed:
The Group is actively engaged with investors on a small number of transactions which have the potential to conclude in the final quarter and completion of which are required to deliver adjusted operating profit progression in the second half over the first half. The Board is mindful that the effects of ongoing economic and political uncertainty on real estate funding liquidity represent ongoing risk to the timing and completion of these transactions.
With H1 operating profit only around breakeven, and with market expectations calling for material full-year profits (e.g. the net income forecast on the StockReport is £3.5m), a significant improvement in H2 is absolutely necessary in order for these expectations to be met. Based on the above statement, I would assume there is at least a 50% chance of a profit warning.
Graham’s view
Despite my lack of confidence in the ability of the company to hit forecasts, I’m inclined to leave our AMBER/GREEN stance unchanged here. My reasoning is simple: our AMBER/GREEN stance, at least as far as I’m concerned, is a view on the balance sheet, not earnings.
If the market had confidence in the ability of WJG to hit profit forecasts, its share price wouldn’t be down by 40% year-to-date. It wouldn’t be trading at a discount to net cash and at less than half of net assets.
So the current difficulties re: profitability are already priced in, I think. From here, it’s a question of how long the recovery might take and whether the share price has been sufficiently discounted to account for the risks involved..
With the company trading so cheaply and still having the potential for a breakeven result this year, or hopefully a small profit, I am fine with retaining our moderately positive stance.
I’m not surprised to see this show up on one of the “Bargain Stocks” screens:
Mark's Section
Rolls-Royce Holdings (LON:RR.)
Up 5% at 1450p (£115bn) - 2026 Half Year Results - Mark - AMBER/GREEN ↑
When I previewed these interim results on The Week Ahead, I pointed out that the Value Rank had dropped to a very low level and that:
It remains a high flyer, but the pressure is now on to deliver numbers that lead to further upgrades to maintain the upward trajectory.
Thankfully, they are delivering, as in today’s results, they say:
Full year 2026 guidance raised; we now expect £4.7bn-£4.9bn underlying operating profit and £3.8bn-£4.0bn free cash flow.
They had previously guided £4.0bn-£4.2bn of underlying operating profit and £3.6bn-£3.8bn of free cash flow, so this is a sizable 17% upgrade, mid-point to mid-point.
H1 Results:
Importantly, this outlook is backed by a strong H1 reported today:
Underlying operating profit rose by 46% to £2.5bn; underlying operating margin of 22.5% with higher profitability in all divisions reflecting the impact of our strategic initiatives and operational improvements
Free cash flow of £2.0bn driven by higher underlying operating profit and with increased investments to support profitable growth to the mid-term and beyond
This is over half of the full-year guidance delivered in H1, for a business with a historically slight H2 weighting (over the last three years, the H2 weighting has been 51%, 55% and 58% for underlying operating profit). This suggests that they may be holding something back for further upgrades during the year.
Adjustments:
Whenever a business is going through a "transformation programme”, it pays to look at the exceptional costs, as many companies would like investors to give management credit for the cost savings but exclude the costs of achieving them.
Here, the figures look reasonable, and the gap between statutory and adjusted figures is relatively small:
Statutory operating profit was £2.4bn, compared to underlying operating profit of £2.5bn. The £116m lower statutory operating profit is primarily due to a £(117)m pension past service charge, £(28)m transformation and restructuring charges, £(8)m amortisation of intangible assets from previous acquisitions, partly offset by £37m positive impact from currency hedges.
While a £28m restructuring charge would be very material in many places, here it is just 1.1% of adjusted operating profit, given the overall scale of the business. That this is reasonable is backed up by the cash flow, with trading cash flow coming in pretty close to adjusted operating profit.
There continues to be a modest amount of pension recovery payments made, but again, these are far from material, overall:
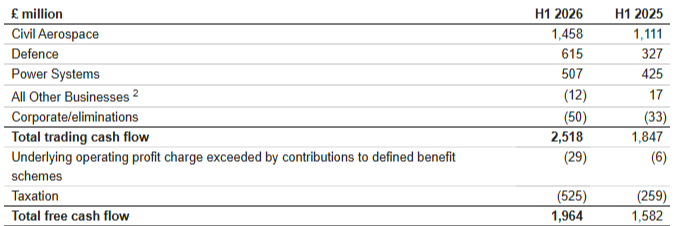
Trading cash flow also shows improvement across all three major divisions, indicating the strength of delivery is broad-based.
Key aspects:
When I previewed these results, I suggested four key things that investors may want to review in these results: Civil Aerospace Engine Flying Hours, Share Buybacks,
Operating Margin Improvements and Balance Sheet Improvements. It is worth going through each one:
Civil Aerospace Engine Flying Hours: Here they say, “In the first half of 2026, large EFH rose by 4% versus the prior period to 113% of 2019 levels, driven primarily by new aircraft deliveries”, nicely above the 110% level I was looking for. Importantly, demand for aircraft and engines remains strong, despite concerns about the impact of higher fuel prices, and the engine order book has increased by 10% year on year. This builds long-term visibility for their key maintenance profit driver. However, there looks to be a modest near-term impact from global worries, as they say, “In Civil Aerospace, we now expect large EFH towards the lower end of the range of 115%-120% of 2019 levels.”
Share Buybacks: Here they say: “We are making good progress with the £2.5bn 2026 tranche of our share buyback programme, having completed £1.1bn by the end of June and £1.4bn to date. This forms part of our multi-year buyback programme, totalling £7bn-£9bn across 2026 to 2028.” So, no immediate upgrade to this. However, it is a multi-year programme, so it would perhaps not be expected at this stage.
Operating Margin Improvements: Today’s upgrade is driven largely by higher LTSA margins, and they say: “In Civil Aerospace, we are continuing to improve LTSA margins across our in-production widebody engines through operational improvements and commercial optimisation, including the further successful renegotiation of onerous contracts. The improvements that we are driving across widebody and business aviation have resulted in gross contractual margin improvements of £574m in the period.” However, I can’t see any formal guidance on further margin improvements today.
Balance Sheet Improvements: Net cash is now up to £2.1bn, an increase of £241m, despite £1.5bn of shareholder returns. It is worth noting that contract liabilities remain significant, with the current figure increasing slightly to £8.6bn. This liability alone exceeds the cash and debt figures.
Other notable impacts:
Defence: While the Iran war may have reduced commercial flights, especially to the Middle East, flying hours for military aviation have increased. Together with “actions to support a stronger aftermarket performance alongside continued self-help”, this means that Trading cash flow in this segment almost doubled compared to the prior period.
Power Systems: While the trading cash flow increase was modest compared to the other divisions, underlying operating profit grew by 72%, and order intake was £4.6bn, more than a 50% increase compared to the prior period. Like many large companies, it is the demand for data centres that is driving this trend, and the company is a beneficiary.
Valuation:
Obviously, we don’t have access to the broker coverage for companies of this size. Still, if we assume the 17% increase in underlying operating profit leads to a similar upgrade in FY EPS, this figure rises from 37.5p consensus to 43.9p. With today’s share price rise, the forward P/E drops from 37 to 33x. At the end of the day, so much of the value here is in the future expectations for multi-year growth, rather than a single year’s figures.
The scale and complexity of the business make it almost impossible to value as an external, non-sector specialist. As such, the investment case lies in continued momentum in the underlying business, and in this regard, the signs today are positive.
Mark’s view
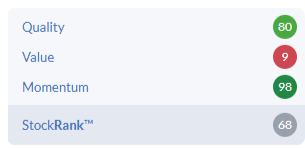
On the surface, a 5% share price rise in response to a 17% upgrade in underlying operating profit, mid-point to mid-point, is an underreaction. However, one of the key metrics of large EFH has been guided towards the lower end of the range of 115%-120% of 2019 levels, and the high rating suggests that continued outperformance was probably expected:
The normal H2 Weighting suggests there may be a further upgrade this year, as they have delivered more than half of the underlying operating profit in H1.
The Value Rank of 9 should give us pause, as there will be no immediate downside protection if the momentum starts to wane. As should a Stock Rank that is starting to moderate. However, with upgrades today and no sign of that momentum fading, I think we should be broadly positive here, with AMBER/GREEN, despite these risks. However, I would be quick to reduce our view if the business prospects or share price started to gain downward instead of upward momentum.
Lords Trading (LON:LORD)
Down 22% at 12.9p (£27m) - Trading Update - Mark - BLACK (RED ↓)
I last reviewed this distributor of building, plumbing, and heating products following their FY25 profits warning in November and reduced our view to AMBER/RED. I didn’t like the adjustments they made to get to their underlying figures and commented that:
With the share price at 23p, this now looks expensive on forecasts (even without applying more sensible adjustments) and risky given the scale of the debt (incl. lease liabilities).
The flat H1 revenue figures released today don’t look too bad in a difficult market. However, store openings and the acquisition of CMO are responsible, with LFL sales down 7%.
No profitability measures for H1 are provided, aside from noting that CMO is EBITDA-positive during the period. If they have this for CMO, they surely have an indication for the rest of the business. So, not giving any figure here leads me to conclude that the numbers are not great.
I’d previously pointed out that EBITDA is a poor measure here, as it excludes significant lease payments from the figure. This only got worse as the company sought to reduce bank debt by executing a sale-and-leaseback of property assets.
The market gradually started to price in these risks, but not sufficiently, it seems, as today’s update is now a profits warning for FY26:
…with no indications of a significant market recovery in the second half of 2026, the Board now expects full year revenue will be in the range of £475m-£495m and adjusted EBITDA for the full year will be £17m-£18m.
It also seems strange that they gave an in-line statement at their AGM in June. Has the trading/outlook really deteriorated by that much in the last six weeks?
Net bank debt is up to £29m from £13.4m at the year end, which they say is a normal seasonal working capital movement. However, last year inventories declined in the first six months of the year, and were lower than the subsequent year end. So again, this raises questions as to how normal this is?
Forecasts:
We have to turn to their broker, Cavendish, to work out the impact. Adj. EBITDA is cut 12%, but again, this is not a useful measure here. Adj. EPS goes from 1.1p to zero. FY27 numbers are cut as well, with EPS going from 1.6p to 1.1p. Bearing in mind that these will depend on the highly optimistic adjustments the company usually makes to its numbers, this is a poor outcome.
Net bank debt is forecast to be £6.5m higher at £24.9m at the year end, and £6.0m higher at £23.8m.
Mark’s view
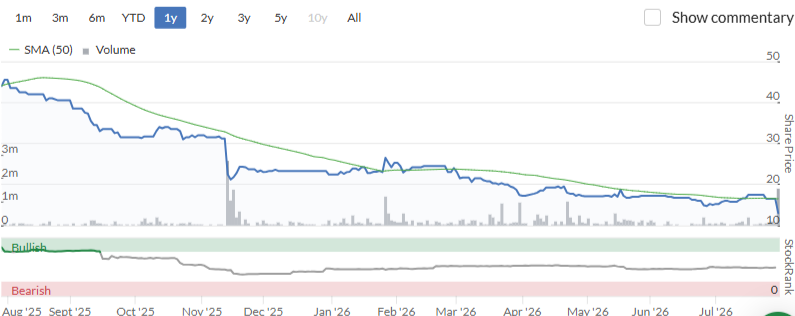
This is a stinker of an update, with profitability cut to zero and net debt forecast to be £6.5m higher. With the share price down around 20% today, but half the enterprise value as bank debt, the EV has only really declined by about 10%. This is a possible under-reaction to today’s news.
However, the share price trend suggests that bad news was at least partially expected:
The company highlights the potential for recovery in better markets:
The Board remains confident in the Group's medium-term prospects. The actions taken over the past 18 months to simplify the business, improve operational efficiency, strengthen cash generation and shift the Group's revenue mix towards structurally growing categories leave the Group well positioned to benefit as construction markets recover.
However, many building products companies look cheaper at the moment with the same or better recovery prospects, cleaner accounts and without the debt risk. Given the risk to equity holders that any further significant deterioration in trading would represent, I think we need to have a fully negative view here. RED.
Vanquis Banking (LON:VANQ)
Down 20% at 92p (£295m) - Interim results - Mark - AMBER ↓
Background:
I’ll start off by saying that I’m not really a banking analyst, so the scale of the market reaction to today’s Interims surprised me on an initial reading.
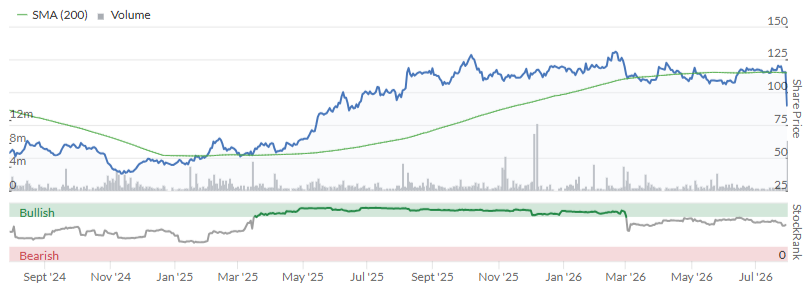
The company had come onto my radar a couple of times recently. Firstly, as a smooth trend as the share price recovered from November 2024 lows, delivering 3x returns to investors who held to November 2025:
Then, looking longer-term, this also had the potential to be a recovery bowl with 2022 highs being significantly above the current price:
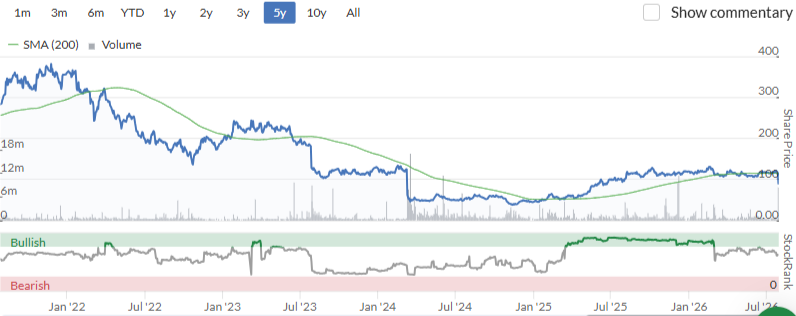
However, this possible recovery looks to be a long way off following today’s reaction. It is worth noting that this is a potential win for Ed’s recent research on Stock Rank jumpers. Investors who bought when the company became a Super Stock in April 2025 and sold when it went below 75 in March this year, would have doubled their money in a year.
The results:
The profit delivery headline looks good:
Profit before tax increased 44%, exceeding our profit for all of 2025, despite absorbing a significant increase in macroeconomic impairment provision.
However, there is an immediate sign that there may be a ting in the tail, with them saying “macroeconomic uncertainty drives more cautious consumer behaviour".
Like many financial companies, the bottom line is the difference between two very large numbers. After earning £218.1m of interest income in 26H1, they had £102.4m of impairment charges. Non-interest income was £19.4m, and operating costs came in at £126.2m, leaving a PBT of £7.7m.
The impairment charge is just 3.5% of average gross customer balances, but shows how sensitive they are to economic conditions and how small changes here impact the bottom line.
It’s a double whammy, as a more difficult consumer backdrop constrains consumer spending amongst longer-term customers (who are presumably more likely to pay back the money they borrow):
Near term outlook moderated: Higher new customer growth in Credit Cards resulted in a greater proportion of growth coming from new customer acquisition than anticipated, which is lower yielding in its early years, as new credit card balances start to become profitable after two years. This was combined with lower than expected Credit Card spending and utilisation from existing customers due to a more uncertain macroeconomic backdrop. The Group are assuming this trend persists, and intend to continue to drive greater volumes of high quality balance growth from new customers. While this will moderate returns in 2026 and 2027, it positions the Group for stronger profitability beyond the near term impact. The Group now expects a return on tangible equity of low single digits in 2026, low double digits in 2027 and mid-teens in 2028.
The company therefore, is cutting their guidance today for net interest margin to greater than 14.5% and 13% for FY26 and FY27, versus 15.5% and 14.5% previously.
The recovery that was to see them deliver mid-teens Returns on Tangible Equity (and therefore much-improved EPS) is now delayed until 2028, from 2027. However, given the economic sensitivity and the downgrade today, I can see why the market may be calling this simply a delay, travelling hopefully.
Forecasts:
Panmure Liberum say:
We leave our balance growth forecasts unchanged. The lower yield and higher impairment guidance feed through to risk-adjusted income, which we cut by c.7.5% across our forecast period. Because the business carries a high fixed cost base, that reduction is heavily geared at the profit line: net income estimates fall by c.67% in FY26E, c.35% in FY27E and c.16% in FY28E.
But the impact is most acutely seen in the EPS forecasts, which they cut by 63% to 5.0p for FY26. The later-year impacts are less severe, but still sizeable, with FY27 reduced by 36% to 14.1p and 16% taken out of the FY28 numbers.
With these in mind, I can see why the market has reacted strongly to the downgrade here.
The positive news is that PL is now forecasting a dividend for the first time, driven by a higher capital surplus. This will be modest at first but is forecast to grow to 4.4p by 2028.
Asset Value:
Of course, short-term earnings are not the only way to value a bank, as many of us found out to our cost in 2008!
In these results, NTAV/share is reported at 134p, and Panmure Liberum forecasts it will rise over the next few years to close to 170p in FY28.
This may represent good value relative to the current 92p share price for those who believe the company can eventually reach its targeted RoTE.
Mark’s view
With current year EPS forecasts cut by 63%, this no longer looks like good value on earnings unless you believe the FY28 forecasts. Given the scale of today's downgrades, the idea that this is just a recovery delayed must be taken with a pinch of salt. The discount to TBV suggests there is value here if that recovery comes. However, with earnings being the difference between several large numbers, I wouldn’t be brave enough to forecast exactly when that is.
Graham increased his view on this company in April, on the news that Vanquis will not challenge the FCA’s redress scheme and is focused on implementation. Its previous, very minor £3m provision for this matter remained unchanged, which was good news. However, this now seems overshadowed by the negative news today on core market conditions.
With so much uncertainty around, I think the Stock Ranks should guide us. After all, they did a great job of calling when investors should have bought or sold the shares over the last 18 months or so. As such, a Stock Rank of 61, which will surely go lower after today’s fall in share price, suggests we should be neutral. AMBER
Fintel (LON:FNTL)
Up 2% at 197p (£201m) - Half Year Trading Update - Mark - AMBER =
Given the acquisitive nature of the business, it is good that the company break out their organic growth rates. The bad news is that organic revenue growth in the half year came in below inflation:
Organic revenue increased 2.0% to £37.4m (HY25: £36.7m) driven by continued growth in Software and Data of 2.9%, or £18.4m to £18.9m, and organic growth in Services of 1.1%, or £18.3m to £18.5m.
Things look better on an adjusted EBITDA basis:
Organic adjusted EBITDA growth of 11.2% to £11.8m (HY25: £10.6m), reflecting improved performance and efficiency in the business.
However, a quick look at recent results shows this to be a poor measure with which to judge a business that capitalises intangible development expenditure.
They also seem to want to be able to regularly acquire businesses to deliver growth, and fire staff to reduce costs while expecting shareholders to exclude the sizable costs associated with doing so.
Forecasts:
This is an in-line trading statement overall, but that is perhaps not that challenging when Cavendish are forecasting a 2% decline in revenue and EPS up 11%.
There is £38.2m of net debt at the half year, and Cavendish calculate they are trading at 9.6x EV/EBIT, which is not expensive, but also doesn’t scream value for a business that appears to be plodding along, and has some significant adjustments in these figures.
Mark’s view
There are some good aspects about this acquisitive company. Defaqto, in particular, is an excellent platform business. However, the businesses appear to be largely ex-growth on an organic basis. This means the 9.6x EV/ (heavily adjusted) EBIT metric calculated by their broker, Cavendish, looks to be up with events.
The Stock Rank and “Falling Star” classification suggest we should be negative on this business. There may be little upside from the current price. However, a negative view is probably overly harsh given the quality of some of the subsidiaries, such as Defaqto, and I think we should be neutral, overall. AMBER
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

47 comments
Decent results from Lloyds Banking (LON:LLOY) although impairment charges were almost double compared with H1 2025 due to the situation in the Middle East and the outlook for house prices.
Amazing to think it is almost 20 years since the start of the GFC (the Northern Rock model failed in 2007 and RBS nationalised post ABN acquisition in 2008). Lloyds Banking (LON:LLOY) CET1 ratio (ordinary shares plus retained earnings) was 8.1% back in 2007, now it is 13.6%.
I own Lloyds Banking (LON:LLPC) preference shares for the 6.3% yield and thinking of adding to my holding but wary of BoE MPC rate rises. The SP was 167 pence at the end of 2021 (when BoE interest rates were 0.1% and also before the start of the Russia/Ukraine conflict) and dipped as low as 128 pence mid 2023 when BoE rates peaked at 5.25%. Current SP is 147 pence. The second dividend payment should be 30 November with the shares going ex-dividend at the end of October so a little time to see what happens.
Would be interested to hear the thoughts of the analysts views on IG group (LON:IGG) acquiring the US firm underdog for 1.3 billion.
Yes, I think Graham still holds. I'm not sure, it sounds like they're becoming a bookie. I'm not sure at all about this. On the other hand maybe all betting is just betting, sports or spread?
Not sure about this US style reporting after hours either. It's probably better, but only when you're expecting it.
So Citadel, the algos champions, issue an interest rate hike warning and the next day go and buy the entire portfolio of Leopold in a single stock trade-:)
Nice!
All the best
Graham, Many thanks for your reassuring analysis of ASA International (LON:ASAI) .
You're very welcome FREng, I hope it also has some connection to reality! G
I will second this… appreciate you taking the time to talk your own (and my) book….
Re Vanquis
"I’ll start off by saying that I’m not really a banking analyst"
Neither am I - but I this caught my eye, my bold...
"While new lending volumes remained resilient overall, with particularly strong growth in Second Charge Mortgages, an uncertain macroeconomic backdrop resulted in more cautious consumer behaviour leading to lower than expected spending and utilisation from existing Credit Card customers."
I would think that Vanquis holders might want to satisfy themselves on whether this is a good time to be growing second charge mortgages.
There might also be a read across to Secure Trust Bank (LON:STB) given their POS retail lending offering. They report their results on Aug 13th. I have sold my position today given the potential read across
The UK has followed the US and left rates unchanged and expressed some confidence that a hike is not imminent although clearly not ruled out. Central bankers would appear to think the economies are slowing...which is not really market consensus. I think the US is under more pressure to not slow...but slowing at the moment doesn't seem to be too negative for equities...and in the UK bonds are rising. Good for the government at least. Sterling is up and Bonds are up so all would appear to be well... for now. Let's enjoy it while it lasts.
And nice bounce in US ...
I thought I would share a few thoughts after watching the results presentation from Mobico (LON:MCG) from yesterday. I had hoped that this business could follow Stagecoach in bouncing back from difficulties, due to the inherent cash cash generation usually associated with bus companies. There were high hopes for the sale of the US school bus business at a mooted £800m+, but I began to be concerned when this sold for under £400m in 2025.
Roll forward a year and a half to these results and I was still optimistic that this business could dig its way out of a hole. Unfortunately, the presentation proved to be an alarming eye opener. Let's start with the, oh so crucial, debt. You don't need all the gory details but suffice to say that net debt is actually higher now than it was at the year end preceding the school bus sale! Scary. Covenant gearing has gone up to 2.9x and will rise above 3x before, hopefully, (in the opinion of management) coming down as a result of the German rail contract renegotiations. By the way, don't forget the convertible debt not shown in the figures (its conveniently classed as 'equity') which will crank up the interest bill by an extra £19m from this year, as the somewhat unusual terms of the loan dictate.
What about business unit performance? This is where the mistakes of previous management really show through. There have been write-offs all over the place from onerous contracts in German rail, Morocco, WeDriveU in the US and more. The exit from such contracts has been expensive and cash consuming. There have also been further spending commitments in US school bus prior to disposal that reduced the true sale price well below the headline figure. UK bus and coach (the original bedrock of the business) hasn't made money for years and doesn't look like doing so meaningfully any time soon.
New management are probably doing the right things (hard to tell) but the business is drowning in debt and doesn't have the free cashflow to extricate itself, in my opinion. Sadly I think the inevitable 'rescue rights issue' beckons (hinted at in the results statement), especially as these figures were unaudited and the new auditor, KPMG, might have more to say in due course. A very sorry situation and as you might have guessed, I am now out. I confess, I have never been great with turnaround situations and I should learn to steer well clear in future. The experts in such matters might explain that I've got it wrong here, but I have lost my nerve and am moving on.
I thought Gooch & Housego (LON:GHH) was in a takeover situation. I hold lots.
I was about to make the same comment. It's difficult to keep track of all the takeovers but GHH was announced a couple of weeks ago on the same day as Rotork.
The table of today's results could do with having 'takeover' added for GHH.
London Stock Exchange (LON:LSEG)
I thought the results were excellent but Mr Market disagrees. Further large buy backs coming. Hard to see how this is not cheap but the catalyst for a re rating appears still AWOL. As i have always thought how long before one of the European Bourses comes calling........
Yes results looked very good to me - perhaps just a bit of profit taking after a recent strong run. Not sure how easy it would be for one of the European bourses to take this over, in terms of regulatory hurdles, although it would certainly be attractive at this price.
Morning chaps,
I don't see PHP in your company list.
Interims released today.
Look ok to me.
Excellent record of paying dividends. Yield over 7%
Rental payments very secure as critical health infrastructure.
Michael
My only concern here is the high LTV (57%) and short maturity of debt (average 4 years) so interest costs likely to rise significantly when they refinance. This would reduce earnings and dividend cover. They could sell properties to reduce debt but this would also reduce their earnings. Obviously some of this will be offset by rental growth.
Great Portland Estates (LON:GPE)
More good letting news from GPE. I am struggling to understand given the shortage of high quality West End offices why the NAV discount is so high and Stocko seems pretty negative
With the huge amount of company news and results, I feel embarrassed to ask for your views on just one, but grateful for your thoughts on ASA International (LON:ASAI) .
The turnover is up but the market seems unhappy, Many thanks in advance
Also would be interested but acknowledge that not everything can be covered especially with so much news
I'd welcome the team's views on ASA International (LON:ASAI) too, as I hold.
I was also a little surprised at the market reaction to ASA International (LON:ASAI) Q2 update. Three potential reasons for this:
1. The statement didn't include the reassuring phrase "we are on track to meet market expectations for the full year." Assuming they are, why not say it?
2. Yes there was growth in the top line, but analysts may have been expecting more. Given the increase in payments overdue by more than 30 days, overall profitability may be flat. We don't know.
3. No mention that I could find of cash flow or net debt, which was up sharply last year. What's the old saying? Turnover is vanity, profit is sanity, cash is reality.
The market does seem to be in a grumpy mood just now. Barclays fell 5% on perfectly decent results earlier this week. I wouldn't read too much into today's price action.
ASA International (LON:ASAI) The reason for the fall may be the growth in portfolio at risk. From the RNS:
PAR>30 of 2.4% versus 2.0% a year ago
PAR>30 was 2.4% as at 30 June 2026 compared to 2.0% as at 30 June 2025, which remains industry-leading. One of the main drivers was the introduction of new trade regulations in Uganda which negatively affected clients.
It had fallen to 1.8% in Q4 25 (from 2.2% in Q1 25) then rose to 2% in Q1 26. The changes seem quite minor to me and can be explained by regulations in one country but the market may not be liking the trend
Anyone else getting notifications but when they press on the icon being told there are no notifications?
Been this way for days now
Yes I reported it and it was fixed v quickly
FTSE100 at an intraday all time high!
All the best
All the noise is still "crash imminent "
Lol
Pets at Home (LON:PETS)
Retailer sales pick up looks impressive. Yet to unscramble the details in the trading update. Perhaps a read across to other retailers Dunelm and Halfords come to mind.
Any help from Graham and team would be appreciated.
Key will be the retail margins at Pets at Home (LON:PETS) .... they were looking to "invest in prices" to win back share. Did they just buy that retail growth?
Vets growth of +1.7% seems lacklustre, especially when clinical FTE headcount +4%. Seems like a margin squeeze there too...
Telling that the entire Trading Update had no statements on margins/profits.
Good point Boon.
Dunelm (LON:DNLM) I hold and as the price was on the floor bought for the Wife in her SIPP. She likes the products so enough said..... Still too cheap in my view
Be careful Shell (LON:SHEL) might need to "get out of Dodge" with Sheriff Fahnbulleh in Town.
Matter of time before they move out of London. The office workforce there is shrinking and no affection at corporate level for continuing with a UK listing in the current lunacy of political thinking and actions.
A merger with perhaps a similar sized co to put them at the top table in the US and then can go for the Weddell sea. Weekend study methinks.
A slightly bizarre day yesterday when MOVE actually fell to 74 although the FT focussed on rises in 30 year bond yields....but VIX spiked to 20.66 as equities had a small freak at the prospect rates might actually rise - yet remained unchanged yesterday. Although all measures of CPI are North of their targets the last published number was on side - falling month on month. We have to wait until August 12 for the next data for July, and rises in energy are back in the cross wires - so im guessing the market is pondering less good data but maybe the Fed does not share this concern. All guesswork really but clearly from yesterday's reaction we can tell the market is in no mood for rising rates.... and unlike Warsh ... thought Trumps rate cuts were coming. Normally as VIX gets above 20 I think some sort of buying opportunity is emerging yet clearly not here - the markets have traded well on hot air for a while and maybe due a reassessment of where we actually are. And where is that? no-mans land I guess .... not goldilocks waiting for rate cuts but the CPI data on August 12 "might" help.... he says hopefully.
Decent results from Rolls-Royce Holdings (LON:RR.) British American Tobacco P.l.c (LON:BATS) Lloyds Banking (LON:LLOY) and Greencoat UK Wind (LON:UKW) all of which I hold. Any comment on Greencoat UK Wind (LON:UKW) welcome as NAV and dividend cover increasing will hopefully lead to the shares rating upward towards NAV again? Thoughts
Primary Health Property interim result is out today.
Hi The wife has this in her SIPP and therefore enough said a boring hold with a good yield and bullet proof income from NHS etc
Tin hats on today, I suspect!
Spreadex currently calling the market down 50 points. From what I can gather most of the rout across the pond is in the tech stocks - something the FTSE doesn’t have a lot of. They were massively overvalued in my view and were an accident waiting to happen once sentiment turned.
Any chance that you could run the rule over today’s interim numbers from Vanquis Banking (LON:VANQ) please Graham. I hold. Headline number looks good, but as always, the devil is in the details - and there are a lot of details.
Edit - now down around 30 points and 12 points of that is due to today’s ex divs.
Undoubtedly true that the tech sector was overvalued and could have further to fall... but just 1 thing to note ... many of the names are already 50% + down... the rotation and strength of eps growth has prevented the indices falling far... those tech names could well fall 70% and some will go bust , but many will go on to multi bag from here over the next few years IMHO...
Good luck if you hold. I hope you’ve picked the winners.
Watkin Jones (LON:WJG) Brief 3Q trading update - potential for some contracts to be booked in next financial year . However with Book at 48.5p and net cash of £61m , SP already discounting a great deal .
Watkin Jones (LON:WJG) pretty cautious update with little detail. I wasn't sure how many of the contract wins had already been declared. H2 dependent on some unsigned contracts. Lots of cash but no momentum...
Hi DD Yes I agree one of my less good investments and whilst the balance sheet looks OK I am increasingly unconvinced that what ever turnaround happens is being forever consigned into the ' Jam tomorrow' category