Daily Stock Market Report (Thur 3rd September 2026) - JET2, CRST, FDEV, ECEL, TRB, EMAN

There isn’t much overnight news, but I’d like to draw your attention to our recent stock pitches: Volex (by Ed Sheldon, who joins me today), and IG Group (by yours truly) (disclosure: I’m long IG group (LON:IGG)).
Researching IG’s takeover of sports betting platform Underdog, I came across Kalshi, the largest prediction market in the United States. It’s less well known outside the US, where Polymarket is more influential.
Anyway, it turns out that Kalshi is in the news quite a lot. Here are some of the biggest Kalshi-related stories from the past week alone:
CNBC: Young adults under 21 traded $5 billion on Kalshi this year, amid prediction market frenzy
Reuters: Prediction market Kalshi to file for US crude oil 'perps'
Politico: Kalshi permanently bans George Santos for insider trading
The Block: Michigan court orders Kalshi to keep blocking sports prediction markets
Sportico: Kalshi stops its sports injury betting markets at CFTC’s Request
It's worth noting that nearly all of these stories have something to do with the regulation of the platform.
Prediction markets are immature and the regulatory situation is far from settled, which makes them interesting from an investment perspective.
I mention all of this because it adds flavour to the story around IG’s acquisition. I’m very uneasy about the amount paid for it. But in the bigger picture, I’m also intrigued as to how these so-called prediction market “derivatives” are going to evolve over time.
Overnight market movements:
The FTSE is unchanged at 10.755
S&P 500 is unchanged at 7,665
Brent crude (November) is down 1.2% at $94.40/bbl
Gold is up 1.1% at $4,435/oz
Bitcoin is up 0.3% at $77,700
The Agenda is complete. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
M&G (LON:MNG) (£8.3bn | SR73) | Adjusted operating profit up 15% to £435m, £2.4bn net inflows from open business, Shareholder Solvency II coverage ratio of 247%, dividend of 6.8p per share. | ||
Londonmetric Property (LON:LMP) (£4.3bn | SR53) | £105 million of investment activity since its trading update in July. | ||
3i Infrastructure (LON:3IN) (£3.6bn | SR46) | 3i Infrastructure plc completes investment in the Lefdal Mine Datacenter campus | 3i Infrastructure has completed its c.€263 million investment in Lefdal Mine Datacenter, a Norwegian data centre campus with significant growth potential. The transaction includes a small portfolio of operating renewable assets. | |
ROSEBANK INDUSTRIES (LON:ROSE) (£3.4bn | SR12) | Revenue of $733m. Group adjusted operating profit in the Period was $110m (2025: $3m loss). Adjusted diluted EPS of 10.3 cents. Net debt of $1,069m, with Group leverage at 2.4x at 30 June 2026. Board has declared its first interim dividend of 2.1 cents per share. Rosebank is trading ahead of full year market expectations for 2026, with adjusted operating profit and EPS expected to be ahead of Company compiled analysts' consensus. | ||
Jet2 (LON:JET2) (£2.8bn | SR98) | The group has seen sustained demand since its Preliminary Results on 8 July 2026. Summer 2026 seat capacity is 7.6% higher than Summer 2025 at 19.9m seats. London Gatwick operation continues to perform ahead of initial expectations. Winter 2026/27 on-sale seat capacity is 8.0% higher than Winter 2025/26 at 5.9m seats. 93% of full-year jet fuel requirement now hedged at an average price of $753. Intends to move to the Main Market before end of current financial year. | AMBER/GREEN = (Ed S) | |
Grafton (LON:GFTU) (£1.89bn | SR96) | Revenue up 6.7% to £1,336m. Adjusted operating profit up 8.2% to £98.5m. Group operating margin of 7.4% (2025: 7.3%). Adjusted earnings per share up 10.8% to 39.4p. Balance sheet remains strong with £78.3m net cash. Full-year adjusted operating profit guidance of £190m - £200m maintained. | ||
Watches of Switzerland (LON:WOSG) (£1.6bn | SR99) | Performance during the 17 weeks to 30 August 2026 remained consistent with the positive trends reported in FY26 results. Trading in the US remained strong and the UK continued to show further signs of market improvement. Well positioned to deliver on FY27 guidance. Expects full-year revenue growth of 5-10% and 40-80bps adjusted EBIT margin expansion. | ||
HUTCHMED (China) (LON:HCM) (£1.58bn | SR16) | Subsidiary HUTCHMED Limited has entered into an exclusive development and license agreement with a subsidiary of GSK, granting the GSK subsidiary worldwide rights excluding Mainland China, Hong Kong, Macau and Taiwan to develop and commercialize HMPL-A830, a first-in-class KRAS-EGFR Antibody-Targeted Therapy Conjugate. Agreement includes a US$110m upfront payment and potential development, regulatory and commercial milestone payments, for up to a total of US$1.295bn, and royalties on net sales. | ||
Great Portland Estates (LON:GPE) (£1.33bn | SR38) | GPE has completed 30 Duke Street St James's, SW1, its prime St James's development, on time and on budget, with all office and retail space pre let ahead of completion. Successful leasing campaign secured average rents 6.7% ahead of ERV, supporting an anticipated development profit on cost of 37.1% and an ungeared IRR of 30.5%. | ||
Breedon (LON:BREE) (£1.13bn | SR78) | Members of Parliament have backed Breedon's policy asks for Government to provide greater support for UK domestic cement production. | ||
Tungsten West (LON:TUN) (£654m | SR36) | Operating loss of £7.9m (2025: operating loss of £19m). Year-end cash and cash equivalents increased to £25.5 million (2025: £0.02 million), driven predominantly by the company's funding activities. Remains on-track and on budget for full commissioning in Q1 2027. | ||
Acceler8 Ventures (LON:AC8) (£632m | SR21) | Group loss after tax was £1,223,732 (H1 2025: £70,997). Group loss per share was £1.63 (H1 2025: £0.09). Cash balance was £1,061,240 (31 December 2025: £209,224). Acquired IIG on 13 August. | ||
Galliford Try Holdings (LON:GFRD) (£599m | SR85) | Galliford Try Appointed to £110 Million River Mease Improvement Project | Environment business has been appointed to a £110m contract to deliver the River Mease Improvement project on behalf of Severn Trent Water. | |
Iqe (LON:IQE) (£586m | SR34) | Purchase agreement with Quintessent Inc. for the supply of Quantum Dot Laser epitaxy. No numbers given and no reference to expectations. | ||
Hilton Food (LON:HFG) (£568m | SR93) | Volume +2.1%, revenue from continuing operations +11.5%. Adjusted operating profit -6.6% at constant FX (£45.8m). “We now expect full year adjusted profit before tax from continuing operations in the range £66m-£71m. This is higher than the previous range of £60m-£65m, despite ongoing challenges in Foppen, and reflects the removal of Dalco losses and favourable year-on-year foreign currency movements.” | ||
Enquest (LON:ENQ) (£510m | SR95) | Revenue -3.5% ($530m), reported loss after tax $39.9m. Net debt $517m. Remains on track to deliver production within the guidance range set at the start of the year. | ||
Alfa Financial Software Holdings (LON:ALFA) (£485m | SR44) | Revenue +4%, operating profit -15% (£18.4m). Trading in line, on track to meet full year expectations. | ||
Seraphim Space Investment Trust (LON:SSIT) (£434m | SR89) | Monthly newsletter with updates based on publicly available information, on the Company's portfolio investments. | ||
Jadestone Energy (LON:JSE) (£196m | SR37) | Prima Energy acquired shares representing 28.3% of JSE. The shares were held by Tyrus Capital Special Situations Master Fund. | ||
Gulf Marine Services (LON:GMS) (£195m | SR72) | Confirmation from a major National Oil Company customer for the exercise of the one-year option for one of its Small-class vessels operating in the GCC region. It’s “a strong endorsement of the reliability and value GMS brings to its clients' offshore operations.” | ||
Crest Nicholson Holdings (LON:CRST) (£158m | SR36) | Trading Update on Positive Debt Reduction Progress and Revised FY26 Expectations | “Market conditions have been more subdued than expected… the Group now expects full-year completions to be in the range 1,350 to 1,400 (previous guidance 1,400 to 1,500) and for EBIT to be a loss of around £10m (previous guidance for EBIT profit of £5m to £10m).” In constructive discussions with its lenders to amend its covenants. | PROFIT WARNING (RED =) (Graham) Lower than expected net debt is excellent news, and the interim results showed the company having net assets of about £690m. Subtract intangible assets and deferred tax assets, and book value is still over £600m. In the short-term, however, there’s a liquidity risk with debts coming due including £50m of senior loan notes in August 2027, plus the large RCF which has those covenants attached and where the lenders seem to be taking their time when it comes to agreeing to waivers. |
Strategic Minerals (LON:SML) (£155m | SR46) | Definitive Agreement signed, with completion subject to conditions, including Australian Foreign Investment Review Board approval. All proceeds will be used to support the Redmoor Tungsten-Tin-Copper Project in southeast Cornwall. | ||
Camellia (LON:CAM) (£146m | SR90) | Revenue £104.6m (H1 last year: £107.7m), trading loss £5m (H1 last year: £9.6m loss). “Crop yields and realised prices for the remainder of the year continue to remain uncertain, making the full-year outcome difficult to predict.” | ||
Frontier Developments (LON:FDEV) (£145m | SR88) | Frontier Announces Collaboration with Disney for New Video Game | Has entered into an agreement with Disney to develop and publish a new game which will draw on Disney's IP. | GREEN = (Ed S) |
Tribal (LON:TRB) (£135m | SR93) | Revenue +7.1% at constant currency. Adjusted EBITDA +0.2% at constant currency. Expects to deliver revenue and adjusted EBITDA for FY26 comfortably in line with current market expectations. | AMBER/GREEN = (Graham) [no section below] | |
Eurocell (LON:ECEL) (£122m | SR83) | Revenue +6%, adjusted operating profit +10% (£11.1m). Statutory operating profit £1.7m. Net debt £93.7m. "The momentum in Q2 sales has continued into the second half and we expect to make further progress this year.” Demand in the RMI market remains subdued. | AMBER/GREEN = (Graham)
This is the type of cyclically exposed business that probably ought to trade cheaply - and it does. The ValueRank is a mighty 94. Poor organic numbers are being masked by acquisitions, but it can be argued that the poor organic performance - and declining EPS forecasts - are already priced in at a P/E multiple of only 6x. Definitely a stock for the value hunters among us - not something I’d be adding to my slightly more quality-oriented portfolio. | |
Journeo (LON:JNEO) (£92m | SR64) | Initial purchase orders totalling £1.3m from GTS Rail Operations Limited. | ||
Panthera Resources (LON:PAT) (£55m | SR26) | Audited Financial Results and Management Update for the 12 Months Ended 31 March 2026 | No revenues, loss from operations $2.7m (2025: $2.4m loss). Has raised £2.69m before expenses at a price of 17.5p per share (last night’s close 21p). | |
Everyman Media (LON:EMAN) (£52m | SR56) | Revenue +23.5%, adjusted PBT £0.1m (H1 last year: £2.7m loss). Statutory PBT £1.9m (H1 last year: £3.4m loss). Net bank debt £17.4m. “While trading performance has been positive for the first half, the Directors retain a degree of caution for the full year outlook due to the challenging economic environment and the significance of Q4 trading to the overall annual performance of the Company.” Discussions re: cancellation/delisting not mentioned. | RED= (Graham) [no section below] The elephant in the room is that Everyman is threatening to delist, but that doesn't even get a mention in today's interim results, which seems strange to me. The results themselves are excellent by Everyman's standards: net bank debt has fallen in H1 and is down by £7m year-on-year to £17m. Adjusted profits are at breakeven (previously loss-making) after revenues surged 23.5%, and that's before the release of Christopher Nolan's The Odyssey along with a very strong slate of other films lined up for H2. But for the time being, I'm staying RED on this: it's still not a financially proven business model, and I'm concerned that even if it does succeed, it will do as a private business, after the major shareholders delist it. | |
East Star Resources (LON:EST) (£37m | SR14) | “Based on these results, we look forward to continuing to progress the Snowy Target for a potential low sulphidation epithermal deposit. The target sits between two known gold deposits of similar mineralisation and with gold samples at surface it remains a compelling target.” | ||
Sealand Capital Galaxy (LON:SCGL) (£36m | SR13) | Launches MercuryGlitter, a new AI-generated content platform designed to help businesses create and manage high-quality content. | ||
Synectics (LON:SNX) (£34m | SR66) | Contracts with an aggregate value of £1.4 million to provide on-vehicle surveillance technology for 220 new buses being introduced by a UK regional authority. No reference to any impact on market expectations. | ||
Edx Medical (LON:EDX) (£34m | SR0) | Revenue £330k, operating loss £5.8m. As we continue to pursue our strategic goals we increasingly see both consumers and healthcare professionals embracing the new tools and technologies being pioneered by EDX. | ||
Renalytix (LON:RENX) (£18m | SR0) | Conditionally raised gross proceeds of £10.1 million by way of a successful Placing and Subscription. | ||
Zinc Media (LON:ZIN) (£17m | SR35) | Zinc commissioned to produce a 90-minute feature film for a leading institution in the Middle East, with a contract value of $6.1m. |
Graham's Section
Crest Nicholson Holdings (LON:CRST)
Down 9% at 55.7p (£143m) - Trading Update - Graham - RED =
Roland was RED on this in April on the day of a very serious profit warning that saw the share price collapse 39%. Profit guidance was cut 79% and we learned that the company was in talks to relax its lending covenants.
Today’s trading update offers little relief. At least net debt has improved: it is “now expected to be better than previously indicated and lie in the range of £70 to £90m an improvement of c. £30m (previous guidance of £100m to £120m)”
But is it improving quickly enough?
The Group remains in constructive discussions with its lenders to amend its covenants and ensure that it has an appropriate level of funding and liquidity going forwards, although the Group now anticipates some slippage in the current timetable and will provide a further market update in due course.
“Some slippage in the current timetable” sounds pretty grim. When it comes to debt that’s in danger of entering technical default, any problem is potentially very serious.
The interim results, published in July, included a going concern warning, due to the company’s difficulty meeting covenants. Crest had received a temporary waiver in relation to the covenant measuring its interest cover ratio (earnings / interest expenses).
Given the collapse in the company’s earnings, it’s not too surprising that this covenant is the one that’s causing problems.
And in hindsight, it’s pretty obvious that a cyclical business is going to have trouble with its earnings-based covenants in a downturn.
Let’s turn to today’s full year profit guidance:
Market conditions have been more subdued than expected through the seasonally quieter summer trading period, with affordability constraints and competitive pricing continuing to weigh on open market sales rates…
Against this backdrop, the Group now expects full-year completions to be in the range 1,350 to 1,400 (previous guidance 1,400 to 1,500) and for EBIT to be a loss of around £10m (previous guidance for EBIT profit of £5m to £10m). The reduction in profitability reflects lower expected completions following weaker open-market demand, and continued competitive pricing, particularly in bulk transactions, also resulting in some further NRV provisions on a small number of sites.
Graham’s view
Lower than expected net debt is excellent news, and the interim results showed the company having net assets of about £690m. Subtract intangible assets and deferred tax assets, and book value is still over £600m.
In the short-term, however, there’s a liquidity risk with debts coming due including £50m of senior loan notes in August 2027, plus the large RCF which has those covenants attached and where the lenders seem to be taking their time when it comes to agreeing to waivers
I’m staying RED on this, of course. I could quickly change my tune if the balance sheet problems were solved, but for now there’s a real danger that the value of the equity could get permanently impaired here, e.g. with a highly dilutive fundraising.
Eurocell (LON:ECEL)
Down 2% at 121p (£120m) - Half Year Report - Graham - AMBER/GREEN =
Eurocell plc, the leading UK manufacturer and distributor of door and window products to the trade, today announces its results for the six months ended 30 June 2026.
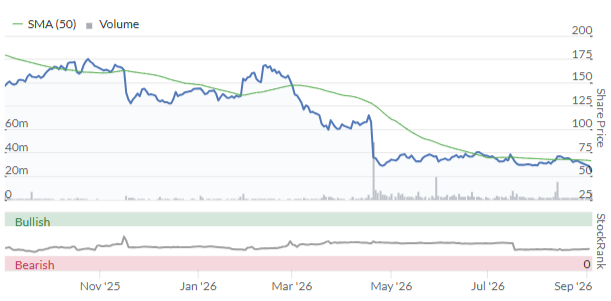
This one has seen its momentum improve in recent months. Mark was moderately positive on it in May:
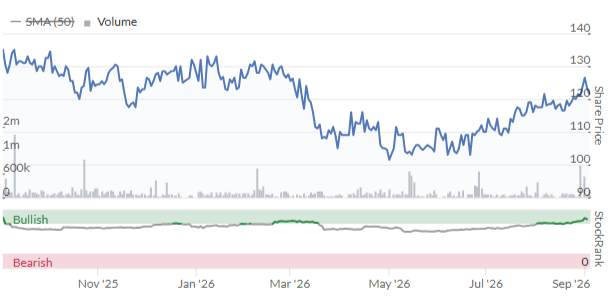
On a day when a housebuilder has issued a profit warning, perhaps it’s helpful to see how a manufacturer of door and window products is doing.
Half-year highlights:
Sales up 6%, or just 1% organically, excluding the acquired Alunet business.
Adjusted operating profit up 10% (not organic) from £10.1m to £11.1m.
In the CFO’s divisional review, we are told that Alunet’s adjusted operating profit was £4m. So take that out of the group result, and you get a year-on-year decline.
The core “Profiles” division, for example, saw revenues decline 6% and adjusted operating fall 24%, to £6.3m. This seems very consistent with a weak housing market.
The commentary on Profiles, for example, includes the following:
We have seen an increasingly challenging market backdrop for new build housing and reduced RMI activity through our trade fabricators. Investor optimism for a housing market recovery in 2026 has faded, with mortgage rates remaining at elevated levels, keeping a headwind on customer affordability. This has been compounded by rising energy costs due to events in the Middle East, with build-cost inflation now running well ahead of house price growth.
The new CEO (since February) describes it as a “robust” performance in the context of weak trading conditions. He pointedly says that prospects are attractive in the medium and long-term - this is what CEOs say when the short-term outlook is poor:
The momentum in Q2 sales has continued into the second half and we expect to make further progress this year. The medium and long-term prospects for the UK construction market remain attractive, and we are well positioned to drive sustainable growth in shareholder value."
Balance sheet/net debt
Net debt is £28.1m before leases (£93.7m including lease). “We operate comfortably within the terms of the facility and in compliance with our financial covenants.”
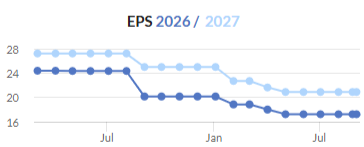
The full year net profit forecast is about £17m this year and £20m next year, so I can believe that they are comfortably within covenants. The balance sheet as a whole has a tangible net worth of nearly £60m.
Graham’s view
This is the type of cyclically exposed business that probably ought to trade cheaply - and it does.
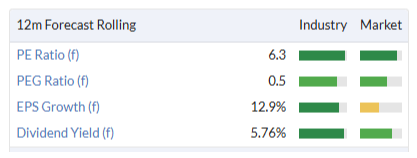
The ValueRank is a mighty 94.
As Eurocell appears to be navigating difficult conditions in a reasonable way, I can see why we’ve been AMBER/GREEN.
Poor organic numbers are being masked by acquisitions, but it can be argued that the poor organic performance - and declining EPS forecasts - are already priced in at a P/E multiple of only 6x.
Definitely a stock for the value hunters among us - not something I’d be adding to my slightly more quality-oriented portfolio
Ed's Section
Jet2 (LON:JET2)
Up 3% at 1,505p (£2.8bn) - AGM trading update and intended move to the Main Market - Ed S - AMBER/GREEN =
Jet2 – the UK's leading provider of package holidays and third-largest airline – has provided a trading update ahead of its AGM later today.
Trading performance:
The group has seen ‘sustained demand’ since its Preliminary Results on 8 July 2026.
Summer 2026 seat capacity is 7.6% higher than Summer 2025 at 19.9m seats, with booked-to-date passengers up 8.8% and growth across both package holiday and flight-only products.
Combined booked average load factor to the end of August was 1.5ppts ahead of the prior year, reflecting disciplined capacity management, targeted investment in load factor and underpinned by attractive pricing.
London Gatwick operation continues to perform ahead of initial expectations, supported by a stronger-than-expected package holiday mix.
Winter 2026/27 on-sale seat capacity is 8.0% higher than Winter 2025/26 at 5.9m seats.
Fuel and foreign exchange hedging positions provide protection for the current financial year: 93% of full-year jet fuel requirement now hedged at an average price of $753 and over 90% of foreign exchange also hedged, delivering a high degree of cost certainty.
"We have been encouraged by the sustained level of demand for both our holiday products through the peak summer season which gives us confidence for the remainder of the financial year.”
Intended move to the Main Market:
The company has also announced that it is planning to move its shares from AIM to the Main Market. It expects this move to occur before the end of its current financial year.
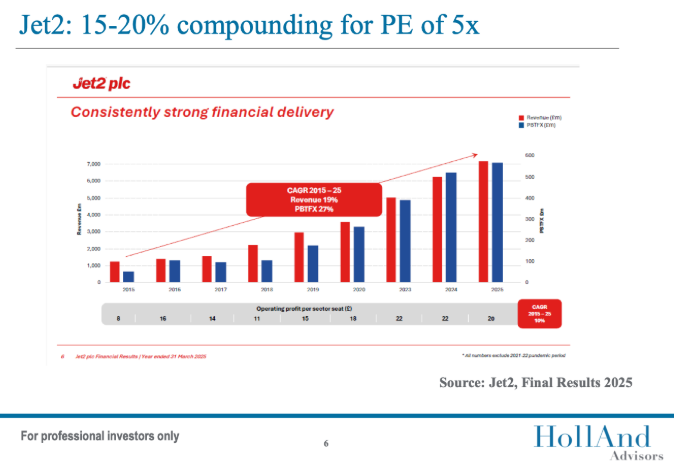
“Over the past decade, the Group has established itself as the UK's leading tour operator and third-largest airline. Today, more than 90% of the UK population is within a 90-minute drive of one of our 14 UK bases and customer satisfaction consistently exceeds 90%. This growth has been achieved alongside strong financial performance, with Group revenue increasing at a compound annual growth rate of 19%.”
“To reflect this track record of growth, the Board of Jet2 has agreed that now is the right time to move to the Main Market. Whilst acknowledging the highly important role AIM has played in supporting the Group's development over many years, the Board believes the intended move represents a natural next step in Jet2's development. It reflects the Group's scale, continued evolution, strong track record and the Board's confidence in its long-term growth prospects, whilst providing a platform to support its future development and enhance its visibility with a broader range of UK and international institutional investors.”
Ed S’s view:
I’m always a little wary of airline stocks. This quote from Warren Buffett comes to mind: "The worst sort of business is one that grows rapidly, requires significant capital to engender the growth, and then earns little or no money. Think airlines.”
But obviously this is far more than just an airline. Today, Jet2 is the UK’s leading provider of package holidays, and consumers love the company (4.3 rating on Trustpilot versus 1.3 for Ryanair).
And when you dig deeper, the business starts to look very interesting from an investment perspective. Not only does it have an exceptional growth track record (see the slide below from Holland Advisors – where it was their largest portfolio holding at the end of July), but it also generates a consistently high return on capital employed (ROCE), sports a strong balance sheet, has rising dividends, and does buybacks.
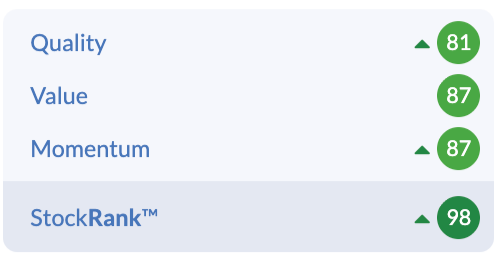
Additionally, Stockopedia’s quant systems rate the stock highly. Currently, it has a StockRank of 98 and a ‘Super Stock’ rating.
In terms of today’s update, there are numerous positives:
Sustained demand with booked-to-date passengers up 8.8% and growth across both package holiday and flight-only products.
Combined booked average load factor to the end of August was 1.5ppts ahead of the prior year.
Fuel and FX have been well managed.
The intended move to the Main Market – this should widen the shareholder base and lead to more interest in the stock (it should join the FTSE 250 at some stage).
One thing worth highlighting is that customers have continued to book closer to departure throughout the peak summer period. What does this tell us?
Well it could signal that UK households are a little stretched for cash and delaying major discretionary purchases. They could be hoping to land last-minute deals.
Overall though, the company is seeing solid demand at present. It seems consumers are prioritising travel spending at the moment and cutting back on other areas of discretionary spending (e.g. sports shoes and apparel).
Cashed-up retirees / Baby Boomers are probably also supporting demand. For this demographic, travel is often a high priority.
Back in July, we gave Jet2 an AMBER/GREEN and I’m going to leave the stock at that rating today. There are some risks around demand in the current environment but with the stock trading on a forward-looking P/E ratio of just 11 (falling to 7.5 using next year’s EPS forecast), I’m cautiously optimistic in relation to the outlook here.
Frontier Developments (LON:FDEV)
Up 9% at 445p (£145m) - Frontier Announces Collaboration with Disney for New Video Game - Ed S - GREEN =
British video game developer and publisher Frontier Developments has today announced that it has entered into an agreement with Disney to develop and publish a new game that will draw on Disney's iconic portfolio of IP.
We don’t get a lot of details but the company says that the game will be fully funded by Frontier and will build upon its extensive experience and proven capabilities as a leader in the Creative Management Simulation (CMS) genre; which includes the Planet Coaster, Planet Zoo, and Jurassic World Evolution franchises, as well as an unannounced Planet game currently in development.
"We are delighted to announce this collaboration with Disney, which further reinforces our clearly defined strategy of developing and nurturing world-class creative management simulation game franchises. Our mission with this game is to connect a passionate creative community of players with one of the world's most iconic and beloved brands, and I can't wait to see what our talented teams will create with this amazing opportunity."
Ed S’s view:
Roland and Graham have both awarded this stock a GREEN rating this year and I’m happy to reiterate that stance today. I see this morning’s update as positive and the market does too – the share price is up 9% as I write.
This stock has been on a wild ride over the last decade. During the Covid tech boom it shot up spectacularly, however, it has since experienced a massive fall.
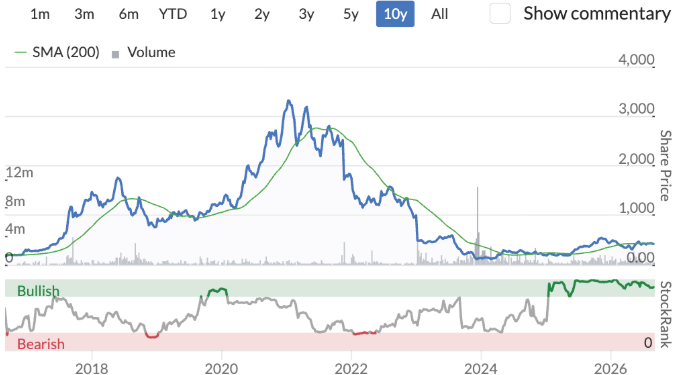
Today, the risk-reward set-up looks relatively attractive, in my view. Back in June, the company posted a good trading update in which revenue for the year ended 31 May was up 16% and adjusted operating profit was up 44%.
The outlook at the time was:
FY27 is expected to start positively, supported by Jurassic World Evolution 3 joining Microsoft's Game Pass subscription service on 2 June 2026, the upcoming Jurassic World Rebirth expansion on 16 June, and expected portfolio sales ahead of the summer promotional period.
Alongside continued revenue contributions from existing games, FY27 performance will be driven by the release of Planet Zoo 2 and Warhammer 40,000: Chaos Gate - Deathwatch. The Board has been encouraged by the positive reception to the announcements of these games and is confident in delivering FY27 in line with its expectations.
At the end of May, Frontier had cash of £44m so its balance sheet is strong. This is allowing it to buy back shares.
Turning to the valuation, it seems reasonable. Currently, the trailing P/E ratio is only about 12.
As for the StockRank, it's 88, which is decent. It’s worth pointing out, however, that the StockRank was 92 back in June.
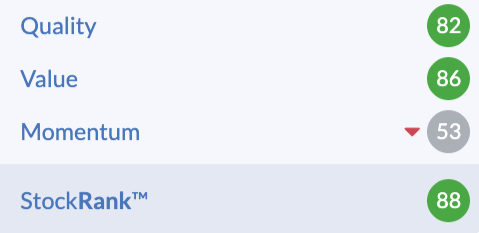
One thing worth flagging is that analysts don’t expect any top- or bottom-line growth this financial year. Looking at forecasts, revenue is expected to be relatively flat while EPS is projected to fall 18%.
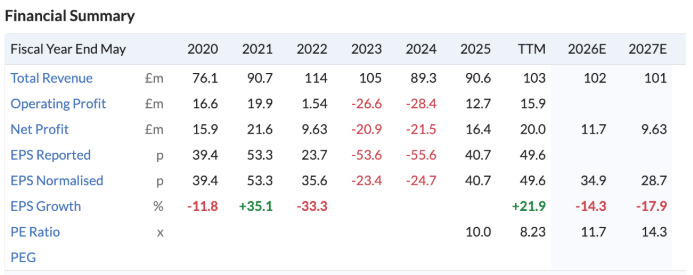
That’s not ideal (Graham pointed out in June that revenues here tend to be lumpy). Having said that, this backdrop could pave the way for a top and/or bottom line beat if business performance remains strong
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

47 comments
Re : Crest Nicholson and Housing Market
Some of the key points in the announcement are a bit glossed over. The important phrase which need some further clarification is ...
"continued competitive pricing, particularly in bulk transactions,"
Various reports suggest that bulk discounts could be in the order of 15 to 20%. What percentage of stock that is currently bulk sold is unclear. More information on the scale of the disposals and what the future assumptions are for bulk sales would be helpful.
Something else that is coming down the track is the class action lawsuit which could see many of the housebuilders on the hook for total figure of £2.2 to 4.5 billion. Crest is not one of them.
https://www.theguardian.com/bu...
I had been following the housing market for recovery but now see it as far too dangerous.
Crest - no position
I'm still in Persimmon (LON:PSN) and Taylor Wimpey (LON:TW.) and hoping the Burnham Government will throw cash at them like the Starmer Government did for Tungsten West (LON:TUN) .
Interesting article. Feels like the UK is becoming more and more like the US in regards to legal action over anything and everything.
I don't really understand how it's possible for them to be price fixing and then claim people are due back very tiny sums like £3k per victim.
Surely if they want to know the price of a competitors home, they can just phone up and make an enquiry like everyone else. As far as I was aware this has never been private information, it is available to the general public when making enquiries.
Perhaps there is more to it, have they price fixed like a cartel?
The information given in the article sounds a bit flimsy. I would think there needs to be more provable wrong doing than this - or is this just a legal firm going after a big pay day, and testing the waters. One to watch perhaps, but doesn't sound like an obvious multi billion class action to me.
Re Housing - Competition and Markets Investigation (not Crest Nicholson)
Metalmaid thank you for the response.
Preceding this action was a CMA investigation which raised concerns and as a result the housebuilders in question agreed to make a £100 million payment which would effectively be routed into the affordable homes program.
The link to the CMA investigation can be found below and might answer some of your questions
https://www.gov.uk/cma-cases/i...
I would guess that lawyers have gone through the CMA documentation and see an opportunity for a class action.
I have followed the housing market for a number of years but i don't see much to encourage investors at the moment, only risk and uncertainty at every juncture. This class action is just another problem for a weak sector to deal with.
FAOD - Crest Nicholson has not been named in the class action and was not one of the housebuilders who had to contribute to the £100 million payment.
EDIT -for some reason the above link might not work and cant be corrected. Might need to search for the case - should be easy to find.
Many thanks intuitive6191 for your considered repose. I certainly agree with you in this regard.
I have followed the housing market for a number of years but i don't see much to encourage investors at the moment, only risk and uncertainty at every juncture. This class action is just another problem for a weak sector to deal with.
Interesting article. Feels like the UK is becoming more and more like the US in regards to legal action over anything and everything.
lol and there was me thinking how do teh regulators let stuff like this fester before taking action - there is very little morals used by those that run housebuilders - i know that buisness aint run on morals - but if you ask them they will pretend they are acting with transparency and fariness - the reality well.
I don't really understand how it's possible for them to be price fixing and then claim people are due back very tiny sums like £3k per victim.
well you have to settle at something if you dont want like 15 year legal battle - even if legal battle was won would most of the proceeds go to peopel or the gov.
The information given in the article sounds a bit flimsy. I would think there needs to be more provable wrong doing than this - or is this just a legal firm going after a big pay day, and testing the waters. One to watch perhaps, but doesn't sound like an obvious multi billion class action to me.
it could be flimsy - but did you read the article ? if they had done nothing wrong why did they hand over £100 mill to make then problem "go away" - hmmmm lest think why.
The class action comes after a Competition and Markets Authority (CMA) investigation into the sector which found evidence that companies might be sharing commercially sensitive details that affected the price of homes.
The watchdog settled last year, securing binding commitments from the seven housebuilders not to share sensitive pricing information. The firms also agreed to pay £100m to affordable housing schemes.
I would say there is a big difference between the £100m payment, and a multi billion class action. I did read the article and didn't feel that the information presented warranted such a class action (although clearly there may be more to it that is not stated in the article).
I respect your right to your opinion - and that's fine if you believe the regulators should be doing more. Personally I felt that the accusations sounded a bit flimsy, the article was unwilling or unable to give specific details of wrong doing. The claims that they made, imo sounds like information that is already available with a small amount of effort.
The idea that the countries biggest house builders don't know what each other are doing is imo a naïve view. Of course they know what they're charging for a home, of course they know what materials are used and what land costs etc. they speak to supply companies, labourers and management and of course they are absorbed into the industry and have a very good idea of all aspects of their competition (land costs, building materials, everything!) - they would be pretty crap at their jobs if they didn't know in extreme detail how their sector and competition worked.
So unless you can state clearly what they have actually done that is so bad that it is equal to a multi billion class action then I stand by my point. Asking me whether I have even read the article is pretty insulting. You might not agree with me, but you always seem to want to have a dig at people who's opinion differs from your own. I won't insult you by asking if you have read the article, but I will remind you that the article is concluded with the following -
Anthony Codling, housing analyst at RBC Capital Markets, said: “We believe that homebuilders are price takers not price setters and compete against the much larger existing homes market. In our view the claim is difficult to prove, and we note that the CMA’s recent investigation into housebuilders did not conclude that the competition act had been infringed.”
In regards to the £3k to £6k compensation. If the average house price was say £250k, then we are talking about maybe 2%. This amount is less than what many people would negotiate as a discount in anything but a strong market. People are not forced to buy a home - there is no gun to their head. Supply and demand do exist, regardless of what some lawyers might claim. From 2014 to 2021 - house prices went up a lot. This is not due to price fixing - this was obviously due to high demand and low supply - something the article wants to deny exists!
If serious wrong doing has been done then of course they should be held to account and the industry should be cleaned up in that regard. If this is the case then obviously there is a lot more detail that we are not aware of. However, it is also possible that this is a legal firm trying it on, maybe believing they can scare them into a settlement and a fat payday.
As I said, its an interesting situation and one to keep an eye on. If serious wrong doing has occurred then action should be taken. However, if this is just a lawyer bandwagon attempt, then it should be called out for what it is. The housing market is obviously in a real mess at the moment. I would say its in need of stimulus (a view most people share), and a trumped up baseless class action (if that's what this is) is really most unwelcome given their current circumstances.
Thanks for your comments Metalaid
Asking me whether I have even read the article is pretty insulting.
you can take my quetion as insult if you want to thats on you - no insult was meant it was simply a question i diswnt know the answer to.
The idea that the countries biggest house builders don't know what each other are doing is imo a naïve view.
so unless you can state clearly what they have actually done that is so bad that it is equal to a multi billion class action then I stand by my point.
The reason for my question was that the investigation was raised due to real evidence that the housebuilders had been directly exchanging data thats different from gaining data from third party sources - that in itself may not prove guilt but lets not pretend that where there could be cartel type behaviour from small number of big boy players that its "normal" to share your data with competitors - its most certainly not normal to do that.
If the companies were 100% in the clean is it plausible they would just chuck £100 million into a government pot on the gareemnt that this was shut down and no fruther details released. I dont know if they paid the £100 mill to close the case but in the absence of any info to the contrary it all seems most likley they agreed to pay then £100 mill on thne basis no questions were asked.
I agree that none of this is firm evidence that they owe any compensation to customers - but its clear they have made a rod for their own back if the CMA are right that data sharing went on - "if they are clean" simply paying to get no further questions asked looks sketchy - why not just let the CMA clear them of any wrongdoing.
I kinda agree with your summary position that there is no proof ref the ambulance chaser stuf having realistic propsects of success - but i firmly stand by my comments that there were serious questions that were asked and these seem to have been swept under the carpet with payment of cash that loks like ikt shut it down. I would agree often these ambulance chasers may just be trying it on
https://www.gov.uk/government/...
The Competition and Markets Authority (CMA) launched an investigation last year following concerns that 7 housing developers – Barratt Redrow, Bellway, Berkeley Group, Bloor Homes, Persimmon, Taylor Wimpey and Vistry – exchanged details about sales including pricing, number of property viewings and incentives offered to buyers such as upgraded kitchens or stamp duty contributions.
per copilot
What the CMA found in 2024
The CMA's February 2024 Housebuilding Market Study stated that it had found evidence suggesting that some housebuilders may have been exchanging commercially sensitive information, including:
sale prices,
rates of sale,
incentives offered to buyers,
other commercially sensitive sales data.
This evidence was significant enough that the CMA immediately opened a separate Competition Act investigation into eight housebuilders.
The CMA expressly stated that there was evidence suggesting housebuilders "may be sharing information with their competitors".
Why competition lawyers care about information sharing
In competition law, you do not need a written agreement saying "let's fix prices".
Exchanging current, non-public information about:
achieved selling prices,
discounts,
incentives,
sales rates,
can reduce uncertainty between competitors and make coordinated behaviour easier even without an explicit cartel agreement. This is why regulators often prosecute information exchange cases separately from classic price-fixing cartels.
The CMA's concern was therefore not merely that housebuilders attended the same trade events. The concern was that they may have shared data that competitors would normally be expected to keep confidential.
Rentguarantor Holdings (LON:RGG)
A couple of very clever financial analysts have suggested the possible material non-compliance with IFRS on disclosure of credit risk.
All the best
Hi Yiannos1, Do you have a source please? Kind regards El
Tom Winnifrith (shareprophets.com)
Paid subscription service.
All the best
much appreciated Yiannos
I have now read the article which is written by one person, Tom Winnifrith, the founder of Share Prophets. While he has no accountancy or financial qualifications he is an experienced financial journalist.
I shall be following the story with interest as I’m a RentG shareholder. It will be interesting to see if the FRC do decide to investigate his concerns & if they do, what they then say (though it will take time if they do as they’re not known for being speedy)
A fellow shareholder spoke to Paul Foy, CEO of RentG, & he’s robustly denying any non-compliance
I think Tom has made it very clear that Rentguarantor Holdings (LON:RGG) is in no financial distress and generating FCF.
He has an extensive financial knowledge-one of the best I came across.
I hold a few shares as well (not much-wish I did!).
I don’t think the FRC will get involved, but trading at10x+ sales now, probably this is the right time to exit.
All the best
Tungsten West (LON:TUN) (No position)
Graham/Ed, is there any chance that you could analyse this one today?
Yesterday I was listening to one of Jonathan Davis Money Maker's podcasts - he was interviewing Charlotte Cuthbertson and Tom Treanor from MIGO Opportunities Trust.
One of the trusts they hold is Baker Steel Resources, which had a large holding in Tungsten West (according to Stockopedia this has now been more than halved).
Baker Steel Resources Trust (LON:BSRT) has done well out of Tungsten West - I'm wondering if there's anything left to be gained?
Most Tungsten is mined in China. Tungsten West is small globally, but significant in terms of secure supply for the West.
Thanks for the request Richard but Tungsten is too far out of my/our wheelhouse. Sorry about that. G
There was a lot of media coverage last week. In summary it is considered a high-risk investment. I do not mind a degree of risk, but this in conclusion was too high for me. And given BSRT have 23% in TUN I would say similar applies. Cornish Metals (LON:TIN) is also re-opening.
I'm a fan Richard and would refer you to OakBloke on Substack for a more elaborate perspective on Tungsten West (LON:TUN) . I disagree with Charles on risk as the Govt have just coughed up £71m to take a stake and get it to production, which was a significant concern. They are also negotiating an offtake agreement for I believe half their estimated output. That is the next potential derisking. I hold through Baker Steel Resources Trust (LON:BSRT) as also like some of their other holdings and it spreads my risk.
Best of luck whatever you choose to do.
Thanks for that sevenccc! I will check out Oak Bloke's commentary.
More broadly, IMHO there is a 'resource war' going on and the West needs to secure its supplies of critical minerals and energy. I don't know how to pick out individual mining stocks so I hold BlackRock World Mining Trust (LON:BRWM) to cover some of this gap.
I'm sure there are ETFs that will probably cover much of this too.
Large jump in SR by Cairn Homes (LON:CRN) to 99 from 78.
That is probably because the forecast figures were updated yesterday but l thought Stockopedia only worked on the actual results, not company forecasts?
Cairn Homes (LON:CRN) I see the interims results were also out yesterday.
Positive, if a little limited, announcement from Frontier Developments (LON:FDEV) today, shares so far reacting well, up 9%. I hold, but they do look good value on a PE of 8.2 x, with trading seemingly holding up. Perhaps due a run?
IG group (LON:IGG)
I take Graham's point re Underdog and posted comment on the predictions market where Nevada kicked back. No idea if this is a read across but like Meme investing it seems Generation Z are well into this. Maybe I am just not up with the hip kids!!! I remain a skeptic on this far more than my generally favoured view of Tasty Trade ( at least it was a business that fitted with IG existing activities) given i am generally uncomfortable with conflicts of interest that clearly were in play
Let's hope I am wrong the fall in the market capitalisation since it was announced means Mr Market gives a big thumbs down
Graham mentions Ed Sheldon's article on Volex so it is a good time to note the FTSE changes announced after the close yesterday:
And now - Jet2 (LON:JET2) will jump into the 250
There's a profit warning from Crest Nicholson Holdings (LON:CRST) this morning. This does not bode well for the house building sector.
Hi John
No real surprise given Crest and Vistry are really hospital cases. Reading the announcements from Crest in recent months is an education in how not to run a housebuilder. Maybe not quite as awful for housebuilders ( note Cairn although it is Irish has had a stocko push to above 90) as this would imply. Sadly the industry needs either incentives or for affordability at a time when energy bills are going one way to come to its rescue. Not time to buy the sector as yet me thinks..........
Crest Nicholson Holdings (LON:CRST) - yes a few signs of distress appearing in the housebuilding sector. There are lots of incentives being offered - reduced stamp duty, part-exchange, price reductions but most housebuilders are still struggling to shift houses. It feels a bit like 2008 to me! The sector is interesting, but not until interest rates have peaked and we are not quite there yet by the looks of things.
We've held Eurocell since it's launch in 2015, some judicious adding has us just into profit on yesterday's close but are we holding an Ed's Bowl, or a colander? Adjusted results seem ok but statutory ones less so. I welcome the dividend rise and share count drop but I noticed 8% holder Welcome Trust dropped to just under 8% a few days ago which is rarely a good sign. Mark left it at Amber Green 14/5/26. Expert observations much appreciated if you have time Graham.
Eurocell (LON:ECEL)
i hold this - kinda shoved into buying this when similar company i have forgotted the name of was taken out - metric here were almost the same so it was an easy decision to invest gaisn here.
At present i would say its all very anemic from them - structurally there is kinda no sign of much if any organic growth ignoring Alunet - they are probably doing the best they can though and Alunet kinda saves their bacon ref overall numbers. Debt is still kinda chunky but if current forecasts are to believed they are trending in right direction. At present though i would say 2027 forecasts look a stretch without bought in profits. i am perhaps being a bit harsh here - operationally i think managemnt do a good job with what they have.
but statutory ones less so.
the majority of the exceptionals (2/3 ish ) are non cash asset impairments - i will kinda happily ignore that - its kinds cheating though if w/off flatters future results with less amortisation or depreciation in future years - as its non cash it doesnt really matter thouugh and stuff like this is standard fare.
pe is cheap as chips here so no reason not to carry on holding - share price has gone nowhere but i do get the dividend to compensate so i cant really complain.
Yeah I looked at this several moons ago when the birth/reincaration of the building industry was in it infancy ( i.e. before Rayner was sacked by Starmer) given a likely beneficiary from ' massive' building etc . My view was management doing all the right things but borrowings too high and it was duly lowly rated.
If I was a bull of housebuilders at the moment ( duh) may be inclined to look again but i like others better. Nice yield....
Eurocell (LON:ECEL)
but borrowings too high
I wouldnt say they are too high particulalry for me (i wont argue with anyone who steers clear though due to debt) more just noteworthy to me - its currently high due to the recent Alunet acquisition plus their buyback and dividend plans dont aid it dropping uber fast. Generally though they do have good cashflow profile so i dont particulalry ever see cashflow being a problem if they deliver decent profits.
ref buyback with cheap pe i am all for that at present. So debt is imho very mangeable and they could probably clear in under 2 years if they wanted to. It does though perhaps give them less flexibility ref say another chunky acqquisition - and the debt would hurt more if profits started trending down.
rmillaree - The name you have forgotten is Epwin I think
indeed it is thanks for that.
Took a look at Eurocell, JASVFS. Cheap as chips! There are good reasons for the cheapness, of course... it's not my cup of tea but I can see why some people would be tempted. G
Good morning Graham,
Tribal (LON:TRB) half-year results are out today. If possible, could you add it to your list of deep-dives please?
Not a deep dive but I've taken a quick look at Tribal, Felix. On a superficial view I think it's undervalued here, but I'd be curious to know what the bear case is. Clearly it's not expected to grow much in the short-term. G
Its good to see that "ROSEBANK TRADING AHEAD OF RECENTLY UPGRADED FULL YEAR 2026 EXPECTATIONS" today. After quite a long quiet spell for the ROSE.L share price, perhaps this will be the trigger to initiate new momentum.
Lets hope so. Great to see debt coming down far quicker then expected and the payment of a small dividend too. Revenues in the main are increasing, along with margins and a reduction in costs. All looks good to me.
Ditto from me I am a ' bit of a Fanboy' of the management team so yes it has been dull recently but cannot see a wrong step here. If 60% of the success of Melrose is repeated I for one am a happy camper.....
Jet2 AGM statement reads well (reaffirms positive trading pattern) with Gatwick progressing "ahead of expectations". Increased winter capacity mostly through Gatwick. Fuel and FX hedged reduces uncertainty. Move to the main market should be positive.
IMO This seems to be a well run company with a simple ethos of providing excellent service. I hold.
I'd appreciate comments from the team.
Jet2 (LON:JET2) good update. Sales up, capacity up. Note to self - should have bought at 1100p. Doh!
I'm surprised that consumer discresionary is doing well. Maybe this is the aging population spending?
As they say, you can't take it with you!
Jet2 (LON:JET2)
I'm surprised that consumer discresionary is doing well. Maybe this is the aging population spending?
Todays update has to be seen in the context of the company having earlier in the year having dropped proft expectations (for this year only i may add) by over 1/3 - so the tough times are kinda alkready factored in by them reducing the expectations to the floor.
Perhaps you are reading too much if you are worrying about consumers spending - for most people holiday is a priority and although we all moan holidaays still seem pretty good value to me compared to other stuff which seems to have shot up in price more. certainly the lucky oldies who can downsize on their house and go out spending are an obviously bouyant % of the customer base. I worry more about price wars and fule than i do consumers putting their hands in their pockets.
Jet2 (LON:JET2) JET2
Being frank its an anooying date - hate any company that simply waffles and doesnt cross reference exactly where they are compared to prior guidance - i think they did earlier when the eps forecasts for this year like halved (whilst upping prior year) - just ridiculous if i am being frank. Perhaps a change to the main markey might help - albeit saga are similar so i wont hole my breath.
Ignoring my gripes update today seems all well and good at face value - main market move makes sense - and the confirmation of increased capacity for next year is good - thats all this company needs to do sell more seats and maintain margins.
Not over convinced its gonna be plain sailing ref propspects and profits - specifically ref margins - i think they have had a mild purple since covid withou other firms being over aggressive ref expansion - last thing any of these companies needs is a price war and high oil prices cant be good either.
Its an extremely solid hold for me at present though.