Daily Stock Market Report (Tue 1 July 2025) - SBRY, MPAC, KITW, SUP, WYN, PAY

Good morning and welcome to today's report.
Update 13:45: that's all for today, see you tomorrow!
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
J Sainsbury (LON:SBRY) (£6.7bn) | Q1 like-for-like sales +4.7%. Continues to expect retail underlying profit c. £1bn and retail free cash flow of >£500m. | AMBER/GREEN (Roland) [no section below] A solid performance with LFL growth ahead of inflation and market share gains. The group is reallocating non-food space to higher-performing grocery, but also reports improved performance from clothing and Argos. Nectar is also doing well and is on track to launch an in-house ad network later this year. Broker ShoreCap has left forecasts unchanged today, but I think good operational momentum and a forecast FCF yield of 7.5% justify upgrading to a moderately positive view. This is also reflected in recent StockRank gains. | |
Burford Capital (LON:BUR) (£1.9bn) | A New York court has ordered Argentina to transfer its shares of YPF. A positive development. | ||
Supermarket Income REIT (LON:SUPR) (£1.1bn) | £215m term loan. SUPR will receive 50% of the proceeds. SUPR’s loan-to-value is c. 31%. | ||
PayPoint (LON:PAY) (£594m) | Second tranche of buyback programme for up to £30m, ending no later than March 2026. | AMBER/GREEN (Roland - I hold) [no section below] | |
Judges Scientific (LON:JDG) (£590m) | Will support CEO as Judges continues to execute its strategy. He was most recently at Oxford Instruments (LON:OXIG). | ||
Warehouse Reit (LON:WHR) (£480m) | “No increase” statement regarding Blackstone’s offer is no longer in effect. Considering its options. | PINK | |
Elixirr International (LON:ELIX) (£326m) | Cancelled from AIM, admitted to the main market. “Reflects our continued ambition.” | ||
CLS Holdings (LON:CLI) (£279m) | Total €41.3m. Office/industrial and office. 10% discount to Dec 2024 valuations. New LTV 47%. | ||
Kitwave (LON:KITW) (£269m) | PW. Consumer fragility. Unable to offset higher NICs. Now expects adj. operating profit £38-40.5m. | BLACK (AMBER/RED) (Megan) A weaker outlook for the seasonally important second half has sent investors scurrying. This may prove to be an over-reaction, but I am uncomfortable with the fact that this profit warning comes less than two months after a trading update which said everything was good. | |
Supreme (LON:SUP) (£241m) | Robust trading. PBT +3% (£30.9m). Positive start to FY26, trading in line with exps. FY25A EPS: 21.6p FY25E EPS: 17.9p (average of 3 estimates published today) | AMBER (Roland) This is a good set of results, but I’m reluctantly downgrading our view on Supreme. Today’s outlook and updated broker estimates suggest to me that earnings could fall by a double-digit percentage this year. There’s also continued uncertainty about the outlook for vaping sales, in my opinion. In fairness, I think the enlarged drinks and wellness business has the potential to make an improved contribution that may offset any decline in vaping over time. However, overall uncertainty means I think a neutral view is appropriate for now. | |
Synthomer (LON:SYNT) (£179m) | Agrees with banks to extend covenant relaxation to end of 2026, given weaker macro conditions. | ||
Augmentum Fintech (LON:AUGM) (£170m) | NAV per share after performance fee 161.5p (last year: 167.4p). Seeking ways to narrow discount. | ||
Mercia Asset Management (LON:MERC) (£136m) | Third-party FUM +10% to £1.8bn. Adj. op profit £10.2m (last year: £9.7m). NAV per share 43.6p. | ||
Eurasia Mining (LON:EUA) (£134m) | Rev +220% to £6.6m, net loss increased to £8.7m. NAV £12.6m. Focus on sale of Russia assets. | (RH) Results to Dec 2024 being published in July are a red flag. | |
MPAC (LON:MPAC) (£129m) | PW. Q2 orders down due tariff uncertainty. FY rev to be significantly below exps. ShoreCap FY25E adj EPS -24% to 33.5p. Buy-in for DB pension. | BLACK (AMBER/RED) (Roland) A shortfall in Q2 orders seems likely to have a significant knock-on effect. Broker notes translate today’s revenue warning into a c.25% cut to profit expectations for 2025. I’m also a little concerned by the decision to downsize US operations that were previously lauded. Mpac has a mixed track record and poor quality metrics. The StockRanks appear to have spotted a weakness in April’s results and had already downgraded the shares to a Value Trap. Given the risk of further downgrades, I’d be inclined to steer clear until some clarity emerges. | |
John Wood (LON:WG.) (£128m) (shares suspended) | Lenders have agreed to extend debt waivers to 31 July 2025. Remains in talks re. Sidara bid. | ||
Wynnstay (LON:WYN) (£85m) | Rev -7.2%, gross profit +7.1% to £42m. PBT +25% to £5.5m. On track for full year forecasts. | GREEN (Roland - I hold) [no section below] Today’s results suggest to me that Wynnstay’s turnaround and cyclical recovery under CEO Alk Brand is on track. Profitability is improved in H1, despite mixed performance on volumes. The balance sheet also remains strong, with net cash of £10.3m at the peak point for working capital (i.e. low point for cash). There’s no change to broker forecasts today. With the stock still yielding nearly 5% and trading c.25% below tangible book value, I’m happy to maintain our positive view. | |
Anexo (LON:ANX) (£81m) | Discussions with DBAY party remain ongoing. PUSU deadline extended to 5pm 15 July 25. | PINK | |
Kooth (LON:KOO) (£67m) | California DHCS has published a report into the use of Kooth’s Soluna service by 13-25 year olds. | ||
Windar Photonics (LON:WPHO) (£52m) | 2024 rev -8%, record shipments of €5.8m. EBITDA loss €0.5m, net loss €0.9m. €7.1m cash at 31 Dec. | (RH) Results to Dec 2024 being published in July are a red flag. | |
Gelion (LON:GELN) (£42m) | System now in advanced commissioning. 92.5% revenue (£900k) recognised in H1. | ||
Challenger Energy (LON:CEG) (£19m) | Sale has made “considerable progress” but not yet finalised. New longstop date 30 Aug 25. | ||
Itaconix (LON:ITX) (£15m) | BIO*Asterix can be used to replace fossil-based products used in paints, coatings & adhesives. | ||
Westminster (LON:WSG) (£12m) | Personnel screening solution for a leading global science at chemicals company at a UK site. |
Megan's Section
Kitwave (LON:KITW)
Down 25% to 238p (£268m) - Interim Results - Megan - (BLACK) AMBER/RED
It’s not the numbers being reported on in these interim results that have sent investors scurrying out of Kitwave this morning, but the outlook. After a slowdown in volumes and the additional costs arising from national insurance contributions, management has confirmed annual adjusted operating profits between £38m and £40m.
It’s worth breaking down why that is problematic.
For a start, the last update from the company was 7 May and then management suggested that everything was ticking along nicely. The bulk of that update focused on the seasonally less important first half of the year, but chief executive Ben Maxted did note the second half weighting and confirmed his confidence in the group’s ability “to meet full year expectations”.
Secondly, management has said this morning that it no longer has confidence that the £2m of additional national insurance costs can be offset. The trouble is that the market sentiment has weakened and with volume lower, the company is less likely to be able to hike prices.
The fact that it has taken less than two months for such a sharp turnaround in sentiment seems a little worrying.
Then there is the fact that the second half is seasonally so important to Kitwave. In 2024, the company reported £10.8m of operating profits in the first half and £23.2m in the second. This morning, management has reported £13.2m of operating profits in the first half, a 22% increase on the previous year. Taking the low point of current forecasts, second half operating profits could be as little as £24.8m - just a 6% improvement on the second half of last year.
And finally there are the material downgrades from brokers. Now, it wasn’t clear before today exactly what management at the company expected for the full year, but brokers at Canaccord Genuity were forecasting EBITDA of £61.1m in 2025, compared to £45.2m last year. The annual forecast has now been downgraded to £54.3m, with cuts to both FY26 and FY27 forecasts as well.
Beware the fate of multiple profit warnings
Despite management’s previous insistence that the company would be able to offset higher NI costs, brokers had already downgraded forecasts this year. Another big cut today, plus the major share price sell off will have disrupted the momentum which had recovered strongly in Q2.
Profit warnings don’t always come in threes, but the fact that this one seems to have come out of the blue doesn’t instill a great deal of confidence that management have got a grip on things.
Added to the fact that this profit warning is a reflection of fundamental weakness in the market, rather than a one-off miscalculation, and I wouldn’t be surprised if we see another disappointing announcement before the year is out.
There are also still relatively heavy adjustments going on after the slew of acquisitions made in the last few years. Reported operating profits were £10.3m, which is an operating margin of less than 3% - not a lot of wiggle room for further disappointments.
Megan’s view:
This has been a strong performer since its 2021 IPO so this morning’s announcement will no doubt be disappointing.
Following this morning’s sell-off and broker downgrades, shares are trading on 8.8x adjusted diluted forecast earnings, which looks tempting. But I would be wary of things getting worse before they get better. AMBER/RED
Roland's Section
MPAC (LON:MPAC)
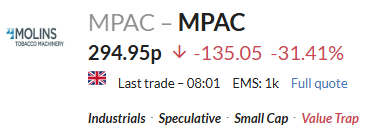
Down 26% to 318p (£95m) - Trading Update & DB Pension Update - Roland - (BLACK) AMBER/RED
This high-speed packaging and automation group has warned today that a shortfall in orders during the second quarter means that full-year revenue will now be “significantly below the Board’s previous expectations”.
Brokers have slashed their earnings forecasts for the year and the market reacted brutally in early trading:
What’s gone wrong?
Mpac says that performance during the first half of the year was in line with expectations, thanks to a strong order book in January and good performance from last year’s acquisitions.
However, the core Mpac business saw a slowdown in order intake during the second quarter. Management says this was due to uncertainty over US tariffs and low consumer confidence.
As a result, the closing order book for June is expected to be c.£90m, compared to £118.5m at the end of 2024.
The second quarter is generally an important period for this business as it lines up production volume for the second half of the year, to which profits are normally weighted.
As a result of this shortfall, management now expects FY2025 revenue to fall significantly below the Board’s previous expectations.
Net debt is now also expected to increase “marginally” from the £37.5m position reported at the end of 2024.
Unhelpfully, Mpac has not provided any comment on the expected shortfall in revenue or the likely impact on profit. The company has not included details of previous consensus estimates in today’s RNS either. All of this means that investors without access to broker notes are left in the dark.
Updated estimates
Fortunately, Shore Capital and Equity Development have both provided updated forecasts today through Research Tree – many thanks for making this coverage available.
Updated estimates suggest earnings in 2025 and 2026 will now be significantly lower than previously forecast, although I would guess the outlook beyond the current year remains uncertain and may depend on tariffs and broader macro issues.
Shore Capital:
FY25E EPS -24.6% to 33.1p (prev. 43.9p)
FY26E EPS -31.9% to 36.8p (prev. 54.1p)
Equity Development has taken a slightly more bullish view on prospects for 2026:
FY25E EPS -29% to 32.2p (prev. 45.1p)
FY26E EPS -22% to 42.9p (prev. 54.7p)
US restructuring
To address low capacity utilisation in the US, Mpac is planning to close its Cleveland Ohio factory and consolidate its operations to its Boston location, which was acquired in 2024. Capacity is also being cut at a location in Canada.
This restructuring is expected to incur a non-cash impairment charge of c.£11.5m. I assume there will be cash costs too, but these aren’t mentioned today.
However, assuming the changes are executed successfully and Mpac retains sufficient capacity, the reduced cost base resulting from these changes could result in stronger positive operating leverage when demand does recover.
UK Pension Buy-In
Mpac has agreed a pension buy in transaction with Aviva (I hold) for £249m. No further contributions will be needed and the company expects to receive a surplus of £5m when the buy out is completed (around two years).
Roland’s view
Mpac’s position seems to be that the company has maintained its market share, but that customers just aren’t buying. Time will tell if this is true, but near-term profitability seems likely to take a serious hit as a result of this disruption to order flow.
I don’t know the history of the group’s North American operations, but I’m a little surprised they are being downsized so quickly. Today’s update talks about taking the opportunity to “accelerate its plans to consolidate its operational footprint in the US”.
However, checking back to the full-year results (published just two months ago, at the end of April), I don’t find any mention of this. Instead, the company talks about the opportunity created by its enlarged manufacturing footprint:
Notably, the expanded operational footprint of the Group now includes two build facilities in the US, along with facilities in Europe, Canada and the UK, positioning Mpac well to respond flexibly to these long-term trends.
I may have missed something, as I don’t follow this company in detail. But the comment above doesn’t suggest to me that Mpac was thinking of consolidating its US operations at that time.
This leaves me wondering if today’s decision to close the Ohio plant is actually being driven by fears of a prolonged loss of business in the US, or perhaps by cost/debt concerns.
Today’s share price fall largely reflects the reduction in earnings forecasts for this year, leaving Mpac on a forward P/E of around nine.
Personally, I don’t see much attraction here. This business already had very poor quality metrics prior to today and is styled as a Value Trap by the algorithms.
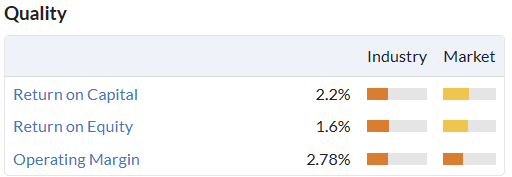
I think this is a situation where it makes sense to follow the StockRanks. I’m also intrigued to see that this is another example of where the algorithms picked up on potential weakness at the time of Mpac’s results, before the market seemed to sense any problems:
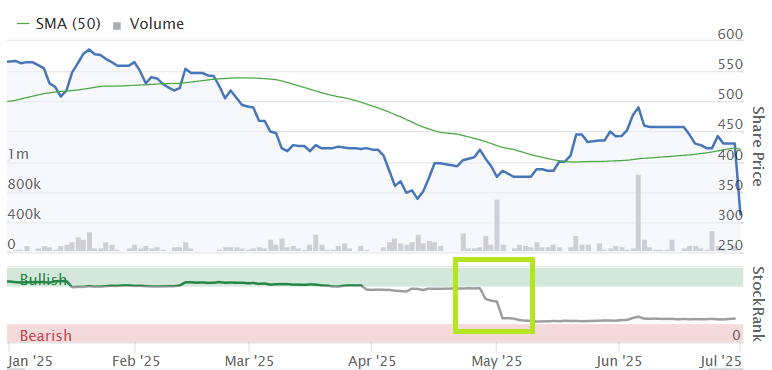
This pattern is something I discussed in more detail in an article in May – it’s not the first time I’ve seen this happen this year.
Mpac has a chequered history with periodic disappointments. I can’t help feeling this might be the latest of these to hit shareholders. History tells us that an initial downgrade is often followed by further disappointments. Mpac’s debt burden is an added concern for me. AMBER/RED.
Supreme (LON:SUP)
Down 5% to 195p (£231m) - Full Year Results - Roland - AMBER
Supreme (AIM:SUP), a leading brand owner, manufacturer, and supplier of fast-moving consumer goods, announces its audited results for the year ended 31 March 2025 ("FY25" of "the Period").
I have an interest in well-run distribution businesses and I know I’m not alone among Stocko subscribers in having followed Supreme’s progress with interest.
Like many of you, I’ve always been slightly unsure just how much of a valuation discount is appropriate to reflect the group’s dependency on vaping products. This issue doesn’t seem likely to go away, as I’ll discuss. But today’s results look solid to me and do not seem to flag up any other concerns.
I think this morning’s modest share price weakness is probably due to uncertainty over the impact of the June 2025 UK ban on selling disposable vapes and some caution on the outlook. Let’s take a look.
FY25 results
Revenue for the year rose by 4% to £231.1m, supporting a 3% rise in pre-tax profit to £30.9m. Adjusted earnings are reported up 3% at 21.6p per share, which appears to be slightly ahead of Stockopedia consensus for 20.7p per share.
While Supreme ended the year with modest net debt of £12.3m, this reflects c.£25m of acquisition spend during the year and doesn’t look a concern to me. My sums show the business generating almost £21m in free cash flow excluding acquisitions, demonstrating excellent conversion from net profit of £23.5m.
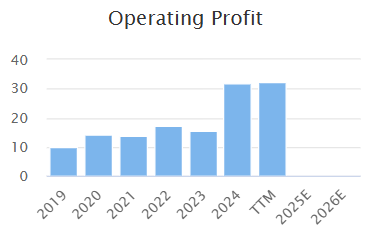
Profitability also remains strong, with an operating margin of 14.1% and return on capital employed of 35.7%. Both figures are consistent with last year, with lower ROCE reflecting the addition of new assets through acquisitions that have not yet contributed a full year to earnings:
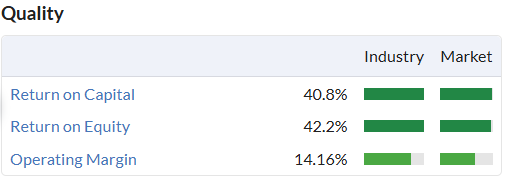
If Supreme can continue to increase capital employed while maintaining this level of profitability, then this should create value for shareholders as the group’s earning power will improve. We can see this has happened to some extent already since the group’s 2021 IPO:
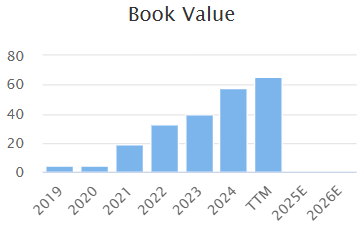
Dividend: shareholders will receive a total dividend of 5.2p for FY25, a 10% increase on the previous year. This gives the stock a trailing yield of 2.6%. Not that exciting, but well covered and supportable alongside growth investments.
Divisional trading: growth vs decline?
Supreme has used these results to debut its new operational structure:
Vaping
Drinks & Wellness
Electricals
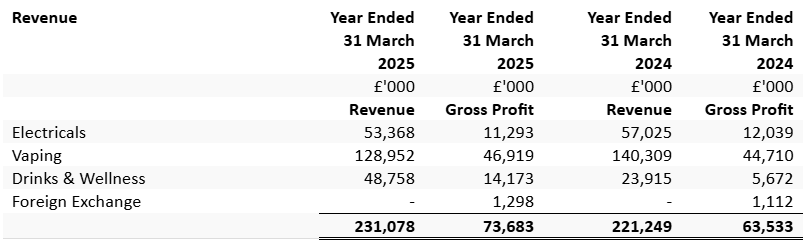
This table from the footnotes to today’s shows the performance of each category last year:
A few points I’d note from these segmental results.
Vaping: sales fell by 8% to £129.0m, but gross profit from this division rose by 5% to £46.9m, giving a gross margin of 36.4% (FY24: 31.9%).
This improvement in profitability reflects a 23.5% fall in disposable vape sales to £54.1m, partially offset by 8% (£5m) increase in sales of non-disposable vapes and margin expansion in the group’s core 88vape business.
Supreme prudently wound down stocks of disposable products last year, but the ban on disposable vapes in the UK only came into force in June. This means it isn’t yet reflected in these figures and we can’t be sure how sales patterns may change over the coming year.
The expected introduction of new taxes on vaping from October 2026 adds another unpredictable variable to the equation, as does the suggestion I’ve seen in some recent data (not from Supreme) that vaping adoption may have peaked in many markets.
On the other hand, I accept the company’s suggestion that impending tighter regulation in this market could lead to sector consolidation that would be beneficial for Supreme, as a larger player.
The reality is that vaping still accounts for 55% of group revenue and 64% of gross profit, so remains highly material to the equity valuation despite growth elsewhere.
Drinks & Wellness: CEO Sandy Chadha seems to be positioning this division to take over the growth mantle from vaping. Last year saw the acquisition of Clearly Drinks and Typhoo tea, which brought with it a number of other potentially attractive brands to sit alongside the company’s existing wellness and sports nutrition products.
Clearly and Typhoo are both brands with c.£20m annual sales and account for the majority of last year’s sales growth.
Supreme says Clearly is now generating “an almost 40% gross margin” while loss-making Typhoo has been returned to profit at an EBITDA level. Management have clear plans for further improvements at this iconic tea brand:
In the four months under Supreme's ownership, the business reported revenue of £6.1 million and contributed positively - albeit modestly - to the Group's Adjusted EBITDA position. In these four months, the priority has been to stabilise the brand and its positioning in the market, determine a cost-effective and ethical supply chain, and re-establish inhouse manufacturing.
I am inclined to see this as an attractive opportunity. My impression is that Supreme’s product development and distribution capabilities could deliver attractive results here.
Electricals: this division was previously Batteries & Lighting. Perhaps unsurprisingly, both of these product ranges are seen as being in structural decline. Supreme says its offerings outperformed the wider market, gaining share.
Even so, revenue fell by 6% to £53.4m last year in this segment. Profit contribution was also weaker, with a lower gross margin (21%) than either Vaping or Drinks & Wellness.
Outlook unchanged
The outlook commentary sounds positive:
Supreme has made a positive start to FY26 and expects to deliver another profitable and highly cash-generative year, trading in line with current market expectations.
However, the problem is that current market expectations suggest a modest fall in profits this year.
Consensus forecasts provided in today’s RNS are for revenue of £236m and adjusted EBITDA of £36.5m. This adjusted EBITDA figure is 10% below the £40.5m FY25 figure reported today.
Forecasts on Stockopedia ahead of today also reflected this expectation, with a consensus EPS figure of 19.6p for FY26:
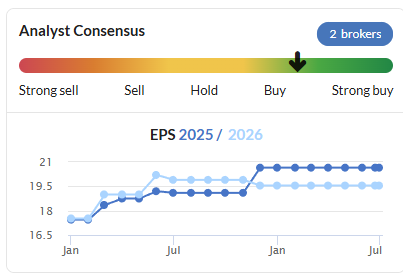
Checking through broker notes shows a range of forecasts, two of which are notably below current consensus:
Zeus - FY26E EPS: 17.4p (unch)
Shore Capital - FY26E EPS: 16.7 (newly introduced)
Equity Development - FY26E EPS: 19.5p (prev. 19.7p)
Assuming the Zeus and ShoreCap figures form the consensus provided by Stockopedia’s data provider, I suspect we could see a modest downgrade feed through to the StockReport in the coming days.
Taking the average of these three estimates gives me a figure of 17.9p, 17% below today’s FY25 result. That would leave Supreme trading on a FY26E P/E of 11.
Roland’s view
I think these are a good set of results from a well-run and reasonably-valued business. The elephant in the room remains the outlook for the vaping business, in my view. Given that this contributes nearly two-thirds of Supreme’s gross profit, investors can’t afford to ignore this risk.
My view is that Supreme is relatively well positioned to handle increased regulation and consolidation in this sector. But the likely impact of greater regulation and tax levies on vaping sales is not clear to me.
I was AMBER/GREEN on Supreme when I last covered the shares, but I don’t think I can maintain this view today. The combination of vaping uncertainty and the seeming likelihood of a fall in earnings for FY26 means I am going to moderate our view to neutral.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

60 comments
MPAC (LON:MPAC) what was it that the algorithm saw that we didn't? I dismissed it as an erroneous jump down, but it seems the algorithm was right and I was wrong (duh!). But what was the information that prompted the huge sudden fall in MPAC rating??? And why was it invisible to humans??
MPAC (LON:MPAC)
with anything like this i like data published in real time to avoid bias in methadology. There are hundreds of companies reporting weekly - so there will always be companies where stock ranks drop - then bad news comes later. thats very much a statistical certainty - even if the data shows some correlation that only applies for a basket of stocks. It would be easy to cherry pick any of number of cases where teh opposite has happened. Any backtested test can easily simply be skewed due to randomness. The true greats benchmakrs are the ones that publish predictions like and update then you avoid using a biased sample. Note i am not knocking the back testing if it works - thats still valid just slightly sketchy without being fully peer reviwed (not really an option) - note i dont think MPAC was even mentioned in that article.
what was it that the algorithm saw that we didn't? I dismissed it as an erroneous jump down, but it seems the algorithm was right and I was wrong (duh!).
I dont know for sure but all holders should know that MPAC was a somewhat risky proposition - they set really high expectations here compared to the past - they had very large acquisition in December 2024 - and its always tricky bedding in large acquisitions and the resks are much elevated and you need to be able to trust mangement - compared to just plodding along where it is all so easier to predict.
Anyway results were published 29/4/2025 - it seems very clear downgrades in ranking followed on from the tweeking of the numbers then - presumably as old year departs the building many stats are changed ? To be once the year end numbers detailing larger share count and acquisition etc were booked on the system its no surprise that this is seen as being more risky. so whilst there was slight caution in tone of update - i ma preuming its fully due to the known stuff ref acquisition - it doesnt take stocky to tell me thats added risk and that stocky would be late to the party perhaps flagging up that risk.
Anyway its setback for managment here - drop if expected sales is huge and to mewith that volum eless in sales being expoected even hitting curent lowered targets seems a big risk (they need to chop nearly 12 mill from admin/overheads next year !). I have no viewpoint on whetehr they have been cuatious and reset bar sensibly low to then imporve - or if they are struggling and simply updating now withn glass firmly fully despite sales orders being massively short of what they planned. I dont know mangement well enough to see whetehr they are cautious grounded and top of figures or not - but the fact they have allowed themselves to be where they are is not great - thats alwasy the issue with large acquisitions though - extra shares - extra debt and no room for the cash being splashed to not be a failure. If they hit 2026 targets though and are back to trending up from here shareprice should bounce back - for anyone on the sidelines though not sure they would want to risk it with added debt - poor update and fact that profit warnings come in t.......'s
MPAC (LON:MPAC)
I presume you are referring to the stock rank at the end of April. The answer to your question is simply that the annual results were incorporated. You can see what changed from:
Before https://s3.eu-west-1.amazonaws...
After https://s3.eu-west-1.amazonaws...
The quality rank was down - look at
to
The momentum rank was down even more -
1 year relative strength was down from -6.75% to -22.0% and a drop in net profit to 31st Dec 2026 showed in the estimates table.
Regrettably I failed to take action on the SR change and sold on yesterday's PW at a nasty loss.
Many thanks to you both for comprehensive answers on MPAC (LON:MPAC). Seems like the answers were actually there if I had only looked properly!! Lesson for me....
Synectics (LON:SNX) very strange price action pre interims, completely at odds to what the company have stated?
Now looks superb value, what am I missing?
A fired accountant?
As an aside on the commentary on todays profit warning from MPAC (LON:MPAC) (I hold), can I suggest an improvement to Stockopedia?
I had missed the low volume directors' shareholdings, a bit of a red/amber flag. My bad, and obvs this information is available elsewhere.
It would really help if Stocko was to display directors' shareholdings on the stockreport. I know it is possible to drill down to directors dealings, but I have never found place in Stocko that shows the current holdings.
It's nice to see Rowland's previous observation held true
I have previously asked that the StockRank Movers table be brought in line with the risers and fallers table by adding the ability to switch from the current list of risers to support reporting of their wayward counterparts. This should be easy to implement, with a nice Risers/Fallers selector at the top.
This would make this tool much more useful by flagging warning signals, allowing a revisit to DYOR, before potentially precipitous falls.
Are we seeing signs last couple of says mkts are turning? July never any good...
Days!!!
Reminder: You have up to 1 hour after posting to edit & correct typos etc.
A witching day, quarter end. Bonus time!
Mercia Asset Management prelims (we are long term patient holders) look good today -- Nothing unexpected but profit/eps/div/Aum are all up, plus a £3 million share buy back announced. Graham covered it on April16th and rated it Green. The CEO's short positive comment ends "Our ambition now is to go much further and faster". Warning sign or fill your boots? I'm hoping one of the team covers it, or other holders on here.
Burford Capital (LON:BUR) is opaque at the best of times, but there are 2 very significant developments today. Over the last few weeks the SP has dropped 20% on fears of a provision in the US budget that would have imposed punitive taxes on the entire industry. That has now been thrown out.
The second is that the judge in the US yesterday rules that Argentina, who owe Burford $17bn, growing at the rate of over $2m a day (at least a third of which is due to the company itself) have been ordered by the US court to transfer the 51% of YPF that they originally misappropriated, to Burford, within 2 weeks. They are likely to appeal, but it is also a big step in bringing Argentina to the negotiating table.
The bizarre thing is that the price of UK shares, where about 25% of trading now happens, fell this morning to 7-8% below the closing price in the US. It is basically back to where it was before the budget fears, and there is no upside granted for the important judgment.
Makes little sense in the short term. In the longer term, it is a uniquely opaque company which is frustrating to own: every quarter they report results that they describe as "superb" or "blow out" and the market just shrugs. I suspect one day some bright PE firm or the management itself takes it private. It often feels to me the unwillingness to say anything about individual cases means that it is essentially a black box not really suited for the public markets.
Yes they might describe each quarter results as "superb" but they're usually referring to the "record" deployment into new cases, and brush over the fact that the existing backlog of cases is generating very little in terms of actual returns. Not sure that PE would go for this as far too opaque and murky, with very lumpy and unpredictable cashflows. Management taking it private perhaps more likely, given that they already own quite a chunk of it.
I have to say both Kitwave and MPAC have said things have slowed. My suspicion is the whole system is slowing, The corrections you are seeing today reflect stock selection but these are reflective of the market and what will happen more broadly if the whole system is slowing. For me equities are just over valued given the head of the free world is not the genius he seems to think he is. His move on the Fed is concerning. His move on Democracy is concerning, in particular given that Capitalism cannot work in an autocratic state. Some will say this is politics, it may be but I am an investor and I am finding it very difficult to invest in the current febrile environment!!
Its not Trump.
It is TACO and Buy The Dip mentality by the markets.
The last financial crisis was caused by opaqueness, complexity in complex CDOs. Lack of information. "If only we had known X, we would know that those CDOs aren't AAA rated and wouldn't have created them, bought them!"
This time, information is freely available. We know exactly what Trump says and does. Direct from his mouth, on Truth Social. We know what economic impacts tariffs have. We know what's in the Big Beautiful Bill. We know when decision making slows down, investment does, and so can spiral. We know a Fed that is not impartial will not be good long-term.
Yet, despite all this information openly out there, openly discussed.... vast swathes of the market believes in TACO and BTD. They believe that something, someone, God, will step in at the right time to prevent anything bad from happening.
So everyone's busy looking for the "hidden risks" that are going to cause the next financial crisis. Unfortunately, because we're much better now at surfacing risks, its all pretty much out there in the open. But people are choosing not to believe.
And this "choosing not to believe" has roots in social media. Its easy to find the alternative view echo chamber. And get positive reinforcement of TACO, BTD.
So there we have it. Historians might look back at this age, and say "All the signs were there, out there in the open. Instead, we had a mania not based on deception and lack of knowledge, but one based on denial and echo chambers"
TACO ?
Trump Always Chickens Out.
Sorry Boon I felt I had to reply to that. I just want you to know I am not on any form of Social Media. I gave up reading even papers 5 years ago. I wanted to form my own views free of the bias out there. I work only from Company announcements, official Govt figures and statistics that come from reputable sources. So no I don't agree this is all about echo chambers. Although I am open and honest enough to accept I could be wrong. That said I obviously don't believe I am and I reserve the right to lose my own money for my own reasons.
Ah I didn't mean you camtab!
I meant some other investors in the market. Thats why we have moves that are illogical.
MPAC (LON:MPAC) Kitwave (LON:KITW)
I must say my views echo with Cantab on this one.
I think both are fundamentally good companies (maybe MPAC was quite aspirational with its recent acquisitions but how else would it grow?-also someone made an excellent point about low CEO/CFO holdings) but I’m now down 45% since early New Year and it’s my worst ever drop.
I think this volatility works for day traders but not for companies who are commissioning work on 18M- 3 year cycles when Trump changes the news feed every weekend- from Greenland to The EU, Ukraine, to DOGE. The list continues.
If you’re a senior leader in business allocating capital, surely you would be apprehensive?
Listening to the Vox podcast today you’d think Trump’s tariffs have had a contrarian effect on investing.
That chimes very much with my own view Camtab.
From discussions with friends and family what I am hearing is that people are baulking at the price of many things and are prioritising what they do spend based on their individual / family requirements.
I personally am looking at the prices in many different areas and thinking no way am I going to pay what is being asked. It's not that I want absolute value, it’s just that it feels as if so many things have become overly expensive for what they are, or producers/manufacturers are bolting on features that I don't need or want, almost so that they can justify the increased prices.
So I also believe that things are slowing down and that this will feed into lower company earnings in due course - even if they haven't been fully reflected yet. The number of offers and deep discounts in my inbox each day has certainly increased, suggesting to me that companies are needing to increase sales. My other half has also noticed this and commented on it recently.
House prices increases have recently slowed and if you look on right move you will see many many houses having to be discounted/reduced. That may be a reflection on stamp duty changes but it may also be people deciding that what people are asking is just more than they are willing to pay.
Add to that the myriad of issues creating volatility and instability around the world, from world leaders ego’s to wars, and index valuations at record highs and it feels that there is much more risk to the downside than the upside.
I may be completely out of step with things as the markets power ahead, but I have to sleep soundly at night and invest with how I see that things may pan out. So I have taken a lot of risk off the table and am now sitting 75% in cash, which whilst not ideal, is at least receiving a decent interest payment each month in my SIPP.
If I’m wrong, and I may very well be, then I’ve just lost a bit of opportunity, and some dividend income, but for me, as I see things currently, it’s a much more comfortable position to be in.
I guess different views are what make a market and why investing is such an interesting and challenging thing to do.
All the best to everyone, whatever their take on the markets.
Richard
The prices of some things out there an absolute disgrace!
And great post Richard!
I'm about 50% in cash, not overly hopeful the good recent weeks will continue.
Certain indices look way overheated, DOW/FTSE100/DAX
Ready for some shorts, as a hedge...
Certain indices look way overheated, DOW/FTSE100/DAX
The FTSE 100 is currently trading on a PE of about 13, and a forward PE of 11, compared to a long term average of 14.5.
The UK markets have been deprived of capital for a while now, so if some of that is flowing back across the Atlantic we might reasonably expect the FTSE 100, which is largely an international index, to continue to slowly rerate, regardless of UK economic and political events. Commodity prices might be more relevant, but most of the major commodity stocks on the market look cheap anyway.
Of course, there's always a crisis around the corner, but if there is then cheap internationally diversified stocks are as good a place to ride it out as any.
timarr
Maybe not the 100, but we shall see...
Difficult morning. I hold MPAC (LON:MPAC) and Kitwave (LON:KITW) fortunately in a 27 share portfolio, neither are large positions
MPAC (LON:MPAC) I really like the 'automation' story, hence my modest holding, but the one niggle that I had was that management never bought any shares, apart from participating in the fund raise at 400p. Both CEO and CFO have paltry holdings.
This morning's downgrades are severe with consensus adjusted PBT and EPS reducing significantly year on year out to FY27. Debt is also uncomfortably high and will stay so it appears for the foreseeable future. I have little confidence in the management and have sold for a 25% loss this morning at 322p. if one is going to panic do so early, as is sometimes said.
It is unusual for me to hold on to a share after a profit warning but I may do so with Kitwave (LON:KITW) The jury is currently out. For me it is a business that is easy to understand albeit not easy to run. Management have been buying the shares and spent close to £290,000 buying 112,000 shares at 258p in early March. CEO, Ben Maxted bought 20,000. The founder Paul Young and his wife hold close to 3% of the company and Ben Maxted 2.5%
Unlike MPAC (LON:MPAC) there is a decent dividend yield. At the current market price of around 250p the revised estimates from Canaccord give a PE of under 10 falling to sub 9 for FY26 and a yield o 4.5% or thereabouts. The company should perhaps focus on debt reduction rather the dividend? I need to look more closely at today's results before deciding what to do.
Wynnstay (LON:WYN) I also hold and have just glanced at the headlines which all in all appear positive. The new management team and the somewhat grandiose named project genesis are it seems making progress.
MPAC (LON:MPAC)
This morning's update was a real shocker but at least management are willing to face us - there is an investor webinar at 09.00am on Friday 4 July 2025. You can register here. This is organised by Equity Development and I find it quite stupid that they have been banned from telling us directly - we need all the information we can get.
They have also produced a research note here showing forecast for the FY25 adj. dil. eps reduced from 45.1 to 32.2 - a 29% drop which is about the same as the SP drop at the moment.
They also had the honesty to put the bad news front and centre, at the top of the RNS.
Not what holders (including me) wanted first thing but better than trying to bury it in the middle of other commentary.
"Trading update, consolidation of US footprint, and notice of results
Q2 order intake impacted by tariff uncertainty causing deferral of order decisions which will impact H2 revenue
Slower market conditions allow opportunity to accelerate US consolidation plans and optimise cost base for when conditions improve"
MPAC (LON:MPAC)
Remarkably chipper interpretation of how todays update affects things by Equity developments - see link below.
they are coming up with adjusted PBT of £13.00 mill this year and £15 mill next year (ignoring wo/ffs) - despite taking complete hatchet job to the sales levels this year and next.
They have also ramped up debt which is probably to be expected with the chunkly one of costs associated with the news today.
https://www.equitydevelopment....
Perhaps its not as bad as the news today may have left one fearing - but i do get the impression that these ED forceasts which they are presumbaly "trusting managment" to enusre are reasonable - look ulta rosy.
There is alot of moving parts with the news today but to me managment dont come out todays update well - and the outlook for next year looks optimistic here. Its hard looking out from tyhe outsie though to see whether the actions taken today might in some respects by necessary reffiicieny improvements that might have been needed anyway. To me though - if you are going out there spending wads on acquisitions you want to be driving the business forward and not going into reverse - i thought this was a company meant to be going places - seems anything like that at present even if the ED update may give comfort to those that have tehn faith.
very odd that based on todays news they (ED) see fair value now being 865p not 650p - if nothing else they seem to have faith here.
Our fair value / share estimate moves to 650p from 865p on our reduced forecasts. Yet even at that
650p level, the implied EV/EBITDA multiple of 9.7x would leave Mpac shares on an undemanding
rating compared to its peers
I think you have misread that. They have reduced fair value to 650p from 865p.
oops indeedy - silly me - that makes more sense
Elixirr International (LON:ELIX) - Be interesting to see what if any effect over the coming weeks on SP following the move from AIM to main market today. Currently only small percentage held by inst investors
I hold, but have also traded profitably, selling a tranche recently at 826p. Bought back in today, with hopefully all AIM/IHT Funds now sold out. Latest trading update very positive, record Q1 and likely record month in April. Expect an update soon.
Brutal start for Kitwave (LON:KITW) this morning, over 20% down. As a holder, here's hoping it's an extreme over-reaction that quickly improves....
Holding for now till the dust settles but the “profit warning comes in threes” is in the back of my head. Still seems reasonably priced particularly given the fall Kitwave (LON:KITW)
MPAC (LON:MPAC)
That’s a doozy of a profit warning today - for any listed company managing expectations is vital - in that regard today’s update is a dismal failure. They have failed spectacularly to quantify what bottom line damage is - it ain’t going to be pretty
MPAC (LON:MPAC) taking a pasting; down 35%. I was ready to sell into a 10% fall....
MPAC (LON:MPAC)
it deserves a pasting based on todays update - horrendous update in every respect (other than the token good pension news which was probably known about anyway)
Pinch and a Punch!
Kitwave (LON:KITW) I don't hold.
Disappointing out loook this morning. Company state that they are now aiming for £38 to £40m opearating profit due to poor trading, particularly in tourist areas and NI costs, but I can't find what their previous guidance was depite looking in previous trading and results statements. Poor discolure in my view, Yellow Jersey PR take note. Can anyone help with this. Thanks,
Marks and Spencer (LON:MKS) - What, no announcement ahead of their AGM today....
Such a big NAV discount on Augmentum Fintech (LON:AUGM. RNS here.
I don't really do Investment Trusts partly for inexplicable NAV reasons - but if the NAV is accurate (who knows?) and at a £169m market cap - according to the AIC it's at a 38% discount to NAV.
For a fintech investment business, it seems steep. Not really my bag though !
Hi Ed,
Charles & Ken host a monthly Investment Trust (IT) thread which features a lot of commentary on Investment Trusts and has a fair few contributors regularly discussing a variety of IT's. I am sure the new July thread will be posted later today.
Augmentum Fintech (LON:AUGM) is a regularly discussed trust - largely due to its wide discount and the fact that there are some potentially strong companies held within its PF.
After doing my research I invested in it in April - Charles was highlighting the anomaly I think in the IT thread across April/May and it has risen by about a third since then.
Within its Top-10 holdings there are some rising stars which on reading the Trusts reports (and the companies own websites) definitely hold some promise (although I appreciate sometimes these are Jam tomorrow companies).
Well worth anyone who has an interest in the IT world takes a look at the thread - it gets a few posts each day after discussing specific trusts, the days news and any interesting sectors.
ATB. Kevin
RE: Augmentum Fintech (LON:AUGM)
The problem is that the market for IPOs and other methods of shifting holdings has been shut for about three years. If you can't sell your assets what are they really worth? IP (LON:IPO) and Molten Ventures (LON:GROW) have a similar problem and even bigger discounts.
If you spend some time looking at the underlying holdings and the realisations that these funds have managed to make then they do look significantly and genuinely undervalued. However, there's no timescale on when they'll come good and in the meantime the market is on a roll. Unlike many other investment trusts there's no dividends to support the share price while waiting for events to transpire.
To take one example, Revolut's IPO is expected this year and Molten Venture's stake there is estimated at £160m, just over a quarter of the current net asset value. That's nearly £100 million uplift on the carrying value. Whether that will shift the dial on MV's NAV is another matter, however, the market really doesn't like these funds at the moment.
timarr
Augmentum seem to be doing very little to tackle the discount unlike some PE and venture funds which have announced some big returns of capital, such as £HVPE They yet again note the wide discount and their determination to tackle it - but do precisely nothing. Other than that quibble AUGM seems to have a promising portfolio and looks very cheap
Bouden, They have said they are aware and actions are being considered . I hold and may well buy more.
To be honest I'm not sure they can do much - cash is not that plentiful now for a cash hungry portfolio so that rules out significant buybacks. Short of a wind down I don't think they have too many options and will just need to wait for sentiment to improve.
Just posted my views on the July trust thread. I have increased my holding today.
Wynnstay (LON:WYN) I like the focus on efficiency and profit. We knew harvests from 2024 were poor. Encouraging that spring conditions were favourable, does this mean that harvest 2025 will be better than 2024? Can’t get much worse. No idea how market will react today but Project Genesis appears to have some room to run. Would appreciate the team’s thoughts. I hold.
Likewise. Seems far too cheap. Could the team have a good poke around please?
As long as there isn't a plague of locusts, but that's when Project Exodus really comes into its own.
Interims from Wynnstay today, I have a decent sized holding.
Revenue down, gross profit up. All explicable.
PBT £5.5m v £4.4m.
EPS 18.3p v 13.9p.
A crude calculation of NTA puts it at about £100m, higher than the market cap.
This looks likely to beat full year forecasts. The harvest may be poor due to drought, but management seem to be running the company well.
A comfortable Hold for me.
Morning GreyInvestor,
We'll be covering Wynnstay (LON:WYN) today (I hold).
Roland
Rachel Reeves set to cut cash Isa allowance
https://archive.ph/UtssR
Twentyfour Select Monthly Income Fund (LON:SMIF) for me wonder why so many shares have been issued in this of late
Trading close to nav the only time they can issue shares without diluting
4k laughable
Easy to circumvent. Put £20k in a Stocks and Shares ISA and invest in money market funds. Fidelity, Legal & General do them. There will be others. Couterparty risk but these are huge companies.
I've had them for years, no issues and get good rates.