Daily Stock Market Report (Tue 10 Dec 2024) - BBSN, GAW, BEG, HVO, SOLI, NCC, AHT

Good morning!
1pm: wrapping this up for now. See you tomorrow!
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing. Links:
Daily Stock Market Report: records from 5/11/2024 (format: Google Sheet).
Companies Reporting
Name/Mkt Cap | RNS | Status/ brief comment | Our view (Author) |
Ashtead (LON:AHT) (£27bn) | Final Results & US listing | Profit warning due to US weakness. FY rev growth exps cut from 5%-8% to 3%-5%. | AMBER (Roland) Previewed in The Week Ahead (MB). |
Centrica (LON:CNA) (£6.7bn) | TU | 2024 earnings expected to be “broadly in line”. | |
Games Workshop (LON:GAW) (£4.6bn) | Amazon agreement. | GAW has finalised its long-awaited deal with Amazon. | GREEN (Roland) |
Moonpig (LON:MOON) (£919m) | Half-year Results | In line. H1 adj PBT +9% to £27.3m, but £56m impairment relating to Experiences division. | |
NCC (LON:NCC) (£511m) | Final Results | There is a recent lengthening of sales cycles. Expecting flat to low single digit revenue growth. |
AMBER/RED (Graham) Down 18%. |
Boohoo (LON:BOO) (£492m) | Letter from the board | The board wants shareholders to vote against the GM resolutions. | |
Porvair (LON:PRV) (£305m) | TU | FY rev +9%, adj eps “marginally ahead” of exps. | |
Begbies Traynor (LON:BEG) (£150m) | Half-year Results | In line. Broker slightly increases revenue forecasts (FY25 & FY26) but adj. PBT forecasts are unch. | AMBER (Graham) |
hVIVO (LON:HVO) (£145m) | Contract win & TU | £11.5m contract to deliver in 25/26. FY24 EBITDA margins at “upper end” of exps. | AMBER (Megan) |
Springfield Properties (LON:SPR) (£106m) | TU | In line. | |
Solid State (LON:SOLI) (£68m) | Interim Results | Existing forecasts maintained by broker Cavendish, except for a reduced dividend. | AMBER (Roland) |
Naked Wines (LON:WINE) (£42m) | Half-year Results | In line. | |
Tortilla Mexican Grill (LON:MEX) (£19m) | TU | FY24 in line, but UK trading ahead. | |
Cambridge Cognition (LON:COG) (£12m) | Trading Update | Profit warning. 2024 revenue £10m (prev: £14m) and adj. EBITDA breakeven (prev: £0.5m). | |
Pennant International (LON:PEN) (£12m) | TU | In line. FY24 exps for rev of c.£14m and adj EBITA of c.£1.2m. |
* Market caps at previous trading day’s close
Summaries
Brave Bison (LON:BBSN) - down 3% to 2.1p (£27m) - Acquisition and Trading Update - Graham - AMBER/GREEN
I approve of this acquisition. Despite buying a loss-making company (even at the EBITDA level), BBSN has made the vast majority of the nearly £11m price conditional on the performance of the business after acquisition. Strategically the deal makes good sense to me and I remain impressed by BBSN’s financial performance.
Begbies Traynor (LON:BEG) - up 5% to 99.1p (£156m) - Half-year Results - Graham - AMBER
Another sturdy performance from BEG as it benefits from elevated levels of insolvency activity and good volumes in the non-residential property market. A small net debt position should cause no concern relative to ongoing profitability. I remain neutral as I think it’s fairly priced at a PER of about 10x for a professional services business.
Solid State (LON:SOLI) - up 6% to 127.5p (£73m) - Half-year Results - Roland - AMBER
Full-year expectations for this electronics supplier have been left unchanged, underwritten by an increase in the order book since 30 September. I remain positive on the long-term story and see this as a potential contrarian pick, but demand remains weak and recovery timing is uncertain.
Ashtead (LON:AHT) - down 12% to 5,522p (£24bn) - Half-year results & US listing - Roland - AMBER
This construction equipment hire group generates most of its profits in the US and has been hit by a slowdown in local construction in that market. The longer-term picture remains positive in my view, but I don’t see any need to rush in after today’s profit warning.
Graham's Section
Brave Bison (LON:BBSN)
Down 3% yesterday to 2.1p (£27m) - Acquisition and Trading Update - Graham - AMBER/GREEN
This is a digital marketing agency that has in general been viewed positively in this report, due to sound financial health - see Paul’s review in September.
The company tried and failed to acquire TMG (Mission) this year.
Yesterday we learned that the company had found a new target: “Engage Digital Partners Limited”, “a global sports marketing company that works with the world’s largest sports brands and federations including Formula 1, ICC, Real Madrid and New Zealand Rugby”.
The rationale makes good sense to me:
Engage will combine with Brave Bison's existing network of channels, which already benefits from partners such as PGA Tour, Ryder Cup, US Open, Australian Open, CPLT20 and Le Mans. The combination will create an enlarged sports & entertainment division for Brave Bison partnering with channels across football, cricket, motorsports, tennis, golf, e-sports and rugby, and totalling £16 million in pro-forma turnover.
Cost: up to £10.6m, but only £2.1m is guaranteed.
For labour-intensive marketing work, it makes sense to me that a large part of the acquisition price would be conditional on performance after acquisition.
This is especially true as I note that Engage is expected to post an EBITDA loss on revenues of £6.9m for 2024. So Brave Bison are doing the right thing by protecting themselves against buying a dud: if Engage helps their performance to improve, they will pay handsomely, but if it doesn’t, they might have to pay very little.
There are two legs to the conditional payments: first up is “equity consideration of £2m”, taking the form of 66.7 million warrants over BBSN shares. The existing BBSN share count is 1.3 billion, so the potential dilution from these warrants is small.
The warrants can’t be exercised until 2028 and “will only vest if the mid-market price per Brave Bison ordinary share exceeds 3 pence [GN note: c. 40% above the current share price], and if the Group has met certain financial targets at the time of exercise.”
In addition there is “contingent consideration of up to £6.5m over three years subject to performance conditions”. BBSN would potentially have the cash to pay this even if they didn’t generate much operating cash flow over the next three years - more on that in a moment.
Overall, I’m going to give this deal a big thumbs up, as I like the way BBSN has protected itself from the risk that it fails to improve the performance of a negative-EBITDA marketing company.
Trading update: BBSN also published a brief trading update along with the acquisition announcement. It was short and sweet:
Trading in the second half of 2024 has been in-line with expectations and the Board anticipates that Brave Bison will meet current market forecasts for FY24 of approximately £3.6m of Adjusted EBIT.
Following the acquisition, the Company is now expected to report net cash of approximately £7.0m at the end of FY24.
The year-end cash forecast is slightly reduced, from £9m to £7m, but pleasingly that still leaves plenty of cash to pay the contingent consideration for Engage, even if the group doesn’t generate much operational cash.
Graham’s view
I’m glad that BBSN has found a more amenable acquisition target than The Mission Group. This deal sounds to me as if it is strategically sound, and I can’t possibly argue that they have overpaid, given how the purchase has been structured.
I’m happy to leave our AMBER/GREEN stance unchanged. While I do admire BBSN’s financial performance in recent years, I’m not convinced that the shares are a slam-dunk bargain at a current market cap of £27m, given just £3.6m of adj. EBIT (before the acquisition of Engage).
Begbies Traynor (LON:BEG)
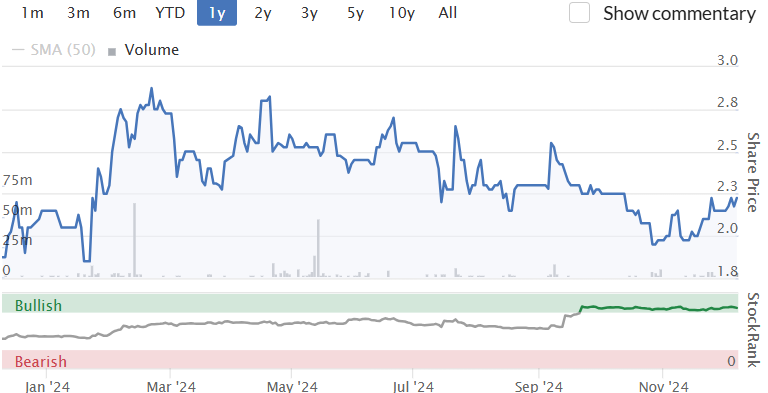
Up 5% to 99.1p (£156m) - Half-year Results - Graham - AMBER
I’m impressed with the 16% revenue growth posted by Begbies today for H1 (to £76m). Organic growth is strong at 11%, while acquired growth contributes the remaining 5%.
There have been “increased year on year insolvency activity levels in higher value cases”.
More bluntly, the company says later in the statement that “UK insolvencies remain at elevated levels”.
But the “property advisory” segment is growing even faster than the “business recovery” (i.e. insolvency) segment.
In property advisory, asset sales have seen “strong growth driven by property auction volumes”.
In total, adj. EBITDA rises 20% to £15m. PBT rises 57% to £4.7m.
The company moves into net debt of £4m, as its acquisition strategy does require significant earn-out payments (£4m paid in H1).
Outlook: in line. The range of forecasts for adj. PBT is £23 - 24.3m (thanks to BEG for disclosing this).
H1 adj. PBT was £11.5m, so no growth is required in H2 to achieve the bottom of the forecast range.
Comment by Ric Traynor:
Since 2014 we have tripled the size of the business with a six-fold increase in adjusted profit before tax. Building on this track record, we are making good progress towards our medium-term revenue target of £200m.
Market conditions remain supportive for the group's service lines which is reflected in our current activity levels and positive momentum across the business. This, together with our financial performance in the first six months, leaves the board confident of delivering current market expectations for the full year, which will extend our longstanding track record of strong, profitable growth.
Dividend: the interim dividend increases by 0.1p to 1.4p.
Headcount (measured in full-time equivalents) has crossed 1,100, up from 1,050 a year ago.
Adjustments: in H1 there are £6.8m of “non-underlying items”, which create the large gap between adjusted PBT (£11.5m) and actual PBT (£4.7m).
There are two components involved here: amortisation of intangible assets (£1.9m) and payments for acquisitions that are deemed to be remuneration, as they require the sellers to stay employed within BEG (£4.9m).
We’ve been over this before. I’m fine with taking these adjustments at face value, but with conditions.
Firstly, if we are willing to ignore the amortisation of intangible assets, then we should be willing to write down the value of all of BEG’s intangible assets to zero. If we do that, the BEG’s balance sheet equity is £6m, not £76m!
Secondly, if we are willing to add back in the cost of acquisitions that are deemed to be remuneration, then we need to remain mindful of the fact that BEG’s success depends on the input of certain individuals, i.e. we need to value this as a “people business” with a lower earnings multiple than we’d give to businesses that do not depend on the input of key individuals.
Estimates: many thanks to Equity Development for publishing a detailed note this morning. I have not read it in its entirety yet, but I note that it includes an adj. PBT forecast of £23.3m for FY April 2026, with adj. EPS of 10.4p, and the company having “free cashflow to fund both acquisitions and dividends”.
They see "scope for a significant rerating” to a PER of 14x, with fair value of 145p.
Graham’s view
I’ve been neutral on this one, as I’m a fan of this business and its management, but I view it as correctly priced (see coverage in November at the half-year trading update).
For the reasons explained above, I’m happy to use BEG's adjusted earnings numbers but I wouldn’t want to pay an above-average or even average multiple for them, and I would also want to treat the balance sheet with caution.
Therefore, to me, a PER of about 10x on adjusted numbers makes good sense. That’s roughly where the stock is currently trading (share price 99p vs adj. EPS forecast of 10.4p). So I’m staying neutral on it. Perhaps when I read the Equity Development note later on, I'll be convinced that it's worth a bit more!
NCC (LON:NCC)
Down 18% to 133.8p (£422m) - Preliminary Audited Results - Graham - AMBER/RED
NCC Group plc (LSE: NCC, "NCC Group" or "the Group"), a people-powered, tech-enabled global cyber security and software escrow business, reports its 16 months to 30 September 2024 ("2024", "the 16-month period"), following a change to the Group's financial year end.
I don’t usually cover this one and my initial question relates to the change in the accounting year-end.
It has taken me a little while to find the answer but in January 2024, NCC said:
The Board has changed the year end of the Group from 31 May to 30 September, this is to drive greater efficiency in our corporate reporting and audit process.
I have no idea how a September year-end would drive greater efficiency than May - perhaps it has something to do with summer holidays?
Back in September 2023, I see that KPMG requested additional time to complete the audit for FY May 2023. NCC would go on to change its auditor in 2024.
Perhaps I am focusing too much on this issue, but it’s remarkable to me how often a change in accounting year-end is associated with some hidden or not-so-hidden problem.
Let’s move on and look at these 16-month results to Sep 2024, which are really 4-month results for the period from June to Sep, as unaudited 12-month results were already published.
In the 4-month period, revenue is up 6.6% (at constant currency) to £105.1m.
Adj. EBITDA has quintupled from £1.9m to £9.5m, and the company posts an operating profit of £2.3m (vs. a loss of £7.7m in the corresponding 4-month period).
Unfortunately finance costs eat all of this operating profit, so the bottom line result is around breakeven.
CEO comment:
"We have made great progress over the past 18 months, transforming the business by focusing on client needs while building the Group's resilience. Our more focused Cyber Security business returned to growth in the second half to May 2024, with improved sources of recurring revenue with Managed Services performing well, and our Escode business building a track record of growth. We are pleased to see this strategic progress coming through in improved gross margin and Adjusted EBITDA - a key priority for the Group.
“Escode” (external link) is the “software escrow” side of the business, which is essentially a software depository.
Market economics - this section includes some negative commentary on the state of the industry, although it does say “notwithstanding macroeconomic factors outside of our control, we remain confident in delivering our medium-term financial goals.” The company’s office in Manila “has enabled us to expand our global capability and offer more options to our clients”.
Let’s bullet point the negative factors at play:
Clients looking for higher levels of assurance during their procurement processes.
Higher value, longer term contracts have a longer buying cycle.
Security leaders are competing for budget with other spending priorities in their organisations, and cyber security is not immune from the cost pressures experienced by other departments.
Cooling of buying activity in the UK re: Budget.
North America tech sector spending has not returned to levels seen during or immediately after Covid-19.
It’s a lot of negativity and this feeds through to an uninspiring outlook statement.
The Group has a strong pipeline of opportunities, and management is pleased with the foundations put in place through strategic actions taken in the period. In line with the wider market, the Group has recently seen a lengthening of sales cycles, in particular across the Cyber business, compared to H2 to May 2024 and also the four-month period to September 2024. In spite of this, management expects to deliver profitable growth across both businesses in the current financial year to 30 September 2025, with flat to low single digit revenue growth and modest Group Adjusted EBITDA gains…
Estimates: Zeus have left their forecasts unchanged.
Net debt has reduced by a few million pounds to £45m.
Graham’s view
I’m not seeing a lot to like here, despite the strong growth in adj. EBITDA. The balance sheet has a negative tangible asset value of minus £40m, and retained earnings (more like cumulative losses) of minus £89m.
Combine that with limited revenue growth forecast by management, finance costs devouring the company’s operating profit, and an IT sector (managed services) that I would ordinarily want to put on a low multiple, and it’s creating a picture of a stock that I’d want to steer away from.
I’ll tentatively put this on AMBER/RED for now. I think it’s trading on a current-year PER (using adjusted EPS) of 21x, falling to 16x for next year. This is significantly higher than I’d want to pay for it.
Megan's Section
hVIVO (LON:HVO)
Up 4% to 22p (£150m) - Contract win - Megan - AMBER
There are positives and negatives in this morning’s announcement from hVIVO (LON:HVO).
On the one hand, the company confirms it has signed a new £11.5m contract with a large pharma company (an existing customer) to test its new antiviral medicine in humans. This should provide reassurance to those who were a little disappointed by the company’s £71m order book announced in September.
On the other hand, the trading update confirms that the company is still set to deliver £62m of revenue in the 2024 financial year, which means that the pace of delivery in the first half has not been maintained. In H1 the company ran through its order book at a rate which meant it delivered 57% of its forecast annual revenues. With no additional orders set to deliver revenue in the second half, the company is still set to report just £26.4m of revenue in H2. That is down on the £28m of revenue generated in the second half of 2023.
And herein lies the problem with Hvivo’s business model: it is very reliant on the pace of innovation at large pharmaceutical companies which rely on its testing facilities to evaluate new drugs.
The company has done what it can to counter that. Earlier this year it expanded into a new facility in Canary Wharf, which means it now runs the largest human challenge trial site in the world. This means that the company will be able to test multiple drug candidates at the same time. The new site, which was financed largely by the company’s existing clients, also comes with a larger laboratory space, which could help it expand its pre-clinical trial offering.
Financially, there are also positives and negatives to be found.
The company receives a good chunk of revenue upfront and booked £21.6m of deferred revenue in the first half of the financial year - a lot of that relating to orders that were to be satisfied throughout the duration of the year. But on the other hand, Hvivo has quite high debtor days and on average it takes 145 days to receive payment from its customers for work delivered.
Megan’s view
I like the ‘picks and shovels’ approach to investing in small cap pharma. The risks associated with a company which provides services to the industry are significantly lower, compared to one that is looking for a groundbreaking new treatment.
Hvivo clearly has a strong position in the market it operates in, but its capacity for growth is somewhat limited by where its clients chose to invest.
In the 12 years since its IPO, Hvivo hasn’t really delivered an awful lot for its investors. I’m finding it hard to get excited by the potential upside, except perhaps as a takeover target. AMBER
Roland's Section
Games Workshop (LON:GAW)
Up 2% to 14,165p (£4.7bn) - Amazon agreement - Roland - GREEN
Games Workshop’s long-awaited film and television production deal with Amazon has been finalised:
Games Workshop has granted exclusive rights to Amazon in relation to films and television series set within the Warhammer 40,000 universe, together with an option for Amazon to license equivalent rights in the Warhammer Fantasy universe following the release of any initial Warhammer 40,000 production.
Today’s statement comes exactly on schedule. When the Amazon agreement was originally announced on 18 December 2023, the company said they would work with Amazon for 12 months “to agree creative guidelines”.
No financial details have been included in today’s RNS and management warns that this could remain a slow burner:
Production processes in respect of films and television series may take a number of years.
Outlook: forecasts for the current year (ending 1 June 2025) are unchanged, following November’s upgrade, which Megan covered here.
Roland’s view
At this point, it’s impossible for us to know what potential impact this agreement could have on Games Workshop’s financial results in the future.
If production goes ahead and is successful, I would imagine this could add materially to the company’s existing licensing revenue. Licensing contributed revenue of £31m and operating profit of £27m last year – exceptionally high margin.
However, as far as I can tell there’s no obligation on Amazon to actually produce any Warhammer films or series. Nor are there any timescales or fixed plans yet.
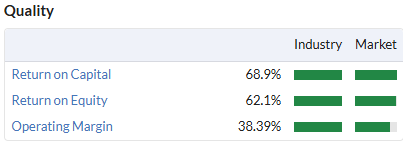
Games Workshop was promoted to the FTSE 100 last week – an incredible result for a niche hobby business. I think this remains a truly excellent company, with outstanding quality metrics:
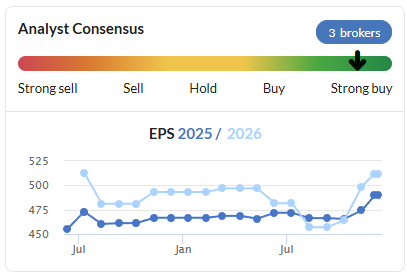
The company upgraded its guidance for the current financial year in November. Brokers also took the opportunity to upgrade FY26 estimates as well.
The shares don’t look obviously cheap on a forward P/E of 28. But Games Workshop’s StockRank remains high, at 85, with strong momentum.
After reviewing November’s trading update, Megan concluded that this stock continues to deserve a GREEN rating. I’ll leave that unchanged today.
Solid State (LON:SOLI)
Up 6% to 127p (£74m) - Interim Results - Roland - AMBER
“The Group order book at 30 November 2024 of £85.5m provides confidence that current earnings guidance for this year and next is deliverable, with potential to outperform, especially in view of spending on individually large programmes that are currently in abeyance.”
Today’s interim results mark the third update from this electronic components supplier in just over a month. Unfortunately the previous update – on 14 November – was a profit warning that wiped 48% off the share price on the day.
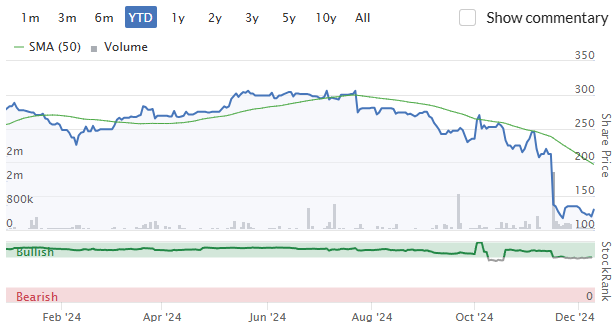
Things appear to be looking up slightly today. The company has left full-year expectations unchanged and suggests that the cyclical outlook for demand may be starting to improve:
There are tentative signs of cyclical improvement in the leading indicators for the industry, and this is reflected in order intake in recent weeks.
Let’s take a look at the main points from Solid State’s results.
Half-year results summary: today’s results cover the six months to 30 September 2024.
Solid State’s revenue fell by 30% to £61.8m during the period, while pre-tax profit dropped 80% to just £1.2m. Even the more favourable measure of adjusted pre-tax profit was 66% lower, at £2.5m.
Encouragingly, gross margin improved marginally to 31.1% (H1 24: 31%) suggesting the company’s pricing power has remained stable. However, the drop in volumes caused negative operational gearing and left the group’s operating margin for the half year at just 3%, compared to 7.9% in H1 last year.
Solid State’s management is keen to highlight that the H1 profit slump was made worse by the early delivery of a large order representing £10m of revenue and £3m of profit. This was expected during the first half of the current year, but actually fell into the second half of last year.
Moving this revenue into H1 would have lessened the scale of today’s profit drop, but H1 profits would still have been lower due to the delay in a big defence order discussed in November’s profit warning (see here).
Bonus share issue/eps calculations: a subscriber has flagged up the potential for confusion relating to Solid State’s bonus share issue on 2 October 2024. This saw the company create four new shares for each existing share. The effect is the same as a five-for-one stock split.
However, the balance sheet date for today’s results was 30 September, which was before the bonus issue. As a result, today’s eps numbers do not reflect the share split. Restated figures will be provided with the FY results. Alternatively, we can just divide by five to get the relevant numbers today:
H1 24 adj earnings per share: -62.6% to 17.5p
H1 24 eps restarted: 3.5p
Dividend cut: Reflecting weaker trading, the interim dividend has been cut by 40.7% to 0.83p per share. Confusingly, this has been adjusted for the bonus issue in the headline numbers.
Trading commentary & order book: Solid State has already flagged up the risk that the UK Defence Review will continue to delay new defence orders.
Defence remains a core market for Solid State, but the company is working to diversify into markets such as industrial computing, communications and medical electronics. Management believes the medical sector in particular has similar attractions to defence, in that there are high barriers to entry, long design cycles and tough certification requirements.
Over time, I imagine this strategy may help to reduce Solid State’s cyclical exposure, which the company highlights in its commentary today:
The global electronics market has continued to normalise, with orderbooks adjusting to reflect shorter lead times and unwinding of overstocking. Political and economic uncertainty has affected some sectors, with certain customers delaying orders in response to shorter lead times combined with slower demand.
To put this in context, Solid State’s order book was £76.6m on 30 Sept 24, down from £99.7m one year earlier – that’s a reduction of 23%.
However, order intake in H2 appears more promising. The company says the orderbook had risen by £8.9m to £85.5m on 30 November.
Outlook: the increased orderbook “gives the Directors confidence in meeting revised full year consensus analyst expectations”. Helpfully these have been included in today’s results:
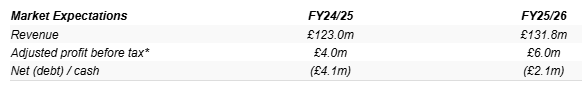
Brokers Zeus and Cavendish (many thanks) have both left their FY25 forecasts unchanged today, at 5.3p and 5.5p per share respectively (adjusted for the bonus issue).
Both figures imply that H2 eps will be around 45% below the restated figure of 3.5p I’ve calculated above. Clearly, earnings are expected to be sequentially weaker during the remainder of the year, despite the more positive tone to today’s update.
Roland’s view
I suspect Solid State will always be somewhat dependent on large and lumpy contracts. But I don’t see anything in today’s results to suggest the company’s core appeal has changed.
Historically, the business has generated a return on capital employed in the mid-teens. This suggests it benefits from some durable competitive advantages and has been able to invest capital at attractive returns as it’s grown.
The two charts below show a combination I like to see – rising revenue and stable ROCE, demonstrating growth at attractive profitability:
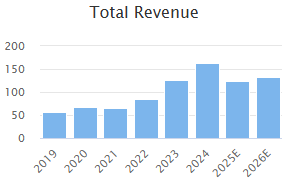
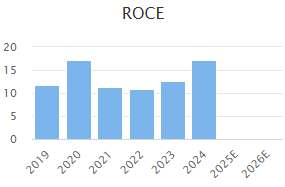
Profitability will be poor this year and today’s results put the stock on a FY25 forecast P/E of 22. However, with the shares trading close to book value, I think any recovery in profitability to historic levels could support a substantial share price recovery.
The StockRanks view the shares as a potential contrarian play, with high quality and value scores and poor momentum.
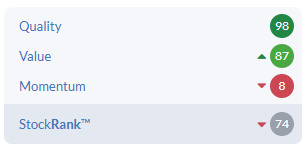
I share this view and don’t see any reason why the long-term growth story should not remain intact for this business, which has been listed on AIM since 1996.
On balance, I think Solid State could reward more in-depth research. However, after this brief review, I can’t ignore the uncertain timing of any recovery. I would not rule out the risk of a further cut to expectations.
For these reasons, I’m going to take a neutral view and upgrade our stance slightly to AMBER.
Ashtead (LON:AHT)
Down 12% to 5,522p (£24bn) - Half-year results & US listing - Roland - AMBER
FTSE 100 construction equipment hire group Ashtead issued two RNS statements this morning. Unfortunately one of them included a profit warning (my bold):
Principally as a result of local commercial construction market dynamics in the US, we now guide to Group rental revenue growth for the full year in the range of 3-5% and hence, full year profit lower than our previous expectations.
Let’s take a closer look at today’s news from this high-flyer, which has been a five-bagger over the last decade:
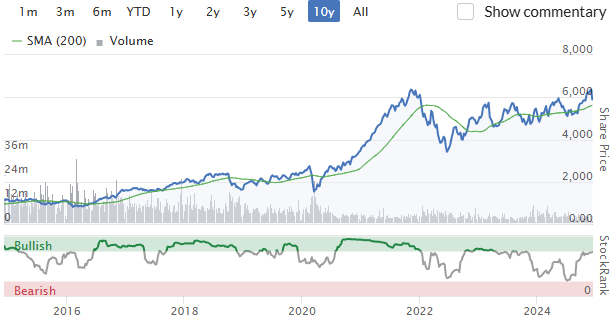
Megan covered this stock in the Week Ahead and warned that any earnings weakness could cause a correction. Unfortunately, that’s what’s happened.
Ashtead’s Q2 revenue growth of 2% was unchanged from the first quarter, leaving half-year revenue up 2% at $5,695m. However, pre-tax profit for the period fell by 4% to $1,197m, which the company says was mainly due to lower used equipment sales and an increase in depreciation and interest costs.
The company’s own measure of return on investment for the half year fell to 15% (2023: 18%) due to lower utilisation of a larger fleet.
Free cash flow was positive at $420m, benefiting from a reduction in capital expenditure during the period. Net debt excluding leases remained broadly unchanged at c.$8.2bn, representing 1.7x EBITDA. While this is a little higher than I’d choose, I don’t see it as a big problem.
2024 results below expectations: Ashtead CEO Brendan Horgan says that US conditions have diverged. While “mega projects and hurricane response efforts” continue to drive demand, local commercial construction has slowed.
Mr Horgan says this is linked to “the prolonged higher interest rate environment”. Underlying demand is said to remain “strong” and Ashtead expects to see a recovery as interest rates stabilise.
However, as a result of this situation, Ashtead has cut its US revenue growth guidance for this year, resulting in an overall downgrade:
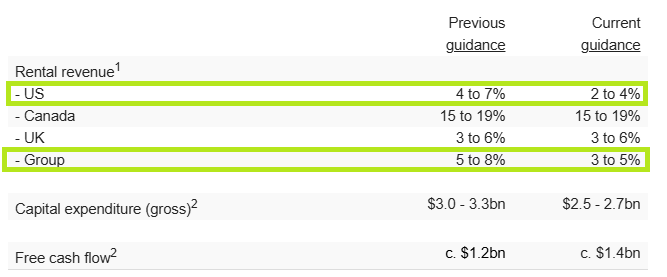
I’m encouraged to see that Ashtead expects to be able to increase free cash generation this year simply by scaling back capex.
The numbers above imply a full-year free cash flow yield of over 4.6% at today’s share price. That’s not a value rating, but it’s not necessarily unreasonable for a faster-growing business, as Ashtead has been (until recently).
Outlook: This business generates more than 90% of its profit in the US, so any drop in revenue in this market has an immediate impact on profit.
I don’t have access to any updated broker notes today. But prior to today, analysts were expecting Ashtead to deliver broadly flat adjusted earnings this year, before recovering in FY26:
FY24 earnings: $3.86 per share
Stockopedia FY25 consensus: $3.90 per share
Stockopedia FY26 consensus: $4.51 per share
Expectations have already been slipping lower this year:
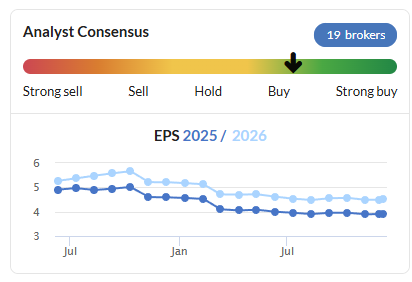
Today’s 12% share price drop suggests to me that the market may be pricing in a further 5%-10% cut to earnings forecasts.
My sums suggest a revised figure of perhaps $3.60 per share (c.285p). That would place the stock on an unchanged FY25e P/E of 19, after today’s drop.
Move to a US primary listing: Ashtead generates over 90% of its profits in the US and reports in US dollars. It’s no surprise to me that the company has decided to move its primary listing to the US.
Today’s statement indicates that Ashtead will retain a secondary listing in the UK, so shareholders won’t be forced to sell or hold overseas stocks.
The decision will be put to a shareholder vote before being implemented, with completion expected “over the next 12-18 months”.
Roland’s view
Today’s profit warning from Ashtead isn’t a complete surprise, in my view. Other companies, such as Somero Enterprises (disclosure: I hold) have also noted the impact of higher interest rates on local construction projects.
I think Ashtead remains an attractive long-term business, but I also think there’s a risk that interest rates will remain higher for longer than expected. If I’m right, the time needed for property markets to adjust might also be slightly longer than expected.
I generally avoid buying shares directly after an initial profit warning. Stockopedia’s research indicates that stocks often continue to underperform following an initial downgrade.
Ashtead’s shares are not obviously cheap, either, in my view, despite strong quality metrics.
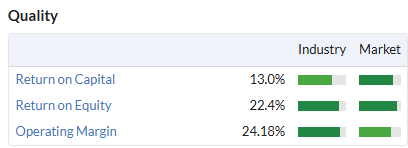
However, this business does have a strong track record and is the second-largest hire operator in the US, with further growth opportunities. I don’t see any reason to take a negative stance at this point, so I’m going neutral with an AMBER view today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

72 comments
See no comments on Baltic Classifieds (LON:BCG)
A chart most would die for. They say don't invest in an IPO until two years under the belt so this has cleared its risk phase.
Not a region would consider although Bank of Georgia (LON:BGEO) is popular, but these have hard workers, with brains and a common societal value with trust generally in their institutions. Only Russia queers the patch.
Just flagging up as there hasn't been any comment on it historically.
Re Warpaint London (LON:W7L) and its retail offer at 510p, on the basis of my application, it was around 6 x oversubscribed when the shares were allocated today. Obviously attractive to small investors like me.
Warpaint London (LON:W7L) was oversubscribed at least 10x!
I got ~10% only, and I just apply exactly as much as I had...
Regarding Begbies Traynor (LON:BEG) being fairly priced. With the added costs heaped on businesses by the budget, I'm thinking that is surely a catalyst for growth in 2025?
Hi where did you read about this and what was the information overnight that lead to the big drop? Cheers Seplat Energy (LON:SEPL)
Good to see Seplat Energy (LON:SEPL) bounce back a bit towards the end of today. I'm still struggling to work out which part of the MPNU acquisition has caused the drop in price?
I put the RNS through ChatGPT and it came back with this:
The acquisition of MPNU by Seplat Energy Plc is presented as overwhelmingly positive, but there are some areas that could be perceived as risks or negatives depending on perspective:
Despite these potential concerns, Seplat's strong financial metrics (e.g., low leverage ratio, significant production and reserve growth) mitigate many risks, making the acquisition largely positive. Still, stakeholders should monitor how Seplat addresses these challenges post-acquisition.
And just for a laugh I asked ChatGPT for a risk rating:
Me: If we were to rate the risk level of this message infers to the company; where green is very good, amber is middling and red is very bad (oh and you can have intermediate levels like Green / Amber etc). What colour would you say this company is after the news update?
ChatGPT
<Detail Removed by Me, to keep it small>
Conclusion:
While the acquisition is transformative and strategically sound, the elevated financial commitments and integration risks warrant caution. Hence, Green / Amber reflects optimism tempered by the need for prudent management and effective execution of the post-acquisition strategy.
I wouldn't trust this reply, but very interesting that it had a go :)
Mega cap but Megan might be interested? Alphabet (NSQ:GOOGL) , although no real financial benefit currently.
'Google's new quantum chip has solved a problem the best supercomputer would have taken a quadrillion times the age of the universe to crack.Google scientists have created a new quantum processor that, in five minutes, cracked a problem that would have taken the world's best supercomputer 10 septillion years to solve. The breakthrough will allow quantum computers to become less error-prone the bigger they get, achieving a milestone that overcomes a decades-long obstacle.'Amazing congrats to the Google scientists.
Intercede (LON:IGP) have a white paper here that states the importance of credentials management due to the advent of Quantum Computing, good to see it on the radar.
Trying to understand the implications of Quantum Computing, apparently everything becomes less secure as we transition which makes IGP solution essential for customers.
We explore the Unified Credential Management of the various solutions for multi-device credentials including mobile devices, FIDO Credential Binding and replacement. The threat of quantum computers becoming available, the cyber agility needed to stay ahead of the threat.
I do hold IGP.
Unified Credential Management in Federal Government
So the worry is Quantum Computing could render all current encryption algorithms redundant. That’s a big statement, and I am not qualified to confirm that’s true, be interested in thoughts from others.
On basic maths if its true what google were saying about then latest quantum stuff - then If that gets into general use yes in theory. As a non expert i would have thought limiting attempts at entry should provide decent cover for some stuff stuff. Not sure how true it is but some of the stuff about ai is slightly scary - ie it trying find out ways to avoid being terminated without telling its masters when it finds out its going to be switched off - not sure if thats someone making a story out of something thats a non issue of not. Could be interesting next few years if computer grunt power and ai does grow exponentially - there are also soem stories that ai progress seems to be slowing - so seems like there is 2 competing narratives at play here depending on what you read where.
On basic maths if its true what google were saying about then latest quantum stuff - then If that gets into general use yes in theory.
Not sure what you're trying to say here, but the link between quantum computing and AI isn't direct, although there is a concern that generative AI is reducing the time needed to make the upgrades necessary to develop quantum computing at scale.
Currently the quantum computing threat to cryptography is still only theoretical but there's no obvious roadbock between the theory and the practice other than time and money. It's hard to underestimate the impact of such a breakthrough - cryptography underpins virtually everything we do, from payments to trading and everything in between.
We do have quantum resistant algorithms that will protect against the threat of quantum attacks (https://www.nist.gov/news-even...) but the problem is that rolling them out is a multi-year process which will involve the replacement of every device in the world using cryptography - so that's every computer, smart phone and payment card for a start. If quantum computing advances faster than our ability to rollout the defences we will have a problem. Even if it doesn't we're still dependent on companies upgrading their systems.
The Intercede (LON:IGP) paper is about as anodyne as you can get, one mention of quantum cryptography, presumably as a scare buzzword, in the middle of what is otherwise a piece of business-as-usual marketing material.
timarr
Hi timarr,
I have the impression that we will all appreciate and gain from a write up about quantum computing (as you are definitely someone that actually understands the subject).
All the shares involved in it over the pond are flying.
All the best
Hi yiannos
Sadly I don't think most people here would appreciate a treatise on quantum computing. However, the ideas behind the subject were first proposed by Richard Feynman over 40 years ago, so this isn't exactly original stuff.
I imagine most people here have heard of Schrodinger's cat - the cat is put into a box with a radioactive isostope which has a 50/50 chance of killing the cat. Until the box is opend the cat is in an indeterminate state - it's neither alive nor dead. Only by opening the box can you determine the cat's state.
Well, quantum computing is a bit like that - you can simultaneously process the outcome of all events based on the cat being alive and dead at the same time. Classical computers have to start from the principle of the cat being dead or alive. Scale those possible states up - say to all 256 states of the first byte of 256 bytes in a cryptographic key then you potentially reduce the time it takes to break that key by a factor of 256 (not true at the moment, but maybe in the future).
It's this inherent parallelism that gives quantum computing its advantage over classical computers. Technically a bit in classical computing is either 1 or 0 while in quantum computing it can be both at the same time - a qubit. All of this means that certain types of algorithm, including those needed to break classical cryptographic algorithms, are much easier for quantum computers. The challenge is to build them, which is a lot easier said than done.
I did a degree majoring on quantum mechanics and I still struggle to communicate the issues without using maths. I mean, wave particle duality shows that one particle can simultaneously go through two slits at the same time ... everything we know is built out of the quantum world, and yet none of it relates to our perception of the world. I'm not actually sitting on my chair as I type this (or hitting the keys) but I perceive that I am.
Nothing humanity ever achieves will be more incredible than our insight into the quantum world - but that insight is built on the intellect of a very small number of people.
As Feynman himself said "If you think you understand quantum mechanics you don't".
timarr
Hi timarr,
Even quantum computing won’t be able to crack a One Time Pad! So, when all is lost we can all send each other very long true random numbers in the post! :-)
Thanks for the link to the new NIST QC resistant algorithms. I used to implement cryptographic algorithms and design secure systems but I retired before their finalisation. I did physics with a module in quantum mechanics at Uni too and could never get my head around wave particle duality either.
I don’t understand the timing of the Google announcement but not surprised by all the hype in the media.
All the best, Si
timarr - you have sent me into nostalgia! Here is a photo of my big red well-thumbed Feynman book on my wall bookshelf. I have spared you the rest of the photo, which was me on my 21st birthday - and it was right in the middle of exams. It is now too distant to remember whether regurgitating something from from that book helped me through those exams but I did pass!
Much appreciated Timarr.
Much appreciated indeed.
An investment banker was trying to explain it to me the other day. I got the impression at the end that he did not understand the market. I have the basics now for further research although I am sure that I will have to read it another 10 times!
There are so many listed companies to research over the next 10 days in order to find the winners. Firstly we will scratch the ones that have been jumping and chasing every hype in the last 2/3 years. Then scratch the ones that will definitely need cash injections. Surely there are still some multibaggers out there. This will be one of the hottest themes in the US market for 2025……..
Thanks
Oh, my aching sides! Haven’t laughed so much for a long while! The idea of an investment banker trying to understand quantum theory… :-)
I don’t think you’ve really taken on board what timarr has written. Every computer chip in the world that performs encryption of any kind will need to be replaced (or upgraded). Every secure web transaction using public key encryption will become insecure. All government level communication devices will be compromised. All data sitting in secured storage will be accessible…
So, it’s far better to consider the consequences than try and understand how quantum computers work, even though the news this week shouldn’t come as a surprise to anyone that’s been paying attention. I should also point out that none of this is going to happen anytime soon because current computers have far too few qubits
Thanks again Timarr for your post.
And after 7 hours of research I am confident enough that I have found two gems in this space. Ready for the bell now!
All the best
I’d read this first: https://media.defense.gov/2021...
Santa Rally trading update - reindeer threatening to strike over conditions and pay - below expectations.
I also hear that recruitment has been frozen for elves in the workshop due to a hike in labour taxes due in the New Year - lack of forward looking confidence for 2025
I suppose that one should be grateful. I run a portfolio of 22 shares the value of which has remained stable over the last couples of months, with some of the team “playing well” and others under par to use a sporting analogy. However being invested in UK small caps, albeit with some having good exposure to America and Europe has been a grind.
With few exceptions they are all cheap, the exceptions perhaps being Bloomsbury Publishing (LON:BMY) and Avingtrans (LON:AVG) , albeit the latter should be valued on a sum of the parts approach rather the using PE or other metrics.
I watched Mello last night and my perception of the fund manager discussion was far from encouraging, so my take is that when all appears to be doom and gloom, one should be buying. The only consistent in life is change. Nothing stays the same and at some point down trodden UK small caps will have their day in the sun.
So hopefully St Nick with his helpers, Prancer, Dancer, Dasher etc will sprinkle a little stardust on good quality UK small caps.
The Elf Inspector
The elves experiencing a growing problem.
Cambridge Cognition Holdings (LON:COG) trading update.
It's a big miss on revenues, but with a promise of new orders arriving which won't be recognised until Q1.....
"Cash expected to be approximately £1m at the year end and expected to increase during 2025"
Frustratingly they don't specify whether they are talking about NET or GROSS cash, which is pretty critical given the state of the balance sheet.
They seem to think they have enough money to recruit a new CEO, or maybe they need the new CEO so they can kitchen-sink and raise money again having said they didn't need to!
Shares have bounced because people were fearing worse after a period of silence following departure of prior CEO.
Hi Roland. Regarding today's announcement from Games Workshop (LON:GAW) , they said in their update of 22 November that licensing revenue for the six months to 1 December 2024 would be not less than £30 million (versus as you point out, £31m for the full year to June 2024.)
Licensing revenue for the same six month period was £14.3 million for 22/23 and around £12 million for 23/24. They are therefore forecasting an uplift of at least £15m in licensing revenue for this latest six months.
Given that they also say today that FY25 forecasts remain unchanged, do you think we can deduce that some of this licensing uplift is actually from the Amazon deal? I wonder if Amazon pay a licence fee on agreement of the creative guidelines and this is what prompted the trading update in November? Do any readers here have knowledge of how these deals are normally structured?
Bear in mind also that the single Warhammer 40,000 episode of the new Amazon anthology series "Secret Level" is released today on Prime Video . I imagine that would have formed part of the same licensing deal and would presumably have been paid for in advance of today's release. It seems very unlikely that the licence for this single episode would be worth £millions on its own and so my hunch is that the overall licence fee for this single episode plus the licence to produce the films and TV series might be an annual licence which will contribute to the extra £15m-£18m (approx.) announced for the first half of FY25.
Hi johnsmith68,
I'm afraid I don't have any insight into the make-up of the Games Workshop (LON:GAW) licensing revenue or the typical structure of industry deals.
It would be great to hear from any subscribers with industry knowledge on this topic!
Roland
RE Movie licensing deals. No knowledge per se - just google thumbs
BARBIE- Mattel, whose Mattel Films co-produced the movie with Warner Bros. Discovery, is expected to take in $100 million in revenue, according to Stifel analysts. That includes $75 million from toys, $12.5 million from licensing the Barbie brand, and $11 million from the film
https://licensinginternational....
Games Workshop (LON:GAW)
The sharp increase in licencing revenue in H125 was predominantly from the successful release of Space Marine 2 which to date has sold over 5m copies.
Any Amazon royalties will accrue on a project by project basis rather than on signing. I don't think any royalties have been paid so far (exSecret Level which will be minor imo) The secret level animation project is completely separate to the Amazon/Vertigo Entertainment deal.
.
Disappointing results from Ashtead (LON:AHT), which I hold. H1 saw revenue growth of just 2% and adjusted EPS down 5%. Full-year revenue guidance lowered from 5-8% to 3-5%. On the plus side, there was a free cash inflow of $420m versus an outflow of $355m last year and the company announced a $1.5bn buyback. The group is proposing moving its primary listing to the US, which doesn't surprise me given that it generates most of its revenue in the US.
Seplat Energy (LON:SEPL) down 25% this morning after announcing company purchase during market hours yesterday without causing alarm. What's up?
SEPL is a SuperStock with a stock rank of 96. Is there an explanation for the very large drop ?
Horrendous fiscal terms in Nigeria - 85% tax rate & huge capex commitments mean barely any FCF for Seplat for the foreseeable. Their hopes rest on switching to a more favourable fiscal regime in Nigeria but this is all just talk at moment. Looks like Exxon got best of deal. Majors rushing for exit in Nigeria for a reason.
That would explain it! Thanks for the insight.
Forgot to mention that they've got to pay Exxon $800m for that tiny FCF & they might have to take on debt just to fund future capex, fairly sub optimal imo.
Games Workshop (LON:GAW) I’d be somewhat taken aback if no films or tv series emerge given the level of effort & $/£ expended to get us to this point….not least as later today this Amazon Prime animation lands
Also a certain Mr Cavill would be similarly nonplussedI hold Games Workshop (LON:GAW) & have done so for years as I believe the IP has Game of Thrones/ Marvel / LoTR potential to be unlocked
Hi rhomboid1, I expect Amazon will produce some Warhammer films/TV series. My only point is that as far as I know, nothing has been (publicly) committed to or scheduled yet. So it's hard to know what might happen and when, or how it might affect Games Workshop (LON:GAW) financials.
I fully agree that the potential value is high.
Roland
Hi Roland
Games Workshop (LON:GAW) phrase it as “
So, what’s next? When will the first project hit screens?
It'll be some years. Project One* is about to go into development proper. So, next up is the script/s that will form the basis of everything else to come.
Of course, as with all carefully crafted things, this all takes time... and trust us when we say, everyone involved is las-focused on getting it all just right.”
https://www.warhammer-communit...
I suppose as investors we really need to look at the probability of this being a significant financial driver for GW …in my view it most certainly will be but nothing is certain.
PS enjoying the recent coverage of the team here
Have held Games Workshop (LON:GAW) in the past but am not a holder right now, did have a small worry about 3D printing, but who who wants to print anything, I barely use my ink printer and refuse to pay those ink prices.
What stop's them from becoming Walt Disney Co (NYQ:DIS), they have fantastic IP that is loved by audiences.
Or is that that laughable?
TheGames Workshop (LON:GAW) IP is probably more Marvel than Mickey Mouse ….but a degree of mainstream crossover looks more likely to happen than has ever seemed plausible before…fingers crossed
It’s the potential for growth and the foundation, Mickey Mouse is the distant past, yet still appealing to some audiences and consumers. Star Wars is the current, and Disney is a very diversified organisation, no reason that could not be the same here.
Solid State (LON:SOLI)
Can someone help me out here : The stock split recently but the half year numbers don’t appear to represent that on the EPS figure? It says last year was 40p for H1 (this year is 8p but I’m not certain that’s down to the split - that looks like a roughly equal fall in profits to me). I’m wondering how the results are being presented - anyone know to save me the digging?
Morning davidjhill,
I'm looking at Solid State (LON:SOLI) currently and will include a comment on the recent stock split.
Roland
Update: in short, the balance sheet date for today's results was 30 Sept, before the bonus share issue. So the eps figures in these results have not been restated to reflect the increased share count.
Thanks Roland - that makes sense : a bit disingenuous of the company to report that way though I suspect, having met the CEO a couple of times, it was technical rather than intentional!
Smiths News (LON:SNWS) contract renewal with Reach (LON:RCH) , £160m in revenue p.a. Yields a comfortable 8.45%, nice sleep easy at night share tucked away in an ISA.
https://www.investegate.co.uk/...
"I am delighted that we have now formally concluded our new contract negotiations with Reach and look forward to ensuring the widespread access and availability of their titles for readers in communities across the UK. The extent of our contracts with major titles continues to demonstrate the pivotal role Smiths News plays in the early morning supply chain.
We have now secured over 90% of our newspaper and magazine revenues through to 2029 which provides underlying revenue stability in addition to creating a robust platform from which to support our growth ambitions for the business."
NCC (LON:NCC) down 20% now.
Looks like an over reaction to me. Am I missing something? lengthening of sales cycles seems balanced for by all the numbers pointing in the right direction. Was it the dividend cut?
Well I saw the later summary and it explains all
** Cyber security firm NCC Group NCCG.L falls as much as 21% to 128p
** Stock biggest loser on FTSE 250 index .FTMC
** Co reports FY operating loss of 21.5 mln pounds ($27.4 mln) vs year-ago operating profit of 1.9 mln pounds
** FY24 revenue falls 3.2% at actual rates to 324.4 mln pounds
However if I read the RNS at 7:00 it seems to tell a different story - both cant be right and the market seems to have worked out which isn't! For what its worth, I work in IT and from my limited perspective I'm seeing a softening in the cyber market.
I would have thought the cyber market would be hardening with the treats from Russia etc.?
NCC (LON:NCC) not had a chance to look at the full figures, but l did see those headlines. 16 month dors not help. Why on Stocko are there the 2024 results already?
Speculation on my part with the softening - but maybe the soft targets are disappearing - most Cos have had their scares - and I know of a major supplier not NCC) that is "for the first time in decade not recruiting and has people on the bench".
Is that a UK or US based company? I have a few shares in some US cyber security stocks.
Begbies Traynor (LON:BEG) report a further 16% rise in H1 adj PBT today, having grown it six-fold in the last decade. The shares have retreated this year and ratings look too low in that context: in this deep-dive report we look at a strong track record and set Fair Value at 145p/share.
Read / hear summary: https://www.equitydevelopment....
Card Factory is a top Berenberg pick
Strategic progress at Card Factory (CARD) has made it a top pick for 2025 for Berenberg.
Analyst Adam Tomlinson retained his ‘buy’ recommendation and target price of 154p on the greeting card and gift retailer, which gained 6% to 102.6p yesterday.
Tomlinson highlighted Card Factory’s prospects in a recent analyst note on consumer stocks and ‘the good news has already started to flow’.
‘Firstly, the group has acquired Garven, a US-based designer and wholesaler of gift wrap and bags into general and speciality US retailers, for $25m from existing resources,’ he said.
‘This accelerates Card Factory’s move into the £70bn US gifts and celebration essentials market, which is a key region to drive international partnerships growth and achieve the group’s sales target of £650m by full-year 2027.’
Secondly, half-year 2025 trading to date has been in line and Tomlinson said its ‘productivity and efficiency savings remain on track, and there are no changes to its full-year expectations’.
He said there was ‘deep value on offer’ from the shares.
Card Factory (LON:CARD) Seems a low risk share.
Business model: Buy cards, put on shelf, get cash.
As Buffett said, make sure an idiot could run the company, because one day an idiot will be running the company. (Or words to that effect).
(I hold).
A simple business but not retail generally is not an easy business. Talking of idiots what happened to the Wilkinson chain !
Just seen a load of Wilko products in the Range, they have more or less replaced Wilkos.
As for Card Factory (LON:CARD) just bought a load of Christmas cards in Aldi, 20 for 99p, wrapping paper in the Range, did not bother going in the Card Factory. The Range are doing a load of cards now but seemed quite expensive. Competition growing?
I seem to recall that Card Factory once had/still has an agreement to supply Aldi.
Card Factory are now sole supplier to Aldi for cards, ousting IG Design in the process - hopefully a theme moving forward.
I see, can't see them making much profit on those cards. Plus it stops some people going in their own shops.
Agreed that the profit margin must be slim - probably not that simple to suggest Card Factory are cannilbalsing their own sales.
Good marketing people will select a partner with low proximity to CF exisiting locations. Different customer base etc - should hopefully result in mainly additonal business.
Well in my location they are close together, just across the car park. I was surprised they opened a shop there, it is never busy, unlike the one in the town centre. It is good for because l can buy cards without having to queue up. Cards in Aldi must a small seller, did not know they even sold them and there were not very many, just a few boxes.
I agree though in other locations they probably don't have much proximity.
But what is their rival called? They have opened a shop in the high street.
litle dave, that was family! Wilko, that is.
New table again?
Please no!
Stop fussing about the table!
I've been assured that work is being done to improve the view of the table for mobile users!
Table is good for me on iPhone 15 Pro.
Funny though, I am old enough to remember receiving sending a cheque in with a contract note by the settlement date and getting paper share certificates in the post. Now we worry that we can’t see a whole table on a mobile screen without swiping right (or is it left, never know which is which!).
Regards
Michael
Remember the broker now Henry Cooke Lumsden!! Don’t know what happened to them. :-)
Table works well for me, on a Pixel 9 Pro. And I have one of the smallest smartphone screens out there.
Need to scroll when using phone in portrait mode, bu otherwise can see the while table in landscape mode.
So we're good I think?
One suggestion is maybe use datawrapper.de to generate tables. They create ones that are flexible for different phone sizes.
Dec 10 (Reuters) - hVIVO (LON:HVO)
HVIVO PLC - £11.5M RSV CONTRACT AND NOTICE OF TRADING UPDATE
HVIVO PLC - SIGNS £11.5 MILLION RSV CONTRACT WITH GLOBAL PHARMA CLIENT
HVIVO PLC - REAFFIRMS FY 2024 REVENUE GUIDANCE OF £62 MILLION
Q&A with hVIVO’s Mo Khan
https://www.voxmarkets.co.uk/a...
Springfield Properties (LON:SPR) - "Confident H1 update, positive market developments" - new research note here: https://www.equitydevelopment....
Springfield’s H1 update reiterates current year expectations and reinforces our confidence in the medium-term outlook for the Group.
Momentum in private housing reservations was sustained through the first half, whilst the affordable housing business achieved a significant increase in gross margin driven by contracts won in the prior year.
Affordable housing providers have been more hesitant in awarding contracts in recent months but last week’s Scottish budget confirmed a material increase in funding for affordable homes delivery in FY25/26, which should stimulate activity into FY26. Springfield continues to engage with stakeholders in the major infrastructure projects planned for the North of Scotland, where it has a significant landholding.
Springfield continues to trade at a c.30% discount to peers, which in our view overlooks the Group’s unique positioning, the likely tailwind from the increased affordable housing budget and clear potential for major investment in housing delivery in Springfield’s stronghold in the North of Scotland.
We remain confident in the Group’s growth outlook and reiterate our 140p Fair Value estimate.