Daily Stock Market Report (Tue 14th July 2026) - RWA, HEAD, ASHM, BRCK, WOSG

There’s been a $5 increase in the price of a barrel of Brent crude oil over the last 24 hours, with the total increase over the last two weeks approaching $15 (from $70 to $84.50).
If you’d like to view the latest market-moving announcement: here is President Trump’s statement which appears to demand a 20% “reimbursement” (tax?) on cargo shipped through the Strait of Hormuz. With the Iranians and now also apparently the United States claiming the right to tax goods that pass through the Strait, I can see why markets are betting on higher oil prices.
Elsewhere, the giant Korean chip maker SK Hynix has just started trading on the NASDAQ. The $1 trillion company has raised $26.5bn. In its domestic market, it's worth about a quarter of the entire value of the South Korean index.
At the other end of the sentiment spectrum, Volkswagen is cutting 100,000 jobs or about one sixth of its entire workforce, as it struggles against increased competition from Chinese car brands.
Overnight market movements:
The FTSE is unchanged at 10,490
S&P 500 is unchanged at 7,525
Brent crude (September) is up 1.5% at $84.50/bbl
Gold is up 0.75% at $4,030/oz
Bitcoin is up 0.8% at $62,700
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£196bn | SR77) | Has entered into an agreement with Dizal Pharmaceutical Co., Ltd for Zegfrovy (sunvozertinib), a novel inhibitor for patients with lung cancer. AstraZeneca will acquire worldwide rights to develop and commercialise Zegfrovy. | ||
BP (LON:BP.). (£83bn | SR95) | Reported upstream production in Q2 is expected to be 2,170 to 2,220mboe/d (1Q 2026: 2,339mboe/d) due to seasonal maintenance predominantly in the Gulf of America and the effects of disruption in the Middle East. | ||
British Land (LON:BLND) (£4.3bn | SR71) | Leasing momentum has continued into Q1 with 567,000 sq ft of leasing completed, 4.8% ahead of ERV and 8.7% ahead of previous passing rent. Reiterates guidance for underlying EPS of at least 30.5p for FY27, underpinned by like-for-like net rental growth at the top end of its 3-5% target range. | ||
Watches of Switzerland (LON:WOSG) (£1.75bn | SR82) | Revenue +13% at constant FX. Adjusted EBIT +6% at constant FX (£155m). Guidance for FY27 is unchanged from that provided in the Q4 trading update. Trading in the first ten weeks has been encouraging. | AMBER/GREEN = (Graham) | |
Ashmore (LON:ASHM) (£1.53bn | SR57) | AUM increased from $50.7bn (March 2026) to $54bn (June 2026). Net inflows of US$1.3 billion. | GREEN = (Graham)
This stock is a case where ignoring both the headline P/E and the dividend yield might make sense. The interim balance sheet had nearly £700m of financial assets (including nearly £300m of cash). This covers nearly half of the market cap. I’ve been GREEN on Ashmore and with the net inflows announced today, I’m inclined to leave that stance unchanged. The shares are a little cheaper now compared to when I looked at them in April, while AUM has grown. The City doesn’t like the stock, which personally I take as a contrarian buy indicator. | |
Genus (LON:GNS) (£1.35bn | SR34) | H2 trading was better than anticipated. Now anticipates FY26 results to be moderately ahead of market consensus with adjusted PBT of approximately £98m. | ||
Integrafin Holdings (LON:IHP) (£1.26bn | SR80) | Quarter end funds under direction on the Transact platform of £85.5bn, up 23% year-on-year. Reiterates cost guidance. IHP is “in a strong position to accelerate profit growth and enhance profit margin in the coming years.” | ||
Atalaya Mining Copper SA (LON:ATYM) (£1.22bn | SR82) | 4 million tonnes of ore mined in Q2 (Q1: 3.4 million, impacted by high rainfall). Continues to expect that production for FY2026 will be at the low end of the original FY2026 guidance ranges. If the prices of diesel and explosives were to remain at recent peak levels for the remainder of FY2026, sees a potential increase of US$0.15 - 0.20/lb above previously stated FY2026 cost guidance. | ||
Iqe (LON:IQE) (£526m | SR25) | Multi-year production order valued at $14 million from a strategic global technology customer. | GN note: no reference to any impact on expectations. | |
Rank (LON:RNK) (£441m | SR56) | Net gaming revenue +6% (£834.1m). Now expects to report full year underlying operating profit ahead of expectations, being at least £76m. Expectations: £68.2m. £5m regulatory settlement to the Gambling Commission re: historical compliance failings. | ||
ACG Metals (LON:ACG) (£440m | SR58) | H1 2026 production of 18,487 oz AuEq exceeded the full-year oxide production target of 17,500 oz AuEq. "H1 2026 was a strong period for ACG, reflecting solid operational performance. We exceeded our full-year oxide gold production target in the first six months of the year, demonstrating the strength of our operating team, and disciplined execution.” | ||
Boohoo (LON:DEBS) (£339m | SR55) | “We are pleased with the continued positive trading through June and July. GMV continues to grow year on year, margins are up and returns are down.” | ||
Tharisa (LON:THS) (£337m | SR99) | Quarterly PGM production at 39.6 koz (Q2 FY2026: 34.3 koz). “With year-to-date production levels, we remain positioned to deliver against our FY2026 production guidance, supporting the Company's sustainable multi generational growth strategy." | ||
Guardian Metal Resources (LON:GMET) (£335m | SR24) | Non-core portfolio now comprises seven exploration-stage projects highly prospective for tungsten (W), gold (Au), silver (Ag), copper (Cu) and lithium (Li). "We believe these assets hold real potential, and we want to see them progress in a way that benefits our shareholders." | ||
Capita (LON:CPI) (£282m | SR18) | Capita will help deliver training services for the British Army’s Collective Training System, as part of the Omnia Training consortium led by Raytheon UK. Transaction price for the contract is £54 million over 15 years. | GN note: no reference to any impact on expectations. Small contract vs. CPI’s annual revenues of c. £2 billion. | |
BRCK (LON:BRCK) (£157m | SR84) | Revenue +1.3%, adj pre-tax profit +4.9% to £38.3m, with adj EPS +8% to 8.91p. Outlook: external conditions remain difficult, but operational gearing means “even a modest market upturn will translate into meaningful results for the Group”. | AMBER/GREEN = (Roland) I think today’s results support the view that this business could be too cheap. The 7% dividend yield was (just) covered by cash generation last year and a forward P/E of 6 seems low even for a business of this kind. In my view, profits should recover quite quickly when external market conditions improve. The difficulty is that it’s very difficult to gauge when this might happen. The StockRanks reflect this nicely, with a high QV score and a low MomentumRank. I’m happy to leave our AMBER/GREEN view unchanged today. | |
RM (LON:RM.). (£90m | SR50) | Continuing revenue -4.2%, with pre-tax loss of £(2.9)m. Decline in revenue mainly reflects the challenges in the UK schools market, which are affecting the Technology division. Revenue will be “slightly down on FY25” but RM remains on track to meet full-year expectations for adj op profit and adj EBITDA. | ||
Victoria (LON:VCP) (£79m | SR49) | Completed €34.4m sale and lease back of its Belgian distribution centre. The book value of this property was €5.6m. A further two property disposals are in progress and are expected to fund the costs of moving Balta Rug production to Turkey. | ||
Robert Walters (LON:RWA) (£76m | SR50) | “First half trading in-line with the Board's expectations.” Q2 net fees -4%, with growth in UK and RoW. Net cash of £17.2m. | AMBER/RED = (Roland) While there do appear to be some green shoots emerging, the decline in net fee income over the last five years has been remarkable and Robert Walters is structurally unprofitable at current levels. This could change (potentially quite quickly) but today’s update is in line and current forecasts suggest it will take another year for the group to return to operating profitability. While I recognise the turnaround potential here, I think there’s still some uncertainty about whether recruiters can return to past levels of profitability. At the risk of being too conservative, I’m leaving our moderately negative view unchanged ahead of this month’s interim results. | |
DP Poland (LON:DPP) (£66m | SR23) | System sales +17.5% to £34.8m, driven by network expansion and positive LFL growth. Store network increased to 139 locations at the end of H1. Remains confident in FY26 outlook despite a slower Q2 performance. Remains focused on conversion to franchise model. | ||
Orosur Mining (LON:OMI) (£65m | SR10) | The second hole (MAP107) in the current drill phase at the APTA project in Columbia reports a substantial gold intersection of 135m @ 1.91g/t Au, including 49m @ 4.06g/t Au. The hole ended in mineralisation. | ||
Poolbeg Pharma (LON:POLB) (£49m | SR28) | Raised £3.5m before expenses by issuing 58.3m shares at a price of 6p, a discount of 16.08% to the mid-market price of 7.15p on 13 July 2026. New cash is expected to extend the company’s cash runway into Q2 2028. | ||
Helium One Global (LON:HE1) (£43m | SR27) | The first production tube trailer has been sold and now left the Pinon Canyon Plant, concluding the early production commissioning and optimisation phase. Uptime and production fill rates have increased recently, with longer phases of stable operation. | ||
Lendinvest (LON:LINV) (£35m | SR34) | FY26 accounts due today will be “briefly delayed”. Auditor BDO has requested more time to complete its audit quality control procedures. The company has “not been told of any material audit issues”. FY26 expectations are unchanged. | ||
Celebrus Technologies (LON:CLBS) (£33m | SR51) | Revenue -39% to $23.6m with ARR +8% to $20.3m. Adj pre-tax profit -97% to $0.2m. Adj EPS 1.04c. Net cash of $32.5m, dividend of 3.39p. FY27 outlook: restructuring complete, strengthened pipeline, confident. | ||
Sosandar (LON:SOS) (£25m | SR70) | Revenue +14%, gross margin improved to 64%, Adj pre-tax profit +100% to £0.4m, in line with market expectations. Net cash of £8.4m. FY27: Q1 net revenue +22%, with website +7%. On track to deliver FY27 expectations. | ||
Hercules (LON:HERC) (£23m | SR34) | New civil projects as part of AMP8 in Thames Water region (c.£4.5m) and Anglian Water region (c.£1.6m). Civil Project awards in 9M FY26 now total over £15.7m, with the majority to be delivered in FY26 (y/e 30 Sept). | ||
Sealand Capital Galaxy (LON:SCGL) (£16m | SR3) | “Whilst the Board is mindful of the broader macroeconomic and geopolitical environment, it expects Group performance for the current financial year to be in line with its expectations.” | ||
Cellbxhealth (LON:CLBX) (£16m | SR13) | “We continue to be focused on disciplined execution and converting our commercial pipeline into sustainable revenue growth and, importantly, we remain on track to deliver revenues for FY 2026 of at least £2.1 million, a 50% increase on FY 2025.” | ||
Itaconix (LON:ITX) (£15m | SR22) | First customer supply agreement for Itaconix’s 8-gram plastic-free dish detergent tablets. Customer is a North American brand. Expects product to be on retail sale by the end of 2026. | ||
Headlam (LON:HEAD) (£15m | SR25) | H1 revenue -22.8% to £188.8m reflecting planned reduction in low margin revenue and various external headwinds. Significant H1 operating losses – “higher than H1 2025”. Net debt increased to £36.2m. Company pursuing refinancing and other options to support balance sheet. | RED = (Roland) [no section below] We’ve been resolutely negative on this flooring distributor for some time now and today’s update confirms my confidence in this view. Headlam appears to be in a bad situation, with revenue collapsing, mounting losses and a debt burden that needs refinancing. Such situations can escalate as customers and suppliers become wary of dealing with a distressed business. Headlam admits that “liquidity issues […] are negatively impacting its ability to trade effectively”. At the very least, I think the odds of an equity refinancing have increased further today. Unless some signs of stability emerge, I think this remains a stock to avoid. | |
Shearwater (LON:SWG) (£10m | SR47) | A 3yr, $1.2m contract to provide Core Email Protection for a large Japanese financial group. |
Graham's Section
Ashmore (LON:ASHM)
Down 2.5% at 209.8p (£1.5bn) - Trading Statement - Graham - GREEN =
This is a Q4 AUM update from Ashmore, the emerging markets asset manager.
Key points:
Net inflows $1.3 billion.
Positive investment performance $2 billion.
Result: AUM grows from $50.7 billion to $54 billion.
There’s growth across most categories, the one exception being External Debt (government bonds denominated in a foreign currency, typically USD), which saw outflows.
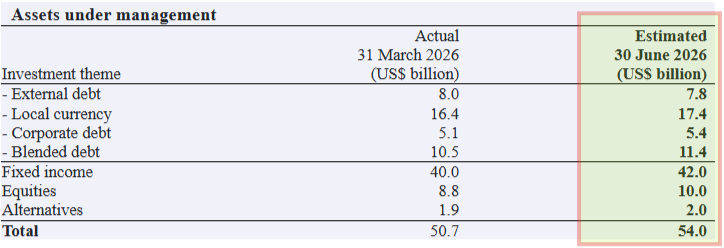
The emerging market large cap equity index rose by 24% - a figure which doesn’t seem to be reflected in the growth of Ashmore’s Equities AUM from £8.8bn to £10bn. But Ashmore say that their active management processes “continue to deliver outperformance for clients across the range of equity and fixed income strategies”.
CEO comment: I’m pleased to see that the CEO's comment is a little different this time, compared to the usual statement that fund managers are underweight EM.
Emerging markets performed well, demonstrating their diversity and resilience following the market volatility caused by the closure of the Strait of Hormuz and the corresponding oil price spike. Against this backdrop, Ashmore's active investment management approach has continued to generate excess returns.
However, this section was probably written before the oil price surge in the last few days:
The risk of a global inflation shock is reducing, provided hydrocarbon exports can be maintained through the Strait. Real incomes are recovering, and markets are beginning to reprice the prospect of a 'Goldilocks' environment, with reduced recession risk underpinned by significant capital spend on AI, energy security, defence and supply‑chain reorientation. Therefore, the forward-looking macroeconomic environment, together with the longer-term impact of recent US foreign policy, is expected to be supportive for EM.
Essentially, the argument is that a healthy low-inflation, low-interest rate environment will be positive for flows into emerging markets - boosting local economies and local asset prices.
The direction of travel of the US dollar is also key, with Federal Reserve rate cuts being very helpful when it comes to boosting the demand for more exotic currencies (although getting rate cuts out of Kevin Warsh might not be very easy in the short-term).
Graham’s view
Looking back, we had $2.3 billion of net inflows in H1, followed by $0.9 billion of outflows in Q3.
This latest Q4 inflow means that we get a positive net inflow result for H2 as a whole, even if it is marginal.
With the help of rising asset prices, AUM has made some meaningful progress, e.g. it was $47.6 billion a year ago. It’s therefor up by 13.4% for FY June 2026 - decent, especially considering that it was a bad year for geopolitics. That said, most of Ashmore’s funds are invested in Asia and LatAm, rather than the Middle East.
Valuation: the interim balance sheet had nearly £700m of financial assets (including nearly £300m of cash). This covers nearly half of the market cap.
For this reason, I don’t pay the headline P/E multiple much attention:
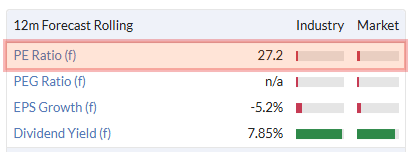
The fortress-like balance sheet explains why the company is able to pay such an enormous dividend (16.9p per share), despite not really having the earnings to do it. This stock is a case where ignoring both the headline P/E and the dividend yield might make sense.
I’ve been GREEN on Ashmore and with the net inflows announced today, I’m inclined to leave that stance unchanged. The shares are a little cheaper now compared to when I looked at them in April, while AUM has grown.
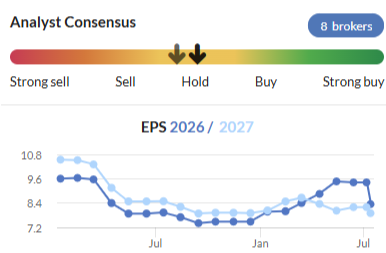
The City doesn’t like the stock, which personally I take as a contrarian buy indicator. EPS forecasts were downgraded recently despite the company not even making an announcement:
Most City analysts say “Sell” or “Strong Sell” (!).
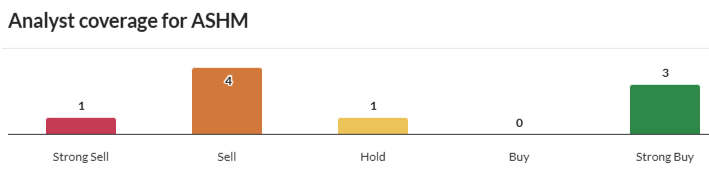
Your views may differ but I always get interested when I see this very negative sentiment, as it proves to me that a stock is unloved!
Watches of Switzerland (LON:WOSG)
Unch. at 749p (£1.75bn) - FY26 Results - Graham - AMBER/GREEN
There’s been a tremendous uplift here since the FY26 trading update in May.
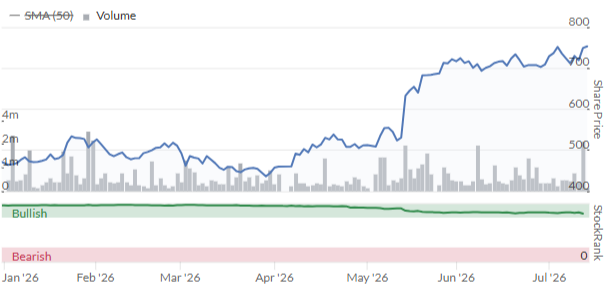
As we learned then, FY26 was an excellent year:
Revenue +13% at constant currencies
Adj. EBIT £155m (this is top of the £152-155m range given at the trading update)
Statutory operating profit (basically the same thing as statutory EBIT) is strong at £170m, though do bear in mind that under modern accounting rules this excludes a portion of the company’s rent payments.
But the statutory PBT number is strong too: £133.5m, which is after all rent payments.
Exceptional items collapsed to only £8.8m, compared to £55.5m last year. Great news.
Last year’s exceptional items included £44.5m of charges related to showroom impairments, while this year’s showroom impairment charge is only £6.5m. The cost of showroom closures was also about £5m lighter than last year.
Balance sheet net assets (tangible) are £309m, up from £235m last year. Net assets per share have increased too, as the number of shares actually fell during the year, thanks to some share buyback activity. Net debt (excluding leases) fell from £94m to £55m.
Outlook:
Guidance for FY27 is unchanged from that provided in the Q4 trading update. Trading in the first ten weeks has been encouraging. Whilst we remain mindful of the geopolitical environment, we have carried good US momentum into the new year and see encouraging signs the UK market is improving. This underpins our confidence in delivering another year of strong revenue growth, alongside a return to Adjusted EBIT margin expansion.
As a reminder, the Group has minimal direct exposure to the Middle East or tourist consumers…
This is now primarily a US business, so the strength of the US consumer is what matters most.
Detailed guidance for FY27 includes:
Revenue growth 5-10% (organically, over 52 weeks)
Adj. EBIT margin to increase 40-80 basis points from FY26
Graham’s view
We don’t have too many UK mid-caps stocks with such direct and heavy US consumer exposure as this one. This exposure appears to be benefiting Watches of Switzerland, and it’s doubling down on it:
The US offers significant opportunity for both market share gain and structural market growth, supported by a luxury consumer increasingly allocating discretionary spend to watches and jewellery
The UK, meanwhile, offers “stable and resilient” demand.
I’ve been moderately positive on WOSG and this is another case where I see no reason to change stance, especially considering that guidance is unchanged.
The main difference since I looked at this last is that the valuation has picked up:
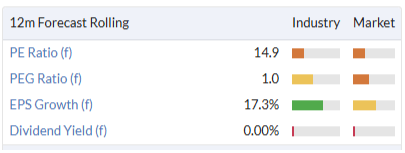
For retailers (not brand owners), this is starting to look a little expensive to me, and to Stockopedia’s computers:
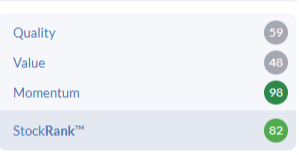
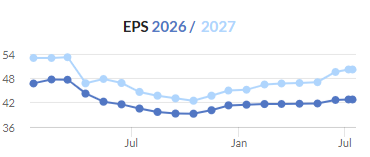
But the reasons for the gains are logical: US consumer exposure, rising EPS forecasts, reducing net debt, strong free cash flow being ploughed into expansionary capex, and clean results with few exceptional items. That’s a lot of reasons for positivity.
So I think that AMBER/GREEN remains the right call for us.
Roland's Section
Robert Walters (LON:RWA)
Down 6% at 99p (£72m) - Q2 2026 Trading Update - Roland - AMBER/RED =
It’s been a positive few days for the UK’s listed recruiters. Shares in Hays have risen by more than 30% since the company issued a trading statement on Friday. Pagegroup gained almost 20% yesterday after an in line trading update.
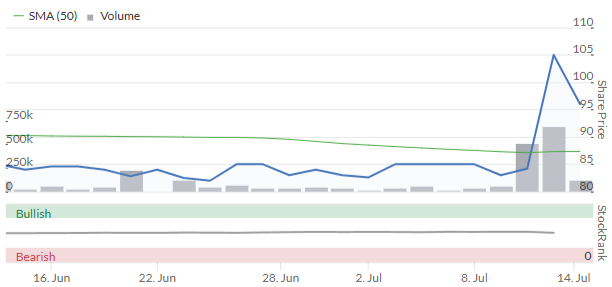
Against this backdrop, Robert Walters share price slump this morning may seem surprising, given that today’s update is in line with expectations. The reality is that the market had already priced in some less bad news from this firm. Despite this morning’s pullback, the shares are still nearly 15% higher than they were a week ago:
Q2 Trading: still shrinking
Today’s update covers the second quarter and the half-year to 30 June, providing an update ahead of the recruiter’s half-year results on 30 July.
As with Pagegroup yesterday, Robert Walters’ largest markets are still contracting.
Net fees fell by 4% to £134.6m in H1, as gains in the UK and RoW (28% of net fees) were offset by declines in Asia Pacific (45% of net fees) and Europe (27% of net fees):
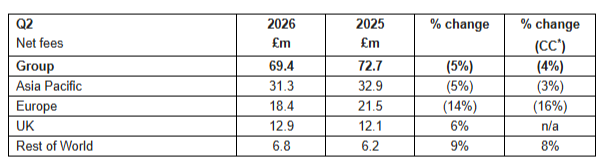
This pattern was mirrored across H1 as a whole.
However, there may be some signs of green shoots emerging:
Group net fees in June were up 1% year-on-year.
Drilling down to country level, the company reports that half of its top 8 markets saw net fee growth in Q2:
In specialist recruitment, Japan (+2%*), the UK (+21%), Spain (+2%*) and New Zealand (+16%*) delivered another quarter of growth among our 'top 8' markets.
The rate of growth is also said to be improving:
Around half (as a proportion of net fees) of the specialist recruitment portfolio grew year-on-year in H1 - a broader base than seen in the prior year (H2 2025: 20% in growth, H1 2025: 9% in growth).
In terms of operational performance, the company reports a shrinking headcount and improved productivity per fee earner in Q2:
Q2 net fee income per fee earner up 6% year-on-year, driven by a 3% increase in specialist permanent placements per fee earner per month;
Total headcount down 3% vs Q1 to 2,782
Fee earner headcount down 4% vs Q1 to 1,648
Sweating the [human] assets makes sense for a business that’s losing money, as long as service quality isn’t compromised.
Robert Walters’ net cash fell from £20.1m to £17.2m during the quarter – a decline described as “in line with expectations”.
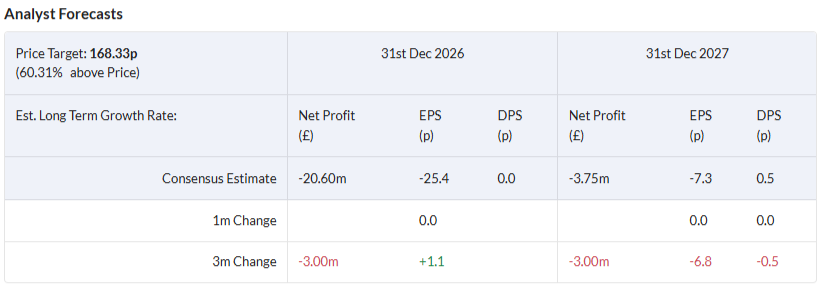
While the group’s net cash position provides a margin of safety and helps underpin the valuation, it’s worth remembering that the business is expected to remain loss-making in both FY26 and FY27:
Outlook
With thanks to Panmure Liberum on Research Tree, we have access to an updated broker note today confirming that forecasts are unchanged:
FY26E adj EPS: -26.0p
FY27E adj EPS: -10.5p
For what it’s worth at this early stage, PanLib is forecasting a return to profit in 2028 with earnings of 5.5p per share. If achieved, that would put RWA shares on a P/E of 17 – not necessarily all that cheap. However, if a recovery was to continue, profits could rise rapidly above this level – earnings peaked at over 50p per share in 2022.
Roland’s view
Here at the daily report, we’ve turned progressively more negative on recruiters as they’ve reported multiple years of declining fee income. Our concerns have grown that technology-led changes in this sector may have resulted in a structural loss of profitability.
I’ve reproduced the chart below from today’s Panmure Liberum note showing the near five-year decline in Robert Walters’ net fee income:
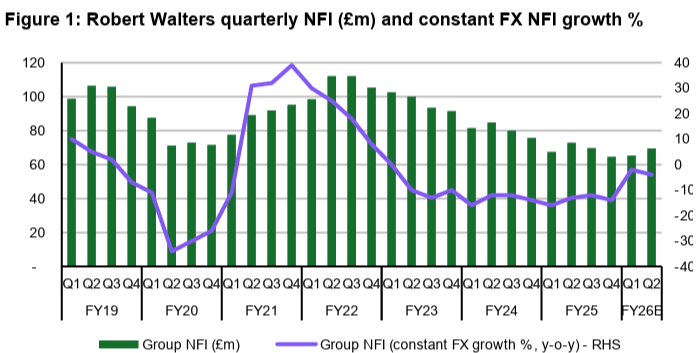
Source: Panmure Liberum 14 July 2026
The question that remains is whether this will turn out to be a normal cyclical decline and will eventually reverse. If it does, then the current depressed share price could provide an interesting opportunity:
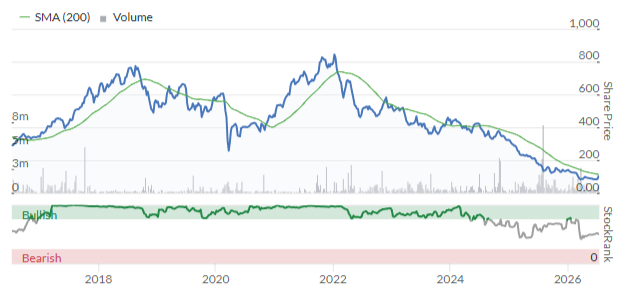
I don’t have the insight into this sector needed to understand the likely answers to these questions. But I’m concerned by the scale of the decline versus past dips:
Dividend suspended: the company didn’t pay a dividend last year. As far as I can see, the payout had not previously been skipped since 1999.
Operating losses: Robert Walters reported an operating loss last year and is expected to do the same this year. This tells us that the business is structurally unprofitable at current levels of activity. This hasn’t happened for at least a decade, probably more. In 2020, by contrast, gross profit fell by 25% but the business still generated a £15m operating profit.
According to Panmure Liberum’s forecasts, Robert Walters is expected to breakeven at an operating profit level next year. Ultimately, this is the bare minimum required for a sustainable business.
Staying negative runs the risk of missing out on the early stages of a possible recovery. On the other hand, the trend in forecasts has been negative and today’s update is no more than in line:
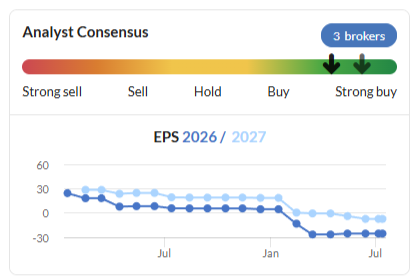
I think there’s a possibility the recruitment sector could reward in-depth research. However, based on the facts today, I’m going to leave our AMBER/RED view unchanged ahead of Robert Walters’ half-year results on 30 July.
BRCK (LON:BRCK)
Up 4% at 51p (£164m) - FY26 results - Roland - AMBER/GREEN =
Some companies are at the mercy of external market conditions more than others. Construction materials supplier BRCK is probably at the upper end of that spectrum. As the company explains in today’s full-year results, subdued conditions in housebuilding and other adverse market conditions mean that the business is facing some uphill battles at the moment:
The Distribution division saw revenue marginally behind prior year, which set against the ongoing and widely reported challenging market conditions is a resilient performance. Group brick volumes have been impacted by changing customer demands, project delays and customer mix. Timber revenue has grown through pricing accretion, whilst cladding distribution revenue has been impacted by the well-documented delays in project approvals by the Building Safety Regulator ("BSR").
There’s no sign yet that these adverse conditions are easing and this was reflected in June’s cuts to FY27 and FY28 broker forecasts – which I’ll return to shortly.
Today’s FY26 results are largely in line with expectations, but the statutory figures are marred by more than £13m of impairment charges relating to past acquisitions and some hefty restructuring costs.
FY26 results summary
Let’s start with a look at the main headline figures:
Revenue: up 1.3% to £645.4m (vs consensus of £650m)
Adj EBITDA up 4.5% to £51.0m
Adjusted pre-tax profit: up 4.9% to £38.3m (Cavendish: £37.9m)
Statutory pre-tax profit: down 46.2% to £6.3m
Adjusted EPS: up 8% to 8.91p (vs consensus of 8.6p)
Net debt up 6.9% to £60.5m (1.2x EBITDA leverage)
The apparent earnings beat seems to have been due to a lower tax rate than expected, so I’m not sure how meaningful this is given the high levels of profit adjustments applied here.
Profit adjustments: there’s a gaping void between adjusted PBT of £38.3m and statutory PBT of £6.3m. The big items on the list of adjustments are:
Amortisation of acquired intangibles: £13.2m
Impairment of goodwill and acquired intangibles: £13.4m
Business Change Project costs (i.e. restructuring): £1.7m
Unwinding of discount on contingent consideration: £2.6m
Fair value losses on contingent consolidation: £0.8m
Regular readers will know I’m not a fan of ignoring the amortisation charge when it reflects real past expenditure. But this is a routine item for many companies and it’s true that it doesn’t affect operating cash generation.
Of more concern perhaps is the £13.4m impairment charge relating to past acquisitions. The company says the “challenging market conditions” of recent years has affected the valuations of the businesses in question.
Digging into the footnotes reveals that the impairment charges apply to seven of the “12 smaller components of the group”, which are grouped together for reporting purposes. Goodwill assigned to all of the group’s larger subsidiaries is unchanged.
Restructuring costs are self explanatory – as we often remark, these tend to occur quite frequently in many companies. I would generally consider these to be operating costs, personally.
Finally, the contingent consideration items reflect changes in the present value of contingent consideration for past acquisitions. While these don’t directly reflect operating performance or cash generation, they are recurring.
These adjustments are all legitimate enough and commonly used. But collectively they give me the feeling that BRCK falls into the category of heavy adjusters.
To test this view, my general approach is to calculate free cash flow and compare it to reported and adjusted profit figures.
In this case, my sums suggest FY26 free cash flow of c.£19.5m before deferred acquisition consideration payments of £10.8m, giving an overall free cash flow figure of £8.7m.
These figures compare to an adjusted net profit of £28.7m and a reported net profit of £1.3m.
Opinions vary on how to treat each individual adjustment. But on balance, I feel that BRCK’s profits are more heavily adjusted than I’d like to see.
Divisional review: to get more of a feel for performance, I think it’s helpful to look at the segmental results for BRCK’s two operating divisions.
Distribution (80% of revenue)
Revenue: £519m (FY25: £521m)
Adj EBITDA: £34m (FY25: £33.2m)
Adj EBITDA margin: 6.6% (FY25: 6.4%)
UK brick markets saw a recovery during the first half of last year, followed by a slowdown in H2. The net result was an increase in total UK brick market volumes of 0.7% in FY26. Within this, BRCK appears to have underperformed the market, with brick sales volumes down 2% during FY26.
To make matters worse, “a highly competitive market” meant that average brick selling prices fell by 1.6%.
Trading with larger customers has been generally more resilient but offset by declining activity with some key social housing customers and other development projects being delayed as a result of the economic uncertainty and poor weather later in the financial year.
The picture was slightly stronger in BRCK’s timber distribution operations, where average selling prices rose by 4.8%, against a backdrop of a 2% decline in volumes. The result was a 2.8% rise in timber revenues.
Performance in other less material product areas was mixed:
Cladding distribution: revenue down 21.4% due to Building Safety Regulator delays and availability issues.
Roof tiles: volumes up 18.3% through extended distribution and new imported product lines.
Towelrads: revenue up 12.3% as demand grows for the larger radiators required as part of heat pump installations.
Design and Install (20% of revenue)
Revenue: up 8.8% to £126.4m
Adj EBITDA: up 2.5% to £24.4m
Adj EBITDA margin: 19.3% (FY25: 20.5%)
This side of the business is both higher margin and growing, albeit margins fell last year. This appears to reflect weaker demand from housebuilder customers. The decline in margins is specifically attributed to negative operating leverage in the Upowa solar installation business, which suffered “higher operating costs with labour utilisation rates being lower than desired”.
Despite this, revenue growth appears to have been achieved in cladding, renewables and roofing.
The Design and Install division has the potential to improve group margins. The company also says that it believes this side of the business is driven by factors that are less connected with the housing market, such as regulatory-led demand for fire remediation.
Outlook
When I last looked at this building materials distribution group in June, I noted the company’s brokers had slipped through a downgrade to FY27 and FY28 forecasts without this being mentioned in the RNS (which concerned the acquisition of the Jacksons fencing business). That’s poor practice (by the company) in my view.
The downgrade to FY27 was made despite the expected impact from the inclusion of Jacksons, implying that without this there would have been a larger cut to FY27 forecasts.
This has since become apparent on the StockReport:
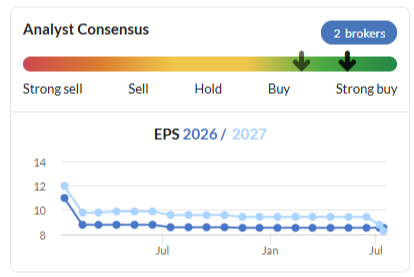
Cavendish has cut its forecasts for BRCK again today, but this relates solely to a change in BRCK’s accounting policies – share-based payment charges are now being included in adjusted EPS, having previously been excluded. All of the broker's other numbers are unchanged, so I don’t see this as a profit warning:
FY26 actual adj EPS: 8.9p
FY27E adj EPS: 8.3p (prev. 8.4p)
FY28E adj EPS: 8.8p (unch)
FY29E adj EPS: 10.3p (new forecast)
I would always include share-based payment charges anyway, so I’m glad to see the company’s adjusted profits move one step closer to my view of reality. However, what we can see is that this year’s earnings are expected to fall before (mostly) recovering in FY28.
Roland’s view
Based on today’s forecasts, BRCK shares trade on a forward P/E of less than 6x, with a 7.3% dividend yield.
My sums show last year’s dividend was just covered by free cash flow, after acquisition-related items. So I don’t see any immediate risk to this generous payout.
While BRCK does carry some debt, it doesn’t look unsustainable to me.
In my view, it’s clear that BRCK could be too cheap. This business should benefit from positive operating leverage when market conditions improve, driving a recovery in profit. But as things stand, it’s very difficult to guess when this might happen.
I think this situation is nicely represented by the stock’s Contrarian styling and high QV StockRank:
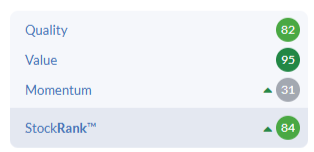
On balance, I don’t see any reason to change our AMBER/GREEN view today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

42 comments
SK Hynix (NSQ:SKHY)
UP 23%!
All the best
Blimey, just seen International Business Machines (NYQ:IBM) is down 25% for the day, which looks mad until you see that it is just back to the price it was at in May! And here I was thinking IBM was a pretty boring business
But it was over $300 in February.
Infrastructure business has performed poorly, but think investors are spooked because it was an early announcement due to missing the mark. Interesting that a comment on yesterday daily report mentioned quantum computing - IBM well placed for this and have multiple research projects ongoing but is a fair way off commercialisation.
Hi,
This article from Yahoo Finance explains things beautifully. Basically customers high capital expenditures on hardware had caused many companies to shift budgets away from software spending.
https://finance.yahoo.com/mark...
Hi, Has Hunting (HTG) issued a Q2 trading update today?
Hunting (LON:HTG) l can't see anything but Stocko says there is one.
H1 26 TU is scheduled for tomorrow 15th July
HTH
thanks
Thanks for the comprehensive analysis of BRCK (LON:BRCK). I’m waiting for the mooted building recovery to become a reality.
Well l suppose new council houses may require bricks?
US CPI data for June has been released and is supportive with fuel prices helping CPI to fall month on month - helping the 12 month number fall below 4%. This reverses the headline grabbing positive number last month but the bond market shrugged it off as a non event anyway. So it shouldn't be too much of a surprise that this number also isn't doing much. As usual the trouble is "other" stuff is going on and obviously in the last few days fuel prices have been rising again as the cease fire appears to be on shaky ground. I have suggested before that the real problem at the end of the year is the CPI will likely be moving up, the wrong way and too high....as weak numbers from the previous year fall out. It would take a few months of these negative numbers to help....so although today's numbers helps the rate backdrop....it doest actually move the dial yet.
Net net its a positive move on inflation ie Down - but we do need more. Equities have risen and bond yields are also down a little. However the market shrug last month to the very positive data makes sense. It goes without saying that if CPI data really behaves ( ie falls) ...this will become something else to worry about.... but we are not there yet.
Rubio is promoting the International Waters line (with no charges) whilst his boss is talking about 20% levies. Chaos replacing consistency is a sort of strategy, but not for anyone running a business or possibly a Govt.
I met a high ranking fund manager at one of the big American banks last year and he told me one of his best friends served high up in the administration during Trump's first term. He told me there was near zero forward planning done and everything was on a reactionary basis.
This has been said by many of those who served Trump in his first term. I think basically he surrounds himself with sycophants, who do not challenge him on anything. He watches Fox News whilst eating burgers and sending out wild Trump "truth" posts like a deranged toddler.
Morning All,
ME International (LON:MEGP) any negative broker notes this morning?
Nothing I'm aware of I would imagine its possibly short term traders who took the chance of bottom fishing before yesterdays results getting out at a small (ish) short term profit.
Boohoo (LON:DEBS) Would be interested in a review by the team.
They are claiming a successful turnaround. These very rarely occur, is DEBS an exception to this rule or is it all smoke and mirrors?
Boohoo (LON:DEBS)
I would say its a job half done - they haev fantastically well to get where they are now - from where they were 2-3 years ago (a bloated mess that had lost control of everything)
It seemks like every update nowadays is positive - and its of the reeal value that if flowing through with regard to future numbers on stocky trending in the right direction.
the 2028 forecasts now showing an expected profit of £22 mill - so thats perhaps the final piece of the jigsaw in that they expect to be back to decent net profits next year. adn this year they expect some profits £8 mill.
On this basis i would say the company should now be firmly off the naughty step.
Should one perhaps be worried whetehr AB is going to throw a spanner in the works and remove all their potential profit in one fould swoop with hugely increased rates / other charges for their large warehouse units. I fear there has to be some risk here that they could be teh fall guy to help the smaller shops get a better rates deal.
Fair play to current managemnt for turning this one around - its just all so sad that they ever lost the plot spending hundreds of millions on head offices and worldwide domination plans.
Perhaps slightly annoying for long term holders that they did a cash raise recently - annoying that they didnt play hard ball and manage without cash raise - perhaps with tehir debt they had little option there.
Good morning all. I'm embarrassed to ask about this £2.8 million market cap company but did one of our dogs just bark quietly? I've been reluctant to to take the capital loss on Getech and after reading today's HY TU added yet another 10,000 shares for £200. I like the stable ARR which they are concentrating on, the slightly better cash in the bank and slightly bigger order book. Adjusted EBITDA of £200,000 against a loss last HY of £100,000 is more optimistic too. Any comments much appreciated. We don't hold LON:BRCK but I'm interest in it as we have a substantial holding in Michelmersh Brick Holdings.
BRCK (LON:BRCK) for the company tag!
re Getech (LON:GTC) As you say, a long-standing dog, and one which I also hold. 15% revenue growth sounds like a pretty definite bark to me. A market cap of 3 million odd doesn't seem much to pay for nearly 6 million of revenue, half of it subscription. The market cap seems much too small for a public company, so I expect a return to reasonable profits will flush out a bid somewhere along the line.
Or a potential dreaded delisting... but I note that the shareholder base is quite diverse.
The problem is, the growth seems a struggle at Getech (LON:GTC) at this low base. £2.8m ARR (so £1.4m for H2) and an expected £1.6m conversion from the order book equals £3m H2 revenues.
Last H2 they did £2.9m. Barely growth there.
They already have 4 of the top 6 supermajors as clients. Could this be their potential maximum?
I don't hold currently but did in the past (when it went up to 30p+ on hydrogen frenzy) and sold out then. Been waiting for a point to get back in since then, but never could get myself over the line and comfortable to re-invest.
I agree with you The Boon Fund. We also had a decent profit a few years ago and stupidly went back in too heavily at what I thought looked good value -- it wasn't! A mistake I repeated even more heavily with Watkins Jones, another dog I'm reluctant to put down.
Is it just me or does anyone else think that it is utterly ridiculous when companies like Sosandar (LON:SOS) do share buybacks? Here is a company that has consistently failed to achieve meaningful profitability or generate cash. Its share count has gone from 152m in 2020 to 248m now as it has returned with the begging bowl several times. Now it wants investors to believe that all is so rosy that it can buy those shares back (never mind that they are worth considerably less than investors paid for them in those fundraisings).
It isnt just you, Sparkler.
Alright armchair CEO...
Give us your thoughts on what you think Sosandar (LON:SOS) should do with its cash...
Personally think they would be better spending more on marketing to support top line growth
Well, let's see. How about one of those old-fashioned things - a dividend? Oh wait a minute, they probably don't have enough distributable reserves for that. Maybe they could continue rolling out the physical stores, since they suddenly decided that they were now key to their strategy!
What they should actually do is a one off return of capital to shareholders. This actually gets the surplus cash back in the hands of all shareholders rather than trying to prop up the share price with regular market purchases that simply soak up institutional selling.
For many small & mid caps there isn’t sufficient liquidity in their shares thanks to our moribund stockmarket. Share buybacks mean the company creates its own liquidity hence why there are so many in place
Institutional shareholders encourage companies they have shareholdings in to buy back their own shares to at least maintain the share price (& hopefully increase it).
I cannot see this situation changing until liquidity & with it the market improves
Correct 100%!
All the best
For some reason the interims from RM (LON:RM.) (I hold ) which were published this morning have not been included in the above table. Could that be rectified please and as this is a a turnaround sceanario it would be great to get an assessment of where they are in the cycle
Be great if you get a chance to have a look at Ashmore (LON:ASHM) team, some fund managers seem to be having their second wind, I'm 50-50 on this one has just under 8% yield but uncovered, from memory they specialise in emerging markets which many are saying is the place to be. They also own a load of venezualain bonds that were viewed as under valued after Trump's takeover of the country not sure if that's still the case though.
Brief summary from me as now heading out the door to work as always happy for any replies positive or negative in relation to this one.
I thought they looked reasonably good but observe most of the positive AUM move is performance and Ashmore (LON:ASHM) have always been high Beta managers. So they do well when EM does well. This makes them a geared play on the positive EM view....but it backfires if EM return trends are not so good. They almost always increase their exposure in downturns which magnifies the pain but then you benefit even more on the way back up. I don't hold but consider it when all the ducks line up for EM.
Thanks RD always appreciate your input.
Morning all. What are the non cash adjustments in the BRCK (LON:BRCK) basic EPS 0.4p that give an adjusted EPS of over 8p? Are they reasonable?
Morning Revs8,
I am sure we'll be taking a look at BRCK (LON:BRCK) this morning!
Roland
Thanks for the very thorough review of the accounts Roland. It really benefits those of us without an accounting background.
Please see Note 5 for an explanation.... the easy answer is always no (unless the company have done a one off transaction that resulted in a lot of additional transitional expenses). This doesn't seem to be the case as far as I can see.....and writing off goodwill and ignoring it as an expense when you paid it....doesnt make much sense to me. Nor the market, which is why the share price suggests that the 8p EPS number is ignored - see the rating. The length of note 5 suggests they go to great lengths to persuade the market they are more profitable than they are.... all of which is a great red flag IMO.... I dont hold and am no expert but my brief look at this note puts me off plenty.
I would disagree - nearly all the adjustments appear to be non-cash accounting adjustments, principally amortisation and a couple of large goodwill impairments. These have no impact on actual cashflow which appears strong. However, the market is clearly sceptical.
Ok no problem - we can agree to disagree... overpaying for targets and investment and ignoring the write off as its non cash of course makes cashflow look better.... oldest trick in the book imo.
Decent robust results and look good value IMO and a large dividend on offer. Don't forget the recent bid approach which was well ahead of where the SP is today.