Daily Stock Market Report (Mon 8th June 2026) - BKS, MPAC, TATE, BRCK, BOOM, PPH

Mid East tensions continue to rumble with Israel and Iran firing missiles at each overnight. In Iran, there have been explosions in Tehran, at various military targets across the country, and at a petrochemical complex in the city of Mahshahr. This comes despite reports that President Trump told Israeli PM Netanyahu to not respond to Iran’s missile strikes.
As a consequence, oil is back testing recent highs although it remains below the levels seen in early May.
In markets, AI-related shares fell sharply on Friday afternoon after another very strong US jobs report saw 172,000 job gains. The Nasdaq fell by over 4% as investors started to price in the potential for rate hikes rather than rate cuts later this year. This negative sentiment continued overnight in the Korean market, where the Kospi index fell by more than 8% at the open.
Overnight market movements:
The FTSE is set to open down 0.75% at 10,300
S&P 500 is up 0.3% at 7,380
Brent crude is up 5% at $97.35
Gold is down 0.75% at $4,300
Bitcoin is up 1.6% at $62,800
Wrapping it up there, thank you. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Balfour Beatty (LON:BBY) (£3.9bn | SR75) | The independent compliance monitorship of its U.S. subsidiary Balfour Beatty Communities, LLC required by the U.S. DoJ formally concluded on 6 June 2026. A number of improvements were made during the monitorship period. | ||
Tate & Lyle (LON:TATE) (£2.2bn | SR75) | Cash offer from Ingredion for up to 615p per share, comprising a payment of 595p per share, plus the right to dividends totalling up to 20p per share. This offer represents a 58.7% premium to the undisturbed closing price on 13 May 2026, or 64% including dividends. | TAKEOVER (Graham) | |
PPHE Hotel (LON:PPH) (£821m | SR41) | PPHE clarifies that the entity within the Fattal Hotel Group which is proposed to be the offeror for PPHE (should an offer be made) is Fattal Hotels Ltd. This entity is also the owner of 1.66m shares in PPHE. The MD of Fattal Hotel Group also owns 1,350 PPHE shares. | TAKEOVER (Graham) [no section below] The Managing Director of M&A at Fattal Hotels - who are hopefully going to buy PPH - was personally buying PPH shares on 14th November 2025, the same day that PPH's major shareholders announced that they were planning to hold meetings with a view to potentially selling their stakes. Although he only bought 49 shares that day (for less than £1,000!), this transaction changes the minimum lawful price at which the takeover of PPHE can take place. Thankfully, the deal can still go ahead at £22 per share. This MD is "a core member of the deal team in relation to the offer", and personally holds 1,350 shares, worth nearly £30k at the proposed takeover price. I don't think any of this affects the likelihood of the transaction going ahead, but I do find it interesting and surprising that someone so close to it could personally profit from it in this way. | |
Boohoo (LON:DEBS) (£328m | SR23) | New partnership to develop beauty and fragrance products across Debenhams Group brands. First collections will launch ahead of Christmas and will include ranges for PrettyLittleThing, Karen Millen and boohooMAN. | ||
Pensana (LON:PRE) (£320m | SR6) | $250m development of Longonjo is on target and on budget for commissioning in 2027 with a 20yr mine life and initial MREC production of 20kt. A “multi-partner offtake framework has been established”. | ||
On Beach group (LON:OTB) (£210m | SR38) | Commencing a buyback programme for up to £10m for completion by 31 Dec 26. Shares purchased will be cancelled. Equivalent to 4.8% of share capital at the current share price. | ||
BRCK (LON:BRCK) (£160m | SR81) | Jacksons was founded in 1947 and supplies premium timber and steel fencing, gates and perimeter security systems. BRCK is acquiring the business for £15m plus £4.9m for freehold land and property and deferred consideration of up to £11m. Jacksons generated EBITDA of £4.2m in FY25 and had net assets of £26.1m. Cavendish forecasts cut: - FY27E adj EPS: 8.6p (prev. 9.6p) - FY28E adj EPS: 9.1p (prev. 10.0p) | BLACK (AMBER/GREEN ↓) (Roland) This acquisition seems reasonable to me, but I’m disappointed to see broker Cavendish has cut its FY27 and FY28 forecasts without the company making any mention of a change to expectations in today’s RNS. While BRCK shares still look potentially good value to me as a Contrarian buy, I think today’s revised guidance justifies a more cautious stance. I’m downgrading our view by one notch ahead of BRCK’s FY26 results, which I expect in July. | |
KEFI Gold and Copper (LON:KEFI) (£157m | SR19) | 2025 operating loss of $(6.7)m with year-end net cash of c.$8.5m. Confident in the development of the Tulu Kapi mine, which has arranged financing of more than $400m and is targeting production in mid-2028. Tulu Kapi is expected to generate annual EBITDA of $355-697m in its first three years of operation, based on gold at $3k-5k/oz. | ||
Pharos Energy (LON:PHAR) (£120m | SR92) | $12.6m received year-to-date, “clearing all receivables due in Egypt” including the collection of contingent consideration from its farm-out partner IPR. Returned to drilling in Egypt, with the first well spudded on 4 June. | ||
Beeks Financial Cloud (LON:BKS) (£111m | SR17) | “Beeks has signed a 5-year contract with a total value of $4.8m with one of the world's largest banks for deployment of the software in one area of its trading infrastructure. Revenue recognition is set to commence immediately, further supporting the Board's FY26 expectations.” | AMBER ↑ (Roland) Investors are evidently relieved that Beeks continues to expect to meet full-year expectations – as we identified in February, H1 performance suggested a revenue shortfall for the remainder of the year unless some new revenue was secured. I continue to have concerns about the profitability and capital intensity of this business and think our cautious view this year has been appropriate. However, I’m willing to move up one notch to neutral today to reflect Beeks’ reduced valuation and in-line guidance. | |
Audioboom (LON:BOOM) (£101m | SR26) | SP -14% Three non-binding offers were received for amounts over 540p per share. The board has concluded these all undervalued the company and has terminated discussions and concluded the strategic review. Trading: strong start to the year continued into Q2; expects to report H1 revenue of at least $45m, with adjusted EBITDA of at least $3m. | AMBER ↑ (Graham) [no section below] The market is disappointed today that no immediate takeover is happening at this podcast publisher, but I think it makes sense for us to upgrade our stance to neutral on the grounds that three separate parties were (apparently) willing to offer more than 540p. With a current share price of 480p, it would be churlish for us to remain negative on this share. That being said, I'm still quite cautious when it comes to Audioboom, due to repeated disappointment in the past. For the record, Cavendish are forecasting revenue of $94.5m and adj. EBITDA of $7.2m this year, converting to adj. PBT of $6.5m. Perhaps I'll need to be a little more open-minded in future about this, as I don't think the valuation is objectively extreme at this level. With 31 cents of adjusted EPS according to Cavendish, the adjusted P/E multiple for the current year falls to about 20x. Perhaps not so crazy, if the current growth trajectory continues? Q1 organic growth is estimated at c. 19%. | |
MPAC (LON:MPAC) (£79m | SR39) | Trading affected by delays in customer decision making, heightened pricing pressure and negative operating leverage from lower volumes. H1 margins are now expected to be lower than last year, with FY26 underlying pre-tax profit “substantially below current market expectations …”. Sale of Lambert subsidiary for initial consideration of £16m. - Shore Capital cuts FY26 EPS estimate by 44% to 21.0p. | BLACK (RED =) (Roland) This is a big profit warning that’s only made slightly more palatable by the sale of a loss-making subsidiary to reduce debt. Mpac is getting its money back on Lambert, having acquired it for £15m in 2019. But I estimate leverage will still be close to 2x EBITDA, while trading conditions and margins in the group’s core business remain under pressure. This is the second profit warning from Mpac in the last year – I think it makes sense to remain cautious until there’s more clarity on trading and the balance sheet. | |
Helix Exploration (LON:HEX) (£73m | SR16) | Agreed to acquire 100% of membership interests of Treasure State Drilling LLC for $600k through the issue of new shares. The main asset held by TED is the drilling rig which has drilled all of Helix’s existing Rudyard production wells, lowering future drilling costs. | ||
Cora Gold (LON:CORA) (£73m | SR28) | Now that Sanankoro is fully funded, CORA is focused on expanding the current JORC compliant mineral resource estimate, extending Reserve mine life beyond the current 10.2 years and supporting future production growth. | ||
MTI Wireless Edge (LON:MWE) (£61m | SR95) | The contract for the supply of communications infrastructure to the Israeli Ministry of Defence has doubled in value, increasing from US$2.2m to approximately US$4.5m. | ||
Revolution Beauty (LON:REVB) (£40m | SR38) | Debenhams and Revolution Beauty have agreed a new licensing partnership to develop beauty and fragrance products across Debenhams Group brands. It’s a related party transaction as Boohoo/Debenhams is the largest shareholder in REVB. | ||
Zenith Energy (LON:ZEN) (£32m | SR23) | Acquires an additional 5 MWp ground-mounted photovoltaic development project in Rome. Total consideration €440k. | ||
Skinbiotherapeutics (LON:SBTX) (£25m | SR n/a - suspended) | Investigation findings: “Accrued royalty revenue of £0.77m was inappropriately recognised [in FY25]...No other issues related to revenue were identified. Documentation provided as support for the FY25 accrued royalty revenue was identified by FRP as fabricated by the former CEO; no evidence has been identified to indicate that anyone else was involved or aware of the fabrication.” Trading on AIM restored today. Cash position £1.5m as of 31st May. | ||
Neo Energy Metals (LON:NEO) (£20m | SR20) | The Board has suspended the CFO while investigating potential misconduct. The misconduct allegation is not in respect to any financial mismanagement, impropriety or wrongdoing and the Company's financial position has not been impacted. | ||
Great Western Mining (LON:GWMO) (£19m | SR23) | GWMO’s shares have been approved to trade on the OTCQB Market in the US and will commence trading at the market open today under the ticker symbol "GWMOF". | ||
IXICO (LON:IXI) (£19m | SR12) | IXI has added three further experts to its Scientific Advisory Board. | ||
Aptamer (LON:APTA) (£18m | SR8) | New funded research programme with Imperial College London, supported by the Gates Foundation. | ||
Oriole Resources (LON:ORR) (£15m | SR27) | Total JORC Inferred Mineral Resource Estimate at the 50% owned Mbe orogenic gold project currently stands at 1.23 million oz contained gold. Results for holes MBDD043 and MBDD044 have returned 23 mineralised gold intersections. | ||
Total Graphite (LON:TGR) (£10m | SR6) | The Board has initiated a graphite portfolio optimisation programme to evaluate the options available to accelerate development and maximise value for all shareholders. |
Graham's Section
Tate & Lyle (LON:TATE)
Up 14% at 558.5p (£2.5bn) - Recommended cash acquisition of Tate & Lyle PLC - Graham - TAKEOVER
On 14th May, we learned that Ingredion were considering a takeover of Tate & Lyle for 615p: 595p plus 20p of dividends.
Today we learn that both Ingredion and the TATE Board are happy to go ahead with this, and we have the formal proposal.
Premium: It’s a 58.7% premium to the share price on 13th May, and an even higher premium when measured against the average price prior to that date.
Shareholder support: there are irrevocable undertakings to support the takeover from shareholders holding 17% of the company.
Rationale from the TATE Board:
The Tate & Lyle Board remains fully confident in the ongoing execution of its strategic plan and that its successful delivery through volume-led growth and strengthened financial performance will create value for the Tate & Lyle Shareholders over time. However, the financial performance in the 2026 financial year was disappointing and, while actions are being taken with urgency to return the business to top-line growth, the continuation of the current challenging market environment creates risks and uncertainties in the timing of delivery of Tate & Lyle's financial algorithm.
The so-called financial algorithm targets “4-6 per cent. organic revenue growth, Adjusted EBITDA growth ahead of Revenue, and Adjusted EPS growth ahead of Adjusted EBITDA”.
In FY March 2026, both revenue and adjusted EBITDA declined by 3% organically.
For FY March 2027, the company has guided for “modest revenue growth” and “broadly flat EBITDA” excluding a $20m charge.
It seems to me that the Board may have realised that they are unlikely to achieve the financial algorithm in the near-term.
We learn that Ingredion’s offer was unsolicited and that they initially proposed to pay 530p, with some of this being in the form of shares rather than cash. Negotiations led to four further proposals, culminating in the 615p cash offer.
This is 9x adjusted EBITDA for FY March 2026. As such, it’s “an attractive opportunity for Tate & Lyle Shareholders to realise a certain cash value… relative to the risks inherent in the execution of Tate & Lyle's strategy.”
Rationale for Ingredion is straightforward:
“Bolstering Ingredion's portfolio and creating significant strategic growth opportunities”
“Creating a complementary and differentiated portfolio for texture and sugar reduction”
Et cetera
Ingredion sees synergies of approximately $130m, at a one-off cost of $175m.
Graham’s view
It always leaves a bitter taste when a struggling company accepts a takeover offer - there is a sense of “what might have been”.
In the chart below, I’ve put a circle around the date when TATE announced that it was making the $1.8 billion acquisition of CP Kelco:
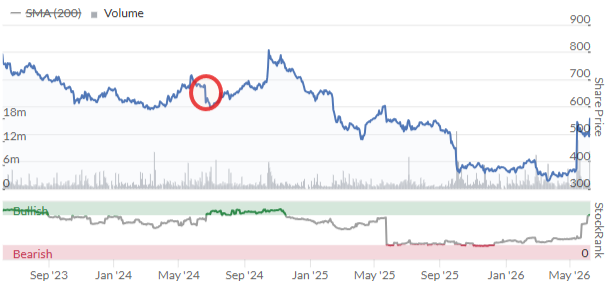
Just before they announced that, two years ago, their shares were trading at 670p, nearly 10% higher than today’s takeover offer.
The company’s leverage multiple had been a lowly 0.5x, following disposals. It moved up to 2.2x after buying CP Kelco
And in hindsight, what value did this acquisition create?
As for the bigger picture, I’m becoming rather wary of ingredients businesses. They’ve always felt a little inscrutable but it seems that the competition in the space might be particularly intense these days, with changing consumer tastes adding to their unpredictability.
And with low ROCE, firms in the space have turned to leverage to boost returns:
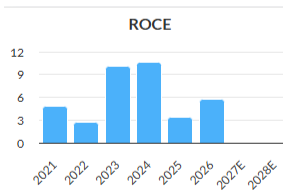
Ingredion (NYQ:INGR) has much higher ROCE numbers than Tate, but they too are moving up the risk spectrum: their leverage multiple will rise temporarily up to 3x in order to fund this deal.
Roland's Section
Beeks Financial Cloud (LON:BKS)
Up 16% at 188p (£128m) - First Market Edge Intelligence® customer - Roland - AMBER ↑
Beeks Financial Cloud Group plc (AIM: BKS), a cloud computing and connectivity provider for financial markets, is pleased to announce that it has secured its first contract for Market Edge Intelligence®, the analytics platform that brings AI-powered insight directly to the colocation edge.
Beeks has signed a five-year contract with a total value of $4.8m with “one of the world’s largest banks for deployment of the software in one area of its trading infrastructure”.
Importantly, revenue from this contract will help Beeks meet full-year forecasts for the current financial year, which ends on 30 June:
Revenue recognition is set to commence immediately, further supporting the Board's FY26 expectations.
In February and March I flagged up my estimate of a c.£4.5m shortfall in revenue visibility needed to meet full-year forecasts. The wording of the statement above doesn’t (quite) guarantee that full-year revenue estimates have been met, in my view, although it’s presumably very close.
This interpretation is supported by a new note today from house broker Canaccord Genuity. CG’s analysts estimate that today’s announcement and another recent win have unlocked £3-4m of additional revenue towards full-year forecasts. My reading of this is that they think Beeks is almost there, but perhaps not quite.
Investors are evidently more confident than previously that Beeks will meet FY26 forecasts.
It’s too soon to know how large the addressable market for the company’s new Market Edge Intelligence service might be, but as an added-value software product, I would expect it to contribute higher-margin revenue than the group’s core infrastructure business.
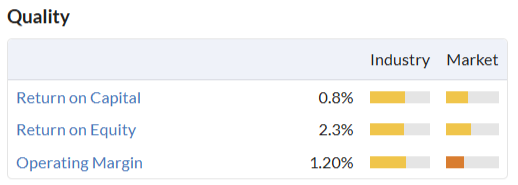
If I’m right (and uptake continues), this could help to improve Beeks’ rather average profitability metrics:
Roland’s view
Beeks’ share price is down by 20% this year and it seems to have been a tight race to meet FY26 forecasts. I think our cautious view this year has been appropriate.
Interestingly, the StockRanks have reached a similarly cautious conclusion by a purely quantitative approach
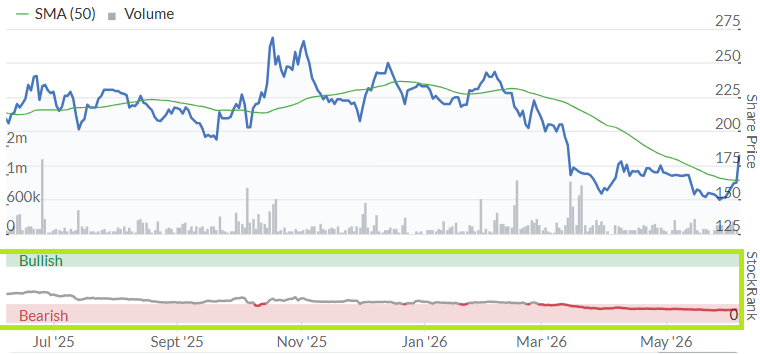
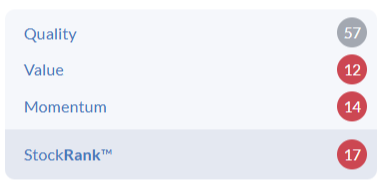
Beeks’ StockRank of 17 is unusually low for a profitable, established business, and highlights weak value and momentum – a classic Falling Star profile. It will be interesting to see if this improves at all after today’s update:
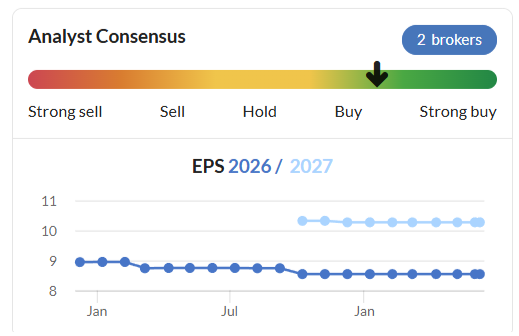
Despite this, broker forecasts have remained stable this year and continue to suggest continued double-digit EPS growth over the year ahead:
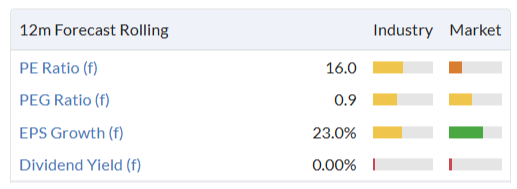
A sub-1.0x PEG ratio also highlights the possible relative value on offer here from rapid earnings growth, despite the high-teens P/E:
I continue to have concerns about the profitability and capital intensity of this business.
But in the interests of balance, I am willing to move our view up by one notch to neutral today to reflect Beeks’ reduced valuation and in-line guidance. AMBER ↑
MPAC (LON:MPAC)
Down 12% at 231p (£70m) - Trading Update and sales of Mpac Lambert for up to £20m - Roland - BLACK (RED =)
In April, Graham concluded there was “a very high risk of a profit warning” from high-speed packaging specialist Mpac. He cut our view down to RED, citing a fragile balance sheet, unhelpful reporting style and departing CFO.
This decision has proved prescient – today we have a nasty profit warning that’s led the company’s house broker to cut its earnings forecasts for this year by 44%.
Mpac’s weak balance sheet and unhelpful reporting style are also on display; there’s no guidance in today’s RNS as to reduced profit expectations and the company is selling a subsidiary to help reduce debt.
Key points
Trading Update: in April Mpac warned of an H2 weighting, with “uncertain market conditions” and said the Middle East conflict was affecting the timing of customers’ capital investment decisions.
Lower order volumes and price competition were also said to be putting pressure on gross margins.
This situation has continued and the company has taken steps to “align operational capacity with current demand levels, reduce overhead costs and to improve cash generation”.
The order book improved to £98.8m at the end of May (31 Dec 25: £90.0m).
Revised Outlook:
Accordingly, the Board now expects first half margins to be below the prior year, and FY 2026 underlying profit before tax to be substantially below current market expectations on a like-for-like basis.
While this is clearly a serious profit warning, the company’s commentary isn’t as clear as it could be.
Today’s RNS doesn’t include details of previous or revised expectations. Nor does Mpac explain the like-for-like basis, although I assume this relates to the disposal of Lambert.
Fortunately brokers Shore Capital and Panmure Liberum have both made updated forecasts available on Research Tree this morning – many thanks.
Here’s a summary of the Shore Capital estimates (Shore is Mpac’s Nomad):
FY26E adj EPS -44% to 21.0p (previously 37.5p)
FY27E adj EPS -35% to 28.2p (previously 43.3p)
Shore also splits out the impact of today’s disposal, providing like-for-like figures that compare revised expectations with prior performance ex-Lambert:
LFL FY26E adj EBIT £12.3m (-27% vs £16.8M previously)
Lambert Disposal & Balance Sheet: today’s update contains a clear warning that the balance sheet is under pressure:
The Group continues to focus on maintaining appropriate liquidity and covenant headroom. This position will be materially improved by the proceeds from the sale of Lambert.
To address this risk and further focus the group on packaging machinery solutions, Mpac has agreed the sale of its Lambert subsidiary. This business is based near York and specialises in bespoke product assembly processes.
£16m disposal: Lambert has been sold to Italian automation technologies firm Mech.i.Tronic S.p.A. for an initial cash consideration of £16.0m. A further £4m of earn-out consideration may become payable, although I note that Shore Capital has excluded these from its modelling.
Mpac purchased Lambert for £15.0m in 2019, so this investment appears to have largely wiped its face, although the business generated a pre-tax loss of £1.6m last year.
The main rationale for the sale seems clear:
The net proceeds from the sale will be used to significantly reduce Group net debt, which stood at £47.9m at 31 December 2025.
Roland’s view
Using today’s revised broker forecasts, I estimate that net debt of £48m would equate to a net debt/EBITDA leverage multiple of 2.8x. That’s higher than I’m comfortable with and may be higher than the company’s lenders want to see, too.
I would guess that the Lambert disposal will presumably reduce net debt to something closer to £30m, bringing the leverage multiple under 2.0x.
However, I’m not sure that’s enough to persuade me to take a positive view of Mpac. This stock is styled as a Value Trap by the StockRanks, a view I think is fair. It looks perennially cheap but appears to lack any major competitive advantages or pricing power.
Expenditure on acquisitions has lifted revenue but so far failed to generate any additional profit – a situation worsened by today’s warning:
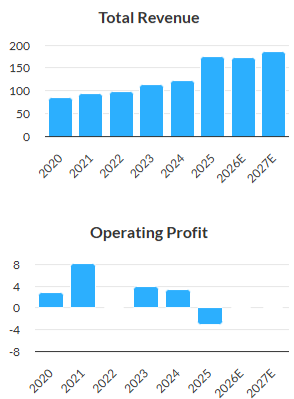
The picture may improve over the coming years, but this is the second profit warning in 12 months:
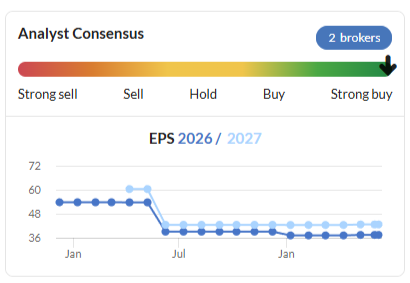
While the reduction in net debt from the sale of Lambert is helpfully, leverage remains relatively high and I am inclined to remain cautious. Checking the 2025 results, I see that the company mentions its compliance with banking covenants (often an indicator that cover is getting tight) and will need to renew its debt facility in 2027.
Additionally, the scale of today’s cut to forecasts means that Mpac’s forecast P/E has actually risen today to 11x FY26 earnings (previously 7x). In other words, the shares are more expensive than they were on Friday, based on current expectations.
I could probably justify moving our view up by one notch to AMBER/RED today on the basis of the reduction in leverage.
However, given the scale of today’s profit warning, I’d prefer to have more clarity on trading and the state of Mpac’s balance sheet before moderating our view. I’m going to stay RED for a little longer.
BRCK (LON:BRCK)
Down 0.2% at 49.5p (£159m) - Acquisition of H.S. Jackson & Son - Roland - BLACK (AMBER/GREEN ↓)
We’ve generally been positive on this construction materials distributor in recent months and my view remains broadly favourable.
Today’s acquisition looks like a sensible deal at a reasonable price, in my view.
However, updated coverage from the company’s house broker today also flags up a cut to earnings forecasts for FY27 and FY28. This has led me to the reluctant conclusion BRCK has pushed out a hidden profit warning through its broker.
Let’s take a look.
Acquisition
BRCK has acquired H.S. Jackson & Son (Fencing) Limited:
Jacksons designs, manufactures and installs premium timber and steel fencing and perimeter security systems. The company’s main markets appear to be upmarket housing and industrial/infrastructure applications.
The business generated revenue of £40.9m and £4.2m of EBITDA during the year ended 30 Sept 25.
Initial consideration: BRCK is making an upfront payment of £15m for the business, plus £4.9m for associated freehold land and property from which Jacksons operates.
Deferred consideration: up to £11m over three years, tested against target financial performance criteria and subject to a one-year extension in certain circumstances.
Total consideration of up to £30.9m
Valuation: we are told that Jacksons generated £4.2m of EBITDA in the year ending 30 Sept 25. That gives the acquisition a valuation range of 3.6x to 7.4x EBITDA, depending on whether you include the property purchase and/or deferred consideration.
For context, BRCK’s own shares trade on a trailing EV/EBITDA multiple of 5x, according to the StockReport.
Roland’s view: BRCK’s markets are cyclical and it looks like Jacksons is no exception. But on balance, this looks like a sensible acquisition which could expand BRCK’s access to a number of attractive end markets.
The valuation looks reasonable to me, assuming the deferred consideration criteria are suitably stretching.
Revised broker estimates: hidden profit warning?
We often complain that investors without access to broker notes don’t always get the full picture from RNS updates. Unfortunately, this appears to be the case here.
There’s no mention of trading or any change to FY27 expectations in today’s update from BRCK.
However, Cavendish estimates for FY27 and FY28 have been cut despite the addition of a contribution from Jacksons. (BRCK has a 31 March year end – Graham covered the FY26 y/e update here):
Here are the revised Cavendish estimates:
FY26E adj EPS: 8.6p (unch)
FY27E adj EPS: 8.6p (-10% vs 9.6p previously)
FY28E adj EPS: 9.1p (-9% vs 10.0p previously)
I’m not surprised to see a cut to forecasts for a construction materials company – relevant peers such as Ibstock and Travis Perkins have both seen downgrades in recent months. The sector is known to be under pressure from subdued demand and cost inflation.
What is disappointing is to see BRCK relying on its broker to slip out a downgrade, without mentioning it in the relevant RNS. I can’t help wondering if the share price reaction to today’s news would have been different if the RNS had included this information.
Roland’s view
Today’s revised forecasts leave BRCK trading on a FY27E P/E of 5.8x with a possible dividend yield of c.7%.
My view that the business could be attractively priced is (mostly) unchanged and I think the StockRanks’ Contrarian styling is apt:
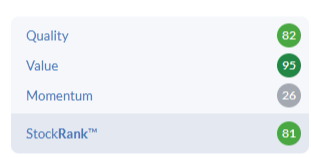
However, I think the size and manner of today’s cut to broker forecasts justifies a more cautious view, so I’m cutting Graham’s previous GREEN view to AMBER/GREEN today.
With FY26 results likely in July, hopefully all investors will be given a clearer view of trading and expectations next month.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

63 comments
Not exactly sure why administration removed my post on NW being a loser.
What do you call one of the largest failures in British financial history?
A winner? -:)
All the best
SpaceX
Quietly big institutions algorithms have cleaned up the IPO from uneducated investors.
Polymarket prices a 20% upside close on first day or trading!
All the best
Yes. And on market open IG AJB all the others will find some technical glitch in trading - aka won't be able to handle the volume. Fair enough but understand the Market. Can make 1k in a day - collecting it is another matter.
On Woodford it looks like the FCA are trying to shut him down.
https://citywire.com/investmen...
Again!
I have followed MPAC from afar ( I use some of their products in my small business) and have an aversion to Small Caps which make ' transformational' acquisitions outside their area of expertise ( i.e. here USA) and rely on local management to deliver. Often the culture is completely different and how much management time is required etc. Truth is the forecasts looked very optimistic and the first profit warning came as no surprise. Generally, one PW is followed by another.....
MPAC (LON:MPAC) - quite a number of comments on today's PW have caused me to reflect on the value of what we subscribe for with Stockopedia.
I first bought MPAC in Sept. 24 when it appeared on Ed's Mulibagger at breakout screen. Then at the end of Sept. and beginning of Oct. two 'transformational' acquisitions were announced. The brokers went wild with target prices raised to - PanmureLiberum 955p, Equity Development 865p and Shore 900p.
All well and good until the PW of 1/7/25 when the sp fell from 430 to 308 - a greater % drop than today. By then I had hardened myself as a result of Ed's PW webinar and sold at 306.5 giving a nasty 29.3% loss. I wondered if I had done the right thing when it almost touched 400 in Oct. 25 but now.... So if you have not seen it this is a must:
However, I would have done much better if I had taken more notice of the one thing we all pay our subscription for - the StockRank. At the end of April, 2 months before the PW, the results to 12/24 were published. Look what happened to the SR:
In this exchange with doctor dave on the 1/7 PW we confess to not having acted at the time! (The before and after links were to prints of the stock reports on 26/4 and 10/5 (Still available via https://www.stockopedia.com/sh... )):
https://www.stockopedia.com/co...
The Charts being sentiment - we don't know about - then clearly not in fashion.
The Q is has the base been found - too early - the chart will tell you when sentiment returns - today or this week is not that week.
What do they do - not much interested - energy oil gas and space on my radar.
Thanks for posting.
I think NW's videos are very good and thought provoking. I was trolled for years on one billboard for calling out the Woodford failures well before it really went pear shaped (i.e. calling out the poor investments and liquidity issues faced by outflows). His investments were truly disastrous and risk management was equally as bad. Nearly every early stage investment failed. He should not have changed his style and should have apologised for his terrible performance. I would not follow what he invests in, but his macro commentary is very good in my opinion so I do watch them.
Tate and Lyle leaves a bitter taste.... very good
How Splenda-id
Tens of thousands of everyday investors lost life savings, retirement funds, and financial security.
The Financial Conduct Authority (FCA) issued a warning notice against Woodford, alleging he failed to act with due skill, care, and diligence.
Providing Neil Woodford with a public platform is deeply insensitive to the thousands of investors who suffered devastating financial losses due to his fund's collapse.
Neil Woodford’s success tenure at Invesco was heavily supported by the firm’s strict institutional frameworks and corporate governance.
Featuring a fool and failed manager here is disrespectful to his victims.
All the best
I believe that Woodford's reason for leaving Invesco was that they would not allow him to buy the unlisted securities that led to his downfall.
Yes that's right, I heard he was getting more and more exasperated with the compliance department and all the rules and regulations he had to follow.
Yes.
Seems that he couldn’t cope with the compliance checks and the hierarchy of Invesco.
All the best
Yiannos, of course what you say is true lots of people lost money. But that is no reason to ignore what he says now. My whole investment career has been about listening to all views and coming to my own conclusion. So i posted a macro economic view which I thought people on this site would find useful. It's the ideas which i thought one or two of my fellow investors would find interesting. It was never about Neil Woodford or the tragedy that unfolded at the end of his career.
For the basis of fact Neil Woodfords High Income Fund was a retail fund and therefore didn't come under the institutional framework. Unless you are referring to the institutional framework in terms of Invesco Perpetual as an Institution. My understanding at the time was his funds were so significant under the whole stable that the Company itself was creating more risk framework around it, because it was becoming a business risk, and this was something he didn't like, which lead to his departure etc etc....
The MTI Wireless Edge (LON:MWE) military antenna business is the highest momentum driver of the MTI investment case — contract wins are frequent, financially material, and each 1 of the 5 (inc today) over the last 12 months has moved the share price positively.
If their water irrigation and other divisions are performing well, the Antenna wins may represent significant upside to already-reasonable estimates.
Castings. CGS. Does anyone know why castings is spiking? I can't seem to find any news.
Castings (LON:CGS) that was on thursday.
but no news since then, odd !
Thanks to both of you.
rumour the reason for the jump in the Castings share price was the announcement of the sale of 80% of Cook Defence Systems to HEICO. Cook Defence Systems is part of William Cook, a privately held foundry group might now have the funds to contemplate takeover bid for Castings
Thank you Ben. I've held Castings for quite some time and am still about 25% in the red.
Within my business I'd say inflation is over 10%, more in the variable cost (or cost of sales) side of things.
As an investor I have been preoccuppied with Inflation and prospects for a while. It is therefore with interest I came across Neil Woodford's thoughts on it recently. Now I know some will have issues with Neil Woodford but he is not a fool and his thoughts are worth listening to. I attach the YOUtube link should anyone be interested.
I think that Neil Woodford is highly intelligent but he is also a fool.
Two different things.
Agreed - Over the years Ive come across many so called experts who can deliver wonderful thought provoking speeches yet are themselves rubbish at doing what they preach. NW is a top ranking example.
I am neither a fan nor a critic but I do know when he worked for Invesco his track record was one of the best over a prolonged period in the City of London. Ranked alongside the likes of Anthony Bolton at Fidelity. People do seem to have forgotten that. His mistake like so many is to think he could run a business and be a fund manager. Different roles altogether and perhaps more an issue of ego.
Maybe not a fool - but his performance (at Invesco too) does seem to stem from playing a risky contrarian attitude - with OTHER PEOPLE's money.
Of course it was with other peoples money, he was a fund manager. Equally risk return profiles are central to investment practise, the proof of skill is in long term performance. I doubt during that period of his career you would find any of his investors complaining about his risk profile.
Rather like Nick Train - and any other "successful" manager then? We can all pick out managers that have had stellar results - for a time, The difference is that I can't think of any others that "bent the rules" in quite such a spectacular manner and weren't fined £46m. NW doesn't deserve respect - his antics were / are deplorable. Can you recollect the "price" he paid to buy more shares in RUTH - to keep it going? A company of which his fund held virtually all the shares that weren't owned by management. That was truly a low point in his career.
poppycock.
Not sure what exactly your response offers to this forum as Lincs has provided you with some insight about NW.
All the best
I disagree with your comment. NW is human. He can't help that. As one of our foremost investment brains, he has had cycles of excellent and less good performance. He has a good handle on things on a macro scale. His current performance is up over 100% in a year for those who subscribe to his current offering.
I think he may be a 'fool' about Chinese robots which are essentially remotely controlled with pre-prepared movements built into them. Then AI imagery is applied to polish the act.
Down the line they may grow more sophisticated. Musk and robotics may follow the path of Musk and self-drive cars which again may become more sophisticated but which we are some distance from being a useful everyday tool except in some limited scenarios.
The idea that China can continue to potentially hollow out their own society by their economic and political philosophy remains to be seen. The net effect of exporting deflation requiring low returns for individual enterprises means mis-allocation of capital on a vast scale. This is leaving aside the damage to the broad swathe of their own people other than those at the top of society.
It doesn't mean the deflationary forces referenced aren't lurking under the canopy of the wars that are in play, but chickens do tend to come home to roost regarding financial imbalance.
Who the damage affects as a result of that imbalance is perhaps harder to pin down in the short term.
Anyone who has bought a Jaecoo recently is benefitting from the significant deflation Woodford is talking about.
agree, i watch his weekly update on Youtube, its extremely insightful, and as you say, he is no fool..
So is Peter Schiff but I'm underwater with the gold bug thing - but it's a long game - buy on the dips, so they say.
Thanks for sharing Camtab. Very persuading arguments. People forget that Neil Woodford was arguably the UK's most successful fund managed for many years. His big mistake was using illiquid startups to try to improve performance. He should have stuck to what he knew.
If this argument plays out then it could be good news for equities in the long term.
He may have been a successful FM for a while, but when he was running his own show he developed (had?) a massive ego, and was blind to this own weaknesses (according to a book I read a while ago). A truly successful investor needs some awareness of their own failings.
Clearly risk management was out the window for capital gains.
MPAC (LON:MPAC)
very very poor update here - ok they did previously flag up the H2 related weighting - that update was as recent as 21st April though - so only 2 months and 10 days of the year left then - for them to go from the viewpoint on that day that they remained "on track" - to being "substantially below" 7 weeks later - well thats pretty poor planning imho.
update on 21st April
The Group remains in line with full year market expectations, which as in previous years will be second half weighted, but, in the context of increasingly uncertain market conditions, it is difficult to predict the full impact of the Middle East conflict on the timing of customer capital investment decisions.
Note they have already had to hugely downgrade expectations here already -s o its not as if they hadnt already had a reset of expectations.
double whammy here is that them shortfall really does hurt the bottom line - imho its bordering on incompetence reducing profits 44% - with just 22 days to go in the year - waaaay to late to tell the market - especially after they had done the same previously not so long ago.
If there is a decent business here - management are very much letting themselves down by not having saavy to provide realistic viewpoint to the market. Perhaps the well publised issues here are such that its beoyond their control - that may be the case - but imho they have buried their head in the sand - and being a company with the debt/liabilities they have - well there wasnt too much margin for failure as tragic as they have delivered.
I think some on here rate management very highly - hopefully if they are as good as some think they might be able to turn this around when issues subside - but at present they are making themselves look like a bunch of amateurs to me.
ref the sale announced today - they seem to have got a decent price bering in mind then losses last year - what profit could that unit make in a good year though ?
MPAC (LON:MPAC) I feel selling the Lambert division is a rushed deal by management to offer the market something against their overall group declining financial performance. Lambert has great expertise and broad sector experience and customer base. They designed and built the Freyr Battery automation, so all that leaning will be lost to the group. Narrowing down the groups automation offering, weakens it considerably. I don't hold MPAC.
MPAC (LON:MPAC)
MPAC (LON:MPAC) I feel selling the Lambert division is a rushed deal by management to offer the market something against their overall group declining financial performance.
I suspect with net debt at £47.9 mill **- they perhaps had very little choice with the cratering of profits that would have provided real cash needed to service said debt. So i would disagree with your sentiment here - but they might have had little choice with the shocking bad trajectory ref overall trading. When you have cash in the bank and no debt you can very much tough out a bad year - you dont have that luxury when you have bet the farm and more - building up debt which you promised would generate higher profits - and that all falls flat on its face.
One error in my prior post - i had wrongly thought ye was 30/6/26 not 31/12/2026 - so its not a late in the year profit warning as i originally thought - it is still though a very speedy deterioration of trading since 21/4 though..
** ref net debt - pretty unhelpful that they only cross reference debt at 31/12 year end- would have been nice if they had provided updated figures now.
MAWHSPI* up 22% from last October
(*Manchester Airport WH Smith Polo index - now at £2.69 a packet)
Very good point cheeky - that is a true measure of inflation - here in Norwich, coffee futures are up with the benchmark Flat White now selling at £4.10 on the JL Cafe (John Lewis) trading platform, up from £3.60 in less than 12 months = +14%
Haha - I agree in general, I think that the inflation figures are probably massaged, but I guess that t'was ever thus. I was making a gentle dig at myself and my bearish view on WH Smith (LON:SMWH) - looking for things that reinforce my confirmation bias whilst absolutely refusing to look for the counterfactuals. Bad form - but I am stubborn !! Watch it bottom here...
edit - I will however continue to keep my eye on this..
Why should they be massaged? The CPI simply reflects price changes in a series of goods. You can quibble about what goes into that basket, and the changes over the years, or whether RPI would be a more accurate calculation, but to say they're massaged suggests manipulation - unless you have evidence for that, I'd avoid using the term.
I dont think that RPI is a better calculation, but CPIH is probably better. No, it is much simpler than that. 3% is the new 2%. Over 5 years that means 16% rather than 10%.
It wasn't long ago they were 4p/6p per pack!
It's just mint flavoured sugar.
first ever contract for their brand new Market Edge Intelligence® platform
Signed with one of the world’s LARGEST banks
5-year deal | $4.8m | Revenue starts NOW
And this is just ONE area of that bank’s trading infrastructure
I read the Beeks Financial Cloud (LON:BKS) outlook statement they included with a bit of pessimism. For their FY Jun26.
[This contract starts immediately].... "supporting the Board's FY26 expectations.”
"We remain confident in delivering a full year performance in line with expectations."
While the word "confident" normally does mean a high degree of meeting expectations, the combination of the two sentences above, and also the choice of phrase of "remain confident in delivering"... suggests to me they are still looking for a bit more revenue to hit their FY Jun26 expectations. Perhaps still needing one or two more contracts (with an upfront fee) to land before year end?
Broker CG suggest BKS will need to convert another 5m from its pipeline to meet 2h 26m in sales. However, they state ...
2.2x FY27e EV/Sales and 15.5x P/E multiples in our view materially undervalue one of the few organic double-digit growers in UK SMID Cap
Beeks Financial Cloud (LON:BKS)
Broker CG suggest BKS will need to convert another 5m from its pipeline to meet 2h 26m in sales. However
hmmmm - perhaps ther is some doubt here if the broker is coming out and saying that - so it might be my inability to read the tea leaves here - so perhaps Boon is right to worry. Not convinced its ever great - if you dont know with 22 days to go whether you you can book enough sales in to get it over the line ref ye targets yoiu have had in place for teh last 9-12 months. I much prefer companies not to have to announce a contract right at the end of the year to get what they have promised all year - when that happens it leaves bad taste in the mouth - especially if as late as now they are saying they are on track.
Beeks Financial Cloud (LON:BKS)
While the word "confident" normally does mean a high degree of meeting expectations, the combination of the two sentences above, and also the choice of phrase of "remain confident in delivering"... suggests to me they are still looking for a bit more revenue to hit their FY Jun26 expectations. Perhaps still needing one or two more contracts (with an upfront fee) to land before year end?
I have to disagree with your logic here Boon - if the stocky data is correct then their 2026 financial year ends at 30/6 does it not? it would seem crazy if with just 22 days to go that they would remain confident with 22 days to go if they didnt have high degree of confidence - if they were not confdent - surely today was the day to add a specific caveat ref "dilvery" . I would go as far as saying if they are not very confident then they shouldnt be saying they are confident with 22 days left.
I simply read the text you are worried about as confirming that they are overall on track - they might have needed to sign this contract to hit targets - perhaps they didnt - but its signed now so nothing to worry about.
in summary surely with 22 days to go they should either have confidence - or not with regard to what they can deliver for the rest of this month? so i see zero need for pessimism here
Fair play to the company if they have managed to get to to elevel where they are now generating £8 mill pa in "clean profits" - i might reserve judgement myself in that regard till i see the year end figures. they have a alot of moving parts and a dont know how much they will be capitalising this year ref "their costs" - imho its much easier to show nice increases in profits when you are capitalising more than you are depreciating/amortising and also when you have increased working capital needs (ie you are bearing brunt of spending now so your customers dont have to splash any cash) - not sure how close they are to point where free cashflow will match profits - thats often the real i am "we have made it momenmt" - at least as things stand they expect to deliver profits well above prior years - so if there are no hidden nasties then it all looks prtetty good - albeit if cashflow is still decently negative then they have further work to do.
I dont know the full details - but i would like to think the contract they have delivered today is higher margin stuff ? if that is the case and there is more to come then they look in a reasonably sweet spot. Not sure if anyone as details ref the posibilities ref this new incoem stream?
good news BEEKS
I'm really enjoying Graham's early morning analysis of macro moves. Trump being made to look like a diplomat by Netanyahu today - no mean feat.
Essential early morning reading to give us a flavour of what to expect during the day.
Yes, it's quite interesting. He seems to be on the ball. I've barely finished my coffee and he's already posted news.
"This negative sentiment continued overnight in the Korean market, where the Kospi index fell by more than 8% at the open."
Those are rookie numbers ;) Many people are likely aware, but the KORU (Direxion Daily MSCI South Korea Bull 3X ETF) is down 42%.
Brace for impact.
Samsung is up 6% from the open on LSE, Micron up 7.5% so far today. Memory demand not going anywhere but up for the foreseeable.