Daily Stock Market Report (Tue 15 April 2025) - HFD, TBLD, BILN, BME, KOO, LIO, RNO, DLAR, RWA, IHP, EMAN, MXCT, MHA, SUS

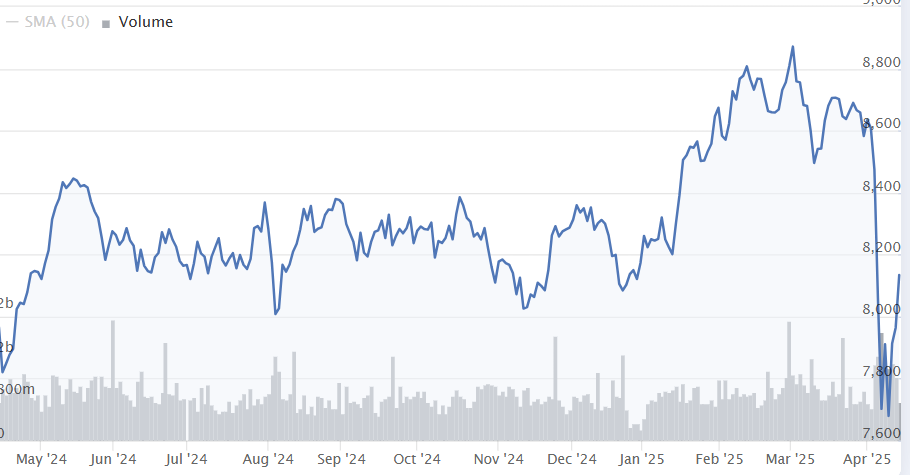
Good morning! The FTSE finished up 2% yesterday and got back within the range where it spent most of last year:
The Aim All-Share Index remains in a state of total depression:
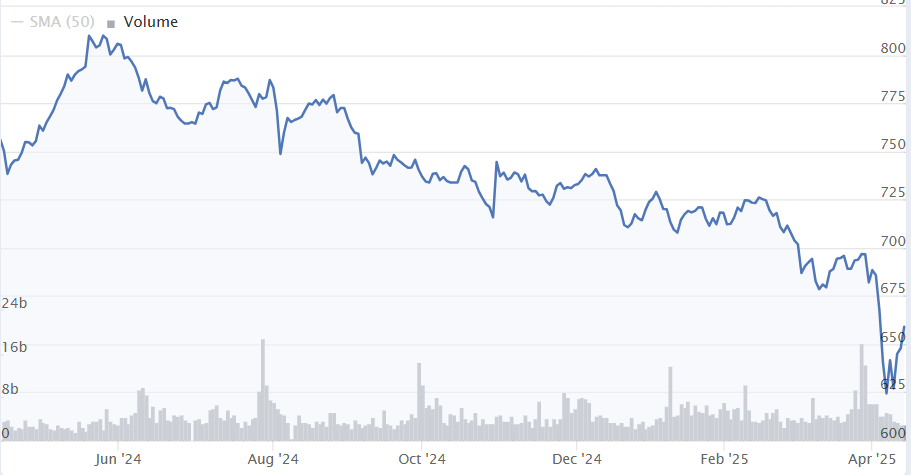
I've reached a point now in my own thinking where I don't know if the Aim Index is useful as a benchmark for anything - its performance has been that poor over the long-term! I'd rather use one of the FTSE Indexes instead.
1.10pm: we've run out of time for now - a remarkably busy day for announcements! Cheers.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Wise (LON:WISE) (£12.1bn) | FY25 vol +23% to £145bn, active cust +21% to 15.6m. Adj income +16% to £1.36bn. 20% PBT mgn. | ||
B&M European Value Retail SA (LON:BME) (£3.0bn) |
SP +3.5% | AMBER/RED (Roland) [no section below] I’m pleased to see there are no further downgrades after February’s profit warning. But I remain concerned by apparent weakness in the core UK business, where LFL sales fell by 3.1% last year. With operating costs up by 6% over the same period, margins must surely be under pressure? In this context, the group’s plans to maintain a high rate of store openings looks a little risky to me. With the CEO departing on 30 April, I’m going to leave my mildly negative view unchanged ahead of June’s FY results. | |
Frasers (LON:FRAS) (£2.8bn) | 25yr agreement to launch Sports Direct in Aus/NZ. Frasers will fund with £29m Accent (ASX:AX1) share purchase. | ||
Tate & Lyle (LON:TATE) (£2.4bn) | Integration of CP Kelco “on-track”, improved EBITDA margin. FY25 results exp in line with guidance. | ||
| Greatland Gold (LON:GGP) (£1.8bn) | Telfer Ore Reserve, Outlook and Havieron expansion | Telfer dual train extended through FY27 before Havieron in FY28. Exp avg 280-320koz/yr in 26/27. | |
Integrafin Holdings (LON:IHP) (£1.0bn) | Q2 25 net inflows of £1.2bn, 7.3% of opening FUD. Total FUD +8% YoY to £65.9bn. H1 group revenue is expected to rise by 9% to c.£77m. | AMBER/GREEN (Roland) [no section below] This investment platform for IFAs is a good quality business, in my view. Today’s update doesn’t change this, with evidence of further inflows and continued growth in its client base. The accounts are somewhat complex, but my previous analysis has found this to be a high-margin, cash-generative operation. Long-term margin pressure could be a key risk, but continued founder ownership is an attraction for me. The shares aren’t cheap, but I think a moderately positive view can be justified. | |
Firstgroup (LON:FGP) (£932m) | FY25 adj op profit & EPS to be ahead of previous expectations. Strong rail perf, bus in line. | ||
PRS Reit (LON:PRSR) (£609m) | Completed homes 5,443, 35 left. ERV +1.5% to £69.6m. LFL rent +10% YoY. Sale process ongoing. | PINK (formal sale process) | |
Atalaya Mining Copper SA (LON:ATYM) (£469m) | Q1 copper prod 14,291 tonnes, +18% QoQ due to higher grades. FY25 guidance unchanged. | ||
Tatton Asset Management (LON:TAM) (£352m) | FY25 net inflows £3.7bn, AUM +24% to £21.8bn. IFAs +135 to 1,100. FY25 results to be in line. | ||
Porvair (LON:PRV) (£325m) | YTD trading in line with exps. New CEO starts today. Re. macro, no change to long-term outlook. | ||
Halfords (LON:HFD) (£272m) | Strong year end, FY25 LFL sales +2.3%. Exp FY25 adj PBT at upper end of £32-37m guidance. | AMBER/GREEN (Roland) [no section below] This is the second positive update on profit this year, following January’s update. It’s good news. But Halfords still needs to mitigate a £23m increase in direct labour costs in FY26, against a difficult trading backdrop. Management expects to be able to “mitigate the entirety” of the Budget impact, but with a new CEO starting this week I will be interested to see what his views are when Halfords reports in June. However, given the seemingly improved momentum, I’ve upgraded my view by one notch today. | |
MHA Plc (MHA) (£271m) | MHA is "a leading professional services provider of audit and assurance, tax, accountancy & advisory services". It begins trading on AIM. Has raised £98m at 100p. SP up 2% so far. | AMBER (Graham) [no section below] It's nice to see any IPO these days and the fundraising amount is significant. A helpful bit of business for Nomad and broker Cavendish (LON:CAV). MHA is the 13th largest UK accountancy firm by revenue and wants to be a top 10 firm in the medium-term. This looks set to be an active M&A player in the professional services sector. Partners in the company still own 54%. | |
VP (LON:VP.). (£215m) | FY25 results to be in line with market exps. Infrastructure outlook +ve, construction mixed. | ||
Liontrust Asset Management (LON:LIO) (£213m) | Q1 net outflows £1.3bn, AUMA -8% to £22.6bn. Cost savings of £6m, intern’l expansion ongoing. | AMBER/GREEN (Graham) Although I have a strong preference for other fund manager shares, I can't downgrade this to neutral as the stock remains extremely cheap against AUM and earnings. It is expected to remain profitable even after years of heavy outflows. | |
MaxCyte (LON:MXCT) (£210m) | “Vast majority” of trading now on NASDAQ. Last day of UK trading expected to be 25 June 2025. | PINK (delisting) (Graham) [no section below] This cell engineering company has been dual-listed since July 2021 and no longer sees value in its AIM listing. As it's a US-based company and the fundraising environment on AIM is unlikely to be helpful, this makes good sense. I note that the company has been consistently very heavily loss-making for years. | |
Harmony Energy Income Trust (LON:HEIT) (£198m) | Recommended acquisition by Drax (LON:DRX) | Scheme docs for 25 March 25 cash offer of 88p per share. Vote 7 May, last day of dealing 12 June. | PINK (under offer) |
S&U (LON:SUS) (£172m) | Revenue stable, PBT down 29% (£24m). Legal & regulatory challenges “almost all resolved”. In motor finance, the company says "evolving regulatory interpretations at times gave precedence to often subjective feelings of customer well-being over their contractual obligation". | AMBER/GREEN (Graham) [no section below] There is an exciting possibility that S&U could leave its legal/regulatory difficulties behind it. I continue to believe that S&U itself was not specifically at fault for any of these problems, and that instead they are to do with the FCA's priorities and with the opinions of the courts on various matters to do with motor finance. Today's results show unusually large arrears and impairments in this division, which is not a surprise as repossessions were curtailed. The "skilled person review" (S166) has recently concluded and S&U has no exposure to the controversy over discretionary commissions. So things are looking brighter here than they have for some time. | |
accesso Technology (LON:ACSO) (£172m) | Rev in line, profit ahead. Slight reduction in revenue outlook. Growth unlikely to exceed 5.3%. | ||
Robert Walters (LON:RWA) (£164m) | Markets remained challenging. Limited visibility. Q1 net fee income down 16% at constant FX, down 17% at actual FX. Europe worst (down 24%), UK best (down 4%). Permanent recruitment, which is the majority of RWA's business, underperformed temporary recruitment. Headcount down 16% year-on-year. company is "highly selective in the replacement of fee earner natural attrition", i.e. not replacing all leavers. Net cash £42m. | AMBER (Graham) [no section below] My concern for the recruitment sector is growing as net fee income has been under pressure for what feels like ages - in the case of Robert Walters, it has been heavily declining for over two years, and their profit margins have collapsed. Is the decline purely to do with economic uncertainty and risk aversion on the part of candidates and corporates? Perhaps. But I find it strange that it persists in an environment of full employment in most major economies, when employees in theory have plenty of options to choose from and should be willing to move. Maybe it is a combination of economic risk aversion and other factors that are cutting out the middleman. Mark was neutral on this in March and once again I'm happy to leave the existing stance unchanged. | |
De La Rue (LON:DLAR) (£112m) | Recommended cash offer of 130p per share (£263m) from Atlas Holdings (ACR Bidco). | PINK (under offer) (Roland) [no section below]. | |
Renold (LON:RNO) (£99m) |
FY25 ahead of expectations. Positive momentum in the final quarter. | AMBER/GREEN (Roland) [no section below] | |
Billington Holdings (LON:BILN) (£60m) | Profit warning: reducing 2025 expectations to revenues slightly ahead of 2024 and FY25 PBT of £7.25m (versus £8.3m in 2024). | AMBER/RED (Roland) [no section below] | |
Kooth (LON:KOO) (£47m) | £15.8m adjusted EBITDA. £21.8m net cash. Outlook: continued US growth. UK remains complex. | AMBER/GREEN (Roland) [no section below] Results from this youth digital mental health specialist look promising, with revenue up 100% to £66.7m, all of which is classified as recurring. The group’s maiden operating profit gives a respectable 13.8% margin, suggesting profitability could be attractive as the business scales. In its core California market, the product now reaches 75,000 users. However, I would argue the political environment in the US makes the outlook for major new contracts hard to predict. Today’s results price the shares on a P/E of 7. Strong fundamentals mean I’m happy to upgrade our view from neutral to moderately positive. | |
Everyman Media (LON:EMAN) (£34m) | Operating loss £3.3m includes c. £3m of impairment charges. Trading in line. 6% fall in admissions would be needed to trip debt covenants. | RED (Graham) [no section below] The company continues to emphasise adj. EBITDA in its highlights, ignoring ongoing losses. It says it is "soundly financially structured". Checking the cash flow statement for a realistic picture, I see a £15m cash inflow from operating activities before changes in working capital. The company also benefited from £5.7m of landlord contributions to venue fit out costs and from stretching its payables. Against these positives, there was a capex bill for over £15m, and £8m of lease-related payments which appear separately on the cash flow statement. I'm still not convinced that this company is making meaningful profits and I agree with the weak StockRank it receives, categorising it as a "Value Trap". | |
Futura Medical (LON:FUM) (£27m) | Ahead of exps. Rev £13.9m, profit after tax £1.3m. On track to launch Eroxon in 20 countries. | ||
tinyBuild (LON:TBLD) (£22m) | Rev -22%, adj. EBITDA loss £3.7m. Operating loss of $20m including $14m of impairments. Outlook: in line. Net cash was £3.1m at the end of 2024 and is expected to trough in summer 2025 prior to the launch of new games. As of March, cash is in “the low single digit millions”. Strong pipeline for 2025 includes some higher-budget, high-potential games. Going concern note sounds shaky. | RED (Graham) [no section below] Please see my comments in February where I outlined this company’s history of cash mismanagement. I bring readers’ attention to the following sentence in the “Liquidity” section of today’s report: there can be no assurance that the Company will succeed in generating sufficient revenues from product sales to continue its operations as a going concern. The company has form for burning through cash and then coming back to investors for more. I think there’s a high risk that they will need another cash injection, unless they have some very successful game launches. | |
Nanoco (LON:NANO) (£14m) | Rev for FY July 2025 to be ahead of exps as result of settlement agreement with customer. | ||
Pod Point group (LON:PODP) (£10m) | PW. Adj EBITDA below market guidance of £14m by £8m, mostly due to a bad debt provision. |
Graham's Section
Liontrust Asset Management (LON:LIO)
Up 1% to 338.6p (£216m) - Trading Statement - Graham - AMBER/GREEN
Another day, another statement from a fund manager about their net outflows.
At least in the case of Liontrust, I’ve not been fully positive on it for some time - I’ve been AMBER/GREEN here due to some extra concerns I have around the company’s positioning and strategy vis-à-vis other fund managers.
More of the same from Liontrust today:
Net outflows £1.3 billion in the quarter ending March (Q4)
AuMA, assets under management and advice, falls 8.1% in the quarter.
AuMA has fallen another 4% since the end of quarter, to £21.6bn as at 10th April.
CEO comment:
It feels that over the past few years, the only certainty has been uncertainty. The current day-to-day unpredictability and fluctuations in markets reinforces our belief in active management and the long-term power of robust and repeatable investment processes.
Our focus remains on what is within our control. We continue to develop the business and are confident we have been making the right changes to ensure it is in the best possible shape for the future.
The statement argues that “The extreme volatility and dislocations we have seen in markets over the past couple of weeks are demonstrating the importance of, and opportunities for, active management and stock picking.”
But is that really true? I’ll be very curious to see whether active fund managers have proven their worth during this period, when the dust settles.
Liontrust provides good transparency in terms of the quartile ranking of their funds - note that this is not performance against benchmark, only performance against other funds. Beating other funds is typically much easier than beating a benchmark index!
I count that 23 out 53 Liontrust funds listed in today’s tables are in the bottom quartile in terms of their performance over the past year.
Or if we look at the 5-year column instead, I count that 26 out of 44 funds are in the bottom two quartiles, i.e. in the bottom half of funds.
And that may be a generous measurement. 5-year statistics tend to be subject to survivorship bias - in the fund management industry, underperforming funds often get closed down or merged with other funds, which removes them from the statistics.
I previously reviewed some of Liontrust’s funds and found they were heavily invested in shares with poor StockRanks. The performance tables suggest that many of their portfolios haven’t been holding up particularly well recently, or over the long-term.
I also note the following sentence under “Brand and Client Service”:
The Liontrust brand is very strong and we are continually engaging with our clients. We receive great feedback on our service and communications directly and through market research and these are more important than ever at times like this in helping clients to navigate volatile markets.
What’s bothering me here is the disconnect between the tone of the commentary and the reality of persistent net outflows for the past three years.
Graham's View
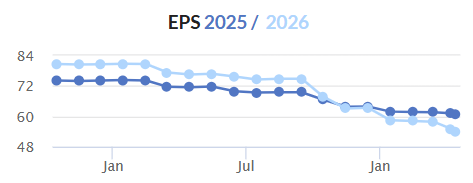
Despite my concerns, I think I can leave my AMBER/GREEN stance unchanged as the stock remains extraordinarily cheap with £100 of AUM for every £1 invested in the stock at the current price. The PER is only 6x although do bear in mind that earnings forecasts have trended lower:
The company has simplified by outsourcing various middle office functions and has cut costs with annualised savings of £6m achieved at a cost of £4.5m. One of my major issues with Liontrust has been management’s willingness to add complexity through acquisitions, when instead I thought they should be slimming down. It’s good to see that when push came to shove, they have simplified its operations.
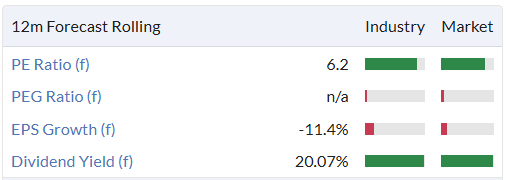
I still prefer the other fund manager stocks by a wide margin. At the same time I don’t think I can justify a move down to a neutral stance here. It’s priced almost like a cigar butt stock, down nearly 90% from its peak in 2021. The current valuation says to me that outflows are expected to continue permanently, until it withers to nothing:
I think the best outcome for shareholders would be for Liontrust to simplify even further and then get merged into a larger fund manager who would remove even more costs and plug its AUM (and its brand) into an existing, highly profitable operating model. I’d have a strong suspicion that such a fund manager would be willing to pay more than the current market for over £20bn of AUMA.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

60 comments
sorry new to all this. does anyone know if there is a way to find a list of companies rated green by the team in the last few months?
There's a link on the daily reports every now and then to a spreadsheet with them all on.
Edit:
Here: https://docs.google.com/spread...
Last updated Mid Feb.
Stockopedia/Graham - maybe if the spreadsheet was unlocked to editing, members could add the colours - the colours are very helpful seeing how the evolve over time
Hi Gag, I'll get back onto this now and start bringing it back up to date. Cheers. G
Ooops looks like Jarvis Securities (LON:JIM) are shutting up shop for £11mil - not sure if the sale includes the £5mil cash on the balance sheet?
Hard to know what to do. 58% on close. No guarantees we'll see any money on return of sale?
They are selling the operating subsidiary jarvis investment .management. As I understand it just the customer list and portfolios will be transferred, no assets.
Thank you planetx for your comments yesterday on Sanderson Design (LON:SDG)
Good to know you think they are "very cheap" I got my timing all wrong with this buy but I intend to hang on as maybe a bid wil surface given the value of the back catalogue in Wallpapers.
I quite agree about your comment about the AIM Index. I think it's a busted flush personally. It's getting on for nearly 4 years since its peak, July 21, that I wouldn't even bother with it anymore. I don't. There are some good companies on it still, but they are few and far between.
I would agree that AIM is more or less useless as a comparator, and surprised there are still people who compare their performance against AIM. I tend to use the FTSE 250 as a rough gauge of what I should be beating within my UK equity portfolio.
Re Everyman Media (LON:EMAN) I recently visited their cinema in Belsize Park. I recommend the film Flow to any lover of arthouse films!
Definitely a nice cinema to go to as a consumer but from a business perspective there are two odd things:
* It has a single screen which will obviously limit what it can show/what's of interest. The theatre is huge with 153 seats - maybe it was hard to structure the room otherwise but surely it would make more sense to have two smaller cinemas for this quieter part of north London. Flow was maybe 15% full at 6.30pm mid-week. Three front of house staff were serving food and drinks to us.
* Oddly it's only a 15 minute walk from Everyman Hampstead! Maybe they avoid showing the same film but they're surely just cannibalising business?
Just a single snapshot of one cinema but perhaps indicative of some of the wider problems with how the business is run?
Surprised Next 15 (LON:NFG) did not make the cut for a write-up given the size, sector and interesting barometer for the US market
Good to see more positive news on Halfords (LON:HFD) which, even after a 10% rise, is still super super cheap.
Halfords (LON:HFD) was 146p 5 years ago, so not much change since then. Lot of activity and a very big bump, but back to where we started then.
Did have a big blip soon after, but just shows that cyclical businesses will remain so. Not sure that it is all that cheap and can suffer fro changing macro circumstances. Mitigating large tax changes, OK but still affects direction of travel. In the meantime, good divi, so long as it lasts.
3i
A year ago, at a Mello Monday evening session, a fund manager talked about the Private Equity attraction with great potentials and big discounts. David asked whether there is any PE trust with premium to which I mentioned 3i at 40% premium and a significant holding in one company (nearly 60%in Action which is a Dutch retailer). Discussion followed about the high risk business here and I got scared and sold out at around £28. The share price has continued it ascent, now passed £40, still with big premium and still with Action being its largest holding.
Buying and holding quality businesses for the long haul takes a lot less work than regular trading but each to his own
Best not to look at 3i as a private equity business - it's basically Action with a few other smaller companies thrown in. I also sold too early, although I think its looking overvalued now. I tend to value 3i with reference to Action's earnings (perhaps a 15 multiple), and for the other holdings I use NAV.
VP (LON:VP.)
A creditable performance in difficult markets. The pick of its peer group by some distance in my opinion. Cheap and will remain so until 'rail' starts to gain traction and the Government's for now beleaguered efforts to kick start house building get started.
Serabi Gold (LON:SRB) - See news on new major shareholder which seems to have bolstered the SP today.
Mello 2025 will be back for two days packed full of company presentations, keynote speakers, panel sessions such as the ever popular BASH and of course lots of networking with likeminded investors . Probably around 30% of the attendees are fellow subscribers from these Stockopedia boards...
Date: 3rd & 4th June 2025
Location: Clayton Hotel Chiswick 626 Chiswick High Road London, W4 5RY
Limited offer for newbies...One of our sponsors has provided two tickets to be given complimentary to two individual investors who have never been to a Mello conference before. So if you would like to claim one on a first come first served basis and remember you must be new to our physical events just email me at David@Melloevents.com
Highlights of Mello 2025:
Keynote Speakers: Hear from industry leaders and learn from the best in the investing world such as Lord Lee, Vin Murria, Christopher Mills, Ben Rogoff, Georgina Brittain, Gervais Williams and many more
Panel Sessions: Gain insights and learn about different investment strategies or approaches.
Networking: Connect with like-minded individuals and other excellent investors.
Exhibitions: explore the different investment opportunities in our exhibitor area and meet management face to face.
Register Now: https://melloevents.com/mello2025/
Discount Code: use code Stocko50 for 50% off tickets
Stay tuned for more updates and exciting announcements. We can't wait to see you at Mello 2025!
#Mello2025
David
Mello 2025 is back
Mello is like Stocko AGM! The chairman, Ed Croft is there accompanied by the CFO and the board members : Graham, Roland, Megan and the rest (apologise if I miss some members). I hope Pul Scott attends.
You meet so many of the community there , Shame about the fact that I can not match the real names with their Pen names here! It would be nice if the nicknames are written on the budge!
Maybe we should ask all those booking their tickets with the Stocko code to provide their online pen names to put on the badges.
A lot of companies covered in the company reporting box today. This must have taken some considerable effort.
I would be interested a Billington Holdings report if it is on the agenda. The key issue in today's full year results appears to b e that 2025 will be more H2 weighted than expected.
No position.
I would second this request, looks to have value with cash of £22m and a new pbt forecast of £7.5m. I have a position as of this morning
For some reason Henderson Far East Income (LON:HFEL) who reported their finals today remains under the radar. It really is a fascinating read on the east versus west conflicts that are going on at the moment. As they point out the US represents aprox 13% of world trade even if they are the biggest single market so I was surprised how positive the outlook commentary was -as an income investor I was very pleased to note the following " Alongside attractive valuations, there is real confidence in the cash-flow and balance sheet metrics that are enabling corporates to surprise positively on dividends .The combination of above-expectation dividend growth and the defensive nature of our holdings should produce a less volatile outcome for investors in a market that is looking increasingly uncertain. There is no change to our view that the drivers of structural growth in the Asia Pacific region can continue to deliver solid performance even during the current uncertainties."
It's difficult at the moment but for any income investor but with a current yield of around 11% this is worth looking at . I would be interested to know if you agree.
I broadly agree fred, but note that the investment managers sell covered calls or similar to boost the yield. In effect you are forgoing growth to achieve the high yield. In investing, as with most things, there's no such thing as a free ride.
Over 10 years they have lost 41% of starting capital. Without doing the proper math, the 11% yield only works out at (very approx.) 6.9% pa. As Nothingventured says, they achieve this mediocre return by selling covered calls + some dividend income. The problem with a covered call strategy is the good stuff gets taken out of the portfolio leaving the crap; it only really makes sense in a falling market, but then the option premium starts to reduce which is a bit self-defeating.
Of course, this is just my view which is coloured by the fact I am of an age where I am increasingly attracted to income with a decent probability of protection against inflating away my capital.
There are better opportunities for income seekers on the UK market with less geopolitical risk and no currency risk, although we must always bear in mind that Rachel from accounts is lurking in the bushes ... she already wants a chunk of my farm when I pass, and I don't think she has finished torturing the middle classes yet.
Jamesalastair, could you name your UK faves? I have a big holding in TRIG now.
UK LISTED
M P Evans (LON:MPE) Ramsdens Holdings (LON:RFX) are worth a look. I hold M P Evans and recently purchased Ramsdens. Rio Tinto (LON:RIO) in the mining sector is also worth a look...commodities look generationally cheap. I also hold Piraeus Port Authority SA (ATH:PPA) - good long term performance, asset backed port authority with circa 5.5% dividend. This will not be everyone's cup of tea though - Greek Port serving Athens with Chinese shipping Company, Cosco, as a 67% shareholder. I also like London-listed Kazak bank Halyk Bank AO (LON:HSBK) who pay 14.1% dividend.
LISTED ON OTHER BOURSES
Outside the UK listed market, I like Argentinian agricultural and property company Cresud SACIF y A (NSQ:CRESY) who will pay around 8% this year and Brazilian O&G company Petroleo Brasileiro SA Petrobras (NYQ:PBR) who pay 18%. Lots of political risk with these.
BUT ...
I think Cresud SACIF y A (NSQ:CRESY) is well placed to benefit from soya bean sales to China as China is no longer buying soya from the US for obvious reasons; I really like their web-based agricultural marketplace for South America, and they are controlling shareholder in Irsa Inversiones y Representaciones SA (NYQ:IRS) which is a major player in the Buenos Aires property sector. They are ridiculously undervalued but any investment in Argentina will be via US-listed ADRs and will require a certain faith in Milei' economic progress.
Petroleo Brasileiro SA Petrobras (NYQ:PBR) has one of the lowest product cost profiles in the World and one of the best assets. I also think the Brazilian economy is at a trough and the Real is at an exchange rate low. Brazil is scarcely exposed to Trump's tariffs as it exports more to the US than it imports and, besides, moving forward China will be a much more important trade partner than the US. You just need to understand the Brazilian Government's prediction for meddling in the company and expect some volatility.
You have to also bear in mind I am older than your average Stocko customer and increasingly looking for income. Also, I have a strong predilection for real assets. What suits me and my personality/circle of competence might not be right for the next person.
One last observation: For the first time in a long time, I think the UK market is the cleanest pair of pants in the dirty laundry basket. Who would have thought, although of course a lot depends on what mischief Rachel from accounts can dream up next.
Henderson Far East or Invesco Asia Dragon
both have performed badly over the last five years when the emerging markets have been out of favour. Invesco (IAD) has lower divi but better capital appreciation.
I hold a few HFEL, and have done intermittently for years. An excellent yield, maybe, but I am aware that I have been paying myself out of capital.
Since 1998 with dividends reinvested HFEL has produced a return of ~7x. AAS which invests in the same geographical area has returned 90x.
Perhaps some of those replying to fred9566’s post on Henderson Far East Income (LON:HFEL) don’t know that following those years of badly underperforming there has been a change of Manager and a change to Investment tactics too. So far the jury is out on whether thst is leading to improved performance.
It’s well worth reading the full Results commentary today. It’s surprisingly bullish overall including on continuing their multiple year record of annual dividend increases. Also until reading it I didn’t know that the US only accounted for 13% of World trade.
Stock markets look ahead, not back and with an 11% yield to lock in and high chance of increases every year, holders get a big dividend paid quarterly while waiting to find out if at last Henderson Far East Income (LON:HFEL) can provide good capital gain on top.
I’ve pasted two extracts on the dividend below but there’s so much more on the background that applies for other Asian Trusts too, in their commentary today.
1 “As you may remember, I have previously noted our conviction that Asian companies have resumed a commitment to higher dividend growth, thus supporting our investment strategy. We should not expect that dividend growth will move in a linear fashion from one year to the next and there will certainly be periods of both slowdown and acceleration. We are currently in a phase where we expect dividends to exceed expectations. That will make Asian markets even more attractive for investors during a period of real uncertainty elsewhere.”
“Additionally, the outlook for dividends remains positive; above expectation increases in the first half of the Company's year indicates that the long-term trend of dividend growth is intact. The region has progressively improved its commitment to dividends, yet has one of the lowest payout ratios globally, leaving plenty of scope for improvement. The combination of attractive valuations, the potential for growth and the number of high yielding investment opportunities provides remarkable protection for investors in the face of uncertain trade policies.
Sat Duhra
Fund Manager
14 April 2025”
Thx .... useful post
However, I am not convinced that 11% yield is locked-in as some of it (much of it/most of it?) will be option premiums from writing covered calls. That is now history.
So where does Liontrust Asset Management (LON:LIO) go from here - if you look at the list of their funds (within their update) - most have been 4th quartile for the past year. I could not see mention of future divi..?
Liontrust are growth focused and UK centric (although not wholly). In strong markets I'd expect them to out-perform. I'd be very wary of the UK investment managers which look cheap. Passive investing is eating their lunch. Better to invest in a fund platform type business where the fees are predictable and grow with world equity markets - like Quilter.
As a contrarian, my instinct is that LIOs funds will revert to the mean. I don’t currently hold.
Yesterday, Citibank moved US to underweight and UK to overweight, so maybe in the medium term that might result in more interest in UK stocks, which would help Liontrust Asset Management (LON:LIO) & Jupiter Fund Management (LON:JUP) among others.
I think the most likely outcome for UK fund managers is a lot of consolidation, however this doesn't necessarily mean takeovers. A lot of Fund Managers are structured such that they bring in Investment Teams on a profit sharing basis - the company provides all the back office & infrastructure and in turn takes a healthy % of the management fees/performance fees. There's obviously a certain tie in period, but it's relatively easy for a team to up & leave or for a financial buy out of the investment team only. That's been the model of the last few places I've worked.
So a gradual picking off of the best performing teams is the most likely outcome over the next few years I reckon. Why pay for the under performing teams and the infrastructure you already have in place?
Agree with your comments on AIM. Whilst there some great companies on there they appear to still be in the minority
one for Ed what if he takes out the 300 lowest (rubbish) MC aim companies and see how that affects the stockranks?!
Good to sea buy and sell entery points on charts have reverted back to the old format show on the chart rather than along the bottom, so much better.
Activist investor out to shake up oil engineer Hunting (LON:HTG)
Hedge fund Oasis Management has built a more than 5 per cent stake, and is calling for $145 million to be returned to investors or used for acquisitions.
https://archive.ph/wszZc
Thanks eParo - couldn't access the original Times link
New IPO MHA starts trading today at 8am on AIM under ticker MHA.
Market Capitalisation of MHA approx. £271 million. Strong institutional support with £98 million raised.
Cavendish (LON:CAV) should be getting a big payout from this float.
De La Rue (LON:DLAR)
Agreed bid - yet again it is Sky news that is first to announce this. They even got the 130p price right.
https://www.msn.com/en-gb/news...
And... Also reporting a counter bid for De La Rue (LON:DLAR) ! Good to see a nice bidding war despite all the tariff turmoil.
Surprising that Spectra Systems (LON:SPSY) not changed despite the healthy bids for DLAR.
(I hold SPSY in the Boon Fund)
I haven't seen any report about a possible counter-bid. The Atlas bid is agreed with some acceptances. Would be interested to know what report you saw.
Mark Kleinman on X:
Exclusive: The City financier Edi Truell has tabled a fresh offer for De La Rue, the Bank of England currency printer, at a small premium to a recommended 130p-a-share bid worth £263m from Atlas Holdings, a US buyout firm, which I revealed last night.
Thank you
Is it just me or has the Stocko RNS feed become completely unreliable?
Could be where they're getting the info from. For example, Greatland Gold (LON:GGP) has another RNS out this morning. Doesn't appear here, but neither does it appear on the London South East website.
Entered in error
I’ve found the new improvements a big step forward personally. What is not reliable?
Weirdly, even though I mention below that an RNS by Greatland Gold (LON:GGP) which was published at 7.00 a.m. today doesn't appear in the RNS feed here, or on the individual stock's home page under the news tab, I have had an email notification from Stocko stating an RNS has been published. That was received at 07.04 a.m..
My RNS feed has both My Markets and My Folios options actioned.
So Toad1957 is right; something's amiss with Stocko's RNS feed.
If you add the "Other" category under the Filter by on the stocks news screen you will find that there is an RNS listed this morning re "Telfer Ore Reserve".
So the issue appears to be that there is no single choice to show all RNS - they are all categorized in some way by something and unless you include that specific category they will not show.
Good luck finding the sweet spot!
(Sorry replied to wrong comment before) ... :)
Thanks for that
TheRaven - if you look at the Greatland Gold (LON:GGP) page it is there classed as 'Other'. Have a look at your personal settings and check that 'Other' is ticked.
Thanks for that. I found 'Other' and have it ticked now.
I have given up. If you go to https://www.londonstockexchang... and click the
symbol at the right of the top menu you can create your own watchlist for free. RNSs are there at 07 00 on the dot.