Daily Stock Market Report (Tue 15th September 2026) - EVPL, TRST, BRCK, SPR, POLN, EYE, SLP

Good morning. Concerns over rising US Treasury yields, rising fuel prices and potential AI disruption continue, but there was no major news overnight that seems likely to affect markets.
As expected yesterday, President Trump pushed back on a suggestion from Anthropic CEO Dario Amodei that AI development should be paced more carefully. He suggested in a social media post that the idea was a “SICK conspiracy” to favour China:
The only control or “guardrails” that AI needs is a STRONG AND SMART (High IQ!) PRESIDENT, and the U.S.A. has that, in spades!
US equity market inflows: an interesting data point reported overnight by the FT (paywall) shows that inflows into US equity markets are now greater than inflows into US Treasuries. The historic chart included in the article suggests the last time this happened was in 2009/10.
I think there’s probably more value in following company news today than trying to draw meaning from macro events, so let’s turn to today’s RNS feed.
Overnight market movements:
The FTSE is down 0.1% at 10,681
S&P 500 is down 0.2% at 7,605
Brent crude (November) is up 1.8% at $107.54/bbl
Gold is flat at $4,296/oz
Bitcoin is down 0.9% at $77,462
Ed Sheldon joins me (Roland) today.
Today's report is now complete. Sorry we couldn't cover everything of interest on this busy day.
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
GSK (LON:GSK) (£75bn | SR82) | GSK to acquire potential best-in-class T cell-engager (TCE) for multiple myeloma from Chimagen Biosciences. Trispecific TCE targeting T cells and two tumour antigens has potential for differentiated efficacy and safety over current TCEs. Phase I trials expected in 2027. | ||
Big Yellow (LON:BYG) (£1.6bn | SR53) | Has contracted to sell its industrial estate in Staines, Surrey for £36.5 million and has received the £2 million retention held back from the previously announced sale of its Harrow industrial estate. The Group will have received gross proceeds of £75 million from these two disposals. Net debt is now 3.7x EBITDA. | ||
Kier (LON:KIE) (£1.1bn | SR85) | FY26 revenue +6.8% to £4,352.5m with adj pre-tax profit +8.8% to £136.4m. Order book +8% to £11.9bn, now targeting greater balance sheet strength. FY27 Outlook: confident earnings will be at the top end of prior expectations. | ||
Trustpilot (LON:TRST) (£1.0bn | SR69) | Half-Year Results: Revenue +23% to $151.4m with pre-tax profit +32% to £4.3m. Adj EPS +44% to 3.1c. Outlook: on track to deliver FY26 guidance. | AMBER ↓ (Roland) Trustpilot is the biggest faller in the FTSE 250 this morning, down c.15%. Looking through the results, what strikes me is that costs are rising as fast as revenue, limiting operating leverage. I suspect markets are also disappointed by today’s in line guidance and were hoping for an upgrade. While I can see the potential for the business to become the dominant player in its niche, my impression is that several more years of growth are already priced in, so I’m moving to neutral today. | |
Princes (LON:PRN) (£739m | SR70) | H1 revenue +7% to £999.4m with pre-tax profit +62% to £39.2m. Net cash of £374m. FY26 outlook: continues to trade in line with expectations. | ||
Tungsten West (LON:TUN) (£668m | SR35) | Hemerdon tungsten and tin mine has entered production, with ore now being processed. Operational ramp-up towards steady-state production continues. | ||
IP (LON:IPO) (£580m | SR57) | NAVps +3.2% to 113.9p with closing NAV of £1bn, supported by +£27m uplift in Pfizer Obesity Royalty income to £152m. NAVps of c.117p at 11/09/26. | ||
Harworth (LON:HWG) (£575m | SR25) | Programme to achieve £7.4 million annualised cost savings by end 2028. £1.3m already achieved through headcount reduction. When complete, this programme will represent a c.20% reduction in administrative expenses. Board reiterates rejection of Peel offer. | TAKEOVER | |
Gresham House Energy Storage Fund (LON:GRID) (£565m | SR n/a) | After consideration, the Board has concluded that initiating a formal sale process is not in the best interest of shareholders. Notes recent 16% uplift to NAV and improving market sentiment. | ||
Everplay (LON:EVPL) (£545m | SR66) | H1 revenue -8% to £66.9m with adj pre-tax profit -55% to £8.8m. However, company notes “strong start to H2” with new titles selling “ahead of expectations”. FY26 outlook: results expected to be materially ahead of current market expectations. | AMBER/GREEN ↓ (Ed S) | |
Pollen Street (LON:POLN) (£488m | SR83) | AUM +39% to £8.5bn with fee-paying AUM +18% to £5.5bn. H1 profit after tax -29% to £19.9m. Outlook: full-year guidance reaffirmed. | GREEN = (Roland) [no section below] Mark was positive on this business in March and I don’t see much reason to change that view today. Underlying profits for the period are stable versus last year, with adjusted net profit up slightly to £19.9m due to a lower tax bill. Growth in AUM looks encouraging to me, in particular the 18% increase in fee-paying AUM. Although the net investment return of 3.4% was below target, we’re told the portfolio is performing in line with expectations with the exception of Shawbrook Group. New private credit deployments are underway and described as on track. With a covered 7% dividend yield and unchanged full-year guidance, I’m happy to remain positive. | |
Wickes (LON:WIX) (£402m | SR70) | H1 revenue +2.1% to £865.3m with retail +0.8% despite 2.4% inflation. Adj pre-tax profit +1.1% to £27.6m with net cash stable at £151.6m. FY26 outlook: Q3 showing improved trend with mid-single digit LFL growth in Retail. On track to meet consensus expectations for c.10% growth in adj PBT. | ||
McBride (LON:MCB) (£333m | SR75) | Revenue +0.8% to £934.2m with adj pre-tax profit -11% to £48.8m. Adj EPS -2% to 21.6p. Net debt +£18m to £122.8m. FY27 Outlook: YTD volumes in line with expectations, cost environment “difficult to predict” with “further price rises likely”. | ||
Kistos Holdings (LON:KIST) (£273m | SR62) | H1 EBITDA of $205m on a pro forma basis, including Blocks 3,4 and 9 in Oman. Total pro forma production of 20,800 boepd. Adj net debt reduced to $23m. | ||
LSL Property Services (LON:LSL) (£246m | SR66) | Revenue +3% to £92.3m with adj operating profit +11% to £15.9m. Adj EPS +14% to 11.7p. Residential sales transactions were 4% below H1 2025. Regulatory developments are “broadly positive for us”. FY26 outlook: expectations for 2026 are on track. | ||
| City of London Investment (LON:CLIG) (£244m | SR95) | Final Results | FUM +13.9% to $12.3bn, with net fee income +9.7% to $76.5m and pre-tax profit +19.3% to $32.4m. Adj EPS +14.2% to 41.9p with full-year dividend +3% to 34p per share. | |
Afentra (LON:AET) (£225m | SR40) | Revenue of $91m with adj EBITDAX of $41.9m and net cash of $28.4m. Block 3/05 drilling: successful oil discovery at Pacassa SW, Impala-2 expected to be next well in programme. Following a strategic review, intends to pursue growth as an independent E&P company. | ||
Sylvania Platinum (LON:SLP) (£221m | SR63) | PGM production +18% to 95,885 4E PGM ounces. Net revenue +117% to $226.3m with net profit +229% to $66.4m. Average 4E basket price in FY26 was +60% to $2,404/oz. Final dividend of 4p giving total payout of 6p per share for FY26. Outlook: expect to maintain strong SDO production performance. Group production guidance of 85-95 4E PGM ounces in FY27. | AMBER/GREEN = (Roland) [no section below] My normal practice is to take a neutral view on commodity producers when commodity prices are high. The exception to this is when I can see some fundamental value in the stock. In Sylvania’s case, I think that could be true. Production is rising, the balance sheet is strong and shareholders are enjoying decent dividends, which provide upfront (irreversible) cash returns. While there’s obviously some commodity price risk here, I think the stock’s valuation at 1.1x book value and on a P/E of <5 is cheap enough to justify leaving my previous moderately positive view unchanged. | |
Eleco (LON:ELCO) (£193m | SR59) | Revenue +8% to £19.9m, with adj pre-tax profit +91% to £4.2m and adj EPS +85% to 5.0p. | TAKEOVER | |
Fintel (LON:FNTL) (£187m | SR41) | Continuing revenue +5.3% to £38.6m with pre-tax profit +56% to £5.0m. FY26 outlook: current trading remains in line with expectations. | ||
BRCK (LON:BRCK) (£149m | SR84) | “The Board’s expectations for the current financial year remain unchanged.” | AMBER/GREEN = (Ed S) | |
Eagle Eye Solutions (LON:EYE) (£149m | SR65) | Revenue +21% to £46.1m with adj EBITDA -19% to £9.8m and a pre-tax loss of £(0.2)m. Net cash +31% to £16.1m. Secured 13 major customer wins and “continued to deepen relationships with major customers”. Transition to SaaS continues, with 85% of revenue now recurring. FY27 outlook: confident in a return to double digit revenue and adj EBITDA growth in FY27. Broker estimates: - Canaccord FY27E adj EPS 10.8p (prev. 9.9p) - Shore Capital FY27E adj EPS 11.7p (unch). | AMBER/GREEN = (Roland) [no section below] Today’s results highlight the ongoing pain caused by the transition from upfront licence sales to SaaS-style subscriptions. The 31% increase in ARR to £44.5m suggests the transition is progressing at a good pace, with 85% of revenue now described as recurring. Revenue is expected to return to growth this year, as are adjusted earnings, although forecasts suggest cash generation will take longer to recover. I also note that there’s a wide range of views on likely FY28 earnings, with Canaccord cutting its estimate to 13.7p today and Shore unchanged at 16.1p. Graham “nervously” upgraded our view to be moderately positive in July, citing the attractive ARR growth and valuation. I’m nervously going to leave that view unchanged, on the basis that I can see considerable growth potential in this sector for a handful of winning companies. | |
MJ GLEESON (LON:GLE) (£144m | SR45) | Revenue +12.1% to £410m with adj pre-tax profit -50.7% to £10.8m. Completions up by 9.8% to 1,968 homes sold, with reservation rates +8% including bulk sales. FY27 Outlook: August “much weaker” than usual with reservations down. Expect to operate fewer sites than planned in FY27/28 due to planning bottlenecks and pipeline rationalisation. FY27 results expected to be in line with expectations. | ||
Springfield Properties (LON:SPR) (£128m | SR94) | Revenue -13.2% to £243.7m with adj pre-tax profit -35.8% to £12.9m. Adj EPS -32.8% to 8.5p. FY27 outlook: private sales remain in line with expectations, with new contract wins for affordable housing. Confident outlook. | GREEN = (Roland) The transformation of this Scottish housebuilder appears to be largely on track, with net debt eliminated and progress on track with the energy industry build-to-rent project continuing. With the shares trading at a c.35% discount to tangible book value and an improving earnings outlook, I think it’s fair to retain our positive view. | |
Personal group (LON:PGH) (£127m | SR67) | Group revenue up 10% to £25.7m, adjusted EBITDA up 22% to £6.7m, PBT up 21% to £4.6m, basic EPS of 12.3p (H1 2025: 9.6p), cash and deposits of £29.4m, no debt, interim dividend increased by 10% to 9.0p. The board is confident in achieving market expectations for the full year. | ||
EKF Diagnostics Holdings (LON:EKF) (£111m | SR58) | Group revenue of £25.0m (H1 2025: £25.2m), adjusted EBITDA up 2.4% to £5.9m,, PBT of £3.4m (H1 2025: £3.6m), basic and diluted EPS of 0.54p (H1 2025: 0.43p), cash and cash equivalents of £16.0m. Board's expectations for FY 2026 remain unchanged. | ||
MPAC (LON:MPAC) (£105m | SR59) | Revenue down 2.3% to £71m, underlying PBT down 62.5% to £2.1m, underlying EPS of 5.7p (H1 2025: 14p), statutory loss before tax of £0.5m (H1 2025: £8.8m). Net debt of £54m. Outlook for the full year remains unchanged. | ||
accesso Technology (LON:ACSO) (£102m | SR90) | Group revenue down 0.2% to $67.8m. Cash EBITDA up 49.7% to $7.6m, statutory profit before tax down 85% to $0.3m, basic EPS down 68% to $1.07, adjusted basic EPS up 27% to $12.75. Net cash of $7.3m. Full-year guidance remains unchanged – expects revenue of approx. $146m and Cash EBITDA of approx. $20m. | ||
Alumasc (LON:ALU) (£86m | SR49) | Group revenue down 6% to £107.1m. Group underlying profit before tax of £10.0m (FY25: £14.2m) with underlying operating margin of 10.5% (FY25: 13.7%), statutory profit before tax of £9.7m (FY25: £12.3m). Leverage ratio of 0.5x (FY25: 0.35x). Board remains confident of improved FY27 margins. | ||
Amcomri (LON:AMCO) (£85m | SR52) | Continuing operations (excluding Premier Limpet): Revenue of £36.2m, up 40%, adjusted EBITDA of £3.7m, up 2%, profit before tax of £2.0m (H1 25: £1.6 million), basic EPS of 1.94p (H1 25: 1.59p), diluted EPS of 1.89p (H1 25: 1.57p). Trading remains in line with market expectations. | ||
DP Poland (LON:DPP) (£61m | SR23) | Group system sales up 21% to £34.8m, group revenue up 7% to £30.7m, group EBITDA up 24% to £3.2m, group profit of £66m vs loss of £457m in H1 2025. The business is trading in line with the market expectations for the full year. | ||
ICFG (LON:ICFG) (£57m | SR42) | Net operating income increased 30% to USD $32.4m, adjusted profit for the period increased by 34% to $USD 15.4m, record lending portfolio, with gross loan portfolio increasing by 25% to approx. $USD 320m at 30 June 2026. Active borrowers increased by 12% to approximately 212,000. Board remains positive about the group's prospects for the remainder of FY26. | ||
hVIVO (LON:HVO) (£44m | SR28) | Revenue of £16.3m (H1 2025: £24.2m), adjusted EBITDA loss of £4.5m (H1 2025: £3.0m), cash of £13m as at 30 June 2026. H2 2026 revenue is expected to be approximately double that reported in H1. The group expects to report positive adjusted EBITDA in H2 2026 and a low single digit adjusted EBITDA loss for the full year. Record group orderbook of £72m. | ||
Zanaga Iron Ore (LON:ZIOC) (£38m | SR28) | Approx. 30,000 tonnes of ore is being extracted to assemble 100 tonnes of composite sample of the hematite zone targeted for Stage 1's 12Mtpa operations. This 100 tonne sample will be sent for subsequent metallurgical testing. | ||
Haydale (LON:HAYD) (£25m | SR3) | Successful application testing of its patented Super-Efficient Thermal Transfer Fluid. The company has signed agreements with Liquitherm Technologies Group Limited, trading as DC Cooling Solutions, and Levidian Nanosystems Limited, establishing the supply chain and route to market. The company and its commercial partners are in advanced discussions with data centre operators representing approximately 200 MW of capacity, with first installations targeted within 12 months. | ||
ImmuPharma (LON:IMM) (£22m | SR1) | Operating loss of £1.1m, compared to an operating loss of £1.2m for H1 2025. Overall reported loss of £4.7m vs £1.9m in H1 2025. Cash balance of £0.7m. | ||
Symphony Environmental Technologies (LON:SYM) (£17m | SR19) | Independent test results strengthen the evidence for d2p® Ethylene Adsorber. First commercial container-load delivered to Sirane Central Americana. | ||
Southern Energy (LON:SOUC) (£14m | SR37) | The company has successfully drilled and cased the Terrible Creek 21-2 #2 Cotton Valley vertical well in the Williamsburg Field. | ||
Thor Energy (LON:THR) (£11m | SR27) | Receipt of first annual A$1.3m deferred payment for Molyhil sale from ASX-listed Tivan Limited. | ||
Sancus Lending (LON:LEND) (£11m | SR52) | Group revenue increased 36% to £13.1m, operating loss of £(3.4m) compared to an operating loss of £(1.1m) in H1 2025, loss before tax of £(17.4m) compared to a profit before tax of £0.1m in H1 2025, AUM increased 11% to £339.1m as at 30 June 2026. Notes challenging market conditions. |
Roland's Section
Trustpilot (LON:TRST)
Down % at p (£m) - AI, Enterprise and US momentum fuel strong growth [Half-Year Results] - Roland - AMBER ↓
It’s a lot easier for investors when companies provide meaningful titles for their RNS releases, rather than marketing hype. The fact that today’s half-year results from Trustpilot have been met with a double-digit share price drop suggests investors have quickly seen through the hype and focused on the numbers.
My impression of today’s results is a little mixed. While headline revenue growth is strong, profitability hasn’t benefited in the way I might have hoped. Let’s take a look.
Half-year results summary
Top line growth was strong and consistent with the company’s five-year annualised revenue growth of c.21%:
Bookings up 22% to $171.2m
Revenue up 23% to $151.4m
Annual recurring revenue up 15% to $313m
Management highlights recent wins…
Strong Enterprise growth across all regions, with new business logos up 41% YoY alongside significant growth in customers signing >$100k contracts. New customer wins include Expedia, Halfords and Bending Spoons
… and also suggests Trustpilot data is becoming an important part of the AI ecosystem:
Trustpilot data increasingly underpins how AI evaluates and recommends businesses. Ranked #1 globally among cited review platforms according to new research by Seer Interactive.
However, profit and cash performance was more mixed:
Adj EBITDA up 46% to $26.3m
Adj EBITDA margin +2.8% to 17.4%
Operating profit -18% to $4.4m
Pre-tax profit +32% to $4.3m
Adjusted free cash flow $16.0m (H1 25: $15.2m)
I think there are a couple of issues worth highlighting here.
One-off costs: Trustpilot booked almost $6m of adjusting items in H1. The majority of this relates to a €4m fine resulting from an alleged breach of the Italian Consumer Code “relating to a single unfair commercial practice”.
Trustpilot has also restated its accounts to reflect “an historical US sales tax exposure” that’s been found. Total exposure is $2.6m, including $0.8m applied to these results.
If we’re willing to overlook these items, then underlying operating profit rose by 89% to $10.2m in H1. This implies an underlying operating margin of 7%, up from 5% in H1 2025.
Operating costs & profitability: while it’s encouraging to see some improvement in underlying margins, my impression is that both margins and operating leverage are lower than I might have expected to see here. The underlying cause of this seems to be that operating costs are rising broadly in line with revenue:
Cost of sales up 18% to $25.7m
Gross margin: 83% (H1 25: 82%)
Sales and marketing costs up 22% to $41.0m (27% of revenue, unchanged from H1 25)
Technology and content costs up 21% to $38.6m (26% of revenue, unchanged from H1 25)
General and administrative costs up 19% to $34.4m, excluding the one-off costs above.
What strikes me about the increase in all of these measures is that it’s almost exactly the same as the increase in revenue (+22%). For a business of this kind, I might have expected costs to be diminishing as a percentage of revenue.
It’s possible that the company’s cost growth will slow as it scales further, supporting higher operating margins. I guess it may depend if Trustpilot achieves the kind of ubiquity enjoyed by services such as Rightmove and Autotrader. Right now, it looks like achieving growth requires a direct input of sales and marketing effort, plus additional on-boarding and tech costs.
KPI metrics: operational progress?
The selection of operating metrics shared in today’s results seem mixed to me:
Number of paying customers +5%
LTM Net Dollar Retention rate -2% to 101%
Average annual contract value up 18% to $11,513
Number of active reviews up 20% to 394m
It’s hard to be certain without more data, but my impression of this is that churn could be relatively high level among smaller customers, while pricing power and upsell activity with existing customers could be limited.
A combination of attrition among SME customers and some larger new customer wins could inflate the average contract value without a corresponding actual increase in the number of larger customers.
I’m happy to consider alternative interpretations of these metrics, but that’s the feeling I get.
Outlook
Following a strong first half, we maintain our outlook for high-teens constant currency revenue growth for the full year and 2-3ppt YoY adjusted EBITDA margin increase for FY26. We remain confident in delivering sustainable growth and operating leverage over the long term, as laid out in March, given the significant market opportunity.
I don’t have access to broker forecasts today, but the 2026 consensus revenue estimate on the StockReport is $309m and last year’s EBITDA margin was 15.6%.
Combining this with today’s guidance suggests we could see FY26 adj EBITDA of c.$56m.
That gives the business an EV/EBITDA ratio of c.21x – not exactly cheap.
Roland’s view
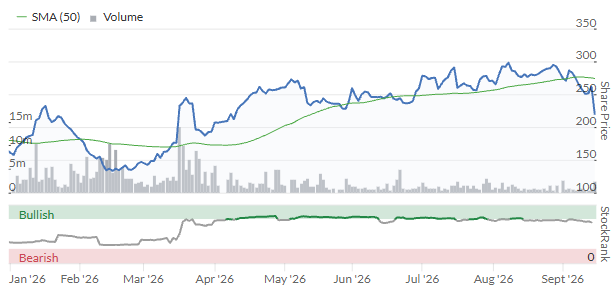
Graham was AMBER/GREEN on Trustpilot in January and noted the relatively low valuation of the business when compared to annualised recurring revenue. Based on today’s results, I estimate the market cap at 3.7x ARR, unchanged from when Graham reviewed the business.
Checking the share price chart shows that the stock has risen since then, but has largely given back those gains following this morning’s falls:
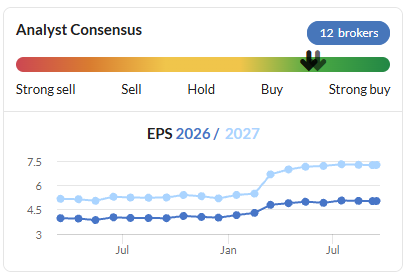
EPS estimates were upgraded following March’s results, but consensus has remained largely unchanged since then.
I’d speculate that the lack of a further upgrade might help explain today’s sell-off – the shares also fell in July following an in-line update:
In the absence of an upgrade to expectations, I’m struggling to get on board with the valuation here. While the business may have the potential to become the dominant service in the trust market, I would argue that several years’ growth are already priced in.
I’m also a little uncomfortable with the sharp rise in costs which suggests the business is still needing to invest quite heavily to build further market share and brand awareness.
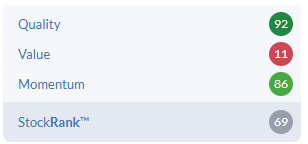
On balance, I’m going to move to an AMBER view today. I think this is a situation that could reward further research and in-depth understanding, but based on this review I think the shares are up with events. This view is also reflected in the very low ValueRank:
Springfield Properties (LON:SPR)
Down 0.1% at 107p (£128m) - Final Results - Roland - GREEN =
We’ve covered this Scottish housebuilder a few times in recent months, notably in June when Graham upgraded our view to GREEN. I also took a look at the business in a Stock Pitch in March, so I’d recommend this past coverage to provide a more in-depth view on the company and its strategy.
In short, Springfield is developing homes for private and affordable sale and has an agreement to build rental housing for the renewable energy industry in the North of Scotland.
Today’s full-year results appear to be slightly ahead of broker forecasts, but this is tempered by some very slight reductions to forecasts for FY27 and FY28. Let’s take a look.
Full-year results summary
Revenue down 13.2% to £243.7m
Gross margin down 2.2% to 16.4%
Pre-tax profit down 37.4% to £11.9m
Adj EPS down 32.8% to 8.51p
Net cash of £1.2m (FY25: net debt £20.9m)
Total dividend up 50% to 3.0p
It’s worth remembering that last year’s results benefited from income from one-off land sales that were carried out in order to reduce debt.
Stripping this out shows that underlying revenue from private housing and affordable housing sales rose by 5.9% and 10% respectively last year. Underlying profitability is also said to have improved:
Significant year-on-year growth in adj. profit before tax when excluding the contribution from land sales in both years
Private housing: completions fell by 5% to 474 homes, but the average selling price rose by 11% to £348k to reflect a higher value mix of properties. Overall revenue rose by 5.9% to £165m.
Private sales generated a customer satisfaction score of 97% (FY25: 96%).
Affordable housing: completions rose by 3% to 243, with the average selling price up 8% to £224k. Springfield says this reflects increasing pricing across the sector following an increase in Scottish Government grant subsidies.
Balance sheet & buybacks: a reduction in debt over the last year has helped to strengthen the balance sheet, leaving Springfield with a small net cash position at the end of the year.
Like a number of larger housebuilders, Springfield shares continue to trade at a hefty discount to book value. I estimate a net tangible asset value per share of 145p from today’s accounts.
With the stock trading at 107p as I type, that means Springfield is trading at a discount of more than 35% to its tangible asset value.
In this context I’m not surprised to see the Board allocating some capital to share buybacks. In August the company announced plans to buy back up to 5,957,273 shares, equivalent to around £6.5m at current prices.
Buying back stock at such a hefty discount to book value should provide a useful boost to NAV and could also generate attractive returns on investment at current levels. Based on last year’s pre-tax profit, I estimate that buybacks today could generate a ROI of 9%.
Outlook
North of Scotland: initial agreement signed for c.300 homes across six sites for “a major energy infrastructure provider” to accommodate workers upgrading the national power grid. The “main works agreement” for the first site is expected “imminently”.
Private housing: reservation rate steady and in line with expectations.
Affordable housing: “continued to secure new contracts on favourable terms”.
Land bank: after deleveraging the balance sheet more quickly than expected, Springfield has decided to develop more of its Central Scotland sites rather than selling them. This is expected to generate additional revenue and profit in the medium terms.
Updated broker forecasts
House broker Cavendish has issued updated FY27 and FY28 forecasts today, plus new FY29 estimates. These present a slightly mixed picture, but I don’t think they detract from the value on offer here:
FY26 actual (Cavendish calc): 7.6p
FY27E adj EPS: 7.8p (-2.5% vs 8.0p previously)
FY28E adj EPS: 11.1p (-3.4% vs 11.5p previously)
FY29E adj EPS: 11.6p (new forecast)
The main changes to the forecasts relates to private housing, which is now expected to be slightly weaker than previously expected over the next couple of years. There’s also a reduction in revenue expected from land sales to reflect Springfield’s decision to keep more of its Central Scotland sites.
Rental income from the planned North of Scotland projects is expected to become a material contributor to revenue in FY28 (c.£20m) and a key driver of growth.
Roland’s view
I guess this is technically a profit warning, but I think it would be overly harsh to classify it in this way.
These are minor adjustments and could easily reverse again at some point, depending on macro conditions.
I don’t think anything in today’s results detracts from the attractive valuation of the business or the growth potential of the business from a combination of build-to-rent and (hopefully) a wider UK housing market recovery over time.
Today’s results show an improved balance sheet and suggest a positive outlook for earnings. When paired with a 35%+ discount to tangible book value, I think it’s appropriate for us to leave our GREEN view unchanged.
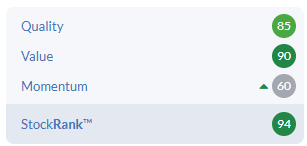
The StockRanks also remain positive, with Super Stock styling and strong or improving factor scores:
Ed S's Section
Everplay (LON:EVPL)
Down 1.5% at 369p (£545m) - Half Year Results - Ed S - AMBER/GREEN ↓
Video game developer and publisher Everplay Group (formerly Team17 Group) has posted its H1 results today.
Key figures:
Group revenue of £66.9m, down 8%.
Adjusted EBITDA of £9.2m, down 52%.
Profit before tax of £1.6m, down 89%.
Basic EPS of (0.4p) versus 7.4p in H1 2025.
Adjusted EPS of 3.7p versus 10.5p in H1 2025.
Cash and cash equivalents of £57.1m.
Interim dividend of 1.1 pence per share, up 10% on H1 2025 dividend.
Outlook:
Strong start to H2 2026 trading, supported by record sales generated from Hell Let Loose: Vietnam and Wardogs, alongside continued resilience from the Group's back catalogue.
Further new title releases expected in H2 2026, providing additional opportunities to drive growth through the remainder of the year.
The Board now expects FY2026 revenue and adjusted EBITDA to be materially ahead of current market expectations, with adjusted EBITDA margin expected to be broadly in line with FY2025.
Company-compiled consensus showed FY2026 revenues of £175.2 million and adjusted EBITDA of £50.7m.
We have entered the period with real momentum, and feel confident in materially exceeding market expectations for the full year. I am pleased to share that our major new releases, including Hell Let Loose: Vietnam and Wardogs, are performing well ahead of our expectations, breaking many sales and player number records.
With a strong balance sheet, resilient catalogue, growing portfolio of first-party IP and innovative third-party games, we are well positioned to deliver accelerated growth.
Ed S’s view:
Today’s H1 results from Everplay are a mixed bag. On one hand, performance figures for H1 look a little concerning both on a statutory basis and an adjusted basis (most of the adjustments relate to amortisation of acquired intangible assets – see table below).
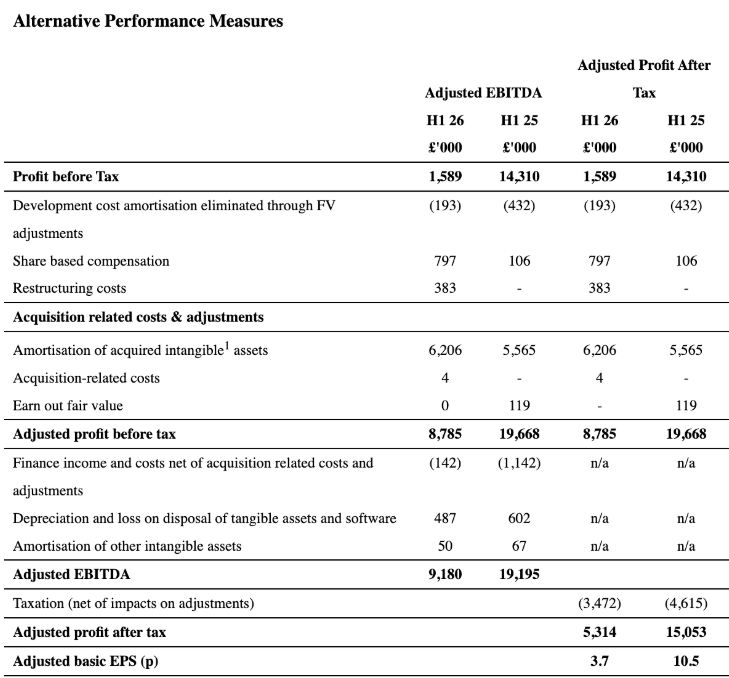
On the other hand, we have news that FY2026 revenue and adjusted EBITDA are likely to be ‘materially ahead’ of current market expectations. We also have a healthy cash balance of £57.1m and a 10% increase to the interim dividend.
In the results, the company explains that the H1 revenue drop reflects the phasing of major FY2026 releases into H2. The adjusted EBITDA drop reflects lower revenues and investment ahead of the major H2 release programme.
The softer performance in the half compared to the prior period reflects the timing of the new release schedule in FY 2026, with larger titles in the second half, together with the timing of investment and other costs ahead of the associated revenue contribution.
Looking ahead, the company is very bullish on its prospects for the remainder of the year. It notes that it has made a strong start to H2, with new titles Hell Let Loose: Vietnam and Wardogs performing well ahead of expectations.
The Group is on track to deliver a record second half performance, returning to strong growth and a sharp improvement in margins, supported and corroborated by the very strong revenue performance from titles released so far in August and September.
When Graham last covered Everplay in late July, he awarded it a GREEN rating. However, since then, its share price has shot up from 239p to 369p – a rise of approx. 54% (it popped 21% last Friday on news that its Wardogs game had passed one million copies sold).
That’s a huge rise in less than two months. And it has implications for the risk/reward skew.
Is it still worthy of a GREEN rating today? Well, the company has told us that revenue and adjusted EBITDA for the year will be materially ahead, which is a big plus.
However, the valuation has risen significantly since late July – the trailing P/E ratio is now around 15. And given that adjusted EPS for H1 was only 3.7p, we’ll need a huge performance in H2 for the company to achieve the 26.8p per share full-year earnings forecast.
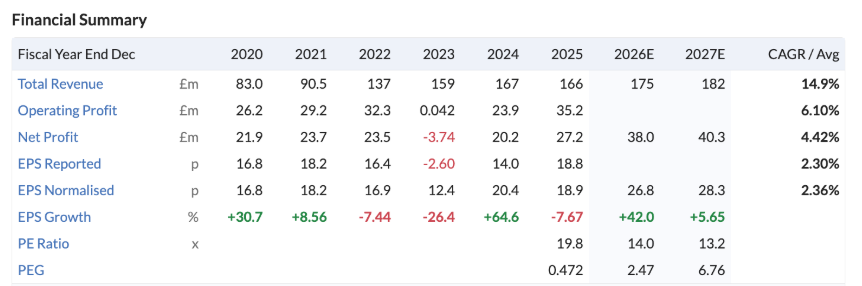
Note that the StockRank system gives the stock a low score of 27 for Value. On the plus side, the StockRank is rising – since the end of July it has climbed from 49 to 66.
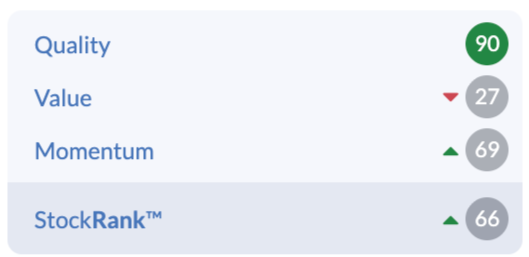
Given the 50%+ rise in the share price in less than two months, I’m going to do something that is perhaps a little controversial and take the stock down a notch to AMBER/GREEN. I still see appeal in it, however, the risk/reward proposition isn’t what it was back in July.
BRCK (LON:BRCK)
Flat at 46p (£149m) - AGM Statement - Ed S - AMBER/GREEN =
BRCK Group – a distributor and provider of specialist products and services to the UK construction industry – has today provided us with a short AGM Statement:
“The trading environment in the first five months of our current financial year has been consistent with the outlook statement issued in July on publication of the Company’s FY2026 results when we commented that near-term market conditions remained challenging. The UK housebuilding industry continues to be subdued, and broader macroeconomic conditions mean there is limited visibility in the timing of a recovery in new housebuilding starts.”
“The Board’s expectations for the current financial year remain unchanged.”
The company goes on to say that it benefits from a diversified business model and that trading at its Design & Install division – which focuses on specialist work including cladding remediation and accounted for 20% of revenue last financial year – has started the new financial year well. It adds that it is encouraged by the improvement in the pace of Building Safety Regulator (BSR) approval decisions.
Ed S’s view:
Back in July, Roland gave BRCK an AMBER/GREEN rating and I think that remains appropriate today. Ultimately, the stock looks very cheap – it’s currently trading on a P/E ratio of less than six.
Note that the StockRank system gives it a 94 for value. The overall StockRank score is 84, which is solid.
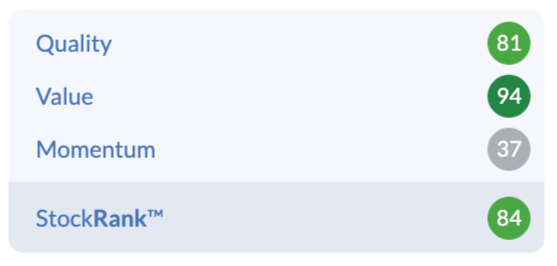
Looking beyond the valuation, another attraction is the dividend yield. With analysts expecting a payout of 3.6p per share for FY2027, it stands at around 7.8%.
Earnings per share for the year are expected to be 8.0p. So, we have a dividend coverage ratio of about 2.2.
On the downside, the company notes that near-term market conditions remain challenging due to the subdued UK housebuilding industry. It adds that there is limited visibility in the timing of a recovery in new housebuilding starts (we’d need to see UK interest rates come down to improve affordability and at this stage it looks like rates may rise in 2026 so things may get worse before they get better).
One other thing to be aware of is that this company is a heavy ‘adjuster’. For example, for FY2026, statutory pre-tax profit was £6.3m while adjusted pre-tax profit was £38.3m (see Roland’s July write-up for a comprehensive analysis here).
Looking at the company through a value investing lens, however, I can see some appeal, especially when the big dividend yield is considered. So I’m happy to leave it at AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
Re; Everplay (LON:EVPL)
Bulkhead have tweeted today that they have sold 2 million copies of WarDogs @ £37 as the base price and a Supporters Edition @ £46. The vast and overwhelming majoirty will have bought the base pack
Thanks for sharing the Everpaly info. In a "The Game Buisness" interview Bulkhead's CEO has said 400,000 units would have been enough to survive and 600,000 would be "ordinary" — so 2 million is over 3x what they considered a good outcome. In addition the Wardogs review score has also moved to "Very Positive" (85%, ~35,000 reviews), up from the "Mostly Positive".
This could be a much bigger winner than anyone thought?
Pebble Beach Systems (LON:PEB)
The earnings numbers on Stockopedia are significantly higher than those shown on Sharescope,
Stockopedia FY26 and 27 respectively EPS of 3.1 and 3.3
Sharescope FY26 and 27 respectively EPS of 2.3 and 2.5
Both show the same revenue numbers of £12,4m and £13.7m. As a statement of the bleeding obvious both can't be right!
could it be that Stockopedia and Sharescope have used different analysts' forecasts? I have the sense that Stockopedia only has access to ResearchGate
Sharescope's figures mirror those from Cavendish who have a target price of 38p. Not that I pay too much attention to broker's target prices.
Sharescope's figures mirror those from Cavendish who have a target price of 38p. Not that I pay too much attention to broker's target prices.
Mello IT . Am I alone on never being sent the link? I hope I get a recording of Max King later at least.
If time permits, or later in the week (if quiet), I would be very grateful for any commentary on Princes Princes (LON:PRN). Update today inline and further confirmation of very significant cash pile (albeit majority of that arising from recent IPO).
It strikes me as interesting. On the one hand, it appears very conservatively priced, including compared to competitors (e.g. Premier Foods); that price difference becomes even more extreme when adjusting for the £374m cash pile which is essentially half the market cap. There has to be an argument that deployment of that cash pile could (and perhaps should) turbo-charge future earnings and the valuation multiple.
Bear case appears to be: (i) no dividends despite the cash pile, which is stated to be earmarked for acquisitions, (ii) no certainty that the cash will be sensibly deployed with respect to those intended acquisitions - i.e. risk of overpaying etc, and (iii) the 87% family stake (you are in effect along for the ride, with the hypothetical risk of a a low ball delisting). I also do not entirely follow the purpose of the announced (but not activated) share buyback, although I suppose there is some (not entirely satisafactory) commentary in today's results. Buybacks in general terms carry the risk of exasperating the concern at (iii) - i.e. will serve to further diminish the free float.
All in, my sense is that this is still materially mispriced, and I own a medium sized position (made as of today), but interested in other thoughts. Many thanks!
Princes (LON:PRN)
i would second a look at this - there seems to be some decent value characteristics here - i wander if floating might be a route to some future exit route for main shareholders ? i think copilot seems to think thats not the primary reason - ie copilot seems to think seem to have listed to raise funds for expansion.
With dominant shareholder(s) it may not be for some ?
Note cash is matched by current trade and other payables - if they were to reduce cash well could you get into issues with supplier credit issues ? - note they do have very chunky inventories receivables and assets - so no overall worries it does seem to have an overall very strong balance sheet - the opposite of your your private equity pimped up type float.
I guess ref buybacks - if the owners are savvy and they know its good value going down that route its good value plain and simple - not sure what the implications are when one ones that much already ?
I hold Princes (LON:PRN) as to me it looks cheap for some great brands and resilient performance in difficult markets. Cash pile helps and a substantial acquisition could transform the earnings picture - likely in short term from the RNS commentary. Bear point could be the recent departure of the CEO, with no new appointee as yet. I will remain patient for now.
Princes (LON:PRN)
one oddity is the decline in the stockranks with a drop from 85 to 70 last 30 days (before todays update mostly) - for those that like the comfort blanket of a green rating that comfort blanket is lacking - i get the momentum rank being poor - seems odd that that quality score would take such a hit ? anyone got any clues here? All i can guess is that as a newly listed entity its pehaps to be expected that the act of listing might have adjusted some of the lfl calcs adversly ? seems odd drop would be in last 30 days before todays update when it seems like nothing would have been happening. With net profit clearly trending up seems slightly odd that quality would not be trending updwards.
Princes (LON:PRN) - I think the numbers are all a bit skewed given recent IPO. See that despite net cash of £374m, EV shown higher than MC! Just one example of why Stocko numbers may not be up to date, or reflecting current position perhaps?
Thank you for your coverage of Springfield Properties Roland, it coincided with my reply to Charles Mitchell also a holder.
I must say I did not read as a profit warning. Looks a great asset play to me with the buybacks increasing NAV per share further.
Everplay (LON:EVPL)
Excellent analysis from Ed. There is nothing wrong in expressing your own honest views backed by numbers, whether they are controversial or not.
All the best
....given that adjusted EPS for H1 was only 3.7p, we’ll need a huge performance in H2 for the company to achieve the 26.8p per share full-year earnings forecast.
Ed, Fair point on the Everplay (LON:EVPL) EPS arithmetic — 3.7p in H1 against a 26.8p YE does mean H2 needs to carry 23p. Worth noting though that the 26.8p figure pre-dates today's guidance upgrade "materially ahead of expectations", so the bar is higher than the original YE 26.8p, once brokers reprice it.
What makes me more confident is that this is backed by hard numbers — Wardogs' 1m+ day-one units and 400k+ peak concurrent players and Hell Let Loose success both verifiable via SteamDB rather than just company assertion, and both games still have most of their commercial runway ahead within the financial year.
STOP PRESS Everplay (LON:EVPL)
Upgrade just out from Zeus: "We conservatively raise 2026 revenue and Adjusted EBITDA to £191.7m (+11.7%) and £55.1m (+12.5%) from £171.6m and £49m, respectively.
Try and spend two hours (this is what I have done) properly investigating Everplay (LON:EVPL) FCF generation, and if you are good at that you will certainly change your mind.
We have analysed Frontier Developments (LON:FDEV) and shared the investment case here. We hold Frontier Developments (LON:FDEV) in our UK portfolio at much lower prices than current levels.
I hope Everplay (LON:EVPL) works for you. You were talking about it yesterday so I get your point!
All the best
£8M FCF in 1H26 despite preparing for launch of 2 large titles in 2H26 doesn't look too shabby to me. Expected to generate FCF of £35M in FY26 and over £40M in FY27. Trading on 8% FCF yield and announced today that 2M Wargames have been sold since launch on 10/9. I take the over that this one will be above 400p in next 6 months
Everplay (LON:EVPL)
They haven’t generated £8M so better to leave this. I truly hope the price will go up.
Good sector to be involved to be honest and Everplay (LON:EVPL) has a good balance sheet. Just not for me at the moment.
All the best
Everplay (LON:EVPL)
Interesting yiannos- are you willing to share executive summary of your calcs
my ramblings as follows.
increase in cash £5.2 million - dividends paid £2.7 mill - purchase of own shares £0.4
there is share based compo of £0.7 mill that would give me £7.4 mill adjusted - if we say we want to look at cashflow before divis and share buybacks - but factor in cost of share based compo.
and proceeds from sale of intangibles £1 mill - could you exclude this windfall from figures ?
that would give you £6.4 mill
Its a series of big numbers so there is perhaps any number of ways you could look at it.
If we say that intangibles have decreased by £4 mill - perhaps it could be agued that cashflow has temporarily benefitted to to tune of £4 mill and that reduction should be excluded if we want to get to steady state position ref intangibles - i would normally take the viewpoint that intangibles coming down is better than going up as i would rather have the positive benefit of excess cashflow rather than having to invest in something that may not pay future dividends.
I would say it would take 5.5 years of £40 mill profits to catch up with the £230 mill intangibles value spent - so perhaps at present your calcs might simply discount some of the capitalisation as likely to not return in the future ?
perhaps its some trickery to do with leases
Trustpilot (LON:TRST) Lost faith in them, their rating is worth little because they receive money from the companies they are reviewing.
Booked a flight with Opodo which they cancelled and would not refund my money. Put a bad review on Trust Pilot which was then deleted by Trustpilot because Opodo said they were looking at my claim.
Opodo sent an email to say they were looking at my claim but then did nothing and ignored emails for the next 10 months. Only got a refund when i put a bad review on all the other review channels and sent copies to Opodo.
Anyone have a spare ticket that they're not using and I can have for free for the Investor Summit this Friday?
Its not really my area of interest/expertise, but just had a brief skim through the agenda and there's 1 session I'd like to attend.
I'm on X/Twitter @ boonfund and on Substack @ boonkoh to message me!
This Afternoon...
Mello Investment Trusts & Funds 15th September from 1pm: https://www.melloevents.com/mitf150926
This is a FREE event and you can register via the link above.
Full Mello Investment Trusts & Funds agenda (subject to minor change):
1:00pm Keynote Presentation from Investment Columnist and former Fund Manager, Max King: "Who's Afraid of the Bond Market?"
1:30pm Company Presentation from Jpmorgan China Growth & Income (LON:JCGI)
2:00pm Company Presentation from Law Debenture (LON:LWDB)
2:30pm Company Presentation from Capital Gearing Trust (LON:CGT)
3:00pm Company Presentation from Custodian Property Income Reit (LON:CREI)
Lots to enjoy virtually as we warm up for MelloLondon in Chiswick this November... where the investor community can come together f2f once again.
If you cannot attend either event LIVE, you can still register and will receive the recording within 48 hours.
Morning team another one for Pollen Street (LON:POLN) if you have time.
Pollen Street (LON:POLN) I hold.
Morning Roland and Ed,
Would you be able to comment on the results from Pollen Street please?
Thanks!
US debt grows over $70K per second.
Mr.XYZ earns £200K a year in the UK. The equivalent in debt growth (comparing his revenues with the US government's revenues) is 0.33 pence per second or just over £100K a year.
US debt has grown by $8.5M until I have posted this.
I hope this is clear!
All the best
They seem to have been able to kick the can for years though Yiannos I thought the debt would blow up over a decade ago, how do you see this playing out yield curve control like in the 70's to try and inflate the debt away ? or something else.
I'm almost beginning to think Democrats would be best to try and avoid winning the next election as the mess that will be inherited will be off the scale all be it Biden is far from blameless also in adding to the debt pile.
Interest payments are so different than past years. They are heading towards 30% of US government revenues. Over $10T have to be rolled over next year on much higher rates.
Long deep recession is around the corner and as soon as inflation cools another round of a multi trillion QE to take the rates back to zero.
The other side is tax increases and spending cuts-exactly what they did in the early 1990’s that has actually worked. Can this be done in our days with all this social media nonsense?
Democrats will win the House and fight hard to win the Senate. If both happen you will see Trump turn into a different softer personality-one that his main interests will be to survive!
All the best
Interesting to see a feature in FT Alphaville that the wedding celebrations of Donald Trump Jnr on an exotic island were paid for by a Russian businessman (whose English is quite limited) who has current or previous close connections to Putin. Of course Jnr posted that they were good friends and this was an unwarranted slur.
Why is it Russians find the Trump family so alluring?
Should that be £10k rather than £100k? Or are you saying us debt will grow from 40tn to 60tn in 1 year?
My numbers are correct. You are reading this the wrong way. No the debt will not grow to $60T in a year!
All the best
I'd read it was $90K per second yiannos1 but what's $20K per second between friends!
-:)
It’s $70K
All the best
City of London Investment (LON:CLIG) i hold
Surprisingly not on the list of companies reporting today. Final results look rather good to me. Unfortunately on holiday with limited time to dig deeper but would appreciate comments from Roland or fellow subscribers.
Morning rwh3ue,
Apologies, City of London Investment (LON:CLIG) somehow got missed at 7am this morning. I've now added them to the table.
Roland (disc: I hold CLIG)
Springfield Properties (LON:SPR) (I hold) Debt has been paid off following land sales, trades at a 30% discount to NAV. House builders are well out of favour at the moment, but SPR is it seems doing OK. They are developing further relationships with the Infrastructure industry busy in the North of Scotland. they already have a contract to build and lease 300 houses. They plan now to develop the remainder of the central Scotland land bank. Equity Development have a (paid for by SR) research note here https://www.equitydevelopment....
Thank you for the link Charles Mitchell, we hold and I'm tempted to add. I'm a bear who's been wrong for 3 years re American markets, Treasuries and equities, but I fear a re-run of 2008/2010 might be getting closer. I suffer from Trump-phobia. We wouldn't escape but there are some shares I'm happy to stay with.
Pebble Beach Systems (LON:PEB) interim results came out last Wednesday 9th Sept. Not reviewed by the team. The Stock Rank system has just caught up with the changed figures and lifted the SR from 80 to 97. For those looking for SR jumps I believe this qualifies. I hold.
same !
Morning Revs8
Pebble Beach Systems (LON:PEB
I hold and added a few after the interims. I bought my initial holding some time back after watching a presentation by Laurence Hulse.
The share price is certainly somewhat sparky this morning. In fairness and without wishing to detract from the great work of Ed and the team I was a little sceptical of the SR jump impact. I am happy to be proved wrong though.
Pebble Beach Systems (LON:PEB) many thanks Revs8. Added to my watch list.
Same. Popped up on my Jump screen so I've bought in to Pebble Beach Systems (LON:PEB) this morning.
With Trustpilot (LON:TRST) the key number I always look at is net growth in paying customers. They say:
Revenue growth was driven by a 13% cc increase in the average annual contract value ('AACV') to $11,513 as we focus on higher value enterprise customers. The number of paying customers, net of churn, increased 5% year-on-year to 28,014.
I am not sure I want to pay 40x for 5% customer growth - but then I've been the loser of that decision so far!
Morning,
The Shareholders Board, the forum we built for verified investors to talk in detail about what they own or follow, is now at over 100 members and the quality of conversations has surprised even us!
It'd be great to see a few more familiar names over there. Joining is free at https://theshareholdersboard.c...
Just to note that you'll need a photo ID to be verified - that's the friction we've chosen to include to keep things civil, and so far, it's working exactly as we hoped.
LSL Property Services (LON:LSL) BRCK (LON:BRCK) Springfield Properties (LON:SPR)
The housing related shares in my portfolio. All appear to be holding their own in an awful market that unfortunately is likely to remain awful for some time.
All are cheap, depending which metrics one looks at and failing a bid are likely to remain so. I shall continue to take the reasonable dividend income and wait for light at the end of the somewhat long tunnel.
On a lighter note BRCK (LON:BRCK) is the only one where I am under water so to speak, but the nice dividends redress the current capital loss.
Roland and team if you wish to choose one of the three to analyse that would be appreciated.
Orosur Mining Announces Discovery at El Cedro
https://www.londonstockexchang...
Were the bold capitals really necessary?
I presume it was copy/paste
Kier (KIE) results seem good. “FY27 expectations increased”
Sylvania Platinum (LON:SLP) results look rather good.
being paid to wait for the re-rate!
Everplay (LON:EVPL) looking very very strong
On their retail investor webinar they said broker upgrades are 10% to revenue and EBITDA. That's perhaps not quite as material as I was expecting but it potentially leaves room for a further beat later in the year if Wardogs continues to perform well.
ACSO Accesso Technology is worth looking at IMO. Only inline today but possibly has the hallmarks of a turnaround. Will be interesting to see if there is any share price reaction to the qualitatively positive comments from the new CEO. I like companies to be understated so I like the tone from Lee Cowie. I hold.