Daily Stock Market Report (Tue 28 Jan 2025) - $NVDA, TIME, CCC, HFD, PETS, ECEL, BAG

Good morning!
My optimistic comments around the UK market yesterday were overshadowed by Nvidia ($NVDA), which fell by 16% and lost $600bn in market value - the largest fall in value by a single stock in financial history. The Nasdaq as a whole fell by 3%.
The reason? Fears around Chinese AI startup DeepSeek, which claims to offer AI language models that require only a fraction of the computing power of US-based rivals.
It’s fascinating how narratives can change so suddenly. A bubble can persist for years, and then collapse for particular reasons that few, if anyone, could have predicted. But the overvaluation was visible for a long time in advance. Yesterday’s events look to me like they could herald the beginning of the end of the AI boom.
If that’s true, it could be relevant for a theme I’ve highlighted before - the excessive concentration of ETF products in Mag 7 stocks such as Nvidia. In my view, this creates the risk of unexpected volatility for investors who wrongly assume that these products are more diversified than they really are.
From stockcharts.com, here are the weightings of the top three S&P 500 components, which together account for nearly 20% of the value of the index:

Perhaps if we see unexpected volatility in the US indexes, that could lead to renewed interest in non-US markets (such as the UK) and in active investing? Or perhaps that’s just wishful thinking on my part!
Nvidia’s stock price has still had a very good year:

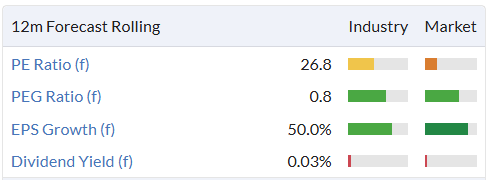
And here are its value metrics (updated to reflect yesterday's fall). I’m not tempted yet!
1pm: all done for now, thank you.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Rentokil Initial (LON:RTO) (£9.8bn) | TU | FY24 trading in line. | |
RS (LON:RS1) (£3.2bn) | Q3 TU | Full year pre-tax profit is likely to be “around the bottom end of the consensus range”. | |
Computacenter (LON:CCC) (£2.2bn) | FY TU | 2024 adj pre-tax profit to be “at the lower end of the range” of forecasts. Y/E net cash £480m. | GREEN (Roland - I hold) |
SSP (LON:SSPG) (£1.4bn) | TU | Q1 LFL sales +6%, FY guidance unchanged. | |
Pets at Home (LON:PETS) (£967m) | Q3 TU | FY25 in line. | AMBER (Graham) Full-year guidance is unchanged. Company is doing well in tough circumstances but I think it could be at fair value here. |
A G Barr (LON:BAG) (£653m) | TU | 24/25 results in line with revs +5%. FY25 expectations are unchanged. | GREEN (Graham) Pleasing performance with rising margins and good progress integrating Boost. Not much to dislike here. |
Harworth (LON:HWG) (£536m) | TU | 2024 EPRA NDV to be “broadly in line” with consensus. | |
PPHE Hotel (LON:PPH) (£533m) | FY TU | 2024 results to be in line with expectations. LFL room rev +2.1% to £306m. | |
Foresight group (LON:FSG) (£419m) | AUM update/acquisition | £800m added to AUM primarily by the acquisition of WHEB Asset Management. | |
SThree (LON:STEM) (£383m) | Final Results | Fees -9%, PBT -13% to £68m. Challenging conditions persist. FY25 PBT estimate: £25m (unch). | |
Big Technologies (LON:BIG) (£375m) | TU | FY24 in line with exps, with revs -9% to £50.3m and adj EBITDA -18% to £27m. FY25 also in line. | |
Wickes (LON:WIX) (£371m) | TU | FY24 profit expected to be towards upper end of forecast range. | |
Idox (LON:IDOX) (£291m) | Final Results | FY24 results in line. | |
| Henry Boot (LON:BOOT) (£285m) | TU | FY results to be in line with market exps. Have “a bit more optimism” for 2025, increasing planning apps. | |
Halfords (LON:HFD) (£276m) | TU | Upgrade to FY25 profit exps after strong Q3 trading. Adj PBT exps £32m to £37m. | AMBER (Roland) |
Franchise Brands (LON:FRAN) (£269m) | FY TU | Adj EBITDA to be “very marginally below” current expectations. | |
dotDigital (LON:DOTD) (£251m) | HY TU | Performance tracking in line with expectations for the full year. | |
Synthomer (LON:SYNT) (£245m) | TU | 2024 results to be in line with expectations. Volumes improved in H2. | |
S4 Capital (LON:SFOR) (£205m) | TU | 2024 results expected to be slightly ahead of current consensus with reduced debt. | |
Foxtons (LON:FOXT) (£201m) | FY24 TU | “2024 earnings ahead of market expectations” on market share gains. Adj op profit +33%. | |
accesso Technology (LON:ACSO) (£196m) | TU | FY revenue in line, “cash EBITDA” ahead of expectations. | |
Eurocell (LON:ECEL) (£160m) | FY TU | 2024 profits in line with expectations. Sales down 2% to £358m. | GREEN (Roland) |
Eleco (LON:ELCO) (£118m) | FY TU | Rev +16%, 2024 results to be “ahead of market forecasts”. | |
Microlise (LON:SAAS) (£107m) | FY24 TU | Adjusted EBITDA and net cash “comfortably ahead of market expectations”. | |
| Time Finance (LON:TIME) (£60m) | Interim Results | Rev +16% to £18.2m, PBT +44% to £3.9m. NTAV +14% to £41.5m. FY trading exp “at least” in line. | AMBER/GREEN (Graham) Mildly positive view as it's expensive but offers unusual growth for a lender and improving quality. |
Personal group (LON:PGH) (£54m) | TU | Adjusted EBITDA ahead of expectations. | |
Lords Trading (LON:LORD) (£51m) | FY24 TU | FY24 adjusted EBITDA slightly below consensus. | |
Dialight (LON:DIA) (£37m) | TU | Q3 “slightly ahead” of expectations. | |
Pressure Technologies (LON:PRES) (£13m) | Contract award | Delivery of pressure vessels to a US defence contractor in Q1 2026. | |
Northcoders (LON:CODE) (£13m) | TU | FY24 in line with exps. Revenue +24% to £8.8m. |
Graham's Section
Time Finance (LON:TIME)
Down 2% to 63.5p (£59m) - Interim Results - Graham - AMBER/GREEN
We already covered the H1 update for TIME in December.
Today we have the interim results.
Headlines for the six months to Nov 2024 are as seen in the trading update:
Revenue +16% to £18.2m
PBT +44% to £3.9m (so that the PBT margin improves)
Net tangible assets +14% to £41.5m
It’s good to see the company itself highlighting its net tangible assets, although I must note that this stock now trades at an even larger premium (42%) against that number.
TIME’s lending activities continue to grow: lending book +11% to £209m. And it continues to perform well with deals in arrears falling to 5% of the lending book. This info was already provided in December.
The Outlook is a good place to look for new information:
Continued positive trading momentum throughout December 2024 gives significant confidence that full year trading will be at least in line with market expectations.
Estimates: in December, broker Cavendish was of the view that TIME had “a good chance” of outperforming their recently upgraded forecasts for FY May 2025.
So it’s quite possible that some investors were hoping for an upgrade today, but this has not yet materialised.
Forecasts at Cavendish remain unchanged today. They continue to suggest FY May 2025 PBT of £7.2m, and earnings per share of 5.9p.
Strategy: the company’s four-year strategy from June 2021 to May 2025 is “well on track” to meet its targets, so a new strategy is set out to guide the company until 2028.
The new strategic targets:
Lending book growth to over £300m from TIME’s existing funding lines.
Arrears and write-offs well controlled at broadly current levels
PBT margin % rising to the mid-twenties
ROE % increasing to the mid-teens
Graham’s view
The target for lending book growth does not strike me as excessively ambitious. It amounts to about 14.5% growth annually (compounded).
An improvement in ROE to the mid-teens would be an amazing improvement:
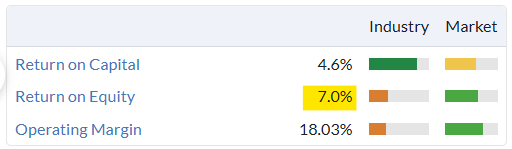
I calculate the ROE that was just earned in H1 as annualising to about 9%, higher than the full-year number shown in the table above.
Indeed, the general trend in ROE post-Covid has been positive:
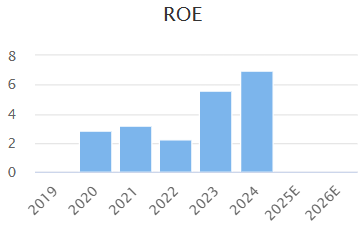
Pre-Covid, I think the company did earn an ROE in the mid-teens, so maybe it can do it again? It has a much bigger asset base now than it did before, and so I’d like to think that we will see both positive operational leverage and economies of scale.
Therefore, my overall view is that the company's 2028 targets are demanding but not unrealistic.
It must be said that this stock remains expensive both against assets and against earnings. Most lenders trade at cheaper earnings multiples than this:
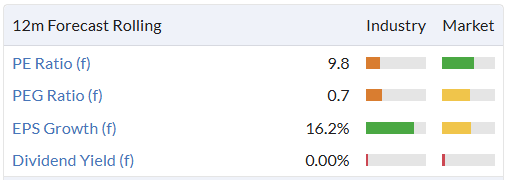
However, the growth and the prospects at TIME strike me as being better than average, with the most important factor being the potential for profit margins and ROE to grow. Let's hope that TIME can continue lending intelligently at higher volumes. I’m comfortable leaving my AMBER/GREEN stance unchanged.
Pets at Home (LON:PETS)
Up 4.5% to 219.8p (£1.01bn) - Q3 FY25 Trading Statement - Graham - AMBER
Roland looked at the most recent interim results for this company in November.
Today’s Q3 update leaves full-year guidance unchanged.
Key points for Q3:
Total revenue down 0.2%, like-for-like revenue down 1%
Retail revenue down 2.4%, down 2.8% like-for-like.
Vet revenue up 21.3%, up 19.9% like-for-like,
Compared to H1, retail revenue is doing a little worse, while vet revenue is doing a little better.
PETS notes that Q3 saw “a more challenging UK consumer backdrop with particularly weak footfall from October”.
But the outlook section has been viewed as positive by investors this morning:
We are on track to deliver modest growth in underlying PBT this year as set out at our H1 results. Against a still subdued consumer backdrop, we have maintained a disciplined gross margin performance, supported by strong Christmas seasonal sell through, and effectively managed our costs.
There is a slight (£4m) increase in non-underlying costs in the current year, but it’s positive news: PETS exiting its Northampton distribution centre faster than it expected to.
The company says it will finish the year with a “robust” balance sheet, even after returning £85m to shareholders in dividends and buybacks.
Estimates
It has been a poor year for EPS expectations at PETS:
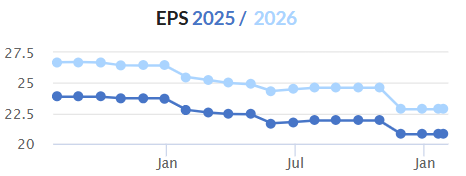
But perhaps it has bottomed out now? Today’s announcement does read confidently.
Zeus re-published their FY 2025 forecasts this month: adjusted EPS of 20.6p on a slight increase in group sales, and finishing the year with a net cash position.
Graham’s view
Like my co-writers previously, I’m not persuaded about the opportunity here.
Quantitatively, it looks interesting:
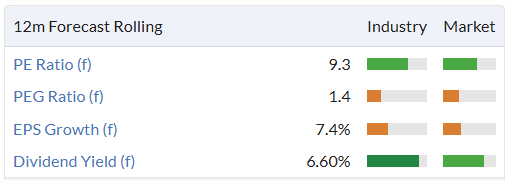
The StockRanks love it:
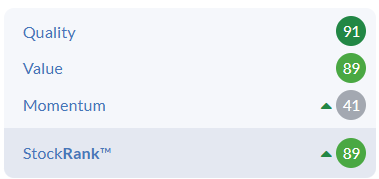
It even passes two bullish stock screens.
Qualitatively, I think it’s mostly the lack of growth and the sector (retail) that is putting me off. There is also the CMA investigation behind the scenes to worry about. This is just such a tricky sector, and throwing a regulatory problem into the mix doesn't help. As things stand, it seems to me that PETS is trading around fair value.
But who knows, maybe consumer spending on pets could pick up this year? It might deserve AMBER/GREEN, but I’ll leave it at AMBER for now.
A G Barr (LON:BAG)
Up 5.5% to 615p (£691m) - Trading Update - Graham - GREEN
I took this off my 2025 watchlist due to last year’s CEO appointment.
Fortunately today we have an in line update from this maker of IRN-BRU and other drinks.
Revenue for FY Jan 2025 will be up 5% to c. £420m, and the adjusted operating margin will improve from 12.3% to c. 13.5%.
It’s good to see that Boost (the energy drinks brand) is being successfully integrated. This acquisition caused a drag on the company’s metrics but they say they are prioritising “value over volume” for it, and that it has seen a step-up in profitability.
Net Cash: rising from £53.6m last year to finish this year at over £60m.
CEO comment:
"A.G. BARR is in line to deliver another year of strong top line growth, margin improvement and cash generation. These headline metrics highlight excellent progress towards our long-term financial goals. We have sustained brand momentum despite the well trailed wider market pressures, and continue to make good progress towards our margin target.
We are committed to consistent long-term revenue growth and have confidence in further margin improvement as per our previous guidance. Our expectations for 2025/26 are unchanged and in line with market expectations"
Expectations: continued momentum is anticipated through to FY January 2026:

Graham’s view
I’m still very fond of this one, even if I no longer have a place for it on my annual watchlist, so I’ll be staying GREEN on it today.
It remains a very quiet source of news, which is something I like - little controversy or drama, just good solid operating and financial performances.
Valuation hasn’t changed much:
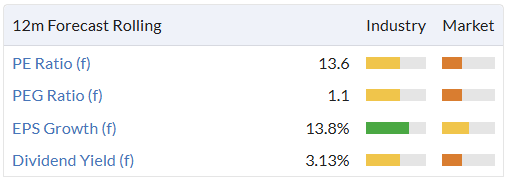
If you go back to pre-Covid performance, net profit margins were well in excess of 10%.
The main rate of corporation tax has increased since then and I acknowledge that this is an obstacle to getting back to those levels.
Investors might also want to think about the Deposit Return Scheme that is due to begin in October 2027.
But still, there is a nice trend of increasing profit margins at BAG - e.g. the officially adjusted operating profit margin that has improved from 12.5% to 13.4% and is expected to rise further to 14.5%.
Hopefully the net profit margin will not be too much further behind.
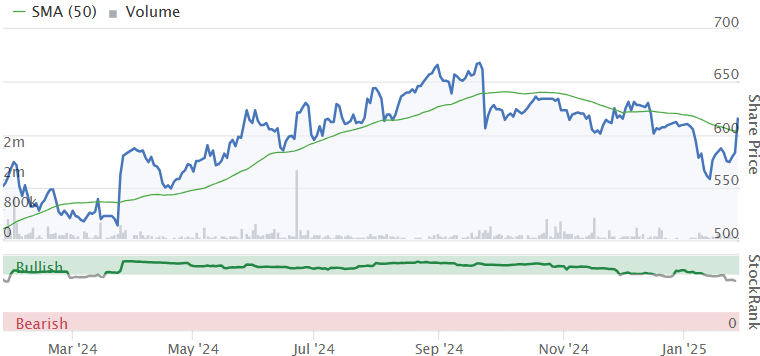
The chart might not seem too excited, or exciting, but these are pleasant times for BAG.
Roland's Section
Computacenter (LON:CCC)
Up 3.6% to 2,188p (£2.3bn) - Pre-Close Trading Update - Roland (I hold) - GREEN
At the time of publication, Roland has a long position in CCC.
This IT reseller and services group saw profits boom during the pandemic and again more recently as the AI rollout drove massive spending on data centres.
The picture has cooled slightly recently though, and as a shareholder I was keen to see whether today’s update would contain any further downgrade to expectations.
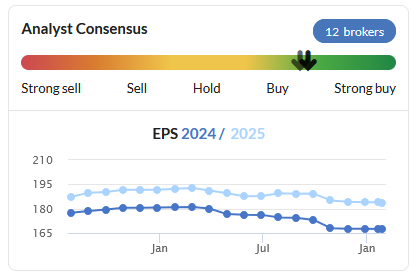
It looks like Computacenter has just about avoided another profit warning, but perhaps only just:
...we now expect adjusted profit before tax for 2024 to be at the low end of the range of analysts' forecasts.
Let’s take a look.
2024 trading summary: market conditions are said to have been more challenging last year. Total revenue for the year was broadly flat, up 0.5% in constant currency but down 2% reported. This highlights some forex headwinds which are also expected to have had a £7m adverse impact on 2024 pre-tax profit.
However, trading during the second half of the year does seem to have strengthened, reversing the slowdown seen in H1 (figures at constant currency):
H2 Technology Sourcing gross invoiced income +13% (H1: -14.8%)
H2 Services revenue +5% (H1: 0.6%)
The company ended the year with a record number of customers generating over £1m of gross profit per annum – this is a key metric used by the company.
While Computacenter was founded in the UK, Germany and North America now generate the largest contributions to profit.
Both markets are said to have delivered “strong performances” last year, but management admits that some Technology Sourcing projects in both the US and UK slipped from 2024 into early 2025.
2024 profit estimate: The company says H2 2024 was “Computacenter’s most profitable half-year in its history”. Adjusted operating profit for H2 is expected to be ahead of the equivalent figure for 2023, which I calculate as £153m.
Adding this to the group’s H1 24 figure of £81m gives me a 2024 adjusted operating profit estimate of at least £234m. At current levels, that gives the stock an earnings yield (EBIT/EV) of around 12% – potentially good value.
Computacenter expects to report a year-end net cash figure of £480m for 2024, excluding leases. This is ahead of the £344m figure reported for 2023, despite a £200m share buyback last year. While the year-end is a seasonal peak, this business is an excellent cash generator in my experience.
2025 outlook: the tone of the outlook comments is notably different for the three main geographic reporting regions:
UK: the increase in employer taxes from April are expected to have a £5m impact in 2025.
Europe: management remain “mindful” of uncertain macro and political conditions in some countries
North America: “we continue to be excited by the growth opportunities we see ahead”
Order intake during the second half of last year was said to be strong, driven by demand from North American customers:
...we exited 2024 in a robust position with a committed product order backlog at the end of December which is significantly ahead of our position in December 2023, as well as at the end of June 2024.
Computacenter says it expects to “make progress” in 2025, with earnings per share benefiting from this year’s £200m buyback – significant for a £2.2bn company.
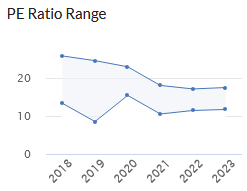
Consensus estimates ahead of today were for 2025 earnings of 184p per share, putting the stock on a forward P/E of 11. That’s at the lower end of the valuation range for recent years:
Roland’s view
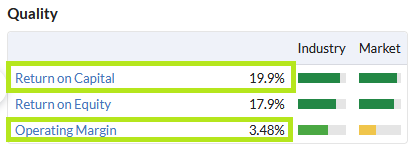
Computacenter is a high volume, low-margin business that generates high returns on capital through its scale and consequent ability to leverage large supplier relationships.
The reality is that there are only a limited number of customers who are large enough to be worth dealing with. In the UK and perhaps some key European markets, many of these are already Computacenter customers.
Naturally, many of the remaining growth opportunities for the group are in North America, which is also a newer market for the company.
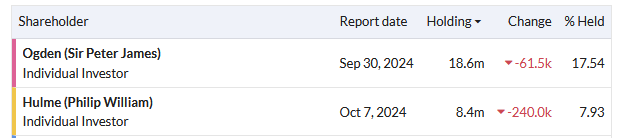
Indeed, I wonder sometimes whether a trade sale to a US business could be the eventual exit route for Computacenter’s two founders:
Today’s update appears to be no worse than expected and the outlook looks reassuring to me. The positive share price reaction this morning may also suggest that the market now believes Computacenter’s slowdown has bottomed out (as Ed discussed recently).
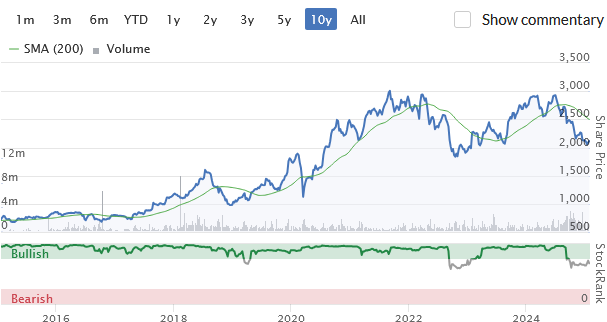
On balance I think Computacenter looks in good health and could offer decent value at current levels. GREEN.
Halfords (LON:HFD)
Up 19% to 150p (£328m) - Trading Update (FY25 profit upgrade) - Roland - AMBER
The full title of today’s update includes the magic phrase “upgrade to FY25 profit expectation”.
Updated profit guidance: today’s upgrade appears to be significant. Let’s take a look at what this retail and services group has to say.
In recent months we have seen an improvement in trading alongside continued progress on a number of key initiatives, including our pricing and promotion strategies and cost reduction measures. Cumulatively, these factors lead us to expect FY25 underlying profit before tax of £32m to £37m.
I can’t find any updated broker notes today. But November’s note from Zeus suggests that Halfords was previously expected to report an underlying pre-tax profit of £28.5m for the 2025 financial year.
Taking the mid-point of today’s update suggests the company’s new guidance represents an increase of 21% in profit expectations for the year, albeit adjusted. That’s a hefty upgrade.
I estimate this could convert into underlying earnings per share of c.12p, 26% above current consensus of 9.5p per share. That would leave the stock on a P/E of 12 after today’s upgrade, broadly unchanged.
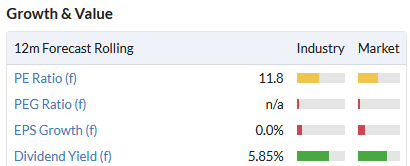
However, reading the remainder of the trading update has left me unsure whether these gains are coming mostly from cost savings, rather than any significant improvement in trading.
Q3 Trading Update: overall like-for-like sales growth during the company’s third quarter (Sept-Dec) was said to be “positive” in both Retail and Autocentres.
Sadly the company does not see fit to reveal the actual LFL figure. My guess is that it was not far above the flat result reported for H1 25.
Instead, management has cherry-picked some lower-level sales metrics to focus on recent highlights:
Strong Christmas gifting in cycling contributed to like-for-like retail sales growth of 13% in December.
In motoring, the Autocentres business enjoyed LFL growth of 10.3% in Q3 (Sept-Dec).
Colder weather has contributed to Motoring Product LFL sales growth of 5.5% in January.
The lack of disclosure of the full Q3 revenue result is disappointing, in my view.
However, it does look like Halfords is going to benefit from a significantly lower cost burden this year than previously expected:
Hedged FX rates expected to be “better than previously anticipated”
Freight costs headwinds expected to be below previous guidance of £4m-£7m
Costs “well managed”, savings on track to exceed £30m FY target
Again, no specific figures are provided for these cost benefits. But my feeling is that it’s not too hard to imagine them adding up to a few million, potentially accounting for most of today’s upgraded guidance.
FY25 outlook: the company says that recent months have seen “an improvement in trading” alongside progress on pricing, promotion strategies and cost savings.
These factors are said to have contributed to the increase in FY25 profit expectations, but it’s hard for us to get an idea of how much trading has contributed given the lack of disclosure on revenue.
FY26 outlook (Apr 25 - Mar 26): management notes “considerable uncertainty” about the UK consumer outlook. The company says that April’s National Insurance and minimum wage increase will add c.£23m to direct labour costs in FY26.
Halfords says it’s working on “possible mitigations” and makes the point that the effect of these changes on the demand environment is hard to predict – many people will benefit from the increase in minimum wage.
Consensus estimates on Stockopedia ahead of today’s update suggested FY26 earnings of 11.5p per share.
We will have to wait and see if these are updated after today’s update. Given the increased cost headwinds for FY26, I suspect forecasts will remain cautious for next year.
Roland’s view
Today’s update is clearly good news, at least as far as it goes. However, I remain sceptical given that the increase in employment costs pencilled in for FY26 could wipe out as much as 75% of today’s updated profit expectations.
More broadly, I’m not really a huge fan of this business. Halfords is exposed to lots of competitive pressures and has a relatively high fixed cost base.
The company has promised more information on how it plans to mitigate these cost increases with its FY25 results, which are normally published in June. For now, I’m inclined to remain neutral despite today’s upgrade. AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

91 comments
has the short section on Eurocell (LON:ECEL) disappeared for anyone else?
I can't see any short sections today.
Hi Ben/Rusty
We didn't make an announcement about this, but we are trying a format where the Summary table itself contains a synopsis of our views, and this replaces the Short Sections.
The table contains this re: Eurocell:
GREEN (Roland)
A solid balance sheet and modest valuation support a positive outlook for this building materials group.
Hope that's ok.
Thanks,
Graham
Thanks Graham, but l would prefer more coverage of small caps, seems to be only about 4 per day now. So more short sections would be welcome, especially on busy days.
We'll work on it, Rusty!
Not sure why Renold (LON:RNO) is up 12% today on no RNS, but nonethe less quite happy with the outcome as I hold (as do a few others on this board I believe). Maybe the shock of NVIDIA (NSQ:NVDA) share price drop has caused a few peeps to turn their gaze on UK small caps is as good a guess as any.
Anyone know why Renold (LON:RNO) shot up 12% about 3pm, share tip? Can't find anything about it. It has fallen back a bit now.
An interesting review of DeepSeek by a retired Microsft software engineer. It's good but obviously has its limitations requiring a lot less resources in computing power, vast data storage in the cloud and your own nuclear power station.
Last Friday I posted on my Portfolio Performance in 2024.
Rusty 2 responded on Serica Energy (LON:SQZ) my 2nd largest holding saying that "some of the SP fall was because it paid out large Dividends of 23p in the last 6 months.
Sparkler commented that "clearly the Market does not believe the numbers and must be betting that a Dividend cut is on the way"
Over the weekend I listened to a Presentation by the CEO and CFO of Serica Energy (LON:SQZ) on the Investor Meet Platform.
I strongly recommend any holders listen to the Presentation which is first class a view endorsed by Mark Simpson and sets out clearly that Q4 in 2024 presented many Operational Setbacks which have now been sorted. The Company anticipates 2025 will see Production up 16% with the highest Well Capacity in the Companys history.
Material FCF will generate strong returns to Shareholders with the Final Dividend being announced on 1st April. Serica Energy (LON:SQZ) pays the Final Div in July and the Interim Div in November.
With a Stock Value of 95. Quality at 95 and a Ranking at 91 Momentum will return. It looks very cheap to me. The Stock appears in Mark Simpsons excellent " More Midcap Madness" stocks which are too cheap today published on Stockopedia on Thursday 23rd Januay 2025.
I bought some at 125.6, roughly mid-sized position for me, on my radar to add more if opportunity arises (spare cash etc). Seems very undervalued, but so do many things listed in LON!
Hi portugull, sentiment is poor toward Serica Energy (LON:SQZ) isn't it, probably driven by Government policy on energy resembling a suicide note (this and the previous administration), leading investors to consider Serica uninvestible which in turn results in scepticism about future earnings and dividend maintainance. I agree last weeks presentation was excellent but one can't blame investors for being wary when the company itself quips that the UK policy on oil and gas extraction is probably the most hostile of any country in the world. I was most struck by the company's ambition, not to overpay in Norway, and to hoover up canny tax sheltering deals when everyone else is abandoning UK waters. Serica management are nothing if not brave. Anyway, it was first class, the Q&A in particular.
Computacenter CCC (I hold but halved my stake in October)
Thanks that is a very good write-up. You have made most of the pertinent points succinctly. Although in an entirely difference business, and with much more volatile earnings, I am struck by the similar valuation at Keller - a p/e of around x11, dividend yield at 3.5%, pretty strong RoCE etc - is this now a norm for quality mid-size UK companies?
But thanks, I feared no-one (else) would look at what has been one of my favourite long-term holdings in the UK.
As a fellow long-term Computacenter (LON:CCC) holder I was awaiting the statement this morning with some trepidation.
Usually when a trading update contains the dreaded phrase "parts of our larger current Technology Sourcing projects in the US and the UK have slipped into the early part of 2025" and then guides to the lower end of expectations you would expect some share price weakness.
On the other hand the share price had been weak going into this and the P/E is undemanding so there was also the potential for a relief rally.
In the end we got the latter, but it just reminded me how difficult it is to successfully trade around announcements even if you have foreknowledge of the following days headlines....
Here's that Crystal Ball paper again:
https://papers.ssrn.com/sol3/p...
CCC
I am also a holder and did not know what to make of the rns. The market liked it and the shares went up. Recently, We have had good discussions on what to do when the shares goes up or down on the trading updates or the result day. The answer is follow the market. Recent price actions in CBG, WJG, BRBY has confirmed this thesis. According to what we heard it keeps going in the same direction for some weeks. Thus , No fear if we have missed today's rise of CCC, HFD .
Let's see what happens in the rest of the week.
I'm afraid it is one of my boring core holdings - a well-run company that is never going to shoot the lights out, but will hopefully still be in business when I need the retirement income.
I've sat tight for the best part of a decade already, and I'm just going to sit tight and see what the rest of this decade brings.
Apple (NSQ:AAPL) have bought about 50% of their shares the last 10 years and have cancelled them. Their buyback programme is currently about $100B pa. Other things being equal the next 10 years they will buyback about 1/3 of their current shares and cancel them.
For clarification purposes!
All the best
Volatility in technology stocks is to be expected, and always has been according to a book I am reading on AI-(The Coming wave by Mustafa Suleyman). He claims the worst tech market crash was railroads in the C19th. 1873 was a major panic. Many investment trusts started out investing in railroads etc, then diversified. F&C Investment Trust (LON:FCIT) was the first. Just for readers interest.
I have the impression that the writers should stick to what they understand best. NVIDIA (NSQ:NVDA) trades at cheaper multiples now than it used to trade when it was $3!!
No need for the writers to analyse companies and markets that they are not familiar with. The AI boom is here to stay and it’s only in its infant stages of development. There are many companies in the AI play that seem to be overvalued at the moment but will continue to grow eg. Nebius NV (NSQ:NBIS).
Deepseek was in the spotlight two weeks ago and yesterday’s reaction was massively overdone. Politics are behind all this and by listening to Trump’s comments last night praising Deepseek’s work makes me certain that China tariffs will be avoided.
I do not own any NVIDIA (NSQ:NVDA) shares and the AI play is not only about NVIDIA (NSQ:NVDA). We will have many days like the one we had yesterday as we did with the internet boom. At the end of the day the US ALWAYS WINS. All the innovation and liquidity is over the pond and it was clear yesterday as the biggest company in the world lost 17% but the Dow Jones ended higher and the SP500 lost only 1.5%.
I bought Nebius NV (NSQ:NBIS) yesterday.
All the best
Contemplating whether to buy back in myself. Took profits on most of my US stuff after Trump's win put the icing on the cake on some lovely long term returns there, and moved to a simple equal weight index in Dec when prices were down, just chilling and waiting for opportunities. Maybe this is the moment...just quicker than I expected!
Hi boringchess
I post over at X @Yiannos11111 all transactions for the portfolio I manage plus some useful information on any unusual call options activity.
All the best
Very interesting Yiannos, my interest is piqued!
https://theinnovator.news/inte...
Regards,
Jon
Ouch.
I believe the the panic over NVDA and DeepSeek is overblown. I think it highly unlikely that the development of DeepSeek was as cheap as reported. I think that what we are being told about is the cost of the successful trial out of many unsuccessful ones that have not been reported. In other words. there is probably not that much difference between the development costs of DeepSeek and NVDA's development costs.
That doesn't mean I'm playing down the situation. DeepSeek is still a threat to NVDA, but when the market settles down, I think NVDA shares will recover, The AI market is still very new and has still a long way to go.
If you like the update from Time Finance (LON:TIME) today you can meet the management team at the next Yellowstone Advisory Private Investor Evening on 12 February at 5.30pm.
Management teams from Time Finance (LON:TIME), Amcomri (LON:AMCO) Kelso group (LON:KLSO) and XP Factory (LON:XPF) will be presenting and there will be plenty of time after the presentations for informal discussions with the management teams over drinks and canapes following the formal presentations.
The event starts at 5.30pm in EC1
Register here
Who can validate the chinese information . This has CCP involved in the development
The chinese ai firm is owned by a hedge fund. There was targeting campaign on social media and news outlets. Then a massive sell off of US markets.
Someone or a business shorting the market would have made a fortune.
#vst was doen a massive 28% and as a energy firm the US will still need power. Nancy pelosi bought millions. So lets see
.
Graham
But the overvaluation was visible for a long time in advance.
Ref Nvidia and bubbles
I get the notion that there could perhaps be a bubble and overvaluations here but could this not perhaps simply be lazy talk?
Looking at next year eps estimates for nvidia i make it a p/e of 26 and growth in earnings 50% pa
So how is this in any way an obvious bubbble? should we be ignoring analyst predictions and predume the whole sector is going to come crashing down?
I am alwasy wary of stuff like this - look at many stock sthat got an unatural boost over covid and you can se that bubbles might very well be at work.
Looking at AI i think its very much front and centre of everything we will do going forward and new new fangled AI has only been about in its working form for a couple of years.
seems odd to presume that what might be the biggest growth area for many years to come musat be soem sort of bubble that cant sustain curent valuations.
I kinda got it when google/amazon/facebook were values in p/ee multiples of hunderds and making litttle money - i was wrong to be wary now. But i have to admit for comnpany that is front and centre of everything ai on potential p/e of 26 and growth of 50% that looks just pretty damn cheap unless there is full collapse in sales. It may be a bubble but i for one am not predicting that is the case.
The bubble would be in the sales... and over investment...in this case, not the PE. That would be the point. No view on my part.
Hi rmillaree, re: NVDA,
While I do lean towards the view that NVDA is still very expensive, my statement that there's an AI bubble is based on general behaviour in the market, not just on the price of one stock. Too many companies are claiming to use AI or ML purely because they know that investors will put a higher value on them if they do that. Too many companies have AI in their name. The Nasdaq (including AAPL, MSFT, NVDA) trades above its average PER and is currently at 31x trailing earnings. Money has poured into the US and its tech sector because it's convenient to invest there and because of tech-led momentum, at the expense of lowly-valued markets such as the UK.
I'm not saying that this is like 1999 but I am saying that too many investors think that AI leads to easy riches. This belief has led to strange valuations and the strange market behaviour we've seen in recent years.
When investors start think that investing is very easy, they are invariably disappointed.
Graham
Hi Graham,
And when investors think that investing is rocket science then they get more disappointment. Liquidity is driving the US and it will for many years to come as all the money in the world are heading their way.
US Interest rates are seem to be falling towards 4% so a multiple of 25 for growth listed companies is fair. Only black swan events will make these multiples lower than 20!
I agree many companies with the AI in them will fail and will be zero but this is always the case with most startups. Who cares about them anyway?
All the best
+1
According to Peter Zeihan, if you look at US demographics and geopolitical trends he sees nothing changing in terms of money flowing in to the US stockmarket from within the us until 2031-33.
Acc to paul krugman if (big if) his interpretation of trump policies are carried out deficits will rise and the usd will rise (!).
Acc to me over a long time horizon it has been unwise to bet against the us for the last 80 years or so.
all i read points to the US being a combination of Switzerland, Germany and somewhere slightly mad for the next few years.
So intend to hold my nose and get a smaller cap tracker
Ray Dalio in today's FT does think it's similar the dot.com Graham, he also thinks many FOMO investors will lose as they did then.
Isn't Ray always predicting doom ?
Yes he is!
Mr, doom and gloom is his nickname.
All the best
It doesn't even need to be a full collapse in sales. It just needs to be a compression in margin as new competitors find their way across the "moat" more rapidly than anticipated. Valuation ratios are not just about the magnitude of next year's earnings - they presume a degree of persistence in the earnings/cashflow yield as well.
NVIDIA (NSQ:NVDA) makes 90%+ gross margins on some products at the moment, and I'm not sure the average investor appreciates that there are alternatives lurking out there which may become viable competitors quite quickly.
This article is well worth a read:
https://youtubetranscriptoptim...
I'm not going to give any opinion on whether he is right or wrong, but he isn't saying anything that I immediately want to challenge.
Pets at Home (LON:PETS)
One snippet caught my eye in today's update.
From what I can see the Recurring Subscription Revenue as a percentage of Consumer Revenue was 13.4% in Q3.
This equated to £62.3m out of the £468m of Consumer Revenue in the period.
In Q3 last year these figures were 10.2%, £46.8m and £457.5m respectively.
This recurring revenue % figure has been rising since it was first disclosed in FY22 and when it was only 6% of Consumer Revenues.
It's a nice trend that hopefully highlights a solid foundation for the business.
A
re Nuclear, Datacentres, AI, Baseload and Energy.....
Global annual energy demand is 136,000 Gigawatts. AI in theory before yesterday, according to an Amazon statement, would double global energy demand in a decade. Clearly we do not have the resources to cope with such demand. It costs at least $1m, a Mega Watt to build energy. Thats a billion in Giga Watt ..... to 2x global energy costs more than the entire mkt cap of all US equities ( current c$55 trillion). ie. was never going to happen in a short space of time. Yesterday's announcement was very positive for all.... that we don't have this perilous new demand for energy that we have no hope of meeting. It does not reduce our demand for energy though, this is always growing, despite a green agenda pushing investment into less reliable sources. The nuclear story is very much intact...as we build very reliable baseload and absorb a high cost that will hopefully fall in time. Yesterday's announcement suggests we should continue to back human ingenuity to solve the world's problems....I feel quite positive about it.
"Yesterday's announcement was very positive for all.... that we don't have this perilous new demand for energy that we have no hope of meeting."
One announcement and the worlds 10year energy problems are resolved?
A huge number of moving parts in trying to forecast the worlds energy requirements over the next decade. Global conflict might be one of them.
I certainly did not intend to suggest 10 year energy problems are solved...quite the opposite in fact. It would appear that a source of stress receded yesterday however... which I take positively.
"It would appear that a source of stress receded yesterday however... which I take positively."
Which would be positive - if it was the case. What announcement are we talking about? Are we at cross purposes?
If true, Deepseek requires a fraction of the computing power, and therefore data centre capacity ... and therefore the latter no longer set to cause huge stress on energy infrastructure.
I think we will need a lot more information than this one announcement to be confident that this is the case.
For me, there is simply too little information on Deepseek to draw any conclusions whatsoever. One fact that is already being questioned is the very low cost of development (circa $6million). If this looks questionable then the other statements perhaps shouldn't be taken at face value.
I have deleted another post on the thread to prevent the thread becoming cluttered with the same discussion.
It is early days for deepseek, it has one major downside its chinese and their customer data will be released to the Chineses government. Can't imagine this will be popular with US companies or US government!
With all the AI, data centres and electric vehicles the governments and big business are suggesting we need we will need far more power than we have - not sure where they expect to get so much additional power from. Maybe a good time to invest in energy providers!
Money flowing back into Liontrust Asset Management (LON:LIO) yielding 16% and Impax Asset Management (LON:IPX) yielding 13% ?
Hi what makes you say that ?
Tech rout probably seeing flows into managed funds?
"Money flowing back in". Do you mean the SP has started to show signs of a recovery with the chart beginning to look attractive or do you mean that Liontrust Asset Management (LON:LIO) have reported client inflows or at least a reduction in the rate of outflow?
I bought back in yesterday off the back of £1M director buys backed by the comments by Cockney Rebel that with the yield the risk reward was looking attractive.
I simply asked a question.
"It’s fascinating how narratives can change so suddenly."
I hear what you're saying on that!
I'm not really a fan of the whole Ai thing, although I think my smartphone being able to do voice recognition is great.
I don't really know what these large companies are doing with AI anyway, I suspect it's mostly a ban wagon. Obviously NVDA is an obvious beneficiary. Apple says "Built into your iPhone, iPad and Mac to help you write, express yourself and get things done effortlessly." I expect it's the same thing for MSFT.
Well, isn't the recent news a good thing? If Apple can now provide its tech more cheaply, for example, isn't this beneficial for Apple?
My own thought is that just as AI has been overblown in general, the news about DeepSink is likely overblown too. It will undoubtedly take a long time for it to feed through, and the effects are likely to be unpredictable in any case.
It will be interesting to see how share prices progress over the coming year. I doubt much fundamentally will change over that period. Still, there's a lot of froth in the US markets which could be knocked off.
I noticed that Personal group (LON:PGH) has very minimal write ups in Stockopedia. I wondered if you would care to provide an assessment as it has a SR of 85 and qualifies as a super stock.
On the topic of index concentration, I've occasionally made use of the following ETF to park my spare US$ while retaining some market exposure:
SPDR S&P 400 US Mid Cap UCITS ETF Acc (LON:SPY4)
It puts you into the S&P 400 mid cap index (which has no overlap with the S&P 500). You should expect significant performance divergence from the S&P 500, but it is a useful place to park money while avoiding exposure to the big names.
Just mind the Excess Reportable Income if held outside an ISA - it is a reporting fund.
I made the mistake of buying an ETF dominated in dollars....the spread was minimal but my provider fleeced me on the exchange rate. I buy sterling denominated ETFs now.
Platform exchange rates
ii has one of the highest at 1.5% . Interactive brokers ( mainly for professional) and Trading 212 have the lowest at 0.2%.
ii allows you to keep multiple currencies (except for ISA) and you avoid frequent exchange costs.
Just a small correction, fx fee is 0.15% on Trading 212 on both ISA and invest accounts. eg. https://www.trading212.com/ter...
interactive investor is one of the platforms I use.
Yes, you take a hit on the initial FX conversion relative to some other platforms (e.g. AJ Bell is tiered down from 0.75% for first 10k), but if you then keep your US$ segregated, settle trades in US$ and accrue dividends in US$ it is reasonably efficient.
I believe ii do accept payments in from foreign currency accounts,
Unlike AJ Bell, ii don't apply FX fees to the receipt of foreign currency dividends.
Note: Keeping your US$ segregated is not possible with ISA accounts.
Many thanks for this Yadi.... I have been suffering under HL's horrific exchange rates since I started buying US Stocks in the last year or so, but will definitely be opening next year's ISA with an alternative provider come April 6th....do you ( or anyone else please ) have any colour re who is best out of Interactive brokers or Trading 212 ? Obviously you can have an FX fee, but you also get charged a spread from mid... with HL its roughly 100 pips on GBP / USD ... so with Cable market mid of 1.2430 currently, you get filled at about 1.2330 on the way in and 1.2530 on the way out ( ISA cant hold Usd balances )... do you have a rough feel for how far from mid the execution happens please ?
Many thanks in advance
Hi Cancun,
I know what you mean.
Best for me is interactive brokers and they only charge a very small fee (£3) and a spread of for example : Bid 1.24651/Ask 1.24652. Also the spread on US stocks is one of the best in the market.
Not recommended for UK small caps though.
All the best
Brilliant Yiannos... exactly what I was looking for... many thanks indeed....
Second vote for IBKR, though yiannos is quite a vote already. They are really targeted at trading investors and they offer a lot of features. They hold DTC code which makes theme useful for trading in RSU and us Espp type programs as well.
Their piece rate for share sales are super competitive.
Brilliant... Many thanks as well Alastair... certainly the FX rates are ridiculously good....
Just be aware they don't offer a SIPP (which is really only a major problem if you like to use "Bed & SIPP" to transfer holdings across)
I agree about HL fees on US shares. I use IG group (LON:IGG) they only charge a forex fee of 0.5%, no other fees, great for buying smaller amounts. On UK shares it is £3 per transaction, so much cheaper than HL. They are not much good for ETFs and funds, though. Prices on everything l have checked has been the same or lower than HL. Spreads on most US shares is tiny.
Excellent update from Microlise (LON:SAAS)
Strong International Growth, Robust Recurring Revenue, and Resilient Performance Despite Challenges in FY24
Microlise Group plc (AIM: SAAS), a leading provider of transport management software to fleet operators, provides an update on trading for the year ending 31 December 2024 ("FY24"). The Group expects to publish its full year results in late March.
Highlights
· Recurring revenue growth of 21.4% to £54.7m, 10.8% organic growth1
· ARR growth of 18.8% to £56.6m, c.9.4% organic growth1
· Group revenue of £81.0m, growth of 12.9%, 5.9% organic growth1
· Adjusted EBITDA2 of £11.3m, representing margins of 14%
· Cash conversion above 89% and net cash of £11.4m
Cyber incident insurance claim underway to recoup costs. More importantly no existing customers were lost and 51 new added since.
https://newsfile.refinitiv.com...
Possible to show the 200 SMA on the graphs?
Possible to show both 50 SMA and 200 SMA on same graph??
Thankyou .KBR
You'll find the answer here https://www.stockopedia.com/le...
Thankyou very much JimMcLad.
KBR.
Be good to get thoughts on Pets at Home (LON:PETS) at home if you have a chance looks good value at these levels, but todays update is far from up beat so could be worth holding fire as may get cheaper yet ?
RE: Pets at Home (LON:PETS)
Hi TP
We have the CMA vets review later this year which is weighing on sentiment, although it's hard to see how PETS will be badly impacted by it (and that was before the Chair of the CMA got kicked out for not being sufficiently pro-growth). Meanwhile the Covid cohort of pets are still young and healthy and people are feeling the pinch financially.
I don't think any of this jeopordises the story for PETS in the longer term. My main concern is a low ball bid taking them out at these levels (or even 50% above).
timarr
Thanks Tim it came up on my garp screen agree re the government coming very slowly round to the pro growth need I work in wealth management and its over regulated to death on such low level issues yet the crooks doing the really bad stuff are ignored time and again.
PETS is a share I bought late last year. I'm a little underwater on it so far, but it's early days.
I think things depends if you take a shorter or a longer term view. I thinks it's a good quality company that has a good position in the market, and should do OK in the long term. It's trading on a PE of 9, PFCF of 6 and an EV/EBITDA of 5.5. Debt position is OK, too.
That's cheap for a reasonably stable business. We're not expecting profits to fall off a cliff next year.
Revenue growth a bit sluggish for what is meant to be a non-cyclical business (well below the supermarkets, for instance). I understand that PE backed Jollyes is expanding quite aggressively so wondering if this could also be a threat?
Personal group (LON:PGH)
EV/EBITDA of 2.7
90% recurring revenues
Top line growing 14%+
Dividend 7.5% and growing
Ahead of expectations EBITDA and bullish outlook for 2025, DYOR but I think this is an absolute cracker.
Given Personal group (LON:PGH)'s strong results the lack of enthusiasm in the Canaccord update seems strange...maybe they need to pay more fees..
I will just add that it was reassuring that the FTSE 100 at least hardly moved yesterday despite NASdaq carnage, so to speak. The nuclear and Uranium stocks were caught in the falls for obvious reasons. Data centre investment and energy requirements could well be curtailed. Fair enough but I think it's positive to let hot money exit and the story was good enough before the AI Data centre frenzy. Yellow Cake (LON:YCA)(I Hold) have an update out with nothing to report apart from business as usual. The Uranium market remains in deficit and I would expect the price to recover quickly, this weakness may even be the catalyst for Utilities to step back in to spot markets.
Agreed. Topped up Yellow Cake (LON:YCA)
Andre Liebenberg, CEO of Yellow Cake, said:
"We remain confident in the long outlook for the uranium price. We see current market volatility as presenting compelling new entry points for investors. We expect to see uranium term contracting increase in 2025, especially among nuclear utilities in the US and Asia/Pacific region, while producers look to meet increased demand by developing higher cost greenfield projects. At the same time, we believe this year will highlight the fragility of the supply side in the face of this growing demand. These factors are expected to place upward pressure on the uranium price."
https://www.investegate.co.uk/...
I have been in here longterm since '21 and also trading it as it is sentiment driven. One thing of interest is the short position and keeping an eye on that to get a feel for entry https://shorttracker.co.uk/com...
How do you like to use this?
I just watch for shorts closing really and am mindful if they are increasing . Burberry was heavily shorted and they started closing and that was the bottom. Not guaranteed but as with all data it helps make a picture that might be worth considering
Interesting, the other way of looking at it I guess could be that when the shorts have piled in then maybe we've reached peak negative sentiment and its due a squeeze to liquidate them all, heh
Geiger Counter (LON:GCL) are down over 10%.
This is an obvious follow through from falls in Cameco and Nexgen ...all indicative of the hit to sentiment and probably a small stop loss mageddon yesterday ( margin accounts triggering stops inducing forced selling ) .... IMO will all blow over fairly quickly but then it's just my opinion. That's what makes a market.
Yes, l went to buy some more Geiger Counter (LON:GCL) but l'm not allowed to now on my platform.
This,Geiger Counter (LON:GCL) is being complicated by Saba taking up an increasing stake. Over 12% now, on their mission to eat up various investment trusts, up from 5% in October. Sold my shares last week untill Saba issues become clearer.
The Deep Seek thing yesterday spooked the energy market. I guess we'll have to see how this plays out over the next few days
Hi. RDH. Yellow Cake (LON:YCA) I’ve been patiently waiting for an under £5 offer and today I took it.
Why? Well I’m buying uranium assets worth £1 for 56p , if we take there nav at 1.8 billion and enterprise value at a billion.
where will uranium go? Who knows! however the consensus is we have a shortage and slow uptake to increased supply…. Sounds like the perfect setup for an investment. Low downside , exponential upside, buying cheap.
The case for nuclear energy is a compelling one regardless of the rise of data centres. I have held Centrus Energy (ASQ:LEU) for a few years in the belief that green energy cannot meet the need to replace fossil fuels for some considerable time.
Mild profit warning from Henry Boot (LON:BOOT) this morning?
Good morning, team. Would you kindly do a quick review of Eurocel (ECEL) if you have time?
Good results from Time Finance (LON:TIME) today. Should go up 10% or more today, and then drift back down about10% over the next few weeks......
Mixed bag of reports today:
It'll be interesting to see how the first two go today - their struggles have been well documented, so price weakness from here would be surprising, but possibly an opportunity.
timarr