Daily Stock Market Report (Tue 28th Oct 2025) - RWS, AAF, REAT, IGR

Good morning!
Thanks to Roland for taking care of the report today! See you tomorrow.
Spreadsheet accompanying this report: link (last updated to: 15th October).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£195bn | SR66) | Approved for the treatment of symptomatic, inoperable plexiform neurofibromas (PN) in adults with NF1. | ||
HSBC Holdings (LON:HSBA) (£172bn | SR84) | Adj PBT up 3% to $9.1bn, w/ adj RoTE of 16.4%. Reported PBT down 14% due mainly to $1.1bn Madoff provision (see y’day). | ||
GSK (LON:GSK) (£66.6m | SR89) | Has delivered “encouraging early clinical data” showing potential for treatment of small-cell lung cancer. | ||
Anglo American (LON:AAL) (£33.4bn | SR65) | Copper and Iron Ore are tracking to 2025 guidance. Steelmaking Coal is progressing towards a return to normal, sale process will be restarted in coming months. | ||
Airtel Africa (LON:AAF) (£8.4bn | SR88) | Rev +25.8%, op profit +35.9% to $959m. Customer base +11% as smartphone penetration increased to 46.8%. | AMBER/GREEN (Roland) Last year’s currency ructions have faded away and I’m left admiring strong, structural growth in both mobile usage and money services. The group’s profitability is significantly stronger than BT/Vodafone and cash generation is also good, underpinning upgraded capex guidance. There are some risks here – concentrated ownership, volatile currencies/economies and leverage. But momentum has been strong and earnings have been upgraded steadily this year. The valuation isn’t outrageous. I am inclined to agree with the StockRanks and take a moderately positive view, with the caveat that I would not view this business as a buy-and-forget stock. | |
Yellow Cake (LON:YCA) (£1.30bn | SR67) | Completed £130m placing, purchased further $100m of uranium. NAVps +5% to 606p. | ||
C&C (LON:CCR) (£504m | SR64) | Rev -4%, adj PBT +12% to €32.1m. FY26 outlook in line with exps. Tennent’s and Bulmers gained share. | ||
Next 15 (LON:NFG) (£395m | SR81) | These US-based capital markets advisory businesses have been sold to their founders/mgt teams. NFG retains a minority interest. | ||
Auction Technology (LON:ATG) (£376m | SR54) | FY25 to be in line with revised exps, with organic H2 rev +4% and EBITDA margin 42-43%. FY26 trading in line. | ||
RWS Holdings (LON:RWS) (£348m | SR93) | FY rev broadly in line with prior year, adj PBT to be at lower end of guidance, c.£60m. Significant H2 growth vs H1 (£18.0m). | AMBER/GREEN (Roland - I hold) Today’s year-end update shows adjusted profits at the bottom end of guidance, so the statutory figures are likely to be lower still. However, I think the group is moving in the right direction and am encouraged by the strong profit performance in H2 versus H1. New medium-term guidance will be provided with the FY25 results in December. I’m happy to remain patient ahead of that date as I continue to believe the business has a significant opportunity to be an AI winner – and is cheap enough to offer genuine value. | |
Idox (LON:IDOX) (£260m | SR54) | 71.5p, 26.8% premium to yesterday’s close. The proposed buyer is a US-based firm that already owns 12% of IDOX. Irrevocable undertakings to support the deal from 23% of shares, plus the buyer’s existing stake. | PINK | |
B.P. Marsh & Partners (LON:BPM) (£239m | SR92) | Sells its 28% stake for CAD $51.9m (£27.8m) net of transaction costs. 21% uplift to carrying value. Defcon is also payable in 2026. | ||
Evoke (LON:EVOK) (£187m | SR68) | Q3 revenue +5% (4% CC). Successful refinancing of 2027 EUR fixed rate notes. Reiterates FY25 adj. EBITDA margin guidance, says adj. EBITDA to be ahead of market expectations. | (Graham holds) | |
IG Design (LON:IGR) (£55m | SR40) |
Confidence in full-year guidance (full-year revenues $270-280m). H1 revenue c. 13% lower, adj. op profit c. $5.6 million. CEO search underway.
| AMBER (Roland) [no section below] Today’s update seems fairly neutral to me. It’s encouraging that full-year revenue remains in line with guidance, but it’s worth remembering that full-year revenue is expected to be c.13% lower than the prior year on a pro forma basis. This is due to headwinds reported earlier this year, such as softer UK demand and pricing pressure in Europe. Operating margin guidance for the current year is unchanged at 3-4% today, but that equates to an adjusted operating profit figure somewhere between $8.2m and $11.0m based on consensus revenue estimates of $274m. That’s a fairly wide range of potential outcomes. It will be interesting to see if IG Design can regain its historic success and market share, now that it has divested its US business. The valuation seems fair to me and I will be keen to review the business again after this year’s peak festive trading period. At this stage, I don’t have a strong view either way, so will retain our neutral view. | |
Ultimate Products (LON:ULTP) (£52m | SR70) | Results in line with expectations. Revs -3%, adj. EBITDA -31%. Current trading in line. “External headwinds are likely to persist in the short-term.” | ||
Colefax (LON:CFX) (£46m | SR94) | £6.1m tender offer after 11.7% of shares were validly tendered. The company offered to buy up to 15% of shares at 880p. | ||
React (LON:REAT) (£11m | SR48) | FY25 results ahead of previously revised market expectations. Revs £25m (exps: £24.5m), adj. EBITDA ≥ £3m (exps: £2.75m). | AMBER/RED (Roland) Today’s upgrade is positive in itself, but forecasts remain a long way below the levels expected before May’s profit warning. In addition, comparing today’s FY numbers with the financial stats given for Aquaflow prior to its acquisition suggests to me that performance of Aquaflow and/or the remaining business may have been disappointing this year. My sceptical view on this business remains unchanged and I think the low P/E rating is probably deserved. I’m going to maintain my cautious view ahead of January’s FY25 results. |
Roland's Section
RWS Holdings (LON:RWS)
Down 7% at 88p (£324m) - Trading Statement - Roland - AMBER/GREEN
(At the time of publication, Roland has a long position in RWS.)
Mark flagged up this week’s year-end update from translation and localisation specialist RWS in The Week Ahead, reiterating his view that established market leaders like RWS have the opportunity to become leaders in the implementation of AI, rather than victims.
This reflects my view too and I also hold the shares – albeit I bought into the recovery story far too soon and my position is somewhat underwater.
AIM-listed RWS is currently in the early stages of a turnaround under newish CEO Ben Faes. Today’s update covers the year ended 30 September and is in line with guidance provided with the half-year results – although only just:
FY25 reported revenue expected to be £690m, -4% vs FY24 (Stocko consensus £715m)
FY25 adjusted pre-tax profit to be c.£60m (previous guidance £60-70m)
I’m not surprised the share price has fallen, especially as this is an adjusted figure – RWS has a recent track record of fairly heavy adjustments, in my view, meaning that this figure could be masking a much weaker statutory performance.
There is some good news, though. Profitability appears to have improved significantly in H2, with today’s guidance implying a strong H2 profit weighting:
H1 adj PBT: £18m
H2 implied adj PBT: c.£42m
Net debt was also stable at £26m, versus an H1 figure of £27m and RWS says today it was able to refinance recently, extending its existing credit facility from $220m to $285m.
Divisional trading: a brief summary has been provided today suggesting mixed trading across the business, but with continued growth in AI-related activities:
Language Services: OCC (organic constant currency) revenue growth, “strong progress in TrainAI”
Language & Content Technology and IP Services: “flat compared with last year on an OCC basis”
Regulated Industries: revenue fell on an OCC basis, “driven primarily by reduced activity in our linguistic validation business”
Updated strategy: the group moved to a new operating structure on 1 October:
This structure streamlines how we sell, integrates our product and technology teams and organises our business into three segments: Generate, Transform and Protect.
CEO Faes says changes within the organisation are having an effect, citing “clearer focus” for sales and “greater collaboration” for the company’s technology teams. The level of post-acquisition integration and technical debt (old software that needs updating) that need addressing in this business is a long-standing concern for me.
RWS spent £41m on software in FY24 while also recording an amortisation charge (primarily software) of £55m. These are big numbers relative to profit, so I’ll be interested to learn more about capex plans in the full-year results.
Outlook: no update on FY26 trading or guidance was provided today – this will be provided with the FY25 results in December.
We intend to provide medium-term financial guidance and new performance targets when we release our FY25 results.
I don’t have access to any broker notes today, but my working assumption is that consensus forecasts will remain broadly unchanged following today’s update, suggesting earnings of 12.4p per share.
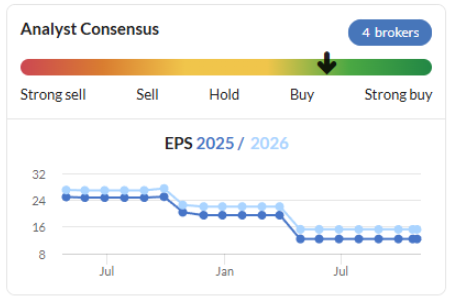
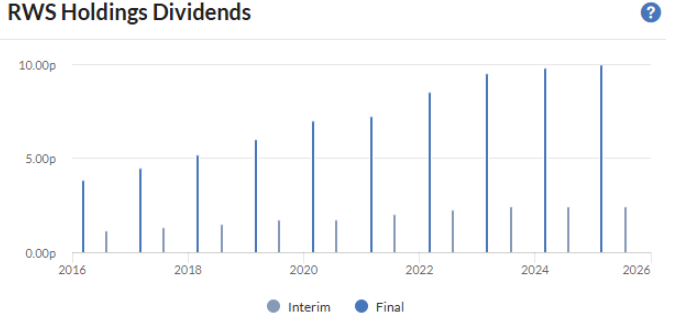
That puts RWS on a P/E of 7, with a potential 14% dividend yield – unless the payout is cut. I can see some logic in this, but equally I imagine that 24% shareholder Andrew Brode may be keen to see the company’s dividend record maintained:
Roland’s view
Today’s results are at the bottom end of profit guidance, but I am encouraged by the increase in profit in H2.
My view on the likely impact of AI remains unchanged – for large-scale commercial applications in areas such as media, travel and consumer goods, I think enterprise customers will be willing to pay for specialist service providers who can provide guaranteed quality, tailored models and content management tools.
RWS should be in a prime position to provide this service, with strong market share and existing relationships.
Of course, I am naturally biased as a shareholder and may be wrong. RWS could turn out to be an obsolete business that can’t change quickly enough to protect itself from smaller, upcoming AI-led operators. The market remains unconvinced:
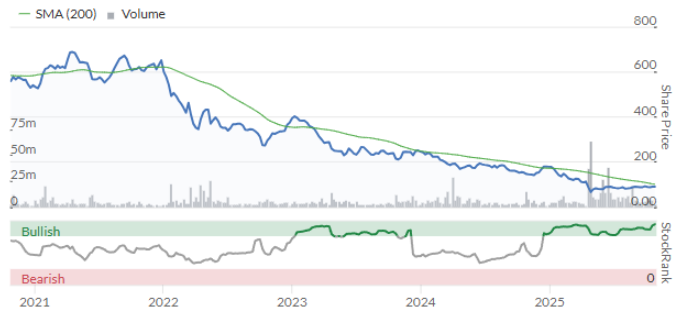
For now, I am going to leave my AMBER/GREEN view unchanged on the basis that I believe the shares are cheap enough at present to be likely to offer value – after all, this is a business with £700m annual revenue and I believe it has a top-two market share globally.
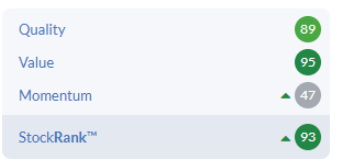
My view is also reflected in the stock’s Contrarian styling and high QV StockRank:
Airtel Africa (LON:AAF)
Up 6% at 246p (£9.0bn) - Half-Year Report - Roland - AMBER/GREEN
The big UK telecoms stocks have a well-deserved reputation for minimal growth and under-pressure profitability. The underlying reason for this is obvious enough – they operate in saturated, competitive and very mature markets.
The exception to this is Vodafone’s African business, which includes both mobile networks and a mobile money business. It’s profitable, fast-growing and a good business, in my view – but it’s subsumed within Vodafone’s wider business, so shareholders’ exposure to this growth is heavily diluted.
For investors who want to invest directly in a dedicated portfolio of African assets while staying within the UK market, Airtel Africa provides an interesting alternative:
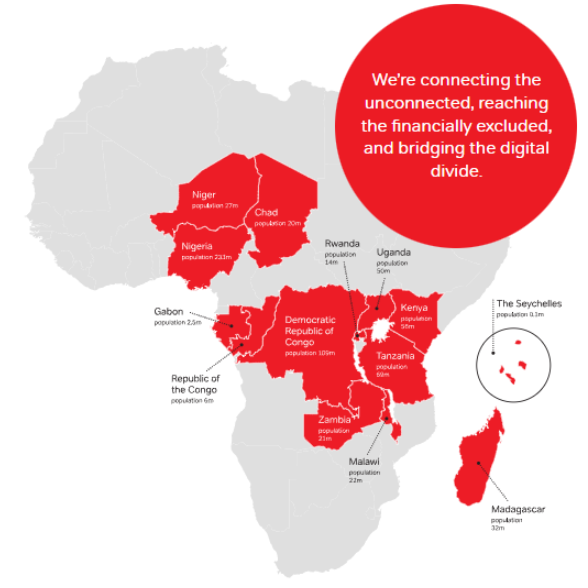
Source: Airtel Africa website
We haven’t covered this stock much before, but perhaps we should have done.
Airtel Africa’s shares have three-bagged since listing in 2019. The firm recently graduated to the FTSE 100:
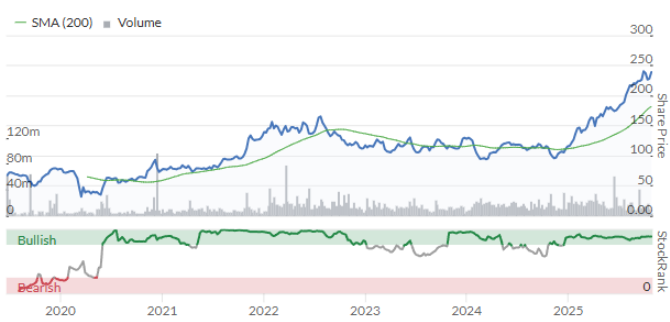
Today’s half-year results emphasise the opportunity here. Many people in the company’s operating markets don’t yet have a smartphone and may not have access to the internet or banking services.
The rapid pace of adoption of these services is driving enviable growth and supporting much stronger profitability than the UK’s legacy operators can achieve:
Half-year results summary: last year’s figures were affected by some big currency movements (mainly the devaluation of the Nigerian Naira). Happily, today’s are relatively free of exchange rate effects and show impressive growth. These results cover the six months to 30 September 2025:
Revenue up 25.8% to $2,982m
Operating profit up 35.9% to $959m
Operating margin: 32.2% (HY25: 29.8%)
Adjusted earnings up 69.9% to 8.3 cents per share
These financial headlines are underpinned by some very strong operational growth metrics. The group’s total customer base rose by 11% to 173.8m, while the number of data customers climbed 18% to 78m. Data is now the largest single driver of revenue, outpacing voice for the first time.
Banking growth also remained strong. The mobile money customer base rose by 20% to almost 50m, while the annualised total processed value was 35% higher, at nearly $200bn.
The company says smartphone penetration in its markets rose by 3.8% to 46.8%, highlighting the pace of growth and the remaining opportunity – this business could get a lot bigger yet.
To accommodate and maintain capacity for further growth, Airtel Africa is investing quite heavily in its network:
Our commitment to delivering a great customer experience is supported by ongoing investment in our network with the rollout of over 2,350 new sites to over 38,300 sites and an expansion of our fibre network by approx. 4,000 kms to over 81,000 kms. This investment continues to drive increased data capacity across the region as overall population coverage reached 81.5% - an increase of 0.7% from a year ago, with 98.5% of sites being 4G enabled.
Capex totalled $318m in H1 and guidance for the full year has now been increased to $875-900m (FY24: $670m) as the company aims to “accelerate our ability to capitalise on the significant opportunity” in its markets.
Balance sheet and cash flow: Net debt rose by around $350m to $5.5bn in H1, but leverage dropped from 2.3x to 2.1x thanks to the increase in EBITDA.
The localisation of the group’s debt profile also continued. This long-running process has been designed to reduce the group’s exposure to currency volatility and is now nearing completion. The company says around 95% of its operating company debt is now in local currency, up from 89% a year ago.
Cash generation also seems good. My sums suggest underlying free cash flow of around $500m, demonstrating good conversion from H1 net profit of under $400m.
Based on today’s reported numbers, the proposed increase in capex this year looks manageable to me.
Outlook: there doesn’t seem to be any explicit outlook guidance in today’s results and I don’t have access to broker notes. But I think it’s reasonable to assume today’s numbers are in line or slightly ahead.
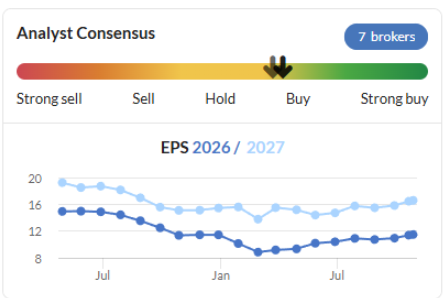
Looking at existing forecasts, today’s adjusted earnings of 8.3 cents represent 54% of the FY26 consensus figure of 15.3 cents. I don’t think there’s very much seasonality to this business, so perhaps brokers will extend the run of earnings upgrades they’ve delivered this year:
Roland’s view
This is a relatively complicated business with quite a few moving parts. The planned IPO of the mobile money business next year adds a further layer of complication to any valuation.
In my view, the combination of leverage and extensive exposure to a range of emerging markets also adds some risk to this investment, when compared to Vodafone or BT.
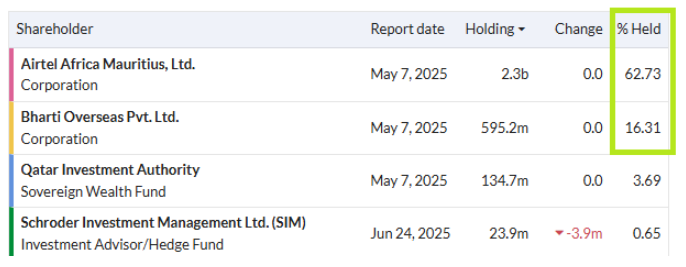
One final point worth making is that ownership remains highly concentrated. In effect, the business is controlled by Indian billionaire Sunil Mittall, who has direct or indirect control over nearly 80% of the stock:
All of this makes Airtel Africa a somewhat different type of investment than Vodafone or BT.
However, I think there’s a good case for arguing that much of this risk is offset by the strong, structural growth opportunities the company has in underdeveloped and (probably) quite lightly regulated markets, compared to the UK/EU.
I can’t see any real reason why the growth in use of smartphones and electronic banking won’t continue across most of Africa – that being so, leading incumbents like Airtel Africa could still become much larger businesses.
The shares currently trade on a FY26E P/E of 20, falling to c.14x in FY27. The dividend yield is less appealing than it used to be, at just 2.1%.
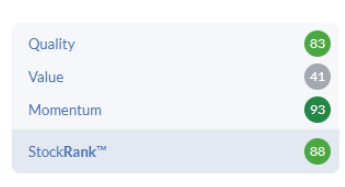
I can see some arguments for taking a neutral view here, but equally I’m reluctant to go against such strong momentum and high profitability. The StockRanks view this as a High Flyer and I am also going to adopt a moderately positive view – AMBER/GREEN.
React (LON:REAT)
REACT Group Plc (AIM: REAT), the leading specialist support services provider to the facilities management (FM) industry, announces a trading update for the year ended 30th September 2025 ("FY25").
I’m relieved to see I took an AMBER/RED view on React in May, since when the shares have fallen steadily. Even after today’s pop, the price is still nearly 15% lower than five months ago.
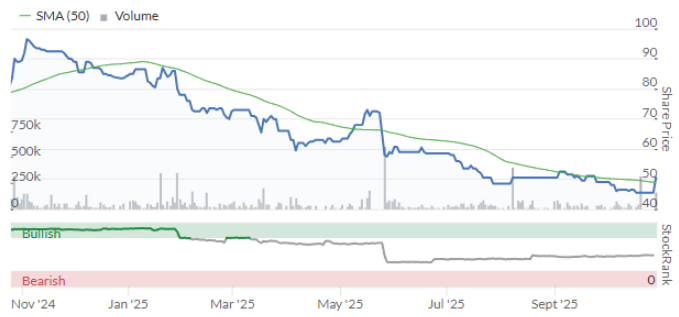
Today’s year-end trading update flags up some promising sounding numbers and indicates that full-year results are now expected to be ahead of previous expectations:
Revenues expected to be approximately £25.0 million (FY24: £20.7 million)
Gross Profit expected to be approximately £8.0 million (FY24: £5.7 million)
Adjusted EBITDA expected to be at least £3.0 million (FY24: £2.4 million)
However, React’s management has not chosen to provide a split between organic growth and the contribution from last October’s acquisition of Aquaflow. Instead, they’ve included this vague comment (my bold):
Revenues increased by approximately 21% year-on-year to c.£25.0 million, driven by continued momentum across core service lines and the contribution from the acquisition of 24hr Aquaflow in October 2024.
Checking the acquisition details for Aquaflow, I find that it generated revenue of £6.1m, gross profit of £3.4m and adjusted EBITDA of £1.2m in the year to 30 April 2024 (prior to acquisition on 28 Oct 24).
React’s financial year started on 1 October, so the company should have had an 11-month contribution from Aquaflow in FY25..
However, plugging 11/12 of the FY24 Aquaflow numbers into today’s update just doesn’t seem to add up. For example, 11/12 of £6.1m is £5.6m. Adding this to React’s FY24 revenue would give a total of £26.2m. That’s greater than the revenue figure reported today, even before any organic growth within the existing group businesses.
I can only see two possibilities – Aquaflow’s performance has deteriorated this year, or there has been a significant contraction somewhere else in React’s operations. Remember that this business issued a profit warning with its interim results in May; we already know H1 was poor for some parts of the group.
The increase in net debt to £5.3m (31 March 25: £4.8m) also suggests to me that true profitability (i.e. cash generation) has not been very strong this year. Debt has risen in H2 despite the lack of acquisitions during that period.
Outlook: with thanks to Dowgate Capital on Research Tree, we have updated forecasts today:
FY25E EPS: 6.7p (prev. 6.4p)
FY26E EPS: 9.3p (prev. 9.1p)
These forecasts leave the stock on a FY25E P/E of 7.5, falling to a P/E of 5.5x for FY26. However, these new estimates remain well below expectations prior to May’s profit warning:
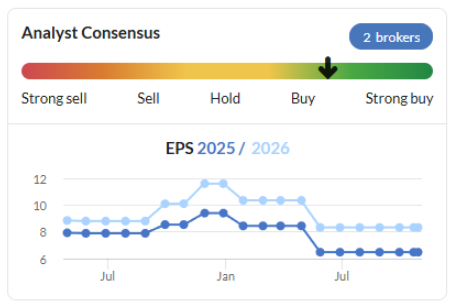
Roland’s view
In May I made the following observation about the business:
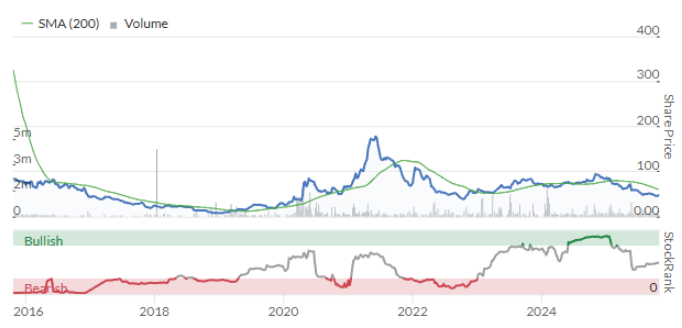
React has a patchy record of profitability. While its collection of operating subsidiaries may include some attractive businesses, management empire building has delivered very little for shareholders – the share count has tripled since 2019, but the share price has fallen.
My view remains unchanged following today’s year-end update, as does the long-term share price history:
While this earnings upgrade is positive as far as it goes, I feel that today’s trading update raises questions about the contribution from Aquaflow since its acquisition and/or the organic performance of the group’s remaining businesses.
As an equity investor, I don’t see anything to interest me here. My overall impression is that this business may be run more for the benefit of its management than for its long-suffering shareholders.
I could perhaps adopt a neutral view today, but React’s very poor history of profitability discourages me:
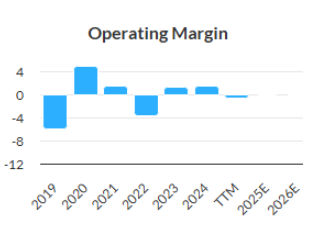
I’d like to see evidence that reported margins have improved before upgrading, so I’m going to leave my view unchanged at AMBER/RED today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
I also find the case for RWS Holdings (LON:RWS) compelling. Sales are still healthy and are forecast to grow. More important than earnings with contrarian.companied. Operating margins have been good in the past and one can hope that this share will revert back to it's former glory given it's dominant market position. Some free cash, low gearing and a low EV/Sales positive factors. The great QV rank another endorsement. Excellent article.
Maybe the media aren’t making a big deal out of the wonderful bull market we have in the UK because they don’t want to jinx it? :)
Goodwin (LON:GDWN) . I wonder how many shares, in the history of Stockopedia's rankings have more than trebled in 3 months (since 28-Jul) and still only have a momentum ranking of 68 at the end of this. I guess its the lack of broker estimates that is mucking up this metric in this case?
Ceres Power Holdings (LON:CWR) I'll add and it does show how you can be wrong Graham gave it a Red on 26th September. Since then the stock price has doubled.
I'm a long term suffering share holder. It also shows you how Bosch got it wrong timing wise on getting out sp wise. BUT we need profits, it has great tech essentially fuel cell technology turning hydrogen into electricity. Some way to go I feel but its getting there a few key contracts and the rest will follow. After all 40 years ago you never got the sack for buying IBM, whose that you say
Graham goes on numbers and you are fueled on hope perhaps? Bosch, a bunch of Engineers. What would they know about RnD.
Ceres Power Holdings (LON:CWR) Is promoted to FTSE250 now we need some profits
Thank you for your RWS coverage Roland, I made the mistake of adding to our losing position last week when I could have bought cheaper today. Good luck to contrarian holders, Mr Market currently shows we're wrong.
Nice little update from Time Finance (LON:TIME) this morning (I hold). Their steady progression seems to be continuing into the new FY. However, the SP continues to track down so Mr Market clearly thinks the peak growth is behind them. I like the strategy and they keep hitting or exceeding so I'll stick with it until the story changes.
Thanks for bringing this to our attention. I wasn't aware of it.
Looks like a buying opportunity to me.
The beats against expectation continues!
Definitely the market is very sceptical on Time Finance and whether their growth story can continue. I am in that camp, sold out earlier this year at 60p+. But they keep delivering. It is still on my watchlist, so happy to buy back in when the time is right.
Aclara Resources (TSE:ARA) spiked on the 14th Oct which I missed seeing aand has spiked again today. I guess it's to do with rare earth minerals in Peru. I gained a few shares by default when Hochschild Mining (LON:HOC) orphaned a couple of subsidiaries, this one and Zinnwald Lithium (LON:ZNWD) . I sold Zinwald as I recognised as being a kennel-squatter but Aclara is a little difficult but I note my dealer, ii is offering free trades with the US and Canadian stock markets from tomorrow and the 31st so I am in a quandary, sell or keep Aclara?
Has anyone seen any news that might explain Serabi Gold (LON:SRB) fall by 12% today, following yesterday’s 5% fall. I’ve been looking for a pull back to add to my holding and this could be it, if the cause is nothing too sinister.
Gold price :
20 Oct £104,584 / Kg
28 Oct £94,363 / Kg might explain it.
But gold down today just 2.5%. Serabi since 20th October down from 270 to 215, quite a drop, notwithstanding the mega rise over the year so may just be a natural pull back from over-exuberance. I’m happy to top up at todays price, cheers Jim
No, Gold has fallen from a peak of USD4,316 on October 20th to USD3,905 today, a fall of 9.5%. I am expecting the fall to continue through Autumn to USD3,500, for a total fall of 19% There is major support at 3,500 and the backdrop of a bankrupt US and de-dollarization has not changed. Central Banks are going to continue moving reserve assets away from the USD to gold. The bull will resume in the Spring in my view.
The Serabi SP fall is not company specific ... have a look at GDX and GDXJ. They are all dancing together to the same tune.
Rhodie
Suggest you add other gold miners to the Serabi chart. To my eyes they are moving like a synchronised swimming team. That was true going up and now it’s true when everything is wobbling. IMHO that implies that SP movements here (up and down) are driven more by the underlying gold price than they are by company specific factors.
Depends on your timeframe. Entirely possible Serabi Gold (LON:SRB) will be lower in 2 months time. But in one years time with a forward PER of 3.5, it is very likely to be much higher.
Trump is pushing the gold price up due to erratic tariff and other policies. Central banks want to reduce dollar holdings and are moving more money into gold. I view the current pullback in the gold price as a neccesary correction after a very large leg up. $4,000 seems to be a base it can build off.
China buying gold and reducing its dependence on the dollar.
Nothing to do with what you are implying!
All the best
I am sorry but I completely disagree. yainnos1. Central Banks, including the PBC, are reducing their dependency on the USD as a reserve asset precisely because the US is no longer viewed as a reliable partner and that is a large part due to the approach of the Trump administration. When you add in the fact that the USD deficit is now 1.8 trillion annually, greater than the US defence budget and the US owes 38 trillion, none of which has the remotest chance of being paid other than in nominal terms through an inflationary default together with a deliberate strategy of weakening the USD, then you have the perfect recipe for a gold bull market. Trump did not create the twin deficits, but he sure knows how to add to them with his "one big beautiful bill". The gold bull will return in the Spring because nothing has fundamentally changed.
Don’t be sorry
I completely disagree as well.
It’s like the US deficit and raising the debt ceiling it’s something new?!
China is selling US bonds as well!
All the best
What is new is the Trump Administration's approach to the debt. There have been comments from the Administration about not paying the coupon on certain long dated treasuries or only paying the coupon on treasuries held by "friendly" countries. There have been other comments about forcing countries to buy US Treasuries in return for "protection" ... a proper mafia approach, although I suppose that would be a better prospect than the US extortion of Ukrainian f-block minerals for no protection. Trump has a documented history of reneging on financial obligations in personal business, which some commentators have linked to his casual treatment of sovereign debt.
Trump has has crystallised the current bankruptcy of the US in the minds of those central bankers who previously went along with the status quo and pretended there was not an issue. There are now limited foreign buyers in US treasuries auctions because nobody thinks they will be repaid in anything other than debased fiat currency.
Of course, America is not the only country heading towards a sovereign debt crisis. Anyone fancy long dated Obligations assimilables du Trésor or long dated gilts? The difference is all risk assets are priced off the 10-year US Treasury, so the grotesque behaviour of Trump matters, whereas the antics of Micron and Sir Sleepy, are almost irrelevant outside their respective countries, which are also bankrupt.
Certainly you are not implying that the US will default on its debt?
Just because the orange kid on the wheel has declared bankruptcy on 100 occasions!
I was a bond trader in my early years and i have posted here in numerous occasions about companies like Petrofac (LON:PFC) and Argo Blockchain (LON:ARB) and many others that their debt prices were sending distressed signals.
What you are implying are personal opinions that I respect, but are not backed by bond prices
Yes the debt is at alarming levels (something that I have heard one million times in my career) but if growth can be sustained at over 3% and short term rates below that then the US will thrive.
Not a fan of any politician-wait till you see Sir Farage on the wheel and see where these UK gilts will rise………..cause all these people that price them are not stupid! That’s what you should worry most about and not the US.
Again, emphasising that I do respect your views.
All the best
Hi Yiannos.
I worked in the City for 10 years in my youth (Spicer and Oppenheim, Cazenove pre the JPM "merger", Phillips and Drew). I can't pretend it gives me any greater insight than the next person, but at least I can add up. One of my more interesting audit clients in the 1980s was a company called King and Shaxon who were one of the, seven I think, London Discount Houses who managed the issuance and market making of gilts between the Bank of England and the market. That system of the London Discount Houses has long gone, but it was orderly, if a bit last century and idiosyncratic. A lot of what has happened in the gilts markets recently (and the UST market) has not been orderly and it makes me wonder if the old idiosyncratic ways were best. Maybe that is just the thoughts of a retired dilettante farmer reminiscing about the old days (which are now 40 years ago). As my nieces and nephews tell me, things have moved on,
On the subject of default, there is more than one way to default, and I would certainly argue inflation is a default. I am not suggesting the current administration is deliberately stocking inflation (quite the opposite) but that will be the immediate consequence of a weak USD and Trump's tariff policies, at least in the short term. However, unlike most commentators I have read, I do not believe in the longer term the tariffs will be inflationary; rather the tariffs are likely to prove to be a one-off inflationary hit, followed by deflation. As we both understand, the whole game will be decided by liquidity flows. If inflation runs at 3% as you suggest and real rates are lower (which is likely and what Trump has been pushing Powell to do for months), then this can only be bullish for gold which is where this whole conversation string started. I remain a long-term gold bull but fully expect a pull back to USD3,500 before Christmas.
Gold is an asset like all the others.
That’s why during the 2008 crisis it has lost about 33%!
If liquidity is not an issue it will go higher-like all the others-I prefer BTC as it will outperform.
All the best
My feeling on gold's performance during the GFC, was that it was the most liquid asset, so got sold first to cover margin calls and other negative liquidity events, hence it dumped like everything else, albeit less so in absolute terms. Gold quickly bounced back. I am not a gold bug - as you say it is just another asset - and I am quite prepared to trade it.
Lost 33% beginning of 2008-October 2008 with collapse of the banks.
Sold like any other asset due to liquidity issues during the Lehman brothers collapse.
It’s just another asset
Thanks
Couple of other factors at play also , I'm 100% pro Ukraine but the freezing of $300 billion odd of Russian assets was a big kicker for foreign central banks to get into an asset that couldn't be frozen at a keystroke. Trump openly saying he wants the dollar lower would also make holding longer dates treasuries less attractive in my opinion although they seem to have no issue getting treasury bills away at the moment.
i can't remember if I posted it here before but as an aside the biggest holders of US bonds are now hedge funds based in the Cayman Islands playing the basis trade, I would imagine if one dug into it the same thing would apply to UK Gilts also.
https://chroniclesmagazine.org...
Gold price heading towards USD 3,500 where it has major support. I sold half my bullion and some of my miners a few days ago. I kept half in case I am wrong.
The long-term price thesis remains intact in my view.
Previous bull markets for gold saw some pretty aggressive pull back in the order of 20 to 25% so after a spectacular run up, this is to be expected.
Is Cockney Rebel one of the most influential voices in the UK small cap space right now? He seems to be moving the market with ease of late, MPAC (LON:MPAC) the other day, Zotefoams (LON:ZTF) this morning.
A very impressive and strong following he's built up from what I can see....
yes, and a very nice licence to print money he has too.
He should try this on LIQUID stocks like BP (LON:BP.) HSBC Holdings (NYQ:HSBC) Lloyds Banking (LON:LLOY) Barclays (LON:BARC) British American Tobacco (LON:BATS) Diageo (LON:DGE)……….
Stocks that have real professional market makers behind them!
All the best
Is Cockney Rebel one of the most influential voices in the UK small cap space right now?
I guess ultimately if people are following their guru of choice that works both ways - exagerated upside but it can also drop like a stone when they fall out of love for their current favourites. Note thats not to put any negative spin on what CR does - CR does at least have very logical choices as to why they think stocks are great.
I guess as long as one knows the score one can act accordingly - if CR and his fans depart the building and you are left with a stock - well you can expect all the fluff and some to have departed then building too.
Oh and when people are selling if they want to get out quick i would expect they and thei key allies would sell up first before they flag up to others that they have sold. Nothing wrong with that as long as its done in transparent way. imho anyone following others shouldnt ever be blaming others if their choice fails - thats kind of golden rulke in investing. If you are blaming others the reality is you were the mug !!
More power to his elbow, he is generous enough to explain his investment rationale and he is right more often than wrong. Occasionally he gets it wrong - and he then holds his hand up. Like Oak Bloke he shows his 'working out' so he justifies his opinions rationally and methodically.
'More power to his elbow' - Been a while since I heard that expression, enjoyed it!
Personally I admire his intuition and method. I don't believe he has enough clout to truly drive the markets.
He's either reading the mood music correctly and hits a winner (like Works co uk (LON:WRKS)) or if not the big players will let the PI's pour their money into a mentioned share and then trade it back down (Watkin Jones (LON:WJG) ).
He is bloody good, isn't he?......
B.P. Marsh & Partners (LON:BPM)
Was kind of expecting it to be a quiet H2 this year - thought they might take pause for breath after pretty manic 18 months but no sign of that.
Acceptable outcome here their initital stake of $30 (£19) returns £27.8 million net of costs - an extra £5 mill uplift from 31/7/25 - oh with potential $24 million extra on top best case
Highlights:
· CAD $51.9m (£27.8m) (net of all transaction costs) cash consideration to be received upon completion by B.P. Marsh for its 28.2% holding
· Original equity investment of CAD $30 (£19), alongside a loan facility of CAD$850,000 (£490,000)
· Sale reflects a £4.9m uplift (21%) from the latest 31 July 2025 valuation
· Internal rate of return to B.P. Marsh of 89.8%
· A further performance related deferred consideration payment of up to CAD $24m is payable to SSRU's existing shareholders in 2026, based on SSRU's performance to 31 December 2025
Note with £240 mill market cap BPM needs larger flow of deals/valuation uplifts each year to keep the lights on (it aint easy to compound 10% to infinity any beyond as you get bigger) . Hey ho what each exit does is realise the cash (hopefully profit) for reinvestment and start again.
IMHO with current discount to TNAV - its a complete no brainer to be buying back shares should they so choose - anything below 750 seems very cheap to me at present. I wander if there isa point at which they would get too big for them to have enough of the very best quality deals being done - in that regard reducig share count super quickly below ntav resets that clock very simply.
Note as highlighted on the results thread recently in the most excellent posts by Jreremy Rea- directors here do get very generous rewards when they deliver the bacon - that can be as much as 10-15% of the value uplift going as their bonuses/shares - IF they acheive compounded asset value uplifts (before divis) at over 8.5% pa - and hit their sweet spot. My viewpoint is thats the deal here for having the skills of the main people in charge - main bods could easy take their cash walk out the door and start up in competition (or delist) or runoff whats there - the key people here are really what makes this business tick imho - albeit as they get bigger hopefully they have the relevant continuity plans in place to replace the old gaurd.
B.P. Marsh & Partners (LON:BPM) Potential $6.77m on top best case - the $24m defcon is shared among all shareholders, and BPM hold (held!) 28.2%.
B.P. Marsh & Partners (LON:BPM)
cheers ISA allowance - i stopped reading too soon - as you say its fraction of the totyal as you rightly highlight - doh.
Yeap, B.P. Marsh & Partners (LON:BPM) continuing to do what they do best, and doing it well. Turning an initial £19 investment into multiple millions isn't a bad business model!
They look a solid longer term compounder to me. But for that Dir. remuneration I would be on fully onboard.
The CPI data that was no worse, even a little better, than expected has been taken well. Somewhere between 0.2% and 0.3% MoM hardly seems worth comment, broadly inline with the Fed target but it has been taken as a positive sign the fed can cut rates. Over the last few months short term bonds, 2 years and less have been positive and yields have fallen reflecting this confidence that rates will be cut. 10 and 30 year bonds have progressed less and so the term premium has risen. This dampens the positive affect cuts may have. The implication being, rate cuts may result in higher inflation, a lower quality source of growth. I can`t help recall the period 2001-02 when rates were cut at least ten times with little effect on the economy...and markets only recovered when the Iraq conflict started. Markets are running positively on the rate cut story into the meeting this week but the signs aren't universally positive. The bond market will be watched closely for how it reacts to these latest moves and enthusiasm for cuts....MOVE ie bond volatility, has halved over the summer....so well behaved down in the 60s for now....any spikes will be felt across asset markets ...but no sign of this yet. Will be interesting to watch for further evidence of a change.
cheers RDHPWARTH - what about the rates paid by the governmnet on debt should this be expected to trend postively? - imho RR really needs a break with regard to things not getting worse with regard to trend in expect rates we all need to pay on our national debt! - would be nice if that trend was downwards or at least stop trending upwards? not sure what the score is there?
This is a tricky one influenced by the refi cycle and where (maturity) governments choose to refi. So short term and index linked potentially cheaper but potentially riskier longer term .... so it's not so easy to conclude the effect as the media highlights. Long bond yields rising isn't helpful and obviously cutting rates help reduce some pressure on governments finances but since debt levels are likely to remain high ... the can maybe kicked down the road but its still there. The penny will no doubt drop that productive growth is needed but the election cycle often influences negatively. For the time being whilst lower interest rates are seen as growth positive the pressure on government finances is less likely to grow but remain exposed to negative surprises..clear as mud Im afraid.
They just need to stop spending but can't seem to get even near 1% of what they need to cut , instead just taking the route of ever more tax as their way of keeping the bond market onside.
They just need to stop spending but can't seem to get even near 1% of what they need to cut
Yes 100% agree - someone on ticktock was moaning they are almost in poverty whilst earning 35k per year - single person with 3 kids. I have every sympathy for them - but the state is paying £1760 of childcare costs for them every month - so this one person is getting 20k pa handout for others to look after their kids before we start on the other benefits they will also be getting. I think its fantastic that we aid people to get back to work and anyone juggling 3 kids and working near full time has to be applauded - but its lunacy to hand out 30k plus per year for people like this. an obvious solution would to be prioritise homeworking jobs for people who have real need but have younger kids.
PS. Also, whilst important during fiscal dominance we don't want to fall into the trap of thinking lower growth and lower rates keeps the whole thing going, this is deflation and Japan...but with terrible demographics. Ok for asset ironically.
Yellow Cake (LON:YCA) update doesn't contain too much new info. other than to confirm that the Nuclear industry continues to announce more build out plans and this should result in increased demand and therefore a shortfall in Uranium. Obviously the financial players like Yellow Cake (LON:YCA) and Sprott will look to sell into this over time...I guess as things tighten in the run up to 2030 and beyond. For me the thesis remains intact and demand from old plant restarts should be enough of a short term catalyst. AI Data centre demand makes nice headlines but is likely many years away, so I don't worry abut it too much. Should the AI trend roll though it will no doubt throw up opportunities in the sector. I continue to hold.
I hold Global X Uranium UCITS ETF USD Acc (LON:URNG) , which has been on a strong run recently. I believe that the combination of decarbonisation and the huge power requirements of AI will create an enormous demand for nuclear power.