Daily Stock Market Report (Tue 3 Dec 2024) - IPX, OTB, SYS1, GNC, VCT, MARS

Good morning!
Wrapping this up at 1pm. Thanks everyone!
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing. Links:
Daily Stock Market Report: records from 5/11/2024 (format: Google Sheet).
Companies Reporting
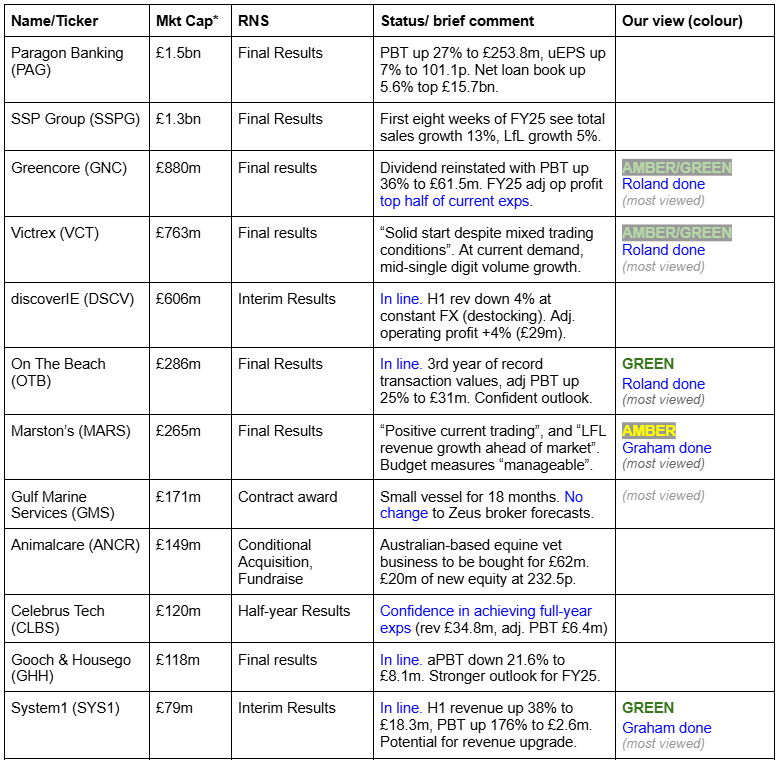
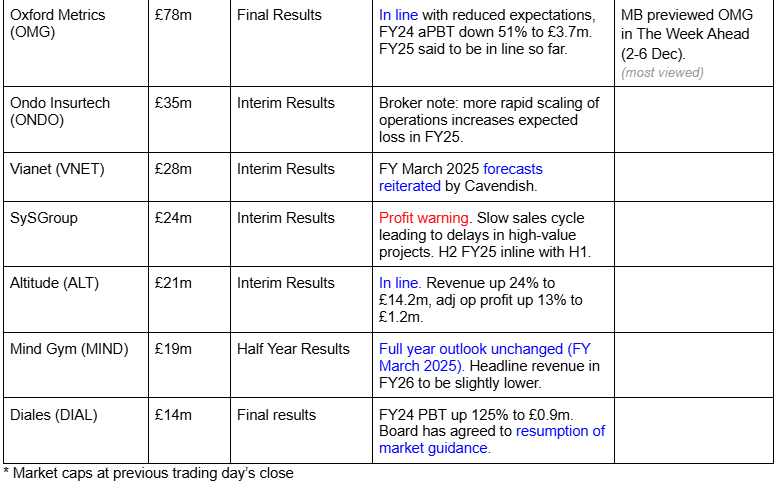
Summaries
Impax Asset Management (LON:IPX) - 328.5p (£442m) - Final Results - Graham - GREEN
Last week’s final results showed stable AUM (around £37bn) despite substantial outflows, thanks to market performance plus a small acquisition. Another acquisition is set to complete shortly. I remain positive on this due to a cheap valuation of c. 11x and credibility in its niche of sustainability.
On Beach group (LON:OTB) - up 13% to 194p (£317m) - Final Results - Roland - GREEN
The online travel agent has reported revenue up 14% and a 25% rise in adjusted PBT. Trading remains strong and management are confident of a similar increase in profitability for FY25. A £25m share buyback should further bolster earnings and unwind pandemic-era dilution. I remain positive at this level.
System1 (LON:SYS1) - down 1% to 616.5p (£77m) - Interim Results - Graham - GREEN
Strong results as expected from this provider of an ad-testing service along with related products and consultancy services. The company should have a strong chance of beating the previous revenue estimate but with £2m of new discretionary spending for growth, next year’s pre-tax profit forecast has been slightly downgraded by its broker to £5.6m.
Greencore (LON:GNC) - up 9% to 215p (£976m) - Final Results - Roland - AMBER/GREEN
This convenience food producer appears to be extending a strong run of improved performance that’s seen the stock double over the last year. Updated guidance today suggests a possible 4% increase to FY25 earnings expectations. I think the valuation is starting to look full, but can’t ignore the potential for further upgrades.
Victrex (LON:VCT) - up 15% to 1,009p (£888m) - Final Results - Roland - AMBER/GREEN
Encouraging results showing a return to volume growth for this specialist plastics business. Pricing power remained relatively weak last year but management expects profits to grow ahead of volumes this year, suggesting improving market conditions. It’s too soon to be sure of the turnaround here, but I’m increasingly positive after a harsh multi-year derating.
Marston's (LON:MARS) - up 7% to 43.2p (£273m) - Preliminary Results - Graham - AMBER
Upgrading this one to AMBER after a set of results showing strong profitability. The main news in the outlook statement is that the company has continued to trade with positive like-for-like growth in the first weeks of the new financial year. They expect to deliver £50m of recurring free cash flow annually in the near-to-medium term and I hope to see the leverage multiple continue to fall from 5.2x (they are not currently paying dividends).
Graham's Section
Impax Asset Management (LON:IPX)
328.5p (£442m) - Final Results - Graham - GREEN
Impax Asset Management Group plc ("Impax" or the "Company"), the specialist investor focused on the transition to a more sustainable global economy, today announces final audited results for the year ending 30 September 2024…
Let’s catch up on another stock that slipped through the net last week.
Assets under management
Impax, like almost all fund managers we follow, has fallen into suffering net outflows. That was true in FY 2024 as clients pulled out a net £5.8 billion.
Positive performance helped to offset the effect of those flows, however, and £300m of fixed income AUM was acquired.
The net effect: AUM was little changed by the end of the financial year at £37.2 billion (end of FY 2023: £37.4 billion).
Profitability
Revenues are earned on average AUM, and IPX’s full-year revenues fell by 4.7% to £170m.
There are knock-on effects on profits, but generally profits have held up ok:
Adjusted operating profit down 9% to £53m
PBT down 6% to £49m
Well done to Impax for managing its adjusted operating costs, which fell by £3m to £117m.
The revenue margin on AUM was stable at 45 basis points - stable is good, as the general trend in revenue margin for the industry is downwards.
Full-year dividend: unchanged at 27.6p, with an implied yield of over 8.4% on the current share price:
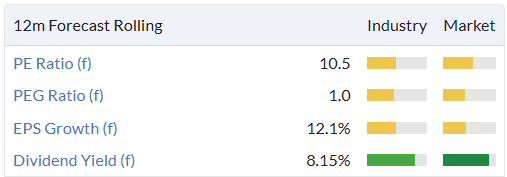
Impax is paying out 87% of adjusted profit in the form of the dividend, far above its minimum target of 55%. The reason given is that it’s in “robust financial health”.
Balance sheet: robust financial health can be witnessed on the balance sheet where there is tangible equity of £108m including cash reserves of nearly £91m (includes amounts held in money market funds which I agree are equivalent to cash).
The comment by the Chair highlights resilience in a period of uncertainty:
Impax has continued to show its resilience over the Period. The Company has made material strategic progress and delivered improved investment performance while focusing on operational efficiency and the control of costs.
Also, the Outlook statement is interesting after a US election result that did not favour the environmentalist movement.
Despite President-elect Donald Trump's negative stance on climate policies, experience from the first Trump administration suggests that the next four years are likely to be positive for US-based businesses delivering innovative products and services in the above areas [GN note: healthcare, semiconductors, reinsurance, infrastructure] and in which materials and energy efficiency are significant contributors. Against this backdrop, we are highly confident that our investment portfolios can deliver excellent returns for clients.
Graham’s view
I tend to be positive on this share: the last time was at 370p in July, when IPX announced the acquisition of another £1.6 billion in fixed income “assets under management and advice”. It’s yet another US-based acquisition for IPX, and it’s expected to close “around the end of the calendar year”.
It won’t come as a shock to readers that I’m staying positive on this one at a PER of about 11x and even lower than that if you’re willing to adjust the cash out to use an EV-based valuation.
Analyst Paul Bryant at Equity Developments puts it on an FY 2025 PER of 10.9x and cites a number of possible catalysts for inflows to resume at IPX. These include interest rate cuts, growth in US industrials under Trump, a flight back to active management due to concentration risk in the Magnificent 7, and renewed interest in sustainable investing.
For me it’s the last one of these that is the most relevant. IPX has a real niche: its entire mission from day one has been “sustainable” investing, and in my view this makes it one of the most credible names in this field.
Investor interest in this niche will come and go, but that doesn’t mean IPX has to lose any of its long-term competitive advantage.
In terms of valuation, investors currently get £84 of AUM for every £1 they invest in IPX, before the effect of the acquisition which is about to complete.
This compares with only £19 of AUM for every £1 invested at the height of optimism in late 2021:
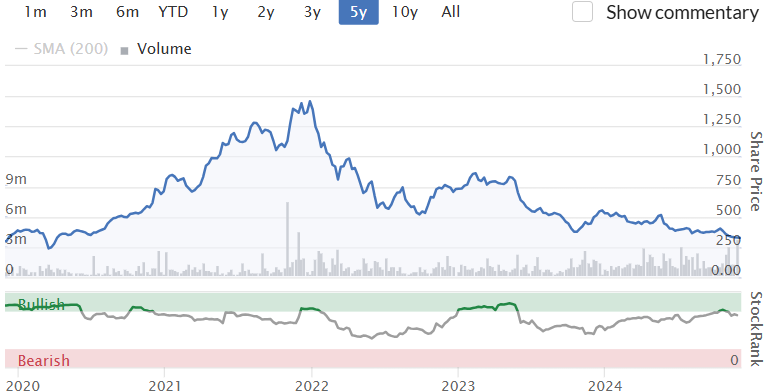
I believe I was justifiably cautious when these shares were overheated. As they now sit in the doldrums, I think I’m justifiably positive.
System1 (LON:SYS1)
Down 1% to 616.5p (£77m) - Interim Results - Graham - GREEN
It took many years for SYS1, “the marketing decision-making platform”, to reorganise its strategy after an initial run of success that lasted until 2017.
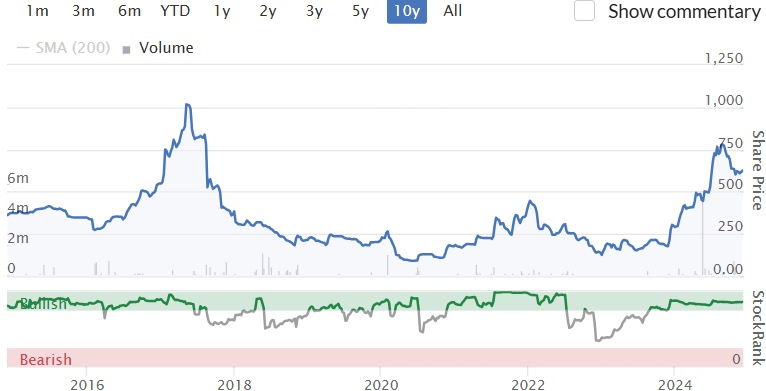
The subsequent run of poor performance has ended at last, and the shares have more than quadrupled since early 2023:
The strategy is now focused on Ad-testing with the flagship “Test Your Ad” product.
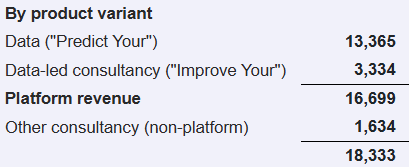
In addition to Data products, the company provides “Data-led consultancy” that it also categorises within “Platform revenue”.
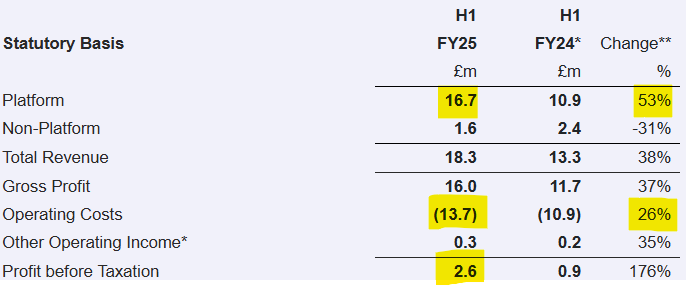
Today’s interim results show a 53% increase in SYS1’s “Platform” revenue, while operating costs increased by only 26%. We get a useful PBT result of £2.6m over six months:
The profits have already been earmarked for spending, but I don’t think SYS1’s shareholders will complain:
£2m additional discretionary investment in the next 18 months aimed at building our position in America and revitalising System1's Innovation proposition.
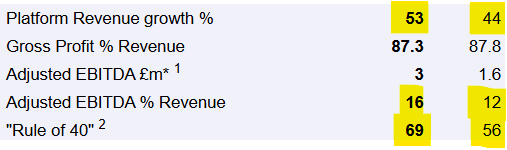
KPIs: System1 is one of the very few companies we cover that uses that “Rule of 40”, a rule that helps investors to determine if software companies are finding an appropriate mix of growth and profitability.
The rule states that revenue growth plus the profit margin should add up to 40.
This implies that investors should be happy with:
40% revenue growth, 0% profit margin.
20% revenue growth, 20% profit margin.
0% revenue growth, 40% profit margin.
Whether investors are in fact happy with each of these outcomes is another matter, but that’s the Rule of 40.
SYS1 says that its Rule of 40 score has improved from 56 to 69, now even higher above the minimum amount:
Another helpful KPI is net revenue retention (NRR), which is revenue (excluding new clients) as a percentage of revenue in the corresponding period last year. It helps to demonstrate customer loyalty, customer satisfaction and the demand for repeat business.
NRR improved to 120% for platform revenue, implying that last year’s clients spent 20% more in H1 this year.
Geographic breakdown: the strategy of US-driven growth is bearing fruit with 79% revenue growth in the US in H1, from £3.6m to £6.4m.
Balance sheet: a nice simple balance sheet with £10.5m of tangible equity including a healthy cash balance of nearly £9m, with no borrowings.
Outlook: in line with full-year expectations for revenue of £36.5m and adj. PBT of £4.4m.
CEO comment:
"The first half has played out in line with our plan with strong platform growth and good progress in the USA, over 160 new client wins and improved net revenue retention with existing clients. System1 has a significant opportunity to increase revenue both in America and within the Innovation market segment and we have already begun a £2m additional discretionary investment programme over the next 18 months to target medium-term revenue growth in these areas".
Later, he says that Q3 has “begun well”, with “potentially some revenue upside compared to current market expectations”.
Estimates: Canaccord have not waited around. They have touched up their FY25 revenue forecast to £37m (from £36.5m). As £18.3m has already been delivered in H1, I think it makes absolute sense to start getting the upgrades in.
For FY26, they increase the revenue forecast by £2m (to £44m) but also reduce the adj. PBT forecast by £0.4m (to £5.6m), due to SYS1’s planned investment spending.
Graham’s view
When it was first explained, I wasn’t a fan of SYS’1 new strategy - and I wasn’t alone. In April 2023, frustration with the lack of progress led to a battle for control of the Boardroom. I thought the strategy relied on success with the biggest advertisers, which wasn’t guaranteed, and preferred the concept of selling more broadly to anyone who wanted to advertise.
However, I cannot complain about the company’s financial progress over the past year and a half.
Valuation has soared and the stock now trades on a current-year PER of 26x, falling to 19x based on FY26 forecasts.
My instincts are to downgrade this to AMBER/GREEN on valuation grounds but it’s important to let winners run and so I’ll leave this on GREEN while it continues to hoover up new clients.
Marston's (LON:MARS)
Up 7% to 43.2p (£273m) - Preliminary Results - Graham - AMBER
Marston's, a leading local pub business with an estate of 1,339 pubs across the UK, today announces its Preliminary Results for the 52 weeks ended 28 September 2024.
I was nervous on this one in October at the time of the full-year trading update. MARS has a freehold property estate but has borrowed heavily against this, leaving it in a complicated financial position.
Today’s full-year results show strong profitability: the PBT result is £42m, up 64% year-on-year.
Pub operating profit is an impressive £147m, but then finance costs of £106.5m eat up most of that.
Finance costs are hopefully on the retreat: net debt (excluding leases) fell by £300m during the year, to £884m, as we discussed in October.
The leverage multiple falls from an entirely unreasonable 8x down to a still uncomfortable 5.2x.
Outlook is positive:
Positive current trading with continued momentum and early progress in embedding strategy across the business
Like-for-like sales in the first six weeks grew by 3.9% marking a strong start to the year and demonstrating continued growth ahead of the market
The recent Budget “puts some additional pressure on costs, but the overall package of measures is considered manageable”.
Balance sheet: the CEO points to balance sheet asset value of £2.1 billion. Net assets have changed little year-on-year: they are now £655m, or 103p per share.
The big difference on the balance sheet is the sale of the company’s interest in its brewing business, Carlsberg Marston’s, to enable a reduction in borrowings.
Going concern: the going concern statement reads quite well this year. The directors have concluded that the company could withstand a reduction in sales of 10% vs. base case scenario. This would only result in a breach of banking covenants in the quarter after the next financial year, and that’s assuming there are no management actions taken to mitigate the impact.
Outlook: LfL sales growth is running at 2.1% in the first eight weeks of the new financial year, with recent weeks affected by snow and storms.
In the near-to-medium term, their targets include revenue growth ahead of the market and £50m recurring free cash flow.
Graham’s view
I’m going to give this an upgrade to AMBER.
I said in October that I wanted to see strong numbers from MARS and signs of solvency.
The much-improved going concern statement today gives me the confidence to switch to a neutral stance as financial distress now seems to be off the table - of course there is never any guarantee, but the company has a fully-tangible, positive NAV of more than double the current share price, and its going concern statement is clean. I believe that if trading were to suddenly collapse, management would probably have actions that they could take to defend the company.
The main indicator that needs to be improved now is the leverage multiple. At 5.2x, this is still too high in my view (I never want to see this over 3x). Remember also that it’s based on EBITDA, i.e. it excludes depreciation which is a significant expense for a capital-intensive business such as pubs (MARS took a £40m depreciation charge during FY 2024).
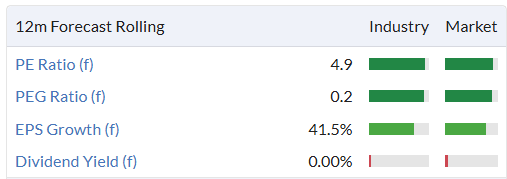
In summary: MARS has made good progress and deserves an upgrade, in my view. But there is more to do. I’m curious to see how they will manage the recent Budget changes to employment costs. If they succeed in mitigating the impact and paying down debt, there is an opportunity for shareholders to do very well from this level:
Roland's Section
On Beach group (LON:OTB)
Up 13% to 194p (£317m) - Final Results - Roland - GREEN
When I looked at On The Beach’s full-year trading update in September, I took a positive view. This stance seemed to have been justified by a strong set of results today. Management at this online travel agent certainly sound bullish, potentially with good reason:
Another record-breaking year of TTV, with adjusted PBT +25% YOY, addressable market expansion and enhanced customer proposition
OTB’s profits have now surpassed their pre-pandemic highs, but the share price remains subdued, even allowing for the dilution that took place in 2020/21.
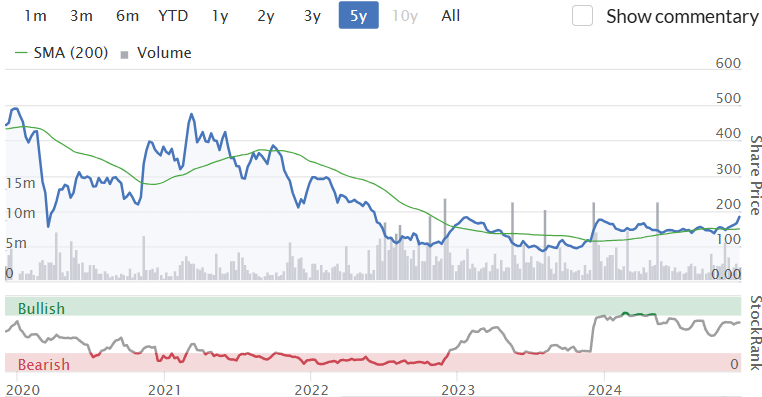
Let’s take a look at today’s results.
23/24 results summary: today’s numbers cover the year to 30 September 2024, so include peak summer trading.
Total transaction value (TTV) rose by 15% to £1.2bn last year, while revenue climbed 14% to £128.2m. I would guess some of this is inflationary rather than volume related, but I can’t argue with the 25% increase in adjusted pre-tax profit to £31m.
On a clean, statutory basis the increase is even more impressive – OTB’s pre-tax profit rose by 84% to £26.5m, a new record high for the business.
The company ended the year with cash excluding amounts held in trust of £96.2m (Sept 23: £75.8m). This is presumably a post-summer seasonal high, but is still quite striking for a company with a c.£290m market cap.
Shareholder returns: management clearly feels that at least some of this cash is surplus to requirements.
OTB’s dividend has been reinstated with a full-year payout of 3p per share, in line with the company’s policy of paying out 25% of net earnings.
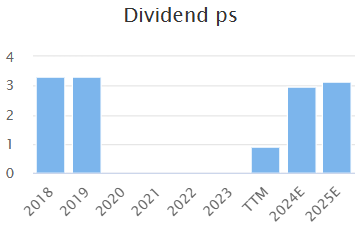
My sums suggest the dividend will total c.£5m. This amount looks somewhat modest when seen alongside today’s other surprise news – a £25m share buyback.
At the current share price I estimate this could see the company cancel around 12m shares, roughly equivalent to an 8% increase in earnings per share.
That’s only equivalent to a £1m increase in last year’s profit, equating to a 4% return on a buyback spend of £25m. However, if profits continue to perform strongly I guess the effective return achieved from this spending could increase in the future.
Trading commentary: passenger numbers in summer '24 were 13% higher than in summer 23. The company once again flags up the “transformational” nature of its partnership agreement with Ryanair, which allows customers to book Ryanair flights as part of an OTB package.
Upgrades to technology are said to be increasing addressable markets and OTB began expanding into city breaks from the final quarter of FY24, supporting the next stage of revenue growth.
OTB has also launched the first stage of its international expansion in Ireland, with onthebeach.ie.
Winter ‘24 bookings are currently said to be 25% ahead of the same period last year. TTV for the year to date (1 Oct-2 Dec) is said to be up by 14%, with bookings up 15%. This seems to suggest inflation has dropped out of the numbers – or else that customers are booking cheaper packages.
Outlook: management are confident that Summer '25 will be “significantly ahead” of Summer '24.
Profit guidance is unchanged and the company reiterates its support for consensus of £37.9m.
I don’t have access to any broker notes this morning, but this looks broadly consistent with the consensus estimates shown on the StockReport.
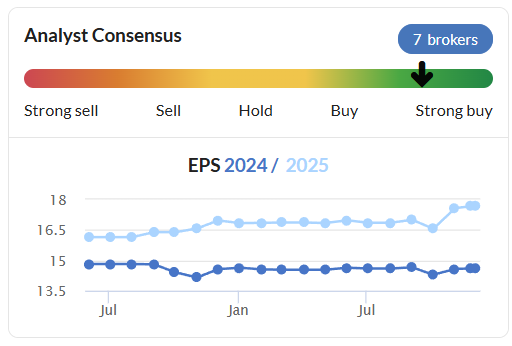
Looking further ahead, On The Beach says it is targeting TTV of £2.5bn and adjusted PBT of £85m. Achieving those medium-term targets would comfortably double the size of the business relative to FY25 forecasts.
Roland’s view
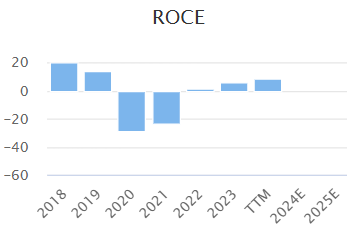
Today’s results show an operating margin of 16% and return on capital employed (ROCE) of 11.5%. These figures have been much higher in the past and I would hope there’s scope for further recovery:
One significant cost for the business is marketing spend in what is a competitive sector. However, I’d expect this to become more efficient as the company scales. This seems to be supported by last year’s results – marketing costs rose by 4.4% to £42.4m, supporting a 9.5% increase in gross profit after marketing costs.
On The Beach looks in decent health to me and appears to be enjoying strong trading momentum. Consumer demand appears to remain strong and as the group scales I would expect its brand to become a more effective asset driving customer acquisition, potentially lowering marketing costs per booking.
The shares have responded strongly to today’s news and are up 13% to 194p at the time of writing. Assuming consensus forecasts remain unchanged, that prices OTB on around 13x FY25 forecast earnings.
Given the group’s positive momentum and improving profitability, I think I can maintain my previous GREEN stance at this level.
Greencore (LON:GNC)
Up 9% to 215p (£976m) - Final Results - Roland - AMBER/GREEN
Today’s results from this sandwich maker and convenience food producer looks strong, with the firm flagging up volume growth ahead of the wider market.
Investors have responded positively: Greencore has notched up its guidance for the current year, despite the looming impact of higher national insurance costs in 2025.
...the Group anticipates FY25 Adjusted Operating Profit to be within the top half of the range of current market expectations
Greencore shares have now doubled over the last year. Is there more to come, or is the price now up with events?
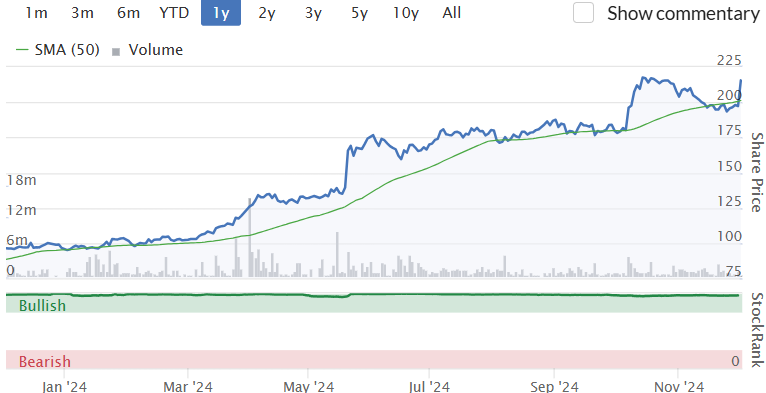
When I last looked at Greencore in July, I took an AMBER/GREEN stance at 187p and commented that moves by CEO Dalton Phillips to improve profitability appeared to be delivering results. My view was tempered by caution due to the mix of low margins and a high-teens P/E rating.
I reckon today’s results support this view, even if I was arguably a little too cautious.
Revenue fell by 5.6% to £1,807m last year as Greencore exited some low margin contracts and made a disposal. These changes helped to support a 3.5% increase in gross margin to 33.2%, supported by price growth of 1.8% and volume growth of 1.6%.That seems a decent result to me.
Improved profitability has been helped by efficiency measures and new contract wins. For example, the company’s soup factories have been consolidated to a single facility, while growth in ready meals is highlighted by contract renewals and a “large ready meal contract successfully onboarded” in late Q4.
As a result, Greencore’s operating profit rose by 27.7% to £84.3m, giving an improved operating margin of 4.7% (FY23: 3.4%).
Looking at the income statement, costs also seem to have been well controlled. Total operating costs rose by 2.6% (£13m) to £511.1m, which seems good to me given the six-month impact of last year’s minimum wage increase – Greencore is a fairly labour-intensive business.
This result supports a 12.1% ROCE (FY23: 11.8%). While not high, I would say this is probably a decent result for this business.
Next year’s increase in National Insurance is expected to add a further £7.5m to Greencore’s costs. However, the company expects to offset these through a variety of measures, including “contractual protections” and “further efficiency initiatives”.
Cash flow & balance sheet: I welcome management’s use of free cash flow in the results, although my calculation of £64.5m is slightly lower than the company’s figure of £70m. Even so, £64.5m (before buybacks) represents a very healthy 139% conversion from net profit of £46.3m.
Net debt excluding lease liabilities fell by £5.9m to £148m. This represents 3x net profit, or 1x trailing EBITDA. That looks comfortable to me, if not as low as I might prefer, for a low-margin business like this.
It’s worth noting Greencore spent £20.9m on interest payments last year, nearly a quarter of operating profit.
There was also some additional good news on cash flow. Greencore expects its pension scheme to be fully funded at the end of September 2025, at which point it will be able to cease making £10m annual deficit reduction payments.
Dividend & shares buybacks: management do not appear to feel any urgency to reduce debt. Last year saw a £50m buyback.
Today the company has reinstated the dividend at 2p per share and announced a further £10m buyback.
Outlook: Greencore says that its “leaner, more agile and efficient operating platform” is helping to drive new product innovations and has enhanced profitability.
Despite the significant cost headwind imposed by October’s Budget, management now expects FY25 adjusted operating profit to be “within the top half of the current range of market expectations”. This is available on Greencore’s website and suggests a range of £98.1m to £107.1m.
With thanks to house broker Shore Capital, we can see that this is expected to translate into a 4% eps upgrade, suggesting FY25 earnings of 13.9p per share.
Roland’s view
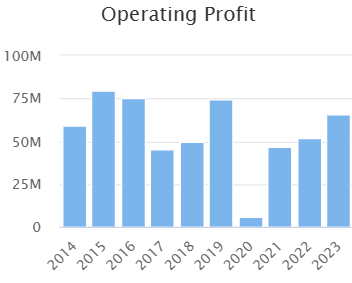
I don’t see much in today’s results to change my view from July. Greencore is an established market leader in the UK convenience food market and appears to be trading well. Last year’s operating profit of £84m appears to represent a new 10-year high for the business, according to Stockopedia data:
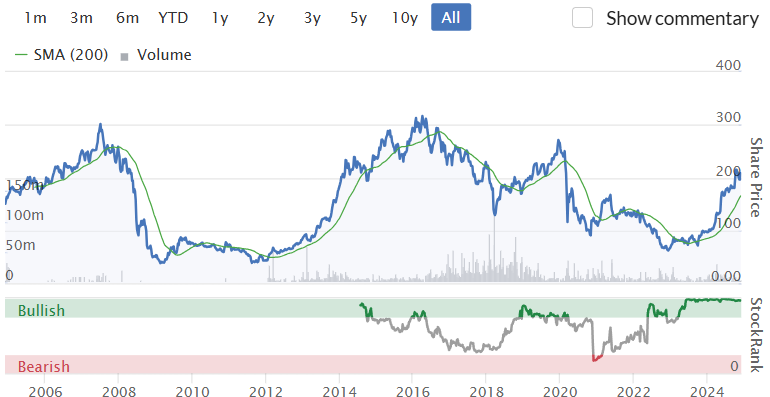
At the same time, Greencore is fundamentally a low margin business, with a moderate amount of debt and a history of cyclicality:
The shares did not look obviously good value to me, even prior to today’s gains:
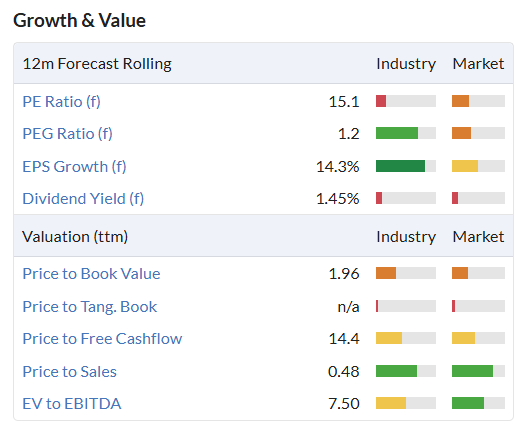
On balance, I’m going to maintain my AMBER/GREEN view here. I think there could be more to come in the short term, but I don’t view this as a quality compounder to continue holding indefinitely.
Victrex (LON:VCT)
Up 15% to 1,009p (£888m) - Final Results - Roland - AMBER/GREEN
Shares in this FTSE 250 chemicals group have seen a remarkable 15% bounce today. I believe the positive reaction to today’s results is driven by this bit of news (my bold):
Full year volume growth of 4% reflects a good finish to FY 2024, with our first 1,000 tonne quarter since Q4 FY 2022
The average selling price for Victrex’s proprietary PEEK polymer (a specialist plastic used in aerospace and other sectors) still fell by 9% to £78/kg last year.
But a return to volume growth might finally signify the end of a cycle of downgrades that has left Victrex’s share price more than 60% below its 10-year high…
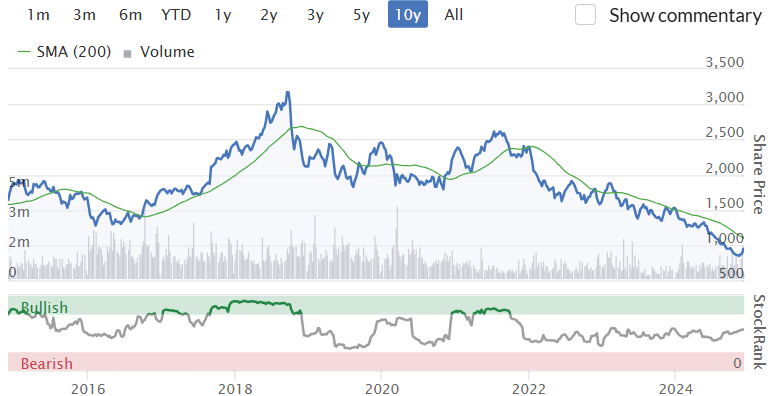
… and had a similar impact on profits:
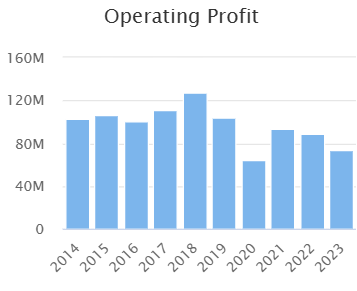
2023/24 results summary: today’s numbers do not yet show a recovery in profit to match volume increases.
While sales volumes climbed 4% to 3,731 tonnes, revenue fell by 5% to £291m due to the fall in the average selling price.
Trading performance was mixed across the group’s sectors:
Transport (aero & automotive) up 8%
Value-added resellers up 14%
Electronics down 12%
Energy and industrial down 5%
Medical down 19% to £53m due to destocking
Underlying pre-tax profit dropped 26% to £59.1m, while underlying earnings fell by 33% to 51.7p per share.
The dividend was held unchanged at 59.6p per share, leaving it uncovered by earnings. This isn’t ideal, but cover is expected to be restored in FY25 and Victrex’s minimal net debt of £21m suggests the company can just afford to maintain the payout.
One reason for the company’s profit slump may be that last year’s average selling price (ASP) of £78/kg was exactly the same as that achieved in the FY19 financial year. In contrast, the group’s FY24 cost of sales of £161.9m were 45% higher than the £112m reported for FY19.
I think investors need to consider whether Victrex’s competitive edge remains strong enough to support the pricing power it enjoyed in the past. The company says its mega programmes – R&D efforts to sell more manufactured parts and less raw PEEK – are making progress, but I’m not sure how much they contribute to the bottom line yet.
Outlook: Victrex admits that the timing of a recovery in its key medical market will be an important factor in any profit recovery.
“The Group has seen a solid start to FY 2025 - ahead of the prior year - despite mixed trading conditions. Our expectations for profit growth are based on robust demand continuing across the end markets of Sustainable Solutions, together with Medical improvement as we progress through 2025”
However, the company thinks it may be able to achieve run-rate volumes of around 1,000 tonnes per quarter over the full year, supporting “mid-single digit volume growth”, with underlying PBT growth ahead of volume growth.
I don’t have access to any updated broker notes, but consensus estimates on Stockopedia for FY25 earnings of 72p per share already appear to price in a positive outcome of this kind.
We’ll have to see if consensus estimates are updated after today’s results. But for now, these numbers price the stock on a FY25e P/E of 14 with a dividend yield of 5.7% after today’s gains.
Roland’s view
Today’s results from Victrex definitely seem a step in the right direction. However, I don’t think Victrex’s turnaround is a done deal quite yet.
Last year’s operating margin of 15.7% and ROCE of 8% are a far cry from the figures of 36% and 21.5% respectively reported in the 2019 financial year. While the company clearly still has some pricing power, this appears to be weaker than it used tobe.
Some of this may simply be due to cyclical factors. The last couple of years have also been dire for many other companies in the chemicals sector, with slumps in demand and some brutal destocking.
On the other hand, I think Victrex is facing increased competition from other PEEK manufacturers, hence its R&D investment in the mega programmes. This attempt at moving up the value chain will be key to a return to long-term, high-margin growth, in my view.
I’ve followed Victrex with interest for a while as a potential investment, but I’ve been wary about buying in too soon. The company’s return to volume growth suggests to me that this could be a good time to take a fresh look – I think this business certainly justifies more through research after today’s results.
I’m going to open our coverage of this interesting business by taking an AMBER/GREEN stance, to reflect the potential I believe exists here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

59 comments
Good momentum for Ferrexpo (LON:FXPO) … passes 3 long screens stocko ranking 91 … if this continues potential reentry to the ftse 250
Have you ever read a so called deep dive on some stock and you have digested all the financials, the key metrics, the financial growth (oh, how we humans are programmed to think linearly) and half way through the article, you realise you have no idea what the company does; how it creates value, who the competitors are, how large is the addressable market, is the market growing, why would a customer buy from the company?
I got to the end of the article and I still have no clue what the company does or even who its customers are.
Our investing world is full of this "deep" financial analysis with no real understanding of the business or its competitive position. It is so obvious not one of these authors has ever actually run a business.
James, is this a complaint about today's article? If it is, I'm not offended, but I just want to be clear that it is. Thanks. G
No Graham ... sorry I should have been clearer and I am not the sort of fellow who seeks to offend anyway. As Timarr says below, "deep dive" analysis is not the point of this forum.
I had just spent half a day reading various various analysts reports which is where my ire was directed. My comment was unclear and added no value .... apologies.
No worries at all James! Thanks for clearing that up. All the best.
You are welcome. I should add I think you, Megan and the team are doing a great job and I continue o enjoy reading this forum over my morning coffee.
Have you ever read a so called deep dive on some stock and you have digested all the financials, the key metrics ...
I mean, yes and no ... I don't think any of the authors or Stockopedia would ever describe the analysis here as a "deep dive" - and it never has been. It's on the day analysis of the numbers - which surely we all know isn't ever going to be the complete picture?
I wouldn't buy or sell anything based on what's covered here, never have done and can't understand why anyone would. The analysis provides a starting point for my own research, not an end point. In any year I'll find no more than two or three stocks that interest me, but they pay for my Stockopedia subscription many, many times over.
To put this in perspective, the two stocks I hold that I found through the SCVR were Cairn Homes (LON:CRN) (Graham) and Ashtead Technology Holdings (LON:AT.) (Roland). The funds I've already repatriated from those will pay for my Stockopedia subscription for the rest of my life.
timarr
Facilities by ADF
Harwood increase
CEO buys a few yesterday
I bought a few last week
Hi PlanetX,
I bought a few yesterday as well. Seems I got my timing right for a change. Below is the announcement for Harwood.
https://newsfile.refinitiv.com...
Thanks, Graham.
ME International (LON:MEGP) results tomorrow…. Anyone banking some profit just in case there is a dip?
Glass half full!
Not me that's for sure
It’s just a trading update, not a results announcement.
Run your winners and trust the process.
Nope ...
There are several competitors in the polyimide space including Dupont, Saint-Gobain and Goodwin (who are about to aggressively enter the market). One of PEEKs direct competitors is Vespel which is the polyimide produced by Dupont in their Industrial Solutions division. Vespel has been taking market share from PEEK at a steady rate and competes in many of the same temperature and stress performance market sectors including aerospace. The interesting thing is Victrex's PEEK product sells for less than the Dupont product, yet the PEEK has been declining in sales volumes and price, the Dupont product is seeing double digit sales growth in both volume and value.
Goodwin have submitted a patent application for their polyimide product claiming reduced volatile chemical use and enhanced solvent recovery (part of the green chemistry future) and enhanced mechanical strength and superior refractory properties. Goodwin have built a new factory to manufacture their new polyimide product,
I am not sure if the polyimide market is growing as I am an agricultural and food chemist and this is not really my area, but it seems logical to assume the products from Victrex, Dupont and also Meldrin from French company Saint-Gobain, are firmly in their sights, I would not bet against the tenacity and chemistry / engineering competence of Goodwin and consequently, I remain cautious on one product company Victrex.
One last point: I am nervous of investing in most chemistry businesses based in either the UK or Germany. Chemistry needs a lot of energy and Germany and the UK have utterly incompetent and sclerotic energy policies which ensure the highest energy costs in the World. Unbelievably, the UK has even higher energy costs than Germany and the only reason our economy is not totally wrecked is that we deindustrialised many years ago. The poor Germans are going through that pain now, as the chemistry business moves out of Germany.
I recently sold Goodwin (LON:GDWN) as I felt the shares got away from the realities and I hold no position in the other companies mentioned.
Victrex (LON:VCT) PEEK is competing in a much lower price/performance sector than DuPont de Nemours (NYQ:DD) Vespel which is the product that Goodwin (LON:GDWN) are going head to head with. In price terms PEEK averages some £75-80 a kg….Vespel & Goodwin’s Ducoya offering https://www.duvelco.com/ are in the £thousands per kg depending on the exact formulation & operate across a far larger thermal range which makes them unique & therefore valuable in a number of leading edge applications such as silicon wafer fab manufacturing.
Obviously Ducoya is at the start of its journey whereas PEEK & Vespel go back to the 1960’s & have well developed market positions.
I hold Goodwin & have done for years …Duvelco is exciting but the upcoming interim’s should shed light on the transformative growth in the Mechanical Engineering division driven by nuclear & defence projects which should keep me happy whilst I await the widespread adoption of Ducoya as the highest performing polyimide …in the world /clarkson mode
Good post. If anything, it reinforces why Victrex has a weak competitive position.
Impax Asset Management (LON:IPX) Graham I appreciate your coverage of fund managers; would it be worth comparing this to Foresight group (LON:FSG) which always seems to slip under the radar? I have held each of these in the past....
Sorry Grippie, FSG always does slip under the radar! G
Presumably people posting on Lindsell Train Investment Trust (LON:LTI) and other Investment Trusts on this thread, realise that there’s also a very good Investment Trust thread on Stockopedia, and my namesake Charles Mitchell, who set it up, now begins a new Investment Trust thread every month.
Below is the link to the latest December thread. The header article itself written by Charles includes a lot of useful links for some excellent sites for Investment Trusts and is well worth reading too.
https://www.stockopedia.com/co...
Also on the monthly Investment Trusts breads is a virtual Investment Trust portfolio which has been running for 8 years, which includes a wide range of Trusts.
Here’s the most recent virtual portfolio update with brief comments after it, including on Lindsell Train Investment Trust (LON:LTI) . But those comments were written before the Lindsell Train Investment Trust (LON:LTI) Results today.
A flat performance over the month (number33 posts the portfolio once a month) except for the big gain for JPmorgan US Smaller Companies Investment Trust (LON:JUSC) ….which I had decided to sell because too many of the holdings were very highly rated. Lucky that I didn’t get round to doing it!
Following their Results and a series of very informative posts from Charles I’m very tempted to cut the £220 loss on Augmentum Fintech(LON:AUGM) . Downside looks limited but it could be dead money for a good while. Thoughts on the wisdom or otherwise of selling Augmentum Fintech (LON:AUGM) anyone?
I’m also getting very tempted by Lindsell Train Investment Trust(LON:LTI) both for the virtual portfolio and for mine. It used to trade at a big premium that lead to warnings from Nick Train that his Trust was too expensive. For a while investors ignored that and the premium went even higher! The share peaked at £1600. Crazy. But that’s all reversed big time now with the share at a big discount and back to £722. And there’s a 7% dividend too. A snag is that very high nominal share price. Don’t know why they don’t go for a share split to attract more investors. So if buying it for the virtual portfolio it would have to be 3 shares. Again ….thoughts anyone?
And it’s been a big mistake never including Rockwood Strategic(LON:RKW. Performance is so good. Is now too late?
I wish I could spot Trusts with very high chance of fast upside to give the performance of the virtual portfolio a big lift to get it back to way outperforming the key UK indexes like it did up to 2023. It has recovered well from the dip late last year, but is still below the 2022 peak when the portfolio had doubled.
See the colourful “Relative Value Since Launch” chart for the Portfolio performance compared with FTSE100 and 250 and the DIRE AIM index.
Again has anyone spotted any Trust where that fast gain looks likely?
Finally, for any newcomers to the Investment Trust threads, this virtual portfolio which has run since 2016, is run the same way as our own portfolios with dealing charges too and full transparency on the sell and buy prices. The aim was certainly to do better than the current % annualised.
btw this virtual portfolio replaced the previous Warrant Portfolio. That portfolio was stuffed full of Investment Trust warrants and subscription shares. (Subscription shares were warrants in all but name and thanks to pressure from Lord John Lee were eligible for ISAs).
That warrant portfolio tripled in no time before falling back to finish 100% up, as sadly all the Trusts gave up on warrants and subscription shares. I SO miss them! They were a great way of getting big and fast gains from Investment Trusts, but far too few investors cottoned on to them. Hence (and for other reasons too) their demise.
Hi Ken. In my humble opinion Edinburgh Worldwide Investment Trust (LON:EWI) should/could continue on its momentum run. The shares are still half the price of their high back in 2021. Since the recent strategic update the shares have gained very nicely and the discount to NAV narrowed substantially.
Another one from Baillee Gifford is Baillie Gifford Shin Nippon (LON:BGS). It's completely out of favour with a large discount to NAV which should provide some tailwind for when it turns around. A strengthening Yen should do the trick very nicely.
Lindsell Train Investment Trust (LON:LTI) which reported today is an interesting special situation in my view. Its unique structure is worth a deeper dive to understand the potential value that may be hidden here.
The market cap is just £144m and yet net assets are £191m. 30% of the net assets are a 24% stake in the unlisted fund-management business, Lindsell Train Limited (LTL) which has suffered hideous redemptions and poor performance along with the rest of the sector. FUM at LTL has declined from £17.5b at July 2023 to £13.8b as of July 2024. However the profit margins remain above 60% (although there is a warning today that once FUM drops below £11b, which may already have happened at this rate of attrition, then margins will drop since LTL’s salary and bonus cap, which restricts salary and bonus payments to LTL employees to c.26% of LTL revenues, may be compromised.
This potential (almost certain) threat to profit margins at LTL and the reduction in dividends from LTL are already threatening the dividends of Lindsell Train Investment Trust (LON:LTI) Indeed, the dividend from LTL received in June fell 16% from last year and 7% from the December payment. Declining LTL dividends will impact the Company’s ability to maintain its dividend at the same level in 2025 without using revenue reserves to do so. Revenue reserves on 31 March 2024 were twice the annual 2024 ordinary dividend paid on 13 September 2024.
Now for the good news. LTL is valued at less than £60m and represents 30% of the NAV of the trust and yet LTL has net assets of £105m including £30m of cash! So if you deduct the cash, the remaining fund management business is valued at just £30m (less than its annual revenue of £36.5m) which seems quite harsh to put it mildly. In addition to the £30m cash, there is a further £80m of investments on the balance sheet.
Even if you were to ascribe no other value to LTL beyond the £30m of cash on its balance sheet then that would give a total NAV for the Investment Trust of £162m against a market cap of £144m.
Surely that value has to be realised at some point and in the event of a turnaround for the fund management business, then things could really get interesting.
I'd love to hear how others view this situation.
LTI don't own 100% of LT Ltd. LT Ltd has 26,660 shares, of which LTI owns 6,378, i.e. LTI only owns 24% of the LT Ltd cash and investment assets etc.
Having said that, I agree that there is an interesting special situation developing here.
Hi ISAallowance
I didn’t actually write that the Trust owned 100% of LTI.
If you read my post you’ll see that I correctly stated that they owned 24% of LTI.
Ah, OK, my bad!
Hi ISAAllowance. Actually, on second look, I think you were correct albeit perhaps not in the way that you thought. The figures I quoted for the asset value of LTL (£105m), I believe may in fact be the value of the entirety of LTL which might make the fair value of LTL on the books of LTIT (£59m) a little high. It would certainly change my investment thesis for LTIT.
I don't have time to look into in detail now but when I have more time I may post something more about it on the Investment Trust thread.
Thanks for making me check my assumptions!
Today's Paragon Banking (LON:PAG) RNS for their finals joins what seems to be a growing trend, where companies ask investors to click through to get the full detail, allowing them to use the RNS as an opportunity to simply provide a carefully crafted summary
Marston's (LON:MARS)
decent results out today , this share is very high risk with debt being waaaay over comfortable levels - management seem to think they can generate £50 mill pa of recurring free cashflow here going forward (clearly stated in outlook statement) - market cap is just over 5 * that level - If they can do that and keep it simple and pay debt down by that sum for the next 4 years whilst keeping estate in tip top order then they would perhaps be back on the straight and narrow - over the years other than via sale of brewing unit (all gone now) they have failed miserably to tackle the debt mountain and/or increase core profits as one would have hoped when they were previously investing in new outlets.
They seems to be in delivering ok stuff at the moment - whether that continues as they hope is another matter.
If they can continue reducing debt and keep estate value at current levels discount to book value would go and share would start to look more attracive.
Still ultra risky investment here but i can see why price has improved somewhat from the low level when there wasnt much sign of better times to come.
Note over the years this company has had to go cap in hand to the market numerous times - so if they are in sweet spot i for one wouldnt presume there wont be tougher times ahead at some stage.
I suspect tha Rockwood Strategic (LON:RKW) is building a position. Note that the newly appointed executive Chairman, Ken Lever is a senior independent director of Rockwood Strategic (LON:RKW).
The debt burden is nominally very high but on page 13 of the presentation slides the NAV is currently £1.03p per share and they give an illustrative future value of £1.48p based on debt amortisation and revenue growing in line with the market
As they say LFL sales were ahead in FY2024 and still ahead so far this year, it looks like that valuation is achievable
Marston's (LON:MARS)
the NAV counts for didly squat if company needs to go to shareholders cap in hand for rights issue AND at that time the shareprice has dropped down in anticipation of that fact. this is an issue for any high debt companies where market cap is well below book value (or near book value) . Great if the problems go away without dilution but nightmare if dilution is ever needed when share price is in the gutter. So whilst upside looks potentially good thats only the case if they dont ever materially dilute when one is holding the can AND the shareprice is in thee gutter at the time as that would reduce upside potential.
eg if they needed to do rights issue to reduce debt by 20% at current shareprice that would be over 50% dilution for current holders !!!
I have no worries about them needing to go cap in hand to shareholders but one does ned to be mindful of the reality if that needs to happen - just look at revolution bars as an example of how much dilution can occur if holders of debt demand shareholders put their hands in their pockets - or directors feel the need.
£50 millions per annum of free cash flow? Wow! Brilliant. By my calculations, it will only take them31 years and they will be debt free. This is a basket case and has been for many years. Bargepole stock. I have no idea why Stocko rates it so highly.
Marston's (LON:MARS)
Lord gnome
Wow! Brilliant. By my calculations, it will only take them31 years and they will be debt free
you have the debt completely wrong here - the debt figure that matters is £884 mill as confiremd by graham. ok if you straight line that thats 17 years. practicably speaking though if they can reduce debt by £50 mill per year then interests costs would soon start to drop materially pretty soon - so in theory that would probably only work out at closer to 10-12 years to fully repay. at that time with no finance fees they could easily make £100 net profit per year and be trading on multiple of current valuation. I wont disagree with anyone who says its a basket case though whilst it has sucha high debt but if the reality is they can erode debt by £50 mill pa on clean basis whilst maintaining estate your calcs are materially wide of the mark probably by something approaching 2/3 !!!
stocky debt figures are often wildy innacurate in real world terms as often there is huge amount of future rent payments included - that is the case here - plus you have used prior years debt total and they reduced debt by £300 mill so your calcs are way off track here.
Sorry, rmillaree I have only just spotted your reply. I appreciate your comments and calculations but it’s a case of if, if, if. Too many ifs to make MARS investable. I’ve been invested in the past and dodged a bullet by getting out in the 130s. I’ve watched them ever since. I don’t rate the management. Serial underachievers. I doubt they’ll clear debts or get them down to anything like a reasonable level in my lifetime. The balance sheet is a horror story and I predict a major fundraising when market conditions permit. We have differing views, but that’s what makes a market.
I’ll still enjoy my pint of Bank’s Bitter, though. (Smile)
Hi Graham. Will you be covering the Animalcare (LON:ANCR) acquisition of Randlab? It's still not in the list and it's a £62m acquisition.
Hi Andy, I'll get this added to the list, thanks. G
Animalcare (LON:ANCR) thanks for endeavouring to cover this announcement Graham. Looks a very interesting acquisition of a high quality asset (near 50% EBITDA margin) with potential for “at least 20%” earnings accretion in FY25. Two questions: why is the acquisition multiple so low at only 10x? And why has the market only shrugged off the discounted bookbuild but not pushed the shares higher? Broker hasn’t issued revised numbers yet which might explain some of the sluggish investor response.
I agree that it does appear to be a very muted response to a positive deal for Animalcare (LON:ANCR). In fact, the share price has been pretty unresponsive for a while now given the impressive prices achieved when selling the Identicare business and the stake in STEM. I think the Company has been making good progress in the past year or so (and I hold).
Perhaps it is fair to say that the EV/Sales multiple for Randlab looks a bit punchy and that the deal is not without its risks given the geographical location of the business (Australia). However, if the margins at Randlab are sustainable and the business integrates successfully it could be very promising.
Yes it does appear to be a muted response. I guess there's a bit of a headwind with the placing at 5% discount and what will be a 10% dilution. I have faith in Jenny Winter, she has done a great job so far in getting the balance sheet to a much stronger position since the disastrous reverse takeover of Ecuphar in 2017. Market may also be just a bit cautious given that history.
ANCR will slip into the backlog for tomorrow, couldn't make it happen today. Sorry about that. G
No worries Graham. Tomorrow would still be much appreciated.
Thanks Graham. Appreciate that
If members have time the report today from LTIT is an educational read on markets shares and the ups and downs of a fund manager's life. We hold.
LTIT? Sorry JASVFS I don’t recognise the epic, can you enlighten me please.
I presume it's Lindsell Train Investment Trust (LON:LTI) half year report published today.
Apology for the late reply jonno, only just got back online. I was referring to Lindsell Train Investment Trust and I'm going through the interesting observations on it from members. I've mentioned before here my friend Maynard Paton covered it for Share-Pad in great depth, it's on his website.
Hi Jasvfs, I used to hold Lindsell Train Investment Trust (LON:LTI) in my income fund but got fed up with his over exposure to underperforming alcohol businesses, his inability to change and adapt the portfolio and his continued collection of millions of pounds in fees for doing a pretty rubbish job.
But that's just what I think of his performance, what are your thoughts, what am i missing?
I agree. they seem to get paid quite a lot for sitting on the sidelines and watching demographic shifts in alcohol consumption. Without analysing details -it's interesting to me that my teenage children don't drink, their friends 100% drink less than my generation did; and in convenience stores and supermarkets there are ALOT of cheaper dupe brands that taste the same (including store own label). I could be wrong but like trepanning, snuff and smoking before I think alcohol brands are just less cool with the kidz. Cinzano anyone?
We are fairly recent holders Burnt Onions but as I've just mentioned to jonno, after reading Maynard Paton's in depth analysis of (LON:LTI) I thought the value on offer around the current price seemed good, I still do. Have you read today's comments on their own performance in the RNS?
A fine trading update from Greencore (LON:GNC) . Profits raised substantially. It makes a change at the moment to see a share price going up on a positive trading update.
Another positive-sounding RNS from Gulf Marine Services (LON:GMS) but with no detail of the new contract, making it rather valueless.
Morning doctor dave,
Re. the contract award at Gulf Marine Services (LON:GMS), broker Zeus has issued an updated forecast this morning leaving forecasts unchanged.
So my assumption is that as with other recent updates from GMS, this is simply business as usual and within current expectations.
Regards,
Roland
Ah thanks Roland!
Diales (LON:DIAL) - "Results ahead of expectations" (and a reminder that we are hosting a webinar with management tomorrow morning at 11am: https://www.equitydevelopment....)
FY24 was the first year in a four-year transformation process for Diales. Profitability was ahead of expectations, notwithstanding staffing related issues in North America and two customers falling into administration during the year. The move to a hub-and-spoke delivery model has increased utilisation levels further, with the new ERP software delivering ‘real-time’ information and the scope for greater efficiencies. With an expected easing of economic headwinds and reduced political uncertainty, plus a growing pipeline of opportunities, we anticipate increased expert headcount and rising utilisation to drive further growth and margin expansion within the forecast period. The net cash of £4.3m gives the Board options, not least possible M&A and a completion of the share buyback programme.
Net cash / share currently amounts to 7.9p or 29.5% of the market capitalisation, thereby underpinning the sector-leading yield and current share price. The shares trade at a marked discount to its peers and the introduction of conservative estimates leads us to increase our fair value to 47p / share, from 40p previously, which represents a healthy premium to the current price.
Full research note here: https://www.equitydevelopment.co.uk/research/results-ahead-of-expectations
Facilities by ADF, the leading provider of premium serviced production facilities to the UK film and high-end television industry ("HETV"), announces that, on 2 December 2024, Marsden Proctor, Chief Executive Officer, purchased 79,947 ordinary shares of 1p each ("Ordinary Shares") at a price of 31.60 pence per Ordinary Share.
Following the purchase, Marsden Proctor now has a beneficial interest in 1,479,947 Ordinary Shares, representing 1.37 per cent. of the Company's issued ordinary share capital.
Looks like the observation by @planetx last week about huge increase in film set activity recently is drawing in director buys.
Harwood Capital also upped holdings by 955k early November.
Facilities by ADF (LON:ADF)
Octopus also increased their stake on the same day 12-11-24 by 2.0m ?
I hold, as of yesterday.
Graham.
On Beach group (LON:OTB) - impressive results. No one was expecting a buyback!
Financial overview
· Record TTV for the third consecutive year, up 15% to £1.2bn (FY23: £1.0bn).
· Revenue increased 14% to £128.2m (FY23: £112.1m).
· Further margin improvement with B2C Adjusted EBITDA margin at 31.7% (FY23: 30.0%).
· Adjusted profit before tax increased 25% to £31.0m1 (FY23: £24.8m).
· Group profit before tax increased 84% to £26.5m (FY23: £14.4m).
· Group remains in a strong financial position with cash, excluding amounts held in trust, of £96.2m (30 September 2023: £75.8m).
· FY24 final dividend of 2.1p per share, full year 3.0p per share, representing 25% of net earnings, in line with capital allocation policy.
· Buyback of up to £25m announced, reflecting Board's confidence in the strategy and business model.
https://newsfile.refinitiv.com...
Outlook looks good too:
"- FY24 growth has continued into the new financial year with YTD TTV up 14% and bookings growth of 15% versus the prior year.
- Our forward order book is at record levels, Group Winter '24 YTD bookings currently +25%.
- We approach our key booking period in Q2 with significant momentum.
- Current trends and strategy give us confidence that Summer '25 will be significantly ahead of Summer '24.
- The Board is confident in delivering FY25 Adjusted PBT in line with the Company-compiled consensus estimate of £37.9m."
Stockopedia currently showing a FY25 PE of 9.71*, with a Market Cap of £287m and it looks like a material amount of such in their own Cash and with a £25m Buyback announced.
Impressive indeed!