Daily Stock Market Report (Tue 6th October 2026) - CKN, SNX, CAPD, TEP, CLBS

Good morning. Overnight news is limited but one story that could gradually impact some of our stocks is the rising cost of corporate debt, especially for sub-investment grade borrowers.
The rising cost of US government debt and the tidal wave of long-term debt being issued by AI borrowers is seen as pushing up the cost of debt for other corporate borrowers. They are reportedly issuing more shorter-dated debt at the moment, in an effort to manage costs and avoid locking in higher rates.
This could lead to both higher finance costs and greater refinancing risk if borrowing costs don’t fall back as hoped for.
BT/TalkTalk: we didn’t cover yesterday’s story on the acquisition of TalkTalk by BT (LON:BT.A) , but I think it’s worth highlighting that this looks to be a very good deal for the UK’s incumbent operator, in my view. By my reckoning, adding TalkTalk customers will increase BT’s share of the retail market by around 15% to c.35%, while also providing much-needed top-line growth.
We’re told that TalkTalk generated £1.2bn of revenue over the last year. It seems reasonable to assume BT should be able to generate cost savings by bringing the business onto its own systems. Assuming the company can generate an operating margin of c.10% from the TalkTalk revenue, then the £400m cash cost of this deal looks excellent value to me.
The caveat is that the acquisition needs regulatory approval, which might normally be tough to secure for a combination that evidently reduces competition. But with TalkTalk in administration and seemingly about to fail, BT appears to have unusual leverage in this situation. Reports suggest that a prompt approval is expected.
Overnight market movements:
The FTSE is up 0.4% at 10,536
S&P 500 is up 0.1% at 7,784
Brent crude (December) is up 0.4% at $100.70/bbl
Gold is down 0.1% at $4,117/oz
Bitcoin is down 0.3% at $85,494
Spreadsheet accompanying this report: link.
Today's report is now complete.
Ed Sheldon joins me (Roland) today.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Informa (LON:INF) (£10.8bn | SR53) | Growth, Focus and International Expansion & Placing Announcement & Retail Offer | Informa plans to focus more closely on its core B2B business and is acquiring events operator Clarion for £2.24bn. Informa will now separate its Academic business. A placing of c.£940m will be used to help fund the purchase of Clarion. | |
Clarkson (LON:CKN) (£1.56bn | SR77) | Trading in August and September has been “very strong” due to ongoing “geopolitical complexity”. The performance of the Broking and Financial divisions has been ahead of expectations. While the trading environment “remains very volatile”, full-year underlying pre-tax profit is now expected to be not less than £135m (Panmure Liberum previously had PBT at £114m). | AMBER/GREEN = (Roland - I hold) Today’s upgrade is equivalent to a 19% increase to 2026 profit expectations, according to broker Panmure Liberum. I see this as a reflection of truly exceptional conditions in shipping at the moment: demand for oil tankers in particular is at record levels. This situation cannot last forever, of course, and I am tempted to turn neutral after such a strong run. However, strong earnings momentum and the lack of any apparent resolution to the situation in the Middle East means I’m going to leave my broadly-positive view unchanged for a little longer yet. | |
Telecom Plus (LON:TEP) (£634m | SR72) | Multiservice organic customer numbers rose by 11% to c.526k in H1, ahead of the 10%+ target. Full-year guidance for adj pre-tax profit of £80-90m is unchanged, with expected 85% H2 weighting reiterated. | AMBER = (Ed S) | |
Avacta (LON:AVCT) (£340m | SRN/A) | Raised £12.5m at 68p, a discount of 5.6% to the closing mid-market price of 72p on 29 Sept 26. | ||
Capital (LON:CAPD) (£269m | SR90) | Capital Enters Australian Drilling Market and Raises Revenue Guidance | Completed acquisition of Metres Down Under Pty Ltd, a “leading specialist underground drilling company” in Western Australia. Total consideration of up to c.US$16m. MDU generated US$6m of EBITDA over the 12 months to 30 Sept 26. Capital raises 2026 revenue guidance to $435-455m (prev. $430-450m) to reflect consolidation of MDU. | AMBER/GREEN = (Roland) This looks like a logical and fairly priced bolt-on acquisition to me. It increases Capital’s exposure to its largest client (AngloGold Ashanti) and may provide new growth opportunities in a key mining region where the company already has relationships. Investors in this business need to consider the underlying commodity price risk, but on balance I share the StockRanks’ view of Capital as a potential Contrarian play that offers an attractive mix of quality and value. |
B.P. Marsh & Partners (LON:BPM) (£235m | SR65) | Acquired a 30% equity interest in Dauntless for a “nominal consideration”. As part of the transaction, BPM will provide a £2m loan facility. Dauntless specialises in marine hull underwriting “focused on niche, brown water, older and distressed tonnage”. | ||
| Kenmare Resources (LON:KMR) (£162m | SR33) | Statement regarding possible offer | Has received a non-binding proposal from International Resources Holdings RSC Ltd regarding a possible cash offer for Kenmare. Talks with IRH are ongoing and there’s no certainty that a firm offer will be made. | |
Andrada Mining (LON:ATM) (£145m | SR38) | This latest batch of data confirms substantial down-dip continuity and structural thickening of the targeted pegmatite swarms. The results demonstrate high-grade lithium alongside pervasive tin (Sn) and tantalum (Ta) mineralisation. | ||
East Star Resources (LON:EST) (£54m | SR20) | Drilling approval for Licence 3631 received and drill rig mobilised, with drilling operations commencing on 5 Oct 26 at no cost to East Star. | ||
Poolbeg Pharma (LON:POLB) (£53m | SR31) | The patent provides protection for POLB 001 and the use of any p38 MAP kinase inhibitor for the prevention of cancer immunotherapy-associated Cytokine Release Syndrome ("CRS") in South Korea with a default expiry of 2044. | ||
Taylor Maritime (LON:TMI) (£53m | SR92) | Has completed sale of three handysize vessels generating gross proceeds of c.$48.6m. The company is in the process of selling the last vessel in its fleet. A further $45m return of capital is now planned for November 2026. | ||
Fairview International (LON:FIL) (£43m | SR18) | Revenue is expected to be approximately £5.9m for the year ended 30 June 2026, up approximately 11% from £5.3m in the prior year. The company has continued to manage operating and administrative costs carefully, leading to improved operating margins. | ||
Celebrus Technologies (LON:CLBS) (£36m | SR47) | Total revenue for the period expected to be approximately $9.2m (H1 FY26: $10.4m) due to lower third-party product revenues. Adjusted loss before tax is expected to be approximately $1.3m (H1 FY26: loss of $1.4m). Results for FY27 are now expected to be below current market expectations, with total revenue expected to be between $20.0m and $20.5m (FY26: $23.6m), and adjusted loss before tax expected to be between $2.8m and $3.0m (FY26: profit of $0.2m ). | PROFIT WARNING (AMBER/RED =) (Roland) This is a fairly serious warning, with c.15% cut from FY27 revenue guidance and an increase in expected losses. While broker forecasts previously suggested a return to profitability in FY28, this has now been pushed back to (at least) FY29. The underlying cause of today's downgrade appears to be poor execution in both sales and operations. That’s disappointing, but not necessarily beyond fixing. The group’s large net cash position means it has plenty of breathing room and recurring revenue from existing customers remains broadly stable. Given the size of this warning I’m staying cautious today, but I might consider turning neutral if Celebrus can start to deliver on guidance. | |
Georgina Energy (LON:GEX) (£32m | SR18) | Approvals for preliminary site inspections currently under way with civil engineering access and site evaluation planned to commence 18 October 2026. | ||
Synectics (LON:SNX) (£31m | SR63) | FY26 revenue is expected to be in line with current market expectations, with adjusted EBITDA at the top end of the previously communicated range of £3.7m to £4.1m. This reflects stronger margins and good performance across the group. | AMBER ↑ (Ed S) | |
Medpal AI (LON:MPAL) (£31m | SR10) | September Trading Update & Publication of Circular to Shareholders | New Health revenue of over £2.7m in September 2026, up approx. 50% on £1.8m in August 2026, from over 22,600 orders. Group annualised revenue run rate is now over £38m, up from over £35m reported on 21 September 2026 and approximately £28m for August 2026. The company has opened discussions with UK clearing banks regarding a working capital facility secured on its receivables. | |
Gelion (LON:GELN) (£30m | SR4) | The company has entered into a Material Transfer Agreement with a top 15 global automotive original equipment manufacturer to assess the applicability of Gelion's NES™ cathode platform across a range of future electric vehicle (EV) battery technologies. |
Roland's Section
Clarkson (LON:CKN)
Up 6.5% at 5,380p (£1.67bn) - Trading Update - Roland - AMBER/GREEN =
(At the time of publication, Roland has a long position in CKN)
Market-leading shipbroker Clarkson reported a 56% increase in underlying pre-tax profit in H1, with gains driven by the impact of the situation in the Middle East.
Today’s trading update makes it clear that market conditions have remained very favourable in the early part of H2 (my emphasis):
Clarksons' trading in August and September has been very strong. The ongoing geopolitical complexity has created further volatility across commodity and freight markets, accordingly in some areas we have seen record freight rates and this has also then passed through to asset prices.
I would guess this is mainly referring to conditions in the oil tanker market. Demand for secondhand supertankers has soared as shipowners and Gulf oil producers have (respectively) rushed to take advantage of record freight rates and secure dedicated capacity to shuttle oil through the Strait of Hormuz. Reports suggest that ageing tankers are being sold for more than new builds, such is the premium being placed on immediate availability.
Unsurprisingly, Clarkson says that both its Broking division and its Financial division (an investment bank for shipping) have been performing ahead of expectations:
The Broking division has delivered revenues significantly ahead of previous expectations, while also adding to the forward order book. Alongside this, the Financial division has executed a number of transactions, resulting in performance also being significantly up on expectations.
Outlook & upgraded guidance:
Consequently, whilst this trading environment remains very volatile the Board now expects underlying profit before tax for the full year to 31 December 2026 to be not less than £135m.
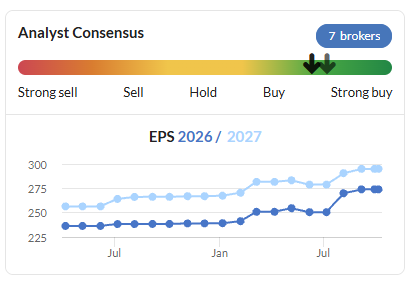
Updated broker estimates: with thanks to Panmure Liberum for publishing on Research Tree, I can see that Clarkson’s 2026 adjusted pre-tax profit was previously expected to be around £114m, so today’s upgrade is equivalent to a 19% rise in profit guidance.
Panmure is “wary of extrapolating the current strength in markets” despite additions to Clarkson’s forward order book, so has left EPS estimates for outer years largely unchanged today:
FY26E adj EPS: 332.2p (+19% vs 279.1p previously)
FY27E adj EPS: 310.0p (+1% vs 306.4p previously)
FY28E adj EPS: 326.3p (+1%)
These upgrades extend an impressive run of upgrades over the last year:
Roland’s view
When I commented on small-cap shipbroker Braemar’s half-year results recently, I said that my main concern was that the numbers weren’t stronger, given the exceptional market conditions in shipping at the moment.
Today’s update from Clarkson seems to support this view. It’s clear that for brokers with the right scale and market presence, conditions are very favourable indeed right now.
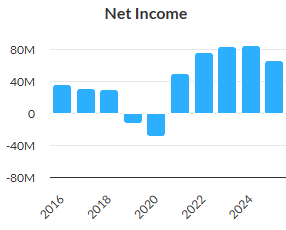
I don’t know how long the current situation will last, but I do think it’s inevitable that conditions will weaken at some point. I think it’s reasonable to believe we could see a sharp decline in profits at some point.
As a long-term shareholder, I am relatively relaxed about the potential downside, but I do think it’s worth emphasising how exceptional current profits may be:
Clarkson’s share price dropped c.15% in May/June when it looked like the US-Iran ceasefire might hold. If a more durable settlement is eventually reached, then I’d be prepared for a somewhat larger correction.
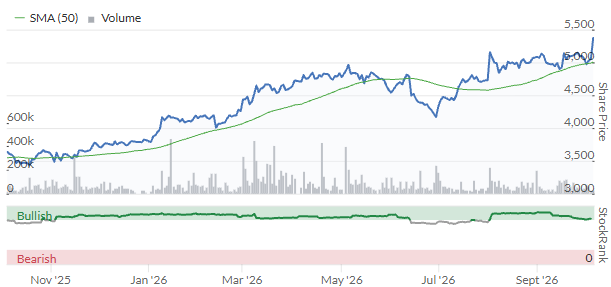
I haven’t taken any profits on my Clarkson position yet, but I haven’t ruled out doing so at some point.
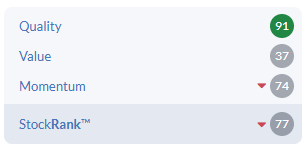
The StockRanks view this as a High Flyer, with a high QualityRank but declining value and momentum scores. I think that’s probably a fair view of the situation, although today’s upgrade may provide a boost to momentum:
EPS forecasts were upgraded by 6% in August and have been lifted by 19% today. While I’m tempted to turn neutral, I think the strength of earnings momentum here means it’s fair to stay at AMBER/GREEN for a little longer yet.
Capital (LON:CAPD)
Up 6.3% at 127p (£283m) - Capital Enters Australian Market & Raises Guidance - Roland - AMBER/GREEN =
Investors have given today’s acquisition news from mining services company Capital a positive reception.
Here are the key points:
Capital is acquiring Metres Down Under Pty Ltd (MDU), “a leading specialist underground drilling company” headquartered in Kalgoorlie-Boulder, Western Australia.
MDU “establishes Capital’s operating presence in the Australian drilling market” and complements the company’s existing corporate presence in Perth WA (around 600km away from Kalgoorlie).
Extends Capital’s relationship with AngloGold Ashanti, an important existing client.
This deal positions Capital as a leading underground reverse circulation drilling specialist.
Consideration: Capital will pay up to USD16m for MDU, with an upfront payment of $11m and a milestone-based earn-out of up to $5m. This earn-out is apparently based on the retention of two key contracts.
According to broker Panmure Liberum, Capital will also assume some c.$5m of debt from MDU.
Valuation: MDU generated $25m of revenue and adj EBITDA of c.$6m during the 12 months to 30 September 2026. This implies a purchase multiple of around 3.5x EBITDA, including the earn-outs.
That doesn’t seem too demanding and should be immediately accretive to Capital’s earnings. The caveat to this, of course, is that MDU’s recent profits might represent a peak figure.
Outlook: today’s RNS included the magic words “Raises Guidance” in its title. However, the only change to Capital’s full-year guidance in today’s RNS is a revision to revenue to reflect the expected contribution from MDU:
Updated 2026 revenue guidance: $435 to $455m (Previously $430-450m)
Revenue guidance for MSALABS and 2026 capex plans are unchanged.
Broker estimates: with thanks once more to Panmure Liberum and Research Tree, we have access to updated forecasts today. Changes are modest but positive:
FY26E revenue: $444.9m (+1.1% vs $439.9m previously)
FY26E adj EPS: 14.6c (+3.6% vs 14.1c previously)
Outer year earnings are not expected to benefit due to the impact of higher depreciation and financing costs – Capital's net debt will rise as a result of this deal:
FY27E adj EPS: 19.6c (unch)
FY28E adj EPS: 21.9c (-3.3% vs 21.9c previously)
Roland’s view
We have generally had a broadly positive view of Capital, most recently here. The company benefits from owner-management and has been a beneficiary of the gold mining boom.
This acquisition appears to be a logical bolt-on deal that will add market share and provide new opportunities for growth.
One potential risk worth monitoring is that Capital’s customer concentration may have increased as a result of this. In today’s note, Panmure notes that AngloGold will now provide c.20% of group revenue.
Another factor worth remembering with this business is that Capital also speculates in the gold market through its ownership of equity stakes in a small number of miners. The company’s investment portfolio was valued at $116.5m at the end of June 2026. Capital should clearly be an expert investor in this sector, but that’s not necessarily a guarantee of future realised gains.
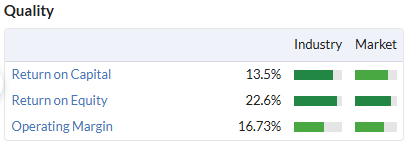
Leaving these niggles aside, I think Capital remains a reasonably priced and decent business. While it’s fairly capital intensive, the stock’s price-to-book value of 0.9x looks attractive relative to recent profitability:
The share price has fallen to reflect the decline in the price of gold from the record levels seen earlier this year:
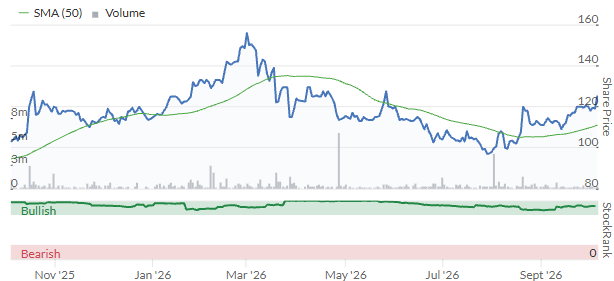
On a forward P/E of 9, I think Capital could be worth a closer look at this level as a pick-and-shovel play on the gold sector.
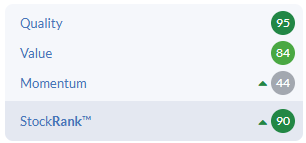
The StockRanks are also positive, with Contrarian styling. Strong quality and value scores are paired with an improving MomentumRank – potentially a promising setup:
I have a longstanding positive view of this business, but I’m staying AMBER/GREEN today to reflect the broader commodity price risk here.
Celebrus Technologies (LON:CLBS)
Down 37% at 60p (£23m) - Half Year Trading Update and Revised FY27 Guidance - Roland - PROFIT WARNING (AMBER/RED =)
Commiserations to holders here this morning – this is a big profit warning, with forecasts 15% wiped off revenue forecasts and the timeline for a return to profit pushed out by another year.
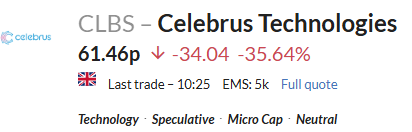
We turned AMBER/RED on this provider of customer data analysts software in April, when Celebrus warned on profits previously. Trading appears to have worsened since then, unfortunately.
Half-year update: key points
Today’s half-year update covers the six months to 30 September 2026.
H1 revenue expected to be $9.2m (H1 26: $10.4m)
Annual Recurring Revenue (ARR) fell by 2% to $14.7m in H1
H1 adj pre-tax loss expected to be $1.3m (H1 26: loss of $1.4m)
Cash balance at 30 Sept: $22.3m (31 March 26: $32.5m, 30 Sept 25: $27.3m)
Revenue: the decline in H1 revenue reflects the continuing evolution of Celebrus’s business model away from re-selling third-party software. As such, I think this is potentially less of a concern than the other issues highlighted today:
The reduction in total revenue reflected “lower third-party revenues”
Software Revenue (i.e. own product) up 13% to $8.9m
ARR: a breakdown of the movements in ARR reveals a self-inflicted loss:
The net $0.3m reduction in ARR reflects a $0.9m impact from the loss of a single customer. This was only partially offset by wins and upsells totalling $0.6m.
The lost customer executed a break clause at the end of year one of a three-year contract. Celebrus admits that “we lost this customer due to imperfect execution on our part”
Cash: the company’s year end is normally a peak for cash flow. But the cash drawdown in H1 appears to have been relatively high, at $10.2m. The corresponding figure for last year was $4.2m.
Outlook & Broker Estimates
Celebrus says it has “seen improvement” from changes made to its sales and marketing operations, but the company notes that “our average deal cycle still sits at around eight months”.
Sales performance appears to have been below expectations in H1:
However, while the number of pipeline opportunities continues to grow, our rate of closing new business has been slower than we had hoped.
When combined with the customer loss mentioned earlier, this situation is expected to have a severe knock-on effect on the remainder of the year:
Following the Board's review of the period and of the second half pipeline, results for FY27 are now expected to be below current market expectations
To its credit, the company provides clear guidance on revised revenue and profit expectations (even though the numbers are fairly dire):
FY27 total revenue expected to be $20 to $20.5m (previous consensus $23.7m)
FY27 adjusted loss before tax expected to be $2.8m to $3.0m (previous consensus: pre-tax loss of $0.9m)
House broker Cavendish has updated its FY27 forecasts accordingly:
Revenue: $20.0m (-15% vs $23.5m previously)
Adj pre-tax loss: -$3.5m (previously -$1.4m)
Free cash flow: -$5.0m (previously +$1.5m)
Net cash: $23.9m (previously $30.5m)
Celebrus was expected to return to profitability in FY28, but Cavendish now expects to see an FY28 pre-tax loss of $2.1m and a further reduction in net cash.
Roland’s view
Mark was AMBER/RED on this business in April following the previous profit warning:
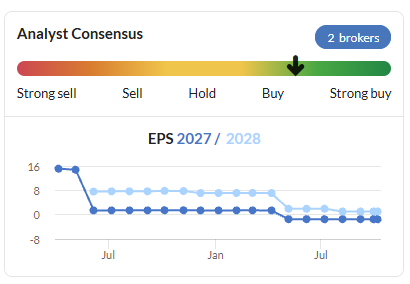
Celebrus shares have now fallen by c.80% from the all-time highs seen five years ago:
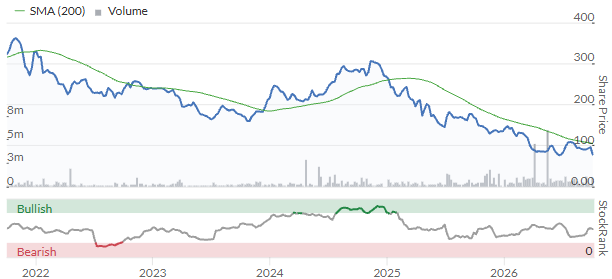
Today’s downgrade is fairly serious. The company’s explanation of the underlying problems suggest that it execution has been poor in both sales and operations.
However, revenue is still expected to be c.$20m this year and I am encouraged by the underlying growth in software revenues.
There’s still a very material net cash position too. This covers around 70% of today’s reduced market cap and provides breathing room for the company to fix the issues it's identified and execute a turnaround.
I’d need to do more research into the company’s products and client base to take a stronger view, but as far as I can see there is no reason why Celebrus shouldn’t be able to recover.
I’m going to leave our AMBER/RED view unchanged today, but I might be inclined to turn neutral if the company can start to deliver on revised guidance.
Ed S's Section
Synectics (LON:SNX)
Up 11% at 192p (£31m) - Trading Update - Ed S - AMBER ↑
Synectics – which provides advanced security and surveillance solutions that help protect people, property and assets globally – has today posted a trading update for the financial year ending 30 November. It tells us:
FY26 revenue is expected to be in line with current market expectations, with adjusted EBITDA at the top end of the previously communicated range of £3.7 million to £4.1 million.
This reflects stronger margins and good performance across the group demonstrating the resilience of the diversified business and the early benefits of changes being implemented under the group’s ‘5P’ strategy.
There was uncertainty around the timing and conversion of energy market opportunities, particularly in the Middle East, but these opportunities remain active and are expected to extend into FY27 with the group continuing to hold a significant pipeline in the sector and encouraging signs of progression.
The group continues to make good progress in implementing its strategy, with the commercial, product and operational capabilities required to support more scalable, sustainable growth increasingly embedded across the business.
The Board is encouraged by the strong progress being made in the strategy execution, and the early evidence of benefits emerging. It remains confident in the group’s growth opportunity as it enters FY27.
Over the past year we have made deliberate changes to how we develop our products, work with partners, target our priority markets and operate the business. There is still plenty to do, but many of the foundations are now in place and we are moving increasingly from building those capabilities to executing against them, and we are beginning to see early evidence of the benefits.
“We enter FY27 with a significant Energy pipeline alongside growing opportunities across the wider critical security markets we serve. Our focus is on converting those opportunities, increasing the pace of execution and continuing to build a larger, more scalable business, with the benefits of the changes we are making increasingly reflected in our financial performance.
Ed S’s view:
2026 has been a challenging year for shareholders here.
In early March, SNX fell 16% after the company posted its FY25 full-year results and advised that FY26 would be a focused transitional investment year in which revenue would fall 10% year on year.
In mid-May, the stock fell another 15% on the back of an AGM trading update in which the company advised that some customers in the energy sector had delayed projects and infrastructure investment and that revenue and profitability for the full year would be weighted towards the second half of the year.
Then, in August, it fell 12% after the company posted a significant year-on-year drop in revenue (£22.2 million vs £35.5 million for H1 2025) and adjusted EBITDA (£1.0 million vs £4.2 million for H1 2025) in its interim results.
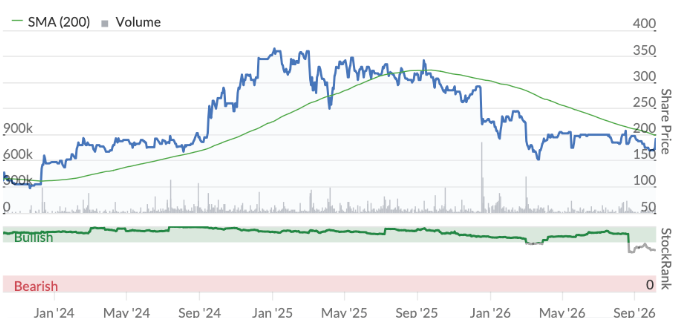
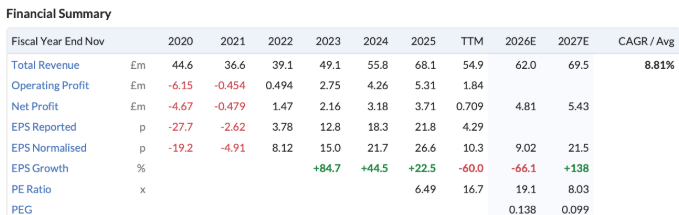
Today, we have a decent bounce (share price is +11%) thanks to news that FY26 revenue is expected to be in line with current market expectations (I see £62m) and adjusted EBITDA is likely to be at the top end of the previously communicated range of £3.7 million to £4.1 million.
The question is – is this the start of a turnaround? Are we seeing the green shoots of a recovery?
I think there are reasons to be cautiously optimistic. The fact that revenue is expected to be in line and adjusted EBITDA is expected to be at the top end of the previously communicated range (despite a soft H1 and the weakness in energy) is encouraging and suggests that the company’s ‘5P’ strategy – which is focused on Product, Partner-led, Market Presence, Productivity, and People – is perhaps beginning to pay off.
Looking ahead, the company believes this strategy will expand its share in a c.£2bn market in the years ahead and underpin ‘accelerated growth’ from FY27 onwards (along with stronger operational leverage). Note that analysts currently expect revenue to jump 12% next financial year to £69.5m.
On the downside, today’s update mentions that there is still uncertainty around the timing and conversion of energy market opportunities. However, these opportunities remain active and are expected to extend into FY27 with the group continuing to hold a ‘significant pipeline’ in the sector.
Taking a step back and looking at the bigger picture, there are plenty of reasons to be bullish, in my view. In its H1 results, the company pointed to the following tailwinds:
Increasing investment in critical infrastructure, transport, and energy resilience
Rising global security threats and increasing focus on protecting critical assets
Growing regulatory, cybersecurity, and compliance requirements
Increasing adoption of AI, automation, and operational intelligence to improve security and operational efficiency
Convergence of physical security, IT, and operational technology driving demand for integrated security platforms
Note that on the AI front, Synectics recently launched Synergy SEARCH, which allows operators to search large volumes of footage using everyday language to describe the people, vehicles, objects or activity they are looking for. This technology has been successfully deployed with its first customer and is now available through an early access programme as part of the latest release of Synectics' proprietary Synergy platform.
Turning to the financials, the balance sheet is strong. At the end of May, the group had net cash of £10.5 million with no bank debt.
As for the valuation, if we take brokers’ earnings forecast for FY27 (not that far off now) of 21.5p per share, we get a forward-looking P/E ratio of just eight. Now, I certainly wouldn’t rely on that forecast, but if we do start to see some operational leverage from the 5P strategy, the stock could start to look quite cheap (interestingly the Stockopedia system classifies it as a ‘Contrarian’ stock).
Given today’s update, I’m going to upgrade the stock from AMBER/RED to AMBER. There is still uncertainty around the energy market in the near term, however, taking a medium- to long-term view, I am cautiously optimistic.
Telecom Plus (LON:TEP)
Up 4% at 857p (£634m) - H1 trading update and notice of results - Ed S - AMBER =
Telecom Plus (trading as Utility Warehouse) – which offers an integrated platform for subscription-style essential household services such as energy, broadband, mobile, and insurance – has issued a trading update for the six months ended 30 September 2026.
Highlights:
Multiservice organic customer numbers increased at an annualised rate of over 11% to c.526k (FY26: c.498k), ahead of the 10%+ target for the full year and c.3x the rate delivered in FY26.
Single service organic customers grew at an annualised rate of c.8.5% to c.791k (FY26: c.759k), resulting in total organic customers increasing at an annualised rate of c.9.7% to c.1.32m (FY26: c.1.26m).
Monthly active Partners in H1 averaged c.4.9k, an increase of around 15% from c.4.2k in the second half of FY26, and comfortably ahead of the group’s target to increase monthly active Partners by 10%+ over the course of FY27.
Total Partner numbers increased to over 88k at the end of September, up from c.77k at the end of FY26.
In-life cross-selling programme resulted in c.25k additional core services cross-sold in H1. On track to achieve FY27 target of 50k core services cross-sold.
Insurance services returned to growth in H1, for the first time since H1 FY25, increasing modestly to c.114k (FY26: c.113k). The company remains on track to launch a motor insurance product in H2 of FY27.
Shareholder distributions:
As at 2 October 2026 its £40m share buyback programme had resulted in c.3.8m shares being purchased at an average price of 821.24p per share, with c.£9.0m remaining to be deployed over the coming months.
Expects total distributions to shareholders for FY27 will remain weighted towards H2, with a c.40%/60% split between the interim and final distributions. At current share price levels, half of this would be via an extension to the share buyback programme, and the remainder by way of dividend.
Outlook:
Reiterates full-year guidance for adjusted profit before tax of between £80m to £90m for FY27.
As previously communicated, for FY27, it expects adjusted profit before tax to be weighted approximately 15%/85% between H1 and H2 respectively.
Expects year-end net debt to adjusted EBITDA for FY27 of around 1.5x before reducing to around 1.0x over the course of the five-year plan.
"Our first half performance builds on the encouraging start to FY27 that we reported at our AGM in August, with growing momentum across all aspects of the business. Multiservice customer growth has been strong, and well ahead of the level we delivered in FY26, driven by the investment we are making in our customer proposition and underpinned by record levels of activity across our Partner network.”
“We are building the foundations for sustained double-digit multiservice customer growth with commensurately higher quality earnings, and are confident in meeting our full year guidance for FY27 as we progress toward our long-term goal of £175 million of adjusted profit before tax by FY31.”
Ed S’s view:
Back in June, shares in Telecom Plus plunged 26% after the company said that it will invest around £55 million annually over the next five years in an effort to double its high-value multi-service customer base, warning that the spending will slash its near-term profits. At the time, management noted that competitive dynamics in some of its core market verticals had led to the decision to invest more heavily than previously anticipated.
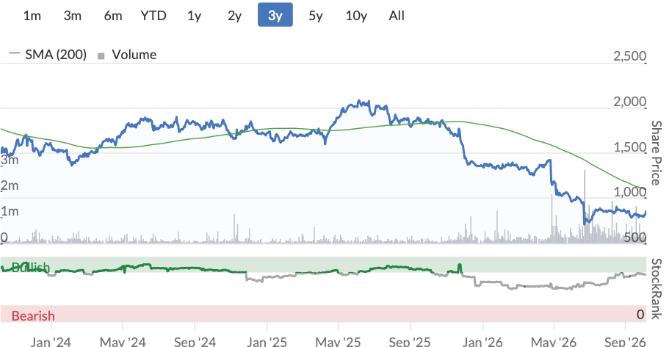
When it made that announcement, the company said that it was targeting adjusted pre-tax profit for the year ending March 2027 of between £80 million and £90 million, down from £132.2 million in fiscal 2026. Today, it reiterates that full-year guidance, which is good news.
Also encouraging is the growth in customer numbers in H1. Multiservice organic customer numbers increased at an annualised rate of over 11% – ahead of the group’s annual 10% target – while single service organic customers grew at an annualised rate of c.8.5%.
On the downside, management still expects full-year adjusted PBT to be weighted approximately 15%/85% between H1 and H2 respectively. While you’d expect winter to drive performance here, that’s a large split and it adds risk in the near term.
Taking a longer-term view, Telecom Plus is targeting more than 1 million multiservice customers by FY31, up from around 526k currently. Given that these customers generate higher margins for the company and typically stay nearly twice as long as single-service users, its revenues and earnings could strengthen significantly if it can execute here (buybacks could also support earnings).
Note that by FY31, the company expects adjusted pre-tax profit of £175 million. That represents a CAGR of around 20% from the mid-point of this year’s guidance.
Looking beyond the numbers at the broader business model, I like the strategy of offering a range of different services under one account. Ultimately, the company is trying to solve an administration pain point and make consumers’ lives easier (it has a 4.2 rating on Trustpilot which is decent).
Offering a range of different services under one package could also potentially protect against the risk of agentic AI-powered customer churn. There’s a theory that AI agents – like Meta’s Muse – are going to empower customers to seamlessly compare providers and switch to the lowest cost providers with minimal effort.
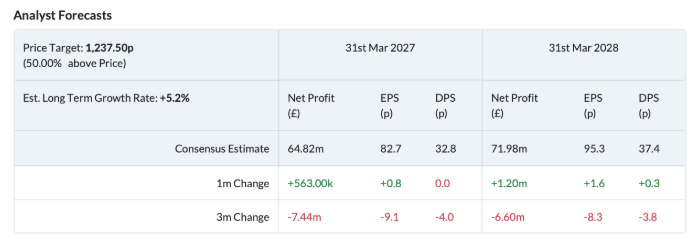
In terms of the valuation, the P/E ratio is relatively undemanding at present. After taking their forecasts down several months ago, analysts now expect 82.7p per share in earnings for the current financial year, giving us a P/E ratio of about 10.
The dividend yield is expected to be around 4%. That’s based on a projected payout of 32.8p per share.
Back in August, Roland upgraded Telecom Plus to an AMBER rating. I’m going to leave it on AMBER for now. In the short term, there are some risks around the H1/H2 profitability split. Taking a medium- to long-term view, however, there are definitely reasons to be optimistic.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

24 comments
Likely not too relevant for lots of investors here but SAP SE (NYQ:SAP) have announced today that they are set to acquire Techwolf. I think this is a brilliant move to allow SAP to get into the workforce data and skills space. Typically clients buy SAP for the financial and PLM side.
Would assume this will impact Workday, Cornerstone, Pearson and any other ERP or skills providers. Not seen the deal price yet but can imagine the market liking this one!
Breaking news on Asos (LON:ASC) .... potential hack and customer data loss situation.
I work in this marketing/customer data space.
It looks like the hack was two systems. One definitely contains customer personal data. The other very likely, along with sensitive commercial data for their eCommerce store.
The two systems are Bloomreach and Snowflake. So likely those companies shares will suffer too (are they listed in the USA?). Unless the mechanism was a breach of user credentials rather than security of either platform.
Worse is that ASOS has extensive European operations, and the regime there for customer data breaches are higher than here in the UK.... could be multiple fines to come, from multiple jurisdictions.
Snowflake (NYQ:SNOW) is a US company and is listed there. Shares have not fallen yet.
No idea about Bloomreach.
Snowflake says it has found no compromise of its platform. I hold.
B.P. Marsh & Partners (LON:BPM)
B.P. Marsh has acquired a 30% equity interest in Dauntless for a nominal consideration.
· As part of the transaction, B.P. Marsh has provided a £2.0m loan facility.
· Dauntless specialises in marine hull underwriting focused on niche, brown water, older and distressed tonnage.
· The business will operate as an Appointed Representative of DA Strategy Limited and is supported by A-rated Lloyd's carriers.
Nice little bread and butter investment for B.P. Marsh & Partners (LON:BPM) - stuff like this really is what they have traditionally done so well - provide financial backup so key industry figures can go it alone (kinda presumption thats whats happening) and make hay for themselves and B.P. Marsh & Partners (LON:BPM) with their 30% cut of tehn new entity.,
Not sure how actively B.P. Marsh & Partners (LON:BPM) get involved in business plans etc but if they have any sense they would simply follow the similar disciplined approaches financially that have worked so well for similar. I doubt thne people in charge need to do much other than perhaps do what they have alwasy done - whilst enusring they have top financial controls ref stuff that they may not have previously needed to do if they were employees.
Not on the list here today, but Amaroq (LON:AMRQ) are delivering, and more, on promise.
With all the public surveillance the authorities today are bent on it seems to me that Synectics (LON:SNX) is in a sweet spot. I hold.
As are Journeo (LON:JNEO) .... ex SNX personnel now work there.
I agree. And performing at top end while energy project pipeline is stalled (and therefore is building for next year) is ‘doubly’ good news - jam today and tomorrow.
I hold both Synectics (LON:SNX) and Journeo (LON:JNEO) and appreciate the comparison but SNX price has been so depressed by scepticism of the CEO’s strategic project, SNX holds much more potential in my view.
https://x.com/RanmoorRuffian/status/2107364046282559796?s=20
BT (LON:BT.A) My view would be the company are being very careful not to say too much of what this could mean ...and hence analysts aren`t saying much either. It is very interesting if BT (LON:BT.A) are regarded as the safest place to transfer MVNO customers if the operator is in financial trouble. Obviously for a few years broadband has been very competitive and churn has being absorbing customers which has hurt BT (LON:BT.A) ....so should this deal go through this is quite the reverse of fortune. Even at 200p there is no premium being put on Openreach as a strategic asset and it looks to me ( says the hopeful holder) like the regulator is happy for BT (LON:BT.A) to be stronger - a domestic champion of sorts. A 10% operating margin on acquisition would be attractive but the TalkTalk customers will sit on the BT network and this has already had its investment. So I don't see BT levels of DA and therefore think there is an upside opportunity where the cash profits for BT from TalkTalk customers are very high. This deal could wash its face easily quickly and may also be the extra catalyst for BT (LON:BT.A) to tackle its own cost base. Oh dear Im getting very carried away now.....but having said all that no-one is being asked to pay up for BT (LON:BT.A) so im a little surprised the shares didnt react more positively. Maybe that is still to come should the deal pass through all hurdles without significant challenge.
I take the view ( I hold in my income portfolio) that this deal will go ahead ( Virgin have already objected I note) as only BT is in a position to deliver a smooth transition for Talk Talk customers. Like a failed energy supplier someone has to be the ' last resort' and only BT could do this. Having said that I remain a holder as I see the largest investments as having been done and therefore cash flow generation and hence shareholder return should be higher up the agenda going forward. One could not rule out BT being subject to future competition rulings given in this country we seem to see dominant players as creating monopolies. With Broadband there are lessons from the number of defunct players who thought they could muscle in but crashed.......... One hopes that BT have not inherited any pension liabilities from TT?????
That's an interesting philosophical point. In this country, domestic dominant players do create monopolies (or are part of oligopolies) but multinationals with strong market positions ought to be backed as national champions. Examples are Shell, HSBC and AstraZeneca (even if they have dual primary listings and so shared with another country).
I'm really surprised there has been no other bids from other broadband players to take on TalkTalk customers.
Vodafone (LON:VOD) springs to mind, being a smaller player (maybe top 5 but far behind Opeanreach, Virgin, Sky) in broadband share I think. This would make them have scale and size. And financially, they are somewhat better shape now for acquisitions, especially £400m. But maybe they already have enough to chew on, with the Three integration.
Sky would be the other player I am surprised hasn't bid for TalkTalk.
And then left field would be the likes of HyperOptic, who desperately need scale. And they can also migrate TalkTalk customers over to their own network, driving even more cost synergies.
Surely if there a bid from one of the other smaller players, the CMA + DCMS + Telco regulator would put all their weight behind that instead. But there isn't.
BT (LON:BT.A) still owns all the cables and connections IIRC?
e.g i'm with plusnet, and get a billon MBs a second or whatever, super fast streaming, tv shows, gaming etc. highly recommend them!
but when there's a problem? who comes out?
it's openreach i.e BT (LON:BT.A)
Kenmare Resources have had a non-binding takeover approach.
Thanks for flagging this up, I've added Kenmare Resources (LON:KMR) to the table.
Roland
Clarkson (LON:CKN) consensus forecast 83.9m, announcing they expect significantly ahead of expectations with forecast 135m.
Morning Dicky,
We'll probably have a look at Clarkson (LON:CKN) (disc: I hold) this morning!
Roland
this is fantastic news for Capital Drilling (CAPD) https://www.stockopedia.com/a/share-prices/capital-LON:CAPD/news/01a10fcd-b59c-7dbd-bf11-447ce8addbc6 Mining is huge in Australia so it will provide it with ample room to grow further. Owning the 'tools' and 'shovels' / 'testing' business is probably a superior way to play the mining industry than putting it in one resource mining company.
Good morning Roland, you covered CAPD's HY on the 26th August (Amber Green), we hold and it's a interesting TS this morning. I'm tempted to add to our holding, it's up slightly since August but maybe buying MDU is significant enough to move the needle? Revenue guidance raised, capex and MSALABS guidance reiterated.
Morning Jasvfs,
Capital (LON:CAPD) is on the list for today!
Roland
Hold your horses just a little. The raised revenue guidance is purely the mechanical addition of the MDU revenues, not an organic beating of expectations (although these were raised earlier in the year). Probably not a deal to move the dial too much at under 5% of group revenues, but a sensible bolt-on.
You're right sparkler, thank you. We've added though as imo Metres Down Under has potential to grow faster with CAPD and Australia is a good place to do it. My overall bear stance remains for reasons Roland mentions in his first 3 paragraphs today - but not on Mincon and CAPD.