Daily Stock Market Report (Wed 13 Nov 2024) - OXIG, TPX, FRAN, GMS, CGS, CRL, DWL, SRT

Good morning! It's Graham and Roland with you today, plus we have some catch-up items from Mark that are ready to go.
Wrapping it up there for today (12.30pm). Thanks!
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023
Companies Reporting
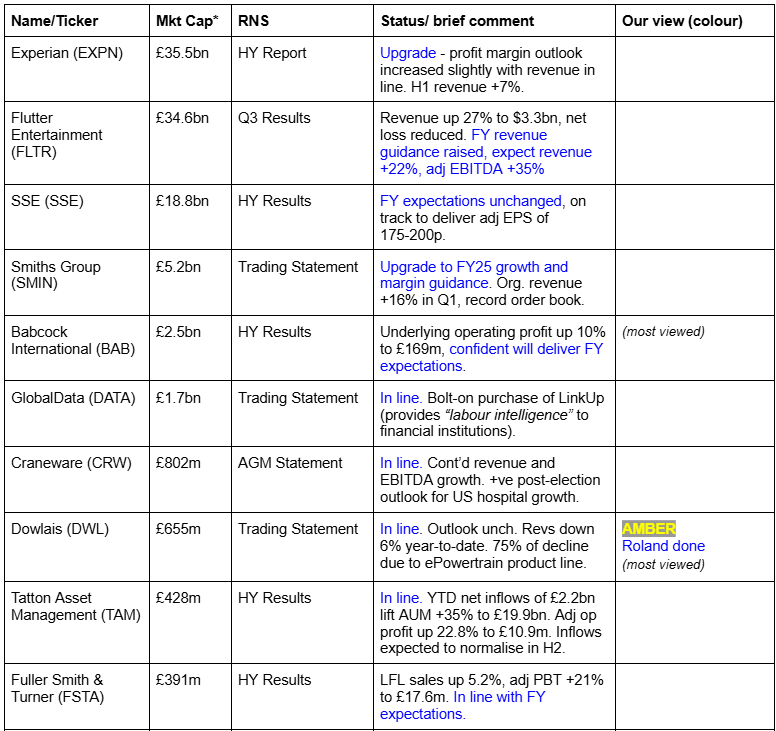
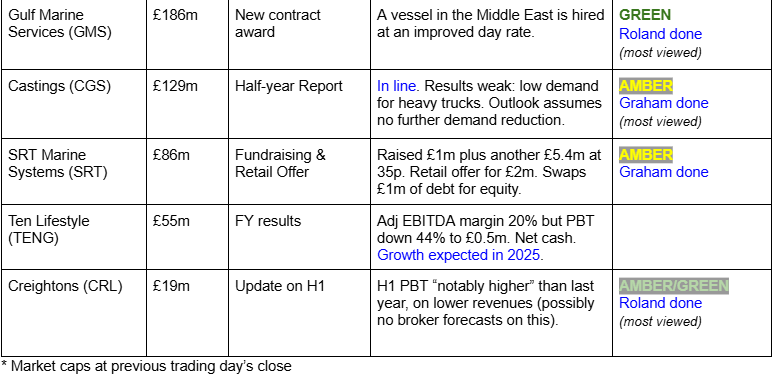
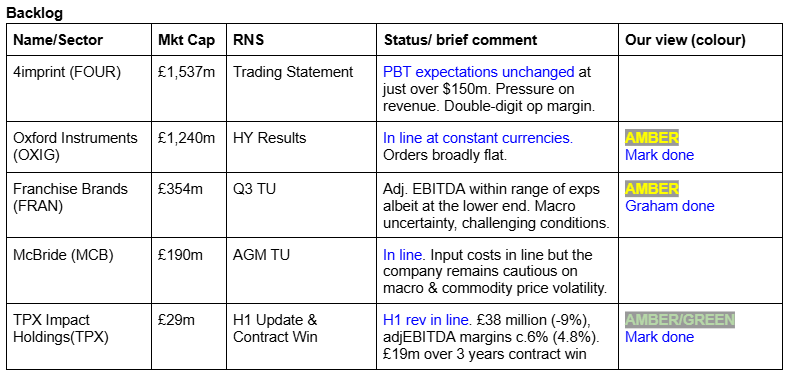
Summaries
Castings (LON:CGS) - down 2.5% to 271p (£118m) - Half-year Report - Graham - AMBER
FY March 2025 is in line with expectations, but shareholders who access broker notes will find that FY March 2026 has been downgraded due to ongoing weak demand from the heavy truck industry, offset by temporary cost cuts as CGS adapts to lower volumes. Cash falls to £16m.
Creightons (LON:CRL) - up 16% to 33p (£22.5m) - H1 trading update - Roland - AMBER/GREEN
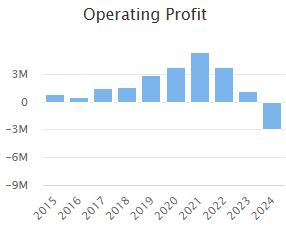
Half-year profits have been boosted by cost cutting. This consumer goods company now expects H1 operating profit of >£1.5m, exceeding last year’s full-year result. It’s a strong start to the year but with no forward guidance, I think a measure of prudence is sensible ahead of H1 results later this month.
Dowlais (LON:DWL) - up 14.5% to 55p (£748m) - FY trading statement - Roland - AMBER
Full-year results are expected to be in line with expectations, albeit with revenue down. Weakness in EV sales appears to be a particular headwind. The FY25 outlook appears to have weakened and debt levels seem a little high to me. This market leader could be cheap at the right price, but I’d want more information to take a stronger view.
SRT Marine Systems (LON:SRT) - unch. at 38.6p (£85m) - Fundraising - Graham - AMBER
SRT continues to prepare its finances for the delivery of a large ($213m) Kuwaiti contract over the next two years. Historically, I found SRT’s dilution of its share count to be off-putting. Tens of millions of new shares are now proposed for creation. Hopefully this time it’s different and the company delivers for its shareholders!
Short Sections
Oxford Instruments (LON:OXIG)
Down 3% to 2070p - HY Results - Mark - AMBER
When Graham looked at this, following Prelims in June, the shares were up 9% on an inline statement, and he commented that:
[the results] which don’t look particularly exciting to me, with adj EPS down 3% to 109p (in line with expectations), a PER of nearly 25x, which looks a punchy rating.
Since then, the shares are down over 20%, so they may be better value now. In June, the outlook at the time was:
Given our strong order book and pipeline, coupled with positive business improvement actions, we expect to make good constant currency progress in the full year ending March 2025.
The Half Year results show good top-line growth, but like many companies at the moment, the results look worse as you go down the income statement:
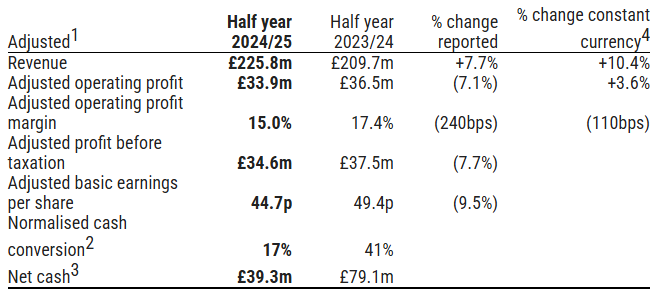
A slight reduction in gross margin and an increase in sales and marketing costs are the primary reasons for the drop.
The difference between the adjusted and unadjusted figures isn’t too large, and consists mainly of the amortisation of acquired intangibles, which is fairly standard. However, there is a big jump in restructuring costs:
During the first half the Group commenced a restructuring programme to deliver productivity and efficiency benefits following the new divisional structure, as well as yielding cost savings where we are seeing short-term order weakness. This resulted in restructuring costs of £2.2m.
This has a decent balance sheet with net cash and net working capital. Although net cash has declined by £43m in H1, this includes £15.4m due to an acquisition and £9.2m paid out as dividends. However, their willingness to make acquisitions makes the growth forecast unimpressive. The StockReport has 8% CAGR revenue growth and 10% EPS, suggesting that there is little operational gearing. This needs to accelerate faster than it is currently forecast in order to justify the current P/E of almost 20. The long-term ROCE here is very reasonable:
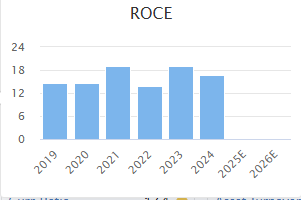
But unless they have opportunities to reinvest capital in similar assets in the future to generate stronger growth, this does them no good. A flat order book also doesn’t give the impression that this is a coiled spring.
Their segmental analysis may reveal a glimmer of hope. Imaging and Analysis currently generate all the operating profit with Advanced Technologies loss-making but faster growing. If they can continue this trajectory and Advanced Technologies becomes profitable, this may have a big impact on the bottom line.
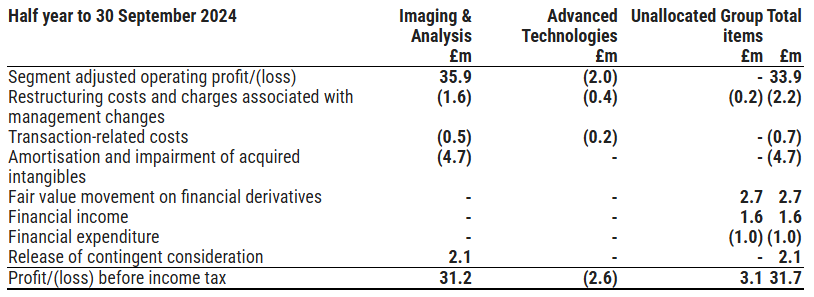
It may well be worth researching this possibility further.
Mark’s view
This is a decent company. However, unless there are signs that growth can accelerate in the future, and these results don’t give any indication that that is the case, the shares appear to be fully priced. Like most good but expensive companies, this gets an AMBER rating.
Tpximpact Holdings (LON:TPX)
Up 16% to 36p - H1 Trading Update & Contract Win - Mark - AMBER/GREEN
TPXImpact Holdings is the new slightly daft name for the previously very daftly named “The Panopoly”. Revenue here grew rapidly from 2019 to 2022:
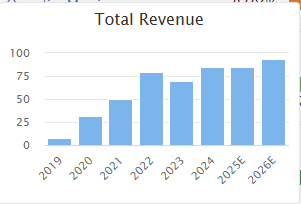
But this never made it into consistent profitability:
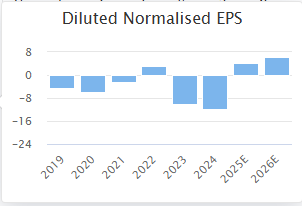
Forecasts are for this to change, though. While revenue remains flat, they are forecast to break into profitability. This update re-affirms how they guided the market at the start of September:
The Board expects to report first-half revenues of almost £38 million, down approximately 9% on H124. Adjusted EBITDA margins are expected to increase to c. 6% (H124: 4.8%).
However, this didn’t prevent the shares from slipping back, in what I presume was tax-selling worries:
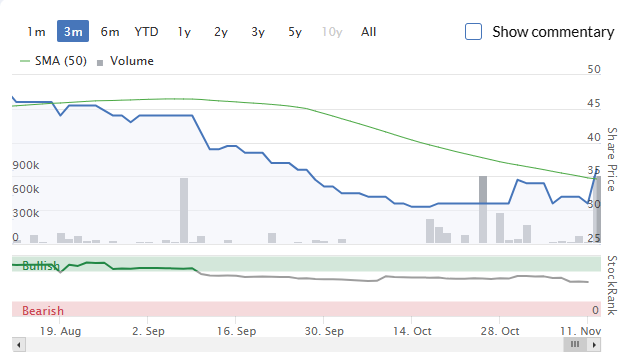
This works out to be around £2.3m adjusted EBITDA. A level that is likely to be break-even, at best. However, things are looking better for H2:
Our confidence in the Company's long-term growth prospects therefore remains strong and the Board reaffirms its FY25 target of flat revenue growth, with an adjusted EBITDA target of £7-8 million in line with consensus estimates.
Things are even better better for 2026:
The Board also remains positive about the outlook for FY26, with like-for-like revenue growth targeted at 10-15% and an Adjusted EBITDA margin target of 10-12% compared to 5.5% in FY24.
This works out to be £10.4m EBITDA at the mid-point of the range.
Net Debt is coming down quickly, too, and a quick look at the last balance sheet suggests that the working capital position isn’t too bad, either. Which can be a problem with this sort of IT contractor. The presence of a large cash balance as well as large debt means that there may be big swings in working capital during the year, but the company has ample facilities in place to manage this.
If we take the 2026 targets at face value, this works out at an EV/EBITDA of around 4, even after the rise. You can forgive the market its scepticism when the brokers’ trend looks like this:
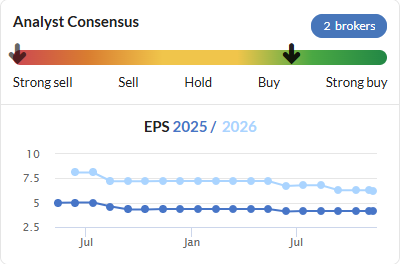
But it is easy to see why there has been a 16% relief rally today. A contract win, also announced, adds to the momentum behind the business:
The award from MHCLG of up to £19 million over three years provides TPXimpact with a pivotal role in supporting the delivery of MHCLG's ambitious digital reform programme to modernise the planning systems utilised across England.
Mark’s view
This sort of IT contracting business will never be particularly highly rated. However, if the company’s guidance is to be believed, which has now been consistently re-iterated, this is now too cheap. Some scepticism is still deserved given the chequered past and broker consensus trend. Hence, an AMBER/GREEN rating feels about right.
Franchise Brands (LON:FRAN)
Down 10% to 165p (£320m) - Q3 Trading Update - Graham - AMBER
Yesterday’s update from FRAN was almost a fully-fledged profit warning.
Despite “resilient underlying demand”, we have the following news:
…the anticipated recovery in project work is now not expected until next year due to continued macroeconomic uncertainty and challenging conditions in some markets. This supports the Board's expectation that Group Adjusted EBITDA for the year ending 31 December 2024 will be within the range of market expectations, albeit at the lower end.
Estimates: going into the update, the range of expectations for 2024 adj. EBITDA was £35.7 - 37m.
Thanks to Allenby for publishing a note with updated forecasts: they have also reduced their 2025 adj. EBITDA forecast by 6% to £39.3m.
FRAN’s Divisions
Pirtek (hose repair, hose replacement): the issue is that “project work and other discretionary spending has remained subdued”, which is consistent with FRAN’s view that the underlying cause is macroeconomic. The UK Budget is mentioned. Perhaps now that the Budget is in the rear view mirror, conditions can improve?
Filta UK (cooking oil management, fryer cleaning): “continued to successfully transition from a direct labour organisation to a franchise model”. In the US, where it is already franchised, Filta saw “strong growth in system sales”.
Exec Chairman comment:
Demand for our essential reactive services continues to drive a resilient performance despite softer demand for non-essential work. We expect this deferred work will be required, albeit the exact timing is uncertain and so we are cautiously assuming a recovery beyond the current year.
Graham’s view
We’ve been neutral on this one. I covered it as recently as 23rd October, when we had a double announcement that A) the company recruited a CEO to take on some of Exec Chairman’s responsibilities (good news, in my view), and B) FRAN was considering a move from AIM to the Main Market (I don’t think this matters until FRAN is big enough to join the FTSE-350).
After yesterday’s share price fall, it is back where it was on 23rd October. I’m inclined to stay neutral. Their main projects now are de-gearing (net debt last seen at almost £75m) and integration (a central IT platform will help all companies to work together). If and when we see signs that these projects are succeeding, I’m open to upgrading my stance here to a shade of green.
Gulf Marine Services (LON:GMS)
Closed yesterday at 17.4p (£186m) - Contract award - Roland - GREEN
A short update on a new contract award from this Main Market small cap this morning.
Gulf Marine Services hires jack-up platforms used by oil and gas operators and – increasingly – offshore wind operators.
New contract: the company has secured a new contract at improved rates for one of its vessels operating in the Middle East:
“We are delighted to have secured this contract at an improved day rates for one of our small-class vessels. This confirms the continuous demand for all the vessel classes we operate.”
Roland’s view
No financial details are provided in today’s update and there is no indication as to whether this will affect the full-year outlook. On this basis, my assumption would be that this is business-as-usual and already reflected in current forecasts.
The investment case here is built around GMS deleveraging while benefiting from strong market demand for its relatively modern fleet. Paul has covered this extensively in the past and I share his view that there has been an attractive opportunity here.
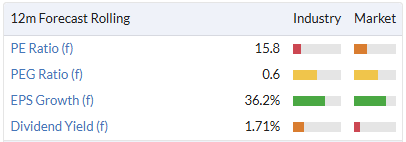
With the stock still trading around 30% below book value, I think it’s fair to argue that some value remains.
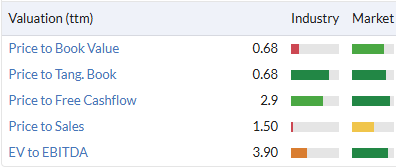
However, I don’t think this is a stock I’d want to pay a high multiple for, given the cyclical exposure and capital intensity.
Return on equity seems to have stabilised at around 13% as GMS’s recovery has progressed:
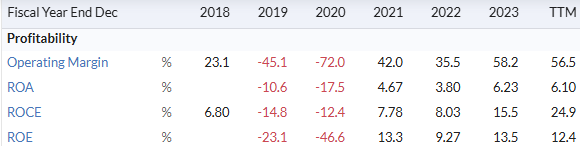
Given this level of profitability, I would be inclined to view book value (H1 24: c.25p) as a proxy for fair value.
Dividends are expected to resume over the coming year, which could provide a further attraction for investors.
With the stock trading on a forward P/E of 6 and a P/B of 0.7, I’m happy to retain a positive view for now.
Castings (LON:CGS)
Down 2.5% to 271p (£118m) - Half-year Report - Graham - AMBER
I like Castings for its concise reporting style and the Half-Year Report today is no different.
Without any introductory blurb, they get straight into it:
H1 sales £89m (H1 last year: £111m)
H1 PBT £4.1m (H1 last year: £10.3m)
The reason for the sharp decline is simple enough: much lower demand for heavy trucks, which are responsible for 75% of CGS; revenue.
OEM customers have reported demand normalisation throughout the period which, as expected, has flowed through to the schedule reductions we have seen from them. The US market is a notable exception where we have seen increased penetration with existing customers.
The problem of volatile demand for trucks in the post-Covid environment has been mentioned before - see our coverage of Castings in June (when I downgraded to AMBER/GREEN), followed by a profit warning in August (when Paul downgraded it further, to AMBER).
Ductile Castings: CGS bought the assets of an iron foundry out of administration in June (here’s the website). The price paid was just £0.4m, which was less than the operating profit the Scunthorpe-based foundry had recorded in FY 2023.
Today we learn that this renamed business (“Castings Ductile”) commenced production in July and “is now trading profitably” (to be precise: it has generated an overall loss since it started trading, but it started to turn a turn from its third month).
It would be terrific if this very cheap acquisition could make a meaningful contribution, but given the price paid it doesn’t owe CGS very much. Importantly, it has diversified CGS into gas/wind power generation and infrastructure.
Foundry operations: output is down 18%, or 20% on a like-for-like basis excluding Castings Ductile. The profit margin has unfortunately collapsed to 2.7%, vs. 7% in H1 last year.
It seems that weaker economies of scale are the main issue; the company was accustomed to higher volumes and had a cost base to reflect that. Or in the company’s words:
Profitability in the period reflects the lower levels of sales and the time-lag to realise the benefits of the actions taken to right size the cost base. Management believe that the necessary actions have now been taken such that the foundries can operate more efficiently at the lower levels of demand during the second half of the year. Importantly, the changes have not been of a structural nature and so can be quickly reversed to take advantage of the upturn in volumes when they come through.
Machining: similar to the foundry operations, profit margins from machining are sharply lower (falling from 10.6% to 6.6%) due to lower volumes. Older equipment has been replaced.
Cash is over £16m but I must note that this has halved compared to March 2024. Even so, the company has declared a new interim dividend of 4.2p (total cost is around £2m). Based on current levels of profitability, these dividend payments don’t look comfortable - I think an upturn in trading is needed to backstop them.
The balance sheet is very strong as usual, with very little going on in terms of liabilities, but I do find the fall in cash disconcerting.
Outlook doesn’t offer much in terms of improved demand, only that CGS will be better able to turn a profit at lower volumes: They do say that they expect to trade in line with expectations for the full year (these expectations reflecting prior profit warnings).
Estimates: despite the "in line" statement relating to the current year, there are cuts to forecasts at the brokers for future years.
Perhaps this isn't worth getting upset about, but I'd appreciate it if companies would tell the public themselves when they need to downgrade expectations for future years, instead of assuming that everyone has a broker note.
With thanks to Canaccord, I see that FY March 2026 has suffered a 3% reduction in its revenue estimate (to £190m) and a 16.7% reduction in its PBT estimate (to £12.5m). This does still imply a modest improvement on the year that is soon to finish, FY March 2025. The ongoing challenging backdrop in Heavy Trucks is the main reason for the cuts, along with higher NI contributions.
Zeus already had more conservative expectations and they only make a £1m cut to their PBT estimate, reflecting higher NI contributions only. Their new PBT estimate for FY March 2026 is £12.1m.
Graham’s view
This was one of my favourite industrial stocks, and I continue to appreciate certain aspects of its management style (e.g. strong balance sheet, cheap bolt-on acquisitions).
However, I feel obliged to stay at a neutral stance now given the lower cash balance and the weaker levels of demand which are apparently here to stay for the foreseeable future.
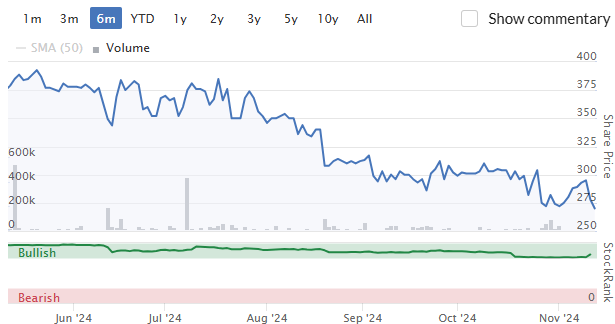
On the basis of the very latest updates, the stock is trading at a forward PER of 12.6x (271p share price divided by 21.5p EPS estimate for FY March 2026). I can’t argue that it deserves to trade at a much higher level than this, so I’m neutral.
SRT Marine Systems (LON:SRT)
Unch. at 38.6p (£85m) - Fundraising - Graham - AMBER
The track record here is volatile, to say the least:
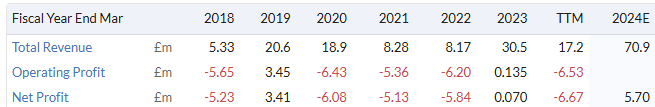
As reported earlier this month and at the end of October, SRT is going ahead with a fundraising to support an enormous ($213m) contract in Kuwait.
The contract is for “an integrated SRT maritime surveillance system”, for use by the Kuwait Coast Guard and other agencies. Implementation will take up to 2 years, and then there will be 10 years of support/maintenance. So that $213m figure is not all going to be earned on day one.
Please once again note that SRT’s financial forecasts are currently suspended by Cavendish.
Financial supports: getting the Kuwaiti deal signed was not so easy and some of the details are worth mentioning. From today’s announcement:
In order to secure the Kuwait contract which was signed on 30 October 2024, the Company was required to provide a performance bond in short order prior to signing the contract. Due to the short timeframe, traditional methods of financing the performance bond were unavailable to the Company. As such, the Company had very few options.
I’ll attempt to summarise the arrangements:
Performance guarantee. Major shareholder Ocean Infinity provided a cash loan of $21m, enabling the issuance of a contract performance bond. It is planned that this will be replaced by a bank guarantee and then by a guarantee from UK Export Finance.
Fresh equity of up to £8.5m is issued at 35p per share, conditional on shareholder approval. Ocean Infinity are partially underwriting the retail offer, i.e. they will pick up some shares if retail investors don’t take up the full amount offered to them.
The new equity of up to £8.5 is from the following sources: £5.4m from Ocean Infinity, £1.1m from certain existing shareholders, and £2m available to retail investors.
There are also quite a lot of warrants floating about.
The share count is currently 222 million, quite a step up from where it was before. The company already raised £10.5m at the start of this year.
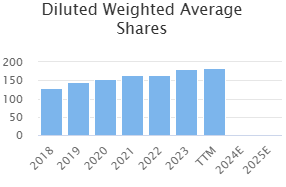
The new fundraise means an additional c. 24 million shares.
On top of that, there is a debt for equity swap releasing another 3 million shares.
And then there are 10 million warrants which were granted to Ocean Infinity at the end of October, plus another 10 million warrants to be granted if shareholders approve this fundraising package, all exercisable at 35p.
If SRT fails to replace Ocean Infinity’s contract performance guarantee within 8 months, SRT will issue another 4 million warrants every month to Ocean Infinity, with a new strike price based on whatever SRT’s share price is at the time.
Here’s a comment from the CEO of Ocean Infinity, who is joining the SRT Board. OI create robotics technology for underwater use:
"We're excited at the possibilities for SRT, and Ocean Infinity, founded on our investment in the company. The burgeoning partnership we have formed allows us both to better serve our clients in the maritime data and services market. We firmly believe in the company and its management to deliver as well as in the commercial opportunities for us to work together for the benefit of both businesses."
Graham’s view
Shareholder support for SRT (especially from shareholders other than OI) is admirable given that the company’s future financial performance is, in my view, anyone’s guess.
OI are a strategic investor and have been rewarded for their assistance with potentially very valuable warrants, so they are a special case.
We know that the Kuwaiti deal is enormous in terms of the revenue opportunity, and we know that SRT are seeking more contracts of this size. But how to value all of this? I don’t think it’s possible, not yet anyway.
Financial accounts here will be extra complicated as the year-end has changed from March to June. The next set of results to be published are the 15 months from March 2023 to June 2024.
This stock is firmly in my “too difficult” tray.
Historically, I viewed it as a company that over-promised and under-delivered. I also felt that shareholders got a bad deal in terms of regular dilution, without ever seeing much of a financial reward.
The first part of that statement remains as true as ever: more dilution is firmly on the cards, with more than 45 million new shares being printed if OI exercises all of the warrants that SRT proposes to create.
Perhaps this time it will lead to financial reward, but it's too high-risk for my own tastes.
Roland's Section
Creightons (LON:CRL)
Up 16% 33p (£22.5m) - H1 trading update - Roland - AMBER/GREEN
“the Group estimates that its profit before taxation for the unaudited interim period to 30 September 2024 will be notably higher than that of the comparable period in the previous year.”
Creightons is a consumer goods company producing a range of hair care and wellbeing products. We last looked at this small cap in July, when Paul covered the full-year results for the year to March and upgraded his view from AMBER to GREEN.
Today’s half-year trading update has prompted a double-digit share price gain at the market open, so it looks like Creightons’ turnaround may be continuing. Let’s take a look.
Half-year update: today’s update is brief, but provides several bits of useful information:
Small reduction in H1 revenue
Tight control on costs, cost base aligned with activity levels
H1 operating profit will be in excess of FY24 adjusted operating profit of £1.5m
Creightons doesn’t have any analyst coverage available on Research Tree (surely an own goal for such a small company?). This means that investors are reliant on today’s guidance for their forecasts until the full-year results are published on 28 November.
What can we learn from today’s update?
Lower revenue: no detail is given about the cause or size of the H1 revenue drop.
However, we do know that Creightons’ FY24 revenue (y/e 31 March) fell by 9.2% due to cost cutting and “product portfolio rationalisation”.
Checking back to last year’s results, the company reduced its brand portfolio product offering from 334 products to 184 products – a reduction of 45%! I would guess that the impact of this is still flowing through the numbers, so the H1 drop in revenue is not necessarily a big concern.
Cost cutting: today’s update mentions cost control, but does not make any mention of sales volumes or general trading conditions.
This suggests to me that the improvement in profitability seen in H1 has been driven by cost cutting.
This would also be consistent with lower revenue. Short term, I don’t see this as a problem. Rebuilding profitability before pursuing volume makes sense to me. But as the saying goes, a company can’t cut its way to greatness.
FY profit outlook & valuation: we are told that half-year operating profit before exceptional items will be “in excess” of £1.5m.
At 32p, Creightons has a market cap of £22m. Assuming net debt remains unchanged at under £1m, I estimate an enterprise value for the business of around £23m.
If I assume an unchanged profit performance for the second half of the year, I get an FY25 operating profit of £3m. I would estimate this might translate into earnings of around £2.3m, giving a possible FY25e P/E multiple of 10x.
Roland’s view
Today’s update provides no information on trading and no forward guidance. Further details are promised when the half-year results are published on 28 November.
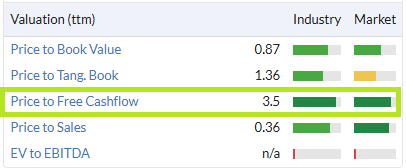
It may be worth noting that although the StockReport shows exceptionally strong free cash flow last year, this was driven by inventory reductions and favourable working capital movements. By its nature this isn’t necessarily sustainable, so I’d be reluctant to rely on this too heavily as a valuation measure until we see some accounts for this year.
Ahead of the half-year results, I’d be cautious about extrapolating recent improvements in Creightons’ profitability too much further. But I’d hope that the performance achieved in H1 should be broadly sustainable over the remainder of the year.
My impression so far is that the newish management have right-sized the cost base, repaid debt and consolidated the group’s product offering into a more sustainable portfolio.
The next step should be to start rebuilding sales growth and volumes.
The valuation still looks reasonable to me and if I held the shares, I’d be happy to continue doing so ahead of the half-year results on 28 November.
However, Creightons’ track record of single-digit operating margins would make me wary about paying too much. This business isn’t Unilever (I hold) or Proctor & Gamble.
Given the recent increase in valuation, falling revenue and lack of forward guidance, I think a measure of caution makes sense. I’m going to moderate our last view and take a stance of AMBER/GREEN.
Dowlais (LON:DWL)
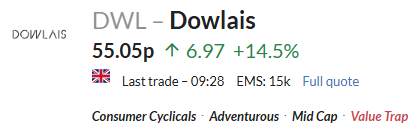
Up 14.5% to 55p (£748m) - FY trading statement - Roland - AMBER
The Group has delivered performance in line with expectations and our full year outlook remains unchanged.
Dowlais is made up from the former GKN Automotive Powder Metallurgy businesses. The company was created when it was spun out of Melrose Industries (LON:MRO) in 2023.
The main business is GKN Automotive, which makes parts such as propshafts, AWD systems and other powertrain parts. According to the company’s website, it’s the market leader in global drive systems. 50% of all vehicles worldwide contain GKN Automotive parts and 90% of global OEMs are customers.
The Powder Metallurgy business is under strategic review for a possible sale, but it is apparently the number one “sintered metal components supplier”.
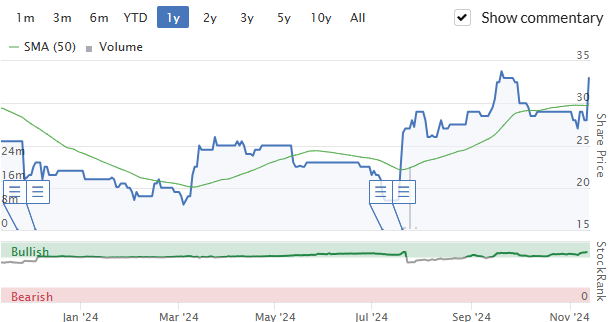
Checking back in the archives, we don’t seem to have covered this stock yet, perhaps because the market cap was much larger when the shares were listed:
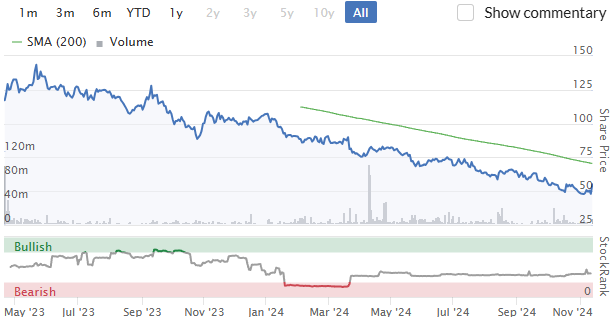
However, today’s trading statement has been met with a rapturous reception, despite merely confirming that results for the year to 31 October 2024 should be in line with expectations.
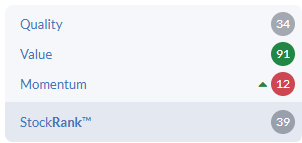
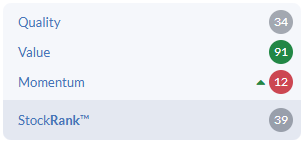
This suggests to me that market confidence in this business may have been quite low. This is a view reflected in a bleak StockRank and some remarkable valuation ratios (prior to today’s gains):
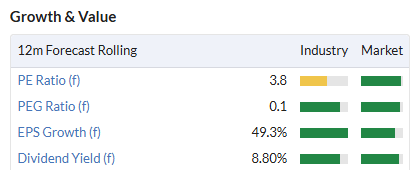
Let’s take a look at today’s trading statement.
Trading update for y/e 31 October 2024: the global automotive sector is in a tough place at the moment and this is reflected in Dowlais’ commentary. However, management do appear to be in control of the business and acting to mitigate weaker demand.
Here’s a summary of the main points:
FY adjusted revenue down 6.1% to £4.2bn, excluding a £173m FX headwind
FY adjusted operating margin of 6.1%, this is 0.3% lower than last year
Operating margin +0.2% vs H1, reflecting cost controls
Automotive: this division generates around 80% of revenue and is split into two reporting segments, Driveline and ePowertrain.
Driveline saw revenue fall by 2.4%, outperforming a 3% decline in light vehicle production outside China.
However, the ePowertrain business, which is more focused on electric vehicles, suffered a 19% year-on-year revenue decline due to a slowdown in demand for AWD and ePowertrain components. Presumably this reflects the wider slump in electric car sales.
Overall, Automotive adjusted revenue fell by 7% in the year to 31 October 2024.
Powder Metallurgy: this business generates about 20% of sales.
Performance was more stable last year, with adjusted revenue down 1.9% year-on-year and adjusted operating margin stable at 9%. Weakness was mainly due to an “unfavourable customer mix in North America”.
“Planned performance initiatives” are said to have offset the impact of weaker market volumes.
Outlook: Dowlais expects FY24 results to be in line with prior guidance.
Since August, industry forecasts excluding China have been revised downwards. S&P is now projecting a 3.9% decline in light vehicle production excluding China for 2024, or 1.9% decline globally.
Consensus estimates on Stockopedia suggest the company could report adjusted earnings of 10.9p per share for FY24. That would price the shares on five times earnings after today’s gains.
With thanks to Edison, an updated note on Research Tree today reinforces this guidance with estimates for FY24 earnings of 11p per share and a 4.2p per share dividend. That implies a useful 7.7% dividend yield, even after today’s gains.
However, management strike a more cautious tone about the year ahead:
Since August, industry forecasts excluding China have been revised downwards. S&P is now projecting a 3.9% decline in light vehicle production excluding China for 2024, or 1.9% decline globally.
This downbeat view is reflected in Edison’s FY25 forecasts for earnings of 12.1p per share, versus Stockopedia’s consensus for 12.9p per share. I’d watch for any downgrades to consensus following today’s statement.
Net debt: I have not looked at the accounts in much depth, but I wonder if one possible reason for the stock’s modest P/E rating may be the level of debt on Dowlais’ balance sheet.
The half-year results showed net debt of £915m, excluding lease liabilities. At the time, the company reported this as leverage of 1.6x EBITDA, well within the covenant limit of 3.5x.
However, depreciation and amortisation are real costs, especially in a manufacturing business. For this reason, I prefer to compare net debt with net profit. This gives me a quick view on how easily a company might be able to repay its debt if necessary.
On this basis, Dowlais’ net debt looks a little high to me, at almost six times FY24 forecast net profit of £154m. I generally prefer this ratio to be less than four times.
Roland’s view
The market leadership of the Automotive business suggests to me that this could be an attractive business to own, if one could buy at the right price, at a low point in the cycle.
I’m not sure if that’s true right now, however. According to the company, the outlook for 2025 appears to have weakened in recent months.
Personally, I’m also a little uncomfortable with the level of debt here.
On the other hand, the market’s favourable reaction to today’s "in line" statement suggests to me that a lot of pessimism was already baked into the price. If today’s statement was better than expected, then perhaps that is a sign the shares are already priced for a cyclical low?
Management also appear to be maintaining profit margins despite weaker volumes, which seems encouraging to me.
On balance I’m happy to mark the start of our coverage by taking a neutral (AMBER) view here. While this may prove to be overly cautious, I think this is a reasonable reflection of the apparent value on offer, tempered by risks from macro conditions and debt levels.
I’d expect to be able to take a more committed view after Dowlais publishes its full-year accounts and updated guidance in March 2025.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

93 comments
*** Tatton Asset Management (LON:TAM) - video recording (Investor Presentation) ***
If you missed the event this week, check out the recording of Tatton Asset Management's Investor Presentation with Q&A covering highlights of strong Interim Results, a Strategic update on the 5-year roadmap for growth and in-depth look at Financials & investment performance: https://youtu.be/EZm7YFm3-lM
Metro Bank Holdings (LON:MTRO) 's got some good momentum lately.Still a decent Stocko value rating too.If only they can get their quality rating up a little more.That was one of Graham's picks a while back i think.
Metro Bank Holdings (LON:MTRO) , I just don't get it, it's valued at roughly the same P/TBV as Osb (LON:OSB) . Metro Bank has not yet demonstrated that it can make any decent return on equity, pays no dividend, and has a rising share count. OSB has consistently made one of the best returns on equity in the UK banking sector, has probably the lowest-cost backroom in the UK banking sector, pays a chunky dividend and is buying back its own shares hand-over-fist at a discount to book value.
Why is MTRO on a tear recently and OSB getting beaten up? At the moment the market is pricing their book value for the same future profitability, but I just don't see it based on their past.
I hold OSB, and I have no personal problem with its price weakness - it's actually beneficial in the long term if they're buying back shares - as long as it doesn't signal a nasty lurking below the surface that the market suspects but I don't. Like with STB, which I also hold :-(
Metro Bank Holdings (LON:MTRO) and On Beach group (LON:OTB)
the thing is we dont really have to tools to work out the answer to your question. Perhaps its the fact that Metro bank has the old school branch network that osb doesnt - perhaps its sources of funding are deemed less risky or its ability to make good margin through the cycle is less questionable?. Perhaps metro has alwasy had an irrational premium that defies logic in which comparing to anything is pointless - i remember carteptright commanded top notch valuation for years back in the day - with the benefit of hindsight it was simply overvalued most of the time for reasons that probably elude us to this day.
Does metro have relatively small amount of shares not in hands of major holders ? sometimes having a small "liquid free float" can mean shares trade at an irrational premium if its very hard to get hold of stock in volume on the cheap?
Considering Metro Bank Holdings (LON:MTRO) was under 30p earlier this year, don't think it has always been at a premium to Osb (LON:OSB).
ISA allowance I’m no expert on banks but I believe metro are climbing back up from an almost bust status…. So the share price rise is more of a survival rise than fabulous prospects. Just my thoughts after having watched metro for a few years (from the sidelines)
The buy case on Dowlais is that whilst automotive supply chain may be a crap business that deserves a low multiple, the powder metallurgy business is higher quality and higher margin and could potentially be sold in for a sum that would wipe out the debt and leave the auto business trading on 2-3 x ebitda. And the auto business is a world leader with exposure to EVs and Chinese EVs so not doomed to secular decline...
Yes but its been a falling knife for sometime
If the powder metallurgy division is the golden egg in the Dowlais (LON:DWL) family, why hasn't there been suitors falling over themselves and multiple offers now on the table?
Bloomsbury Publishing (LON:BMY)
I have just watched the Bloomsbury Publishing Investor Meet webinar. I am a bit confused as there were 2 slides telling us that the company is 'trading ahead of expectations', I am not sure that I have seen this on a results webinar before and I dont know if it meant that these results that they were reviewing were ahead or that they were 'ahead' for the year and the expectations had not been upped since the results or that they were even more 'ahead' i.e since August 2024 and since the last RNS .
One thing that I was sure about though was that I would definitely be happy for CEO Nigel Newton to be running any company I owned, even in his position he did not waste an opportunity to encourage viewers to buy Bloomsbury published books as Christmas presents and I am fairly sure the last viewer question of 'which books are the three of you currently reading?' was staged to get in another plug.
Class act.
Bloomsbury Publishing (LON:BMY)
Looking at the slides they show:
The second is a summary slide so a repeat of the first.
They are a presentation of the results statement where the RNS says:
"......we now expect trading for full year 2024/25 to be ahead of the current consensus expectation.3
3. The Board considers consensus market expectation (before this publication) for the year ending 28 February 2025 to be revenue of £319.3m and profit before taxation and highlighted
items of £37.5m".
The slides would have been used for a presentation to analysts on the day (24th Oct.) whereas we plebs have had to wait until now for our presentation and in the intervening period the forecasts have moved up.
Re Bloomsbury results slides
There has been some lobbying prior to Rachel Reeves Mansion House speech tomorrow to introduce a research platform that would allow all investors to access professional analysis on listed companies.
Full story on this on city am
https://www.cityam.com/what-th...
Why not just read the Bloomsbury Publishing (LON:BMY) 24-October Interim results which clearly states in the header that they are "Upgrading full year expectations after record first half revenue and profit".
Today's was the presentation for those results. So he was just repeating exactly what was in the RNS. No conspiracy, no new news, just a three week delay between the RNS and some slides saying exactly the same thing!!!
You an find research on their website to be viewed by all.
https://www.bloomsbury-ir.co.u...
Graham, thanks for your update on Castings (LON:CGS) today. Regarding cash, I do see the company pointedly highlighted the payment of £9.2m of dividends in the period from the FY announcement which took the form of a final divi (14.19p) and a special (7p). Brokers seem to suggest the specials will only take place when there is a higher Y/E cash balance then forecasted at least this and next year.
The company also looked to have had some adverse WC movements which hampered cash. Finally, they had higher capex which relates to their new foundry due to open mid-2025. I therefore see cash outflows as higher than normal, although agree, it clearly needs an eye keeping on it!
Hi James, points taken re: CGS. I'm not overly worried about the cash situation, it's just striking to me how much it has reduced! Appreciate the colour on the dividend. I expect management will be sensible. G
In my opinion the majority of private investors would be much better to just buy a tracker and let the market be the stock picker, you'll always then hold the best companies at that time, as this video shows.
Human ego and emotion will usually fail to beat the market over time, most fund managers in the US cant. Of course the whole financial industry wont tell you this as its in their interest to keep everyone playing the game.
If you want to get funky you can use a sell trigger to get out of potentially large drawdowns early with a percentage or all of your holdings. That's about as complicated as I like to make it. Add on pullbacks, sell some/all if theres a sell trigger, buy lots if theres a crash. As long as you have a long enough time horizon then its about simple as it gets
A very simple sell trigger 10w/20w cross has only needed to be actioned 6 times in 10 years.
Interesting stuff Wolf I totally agree there are a handful of people who really should be in the markets doing there own thing I would hazard a guess that its 0.25% of the total population mainly through inability to get rid of duds that go onto lose 70% plus of starting value.
Out of interest presumably the 10w is same as the 50 day moving average and 20w is same as 100 day ? also do you use simple moving average or end of day ?
Sorry late edit presumably sell when 10 week broken , buy back when price closes back above 20w ?
Thanks
Andy
Weekly is better, removes the noise. Use EMA to pick up more recent price movement. Tried using a simple moving average but it was too slow to trigger a sell so EMA is best. Tested this back to 1950, you'll get some false triggers occasionally like October 2023 but when it works its a great way to get you out early as in Jan 2022.
One thing it does tend to do is trigger more in hesitant markets such as 2000 - 2008 and during the 70's. But overall it simply a case of checking on Monday ...if its triggered either buy or sell, removes all emotion and opinion from the process.
Thanks Wolf can you use Stock to do this is the 50 shown below indicating daily or weekly do you know as it doesn't seem there's a choice between 50 daily or 50 weekly on Stocko ?
Phoenix, if you change the chart to weekly from daily that'll work fine. Sell when 10w crosses 20w. Then buy when it crosses up.
Sell triggered in Feb 2022 around 4500. Stick the money in a money market fund 5%, buy 11 months later when it crosses up below 4000.
2008 triggered a sell at 1480. Buy triggered 18 months later at 900
2000 sell triggered 1450. Buy triggered 2.5 years later 890 (there were a couple of short term false buy triggers half way through the selloff also but buy/sell within 60 points of each other)
This is how I run my kids ISAs
Thanks again Wolf so ideally sell on the break of the 50 week and buy back in on crossing the 100 week ?
Sorry Wolf just saw your explanation below we must have crossed over, thanks again for your help and all you do here, even with Paul leaving so long as the top table crew keep knocking around Stocko that will be enough to secure my ongoing sub.
Regards
Andy
Hi Wolf, very helpful and thought provoking. Out of interest, what money market product would/do you use, short dated treasury?
Some good money market like options here jburge
Fascinating video, WoSS, thanks for that and the sell trigger info.
In my opinion the majority of private investors would be much better to just buy a tracker and let the market be the stock picker...
Just over a year ago, I rebalanced my portfolio to have one third global tracker; one third shares; one third investment trusts. After a year, the proportions are pretty much the same. This leaves me fairly pleased with my performance - as a near-beginner, I put this down to my Stockopedia subscription as I think I'd have lost the lot otherwise. It also leaves me wondering why I don't just put it all in the tracker, as you say.
That video reminds me of the three cups game. The peanut started under one cup but which cup was it under at the end? Food for thought (get it?), seeing as one's portfolio is increasingly cash without a home - but Wolf, I'm doing miles better than when you drew me into the charts nearly six months ago, and now I find I've got to give it all up and buy a tracker....
Haha it is hard to stop watching isn't it.
Well, theres always room for outperformance TEIN isn't there. Small investors do have the big advantage of being able to buy and sell when we want, so shouldn't be too hard to beat fund managers with a little discipline. Most PIs have to work full time jobs tho so that makes a tracker much more sensible option Id say.
Imagine a world with no profit warnings :)
If its a choice of paying a 1.2% fee for a fund manager who's lost money in 5 years or a tracker at 0.07% fee I know which Id prefer.
Im really pleased you've found charts helpful. When people stop thinking of them as some sort of fortune telling device and just a visual picture of what the market thinks today and in the past then its great help.
Great stuff wolf. Something I've been thinking of doing, I work full time have a young family etc.
Or maybe I'm just lazy
John I've worked in wealth management for nigh on quarter of decade the portfolio's i put together for clients consisting of etf's, closed funds and investment trusts generally average 8-12 pa (bar 2022) for medium risk yet my own individual stock picks that I spend 8-12 hours per week on do less than half that.
Hence I'm moving towards a portfolio of 22 investment trusts and 3 years worth of sipp income requirements in three separate money market funds as I am aiming to go down to three day week when I pass 55 this Dec.
Effort to pay off on single stocks is like trying to get into the olympics most of us could run 100 meters (just at my current age) but only a handful reach peak performance thankfully most of them in the private investor space knock around this board and are happy to help.
My mindset isn't right for individual stocks I extend stop losses to much when hit and average down to much all the stuff I know I shouldn't be doing, but at least with investment trusts there is less risk of total loss on average downs.
I must admit when I went on holiday a couple of weeks back and compared what I would have made in one of my to client models against my own picks I was pig sick with how much I had missed out on, this for something which once set up I could probably put 15-30 minutes a week into tops with either quarterly or half yearly rebalancing.
Problem is like most on here i love the subject even though i am rubbish at it , knowledge wise I would put myself in the top 1% in the UK so lord knows how much the other 99% messing around in bitcoin, forex and day trading must be losing egged on by shills on Youtube promising them riches.
Completely agree Phoenix. I am back into a significant proportion of PF across high performing ETF's, IT's and some UT's.
I keep a proportion in small companies which I research, but like you, I am not that successful and often regret not increasing my holdings in the great collectives.
Having retired earlier this year I thoroughly enjoy the researching of companies etc and using Stocko (and other tools), but even now I find there are too many other great things to do with my time that I still probably cannot find an edge.
Anyway, must dash, off mountain-biking for the day...............
@ the pheonix - the investment trust board would be happy to receive your input !
I will look to chip in Dave, the two Mitchells and Shoeshine boy already do a great job on that thread but I will aim to add to the debate when things slow down for me normally when December ticks around.
Except that in reality these charts only work in hindsight.
There are so many occasions where moving averages start to converge, but it is only AFTER they have crossed that it is clear they have indeed crossed - often they bounce away after touching but not crossing, generating a false alarm. If you wait for a clear cross, the market has usually moved a LONG way in your observation period. It's the same with RSI and MACD based triggers as well.
In a really steep market fall it doesn't work any better than stop-losses either - you blow right through without touching the sides....
A further difficulty is that historic charts, even of the high/low candle variety don't really capture the full market volatility - they can't handle spikes from rogue auctions, outages etc. Nor do they always capture the widening of the bid/ask spread - the price on the historic chart ain't the price you could have dealt at.
Once you add these real-world problems you discover the dealing spreads
and stamp duty incurred on false alarms (sell...oops, buy back quick)
materially alter the outcome.
And then in a crash you find you can't sell after the model tells you to, because....
1. Your broker won't pick up the phone
2. The market makers have wound their necks in
3. The online platforms are swamped and failing to provide quotes, even if you do manage to log in.
And finally - very few humans have the discipline to follow what the model tells them to do. Especially when half of your workplace has left the premises to queue outside Northern Rock!
WOSS was discussing trackers though , rather than individual stocks ...
Absolutely Cancun. I only ever use this on the S&P.
I have the impression that Wolfie was talking about a totally different thing!
All the best
Thanks for this Wolf OSS, Fascinating video; how can i get a copy for my 30 yr old grandson who is just getting into financial investing, it will get him moving in the right direction & partially steer him away from searching for short term gains.
I too use Ma's and find them invaluable for knowing when to be in and out of the market, especially this current volatile FTSE,
Funderstruck, If you click on the title of the video it should open the YouTube page or search 'top 10 s&p 500 companies by market cap'
One thing I would add to this if I may, funds in Sterling don’t always line up with the index due to currency fluctuations. That may not matter all that much in the long run, I haven’t done the backrest, but there are currency hedged funds. ishares do one but the downside is higher fees, I think 0.2%.
Is anyone smarter than me and can tell me if it’s worth the higher fees of the hedged etf? Or would the currency fluctuations balance out roughly over time?
can tell me if it’s worth the higher fees of the hedged etf? Or would the currency fluctuations balance out roughly over time?
Hi Matt - I'm no expert but this article might be relevant, it's something I learnt about when considering the same question:
https://monevator.com/dont-cur... Don’t bother currency hedging your equity portfolio. Especially not if you live in the UK. It’s what old-timers call a Texas hedge: one that increases both risks and costs.
Thanks!
Fascinating post and people should be shocked that Berkshire Hathaway (which we hold) has not beaten the S&P500 over 5 or10 year periods (which we knew).
I am puting in place a strategy for my passing for my wife and family which is based around selling all my positions and investing in a balanced multi asset portfolio based on Vanguard ETFs + the Royal Mint Gold ETF managed by HAN. My wife and family have zero interest in the stock market and my wife pointed out to me that I had made a lot more money in agriculture, forestry and tourism than I ever made in the stock market.
Food for thought.
Your another poster i rate highly James so interesting to see your going same route as me but for different reasons, least it will give you more leisure time away from farming duties.
Thanks for the informative post, something that I might apply to my daughters s&s ISA. I’ve also considered just using a tracker and having it done with, but we love the chase don’t we? The possibility of waking up one morning to find your stock has multi bagged? Dreams can come true I guess! Either way, over the last few years of choppiness I’ve taken profits much sooner than I usually would, and just keep repeating the cycle. jd sports was one I traded throughout this year, buying heavily in the 100 and 110s and selling in the 130s. I made around 30-40 percent on this one, but if I’d of sat on it I’d only be up around 6 percent now. Food for thought. I think the more I grow my portfolio the more I should diversify, but so far it’s served me well so I’ll stick as is for now.
Thank you for your coverage of Castings today Graham, I like their straightforward reporting too and being a sucker for British metal bashing companies added a few more to our long term holding. I note your observations on brokers notes, the thinly covered dividend and reduced cash. If Trump can do as he says and end the Ukraine war quickly, hopefully without giving a fifth of it to Putin, perhaps Casting's heavy trucks business will revive as Ukraine rebuilds its country. I also like the potential in green energy production mentioned in the results.
Speaking as someone who works for one of Britain's metal bashing companies, the orderbooks are in a steep decline across the board and have been since July/August. This includes one of our customers who manufactures components for heavy trucks. It has been blamed on Labour's talking down of the economy (ahead of the budget), the forthcoming budget (now delivered), the US election (now resolved) and high interest rates (cut last week). No signs of life yet....
Hi JASVFS, you're very welcome for the coverage - I still like CGS and want to be more positive on it. Best of luck! G
As reliable as Father Time, its nearly Christmas so SRT Marine Systems (LON:SRT) is round with the begging bowl again. But don't worry - they have signed a great big contract and more are on the way, so all will be well in the end. No honestly, it will. This time they really mean it! "But didn't they say that last time and the time before that and the time before that and the time before that.......?"
Gulf Marine Services (LON:GMS) has probably been told/asked by Seafox to raise the company profile as Seafox shareholders sell the 150m GMS shares that were distributed to them.
Oxford Instruments (LON:OXIG) Hi Mark - thanks for your report The one item that sticks out to me is the currency - the fact that profit is down 7.1% from £36.5 to £33.9m yet is reported as a 3.6% increase in constant currency. Thats over 10% difference taken by currency fluctuation in a 6 month period!
The relentless decline in Liontrust Asset Management (LON:LIO) continues unabated. Now yields over 17% so mkt expecting a cut in dividend when it updates next week. Buffetology says it's a coiled spring.
Liontrust a ‘coiled spring’, says Buffettology
Liontrust Asset Management (LIO) is a ‘coiled spring’ that could do very well if sentiment towards the UK improves, says Sanford DeLand manager Keith Ashworth-Lord. He holds the asset manager in his £406m CFP SDL UK Buffettology fund, where it was the biggest faller in October, with the shares dropping 14.5%. The investment group continues to experience net outflows, which Ashworth-Lord said was "symptomatic of the current sentiment towards UK equities and the quality growth investment style in particular. We know this cannot continue indefinitely and await further details of the Mansion House proposals which should encourage – either by carrot or stick – greater investment into UK assets by pension funds. As we witnessed during the first half of 2024, Liontrust is a high beta stock and is one of many coiled springs in the fund that will be very sensitive to any improvement in sentiment towards the UK." The shares fell 2.7% to 418p on Tuesday, extending losses to 31% in 2024 to date.
https://citywire.com/funds-ins...
Along with many I despair at the state of the UK mkts, the last four yrs hopeless for me.
You'll still have done better than Buffetology Mike, their 5 year return has been hopeless, not just in performance but opportunity cost. If the last 5 years don't turn people towards a simple low cost global tracker then nothing will.
Couldn't agree more, I hold this fund and am well ready to bin it. I've never really been able to work out why it performs so badly given the top 3 holdings of Games Workshop (LON:GAW) , Relx (LON:REL) , Jet2 (LON:JET2) but also Next (LON:NXT) etc. whereas Liontrust Asset Management (LON:LIO) doesn't make it onto the Top 10.
Time is up for me, worse than a jam-tomorrow story stock
The trouble with closed end funds like Buffetology is that when markets fall they face a double whammy. Not just does the fund value fall but human nature dictates that investors pull their funds out, forcing them to sell into a declining market. In a bull market the opposite occurs, making the managers look like investment gods.
That said, they have made some odd and erratic moves over the years. Lindsell Train have faced similar problems, with similar results, but they've consistently stuck to their beliefs, so at least you know what you're investing in.
On that note Lindsell Train Investment Trust (LON:LTI) - an open ended investment trust - looks incredibly cheap. Although you do need to satisfy yourself about the value inherent in their stake in the management company, which is a significant proportion of the NAV.
timarr
Don't disagree Tim but the spread has always seemed lumpy to me on Lindsell Train Investment Trust (LON:LTI) .
Don't disagree Tim but the spread has always seemed lumpy to me on Lindsell Train Investment Trust (LON:LTI) .
Hi The Phoenix
It is, but it's not the kind of stock to buy for trading. If you intend to hold for the duration the spread becomes irrelevant. But a spread of about 2% on a discount of 28% to NAV doesn't seem like a terrible hit. Share price frequently moves more than that in a day.
timarr
Hi Timarr
I think you’ll find that Buffetology and the companion free spirit fund are not closed end, like investment trusts, but open ended. What one might refer to in old money as unit trusts.
Hi jonno
You're absolutely correct, aged brain fade on my part. But the thrust was correct - open ended funds like Buffetology have to sell shares to meet redemptions, usually when share prices are going down (conversely if they're successful and attract funds they often have to buy shares when they're expensive). Closed ended funds - investment trusts - don't.
Although to be fair, investment trust discounts can widen alarmingly in bear markets. Lindsell Train Investment Trust (LON:LTI) is a case in point - at one point its chairman was advising people not to buy it because it's premium to NAV was so large.
As the monthly investment trust article amply demonstrates buying closed ended funds at significant discounts usually ends well.
timarr
We got on the train after reading Maynard Paton's analysis of it for SharePad timarr. I add a few every time Michael Lindsell buys a lot which has been quite often.
Buffetology has got the name but not the performance
So spot on Wolf I have mentioned before I work in wealth management and the quality of the posters on here are a level above a lot of the fund managers I meet.
The ego I am right the market is wrong issue is as prevalent there as it is with private investors.
WoSS, This is the direction I have taken over the last year. I now hold US based ETFs in semi conductors, healthcare, defense, silver &S&P 500 and I am researching an ETF covering US industrials. Any suggestions.
To add to my post above are there ETF sectors that will benefit from Mr Trumps intervention?
As illustration of the trend towards tracker/low cost alternativesent (as if its needed), Tatton Asset Management's (TAM) results include the comments "Accordingly, during this period, we were pleased to launch a range of highly competitive Passive funds in response to demand from our IFAs and their clients. These funds offer a low cost, diversified investment option that aligns with the principles of long-term wealth
accumulation."
Regards Geoff (long suffering holder of LIO, happier holder of TAM & EXPN reporting today)
Yes I am starting to pull funds out. Maybe not the best timing (when is) but there are better returns elsewhere. I am sticking now in the UK to mainly companies that have revenue outside the UK and don’t have a lot of employees so won’t be so impacted by NI or the minimum wage. Whilst the PE and yields still look good you have to question whether profits won’t get slashed next year on higher costs.
I really hope Liontrust Asset Management is a coiled spring. My biggest loser, contemplating selling today but I just can't stomach it. Thanks for posting eParo.
Cordel (LON:CRDL) also announces two new contracts today with no figures listed. Seems to be a theme of the day!
Two new customers, both large operators. My impression is that they are both modest contract scopes in themselves but could lead to much larger engagements. What is significant is that they are both major operators and are ‘straight to contract’ without a POC/trial, which demonstrates the credibility and reference-ability Cordel now have in the market.
For a £14mn company,Cordel (LON:CRDL) are winning some important contracts from very large rail companies internationally. Such companies wouldn't risk major accidents or damage to their infrastructure or (in the latest contract) a major mistake in the design of a new fleet of trains without real assurance that the measurement technology works and that the company will be around to maintain it.
`it seems to me that CRDL must have developed IP that has a value way above their micro market cap. I hold, of course.
Hi Graham,
Is it possible to have a link to the StockReport page in your 'Companies Reporting' table rather than just the name? E.g Oxford Instruments (LON:OXIG) rather than 'Oxford Instruments (OXIG)'
Would make looking up company data in your table much easier. tia
Hi eParo, as things stand the table is just an image. We'll need help from the developers to make it interactive/clickable but that is something we are looking at. Sorry, no timeline for when it might happen, as I don't yet know how difficult it will be to make it happen. G
Creightons (LON:CRL) Operating profits up quite significantly, now beyond 1.5mil for the period. Overall, profit could be 50% higher than last year quite comfortably and this isn't reflected in the SP. Can they grow revenue further is the even bigger question, if so Creightons could multibag. Looks cheap to me hence I hold. Should see a bounce today (much needed for my folio after yesterday!)
Creightons (LON:CRL)
Did look remarkably cheap based on last year’s FCF generation. Should have been trading north of 50p.
I hold
All the best
Tatton Asset Management (LON:TAM) - "H1 revenue +24%, profit +23%, forecasts upgraded", new report from Equity Development available here: https://www.equitydevelopment....
AUM jumped 14% over H1-25 (to 30 Sep 24) from £16.6bn to £18.9bn. Net inflows added £1,832m (22% p.a. inflow rate, far higher than all peers, see page 4), and investment returns £534m (3.2% over 6m). Including 50%-owned 8AM Global, Assets-Under-Management/Influence totalled £19.9bn. In the six weeks post-results, AUM/AUI increased another 4% to £20.6bn in early-Nov.
This is an exceptionally strong start to the next leg of Tatton’s growth journey. In June ‘24 it set a target of reaching £30bn AUI by end-FY29, an 11% CAGR.
Our previous forecasts assumed average net flows of c£150m per month. That was clearly overly-conservative. Monthly net flows actually averaged £305m over H1-25, far higher than £192m in FY24 and £150m in FY23. We upgrade forecasts assuming net flows of £200m per month for H2-25, as per Tatton guidance, reducing to c£170m per month after that (October net flows: £265m), also as guided.
This change materially increases our FY25 revenue and profit forecasts and our longer-term forecasts (see page 18). In turn, our fundamental valuation increases from 640p per share to 715p.
But with such a superior offering compared to peers in platform MPS (page 5), and structural market tailwinds (page 15), there is certainly potential for Tatton to grow faster than our current forecast and for our fundamental valuation to rise again.
Creightons (LON:CRL)
A brief update from Creightons this morning telling us that the interim numbers to be released on November 28 will show a much improved result on same period last year and more than the whole of the previous year.
Not many numbers to go on but probably worth a look.
deleted, original post now edited !
Gulf Marine Services (LON:GMS) new contract for a small boat. Sounds modest, but enough for an RNS, Should result in a few % uplift. I hold.
Their boats are hugely impressive. If you've never watched a vid of an offshore platform or a turbine being installed in the ocean I'd heartily recommend it. Superb engineering.
I hold.
Can’t see why Gulf Marine Services (LON:GMS) needed to tell us that one of their small vessels got a new contract at higher rates without any figures! Why is it significant? I hold
Gulf Marine Services (LON:GMS) - In fact doesn't even say if the contract is for a week - a month or a year. What on earth are we supposed to make of it.
Gulf Marine Services (LON:GMS)
Zeus says it is for 10 months and at higher day rates, my takeaway is the overall direction of travel and momentum is extremely positive, I have just added.
Hi Burnt Onions,
Thanks for flagging up the Zeus note on Gulf Marine Services (LON:GMS), I missed this first thing.
Having taken a look, Zeus are leaving their forecasts unchanged at this point.
I think it's probably fair to assume this new contract does not alter FY expectations . But as you say, the business does appear to be trading well at the moment.
Roland
Presumably because individual contract terms are confidential.
I think the vessel might of been out of contract (hence why annoucement) take a look at latest presentation vessel contracts graph now has new higher daily charges
Hi Graham. Late yesterday it was released that PayPoint (LON:PAY) will be added to the FTSE 250 index and deleted from the FTSE SmallCap index as of 15th Nov.
You’ve have previously been very positive on PayPoint (LON:PAY). First time I’ve held a stock that has moved to a larger index. I assume this should be positive for the SP. Is this what’s been driving the price higher with traders pre emptying the move? Will trackers need to buy to balance portfolios? We’re in the volume gap at the moment, so not much supply. Any thoughts are welcome. I hold.
Thanks for pointing this out Revs8, I see that BlackRock added 669k shares in October and perhaps they are still buying. I don't see their actions as a driver of the share price, more as a response to the share price, but of course their buying activity doesn't hurt, some of which could be linked to FTSE 250 inclusion. PayPoint has been in the FTSE-250 before - let's hope it sticks around permanently this time! G
You’ve have previously been very positive on PayPoint (LON:PAY). First time I’ve held a stock that has moved to a larger index. I assume this should be positive for the SP. Is this what’s been driving the price higher with traders pre emptying the move? Will trackers need to buy to balance portfolios? We’re in the volume gap at the moment, so not much supply. Any thoughts are welcome. I hold.
Markets factor in all known news and they've been expecting PayPoint (LON:PAY) to get promoted for a while now which is one factor which has been driving the price higher. In my experience when companies actually move indexes the reaction tends to be mildly negative.
That said the recent movement has been significant. For a long time Paypoint was a rather dull, ex-Post Office company with bureaucracy and share price performance to match. It appears to have shaken itself up and the resultant earnings increase justifies the price increase.
On the other hand, at the moment being a decent company on a very low rating in the UK doesn't generally equal price outperformance so I suppose there's a chance Asteriscos Patrimonial are considering making a bid.
I hold.
timarr
Thanks Tim quality input as always
£PAY
One of the few stocks where I have had to average down a few times, which isn't my natural inclination. But I thought with its strong cash generation, dividend policy, and earlier moat (somewhat eroding now) it wasn't a bad bet. Its maneuvering to seek some fresh income streams whilst remaining a bit of a cash cow.
It took a while to come good vs my re-investment attempts, but now is in positive territory.
Pleased to see Graham thinks it has some good fundamentals, but not always a business that it is easy to read, so analysis is helpful.
Hi Revs8 - Do you have a list of the changes apart from paypoint. Looks like there could be a good few fallers and risers this time.
FWIW just noted that Boku (LON:BOKU) which is similar MktCap and also a payment enabler but very different clients has announced an agreement with Amazon Japan. Also quite an anomaly - an American company listed on AIM in London
another company got takeover/delisted so PayPoint (LON:PAY) entered fste 250, index review is early december. Diversified Energy (LON:DEC) will probably make a late run for fste 250 entry Trump affect?