Daily Stock Market Report (Wed 19th November 2025) - Nvidia earnings, ITH, LIKE, NTBR, JET2, CRL

Good morning!
Writing this on a Chromebook using hotel Wifi, hopefully you don't notice much difference! Cheers.
The FTSE was down 1.3% yesterday due to generalised jitters that markets are overvalued. Nvidia, the poster child of the AI/tech bubble, reports results today (after hours). The market learned this week that legendary invetor Peter Thiel had sold his entire stake in it ($100m). Softbank also sold its entire stake ($5.8 billion) and of course there was the recent disclosure of Michael Burry's short positions - Nvidia being his other major short, along with Palantir.
Nvidia is 7.5% of the S&P 500, and of course very highly-rated, so it makes sense that markets would worry in these circumstances - I think they should be worried! And as usual, US volatility is going to have some knock-on effects on UK shares, even if the logic for that is not always entirely clear.
The Agenda is complete.
Spreadsheet accompanying this report: link (last updated to: 10th November)
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
Lloyds Banking (LON:LLOY) (£52.6m | SR63) | Curve is a UK fintech operating a digital wallet platform that will improve the bank’s mobile payments offering. Not expected to have a material financial impact in 2025 or 2026. | ||
Sage (LON:SGE) (£10.4bn | SR44) | Rev + 8%, op profit +17% to £530m. Adj EPS +18% to 43.2p (in line). FY26 outlook: expect rev +9%, w/ improved margins. | ||
Severn Trent (LON:SVT) (£8.2bn | SR61) | Rev +18%< , adj PBIT +56.5% to £466m. Adj EPS +74% to 101.0p. New CEO appointed. FY26 guidance: net performance incentives now exp >£40m (prev. >£25m), op cost growth 5-8% (prev. <12%). Expect c.13% regulatory return. | ||
Smiths (LON:SMIN) (£7.9bn | SR69) | Q1 in line with exps, with revenue +3.5%. Approved further £1bn share buyback, FY26 guidance reiterated. | ||
Ithaca Energy (LON:ITH) (£3.9bn | SR98) | YTD production 115 kboe/d (YTD 24: 52.5 kboe/d), YTD opex $19.1/boe, YTD EBITDAX +98% to $1,501.2m. FY25 outlook unchanged for 119-125 kboe/d, expect higher production in 2026. | AMBER/GREEN (Roland) [no section below] I was AMBER/GREEN on Ithaca at the time of August’s H1 results, since when the shares have risen by a further 20%. Today’s update confirms further progress and reiterates full-year guidance. One possible slight niggle is that net debt rose from $671m to $1,064m in Q3. This appears to reflect a $238m increase in capex compared to the same period last year, plus the $136m completion payment for the Japex acquisition. I don’t have a particular problem with this level of leverage, but I think it’s worth monitoring whether debt levels continue to rise to fund capex – this might suggest the company is overpaying on the dividend and could be left vulnerable if oil or gas prices fell sharply. However, the benefits from the increased scale and lower cost per barrel of the group’s expanded portfolio are clear – full-year guidance implies opex of c.$19/boe, from $22/boe in 2024. Dividend guidance for a total payout of $500m is also reiterated today, with $167m already paid and a further $133m declared today. That underpins a c.9% yield at current levels. Current 2026 forecasts suggest a fairly flat performance next year and I would probably consider a neutral view if the stock became much more expensive. For now, I’m going to leave my view unchanged at AMBER/GREEN. | |
British Land (LON:BLND) (£3.8bn | SR65) | Underlying profit +8% to £155m, adj EPS +1% to 15.4p. Occupancy 95%, total property return 3.8%. FY26 outlook in line with exps. | ||
Rotork (LON:ROR) (£2.7bn | SR46) | Order intake +6% during 4mo to 31 Oct. End markets “remain supportive”. FY expectations unchanged. | ||
Jet2 (LON:JET2) (£2.59bn | SR60) | Rev +5%, PBT +1% to £800.3m. Record passenger numbers and profit. FY outlook in line with exps. | GREEN (Roland) | |
Hochschild Mining (LON:HOC) (£1.85bn | SR84) | Tiernan subsidiary has completed C$58.4m placing. HOC’s proceeds will be C$16.5m. HOC’s holding reduces to 61.9% fully diluted. | ||
Hill & Smith (LON:HILS) (£1.66bn | SR90) | Trading positive with good momentum in US business. UK more challenging. FY expectations unchanged | ||
Genus (LON:GNS) (£1.58bn | SR67) | Strong start to the year, board expects FY adj PBT to be modestly ahead of current market expectations. | ||
WH Smith (LON:SMWH) (£776m | SR43) | Findings following the independent Deloitte Review & Board Changes | Deloitte review found that supplier income recognition has been overstated in North America. Mostly a timing issue. Now expect FY25 NAm trading profit of £5-15m (prev. c.£25m). CEO steps down with immediate effect. | |
Workspace (LON:WKP) (£774m | SR28) | Performance in line with exps. Improved retention and conversion from new enquiries. LFL occupancy -2.5% to 80%, LFL rent roll -3.3% to £107.1m. EPRA NTAV -6.8% to 721p. | ||
Beauty Tech (LON:TBTG) (£247m | SRN/A) | Strong trading in Oct/Nov. Board now expects FY25 revenue and adj EBITDA to be ahead of exps, at no less than £128m and £32.0m respectively. | ||
Eagle Eye Solutions (LON:EYE) (£82m | SR34) | Trading started well in H1, with new wins including North America. Confident in FY expectations. | ||
Likewise (LON:LIKE) (£70m | SR71) | SP -12% PW: YTD sales +8.9% but underlying PBT will now fall short of current market forecasts, albeit will be ahead of previous year. Zeus forecasts: FY25E EPS cut by 25% to 0.9p FY26E EPS cut by 24% to 1.2p | BLACK (AMBER/RED) (Roland) Today’s profit warning has had a surprisingly muted market reaction, in my view, given the scale of the cuts made by house broker Zeus. While I recognise that revenue growth is ongoing here, today’s update suggests cost pressures and possible underperformance in parts of the business may have led to falling profit margins. Today’s revised forecasts have left Likewise shares trading on a forward P/E of >20, which looks high to me given the loss of momentum. I’m inclined to be cautious here until there’s some evidence that profits are returning to growth. | |
Mulberry (LON:MUL) (£67m | SR33) | Rev -4%, but wholesale +36%. Operating loss reduced to £(4.9)m. Trading in line with board’s expectations. | ||
Kooth (LON:KOO) (£46m | SR46) | Acquired telehealth platform for 5-12 year olds from Kismet Health. Expected to help expansion into new states. Financials not material and not disclosed. | ||
Ondo InsurTech (LON:ONDO) (£43m | SR11) | Indiana Farm Bureau Insurance is expanding its use of LeakBot from 10,000 devices to 20,000. | ||
Manolete Partners (LON:MANO) (£39m | SR64) | H1 (to September) saw the first truck cartel claim “combined with a lower than average case settlement value during a quiet summer. Trading in September showed a marked improvement and this has continued into October. New case referrals remain buoyant, at close to record levels.” | ||
PCI- PAL (LON:PCIP) (£37m | SR34) | New integration to Epic, one of the world's leading electronic health record systems, enabling healthcare providers to process payments securely across any channel. | ||
All Things Considered (OFEX:ATC) (£23m | SR19) | Raising money at 125p (most recent close: 140p). “Net proceeds of the Fundraising will provide additional working capital and a strengthened balance sheet to continue ATC's growth strategy,” | ||
Creightons (LON:CRL) (£19m | SR69) | PBT down 11% (£1.5m). Customer issues have restricted growth. “Whilst it is not anticipated that all deferred sales will be recovered, the reinstatement and improvement of these issues is expected to contribute positively in the coming year.” | AMBER (Graham) [no section below] I’d like to be more positive on this but given these numbers, and the commentary accompanying them, I’m inclined to stay cautious. Mark was also AMBER on Creightons in July. The company says that the issues it has faced are beyond its control - such as a contract manufacturing customer delaying product launch until 2027 - but for me this only underlines the very average quality of that side of the business. It does still deserve to trade at a reasonable earnings multiple and based on twice the H1 figures, that multiple is currently 9x, making no adjustment for cash or debt. Cash is over £3m if you are willing to look past £2m of mortgage debt and nearly £1m of leases. This is a brand owner, deriving about a third of revenues from its own brands, although this category (like the company’s overall performance) isn’t growing. Overall, while I think there could be upside, I also think there’s every chance that the stock is fully valued here. So I’ll keep us neutral. | |
Northern Bear (LON:NTBR) (£18m | SR100) | Adjusted operating profit £4.1m (H1 last year: £1.7m), includes non-recurring £1.3m profit. Group continues to trade slightly ahead of current market expectations | GREEN (Graham) Reverting back to fully GREEN here on the basis of the stronger cash position, which reduces the risk level. There are still plenty of risk factors, including the weather, but the stock still trades cheaply against earnings at this level, and it pays a dividend. One of the better nano-caps we look at here, in my view, and it has a StockRank of 100. | |
Zoo Digital (LON:ZOO) (£10m | SR42) | Operating loss $1.2m (H1 last year: loss $2.5m). Trading in line, confident on track to deliver full year results in line with market expectations. |
Graham's Section
Northern Bear (LON:NTBR)
Down 3.5% to 124p (£17m) - Interim Results - Graham - GREEN
It’s not every day I get to cover a company with a StockRank of 100!
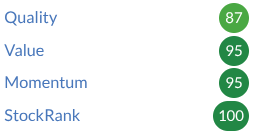
We’ve been moderately positive on this one - clearly we should have been more positive:
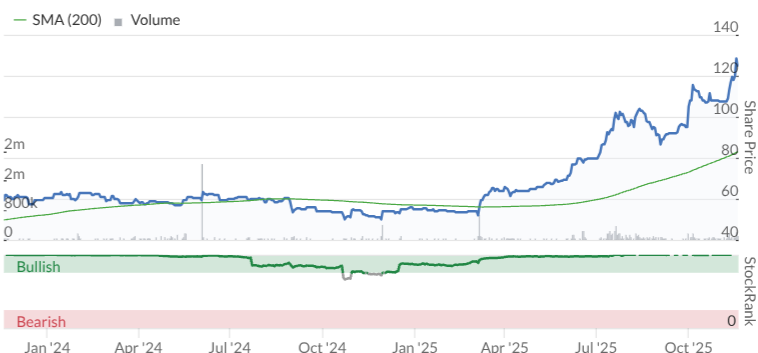
Let’s get the bullet points from today’s interim results:
Revenues +31% (£49.4m)
Operating profit £4.1m (H1 last year: £1.7m)
The operating profit figure for H1 this year includes a £1.3m “non-recurring” profit.
The company is at pains to not say what the non-recurring profit relates to, other than that it “arose from the Group's normal trading activities”.
Interestingly, when the company initially mentioned this mysterious profit in an October trading update, they said it was “approximately £1.0 million”. It has since grown to £1.3m.
If I was to quibble with their presentation, I would say that they could have left this unusual item, whatever it is, out of their “adjusted” operating profit. If the point of adjustments is to show performance that might be repeatable in future, would that not make sense?
The company does helpfully point out that without this item, EPS would be 15p rather than the 21.9p that was officially recorded.
For those who may be unfamiliar, Northern Bear is a group of businesses in Northern England that provide a range of building services: fire protection, roofing, electrical, etc.
Outlook reads well, albeit with some disclaimers. Given the strong share price movement seen in recent weeks, I can understand some profit-taking this morning:
The Group has again traded very well during the first half of FY26 with strong underlying trading performance across all divisions.
Market conditions are largely flat within our major regions and we are finding market pressures starting to affect some of our businesses…
…the Group continues to trade slightly ahead of current market expectations. In addition, the full year outcome for FY26 is expected to be broadly consistent with the strong underlying profit performance for FY25 after adjusting for the non-recurring operating profit referred to above and trading losses and related closure costs in H Peel & Sons Limited (in FY25). This is on the assumption, inter alia, that current market conditions do not worsen, there are no further one-off non-recurring losses, the additional investment in operations continues to meet revenue expectations and that there is no major weather-related disruption.
For FY March 2025, the company made a full-year operating profit of £3.4m, and it adjusted this up to £3.8m to exclude the costs to close a loss-making business.
So it sounds like we are headed for another c. £3.8m operating profit result for FY March 2026.
This implies a very large H1-weighting, as the company already booked £2.8m in H1 (excluding the one-off profits).
Estimates: Hybridian have in fact pencilled in £4m of adj. operating profit for this year, which seems more reasonable than only £3.8m. Northern Bear only needs £1.2m of op. profit in H2 to hit this! They report a “stable” order book, implying a normal level of visibility.
Graham’s view
I’m happy to revert back to GREEN here, a stance that we did take a year ago, with the deciding factors being cash flow and the balance sheet.
With companies of this size and at such lowly ratings, one or two good years can transform the valuation after you take cash and debt into account, and my impression is that this may be happening here.
- Sep 2024 balance sheet: net debt £1.4m.
- Sep 2025 balance shet: net cash £3.8m.
Following very best practice, the company points out that its net cash/debt position is highly variable and can change by £1.5m in days. So they also provide this information:
The lowest position in the Period was £0.6m net cash, the highest position was £4.7m net cash, and the average was £2.7m net cash.
In the interim results last year, they said:
The lowest position in the Period was £2.5m net bank debt, and the highest position in the Period was £0.1m net bank debt, and the average was £1.5m net bank debt.
From this point of view, the change in the average was over £4m.
A stronger cash position means the company is less risky, can invest flexibly into its existing businesses, can think about acquisitions, and can more easily afford to pay its dividend. So I think fully GREEN is appropriate here now.
Roland's Section
Likewise (LON:LIKE)
Down 12% to 24.6p (£62m) - Trading Update - Roland - BLACK (AMBER/RED)
Shares in flooring distributor Likewise have performed well this year, aided by a number of earnings upgrades. Unfortunately, the company has issued a profit warning today. This appears to suggest that respectable revenue growth has not been sufficient to outweigh the impact of higher costs.
Trading update & revised guidance: today’s update reports sales growth of 7.2% so far in the second half of the year. While positive, that’s below the 10.2% achieved in H1, giving year-to-date revenue growth of 8.9%.
Within the group, sales in the Likewise Floors business rose by 13.3% during the period. This suggests to me that the Valley wholesale business (acquired in 2022) may have underperformed.
Management strikes a bullish note on trading in “challenging markets”:
This has all been achieved in what would still be considered challenging markets, compounded by the hottest summer on record and demonstrates consistent increases in share over the last five years.
… but then goes on to cut profit guidance for the year:
Due to increased costs and an imbalance in the revenue increases across the Group's various activities, Underlying Profit Before Tax will fall short of current market forecasts, however the Group will produce Profit significantly ahead of previous years, notwithstanding absorbing the additional National Insurance Contribution costs.
The company’s comment about an imbalance in revenue growth across its business is a little vague, in my view. But if I’ve understood correctly, I think it may support my idea that parts of the business (Valley?) have underperformed, resulting in a hit to overall margins.
Updated Estimates
With thanks to house broker Zeus for making its notes available on Research Tree, we have updated forecasts today. While revenue estimates have been tweaked slightly higher, there are big cuts to earnings expectations:
FY25E adj EPS: 0.9p (-25% vs 1.2p previously)
FY26E adj EPS: 1.2p (-24% vs 1.6p previously)
Even after this morning’s share price drop, these forecasts leave Likewise on a FY25E P/E of 27, falling to a P/E of around 21 in 2026.
Roland’s view
Likewise was styled as a High Flyer by the StockRanks prior to today’s warning, thanks to a string of earnings upgrades this year:
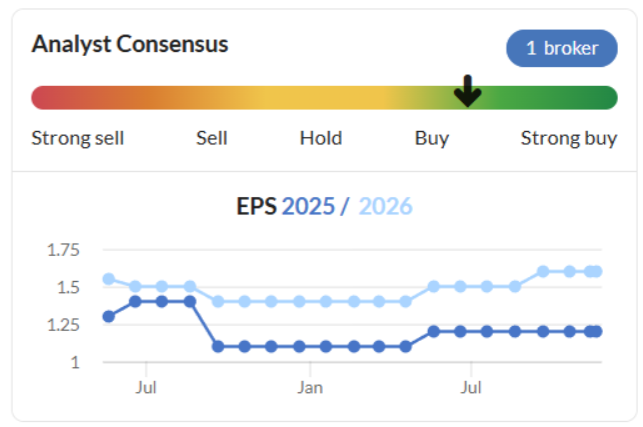
That run of upgrades has clearly now ended, with earnings forecasts for 2025 and 2026 now cut to levels lower than any previous consensus forecast this year.
With the benefit of hindsight, there was some clue to today’s warning in September, broker Zeus raised revenue forecasts but left earnings forecasts unchanged. It was clear that rising costs were preventing the kind of operating leverage we might hope to see from rising sales.
Looking at today’s forecasts, revenue growth is expected to be c.8% in 2025 and 2026. In my view, that’s respectable, but not overly exciting against a backdrop of low single–digit inflation.
As Graham pointed out in September, flooring can be a difficult sector with inconsistent profitability. I’m surprised today’s share price drop hasn’t been greater. A forward P/E of 20+ for a low margin distributor doesn’t seem to offer any margin of safety, in my view. I suspect the StockRanks will show a sharply reduced MomentumRank after today’s updates are digested, resulting in a loss of the stock’s High Flyer styling:
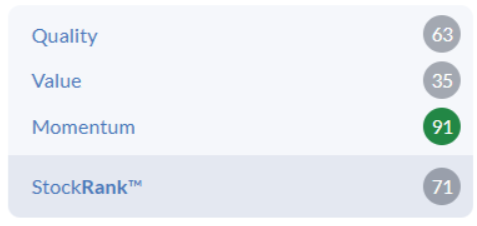
Given what we know about profit warnings often signalling the start of a longer period of underperformance, I’m going to take a cautious view today. AMBER/RED.
Jet2 (LON:JET2)
Up 3% to 1,339p (£2.7bn) - Half-Year Results - Roland - GREEN
I took a positive view on holiday operator Jet2’s results in July. But in September, the company advised investors that operating profit could be at the lower end of the consensus range this year due to limited visibility on bookings in “a less certain consumer environment”.
The good news today is that there is no further hedging on guidance – the company simply says it’s trading in line with expectations.
H1 results summary
Jet2 says today’s H1 results show record passenger numbers, revenue and profitability. Despite “a fast-moving, late booking market”, passenger numbers rose by 5.6% to 14.1m. This wasn’t quite enough to absorb an 8% increase in seat capacity to 15.98m, causing the average load factor to fall to 88.2% (2024: 89.8%).
Even so, this performance supported a decent set of financial results:
Revenue up 5% to £5,342.2m
Pre-tax profit up 1% to £800.3m
Earnings per share up by 8% to 300.4p, aided by buybacks
Interim dividend up 2% to 4.5p per share
New £100m buyback programme
Profitability remained very strong. While the H1 operating margin of 13.4% (H1 25: 13.8%) reflects peak summer trading (H2 is normally loss making), my sums suggest a trailing 12-month return on equity of 23.6%. Although this is below the c.30% figure reported last year, it’s still a stronger result that’s in line with the group’s historic range.
Trading commentary: the mismatch between profit and revenue growth tells us that Jet2 has not been able to fully pass on all cost increases to its customers.
Reading the management commentary suggests the main area of cost growth was in the holiday business:
Hotel accommodation costs increased 7% to £2,295.3m (2024: £2,137.2m) primarily due to inflationary rate increases of 6%, an increased proportion of bookings to higher star rated hotels, plus customer volume growth, partially offset by a 2% currency benefit for Euro-denominated hotel costs.
There were also cost increases in other labour-intensive areas, such as airport handling, staff costs and in-resort transfers.
Balance sheet: this business is also differentiated by its very strong balance sheet. Jet2 had gross cash of almost £3.4bn at the half year, with net cash of more than £2bn including all debt and lease liabilities.
The strength of its balance sheet gives Jet2 the option to invest and manage its operations for quality long-term growth, in a way that might not be possible if it had less flexibility.
Although it’s worth noting that the cash balance includes around £1.3bn of customer deposits on advance bookings (and hence future obligations), this isn’t uncommon in this sector. The only time it could become a problem would be if Jet2 had to stop operating normally, as it did during the pandemic – hopefully an unlikely scenario.
Buybacks: I am not always a fan of buybacks, but Jet2’s profitability and valuation at 1.3x book value mean I’m quite comfortable with the decision to repurchase more shares. My sums suggest such spending should generate a double-digit return on investment, in addition to providing a useful boost to earnings per share.
Outlook & Estimates
Guidance is left unchanged today, with Jet2 helpfully specifying a consensus operating profit forecast of £453m – broadly unchanged from last year.
The actual result may be influenced by start-up costs at the company’s new London Gatwick base, but I don’t see this as a concern given the company’s disciplined record of expansion.
Broker Shore Capital has provided updated forecasts today, leaving FY26 almost unchanged, but trimming its earnings estimates for the following two years:
FY26E adj EPS: 222p (prev. 223.2p)
FY27E adj EPS: 195.3p (prev. 218.6p)
FY28E adj EPS: 216.1p (prev. 238.6p)
Taking FY27 as the lowest of these prices Jet2 on a P/E of seven after this morning’s gain – that still looks reasonable to me.
Roland’s view
This business is inescapably cyclical and is also exposed to commodity prices and general inflation. However, I believe it’s well run, very profitable and currently quite reasonably valued.
While there’s obviously some uncertainty about the outlook, I can see plenty to like here on a medium-term view and share the StockRanks’ view of this as a Contrarian stock.
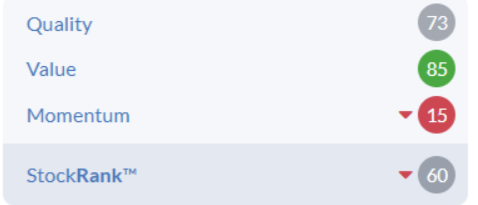
I’m going to take a chance and leave my GREEN view unchanged today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
NVIDIA (NSQ:NVDA)
In a rather conservative mode and after these incredible results and the upgraded guidance, the net cash balance will be north of $350B by 2028.
That’s Biliions!
As always
All the best
Is there an option to block certain posters on Stocko ?
Send an email to Jensen maybe he can help you…jensenhuang@nvidia.com
He seems to have all the right answers these days.
Is that the best you can do ?
yiannos1@trulyobnoxious.com
$350B! That’s a heck of a lot of cash. Provided they don’t lend any of it to the hyper scalers, that would be nearly 8% of current market cap. That would make an Enterprise value of only $4.18T.
That’s Trillions!
Ps. Just having an ironic joke with you Yiannos. I always enjoy and respect your posts and you would be the last person I would block. All the best.
NVIDIA (NSQ:NVDA)
The poster child disappoints….. yet again.
Bad numbers and bad outlook…… yet again.
As always
All the best
NVIDIA (NSQ:NVDA)
There is nothing worse than posting a couple of meaningless lines about this company.
I get the bitterness of being left out of the best performing stock of the decade. That I do understand!
I get the feeling of being left out of this amazing US market and the incredible gains it has given in 2025. Where do I start? The data centres? The quantum computing stocks? The rare earth stocks? All covered here by myself before they have moved upwards. Rocket Lab (NAQ:RKLB)? When this was $6!
But if you want to play this game of the bubble narrative then one should give numbers and analyse them in detail.
I have personally done this here when NVIDIA (NSQ:NVDA) was trading at $107.
NVIDIA (NSQ:NVDA) has also been sold many times and the biggest was during the 2022 bear market when it lost about 60% of its then value. Always comes back stronger……
Just remember if NVIDIA (NSQ:NVDA) fails then the FTSE100 will be back to 7500!
At least….
Be careful what you are wishing for.
As always
All the best
Personally, I think companies like MSTR are the poster child for the BS in the markets at the moment, which is not just an AI bubble but more of a leverage bubble of people doing stupid shit with lots of leverage in any field that has momentum upwards.
Nvidia on the other hand is one of the best businesses in the world, with amazing products/growth and correspondingly trades at a pretty premium price.
Correct 100%!
All the best
Jet2 (LON:JET2) adding a new base at Gatwick should have quite an impact I would have thought - they will be serving 29 routes from the end of March, bringing a welcome alternative to easyJet (LON:EZJ), who currently operate a staggering 47% of flights from the airport.
WH Smith (LON:SMWH) I’ve contacted the FCA asking that they instigate a review, along the lines of the Tesco saga some years ago, to establish if compensation is due to those shareholders who were misled by June’s RNS, prior to the admission that there were errors in North American financials, which stated that the market expectations were realistic.
Hi Graeme,
Writing this on a Chromebook using hotel Wifi, hopefully you don't notice much difference! Cheers.
I'm reading it on a Chromebook. Isn't it great when it works without taking ages to install an update when you want to use it, in spite of all your efforts to take control and get it done while you sleep.
A further revised offer for International Personal Finance (LON:IPF) with another extension of the PUSU deadline. Same offer price, but this time, as the whole charade is taking so long, it now includes the year end dividend up to 9p as well.
Where are you reading this?
An RNS was released at 11am, so missed the usual news sweep first thing.
Doesn’t appear to have been attached to the International Personal Finance (LON:IPF) page on Stocko either. Thanks.
Doesn’t appear to have been attached to the International Personal Finance (LON:IPF) page on Stocko either. Thanks.
It is:
https://www.stockopedia.com/ne...
Most notably the bidder has now gone off to look down the back of the sofa for the funds to complete the transaction:
The sole remaining pre-condition to the Further Revised Possible Offer is the raising by BasePoint of finance for the Further Revised Possible Offer. BasePoint has asked the Board for more time to bring this financing to a conclusion. The Board understands that BasePoint is continuing to make constructive progress regarding raising finance.
timarr
....but they already did that last time. This is getting really annoying!! International Personal Finance (LON:IPF)
Re: Likewise
My local flooring contractor used to comment that he had two distinct drivers of business. The housing market and Christmas. The rest of the year was steady with Summer (or the weather in Summer) not really being a factor.
The Housing and Construction sector has been quite weak recently so perhaps not much of a surprise that this was a miss.
One problem nowadays is that carpets are very durable and will last years. Without a pressing need to replace, it has become more of a discretionary spend rather than a necessity. When budgets become squeezed, it will be some way down the list of priorities.
Undoubtedly, companies such as Likewise are linked to the housing market and could be one of the first indicators of an upturn. Its a sector that I am monitoring for a turnaround - eventually.
Is there a case for Sage (LON:SGE) being cheap, on a forward PER of only 22.4 according to Stockopedia? The company has been tracking good eps growth since 2022, it has a strong market position, and reliable software ARR usually gets valued more highly than do industrial businesses generally. I see the Stock Rank is low - only 44 - reflecting the poor momentum score - and it is classed as a Falling Star.
Sage (LON:SGE)
Is there a case for Sage (LON:SGE) being cheap, on a forward PER of only 22.4 according to Stockopedia?
sure if they can grow profits organically at 10% PLUS per year on average for next 10 years - the rating doesnt look expensive. They are clearly in sweet spot now. I can say historically their customers tend to be very sticky - so i am positive ref outlook and happy to hold.
obviously with pe rating of 22 they need to keep churing out decent clean profit increases each year really if you want "uplift" from where you are now. so perhaps i might use something more along the lines of garp (growth a ta reasonable price) rather than cheap.
I see the Stock Rank is low - only 44 - reflecting the poor momentum score - and it is classed as a Falling Star.
momentum speaks for itself (and is poor) I would be interested for explanation of why value score is so low here - is that expected to be the case with p/e of 22. is the company still being penalised for lower numbers back in 2023? If this companies value is in the brand - does this get ignored as its not a tangible asset. looks like its the case of 2 out of 3 is bad ref dropping ratings. can we track historical value numbers?
I've learnt to never fight the Falling Star. When I see a share like Sage (LON:SGE) , that I would like to own, I set an alert - Fundamental Alerts - Other... - Profile - StockRank Style and then choose Exclude and I include all four losing styles including Falling Star. That way, when it ceases to be a Falling Star, I will get an alert. Loss of momentum from a high flying share can last for years and although I think Sage (LON:SGE) is a great business, it doesn't offer enough yield to warrant the wait for sentiment to turn. As the saying goes, the market can stay irrational longer than you can stay solvent (forgive me if I've mangled this truism).
NVIDIA (NSQ:NVDA)
The poster child of the AI/tech bubble????
I think you have gone too far with this one. No need to read this nonsense.
All the best
Nobody likes the guy who takes away the punchbowl at the end of the party
What does this had to do with NVIDIA (NSQ:NVDA)?
What does NVIDIA (NSQ:NVDA) have to do with the AI bubble?!
I thought so!
Northern Bear (LON:NTBR)
its all a bit messier than i would like.
the problem here is that first half trading has been exceptional - they seem to be in a great sweetspot - albeit they concede market conditions are tough.
they say trading is slight ahead of expectations up to now
they then ruin the whole show by saying the full year outcome is only expected to be "broadly consisent with 2025"
· The Trading Update on 1 October 2025 outlined the positive underlying performance during H1 FY26 and the Group continues to trade slightly ahead of current market expectations. In addition, the full year outcome for FY26 is expected to be broadly consistent with the strong underlying profit performance for FY25 after adjusting for the non-recurring operating profit referred to above and trading losses and related closure costs in H Peel & Sons Limited (in FY25).
i just dont get it
Had this non-recurring operating profit been excluded, operating profit, EBITDA and Basic earnings per share for the Period would have been £2.8 million, £3.6 million, and 15.0 pence per share, respectively.
so we have £2.8 mill H1 operating profit removing the items above
we can expect to broadly match last years £3.4 mill
so they are expecting only £0.6 mill operating profit h2
if thats what they deliver the market will be looking at the h2 and saying they have gone into decline.
Whats probably more important is what they expect for ye 31/3/2027 - so we ideally need broker updates ref 2027 - if they are setting higher bar for 2027 thats fine.
so the mismatch here to me is that if there is an explanation ref dropoff i have missed it
Note
they are clearly investing here - so i dont have any issue with one 6 montn period having lower profits - but if my calcs are right they might have glossed over this.
i havent had deep dive so i might have missed something.
Note they tend to be conservative and not over promise - so there is deffo scope for them setting very low bar ref ye numbers - in that regard if they will end up with better than £0.6 mill operating profit h2 - i kinda wish they would have the confidence to have slightly higher expectations.
Any of my above calcs may be wrong or wide of the mark here !!
Northern Bear (LON:NTBR)
Good questions rmillaree, last year's result was actually £3.8m after adjustments so that is what they have suggested. In this case "broadly consistent" does not necessarily mean below, as you say they tend not to over-promise and as I point out above, Hybridian are forecasting £4m. Unfortunately Hybridian does not offer FY27 forecasts yet.
Northern Bear (LON:NTBR) i'm delighted with the results and take confidence in what the mgt do, not what they say. they have busted forecasts for the last 2-3 years. i estimate very bad weather can cost them c.0.4m in profit phasing. so as Graham says the broker is implying 1.2m for H2, when last year they did 1.8m in great weather conditions. Thus i think mgt see only upside from the broker forecasts since they can't control timing of the weather.
mgt in the last 5 years have regularly beaten forecasts, have grown the business from c3m ebita to c.5m through covid, recessions, interest rate hikes etc..., they've bgt back 25% of shares, and turned from 3m debt to 3m AVERAGE meet cash - they are doing very well.
additionally, last year they had 400m closure costs that they took above the line without a whimper, this H1 they increased by 60%, and they have 1.3m of exveptional profit. my conclusion is that they very likely have a nice nest egg up their sleeve - stated provisions alone are 500k.
and lastly, for a business that has been steady for 10 years, I'm delighted, and totally trust the mgt to be INVESTING - hopefully that means higher profits in years to come.
disc i hold (1 of top 5)
Northern Bear (LON:NTBR)
cheers Graham - thanks for your correction here - i was very much in speed mode when i looked at it this morning so nice to see its slightly higher expected figure - plus broker seems to be going higher again. Factor in some seasonal bias towards summer and ongoing investemnt and its probably not as bad as it looks.
what i do need to remember now though is that shareprice has doubled from where it was - so going back to the bald old days of profits at £1.5 to £2 mill and it wont be as easy to justify higher value. So i would be happy to bank profit here - but i still think it perhaps has further to run if they are being uber cautious and might deliver £3.5 mil plus net profit sooner rather than later.
for small company like them i get the felling that whilst they are more procative than they used to be - they would rather spend time earning their crust rather trying to predict then future.
can i ask have you meet the mgt? i have been impressed with the new CEO and the broader team seems much more shareholder focused, i think ironically started with the Canadian ex major shareholder (i've also talked to directly).
for me, the cash flow record is tremendous, twice reducing debt to net cash, and share count reduced twice in recent years. from my analysis, there is no other company worth MV <25m (UK market + aim) that can match these statistics.
i agree, they operate in cyclical businesses, the good news is that at the moment we seem to be at the bottom of the cycle. fingers crossed.
one is able to buy in size today so seems a seller offloading to counter the buys.
my chart analysis supports rise back up to previous highs
disc i hold
Northern Bear (LON:NTBR)
can i ask have you meet the mgt?
Nope
i have been impressed with the new CEO and the broader team seems much more shareholder focused, i think ironically started with the Canadian ex major shareholder (i've also talked to directly).
to be fair to the old lot the results were never terrible and back in the day the balance sheet did need strengthening to see them through the cycle. Hey ho seems to be more progress now though and i dont think that much has changed fundamentally - i do like the lets just invest here and branch into this or that in as organic matter as possible - kind of just extending on what they know works. They are probabaly a semi go to name ref bigger jobs now so councils and the like probably like dealing with outfits like NTRB as they are tried and tested. Eg the decent contract they have recently completed for Newcastle council.
https://northernbearplc.com/mg...
for me, the cash flow record is tremendous, twice reducing debt to net cash, and share count reduced twice in recent years. from my analysis, there is no other company worth MV <25m (UK market + aim) that can match these statistics.
I dont think its ever really been a problem particulalry - just they had some historic stuff (acquisitions etc needed to be paid for ) - its a nice simple business that profits will turn to cash sooner or later - with the odd caveat that at some stage they will face bad debt nasties - or contract dispute nasties from time to time.
Have been tempted to sell out if things did look toppy but there is enough to keep me here for now.
I am intrigued by the Creightons (LON:CRL) interim results today. The drop in profitability was expected, and is in the share price. Their outlook comments are surprisingly positive. They are still cash generative, despite the lousy backdrop, and the net debt accumulated after Covid has been eliminated, and there is now a healthy net cash position. The report emphasises tight working capital management. The downside to this business is of course the very slender overall operating margin, and of course they are in a very competitive line of business. I am out of this at the moment, not liking anything UK consumer facing, but that could change.
Today's data is positive and some banks will increase the chance of a rate cut in December but mainly due to a 0.6% falling away at the back. 0.4% current month is still a little high....and there are no large numbers falling away until April....so current numbers will carry the weight for the next 3-4 months.... April last year at 1.2% upset things a little but could be a positive next year if not matched. My conclusion is don't get too carried away by rate cut prospects especially ahead of the budget. If things are really slowing quickly then a rate cut or two won't make a huge difference anyway..... fingers crossed for something good in the budget for sectors like construction and housing. UK Bond markets have hardly moved today.
Everything's going in the right direction in Crimson Tide (LON:TIDE) interims today. Its tiny, new CEO and Chair, and in recovery after 18 months of distraction from two take-overs/mergers that didn't happen.
Excellent Results from Ithaca Energy (LON:ITH) today, which gets 99 ranking. The dividend yield is still around 10% even after the share price more than doubling. I held a then losing stake but couldn’t resist averaging down at what seemed at the time an extraordinarily oversold price of £1.04 in 2024.
Both stakes are now well up…..but the £1.04p average down (now up 130%) is yet another example of buying on big undeserved share price dip paying off in spades. Buy quality on big dips and top slice after subsequent big gains. It usually works. Buying after big gains, is obviously much riskier, and after a lot of profit had been there for the taking, but for some reason a lot of investors seem scared to buy when”there’s blood on the streets,” and wait until it looks safer but by then the previous (missed) share price gains means the downside risk is higher.
The dividend yield at that £1.04p buy price is well over 20%. That’s a real reward for shareholders, unlike the supposed “reward to shareholders” from buybacks where shareholders don’t receive any cash, and when despite the buybacks the share price then falls.
Share Buy-Backs help Executive Directors achieve share-price targets for bonus payment and is the reason for their being.
Happy Nvidia day all.... VIX has already spiked from 17 to 25....and normally I think don't get too bearish when Vix is already 20+ .... MOVE which measures Bond volatility is picking up. from 66 to 83 but 83 is still low in a post covid world. I think this is more of a risk ....that it returns to 100-125. My guess is it won't be Nvidia results that do it...more interest rate confidence and therefore inflation data. In the UK (for what it's worth) this is well behaved today. What's the point? Well we are already alerted to market strength for my guess, a whole host of reasons, not least year end, result in profit taking and position tweaking after very good runs. The crux for me is whether this years trends have another run next year or not... so I guess guidance will be the big tell from Nvidia but who knows. The point is market risk measures have already moved a decent push.... and something very negative would be needed to push them worse... let's hope not.
and meant to add that UK equities are such a small part of portfolios these days that of course all these international events matter more than ever.
Any thoughts on hedge funds now being the biggest holders of US treasuries RD through the basis trade do you see any near term issues with this possibly blowing up ?
Short answer is who knows? Im not so concerned about a basis trade to be honest....a very big low risk trade which is I think market neutral. Forced sellers of Treasuries could be a problem, mainly because the solution is probably QE and fed buying... but investors mainly hold Treasury because they have to for some reason.... so we should in theory start to see lots of warning signs that liquidity is drying up and repo markets under pressure etc Treasury yields being too high, despite rate cuts would be a bigger problem for equities and any asset that uses low yields for valuation but that's another matter.......
I can't help remember all the presentations in 2001-2002 I was giving trying to explain why 10ish interest rate cuts hadn't made any difference as being relevant next year.....
Thanks for the reply as always.
It was great meeting Graham, Roland and some other subscribers yesterday at Mello. Also shout out to Mark for a fantastic presentation. Looking forward to see the Stocko presentations today and meeting more subscribers, so if you see a young handsome Spaniard don't hesitate to come and say hola