Daily Stock Market Report (Wed 22nd April 2026) - CER, LIO, RKT, TPX, QTX, PINE, SHOE, TENG

Good morning!
The FTSE is set to open lower this morning, below 10,500, after weakness yesterday afternoon.
The US-Iran ceasefire has been extended, but not in a very meaningful way:
- The two sides never met for face-to-face talks in Islamabad, with Iran stating that US demands were unreasonable.
- The Strait of Hormuz remains closed.
- The US blockade remains in force.
So why is the ceasefire still in place? Apparently because the government of Pakistan, which is mediating, asked Trump to hold off on fresh strikes. Brent crude is now at $98.
Live webinar on Thursday at 5pm: with results season over, Ed and I will be taking a fresh look at our favourite investment ideas tomorrow evening. Here's the registration link.
Wrapping it up there, thank you.
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
BHP (LON:BHP) (£151bn | SR83) | Copper production is expected to be towards the top end of FY26 guidance. Iron ore production on track. | ||
Reckitt Benckiser (LON:RKT) (£32bn | SR74) | Revenue down 11.8% due to weakness in N. America & Mead Nutrition. LFL revenue +0.6%. FY revenue guidance unchanged for Core LFL revenue to be +4% to +5%. | AMBER/GREEN = (Roland) This trading update flags up a number of headwinds, most of which I believe are temporary. Although earnings forecasts have fallen recently, my impression is that the core business is probably performing well and looks unusually cheap on a forward P/E of 13 and 5% dividend yield. With the caveat that I see this as a long-term investment, I am leaving my broadly positive view unchanged today. | |
Fresnillo (LON:FRES) (£24.5bn | SR87) | Silver production -8.5% to 11.1moz vs Q4 25 due to lower grades and ore volumes. Gold production up 0.7% to 136.1koz. Performing in line with 2026 expectations. | ||
South32 (LON:S32) (£10.5bn | SR77) | Production guidance is unchanged for all operations except Australian Manganese, where elevated site water levels remain an issue. Net cash rose by $121m to $96m during the quarter, due to higher commodity prices. | ||
Bunzl (LON:BNZL) (£7.7bn | SR96) | Revenue up 1.5% in Q1 at constant exchange rates, supported by volume growth and tariff-related price increases. 2026 guidance unchanged. Continue to expect operating margin to be slightly down year-on-year. | ||
Croda International (LON:CRDA) (£4.2bn | SR86) | Revenue up 1% to £431m at constant currency. Strong growth in Beauty Actives and Fragrances & Flavours, lower sales in Crop Protection. No change to 2026 expectations. | ||
Aberdeen (LON:ABDN) (£3.9bn | SR93) | AUMA -1% to £547.7bn, with net outflows of £2.9bn. Interactive Investor customers +14% year-on-year, with net inflows of £3bn. Firmly committed to FY26 targets for adj op profit of at least £300m and net capital generation of c.£300m. | ||
JD Sports Fashion (LON:JD.) (£3.7bn | SR83) | Chair Andrew Higginson will stand down at July’s AGM. He’s been in the role since July 2022. A search for a replacement is underway. | ||
Hochschild Mining (LON:HOC) (£3.4bn | SR75) | Q1 26 attributable production in line with expectations: gold 55,252oz, silver 1.6moz. Mara Rosa turnaround on track. 2026 production guidance unchanged: 300-328k gold equivalent ounces & AISC of $2,157-$2,320/ge oz. | ||
Quilter (LON:QLT) (£2.5bn | SR72) | AuMA of £141.91bn at end March, +19% year-on-year. Net inflows of £3.0bn. | ||
Renewables Infrastructure (LON:TRIG) (£1.58bn | SR74) | Company notes a series of government policy announcements relating to energy. In particular, TRIG believes changes to Contract for Difference could “increase revenue stability for generators”. | ||
Senior (LON:SNR) (£1.20bn | SR76) | Revenue up 2.5% vs prior year at constant exchange rates with strong performance in aerospace. “... full year performance anticipated to be above the Board’s previous expectations”. | PINK | |
GB (LON:GBG) (£516m | SR69) | Strong growth in core Identity and Location segments. FY26 revenue up 3.2% to £285m, with H2 growth in “mid-single digits”. FY26 adj operating profit to be c.£67.6m (FY25: £67.0m). FY27 outlook unchanged. | ||
Cerillion (LON:CER) (£422m | SR45) | Signed Omantel in January as a major new client, with an expected contract value of c.£42.5m. FY results are expected to be “strongly weighted” to H2, with H1 revenue to be c.£18m and H1 EBITDA c.£6.2m. The Board believes Cerillion “remains well-positioned to meet market expectations” for the full year. | AMBER = (Roland) Today’s update is in line, but includes guidance for a very unusual 74% H2 weighting to EBITDA profit. This appears to be based on expectations that the order book, including the recent Omantel deal, will start to unwind in H2. I can see the potential for this, especially if this includes recognition of a licence fee from the Omantel deal. However, management’s lack of disclosure around the value of the order book or the scheduled unwind means investors are left with no visibility and an uncomfortable dependency on H2 performance. I admire the quality and track record of the business, but I think the share price looks up with events and can see some risk that H2 will disappoint. On balance, I’m staying neutral today. | |
Tharisa (LON:THS) (£348m | SR99) | Jacques Breytenback is appointed as CFO Designate with effect from 1 May. He will assume the role from 1 August 2026. He has 25 years experience in mining, including Petra Diamonds and Anglo American Platinum. | ||
Malibu Life Holdings (LON:MLHL) (£323m | SR34) | Book value per share up 4.5% to $33.33. Total comprehensive income of $24m, shareholder equity of $569m. Outlook: remains committed to the medium-term target of generating annual premiums of $5bn and mid-teens return on equity by the end of 2028. | ||
Pinewood Technologies (LON:PINE) (£278m | SR11) | 2025 revenue up 29.8%, adj EBITDA up 17% to £16.4m and pre-tax profit up 3.5% to £8.8m. Total Contract Value of £64.5m at the end of 2025, reflecting incremental future revenue. FY26 EBITDA to be in line with market expectations (consensus: £21.3m). | AMBER ↑ (Graham) [no section below] We turned negative on this at last month's profit warning. Today's full-year results are accompanied by an in-line outlook statement: the business is growing very strongly (+30% in 2025) and is forecast to continue growing the top line as it continues rolling out its software across North American dealerships (+32% growth forecast for 2026). There is "system testing underway" at the major US dealership group Lithia while in the UK, both Marshalls and Lookers are coming on board. Looking ahead, the company says it's confident that it will achieve underlying EBITDA of £58-62m by 2028, versus just £16m in 2025. Given the very impressive growth that it's achieving, the fact that it's achieving success in the United States, and the apparently central role played by its software across an entire industry, I think it's a little too dangerous for us to stay negative here, even if the rollout may see further delays. The P/E multiple is 34x but there's a lot more under the hood here. | |
Ferrexpo (LON:FXPO) (£258m | SR59) | Board believes an equity capital raise is the only viable solution to raise required funding. Intends to launch a fundraise for at least $100m as soon as possible following shareholder approval. Talks are underway with 49% shareholder Fevamontinico in relation to the planned fundraise. | ||
Helical (LON:HLCL) (£240m | SR43) | “Strong progress” during the quarter, with further lettings to tech/AI clients. Notes “strong rental growth being driven by a market with very tight supply”. | ||
Kistos Holdings (LON:KIST) (£220m | SR53) | 21.8 kboepd in Q1. FY26 proforma production guidance remains at 19 - 21 kboepd. Adjusted net debt $78m. | ||
Kenmare Resources (LON:KMR) (£205m | SR23) | “Kenmare is on track to achieve its 2026 guidance on all metrics and drew down 99,900 tonnes of its finished product stockpiles in Q1, in line with its value over volume approach.” | ||
Pulsar Helium (LON:PLSR) (£175m | SR28) | Pulsar Michigan has entered into an exclusive Option to Lease Non-Hydrocarbon Gas Agreement, covering 488,090 gross acres. The agreement “marks a transformative step for Pulsar and for our Falcon Project in Michigan”. | ||
Liontrust Asset Management (LON:LIO) (£166m | SR87) | Net outflows of £0.8 billion. AUMA falls from £21.5bn to £19.6bn. | AMBER/GREEN = (Graham)
Being AMBER/GREEN on this has been a mistake, as I’ve naively thought that it offered value for some time. There are now £124 of AUMA for every £1 spent on Liontrust shares at the current level. That’s actually less cheap than it was in January, when I last looked at the company - so I’m still sitting in the camp which says that the shares might offer some value here, and that they could have hit a bottom. The company is expected to see a solid profit margin this year, with the high forecast dividend yield (7%) easily covered by earnings per share. | |
Quartix Technologies (LON:QTX) (£135m | SR82) | Q1: new subscriptions and the rate of customer acquisition were lower year on year but prospects remain encouraging for the rest of the year. Revenue and profit are in line with achievement of market expectations. | AMBER/GREEN ↓ (Roland) [no section below] Today’s sell-off has no doubt been prompted by the fall in new customer acquisition versus last year. I think this could be a little harsh. Annualised recurring revenue growth over 12 months to 31 March was 12%, compared to 14% in calendar 2025. Similarly, customer growth is still positive, with the customer base increasing by c.1% in Q1 versus the 2025 year end. Quartix has reiterated full-year guidance today, suggesting c.16% EPS growth this year. The P/E of 16 doesn’t seem unreasonable against this backdrop and I think the business remains attractive on a medium-term view (see my comments on the FY25 results). I am going to revert to a moderately positive view to reflect slower growth and today’s unchanged forecasts. | |
LBG Media (LON:LBG) (£112m | SR80) | Increasing FY26 revenue expectations to c.£110m. However, the revenue mix has lower margins, so Group FY26 EBITDA is to be c.£22m (consensus: £25.4m). | BLACK | |
Ten Lifestyle (LON:TENG) (£71m | SR72) | SP +11% Trading since the period end has been in line with the Board's expectations for FY 2026. But the Board now expects FY 2027 revenue and adjusted EBITDA to be ahead of current market forecasts, due to contracts won during this financial year. | AMBER/GREEN ↑ (Graham) [no section below] I nearly upgraded this to AMBER/GREEN in January, when it announced an interesting new contract. Today we have confirmation that new contracts are setting up the company to beat market expectations for FY August 2027 (the financial year starting in four months). I like the value on offer here: the P/E was 12x as of last night, which might sound fair, but there's the potential for very significant operating leverage from this point on. H1 EBIT was £1.6m, on net revenue of £33.7m, similar to the prior H1 period, but a few large contracts could see this figure take off in the years ahead. TENG's services are used by high-net-worth banking clients, a demographic that is likely to grow in size, and TENG is well-placed to cater this demographic internationally. It's diversfied across Europe, the Americas, and Asia-Middle East-Africa. I'm increasingly a fan of this stock. | |
Fevara (LON:FVA) (£66m | SR56) | “Trading since the half year has been encouraging, with continued strong performance in the UK and further margin improvement. The Board is confident in delivering a full year outcome in line with market expectations”. | ||
hVIVO (LON:HVO) (£63m | SR36) | Signed a contract to conduct a Phase III human challenge trial for ILiAD Biotechnologies, Inc. to test its Bordetella pertussis vaccine candidate. “This multi-year contract will make a strong contribution to near- and mid‑term revenues.” | ||
MTI Wireless Edge (LON:MWE) (£59m | SR96) | Antenna division has received two orders, totaling approximately US$1m, to supply military antennas. | RNS Reach - this announcement should not have any impact on forecasts. | |
Creo Medical (LON:CREO) (£53m | SR61) | Strong trading performance in Q1 FY26. Year-on-year revenue growth of 60%, the upper limit of management’s expectations. On track to deliver 40% to 60% full year revenue growth. | ||
R E A Holdings (LON:RE.) (£51m | SR82) | Revenue +3.7% ($194.9m). PBT $24m including non-routine losses of $3.8m. Current CPO prices comfortably above the 2025 average. Outlook encouraging for increasing returns from the agricultural operations, augmented by contributions from stone and silica sand. | ||
Tpximpact Holdings (LON:TPX) (£35m | SR94) | Expects to comfortably exceed the recently upgraded consensus across all key financial metrics. Revenue +1%. Adjusted EBITDA +54% (£8.6m). Net debt reduced to £4.2m. | AMBER/GREEN = (Roland) A second upgrade in two months means estimates for FY26 earnings (y/e 31 Mar) have now risen by nearly 50% since the start of the year. I am impressed by progress but note our previous concerns on the dependence on large UK government contracts. Although the forward P/E of 8 looks very affordable, I’m leaving our moderately positive view unchanged today to reflect the company’s track record of reported losses – I’d like to see statutory profits as well as adjusted earnings before being fully positive. There’s no doubt momentum looks strong at the moment, though. | |
Celsius Resources (LON:CLA) (£24m | SR20) | Trading on AIM is unaffected but the company has requested a trading halt on the Australian exchange. Something to do with “developments associated with an alternative conflict resolution process and governance of its Philippine affiliate company, Makilala Mining Company, Inc”. | ||
Shoe Zone (LON:SHOE) (£24m | SR80) | SP down 6% | BLACK (RED =) (Graham) [no section below] | |
Alien Metals (LON:UFO) (£19m | SR27) | Inaugural Mineral Resource Estimate for the Elizabeth Hill Silver Project in Australia. 2.79 million ounces of silver, comprising 0.37 Moz Indicated and 2.42 Moz Inferred. | ||
Prospex Energy (LON:PXEN) (£14m | SR18) | Subsidiary PXEN Tatra has been formally awarded the Dunajec onshore licence area in Poland. | ||
Wishbone Gold (LON:WSBN) (£10m | SR9) | Raised £1.1m gross at 26.35p (last night’s close: 31.5p). 1 warrant issued for every two new shares, strike price 40p. |
Graham's Section
Liontrust Asset Management (LON:LIO)
Up 1% at 272p (£168m) - Trading Statement - Graham - AMBER/GREEN =
There’s zero surprise to read of more outflows here:
Net outflows in the quarter of £0.8bn
AUMA falls from £21.5bn to £19.6bn
On the bright side, £2.6bn of AUMU is set to come in from the acquisition of River Global (LON:RVRG), and there are £500m of institutional mandates that have been awarded but not yet funded.
But with the persistent stream of outflows, these positives are swimming against the tide.
CEO comment:
"Liontrust is benefiting from investor diversification away from US equities and increasing demand from clients for active management, led by strong performance across our European strategies…
This more positive outlook for flows reflects the expansion of Liontrust's international distribution. We are extending our reach in the Middle East and Asia and have continued to make further progress in Europe…
As Liontrust enters the new financial year, we are well positioned to drive organic growth, realise benefits from the proposed acquisition and take advantage of the increased demand for active management."
Performance: they mention eight funds that have performed in the first or second quartile over 1 and 3 years. But I count 56 funds in their fund table. My general impression is that performance has not been very good. Which naturally makes it difficult to attract flows!
Graham’s view
Being AMBER/GREEN on this has been a mistake, as I’ve naively thought that it offered some value for some time:
But the share price has been in long-term decline:
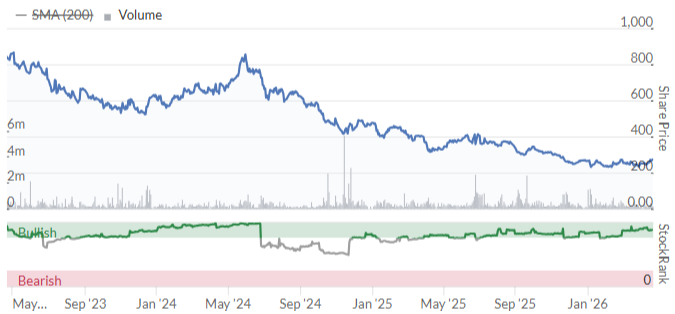
Could it be making a low here?
If we compare the very latest AUMA figure (£20.8bn, 20th April 2026) with the current market cap, there are now £124 of AUMA for every £1 spent on Liontrust shares at the current level.
That’s actually less cheap than it was in January, when I last looked at the company.
AUMA will get a further boost from the acquisition of River Global, which should complete in a few months.
So I’m still sitting in the camp which says that the shares might offer some value here, and that they could have hit a bottom.
My cautious optimism has been wrong so far. But other UK fund managers are now seeing some inflows. Perhaps Liontrust can at least hope to see flows reach a breakeven point at some point this year?
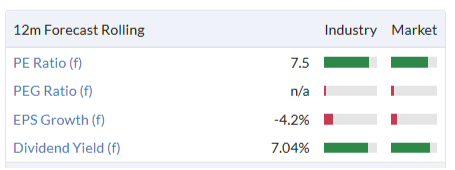
It’s not my top pick in the fund management space, but profits are profits. Liontrust is still expected to see a solid profit margin this year, with the high forecast dividend yield (7%) easily covered by earnings per share. I find it very difficult to be negative on a stock offering this sort of value.
The StockRanks agree, accurately describing it as a Contrarian play.
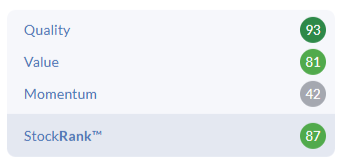
If fund performance remains poor, and if outflows persist even when most other fund managers have recovered, the outcome should in the end be a takeover from a larger group. There should always a “buyer of last resort” for a business like this.
Roland's Section
Cerillion (LON:CER)
Down 6% at 1,347p (£398m) - H1 Trading Update - Roland - AMBER =
Cerillion plc, the billing, charging and customer relationship management software solutions provider, announces an update on trading for the first six months of its current financial year ending 30 September 2026.
This is an in-line update and there are no changes to broker forecasts this morning for Cerillion. But the market reaction suggests a more sceptical view of today’s guidance, which includes a very heavy H2 profit weighting.
Cerillion leads today’s half-year update with news of its largest contract to date, a five-year deal with Omantel with an expected value of c.£42.5m. This was previously announced in January, but it’s the clear highlight in a half year that is expected to see revenue and profit fall sharply relative to the same period last year:
H1 26 revenue down 14% at c.£18m (H1 25: £20.9m);
H1 26 EBITDA down 37% at c.£6.2m (H1 25: £9.9m).
Outlook: management is guiding for full year results “to be strongly weighted to the second half”. A strong order book (value unspecified) is “anticipated” to unwind during the latter part of the year, supporting a stronger revenue performance.
As far as I can see, the main basis for this guidance is that the Omantel deal will drive significant revenue recognition in H2, including an initial licence fee.
We are also told that new orders during H1 were £39.6m, double the result achieved during the same period last year. This mainly reflects the Omantel win, so may not be a sustainable rate of new business.
The company says that the H2 weighting is “like last year”, but I think this is stretching a point:
Cerillion’s 2025 results carried an H2 weighting of 54% (revenue) and 57% (adj EBITDA);
Today’s guidance implies an H2 weighting of 67% (revenue) and 74% (adj EBITDA).
I should emphasise that broker forecasts from both Cavendish and house broker Panmure Liberum are unchanged today, so this is not a stealth profit warning.
However, commentary from both brokers highlights the lumpy nature of progress here, describing it as characteristic but perhaps uncomfortable for investors who are unfamiliar with the business!
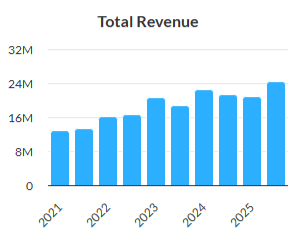
A look at past performance certainly suggests this level of H2 weighting is unprecedented in recent years:
Roland’s view
As we always say in these circumstances, it’s possible that Cerillion will deliver H2-weighted results and meet full-year guidance.
However, when we see an unusual weighting of profit to the second half of the year like this, we often find there’s an increased chance of a profit warning later in the year.
In this case, broker forecasts have edged lower over the last 18 months, but have been fairly stable:
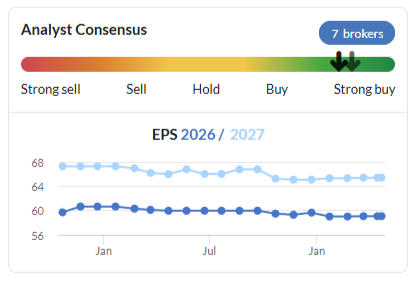
While I continue to admire Cerillion’s long-term growth and super quality metrics:
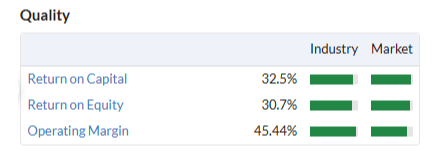
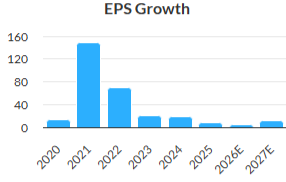
… I am mindful that earnings growth has slowed considerably in recent years:
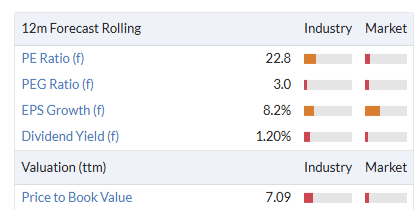
The shares are not obviously cheap, either:
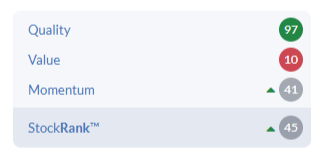
The StockRanks style Cerillion as a Falling Star and suggest caution on value:
I’ve previously noted the complex and lumpy accounting of Cerillion’s multi-year contracts and recognise that this is not necessarily an issue.
Given the strong quality metrics, I could get on board with a forward P/E of 20+ if I was confident about earnings growth.
However, I think the company could provide more visibility for investors than it’s chosen to do today. By specifying the value of its order book and giving some guidance on the value scheduled to unwind in H2, we would have been able to gain some visibility on profit for the second half of the year.
As things stand, we simply have to trust that this situation will deliver an unprecedented level of H2 profit weighting.
I was neutral on Cerillion in November. While I have some concerns, I do also admire the quality and track record of this business. Cerillion has built its reputation and gained market share while often competing against much larger rivals.
I’m going to leave my AMBER view unchanged today, reflecting my mixed view on the shares at current levels.
Reckitt Benckiser (LON:RKT)
Down 6% at 4,633p (£30bn) - Q1 Results 2026 - Roland - AMBER/GREEN =
Today’s first-quarter update has seen the consumer goods group’s share price continue its recent descent:
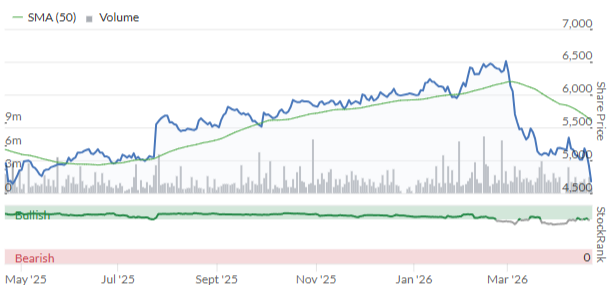
Today’s share price drop may partly be explained by weaker-than-expected sales. Newswire commentary suggests that today’s first-quarter like-for-like revenue growth of 1.3% was below consensus expectations for a figure of 2.9%.
There are lots of moving parts here, but I think the key number to look at for the continuing business are the Core Reckitt + MJN figures (the Essential Home business has now been divested):
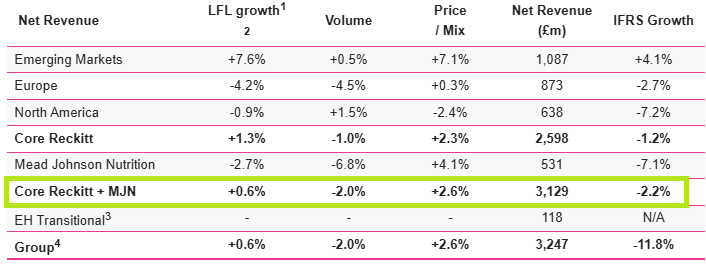
The highlighted line flags up weak volumes (-2%) and limited pricing growth, resulting in an overall Q1 revenue decline of 2.2%.
The main reason for the drop in volumes seems to have been a “weak cold and flu season” in Europe and North America. Good news for consumers, not such good news for makers of branded cold and flu remedies.
However, today’s commentary also flags up a number of additional headwinds:
Geopolitical disruption to operations and supply in our Middle East business – current forecasts do not reflect any impact beyond H1.
High single digit LFL net revenue growth in Emerging Markets, but with a c.2% headwind as a result of international sanctions disrupting the group’s Russian operations. Essentially, it seems Reckitt is having to reformulate products sold in Russia so that they no longer benefit from EU-owned Intellectual Property.
In Europe, competition and discounting is making it difficult for Reckitt to expand its share in key categories; “growth rates remained challenged”. The company says it’s seeing encouraging initial results from efforts to gain market share with Finish.
High commodity prices are having an impact: Reckitt estimates that oil at $110 per barrel for the remainder of 2026 would add £130m to £150m to the group’s cost base. This is said to be “manageable”.
Outlook: this is another company that’s guiding for an H2 weighting to profit:
We maintain our expectation for Group adjusted operating profit margin for FY 2026, with the delivery of this weighted to H2. In H1, the impact of stranded costs, lower seasonal incidence on our higher margin seasonal OTC business and higher commodity prices are expected to result in Group adjusted operating profit margin around 200bp below H1 2025 (24.6%).
I don’t have access to broker forecasts today. My working assumption is that consensus estimates are likely to edge lower, given that today’s weak revenue performance appearst to have been unexpected by the market.
This would continue a trend of recent downgrades that have already seen 2026 consensus EPS estimates cut by 10% in three months:
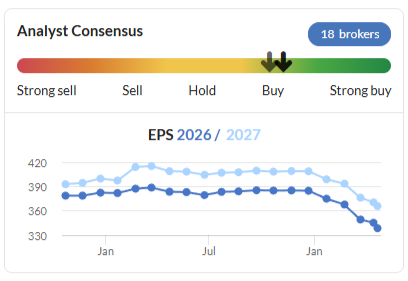
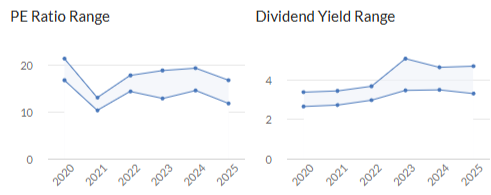
Assuming no major further changes to forecasts, Reckitt shares are now trading on a forward P/E of 13 with a 5% dividend yield. This is at the low end of the group’s valuation range in recent years and looks potentially good value to me:
Roland’s view
Reckitt is still paying the price for its misguided acquisition of infant formula producer Mead Johnson, whose main brand is Enfamil. This business has since been designated as non-core, but can’t easily be sold as it’s mired in lawsuits alleging the company’s products can cause a serious bowel disease in pre-term infants. The company hasn’t provided for specific damages, but it is involved in some of the same cases as Abbott Laboratories, which was recently ordered to pay $70m in damages in one case.
More broadly, Reckitt appears to be facing a number of temporary headwinds, at least some of which should ease over time.
On a short-term perspective, I think a neutral view is appropriate here. However, as an investment I would argue that the fundamental appeal of this business relies on its ability to perform reliably over very long time periods (unlike many other businesses).
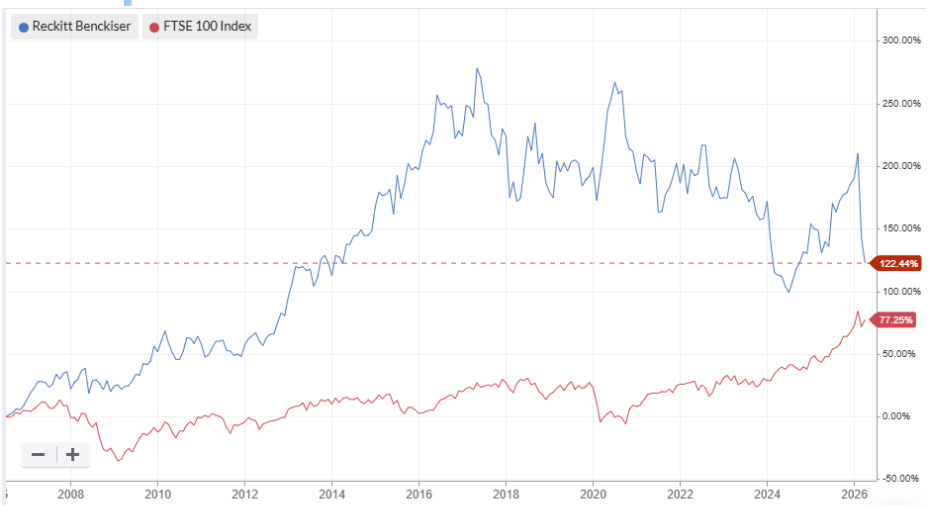
Reckitt has arguably been going through a bad patch for several years, but has still comfortably outperformed the FTSE 100 on a 20-year view. The dividend has also not been cut for at least 20 years, as far as I can see.
It’s often said that consumer brands will be displaced by cheaper own label brands. Today’s commentary makes it clear that this is a source of pressure on trading in Europe at the moment.
At the same time, I think it’s worth remembering how long companies such as Reckitt and Unilever (disc: I hold) have been trading successfully. Reckitt’s history can be traced back to 1840, and Unilever is similar.
These companies’ focus on consumer goods and products that can readily be substituted means they have to adapt to stay in business. The size and age of these businesses proves how good they are at doing this.
The cautious tone of today’s results and the recent downgrades to earnings forecasts mean that I should downgrade my previous AMBER/GREEN view (in January) to AMBER today.
However, I have to admit I’m reluctant to do this. Reckitt’s core brands – names such as Dettol, Strepsils, Durex and Lysol are used by millions of people daily. In today’s update, the company highlighted strong growth in areas of the business that aren’t affected by temporary headwinds:
[...] double-digit growth in China and India and mid-single-digit growth in non-seasonal brands in North America
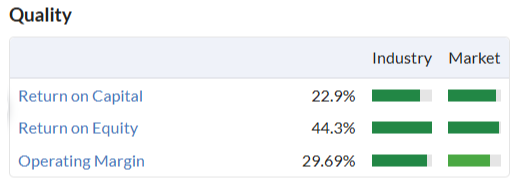
I’ve rarely seen Reckitt shares trading as cheaply as at present. A P/E of 13 and a 5% looks undemanding to me for a business with this heritage and strong quality metrics:
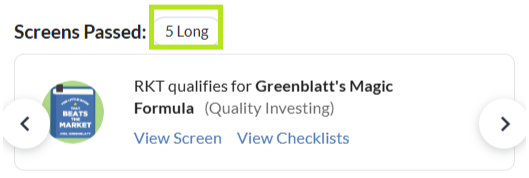
I note that the stock also qualifies for a number of quality/value screens suggesting it could be attractive on a longer-term view:
Tpximpact Holdings (LON:TPX)
Up 14% at 42.5p (£40m) - Full Year Trading Update and Notice of Results - Roland - AMBER/GREEN =
TPXimpact Holdings PLC (AIM: TPX), a leading technology-enabled services company focused on people-powered digital transformation, provides a trading update for the financial year ended 31 March 2026 ("FY26").
This software company has been on a tear recently. Today’s update is the second upgrade to full-year guidance in two months, following an update at the end of February. The shares have doubled already this year:
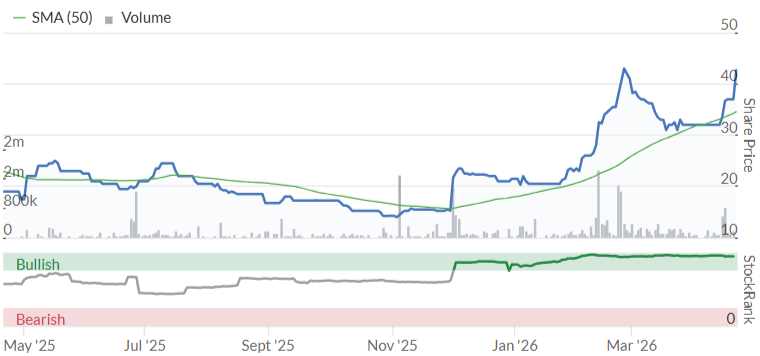
I’ve not looked at this business in much detail before – probably because TPX has generated an operating loss in five of the last six years. Against this backdrop, I’m keen to see how this improved sentiment is expected to translate into an improved financial performance.
Here’s how the company’s guidance has changed this year. This has led to house broker Cavendish lifting FY26 earnings forecasts by nearly 50% in the last two months:
FY26 guidance (y/e 31 Mar) | Revenue | Adjusted EBITDA | Adj EPS (Cavendish) |
Previously | £76.2m (consensus) | £6m to £7m | 3.4p |
24 Feb upgrade | £76.2m (consensus) | Not less than £7m | 3.9p |
22 April upgrade | £78.1m | c.£8.6m | 5.0p |
With thanks to Cavendish for providing update forecasts today, we can see that FY27 estimates have also been upgraded:
FY27E adj EPS: 6.1p (previously 5.0p)
These revised estimates price TPXImpact on a FY26E P/E of 8.4, falling to a FY27E P/E of 7.
Roland’s view
There’s no trading commentary today, but the company has previously reported a number of big UK government contract wins, as Mark discussed in February. He made the point that the company appears to be reliant on government spending, with relatively few large contracts contributing a significant part of revenue.
While delays to government spending plans held back past performance, the cork appears to be out of the bottle now.
Current forecasts suggest the valuation remains undemanding even though the shares have doubled this year.
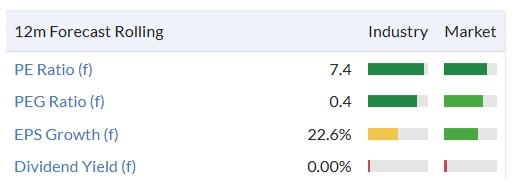
With the caveat that I would like to see the company’s unadjusted accounts, I can’t really argue with the StockRanks perception of this as a potential Super Stock.
I see that the shares now also qualify for the interesting Tiny Titans screen – a strategy that’s historically delivered very strong results.
I am going to leave our view unchanged at AMBER/GREEN today for the sole reason that TPXImpact has reported a statutory loss every year since 2023, including H1 26. The interim results show adjusted pre-tax profit of £2.2m converting into a reported pre-tax loss of £(1.7)m, thanks to a plethora of adjusting items.
This approach may seem overly cautious, but my preference is to focus on real profit and cash flow. We haven’t yet seen much of this for TPXImpact, although forecasts suggest this situation should start to improve from FY27 onwards.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

59 comments
Catching up at the weekend (again!). Thanks for covering Reckitt Benckiser (LON:RKT) , agree it's a quality stock having looked at the range of products it sells. I've set an alert at £42 which is the 10 year low back in 2024. Net debt is covered by just over 2 times 2025 net profits. People who buy own brand cheaper alternatives will probably still contribute to Reckitt Benckiser (LON:RKT) as I suspect they produce both premium and own brand products ? Solid dividend, well covered.
Could spend a lifetime investing only in FTSE 100 Index (FTSE:UKX) stocks, this is why I much prefer to the DSMR to the old SCVR. Thanks again.
Hi SSB
RE: Reckitt Benckiser (LON:RKT)
Good company though it is the various lawsuits over Enfamil remain a worry. At the top end the impacts of these are estimated to be $8 billion, so about 25% of the market cap. More likely we'll see this settled somewhat lower than that, but it will continue to cast a shadow over the operating results until it's resolved, which isn't likely until sometime in 2028, although a critical case starts in July this year.
Personally, I'm happy to sit on the sidelines while this plays out but clearly everything has its price.
timarr
Hi timarr,
thanks for reverting on my post. Agree with what you say and I did note the Enfamil legal issues as a potential negative. My post was maybe poorly worded: when I referred to setting an alert, I was only referring to a Stockopedia alert to investigate further and not necessarily an automatic buy into my broker account. If anything, I do too much research these days & the slightest thing puts me off buying; I may regret this approach at some point in the future as I probably should be taking more risk. What struck me about Reckitt Benckiser (LON:RKT) was the list of instantly recognisable brands, most of which I have either used in the past or use now.
SSB
Ref. HSP Hargreaves Services Tender Offer with Platform deadline tomorrow- has anyone got suggestion on what action to take??Thanks. KBR
Seraphim Space Investment Trust (LON:SSIT) I HOLD
This has been tracking higher last few days and a real spurt today on little to no news, as far as I can see. Anyone got any ideas/thoughts or heard any news?
Seraphim Space Investment Trust (LON:SSIT) I hold
This is a useful source of information about the companies in SSIT's portfolio. Some of these are performing very well and could be seen as undervalued.
https://investors.seraphim.vc/...
Space is attracting lots of interest particularly with the upcoming IPO of Space X. SSIT have raised the prospect of creating a separate class of shares to raise funds to acquire unlisted companies that it thinks can grow rapidly. I guess they want to secure this additional capital ahead of the SpaceX IPO which could suck a lot of money out of the market.
To learn more you can listen to the CEO talking about what SSIT invests in and why in this You tube interview. It's long but very illuminating. IF you are still interested, ADVFN has an active discussion board with some knowledgable contributions.
Thanks for that rwh3ue - I'll have a listen/watch to the YouTube video
Following up my post on the latest severe Crest Nicholson Holdings (LON:CRST) profits warning yesterday; today provides yet another example where selling straight away on a profits warning yesterday is such a good tactic for minimising losses. After all there are plenty of alternatives regularly issuing “better than expected” updates to check out.
Today it’s Shoe Zone (LON:SHOE) YET AGAIN! I’ve lost count how many profits warnings they’ve issued since the first on in 2024 when SHOE coukd (and should in my opinion) have been sold.Share price is down another 10% today to 45p.Shoe Zone (LON:SHOE) could have been sold around £2.50 after the first profits warning. Selling then meant investors were out ahead of the subsequent 75% share price fall.
Why do investors stick with a share like Shoe Zone (LON:SHOE) instead of doing the obvious and escaping asap???
It is hard to sell because it means taking a painful loss. I try to ignore the price i paid and just press the sell button. But it has taken years of training to do that.
I think its hard taking a painful loss, but even harder to admit you just got it wrong. I think lots of investors (myself included) assume that they are right and the market has got it wrong, and its just a case of waiting for everyone else to realise - much to our own detriment!
So do I sell my shares of Ferrexpo (LON:FXPO) ......hmmm
Yes
It took me a while to learn to sell on the first profit warning. It has cost me a few sharp turnarounds but saved me from a whole bunch of duffers. A really honest cold stare at the question “ if you did not own it would you buy it now” has helped me press the sell button.
It’s not a cast iron rule though. Accepting that many profit warnings are the first of many there are situations where there is a bounce back. I have sold on a profits warning only to see the share recover, equally I haven’t sold and seen a share continue to fall! If only a crystal ball was available! Ken, as you know from previous comments Digital 9 Infrastructure (LON:DGI9) was one I should have exited. On the other hand I sold Saga (LON:SAGA) and it has nearly 6 bagged since. Most recent concern is what looked like a mild profit warning from Dunelm (LON:DNLM) but I consider this to be one of the best players in its sub-sector of the retail market so I continue to hold for fear it will bounce back. My loss is in the single digit % so not too concerned yet….
I agree that if a profits warning is because of temporary short term problems, then IF that Company reassures that the issues really are temporary along with a more bullish outlook statement, then that’s a fairly rare occasion when it might well be better to sell than buy.
As for Dunelm (LON:DNLM) I sold (despite really liking our nearest store and their pricing) on a less bullish outlook around £14 a few years ago.
Is it a buy now it is much lower? Possibly. A reason for the share price fall is Chinese competitor Temu. Is that now priced in?
I also missed out on the huge gain in the Saga share price mainly because for health reasons my focus now is more on big dividend yielding shares and Investment Trusts.
Is anyone else unable to access their portfolios on the site this morning?
Are you using the Duckduckgo browser by any chance? I haven't been able to access the site at all today using that browser despite clearing cache. It has always worked well until today. I tried another browser and got through immediately.
Thanks, no, I've not heard of that browser. I was able to see folios on my PC but not on my mobile. But all of a sudden it's back to normal...
on renewables : guess it depends on where you go fishing - ASFAIK the government tax was on the older generation renewables meanwhile the likes of ITM Power (LON:ITM) has a government equity stake and a preferred supplier to GB Energy . I have no interest in the politics but I go with the flow ..especially the capital flow. in the US it's don't fight the Fed, in the UK it's increasingly becoming don't fight the fiscal (NLW on retailers/hospitality, tax on oilers, electricity, banks' profits next? )
Renewables are up over 40% on the month - rel sector plot week/month for UK : similar in US with Bloom Energy (NYQ:BE) up 60%/month on AI DC deals (Oracle etc)
ITM Power (LON:ITM) is up 120% on the month on multiple catalysts and has an mcap of £952m which would rank it in the top 140 of the FTSE 250 above Kier (LON:KIE) or Trainline (LON:TRN) - very different sectors and SRs - reckon that will amuse on a funnymental basis but that's the power of momentum and sentiment - Ceres Power Holdings (LON:CWR) and AFC Energy (LON:AFC) are the other two of size/liquidity
(plots are rel price mom on a week/month basis sized by mcap coloured by bullish(green) to bearish (red) : cross hairs are median values in each timescale - from runprofits.com research
I know a few people like to use this metric but I don't think fund managers should be valued with reference to AUM (ie every pound buys X pounds of AUM). As we have seen AUM can evaporate very quickly. In addition, it doesn't take into account the revenues and earnings produced by that AUM - some types of funds will be able to charge higher fees, while some fund managers will be more efficient with lower costs. In other words higher AUM doesn't always translate to higher earnings.
A totally fair and well-made point, Bouden. AUM/market cap (or EV/AUM, which is more common) is only ever going to be a shorthand, rough measure. A bit like P/E. I do need something to anchor valuation against when looking at fund managers, and I find that it's worth checking. But of course in isolation, it's only ever going to be able to do so much. G
Tui Ag (LON:TUID) warned today on profit , Ft suggesting domestic tourism will benefit this summer , was thinking Whitbread (LON:WTB) might be a good bet but its being heavily shorted
Endless government tampering on electricity pricing for renewables. Thats 5 changes announced in as many months. How can anyone invest in this environment? Renewables Infrastructure (LON:TRIG) for latest 3 changes!
Following the PW and macro comments from Shoe Zone (LON:SHOE) today, how are people feeling about the results next Tuesday from Card Factory (LON:CARD) ?
FWIW, having had a number of family birthdays and special occasions lately to buy cards for and being an ex Card Factory (LON:CARD) holders that still supports the local store I have seen a marked increase in their card pricing so maybe in the short term the numbers may not be too bad.
My bear points would be a) that this has negated one of their USP's, much cheaper cards than competition, b) the march ever higher of postal costs cannot being doing them any good.
I like the Card Factory business model, but the price action is consistently down.
Don't try to catch a falling knife, it rarely ends well.
Tpximpact Holdings (LON:TPX) qualifies for Ed's 'Rule of 3' - Ahead statement/reaction>+10%/SR>75
Cavendish increases adj. eps for year to 3/26 from 3.9 to 5.0p and for the current year from 5.0 to 6.1p.
@SRB Does anyone know why this has dropped 10% on little volume this morning?
Serabi Gold (LON:SRB) not specifically but it is a very volatile share and often has large percentage moves in single days. Particularly recently.
Lots of miners to a hit yesterday
This miner does seem more volatile than others. If you look on the Stocko page it shows a TU due 28th April - though it's not shown on the Serabi website. May be worth holding on for - or selling before..!
So cheap today and yet so expensive, I hold Serabi Gold (LON:SRB) .
Gold price has fallen because of the Iran war. Gulf states have no income and have to spend a lot more. They have sold gold along with a few other central banks.
In the long run, the Iran war will be good for gold. There is an accelerating move away from dollar denominated assets along with increased inflation which are both very good for the yellow metal.
I suggest the weakness in Serabi Gold (LON:SRB) is a buying opportunity.
Morning - I'd be very keen to hear views on Reckitt Benckiser (LON:RKT) - It superficially looks like a quality business trading at a discount to its historic valuation. Been watching it a while.
Volex (LON:VLX) (I hold) sets new targets.
April 22 (Reuters) - Volex PLC VLX.L:
thanks Jim for this - I think it should have come up on the STOCKO morning report especially as its a popular stock here. And BTW Mkt Cap now exceeds £1b - so good its moving to FTSE250 soon
bohenie
It was a Reuters report. In case you haven't noticed Volex (LON:VLX) are doing a presentation to institutional investors and analysts (started 1400). A recording will be made available later this afternoon at https://www.volex.com/investor...
Hi Graham a second for your thoughts on Aberdeen (LON:ABDN) yourself and Timarr highlighted it at lower levels.
It still looks good value to me given they have the 10% stake in Phoenix and the rumoured £800 mil db pension scheme surplus they are trying to unlock plus a very good yield still despite the price rise over the last year.
Graham - the term for it is TACO!
Good morning all!
May i politely suggest to Thatmanrobert that you direct people to research on companies, with a link maybe, rather than posting the full nine yards on this BB.
Thank you
Agreed.
I'm all for that, the DMSR doesn't have the house room.
I'd love to see a dedicated thread started for Thatmanrobert's very interesting, informative and well-considered posts. I'd be a frequent visitor, I suspect.
That's a good thought Bob Cratchit. I have found Thatmanrobert's summaries quite an interesting and informative use of some of this new tech, though perhaps a little extensive for the BB especially on busy days. Useful tasters so far. Thanks to Thatmanrobert for sharing.
Prompted me to try AI on a share chart, interesting result
Thanks Bob. Here is a recent one which I acted on.
For LSE:FTC (Filtronic plc), the analysis as of April 16, 2026, reveals a classic Stage 2 "High Flyer" setup , Filtronic—a high-frequency electronics leader is currently riding a massive "Space and Defence" super-cycle.
Technical Analysis: The 1-Day Chart (Last 10 Trading Days)
Filtronic has entered a "Power Play" phase. After a brief consolidation in early April, the stock has exploded toward new 52-week highs on the back of major contract wins with "New Space" giants and European defence primes.
10-Day Price & Volume Data
Date (2026)
Price (GBX)
% Change
Volume Signal
Apr 02
205.0
+2.0%
Constructive tightening
Apr 07
204.0
-0.5%
Low-volume absorption
Apr 08
212.0
+3.9%
Breakout Initiation
Apr 09
204.0
-3.8%
Profit-taking / Natural reaction
Apr 10
200.0
-1.9%
Shakeout at 200p support
Apr 13
199.0
-0.5%
Bottom of the "Handle"
Apr 14
206.0
+3.5%
Institutional recovery
Apr 15
216.0
+4.8%
High-Volume Surge
Apr 16
217.2
+0.6%
New 52-Week High (Intraday 223p)
The 10 Best Indicators & Signals
Weiss Wave Strength: Dominant (9.4/10)
The Weiss Wave shows an overwhelming "Buying Tide." The volume associated with the "Up Waves" (Apr 14–16) is 4.5x the volume of the preceding "Down Wave" (Apr 9–13). This indicates that the "Weak Hands" were shaken out at 200p and replaced by institutional buyers.
Fundamental Review
Conclusion: Buy/Sell Recommendation
Verdict: BUY / HOLD (Stage 2 Continuation)
From a Minervini perspective, Filtronic is the "Alpha" stock in the UK technology sector. It has successfully completed a VCP (Volatility Contraction Pattern) "Handle" between April 8 and April 13 and is now in a "Power Play."
Recommendation: BUY. This is a premier institutional-grade momentum setup. Do not chase if it gaps above 230p.
Filtronic (LON:FTC) I hold
The current SP is 268 mid so "Buy at current levels (217p). A break above the intraday high of 223p would be the final confirmation for a move to 250p." is not up with events.
Kindly look at the analysis date to appreciate its value and direction.
Filtronic (LON:FTC) great company but now trading at 220p while forward EPS stuck at 3.5p. Not for me at these multiples.
Filtronic (LON:FTC) Hey DD where are you getting that price from? I know Stocko has had a few operational probs recently, but I have a price of £2.76…. Where r u seeing 2.20?
Oops 280 Now!
;p
The analysis/format is primarily for chartists looking for the quick picture and any potential edge. Its also a massive time saver for them.I currently have exclusive 24/7 access to the UK/US analysis on a single keystroke on a restricted basis pending further pipeline developement which I hoped would benefit all subscribers wanting to add to the excellent daily site reports which are fundamentally based while the site charts are deficient in terms of overlays indicators and time frames when compared to the likes of Sharescope,TradingView and Investing.com.
Thatmanrobert - looking at the comments today I think there are those here who are not chartists who do not wish to scroll through the length of your posts and others who appreciate them.
A similar situation arose some time ago regarding investments not direct with a single company so now Charles Mitchell puts up an Investment Trust , REIT and ETF post on a monthly basis. See https://www.stockopedia.com/co...
I would suggest that you could do similarly with chartist details - the frequency of new posts would be up to you. I see from your profile that you have not yet created any posts of your own. To do this go to 'Discuss' in the left hand menu and click 'Create Post' at the top. One good thing about your own post is that you can make changes whenever you want unlike the comments where the limit is an hour.
GB (LON:GBG) looks intersting. Only ‘inline’ but the forward p/e of 10.9 and trading below net asset value would imply the market was expecting worse? Growing mid single digits but sounds like there is hope for that to increase and the company appears to be trading well. This is one where another year of improved performance could really drop down fast to the bottom line earnings. Good risk reward?
Big day of reports. Will be very interested in your views on Aberdeen (LON:ABDN) (interactive investor leading the way) and Liontrust Asset Management (LON:LIO) (surely at the bottom now??)
Need to show net inflows I feel, before it is a bottom