Daily Stock Market Report (Mon 24th November 2025) - SAA, SAAS, MWE, CER, DSW, TTG, FAB, SFOR

Good morning!
The Budget is coming up on Wednesday - always an exciting day for UK markets.
Wrapping it up for today, thanks everyone.
Spreadsheet accompanying this report: link (last updated to: 10th November).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£214bn | SR75) | Plans to invest $2bn to expand its existing Frederick and Gaithersburg facilities, adding manufacturing and development capacity. | ||
BHP (LON:BHP) (£101bn | SR95) | BHP confirms it is no longer considering a combination of the two companies. | ||
IMI (LON:IMI) (£5.9bn | SR73) | Sold Truflo Marine business to Fairbanks Morse Defense for an enterprise value of £225m. Expect completion mid-2026. | ||
| ROSEBANK INDUSTRIES (LON:ROSE) (£1.4bn | SR4) | Trading Update | Highly confident full year expectations will be achieved. Expects net debt to be below expectations of $500m, leverage to be approx 2.5x. | |
Cerillion (LON:CER) (£400m | SR34) | Rev +4%, pre-tax profit +10% to £21.7m. New orders +25%, order backlog +21% to £56.9m. 2026 outlook positive, broker forecasts broadly unchanged. | AMBER (Roland) Today’s results appear to be in line and highlight an impressive 45% operating margin – a new high. However, there’s no upgrade to the outlook and growth is at the lower end of the rate I’d want to see to justify the current valuation. A review of the balance sheet also flags up the complexity of the company’s multi-year contracts and suggests to me that net cash may not all be surplus to requirements. I’m open to the possibility of upgrading my view here and believe this business might be worthy of more in-depth research. For now though, I’m staying neutral to reflect indifferent momentum and a weak StockRank. | |
TT electronics (LON:TTG) (£241m | SR76) | Jul-Oct revenue was £150m, “broadly flat” versus H1 2025. FY25 guidance unchanged (adj op profit £33.7m) but this outcome will require “significant step up in” Nov/Dec, with c.£12m of op profit needed during this period. FY26 outlook “broadly in line with 2025” | PINK (under offer) / BLACK (Roland) [no section below] | |
Tristel (LON:TSTL) (£170m | SR62) | American Institute of Ultrasound in Medicine has issued updated guidelines, for the first time accepting chlorine dioxide as an option for high-level disinfection. Leaves conditions “well-aligned” for greater adoption of Tristel ULT. | ||
Microlise (LON:SAAS) (£162m | SR74) | H2 trading “mixed” due to a slower recovery in the automotive and construction sectors. FY25 revenue and EBITDA to be below expectations at >£84m and >£8.3m respectively (previously £91.3m, £12.7m). FY26 outlook also downgraded. Canaccord Genuity estimates: - FY25E EPS 3.1p (prev. 5.5p) - FY26E EPS 4.9p (prev. 6.6p) | BLACK (AMBER/RED) (Roland) Today’s profit warning is quite a big one. I cannot help feeling that the company has left it as long as possible before admitting that it won’t meet previous expectations. More broadly, this 2021 IPO is not a business I’ve looked at before, but appears to have some intriguing characteristics – while it has a big share of the telematics market for UK HGV fleets, profitability is markedly weak. The CEO also controls more than half the shares. I’m intrigued, but plan to wait for the full-year accounts before conducting a more detailed assessment. | |
M&C Saatchi (LON:SAA) (£154m | SR49) | US government shutdown had a material impact on Q4 revenue and profit. FY25 results to be below expectations, with LFL net revenue -7% and op profit of £26-28m (PanLib previously: £31.4m). | BLACK (AMBER) (Graham) The broker forecast for next year's profit result gets cut by 25%, but I think there's enough value here to keep me neutral rather than negative. It had net cash (prior to a small acquisition in October), is still profitable according to forecasts, is embarking on a reasonably-sized (£5m) share buyback, and recently received a £50m bid for its Enterprise division. On a forward PER of less than 8x, I think this could be an interesting contrarian idea. | |
S4 Capital (LON:SFOR) (£119m | SR43) | SP -9% 2025 like-for-like net revenue to be down by just under 10%. Now targeting operational EBITDA, c. £75m, below the current market consensus of £81.6 million. Lower project-based revenue, continued client caution and a slower ramp up of new business wins than expected. New forecasts from Dowgate: for next year, FY26 revenue is now forecast at £672m (prev: £676m), and adj. EBITDA £85m (prev: £90m). Net debt forecast for 2025 rises to £137m. | BLACK (RED) (Graham) [no section below] This remains in the unenviable position of having net debt higher than its market cap, at a time when corporate marketing budgets have been slashed. Mark was AMBER/RED on this in September as he correctly noted that an earnings miss was likely (revenue expectations had been cut but EBITDA expectations unchanged). SFOR follows through now with an admission that adjusted EBITDA will miss expectations. This is a company where earnings tend to be enormous, with the full complement of depreciation, amortisation, impairment, share-based payments and restructuring charges. Tangible equity value is deeply in the red, which in my view suggests that investors are right to be worried about the leverage involved here (even if the leverage multiple is still well below the level it would need to reach to break covenants). Although the cut to the EBITDA forecast for next year is not huge in percentage terms, I think I'm right to downgrade our stance on this to fully negative given the lack of earnings quality, the downward momentum in forecasts, and the poor balance sheet. | |
ImmuPharma (LON:IMM) (£49m | SR24) | Now aims to complete a partnership deal as soon as practicable in 2026 (previously wanted to complete a deal by the end of 2025). Cash runway now extends into Q4 2026. | ||
Ondo InsurTech (LON:ONDO) (£42m | SR11) | Nationwide has placed a further order for LeakBot devices and services to expand the program into ten additional states. | ||
MTI Wireless Edge (LON:MWE) (£37m | SR72) | Revenues +12%, profit from operations +21% ($4.2m). $4m net cash from operating activity. Outlook: Positioned for a strong full year outturn, driven by all three divisions performing well. | AMBER/GREEN (Roland) [no section below] There are no changes to broker forecasts today after a solid Q3 for this Israeli technology group, which generates much of its revenue from the defence sector. Taking each of the divisions in turn, the antenna business benefited from “rising demand for military antennas globally”, but more mixed demand for its 5G backhaul and ABS antenna solutions (both aimed at mobile operators). The MTI Summit business also enjoyed good demand from defence clients, while in Mottech (which sells electronic water management and irrigation solutions), management reported continued growth from businesses and governments. Segmental profits were fairly evenly split across the business, ranging from $1.1m to $1.5m for each division. The balance sheet remains strong and quality metrics are respectable. I continue to see this as a decent business at a reasonable price. However, it’s family-controlled, overseas-based and has some geopolitical exposure. Full-year forecast EPS growth is also relatively pedestrian, so I’m going to leave my previous moderately positive view unchanged today. | |
EnSilica (LON:ENSI) (£36m | SR23) | Purchase order for the next phase of development of a satellite payload ASIC. Increases company’s contractual coverage against FY26 revenue guidance and will be worth $ millions over FY27 and FY28 if it continues to progress as expected. | ||
Powerhouse Energy (LON:PHE) (£23m | SR3) | PHE’s consulting division has progressed contracts previously announced as well as gained new contracts. Now necessary to grow this team further. | ||
Fusion Antibodies (LON:FAB) (£14m | SR17) | Revenues £0.84m (H1 last year: £1.2m). Loss reduced to £0.51m. Cash £0.25m. Going concern warning. FAB are "specialists in pre-clinical antibody discovery, engineering and supply for both therapeutic drug and diagnostic applications." | RED (Graham) [no section below] This has a paper-thin balance sheet for a listed company, with net assets of only £726k. Thankfully its assets are mostly liquid but it has a major need to get paid: receivables (£868k) are higher than six-monthly revenues, and this includes debtors of £543k. The company's cash balance is only £250k and it continues to post losses as it has done for as long as records show. I'm no expert in the science here but I can read a going concern warning: "Due to the risk that revenues and the related conversion of revenue to cash inflows may not be achieved as forecast over the going concern period, the Directors believe that there exists a material uncertainty that may cast significant doubt on the Company's ability to continue as a going concern without raising additional funds..." This is an automatic RED for me until it raises funds and extends its cash runway. | |
DSW Capital (LON:DSW) (£13m | SR63) | Trading “resilient” and in line with management expectations. Results are typically H2-weighted. “The business continues to trade well but the Board remains mindful of… uncertainties, particularly regarding the forthcoming Budget”. | AMBER (Graham) [no section below] Mark was AMBER on this in May and the share price/market cap are unchanged since then. Perhaps AMBER was the right call, then! EPS forecasts have increased only marginally since then. Today’s broker update from ShoreCap leaves EBIT forecasts unchanged for now (£2.5m this year, £2.7m next) with a small adjustment needed to correct a previous mistake in their analysis, leading to a 6% reduction in the PBT forecast (to £2.4m). This isn’t very important when it comes to the investment case, in my view. My view is that small professional services businesses should trade at low earnings multiples, and DSW is trading at 7x. That’s probably about right, with plenty of upside available if their M&A franchise takes off. I’m staying neutral. |
Graham's Section
M&C Saatchi (LON:SAA)
Down 12% to 111p (£137m) - Graham - BLACK (AMBER)
Some unfortunate timing from me recently, as on 3rd November I upgraded our stance on M&C Saatchi from neutral to AMBER/GREEN.
The reason for that decision was takeover interest in Saatchi’s “Performance” division, at an enterprise value of £50m.
However, it looks like I’m going to have to take our stance on Saatchi today back to neutral, at best.
Full-year trading update:
Trading in the second half of the year has been adversely impacted by the unprecedented US Government shutdown, the longest in history, affecting our Issues specialism which is a significant contributor to the Company's fourth quarter revenue and profit.
This must be the “Global and Social Issues” service, listed on their website. “Our clients include governments, NGOs, multilaterals, foundations, philanthropies and consumer brands.”
They say there is no impact to ongoing contract agreements or long-term growth prospects, but:
…the Company now expects a LFL net revenue decline of around 7% (or a decline of around 1.5% excluding Australia) with operating profit in the range of £26m to £28m, indicating an operating profit margin of around 12.5% - 13.0%, which is below the expectation set out in the Company's interim results announcement.
Estimates: my thanks to Panmure Liberum for publishing on this today.
They note that the “Issues” business is worth about 30% of SAA’s total revenue, and at a higher than average margin - that’s huge.
FY 2026 revenue forecast £210m (previously £212.7m), adj. EBIT forecast £26m (previously £31.4m).
FY 2026 revenue forecast £218.6m (previously £227.2m), adj. EBIT forecast £28m (previously £37.3m).
I note that although the company says the long-term prospects are unaffected, that doesn’t spare 2026 from seeing a major cut to its profit forecast, as Panmure pencils in more damage arising from the US government shutdown.
More positively, the company says it’s on track for its £12m cost saving programme.
Australia: this business has been restructured, including a “reset of the overhead cost base”. This business is set to be a big drag on Saatchi’s overall LfL revenue growth for the year, considering that the company is guiding for a decline of 7% including Australia, or only 1.5% excluding. But hopefully that sets it up for better performance moving forward.
£5m share buyback:
The Company believes that its strong balance sheet provides the opportunity to repurchase shares given the current market position.
At the most recent interim results, the company had £11m of net cash. Given that it is still profitable, it should be able to afford this buyback and it is a meaningful figure, given the current market cap of just £137m.
So rather than viewing it as an unnecessary sop to shareholders, I find myself agreeing with this buyback.
Graham’s view
In a situation where I could be neutral or negative on a stock, I like to let the balance sheet decide for me.
Again turning to the interim balance sheet: it’s not as bad as I’d typically expect from companies in this sector, with positive tangible net worth and the net cash figure I’ve previously mentioned.
Admittedly the positive tangible net worth relies on items whose real value might be difficult to fully realise in an emergency (things like deferred tax assets and PPE), but I think the overall list of positive factors is compelling enough:
Net cash (prior to a small acquisition in October)
Still profitable according to forecasts, with a double digit operating profit margin.
Reasonably-sized share buyback to take advantage of the shares hitting mult-year lows.
Recent £50m bid for its Performance division, which was rejected on the grounds that it was too low.
Putting all of this together, I’m happy to stick to neutral on SAA. I'd even want to upgrade it to AMBER/GREEN again, if it was clear that trading had stabilised.
The latest P/E multiple for 2026, using the share price as of writing this (111p) and the new Panmure forecast (£14.5p) is only 7.7x.
Not bad value for a profitable business with a net cash position, although of course there’s going to be a wide range of possible outcomes for 2026.
In Stockopedia terms I acknowledge that it’s a Falling Star, which is a losing StockRank style:
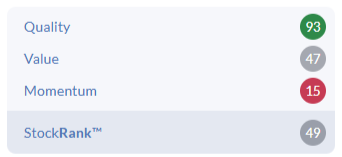
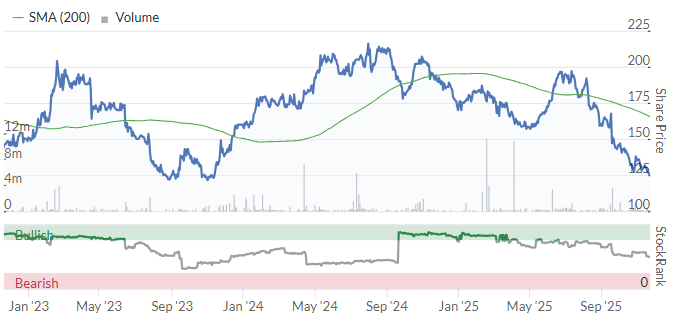
The profit forecast for next year has just been cut by 25%, which is a serious financial event no matter which way you look at it.
On the other hand, the US government shutdown has ended, as of a few days ago. Perhaps we could even get a positive earnings surprise from this stock next year?
Roland's Section
Microlise (LON:SAAS)
Down 29% to 99p (£115m) - FY25 Trading Update - Roland - BLACK (AMBER/RED)
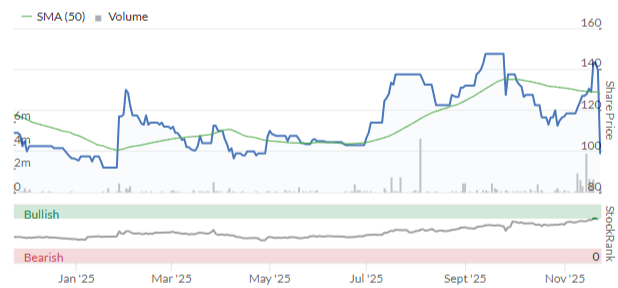
Commiserations to anyone holding shares in Microlise this morning. The company has issued what looks like a fairly serious profit warning to me, including cuts to both 2025 and 2026 expectations.
We haven’t covered this 2021 IPO in any depth previously, but I am loosely aware that it’s a telematics business. Checking the website, I see Microlise describes itself as a “leading provider of transport management software to fleet operators” .
According to AI, Microlise has a 58% market share among large UK HGV fleets (>500 vehicles). It also offers additional functionality such as route and schedule management for haulage fleets. Sales include hardware, software and support services.
Some well-known names are highlighted on its website:

What’s gone wrong?
Today’s statement highlights two main areas of weakness that have prompted today’s downgrade to FY25 expectations.
Global OEM customers: lower order volumes from global OEM customers in the automotive and construction sectors mean that OEM revenues are expected to be lower than in FY24. This is said to be mainly due to tariff disruption, along with “general weakness” in the macro environment.
The company says global OEM customers are expected to deliver 27% of FY25 revenue, down from 33% in FY24. My sums suggest this could equate to a drop in global OEM revenues from £26.2m in 2024 to c.£23m in 2025.
Worryingly, this trend is expected to continue in 2026 – current expectations are for FY26 revenue from OEM customers to be below FY25 levels.
Softer UK sales: direct sales to UK customers have been weaker this year, impacted by delays in a “a small number of customer projects”. One project in particular is mentioned, “a British multinational retailer which was hit by a cyber-attack earlier this year”. I’d speculate this might be Marks & Spencer.
Revenue from these delayed customer projects is now expected to be recognised in 2026.
Cost savings are now underway – the company expects to reduce headcount by approximately 10% by the year end. This is expected to generate annualised savings of “at least £4.0m” at an upfront cost of c.£1.5m.
Outlook & Estimates
Helpfully, Microlise has provided details of both its revised expectations and previous consensus forecasts in today’s RNS.
FY25 revised outlook: revenue of at least £84m, with EBITDA of at least £8.3m (previous consensus was £91.3m and £12.7m, respectively)
This equates to an 8% reduction in revenue guidance and a 35% cut to EBITDA expectations. This appears to be a nasty case of reverse operating leverage. With the prospect of further weakness next year, it’s easy to see why the company is cutting headcount quite significantly.
Broker forecasts: with thanks to Canaccord Genuity on Research Tree, we have updated earnings forecasts for both 2025 and 2026 – big cuts have been made:
FY25E adj EPS: 3.1p (-43% vs 5.5p previously)
FY26E adj EPS: 4.9p (-25% versus 6.6p previously)
Notably, CG has withdrawn its 2027 forecasts – an unusual step at this stage, suggesting a lack of confidence in the outlook.
Roland’s view
The shares are down sharply today, reversing recent momentum. It looks like investor sentiment has got out of kilter with reality:
In fairness, earnings expectations for 2025 had been edging lower for some time:
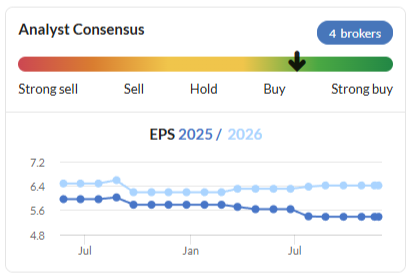
However, I can’t help feeling that Microlise’s management may have left today’s warning as late as possible – after all, weaker trends in the automotive and construction sectors have been reported for some time.
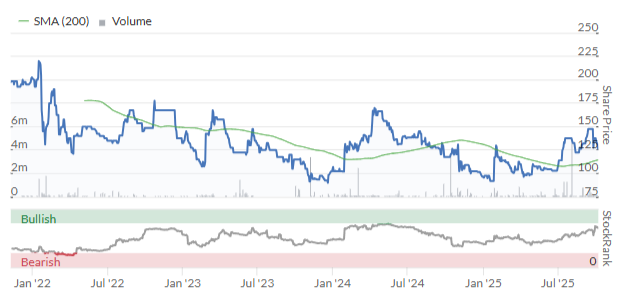
Stepping back to take a broader look at this business, I have mixed feelings. Microlise floated in 2021 and has so far proved an unrewarding investment for shareholders:
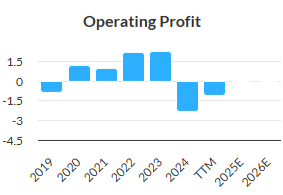
Profitability has been weak and inconsistent in recent years:
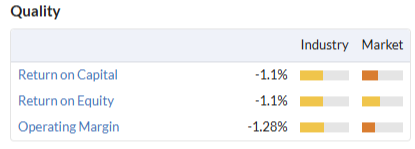
However, even after today’s fall the shares still seem to be priced for growth, on a FY26E P/E of 20. Despite this, the company’s quality metrics don’t seem consistent with its presentation as a growing software-focused company:
In fairness, Microlise does have some attractions. The balance sheet looks fine with no drawn debt and expected net cash of c.£11m at the end of 2025.
CEO Nadeem Raza also remains a 50.05% shareholder in the business, according to our data. The downside of this is that he retains almost sole control of the company – minority shareholders are unlikely to have a strong voice. However, the value of his shareholding has fallen from c. £80 million to around £58 million today. I would imagine he is now well-incentivised to find ways of returning the business to growth..
On balance, I’m intrigued by Microlise, but would like to wait for the next set of accounts to form a more detailed assessment. In the meantime, I’m going to take an AMBER/RED view to reflect the declining earnings forecast trend, weak profitability and our knowledge that companies often underperform for a time after warning on profits.
Cerillion (LON:CER)
Up 3% to 1,400p (£413m) - Final Results - Roland - AMBER
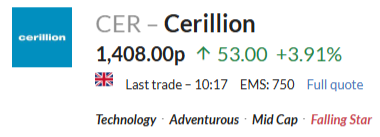
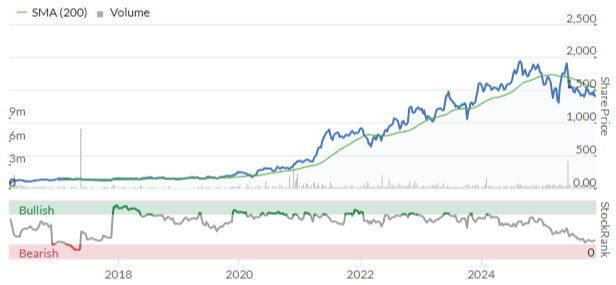
Over the last year, this provider of telco billing and CRM software has made the uncomfortable transition from High Flyer to Falling Star.
While we’ve admired the high-quality growth generated by this business in the past, Graham and I have both been neutral on Cerillion this year.
Do today’s results for the year ending 30 September provide enough good news for us to turn positive again?
FY25 results summary
Today’s results are in line with broker forecasts and show a relatively slow year for revenue growth, but with improved margins and a strong pipeline of new opportunities.
Revenue up 4% to £45.4m
Recurring revenue (e.g. support & maintenance) up 3% to £15.9m
Pre-tax profit up 10% to £21.8m
Adjusted earnings up 8% to 56.5p per share
Dividend up 17% to 15.4p per share
Net cash up 15% to £34.4m
Trading commentary
The company completed two new implementations last year, for Virgin Media (Ireland) and Paratus, a South African business. CEO Louis Hall reports a “significant increase in R&D” to support product development – the company recently launched a new version of its software.
Inevitably, AI gets a mention – Mr Hall says that Cerillion’s developers are “focusing further on AI”.
Away from software development, sales and marketing resources were also increased last year. New contracts signed included £25.3m of agreements “with an existing European customer” and an £8.5m contract with Ucom, a leading telecommunications provider in Armenia.
These deals helped to support a 21% increase in order backlog to £56.9m, which includes £47.4m of sales contracted but not yet recognised. (The balance is from annualised support and maintenance revenue.).
Looking further ahead, the new customer sales pipeline expanded by 5% to “a new high” of £275m at the end of September. I’d imagine that executing well on this pipeline will be key to returning the business to stronger rates of growth.
While this year’s 10% pre-tax profit growth is respectable, it’s well below the double-digit growth rates seen in the past:
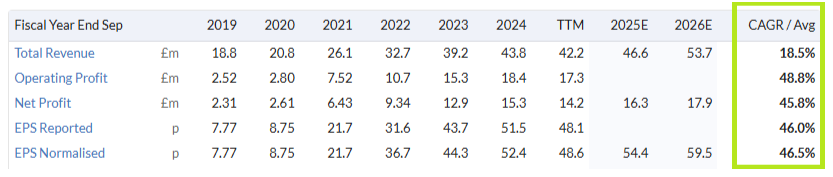
To some extent, I think slower growth is probably inevitable as the company gets larger. But I’d like to think there’s scope for some improvement in revenue growth from the rate seen last year, which seems to barely reflect inflation.
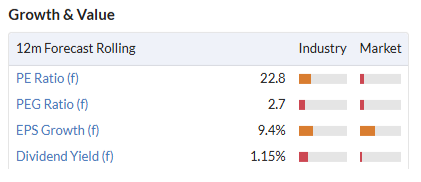
Certainly, I’d argue that the valuation still implies decent growth expectations:
Accounting review
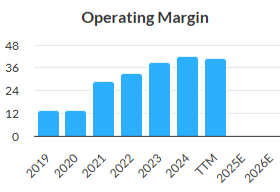
Profitability: it’s good to see Cerillion’s ability to generate positive operating leverage seems to remain intact. Operating expenses only rose by 1.2% last year, despite a 4% increase in revenue. This supported a 12% rise in operating profit to £20.6m – equivalent to a very impressive 45.4% operating margin.
This continues a trend of margin growth as the business has expanded:
More broadly, this business has fantastic quality metrics, reflecting its apparent pricing power and capital-light business model:
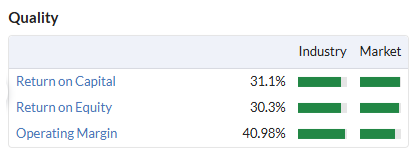
These numbers are reflected in the QualityRank of 88.
Balance sheet: my sums suggest net profit of £16.6m converted into free cash flow of £14.1m last year, before working capital movements. When paired with the £34m net cash position (8% of the market cap), I don’t have any serious concerns about the balance sheet or quality of earnings for this business.
The only caveat to that is that the company’s multi-year contracts and backlog mean that revenue recognition is quite complex: the accounts show £25m of contract assets or accrued income – revenue earned but not yet invoiced.
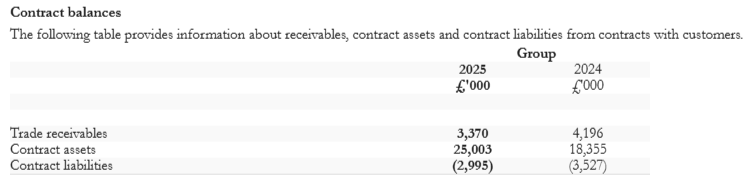
Of the current £47.4m order backlog (“unsatisfied performance obligations”), the company expects c.33% to be recognised in the next 12 months, with the remainder to be recognised over following years. This reflects the average contract length of five years.
The company also comments that payment terms vary widely:
In some cases, customers pay in advance of the delivery of solutions or services; in other cases, payment is due as services are performed or in arrears following the delivery of the solutions or services.
We can see a breakdown of the impact of this situation in the footnotes. I’ve highlighted a relatively unusual level of non-current receivables:
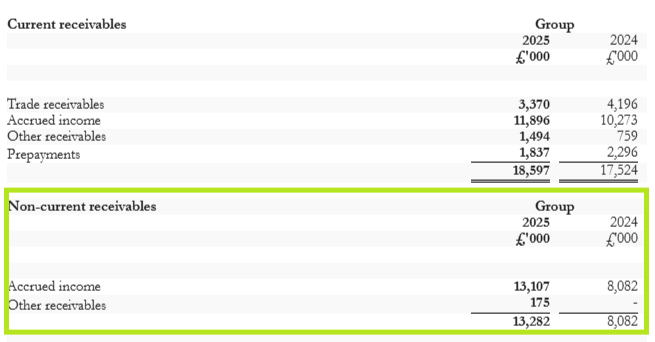
I can’t be sure, but I would guess the high level of accrued income probably means that not all of Cerillion’s cash balance is truly surplus to requirements. Some of it may represent cash received upfront for work yet to be delivered.
[Correction 25/11/25: I've been contacted by Cerillion's advisors who have pointed out that my original comment above suggests that Cerillion's cash balance may include accrued income. This is incorrect, of course. Cash received in advance of invoicing is deferred income, not accrued. Accrued income represents revenue recognised but not yet received. Apologies for any confusion this caused - my thanks to the company's advisors for flagging this up.
The point I intended to make was that the staged profile of billing on Cerillion's multi-year projects (reflected in its accrued income) may mean that having adequate cash on hand to fund work in progress is an important element of the business model. Thus it's possible, in my view, that not all of the group's net cash is necessarily surplus to requirements.]
If I’m right, this might also explain the company’s very low dividend payout ratio (seen as a high level of dividend cover):
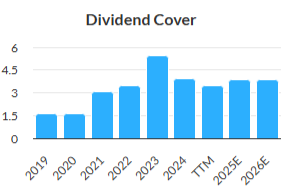
Working in this way appears to be a natural element of Cerillion’s business model and I’m not suggesting any problems – the company seems to have worked successfully in this way for years. But this kind of complex long-term contract does mean that revenue recognition is much more complex than in other types of business – and harder for outside investors to understand.
Outlook & EPS Estimates
Today’s management outlook commentary is positive but perhaps a little vague, in my view. Here’s an extract:
We expect to make very good progress over the new financial year and will continue to invest in the business to support growth.
Fortunately, I’m able to access a new note from broker Panmure Liberum. This confirms that today’s guidance is effectively in line; PanLib’s analysts have made only very slight changes to forecasts, which they say reflect an assumption that margins will remain at the top end of the company’s guidance range:
FY26E EPS: 58.4p (+1.2% vs 57.7p previously)
FY27E EPS: 64.1p (new forecast)
These estimates price the stock on a FY26E P/E of 24, falling to a P/E of 22 in FY27.
Roland’s view
Today’s results give Cerillion and EBIT/EV yield (see here) of around 6%. For a company with this level of profitability, I don’t think that’s necessarily too expensive.
If the business can maintain 10%+ earnings growth for a few years, then I think the shares could deliver some upside from current levels.
The risk is that from my perspective as an outsider, visibility on growth prospects is poor and revenue recognition from long-term contracts is complex and somewhat opaque.
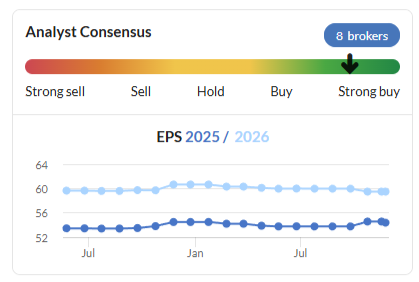
Today’s results and outlook are also only in line, not ahead of expectations, extending an 18-month run of broadly flat expectations:
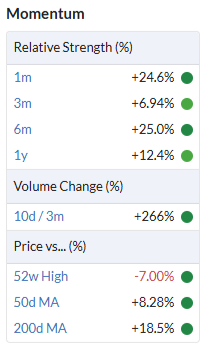
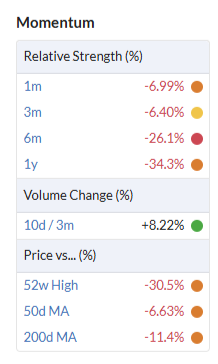
Technical momentum is also weak here:
The decision I need to make today is whether to maintain my previous neutral view, or move up one notch to AMBER/GREEN.
It’s possible that I’m being too conservative, but I’m going to stay at AMBER to reflect the lack of upgrades, Falling Star styling and low StockRank.
I’m certainly open to upgrading my view, and would hope to have the chance to do so over the coming months. Indeed, I think that this business might reward more in-depth research into the product and competitive landscape than we are able to do here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

38 comments
A big shout today for – so far - one of the little guys – Sulnox (SNOX) trading on Aquis.Stock Exchange. Shares can be traded in more or less the normal way on Interactive Investor, Hargreaves Landsdowne and a number of other well known platforms.
Some of you may have seen Ben Richardson, CEO of Sulnox in one of the many presentations given in the last two weeks. He was in Abu Dhabi after being invited to speak and exhibit at the exclusive ADIPEC technical conference 2-6 Nov,. then back to the UK for an InvestorMeetCompany presentation on the 18th. He was presenting at Mello Chiswick on the first day; then at an Aquis Showcase Investor Conference on the 19th in London. If you didn't see the I.M.C., its well worth a look.
Well today, all this exposure was capped by one of the most significant RNS’s I as a long time follower can remember. In response, 100k shares were traded by lunchtime, and by the upward movement in SP, the response was positive. The much-travelled CEO, Ben Richardson must be tempted to crack open the champagne, if he isn’t too tired!
‘ Sulnox, the greentech company delivering lower fuel costs and emissions with zero capex is pleased to announce a global long-term distribution agreement with Drew Marine USA, Inc. one of the world's largest suppliers of performance chemicals and fuel management services to the maritime industry’
Sulnox has been making great headway in marine during 2025, with lots of trials culminating in real adopted usage – 1 smaller cruise group, and 2 substantial fleets of cargo vessels. With a 50+ key country block of patents, usage in 40 countries and 6 major hubs worldwide, and a serious number of partners and major shareholders/distributors. this puts the first of many arrangements which can be described fairly as ‘icing on the cake'
Sulnox, the greentech company delivering lower fuel costs and emissions with zero capex, is pleased to announce a global long-term distribution agreement with Drew Marine USA, Inc., one of the world's largest suppliers of performance chemicals and fuel management services to the maritime industry.
Connecticut, USA-headquartered Drew Marine has a presence in more than 1,200 ports across the globe. In addition to serving bulk carriers, container ships, cruise ships and recreational vessels, Drew Marine has decades-old relationships with government and military fleets worldwide.
Central to its offering is exactly what Sulnox is designed to provide – ‘to customers seeking fuel efficiency with lower emissions and carbon intensity. Its specialism is in recommending combustion improvers, supported by diesel performance analysis solutions.
What more will Drew offer Sulnox? ‘It will gain access to Drew Marine's extensive global team of experienced technicians and account executives who work closely with fleet crews. In addition to a global sales force, providing comprehensive training for products, Drew Marine has a further global network of service engineers offering high levels of onboard support to customers. This resource is backed by a technical support centre, which provides data analysis and assists with managing customer logistics.’
Sulnox's core product, Sulnox EcoTM, will also gain access to Drew Marine's network of warehouses globally, from which more than 1,000 customers are served. Drew Marine, which works with some of the world's largest marine groups, will stock Sulnox Eco alongside its present additive portfolio, with a view to increasing prominence over time. The Board of Directors of Sulnox anticipates this Agreement to lead to significant new business for the Company.
All of these together expand Sulox’s markets, its geographical coverage, staff and technical back up in one mouth-watering stroke.
The two companies' customer bases are highly complementary, with c.75% new to Sulnox. Drew Marine clients include bulk carriers, container, tankers, offshore, military users, and a significant presence in the cruise sector, where Sulnox has already gained traction. The Agreement offers enhanced access to further major and highly relevant geographies in which Sulnox is not yet entrenched, including China, India, Japan, Brazil and Germany.
Not surprisingly, Ben Richardson said:
"Drew Marine has a huge presence globally, representing a very sizeable opportunity for Sulnox. Critically, it is an organisation that understands extremely well the value of our products to all types of maritime user needing to achieve greater fuel efficiency and progress in decarbonisation, with no capital outlay or disruption. It also recognises that maintaining peak engine performance, as increased lubricity and detergency deliver mechanical benefits, helps support consistent gains in efficiency and emissions.
Scot R Benson, CEO of Drew Marine, notably added:
"Innovative green solutions such as Sulnox are key to both our offering to customers and our commitment as a company to a sustainable future through energy efficient strategies. We're excited to be getting behind truly game-changing products for the maritime industry as it strives to navigate the energy transition amid rising costs and tougher regulation on emissions. It's particularly satisfying to work with a partner whose ethos and mission align with ours: not just selling chemistry, but solutions to the marine industry's most pressing problems of fuel cost reduction and emissions regulation."
The huge potential revenue impact will not be realised immediately, but the calendar 2026 and 2027 horizon is immediately a whole lot brighter.
Any reason for the fall in Serica Energy (LON:SQZ) today?
Gas prices down and Budget will not cut north see energy taxes I sold this morning
Newbie question here... Why has the StockRank of MoneySupermarket MONY (LON:MONY) fallen by 12 points on Friday?
MONY (LON:MONY)
seems pretty obvious to me - if you look at the note next to the momentum rank - its flagged as being -20 over the last 30 days. So whilst it may not be solely related to sharepirce the fact all the momentukm rsi numbers are negative and te price clearly has been heading down - i think its pretty obvioous that on any sensible measure this stock has poor momentum.
note it also mentioned that momentum included the following
"recommendation upgrades, earnings upgrades and earnings surprise"
if you look at the change in eps expectations per stock for the last 12 months its clear that the trend there ihas been downwards too - albeit it seems to have mostly bottomed out the last few months. So negative to sideways trend cant really be seen as positive overall - albeit some may take comfort from decline in downgrades - in that regard though without upgrades that are above non material level - they simply seem to be saying if stopped getting worse for now - or if it is stil getting worse they may not have told us yet !!!
the stocky ranks do most certainly punish stuff like that what what i have see.
Novo Nordisk A/S (NYQ:NVO) now has a dividend yield of 4.2% (twice covered), and EV/EBITDATTM around the lowest its been in 20 years. Yet analyst estimates keep falling, and the shares seem to be in a horrible downtrend.
M&C Saatchi (LON:SAA) worth noting that the US funding deal done to end the US shutdown was only to January 2026. Another shutdown in January is a distinct possibility…
Indeed.... I've not heard of any progress being made in the Senate or House on a permanent budget deal.... and we're now at Thanksgiving, with the Dec lull coming up too...
Harwood/Rockwood must be annoyed with M&C Saatchi (LON:SAA) - I think I remember that they just topped up their holdings in the last 2-3 months?
Richard from Rockwood was also up on stage at Mello and briefly mentioned it....
Looking through my notes, I wrote "not a very convincing pitch, no conviction, compared to the rest of the top 10 holdings that he ran through. Didn't spend much time. Did talk about the "World Issues" division and said it was the gem and growing, with many government contracts. But he himself doesn't seem to be very involved in this pick; given he didn't quite get the name of the division right. So probably not a super high conviction in their fund."
Roland-
Volex (LON:VLX)
When you wrote about this company's results the other day you said: "The company says that Data Centre sales “operate through a hub model” which results in longer cash conversion cycles. I’m not sure exactly what the hub model means".
Neither was I so I asked at the presentation and got a detailed reply that you can hear here https://www.investormeetcompan... At the top left under 'Fri 14 Nov 13 00' click Q&A and go to Question 16.
Thank you for following up on this sharw, I will have a listen to the Volex (LON:VLX) call.
This sounds like a good example of when speaking to management can be useful.
Roland
Answer from Meeting:Now how that works, how certain customers ask us to support them. Is by putting inventory into hub locations, particularly in the US and that allows us to manufacture in Asia, and then we ship to the hub locations, and then that inventory is available for the customer to pull to meet their requirements. And it works very well for the customer because that inventory sits on the Volex balance sheet, which is one of the reasons why you see this adverse movement in working capital. But for operational reasons from a customer's perspective, they like that confidence that as there are peaks and troughs in demand of their particular use case, so when they're building data centres that, They need to move very quickly to populate the data centre with infrastructure which includes all the server switches, and then of course the cables that critically connect all of those things together. They want the confidence that they can go to those hub locations in the locality of where the data centres are being built and move very quickly to achieve the achieve their build out requirements
Supermarket Income REIT (LON:SUPR) was due to hold its AGM today at 10.00. Did anayone here attend or has anyone seen any statement made at the AGM?
I can’t see anything in their website…..
Newsroom chatter focus is on an Ukraine peace deal putting pressure on the defence sector ...not flowing through yet .... but could be decision time for the likes of BAE Systems (LON:BA.) Chemring (LON:CHG) and Babcock International (LON:BAB) all of which had numbers that looked fairly good too me. Obvs just my opinion heading into next year..... all these stocks have already been quite weak relative to the market for some time.
Britain has agreed to increase defence spending, due to Nato commitments. I don't think Mr Putin will be disappearing anytime soon, I can't see any big cuts in defence spending. If Ukraine doesn't agree to the proposed peace deal and Mr Trump pulls support for Ukraine, Europe, including the UK, might find they are spending more to support Ukraine. We'll have to see what Rachel from accountants has to say
She'll be blaming putin and trump whatever happens.
Plus she always has 1066 battle of hastings in her back pocket if it starts to get really heated and she needs an out.
Expect lots of rhetoric and minimal action.
I agree. Britain has to build up its drone defences, its cyber defences, its navy (current Russian incursions and small boats interception?), its ground forces, its ammunition production and probably a host of other areas too.
A Ukraine capitulation/ceasefire would only buy time - not restore a peace dividend.
A Ukraine capitulation/ceasefire would only buy time - not restore a peace dividend.
i think its nonsense to suggest that ending a war is "buying time" - thats disrespectful imho to what a cessation of war brings to the table - normally. I can't see on any level how a permanent cessation of war is not good news. I know we in the west probably want to win and destroy russia at all costs - but imho i cant see any downsides if there is ceasefire.
Note we have been spending billions on consumbale costs of killing people here and consumables protecting ukraine - when we have ceasefire those consumable costs stop - so imho its very much the case that the vast spending on the war machine should soon tailoff after the end of hostilities. Yes the background stuff caries on and may perhaps increase - but the running costs of active war machine are many many billions.
Yes there will always be uncertainty ref the future unless both sides geta perfetct deal or one side is destroyed and gives up the fight - lets be frank there is close to zero % chance of that olutcome anytime soon - but at least the killing will have mostly stopped. Its a shame we threw ukraine under the bus by promising to protect them when they gave away their nukes - and we then withdrew that protection - or didnt back up our promise and prevent the invasio. Ref disputed territory - its reasonably clear that some of this territory has high % of russians living there - when 50% or more of people might want to align with different country imho that always posses problems ref keeping the status quo.
If we keep to the defence sector investment prospects, however controversial, I think to summarise order books are likely to remain strong reflecting the European rebuild. However in the short term, say 6-12 months, a fall in activity in Ukraine is likely to be disruptive. Since all these shares have been weak for sometime I guess there is already an expectation of this, but investments made now should be done expecting less than perfect trading in H12026. It goes without saying that we are simply discussing the investment prospects of companies in the sector.... and of course, investors who are unhappy with what these companies do, can ignore the sector should they wish to.
If we keep to the defence sector investment prospects, however controversial, I think to summarise order books are likely to remain strong reflecting the European rebuild
yes i would agree with this and i think we may have agreed to up our spending to closer to 5% in next 10 years and other countries similarly. So i dont disagree that all other things being equal ignoring wars spoending will go up.
i would expect the volume of war related consumables to go down though when teh war ends - albeit there may be a period of beefing up stuff for future use.
what moves the dial more i am neutral on - i think unkraine spent $125 billion in 2024 - thats alot of spending to drop out as and when the war ends.
Thats a large number - we would need a bit more info. on what that's for to start to factor it in to the sector prospects.
i probably wouldnt read too much into my comments here - yes its a large number but i simply took it from copilot so there could be any number of things that make up that number and a very high % might not relate to defenec spending stocks in any manner. I dont want to labour my initital point - it simply seemed common sense to me that if and when the war stops and its not liklely to restart soon (if thats termporary peace) - then there may be some tailoff in spending directly related to teh activities of war. Its not so common for counrtiers to go invading others so i would be reasonably hopeful if they could agree a deal that it may stick - i am biased though in that i think thats waht most woluld want - its not necessarily something that suits the main players. In that regard i fully respect that ukraine dont want to be bullied into giving away sovereign territory - just because putin has taken it and he thinks he can keep it - unfortunately there is not much evidence at present that either side is winning here in the convential sense of the word.
The recent press conference held by Putin was explicitly clear the war does end until Ukraine becomes Russian, in the same press conference he explicitly threatened other sovereign European nations. Everyone wants the war to end, that is in the gift of Putin unless he is defeated in the field or the Russian people overthrow him. I suspect many Russian speaking Ukrainians no longer support Putin. Sadly this war will not end soon. In my view NATO needs to grow some balls and help Ukraine win this war against a tyrannical dictator and in doing so help European security. I am holding on to my defence stocks there is a lot of catch up spending required to match Russian or Chinese defence spending
I am holding on to (most of) mine too. Ammunition stocks, at least in the UIK have been very depleted by gifts to UKR, and will take a while to rebuild. €RHMD 's announcement in May of building a new barrel manufacturing plant in Telford was done in the recognition that there will be long term requirements to rebuild Europe's defences notwithstanding Putin's comments.
The issue in the short-term (in the UK at least) is that Starmer mouths platitudes of raising defence (inc security) spending to 5% of GDP, but is not committing cash short-term. For example, the New Medium Helicopter contract is still not awarded. €LDOM must be getting very frustrated. We need more than platitudes from European leaders.
The recent press conference held by Putin was explicitly clear the war does end until Ukraine becomes Russian
well he wuld say that wouldnt he - my point is that if the war is cosing $200 billion per year in comsumables - and teh war stops and isnt likely to restart anytime soon - imho its pretty obvious that that $200 bill pa spend can and will drop out the system - might not happen immedeitaly and it might be covered by increase defense spending - but its different level of cost funding active war to having potential war - imho is nonsense to suggest otherwise.
There are only a lot of russians in the occupied territories because the occupiers have gotten rid of the ukraine nationals - in the ground / deported to gulags / relabelled as russian - or simply stolen them (According to the Russian Ministry of Defense, over 307,000 children were transferred to Russia from 24 February to 18 June 2022, alone.[38])
Ukraine could be taken off the chessboard but there would still be a dominant Russia to consider. BAE Systems (LON:BA.) has a world-wide range of customers contracted to it. I am long in it.
My friends investment manager bought BAE for him at £20 two months ago so much for investment managers
Synetics (SNX) news this morning of a 5 yr extension to their framework from Stagecoach. Up 3.8% (partly to recover the car crash of Friday?)
For years and years to come they will be talking about the "2025 Black Friday stock market crash"
You first read it here!
PS. Good morning everyone! Have a good day!
Bring it on. I am 98% in cash now
some might say going so heavily into cash is putting Descartes before the horse ...
I think I understand the joke, so i am
The US stock market is shut Thursday and closes for a half day on Friday, so I think it is even less likely to happen on Friday than normal.
Apologies... there is no need for this type of thing....it adds nothing to sensible debate about investments.
Have nice day!