Daily Stock Market Report (Wed 7th Jan 2026) - TPT, GSK, RKT, PSDL, ENSI

Good morning! Company news is still a little light at the moment.
Today's Agenda is complete.
Spreadsheet accompanying this report: link (updated to 16th December).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
GSK (LON:GSK) (£77.4bn | SR91) | EU approval of Shingrix PFS & Positive phase 3 data for GSK’s bepirovirsen | PFS means prefilled syringe - a more convenient delivery method. Shingles affects c.1.7m each year in Europe. Bepirovirsen is a treatment for chronic hepatitis B, which affects >250m people globally. | AMBER/GREEN = (Roland - I hold) [no section below] I’ve commented on GSK several times already this year (here, here and here.) I don’t have anything to add today other than that from my layman’s perspective, these updates appear to provide further evidence of positive momentum within the group’s pipeline and portfolio. My broadly positive view remains unchanged. |
Reckitt Benckiser (LON:RKT) (£40.8bn | SR80) | Will return c.£1.6bn to shareholders through a special dividend of 235p per share, using proceeds from the sale of the Essential Home business. A 24 for 25 share consolidation will maintain share price comparability. | AMBER/GREEN (Roland) This divestment is aimed at making Reckitt a higher quality, higher growth business, more closely focused on its largest brands. On balance I think this is a reasonable expectation, with the caveat that the Mead Johnson baby formula business remains a potential millstone due to ongoing product liability legal actions. Reckitt shares aren’t cheap on a P/E of 17, but I see this as a reliable long-term defensive performer. On the basis that I think management is taking sensible steps to improve performance, I’m going to take a broadly positive view ahead of March’s full-year results. | |
HUTCHMED (China) (LON:HCM) (£1.80bn | SR28) | A trial of sovleplenib in patients with wAIHA has met its primary endpoint within weeks 5 to 24 of treatment. | ||
Intuitive Investments (LON:IIG) (£303m | SR48) | Agreement with China’s national certification agency allows for a pilot of a commercial Paperless Play Lottery - a “critical enabler” for the expansion of Hui10’s digital lottery platform. | ||
Henry Boot (LON:BOOT) (£295m | SR77) | The sale to Vistry delivered an internal rate of return of 9.2% and means that Hallam Land has exceeded its 2025 sales target, with a record 3,957 plot sales last year. | This is a Reach announcement, i.e. a non-regulatory press release. | |
Phoenix Spree Deutschland (LON:PSDL) (£154m | SR54) | Sales in December “materially exceeded” the company’s target, with €5.4m of notarisations. FY25 sales totalled 122 units (€36.0m). Phoenix intends to return capital to shareholders in 2026 through share redemptions. | AMBER (Roland) [no section below] This property company is engaged in a run-off strategy to liquidate its portfolio and return cash to shareholders. It’s not a stock I’ve looked at before, but a couple of things struck me as being potentially interesting about today’s announcement. The first is that capital will be returned by share redemptions. These aren’t the same as buybacks. The company will redeem shares at a value that’s expected – according to today’s announcement – to be aligned with IFRS equity value. In other words, the book value on the balance sheet. Checking the June 2025 accounts, my sums suggest a NAV per share of around 255p. With the shares trading at c.170p, there’s a potential value opportunity here that’s reflected in the stock’s current discount to book value. The second point I want to highlight is that the company’s previous guidance in November was that redemptions were expected to be in line with EPRA NAV per share. This is an industry-standard measure that’s typically higher than IFRS NAV – PSDL’s EPRA NAV was reported at 298p per share in the June 2025 interim results. In other words, significantly higher than the IFRS NAV per share of 255p. Unless I’m missing something, my conclusion from this is that expectations regarding shareholder returns have been downgraded today. I’m flagging Phoenix SpreeDeutsch as a special value situation that investors might find interesting for further research. I don’t have a strong conviction either way on this initial review, so I’m going to go AMBER today. | |
Topps Tiles (LON:TPT) (£87m | SR84) | Q1 revenue ex-CTD +3.7%, “outperforming the market”. CTD store disposals are complete and Fired Earth brand is now operational. | AMBER/GREEN = (Roland - I hold) A solid Q1 update, in my view, given the subdued market backdrop. I’m hopeful the full integration of trade distributor CTD following the completion of the CMA process may also help group performance. Looking back at last year’s results, I’ve flagged up concerns about the profitability of the group’s leasehold estate and the lack of free cash flow support for the dividend, but I don’t think these are significant enough to warrant a downgrade at this time. I’m leaving our view unchanged today ahead of a more in-depth half-year update in the spring. | |
EnSilica (LON:ENSI) (£50m | SR40) | Reiterates current guidance for FY May 2026 of revenues of £28 - £30m. More than 95% of revenues are already covered by existing contracts. EBITDA of £3.5 - £4.5m. | RED = (Graham) | |
Aptamer (LON:APTA) (£27m | SR34) | Revenue for H1 26 is £0.83 million, +27%. FY26 fee-for-service order book of over £2.0 million in new contracts. “Strong” sales pipeline of £3.1m. | ||
Galantas Gold (LON:GAL) (£16m | SR21) | Andacollo is a past-producing, large-scale open pit heap leach gold operation in central Chile. Total consideration $32m over years. Related party transaction: the asset is currently indirectly owned by Galantas’ SVP Operations. | ||
Eden Research (LON:EDEN) (£14m | SR15) | Mevalone has been granted approval by the French authorities for use on grapes to control downy and powdery mildew. | ||
Directa Plus (LON:DCTA) (£14m | SR30) | FY25 update: revenues €7.0m (FY24: €6.66m) and adjusted LBITDA broadly in line with expectations of c. €2.5m (FY24: €3.64m). Gross cash balance €1.5m. Board continues to “assess its optimum options to secure the requisite funding which will be needed in FY26 to support future growth.” | ||
Blackbird (LON:BIRD) (£10m | SR3) | Epidemic Sound’s music and sound effects catalogue will be integrated directly into elevate.io’s video editing platform. | This is a Reach announcement, i.e. a non-regulatory press release. |
Graham's Section
EnSilica (LON:ENSI)
Up 4% to 53.95p (£52m) - Trading Statement - Graham - RED =
EnSilica plc (AIM: ENSI), a leading fabless chipmaker of mixed signal ASICs (Application Specific Integrated Circuits), provides the following update on trading for the six months ended 30 November 2025…
We don’t study too many microchip companies in this report.
I haven’t looked at this one since its April profit warning, when I downgraded our stance on it to RED.
The share price has staged something of a recovery since then (the profit warning is highlighted below):
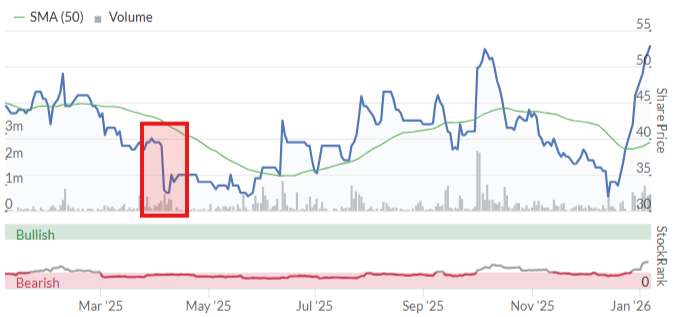
Today’s update is positive and reassuring:
The Company is pleased to report that it generated solid new business momentum across the Period alongside producing strong levels of Non-Recurring Engineering ("NRE") and recurring supply revenue from existing contracts, delivering revenue growth in excess of 35 per cent during the Period on a like for like basis.
H1 2026 revenues will be c. £12.7m, with positive EBITDA of £1.7m (H1 last year: EBITDA loss £0.2m).
Cash balance: £2m.
Outlook: they reiterate guidance for £28-30m of revenues, with EBITDA of £3.4m - 4.5m.
CEO comment:
"With business already booked to support £28 million to £30 million of revenue in FY 2026, and with several customer chip tape-outs scheduled for the second half of the financial year, we expect FY 2026 revenues to be weighted towards the second half.
Looking beyond FY 2026, the depth, quality and duration of our contracted and pipeline programmes point to a level of long-term value that is not yet fully evident in our near-term financials. As these programmes progress from design through tape-out into sustained production, our highly scalable model and underlying quality of the business will become increasingly apparent."
Graham’s view
It’s perfectly reasonable for the CEO to argue that the near-term financials don’t yet reflect the company’s progress, but as a value-biased investor I do have a tendency to wait for lots of evidence/proof before believing the story!
The historic financials here aren’t great in terms of bottom-line profitability:
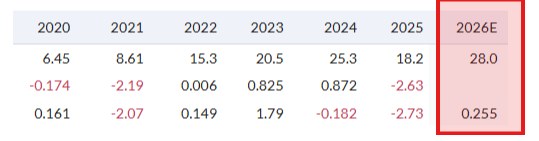
Not being an expert in this industry, it’s hard for me to say whether or not Ensilica has any sort of sustainable competitive advantage - the financial results obviously do not indicate it yet.
The design, supply and manufacture of various types of integrated circuits is surely an intensely competitive space in which to operate. I’m not sure what a competitive advantage would even look like.
And I note that EPS forecasts have been soft even since the April warning:
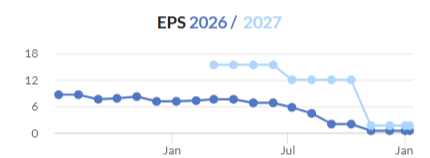
I’m therefore on the fence between leaving this on RED and upgrading it back to AMBER/RED.
When I’m on the fence, my first check is the balance sheet. According to PanLib today (many thanks to them), the net debt forecast for FY May 2026 is £7.2m, an increase from the £6m at the prior year-end.
If the company was in net cash, I’d go back to AMBER/RED without hesitation.
As it has a material amount of net debt relative to the size of the company, and as EPS forecasts have generally trended downwards over the last year, I think staying RED makes sense.
It’s not as if the stock is trading at a cheap multiple:
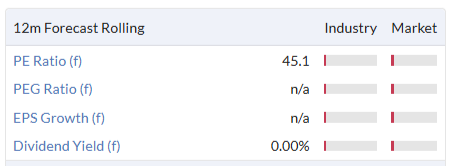
RED might be a little harsh, but that’s where I’ll leave this for now.
Roland's Section
Topps Tiles (LON:TPT)
+4% at 46p (£91m) - Q1 Trading Update - Roland - AMBER/GREEN =
(At the time of writing, Roland has a long position in TPT.)
Full credit to Topps Tiles for being only the second listed UK retailer (after Next yesterday) to release a post-Christmas trading update. Topps is currently a member of my SIF portfolio, so I’ve a keen interest in progress at this small-cap.
Today’s update covers the 13-week period to 27 December 2025 (Q1 FY26). It lacks some of the detail provided by Next, but it does contain some useful information for investors. Here is my summary of the main points:
Total group revenue +1.6%, including the impact of store closures at CTD Tiles (acquired in 2024)
Group revenue ex-CTD +3.7%, “outperforming the market”
Topps Tiles brand revenue +2% like-for-like
Trade sales +3.7%
Digital sales 19.7% of revenue (FY25: 19.0%)
Market conditions appear to remain challenging, with sales growth broadly in line with inflation. Looking at today’s figures, I would guess that sales volumes are probably flat or slightly negative.
However, efforts to gain market share gains through expansion in trade and online seem to be making progress – Topps says it outperformed the wider market in Q1. This could leave the group well positioned for when demand does become stronger.
Usefully, Fired Earth (a premium brand purchased out of administration in November) was up and running before Christmas, allowing the group to fulfil “strong demand from customer orders”.
CTD Tiles: one important area of progress recently has been the completion of the CMA process relating to Topps’ acquisition of Ceramic Tile Distributors (CTD Tiles) in 2024.
Topps paid £9m for certain assets and stores from CTD when that business went into administration, but the deal was called in by the CMA for investigation, preventing Topps from fully-integrating the business. That process is now complete and today’s update provides a useful summary of the situation:
“CTD operation is now smaller than it was”, operating from 22 stores versus 31 a year ago
CMA-mandated store disposals have completed, with the fourth and final disposal taking place in December
Remaining CTD stores delivered 4.7% LFL growth during the period
CTD performance in Q1 provides “a solid foundation” for the group’s plan to return CTD to profitability in FY26
Topps has been publishing revenue figures excluding CTD Tiles for some time now, but my hope is that this business will now be fully consolidated and no longer require exceptional reporting.
The appeal of CTD to Topps is that it provides exposure to the Architect & Designer and volume housebuilder segments. These are markets where Topps previously had “limited or zero representation”, respectively.
Management has previously said they believe CTD has the potential to contribute £30-£40m of profitable sales over the medium term.
Management changes: Alex Jensen replaced long-serving CEO Rob Parker on 8 December, after “a seamless transition process”.
Jensen’s last role was as CEO of National Express’s UK, Ireland & Germany business. Prior to that she had a career at BP, including leading the retail and B2B fleet services business as divisional CEO.
Topps’ CFO also left in September and his position is currently being covered by a (second) interim CFO. A new permanent CFO (appointed by Jensen) has been recruited from Watches of Switzerland Group and is expected to start work in “Spring 2026”.
Outlook & Estimates
Today’s update conspicuously lacks any mention of profitability or whether trading is in line with expectations for the current year. Admittedly it’s early in the year, so I wouldn’t read too much into this.
Fortunately, broker Zeus has shared an updated note on Research Tree today. Forecasts have been left unchanged, suggesting that today’s update is in line with expectations:
FY26E adj EPS: 4.4p
FY27E adj EPS: 5.4p
FY28E adj EPS: 6.5p
Topps normally issued a half-year trading update around the start of April, so I would guess the company may provide a more detailed update on trading at that time.
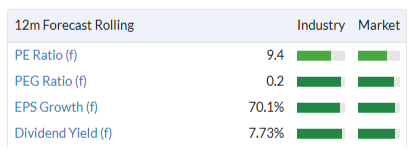
As things stand, Topps Tiles continues to look modestly valued:
Underperforming stores?
When Topps acquired CTD assets in 2024, the deal included a licence to operate 30 stores. While the CMA required the disposal of four locations, the reduction in CTD storecount from 31 to 22 over the last year suggests to me that some of the stores acquired may not have been performing as well as hoped.
I suspect this reflects a wider potential concern for Topps, which has c.300 leased stores. Total lease liabilities were c.£100m at the end of FY25 and servicing these entailed cash outflows of c.£22m.
The balance sheet also showed a net lease liability of c.£22m, suggesting a number of stores may be loss-making or underperforming.
Lease outflows certainly accounted for much of the group’s cash flow last year. My sums suggest net profit of £6.0m only converted into free cash flow of c.£2.8m in FY25.
That’s not sufficient to cover the £5.7m dividend declared for FY25, or the £3.9m of dividend cash outflows during the FY25 period.
In fairness, cash generation has generally been fairly good in this business and Topps still ended last year with net cash of £7.4m, excluding leases.
The company’s short average unexpired lease term of 2.5 years also means it has the flexibility to close or relocate stores quite quickly if needed. Short leases also mean regular renewals. These may offer opportunities for rent reductions, but could also see rents rise in popular locations.
Roland’s view
While I’d like to see more robust cash flow support for the generous dividend, I would hope that cash performance might improve as the CTD acquisition beds in and is finally properly integrated in the business.
We’ve been broadly positive on Topps Tiles recently and I don’t see much reason to change this today. The company is operating in a difficult market, with rising costs and somewhat stagnant demand. In this context, I think performance is pretty respectable, with the business well positioned to benefit when market conditions do start to improve.
Reckitt Benckiser (LON:RKT)
+0.3% at 6,080p (£54.6bn) - Special Dividend and Share Consolidation - Roland - AMBER/GREEN
This divestment is aimed at making Reckitt a higher quality, higher growth business, more closely focused on its largest brands. It’s a similar strategy to that pursued by Unilever (disc: I hold) which recently spun out its lower margin, slower-growing ice cream business.
Reckitt’s 2025 half-year results showed the Home Essentials division still generating a respectable 22% operating margin, but like-for-like sales were down by 6.5% and there was a 5% fall in volumes.
This contrasted with a modest increase in volumes and positive LFL sales for Reckitt’s core business.
My take from this is that Home Essentials brands such as Air Wick and Calgon are more vulnerable to substitution than flagship Reckitt brands such as Durex, Gaviscon and Strepsils.
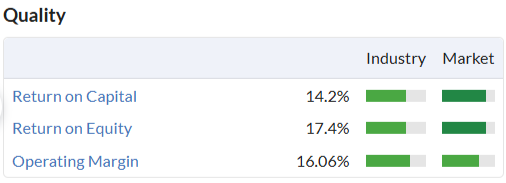
Reckitt expects this disposal to contribute to its target of reducing fixed costs to 19% of revenue in 2027, down from nearly 22% in FY24. Progress so far is yet to be reflected in the stock’s quality metrics, but I suspect these may improve when the 2025 year-end accounts are published that exclude Home Essentials.
Roland’s view
I think it’s probably fair to conclude that this disposal will improve the overall quality of Reckitt’s business. However, I’d caveat this – in the short term at least – with a reminder that the Mead Johnson baby formula business remains a potential drag on returns, due to ongoing product liability legal actions and stagnant growth.
Mead Johnson was a deeply misguided acquisition by previous management, in my view, and if I was a shareholder I’d hope for a disposal when the legal situation is resolved.
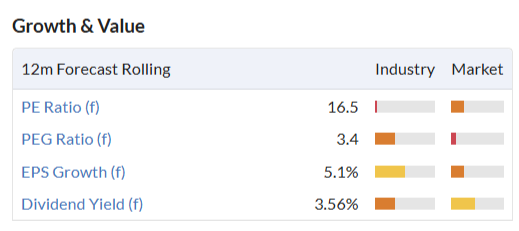
Reckitt shares aren’t cheap on a P/E of 17, but earnings are recovering and I see this as a reliable long-term defensive performer. Cash generation is also generally strong, supporting a dividend that hasn’t been cut for over 20 years (I think).
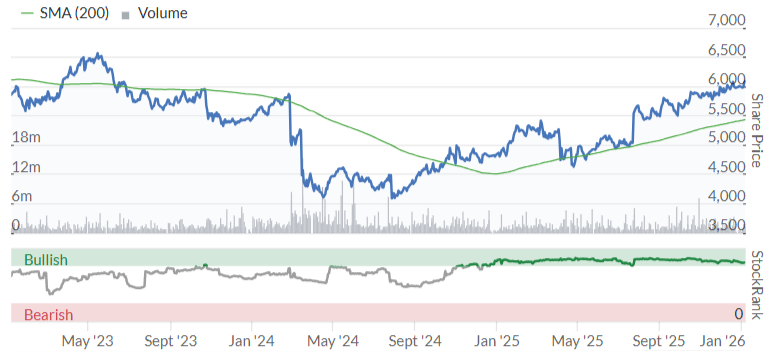
The group’s shares have recovered well over the last two years but remain below previous highs. On the basis that I think management is taking sensible steps to improve performance, I’m going to take a broadly positive view today. I’ll hope to take a more detailed look when the group’s 2025 results are published in March.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

30 comments
Topps Tiles (LON:TPT) Thanks for your analysis of Topps, Roland. One point for you to consider, if I may. You wrote: "The balance sheet also showed a net lease liability of c.£22m, suggesting a number of stores may be loss-making or underperforming".
This isn't really indicative of anything on its own other than reflecting the way IFRS 16 accounts differently for lease assets and lease liabilities over their life. However. note 14 contains some handy information about the impairment of their lease assets during 2025, inter alia the performance of the related stores. That shows that during the year, they reversed some previous impairments but also booked some new ones, Net, I think it's an overall credit to p&l of c £4m.
Worth having a closer look
Phoenix Spree Deutschland (LON:PSDL) AIC have the latest NAV at £2.50p. It has been a really poor performer price and NAV wise. Over 3 years the NAV is down 37.7% against the European property sector (AIC) down 23.8%. The discount has gone from par in 2021 to a discount of 50% in early 2024. Current discount is 32%. Current LTV was around 41% at interims. I have managed to make a negligible profit out of this in 2024. I sold out after a few months over concerns about the Berlin property market. It could be that with low number of permit buildings being issued and so PSDL may be well placed. They have taken steps to improve the energy efficiency rating of older properties which puts them in a good position regarding private landlords who might suffer the so-called "Brown discount". I am not sure as they are now selling how much they benefit form the large student population in Berlin, though this has attracted institutional buyers to provide student accommodation. i am going to research the opportunity further.
The current share price implies a value of the property portfolio of €2,800 per sqm vs sales completed over the last year by PSDL at and avg of €3,800, which is ~3% above IFRS NAV. The key question is how long will it take them to dispose of their entire property portfolio. I calculated with 5 years, which I believe is conservative, and you then get to an IRR of 15% assuming they sell all remaining properties at IFRS NAV (15% discount to EPRA NTA) and spread equally over 5 years.
Some research I have done after my 1st post estimates maybe 110% return- that assumes 3% property inflation. Assuming 0% increase then maybe 70%I quite like these situations- Palace Capital (LON:PCA) was similar, although recently things have slowed down there (until the last RNS re a large shareholder wanting CEO to stop taking his excessive salary). Risk is the rump, but looks like the refurb strategy should avoid that. I bought some just now at £1.71
£PDSL yes shareholder returns have been downgraded, but as its prorated non-optional redemptions total shareholder value hasn't been as the company will retain more value as a result of the lower redemptions
Is anyone sighted on what has happened to cause Amedeo Air Four Plus (LON:AA4) to drop today, no news that I can see, due to be going ex-dividend soon but I cannot see it as today. Thank you
Simon T in Inv Chronicle online article said bank your profits inAmedeo Air Four Plus (LON:AA4)
ST @ the I.Chronicle suggested taking profit today
Augmentum Fintech (LON:AUGM) Pitchbook (Morningstar) https://global.morningstar.com... seem to think there is a 97% chance Zopa will IPO this year. Maybe some good news for AUGM will be forthcoming. Pitchbook 2026 can be downloaded here. https://pitchbook.com/news/rep...
Graham - for right or wrong I’ve had a nibble at PayPoint (LON:PAY) . Thought about it over Christmas and then prevaricated as usual. I waited until it had gone up three days in a row and looked more like a break out from the recent flatlining.
Literacy Capital (LON:BOOK) gave notice of a holding realisation today "proving" their mark to market valuations but the share price continues to languish and slowly sink.
I bought BOOK in December after doing some research. The discount is large historically for the trust, yet the underlying portfolio is doing OK as shown by todays RNS. I am reasonably confoident is just caught up in the general PE trust malaise, which finally Trusts like Molten Ventures (LON:GROW) seem to be overcoming. Seraphim Space Investment Trust (LON:SSIT) languished until the last few months and whilst not maybe a pure PE trust it is not far off and was on a huge discount 9 months ago. If your interested here is a link to the Gemini AI Deep research note I used. https://docs.google.com/docume....
Private Equity trusts get reasonable coverage on the monthly investment trust board. Here is it the link to the latest months. https://www.stockopedia.com/co...
Galantas Gold mega deal https://www.londonstockexchang...
This company is and will continue re-rating big time in my opinion of course.
The announcement is staggeringly impressive for a minnow with a low market cap 'A historical mineral resource estimate(1)(2) for the Project estimates its measured and indicated mineral resources at an aggregate of 2.02 million (M) ounces (oz) of gold (Au), consisting of 130M tonnes (t) at 0.48 Au grams per tonne (g/t) and estimates its inferred mineral resources at 5.06M oz Au, consisting of 358Mt at 0.45 Au g/t.'
I have been looking at the gold mine in Chile and it will be a Huge Cash Cow for the company (IMO only of course) . Everything is in place as far as infrastructure and all licences are concerned. It's a Turnkey Mining Asset IMO.
Morning folks.
For those with an interest in gold and the royalty/streaming companies, I posted an analysis of Triple Flag Metals (Triple Flag Precious Metals (TSE:TFPM) here: Triple Flag Precious Metals: Investment Briefing & Strategic Outlook (2025–2030) | By jamesalastair | Stockopedia
There is a review of the ETF portfolio here: Portfolio Review - Alastair Kendall. This portfolio is up 84.5% year to date.
There is also an interesting article by Anne Applebaum on the Substack (Alastair Kendall | Substack) and new articles scheduled, written by two US hedge fund managers invested in the real asset space, and another by the recently retired UK air attaché to Paris on why Europe cannot afford 3 6th generation fighter jet programmes.
I think 2026 will be the year of solid performance in commodities: silver, uranium, copper, aluminium and Nickel all look very bullish on fundamentals and chart technicals. Gold, which I regard as real money and which James Grant (of the Interest Rate Observer) regards as a zero coupon bond issued by God with no counterparty risk, will continue towards US$6,000.
I left my crystal ball on the number 21 bus though ... of course nobody knows what the future holds, but I suspect it will be chaotic.
KEFI Gold and Copper (LON:KEFI) is one of my long shots that I began to buy in 2019 and so far has failed to hit its mark. A bit of a let-down yesterday when the share price went well below the recent retail offer. Talking of contrived dilution though, the executive chair Harry Anagnanostaras-Adams, did explain something of this on a date in 2025 and ha apologised to shareholders for it. Can't make an omlette without breaking eggs, eh? Harry plans on full production is at Tulu Kapi in 2028, (first pour in 2027?). I'm hoping to see Keki become another Anglogold Ashanti, Centamin, Greatland Gold, Pan African , Serabi Gold, or Thor Exploations success story. Yes, there are others but I missed out on them.
Me too SM! As a result I have landed on AMRQ....and Stocko figures look great...whatever Mr T says about Newfoundland. My only gold holding was CAPD and a 28% return. Most gold miners have done a lot better than that so I have sold it and bought some GCL and GPM. Time will tell!
HUTCHMED (China) (LON:HCM) is a curious company.
Over the last 10 years it has made operating losses in 9 of them. Hardly something to get excited about. It has a market cap if £1.8b, too.
It has also been issuing shares at a rate of 6% pa. But it has net cash of $1.3b. Cash/assets is a whopping 77%. It has oodles of cash, if you believe that figure.
Compare that with something like AstraZeneca (LON:AZN) , whose cash/assets is a rather more modest 7.2%.
It's all too much for me to swallow. It's a Chinese company, and these kind of accounting oddities are all-too-familiar.
It was floated in 2006, which strikes me as a long time for a Chinese company. I
Anyway, avoid.
Contrived dilution for stupid investors? (Often found in the AIM).
PWC are the auditors.
Pawns With China?
For years it was a top ten holding in Slater Growth fund - need I say any more
HCM What's interesting is that I pulled up the Stocko report from Oct 2019, when shares were at 304p. Its value score was a very low 6. It had made losses in 5 of 6 years. Shares were issued at about 5% pa, and there was still a suspiciously high cash/assets ratio of 48%. So the signs were there for years.
I looked on the ADVFN to see what people have been saying of late. There's a lot of talk about medical terms that sound impressive. I also saw a comment about revenue growth.
I feel they've missed the most obvious question of all: how comes it doesn't make any money? All this company seems to do is raise lots of money, have lots of cash on the balance sheet (vastly more than similar operations). Sure, it has lots of revenue growth, but so what? They don't get turned into profits or sweet sweet dividends.
How this company has kept going for so long is beyond me. The plug should have been pulled years ago.
Vodafone up 50% last year and above 100p!
Slowly , I am believing it!
With the upcoming Starlink IPO I believe Musk is looking for partners licenses and bandwidth so can connect satellites to the mobile network. Think of AI data centres in space with free energy and providing internet etc to everyone without masts, wires etc and the cost of water, energy etc.
Filtronic (LON:FTC) are involved and watched here.
Bezos also in the space so a bit of bidding competiton although Musk first mover.
I am a complete Dummy with this stuff so maybe of interest here. Vodafone (LON:VOD) as good as any for partnering. And any companies supplying Starlink.
The IPO itself would be for those of a gambling nature I guess as the tech is still being developed for the harsh environment of space.
I might start a Space Junk Recycling Company, might need it in 10 years with all this stuff floating around above us.
Airtel Africa (LON:AAF) ?
AAF is a momentum stock and I have decided to ride that wave! With the growing population and increasing data demands its prospects are promising. TMI includes it in its 2026 naps with a full assessment of its business.
No IPO or timeline for Starlink has been announced. Frankly, I'd be surprised if Elon Musk opts to list any more of his companies on the stock market, unless there's a sudden desperation for money. SpaceX has plenty of revenues as it is, and never struggles to raise money when needed.
No IPO or timeline for Starlink has been announced.
Well, Musk has apparently confirmed that the IPO will happen in 2026. Whether that means it will happen is one for the Musk watchers:
https://www.cnbc.com/2025/12/1...
In the event that this does happen the key UK vehicles for this are Scottish Mortgage Investment Trust (LON:SMT) (15.3% of NAV) and other Ballie Gifford trusts Schiehallion Fund (LON:MNTN) (14%), Edinburgh Worldwide Investment Trust (LON:EWI) ( 15.9%) and Baillie Gifford Us Growth Trust (LON:USA) (11.4%). I hold the former two, the latter two are under attack from Saba.
A lowball IPO price would drag NAV lower but at the top end you could see significant upward revaluations in all of the trusts. Personally the valuations being put on Space X seem insane to me, but I guess the sky is the limit (only, obviously, it's not ...).
timarr
There is already a space junk de-orbit company in Seraphim Space Investment Trust (LON:SSIT) portfolio! It's their second largest holding.
I think there are already companies focused on space junk eg D-Orbit. https://www.dorbit.space/
D-Orbit is a private company partly held by https://www.dorbit.space/ Space Investment Trust (LON:SSIT) , which has been up over 50% in the last month, mostly I believe because of its stake in ICEYE.
I hold but now SSIT looks quite expensive - trading above its NAV.