Daily Stock Market Report (Wed 26 Feb 2025) - CLIG, BRCK, WATR, IPF, AVG, MGNS, PETS, SBDS, EMR

Good morning! We have a section from Mark on CLIG to kick us off today.
1.30pm: That's all for today. Cheers!
Spreadsheet that accompanies this report: updated to 14/2/2025.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
ConvaTec (LON:CTEC) (£5.1bn) | Full-year Results | Rev +7%, op profit +23.7%. Leverage lower. Confident outlook, FY25 guidance reiterated. | |
Hikma Pharmaceuticals (LON:HIK) (£5.1bn) | Final Results | Rev +9%, ahead of exps. Core op profit +2% to $719m in line with exps. “Strong” 2025 outlook. | |
Rathbones (LON:RAT) (£1.9bn) | Full-year Results | FUMA +3.7% to £109.2bn, PBT +73% to £99.6m. Cost savings ahead of target. H2 bias in FY25? | |
Morgan Sindall (LON:MGNS) (£1.7bn) | Full-year Results | “Record” year, rev +10% and PBT +19%. Improved daily net cash. 2025 to be in line with exps. | AMBER/GREEN (Graham) [no section below] This construction share has doubled since we gave it the thumbs up in 2023. Led by founder and 6% shareholder John Morgan it continues to go from strength to strength. The outlook is in line despite economic uncertainty. I adjust our stance lower to reflect the much higher valuation now attached to the shares. May still offer value considering year-end net cash of nearly £500m. StockRank 96. Great emphasis by management on profit margins and ROCE targets. |
Hammerson (LON:HMSO) (£1.4bn) | Final Results | LFL gross rental income +1.6%, adj earnings £99m (FY23: £116m). EPRA NTAVps 370p, LTV 30%. | |
| Pets at Home (LON:PETS) (£1.2bn) | Media reports - FT. Also see City AM. | SP up 14% Rumours of private equity interest. Separately, there are suggestions by Jefferies that the CMA probe into vet services will have limited impact. | AMBER (Graham) [no section below] A spokesman for the private equity firm has told the FT that the speculation is "totally incorrect". It's hard to know what to believe. I was neutral on this share in January (at 220p) and am not inclined to change my stance at 260p in February based on rumours. If the CMA probe has no impact that will be a definite positive and I could think about turning AMBER/GREEN. For now I'll wait to receive more solid information. |
Chemring (LON:CHG) (£1.0bn) | AGM TU | FY25 outlook in line with exps. Order book 30 Jan 25 £1,351m (Jan 24: £991m). £40m buyback. | |
Aston Martin Lagonda Global Holdings (LON:AML) (£1.0bn) | Full-year results | Rev -3%, op loss of £99.5m. Net debt +43% to £1,163m. Exp +ve adj EBIT in FY25. | |
Brickability (LON:BRCK) (£198m) | TU | Resilient performance, good order visibility on y/e 31 March. FY25 adj EBITDA to be ahead of exps. | GREEN (Roland) |
Seeing Machines (LON:SEE) (£187m) | TU | H1 25 revenue flat at $25.3m, LBITDA $9.5m-$10m. Net cash $39.6m, cars on road +90% YoY. | |
International Personal Finance (LON:IPF) (£176m) | Final Results | Pre-exceptional PBT £85.2m, ahead of guidance (£78-82m). New £15m buyback. | GREEN (Graham holds) |
Tracsis (LON:TRCS) (£120m) | TU | Slow start to CP7 impacting RCM. Successful conversion of pipeline needed for FY25 to be in line. | |
Avingtrans (LON:AVG) (£116m) | Interim Results | Revenue +21%, in line. “Solid visibility” over H2; Board “confident about the Group expectations”. | AMBER (Roland) |
Water Intelligence (LON:WATR) (£63m) | TU, acquisitions, strategic update | In line. EBITDA +12% ($15m). US acquisitions: $1.2m & $3m. New water monitoring partnership. | GREEN (Roland) |
Angling Direct (LON:ANG) (£30m) | TU | FY Jan 2025 rev, adj. EBITDA slightly ahead of exps. UK like-for-like store sales +6%. | |
Empresaria (LON:EMR) (£13m) | Strategic Update | Strategy: will focus on core in UK/US and Offshore Services (India). Exits to eliminate net debt. | AMBER/RED (Graham) [no section below] Accelerating the slim-down to focus on only three divisions. Moves to a single brand in UK and US. I was AMBER/RED last October due to the level of borrowings involved and net debt was higher still at £15m as of Dec 2024. Recruitment conditions remain poor and it’s reasonable to worry that there are structural problems with the sector. Decision action is welcome. I’ll leave my stance unchanged until I see what values are achieved in the forthcoming disposals. |
Silver Bullet Data Services (LON:SBDS) (£9m) | TU | Revenue £9.4m (LY: £8.3m) Positive EBITDA run rate in Q4, anticipated to continue in 2025. | AMBER/RED (Graham) [no section below] Understanding the product set is a challenge: digital transformation for businesses with an emphasis on improving the customer experience (CX). Positive EBITDA run rate is positive and £6m of revenue has already been booked for 2025. However, the word “cash” isn’t mentioned today and I’m not convinced that the company has very much, so I’ll take a moderately negative stance. |
Backlog
City of London Investment (LON:CLIG)
Flat yesterday at 356p - HY Results - Mark - AMBER/GREEN
Funds under management are down slightly on the half year. However, it is the average that matters for fees, and here, the trend is positive:

They say FUM at the end of January are also up and stand at around £10.1b.
This sees an increase in fees:

That feeds through to the bottom line:

While there is quite a way to go before they return to 2021 highs, these are at least moving in the right direction (something not many asset managers can say at the moment.) Importantly, for many holders of this high-yielder, there is improved dividend cover. Here are the company’s own assumptions for this:

Their investment strategy of investing in closed-end funds trading at a discount also seems to be doing well across the board, which perhaps bodes well for outflows to turn into inflows over time. They give some more detail than usual with these results:

(Apologies for the picture; they don’t appear to allow text to be copied out of their interim report.]
One of the risks here is that the returns from good performance end up going out as bonuses to the managers rather than to shareholders. This is something the company had an issue with in the past, with the founder stepping back in to get costs under control. Since handing over to the current team, there is little sign of this, with employee costs up less than 3% over the last year. One to watch out for when annual bonuses are accounted for at the end of the year, though.
Until then, the forward P/E looks a little high, given the lack of long-term growth:

But given that almost all these earnings turn into free cash, it enables them to pay the market-leading 9% dividend yield. Unlike many asset managers at the moment, this is covered by earnings and cash flow.
Mark’s view
This is very much a steady-eddy compared to many asset managers. Its relatively low-risk strategies appear to be outperforming, and the fees earned cover the 9% dividend yield, so I can easily see this being attractive to income-focused investors. AMBER/GREEN
Graham's Section
International Personal Finance (LON:IPF)
Up 4% to 132.6p (£288m) - 2024 Final Results and Accounts - Graham - GREEN
At the time of publication, Graham has a long position in IPF.
IPF is a home credit company, online lender and credit card provider. It operates in various European countries, Mexico and Australia.
I had the privilege of speaking with IPF’s CEO Gerard Ryan, CFO Gary Thompson and Investor Relations Manager Rachel Moran this morning.
I’ve also been listening to their results webcast.
Below are the notes from my Q&A. Please note that I didn’t record the meeting - I took handwritten notes and typed them up here. So if there are any errors they are mine alone!
First, let me post the key statistics table so you can have a big-picture view of the results:
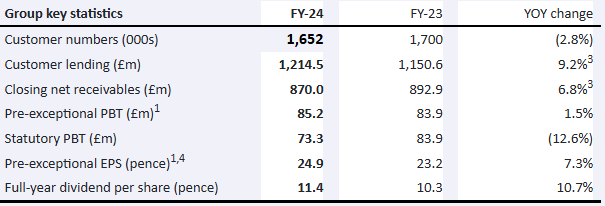
The outlook statement says:
Our strong operational and financial performance in 2024, together with our strong balance sheet, lays the foundation for accelerating the rate of growth and the pace of change in 2025 as we continue to execute against our Next Gen strategy.
In Poland, the receipt of the full payment institution licence enables us to accelerate its return to growth whilst in Mexico home credit, where we have upgraded our IT systems infrastructure, we anticipate strong demand to fuel growth and geographic expansion. Following an excellent performance in 2024, we expect IPF Digital will continue to build scale and deliver further strong growth in 2025, particularly in the very attractive Mexico and Australia markets.
Now here are my notes from the Q&A!
1. Exceptional costs.
Background: In 2023, pre-exceptional PBT and statutory PBT were both £83.9m, i.e. there were no exceptionals.
In 2024, IPF generated “pre-exceptional” PBT of £85.2m in 2024, while statutory PBT was £73.3m.
My question related to the outlook for exceptional costs - would they calm down or remain at a higher level?
Answer: about half of the exceptional costs were related to the refinancing of IPF’s Eurobond, and that is done now. That bond is now trading at a yield of 8.5% (it was issued at 10.75%!).
The other half of the exceptional costs relate to the restructuring in Poland, an area which can now start to grow again. Historically IPF was a siloed organisation. Moving forward, there will be more shared services between different countries. To the extent that exceptional costs are needed in future it should have more to do with natural attrition than particular countries that need to be restructured.
2. Impairment rate.
Background: the impairment rate has fallen from 12.2% to 9.6%, far below the target range of 15-20%. What explains this?
Answer: The quality of the portfolio. IPF’s customers have access to jobs and higher incomes than they did before. Due to cost of living challenges they need additional finance but they are able to repay from their income. Secondly, regulations have forced IPF to find customers with proof (documentation) of their income, rather than operating in the cash economy. This also sends IPF higher up the quality spectrum in terms of customer credit quality.
Successful execution by IPF’s employees is another key factor in driving the low impairment rate.
Follow up question on impairments: should the target range be adjusted, given how far below it the actual impairment rate is?
Answer: it could be adjusted lower but they are happy to leave it where it is for now. In 2025 they are planning to gain a lot of new business and lots of new customers will inherently bring a higher risk. Also, growth in Mexico was slower than expected in 2024. The impairment rate in Mexico is 30% and as this region grows it will raise the impairment rate.
If they did lower the target impairment rate, they would also want to lower the target revenue yield (i.e. they would expect lower revenue at a lower impairment rate).
3. Regulations
Background: Poland had a major restructuring after an interest rate cap was brought in. As this is such an area of concern for investors, have there been any developments in terms of regulations since we spoke last?
Answer: Nothing new here. There are Europe-wide regulations that apply. In terms of specific countries, there is still no rate cap in Czechia and that may come in at some point. A new cost of credit cap came into force in Romania in November (not material).
4. General question on collateral
Background: It was put to me by a subscriber that IPF suffers from not having access to collateral. Its customers do not have much collateral to put up and if they do, other lenders will have first claim to it. Would IPF like to address this?
Answer: this reflects a misunderstanding of the business model. The average loan amount is £900 in Europe and only about a third of that in Mexico. IPF has no interest in repossessing a customer’s television to repay a loan, and does not want to keep people in debt. What they do is help people by extending contracts at no cost to give them the time to repay. Collateralised debt is not their business model and never will be.
Historically, the stability of their impairment rate (without collateral) has been incredible. Collateralised lending brings its own set of risks, e.g. the value of 2nd hand cars can fall.
5. Buybacks
Background: IPF has announced a new £15m buyback having just completed one in H2. I like companies at cheap earnings multiples buying back their own shares. Is it reasonable to think that IPF could very meaningfully reduce its share count in the years ahead through the use of buybacks?
Answer: For us, buybacks are not about ego. It’s about being disciplined. If we have a surplus that we can’t use effectively to grow, then we will deploy it on buybacks. The exceptional tax credit (£17.4m) that we gained in 2024 was unexpected, and we are happy to return it to shareholders.
Summing up: we think investors should be pleased with these results. They include a successful refinancing, meeting and beating historic guidance, our pre-exceptional return on required equity (RoRE) hitting our target range (15-20%), and carrying good momentum into 2025.
Graham’s view
I need to move on and look at other companies now, but I’m glad I had the chance to look at this in detail. IPF was on my 2025 watchlist and I’m now a shareholder in the company.
All lenders carry risk but personally I think the risks are priced in here:

The StockRanks love it, too:

It’s not every day that I find a company at a very cheap earnings multiple that is buying back its shares (£30m in total announced across two buybacks, more than 10% of the market cap), and appears to have good growth prospects. It’s too good of an opportunity for me to pass up and I’m hoping to add to my position.
Roland's Section
Brickability (LON:BRCK)
Up 6% to 65p (£210m) - Trading Update - Roland - GREEN
It’s good news this morning for shareholders in this building materials distribution group:
the Board now anticipates delivering adjusted EBITDA modestly ahead of market expectations for the year ending 31 March 2025.
The company helpfully specifies a market consensus for FY25 adjusted EBITDA of £47m prior to today.
Estimates: I can’t find any updated broker notes this morning, but I would guess that use of “modestly ahead” suggests an increase of around 5%.
On that basis I estimate today’s update may suggest FY25 adjusted EBITDA of perhaps £49m.
My number crunching suggests this could equate to adjusted earnings of just under 9p per share, compared to previous consensus of 8.5p. That would leave Brickability on a FY25E P/E of seven.
Trading commentary: Brickability notes the “challenging market backdrop” but says its diverse revenue streams have supported revenue growth over the period.
During the four months to 31 January 2025, revenue rose by 12.3% on a like-for-like basis, with growth across all of the company’s divisions. These highlight more diversity than we might expect from a company with Brick in its name:
Bricks and Building Materials & Importing: strong revenue growth, but pricing has become “increasingly competitive” due to softer demand
Distribution: H1 trend has continued with strong demand for Solar PV products from the Upowa business
Contracting: building safety remediation continues to support demand for cladding and fire remediation services. Divisional margins “significantly ahead of the Group’s blended average”
Outlook: trading during the first 10 months of the year ending 31 March has been “resilient”.
Current momentum and good visibility on orders for the remainder of the year are said to support today’s upgrade to EBITDA guidance.
Brickability CEO Frank Hanna believes the business is well positioned “to benefit quickly” when new housing volumes start to rise, but cautions the pace of this recovery “is still uncertain”.
Roland’s view
Given Brickability’s stable trading, I think a cautious outlook is probably already reflected in the share price, which has sold off sharply over the last year:

My only slight qualm here is net debt, which was £56m at the end of H1 and is expected to be £60m at the end of March (according to a Cavendish note from Dec 24).
Given that this is a low margin business, I wouldn’t want to see borrowing climb much higher than this. But I don’t think there’s too much to worry about at current levels, which suggest a net debt/EBITDA multiple of perhaps 1.2x.

With the stock continuing to trade at a modest valuation with a well-covered 5.5% dividend yield, I’m happy to maintain my GREEN view from November.
Water Intelligence (LON:WATR)
Up 5% to 385p (£67m) - 2024 Trading Update & Partnership with StreamLabs - Roland - GREEN
Today’s update from this “leading multinational provider of precision, minimally-invasive leak detection and remediation solutions for both potable and non-potable water” is a triple header:
Water Intelligence plc … is pleased to provide (i) a trading update for the year ended 31 December 2024, (ii) announcement of two acquisitions to kick-off 2025, and (iii) update to the Group's Strategic Plan especially highlighting a partnership with StreamLabs Inc. (www.streamlabswater.com) that will add to organic growth and drive brand differentiation across the US.
Let’s start with a look at the company’s 2024 trading update to provide a base for our expectations.
2024 summary: Graham has previously commented on the need for stronger revenue growth here to drive expansion of the business. Water Intelligence appears to be delivering on this, with double-digit revenue growth in 2024, which the company says is in line with expectations:
Revenue up 10% to $83.3m
Franchise revenue -3%, US corporate locations +11%, reflecting franchise buybacks
Adj EBITDA up 12% to $15.0m
Adj PBT up 4% to $9.1m
Reported PBT up 1% to $6.3m
Clearly there’s some leakage in margin between EBITDA (up 12%) and adjusted PBT (up 4%). We may have to wait for the full-year results to find out why. However, today’s update does reveal an increase in total debt and leverage during 2024:
Net bank debt: $11.1m (2023: $1.3m)
Total net debt of 1.48x adj EBITDA (2023: 0.53x)
Total net debt includes deferred franchise acquisition payments. Based on the EBITDA multiple provided I estimate total net debt may have been c.$22m at the end of 2024, up from $7.1m at the end of 2023.
Again, we’ll have to wait for the FY results to learn the cause of this cash outflow over the last year. I know the company has previously described itself as “under-levered” and has been making acquisitions, so this may not indicate any problem with cash conversion.
Acquisitions: two more acquisitions have been made “to kick-off 2025”, including another reacquisition of an American Leak Detection franchise (ALD is WATR’s subsidiary):
a small plumbing business in Connecticut (acquired for $1.2m or 4x profits)
An ALD franchise in Georgia and S. Carolina (acquired for $3m or 5.5x profits)
Both companies are said to serve “high-end residential homes” and are a good fit for StreamLabs products – Water Intelligence’s new strategic partner.
StreamLabs Water partnership: StreamLabs is a US company that’s owned by US insurer Chubb and appears to offer complementary services to Water Intelligence:
a US company with various high quality water monitoring products and a strong insurance channel pedigree.
ALD plans to launch a preventative maintenance line of business supported by StreamLabs products. This is expected to drive organic growth through the company’s existing insurance company relationships – insurers are said to have an increased focus on preventative maintenance.
Outlook: no financial guidance has been provided today, but Executive Chairman (and 28% shareholder) Dr Patrick DeSouza sounds confident about the outlook:
We had a strong 2024 and during Q4 seriously developed our plan for market leadership in Preventive Maintenance for water loss because of aging residential and commercial infrastructure. We executed two more national insurance accounts preparing the way for our StreamLabs partnership signed recently. We are ready financially and operationally for our next phase of accelerated growth and we look forward to the rest of 2025.
Consensus forecasts prior to today suggest WATR’s earnings could rise by 15% in 2025.
Roland’s view
Water Intelligence appears to be trading well and taking logical steps to expand its reach and broaden its service offering.
The shares continue to look reasonably priced to me, given the outlook for earnings growth.

I look forward to seeing the full-year figures, but have no qualms about maintaining Graham’s previous GREEN view today.
Avingtrans (LON:AVG)
Up 4% to 364p (£119m) - Interim Results - Roland - AMBER
Engineering group Avingtrans supplies equipment and services to customers in the energy, medical and industrial sectors.
Today’s results cover the six months to 30 November 2024 and appear to support an unchanged outlook for the current financial year.
With a strong first-half performance and a pleasingly robust order book, the Group is well-positioned to meet market expectations for the full year and the Board views the future with confidence.
Mark commented on a recent Avingtrans contract win on 13 Feb, giving a taste of the way this group owns and improves niche engineering businesses.
Today’s interim results provide a bigger picture view of the group’s performance. Let’s take a look.
H1 results summary:
Revenue up 21.2% to £79m, in line with expectations
Adj PBT stable at £4.5m (H1 24: £4.4m)
Reported PBT up 13.5% to £3.8m, mainly due to an absence of acquisition costs
Adj EPS up slightly to 12.0p (H1 24: 11.7p)
Net debt exc. leases of £8.9m (H1 25: £6.1m)
These headline numbers look strong in terms of growth, but it may be worth remembering that Avingtrans’ profits fell sharply last year. So this year’s performance might be seen as a return to growth – earnings are not expected to exceed FY23 levels until FY26.

Profit margins either improved or worsened, depending on your preferred metric:
Gross margin down 1.6% to 30%, due to a greater proportion of OEM sales
Operating margin rose by 0.2% to 5.7%
Both the company’s two main reporting segments delivered double-digit revenue growth last year:
Advanced Engineering Systems (AES): revenue rose by 21% to £76.8m, with adjusted operating profit up 41% to £7.8m, giving a useful 10% margin.
Management comments on the strong performance of the Hayward Tyler subsidiary, driven by data centre growth and transport electrification.
Medical Imaging: revenue rose by 49% to £2.2m. However planned spending saw this division report an increased operating loss of £2.6m (H1 24: £1.1m loss).
The company says Adaptix product sales (3D X-ray technology) have commenced, with “multiple initial distributors” appointed in the US and UK. EU distributors have also been identified.
Magnetica (“next-generation” MRI technologies) has also appointed a distributor for the USA.
This division is still at an early stage of growth but appears promising and could be worthy of further research for interested investors.
Outlook: the company says it is “confident about achieving market expectations for FY25”, given the strength of its order book:
Order book in AES secured to achieve 95%+ of the FY25 market expectations, providing strong visibility and confidence in meeting targets
In addition, Avingtrans says it has secured over £100m in orders for future years.
Estimates: with thanks to Singer Capital and Cavendish, updated broker coverage is available on Research Tree today.
Analysts at both companies have left their forecasts unchanged today. FY25 earnings estimates of 14.3p (Singer) and 14.8p (Cavendish) bracket Stockopedia’s consensus figure of 14.5p per share, implying a forecast P/E of 25 for the current financial year.
Earnings growth is expected to pick up in FY26 with both brokers offering estimates of 25.9p per share, equivalent to a P/E of 14.
Roland’s view
I’m not hugely familiar with Avingtrans, but as a niche engineer I’ve always been a little surprised that profitability isn’t a little stronger.
In fairness, I imagine this situation could improve if AES can maintain growth and if the Medical Imaging division can achieve a profitable scale. These assumptions don’t seem unreasonable to me, given the company’s track record:

The shareholder register shows chairman Roger McDowell with a sizeable holding and reveals that fund manager Harwood is the largest shareholder. This suggests to me that there’s both smart money in AVG and boardroom alignment with external shareholders.
I can see that this could potentially be an interesting long-term investment that would reward further research, beyond the scope of this report.
However, the valuation seems up with events to me, based on FY25 estimates. Any upside seems dependent on a strong upturn in earnings next year.
At this stage I’m going to maintain our neutral view, but if trading improves as expected I could see myself taking a more positive view later this year. AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
Mello 2025 has just been launched and available to book your place
I am taking a relatively comfortable back seat but the Mello team are thrilled to announce the launch of Mello 2025, which will be back for two days packed full of company presentations, keynote speakers, panel sessions such as the ever popular BASH and of course lots of networking with likeminded investors . Probably half the attendees are from these Stockopedia boards...
Date: 3rd & 4th June 2025
Location: Clayton Hotel Chiswick 626 Chiswick High Road London, W4 5RY
Highlights of Mello 2025:
Keynote Speakers: Hear from industry leaders and learn from the best in the investing world such as Lord Lee, Andy Brough, Vin Murria, Gervais Williams and many more
Panel Sessions: Gain insights and learn about different investment strategies or approaches.
Networking: Connect with like-minded individuals and other excellent investors.
Exhibitions: explore the different investment opportunities in our exhibitor area and meet management face to face.
Register Now: https://melloevents.com/mello2025/
Discount Code: use code Stocko50 for 50% off tickets
Stay tuned for more updates and exciting announcements. We can't wait to see you at Mello 2025!
#Mello2025
David
Why have bank shares jumped?
Hi Graham & Roland, is one of you able to circle back to Arcontech interim results which came out on Monday this week please if you get an opportunity please? Nigel Ridge has taken a 4.594% stake in it yesterday (formerly of Blackrock, but now retired).
Many thanks.
DH2
Hi DH2, I'll see what we can do! Cheers. G
I see Nigel Ridge (retired from Blackrock fund manager's in 2024) has taken a 4.594% stake in Arcontech yesterday (announced today).
I suppose I shouldn't be surprised, given the state of the small cap market at present, but I expected Tracsis (LON:TRCS) to bounce today on their trading update. Yes, the first half has been tough so far and so meeting full year forecasts will require a good H2 but we knew already about delays in the rail industry and this appeared to have been fully discounted by a sharp sell off in the shares since December. Furthermore, 2026 now looks well underpinned by recent contract wins and I am a relaxed holder at this level.
Warpaint London (LON:W7L) Anyone aware of the reason for Warpoint to be wobbling further today? Having searched I cannot spot a reason.
Likewise, cannot find anything on this..
Thanks for your interview notes on International Personal Finance (LON:IPF) Graham, looks like a positive update overall.
Thank you on the commentary for WATR. looks ok and the pricing seems fair. lets hope we see the growth reflected in the SP downstream. Nothing worrying in the news so all good in my opinion.
Wienerberger AG (WBAG:WIE)
For those with an interest in the UK residential market, Wienerberger released their FY24 results today.
https://www.wienerberger.com/c...
Sadly, there isn't much detail on the UK brick market this time (they usually add a sentence or two as they are the 3rd largest producer in the UK) but I found these UK-specific comments interesting:
A
What a world we live in.
TSLA sits on a PE of 145. Their EU sales drop 50%, shares drop only 8%. If this was UK-listed the shares would be down over 20%.
PETS up 10% today. No news (that I can see). I'm pretty happy about that. I bought those in late December. They had a profit warning last year, smacking the shares. Then there's the whole CMA thing. Everyone is worried about tax hikes, too. Shares were at a 3-year low. Yet I figured it was actually growing OK. Look at the revenue growth over the last 5 years. Nearly 9%pa. I also heard that it had been picking up market share. P/FCF is 6.7. EV/EBITDA 5.9. I figured it was worth a punt.
MGNS Record year, PBT +19%. Shares have barely budged, and were down at one point. Maybe the market saw expectations "in line" for 2025 and got bored, or something. P/FCF of 10 and EV/EBITDA of 8.3. I hold.
If TSLA was UK listed it would probably be on a PE of about 8 not 145.
True enough! I pretty much said the same thing to my mate in the US. It's a whole different investment world across the pond.
Tesla's a special case, though, because of the hero-worship of Musk, and the myth that he's a majority owner. The reality is that he seems to have lost interest.
He's turned on all those who hero worshipped him up to becoming the world's richest man... His Ratner moment.. They definitely do it bigger in America.
How long before Musk is surrounded by jars of his own body fluids, aka Howard Hughes.
Neuralink will keep him alive forever. Maybe not on Mars though.
A few decades ago we had Johnny Cash, Bob Hope and Steve Jobs.
Now we have no Cash, no Hope and no Jobs.
Please don’t let Kevin Bacon die.
- courtesy of Mr Bill Murray. Long live Elon I say.
Lets hope its his Ratner moment x 10
Saw a picture of a poster at bus stop with a Musk atop a Tesla giving a Nazi salute. The text read, 0 to 1939 in 3 seconds. The car was advertised as the Swasticar. Amazing what having too much money does to you.
As much as I dislike musk, for transparency, this was by an anti musk group called 'everyone hates elon'. So not really as it appeared if you thought musk was behind it.
No, I knew it was an anti Musk poster. Just thought it caught the public mood about a guy who has lost sight of decency.
PETS Seems to be a bid rumour, as Ed pointed out. That's a shame. I had been looking for an excuse to buy some shares and December proved an opportune time. I wasn't necessarily thinking of a quick in-and-out. Sigh.
Just seen Pets at Home (LON:PETS) up tad over 7% at open nothing I can see on news wires just wondered if anyone had heard anything ?
Regards
Andy
Short positions closing? 4.1%+ out on loan.
It's bid rumours ... Pets at Home (LON:PETS) - good article on FT Alphaville - they've snuffed out that someone at BC Partners has created something that looks like a bidco
https://www.ft.com/content/ed8...
Thanks Ed, Tim and BnB see what the end of day brings
Ed, why is Everplay (LON:EVPL) showing a share price of 264p, on the Stockreport, when the share price is only 217p?
It's showing 217p now.
Probably end of day auction period when you viewed it. Quotes can be weird then.
Thanks Ed, but it is still 264p on the Stockreport screen, has been all day.
The price at the top of the stock report is a closing price from late January. Definitely something weird happening on that one Ed …
Maybe a bug to do with the ticker changing from TM17 maybe?
Pets at Home (LON:PETS) spiking. Bid rumours? CMA not pursuing (unlikely, CVSG relatively unmoved)? Anyone know more?
Pets at Home (LON:PETS)
And now up over 10%. It's fairly heavily shorted, so there could be some arse covering going on.
Although if PETS does come under threat from a low ball bid while its price is depressed in part due to the CMA investigation I reckon there'll be a lot more at the regulator ...
But it's not the CMA investigation being resolved, they released the latest documents for review only a few weeks ago.
So many UK stocks at silly prices, it's pretty much open season.
timarr
Pets at Home (LON:PETS)
Share price up on bid rumours:
https://www.ft.com/content/ed8...
And now 5 companies set up 2 days ago, aptly prefixed with the word 'PUG':
https://find-and-update.compan...
Given how random it is that someone has "discovered" this, I can only assume that there might actually be some truth to the rumours.
A
Rathbones (LON:RAT) may be worth a glance: pre-tax profit up 79%, lots of things moving (finally) in the right direction. FUM increased by £5.2bn despite an underlying outflow of £1.4b.
A lot of this is due to the merger / takeover of IW&I but it does seem to have gone smoothly, with only 0.3% of IW&I customers declining to move to RAT.
Allegedly the merger here may have led to RAT withdrawing from a lot of smaller Investment Trust positions, which may account for some of the weakness in that sector.
timarr
Hikma Pharmaceuticals (LON:HIK) - Good results as far as I can see but down almost 9% first thing - Is there anything going on or just the usual unpredictability of the MKT?
Hikma
good results but the share has gone up considerably over the last three months. some consolidation is expected.
Avingtrans (LON:AVG) Positive interims that belie the share price performance as is the case with many good quality small caps. Investment in the Medical division , especially Adaptix appears to be coming to fruition.
Brickability (LON:BRCK) Pleasing trading up date given the challenging economic backdrop and the Government's current inability to improve house building.
I hold and as expected see both shares as having significant upside.
Avingtrans (LON:AVG) PIE strategy (Portfolio Integration Expansion) seems to replicate the much loved, and very profitable, earlier incarnation of Melrose Industries (LON:MRO) . Would be interested to hear an expert’s analysis. I hold.
City of London Investment (LON:CLIG) : arguably an elephant in the room which is rarely discussed is that the biggest shareholder George Karpus, who owns over 30% of shares, turns 80 this year if his companies house birth date listing is correct. I don't think he has indicated what his intentions are unless I've missed something. Possibly risks creating an overhang? Or, more positively, a bidder??
Good morning, Team. Please could you have a look into Water Intelligence (LON:WATR)?some interesting looking announcements this morning...
Me too please
Thank you for the write up City of London Investment (LON:CLIG) is a good read, it caught my eye yesterday morning so your views are helpful.
International Personal Finance (LON:IPF) ahead of guidance headlines. Some complex "exceptional items" accounting but should be fairly well received. I hold.
Trading update out for Brickability (LON:BRCK)
- ‘adjusted EBITDA modestly ahead of expectations’
Imagine what might happen if the government actually manages to get house building back on track!
According to Henry Boot they are re planning
I would rather not, thank you ! More cement, more traffic, more pollution, less trees .
I know that is what we call " Growth ".
The interesting part of the Brickability (LON:BRCK) TU for me was this:
"The regulatory focus on building safety continues to provide a supportive backdrop for the Contracting Division, which is benefiting from a multi-year pipeline and order book within its specialist cladding and fire remediation businesses, contributing to divisional margins significantly ahead of the Group's blended average."
Companies like Watkin Jones (LON:WJG) are spending large amounts of money on cladding remediation and it looks like BRCK are increasingly involved in this higher margin business hopefully driving profit growth over the next few years until the house building boom (eventually?) arrives.