Daily Stock Market Report (Wed 29 Jan 2025) - VANL, PAY, DWL, HSP, AJB, CWR, SMWH

Good morning! The Agenda is now complete.
1pm: we're out of time now for this report, enjoy the rest of your day!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
United Utilities (LON:UU.) (£6.7bn) | Final Determination & TU | Agreed £13bn capex for 2025-30. Current trading in line with FY25 guidance. | |
AJ Bell (LON:AJB) (£1.8bn) | TU | Record AUA up 3% to £89.5bn in Q1. Customer numbers +4% in qtr. Outlook positive. | GREEN (Graham) Staying positive on this one even if growth might possibly be less rapid than it was before, due to its excellent market positioning. |
Pennon (LON:PNN) (£1.5bn) | £490m Rights Issue | Issuing shares at 264p, 35% disc to ex-rights price. Cash needed to fund spending through 2030. | |
WH Smith (LON:SMWH) (£1.5bn) | TU | LFL sales +3% in 21 weeks to 25 Jan, Travel LFL +8%. N. Am performance improving. | AMBER/GREEN (Graham) A pleasant update from this Travel retailer, with the expected divergence between growth in Travel and shrinkage on the High Street. The recently announced possible sale of High Street continues to make a lot of sense to me. |
Raspberry PI Holdings (LON:RPI) (£1.4bn) | TU | Channel demand normalising. Adj EBITDA “not less than $36m” for 2024. Outlook sounds mixed. | |
Dowlais (LON:DWL) (£920m) | Takeover offer | Cash and shares offer from US peer valued at 85.2p per DWL share. |
PINK (Roland) |
PayPoint (LON:PAY) (£502m) | TU | On track to deliver FY25 exps. Net rev +1.9% to £53m in Q3, some weakness in Shopping div. | GREEN (Graham) Upgrading this on valuation grounds (it’s cheaper now vs. Nov). On track for £100m of EBITDA by the end of FY26. |
FDM (Holdings) (LON:FDM) (£290m) | TU | 2024 results to be in line with exps. 30% headcount reduction. 2025 outlook uncertain. | |
Ceres Power Holdings (LON:CWR) (£270m) | FY TU | Record order intake >£110m, revs at upper end of guidance £55-£60m. GM exp 78-80%. | AMBER (Graham) Heavily loss-making and therefore speculative, but the historic losses are offset by a strong balance sheet and really impressive growth. |
Hargreaves Services (LON:HSP) (£195m) | Interim Results | H1 rev +14% to £125m, PBT +96% to £5.3m. FY results to be in line, divisional perf mixed. | GREEN (Roland) |
SRT Marine Systems (LON:SRT) (£139m) | Contract Award | Signed phase II of long-term project valued at $15m, completing in 2025. Phase 3 exp in 2026. | |
hVIVO (LON:HVO) (£139m) | TU | 2024 rev +11.9% to £62.7m. EBITDA mgn c.26%, cash of £44m. New large trial unit opened. | |
EKF Diagnostics Holdings (LON:EKF) (£120m) | FY TU | Rev falls to £50.2m (below exps); reflects focus on higher margin products. Adj. EBITDA £11m. | |
Litigation Capital Management (LON:LIT) (£105m) | TU | “Mixed results”. H1 realisations A$52m vs. invested capital A$14m. H1 after tax loss A$8m. | |
Van Elle Holdings (LON:VANL) (£42m) | Interim Results | Rev -4%, adj. EBITDA unchanged at £6.2m. Challenging conditions. Confident in achieving exps. | GREEN (Roland) |
Naked Wines (LON:WINE) (£33m) | TU | Solid peak trading performance, in line. Rev -8.9%. Net cash £30m. Inventory reduction could hit EBIT. | |
NAHL (LON:NAH) (£32m) | FY TU | In line. Rev £38.8m (2023: £42.2m). Adj. PBT £2.2m. Net debt £7.1m. Outlook in line. | |
CT Automotive (LON:CTA) (£22m) | TU | “Broadly in line”. Rev $117m (vs $119m), PBT >$8.6m (vs $9.3m). O/look: mid-single digit rev growth. | |
React (LON:REAT) (£20m) | Final Results | Rev +6% to £20.7m. Cash £1.8m. Outlook in line. Transformational acquisition being incorporated. | |
Virgin Wines UK (LON:VINO) (£17m) | TU | FY25 outlook in line. Xmas trading +6.7%, Dec revenue +9% vs 2023. | |
Velocity Composites (LON:VEL) (£15m) | Final Results | Rev +40% to £23m. Adj. EBITDA £0.4m (slightly ahead?). Confident in strong growth. |
Graham's Section
PayPoint (LON:PAY)
Up 2% 719p (£513m) - Trading Update - Graham - GREEN
Paypoint’s Q3 update is “on track to deliver expectations for FY25”.
This is a detailed quarterly update with some unusually long paragraphs of text from CEO Nick Wiles. Let’s see if I can break it down for you:
Momentum building for £100m EBITDA by end of FY March 2026
Group net revenue +1.9% to £53m
Looking at the divisions ordered by revenue in the quarter:
Shopping division (includes PayPoint One terminals and PayPoint Mini point of sale systems): net revenue down 2% to £16.1,, despite an increase in the UK retail network.
Love2shop: net revenue up >1% to £18.8m. Highstreevoucher.com is ahead of plan while Park Christmas Savings was “solid”.
Payments & Banking:(includes both the omnichannel product “Multipay” and legacy energy sector business): net revenue up less than 1% to £14m. Digital revenue grows strongly while the legacy energy sector business declines.
E-commerce (includes Collect+): volumes up 36.8% vs same peak quarter last year. Net revenue up 32% to £4.1m.
So as usual we have the decline in the old cash/energy-based activities, but other activities are stable and E-commerce is growing rapidly from a low base.
Net debt has risen to £109m as PayPoint has been investing in obconnect (it now owns 55% of this) and carrying out a £20m share buyback programme. Net debt should fall back below £100m by 31 March 2025.
The company has a target leverage multiple (net debt/EBITDA) of 1x and so as EBITDA hopefully rises towards £100m, it should hit its target leverage. There are seasonal and one-off factors at play, so it can’t be expected to maintain the same leverage multiple throughout the year.
Dividends vs buybacks: the company is planning to continue with buybacks for 3 years in total (this is year 1), potentially increasing buybacks in years 2 and 3. At the same time, dividends will only increase “at a nominal rate”, with the idea that the dividend payment will become more affordable as the company’s earnings grow. Dividend cover is about 1.5x currently, and the company wants this to grow to 2x. Seems sensible to me.
Estimates: Panmure have left estimates unchanged today, including FY 2025 revenue of £190m (up 5%) and EPS of 69p (up 10%). EBITDA this year should be around £90m.
Graham’s view
This stock features on my watchlist and is one of my favourite stocks for its cash generation and quality metrics. And it usually has a cheap valuation despite, in my view, having some interesting growth opportunities and some of its products (such as PayPoint One) being market leaders in their niche.

As it has an old-fashioned energy payments business that’s in decline, I think some investors write it off as a dying business. But I think there is much more to it than that, if you look across all of its four divisions.
I do acknowledge that top-line growth is limited: only 1.9% for the quarter, but hopefully around 5% for the year.
[As an aside, please note that the Revenue number on the StockReport for 2024 refers to gross revenue, but the number used by brokers (and me) is net revenue, which is much lower.]
Roland was AMBER/GREEN on this in November (at 790p), with the stock trading at a PER of 11x.
It’s now trading at 10.4x earnings (for FY March 2025). Or if you use FY March 2026 earnings, it’s at 9.6x. You may wish to adjust this for the debt load. But I like the value on offer here.
The capital allocation plan makes sense to me: they will hopefully continue buying back some shares at this valuation, at an earnings yield of about 10%.
If the share price were to fall much further than this, I hope that they’d increase the amount spent on buybacks and perhaps even make it larger (in pound terms) than the dividend, which costs about £27m p.a.
And vice versa: if the share price increases, I hope they’ll spend less on buybacks than planned.
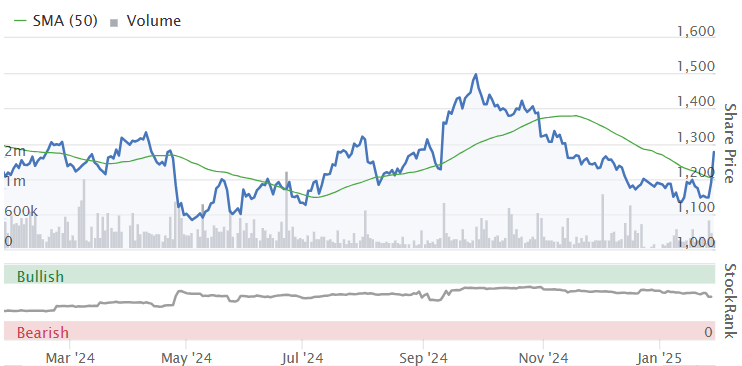
Overall, I remain very happy with this stock on my watchlist and the StockRanks don’t disagree with me, giving it a near-perfect score:

AJ Bell (LON:AJB)
Down 2% to 439.6p (£1.8bn) - Q1 Trading Update - Graham - GREEN
Let’s check out the Q1 update from this highly-rated investment platform.
Key points from the platform business:
19,000 extra customers, up 4% in the quarter to 561,000 (up 16% year-on-year).
Direct-to-consumer (not advised) customers leading the growth, up 20% year-on-year.
Assets under administration up 17% year-on-year to £89.5 billion (N.B. this includes the effect of both net inflows and market market movements).
Quarterly net inflows are slightly up on the corresponding quarter last year (£1.4bn vs £1.3bn).
At AJ Bell Investments, AUM are up 38% year-on-year to £7.2bn, starting from a fairly low base. Net inflows for the quarter are solid at £0.4bn.
CEO comment is interesting as it suggests that the October Budget was responsible both for higher pension contributions in the D2C platform, but also for higher pension withdrawals in the advisory platform.
I guess that the average age of customers in the D2C platform is probably lower than the average age in the advisory platform? So in advance of the Budget, one set of customers was busy making contributions, while the other set of customers was busy making withdrawals!
Or perhaps it might also be that retail investors were more worried about the Budget than financial advisors? AJB’s CEO notes that pre-Budget speculation “caused a short-term behavioural change among retail investors”.
He concludes:
"The strong start to the year positions us well as we approach the busy tax year end period. We remain focused on the significant long-term growth opportunity that exists in the platform market. Our dual-channel approach and continued investments into our propositions and brand mean we are well-placed to continue our strong growth."
Graham’s view
With the shares down by 2% this morning, there’s a suggestion that this update may have slightly disappointed some investors.
As noted by Ken Mitchell in the comments and reported by Thomson Reuters:
The market may have been expecting a better performance in the Advised business in the mix given both IntegraFin and Quilter reported very strong net inflows over the same period earlier this month," said James Allen, a Panmure Liberum analyst.
Clearly the market has much higher standards for platforms such as this than it does for the active fund managers we cover. Platforms are still expected to generate inflows, and AJ Bell in particular is expected to do so, given its strong growth trajectory in recent years.
If I compare this quarter’s progress with the progress in the corresponding quarter last year, I get the following growth rates:
Advised platform: net flows for the quarter were 1.2% of starting AUA last year, vs. 0.5% of starting AUM this year.
D2C platform: net flows for the quarter were 3% of starting AUA last year, vs. 3.6% this year.
AJ Bell Investments: net flows were nearly 9% of starting AUM last year, vs. 6% this year.
I know that we shouldn’t read too much into quarterly movement, and that year-on-year progress is still excellent, but perhaps there are signs that things have slowed down a little, in terms of percentage growth?
But with the tax year-end approaching in a few months, I wouldn’t write off AJB having an excellent financial year. This is still a very decent Q1 update in my view.
The stock as usual is quite expensive at a PER of about 20x but it’s actually a little cheaper than it was when I reviewed this last, in October.
Given the company’s continued growth and (arguably!) a best-in-class offering that causes a headache for competitors, I’m willing to leave my GREEN stance unchanged.
Ceres Power Holdings (LON:CWR)
Up 2.5% to 143.1p (£277m) - Trading Update - Graham - AMBER
I don’t normally cover this one. Ceres is “a leading developer of clean energy technology”.
Clearly it’s still at an early stage of its development, with revenues rising but losses also looming large:

Highlights from today’s full-year update:
Order intake greater than £110m, two new manufacturing partners and an electrolyser partner.
Revenue at upper end of guidance (£55-60m), up by c. 150% vs. 2023.
Cost base reduced by c. 15% going forward.
Cash and short-term investments c. £102m at year end, in line with expectations.
The company is active in Taiwan, Japan, India and South Korea, and has partnerships with blue-chips such as Bosch and Shell.
CEO comment:
2024 was an exciting year for Ceres as we accelerated our commercial delivery with two new major manufacturing licensees and continue to establish Ceres as the industry standard through the adoption of our technology globally. Alongside our first electrolyser partnerships, we now see increased opportunities for our power technology resulting from the rising energy demand from AI data centres and the strain on power grids from increased electrification.
Graham’s view
I’m often quite negative on loss-making start-ups but the cash balance at Ceres is impressive - is there any chance they might be fully-funded to profitability, especially since they are earning a gross margin of up to 80% on revenues?
And they don’t seem to have diluted shareholders too much in recent years, despite the very large losses suffered:

Despite its large historic losses, I think a neutral stance is fair on this one.
WH Smith (LON:SMWH)
Up 8% to £12.82 (£1.7bn) - Trading Statement - Graham - AMBER/GREEN
I reported positively this week on SMWH's announcement that it was considering the sale of its High Street business.
The market loved that announcement and it's very happy again today, with a positive trading update.
Headlines:
Good start to the financial year with strong growth across all Travel divisions.
Acceleration in like-for-like revenue in North America
The statement covers the first 21 weeks of the financial year (an odd choice, but that's what they've done).
Revenues are up 4% at constant currencies, including 8% growth in the Travel division and a 6% reduction in the High Street division. Nothing surprising there - Travel is the long-term growth opportunity, while the High Street is battered by competition from all sides.
Within Travel, the "Rest of the World" segment (excluding the UK and North America) has the strongest revenue growth, up 9% like-for-like and up 16% in total, at constant currencies. North America and the UK also grew but at more modest rates.
The company is very focused on North America right now and announces various new stores in Orlando and Portland today. The North American pipeline now has c. 60 new stores.
In the High Street division, the focus is on cost savings (£11m of annual savings to be delivered this year) as the company decides its next steps for this division.
The CEO comment concludes:
"The Group is in a strong position, and while there is some economic uncertainty, we are confident of another year of good growth in 2025."
Graham's view
No reason at all to change my mildly positive view on this one. It has a truly high-quality retailing proposition in the Travel division, where I think it is somewhat insulated from competition. At the same time it has a High Street Division which will hopefully be sold and leave the company with a nice decision to make about the new balance sheet position it might achieve. So I think shareholders can be very pleased here.
Roland's Section
Van Elle Holdings (LON:VANL)
Down 1.3% to 38p (£41m) - Interim Results - Roland - GREEN
This construction group specialises in groundworks and has exposure to sectors including infrastructure, commercial property and housebuilding.
Van Elle’s unusual April year end means that we have interim results for the six months to 31 October today, rather than the trading updates being proffered by most companies at the moment.
Today’s numbers reflect a drop in activity compared to the prior year, but they don’t look disastrous to me and seem to suggest the outlook may be improving. Van Elle has left its full-year guidance unchanged today, albeit with a slight caveat:
Assuming continued strengthening of the Group's end markets, the Board remains confident in achieving market expectations for the full year.
Let’s take a look at some of the key items in today’s results.
Revenue down 4% to £65.2m
Pre-tax profit down 24% to £1.9m
Underlying EPS down 12.5% to 1.4p
Net cash (excl. leases): £3.1m (HY23: £8.9m)
Underlying ROCE: 9.1% (HY23: 10.0%)
It’s nice to see a company citing return on capital employed as a KPI. Too few businesses report this important metric, in my view. Even better, I am pleased to see that Van Elle’s figure broadly matches that shown on the StockReport. This suggests the company’s calculation is not too heavily adjusted.

Trading commentary: Van Elle’s activities are reasonably diversified across sectors. This seems to have provided some protection against weaker areas such as housebuilding.
Residential (H1 rev -4% to £28.1m): housing has been a weak area but the company says it’s “showing signs of recovery”. Housing-related orders received in H1 were 52% above HY24.
Infrastructure (H1 rev -9% to £26.2m): in rail, the company has seen a slow start to the new CP7 regulatory period with revenue below expectations. However, activity is increasing in H2, aided by ongoing TransPennine Express upgrades (much needed!).
In Highways, government spending has also been lower than expected.
In Water and Energy, the company is working to build larger market positions, aided by the recent acquisition of Albion Drilling. Today’s updates from United Utilities and Pennon highlight the additional regulatory spending planned in water over the next five years – I imagine there should be significant opportunities for Van Elle.
Regional construction (H1 rev +9% to £10.5m): this is mainly general commercial and industrial construction. The market is said to remain “very competitive” and “extremely price sensitive”.
Van Elle expects the London market to lead “a recovery in developer confidence”, although taller residential projects are being held back by the new Building Safety Act.
Industrial markets including data centres and warehousing are said to offer “significant opportunity”.
Outlook: Van Elle’s order book rose by 24% to £43.4m between April and December last year and the company says that both housebuilding and rail are expected to see increased activity this year.
Subject to recent improvements continuing, management expects to achieve results in line with market expectations, which the company cites as being for underlying pre-tax profit of £6.0m.
Checking Research Tree for updated broker notes finds three offerings today, from Dowgate, Zeus and Progressive - many thanks to all.
Zeus - FY25E earnings unch. at 4.1p per share
Progressive - FY25E earnings cut from 4.2p to 3.9p per share due to risk of further delays in residential
Dowgate (initiation note) - FY25E at 3.9p per share
So based on these three estimates, my sums suggest a FY25E consensus earnings estimate of 4.0p per share. That’s slightly below the 4.2p per share shown on the StockReport ahead of today.
That would put Van Elle on a forward P/E of 9.5, dropping to a P/E of 7 on unchanged FY26 forecasts.
Roland’s view
While the company appears to have a healthy and improving backlog of work, a number of projects have previously been delayed or are awaiting external approval to commence.
With the year end fast approaching on 30 April, my feeling is that there’s an appreciable risk some revenue could slip back into FY25. This might trigger a small miss to FY24 profit expectations.
I would be happy to be proved wrong. But my experience is that when companies say they will hit guidance if trading continues to improve, it doesn’t always happen.

However, while the exact timing of a recovery may be uncertain, I am fairly confident that a recovery is getting underway. In the meantime, I think the risk of a slight miss is probably already reflected in the share price.
Van Elle itself appears to have positive prospects, a sensible balance sheet and a reasonable valuation, so I’m going to stick my neck out slightly and maintain our previous GREEN view.
Dowlais (LON:DWL)
Up 11% to 76p (£1.0bn) - Recommended takeover offer - Roland - PINK (takeover)
So long, farewell. Automotive parts manufacturer Dowlais’s short spell as a standalone listed company may have reached its end after less than two years on the London market.
This FTSE 250 firm (formerly part of GKN and then subsequently Melrose Industries) has unveiled a £1.16bn takeover offer from a US peer, American Axle & Manufacturing Holdings (NYQ:AXL)
When I saw the takeover headline in the RNS at 7am, I assumed that American Axle was a larger rival, but this doesn’t seem to be the case – it’s actually much smaller and more heavily indebted, but with more highly rated shares. A familiar story for UK investors at the moment.
DWL | AXL | |
Market cap | £920m | £550m |
Net debt | £1.0bn | $2.1bn |
2025 f’cast P/E | 5.6 | 12.4 |
American Axle’s stronger valuation and high leverage may explain why today’s offer is part cash, part shares.
The deal would see Dowlais shareholders gain a 49% stake in American Axle, which is listed in New York and is part of the S&P 600 Small Cap Index.
Let’s take a look at the offer on the table for Dowlais shareholders, assuming the deal goes ahead.
The offer - for each Dowlais share, shareholders would receive:
42p in cash
0.0863 new American Axle shares
Up to 2.8p as a final cash dividend paid prior to completion
The offer is said to have a total implied value of 85.2p per Dowlais share, based on yesterday’s closing price of $5.82 for American Axle. This means it’s broadly 50/50 cash/shares.
However, this is only a 25% premium to yesterday’s closing price for Dowlais, and well below the level the shares were trading at 12 months ago.
Roland’s view
Investors are unimpressed by this proposal, judging from Dowlais’s share price reaction this morning. The stock is only up 10% to 75p, more than 10% below the supposed value of the offer.

If I was a Dowlais shareholder, I think I’d be disappointed too:
Based on 2025 consensus forecasts, DWL will contribute nearly 80% of FY25 profits to the combined group, but DWL shareholders will only own 49% of the combined business;
The offer only values DWL on a FY25 P/E of 7 and in my view does not offer a fair premium to reflect potential improvement in earnings in 2025 (and beyond);
AXL is smaller and more highly leveraged than DWL. The combined group is expected to have leverage of 2.5x EBITDA, versus 1.6x for DWL at H1 24;
AXL is a US-listed small cap, not an area many UK investors target. I imagine many UK fund managers will be unable to hold AXL shares.
The companies say that combining the two businesses will create $300m of cost savings, creating a business with more advantageous scale and a diversified customer base.
I don’t know much about the market outlook or detailed conditions within the automotive sector. Perhaps it’s possible that both companies are struggling with subscale operations and unbalanced customer bases. I don’t know.
However, my feeling is that unless conditions are getting much worse than previously expected, Dowlais shouldn’t be desperate for a deal. The company’s most recent trading statement (in November) was in line and did not appear to contain any nasty surprises – the shares have risen by 40% since it was published.
At first glance, it to me looks like American Axle may be in greater need of a deal and is hoping that it can leverage its more highly-rated shares to acquire some cheaper UK earnings.
If I was a shareholder, I would be planning to vote against this deal.
Hargreaves Services (LON:HSP)
Up 2% to 602p (£199m) - Interim Results - Roland - GREEN
Today’s half-year results from this infrastructure services and land development group provide the usual clear update on the (many) moving parts of this unusual group.
I’ve kept an eye on this business for a number of years and have always been impressed by its clear reporting. Today’s results do not seem to suggest any cause for concern:
the Board anticipating delivering full year results in line with market expectations.
H1 results summary: Hargreaves financial year ends in May, so today’s numbers cover the six months to 30 November 2024.
Revenue up 13.7% to £125.3m
Pre-tax profit up 96.3% to £5.3m
Earnings up 134.6% to 12.2p per share
Interim dividend up 2.8% to 18.5p
Net asset value up 2.3% to 580p per share
Services: Management say the company’s services division, which is predominantly earthmoving, had a strong H1. The company tends to be employed on large infrastructure projects – current examples include HS2 and Sizewell C, “where our competence and safety culture are highly valued”.
90% of Services revenue is secured for the full year. As a result of additional earthmoving work, management now expects Services revenue to be c.10% above expectations, leading to an improvement in divisional pre-tax profit.
Hargreaves Land: the sale of one 11-acre site at Blindwells (near Edinburgh) was completed for £9.3m. Unfortunately a further sale has been delayed due to site access problems. This shortfall will offset the outperformance expected in Services for FY25, leaving overall group performance in line with expectations.
An initial tranche of renewable energy assets have also been placed on the market (two wind farms and five access agreements). These have been valued at £12.6-£13.5m. The company is hopeful of completing a transaction in 2025.
HRMS: this is a German business active in metal recycling and coal trading. It returned to profitability in H1 and currently provides regular cash dividends to Hargreaves. The group’s financial exposure to HRMS fell from £70.2m to £62.7m during H1 as a result of cash received.
Outlook: FY25 results are expected to be in line with forecasts:
Despite the completion of a material sale at Blindwells, another planned sale is likely to be delayed until early in the next financial year due to a delay in securing technical approval for site access. This delay is expected to offset the anticipated gains in Services. As a result, the Board anticipates the Group will perform in line with market expectations for the full year.
Updated notes from brokers Cavendish and Singers leave FY25 forecasts unchanged today. However, analysts at both companies have upgraded their FY26 and FY27 profit estimates, citing improved expectations for Hargreaves’ Services business.
Comparing the brokers’ earnings estimates with the StockReport, my impression is:
FY25E: unchanged at 42.5p per share
FY26E: upgraded from 44.5p (StockReport) to an average of 51.5p per share
These changes suggest that Hargreaves’ forecast P/E could fall from 14x in FY25 to under 12x for FY26.
When paired with the stock’s 6% dividend yield, I think this could be quite reasonable value.The StockRanks are also very positive:

Roland’s view
A few years ago, Hargreaves shares were trading well below asset value, providing investors with a classic value play. While asset backing remains strong, that’s no longer the case. At just over 600p, the shares now trade at a small premium to their tangible book value of 580p.

Debt levels remain modest and underlying cash generation still looks strong to me, albeit somewhat lumpy. The 6% dividend yield looks well supported to me, at present.
The main risks I can see are that Hargreaves remains exposed to timing issues on large deals and to commodity prices and industrial activity (in Germany).
Although the shares have become a little more expensive since I covered them a year ago, I think the current price tag is probably justified by near-term expected performance.
I believe this is a well-run business with committed long-term management and a clear strategy to transition to a less capital-intensive business model. GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

87 comments
Reassured by results today from Hargreaves Services (LON:HSP) and PayPoint (LON:PAY). Hold both as a shareholder than following the crowd and investing on fundamentals.
I am bit late to the party today so I am reading a complete thread.
From a readability perspective it makes it difficult when a post is deleted as quite often there are many posts referring and connected to the deleted post.
Also the posts get very narrow on my screen as blue lines encroach onto the screen where sub-posts are plentiful.
Is there anything Stock can do to improve format and readability?
Use your phone in landscape mode to sort out the blue line problem.
Thank you - I use a laptop......
Huge amount of screen devoted to "Securities mentioned" with the important discussion squeezed into very small remaining space between blue lines.
As a workaround I play with the browser settings - but not ideal.
Saga (LON:SAGA)
I dont believe it (as victor would say)
https://news.sky.com/story/sag...
saga seem to manage to make a hash of everything they do - on the face of it decent terms refinacing to give them plenty of time should be complete game changer - lets see if finance company charge a huge wad to provide this finance.
#DWL #AXL
Hi Roland - I suspect one of the possible attractions of the #AXP deal to the Dowlais (LON:DWL) Board, was effectively being able to delist from the UK market - & instead trade on the NYSE under an existing company's quote, where valuations are much higher for similar auto-parts businesses.
I suspect one of the main attractions to the Dowlais (LON:DWL) board is probably bonus payment in the event of change of control!
I'll be voting against and encourage others to do the same. This deal is trying to get the company on the cheap - after all it was de-merged from Melrose at 120p. The Board own 0.3% of the company - not sure the % in public hands but let's hope majority of private investors and some enlightened institutions vote against, failing to achieve the 75% of votes required....
I agree totally with Roland on Dowlais. Stay independent, keep buying your shares back and paying us a generous dividend .
I can't help but think that yesterday's 10% spike at Renold (LON:RNO) may have been the result of a read across of careless whispers on the Dowlais (LON:DWL) bid.
I an still having the 404 error message when searching for individual stocks. Would be useful when you know there is an issue to post something on the TODAY page to keep customers informed of an issue.
Angle (LON:AGL) I hold
Some brief extracts from today’s RNS which has caused daily trading volume to increase by 8 fold as of midday.
“ANGLE plc ………………… announce new, successful results for the Company's dual circulating tumour DNA (ctDNA) and CTC-DNA workflow using, for the first time, an end-to-end Illumina solution for analysis.
There were also mutations identified in ctDNA alone that were not found in CTCs. This evidence confirms the importance of including CTC-DNA analysis alongside ctDNA so that clinically relevant cancer mutations are not missed. Analysing both analytes found twice as many mutations, which could be used as potential biomarkers to guide treatment.
As a result of these positive findings and their importance to both companies, Illumina has assigned their entire European Association for Cancer Research (EACR) webinar to ANGLE's findings. They will present ANGLE's results on 6 February 2025 at 16:00 GMT.
Illumina is the world's largest provider of NGS systems and assays and has built an installed base of more than 23,000 sequencing systems across more than 9,500 customers in 155 countries.”
https://www.stockopedia.com/sh...
Why is the Nasdaq Composite Index figure quoted on the home page always a day out of date, unlike the other indices which are 15 minutes delayed up to date? For example, this led to a wholly misleading situation yesterday. The home page all day was stating that the Nasdaq Composite Index was down 3% whilst, in fact, it was up 2%.
Any news on when the '404 error' will be resolved when trying to access individual stocks?
it's all working for me now sparkler?
Arrow Exploration (LON:AXL) is wrongly being flagged as taking over Dowlais
Apologies, I've fixed that AXL issue.
Hi Graham. I think some mention should be made where when Buybacks are referenced, in analysing results, as to whether the shares are cancelled and/or put into Treasury/ Employee Benefit Trusts etc. Shares in Treasury /Trusts are treated as still being in issue and don’t immediately affect p/e’s etc.
These mechanisms may be used for Employee remuneration or for cash/share acquisition offers. So the value proposition for existing shareholders can be different than it looks on first review.
Thanks
Trident, fair point. For future reference, if I'm talking about a buyback my default assumption is that the purpose of the the buyback is to return cash to shareholders / reduce the share count.
In the case of PayPoint, as per the 1st July 2024 announcement:
The sole purpose of the Programme is to reduce the share capital of PayPoint and therefore the Ordinary Shares purchased under the Programme will be cancelled.
Also, I should point out that P/Es are based on shares outstanding, not shares in issue. So if a share has been repurchased and is held in Treasury rather than cancelled, it has still reduced the P/E.
HUGE Point well made Graham re PayPoint or any other Buyback program, I'm sure many are unaware of but really ought to be !
Not only DYOR - But beware of the salient facts!
The sole purpose of the Programme is to reduce the share capital of PayPoint and therefore the Ordinary Shares purchased under the Programme will be cancelled.
Also, I should point out that P/Es are based on shares outstanding, not shares in issue. So if a share has been repurchased and is held in Treasury rather than cancelled, it has still reduced the P/E.
Yes but these can be brought out of the treasury at any time, maybe to award to directors or staff, then the P/E will increase. This is an issue with certain stocks, l think Renold (LON:RNO) is one.
Exactly the point - you need to know the number held in treasury just as Graham said. I don't invest in companies that spend profits buying back, to then gift to the Executive team that voted for the buyback! Personal stance on skin in the game level playing field etc
Based on today's announcements revenue and profit growth for hVIVO (LON:HVO)'s challenge model business seems to have dried up and gone into reverse. It's now clearly investing in adjacent sectors and markets to maintain growth momentum.
To revitalise the share price hVIVO (LON:HVO) needs to be more transparent about market demand and provide a vision of how it sees each of its business streams contributing to its evolving strategy objectives. Today's analyst investor meetings would be good place to start.
Based on today's announcements revenue and profit growth for hVIVO(LON:HVO)'s challenge model business seems to have dried up and gone into reverse.
No. There is a global slump in CRO work that has affected all players. It has nothing to do with the challenge model.
It's now clearly investing in adjacent sectors and markets to maintain growth momentum.
Certainly Germany is a different market but therapies have global reach so I don’t see how this is a bad thing or wildly divergent. As for adjacent sectors, the target is an in-patient/in-human trial platform. How is that beyond HVO’s circle competence?
The fact is shareholders simply need to be patient and wait for the CRO market to mean revert. Anyone waiting for the upturn may find they can use the funds better in the meantime. Or may miss the takeout at £0.35 - £0.42. It’s their choice.
The numbers clearly show revenue and profit growth have reversed in what was their core business.
I've not said anything about hVIVO (LON:HVO)'s circle of competence or the adjacent markets being widely divergent....the markets appear to be adjacent, but requiring investment if they are to successfully address the decline in growth and turn around a loss making acquisition. An important change and challenge which shouldn't be dismissed off hand.
Management could have been much more transparent about the challenges they face.
Like all investments, I think it's important to discuss both the downside and upside risks.
Completely agree. I was just giving the other side of the argument. Neither of us can know for sure!
If someone wants to post and comment that the most successful investment strategy of the last two decades i.e. passive investing, is wrong and regarding it as a pyramid and a failure then I HAVE the right to comment ams express my opinion and views.
Deleting honest posts based on facts and figures is an insult to your community and your subscribers.
Your subscribers have the right to read all posts and make their own judgements.
I repeat calling the whole US ETF instrument a pyramid is misleading.
All the best
To the moderator that has deled my post :
Free speech is precious especially if it’s backed by real life facts.
It is an insult to delete my posts just because I do not agree with the statement and the misleading information of a certain commentator.
ETF’s have and will be the driving force behind the US stock market and economy in general. Also the crypto has no correlation with the stock market’s performance. We have seen many BTC corrections where the stock market was making new highs and vice versa.
Calling the whole market a PYRAMID ETF the. NVIDIA (NSQ:NVDA) the ‘deep fried Nvidia!’ when at the same time Amazon.com (NSQ:AMZN) was making NEW HIGHS is totally misleading. If that was the case the whole market was going to crash on Monday.
We all have a different way of investing but passive investing has proven to be a very profitable and effective strategy to make yourself rich!
Feel free to delete my post again.
All the best
Yiannos, I read your comment this morning and I thought there was plenty of merit in what you said, it was perfectly reasonable, equally there is merit in what Paul says, so to the moderator why can't we have two different opinions on the board? (especially from two respected posters)
There was no malice in the wording, and we are all adults here, I am a little taken aback and confused by this latest censoring....
Paul can have his opinion and I can have mine and so is everyone else. I felt calling passive investing and the ETF instruments a pyramid is misleading to the readers as this is certainly not the case!
I thought the days of the other Paul have gone where everyone was attacked for not agreeing with him
I thought everyone can post and comment as they feel and hopefully the whole community will benefit from different opinions.
I hoped that the culture has changed but unfortunately this is not the case.
Not to be waisting my precious time here anymore.
All the best
Please do not leave yiannos1. I find your comments both interesting and valuable.
I find these days X a better platform of expressing my honest opinions.
All the best
Perhaps whoever deleted the post could explain their rationale, especially given that recently there has been less engagement on the discussion boards. FWIW I get more value, personally, from the discussion boards than the analysis - and I'm wondering what I'm paying for when more and more contributors are leaving...
Hi Viz,
To be honest it’s the person that has flagged my post that should explain to all of us why he has done it (if he is brave enough!).
All the best
Yiannos,
Sorry about any misunderstanding. I've spoken with the team here and learned that multiple users flagged your post for moderation. The moderator decided to moderate it because of the tone of the comment - basically, it was seen as being rude. This is just to clarify what happened for you.
All the best
Graham
I for one would be very disappointed and saddened if Yiannos1 were to stop posting as a result of this moderation. It is clear he has a lot of support looking at the thumbs up for his posts. The discussion boards with differing opinions are sometimes more useful than the stock analysis, and I personally find his posts very informative
AB
I understand he has received a suspension. If true, totally uncalled for :(
I rarely get involved in these tiresome spats, but struggle to see why this individual gets so much support. His tone is consistently obnoxious and while he does appear relatively knowledgeable, I feel this forum would be a much more pleasant place without him. I'm pretty sure he was a factor in Paul Scott leaving too.
Is there a block poster function on stocko? Those that find him rude could then use this function, and leave the rest of us to still read his posts?
Unfortunately you'd still have the tiresome back and forth responses from the other members he's picked a fight with - unless you block all those too!
There could be a 'Leave the Conversation/thread' function made available to cover such scenarios.
Everyone is entitled to their opinion. But would you prefer a 'more pleasant' place where people just post platitudes, or a proper discussion place where challenges are made and often can be proved correct?
I know he isn't everyone's cup of tea, but surely we need people like Yiannos to avoid people drifting into echo chambers where actually, aren't making profits and not seeing an alternative, factual view?
Aren't we big enough to disagree with others without having to censor views?
I think it should be standard practice that, if any post or comment is deleted by a moderator, the author should be given an explanation as to why it has been deleted.
Yes, l quite agree. Some of mine were deleted last year, no explanation was given and could not see any reason for it, apart from maybe replying to some posts that also were also moderated.
I did not see anything wrong with it. Deleting posts is a sure way of getting rid of members, probably not a good idea, seeing that many have left recently.
Maybe the dumb money is not so dumb, better than investing in Pfizer (NYQ:PFE). That is what Warren Buffett has been being saying for years, invest in a S&P500 tracker.
Rusty2
Exactly what I was trying to say!
And then you have to use your logic and ask yourself why someone that has UK small cap companies as clients wants to post and make a statement that was totally misleading. He can post of course what he likes, but I have the right as well to doubt it and explain my honest thoughts as I always do.
All the best
Interesting to see Rockwood adding to Trifast (LON:TRI) again yesterday with a couple of purchases adding around £200k following similar buys in November and December last year. Looks like they're building up their position which perhaps bodes well for a decent exit in a year or two.
I’m getting 404 error messages as well - unable to look at any stock page
All the links are broken on this page. I get error 404 message on everylink. Also on React (LON:REAT) stockrank page. On my folios it is the same issue.
OK seems to be working again now.
Actually not only the links on this page. If I go to the homepage and search for any stock I get a 404 error
Looks like it is Amazon cloud, lots of reported outages.
This is still happening on numerous stocks.
Still playing up on some stocks.
Be great if you have time to give a view on FDM (Holdings) (LON:FDM) Graham Stocko predicting future profits of 20 mil, north of 7% divi (covered just) has net cash, but despite what the press would have you believe about companies crying out for people in IT from people I know working in the industry its by all counts a tough time to get work.
AJ Bell (LON:AJB) (I hold). As todays summary spreadsheet states:
Record AUA up 3% to £89.5bn in Q1. Customer numbers +4% in qtr. Outlook positive.
Reviewing the TU appears to be lots of materially positive numbers on customer numbers and AUA vs. prior year. As the share price is down nearly 4% this morning the market was clearly expecting more. Perhaps there is a concern over slowing growth in the 4Q. Be interested in a more detailed review by the DSMR team.
Here’s the likely reason for AJ Bell (LON:AJB) small share price fall
** "The market may have been expecting a better performance in the Advised business in the mix given both IntegraFin and Quilter reported very strong net inflows over the same period earlier this month," said James Allen, a Panmure Liberum analyst”
Also note Stockopedia 22“value” score. The otherwise good news and progress priced in?
AJ Bell (LON:AJB) (I hold). As todays summary spreadsheet states:
Record AUA up 3% to £89.5bn in Q1. Customer numbers +4% in qtr. Outlook positive.
Reviewing the TU appears to be lots of materially positive numbers on customer numbers and AUA vs. prior year. As the share price is down nearly 4% this morning the market was clearly expecting more. Perhaps there is a concern over slowing growth in the 4Q. Be interested in a more detailed review by the DSMR team.
I am surprised by the fall in the Litigation Capital Management (LON:LIT) share price today given that the loss in the Queensland electricity users case had been previously announced and today’s results show a 370% return on cost on the cases realised in the period. Overall I am interpreting this as a good result- what am I missing?
All I would say is that the profits these litigation companies actually generate is a lot lower than the spectacular case returns they like to highlight - once all their costs are factored in the return on equity is actually quite modest (not to mention highly volatile and unpredictable)
The explosion (see below) of cheap trackers (US ETFs now worth $10.4 trillion in AUM) seems to be the main reason why the 'Mag 10' stocks account for 40% of the #SP500's mrkcap vs 18% ten years ago.
The problem being that this 'dumb money' lacks price discovery. Buying more of things when they go up, whilst equally dumping stuff when prices fall. The exact opposite of what canny investors should do.
Indeed this passive investment strategy relies 100% on the theory of 'efficient markets'. Yet as every 'grey haired' investor knows, share prices can be wildly irrational.
Worse still, if there is a major market dislocation sometime - such as when Nvidia got 'deep fried by Deepseek' on Monday. Then this ETF 'pyramid' scheme could come crashing down - especially if say there was ever a Crypto blowup .
Instead for me, I try to stay active - purchasing individual stocks on the basis of their fundamentals, not momentum.
Ah but Paul,
Buying more of things when they go up, whilst equally dumping stuff when prices fall.
But isn't this what I'm trying to do now as a PI, and if I'd done this all along I'd be a very rich man now.
Yes SM, if you're purely a momentum based trader.
Personally I'm nowhere near clever enough to predict short term price movements
No point buying into a downtrend though - may as well let it revert or at least rebase first,
So true and quite scary - I recall an incredible interview on a Grant Williams podcast back in 2020 with Mike Green (then at Logica Advisors) who was raising the alarm about the terrifying potential of passives as they grow and crowd out active trades. It's a long time since I listened to it but IIRC, his modelling concluded that the lack of price discovery caused by a dominant passive environment could cause such immense market volatility that in extremis it would be possible for the market to fall practically to zero due to the weight of passive selling!
Of course when AI is in charge it will be impossible for anyone to ever lose money.
Nothing could possibly go wrong.
Would welcome coverage on Van Elle Holdings (LON:VANL)
VANL is getting posted up now, ben! Thanks for the comment.
Dowlais (LON:DWL) recommended cash/share offer at 85.2 - I was noting the chart recently seemed to have perked up and was looking bowly. Whilst it has been recommended, it is still too cheap :(
Wondering why Dowlais (LON:DWL) has only increased by less than 10% this morning - to 75p Just looked up AXL NY and frankly not impressed which perhaps explains
Hi bohenie,
I'm just taking a look at the American Axle & Manufacturing Holdings (NYQ:AXL) / Dowlais (LON:DWL) offer now.
Roland
RE Dowlais (LON:DWL), the offer also includes positions for the Dowlais directors on the board of American Axle & Manufacturing Holdings (NYQ:AXL). Perhaps with US sized salaries.
American Axle & Manufacturing Holdings (NYQ:AXL) is only £550m mcap according to Stocko.
Thanks Rowland - but what are the chances of shareholders voting this down - Inst shareholders just 33% according to the list. I'll hang on for now but frankly tempted to take the money now rather than hang around for months. At least there's now a few more pence in the Mkt SP
hVIVO (LON:HVO) bizarre reporting strategy this morning, first they drop a short TU and a bit later a second briefing covering acquisition and outlook. Way more detail in the second one that's relevant. Am still hurting from adding in Nov24 at 26p so hope the market likes this new plan for growth. Hope it makes the list on here too !
Hvivo (HVO)
It's a profit warning disguised by the acquisition. I've taken my profits and I'm out!
Mo is overly promotional and inevitable that it would come back to bite him at some point.
Agreed about Mo. I prefer my managers to be good professional managers of the business. Some come across like snake oil salesmen, pushing their company like it is a product to sell rather than a company to manage
hVIVO (LON:HVO) - It is so annoying that the details of the acquisition makes no mention of the profitability of the German company and what economies of scale if any that it would add to Hvivo.
They need to up their reporting game if they want confidence of the likes of retail investors.
Not at all surprising that the SP has dropped 3% this morning but in for the long term.
The Mannheim and Kiel units recorded unaudited revenues of €19.9 million in the financial year ended 31 December 2024 (€18.6 million in 2023), with an adjusted EBITDA loss of €1.8 million (€1.6 million in 2023).
Thanks Kouremenous. Scanned the summary and not the detail. Mad rush today!
Does anyone know what caused the large jump in Renold (LON:RNO) yesterday? I can't seem to see any news on it
Can’t find a concrete reason why PocketMoney. Renold (LON:RNO) the stock price has been in the bouncing around the 47-50 for sometime now. I unfortunately got stung with this one after a 50% gain. I seem to recall something shady move from the directors which of course was not well received. I sold out but have keep this one on a watchlist.
Microlise (LON:SAAS) Singer Capital Markets:
Microlise has released a y/e update, which provides several reassuring data points that highlight quality and resilience of the business.
Recurring revenue, EBITDA and cash are all comfortably ahead while forward looking indicators also look good.
ARR grew +9% organic to £56.6m and the pipeline is bigger than before the cyber security incident.
Microlise has navigated this challenging period far better than feared and trading on 1x fwd. EV/Sales, 7.5x EBITDA or a 6% historic FCF yield, the shares offer exceptionally good value. A 2025 ‘best idea’.
PayPoint (LON:PAY) Comprehensive update and quite positive IMO. Are you up for the task of analysing this one Graham? I hold.
Morning revs, it's one of my favourite stocks - and on my watchlist - so I'll be keen to cover it! G