Daily Stock Market Report (Wed 5th November 2025) - TCAP, VANQ, TRN, CWR, MKS, MNG, JDW, HEAD, VEL

Good morning!
With so much US news this week, I've tried watching CNBC's "Closing Bell" in the evenings. But the problem with CNBC is that it's far too exciting - it gets my adrenaline going more than a scary movie! So I'm ending this experiment already. Long live newspapers!
All done for today, thanks.
Spreadsheet accompanying this report: link (last updated to: 31st October).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
Coca-Cola Europacific Partners (LON:CCEP) (£30.3bn | SR58) | Q3 rev +1.0%, YTD +3.3%, with volumes up 3.7% YTD. Full-year guidance unchanged. | ||
Marks and Spencer (LON:MKS) (£7.9bn | SR82) | H1 adj PBT -55% to £184m, due to cyber incident. H2 profit to be “at least in line with last year”. Consumer environment remains uncertain. | AMBER (Roland) I am impressed by the way M&S has handled its recovery from April’s cyber attack, but slightly disappointed that the “residual effects” are still ongoing and seemingly affecting trading results. I also note that the company’s house broker has cut its underlying forecasts for the current year, excluding the benefit of an impressively-prompt £100m insurance payout. While I am broadly positive about the medium-term outlook, I think the shares are probably fairly valued ahead of the key festive period, so I’m staying neutral a little longer. | |
Weir (LON:WEIR) (£7.5bn | SR77) | Rev +2%, with growing demand from copper, gold & iron ore. FY25 guidance reiterated; growth in constant currency revenue and op profit, with op margin c.20%. | ||
M&G (LON:MNG) (£6.5bn | SR57) | AUMA up 2.8% to £365bn vs Q2, Q3 new business net inflows of £1.8bn. Positive outlook. | AMBER/GREEN (Graham) M&G has tended to trade very cheaply since its demerger from Prudential, but in more recent times this has corrected. It still offers value at this level in my view: it doesn't suffer from the same problems as the smaller fund managers in this report, although it does have a few different ones, including a Life division that is probably in long-term decline. But I don't think anyone can deny that this is a highly credible organisation, and I view this as a blue-chip stock. | |
Barratt Redrow (LON:BTRW) (£5.3bn | SR41) | Reservation rate 0.57 (FY25: 0.59), due to lack of bulk sales. Order book at 26 Oct: 10,669 (Oct 24: 10,706). 60% forward sold for FY26, FY guidance unchanged, subject to Budget. | ||
Drax (LON:DRX) (£2.4bn | SR90) | Signed CfD contract with govt for operation of Drax from April ‘27-March ‘31. Strike price £109.90MWh on all four biomass units. Adj EBITDA exps unch. | ||
TP Icap (LON:TCAP) (£1.95bn | SR94) | Q3 rev +3% (CCY), with Global Broking +7% but Energy & Commodities -7%. “Remains comfortable” with market exps for FY25 adj EBIT. | AMBER/GREEN (Roland - I hold) [no section below] Today’s update from this FTSE 250 interdealer broker is in line, but doesn’t sound overly confident to me. The good news is that profit guidance is unchanged and the company’s core Global Broking business continues to trade well. TP ICAP is a market leader in this business, which generated 70% of profit in H1. However, revenue in the second-largest division, E&C, fell, as it did in H1. Instead of blaming market conditions, management says this drop is due to “competition for broking talent”. This issue has been flagged in every update this year, making me wonder whether some of the company’s top performers may have jumped ship following very strong results (and presumably big paydays) in 2023/24. Today the company says it has a “strong hiring pipeline” that’s expected to deliver results from 2026. We will see. I’m also a little frustrated by the seemingly slow progress with the company’s high-margin data business, Parameta Solutions. Parameta’s revenue growth seems slightly humdrum to me, at 5%, while a planned IPO in the US remains on ice while management “assess the appropriate timing”. I’ve been a fan of this business over the last couple of years, thanks to its low rating, high yield and improving profitability. The stock is also currently the longest-serving position in my SIF portfolio (since March ‘24). However, a falling MomentumRank means it’s getting increasingly close to a sale under my rules. To reflect this concern, I’m going to moderate my view by one notch today. | |
Lancashire Holdings (LON:LRE) (£1.55bn | SR80) | “Strong” Q3 with disciplined growth. GWP +7.4% to $1.8bn and investment return 5.6%. Renewal price index of 96%. Special dividend of 75c/share. | ||
Princes (LON:PRN) (Approx. £1.2bn | SR n/a) - New Listing | This food group begins trading today. The offer price was 475p, giving a market cap of £1,162m. | ||
Trainline (LON:TRN) (£1.04bn | SR65) | Ticket sales +8%, revenue +2% to £235m. Op profit +38% to £68m. FY26 adj EBITDA guidance upgraded to +10-13% (prev. +6-9%). | AMBER/GREEN (Roland) [no section below] Graham and I have both been AMBER/GREEN on this rail ticket aggregator over the last few months. The shares have fallen heavily this year, but trading continues to improve and is now demonstrating the strong profitability I’d hope to see from a business of this kind, with an H1 operating margin of 29% and 42% return on equity. Such strong metrics seem at odds with a forward P/E of 12, but I think there are a couple of risks that prevent me going fully GREEN here. Around half the group’s profits come from its UK Consumer division, which helps travellers navigate the insane complexity of UK rail ticketing. It’s a great service, in my view, but it is exposed to regulatory risk and the potential for new competition from other ticketing systems. Both risks are in evidence this year. In April, the commission rate earned by Trainline on UK ticket sales was cut by 0.5%. In today’s results, the company notes that the expansion of TfL’s Project Oval contactless payment network is putting £150m of UK consumer ticket sales at risk [of being lost to Trainline]. Trainline is developing its own PAYG system, while the group’s expanding operations in Europe and its B2B division should help to dilute exposure to UK consumer ticketing. Even so, I think it’s fair to apply some discount for the unknown risk of future disruption. For this reason, I’ve left my view unchanged at AMBER/GREEN today. | |
Metro Bank Holdings (LON:MTRO) (£734m | SR54) | Reaffirming all guidance for FY25 and beyond. 12% lending growth vs H1, exit net interest margin of 3.03%. 9% reduction in run-off lending, freeing up capital. | ||
J D Wetherspoon (LON:JDW) (£725m | SR38) | LFL sales +3.7% in 14 weeks to 2 Nov, with total sales +4.2% YTD. Outperforming the wider sector. Outlook “slightly more cautious” ahead of Budget. | BLACK (AMBER) Graham) [no section below] JDW's share price is unchanged today but I think the market has been pricing in the obvious: that taxes and consumer sentiment are not providing a very healthy backdrop to trading for JDW, and that the upcoming Budget includes some risks. The shares are down 10%+ since August. In typical Tim Martin fashion, today's new guidance is not quantified in this announcement and investors are left to interpret the meaning of "slightly more cautious". But it's clear that the company is acting cautiously, with only 15 pub openings planned for the current year (an unchanged plan from that which was published in the most recent full-year report). At least like-for-sale sales growth of 3.7% in the Q1 period means that sales growth is keeping up with inflation, although I'm not sure that like-for-like costs can avoid rising faster than inflation. Certainly the company is doing a very good job of managing costs for now; earnings estimates in the market suggest that profits in the current financial year (FY July 2026) will match the prior year, which I would view as a minor miracle given the tax rises at work. I've been neutral on this stock and I'm happy to leave that stance unchanged today: I do view it as very well-managed and well-capitalised, and I would be glad to upgrade my stance when it's more clear that the company can maintain profits despite the ongoing - and forthcoming - changes to the tax code. | |
Ceres Power Holdings (LON:CWR) (£608m | SR22) | Agreement for production of Ceres' proprietary solid oxide fuel cell technology with Weichai, a global OEM/power systems developer in Shandong, China. | AMBER/RED (Roland) [no section below] This new agreement with Weichai is said to supersede “existing agreements with Weichai”. Checking previous years’ results, it seems Ceres was previously working with Weichai to develop stationary power units “based on the Ceres technology”. If I have understood correctly, today’s licensing deal means Weichai is ready to move from product development to production, becoming the fourth licensing partner to use Ceres technology in its product range. This certainly seems like good news. Unfortunately there is no guidance today on the expected revenue impact of this agreement, other than a mention that licence fees are not likely to be recognised until FY26 – so FY25 revenue expectations presumably remain unchanged. Ceres has been a jam tomorrow stock for as long as I can remember and has not turned a profit since its IPO in 2004. The question now is when – or if – this might change. CEO Phil Caldwell is targeting a 20% reduction in operating expenses for 2026. Based on H1 25, that could imply operating costs of £55-60m in 2026. With revenue forecast at £57m, the result may be close to breakeven – although broker forecasts suggest a net loss of c.£12m next year. I can see the bull case here for the business, but I’m not convinced the current valuation is attractive; Ceres is currently trading on 13x FY26 forecast sales. The share price simply looks ahead of events to me, something that’s also reflected in the stock’s Momentum Trap styling. | |
Conduit Holdings (LON:CRE) (£538m | SR30) | Growth in gross premiums written of 8.5%. Strong investment return of 5.4%. Outlook: market conditions remain adequate although some rate softening has occurred and is expected to continue. | ||
Bluefield Solar Income Fund (LON:BSIF) (£428m | SR39) | Persistent discount to NAV for over three years. Following engagement with shareholders, starts a Formal Sale Process. The board remains open to all options. | PINK | |
Vanquis Banking (LON:VANQ) (£292m | SR86) | Customer balances +18% y/y and full-year guidance increases. Net receivables +21%. NIM guidance reduces to >16.5% (previously >17%). Other guidance unchanged. Limited liability to motor finance: £3m provision. | AMBER/GREEN (Graham) [no section below] I turned AMBER/GREEN on this in August when we had a stabilising update at the company’s interim results: it had previously given a downgrade to its medium-term forecasts back in March. Today’s update reads well to me: strong growth in customer balances and in receivables, and it remains on track for “low single-digit ROTE” this year. There are perhaps two small negatives. The first is the reduction in net interest margin (NIM) guidance, although this is well explained by the company targeting growth in low-margin Second charge Mortgages. While the margin will be lower than previously forecast, the actual net interest income result will be in line. The second slight negative is the £3m provision for motor finance redress, with a warning that an additional £4m liability could arise. I previously thought that Vanquis might not have to pay any compensation under this redress scheme, as it didn’t pay discretionary commissions linked to interest rates. However, it turns out that 2% of motor finance commissions paid by Moneybarn have been above 35% of the total cost of credit and 10% of the loan amount. Still, these are small numbers compared to the overall size of the Vanquis group. Overall, I remain comfortable with my moderately positive stance here: the shares offer a discount to tangible book, a bank that is earning low but positive ROTE, and the potential for this to improve as it both scales up and delivers its planned cost savings. The CET1 capital ratio may have reduced to 17.4%, but this would generally be considered extremely safe in the banking industry. | |
Redcentric (LON:RCN) (£191m | SR65) | Managed Services Provider H1 revenue reduces to £67m, in line with management expectations. Adj. EBITDA improves to £9.1m, modestly above management expectations. | ||
Kitwave (LON:KITW) (£173m | SR50) | H1 trading has been as anticipated; the Board expects profits to be in line with market expectations for FY Oct 2025. CFO will retire, be succeeded by KITW’s Financial Controller. | ||
Braemar (LON:BMS) (£76m | SR75) | FY26 board expectations unchanged, with H2 market conditions improving. H1 revenue down 16%, underlying operating profit down 30%. | ||
Headlam (LON:HEAD) (£46m | SR27) | SP -12% Challenging market dynamics and execution. Revenue down 5%. The Board expects full year performance to be below expectations. Comprehensive programme of restructuring, cost reduction and operational improvements. Potential property disposals to boost the company's financial position. | BLACK (RED) (Graham) [no section below] We were AMBER/RED on this as recently as October, and our concern is justified by a serious profit warning today. In hindsight, it was not a great sign to see the CEO leave his position with immediate effect and with little ceremony. I'd have zero desire to go bottom-fishing here, as floor coverings is one of the most difficult sectors in my experience. There's an old Carpetright near me, frozen in time since it went into administration in July 2024, to remind me of that! Headlam is operating without a permanent CEO at the moment, instead being run by its Chairman. It's also carrying a net debt position of £24m although against that it says that its property portfolio is worth £94m (2023 valuations). So maybe there's some hidden value? If property disposals can reduce debt as planned then solvency will not be a problem and I'll be able to get this off RED reasonably soon. But for now only a purely negative stance makes sense. Even before today's warning, the company was not forecast to make any real profits for the next several years. | |
Water Intelligence (LON:WATR) (£45m | SR77) | The Group continues to be in-line with expectations for 2025 and is increasingly confident about expectations for 2026. 9-month revenue +9.2%, EBITDA +14% ($12.7m). | ||
Corero Network Security (LON:CNS) (£45m | SR11) | Management reaffirms guidance for 2025 of revenue $24.0 - $25.5m (FY 2024: $24.6m) and EBITDA $1.5m loss - $0m (FY 2024: $2.5m profit). | ||
OPG Power Ventures (LON:OPG) (£22m | SR93) | Buyback offer - similar to tender offer - at 6.27p (latest price: 5.45p). Proposes cancellation of AIM listing. | PINK GN note: Major shareholder owns 51.5%. | |
Tpximpact Holdings (LON:TPX) (£13m | SR60) | “Confident in achieving the full-year guidance previously provided for Adjusted EBITDA of £6-7m” (sic). | ||
| Velocity Composites (LON:VEL) (£12m | SR54) | Trading Update | SP -17% FY25 and FY26 revenue will be lower than current market expectations, though adjusted EBITDA for both years is expected to show improvement on prior years. New estimates from Canaccord Genuity: FY October 2025 revenue £20.7m (previously £23m), FY 2026 revenue £20m (previously £26.6m). FY October 2025 adjusted pre-tax loss £0.9m (previously £0.7m loss), FY 2026 adjusted pre-tax loss £0.6m (previously £0.3m profit). | BLACK (AMBER/RED) (Graham) [no section below] The last time we looked at this was when it issued a revenue warning in May, and Mark commented at the time that it was a big miss. Today we have another very large revenue miss including over £2m that has disappeared from FY October 2025 - the financial year that ended a week ago - and a major cut to the FY 2026 forecast. Real profits remain beyond the foreseeable future, and this is a company that hasn't made a profit in the last decade. As a supplier to aerospace manufacturers, it appears to lack both revenue visibility and negotiating power, given the ease with which customers can apparently move to facilities that don't use VEL's composite kits. The net cash position has reduced to zero and I may need to turn fully negative on this before too long, if the trend of poor trading continues. |
Graham's Section
M&G (LON:MNG)
Up 1% at 272.4p0.9p (£6.5bn) - Graham - AMBER/GREEN
Significantly larger than most fund managers we cover, M&G is an enormous asset manager that includes a wide range of mutual funds and institutional mandates.
Let’s try to understand today’s Q3 update. Here are the key points:
AUMA up 3% in the quarter to £365 billion
£1.5 billion of net inflows from external clients in the Asset Management division.
£2.0 billion of net outflows in the Life division (this is in the table, not in the headlines!).
Both divisions saw their AUMA increase during the quarter. But long-term, the Life division might not be terribly exciting, as it includes many old funds that will be wound up sooner or later.
In Asset Management, there is a nice little tailwind on the way:
Momentum expected to continue in coming months, as we begin to generate new business flows through our partnership with Dai-ichi Life.
Dai-Ichi is the third largest life insurer in Japan. The two companies announced their strategic partnership back in May, with M&G becoming Dai-ichi’s preferred asset manager in Europe, but there are many other aspects to their planned cooperation.
$5 billion of new business is expected over five years - that may not be very large in the context of M&G’s entire business, but the two companies working together will enjoy the benefits of international scale.
Graham’s view
M&G is such a large (and quite complex) organisation that I almost need to treat it like I do the High Street banks: I accept that I’m never going to understand every facet of them, but I try to take a big-picture view when I can.
Ultimately I treat M&G the same way I treat Aberdeen (LON:ABDN), which is to say that I put it in a separate category to the smaller fund managers we cover in this report. They both take care of very large institutional mandates - from sovereign wealth funds, pension funds, charities, etc. - that to some degree separate them from the ebb and flow of retail investor sentiment.
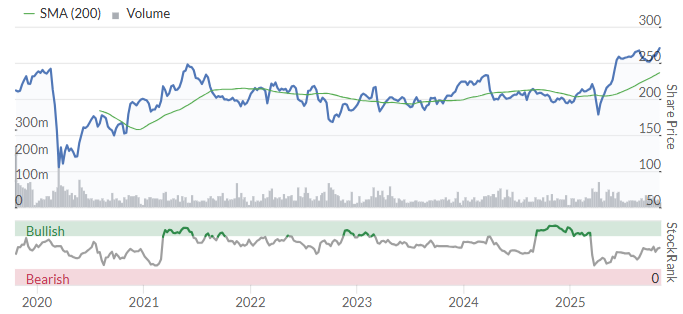
Since its demerged from Prudential and IPO’d, it has tended to trade very cheaply, although in more recent times this has corrected:
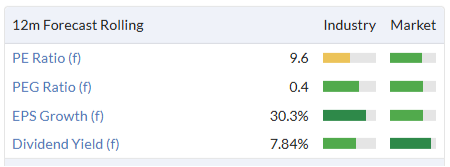
It does still appear to offer value at this level:
I wouldn’t mind owning some M&G shares at this level and so GREEN is a plausible stance for me, but I note that Roland was merely AMBER in September. So I’ll be a little bit cautious and hike our stance by only one notch, to AMBER/GREEN.
Roland's Section
Marks and Spencer (LON:MKS)
Up 1% to 389p (£8.0bn) - Interim Results - Roland - AMBER
When I covered Marks & Spencer’s full-year results in May, the company was still in the throes of dealing with the aftermath of a major cyber attack. While the FY25 results were pretty strong, the company was expecting a £300m hit to profit from the attack and the timetable for a return to normal was still unclear.
At the time, I said:
I think there’s the potential for a sluggish return to normal customer behaviour and perhaps some extra costs. I’m staying neutral for now, but would hope to turn positive again later this year.
The cyber attack is now over and operations are (nearly) back to normal – so today’s half-year results provide us with a good opportunity to revisit this business. M&S was on a positive trend prior to the attack – can CEO Stuart Machin (who I think has done an excellent job) regain this momentum?
H1 26 results summary
Today’s financials are a mixed bag, as I would expect given the scale of disruption faced by the company during the half year. There are also a few points that need explanation, which I’ll return to shortly:
Revenue up 22.5% to £7,942.3m
Adjusted pre-tax profit down 55.4% to £184.1m
Reported pre-tax profit down 99% to £3.4m
Adjusted EPS: 6.6p
Dividend per share up 20% to 1.2p
Adjusted return on capital employed: 12.4% (HY24: 15.0%)
Revenue: this number immediately looks odd – how can sales be up by over 20%? The answer is that M&S has consolidated its share in Ocado Retail into its accounts this year, meaning that Ocado sales are added to revenue.
Previously, the Ocado stake was accounted for as an equity investment, meaning that M&S only reported its share of Ocado’s profit/loss in its accounts.
Oado contributed £1,4799.9m of revenue in H1, on which it generated an adjusted operating loss of £3.1m.
Stripping Ocado’s sales out of the group total shows us that M&S revenue fell slightly in H1:
Food up 7.8% to £4,531.9m
Fashion, Home & Beauty down 16.4% to £1,697.6m
International down 11.6% to £255.8m
Total revenue ex-Ocado down by 0.3% to £6,462.4m
Profit: impressively, M&S has already received a £100m insurance payout for the cyber attack. This has been added into H1 adjusted profit. In my view, this is a slightly odd choice.
The company incurred £101m of cyber-related costs in H1. Understandably, these were treated as an adjusting item. However, for the company to then include the matching insurance payout as a contribution to profit gives a somewhat distorted view of underlying trading profits, in my opinion.
Stripping out the insurance payout from profit gives me an adjusted pre-tax profit figure of £84m for H1, down by 79% from £413m in HY25.
Trading commentary: One reason for this large fall is that the stronger-performing Food business has a much lower margin than Fashion, Home & Beauty (FHB) – the Food operating margin was 5% last year, compared to 11% for FHB.
As a result, adjusted profits have been hit hard by the decline in FHB sales since the cyber attack.
Food sales rose by 7.8% in H1, contributing a divisional operating profit of £89m. Volumes rose by 2.8%, with larger basket sales (over £30), up 12%.
This side of the business seems to have benefited from the predominance of in-store shopping, versus online/click and collect in FHB.
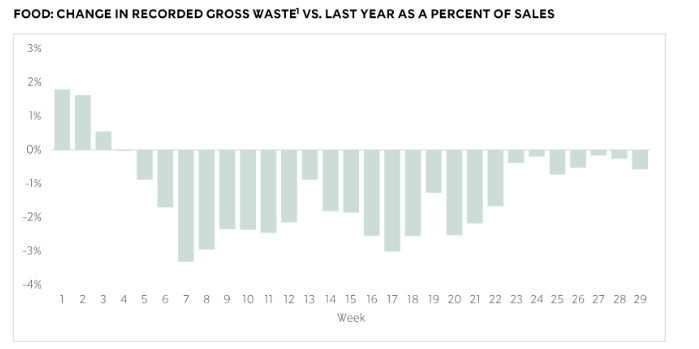
Food operating margins fell to 2% (HY25: 5.1%) due to higher levels of discounting and waste, but waste levels are now returning to normal. M&S has commendably provided a Next-style chart in today’s report to illustrate this:
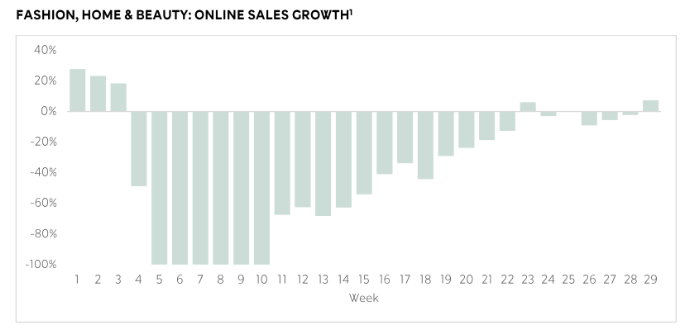
Food, Home & Beauty: this side of the business has suffered harder and longer from the cyber attack. Sales fell by 16.4% and FHB operating profit was just £46.1m, reflecting an operating profit of 2.7% (HY25: 12.0%).
As regular shoppers will know, online ordering and click and collect were suspended for a long time, while in–store availability was also affected. However, online sales growth has now turned positive again:
Balance sheet/cash flow: it’s fortunate that M&S entered this period with net cash of £438m (March 25) excluding leases. More than £100m of cyber-related costs and £245m of capex contributed to a free cash outflow of £193m in H1.
As a result, net cash dropped to £176m before lease liabilities, while the inclusion of lease liabilities relating to Ocado Retail lifted the group’s reported net debt to £2.5bn (HY25: £2.2bn).
Statutory net debt is a big number here, but I don’t see too much to worry about at this point, assuming trading continues to recover as expected.
Outlook
We are confident we will be recovered and back on track by the financial year-end. In the second half we therefore anticipate profit at least in line with last year, as the residual effects of the incident continue to reduce in the coming months.
Following the attack, M&S adopted a policy of fixing things the right way and taking the opportunity to upgrade technology where necessary. While this probably wasn’t the cheapest or quickest approach, I think it’s the correct choice and is likely to pay off over time.
In the near term, I suspect this year’s results will depend heavily on whether trading returns to normal over the key festive period. Watch out for M&S’s post-Christmas update.
With thanks to house broker Shore Capital on Research Tree, we have updated forecasts today.
Shore’s analysts appear to be surprised by the speedy insurance payout, which wasn’t previously factored into their forecasts. This has led to some confusing wording in today’s note, which I’ve tried to decipher below:
Adj PBT: Shore’s previous forecast was for FY26E adj PBT of £600m, excluding insurance (£100m received in H1).
Today’s updated FY26 adj PBT forecast is for £655m, including £100m of insurance. This means the new base forecast for trading adj PBT is £555m. That’s effectively a significant cut from Shore’s previous forecast, perhaps because the aftermath of the cyber incident is dragging out longer than expected.
Shore’s EPS forecasts reflect the company’s approach – FY26 EPS estimates rise today because they now include insurance, whereas previously they didn’t! Forecasts for later years have been trimmed, but only very slightly:
FY26E adj EPS: 23.4p (prev. 20.6p)
FY27E adj EPS: 33.9p (prev. 34.4p)
FY28E adj EPS: 35.6p (prev. 36.2p)
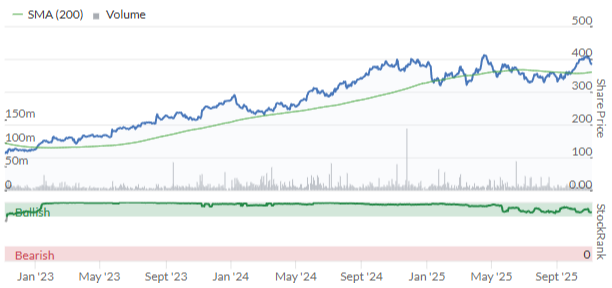
Looking through to FY27 puts M&S shares on a forecast P/E of 11.5 – significantly cheaper than Tesco, for example.
Roland’s view
My concern in May was that a recovery to full trading volumes and margins might take longer than initially expected. To an extent, I think this caution was justified – today’s mention of “residual effects” makes it clear that operations and trading have not yet fully returned to normal.
What’s more difficult is deciding whether to go AMBER/GREEN, or leave my view unchanged at AMBER.
I’d like to be more positive, but I’m aware that the company’s house broker has – technically – cut its forecasts 4today.
In addition to company-specific challenges, there’s also the risk that November’s Budget could create further cost headwinds for retailers.
It’s a finely-balanced decision, but I’m going to stay at AMBER today and revisit the situation after Christmas.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
Gold, etc
Are the Rohimm about to ride to the rescue of leveraged gold traders (imagine trumpets, Gandalf on the floor, staff broken and the Orks crashing the door down - aka my spread bet account).
Gold - there is not a lot of it, it is not easily found or dug up and most importantly cannot be produced with computer code or printed into fiat paper - but they will try.
Whatever is liquid - can buy and sell - until you can't.
Just noticed ME International (LON:MEGP) had a tick up at close, ex div tomorrow and updates Friday wonder if we might get good news re someone buying it ?
In my retirement portfolio M&G (LON:MNG) is one of the core holdings. Great yield, share price keeps edging up and I can see little headwind that is going to cause them huge problems. My mothers broker (she is 90) reckons it is not possible to get a yield above 2.5% safely- I have suggested they look at companies like this- capital growth is not an issue for her, she just needs a decent income. Aberdeen, Legal and General the list goes on. I will not shame them but they are quite well know. For a 90- year old the portfolio gets "churned`' in my view and holding gold seems an odd choice. These sort of companies, in my view, should be the core of an income producing portfolio.
Even if you were not already retired, a reinvested 7%+ dividend would compound nicely over the years.
Totally agree John
My mothers broker (she is 90) reckons it is not possible to get a yield above 2.5% safely- I have suggested they look at companies like this- capital growth is not an issue for her, she just needs a decent income. Aberdeen, Legal and General the list goes on. I will not shame them but they are quite well know.
They're not alone, it's the risk modelling. As soon as people say they're risk adverse (which advisors are virtually mandated to do for anyone over retirement age) it force excludes equities. Any advisor that put your mother into equities could face regulatory penalties and would be virtually certain to lose a lawsuit if they lost capital and her estate sued them.
The only way around this is to sack the advisor and do it yourself - but be very certain that any other beneficiaries are involved in the decision (in writing) otherwise you could find yourself in a whole heap of trouble.
timarr
I wish I could sack them, but my late father set it up and she is loathe to move. She is in the most odd equity funds from Far east to USA to gold- and the yield is paltry in my opinion. I question the stockbroker from time to time and they just refuse to listen. As it happens we might be taking a chunk out and risk the `IHT bill- she is pretty fit !
You've neatly summed up why I've DIY'd for 25+ years. When people realise they either think I'm stupid or a genius (not because I did it or my results, just an assumption). I'm neither but quickly realised that the industry rules weren't the right way for me.
I can sort of understand it in bygone times when you had to buy an annuity and therefore protect from shocks as you near retirement but these days there's an argument that my investment choices outlast my lifetime through inheritance.
One other recent thing that also really annoys me is that smaller advisories are being taken over by larger firms. They then change investments to fit corporate aims rather than individuals. So what was a nice friendly flexible firm 5-10 years ago is now totally different. A friend worked in the industry for 4 decades and his last company went through that process and he left as he felt he was compromising his loyal customers.
Charles,. Some 20 years ago I had a financial epiphany and have managed both my wife's investments and my own ever since. Between us we had around 14 different pensions - some mid size and some small - all from various previous employers; yes we get itchy feet / bored after a while and look for pastures new. I queried the cash in / transfer value of these various pensions with a view to possibly having DIY SIPPS and was amazed that not ONE of the pensions was actually worth as much as had physically been paid into it. Yes, that's right - all of them had lost money; despite the fact that some were over 20 years old. Of course, the various companies had taken their annual charges - even if the funds had lost money. So the net result was that had we simply stuck the money into interest paying accounts and let it accumulate we would of had nearly twice as much in our pot as the experts had generated for us. Of course, doing that would have deprived them of their nice new Audi A6 company cars and smart Armani suits. Me, cynical - you bet. Its a travesty of the term financial advisor - your mother is being given appalling service by a system that is stacked against the individual in preference for a greedy industry which is only interested in its own self enrichment.
Totally agree.
I remember the days of 5% bid offer spread when you took out a unit trust, and the old insurance ISA you used to be able to put a grand into the charges were that high even if it grew at 7% per annum after ten years you were still down on the original investment.
Hi Graham, Roland & the Stoko team, is there any chance if your going to spend the time writing an update that's worthy of being mentioned in the daily headline, that you can also copy and paste it into the main section of the page as well so it appears in a more readable format than being dumped into a narrow elongated column of a spreadsheet? Reading one and a half or two words on a line is no use and it doesn't do any justice in a presentable way to the time, knowledge and effort you all put into writing it. All of which I really appreciate and really look forward to reading.
It doesn't always need to be jazzed up with the graphs from the stock report main page but the never ending column of a couple of words trailing down the page is really getting on my nads.
I'm sure I could give the spreadsheet the old right click, double click rolly polly backflip or whatever it takes to make it readable but that's not so easy when you've got a coffee in one hand and a donut or a croissant in the other. The trauma of deciding which one to put down to be able to read the daily report is unbearable in that format and it ruins the user experience. Or at least mine.
One main section write up today and the rest in spreadsheet form is pants and right now I'm hanging on by a thread ... pardon the pun, only for the readers comments and not the content provided in that format. The site already has a function where I can read the RNS's and market news for the day so I don't get the fascination with spreadsheet thing ? If the QVMS scores are based on the data from the latest financial results and are the traffic lights why is there a need for a spreadsheet with another traffic light system as well? Are we moody's or another ratings agency now upgrading or downgrading the colours on a separate system by a notch? I get it for tracking offers and takeovers and other things stoko doesn't update so quickly on but not as a daily report.
Like I said I really do value the site and look forward to reading all of the daily write ups and comments from everyone who uses it but not so much right now in this format.
Just two days left to buy tickets....final release on Saturday is at increased prices to avoid the last minute rush that we always seem to get
MELLOLONDON — Mello Events
We have an amazing two day line up so do come and enjoy all the presentations and panels not to mention our best ever line up of speakers including Ed Croft
Hi Graham, Bloomberg TV for me these days but I don't watch closing bell unless markets have gone crazy for some reason. It still sensationalist but a little easier on the ear...
Timing can be everything in the J D Wetherspoon (LON:JDW) training update today.
Given the politically aware CEO is keen to engage in political debate around the taxes impacting his business, was he ever likely to talk up J D Wetherspoon (LON:JDW)’s prospects pre budget?
There was an ‘in line’ nod to shareholders and staff. In the meantime, their low cost prices have gone up (not in the update)…and they’re still as much as 40% cheaper than the competition so lots of space to grow into.
Their estate is unrivalled in terms of location and size and the small but growing franchise strategy potentially offers improved returns from a slightly lighter capital model.
I think the continued market share increase was notable, as I see J D Wetherspoon (LON:JDW) pubs becoming a core stop off for alcohol, food and even tea/coffee for an increasing number of cost conscious customers i.e. they’re becoming more relevant to more people in more circumstances.
In a recent podcast, Peter Lynch spoke about how people miss a lot of value by underestimating growth potential once businesses reach a certain size. J D Wetherspoon (LON:JDW)’s PEG of 0.8 suggests there’s more to come.
Cheers to the beers!
They have far fewer, and larger outlets than in the past. They are buying freeholds reducing costs but increasing debt. As the NZ born part owner paid £165M personal income tax in 94 he can express any opinion he likes as far as I am concerned. One assumes he turned down a Knighthood?
Just keep an eye out and buy when Tim Martin does. Sorted.
Hi, also, I cannot see BT on the traffic light/update spreadsheet. Thanks.
trn (trainline) Will the new railway bill have an impact on trainline?
The Railways Bill will empower GBR to bring fares and ticketing into the 21st century. Passengers will ultimately be able to purchase tickets through a new GBR website and app, replacing 14 existing operator ticketing platforms. Tickets will be available to purchase at station ticket offices, via ticket vending machines and onboard trains, to ensure all passengers can purchase a ticket with ease and travel with confidence. GBR will also build on the expansion of successful Pay As You Go and fares trials, making travel more flexible and simpler.
I don't think a website created by a government of any colour will be as good as one made by a private for profit company built over many years. Unless the government can use its monopoly position to offer cheaper tickets.
Ticketles travel with swiping in and out of stations seem a bigger worry for Trainline (LON:TRN) I'd say.
Yes, but heavily trailed over several years and already priced in
I think Trainline might White label the gov website, they’re in the running after an initial snub/oversight by the government…
I think Trainline might White label the gov website, they’re in the running after an initial snub/oversight by the government…
I think this might be the best solution all round. Removing all questions about the company’s future without hindering its expansion into Europe. Arguably enhancing its prospects overseas. It’s about time we owned some their utilities!
Hi, and good morning, I am looking forward to your updates, holding MKS, BTRW and BMS. Thanks too for the spreadsheet, a great idea with current traffic light colours. Incidentally, I cannot see BARC on this?
Marks and Spencer (LON:MKS) a quick scan of their commentary this morning reveals a drop in margin in food that they put down to the cyber event and associated problems, however I feel that the board have not addressed the shrinkage/shoplifting issue and I think this could be a large contributor. The board definitely used to think that 'Mark's' customer do not steal, but things have changed, my local Food Hall gets pillaged daily, yesterday evening I saw a chap brazenly put 4 of the most expensive ready meal kits, £25 each, in a bag and walk out. These are displayed half a dozen steps from the doors and are probably the most expensive food item on offer. I told a member of staff and their reply was, 'yes they always come in when the security guard is on his break'. Not good enough I am afraid.
As in a gun club where everyone is the Safety Officer all the staff in a shop should be the Thief Alarm.
Marks and Spencer (LON:MKS)
TBH a few years ago I would have stopped the guy myself ( he wasnt very big!) but with the predominance of knife crime and no skin in the game I thought better of it and just told a staff member.
The knock on of shoplifting these days is that these EPOS systems that control your stock will still think that the store has 4 of those items in stock and wont reorder cos they have not been scanned as sold. I met Mike Ashley of Sports Direct fame on holiday many years ago when his business was called Sport Soccer, he had just had a similar system installed in the few stores that he had and he had to have a manual override on ordering as he realised that the "little buggers only nick the popular sizes" so he would often be out of size 34 waist mens shorts or track suit bottoms while his stock read was telling him that he had plenty. I am not sure how large retailers deal with this problem nowadays but would be interested if anyone knows.
Maybe not the right place to ask, but I will ask anyway
Is anyone else having issues with the stock upgrades section showing out of date and wrong information?
I did query it and I think it's fixed now.
J D Wetherspoon (LON:JDW)
hard to take much out of todays update - it doesnt really say much ref costs. i would take that as neutral at best.
previous update seemed chippa enough - but i think overall brokers did downgrade after that update (03/10). so whilst i thought they very much looked on track for priro expectations - Graham went as far as saying he had "no confidence" ref current year forecasts on that day - and up till now it looks like he has been right with direct downgrades after that update. Overall i think that the trend here is abvolutely fine and dandy - even if there are some minor wobbles about the exact year end numbers.
J D Wetherspoon (LON:JDW)
i must have swicthed off here (tto much rant) before the all important last sentence which did say the following.
"The company is pleased with the continued sales momentum but is mindful of the Chancellor's Budget statement later this month and, as a result, is slightly more cautious in its outlook for the remainder of the year."
I cant really take this as being confident - but i am not overly negative here - i think J D Wetherspoon (LON:JDW) are very wary about shouting from the rooftops all is great even whn it is - so i dont think its unususal for them to be cautious whilst at same time hopefully still delivering decent progress.
One thing i would say is that hmrc are very unlikely to be wanting to target a company like wetherspoons - they are very mucha bellweather for many uk retailers and the like - if J D Wetherspoon (LON:JDW) are struggling then thats a sign that life is tgough for everyone. They have very much had their pound of flesh screwed out of them recently - ref wages increases- ni increases - rates increases - energy price increases and everything else to boot
Right now who can be confident in anything UK except gold?
Right now who can be confident in anything UK except gold?
I am old enough to know that most people are really moaning about first world issues here. compared to anything back in the day uk isnt doing nearly half as bad as what people make out - they have it easy compared to 70's 80's and 90's whether they accept it or not. In my neck of the woods most people i know are doing fine and making ends meat - and thats in tehn north east which isnt renowed for being an affluent part of tje country ! . Note i agree its tough times on lfl basis and powers that be have run the country negligently by stealing from future generation and helping people to move abroad pay no taxes and have no penalties applied !!- and we are unecessarily bumping up prices of essentials. So not helping ourselves.
if i look back to 1991 when i left education unemployment rate was 8.6% - so compared to similar tough times in the past its not as bad as it could be now - we arent in the real deep craopla as long as we can keep a lid on national debt and work towards balancing the books )ok debt not increasing in real terms starying point 1) - my simple theory is that if we did that and didnt screw people over and taxed properley thats all the stuff we need to do for uk to be fine. Perhaps with minor tweeks like ensuring we build enough ffin new homes so young people can afford a home if the population keeps growing.
ref gold - who knows thats been on a tear - so i have no idea whether its going to carry on or might get toppy at some stage.
Hi rmillaree. Well, look at it this way, Momentum works at the state the Nation is in, same as in shares, and has been moving in the wrong direction. I completed my grammar school education in 1961 and can remember reading Korean War headlines on the daily newspaper and sweet rationing too! The Berlin Airlift (I lived near Lyneham), Suez came a bit later. I'm talking confidence, not making comparisons of which I could make many. No, I'm not at all confident.
request for comments on TP Icap (LON:TCAP) - cheers.
i have bought into this recently - must admit dont know much about the company (not sure i need to) - p/e rating seems reasonable - stock ranks seem reasonable and trading seems reasonable - with fairly steady eps projections including higher expected eps next year.
Cant work out if chart is going up sideways or trending down now here - at a minimum it seems fluff has come of the shareprice somewhat - thats partly waht tempted me in.
todays numbers seeem meeeeh - but they are on track - i guess with p/e of under 8 they arenmt necessarily going to be shooting the lights out.
there was mention of spinoff here - not sure if this might unluck value - i think thats possible.
Update in that regard today is also meeeeh - based on comments below that sounds like its very much on backburner at present - probably not great news if listing would be good news or that suggests they cant get the price they think its worth.
Parameta Solutions Update
The Board remains focused on Parameta's sustainable growth and will continue to assess the appropriate timing for a potential minority US listing.
I guess i await new of whether thats all as suspected or not if there are any broker updates - i cant see anything here that is likley to move dial in upwards direction.
Recently bought into this one myself so a +1 from my side. Looks cheap but then maybe the update suggests why
Also tempted but mainly as a beneficiary of strong $ ....maybe weakness has held stock back since it is making relative lows despite Goldman Sachs (NYQ:GS) and JPMorgan Chase & Co (NYQ:JPM) very much in favour. Interesting that it's not having a much better year but fixed interest markets are quiet ...obviously not a trade for a wide correction in markets. Rating interesting but I doubt much will happen without a transaction .... as I say.. tempting.
TP Icap (LON:TCAP)
cheers RDHOWARTH - its not the kind of share i want to overthink - stuff like dollar will be tailwind today and headwind tomorrow or vice versa. I wouldnt be confident ref dollar strength at present - somewhat the opposite. But its kinds ditto ref the GBP too
with dividend yield of 6.5% - i dont really need much if anything to be happening for me to be content as long as they are ticking over and have no fundamental flaws in their business model - ref delivering the bacon.
Not sure why they have been doing so well from 2024 onwards compared to previously - so my only real worry is if they have managed to make a quick buck somehere with stuff that might not be so easy to make thos profits long term. With expectations for good 2026 though 2023 and prior seems very much in thne rear mirror as things stand.
I jumped out today for 5% loss, don’t like the falling momentum.
Roland nailed BMS March 24th with Amber Red. Again today's HY starts with a positive statement....then you get to the numbers - all down except for risk advisory. As long term sufferers and loyal holders we could do with some risk advisory on this company if anyone has time.
Both M&G (LON:MNG) and Vanquis Banking (LON:VANQ) delivering positive trading updates today. Two that I hold, so I will be interested to get your take on them, Graham.
Cheers Lord Gnome, I'll see what I can do!
Thanks Graham. Greatly appreciated. MNG has been a spectacular buy for me, back in the 180s with a 10% yield. Happy Days! I can afford to sit it out with VANQ. This was a conviction buy for me at 95.5p. It's my only recovery stock and I will only sell if I see a better opportunity. Cheers!
Debt
https://www.stockopedia.com/ne...
Trainline (LON:TRN) raising guidance !
Trainline (LON:TRN)
It's a cracking company, yet it's always being sold off, I genuinely don't get it?
Trainline (LON:TRN)I dont think investors believe it has any moat however the numbers would refute this. It is a great share for trading though.
I wonder if the fear holding Trainline (LON:TRN) valuation down is Tap & Go ticketing which might make it superfluous?
"Project Oval" (TFL's expansion of contactless payments) .. will put £150 million of UK Consumer net ticket sales at risk. (This impact forecast is taken from today's results).
If contactless goes Nationwide, they might well be toast!
Also, as someone else has commented, and indeed as noted in today's results, "the UK Government intends to consolidate the ... train operator retail sites into a single public sector retail website and app." You could easily imagine a government minister handing the contract to a mate of theirs who is currently bored having mothballed their PPE importation business.
For me it's always been 3 concerns:
All in all, high risk / low reward.
Personally I think the scepticism / low share price of Trainline (LON:TRN)is wonderful in the context of their chunky share buyback programme. It allows a LT transfer of value from the impatient / sceptical to the patient. For the sceptics I highly recommend listening to this morning’s webcast and the associated Q&A. They are not disappearing anytime soon. And in the interim the current valuation offers a 10%+ forward OpFCF yield and growth optionality in Europe
Trainline (LON:TRN)
one doesnt have to be a sceptic (to me they seem to keep delivering so i am more positive than not) to worry that the national portal that will dish out all tickets mignt end surplanting Trainline (LON:TRN) as the main player.
what is the companies current stance ref their thoughts in that regard?
If that portal will simply replace current myriad of suppliers - but still actively link with "external agents" - i dont see a need for anything to change. I would say though - if that portal gets its act together and is tasked to "actively drive sales" via that portal - i might be worried that the way to do that is to offer the best deals via the main portal.
is it known that this national portal will still carry on linking with external parties ? and not activaley be competing with those xternal providers.
the main worry would be that to make itself look good they would want more stuff to go via them - so that if there is margin being made its with them and no trainline. so unless its kown that it would be neutral i would be more than slightly worried until i have some assurances its likely to business as usual ref external agencies.
And when was the last time you saw a govt deliver anything on time, on budget and competitive with the private sector? You are discounting Trainline’s market recognition and years of experience. Uber has just given it a good try throwing mounds of cash at the problem - and got nowhere. The govt!? If they were serious they might as well just buy Trainline. Would certainly cost the tax payer less and be more effective. But let’s see
Trainline (LON:TRN)
You are discounting Trainline’s market recognition and years of experience.
no im not - read my post (apologies if its not clear) - i am more positive than negative ref trainline - i am simply asking the question if this site will compete with trainline or not.
Do you have the answer to that specific question - its obviously an elephant in the room type of question - we may not have the answer now but there will be an answer sooner or later.
If it does compete directly with trainline - rather than actively "partner" with trainline - surely you can see that might be something of an issue.
the IT here is neither here no there imho. Even government bodies can knock up stuff what works nowadays - imho key is whether that entity still wants to partner with the likes of trainline
If they were serious they might as well just buy Trainline.
The whole point if that this new entity is being broight into existence to do much more than ticketing - ticketing is just part of the proces - its rightly all being merged together - imho that can quite happily exist alongside external partners - if it is happy too. Note as it does much more stuff too - imho is fairly obvious that they are going to make a decent effort to get something internally that adds value and looks good - imho it sems here that they key reason for this to exist is to drive up passenger use and be more coherent - so anything that drives extra traffic is likely to be good that doesnt have to be bad for trainline.
Nobody is mentioning Uber as a threat. With or without the national gov portal I see them as a big threat. They already offer train tickets, often cheaper than Trainline and have a huge existing user base. Either way I think the discussion shows there's little moat to protect it.
And there's also now Trip.com offering tickets.... in the UK and also across Europe.... not as polished as Uber or Trainline booking, but this isn't rocket science.... train ticket booking pathway is short and simple.