Daily Stock Market Report (Wed 9 July 2025) - IPX, JET2, HTG, SYS1, SATS, ZIG, WPP, FIN

Good morning! The Agenda is complete.
Spreadsheet accompanying this report: link.
Wrapping it up there, cheers!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
WPP (LON:WPP) (£5.7bn) | PW: performance worsened in Q2. H1 LFL rev now exp -4.2% to -4.5% & H1 op profit £400-425m. | AMBER/RED (BLACK) (Roland) [no section below] | |
Londonmetric Property (LON:LMP) (£4.6bn) | £7.3bn portfolio after recent acquisitions, with rent of c.£410m. Avg 16% uplift on rent reviews. | ||
Jet2 (LON:JET2) (£3.8bn) | Rev +15%, PBT +12% to £593m. Passenger numbers +12%. FY26 trading in line with market expectations. Canaccord FY26E EPS: 223.7p (+5% vs FY25). | GREEN (Roland) Growth looks likely to slow somewhat this year, but Jet2 continues to generate respectable double-digit returns on capital and has one of the strongest balance sheets in the business. With the stock trading on a P/E of eight, I’m happy to take a chance on the slightly weaker outlook and maintain my positive view. | |
British Land (LON:BLND) (£3.5bn) | Norton Folgate 64% let. Storey at Bishopsgate now fully let, Storey at Broadgate 67% let in 6 weeks. | ||
| Cairn Homes (LON:CRN) (£1.13bn) | H1 2025 Trading Update | Confident in full year guidance: revenue growth >10%, operating profit c. €160m, ROE c. 15.5%. | |
Smarter Web (OFEX:SWC) (£856m) | Raised further £10.3m through share sale. Founder Webley now controls 10.7%. See Mon 5/7. | ||
ZIGUP (LON:ZIG) (£827m) | Rev -1.1%, adj PBT -7.6% to £167m. Fleet assets up 16.2% to £1.5bn. Outlook positive. | AMBER (Roland) | |
Close Brothers (LON:CBG) (£618m) | Focusing on commercial customers, stepping back from retail. £20m cost saving by 2030. | ||
Young & Co's Brewery (LON:YNGA) (£593m) | YTD rev +6.6% in total, +7% LFL. “Strong momentum […] confident about the year ahead”. | ||
Hunting (LON:HTG) (£496m) | SP +10% | GREEN (Roland) [no section below] | |
Everplay (LON:EVPL) (£457m) | Strong trading,. FY results to be slightly ahead of exps. Acquired all rights for “Hammerwatch”. | ||
Galliford Try Holdings (LON:GFRD) (£429m) | FY results to be slightly ahead of exps, with adj PBT >£41.6m. FY26: 90% of revenue secured. | ||
GYM (LON:GYM) (£283m) | H1 LfL rev +3%. Total rev +8%. Net debt £51m. Confident in FY outlook. Opening 14-16 new gyms. | ||
| Impax Asset Management (LON:IPX) (£257m) | Q3 AUM Update | AUM +3.1% to £26.1bn. Net flows -£1.3bn offset by £1.1bn takeover and market movements. | AMBER/GREEN (Graham holds) Leaving our AMBER/GREEN stance unchanged to reflect that the bull thesis is a bet against the continuation of current trends. If AUM can stabilise and return to growth, I do think that the potential returns from the current market cap are very interesting. |
SRT Marine Systems (LON:SRT) (£189m) | Rev +423% (£77.5m), adj. PBT £4.4m. Cavendish forecasts: FY26 rev £115.8m, adj. PBT £10.2m. | ||
Renold (LON:RNO) (£181m) | Rev +3.9%, adj. op profit +11%. Demand is slightly below FY25, expect it subdued in H1 (PW?). | PINK (recommended offer at 82p) | |
System1 (LON:SYS1) (£55m) | TU: Q1 revenue -7%. Tariff impact on European clients and currency headwind from the weak dollar. Outlook: revenue +15%, profits in line. Canaccord reduce their FY March 2026 revenue forecast from £45.1m to £42.9m, and their adj. PBT forecast from £5.9m to £5.7m. For FY27, adj. PBT is seen growing to £7.9m. Net cash £11.7m. Founder and President John Kearon, also the largest shareholder, steps back to become a NED. | AMBER/GREEN (Graham) [no section below] We discussed US growth concerns at the time of the full-year trading update in April. Today’s trading update does indeed see a soft revenue performance, including a 3% reduction in core “Platform” revenue. Forecasts are also a little weaker despite the company saying that profits for the year will be in line. Strategically the company continues to carry out its plan of winning large new corporate clients (80 new client wins in Q1) and building its US business (US Platform quarterly revenue +16%), and so non-US, particularly European revenue must have shrunk given the overall quarterly result. I’ll leave our moderately positive stance unchanged: while I do think this is primed to do very well for shareholders from the current valuation, especially considering the strong cash position that covers 20% of the market cap, I am mindful that their growth journey is currently facing up against some headwinds. The small downgrades to forecasts today also suggest that some caution is justified. But overall I do still very much like the story here. | |
TAO Alpha (LON:SATS) (£48m) | Hires influential bitcoin expert (with a large YouTube channel) to be their Chief Bitcoin Strategist. | RED (Graham) [no section below] Their new bitcoin strategist has a really polished-looking YouTube channel so well done to him for that. However when I check the company's Feb 2025 balance sheet, I see that there was almost nothing of value on it. There were also no revenues on the income statement. Three weeks ago the company raised £5m and adopted a Bitcoin Treasury strategy - it can own bitcoin and other "stablecoins", i.e. "mature coins which the directors believe provides liquidity within the parameters of cash equivalency". Incidentally, the recent £5m raise had an unusual structure: it was an "investment" with "no interest or fees", a maturity date of November 2025, and a conversion price of 0.2p. In other words, a convertible loan note. The company has also announced the launch of a "second secured convertible loan note" for £100m, to be offered to accredited investors in the US. These notes have a conversion price of 1p. If shareholders are planning to vote for conversion (and I'm not sure if there will be a viable alternative), then why on earth are the shares changing hands at 10p? This makes zero sense to me. | |
Finseta (LON:FIN) (£18m) | SP -25% "On track to deliver expectations." H1 revenue +16% (£5.9m). Adj. EBITDA £0.3m due to investment. Expecting significant H2 revenue growth consistent with previous years, at an improved gross margin compared to H1. | AMBER/RED Graham [no section below] It's a remarkable share price fall, considering the headline to this trading update is "on track to deliver full year results in line with Board expectations, including significant revenue growth". I can find two reasons for the fall. Firstly, there is a very, very large H2 weighting. Full-year revenues are supposed to be c. £15m,, and full-year adj. EBITDA is supposed to be £1.7m. The company in H1 has therefore only achieved 39% of full-year revenue, and 18% of full-year adj. EBITDA. The company says that there has been encouraging new customer onboarding in H1 but it needs a very large jump in H2 to bridge the gap to full-year expectations. The second reason for selling activity today could be the news that a major shareholder reduced their interest last week from nearly 10% to only 8.2%. While today's announcement is not strictly speaking a profit warning, I'm going to interpret as one, and therefore take a moderately negative stance, as I perceive a high risk that the company fails to meet full-year forecasts. Hopefully it can prove me wrong! | |
Shearwater (LON:SWG) (£11m) | FY25 revenue, adj. EBITDA slightly ahead of expectations. Confidence in growth in FY26. | ||
Croma Security Solutions (LON:CSSG) (£11m) | Meets expectations for FY25. Revenue +10% (£9.6m). Market conditions remain challenging. |
Graham's Section
Impax Asset Management (LON:IPX)
Unch. at 194.8p (£257m) - Graham - AMBER/GREEN
At the time of writing, Graham has a long position in IPX.
After sensing a great deal of cheapness here for a long time, I eventually took the plunge and bought a few shares in this one last Christmas, at 247p.
When the ESG agenda was more confident, and when inflows were easy, this stock traded as high as £14 per share.
There was a profit warning in April, and I consider myself lucky to be only down by about 20%. Earnings forecasts did get revised higher again in May. The company has also started buying back its own shares.
Today’s Q3 update shows continued outflows during Q3 (to June), of £1.3bn.
Thankfully this is offset by positive asset value growth of £1.0bn, despite the tariff issue that kicked off at the beginning of the quarter.
Impax has also completed an acquisition that brings in £1.1bn of fixed income assets.
In table format:
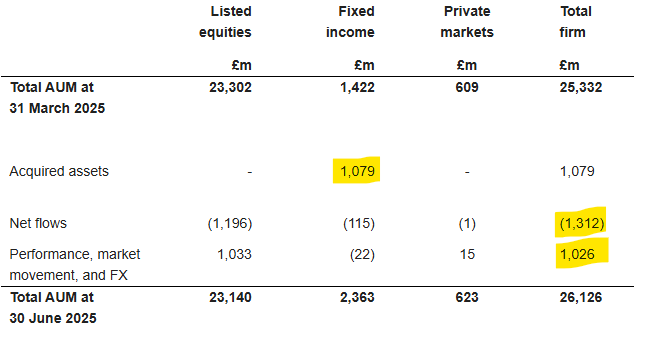
In total, AUM grows from £25.3bn to £26.1bn.
CEO comment excerpt:
The majority of our AUM follows investment strategies that have outperformed their generic benchmarks this calendar year, and in our larger listed equities business, there was a significant reduction in net outflows compared to the previous two quarters, with positive flows in June, reflecting strong institutional client commitments and fresh momentum in our wholesale channels in Europe."
That there were enormous net outflows of over £10bn in H1, which included the loss of huge mandates from St. James’s Place.
Estimates: many thanks to Andy and Paul at Equity Development for alerting me to their latest note on IPX. Paul has left the estimates unchanged, including AUM at the end of FY25 of £25bn. This might be considered conservative seeing as AUM is currently above that level, but I think it’s reasonable to allow for further net outflows and/or market weakness. Their EPS estimates for the current year is 19.5p, putting the shares on a PER of 10x.
(For context, EPS last year was 28p, and 30p the year before that.)
Graham’s view
I still think this is a really interesting recovery stock - not that it’s necessarily in recovery yet! But it’s trading at a low PER and a very cheap multiple of AUM (over £100 of AUM for every £1 invested in the stock at current levels). This multiple is as cheap as the fund managers which I consider to be undifferentiated and less interesting than Impax.
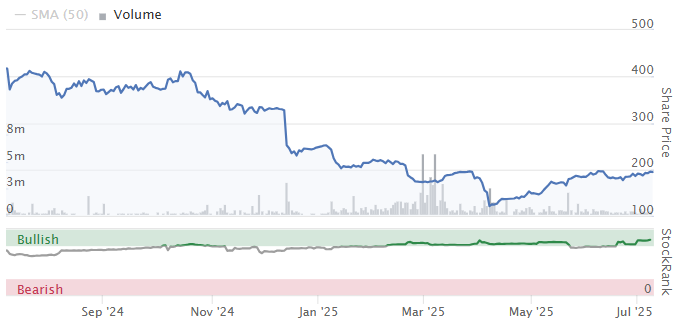
There’s no guarantee that it will happen, but if we see AUM stabilise and then any sort of return to growth, I think the shares are priced for a fabulous recovery. By this I mean that the shares should trade at a higher multiple, e.g. 15x (with higher earnings than currently) or at a much more attractive multiple of AUM, e.g. £50 of AUM per £1 invested in the stock (with higher AUM than currently).
If that doesn’t happen, then I would at least hope for a merger/takeover at a reasonable price. But of course I can’t guarantee that this will happen either.
I do feel confident in saying that fund managers' valuations are at extremely depressed levels. And I’m personally willing to bet that at least a couple of them will recover.
I’m leaving our stance on this unchanged at AMBER/GREEN to reflect the fact that the bull thesis is a bet against the continuation of current trends.
Roland's Section
Jet2 (LON:JET2)
Down 6% to 1,709p (£3.6bn) - FInal Results - Roland - GREEN
Jet2 plc, the Leisure Travel group (the "Group" or the "Company"), announces its preliminary results for the year ended 31 March 2025.
We’ve generally been positive on this well-run short-haul airline and package holiday operator. Today’s results seem unlikely to alter that trend.
The key numbers from today’s results are all moving in the right direction:
Revenue up 15% to £7,173.5m
Pre-tax profit up 12% to £593.2m
Earnings per share up 15% to 213.1p
Total dividend up 12% to 16.5p per share
£250m buyback announced in April is over 35% complete
This growth reflects underlying expansion of the business over the last year. The total number of passengers flown rose by 12% to 19.7m while higher-margin package holiday customers rose by 8% to 6.58m.
Jet2’s focus on holidays means it receives a lot of cash upfront in the form of customer deposits. In addition to this, the company has always prudently maintained a strong balance sheet. Today’s results show a reported net cash position of £2.0bn, including £3.2bn of total cash and £1.1bn of own cash (excluding customer deposits).
As these numbers imply, the group does have some debt. But the cost of this borrowing is hugely outweighed by interest income, boosting the group’s profits considerably:
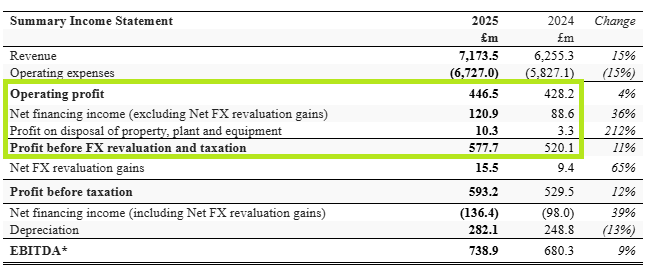
Net finance income increased Jet2’s operating profit by 27% last year – a remarkable result that’s generating meaningful returns for shareholders, helping to support dividends and buybacks.
(As a side note, Jet2 was one of the stocks I discussed in a recent screening piece on cash-rich companies.)
Profitability: Jet2 boasts very respectable quality metrics, according to the StockReport:
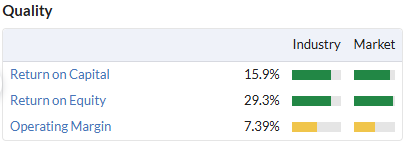
Checking today’s results tells me that last year’s performance was slightly weaker on margins, with an operating margin of 6.2%.
Lower margins are said to reflect inflationary cost pressures and a later booking profile, presumably implying some price reductions on late bookings to ensure capacity is filled.
However, the group’s return on capital employed was unchanged at 15.9%, suggesting that on a longer view the company is continuing to deploy capital successfully.
Spending over the last year included new bases at Bournemouth and London Luton, bringing 85% of the UK population within a 90 minute drive of one of the company’s 13 UK bases. Seven new Airbus A321neo aircraft were also added to Jet2’s fleet last year.
Outlook: travel is a cyclical business. While Jet2’s focus on relatively affordable short haul leisure travel probably dampens some elements of cyclicality, it doesn’t remove it.
The share price has dipped today and my guess is that a slightly more cautious tone on outlook is probably responsible.
While the company states that it is currently trading in line with market expectations, the tone of CEO Steve Heapy’s comments suggests to me a level of underlying uncertainty. Here are a couple of examples:
Bookings for Summer 2025 continue to be made closer to departure, as previously announced, but it is clear that customers' eagerness to get away from it all and enjoy a relaxing overseas holiday in the sun remains strong, provided pricing is attractive...
We are satisfied with our progress for FY26 to date, although we remain mindful of the late booking profile which limits forward visibility and the evolving geo-political and economic landscapes.
Estimates: with thanks to broker Canaccord Genuity, we can see that forecasts are largely unchanged today, except for some very slight adjustments:
FY25A EPS: 213.1p
FY26E EPS: 223.7p (previously 223.9p); +5% versus FY25
FY27E EPS: 229.5p (previously 234.0p); +2.5% versus FY26
The gist of CG’s view seems to be that operating margins will remain under pressure, but that finance income will continue to reduce the impact on the bottom line.
Roland’s view
Jet2 is one of the AIM market’s largest and most successful companies and it continues to expand. Passenger numbers rose by 12% last year and on-sale seat capacity for this summer is currently 8% higher than last year.
In this context, I think it’s interesting to note that this airline remains a relative minnow alongside budget travel giants Ryanair and easyJet.
Ryanair’s latest monthly metrics show the airline flew 19.9m passengers in June. That’s slightly more than the 19.8m that Jet2 carried in the whole of last year! easyJet expects to fly c.100m passengers in its current financial year.
While these larger airlines target a broader range of routes and customer segments, I think these figures support the view that Jet2 could still have plenty of runway left for growth.
Today’s FY26 estimates price the stock at less than eight times forward earnings, backed by one of the strongest balance sheets on the UK market. Notwithstanding the macro risks, I’m happy to maintain my previous GREEN view following these results.
ZIGUP (LON:ZIG)
Down 7% to 337p (£755m) - Preliminary Results - Roland - AMBER
ZIGUP plc (LSE:ZIG), the leading integrated mobility solutions platform providing services across the vehicle lifecycle, is pleased to announce its results for the full year ended 30 April 2025.
In May, I tentatively upgraded my view on van hire and accident repair group Zigup to AMBER/GREEN, after the company said its results for the year to 30 April would be “modestly ahead” of expectations.
Today we have the actual numbers, which have received a negative reception from the market despite being billed as “ahead of expectations”.
Did I get it wrong in May, or is today’s drop highlighting a potential buying opportunity? Let’s take a look.
FY25 results summary
2024/25 were always expected to be reset years following the bumper profits generated during the supply chain crisis period of 2022/23.
Sure enough, Zigup’s profits did fall last year while its revenue flatlined:
Revenue down 1.1% to £1,812.6m
Adjusted pre-tax profit down 7.6% to £166.9m
Reported pre-tax profit down 37.4% to £101.5m
Adjusted earnings per share down 4.9% to 58.4p
Revenue appears to be below consensus expectations of £1,882m, but adjusted EPS of 58.4p is ahead of Stocko consensus for 54.1p. I assume that this adj EPS figure is the “ahead” result management has referred to today.
Trading in the core Northgate van hire business appears to have been relatively strong last year, with revenue up 5.2% to £683m and rental profits up 9.1% to £120m.
Zigup’s overall result was held back by falling profits elsewhere:
the continued normalisation of disposal profits (down 15% to £53m)
lacklustre profitability in the claims management division, where revenue was flat at £872m and operating profit fell by 26% to £38m.
Disposal profits are a core element of any vehicle rental business, but in fairness I think the company’s fleet is still evolving as the changes made during the supply chain crisis are unwound. I would expect this decline to level out fairly soon – the company says the average age of its UK fleet fell by 5.5 months to 28.5 months last year.
Rental profits grew ahead of rental revenue last year, indicating an improved margin and suggesting decent demand for hire vehicles.
This growth seems to have been concentrated in Spain, where the average number of vehicles on hire rose by 9.4% last year. In the UK, there was a 2.6% decline in vehicles on hire.
The net result of all this change was that Zigup invested in expanding and freshening its rental fleet last year. This resulted in a free cash outflow for the year of £58.1m and an increase in net debt, although this may not be a problem if the newer vehicles generate expected positive returns going forwards:
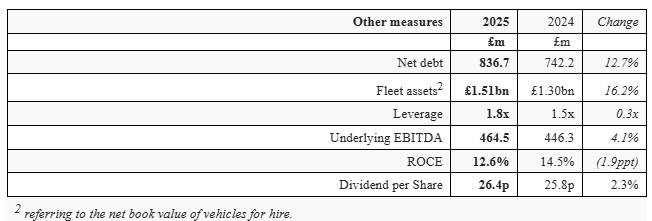
For hire businesses I tend to look at net debt as a proportion of rental asset value, using 50% as a rule of thumb for comfortable leverage. These figures show this ratio reducing from 57% to 55% last year, which seems positive.
However, lower profits mean Zigup’s net debt to EBITDA ratio rose to 1.8x, which is towards the upper end of what I’d want to see for a business with somewhat average profitability metrics:
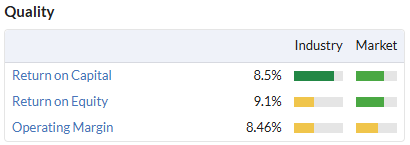
The company’s profits are heavily adjusted, but on a statutory basis my sums suggest an operating margin of 7.5% for FY25, with a return on capital employed of 7.2% – both below the comparable figures from last year.
Outlook
As with Jet2, I think the reason for today’s share price drop is likely to lie in the outlook rather than in last year’s results.
Today’s FY26 guidance is positive, suggesting further trading growth in the two operating divisions, albeit with some apparent uncertainty on disposal profits:
We see good opportunities in FY2026, with robust demand for our mobility solutions across our markets.
We would expect this to include achieving mid/upper single digit underlying EBIT growth for our operating divisions, before taking into account disposal profits.
I am inclined to take a cautious view on the overall outlook for profits this year. Last year’s weaker trading in the UK hire business provides one clue about possible challenges. So too does the weaker FY25 result from the claims business, which came despite management commentary on “insurance contract extensions” and “new partner channels”.
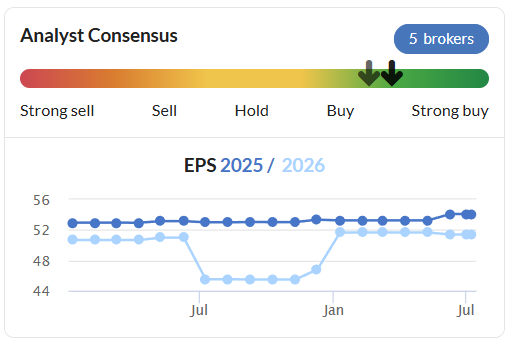
Broker consensus forecasts ahead of today suggested FY26 adjusted earnings could fall by 5% to 51.4p per share. I’m not sure if this commentary implies any change to these expectations, given today’s earnings were ahead of previous expectations.
Roland’s view
Excluding disposal profits from guidance is understandable in some ways, as I explained above.
But in another way, I don’t think it’s really acceptable. Disposal profits are a core element of the vehicle rental business model. Zigup sold over 20,000 used vehicles last year, equivalent to nearly half its rental fleet.
In today’s results, the company says used van disposal pricing has been stable since October 2024. Management also reminds us that it has “successfully forecast and highlighted” disposal pricing trends on a number of previous occasions.
All of this leaves me wondering why today’s guidance for segmental profit growth has been caveated by the exclusion of disposal profits. I can’t help feeling this might be a way of disguising the possibility that overall profit growth this year will be limited, or even negative (in line with forecasts).
My view on this business is mixed. I upgraded to AMBER/GREEN in May but had previously been neutral.
The shares often look cheap and indeed today’s results leave Zigup trading below book value, with a near-8% dividend yield that’s remained covered by earnings (albeit not by cash flow).
On the other hand, leverage is significant and profitability appears to be under pressure. Looking ahead, consensus expectations prior to today were for a further drop in earnings for FY26. Today’s outlook statement doesn’t address these expectations directly, in my view, instead providing caveated guidance about underlying divisional profits.
It’s possible that I’m being too cautious, but I’m going to revert my view to neutral today
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

58 comments
Jet2: steady as you go results but several headwinds ahead:
1.Bedding in Gatwick will be 2026 cost
2. North American World Cup with at least 2 home countries in will top slice growth
3. November tax rises will hit consumer affordability driving even greater promotion activity. ( direct flights rather than full holiday packages already apparent).
Time will tell but challenges ahead though I agree Jet2 undervalued.
ZIGUP (LON:ZIG)
hmmmmm - great show of support here by then CEO buying £250k worth of shares. Perhaps the slightly downcast tone here has an explanation if that suits him to have depressed shareprice for this topup.
note it looks like he is buying back in having previously sold out at 400p - so whils not beinag aday trader looks like he isnt adverse to some double dipping.
For those who may be interested I've published a H1 review of my 2025 watchlist. Cheers!
Change of CEO at Tracsis (LON:TRCS)
Wynnstay (LON:WYN)
Anyone know what happened? I cannot find any information.
Or is it a glitch with Tradingview?
Yahoo says it’s up 54%, LSE says 0.69%. Suspect it's a data feed problem. If you hold and it’s up at your broker SELL now.
If something like that happens try looking at the trades - you will find a rogue figure at 15 24 and then corrected from 561 to 361:
https://www.lse.co.uk/ShareTra...
ZIGUP (LON:ZIG)
great summary Roland
I am a big fan of zigup - i will give todays update a 6/10
there is nothing new here to worry me specifically - but the results reinforce the fact that the size of the fleet and the debt has gone up to deliver similar results. Thats aprobably over simplistic as there are many moving parts here (fleet value has incresed £200 mill!! thats a big jump in one year) - they are probably perhaps at peak point ref refinancing older vehicles here - although increases in the fleet size complicate the picture. It was previously all flagged up here albeit it would have been nice if they had been able to say debt has peaked and will drop - so would be nice to see estimate of debt at next year end - if anyone has details.
the metric going against it at present ref debt rising could quickly reverse if fleet value stops increaisng - or increases at much more modest rates - fleet value has increased by £200 mil and net debt has only gone up by £90 million - so they have maanaged to invest £110 million in net new fleet without using debt - not easy to get that wonga from down the sofa.
Overall i am 100%m happy to keep holding here at current levels and feel the share are still too cheap - they are trading below NTAV and the debt at 58% of the fleet value is not a worry (to me)
Any news onJames Fisher And Sons (LON:FSJ) ? Big fall today, and nothing on the RNS
Martin Ward, Zigup CEO, just spent £250k on shares. Hopefully he knows a bit about the company, so looks positive!
https://www.investegate.co.uk/...
Alumasc (LON:ALU) weakness lately, opportunity with update due soon?
Wow, JohnDoe, I admire your optimism! I am a big fan and long term holder of Alumasc (LON:ALU) , but my immediate thought when a small cap falls inexplicably ahead of a trading update is that it won't be good. I would love to be proved wrong and certainly all was going well at the half year results so fingers crossed!
I agree. With weakness everywhere in the sector the poster child for building products looks like its about to disappoint. One of my best performers of past 18 months - i should have top sliced. Lesson never learned.
Fund managers: I've long liked investing in fund managers as they tend to increase their AuM even during bad times, and their balance sheets usually support high dividends. Like Graham, I've also felt confident that active fund managers' valuations are at extremely depressed levels and will recover.
But I'm starting to question that view. In their recent results, Polar Capital said 'Actively managed equity funds have seen net outflows in seven of the past eight years, culminating in a record $450bn withdrawn in calendar year 2024.'' (Polar themselves have been the exception to that rule).
Also, why shouldn't actively managed funds be seeing good net inflows right now? FTSE100 is near an all-time high, same for S&P500, NASDAQ etc.
I am starting to think that maybe the popularity of passive funds and growth in private investment opportunities/attractiveness means there is now a permanent structural change in the industry which is going to significantly limit the upside for active managers?
I appreciate institutions and PIs might be parking more of their cash in interest bearing accounts right now which might unwind when interest rates fall - but maybe it will be passive funds that benefit?
Just some thoughts and keen to hear from others. I hold Polar Capital Holdings (LON:POLR) & City of London Investment (LON:CLIG) although my patience with the latter's low growth is wearing thin.
Share your frustrations - but there are so many anomalies out there. I too hold Polar Capital Holdings (LON:POLR) and some of its funds are fine others not. E.G. Polar UK Value Opportunity is not an opportunity at all - those it has improved recently but not enough. Schroders (LON:SDR) seems on the up but I cannot understand how it has so much debt on the balance sheet ? The top all round fund manager at the moment seems to be Artemis - but they are not listed!
Agreed. I think the trend away from active managed funds is accelerating. People are emboldened to take control of there own money by the information available on the net.
Verona Pharma (NMQ:VRNA) Yiannos strikes again! A big sMerck on investors faces although seems a bit cheap?
Good to see Hunting (LON:HTG) SP finally (?) taking an upward path. More to hear I'm sure on today's webinar. Welcome news also regarding an increase divi
And glad you call it the Gulf of Mexico, Roland. You'd be denied access to White House press briefings for that...
Finseta (LON:FIN)
Morning Graham
If you could find time to do a write up on this I’d be most grateful. It’s not been fully written up since Feb 24.
Thanks for all your great work!
D
System1 (LON:SYS1) probably correctly qualifies as a "falling star". As a holder I've been slow to react to the cautionary note in the April update and had hoped that this was already reflected in the share price, but alas no. The flip side is that despite their own caution they are confident in meeting their expectations for this year and are still targeting 15% revenue growth which isn't too shabby. Would be grateful for the team's thoughts.
I've actually been trying to top up my System1 (LON:SYS1) for the last hour+, without success.
I think the Q1 issue is isolated and the longer-term outlook is still good. It now seems I might not be alone in this opinion.
It's so frustrating, as I keep being told 'no counterpart for the trade could be found'. I can only assume that the morning's selling has dried up and everyone (or a whale) is now buying.
I couldn't get a price for System1 (LON:SYS1) online with AJ Bell but have just had a limit order executed. Only a small amount though but at least it has gone through
Looks like I was right; it's gone from nigh on 14% down at one point to just 6% down at the time of writing. I eventually got filled at 400p. -_-
Not surprised there is weakness for System1 (LON:SYS1) in signing up new customers, also getting more "consultancy" projects signed off, due to caution by advertisers from the Tariff announcements.
Broker has downgraded FY26 forecast I think?
However, I think the market has priced in a lot of the bad news already since the Tariffs announced. Not a surprise that advertising is struggling, with all the agencies reporting similar.
Still really cheap though. Only 7x-ish EV/EBITDA. With slow growth seeming to be one-off. USA still growing very strong, and that is the grand prize. Its a prime takeover candidate IMO by a US-based marketing company, who can bolt on System1 to their propositions AND have the ready made sales team to sell. 7x EV/EBITDA is a bargain from a US valuation perspective.
Only question now is whether we're going into a recession globally, and advertisers permanently cut back on spend. No TV ads, no need for System1 platform.
I continue to hold as I think companies will adapt to the "new normal" of Tariffs. Products still need to be sold, customers still need to be swayed. Their platform is good and in demand. This is a temporary blip. Unless... recession.
(I hold in the Boon Fund)
I'm starting to wonder why ZIGUP (LON:ZIG) is still a super stock. All indicators down again today not least the share price (I hold).
Glass is half full for me on ZIGUP (LON:ZIG) . There was a reduction in both revenue and profit expected as the price of used vehicles has normalized post COVID and this was to be expected. The core business of company outside of those vehicle sales continues to be robust and the cash flow and profitability is still strong (particularly when you look at the PE and ROE/ROCE.) I do wonder at some point if some PE company is going to be attracted to this as they would be able to use their funds to get cheaper debt and cream off the cash from it. Until then I'll happily take the 8% divi yield. Note I have held this since 2020 and am up around 100% even after todays fall.
Agree I think Zigup results looked pretty good - we know disposal profits have been volatile and will likely be difficult to predict going forward, but the core rental business is performing well. Might not be the world's highest quality company, but I think this looks attractive value trading below TNAV, on a PE under 6 and a yield of around 8%. As others have said, this would make a good target for private equity so wouldn't be surprised if it gets a bid if it stays down here.
ZIG . I own, but I'm in two minds. Bought in Jan 2021 at 270p. It has performed in-line with the All-Share (maybe a tad better as it has an above-average divvie).
I've given it a frownie face in my little notebook, so it's kinda half in the door, half out. Positives are low PE ratio, high divvie (looks sustainable so far) and high StockRank. They also have an integrated platform which they talk about in their webinars. The idea here is that it's a complete and convenient system for their customers, saving them from faffing around. It seems to be fairly well received, so maybe they can get a competitive advantage out of it.
Negatives are that they've really upped their share count (11%pa over 5-odd years, which is really quite something). Consequently, EPS has barely budged from 0.492p in 2015 to 0.540p in 2024. So I wouldn't be interested in it if I wanted it as part of a QARP portfolio.
So,I see good points and bad points and just stuck with it. I wouldn't blame anyone for bailing on it, though.
I think from memory the share count increase is entirely due to the Northgate acquisition of Redde in 2020 which was paid for in shares? Since 2021 the share count has been coming down slightly.
ZIGUP (LON:ZIG)
Negatives are that they've really upped their share count (11%pa over 5-odd years, which is really quite something). Consequently, EPS has barely budged from 0.492p in 2015 to 0.540p in 2024. So I wouldn't be interested in it if I wanted it as part of a QARP portfolio.
They most certainly have not upped the sharecount over the last 5 years -they have done the opposite practicably speaking - the sharecount (net of shares in treasury) has nicely decreased from the level it started at when the merged company came into existence in February 2020 - i would it was 246 million shares in issue - the shares in issue net of shares in treasury has decreased nicely and stocky confirms that fact if you check share count.
You may argue that shares in treasury could be used foor nefarious purposes - i suspect practicably spoeaking not cencelling thme gives them options - if they they wanted to acquire halfords and needed to issue some new shares - they have 21 mill doing nothing.
last year
The calculations above are based on the number of shares in issue at 30 April 2024 of 246,091,423 (2023:
246,091,423) less treasury shares of 18,981,862 (2023: 16,877,571).
this year
The calculations above are based on the number of shares in issue at 30 April 2025 of 246,091,423 (2024: 246,091,423) less treasury and own shares of 21,353,976 (2024: 21,748,799).
Consequently, EPS has barely budged from 0.492p in 2015 to 0.540p in 2024. So I wouldn't be interested in it if I wanted it as part of a QARP portfolio.
and comparisons here prior to 2021 year are pointless - in 2020 there was a merger of near equals that completely changed all financials. Note the old redde business that had the same ticker was the much more spivvy side of things (claims management) so would have trdaed on lower pe - so i would expect prior metrics for that entity to be better as there was little certainty their profits were sustainable.
If you start your comparisons with 2021 the first year of the combined entity you would see there is very nice increase over that time in earnings for the £65 mil profit then - albeit slightly flattered when second hand vehicle prices were at silly levels - yes second has prices would have been elevated as far back as 2022.
ZIGUP (LON:ZIG)
I'm starting to wonder why ZIGUP (LON:ZIG) is still a super stock. All indicators down again today not least the share price (I hold).
it will likely take time for latest financials to feed through the system - so keep an eye on rankings here when they update soon. I supect stocky rankings may not like the jump in debt. You have to factor in how much they benefitted from elevated used prices and the fact they need to invest now - you arent going to have no issues with stock on pe 7 or below.
JET2 Down 5% today. Revenues, PBT and passengers all up. Stock rank of 94, PE of 9. Go figure.
I've held Jet2 (LON:JET2) for a while now and I am always shocked by the volatility after each announcement (mostly negative) on slightly conservative outlook messages that they seem to make every time. At the end of the day it must be very difficult to forecast how many people are going to go on holiday given it is discretionary spend. However, I continue to hold on the basis that majority do, they could get a lift if people chose to go to EU rather than USA and they seem to be a very well run business. I'm surprised that they are so volatile, based on the value of this stock and the quality of their business, it's a long term hold for me.
Wisdomtree Commodity Securities (LON:COPA) is up 12% today, yet the copper price is down, does anyone know what is going on?
Copper prices jumped after the UK market closed - so this is playing catch up from yesterday to factor in the price move.
Really, that is not showing on commodity live prices on IG.
I see the high grade copper price did shot up yesterday.
Not sure about IG I don't use it - but at 17.45 UK time Copper futures were trading around $5.00 and jumped to around $5.60-5.80 after the Trump tariff news
Copper futures jumped in response to Trump's new threat of 50% import tariffs on the metal.
I`ve read that copper prices spiked on US COMEX yesterday but copper prices fell on LME and SHFE, so this may explain the anomaly.
Thanks, it is only the high grade copper that spiked up, initially l was just looking the copper prices. Seems Wisdomtree Commodity Securities (LON:COPA) must be based on the high grade copper.
Sensing disappointment in the Jet2 (LON:JET2) results as we are down 4% on open when I thought the results cracking,
Yes the EPS figure is well above broker expectations meaning a further FY26 uplift is likely.
Wondering if market spooked by cash going down (which I think is capex related) or comment about competitive pricing.
Could be a good buying opportunity - the p/e ratio here is modest for a company that continues to deliver well.
Cash went down but borrowings went down by a lot more so I don't see any issue there on a net basis.
SRT Marine Systems (LON:SRT)
FY25
FY24*
% change
Group Revenue
£77.5m
£14.8m
423%
Profit / (Loss) before tax and exceptional item
£4.4m
£(14.4)m
n/a
Gross cash balance (excluding restricted cash)
£4.2m
£2.8m
50%
Highlights
· $213m system contract signed with the Kuwait Coast Guard in October 2024.
· System contracts with an aggregate of £320m now active and being implemented.
· Current new system prospects validated pipeline valued at up to £1.4bn.
· New NEXUS transceiver expected to start shipping in H1 FY26.
· Financial guidance reintroduced by Cavendish.
Hopefully the revised guidance will lead to a rerating on Stocko.
SRT Marine Systems (LON:SRT) I hold
Jim, I was hoping, as I think you may have been, that the team might examine the implications of this trading update. But no, yet again SRT is stuck in the Stocko jam tomorrow mind set and ignored. Being a global leader in a niche is apparently not worthy of attention.
Rwh3ue
C’est la vie. Don’t be bitter – just rake in the profits! Maybe when it changes from
Technology Highly Speculative Small Cap Momentum Trap
to
Technology Jam Today Large Cap Super Stock
there will be more interest shown 8-)
"Maybe when it changes from"
Maybe *if* it changes!
Yes, if it transitions to jam today then I'm sure they'll be more commentary shown. Of course some jam tomorrow companies come good. The main educational point I've picked up from Stockopedia though is that as a basket jam tomorrow will under-perform jam-today. Maybe you have the insight required to separate the wheat from the chaff, but I certainly don't, and I wouldn't expect the commentary team to try to attempt it either.
Just picking a few jam tomorrow names at random that I remember seeing in the comments on this board - how has a basket of Angle (LON:AGL), SIMEC Atlantis Energy (LON:SAE) and SRT Marine Systems (LON:SRT) performed against a random basket of top-decile stockranks over the last 10 years?
ISAallowance
SRT Marine Systems (LON:SRT)
"Maybe when it changes from"
Maybe *if* it changes!
Please note the 8-) at the end of my last post.
For info, most of the stocks I hold are screened from Stocko (previously Company Refs) and I now mainly concentrate on Super Stocks (including Jet2 (LON:JET2) . That does not preclude me looking further afield. I’ve had the ‘it’s done nothing for 20 years’ debate here before and I believe I responded along the lines of ‘when the facts change I change my mind ….’
Today’s figures and associated commentary elsewhere show the facts have changed and IF Stocko analysis changes you may revise your view.
Hi Graham
Also a trading update from Cairn Homes (LON:CRN) that looks positive at first glance.
timarr
thanks timarr! We'll get that added in.
I'm with you there Timarr. Bought this just below the £1 , about 18 months ago ,and it does what it says on the packet. Probably the greatest growth rate is behind us ,but where can you buy a £1B + co ,on p/e of 10 - growth of 10% and 5% div. well covered ,and 28% debt. I have it as my second biggest holding ,and hav'nt considered selling yet . Tony
Impax Asset Management (LON:IPX) AuM up 3% over 3rd Q. Is this beaten up (though up 30% over last few months) manager showing signs of recovery.
This was my first reaction but increase in AUM at Impax Asset Management (LON:IPX) was due to an acquisition, not organic growth.
David
Works both ways. A big decrease earlier was due to the loss of St James. Impax Asset Management (LON:IPX)
Yes, but the loss of St James is part of everyday business i.e. organic whereas an acquisition is an external boost to sales, so I don't think the two are comparable. When (if) Impax Asset Management (LON:IPX) genuinely returns to organic growth then we can get more interested.
Yes and outflows still heavy - largely offset on this occasion by strong markets movements, but can't rely on that every quarter.
AUM +3% in Q3 on strong markets and acquisition
"we would again highlight Impax’s deeply discounted PER in comparison to sector peers and believe it to be a robust business with a huge opportunity. Our DCF valuation remains at 400p / share, more than twice the share price."
https://www.equitydevelopment....