Daily Stock Market Report (Wed 9th September 2026) - VCT, CNS, GDWN, MAB1, ANP

Good morning. The US has escalated its trade war with Canada by banning the import of certain Canadian products, including dairy, motorcycles and whisky. The US is also said to have launched additional 50% tariffs on certain other Canadian exports.
In the Middle East, the US claims to have “destroyed” a number of Iranian oil tankers following strikes on a US warship. However, oil prices have stayed below $100, probably aided by the knowledge that an increasing amount of oil is exiting the Strait of Hormuz.
Closer to home, a visit by US envoys to Ukraine did not produce any apparent breakthroughs and was followed by renewed Russian attacks on Kyiv overnight. The US team also visited Russia, following which Donald Trump is said to have spent around an hour on the phone with Vladimir Putin.
Finally, Apple’s new CEO John Ternus is expected to unveil the company’s first foldable phone at a launch event later today. It’s expected to be priced at around $2,000. Also in tech, Anthropic is reported to have withheld its latest model from testing by the UK’s AI Security Institute (Aisi) ahead of its release, continuing a trend of restricting access to top models for non-US nationals.
Overnight market movements:
The FTSE is down 0.4% at 10,770
S&P 500 is up 0.1% at 7,684
Brent crude (November) is up 1.1% at $98.97/bbl
Gold is up 0.3% at $4,400/oz
Bitcoin is up 0.5% at $78,868
Mark Simpson joins me (Roland) today.
Today's report is now complete. See you in the morning!
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Aberdeen (LON:ABDN) (£4.56bn | SR87) | Torbjörn Magnusson will join the Board as Chair-designate with effect from today. He will become Chair following regulatory approvals. | ||
Energean (LON:ENOG) (£1.46bn | SR33) | H1 production -10% to 124 kboepd due to a 41-day mandated shutdown. Excluding this, production has averaged 135 kboepd, in line with FY26 guidance. H1 profit after tax +45% to $160m, with EPS +50% to $0.90. Outlook: 2026 guidance reiterated, with exploration and decommissioning expenses reduced. | ||
Playtech (LON:PTEC) (£1.25bn | SR72) | Playtech notes that the Spectrum Report corroborates or fails to rule out several of Black Cube’s key claims. Playtech is currently in a legal dispute with Evolution AB. | ||
| Goodwin (LON:GDWN) (£1.16bn | SR27) | Response to Press Speculation & Sale of Mechanical Engineering Division | Goodwin confirms it has agreed to sell “a substantial part of its Mechanical Engineering division” to a Cerberus Capital Management (private equity) for £1.1bn. “Goodwin intends to pay a significant proportion of the net cash sale proceeds … to its shareholders”. | AMBER/GREEN ↑ TAKEOVER (Mark - I hold)
The market clearly doesn’t like the price achieved for the sale of the Mechanical Engineering Division. However, this reaction has led the market to value the remaining businesses at a negligible amount (including a refractory business that generated £15.7m operating profit last year). |
Victrex (LON:VCT) (£757m | SR93) | Strong momentum has continued into Q4, with growth driven by Aerospace, Value Add Resellers and Electronics. FY26 outlook: “Underlying PBT now expected to be in the range of £45m to £47m, ahead of prior guidance of £42m to £44m.” | AMBER/GREEN ↑ (Roland) In May Victrex was downgrading guidance, in July the company was in line, and today it is ahead. If Victrex can now start to deliver margin improvement alongside volume growth, then I think this return to positive momentum could support significant further upside despite the recent c.70% share price growth. After all, this business used to generate double the current level of earnings. While the current valuation looks up with events on 23x FY26E EPS, I think it’s reasonable to take a broadly positive view at this early stage in the group’s recovery. | |
WAG Payment Solutions (LON:EWG) (£696m | SR51) | H1 revenue +10.7% to €179.5m with adj EBITDA +10.5% to €70.6m and pre-tax profit down 46.5% to €8.4m. Total active trucks rose by 7% to 334.8k, with average number of products per truck +0.1% to 2.7. Outlook: confident in delivering FY26 guidance. Adjusted cash EBITDA guidance narrowed to €110m to €115m (prev. €105m to €115m). | ||
Harworth (LON:HWG) (£577m | SR30) | Total accounting return -3.7%, with EPRA NDV per share -4.3% to 214.8p since year end. Portfolio value -1.2% to £301.4m since year end. Response to offer: Board confirms its unanimous rejection of the unrecommended offer from Peel, highlighting that it is at a 19.7% discount to EPRA NDV of 214.8p per share. | TAKEOVER | |
GYM (LON:GYM) (£341m | SR66) | Revenue +10% to £133.1m with adj pre-tax profit +31% to £6.4m. Adj EPS +21% to 2.9p. Average revenue per member per month +5% LFL. Outlook: on track to deliver 3% LFL revenue growth. Expect full-year adj EBITDA to be at the top end of the current analysts’ forecast range. | ||
Property Franchise (LON:TPFG) (£287m | SR77) | H1 revenue +7% to £43.3m with adj pre-tax profit +7% to £15.5m and adj EPS +8% to 19.8p. Managed rental portfolio remains at c.149k properties (H1 25: c.150k) following implementation of Renters’ Rights Act. Outlook: entered H2 with good momentum. Expect full-year trading to be in line with expectations. | ||
Mortgage Advice Bureau (Holdings) (LON:MAB1) (£283m | SR61) | H1: now expects adj pre-tax profit to be c.£14.8m (prev. £14.6m). FY26 outlook: reduction in interest rates and recovery in purchase activity “has not materialised”. Now expects FY26 adj pre-tax profit to be c.£38m (previous consensus: £43.4m). | PROFIT WARNING (AMBER ↓) (Roland) It’s tempting to assume that housing market conditions are to blame for today’s warning, but reading this update (and July’s commentary) more carefully suggests to me that the main reason for this downgrade is the underperformance of the group’s Fluent subsidiary, which was acquired quite expensively in 2022. The means the issue could be an isolated problem and the core business might still be trading largely in line with expectations. I think it’s disappointing though, especially as the deal was funded through both new equity and debt. With no improvement to housing market conditions expected this year and a new headwind holding back group results, I’m turning neutral today despite the apparent cheapness of this stock. I think Contrarian styling is apt, but I’d like a little more clarity before committing to a positive view. | |
ASA International (LON:ASAI) (£253m | SR70) | H1 underlying net profit +42% to $34.3m, excluding favourable one-offs. Return on average equity increased to 55%, from 49% in H1 25. Gross loan portfolio +12% YoY to $603.9m. 2026 outlook: expect underlying net profit to be “in line or slightly ahead” of FY26 consensus of $70.2m. | ||
Sovereign Metals (LON:SVML) (£176m | SR9) | This study shows the Kasiya resource can potentially deliver rare earths. It’s estimated that for c.US$29 million of additional capital, the development could potentially add c.US$722 million of pre-tax value at a c.151% rate of return, with payback in around 18 months. | ||
Frontier Developments (LON:FDEV) (£159m | SR88) | FY Revenue +16% to £104.8m, Adj. Op Profit +62% to £21.4m, EPS +76% to 74.6p. Cash £44m (FY25: £42.5m). £5m special dividend in October. David Braben will transition to a Non-Executive Director position on 1 October 2026. Confident in delivering FY27 in line with expectations. | ||
Personal group (LON:PGH) (£130m | SR71) | Extending its strategic partnership with healthcare services and health cash plan provider, Simplyhealth. Simplyhealth's On Demand services will be integrated into Hapi, Personal Group's employee benefits platform. | ||
Anpario (LON:ANP) (£109m | SR79) | H1 Revenue +7% to £24.3m, EBITDA +22% to £5.0m, PBT +11% to £3.8m. Cash £11.0m (31 Dec: £12.4m) after £2.1m of share buyback in period. Softer start to second half sales performance. Iran conflict impacting Asia, with lower sales compared to the prior year, which has softened the start to the second half for the Group. We expect these challenges to continue for the remainder of the year. House broker Shore Capital leaves 2026 forecasts unchanged. | AMBER ↓ (Roland) [no section below] There's no change to forecasts from the company's house broker today, but these results don't mention full-year expectations and suggest management are remaining "optimistic" despite difficult macro conditions that are expected to persist in H2. In March I moved down one notch to AMBER/GREEN to reflect expected slowing earnings growth. My impression now is that there may be an increased risk of a miss to full-year forecasts due to a weaker second half, so I'm going to switch to a neutral view. Greater research into the company's end markets might allow a higher degree of conviction here, but in the absence of this I think the current valuation looks about right to me, especially as FY27 forecasts suggest minimal earnings growth next year. | |
Made Tech (LON:MTEC) (£68.7m | SR74) | Has been selected as one of a list of suppliers to three lots under the Met Office's new Delivery Partnerships Framework 2. | ||
James Cropper (LON:CRPR) (£54.7m | SR96) | Expects full year trading to be in line with market expectations. | ||
Corero Network Security (LON:CNS) (£43.5m | SR23) | Revenue +42% to $15.5m, EBITDA $2.6m (25H1: $1.4m LBITDA), PBT $1.42m (25H1: $2.36m LBT). Net Cash $2.1m (25H1: $3.1m). Based on a strong start to H2 2026, recent customer wins and an improving pipeline, management now expects Corero to exceed market expectations for revenue and significantly exceed market expectations for EBITDA for FY 2026. | AMBER ↑ (Mark) | |
Amigo Resources (LON:AMGO) (£35.2m | SR83) | Independent laboratory testing of selected material has returned combined PGM values of 6.94 - 7.07 ppm across the tested PGMs. Amigo's geological team has completed the initial geological reconnaissance programme across 13 historic mine-waste dumps. | ||
Pebble Beach Systems (LON:PEB) (£32.9m | SR80) | H1 Revenue +10% to £6.5m, Adj. EBITDA +25% to £2.5m, Adj. PBT +73% to £1.9m, Adj. EPS +88% to 1.5p. Net Debt excl. Leases £0.8m (25H1: £3.4m). Trading since June has been in line with management expectations. Looking ahead over the remainder of the financial year, Pebble looks very well-positioned to meet our forecasts. | ||
Carclo (LON:CAR) (£27.3m | SR53) | Underlying operating profit and return on sales remain in line with management's expectations. | ||
Nexteq (LON:NXQ) (£27.1m | SR74) | H1 Revenue -34% to $26.7m, Adj. LBITDA $2.8m (25H1: $1.9m EBITDA), Adj LBT $4.0m (25H1: $0.9m PBT). Net Debt $1.4m (25H1: Net Cash $25.0m). FY 2026 trading guidance remains in line with Management's expectations, but requires Two significant gaming orders to be secured. Planned Taiwan office move will not go ahead. Agreed to sell the property. | ||
Light Science Technologies Holdings (LON:LST) (£17.6m | SR12) | Passive Fire Protection division has secured approximately £0.8 million of additional business since the Company's PFP Division trading update released on 24 June. | ||
GreenRoc Strategic Materials (LON:GROC) (£12.7m | SR28) | Seven holes have been completed from two drill pads, Pad 1 and Pad 3, targeting the northern extension of the graphite orebodies. | ||
Windar Photonics (LON:WPHO) (£11m | SR17) | CFO Søren Belmar is to step down with immediate effect. |
Roland's Section
Victrex (LON:VCT)
Up 15% at 1,004p (£m) - Pre-Close Trading Update - Roland - AMBER/GREEN ↑
Victrex plc, the innovative global leader in high-performance polymer solutions, today announces a pre-close trading update for the year ending 30 September 2026.
Today’s update from Victrex is brief but appears to solidify a change in trajectory for this chemicals business, with an upgrade to full-year profit guidance.
Here are the key points:
Strong Q3 momentum continued into Q4, with good demand in Aerospace, Electronics and Value Added Resellers (where Victrex sells bulk PEEK to other manufacturers).
Completed a 10% reduction in headcount, with initial benefits in Q4 and expected annualised savings of at least £10m expected from FY27.
Completed disposal of US Kleiss Gears business, recording a loss on disposal of c.£3m.
Outlook: the board now expects FY26 underlying pre-tax profit to be £45m to £47m (previously £42m to £44m)
Updated EPS estimates: I don’t have access to any updated broker forecasts this morning, but some number crunching gives me a revised FY26E EPS estimate of 41-42p. That lifts the stock’s forward P/E of around 23x after this morning’s gains.
Roland’s view
I have to hold my hands up and admit that we may have missed the turning point for Victrex earlier this year.
Until quite recently, the trend at Victrex was persistently negative. The shares had been falling for five straight years…
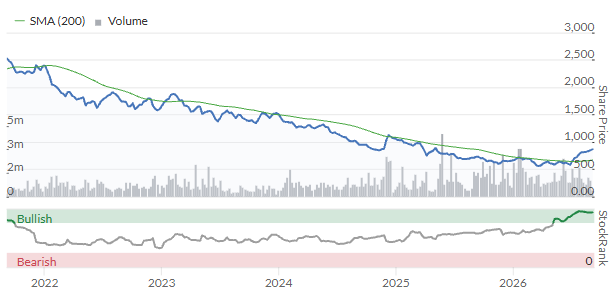
… while repeated profit warnings had seen earnings estimates halve over the last 18 months:
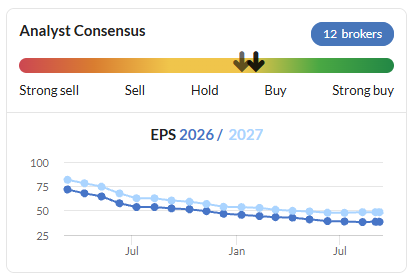
However, the picture appears to have changed over the last four months:
11 May: Our last coverage was of May’s half-year results. At that time, I moved to AMBER/RED following what appeared to be another profit warning, with pre-tax profit downgraded to £42-44m versus previous consensus of £46.6m.
7 July: Victrex’s third-quarter update reported stable selling prices and included a key phrase suggesting performance might be stabilising: “momentum continues in Q3: full year guidance maintained”.
With hindsight, it looks like I was too cautious in May and then did not spot the significance of the July update.
However, the clues were in the data and the StockRanks did spot the opportunity.
Ed has talked about the significance of StockRank jumps recently. Here’s another example – Victrex’s StockRank jumped and then started trending higher, right before the share price took off:
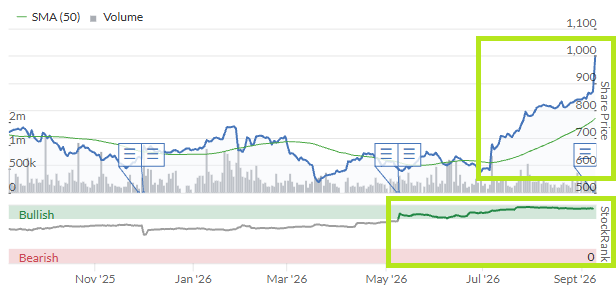
Victrex’s share price has now risen by 70% since the company’s Q3 update on 7 July. Today’s upgrade suggests that the company’s previously-negative earnings momentum may now have turned positive.
If this new momentum can be maintained, then further upgrades could be possible. The big question now is how much of the recovery has already been priced in.
That is a difficult question to answer. While the shares are still trading >50% lower than five years ago, Victrex has lost a lot of its previous profitability over this period. Margins have been compressed and much of the volume growth reported has been in the lower-margin VAR business – essentially bulk sales of raw material, rather than finished parts.
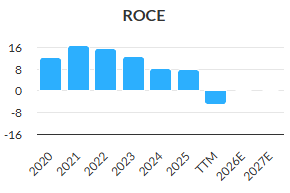
Consensus forecasts don’t yet reflect this, but I expect to see a sizeable dividend cut this year. The payout remains uncovered by earnings and the group’s debt levels (while manageable) have been rising.
When broker Singer Capital initiated coverage in August, they set a 970p price target and forecast a 77% dividend cut to 13.4p.
The share price is 1,004p as I type, so by some measures at least we might argue the valuation is up with events.
Personally, I think there could be some further upside to this price target on a medium-term view, if margins and volumes can return to growth. After all, Victrex used to routinely report earnings of c.80-90p per share. The shares could still be cheap at current levels.
The question is whether past profitability (or better) is still achievable in an evolving market for PEEK. I’m not sure, but I think it’s reasonable to believe Victrex could once again become a larger and more profitable business after a cyclical slowdown across the chemicals sector.
Victrex has scheduled a Capital Markets Day on 24 September at which CEO Dr James Routh plans to flesh out his plans for the business and his view on growth opportunities.
I’m going to move our view to AMBER/GREEN to reflect the sharp improvement in momentum and expected improvement in profitability from 2027 onwards. I acknowledge there’s some valuation risk here, but I think this remains a decent business.
Mortgage Advice Bureau (Holdings) (LON:MAB1)
Down 19% at 398p (£233m) - Trading Update and Revised 2026 Expectations - Roland - AMBER ↓
Today’s update gives with one hand but takes with the other. While this franchised mortgage broking business has upgraded H1 profit guidance, it has also made a substantial cut to full-year 2026 profit guidance.
Let’s take a look.
Half-year update: this relates to the six months to 30 June 2026.
On 23 July, MAB nudged up its H1 guidance to indicate that adjusted pre-tax profit for the period would be £14.6m (H1 2025: £14.5m).
The company has now completed its half-year reporting process and expects to report adj PBT of c.£14.8m, slightly higher.
Current trading and outlook
This is where the problems start. MAB has cut its full-year profit guidance by 12% versus consensus:
… the Group now expects Adjusted profit before tax for the year ending 31 December 2026 of approximately £38.0m. This compares with current market consensus of £43.4m.
A number of reasons are given for this, some of which relate to market conditions and some of which are company-specific issues:
Housing market: MAB says that earlier this year, interest rates were expected to fall and house-buying activity was expected to increase. Neither of these things have happened. The company cites UK housing market data showing that purchase transactions were 3% lower in the seven months of 2026, while mortgage approvals for house purchases were 15% lower in July than one year earlier.
Problem acquisition? A “material proportion” of the growth expected in 2026 was due to come from Fluent (acquired in 2022). This hasn’t happened; management says that “delivery against Fluent’s strategic plan has been slower than anticipated”.
As a quick recap, Fluent is an online-focused lending intermediary that specialises in areas such as second charge mortgages and bridging loans. MAB paid £72.7m for 75.4% of Fluent in 2022, when it was expected to have generated £4.2m of EBITDA.
What’s the real problem?
We all know housing market activity is soft. I would be surprised if it has taken until September for MAB to factor this into its forecasts, especially as the company said in July that it was “not assuming an improvement in housing transactions” while macro uncertainty continued.
The numbers provided today suggest to me that the main reason for this profit warning is Fluent, which looks to have become a problematic acquisition.
Fluent: M&A gone bad?
The acquisition of Fluent was a big deal for MAB in 2022, requiring a £40m equity placing and additional debt.
The purchase was priced on a trailing FY22 EV/EBITDA multiple of around 23x (i.e. it looked expensive), so there was clearly an expectation of strong growth from Fluent.
Unfortunately, Fluent doesn’t seem to have delivered as hoped:
2023: pre-tax loss of £1.1m
2024: adjusted pre-tax profit of £4.3m
2025: not specified, but we are told that Fluent “returned to a clear growth trajectory”.
That brings us up to today. We’re told that delivery against Fluent’s plan has “been slower than anticipated” due to delays with expected new lead sources:
Following a steady recovery in business performance and the continued development of its mainstream first-charge mortgage proposition, Fluent was expected to deliver a significant step-up in 2026, supported by new contractual lead flows. However, the launch of these arrangements has been delayed.
As a result, the company has incurred “pilot costs” without the expected contribution to revenue.
Management provides some frustratingly vague profit guidance for Fluent today:
Fluent’s expected contribution to Group Adjusted profit before tax for 2026 is approximately £5m lower than previously anticipated.
This tells us what the shortfall is expected to be, but it doesn’t tell us what the previous expectation was for Fluent. Was Fluent even expected to make a profit in 2026? We can’t be sure.
I tend to view a deliberate lack of disclosure as a sign that the underlying facts aren’t very positive, so I suspect Fluent’s contribution was already expected to be quite modest this year.
I think Fluent has triggered today’s warning: MAB has cut group level adjusted pre-tax profit guidance by £5.4m today while also cutting pre-tax profit guidance for Fluent by around £5m.
Based on these numbers, I think it’s fair to assume that the underperformance of Fluent is the main reason for today’s profit warning, not difficult housing market conditions.
Updated forecasts: Despite being a small cap, none of MAB’s three brokers make their coverage available on Research Tree, so I don’t have access to any updated forecasts today.
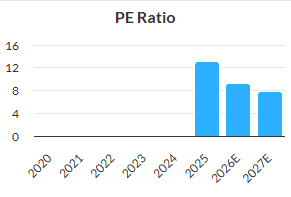
Using the previous consensus forecasts available on MAB’s website and a guesstimated tax rate, my number crunching gives me a revised FY26E adj EPS estimate of around 47.5p per share, around 10% below the previous estimate of 52.6p.
If I’m right, that leaves the stock on a FY26E P/E of around 8.4x following today’s fall – in line with the valuation prior to today:
Roland’s view
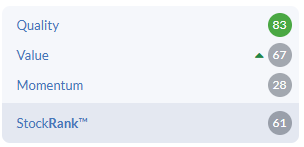
Graham cut his view on MAB to AMBER/GREEN in July, citing the demanding H2 profit growth and heavy H2 weighting. This turns out to have been a good call. The StockRanks have also moderated, suggesting a Contrarian view:
In some ways, I think it’s encouraging that today’s warning appears to be largely driven by underperformance at Fluent: it suggests that the core MAB business is still performing largely as expected.
On the other hand, it’s disappointing to see that management has potentially allocated capital quite poorly by buying a business that is still not delivering as expected, four years after its acquisition.
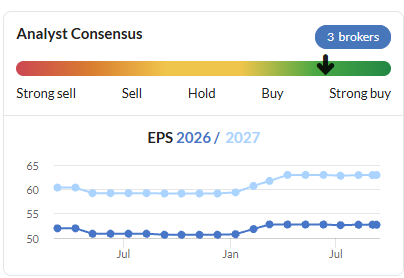
Until today, the trend in earnings forecasts has been flat or positive over the last 12 months, so a positive view has made sense:
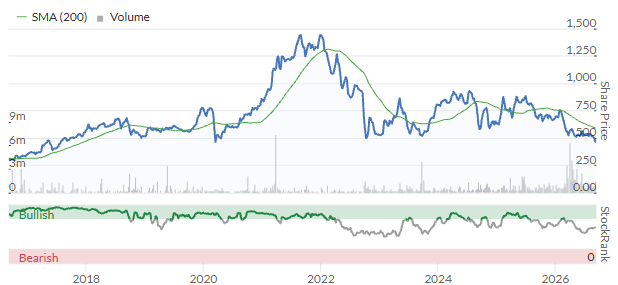
I think it’s also interesting that the shares are now trading at levels first seen nine years ago, since when revenue has doubled and operating profit has risen by c.70%:
In its 2025 results, MAB said its market share of new mortgage lending was 8.4%, while its share of Product Transfers was 3%.
That’s a fairly large chunk of the UK mortgage market.
If or when housing market activity does improve, it’s not hard to imagine MAB being a major beneficiary of increased activity, especially as new lending is more likely to include an insurance policy, boosting commission income. The company’s quality metrics remain strong and have historically supported strong cash generation:
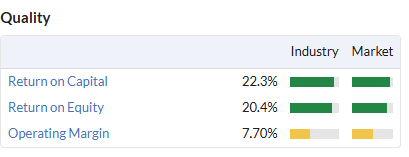
Are the shares cheap and good enough to allow me to maintain our AMBER/GREEN view following today’s profit warning?
Perhaps they are. But with no improvement in housing market conditions on the horizon and continued underperformance from an expensive acquisition, I’m going to turn neutral to reflect the increased level of uncertainty here.
If the half-year results provide greater clarity on trading and the outlook for 2027, then I would hope we might be able to move back to AMBER/GREEN again fairly soon.
Mark's Section
Corero Network Security (LON:CNS)
Up 15% at 9.81p (£43.5m) - H1 2026 Interim Results - Mark - AMBER ↑
Corero describes itself as “the distributed denial of service ("DDoS") protection specialists and champion of adaptive, real-time service availability”. So it is perhaps not surprising that they are trading well in an environment where cybersecurity is facing an increased focus.
The headlines read well, with a significant increase in revenue and a shift back into positive EBITDA:
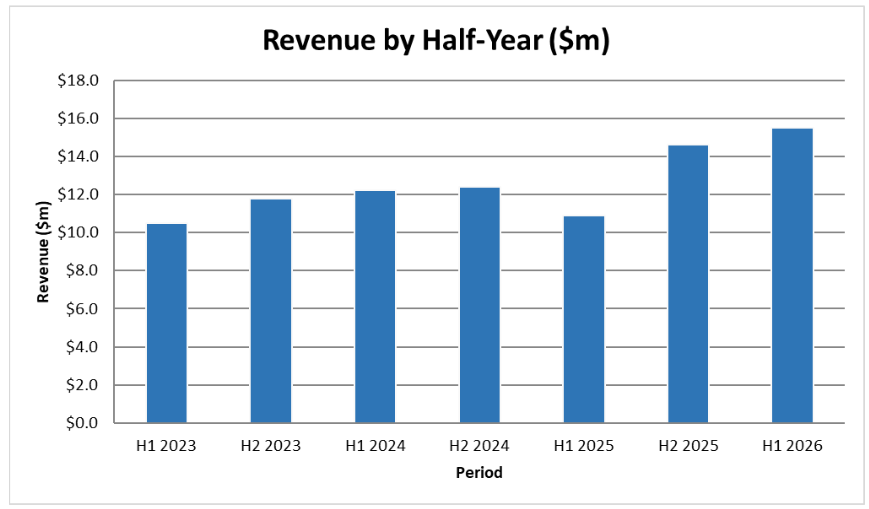
· Strong revenue growth of 42% to $15.5 million (H1 2025: $10.9 million)
o Underpinned by new customer wins and contract expansions
· EBITDA improved to $2.6 million (H1 2025: loss of $1.4 million)
· Order intake increased 14% to $14.3 million (H1 2025: $12.5 million)
o Year-on-year progress highlights ongoing traction with channel partners and ongoing expansion of product offering
· Annualised Recurring Revenues ("ARR") grew by 12% to $24.1 million (H1 2025: $21.6 million)
· Continued high customer retention at 96% further underpins Corero's market leading position (H1 2025: 98%)
However, a couple of things stand out from this. The first is the lack of mention of profits or cash in the highlights, which suggests the company may be less focused on these measures than I would like.
Scrolling to the end of the Chief Financial Officer's Review, I find that Positive EBITDA does indeed turn into positive PBT:
Profit before taxation for H1 2026 was $1.4 million (H1 2025: loss $2.4 million). The reported earnings per share was $0.3 cents (H1 2025: loss $0.5 cents).
However, cash is down, with the blame put on the shift to a subscription model:
Cash and cash equivalents as at 30 June 2026 was $2.1 million (H1 2025: $3.1 million), a reduction of $1.9 million in the six-month period (H1 2025: $2.2 million decrease) as the Group continues to navigate the changing cashflow profile from the uptake of subscription services. Receivables have increased to $11.1 million as at 30 June 2026 (H1 2025: $8.7 million) as a result of revenue growth.
Recurring Revenue:
ARR is said to have grown by on 12% compared to the headline revenue figure of 42% growth. There’s not enough in here to be immediately concerned. However, cash flow should remain under close watch.
What the ARR growth does in fact reflect is that this is not so much a strong H1, but a very weak H1 comparator from last year:
EBITDA was actually down on H2 last year:
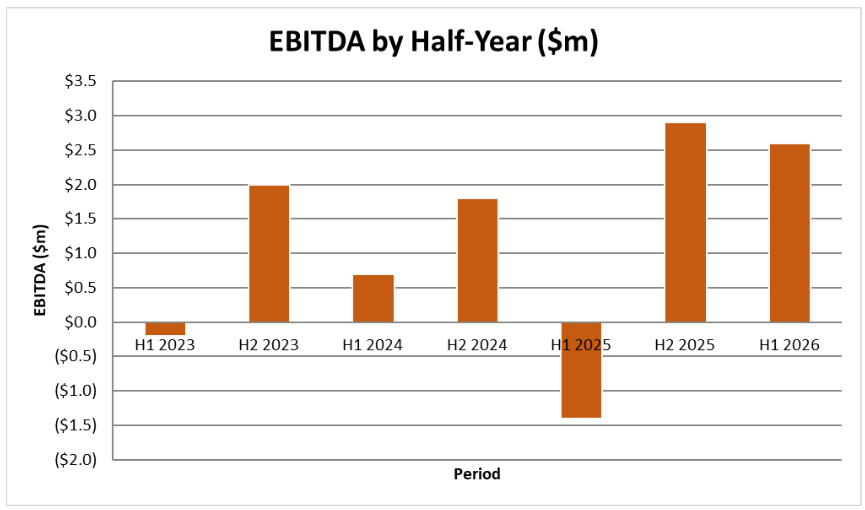
Corero does indeed appear to have some seasonality. However, management appear to have never directly addressed why this is, apart from saying “customer buying patterns”. The only thing I can think of is that Corero's customer base run annual capex and network-capacity planning cycles tied to a calendar fiscal year, and that tend to finalise and sign larger infrastructure and security contracts later in the year. The shift to more recurring revenue contracts should reduce this seasonality effect.
Outlook:
The seasonality effect on non-recurring contracts is still strong enough for them to upgrade expectations, though:
Looking ahead to the remainder of the current financial year, based on a strong start to H2 2026, recent customer wins and an improving pipeline, management now expects Corero to exceed market expectations for revenue and significantly exceed market expectations for EBITDA for FY 2026.
Forecasts:
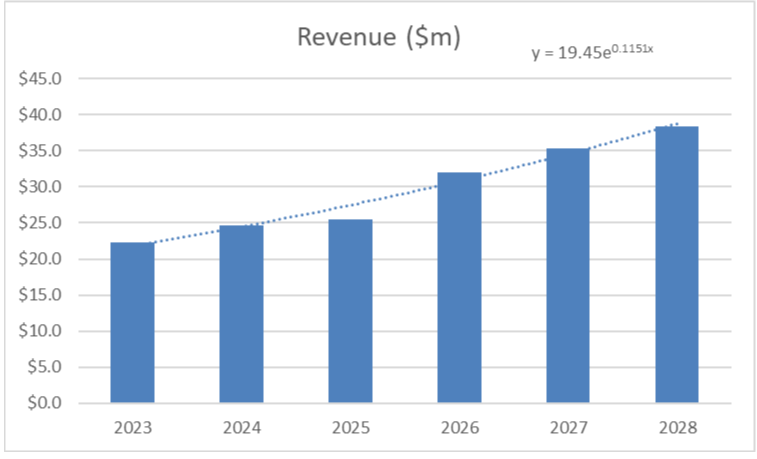
In response, Canaccord increase their Sales number from $29.0m to $31.9m and adj. EBITDA from $3.1 to $5.3m. EPS goes from break-even to 0.5c. Zeus move to a very similar $32.1m, $5.3m and 0.5c.
Here’s what that looks like:
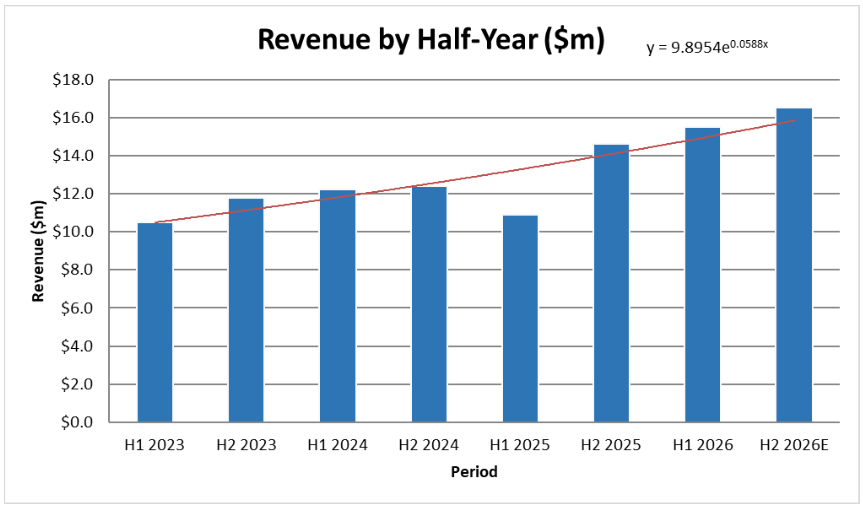
So this new consensus is in line with longer-term trends. Perhaps we shouldn’t be surprised by the upgrade.
The brokers also upgrade outer years in line with these longer-term trends:
Valuation:
Zeus don’t give an explicit valuation, but say that:
The share price has come off unduly over the summer and at the current 8.5p our upgraded forecasts now see the stock trading on an EV/EBITDA of just 10.2x CY26 and 8.2x CY27. We continue to feel that it offers excellent value for its growth opportunities and security, compared to the CY26 multiples of other London cybersecurity stocks; NCC Group on 11.2x and Intercede on 10.7x (CapIQ 9Sept26).
Canaccord put an increased 21p price target on the stock, saying::
On 1.5x CY27E EV/Sales & 2.2x EV/current ARR the shares are in our view materially undervalued with growth-adjusted valuations of listed comps suggesting >4x EV/S.
I’m not a huge fan of ARR valuations. There are too many variables that impact profitability beyond ARR for this to be a great comparator amongst companies IMO.
Overall, revenue is forecast to grow 12% pa over the next couple of years, and EBITDA by a similar amount. This does appear to be in line with long term trends so perhaps one could argue that say 8x EV/EBITDA is fair value. However, offsetting this Canaccord are forecasting EBIT and EPS to be flat, and capex is running ahead of depreciation and amortisation. I think I would struggle to pay more than 8x on this basis. This would be around £36m EV on a forward basis.
The current £52m market cap based on a 10p share price therefore doesn’t look like great value at 11x EV/EBITDA, even if we assume that some of the working capital outflow will reverse into year-end, making the EV £3m or so lower.
Something the StockRanks back up:
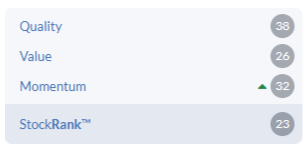
Although I’d expect them to improve when stronger FY26 numbers get processed next year, instead of unusually weak FY25.
Mark’s view
I think the Stock Rank and our previous view of RED may be a little harsh here. This is a reasonable business growing revenue at low-teens percentages. It has net cash which helps investors to take the long-term view. However, there doesn’t appear to be a huge amount of operational gearing, and brokers are forecasting this revenue growth to merely offset cost increases leading to flat EPS going forward.
Given the scale of the upgrade in EBITDA today, this could be the start of a more positive trend for the company. However, I note that this upgrade merely returns forecasts to longer term trends. The next upgrade would require a genuine step change in performance, that I don’t think is guaranteed.
A forward EV/EBITDA of 11 doesn’t look great value for a business that capitalises a lot of costs, but cybersecurity is an area that is gaining increasing attention amongst investors. I think for this reason, combined with the scale of the upgrade, I may be able to stretch to an AMBER view.
Goodwin (LON:GDWN)
Down 4% at £151 (£1.16bn) - Response to Press Speculation & Sale of Mechanical Engineering Division - Mark (I hold) - AMBER/GREEN
This has been one of the most fascinating market situations of late.
In a move that shocked many, on 7th August the management of Goodwin positioned itself to sell “a substantial portion” of its Mechanical Engineering division. Given this is a family-controlled business that operates with a very long-term horizon, this opened up a huge range of possibilities.
The rationale was that the management had received interest at a level they couldn’t ignore. However, the eagle-eyed will have spotted that key Goodwin family members had recently moved their residency to locations with more favourable tax regimes. It was not clear what the major driver of the sale was.
On August 28, Goodwin published its full-year results and used them to confirm the sale process was live. Trading profit had more than doubled to £77.5 million on revenue that rose to £280m. Management said the sale process for Mechanical Engineering (which alone had generated £211 million in revenue and £68.7m in operating profit that year) was actively under way, targeted completion within 12 months, and reiterated that most of the proceeds would go back to shareholders, with the group aiming for zero net debt afterward. Shares jumped over £200 on the news, with many speculating that the price for assets would be in excess of the then share price.
Yesterday evening, the FT reported that:
Cerberus, the private equity firm founded by billionaire investor and US defence official Stephen Feinberg, is nearing a £1bn deal to carve out the defence business of London-listed engineering group Goodwin.
The price mooted was clear a disappointment to many holders, leading to the share price to fall around 20% yesterday afternoon.
Today we get some more detail, first in a “response to speculation” RNS, and then in confirmation of an agreed sale:
…reached an agreement to sell a substantial part of its Mechanical Engineering division which includes Goodwin Steel Castings Limited, Goodwin International Limited, Noreva GmbH, Easat Group and the Pumps Division… to an affiliate of Cerberus Capital Management…for a headline cash consideration of up to approximately £1.1 billion (subject to customary closing adjustments), following an extensive and thorough sale process conducted by Goodwin.
Although the share price has been volatile in response, the confirmation has led to a further decline in the share price so far today.
The typically low Stock Rank for Goodwin over the last decade, particularly the Value rank has put me off owning shares here...
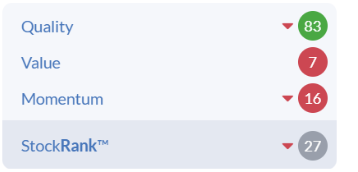
…until today.
Valuation:
At £152/share the market cap is £1.14bn, which means that the market is valuing the business at around the disposal proceeds. On top of this we have £25m confirmed dividend payout (going ex-dividend on 17th Sep), the refractory business, Duvelco, and AVD Fire. They say:
Particular emphasis will be placed on accelerating the commercial development of the Group's newer growth opportunities, including Duvelco and AVD Fire, alongside supporting the continued expansion of the Group's established Refractory businesses. The Board believes these businesses offer significant long-term value creation potential and will benefit from increased management focus and investment.
Refractory generated a £15.7m operating profit last year. “Technological” lost £3.5m, but it would seem strange to put no value on Duvelco, which they see as a great opportunity, even if commercial sales are taking longer than expected.
The market clearly sees some risk with the deal. Let’s go through each one:
Completion: They say: “The Transaction is expected to complete in the first quarter of 2027, subject to the receipt of customary regulatory approvals and completion of an internal reorganisation.” Given the sale to a US company with links to the current administration, it seems unlikely that approval won’t be given by UK or US authorities.
This is a substantial change of business and will need shareholder approval. I’ve seen chatter that suggests shareholders don’t see this as a good deal, but the family holding surely gets this over the line.
The time value of money for 6 months' completion is surely 5% max for most shareholders.
Up to £1.1bn: This leads to some wiggle room for the final payment to be less than the deadline figure. However, this reads as if the price is agreed but the usual adjustments for intercompany balances and working capital will apply. These should not be significant.
Use of proceeds: A company hanging on to the cash can be a risk, but we have confirmation that “Goodwin intends to pay a significant proportion of the net cash sale proceeds from the Transaction to its shareholders. The quantum, timing and form of this payment will remain at the discretion of the Board, and an update will be provided in due course.” My own feeling is that they will aim for around £1bn returned, with up to £100m retained to invest in the Technological Division and pay any transaction costs.
Future corporate structure: Could the family want to retain a bigger proportion of the remainco and use a delisting or similar to force it? It seems unlikely to me, and if they did go this route, they would surely offer a tender at greater than the current price, as they would have to accept that Refractory and Technological each have some value?
Mark’s view
Graham viewed this as AMBER at £194, due to the uncertainty with the valuation of the for-sale parts of the company. His caution has proved prescient, with many disappointed by the price level achieved. However, with much greater certainty on the sale, and the market cap valuing the remaining parts of the business at negligible value, it seems hard not to be more positive. The nature of the investment here has shifted, from one where one backs a management team for very long-term growth to a short-term mispricing based on a sum-of-parts. Personally, I am much more comfortable with the latter. Hence, I have been buying on today’s weakness. There are still risks involved, but going through each one, I don’t see enough concerns to put me off holding, at least until the sales proceeds are received. AMBER/GREEN
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

71 comments
Victrex (LON:VCT) I’ve had a rough ride with this, having bought in June 23 at around £15 a share. I noticed the Stockrank was extremely positive in April and doubled down at £6 a share.
The holding is now break even. But the question is, whether to exit unscathed now or keep holding for further upside recovery.
I bought in last month and have seen a quick jump. Outlook appears positive and shares have momentum, I am holding on!
Corero Network Security (LON:CNS)
There is no investment case here and massively overvalued.
Increased revenues with massive increase in receivables and cash decreasing, are all classic red flags.
Frontier Developments (LON:FDEV) now this is what I call a great FCF company, returning capital back to shareholders through special dividends and buybacks. We hold in our UK portfolio at much lower prices.
All the best
Corero Network Security (LON:CNS)
"There is no investment case here and massively overvalued."
In your opinion yiannos1, from a perspective which from your profile involves zero knowledge of Internet security. I worked for the company which invented ethernet and whose hardware built 80% of what became the internet. This company in the mid 80's had a private network using leased telephone lines, of 50000 computers around the world before the US government freed up access to what was a private government network called Arpanet. Recent events have shown the foolishness of abandoning private networks on systems for such as air traffic control and we rely on technology to filter out bad actors but that horse has bolted and internet access covers every aspect of modern life, including our ability to share opinions. I have confidence in the fact that major computer, network and cloud companies are choosing CNS solutions to distributed denial of service attacks* and as a software solution then profits will drop to the bottom line as predicted.
All the best
*A distributed denial of service attack is a result of the public inadvertently installing malware from clickbait. A large volume of remote bots can be simultaneously activated to swamp a target website and legitimate traffic grinds to a halt. The company presentation is available on You-tube here
CNS (TYO:4076)
I have confidence in the fact that major computer, network and cloud companies are choosing CNS solutions to distributed denial of service attacks* and as a software solution then profits will drop to the bottom line as predicted.
does that justify the market cap though - if you look at the interims they spent more on intangibles than they made in profit and had $2 mill net outflow at cashflow due to increase in receivables presumably.
Perhaps this company is on the cusp of better times - but even up to 30/6/2026 its basically still hemorrhaging cash - looks like they have turned $10 mill of cash around 2020 into $2 mill of cash now - paid no dividends and increasaed shares in issue - lets not pretend its beenb anything but woeful business up to now.
I would say there are shoots of hopes - sales are expected to be higher and 2027 profit forecasts indicate they are saying on that metric better times will be ahead. some might say "well they would say next year will be better wont they"
to me proof of puding has not been delivered at any level yet - beating expectations though is a decent helper towards perhaps things changing - with so many years of failure should they be given the benefit of the doubt now ref rosy hopes for 2027? - hmmmm
Even if they deliver profits on point - well how much will they blow on intangibles delivering profits ?
Super update from them yesterday, share price up nearly 20%. Maybe Phil Fisher's scuttlebutt methodology should not be so peremptorily dismissed.
Goodwin (LON:GDWN) Burnham to block the deal? www.dailymail.com%2Fhome%2Find..." class="redactor-autoparser-object">https://www.thisismoney.co.uk/...
Goodwin (LON:GDWN) as my largest position has spent most of the last year surprising me & today was one of the biggest yet. I’m obviously guilty of being far more optimistic of what the realisable value of the Mech Eng division was but I don’t suspect those in the room doing the negotiations of doing anything other than the right thing for all shareholders.
A full focus on Duvelco & AVD and the balance of the refractory division seems promising to me …and obviously to the Goodwin family too so I’m looking forward not backwards.
in the meantime I need to work out where to redeploy my incoming capital return…
HI Rhomboid, The market pricing the remaining businesses below the cash return seems unfair? Especially given the potential returns from Duvelco...
Anpario (LON:ANP) I hold
I agree with Graham that this looks set up for a miss in H2.
I found it interesting that :
Hopefully the forthcoming IMC should shed some light on these !
I think you are maybe getting a little overly concerned here, Lochinver. I have held Anpario (LON:ANP) for quite some time and I'm fairly sure that this is how they always report their numbers. Any more precise detail would probably be misleading because they have a history of large swings in sales by geographic region. What matters here is the overall annual outcome and this has finally shown growth in the last couple of years after flatlining for some time. The excellent acquisition of BioVet in the US probably accounts for a lot of that.
I actually thought the outlook statement suggested that the softer conditions in Asia might be entirely offset by new product sales elsewhere. Clearly there is an elevated risk of a miss on forecasts at the full year, but I understand that Shore Capital have left numbers unchanged for now.
Finally, if you check the last line of the AGM statement in June you will find that they announced their interim results date right back then! Something to be applauded and a mystery as to why it wasn't picked up by the data providers of reporting dates.
Overall I remain comfortable with this quality business and prepared to accept a degree of short term volatility.
Thats good to hear Sparkler, thanks for that
Treasury yields will only drop significantly if the US economy enters a deep and extended recession.
Bessent will try every manipulated way possible and fail!
All the best
Hi Yiannos,
I understand Bessent is using short term Treasuries to buyback long term Treasuries. My understanding is that this is the equivalent of rearranging deckchairs on the Titanic. As you state, it will fail and its just prolonging the inevitable.
David.
Absolutely correct!
I have posted last night on X a detailed analysis of the US debt and the interest payments, comparing 2016 to 2026 and then to 2028 estimates.
Long deep recession is inevitable.
All the best
SThree (LON:STEM) RNS just announced it's received a bid approach:
"The Board of SThree notes the recent media speculation and confirms that it has received an unsolicited, preliminary and highly conditional approach from Circle8 Group Inc. (“Circle8”) regarding a possible offer for the entire issued and to be issued ordinary share capital of SThree."
SThree (LON:STEM) I wondered why price shot up earlier, could not see any news. I hold.
I hold SThree (LON:STEM) as well. (forgot to mention that.)
For anyone still following Sunbelt Rentals Holdings (LON:SUNB) (formerly Ashtead), it just produced a decent earnings report:
- Total revenue increased 11.2% to $3,115 million
- North America General Tool segment rental revenue increased 7.4% and North America Specialty segment rental revenue increased 25.3%
- Adjusted earnings per share increased 20.4% to $1.18
- Co raises full-year total revenue growth guidance to between 6% and 9%, up from 4.5%-7.5% previously
I hold.
Goodwin (LON:GDWN) Am I correct in thinking that, based on Mark's assessment above, if they intend to return 1bil to shareholders it will equate to £125 per share?
Mark refers to the company returning £1m of the sale proceeds to shareholders - won't the company have to pay tax on the sale proceeds?
I read this part
" My own feeling is that they will aim for around £1bn returned, with up to £100m retained to invest in the Technological Division and pay any transaction costs."
Goodwin (LON:GDWN)
This morning's second RNS reads as follows;
The Board intends to pay a significant proportion of the net cash proceeds from the Transaction to shareholders, and that any remaining net cash proceeds will be used to support and accelerate growth in the Group's Remaining Business.
I have a feeling holders are assuming significant means 'all' , well context is everything and AI would suggest 'significant' is likely to be 15-50% .
well context is everything and AI would suggest 'significant' is likely to be 15-50% .
well thats kinda proof that AI doesnt have a clue ref the context here - no proof of the pudding but surely they will pay out 75%-80% plus - cant see any benefit leaving spare cash sat there if you want to max overall shareholder value pronto.
I didnt reference this particular situation to AI when I asked what % 'significant' could mean. If someone has lost a 'significant' amount of blood in an accident what % do you think that would be? My point was the term 'significant' is very vague.
Very unlikely that tax will be due to the UK Substantial Shareholding Exemption. Given Goodwin is likely to sell shares in a subsidiary and held at least 10% of the ordinary share capital for at least 1 year then no UK tax would be due upon disposal.
Everplay (LON:EVPL) resistance at 280 maybe about to go, could be a nice run up to 340p if results are fine
Frontier Developments (LON:FDEV) ... great results - but David Braben becoming a NED rather than an exec role - end of an era - I haven't thought through what it means for the business.
He is a GOAT - thanks to him many hours spent playing Elite on the ZX Spectrum. Remember - https://www.telegraph.co.uk/te...
Hi Edward, is there any way of Direct Messaging you?
Yes, great results Ed. I bought Frontier Developments (LON:FDEV) in May after they met the "Stock Jump" criteria ("ahead" RNS, SR above 75 and a 10%+ jump on the day) and have been patiently(!) waiting for some momentum.... Here we have it! Still looking good value in my view. Thanks Ed!
Nice to see Made Tech (LON:MTEC) properly breaking out now. I shared this chart in a newsletter a few weeks ago, the week that both MTEC and Kainos (LON:KNOS) announced good news.
Lots of "significantly" and "aheads" and contract wins in a row... without quite breaking out of a year long range. Eventually something has to give way.
I first bought these when Mark went green on them in Dec last year following a good update. Added twice more. Now sat at +35% so thank you
Pathos Communications (LON:NEWS) It's small and new to the market, but the Pathos interims today look very good yet get no mention at all. Cavendish have a TP of 50p. It looks tom be an interesting play that is delivering on promise made at Mello. For clarity i currently do not hold.....
Re : Mortgage Advice Bureau
Probably no surprise that anything housing related is under pressure.
I was intrigued by the statement.
"Product Transfers account for by far the largest share of refinancing activity and, with affordability constrained, the mix is expected to remain weighted towards Product Transfers rather than remortgages"
I thought from this article that the market might be moving away from this product mix....https://theintermediary.co.uk/...
Irrespective of how the refinancing is carried out - like other posters here, I don't see housing affordability improving in the near future and would question any (not just MAB) 2027 forecasts.
No position
ASA International (LON:ASAI) appears to have excellent results. I note though that its Operational Cash Flow and Free Cash Flow appears to be well below EPS. Can anyone explain why this might be the case given the nature of its operations.
ASA International (LON:ASAI) I wonder how long Stocko will maintain such a poor quality rating (17) after such stellar results, especially with such a conservative payout ratio/
Steppe Cement (LON:STCM) - A late addition to the party, announced interims at 9am. I can't say I like companies releasing RNS's at anything other than 7am. Results look to be good.
Goodwin (LON:GDWN) A lesson for all PI's
The danger of investing in a company with majority founder holdings can plainly be seen in the path Goodwin plc has taken recently. No matter the size of your holding if you are not family you are simply along for the ride and will be told when the journey has ended. No matter how much research you do you have no insight in to the really important decisions. This is not sour grapes, I made very good money from Goodwin, prompted by rhomboids postings, so thank you rhomboid, however I don't take huge positions and tend to take profits too early. I was fortunate to get out in March , that was just luck with a little bit of charting thrown in. TBH as PI's we are lucky to piggy back on the success of some brilliant entrepreneurs, we can buy one day and sell the next, profiting, hopefully, from someones hard graft over a number of years. The lesson to learn is the downside of this is that we are not really shareholders in the full meaning of that word, we are just guests and as such we should be grateful but realise the limitations that the invite provides and use that knowledge to our advantage. It would be too easy to say that looking back at the November placing, the odd March TU RNS and then the about turn in August it was obvious something was going on, because when it was obvious it was too late. Lets hope Goodwin goes from strength to strength in its smaller form.
As a PI shareholder you’re along for the ride on all positions, not sure if the interests of one large shareholder (or family) is any different to institutional shareholders. The thing with Goodwin is in giving little information they didn’t hide their indifference to outsiders. I guess everyone knew that before investing.
"TBH as PI's we are lucky to piggy back on the success of some brilliant entrepreneurs"
Your post describes our situations very well, Helvellyn. Sometimes we are the vehicle for founders to cash in some of their hard work and let others share in the ongoing story, sometimes we are the useful idiots buying into the end game. Directors selling into fundraising "to aid liquidity" is one red flag for me. Goodwin had always kept its distance from the City until recently when they had a bumper year end with a special dividend and I think it was then that the sharks scented blood and started the ball rolling knocking on Goodwin's door. Anybody else got clues to watch out for.
I really can't complain in this case, having made a good profit over the last couple of years, just a pity that a great company might end up being just a memory here with all its IP and key people moving on leaving us just a service economy cutting each other's hair. It was always obvious to me that its big US customer, who couldn't find a local supplier, might one day want to secure its supply chain by buying Goodwin.
Nicely said on Goodwin (LON:GDWN).
Will add that subscribers should pay more attention to posters that actually do their homework before sharing their work/views.
Honest opinions shared here after hours of research and 4 decades of experience in the markets, should always be taken seriously.
All the best
Goodwin (LON:GDWN)
https://www.stockopedia.com/a/...
That didnt take long ;-))
Morning Helvellyn,
Goodwin (LON:GDWN) is now added to the table.
Roland
I would be interested in any thoughts on the continued Funding Circle FCH sell off as I just do not understand it.
Major disappointment for me too as it is my #1 by some margin and does seem an odd reaction to yesterday’s news but I think the 3 main factors in play are:
1 – CEO leaving unsettling retail investors
2 – Despite posting a “beat” it seems the magnitude of the beat was less than analysts were pencilling in
3 – Profit protection / taking after a good run of late.
I will be continuing to hold this one and am hopeful that sanity will prevail ! Would be very happy so see others’ views.
Added yesterday purely on a technical outlook
Re Funding Circle
"I would be interested in any thoughts on the continued Funding Circle FCH sell off as I just do not understand it"
Maybe some hangover from the CEO announcing departure - reported and discussed here yesterday,
Also , 15% of the UK's SMEs are in construction - by far the largest category. Not a strong sector at the moment and might be future a drag on performance.
No specific knowledge here, just thoughts as requested.
Damage at Mortgage Advice Bureau (Holdings) (LON:MAB1) is surely the 15% reduction in mortgage approvals (ie jittery lenders);
I'm viewing this as being akin to "contract delays" rather than any structural problem with the business.
This wll be on 6.5% yield after todays drop.
QV at sale prices???
Hi
I agree to an extent, unclear what Mr Market was expecting given the housing market and therefore transactions have virtually ground to a halt. Like housebuilders you would need a catalyst for a pick up and I am not sure that would be a rise in UK interest rates. Yes I am looking for more stocks for the yield tranche of my portfolio and did look at this a little while back. Interest deferred is the apposite comment
Mortgage Advice Bureau (Holdings) (LON:MAB1)
I'm viewing this as being akin to "contract delays" rather than any structural problem with the business.
the proof of the pudding will be the impact on next years forecasts - its rarely the case with profit warnings like this that the following year is not impacted too - over to the brokers to give us the reality of where expectations are now. so unless brokers dont chop next year i think you are being a bit generous here. Having a quick butchers i think they have most likely been guilty of being overconfident ref growth - following years forecasts are nearly always built on carrying on as hoped and then sum.
It must be like 90% of the time when companies give update like this that its basically permanent lowering ref future - rather than just £5 mill from this year with next year as previously expected.
If next year was not affected i would kinda expected them to specifically say so.
Hey hoy the crapola will hit the fan once in a while and any company can be caught out by £5 mill - its not an easy game projecting 12 months in advance. I would question though if managment benefitted from rosy projections perhaps?
looking at what they did say
The Group does not expect a meaningful recovery in purchase activity in the short term.
ok new purchase may be minor part of their business but that sounds structural.
Delivery against Fluent’s strategic plan has been slower than anticipated. Following a steady recovery in business performance and the continued development of its mainstream first-charge mortgage proposition, Fluent was expected to deliver a significant step-up in 2026, supported by new contractual lead flows. However, the launch of these arrangements has been delayed. Pilot costs have therefore been incurred ahead of the associated revenue contribution. As a result, Fluent’s expected contribution to Group Adjusted profit before tax for 2026 is approximately £5m lower than previously anticipated.
this sounds pretty structural - that they are a a year behind what they promised kind of
to me it seems like they simply over egged their growth pie and and making excuses for their poor over optimistic projections. Not sure how key fluent is but seems like they are laying the blame there.
pe wasnt too bad here - so hopefully the market might have factyored in that forecasts where not fully in then bag ? could this be a buying opportunity if this is a one off "kitchen sinking" ref bad news - hmm whats that saying about what to do ref first profit warning ?
One thing that does stand out is that 2026 onwards seems to be a lot more rosy ref bottom line numbers than prior years - not sure if thats mistmatch between "adjusted profit" and actual bottom line profit previously ? can we expected bottom line to show these serious improvements over prior years ? that might simply be eliminating nasties ? can they actually deliver that ?
Profit warning, out straight away!
Victrex (LON:VCT)
One of my recovery plays. It doesn’t look optically cheap, but in large part recovery plays never do. The new CEO is streamlining the business, including reducing headcount.. it is doing more with less.
Pebble Beach Systems (LON:PEB)
Another recovery play where the investment metrics look a little more enticing. Should be cash positive in the near term with the prospects of dividend payments starting.
Thoughts of Graham and the team welcomed.
Late RNS from Goodwin (LON:GDWN) this morning confirming disposal discussions at headline price of £1.1 billion. Rumours of pricing in an FT article caused a massive crash in the share price in late trading yesterday afternoon.
Corero Network Security (LON:CNS)
The words significantly exceed appear in their results.
Wise (LON:WISE) :
Morning!
Wise: Regulatory update + Goldman CFO interview
This is information from Wise’s CFO Emmanuel Thomassin at Goldman Sachs Communacopia Technology Conference on 8 September.
It’s not directly from the Wise website, but I listened to the call and further details are from the investing.com transcript.
Apologies if this is a little verbose, but I’d rather provide a little too much (rather than incomplete) detail.
Given the current US and Belgian AML concerns, the regulatory comments are the most important new information.
There were also interesting disclosures around Visa/Mastercard economics, Wise Assets, Platform and customer holdings.
I’ve used quotation marks for Thomassin’s words.
Anything labelled Inference is my interpretation rather than something Wise has claimed.
1. US AML remediation
On the US multistate consent order, Thomassin said:
“We resolved all the remediation from the consent order, and then we’re waiting for the confirmation of the state that everything has been remediated.”
Fact/management statement: Wise believes it has now completed the remediation required under the US consent order.
Inference: Wise believes it has satisfactorily addressed the required actions. It is explicitly still awaiting confirmation from the relevant states.
It is presumptuous to describe the US AML matter as resolved. However, this appears to move the position from ‘remediation underway’ to ‘management says remediation completed’; further regulatory validation is pending.
2. Belgium
On the Belgian AML remediation, Thomassin said:
“[It] is something that we will deliver by the end of the year, and then the regulators will come back to us after observing the remediation.”
Fact/management statement: Wise expects to deliver the required Belgian remediation by the end of 2026.
Inference: We have been given a time line for Belgian remediation, and that is the end of this year.
This is obviously caveated that delivery is not the same thing as conclusive remediation, the important subsequent evidence will be the NBB’s assessment after observing the new controls.
3. The failed OCC application
Thomassin was also candid about Wise’s rejected US national trust bank application:
“Looking back with some insight, I think we would have reconsidered the application that we made…”
Wise continues to intend a new application under a GENIUS Act framework, although no firm timetable was given.
Inference: The willingness to acknowledge that Wise itself would have reconsidered the original application is encouraging from an organisational perspective.
That does not evidence the underlying regulatory deficiencies have been currently and definitively fixed.
I’d add solving ‘Belgium’ doesn’t neatly address the failed OCC application; the OCC also identified additional US-specific issues around national-bank/fiduciary expertise and proposed management/governance. However, I suspect there is overlap in these remediation areas, and the work done is probably complementary.
In conclusion, I feel this is positive management-reported progress that will hopefully mature into appropriate regulatory validation.
⸻
Visa/Mastercard — tangible evidence of scale economics
This was the most interesting economic disclosure.
Discussing the benefits Wise receives as its volumes increase, Thomassin said:
“as the volume grow, we go back to the banks and negotiate better terms, better conditions.”
He then explicitly extended that to the card networks:
“This is the same with Visa /Mastercard, where we have been negotiating better terms and conditions because of the volume that you generate.”
How the resulting efficiencies are utilised:
“All this efficiency will drive margin, and then we will consider to reinvest…”
Into take rate adjustments and direct business investment.
Inference: this looks like further clean evidence of Wise’s ‘scale-economies shared’ I’ve previously mentioned operating in practice:
more volume → greater negotiating power → better supplier economics → lower unit costs → capacity to reinvest/reduce prices → potentially more volume.
It’s interesting this is occurring with behemoths such as Visa/Mastercard.
Wise doesn’t need to displace every incumbent infrastructure provider; increasing scale improves the economics of using their infrastructure.
⸻
Wise Assets — BlackRock and JPMorgan
Thomassin explained that customers may invest money through Wise using products involving partners including BlackRock and JPMorgan, with the investments held off Wise’s balance sheet.
Customer holdings reached approximately $41bn in Q1, and Thomassin described customer deposits/holdings as:
“the fastest-growing KPIs last year”
He also said:
“More and more people are getting their salary paid on Wise and use it as everyday account…”
Around 66% of retail customers and 60% of business customers now use the Wise Account, according to the discussion.
Q1 also saw 51% of net revenue coming from non-cross-border sources.
Inference: This is becoming strategically important. Cross-border transfer increasingly looks like the acquisition wedge into a broader financial relationship.
Wise can potentially own the customer relationship, account and distribution layer, while institutions such as BlackRock/JPMorgan provide specialist underlying financial products.
Wise can deepen the customer relationship without having to manufacture the entire financial-services stack itself.
⸻
Platform reaches 6%
Thomassin gave an updated Platform KPI:
“Platform moved from 0% to 6% today of the global cross-border volume that we are generating.”
Importantly, that’s 6% of cross-border volume, not revenue.
He also said:
“We guide the market that we will be around 10% of the total cross-border volume within the next three years or so.”
He described existing institutional customers expanding in two directions: adding additional currency corridors and subsequently additional products/services.
Inference: the interesting feature isn’t a new Platform customer win. Initial bank integration potentially creates a multi-year expansion opportunity within that customer. The ~10% target now gives investors a useful quantitative checkpoint for the next three years.
⸻
Wise Business is being embedded into SME workflows
Thomassin discussed integrations with local accounting-software providers, allowing SMEs to initiate payments and reconcile them within their accounting workflow.
He said:
“That integration will increase the stickiness of these small businesses.”
Inference: this potentially creates switching costs that have little to do with headline FX pricing. Wise becomes embedded in the business’s operating workflow rather than being a cheap cross-border provider.
⸻
Customer acquisition remains predominantly organic
Despite Wise increasing marketing expenditure substantially, Thomassin said:
“70% of new customers come through recommendations from existing customers.”
He also discussed approximate marketing payback hurdles of 15 months for retail and 22 months for business, and indicated that Wise would be willing to spend more where those returns remain available.
Inference: that provides some reassurance that accelerating customer growth isn’t solely being purchased through escalating acquisition spending. Word-of-mouth remains the dominant acquisition channel.
⸻
The invisible infrastructure moat
Finally, Thomassin made an interesting point about direct payment-system integrations: investors may underestimate their value because they aren’t visible as conventional balance-sheet assets.
Japan apparently took approximately four years to secure.
Wise describes itself as having 9 direct connections, 80+ licences and 90+ banking partners.
Inference: this is important when assessing replicability.- I feel this is an inadequately understood moat.
Software can be reproduced relatively quickly.
Accumulated licences, regulatory permissions, banking relationships, direct integrations and the years required to obtain them cannot.
Thomassin added:
“There’s no reason in our mind that Revolut should not use us in 5 years from now.”
That’s ambition, not a forecast. It describes Wise’s ultimate Platform objective: become infrastructure sufficiently useful that today’s competitors eventually consume it.
Conclusion
I think the regulatory comments are the headline.
Wise says the US consent-order remediation is completed and awaiting state validation, while Belgian remediation should be delivered by year-end before the regulator assesses it.
That’s more concrete than we’ve previously had, but I’d caution against promoting management-reported remediation to successful regulatory remediation until the regulators themselves do so.
The Visa/Mastercard disclosure is perhaps the earliest post- dual listing evidence I’ve seen of Wise’s scale directly improving its input economics.
Wise Assets + $41bn of customer holdings + increasing salary/everyday usage further support Wise is deepening from a transfer service into a broader financial relationship.
And Platform at 6% of cross-border volume, targeting ~10% in around three years, gives us a concrete metric against which to test the institutional-infrastructure thesis.
Thank you for your patience!
Source: Emmanuel Thomassin, CFO, Goldman Sachs Communacopia + Technology Conference, 8 September 2026. Direct quotations above are from the available conference transcript; interpretation is explicitly labelled as such.
As Blaise Pascal said "Je n’ai fait celle-ci plus longue que parce que je n’ai pas eu le loisir de la faire plus courte*.
Or was it Mark Twain :)
Or was it Mark Twain :)
Whoever it was, they were a lot more succinct than AI, that's for sure ...
As an Electronic Money Institution Wise (NSQ:WSE) can't charge interest, so "interest bearing" accounts are actually investment accounts - which opens up unsuspecting holders to CGT. As I discovered the other day ...
As ever, the network effects remain the engine: everything else spins out of that. Regulatory issues should be hurdles rather than barriers.
timarr
Arguably for anyone on higher or additional rate treating the income as gains should be a positive - 24% CGT if not covered by unused threshold or offset against losses, with no 2% surcharge, oh, and no cliff edge imact on marginal rate at £100,000.
Pascal, he did sums and there's nought new about slop
Wordsworth, may I suggest in future you provide a link rather than the Full Monty!!!
Apologies, both! It was clearly more ‘Substack’ than ‘Stocko’!
For those avoiding Un-Wise rabbit holes:
Wise CFO update from Goldman:
US consent-order remediation is, according to management, complete and awaiting state confirmation; Belgian remediation is expected to be delivered by year-end.
Separately, Platform has reached 6% of cross-border volume (target ~10% in ~3 years), customer holdings are the fastest-growing KPI, and Wise says its increasing volumes are allowing it to negotiate better terms with Visa/Mastercard. Wise Assets uses partners including BlackRock/JPMorgan, while Business integrations are increasing SME workflow stickiness.
My interpretation: encouraging regulatory progress but not yet regulatory validation; meanwhile several pieces of the long-term scale/network thesis are becoming increasingly observable.
There’s more :-)
All the best
Thanks very much for the extra colour as Wise is a complicated business to understand.
It would be nice if the Wise (LON:WISE) share price could remind my portfolio that it is a growth stock, having walked sideways for the last two years. Who knows, we might even get a dividend to reward our patience when they achieve their 10% share of cross border volume.
Many thanks David, as a Wise shareholder I really appreciate you sharing your in depth analysis. You are certainly very knowledgeable on the company and I always appreciate and look forward to your updates. Many thanks again