Diploma beats expectations with 45% earnings surge while flagging slower FY27 growth

Analyst’s view:
Today's earnings are slightly ahead of consensus, thanks to with organic revenue up by an impressive 15% last year. Growth looks set to slow in FY27 due to tough comparatives, but my sums suggest that today's guidance is in line with or perhaps slightly ahead of previous consensus. I'm reluctant to downgrade such a high quality business against this backdrop, so I'm leaving our view unchanged today despite the stock's demanding price tag.
Up 0.8% to 7,220p (£9.6bn) - Full-Year Results
Shareholders in this value-added distribution group are likely to be reassured by today's full-year results. Demand for the vast range of components and services provided by Diploma to its customers remained strong during the year ended 30 September, with organic revenue up 15% and total sales up by 21%.
Today's FY27 guidance is for "another strong performance", with results expected to be "ahead of our financial model" over the coming year.
Let's take a look.
Full-year results summary
Diploma operates as a group of semi-autonomous businesses, enhancing its organic growth with regular bolt-on acquisitions. This business is a relatively rare example of this strategy being applied successfully to deliver high-quality compound growth over a long period.
Today's numbers highlight the quality of the business and appear to be slightly ahead of consensus:
Revenue up 21% to £1,840.3m (ahead of StockReport consensus: £1,825m)
Organic revenue growth +15%
Operating profit up 37% to £390.0m
Operating margin up 2% to 21%
Free cash flow up 31% to £323m
Adjusted EPS up 45% to 255.6p (ahead of StockReport consensus: 251p)
Full-year dividend up 5% to 65.4p
Return on adjusted trading capital employed (ROATCE) of 25.3% (FY25: 20.9%)
Sales growth was clearly strong last year but the company's commentary makes it clear that some areas were stronger than others.
Indeed, it looks like one of Diploma's subsidiaries was responsible for a full third of the organic growth achieved last year: aerospace fasteners business Peerless is singled out a number of times for its "continued outstanding performance". Excluding Peerless, we're told that organic growth across the remainder of Diploma's portfolio averaged only 10%.
Profitability: I'm not generally a fan of company-adjusted measures of return on capital employed as they often seem a little too idealised and fine-tuned. However, Diploma's profitability last year was impressive, however it's calculated:
Company-preferred ROATCE measure: 25.3%
Return on Capital Employed (my calculation): 21.6%
Return on Equity (my calculation): 21.8%
Diploma makes "quality compounding" a core part of its business model. Few businesses do this and even fewer genuinely deliver, but to my mind there's no doubt that the company deserves to be considered as a high quality business.
Divisional performance: variations in performance across different end markets are always to be expected. Right now, defence, aerospace and data centre customers all appear to be driving strong demand, while healthcare and some non-US markets are more challenging.
This is reflected in the performance of Diploma's three sectors:
Controls (revenue +32% to £1,102m, adj op profit +55% to £387m): Windy City Wire (30% of sector revenue) delivered organic growth of 19% while the remaining businesses in this sector delivered organic growth of 27%, led by Peerless. This remains Diploma's flagship division, with an adjusted operating margin of 35% last year. Outlook: management says demand remains strong with multi-year backlogs in aerospace, albeit strong comparators may lead to lower growth rates over the next year.
Seals (revenue +5% to £477.5m, adj op profit +6% to £93m): in North America, this sector saw "continued market share gains" and made progress in "attractive growth markets" such as water management and nuclear power. Conditions were more difficult outside the US, especially in the UK where "weakness persisted across construction, agriculture and industrial markets", albeit with some improvement during the second half. Outlook: "continues to improve as we enter FY27", with North America remaining strong and international markets improving, supported by investment within the business.
Life Sciences (revenue +12% to £261m, adj op profit +15% to £52m): despite a creditable set of financial results, most of last year's growth was driven by acquisitions - organic revenue rose by just 1%, potentially implying a fall in organic volumes after price inflation. Today's commentary suggests the weakness is more cyclical than structural, with "healthcare market pressures and short-term product lifecycle effects". Outlook: "we expect the first half of FY27 to continue to be challenging".
Acquisitions: the company's acquisition machine continued to fire last year, with 14 new business acquired for c.£281m. These are expected to add £37m of annualised operating profit. That gives an average purchase multiple of 7.6x EBIT.
For contrast, Diploma's own EV/EBIT multiple is around 20x, even using adjusted operating profits.
The contrast between these two valuations highlights another attractive element of this business: Diploma's scale and stock market listing means its earnings are valued far more highly by the market than those of the individual companies it acquires. This leads to an arbitrage effect, whereby earnings of acquired companies are immediately re-rated to a higher multiple, underpinning share price growth.
FY27 Outlook & Guidance
CEO Jonny Thomson guidance for FY27 would be impressive by most standards, but does represent a slower rate of growth than seen over the last year:
Total revenue growth of 12% (+6% organic, +6% acquisitions)
Expect double-digit Q1 growth, moderating as Diploma laps strong comparators from Q2 onwards
[Adjusted] Operating margin of 25.5%
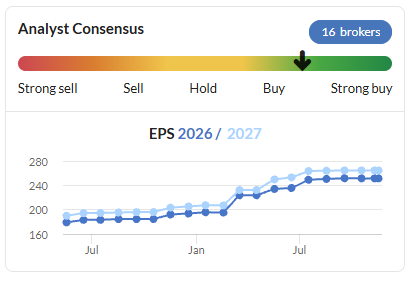
I don't have access to broker forecasts for Diploma, but my sums suggest this guidance is in line with or slightly ahead of the previous consensus. Initial updates to our consensus EPS trend chart this morning suggest EPS estimates are likely to remain largely unchanged:
Roland's view
Diploma's appeal as an investment lies in its ability to maintain high returns on capital while also expanding its asset base. This combination will mathematically lead to attractive rates of profit growth.
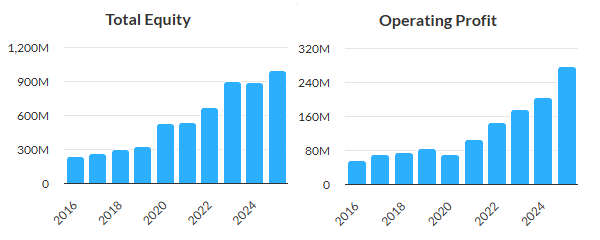
We can see this by looking at the group's balance sheet equity and operating profit since 2016. Both have increased at least fivefold over the last 10 years:
Over the same period, the company's shares have risen around 7x:
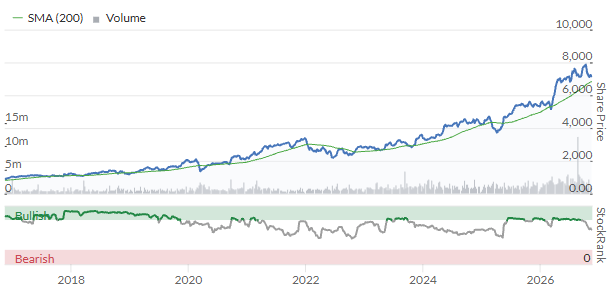
The shares have also re-rated and become more expensive over this period, but not by as much as we might suspect.
Stockopedia's history function lets me see that in November 2016, Diploma was trading on a rolling forecast P/E of 19.4. Today, the rolling P/E is 27x.
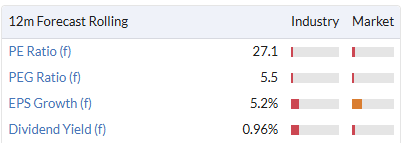
If Diploma can maintain its track record, then it's possible that the share price remains reasonable today. However, I think it's fair to say that the risk of disappointment is higher on a P/E of 27 than it was on 19.
Personally, I remain both deeply impressed and priced out of this business! Although I'd be a buyer on c.20x earnings, the current price tag is just a little too rich for my value instincts to accept - especially as earnings growth seems likely to slow in FY27.
The StockRanks are similarly conflicted, styling Diploma as a High Flyer with a notably low ValueRank and a declining MomentumRank:
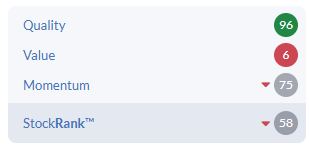
While I'm cautious, I'm reluctant to downgrade such a high quality business when today's results have beaten expectations and guidance for next year is level with or ahead of consensus.
To reflect this mix of factors, I'm going to leave my previous AMBER/GREEN view unchanged today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Diploma (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?